You’re going to come across a lot of advice about why you should or shouldn’t acquire debt financing for your business. Without getting into that debate, yes, “bad debt” can have negative results in your personal and professional life. But, when you know how to leverage it properly, business credit can completely transform your company and your lifestyle in tremendous ways. It can also bring additional revenue and cash flow.

Discover the "3-Step System" to Get You Significant Business Credit (Without Having to Show Any of Your Financials). So that you can increase your cash flow, have true freedom and peace of mind!

So, if you have a good business credit score (or you’re ready to learn how to get there), you know how to turn $1 invested in your business into $2, and now you want to learn how to take your business to the next level, this guide is for you.
Here, you’ll find the following:
My Experience With Business Credit
Before you dive into the nitty-gritty details, I want to share my story. Learn where I was before discovering business credit. Then, find out what caused the shift in my beliefs and understanding of business finance. After that, learn how business credit can completely transform your life.
Where I Was Before I Discovered the Power of Business Credit
Before I discovered the immense value of business credit and how to leverage it to fuel a successful real estate investment company, I was working as a technical recruiter. My job was to place high-level IT professionals and contractors that made $100 to $300 per hour with big companies like Johnson & Johnson and Merck.
My job came with a salary, a nice office, plenty of windows, and an overall pleasant environment. Plus, I was able to earn a commission when I placed someone at a position. It took a lot of work and a few dead-end jobs to get to this point but actually, I liked my job at the time.
At that stage in my career, I had the potential to earn more than just a base salary, which was important to me, and I liked my co-workers. I knew that if I worked harder I could make more money and I found comfort in that.
But, one Wednesday morning around 8:30 am, I was driving to work when I looked to the side of the road and noticed a couple of guys playing golf. And, I realized that I wanted the freedom to play golf in the middle of the day. It was at this moment, I first questioned the 9 to 5 lifestyle and I started to feel like a caged bird.
Suddenly, I didn’t want to work from 9:00 to 5:00 every day and limit myself to two weeks of paid vacation each year for the rest of my life. Instead, I wanted to spend time with my family and have the freedom to travel whenever I wanted. I was in my 20’s. And, before that moment, I didn’t believe I could have that kind of life for another 40 years when I was ready to retire.
But, at that moment, there was a shift in my beliefs. While I didn’t yet know I could attain the dream, I decided to try anyway. I made the leap and launched a real estate investment business while working a full-time job.
At this time, I had to use personal capital — my own personal credit cards and cash to fund my business. Personal credit cards were helpful because they allowed me to operate as if I were a larger business. And, my goal was to get the results a larger company would get, use the revenue to pay off debt, then repeat the process. So, it was working.
However, the more personal credit you use, the worse your score ends up because your utilization is too high. So, launching the business ended up messing up my personal credit. I was still hopeful, but there were some obvious problems.
The Headline That Changed My Beliefs
During the early stages of business, I was a sponge. I was trying to learn everything I could. So, I signed up for every email list that I thought might help me create the success I wanted, even if I would only get scraps from each of them.
One day, I got an email with a hook that said something like, “26-Year-Old-Kid Gets $100K in Funding in 100 Days.” While I didn’t believe it could be true, I was still intrigued. So, I clicked the link, watched the webinar, and I paid for the course.
After that, I bought every course and book I could find about business credit. From these sources, I pulled out all of the best parts, let go of the useless or outdated information, and used my newfound knowledge to come up with a plan for my own business.
Then, the magic happened in 2007 when I decided to launch a direct mail marketing campaign. I wanted to send letters to homeowners that might have distressed properties because I was looking to invest in real estate. And, I thought this would be a great way to get off the ground. So, I applied for a business credit card to fund the campaign.
When I got approved for a $25K business credit card with no reporting to my personal credit profile, I was amazed. At that time, the highest limit I had on my personal credit was $15K. I used the credit card to execute a successful campaign, got my company off the ground.
So, I got a few more business credit cards, cleared $100K, and I invested heavily in my marketing. When I saw that the model worked, I went in and doubled down. Before this, I never would have been able to afford radio ads. But, once I had credit, I was able to leverage advertising channels that delivered substantial results. As a result, I started to see a very positive return on my investment.
How This New Discovery Shaped My World
Soon after obtaining business credit, I was able to leave my job as a technical recruiter because I was making more money in real estate. And, it didn’t matter if I had high credit utilization on my business credit cards because nobody could really see it on my personal credit report.
Now, I am able to see success a lot quicker because I have extra funding behind me. I have opportunities that didn’t exist before. I can do more marketing which opens up more revenue. I was able to get an office, hire employees, and founded a real company within 90 days of getting business credit.
Years later as a result, I have a real estate portfolio and I can play golf whenever the heck I want. My wife and I have been able to go to the places and see the things we want — we’ve been to 16 Caribbean islands and I’ve been to some really awesome places like Japan and Thailand. So, we did cross over to the lifestyle we had dreamed about. It really was possible.
There is one more, completely accidental transformation that has happened as a result of what I learned that is even more exciting. Shortly after realizing that business credit was the key to obtaining the capital I needed, I attended a seminar. And, while I was there, someone overheard me talking about my experience and stopped me.
The stranger asked me to repeat what I had just said. And, when I had told him that we can get all this funding for our business beyond personal credit, he asked a question that would change my life forever.
We were on a lunch break and he suggested that I come up with five tips to secure business credit to share with the audience. Then, at the end of my presentation, ask, “Does anyone want to learn more?” If they did, we would ask them to walk to the back of the room and sign up for a workshop to learn how to implement these five tips to obtain new business funding over the next 30 days.
At the time, I despised public speaking. I had said that standing up in front of a crowd to tell my story was something I would never do. But, I had a choice and I said, “yes.”
But, I didn’t have a course to sell.
So, I grabbed an index card, came up with five bullet points, and presented them to the crowd, my heart pounding the entire time. And, at the end of my 15-minute speech, one-third of the group stood up and walked to the back of the room to sign up for my course where we were going to delve deeper into those five bullet points. I was like a happy puppy with all of the energy and excitement around this new discovery I had to share with these people.
I thought back to all my recent training and reading materials. Then, I took what I liked from the best parts of all of it and left out the rest. And, when I launched my business credit coaching business in the back of the room at the seminar that day, I only hoped I could bring something more valuable to the marketplace.

The reason Business Credit Workshop’s name is so simple is that I only had a few minutes to come up with it. Now, I’ve coached over 1,800 individuals to obtain the credit they need to take their businesses to the next level. And, this doesn’t include all of our members who have taken advantage of the backend training we offer.
Today, I have a database of bankers. And, I talk about the trade secrets that the “gurus” didn’t want to tell people. I talk about the top 50 lenders I like to use. I share the nitty-gritty details.
My five bullet points are now a fully-sharpened, seven-step system for obtaining business credit. Because of what I learned, my business and personal life have improved tremendously, and I’ve been able to help thousands of other business owners make life-altering transformations within their companies.
Solving the Mysteries of Business Credit
Now, I want to tell you how you can take what I know and apply it to get funding for your business. Get ready to learn the fundamentals and the secrets of getting the working capital you need to grow your company and increase your revenue.
Why You Need Working Capital to Scale Your Business
I really love the way one of my past coaching clients, Brendan Purnell put it when interviewed for a case study: “Personal credit is limited and cash flow is a gamble. Make sure you have adequate capital because, in the blink of an eye, you can go belly-up if you are under-capitalized.”
According to the Federal Reserve, 40% of businesses struggle with their operating expenses, which is the top financial challenge business owners face. And, if you can’t get the capital you need to operate, you can’t keep your doors open, let alone grow and thrive.
I recently spoke with someone who had a hair salon in Oregon back in 2009. She saw an opportunity to offer a professional-quality, organic haircare line and nobody in the US was doing it yet. In the beginning, she made the hair products available exclusively to her salon clients. When the product line was a hit, she decided to put the shampoos and conditioners online to see if there was enough interest to go national.
And, within less than a month, she got an inquiry for a $20K order. But, she didn’t have the capital to fulfill it. So, after a lot of head-scratching, she decided to refer the customer to her supplier (the only other seller she knew of). Ultimately, she liquidated the business because she felt in over her head.
Now, when you know about business credit, you can have an entirely different outcome. Here’s an example of a similar problem with a happier ending:
One of my original coaching clients, that I met at the first speaking event, is a man named Greg Dashkin. Greg lives in New Jersey where I live and was running a marketing business when we met. He sold t-shirts, pens, and other swag to small and large companies. And, he was making money at his business.
But, when he would get a $20K order, he couldn’t fulfill it due to lack of capital and he would have to refer sales to his competitors. He was missing out on a lot of potential revenue and was constantly stuck. Many times, this exact problem causes potentially profitable businesses to shut down.
So, after hearing Greg’s problem, the event host told him to talk to me. He told him that I had something that could change his business. Greg and I started working together and he got $100K in credit pretty quickly, which solved his problem.
And, he was one of the most appreciative entrepreneurs I’ve ever worked with. To this day, we still talk, we still work together, and he still encourages me to keep spreading the message.
Furthermore, you don’t have to be stuck to leverage business credit for growth. Some entrepreneurs just want to scale faster.
For example, I work with an Amazon seller named Scott. When he first came to me for coaching, he was pretty successful, earning about $30K per month. In eCommerce, the margins are about 20%. And, once you know how to sell a 10-cent hat for $5, it’s easy to scale.
But, if you rely on cash flow to invest back into your business, growth is slow. But, after Scott realized how to obtain credit for his business, his sales jumped from $30K to $130K. When you have the capital to invest in more products, you can cross the six-figure income threshold.
Business Lines of Credit vs Angel Investing or Venture Capital
In full disclosure, I’ve never worked with Angel Investors or Venture Capitalists to fund my business. But, I did work in a business incubator office. So, I networked and had friendships with local venture capitalists (VCs) in New Jersey. And, I really like their system.
If you’ve ever watched Shark Tank, you’ve seen how innovative entrepreneurs try to pitch their ideas to highly successful business investors. That’s precisely how VC works. There’s nothing wrong with this system (plus, who wouldn’t want to work with Mark Cuban?). When you work with a VC, you have a mentor who builds you up and gives you funding.
But, there’s a catch — you also have to give up equity in your business when you work with a VC or angel investor. Ultimately, an investor wants a portion of your profits. Plus, most of the time, they push you to sell in the end. And, that’s not what I have ever wanted.
So, instead of giving up equity in your company, I like the idea of learning to obtain the same amount of funding and maintaining full control over your operations.
And, there’s a myth that you can’t use credit everywhere. It’s actually extremely easy to convert credit cards into cash or a check. So, In place of Angel Investing or VC, I prefer business credit cards or business lines of credit. When I first started obtaining credit, I leveraged big banks like Chase and Bank of America.
Then, I realized that I preferred to work with local community banks and credit unions. I elect for smaller banks because the underwriting for national banks is extremely strict. And, if you don’t fit inside a set box, it can be more difficult to obtain credit.
On the other hand, when you work with a portfolio lender (which means the institution lends its own money) or a credit union, the underwriting is done in-house. So, the requirements are more flexible and, if you have someone at a bank who can vouch for you, people are more willing to work with you.
Recommended Reading:
- Should You Open a Navy Federal Credit Union Business Account?
- PNC Bank Business Credit Card Review & Comparison
The Basics of Business Credit for Absolute Beginners
When I speak to business owners and I start talking to them about business credit, one of the first things I tell them is that they need to have a good business credit score. And, many of them don’t know that exists. Furthermore, some of them have existing business credit scores that they are unaware of.
So, before you can implement any of the advice you read here, you need to understand your business credit profile. There are three bureaus that monitor business credit:
- Experian Business
- Equifax Business
- Dun and Bradstreet (D&B)
So, as with your personal credit score, your business will have varying scores from different bureaus. The DUNS number from D&B is a little different from the scores Experian and Equifax Business use to classify business credit. And, one of the first action steps to take is to register for a business credit monitoring account.
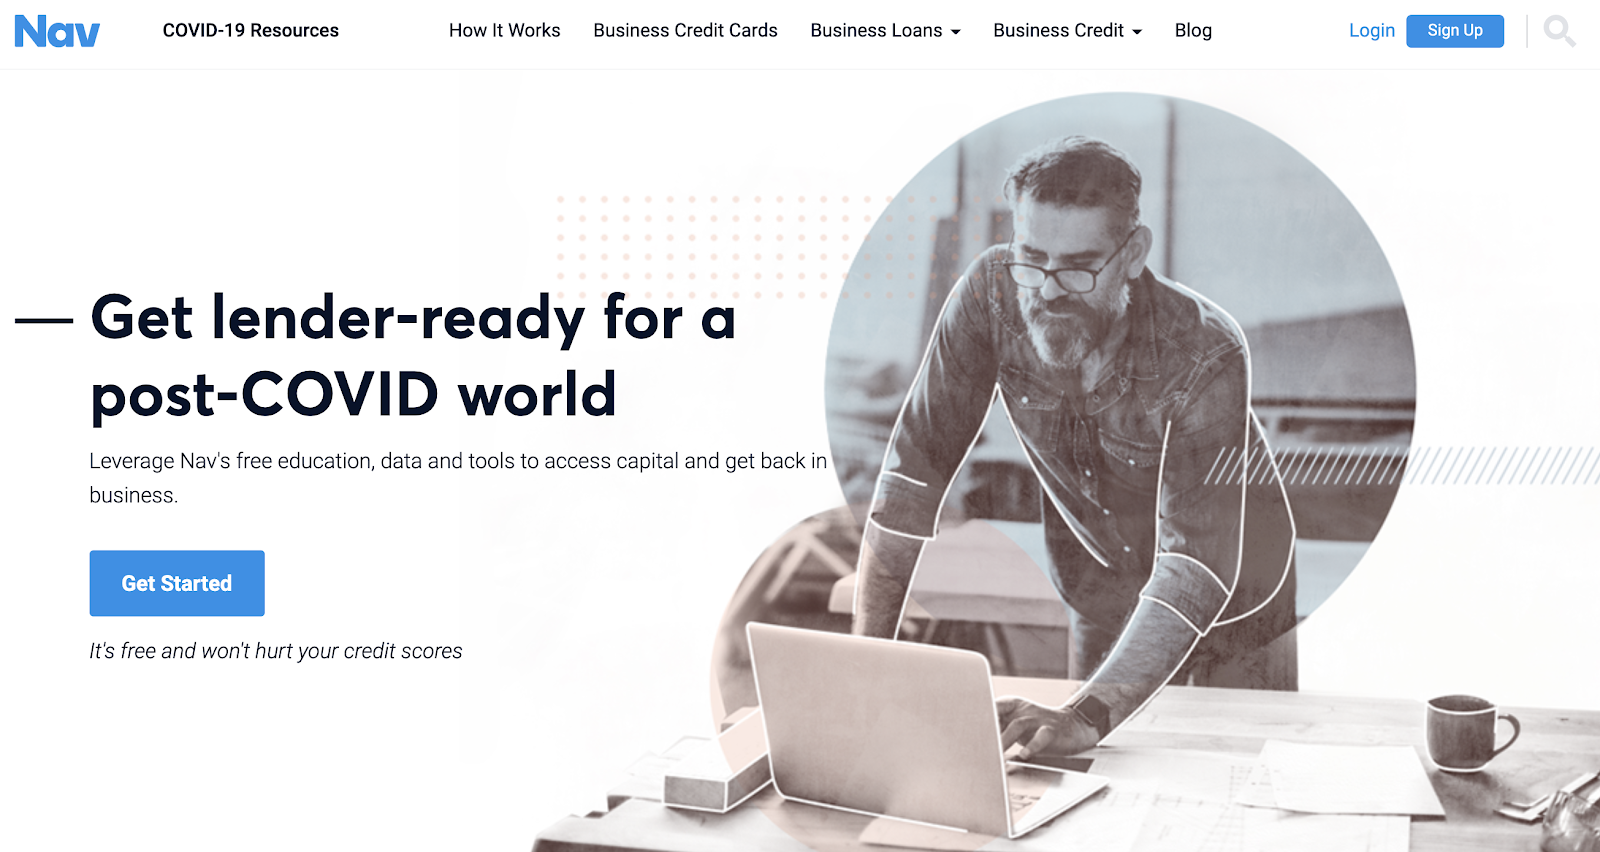
Nav is a business credit monitoring platform that packs a punch. There are three reasons you need to register for an account.
- You can scan your report for inaccuracies and clean up anything negative.
- The platform will give you feedback about the areas you need to improve to boost your score. You can use this feedback to stay informed as you build your credit profile.
- For a monthly fee, you can upgrade your account and enroll in “Loan Builder,” where the company reports to credit bureaus that you are paying on-time each month. So, you get a better credit tracking service with helpful tools and simultaneously increase your business credit score.
Having a good credit score is not the entire process, but it is a fundamental part of the system. Without this, the rest of what you learn here is useless.
So, if you don’t already have one, go sign up for a Nav account right now. Then, read on to dive deeper.
The Greatest Business Credit Obstacles You’ll Face
When you start at the bottom of the mountain learning about business credit, you can’t see every obstacle you’ll face before you’re able to stand at the peak and look down. But, if you’re told what to expect, you can better prepare yourself.
There are a couple of hurdles that arise at financial institutions every few months or once per quarter.
- Financial programs change
- Bank employees leave
First, for example, if you’ve been in business for a couple of years and you’re profitable, a bank might extend a “no-doc” business line of credit one quarter. With a no-doc, no financial statements are required. And, you may be able to get a no doc for up to $100K. But, if things change within the lending industry or the bank’s own financials, that program might not be offered later.
So, this is not a ‘set it and forget it’ system. It’s a living, breathing organism. If you place a tent in the woods, you can’t just waltz back to the forest months later and expect it to be there — it could easily be taken or destroyed by weather or wildlife. Business lending is the same.
Second, your contacts at the bank might leave. Sometimes they will tell you and sometimes they won’t. In some cases, these people move to other banks, and in others, you won’t know. So, once you have a rapport with someone, if you don’t keep their LinkedIn profile or personal cell phone number, you may end up needing to start a brand new relationship.
So, keep your finger on the pulse to monitor the mood of the banks and maintain close relationships within them. That’s why our account managers are always networking with banks to find new programs and stay up-to-date with changing environments with hundreds of contacts. And, this is why some of our long-time clients come back every few years for more coaching.
While these ever-changing ecosystems involve quite a bit of effort, take it from me, the view from the summit is glorious.
The Key to Unlock Your Business Credit Potential
When you want to overcome the challenges above, you need to have the right mindset. So, if you only ever listen to one piece of advice about business credit, let it be this: build rapport with the right people.
While this sounds simple in theory, this tip needs to be taken seriously. Rapport and relationships are the trade secret that most financial gurus don’t want to explain to you. This is probably because they always want to be the best. But, I don’t feel like I’m doing my job unless my clients and students can master the concepts I share.
For example, after learning our approach to obtaining business credit, one of our coaching clients drove from New Jersey to upstate New York to Key Bank, which used to be called First Niagara (now KeyBank). In just one day, he came home with a line of credit for each of his two businesses. He got $50K for each, totaling $100K.
Discover the "3-Step System" to Get You Significant Business Credit (Without Having to Show Any of Your Financials). So that you can increase your cash flow, have true freedom and peace of mind!
So, without my help, understanding the processes and techniques he had learned from Business Credit Workshop, and how to network and build rapport, he went out on his own and had successful results. He then shared his new contact with me. After that, we were able to help many future coaching clients obtain substantial lines of credit from Key Bank because we then had someone within the institution who knows us, likes us, and trusts us.
Still, I have to do my job of filtering out businesses and placing them with the most well-matched banks and lenders. And, I help entrepreneurs become qualified before introducing them to our contacts. But, Greg’s situation was satisfying because I felt like he made it out of the workshop with mastery over the principles we teach.
And, anyone can do the same thing once they understand rapport in professional relationships. But, like in Greg’s case, some of them come back anyway because they know we have account managers dedicated to networking with banks to keep our database up-to-date — and they don’t always want to do the work on their own.
To build rapport, one actionable takeaway is to call the bank or email even when you don’t need anything from them. You want to check-in from time to time to time and treat bankers like friends. Because when bankers or brokers know you, like you, and trust you, they will work with you and with underwriters to make things happen.
An advanced hack (that I learned from my wife) is to keep track of what’s going on in peoples’ lives. Take notes. With modern technology, you can use a CRM or helpdesk platform to record information about people. But, as an individual or small business owner, you can simply write things down in your day planner.
For example, if you know somebody is having a baby, write that down. Then, when you call back, you can ask them how the baby is doing. Of course, people love it when you listen to them and pay attention to what’s going on in their lives. And, while you may not have considered this important in the realm of credit, it most certainly is.
When I started my real estate investment business, I went to my local real estate investment club and made friends with the owner because he was successful. And, six months after I met him, I started asking questions to pick his brain. Try to think of the business credit journey as a lifelong professional relationship with a bank or a person. After that, other pieces of the puzzle fall into place.
So, make friends with the person who gets the approvals at the bank. And, here’s how you can do that.
- Network with the banks
- Build rapport with decision-makers
- Ask what goes into an approval
- Listen to the answer
- Implement your friend’s advice
To get credit cards, your best friends don’t have to be bankers, but it will help if you get out to some Chamber of Commerce meetings and make meaningful connections. Yes, the meetings can be kinda boring, but everyone is there to network and build their own professional networks. Invite someone to dinner or a drink and try to establish a new friendship.
Another great channel for networking, especially today with social distancing in place across the globe, is LinkedIn. Start learning how to leverage the platform to your advantage and see if there’s anything you can do to help someone that would be a beneficial professional connection to have, namely credit union or bank employees.
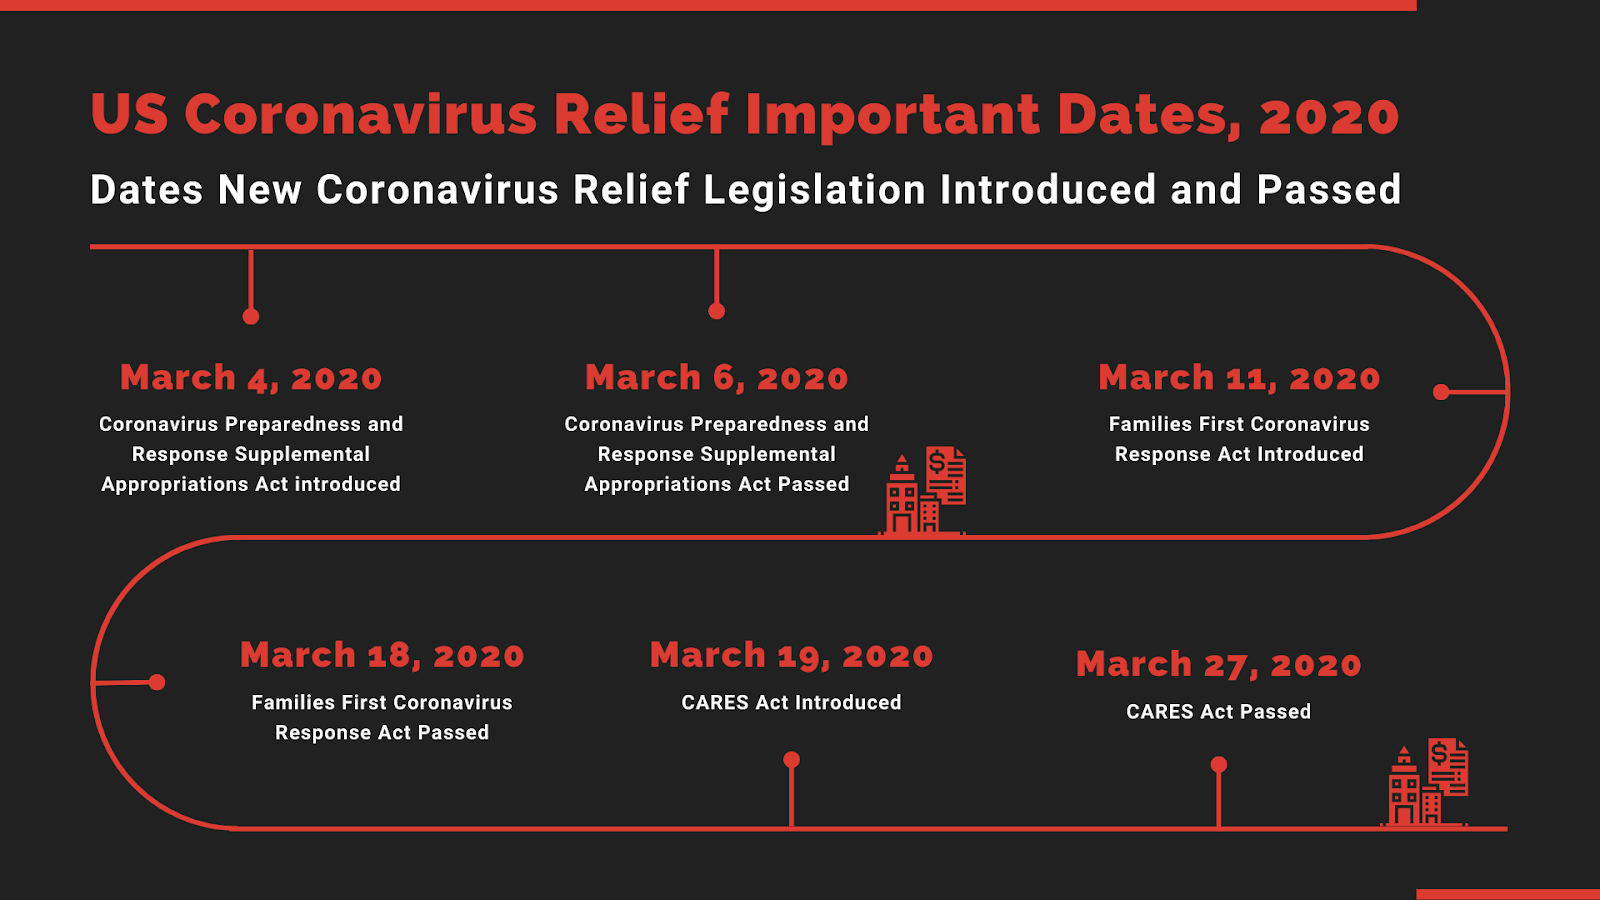
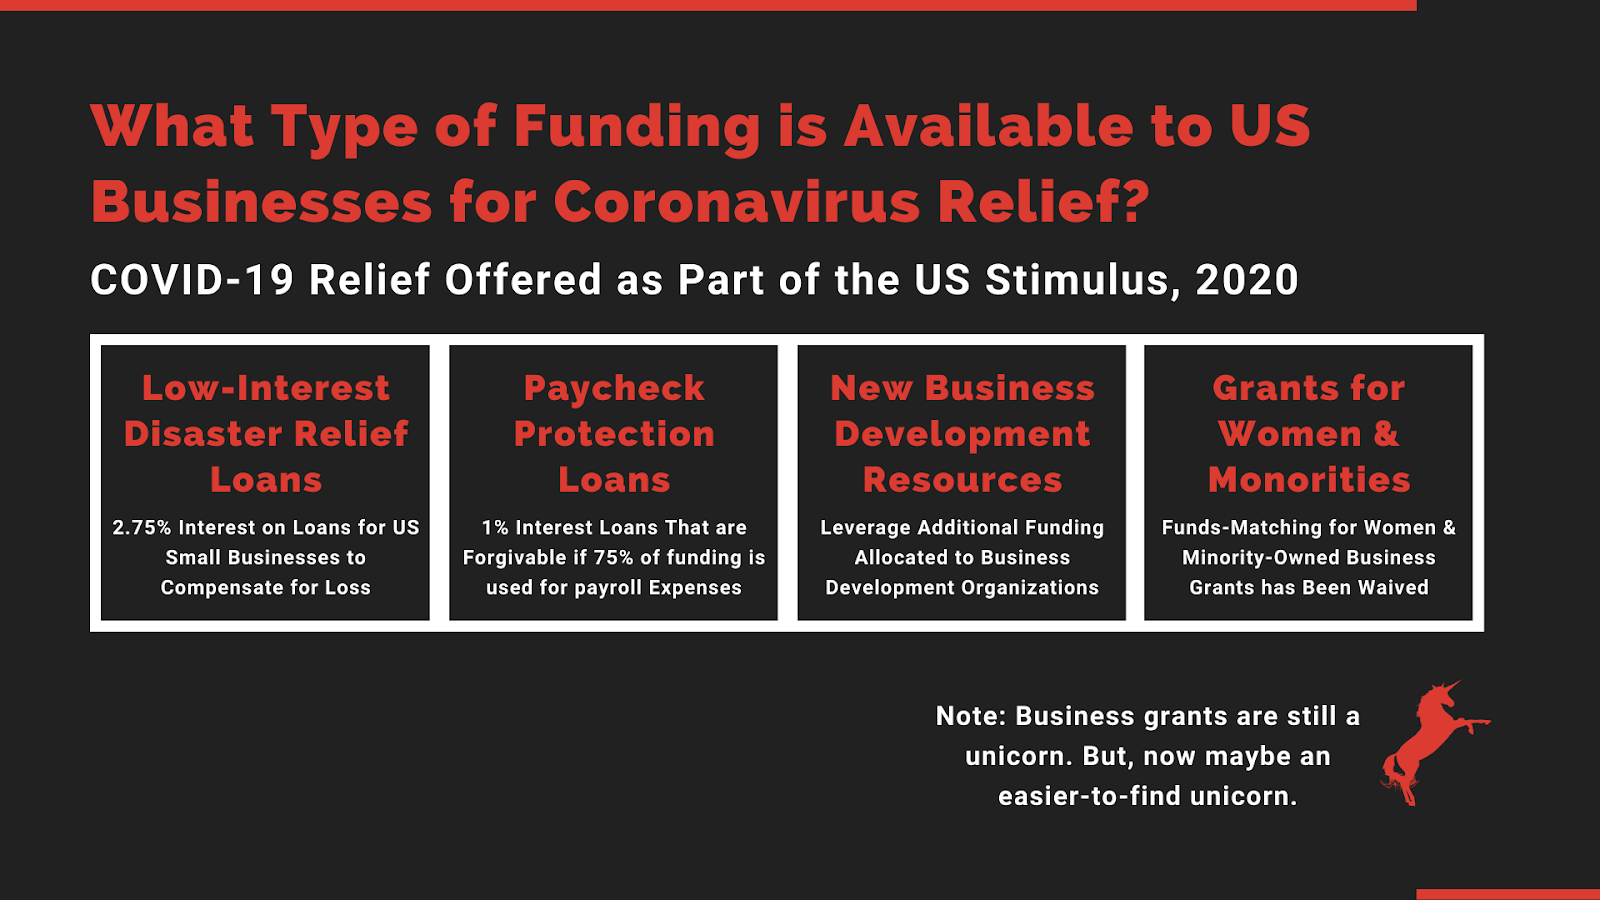
This knowledge will come in handy especially in times like right now when we’re experiencing major economic change. Because of COVID-19 and the PPP program, business owners are scrambling to get their low-interest, forgivable loans to stay afloat. So, banks are working unprecedented hours to service their customers.
Traditionally, bankers work from 9:00 to 5:00 Monday through Friday. Presently, they’re in the office after hours, weekends, and even on Easter to process 30K applications. Still, I’m getting personal emails and texts from bankers along the lines of, “Hey, Joe. PPP money may run out soon, so let’s get you taken care of.” It’s a small effort that brings a big result, in this case someone at the bank looking out for me.
Final Summary
Now, if you are ready to take the next step to revamp your business and lifestyle, I have some homework for you to start today:
- Sign up for an account with NAV.
- Check out your business credit score and create a plan to clean up anything that makes your business high risk for lenders.
- Join at least one new group where bankers hang out.
- Introduce yourself to someone who works at a community bank or credit union in your area.
And, if you want to keep learning and improving your situation, make sure you check out our recent client case study here.