• Home
  • Free Funding Guide
  • What We Offer
    • Products
    • Services
    • Free Guide
  • About Us
  • Contact
  • Sign Up

  • Ask Joe Any Question!
  • Business Credit Cards
  • Business Line of Credit
  • Topics

Is Dell Business Credit Worth Your Time?

February 10, 2020 By Joe

Is Dell Business Credit Worth Your Time?

When you’re a Dell-lover looking to build your credit profile and in need of a new computer, in-house financing is a natural place to turn. You can get upfront funding for your new equipment and potentially boost your scores. But, is the program worth your time? Read this Dell business credit review, and answer that question yourself. 

First of all, What is Dell Business Credit? 

Dell business credit is one of three business financing packages offered by Dell to fund the purchase of its PCs, electronics, and accessories. The business credit program is controlled by WebBank, who also partners with companies like Avant, Lending Club, Fingerhut, and PayPal to offer financial services to these brands’ existing customers.   
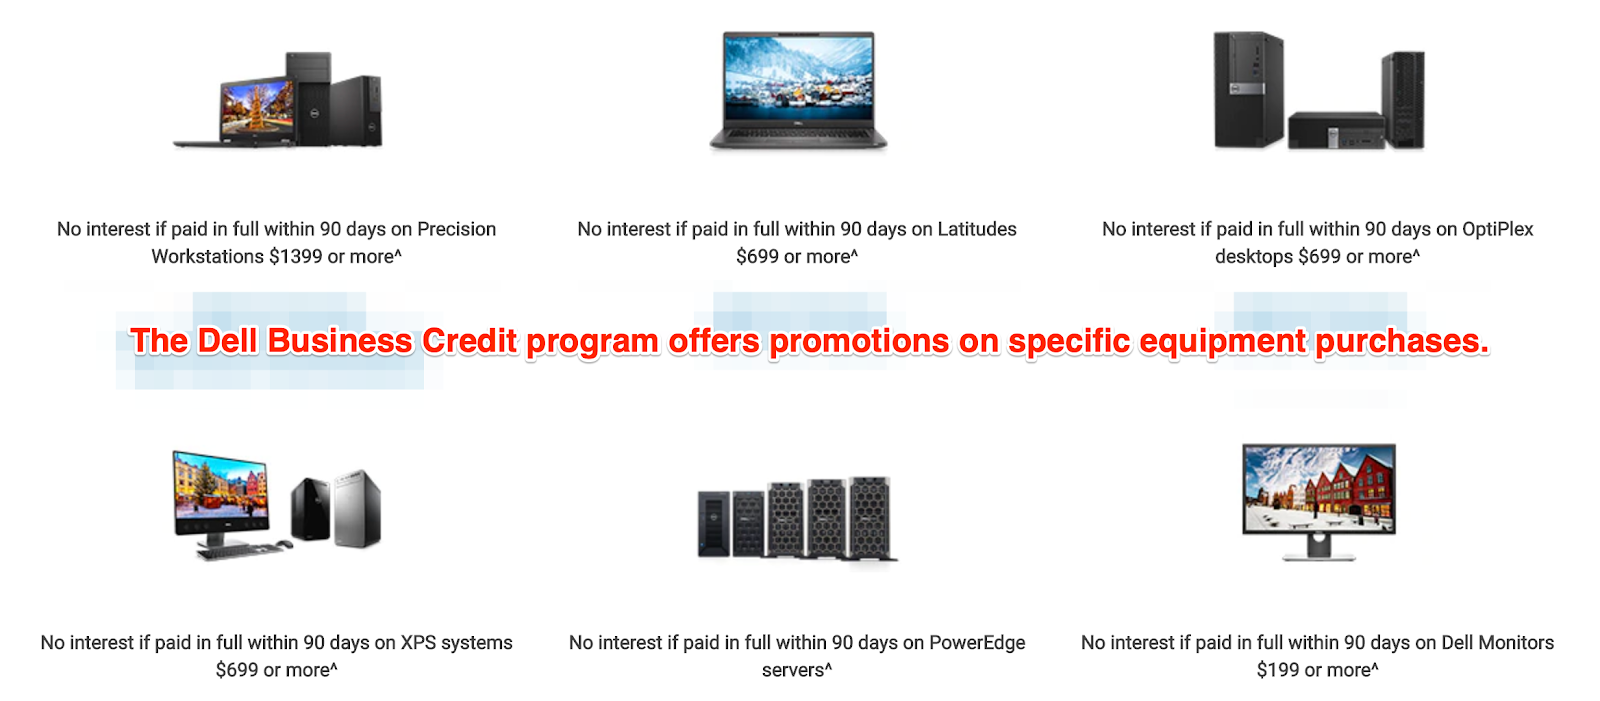
Dell Business Credit Offers Promotional Pricing on Specific Equipment

Financing can only be used to purchase directly through Dell and the brand offers promotions on specific equipment. 90-day, 0% interest is a popular example. 

The three financing options offered by Dell are: 

  • PC as a service
  • Dell business credit
  • Lease options

In addition, Dell offers custom solutions for enterprise solutions for medium and large businesses. So, larger companies can reach out with their needs to come up with packages under the pretense of greater savings on bigger orders. 

At first glance, the program looks fine. Yet, Dell’s business financing reviews online seem to deliver more than the usual amount of complaints. So, I decided to dig into the program and share unbiased facts. After reading through, you should be able to decide if the program is worth your time. 

Next, How Difficult is it to Get Dell Business Credit and Will You Qualify? 

Borrowers who apply for Dell business credit are often surprised by the approval process and credit amount. For example, one business applicant who made $62K in purchases from Dell the previous month was offered a $5K tradeline (MyFico). The amount of funding led this user to the conclusion that WebBank, the actual lender, doesn’t factor customer metrics within the Dell company into its decision. 

While this seems a bit wonky and impersonal, Dell did allegedly finance another customer for the same $5K business credit with no social security number and after locking their reports (MyFico). This possibility is appealing because it means that you could potentially qualify for a tradeline without sharing your personal credit report and conceivably start building business credit.

So, if WebBank will qualify an applicant for $5K in credit with no credit history, how easy is it to get a Dell business credit card? 

According to WallettHub, WebBank’s cards, including the Dell Preferred Account (which is not the same as the business credit card) are subject to approval with personal credit scores of 640 and up. So, while all situations are different, it’s a fair assumption to make that it is pretty easy to qualify. 

And, What Business Credit Report Does Dell Pull? 

If you have a fair business credit history with one bureau and bad credit on another, you need to make sure your lender will look at the report with the more favorable score. So, which report will Dell/WebBank peek in at when qualifying you for approval? According to multiple borrowers, you’ll see a hard pull on your Experian report when you apply for a Dell business account. 

Then, Why all the Poor Reviews? 

Let’s take a look at the common complaints about this card from existing borrowers. 

  • High interest
  • Poor customer service
  • High interest
  • High interest
  • Lack of payment technology
  • High interest

Many of Dell’s borrowers complain about the fact that they still owe the full amount of their equipment after making payments, sometimes for years. And, they express that there was no explanation that if their account wasn’t paid in full before the promotional no-interest period, that they would be charged the full interest amount. 

Yes, the above is frustrating, but these payment conditions were in the terms and conditions laid out by Dell and WebBank. It’s just that the borrowers didn’t see or understand them. 

You should always expect to pay interest on purchases made during a promotional 0% interest financing period if your balance is not paid in full before the end of the period. 

So, is Dell Business Credit Worth Your Time? 

If you need Dell equipment, should you go straight to the source for funding? — This is the wrong question. Instead, ask yourself the following: 

  • What are Dell’s current business credit promotions? 
  • If I leverage these promotions, can I save money on the equipment I need (the promotions often offer 15% price discounts on products)? 
  • If I leverage these promotions, will I be able to pay off my card within the promotional period to prevent future interest spikes? 

If you need Dell equipment and you can afford to pay off your purchase within 90-days, there’s no reason not to take advantage of the financial services. In fact, you could see a bump in your credit scores for on-time payments. 

Related Answers

Does Dell have financing?

Yes, Dell offers several consumer and business financing solutions through WebBank for the purchase of its equipment and accessories. 

What credit score is needed for Dell financing?

According to WalletHub, WebBank, who controls Dell’s financing options, qualifies borrowers with credit scores of 640+

What business credit report does Dell pull?

When applying for Dell business credit, your Experian report will be pulled. 

Does Dell finance bad credit?

According to many borrowers, Dell credit is fairly easy to qualify for, but typically, lenders do not finance anyone with bad credit. 

Can I buy a laptop and pay monthly?

Yes! You can leverage financing directly through most laptop manufacturers as tradelines or use alternative funding options to make monthly payments on a new laptop. 

Can I lease a laptop?

Yes! Most major laptop manufacturers have lease options for businesses and consumers. Dell’s progressive leasing is one example. 

Final Thoughts

Dell business credit offers no major rewards — this type of financing doesn’t allow you to generate points, airline miles, or cash awards. But, for businesses early in the credit building journey, if leveraged properly, Dell’s in-house financing can be helpful. Learn how to make the most of your credit profile. Start by understanding how to use 30-day net vendors to boost your business credit score.

Should You Open a Navy Federal Credit Union Business Account?

February 4, 2020 By Joe

Navy Federal Credit Union Review

Navy Federal Credit Union Business Solutions Review

If you’ve been in the military or you have a family member or friend who has, you’ve presumably heard of Navy Federal Credit Union. And, you probably already know that it’s a great organization. But, did you know that you don’t have to be active in the military to become a member? And, did you know you can open a business account to leverage the perks for your company?

It’s true. There are quite a few benefits your business can take advantage of with Navy Federal. In this Navy Federal business account review, you’ll find a summary of them. Read on to decide if a Business Solutions account is right for you. 

What is the Navy Federal Credit Union? 

Navy Federal Credit Union is an NCUA-insured financial institution exclusively operated for the military and their families. To qualify for membership, you or one of your family or household members must have ties to the armed forces, DoD, or National Guard.

And, What are the Benefits of a Navy Federal Membership? 

The institution offers powerful financial products and services with low rates, fees, and charges as well as convenient banking and home buying. Members can take advantage of exclusive special offers and discounts from various partners. 

Here are the Navy Federal Credit Union’s exclusive member partners and programs. 

  • Visa – Access discounts of up to 15% for card use with select retailers.
  • Geico – Leverage member discounts on auto insurance. 
  • RealtyPlus – Receive $4K to $8K cashback on a home purchase. 
  • Enterprise Rent-A-Car – Get elite member discounts off everyday low rates.
  • Hertz Rent-A-Car – Save up to 20% off car rentals. 
  • Auto Buying Program – Experience a hassle-free vehicle purchase process and exclusive savings.

Furthermore, Navy Federal is a portfolio lender, which means that they lend their own money. Because they’ve cut out the middle man, they are able to offer lower rates on loans and lines of credit than most lenders. So, this is a valuable company for a small business in need of banking or lending to work with. 

What Financial Services Can You Access with a Navy Federal Business Account? 

Business Solutions by Navy Federal is centered on delivering the most beneficial financial tools and resources available to small business members. What products and services can you leverage to help you meet your company goals? 

The program for qualified members with military ties offers several financial services for small businesses including loans, lines of credit, checking, and savings accounts. Learn more about each of them below. 

Business Loans

Navy Federal Credit Union business loans can help you improve business cash flow. Leverage real estate, vehicle, and term loans with low rates and fees. 

Real estate loans taken from the credit union can help you purchase residential rental properties, commercial real estate, multi-family dwellings, or pay for a property renovation. Pay for a new purchase, refinance, or remodel an existing building. 

Loan to value on real estate loans through Navy Federal ranges from 65% (remodel) to 80% (new purchase). There are fixed and variable rate options. And, you’ll experience no prepayment penalties. 

Vehicle and term loans give you access to permanent working capital, equipment, company cars, heavy-duty trucks, and more. Purchase or refinance your auto or equipment. Loan to value on these loans is 75% and there are no prepayment penalties. 

Business Lines of Credit

Navy Federal business credit card can elevate your business’ purchasing power. Apply for a Visa™ or MasterCard™ and pay an APR as low as the prime rate +5.9% with no annual fee. Earn Business Rewards of one point per $1 spent and redeem them for airline tickets and more. 

Navy Federal Credit Union Business Solutions Credit Cards

Here’s a taste of what you can earn through Navy Federal’s Business Rewards card.

  • Redeem 5K points for a $50 BestBuy gift card. 
  • Redeem 10K points for $100 cashback. 
  • Redeem 15K points for a $150 round-trip airline ticket. 
  • Redeem 50K points for a $500 round-trip airline ticket. 

Plus, Navy Federal Credit Union business lines of credit come with no foreign transaction fees or earning cap. The cards are great for business travel expenses. 

Business Checking and Savings

Navy Federal Credit union business checking and accounts provide essential financial building blocks for your business. The best part is that all accounts earn dividends. 

Business checking accounts include the first 30 transactions for free. Each transaction thereafter will cost 25 cents. There is no monthly service fee. These accounts are recommended for new businesses and those with limited cash flow activity. 

Business Plus checking accounts include the first 50 transactions for free. And, like the standard business checking account, each transaction thereafter will cost 25 cents. There is an $8 monthly service fee. These accounts are recommended for growing businesses with steady banking activity. 

Business Premium checking accounts include the first 100 transactions for free. And, each transaction thereafter, as with the standard and Business Plus accounts, will cost 25 cents. The monthly service fee will range from $0 to $20. These accounts are recommended for mature businesses with large transaction volumes and high deposit values. 

Business savings accounts come in three options at Navy Federal. 

  1. Money market savings accounts
  2. Jumbo money market savings accounts
  3. Certificates

Minimum deposits range from $100 to $100K. Market savings accounts come with no term restrictions. And, these accounts will typically earn more than a traditional savings account. 

How do You Open a Navy Federal Business Solutions Account? 

If you think you meet the Navy Federal business account requirements (LLC, Sole Proprietors, and Corporations), here are the steps to take to leverage Business Solutions. 

  1. Check your eligibility. If you are a military service member, Department of Defense civilian, or spouse, parent, grandparent, sibling, child, or grandchild of one, you may qualify for Navy Federal membership. 
  2. Become a Navy Federal Credit Union member. Apply for membership online through the organization’s website. Or, if you are not the service member, you will need to go into a branch to sign up. 
  3. Enroll in digital banking. Once your application has been approved, enroll in personal digital banking. 
  4. Complete a Navy Federal Credit Union business account application. Fill out the appropriate documents and submit them online or call 1-877-418-1462 to apply over the phone. 

Once you’ve been approved by the organization for a business account, you can access all of the services listed above. 

Related Answers: 

Can a business join a credit union?

Yes. Many credit unions provide financial solutions for both personal and business members. 

Can you join Navy Federal if you were not in the military?

Yes. Navy Federal was designed for veterans and active military, but you can apply for a membership if you have direct ties to someone who has served.   

What do I need to open a bank account with Navy Federal?

To open a bank account with Navy Federal, you must become a Navy Federal Credit Union Member. To qualify, you or someone in your household must have ties to the military. 

Does Navy Federal give small business loans?

Yes. Navy Federal Credit Union has several types of small business loans and lines of credit to extend to Business Solutions account holders. 

Does Navy Federal offer business credit cards?

Yes. Navy Federal Credit Union has several types of credit lines and small business loans to extend to Business Solutions account holders. 

Does Navy Federal check your credit?

Yes. When you apply for a line of credit or loan through Navy Federal, like most lenders, they will run a credit check. The institution may sometimes extend a credit line to someone with little to no credit history. 

Does Navy Federal have a minimum balance?

Yes. Navy Federal has a minimum $5 savings balance for members with a checking account, IRA, ESA, or certificate and $50 minimum balance for members with a standalone savings account. 

Does Navy Federal have Zelle?

Yes. Navy Federal members have free access to Zelle, a way to easily send money between US banking accounts within minutes. 

How do you build business credit?

To build business credit, you must apply for and make responsible payments on lines of credit extended to your business using your EIN or DUNS™ number. Learn more about credit for business via Business Credit Workshop.  

Final Thoughts

Navy Federal is a fantastic financial institution that doesn’t cost an arm and a leg to leverage. When you need to leverage working capital solutions or you want to open an account to build your business credit, this is an excellent channel to do so, if you can qualify. For more credit boosting advice, sign up for our free secrets to get $100K in business credit in 30 days. 

Can You Pay a Mortgage with a Credit Card? The Answer is… Complicated

January 29, 2020 By Joe

Can You Pay a Mortgage with a Credit Card? The Answer is... Complicated

Are you looking for a way to increase your credit spending and meet the sign-up bonus your new credit card issuer has offered? Or, perhaps your mortgage is due and you won’t get paid in time to pay it in full. Either way, you’re exploring your options. You’re asking, “Can I pay my mortgage with a credit card?” 

In short, the answer is ‘yes.’ However, your lender isn’t going to make it easy for you. So, let’s explore some of your options for paying a mortgage with a credit card.

We’ll look at the advantages and disadvantages of each option. After that, we’ll explore solutions to some of the problems that might arise so you can make an educated decision about whether or not to take this route. 

First, Why Would You Want to Pay Your Mortgage with Your Credit? Isn’t This a Bad Idea? 

In most cases, paying on any kind of loan with a credit card is a money-suck. Most credit cards’ annual interest rates run around 25%. Why would you pay that when you don’t have to? 

Plus, using a credit card rather than a check or ACH transfer to your lender requires more steps. Mortgage lenders do not traditionally accept credit cards as a payment option, so you have to find workarounds. 

However, there are some situations when you would want to use a credit card to pay your mortgage. 

  • Your property is facing foreclosure by your lender because of missed payments on your mortgage, and a credit card is your only funding option. 
  • You’re temporarily low on cash and want to avoid a late payment fee that is higher than the interest you would pay by using a credit card. 
  • You want to hang onto your cash because it’s accruing more interest in an investment fund than you would pay in credit card transaction fees for the cost of your mortgage (this is remarkably rare). 
  • You need to spend more in order to meet the sign-up bonus on your new credit card to collect points or other rewards. 

Unless you plan to pay the card down right away or you’re in a 0% APR introductory period, be wary. Using your credit card to pay your mortgage can come at a cost. But, if leveraged properly, you can come out ahead. 

2 Systems to Pay a Mortgage with a Credit Card

We’ve looked at methods to pay rent with a credit card. There, we explored ways to get your credit card balance to your property manager for rent payment. Rent is a bit simpler because there are platforms created just for property managers to help renters build credit (usually, before they are ready to buy homes).  

Now, what are the systems you can leverage to pay your mortgage on a credit card? 

  1. Take a cash advance from your card issuer and use it to pay your mortgage. 
  2. Use an online payment system to pay your mortgage with a credit card. 

Each method comes at a cost, so make sure you understand the advantages of each method before you proceed. 

The Pros & Cons of a Credit Card Cash Advance to Pay a Mortgage

A cash advance on a credit card is quick, convenient, and simple. All you need to do is contact your credit card issuer and request the advance. If you have a pin set up, you can simply withdraw funds from an ATM. So, you can access your funds immediately. 

Credit Card Cash Advance Advantages Summary:

  • Immediate access to funds
  • Convenient request methods

But, a credit card cash advance comes at a significant cost. According to CreditCards.com, average transaction fees for a cash advance are 5% and the average APR is 25%. Plus, APR will start to accrue instantly. These costs in addition to ATM fees are pretty hefty. 

For a $1,000 mortgage payment, you’ll pay $1,050 plus ATM fees immediately. And, for a $2,500 mortgage payment, it will cost $2,625 plus ATM fees upfront. Then, if you don’t pay your card off immediately, interest will pile up. So, if you take out a cash advance, you’ll pay more than necessary to access your funds.

Furthermore, a cash advance will not count toward spending to earn introductory points or rewards from your card issuer. So, if your reasoning for paying your mortgage with a credit card is to earn bonus points on your card, this isn’t the way to do it. 

Credit Card Cash Advance Disadvantages Summary:

  • Average transaction fees of 5%
  • Average instantly-accruing interest of 25%
  • Unnecessarily high costs
  • No credit card bonus points or rewards earned

The Pros & Cons of an Online Payment System to Pay a Mortgage

An online payment service like Plastiq will enable you to pay your mortgage with a credit card. Currently, the average transaction fee for using their service is 2.5%, about half the cost of a cash advance. So, the cost of one of these systems is low. 

Pay Your Mortgage With a Credit Card Plastiq

Be sure to double-check the fees for each online payment service before you opt to use one of them as the terms and conditions are subject to change at any time. 

In addition, you can use most major credit cards to pay nearly any bill. For added convenience, Plastiq accepts major credit cards for mortgage payments. Currently, this includes MasterCard, Discover, JCB, and Diners Club credit cards. 

Furthermore, you don’t have to get pre-approval from your lender. Plastiq will send them an ACH transfer, direct deposit, or a check on your behalf in exchange for a small percentage of the transaction. Pay one-time, manually as needed, or set up automatic payments. This option gives you a ton of freedom. 

Online Payment Service Advantages Summary:

  • Low transaction fees (2.5%)
  • Can conveniently pay multiple bills that do not accept credit card payments
  • Use MasterCard, Discover, JCB, and Diners Club credit cards to pay mortgage
  • Experience freedom in your options 

But, because of restrictions in place by the credit card companies, you cannot use Visa or American Express cards to pay a mortgage with Plastiq (though, you can pay other bills with these cards). So, if you’re looking to boost the points on one of these cards, think again — they just don’t allow it. 

And, you have to consider the cost. Is 2.5% of your mortgage payment transaction actually worth the bonus points you will receive? The answer to this will depend on your credit card and rewards program. 

Online Payment Service Disadvantages Summary: 

  • You can not use Visa or American Express credit cards to pay your mortgage, under any circumstances.
  • The cost of transaction fees may not outweigh the number of bonus points that you can earn. 

Related Answers:

Can you use a credit card to pay your mortgage?

Yes. With certain online payment services, you can convert credit card funds into check, wire transfer, or ACH transfer funds to pay your mortgage, but there are stipulations. For example, there will always be a transaction fee.

Can you buy a house on a credit card?

Yes. You can use online payment services to convert your credit into check, wire transfer, or ACH transfer to buy a house. But, again, there are stipulations.

Do real estate agents accept credit cards?

Yes. Like any other independent service providers, real estate agents can enable their clients to make payments with a credit card. However, not all real estate agents will accept credit. It is the decision of each agent to accept cards or not.

Can you pay closing costs with a credit card?

Technically, yes. You can use certain online payment services to convert your credit into a check, wire transfer, or ACH transfer to pay the closing costs on a mortgage. But, as with other non-traditional payments you might make with a card, there are stipulations.

What does Doxo mean?

Doxo is the name of a financial app that allows users to pay their bills online, as long as the providers are part of the Doxo network.

Final Thoughts

So, you can’t hack your introductory rewards points on a Visa or American Express card to pay your mortgage. But, you can enlist an online payment service to boost your points with on a MasterCard, Discover, JCB, or Diners Club card for a low fee. Or, if you’re in a pinch, you can get a cash advance from your card issuer to pay your mortgage. 

As an added perk, if you pay your card as agreed and keep your balance within a healthy ratio, paying a mortgage with a credit card can help you boost your credit score. To learn more credit building tips, sign up for our free business credit training today.

This is How to Pay Rent with a Credit Card (Home or Business)

January 29, 2020 By Joe

pay rent with credit card

Your rent is almost due, and you’re looking for a way to increase your credit card spending so you can leverage your card’s sign-up bonus. Or, you’re temporarily low on cash, but you’ve got plenty of credit to leverage. So, you’re asking “Can I use a credit card to pay rent?” Here’s your answer: there are ways, but they require further explanation. 

So, here’s everything you need to know to make a rent payment (or multiple rent payments) with a credit card.  First, see a summary of your options. Then, look at the pros and cons of each. After that, learn the answers to some relevant questions so you can decide whether paying with a credit card is the right choice for your situation. 

3 Top Ways to Pay Rent With a Credit Card

You know you can make rent payments with your credit card. But, what options do you actually have? Here are three methods for getting commercial or residential rent paid with your credit. 

  1. Request a cash advance from your card issuer and pay rent with the money.
  2. Introduce your landlord to a service that enables them to accept credit cards for rent payments from tenants. 
  3. Use an online payment service like Plastiq or CardUp. 

Each of the above options can work in the right situation. So, learn more about each method so you’re sure to make the right choice. 

If you’re not a renter, but you need a way to utilize your card’s sign up bonus, learn how you can pay a mortgage with a credit card.  

The Ins and Outs of Using a Credit Card to Pay Your Rent 

Now, should you ask your card issuer for a cash advance, convince your landlord to try a new system, or leverage an online payment service? Explore each option below to determine which, if any, is best for you and your situation.

Method #1: Take a Cash Advance From Your Card Issuer to Pay Rent on Your Home and/or Commercial Space

The most obvious, fastest, and simplest way to pay your rent with a credit card is to request a cash advance from your card issuer. Basically, you call your credit card company and request a cash advance in the amount of your rent. Then, the card issuer makes a deposit into your bank account. 

In exchange, you pay the associated fees and your card payment balance instantly increases. After that, you can use your increased bank account balance to pay your rent. Easy, right? 

So, this would typically be the right option when you’re desperate. If you’re short on time, funds, and need to get the rent paid, a cash advance will work. Just be aware that this method will cost you. 

According to CreditCards.com, here are the average costs for a cash advance. 

  • Transaction fees: 5%
  • Interest: 25% 

Also important to note, on an advance, you don’t have a 30-day+ grace period in which interest will start to accrue. Instead, you will begin paying interest immediately. 

The transaction fees alone on a $1,000 cash advance will be around $50. Then, you’ll usually pay even more toward interest, depending on how long you wait to pay it off. 

Furthermore, a cash advance will not typically count toward credit card rewards. So, if you’re paying your rent with a credit card to leverage points, this method won’t help you much at all. 

Will a Credit Card Cash Advance Help Boost Your Credit Score? 

Yes, if you pay your card balance as agreed, a cash advance has the potential to help you increase your credit score. On-time payments can impact your score with all major credit bureaus. And, credit card issuers typically report payment history each month. 

However, especially since other methods cost less, avoid a cash advance on your credit card unless you’re in a pinch. And, pay back the advance as soon as possible to avoid paying more than necessary.

Method #2: Introduce Your Landlord to an Online Rent Payment Service to Enables Them to Accept Credit Cards for Tenant Rent Payments

Many property management companies already allow their renters to pay rent online. So, before you finish learning about this method, are you sure your landlord doesn’t already offer an online payment opportunity? If you are sure, read on — you may be able to show them a new, mutually-beneficial system. 

Recommended: Buildium Property Management Software — An Extensive Review

Which is the Best Online Rent Payment Service? 

There are several modern cloud-hosted property management software options that enable you to pay your rent with a credit card. So, try to get your landlord on-board by introducing them to a new, more convenient option like one of the following.

Which is the Best Online Rent Payment Service?

As you can see from the above chart, this method is much less expensive than taking a cash advance on your credit card. However, you will still pay interest based on the agreement you have with your creditor. 

And, when you pay rent on-time, some platforms like RentTrak and PayYourRent will report your payment activity to credit bureaus. So, not only will you receive a credit boost from paying your credit card on-time; you will also get a separate positive mark on your credit report for paying your rent. So, in some cases, this method has double credit-boosting power. 

Moreover, in most cases using a credit card to pay rent to one of the above companies will count toward your card’s promotional bonus points. Just double-check your card issuer’s promotional terms and conditions to be sure. 

There are a lot of benefits to going this route. The only major hurdle is that you have no control over whether or not your property management company will want to implement this route. So, you’ll have to work out your sales muscles. 

And, if you take this route, theoretically, late rent payments can negatively affect your credit score. You will open a new set of risks along with the rewards. But, as long as you consistently pay your rent on-time, you shouldn’t experience any problems. 

Method #3: Use an Online Payment Service to Pay Rent on Your Home and/or Commercial Space With a Credit Card

Finally, online payment services can be used to pay rent (and nearly any other bills) with a credit card. In exchange for a small fee, these systems make it easy for you to maintain complete control over which bills are paid from which funding sources (i.e. pay your rent with a credit card). 

Online payment services like Plastiq, CardUp, and RadPad invite users to pay bills and buy items with credit cards where cards are not typically accepted. Use your Visa, MasterCard, American Express and other major credit cards to pay your rent using this method. 

Essentially, you connect your credit card to the service as a payment method and the system automates your rent payment using the means that your landlord prefers. Your payment can be sent as a check, wire transfer, or ACH transfer. 

Online Payment Service Comparison 

The following comparison table includes processing fees followed by which cards are accepted by Plastiq, CardUp, and RadPad. 

Plastiq vs CardUp vs RadPad

The only downside to this method is that you will pay a fee in addition to your card’s regular interest charges for each transaction.  If you opt for an online payment service to automate your rent payments, you will only pay a small transaction fee for using the platform. 

So, this can be an excellent option to pay rent with a credit card and simultaneously leverage your card’s sign up bonus and boost your credit score with on-time payments. And, in some cases, the landlord or property manager will opt to cover the transaction fees for their tenants’ convenience. 

Conclusion

To pay your rent with a credit card, you can take out a cash advance, introduce your landlord to a new payment platform, or use an online service. Each method comes with a unique set of advantages and disadvantages. 

For many people, online payment services like Plastiq or CardUp are wonderful options for paying your rent with a credit card. You can leverage these systems with fewer fees than a cash advance. Plus, you won’t have to convince your property management company to make any internal changes to their business processes. 

However, if your main goal is to improve your credit, put in the extra effort and ask your landlord to move to a platform like RentTrak or PayYourRent that enables you to pay rent with your credit card and reports on-time payments to the major credit bureaus. 

For more valuable advice, sign up for our free business credit training today. 

How to Get Approved for Amazon Net 30 Terms (“Pay by Invoice”)

December 21, 2019 By Joe

Amazon Pay by Invoice net 30 account

Net 30 tradelines not only provide an opportunity to buy now and pay later, but also – sometimes – give you a chance to build business credit. Amazon Pay by Invoice offers net 30 terms, which may be just what you’re looking for. 

But, is it worth looking into? And, what do you need to get approved? Here, I’ll cover just that. 

This is what’s in store: 

  • What is Amazon Pay by Invoice?
    • Amazon Company Overview
  • Features & Benefits of Amazon Pay by Invoice
    • Flexible Payment Terms
    • Extended Payment Options with Business Prime
    • Itemized Digital Invoices for Easy Management
    • Credit Limits & Eligibility
    • Credit Reports & Authorization
    • Interest Charges & Costs
  • How to Set Up Pay by Invoice on Amazon Business
  • Frequently Asked Questions
  • Conclusion

Let’s begin! 

What is Amazon Pay by Invoice? 

Amazon net 55 line of credit

Amazon Pay by Invoice, is a payment option for eligible Amazon Business customers that lets you snag what you need and pay the piper later with net 30 terms (this means you have 30 days to settle the bill). It’s a type of Amazon business line of credit, though not an Amazon credit card. 

Pay by Invoice is a friendly IOU setup, freeing up your cash flow and making the whole purchasing process smoother. 

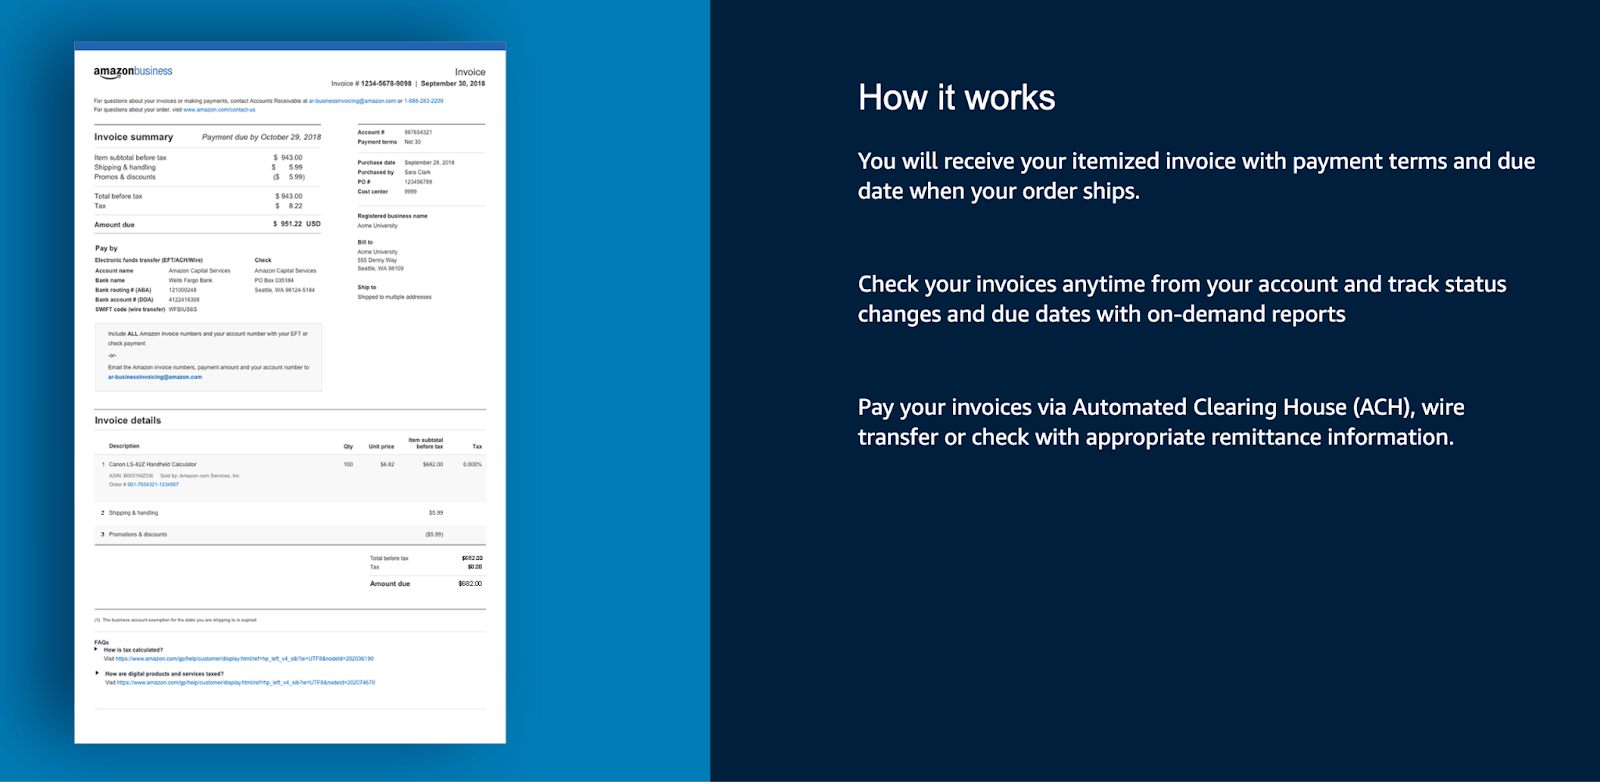
With Pay by Invoice, you get an itemized invoice with details when your order ships, and you can even extend the payment window further if you’re rolling with a Business Prime membership (previously Amazon net 55). 

Just remember, it’s not a free-for-all; there are credit limits, and Amazon might peek at your business credit reports to keep things on the up-and-up. And of course, if you snooze on the payment, there’s a 1.5% monthly interest rate waiting to say hello. 

But overall, it’s a handy way to manage your purchases without emptying your wallet upfront.

You may also like: Amazon Business Prime Credit Card: Full Review +How to Get One 

Amazon Company Overview

Amazon line of credit

Amazon, a powerhouse born as an online bookstore in ’94, has grown into the Godzilla of e-commerce, offering everything from books to gadgets, groceries, and even cloud computing. With Jeff Bezos turning a garage project into a tech empire, Amazon’s reach extends to fast shipping through Prime and innovations like drone deliveries. 

Based in Seattle, Amazon boasts subsidiaries like Xoox for future driverless taxis, Whole Foods, Twitch, and IMDB. 

Led by CEO Andy Jassy since Bezos stepped down in 2021, Amazon’s influence spans various industries – Amazon offers a handful of funding options for consumers and businesses, including credit cards from Chase and American Express that give extra cashback on purchases from Amazon and Whole Foods. 

Now, what can you expect from Amazon Pay by Invoice net 30 terms? 

Recommended: Using 30 Day Net Vendors to Build Your Business Credit Score 

Features & Benefits of Amazon Pay by Invoice 

Pay by Invoice Amazon

Overall, Amazon Pay by Invoice is a handy tool for: 

  • Managing business purchases
  • Offering flexibility
  • Transparency
  • Control over your cash flow 

Before you decide if this is the right offer for you, let’s take a closer look behind the curtain of this Amazon business net 30 account. 

Flexible Payment Terms

If you want to buy now and pay later, this is totally possible. 

Amazon Pay by Invoice offers eligible Amazon Business customers a flexible payment option, allowing you to buy what you need and settle the bill 30 days later. You get room to breathe with a net 30 setup.

Extended Payment Options with Business Prime

Net 30 isn’t your only option with Pay by Invoice. 

If you’re rocking a Business Prime membership, you can level up your Pay by Invoice terms to 45 days with Small and Medium plans or a generous 60 days with the Enterprise plan. This can give you even more flexibility in managing your cash flow.

What is Amazon net 55? 

Amazon net 55 refers to 55 day payment terms through Pay by Amazon. However, current extended payment periods on Amazon’s net 30 accounts are either 45 or 60 days. 

Itemized Digital Invoices for Easy Management

Amazon Business account net 30

A key benefit, you can track and manage digital invoices with Amazon Pay by Invoice. 

The service provides on-demand itemized digital invoices that simplify the reconciliation process. These detailed invoices, complete with corresponding purchase orders, make tracking spending a breeze and facilitate a smooth 3-way match.

Credit Limits & Eligibility

So, how much 

Upon approval for an Amazon Business account, your account is assessed for a Pay by Invoice credit line. Amazon may – at its discretion – apply, adjust, or revoke credit limits based on business activity. To be eligible, you need an invite, and the credit line, once approved, is accessible via the Billing & Shipping section of Business Settings.

Credit Reports & Authorization

By opting for Pay by Invoice, you grant Amazon the green light to check your business credit reports to verify identity, prevent fraud, and evaluate your eligibility. It’s important to keep your provided information accurate, and Amazon may request additional details as needed.

Does Amazon report Pay by Invoice payments to Dun & Bradstreet? 

Currently, no – on-time Pay by Invoice payments aren’t necessarily reported to business credit bureaus. If you’re looking for tradeline accounts that report, check out these 41 companies that help build business credit.

Amazonbusiness

Interest Charges & Costs

As with all funding offers, there can be some associated costs with Pay by Invoice. 

If you miss the payment deadline, be prepared for a 1.5% monthly interest rate on the outstanding amount. Additionally, any accidental payments or positive account balances when closing your account can be refunded upon request. 

While Pay by Invoice itself doesn’t incur extra fees, there might be charges if third-party agencies get involved in collections for past due invoices.

(Plus, you’ll have to pay for your Prime membership.)

How to Set Up Pay by Invoice on Amazon Business

To boost your shot at Amazon Pay by Invoice, pay your bills on time and keep your Amazon Business account in top shape with accurate info. Follow the rules, stay legit, and watch for eligibility updates. Also, place orders to keep your account active

Eligible businesses are generally those that demonstrate: 

  • A reliable payment history
  • Financial stability
  • Adherence to Amazon’s terms of service 

You’ll also need a registered business, an EIN, and some business credit history. 

The invitation is extended to account administrators, and upon approval, they receive an email with instructions to set up Pay by Invoice in the Business Settings.

If you have questions or need help, reach out to Amazon Business Customer Service. It’s an invite-only deal, so focus on good buying habits, and hopefully, that invite lands in your inbox! 

Once it does, here’s what to do: 

  1. Log in to your Amazon Business account.
  2. Go to “Business Settings.”
  3. Click on “Billing & Shipping.”
  4. Check the status of “Pay by Invoice.”
  5. If needed, initiate setup.
  6. Manage invoice preferences, including billing address and frequency.
  7. Explore additional features like invoice templates and group payments.
  8. Review and save your settings.

After this, you should be able to enjoy net 30 terms from here on out… 

Recommended: Here’s How to [Actually] Get Business Credit With Just an EIN +More Options 

Frequently Asked Questions

How do I become eligible for Amazon Business Pay by Invoice? 

Eligibility for Amazon Business Pay by Invoice is determined by Amazon based on factors like your business’s creditworthiness and purchasing history. It’s an invite-only program for Amazon Prime Business members, so you’ll need to sign up for an account and keep a positive buying track record to increase your chances of an invitation.

Can I customize the payment terms with Amazon Pay by Invoice?

Yes, you can customize payment terms based on your Business Prime membership. With Business Prime, you can apply for extended terms, such as 45 days for Small and Medium plans or 60 days for the Enterprise plan.

How does Amazon determine my credit limit for Pay by Invoice?

Amazon assesses your account for a Pay by Invoice credit line upon approval. Credit limits may be adjusted by Amazon at their discretion. The credit line remains open for a limited time, and it’s important to activate it promptly.

Can I track and manage multiple buyers' spending on Amazon with Pay by Invoice? 

Yes, you can set up multiple buyers and track their spending on Amazon. The system allows you to search and download invoices by various criteria, providing enhanced reporting with built-in analytic tools.

What happens if I miss the payment deadline with Pay by Invoice? 

If you fail to make payment on time, Amazon may charge interest at the rate of 1.5% per month on the outstanding amount. It’s crucial to adhere to the payment terms to avoid additional charges and maintain a positive relationship with Amazon Business.