• Home
  • Free Funding Guide
  • What We Offer
    • Products
    • Services
    • Free Guide
  • About Us
  • Contact
  • Sign Up

  • Ask Joe Any Question!
  • Business Credit Cards
  • Business Line of Credit
  • Topics

Is LendingPoint Any Good for Financing? [Lender Review]

November 18, 2020 By Joe

LendingPoint review and pricing

You’re looking for a way to get fast cash flow. If you haven’t invested in building your business credit or your have a low personal FICO score, your options could be limited. Enter LendingPoint, a lender that caters to people with less than ideal credit, offering personal loans for various uses. 

Furthermore, this lender provides an option for merchants to extend financing to their customers and clients, which sounds awesome. So, are they legit? 

Here’s what’s in store: 

  • What is LendingPoint?
  • LendingPoint Loan Overview
    • LendingPoint Pricing
    • Does LendingPoint Report to Credit Bureaus?
    • How to Qualify for a LendingPoint Loan
    • How Long Does LendingPoint Take to Approve?
  • LendingPoint Merchant Solutions Overview
    • The Benefits of Merchant Solutions
    • LendingPoint Alternatives for Merchants
  • Conclusion

So, keep reading to learn more. 

What is LendingPoint? 

Founded July 2014, LendingPoint is positioned as a lender for those with lower credit scores who can prove their dependability in other ways: income, credit behavior, job history. LendingPoint’s core offer includes personal loans up to $25K. The company is based in Kannesaw, Georgia. Tom Burnside is the CEO and co-founder. 
Where is LendingPoint located?

Before founding LendingPoint, according to his LinkedIn profile, Burnside spent 13 years as the President and Chief Operating Officer (COO) of Capital Access Network (now known as CAN Capital). There, he was responsible for design, development, and implementation of their unique credit scoring model. 

LendingPoint’s loans are designed for multiple uses, such as unexpected urgent expenses, debt consolidation, medical or dental costss, home improvement, travel, taxes, wedding, or other personal financial reasons. And, to date, the company has loaned over $1.8 billion in the United States.  

Note: Some people get LendingPoint confused with Lending Club. A few years back, the CEO of the latter was involved in a scandal, which discredited the company’s trustworthiness to investors. These two businesses are unrelated. 

LendingPoint Loan Overview

Google review LendingPoint

As a funding solution, LendingPoint gets some pretty rave reviews. On the other hand, there are naysayers. So, what can you expect from personal loans? Here’s everything you need to know, including costs, requirements, and a quick look at competitors. 

First, LendingPoint is a direct lender in certain states, meaning they sometimes use their own, private funds to finance borrowers. In other cases, they may offer financing extended from another source like FinWise Bank. 

LendingPoint Pricing

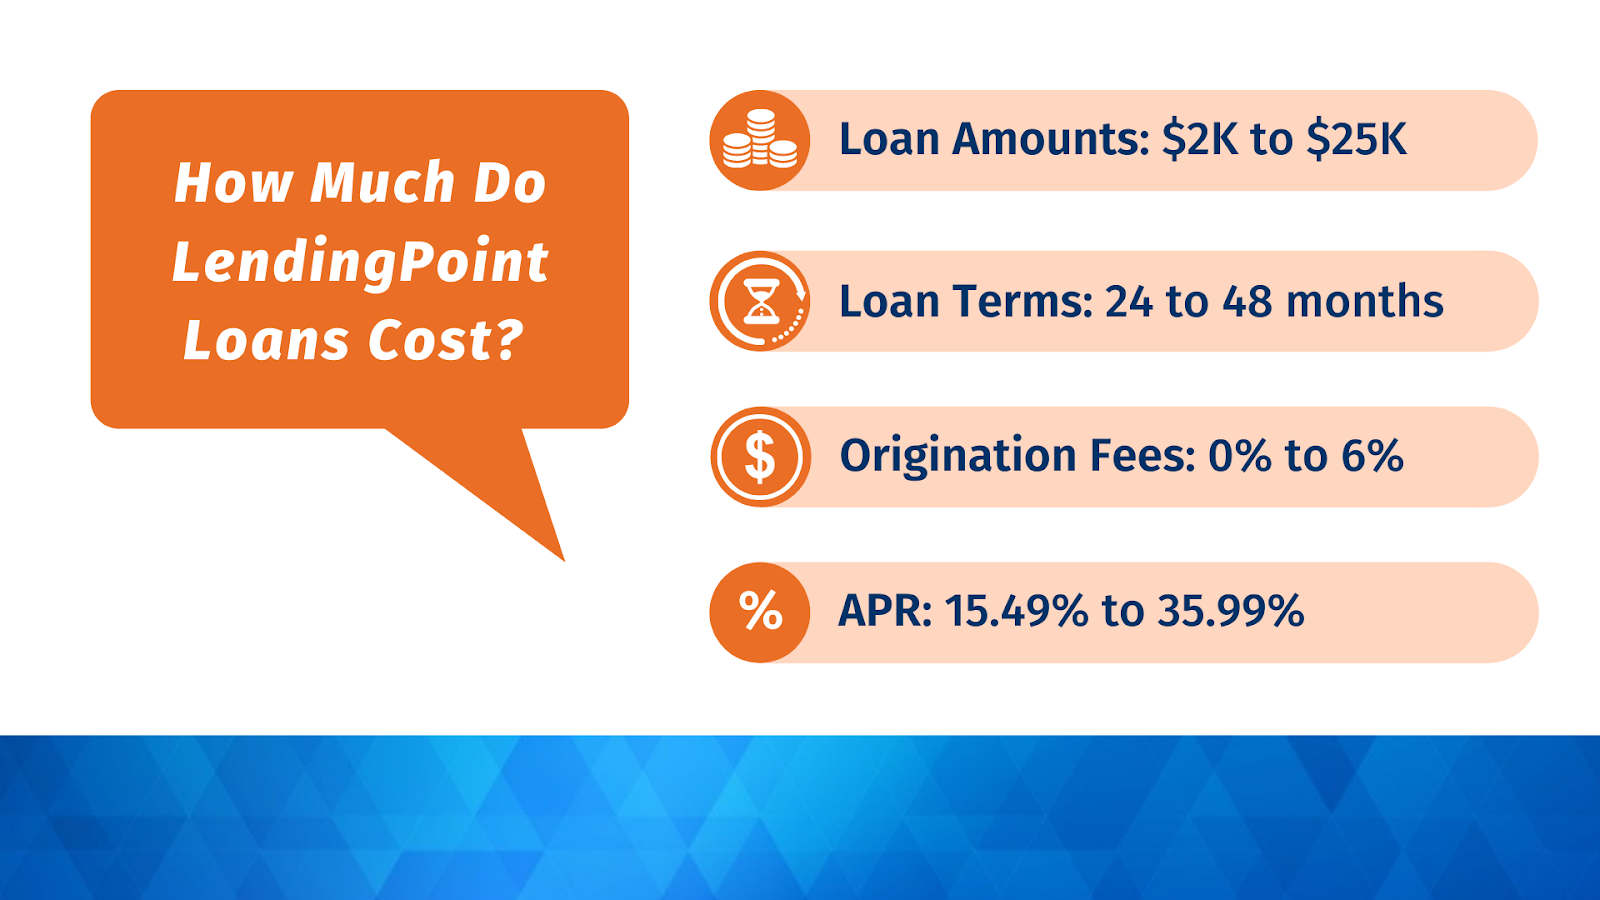
As with all funding providers, there are layers to LendingPoint’s pricing. Let’s take a examine the costs of their funding. Loan amounts range from $2K to $25K with terms from 24 to 48 months. Origination fees range from 0% to 6% with interest rates between 15.49% and 35.99%. 
LendingPoint pricing origination fees interest rates

So, if you take out a $10K loan with a 6% interest rate, the total amount owed with fees might be $12,700. In this scenario, monthly payments at 24.098% APR with 24-month terms should be around $530 per month. You could be offered the option to deduct the origination fee from the dispersed amount if desired. 

You might also like: Torro Business Funding Review: Is This “Zero Hassle” Offer Legit?

Does LendingPoint Report to Credit Bureaus? 

According to Experian, LendingPoint promises to report to one or more personal credit bureau(s), not all three. So, on-time payments toward a LendingPoint loan can essentially help you improve or maintain your personal credit with at least one bureau. Furthermore, they do not report payments to business credit bureaus. 

How to Qualify for a LendingPoint Loan

While LendingPoint is positioned as a funding option for those with “fair credit,” not just anyone will qualify. As stated previously, you will need to prove your creditworthiness through other means. 

A credit score of at least 585 is a must for LendingPoint. So, if your score is lower than this, you’ll need to look elsewhere for funding. Furthermore, the lender will take into account your income, the intended use of funds, and other details to get a clear picture of your ability to repay the funds. 

Bankruptcy within the last 12 months could disqualify you, but older bankruptcies may be okay. Other immediate edisqualifying factors could be too many recent credit inquiries, annual income lower than $35K, and the inability to verify income or identity. 

Related Reading: Credit Secrets Book Review: Can You Erase Bad Credit History? 

LendingPoint does not do a hard inquiry on your credit when prequalifying borrowers. Instead, they do a soft-pull. So, checking out what you might qualify for will not impact your credit score and other potential lenders will not see that you applied for funding. 

How Long Does LendingPoint Take to Approve? 

After you apply for a loan through LendingPoint, you’ll be asked to share documentation that proves your ability to repay the loan and your identity. 

  • Your social security number
  • A federal, state, or local government-issued photo ID
  • A verifiable personal bank account
  • Proof of annual income of $35K or more 
LendingPoint CreditKarma review

Once your full application is complete, you will know within a week and in ass little as 24-hours if you have been approved. Then, your funds should be dispersed by the next business day. 

LendingPoint Merchant Solutions Overview

If you’re a business owner interested in working with LendingPoint, their merchant solutions offer might be right up your alley. Through the platform, you may be able to offer financing to your clients and customers. 

For example, one of the most popular LendignPoint partnerships is with Invisalign. Patients seeking clear teeth aligners without the cash to pay upfront can access LendingPoint’s offer from Invisalign’s brand website. As of August, 2020, eBay has partnered with the lender to bring a new “buy now, pay later” solution to their shoppers. 
LendingPoint Invisalign

Instead of a $5,000 pricetag, your offer could instead be ~$250 per month. To consumers, sometimes a smaller monthly payment is a better deal. So, this might make sense when you’re trying to grow, scale, and just increase your sales. 

The Benefits of Merchant Solutions

If you opt to add financing to your offer, LendingPoint Merchant Solutions can make it simple. First, applicants can apply from any device, including their own phone or a tablet that you provide in-office.  
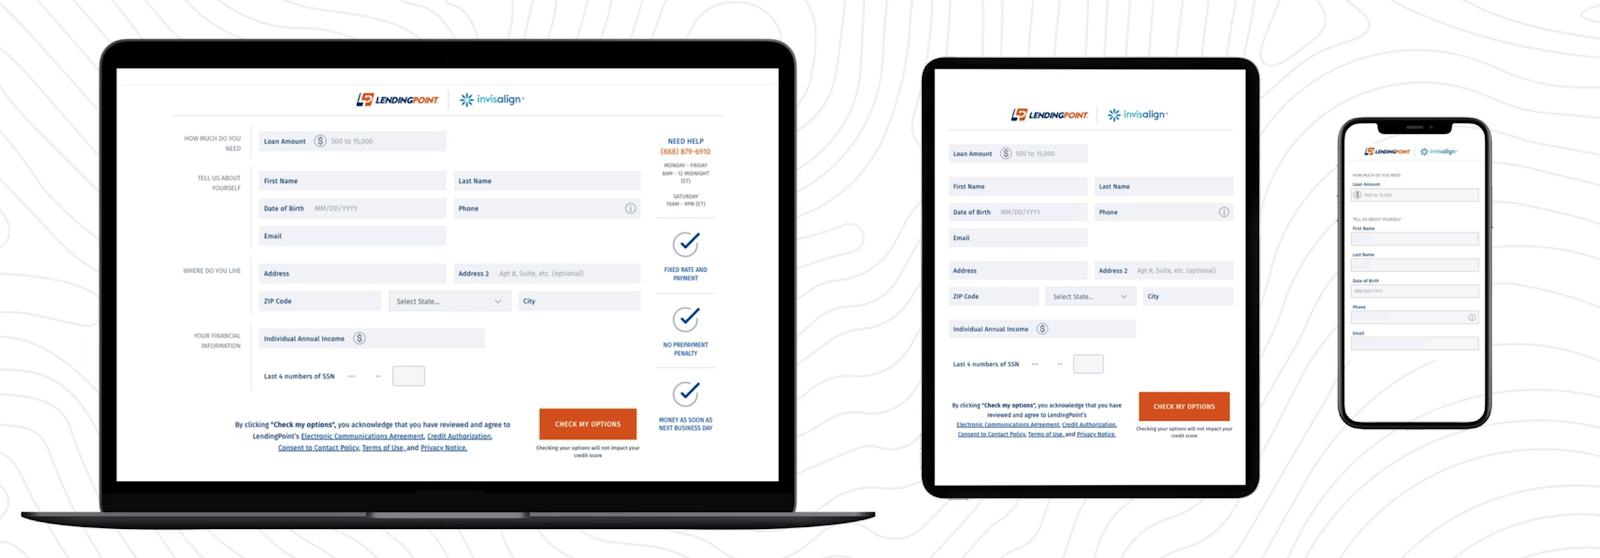
LendingPoint login

Next, the qualification terms are pretty easy. The brand marketing materials boast “more approvals” for consumers. 

And, your clients and customers can check their rate (prequalify) before applying. So, there’s minimal risk to them. 

LendingPoint Alternatives for Merchants

Before you dive into a commitment, it’s smart to explore your options. Here are a couple of choices to explore (there are many other solutions out there). Side-by-side, this is what your customers might expect from each:

Loan AmountsLoan TermsOrigination FeesInterest Rates
LendingPoint Merchant Solutions$2K to $25K24 to 48 months0% to 6% 15.49% to 35.99%
Acima Credit$500 to $5K90 days, 12, 18, or 24 months$25+Unlisted
FinanceItUp to $60KVaries$06.99% to 14.99%

Conclusion

So, is LendingPoint good for funding? If it’s the only lender you might be able to qualify with and you’re in need of quick cash, sure. LendingPoint offers a competitive personal loan offer for consumers with fair credit. 

Now, you if you’re looking for a way to provide your clients and customers with financing between $2K and $25K to purchase your products and services now and pay over time, LendingPoint Merchant Solutions could be an excellent source. I do recommend you explore further. 

And, if you want to learn how to obtain no-doc lines of credit up to $100K for your company, join Business Credit Workshop today.
A Complete Fundwise Capital Review: Should You Use Their Business Funding Services?

October 25, 2020 By Joe

Fundwise Capital Review

Today’s business owners who seek funding have a plethora of options. Because of the convenience, among the most popular choices are online lenders. Before you start submitting applications all willy nilly, you should always know what you’re getting into. 

Since most people don’t blindly trust endorsements from finance gurus (Grant Cardone, for example), I want to help you sort through existing Fundwise Capital reviews and get to the truth. 

Here’s what you’ll discover: 

  • What is Fundwise Capital?
    • This is Fundwise Capital in a Nutshell
    • Who is Fundwise Capital For?
    • How Much Does Fundwise Capital Cost?
  • What is the Fundwise Partner Program?
  • Final Takeaway

Now, let’s get to it… 

What is Fundwise Capital? 

Founded in 2013 and based in Provo, Utah, Fundwise Capital is an online lender that offers lines of credit and term loans to their clients. 

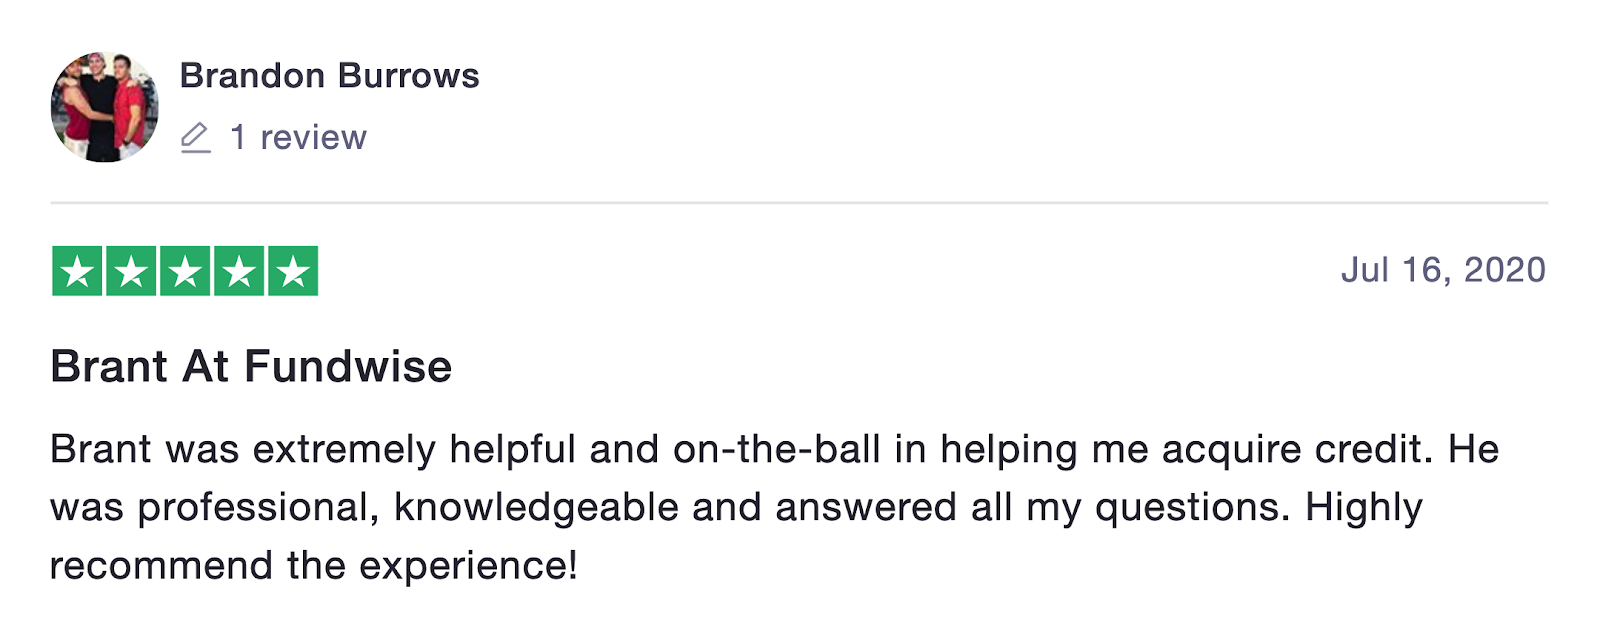
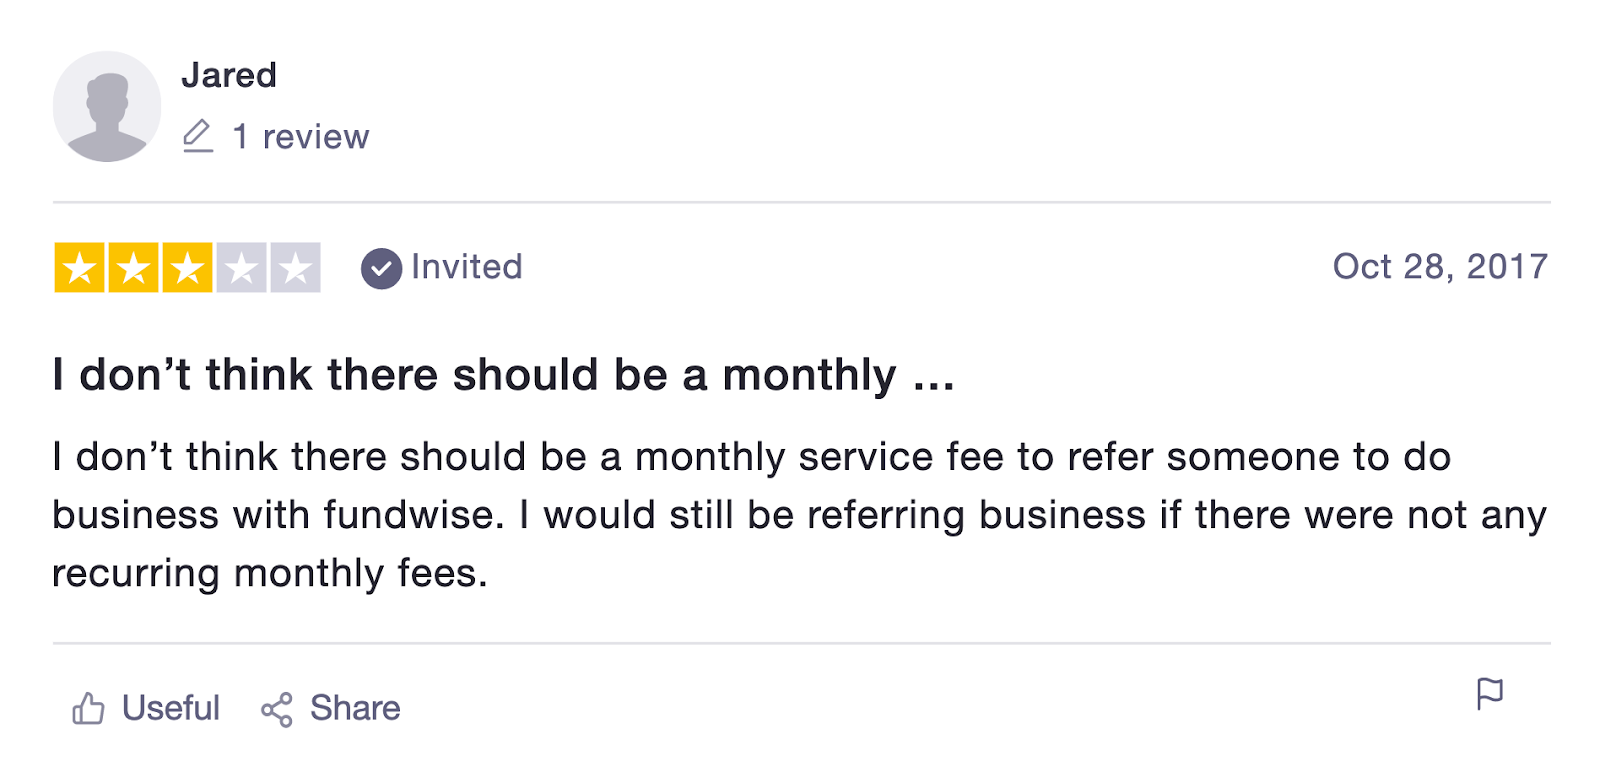
Fundwise Capital Review Trustpilot

Unsecured lines of credit and credit cards from $15K up to $200K with 0% interest for the first 9-15 months with “competitive rates” after the introductory period. They also help business owners access unsecured term loans, but they don’t describe the terms and conditions on their website. 

This is Fundwise Capital in a Nutshell

Who owns Fundwise Capital?

Fundwise was founded by Utah-based entrepreneur Leo Kanell who also founded 7 Figures Funding, Identity Insured, and 7 Figures University. 

What are the fees for Fundwise Capital?

Fundwise fees are $500 upfront plus 9% of the final approval amount. 

How does Fundwise Capital Work?

Fundwise representatives know some of the best banks to apply for business loans and credit cards with, based on unique qualifications. They help businesses take the proper steps to obtain funding through external lenders. 

Are Fundwise Crowdfunding and Fundwise Capital Related?

You might come across an Estonian crowdfunding company with the name Fundwise — the two companies are not related. 

Now, Who is Fundwise Capital For? 

Fundwise is geared toward businesses that need funding. To qualify, you must have a credit score of 650 or higher. If your credit score falls below this number, you can use a credit partner (co-signer) such as a business partner, family member, or friend with a qualifying score. 

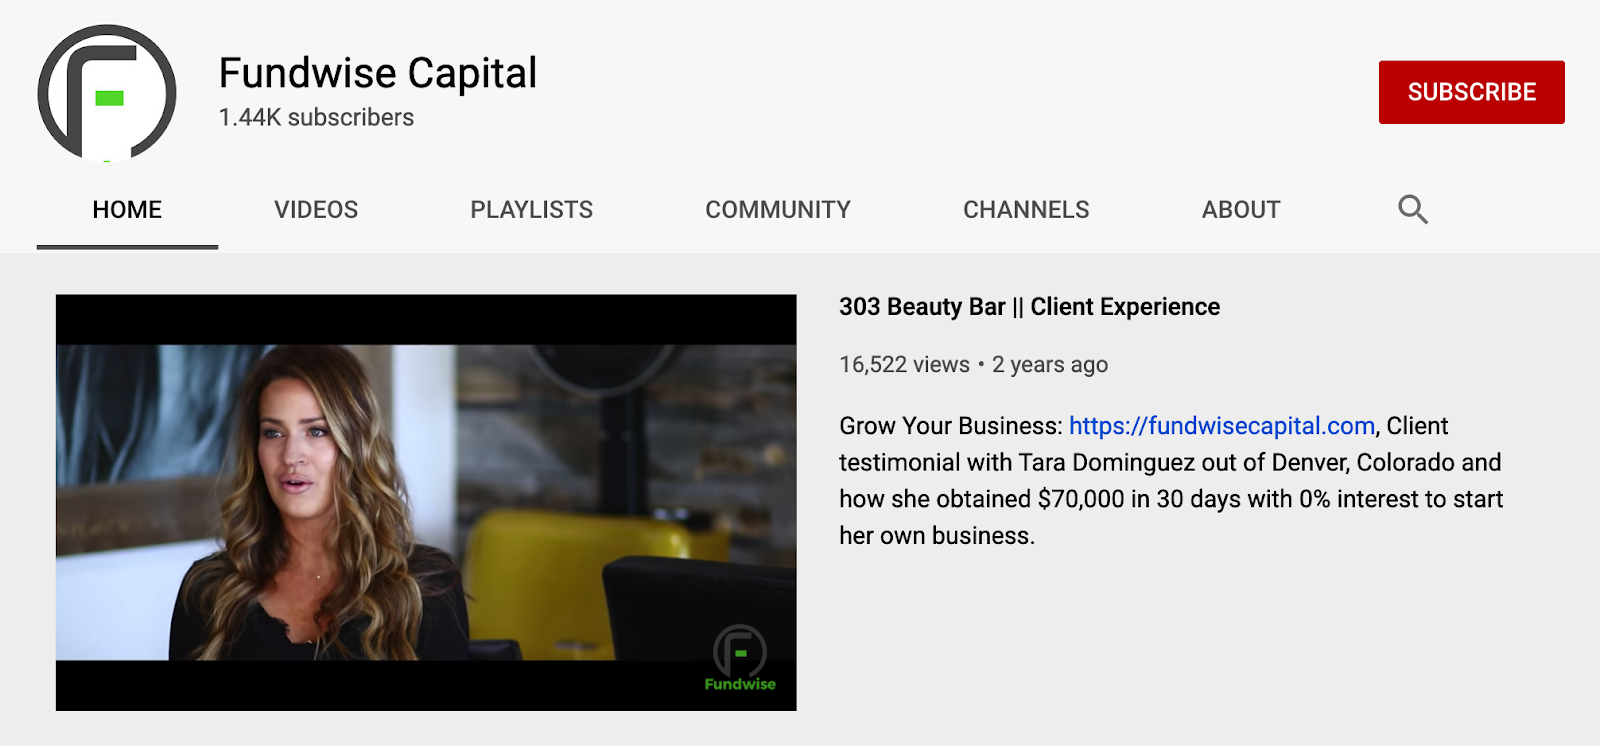
Fundwise Capital YouTube

Fundwise Capital’s financial services are designed for: 

  • Startups
  • Small business owners
  • Real estate flippers
  • Restaurant owners
  • Salon owners
  • Franchise investors
  • Coaches

While the above list outlines Fundwise’s target clients, there aren’t restrictions on how the money can be spent. So, the offer could essentially be leveraged by anyone who meets the credit qualifications. 

To “apply,” you’ll enter the usual information including personal credit score, business income, and first and last name into a form. After that, a Fundwise representative will contact you the following day to discuss your options. 

Keep in mind that this isn’t an actual funding application, so it won’t affect your credit score. Instead, this is a way for Fundwise reps to collect new lead information and pre-screen you for the appropriate products. 

And, How Much Does Fundwise Capital Cost? 

While the credit cards and term loans you obtain may come with 0% APR, you will pay a fee. The cost to leverage these services will be $500 upfront and an additional 9% of your total funding obtained as an “approval fee.” 

So, at this rate, here’s what you can expect to pay:

  • $15K in funding = $1,850 to Fundwise
  • $25K in funding = $2,750 to Fundwise
  • $100K in funding = $9,500 to Fundwise
  • $200K in funding = $18,500 to Fundwise

Theoretically, if you spend and pay off your funding during a 0% APR introductory period, you might pay less with this offer than you would on a credit card with an APR around 20%. 

Now, there is something else to watch out for: You could unknowingly get upsold on credit monitoring software or credit counseling, so brace for that. The credit monitoring software Fundwise promotes is from seeyourscore.com (located at the same street address in Provo, Utah as Fundwise Capital). Monitoring through the platform costs $29.99 per month and some users have had a hard time canceling their subscriptions. 

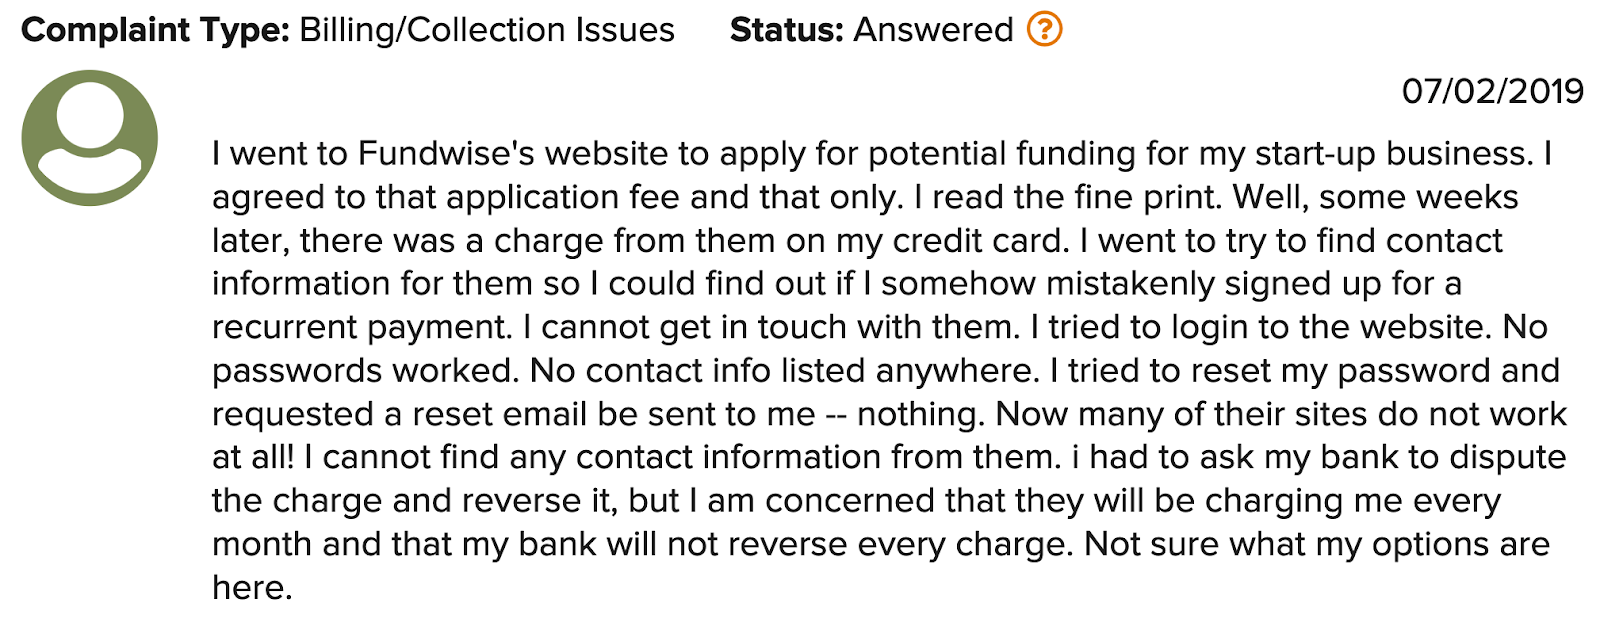
Fundwise Capital BBB

In addition to credit building and monitoring bonus offers, Fundwise Capital has another product worth looking into (for satisfied clients, anyway): Fundwise Partners. 

What is the Fundwise Partner Program? 

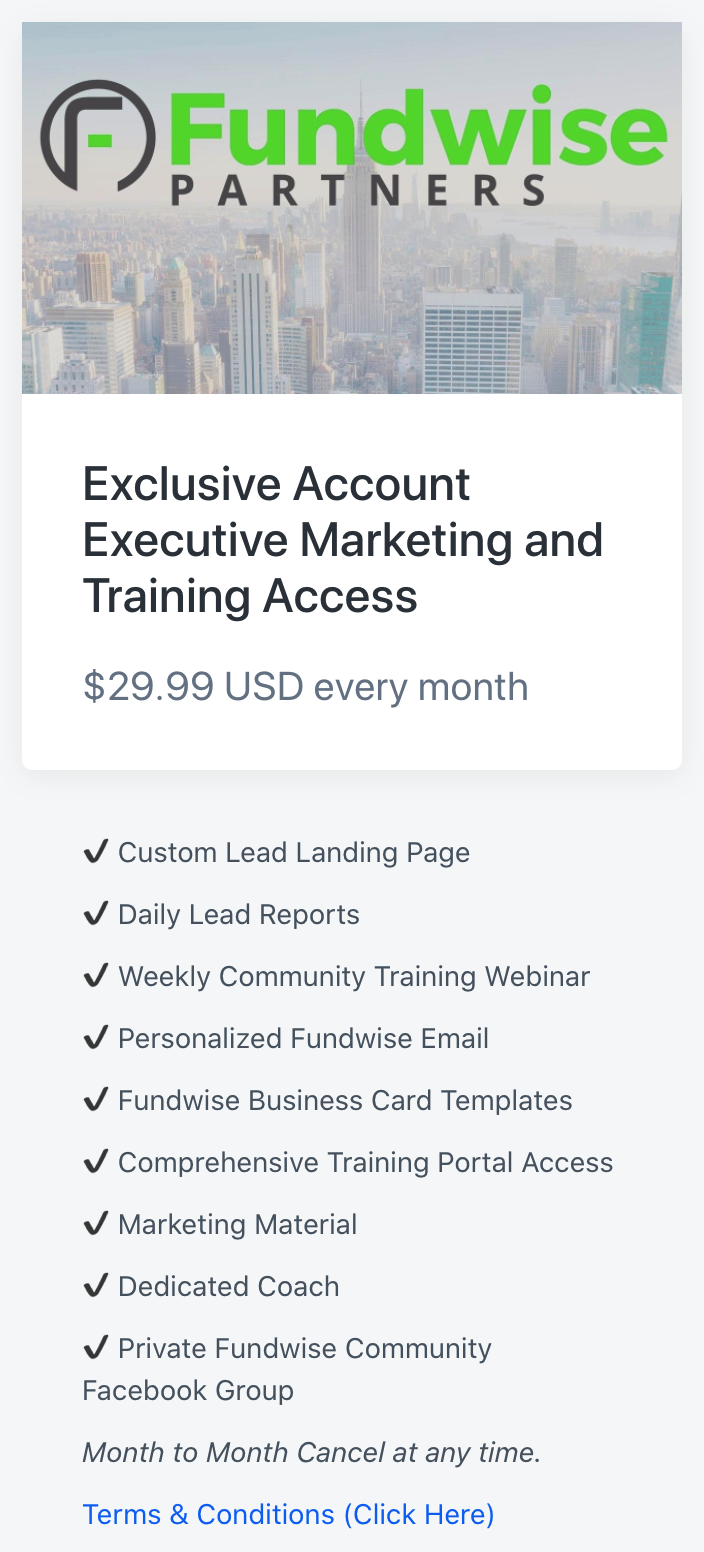
Fundwise Partners is a program designed for affiliates to earn a commission for referring other business owners to the core offer. 

Affiliates or “partners” get a unique landing page through which to send leads to the platform. They are also provided with a dashboard to track leads referred, funded accounts, and conversion rates. 

Fundwise Partners Login

This is a two-tier affiliate system, which means that you can also refer affiliates to the platform for a commission. Some affiliates primarily focus on promoting this platform to business coaches and entrepreneurs with a large network of other owners. Allegedly, some affiliates earn hundreds of thousands per year. But, there’s a catch… 

Fundwise Capital Complaints

…the partner program costs $29.99 per month. 

Fundwise Capital Affiliate Program

Frankly, the Fundwise Partner program sounds more like an MLM business than a typical affiliate program. And, if that’s your thing, there could be a full-time opportunity here. 

Final Takeaway: Should You Apply for Business Funding Through Fundwise?  

As we wrap up, there are a couple of things I don’t love about Fundwise Capital: 

  • Their website is a little wonky and missing information about pricing, fees, and other important details. This lack of transparency makes the company seem potentially unreliable. 
  • Business owners who don’t qualify for funding seem to be rolled into paid offers with the promise to help clients improve their odds of getting funded. Unfortuanately, these offers don’t seem to provide a ton of value compared to other products in the marketplace.

And, there are some aspects I can appreciate about their business funding offer: 

  • Fundwise Capital seems to rely on soft-pulls, which have no negative impact on credit scores — unusual and refreshing.  
  • Credit cards, lines of credit, and term loans are my favorite type of funding for small businesses because they allow owners to maintain the highest level of control over cash flow. 

So, like all business funding options, Fundwise has its benefits and its drawbacks. They’ve helped enough companies obtain funding to earn their star in the hall of business funding fame. Now you should know enough about the offer to determine whether it’s right for you at this time or not. If you want to learn how to get $100K in business funding in as little as a month, enroll in Business Credit Workshop today.
How to Interpret Lendio Reviews: Is This Funding Company Legit?

October 18, 2020 By Joe

Lendio Business Funding

Business owners across the world, now more than ever, turn to online lenders to keep their cash flowing and their doors open. One of the significant names in the business finance game today is Lendio. But, is Lendio a legit company? You want an honest answer, so here it is. 

Let’s examine actual Lendio reviews from some of the most trustworthy consumer sites and thoroughly examine the brand’s offer. Here’s what we’ll cover. 

  • What is Lendio?
    • Who is Lendio and Where is the Company Based?
  • How does Lendio Work?
    • What Type of Funding Can You Get Through Lendio?
      • Credit cards
      • Lines of credit
      • Term loans
      • Startup loans
      • Accounts receivable financing
    • What is Sunrise by Lendio?
  • Is Lendio an SBA-Backed Lender?
    • So, Has Lendio Funded any PPP Loans?
    • And, If They’re Not Funding, How Does Lendio Make Money?
  • Now, How to Decrypt Mixed Lendio Customer Reviews
  • +Bonus: A Quick Look at Lendio’s Franchise Offer
  • Final Answer: Is Lendio Legitimate?

Read on to piece together the puzzle. 

What is Lendio?

Lendio is a simple small business loan marketplace. The platform connects business owners with the lenders that they are most likely to obtain funding from. The platform offers connections with lenders who offer all types of cash flow increasing options like credit, loans, equipment financing, mortgages, accounts receivable financing, and more.

Who is Lendio and Where is the Company Based? 

Lendio, Inc. was founded by Brock Blake, the current CEO, in 2011 and the company extended their first loan in Q4 2013, according to Wikipedia. The CFO is Chad Iverson. Company headquarters are located in Lehi, Utah. 

How does Lendio Work? 

If you’re a small business seeking funding, here’s what you might expect from Lendio. The application should take about 15 minuted to complete and will connect you with 75+ lenders. In many cases, you could get the funds you seek in as little as a day. 

First, Lendio looks at your self-reported credit score range. Then, they find out how long you’ve been in business and how much money your company has generated over the last 90 days. After that, they ask what you need funding for. 

Terms and conditions vary for business acquisition vs expansion or payroll, for example. So, by determining why you need funds, they filter out various lenders who aren’t likely to approve you. 

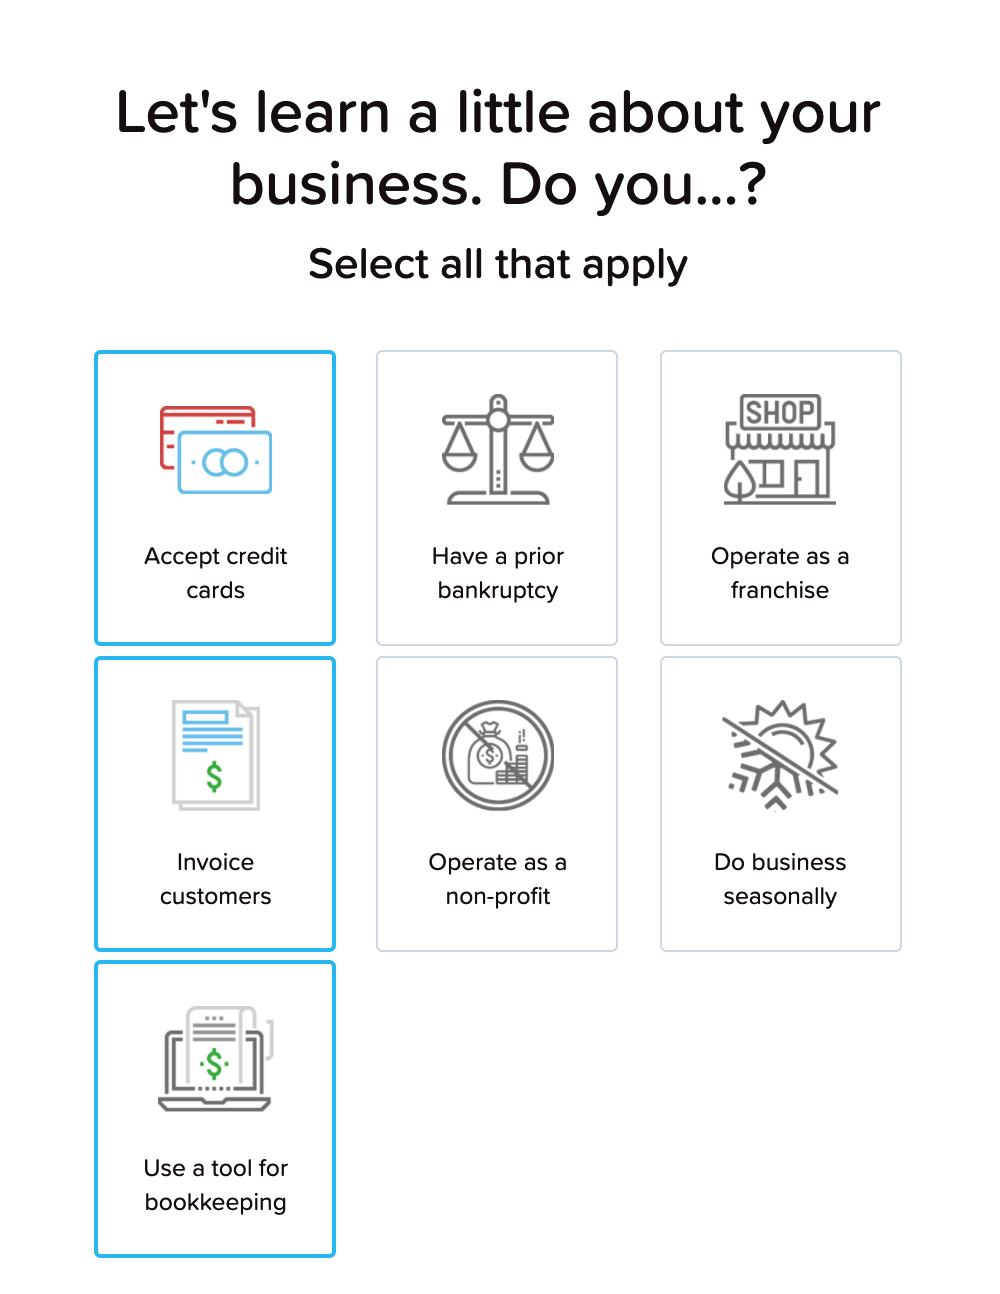
When that’s over, the platform looks at certain aspects of your business that may help or hurt your qualification odds like if you have a prior bankruptcy or if you operate as a non-profit. 

Lendio com reviews

Once you’ve shared the above, the platform looks at the location of your business, your annual personal income, and your percentage of ownership in the company. Finally, there is a differentiator between Lendio and competitors: they want to know what factors are most important to you whether it be amount, speed, or cost of funding you’re looking for. 

Once you agree to the terms and conditions (*which include the possibility that you’ll be contacted by auto-dialers and partners — probably why many people are asking “How do I get rid of Lendio emails?”), the platform will do a soft pull of your credit via Experian using your social security number. At this point, they don’t ask for your DUNS number. 

Lendio login

If the platform can’t make the connection automatically, Lendio will ask you to manually enter your business’ financial information. You’ll be asked for your entity type and annual profits. 

And, if you’re likely to be qualified through one of Lendio’s partners, they’ll let you know instantly and connect you to a possible funding channel. 

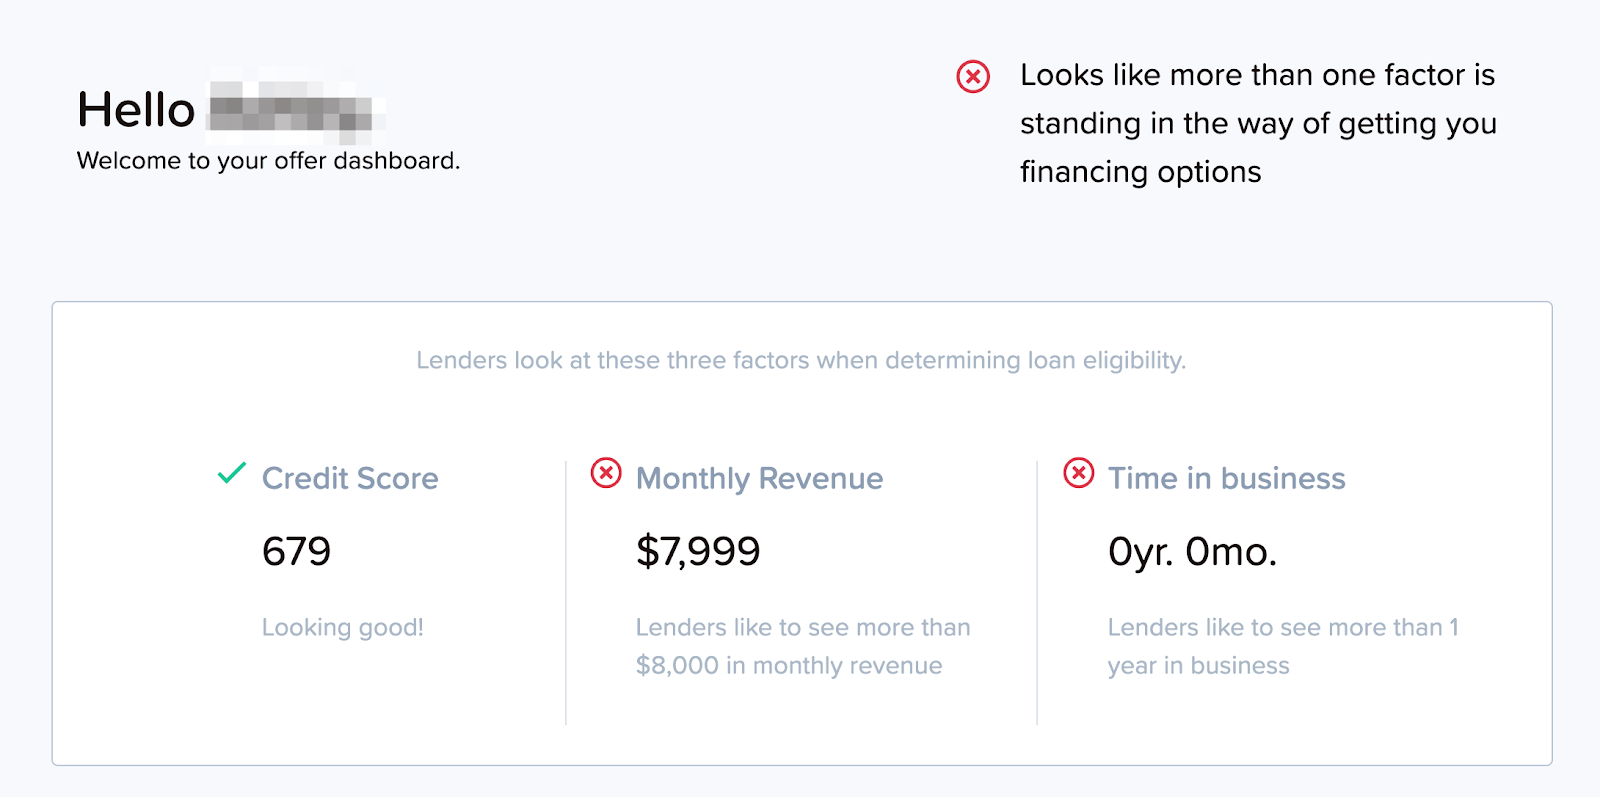
If not, the platform lets you know precisely what’s standing in your way of getting funded and tells you what to do next. 

Lendio business loans reviews

And, when this happens, the system will suggest the next steps you can take to get ready for funding, which may include applying for a credit card or connecting with a partner like LegalZoom or Credible. 

What Type of Funding Can You Get Through Lendio? 

Via Lendio, you can access several types of funding types from their network of banks and online lenders. Now, let’s examine a handful of them and, for each, see some of the top lenders in their network.

First, here’s a quick summary. 

Lendio Rates Chart

Credit cards

If you’re looking for plastic, they have it. Just determine how much you need and the Lendio platform will try to help you determine which credit card issuer is likely to help you get it and at what rate. In many cases, you could be looking at 0% introductory APR offers, but this is likely to increase later. And, if you’re not quite ready for larget credit lines, Lendio might connect you with credit building options. 

Some of the leading credit cards Lendio might match your business with could come from Chase, American Express, LenCred, Bank of America, Credit One, and Seek Business Capital. 

Lines of credit

Through Lendio, line of credit amounts can range from $1K to $500K with interest rates between 8 – 24% and terms between one and two years. If your company qualifies, you may be able to access funds as quickly as within a couple of weeks. 

For business lines of credit, Lendio might connect you with Kabbage, Blue Vine, Fundbox, Headway Capital, or Fundation among others. 

Term loans

Term loans that you can apply for through Lendio might range from $5K to $2M with have interest rates as low as 6%. And, the terms can range between one and five years. Access funds obtained through the platform in as little as 24 hours. 

Some of the term loan providers Lendio could link you with include OnDeck, Fundation, American Express, Funding Circle, Opportunity Fund, Credibility Capital, and Lending Club. 

Startup loans

In most cases, startup loans can be the most difficult to obtain because financial institutions are more eager to lend to an established business. But, if you meet the requirements, you can leverage loans of $500 to $750K at interest rates between 0 and 17% to start a business. Access funds in two to four weeks and pay off your loan over the course of 25 years. 

Startup loan offers that Lendio might match you with could come from Chase, American Express, or Bank of America. 

Accounts receivable financing

Have outstanding invoices? Then, you may be able to leverage them as collateral through accounts receivable financing throught the Lendio platform. Get cash in an amount up to 80% of your current accounts receivables and pay factor rates as low as 5%. Get this type of funding in as little as 72 hours and pay it off in a year or less. 

If you qualify for accounts receivable financing through Lendio, it might come from Eagle Business Credit, Internex Capital, BlueVine, FundBox, or ActionCapital. 

What is Sunrise by Lendio? 

Lendio bookkeeping software

In some cases, the next steps that the platform claims will set you on the journey to obtain working capital, loans, or credit via the platform will include signing up for Sunrise, the brand’s bookkeeping software. 

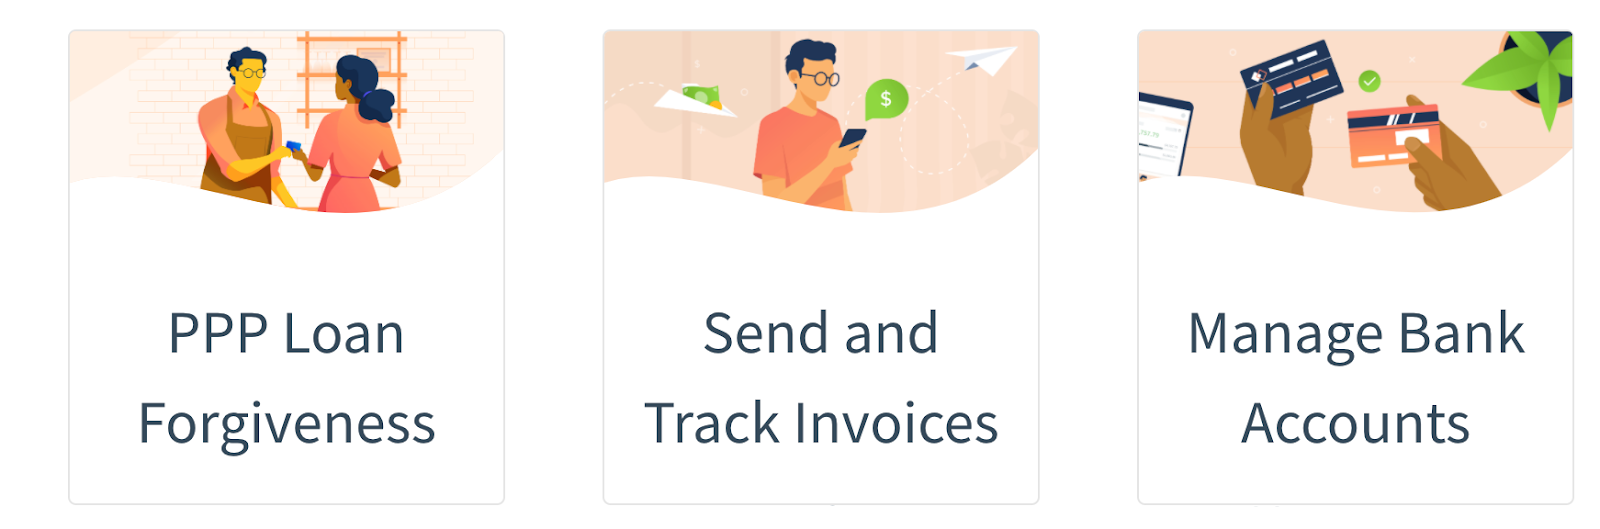
If you create an account, you’ll be asked what your priority is. For example, are you looking to apply for PPP loan forgiveness, send and track invoices, or manage your banking? 

Sunrise bookkeeping app

When connecting your business banking information, Sunrise gives you the option to connect to major banks as well as smaller community banks and credit unions. From the dashboard, you can track income and expenses, send and receive invoices, and manage your business bank accounts. 

This platform isn’t as automated or feature-rich as leaders like Quickbooks, but it seems to have everything you need for simple accounting and invoicing. Plus, invoicing only costs 1% per transaction, which is low. 

Is Lendio an SBA-Backed Lender? 

Lendio was one of 19 finetch companies participating in PPP loan application processing as of May, 2020. Yet, Lendio is not a lender. Instead, they match you to the most appropriate lenders in the United States based on your needs. And, the SBA does approve of their legitimacy. 

Is Lendio legit for PPP?

So, Has Lendio Funded any PPP Loans? 

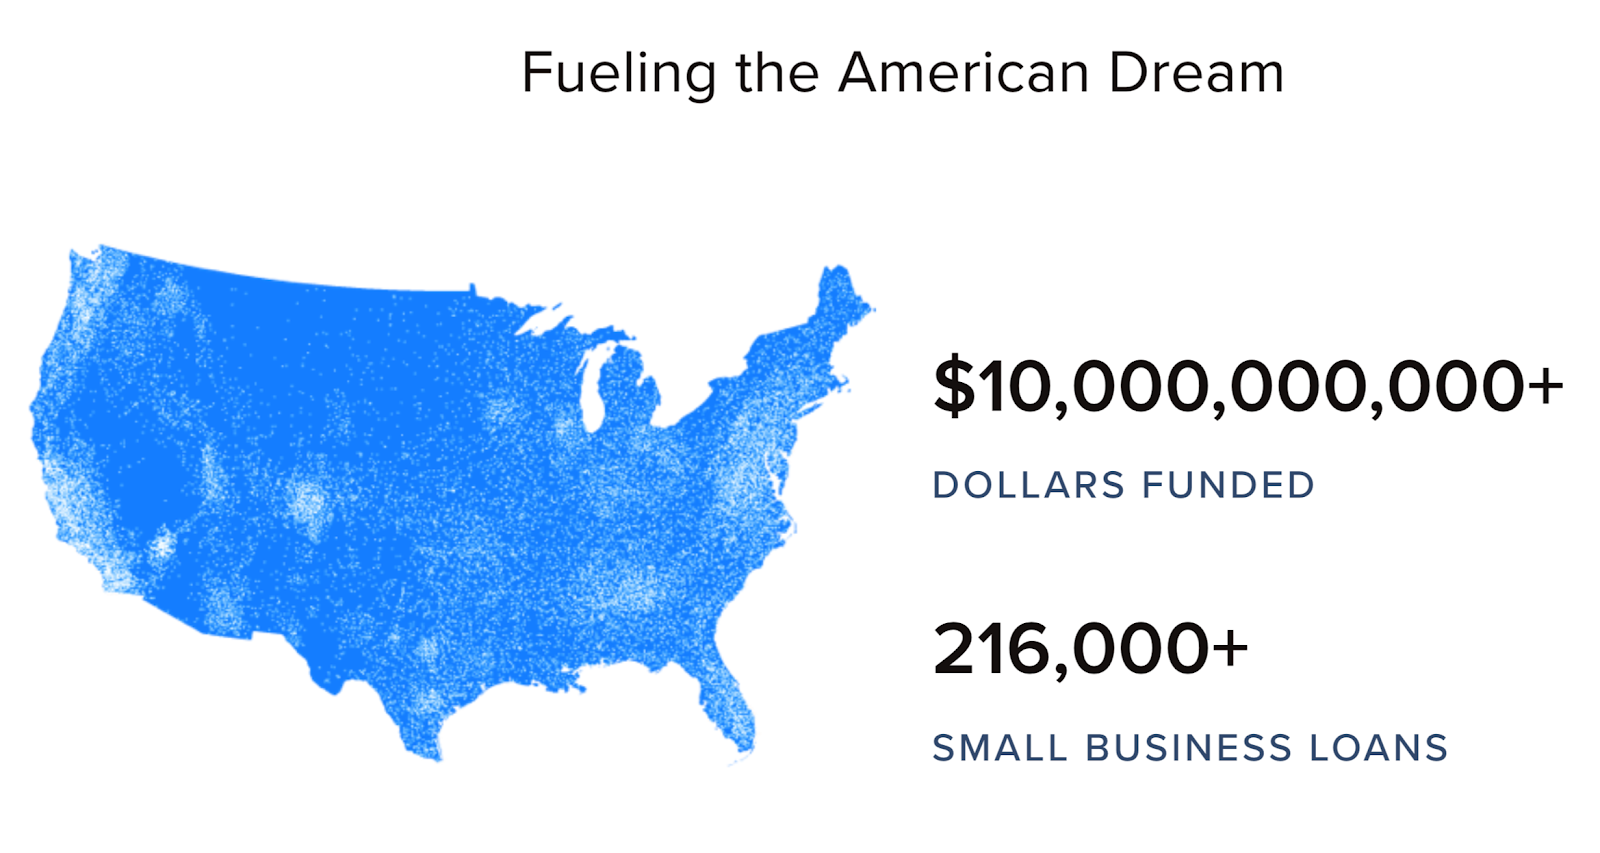
As of July 2020, Lendio reported to have facilitated $10BN in total funding for the PPP program. And, despite the fact that August 8, marked the end of the PPP application period this year, Lendio is still accepting PPP applications in hopes that congress will extend the small business relief program. Still, the company does not provide direct funding. 

Yet, according to many, Lendio is a good source for PPP application processing. 

Lendio reviews PPP

And, If They’re Not Funding, How Does Lendio Make Money? 

Lendio doesn’t charge a fee, so how do they make money? Well, they don’t charge the small business owner. Instead, the get their money as a sort of finder’s fee or a setup similar to affiliate marketing from the Lenders who fund their applicants. 

Think of Lendio as a broker who takes a cut from the big guy. Note that this typically means that the applicant may pay more than if they cut out the middle man and apply directly with a lender. But, the latter is a less convenient option. 

Now, How to Decrypt Mixed Lendio Customer Reviews

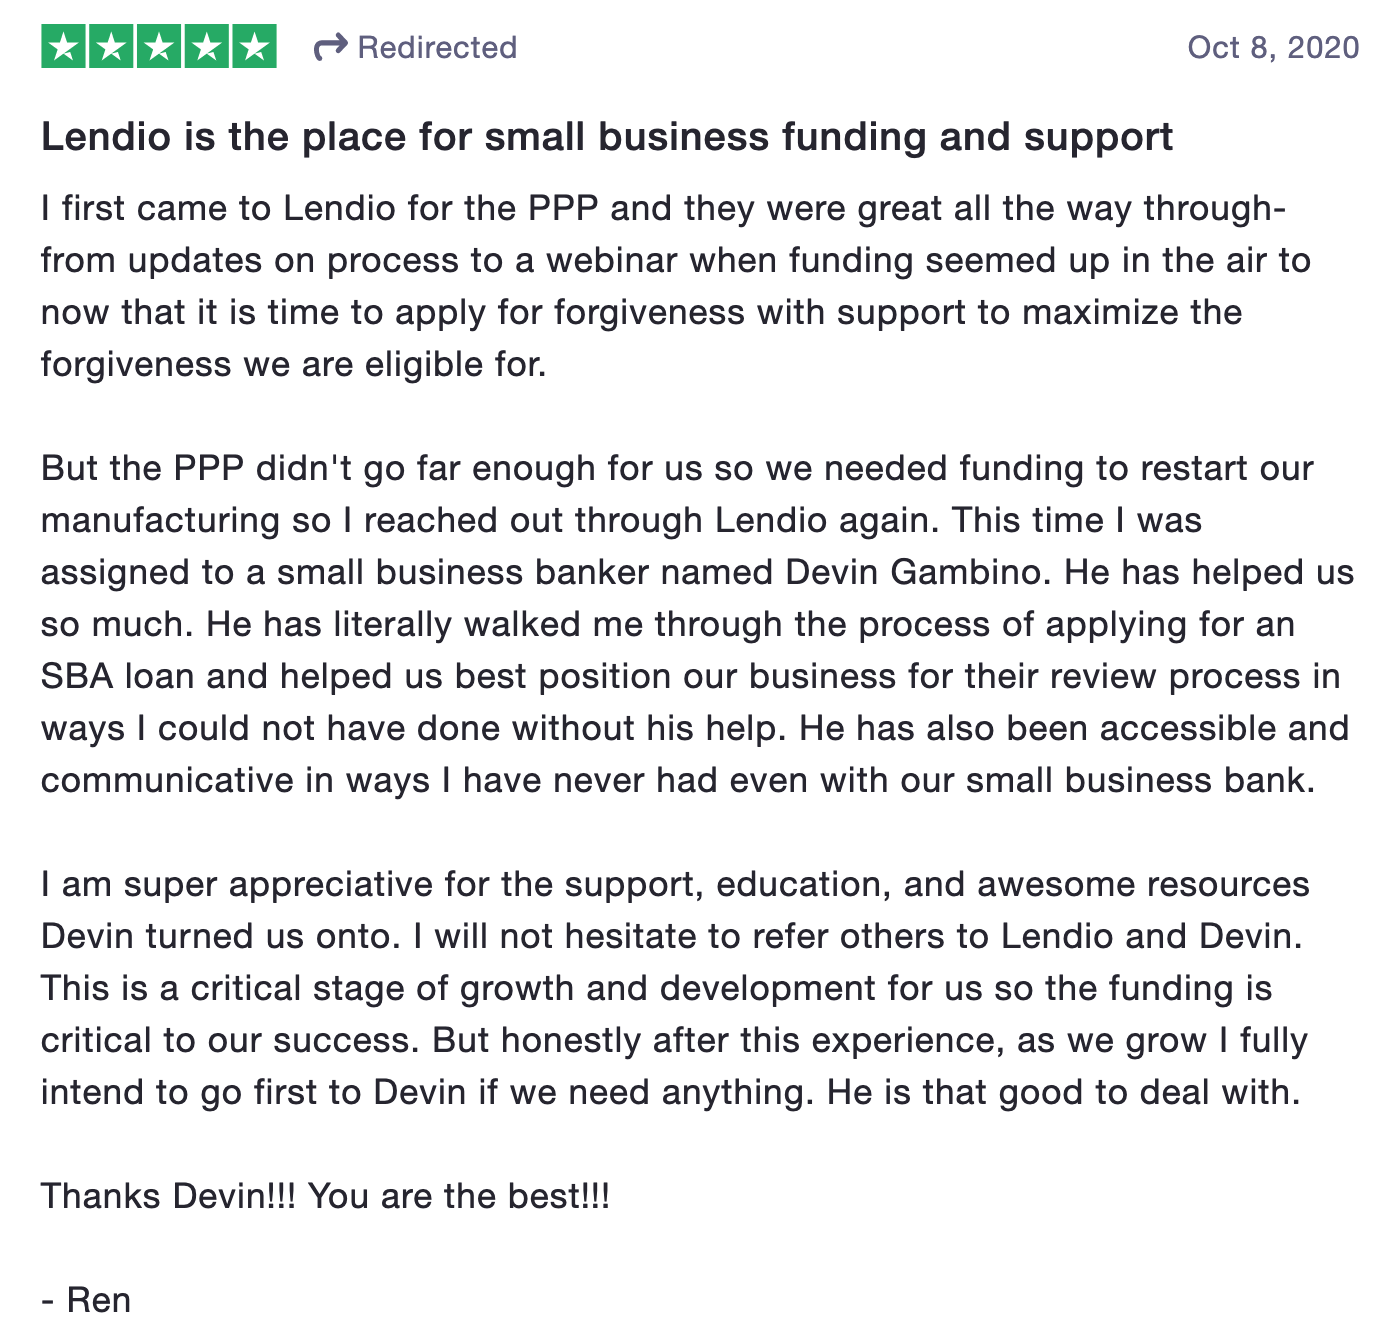
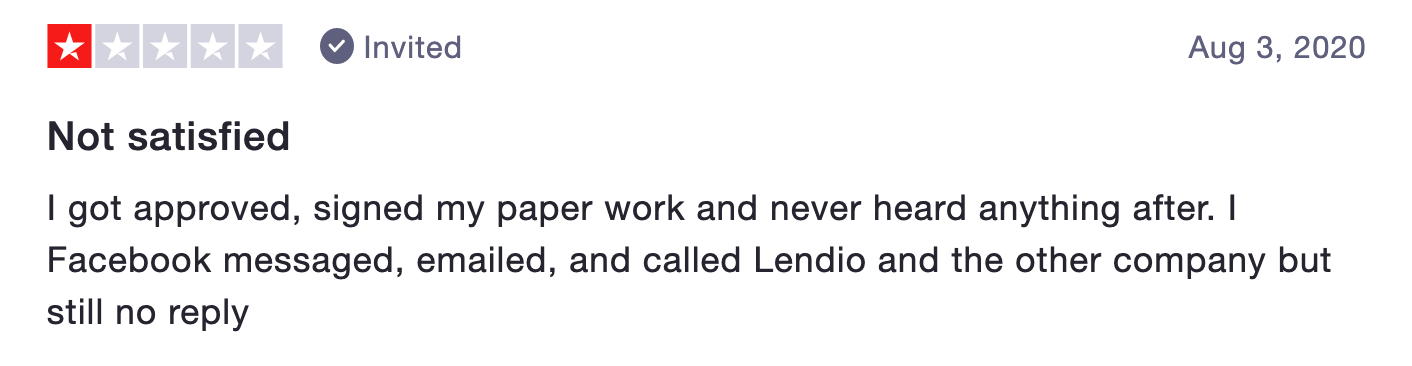
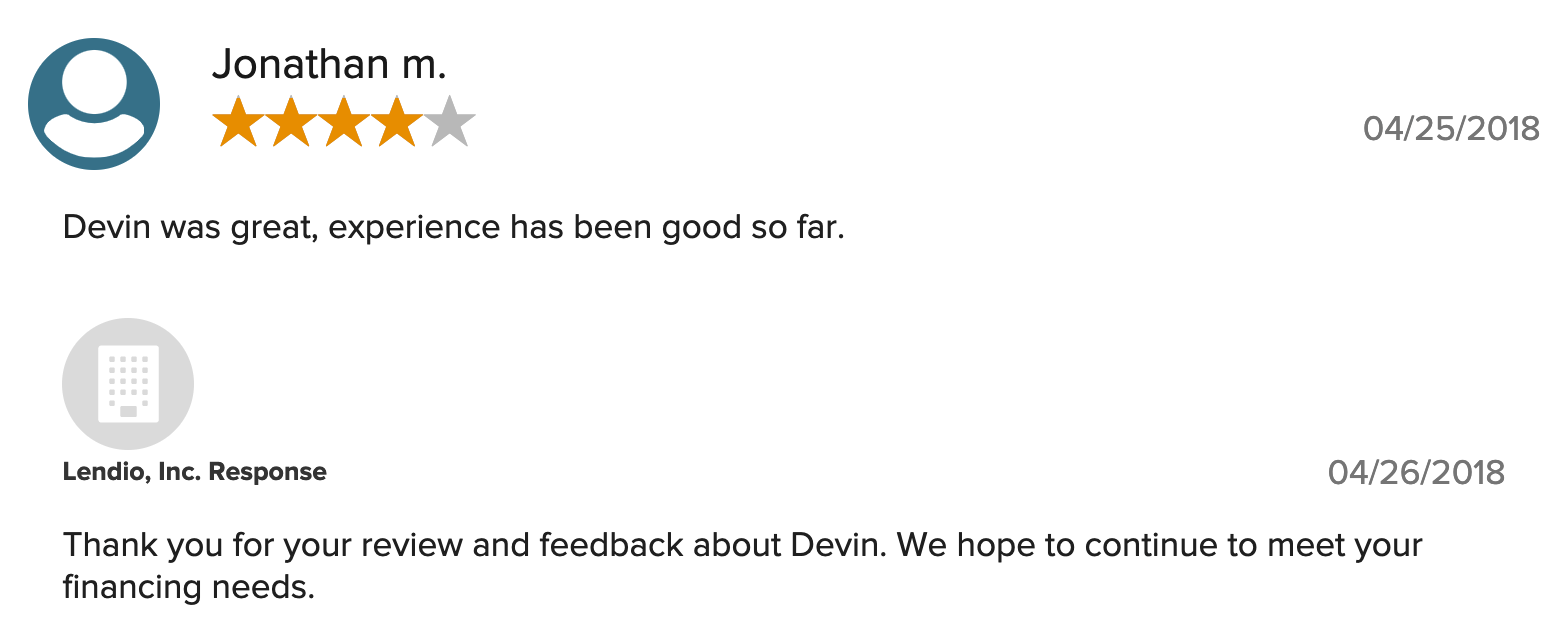
On one hand, you’ll see 5-star reviews like the one above. Then, on the other, you’ll come across the naysayers. Take the following, for example: 

Lendio reviews TrustPilot

Even if they make up a small portion of feedback, this caliber of review is enough to make you think twice about doing business with a financial company. 

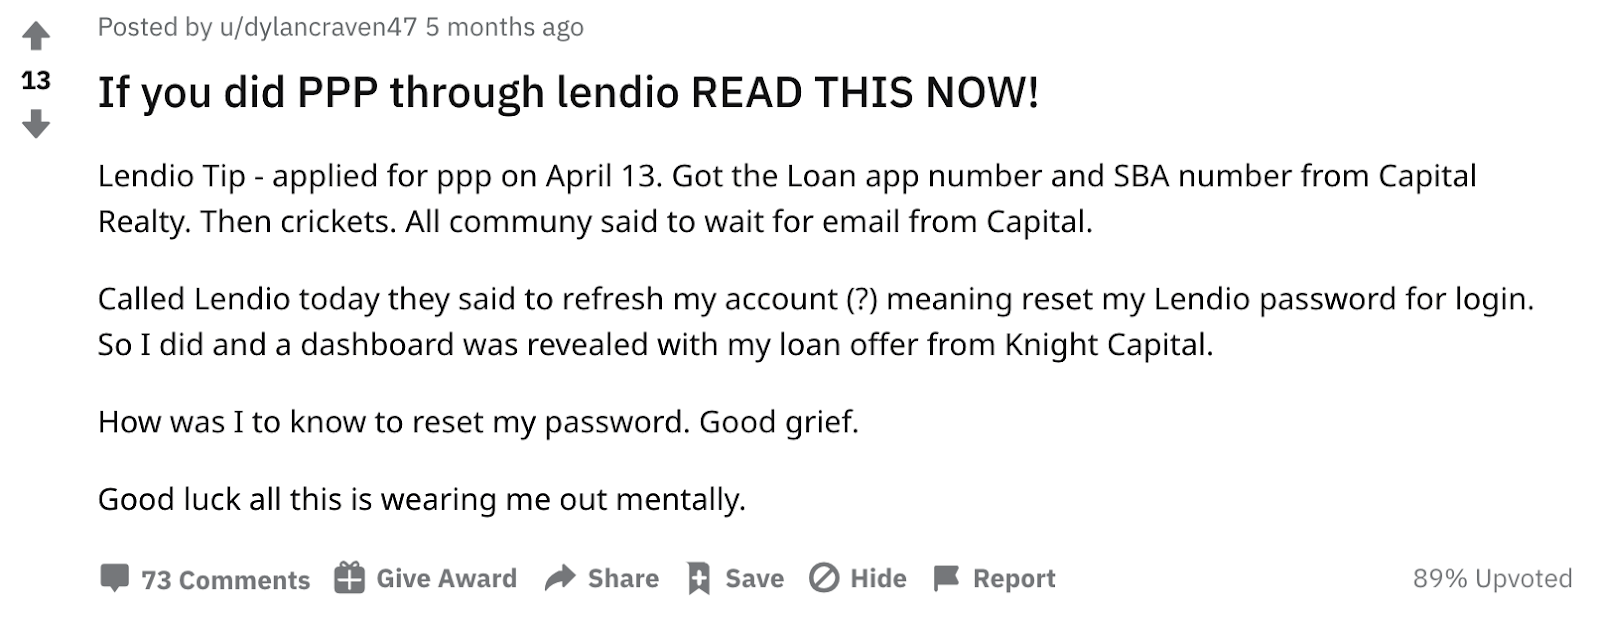
If you check out forums like Reddit, you might read about wonky system glitches. 

Lendio reviews Reddit

Then, if you dig further, you may find that Lendio, Inc. is not BBB accredited and they have mediocre ratings on the platform.

Lendio reviews BBB

So, what should you make of this confusion?

First of all, I need to point out that 2020 has been a whirlwind. I don’t know of a single company who didn’t face unexpected challenges this year. Our proverb for the year should be, “Have patience and trust the process.” Now that we got that out of the way, let’s just say that it is what it is. 

Very few  brands have a 5-star rating across the board. And, this doesn’t mean that they aren’t helpful or legitimate. TrustPiolt and BBB are designed for consumers, and most people don’t run to them when they have a great experience. But, if you have a bad experience, you want people to know. 

Therefor, I recommend that you read the reviews, trust that you might expect similar results, but don’t judge too harshly based on the bad experiences. Many business owners have leveraged this platform and marketplace to grow their businesses. If the system is a good fit, you could be one of them. 

+Bonus: A Quick Look at Lendio’s Franchise Offer

Before we wrap up, I want to mention another feature of Lendio’s offer in case you were wondering. Since 2016, they’ve presented the option to Franchise their offer for your own gain (up to 70% commission to keep for yourself).

In most US states, excluding California, Utah, and North Dakota, franchise opportunities are open to the public. So, if you live in any other state, you have excellent business networking skills, and you’ve got $55-65K to invest, this might be worth looking into.

Final Answer: Is Lendio Legitimate? 

Yes, Lendio is an established, trustworthy company. They’ve helped many small business owners get financed. However, this is not the funding marketplace I recommend. Instead, I have more trust in Nav and feel that their offer provides more value while giving the business owner heightened control over the funding process. 

If you want to learn how to build business credit so you can obtain up to $100K in funding in 30 days, enroll in Business Credit Workshop today.
Fundbox Review: Are These Lines of Credit Legit?

September 23, 2020 By Joe

Fundbox review

When you’re in a pinch or you want to scale your business operations, you might turn to online lenders for working capital. Fundbox loans (which are actually revolving lines of credit) are a popular option right now. You may even be considering applying with the company. Before you do, read this. 

Here, you’ll learn everything you need to know before you make a critical business financial decision. This is what we’ll cover: 

  • What is Fundbox?
    • Frequently Asked Questions:
    • How Does Fundbox Work?
      • 1. Fundbox Credit
      • 2. (Previously) Fundbox Pay Net Terms
      • 3. (Previously) PPP Loans
  • Fundbox Line of Credit Requirements
    • Personal Guarantee Requirements
    • Prohibited Businesses
  • Does Fundbox Report to Credit Bureaus?
  • Final Takeaway

Now, let’s get to it! 

What is Fundbox? 

Fundbox login

In a nutshell, Fundbox is a fintech company that extends working capital in the form of revolving credit lines to companies that make at least $50K per year. 


Frequently Asked Questions: 

Where is Fundbox located?

Fundbox is headquartered in San Fransisco, California. 

Who owns Fundbox?

Eyal Shinar is Fundbox’s founder and executive chairman, previously CEO. 

How big is Fundbox?

According to Crunchbase, Fundbox currently has 17 team members, 25 investors, and $453.5 million in funding as of September 2020. 

Where does Fundbox funding come from?

Lines of credit and loans are made directly by Fundbox and by First Electronic Bank. 

How much is Fundbox worth?

Fundbox valuation was estimated at $750 million in 2020, according to Forbes. 


How Does Fundbox Work? 

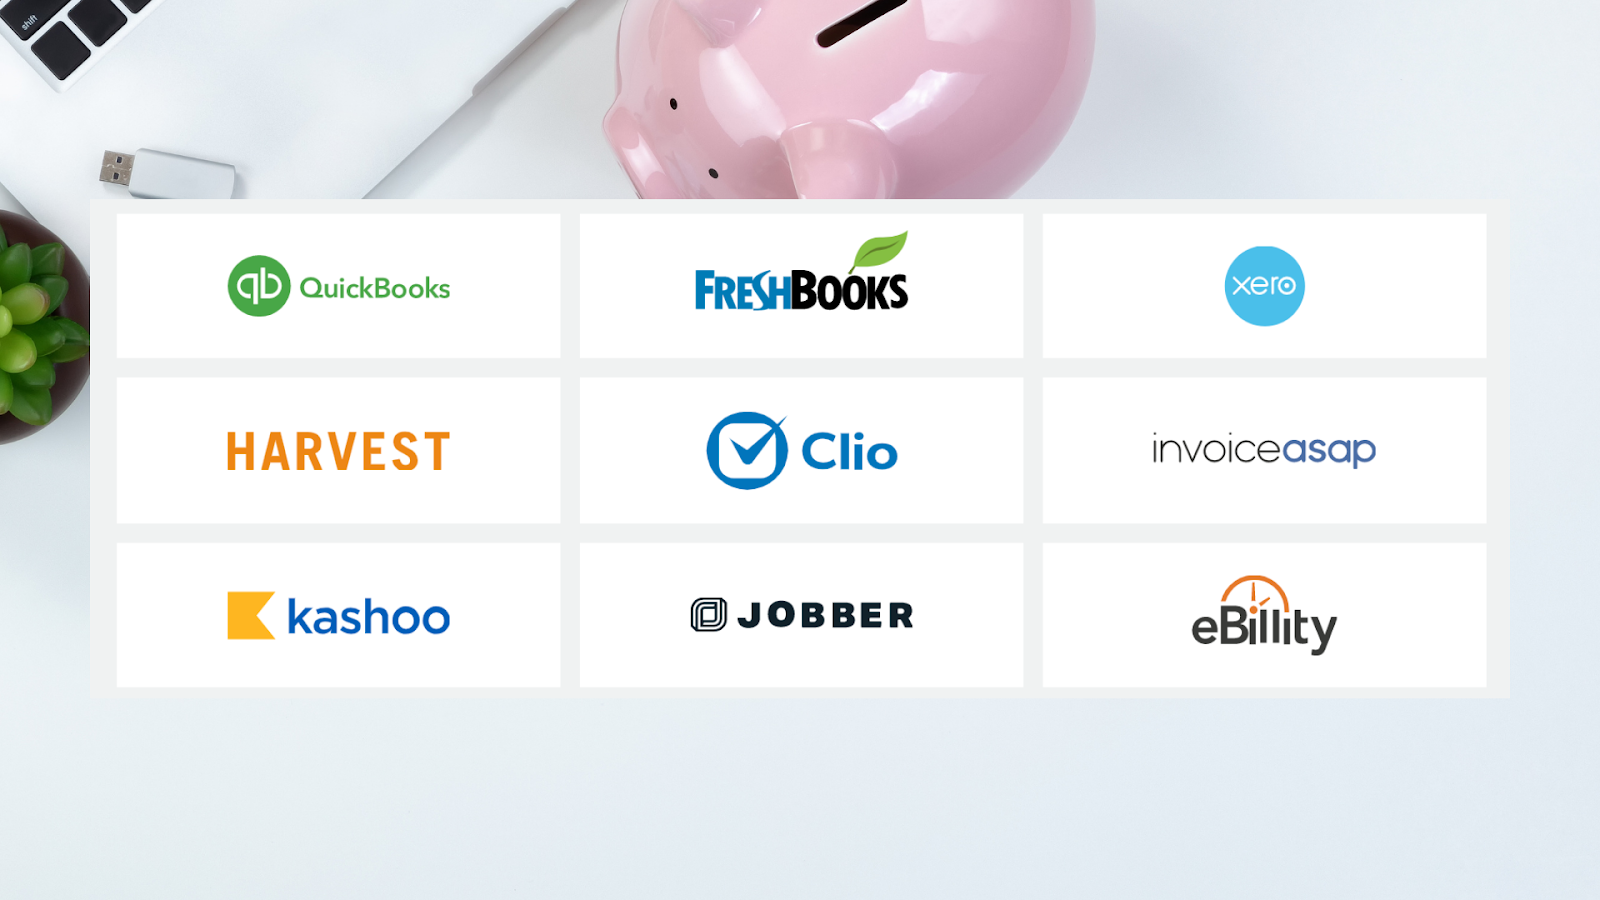
Fundbox uses predictive modeling to help small businesses and freelancers optimize their cash flow. Essentially, a company connects Fundbox to its accounting or invoicing platform and business bank account to prove cash flow. The system analyzes accounts, which takes a few minutes. After that, the business is automatically approved or denied access to funding through the platform. 

Quickbooks Fundbox review

While the database of supported online banking software is massive, not all banks are accessible through the platform. So, some users who do their business banking at very small community banks or credit unions may not have access to Fundbox’s financial services for this reason alone.  

Furthermore, only business bank accounts qualify. So, freelancers or contractors who use a personal checking account for both personal and business use will be unable to use the service (yet another reason why you must have a business checking account). 

Once you’re set up in the platform, you may qualify for business credit. Learn more about each offer below. 

You might also like: Torro Business Funding Review: Is This “Zero Hassle” Offer Legit?

1. Fundbox Credit 

After your account is set up, you may get an offer for a revolving credit line in hours or minutes. You can then draw funds directly from your Fundbox dashboard to your business checking account for a maximum of $50K on your first draw. These funds must then be repaid weekly within the set repayment period. 

Reddit Fundbox review

Repayment periods on Fundbox credit might be 12-24 weeks. And, if you repay early, you will save on interest, which starts at 4.66% for a 12-week plan and goes up from there. And, “revolving” means that once your funds are replenished, you can draw from your limit repeatedly. 

Periodic account reviews may increase or decrease your funding limit and/or interest rate over time. 

2. (Previously) Fundbox Pay Net Terms

Typically, net 30 vendors that report to business credit bureaus are one of the first stops when establishing business credit. With Fundbox Pay, businesses could apply to send or accept payments for products and services with net terms. 

Vendors who wanted to accept payments with net terms could apply as a merchant on the platform. Or, buyers could invite their vendors to the platform for the ability to buy now and pay later. It was a convenient funding option for businesses who were temporarily tight on cash. 

Unfortunately, as of about a month ago, Fundbox no longer offers a net terms product. 

3. (Previously) PPP Loans

While the application period for PPP loans, as outlined in the 2020 US stimulus, has passed, we should still acknowledge this offer. The reason it’s important to note is that if there is another round of similar financial offers in the future, Fundbox could be a potential funding source. 

Is Fundbox legit for PPP

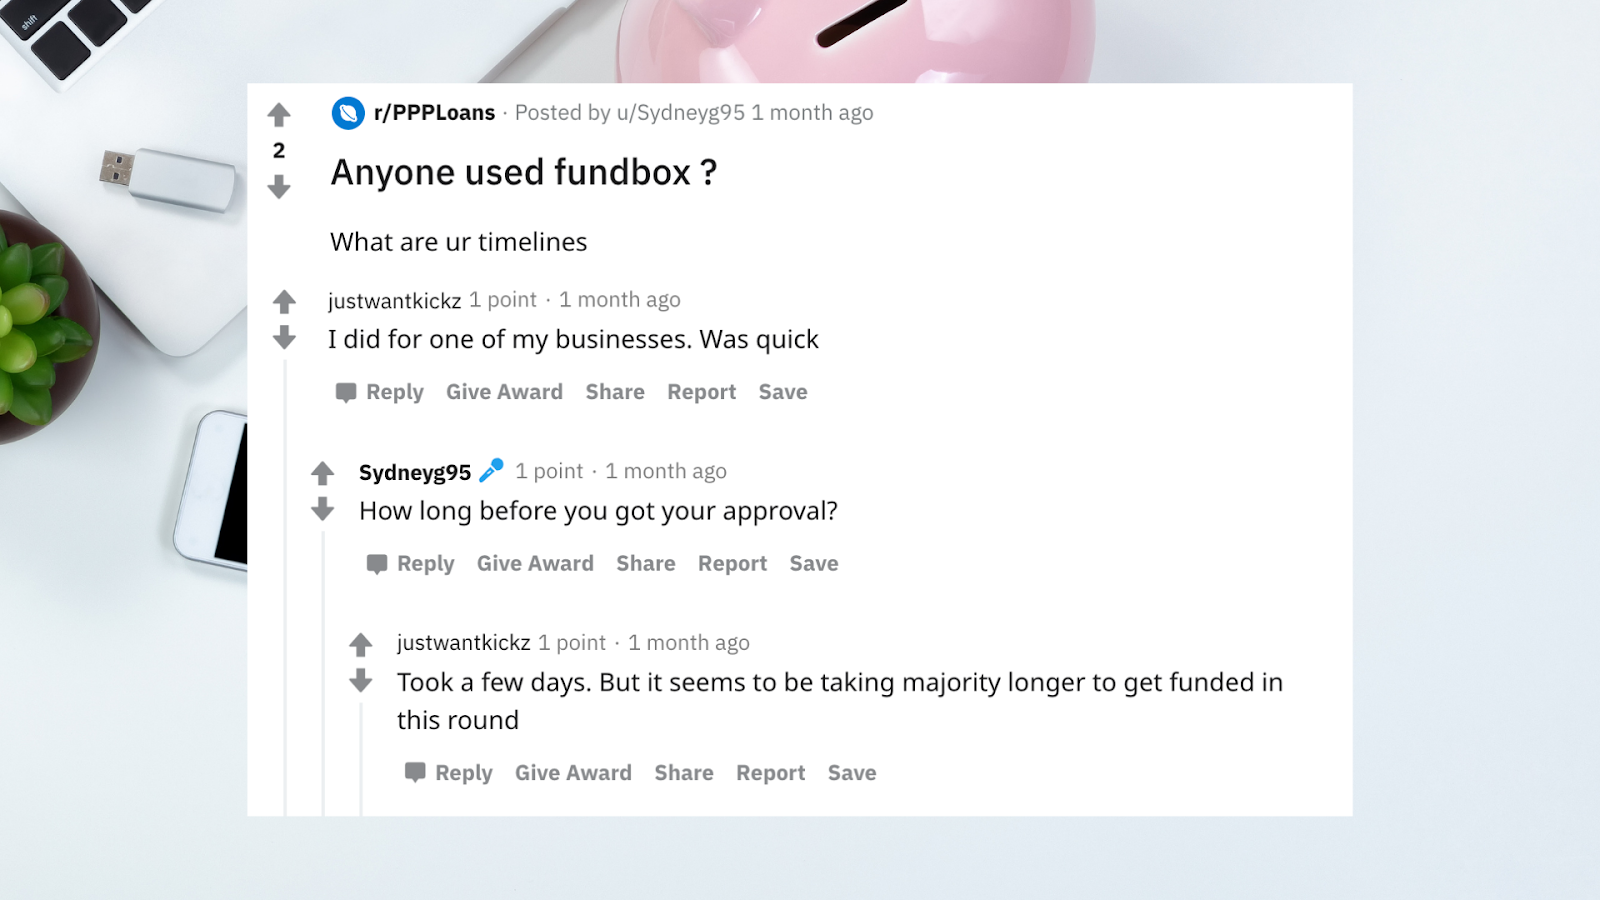
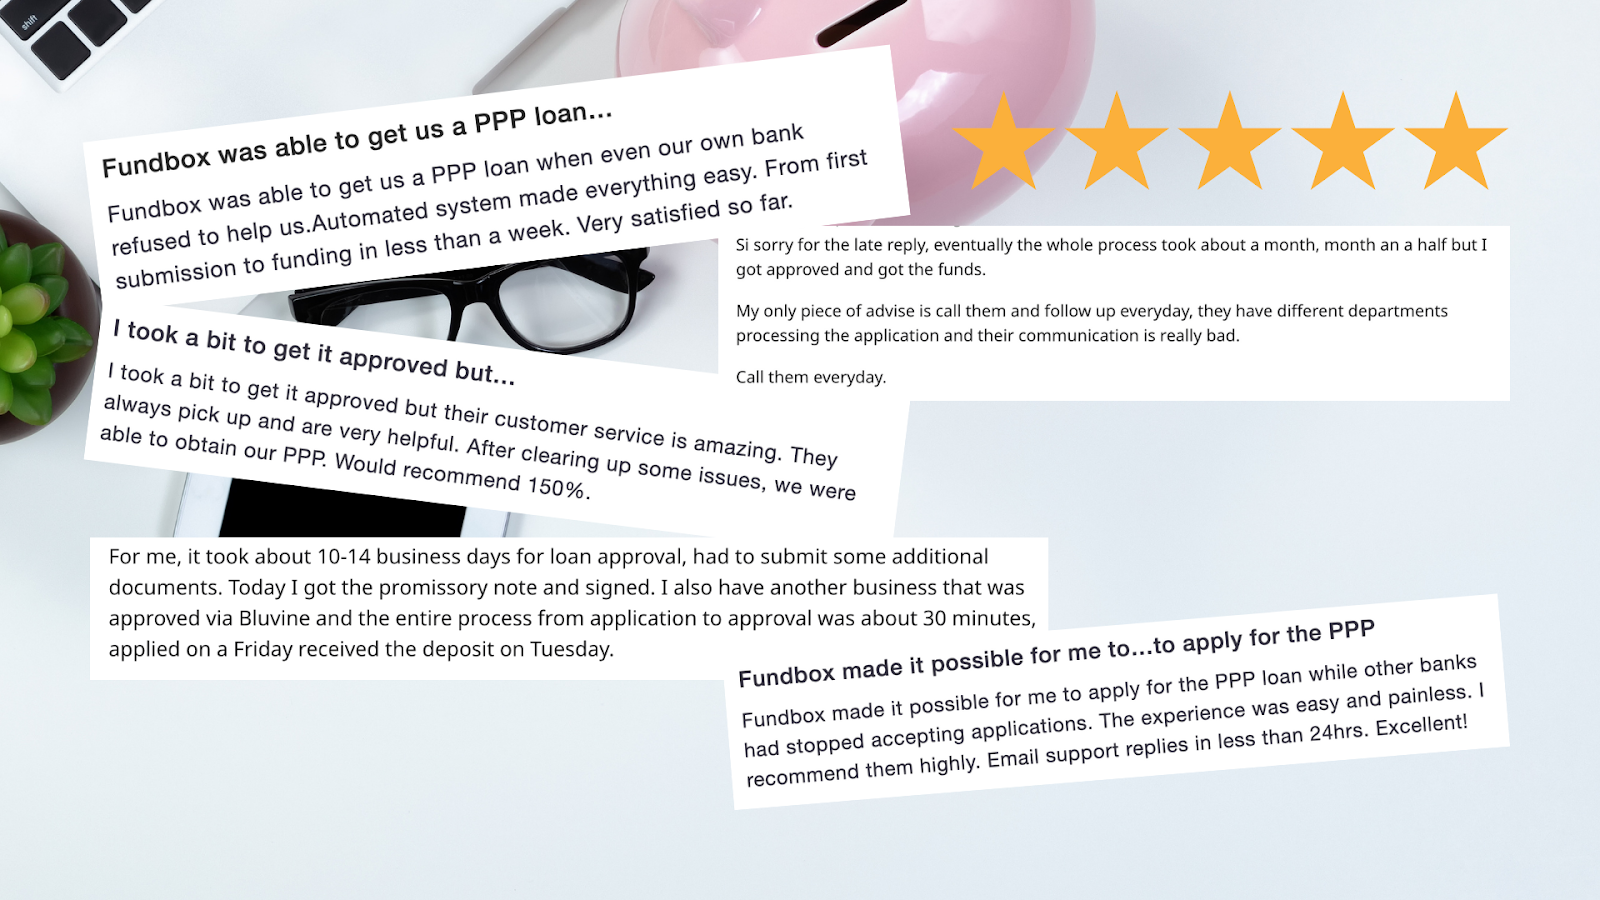
Fundbox PPP loan reviews are pretty much unanimously positive. The only complaint that applicants seemed to have was that the process took awhile. But, while these applicants waited from a couple of weeks to a month for approval, we’ve all heard of others who waited even longer.  

Fundbox Line of Credit Requirements

As stated above, Fundbox borrowers must have a business checking account. In addition, the platform has other (relatively relaxed) requirements. If you have at least three months of business checking transactions that show activity that proves around $50K or more in annual revenue, a soft pull to your credit report that shows a minimum 500 personal credit score can qualify you. 

Trustpilot Fundbox review

In some cases, the platform may conduct a one-time hard pull. And, at least two months of history in a compatible accounting software might allow you to bypass the three-month banking history condition. But, if you connect the platform to a personal bank account, you will not be approved. 

Personal Guarantee Requirements

These loans/credit lines do not require a personal guarantee. So, if your business defaults, you will not be held personally responsible. However, the proprietary algorithm that makes funding approval decisions makes it unlikely that this will happen — only companies who show the likelihood of repaying the loan will be approved. 

Prohibited Businesses 

If you’re in a questionable line of business, you already know that some major platforms might reject you. And, that could be the case with Fundbox as well. 

Businesses in the following industries are prohibited: 

  • Adult services and entertainment
  • Weapons and firearms
  • Gambling and online gaming
  • Drugs, dispensaries, and paraphernalia 
  • Money service businesses 
  • Not-for-profit organizations 

Unfortunately, if your business falls under one of these umbrellas, you’ll need to look elsewhere for capital. 

Does Fundbox Report to Credit Bureaus? 

Business owners who receive funding might want to know if Fundbox reports to major credit bureaus. This is important because loans that are not reported will not have a positive impact on your business credit score.  

Unfortunately, at this time, Fundbox does not report to D&B or any other business credit bureaus. So, any payments you make toward funding will not have an impact on your business credit. 

Final Takeaway

So, yes, Fundbox loans and lines of credit are completely legit. The proprietary software can help businesses access working capital fast without too many hoops to jump through. But, there are some limitations that might lead business owners in another direction. If you’re interested in learning how to get $100K in business lines of credit in 30 days, sign up for Business Credit Workshop.

Credit Secrets Book Review: Can You Erase Bad Credit History?

August 31, 2020 By Joe

Credit Secrets book review
Credit Secrets - As Seen On Larry King Special Report

Discover the program now helping over 1 million Americans finally get the credit scores they deserve

Buy Now
Lasso Brag

Business credit coaching clients come to me often with a fundamental dilemma — they need to repair their personal credit before they can obtain high business credit limits. While I do teach how to obtain business credit without personal guarantees, clearing up personal credit can be a massive weight off your shoulders and opens you to a world of options. The Credit Secrets book by Scott and Alison Hilton claims to have all the answers. But, does it really?

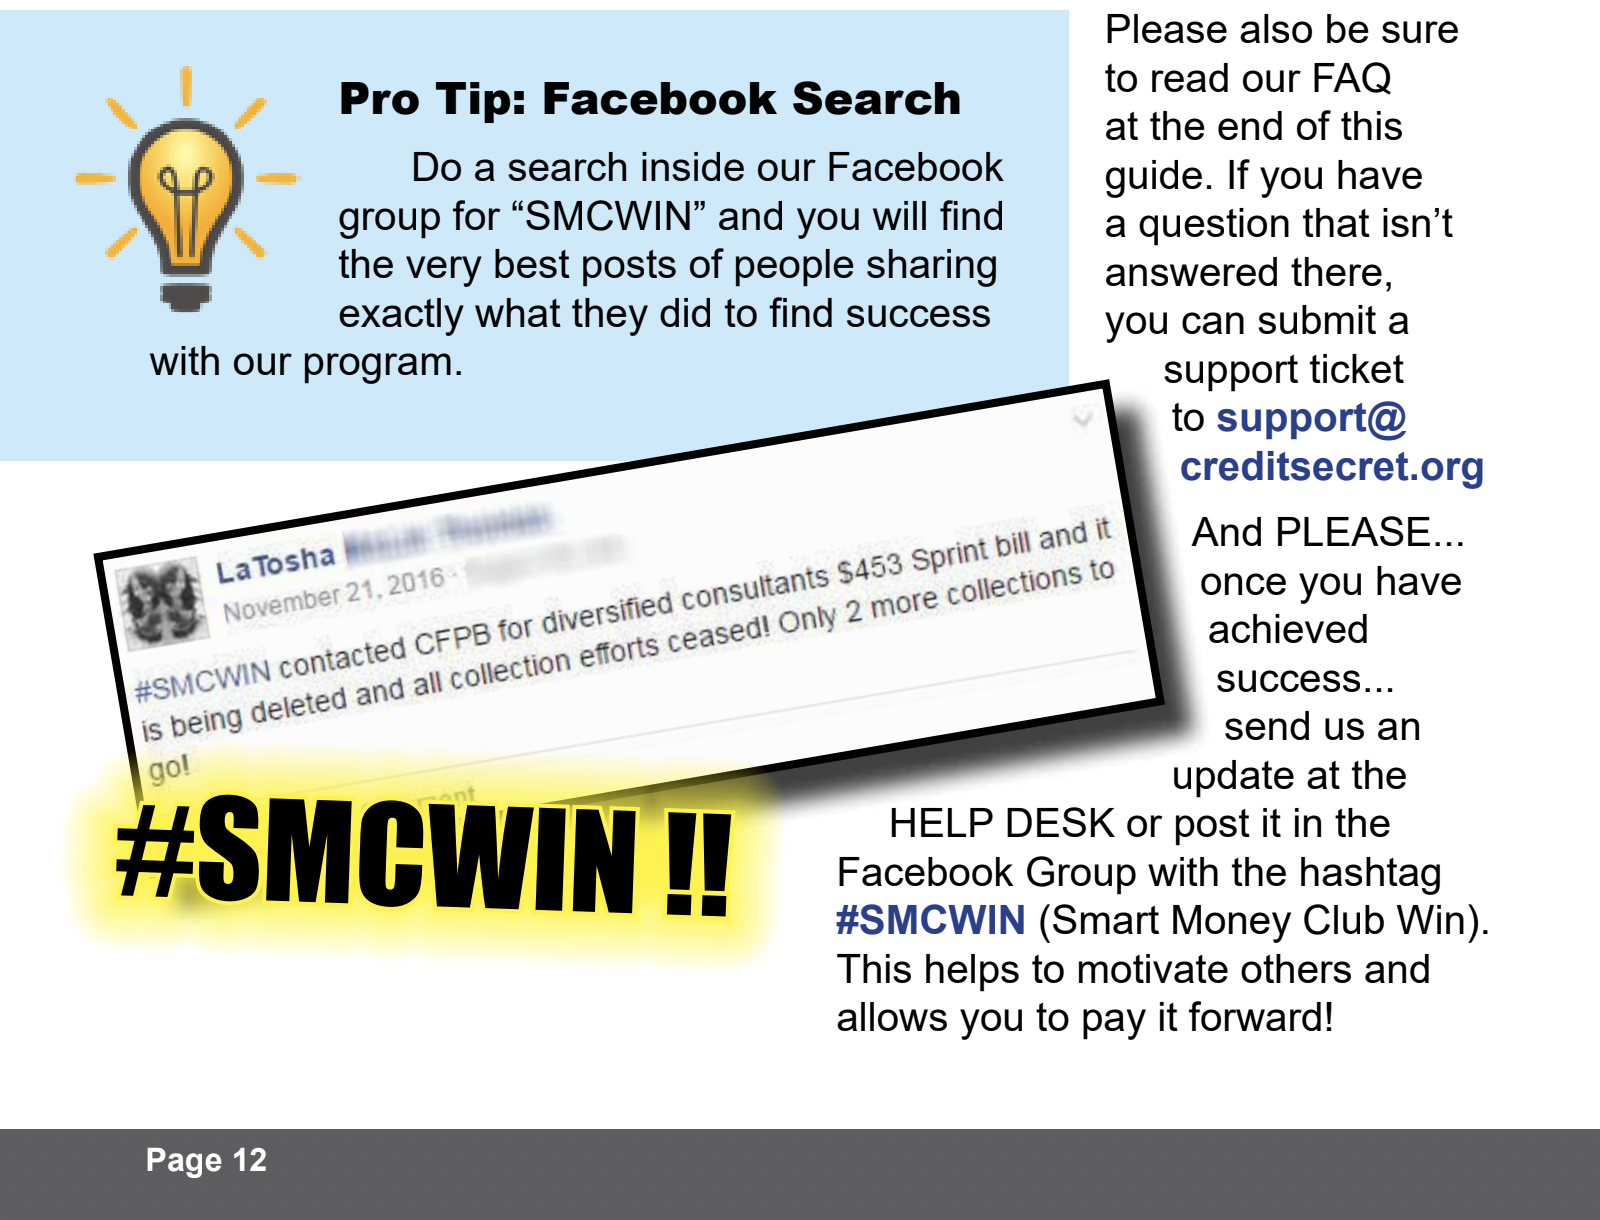
I’ve read the book, I’m a member of the Credit Secrets Facebook group, and my career was built on credit consciousness. Here’s my honest and straightforward review of the program.

This is what I’ll cover: 

  • What is Credit Secrets All About?
    • Here’s What Readers Have Had to Say
  • What Questions Does the Book Answer?
    • What Will You Learn About Consumer Protection Laws?
      • How Much is the Credit Secrets Book?
    • What are the Free, Added Bonuses?
    • The Facebook Group
    • +The Money-Back Guarantee
  • Credit Secrets Automator Software
  • Frequently Asked Questions
  • Final Thoughts

Now, learn what you’ll get if you take advantage of the offer. 

What is Credit Secrets All About? 

Credit Secrets website Credit Secrets phone number

Credit Secrets (yes, I’m referring to the book that was featured on Larry King) is nine chapters of advanced credit hacks. 

  1. Getting Started
  2. Getting Inaccurate / Incomplete / Unfair / Unverifiable Items Removed
  3. Advanced Tactics
  4. Lawsuits
  5. ChexSystem Removals
  6. Student Loans, Repossession, and HIPAA
  7. Advanced Credit Techniques
  8. Frequently Asked Questions
  9. Statute of Limitations Chart 

In the end, the book includes a glossary of credit terms used in the text. 

Consumer credit reports are filled with errors that often go overlooked. But, if you know what to look for, you can leverage these errors to your advantage; this is the premise of the book. In a sense, you can erase bad credit history with the knowledge you unearth after reading the Credit Secrets book. 

Credit secrets book PDF

In a nutshell, you will learn to make it seem as if credit bureaus will have an easier experience removing negative items from your credit report than leaving them there. And, you will learn what to do and what not to do. 

Here’s What Readers Have Had to Say

When you visit Credit Secrets’ website, you see a ton of reader reviews, all touting the system as a lifesaver. But, what will you find when you poke around other corners of the web? 

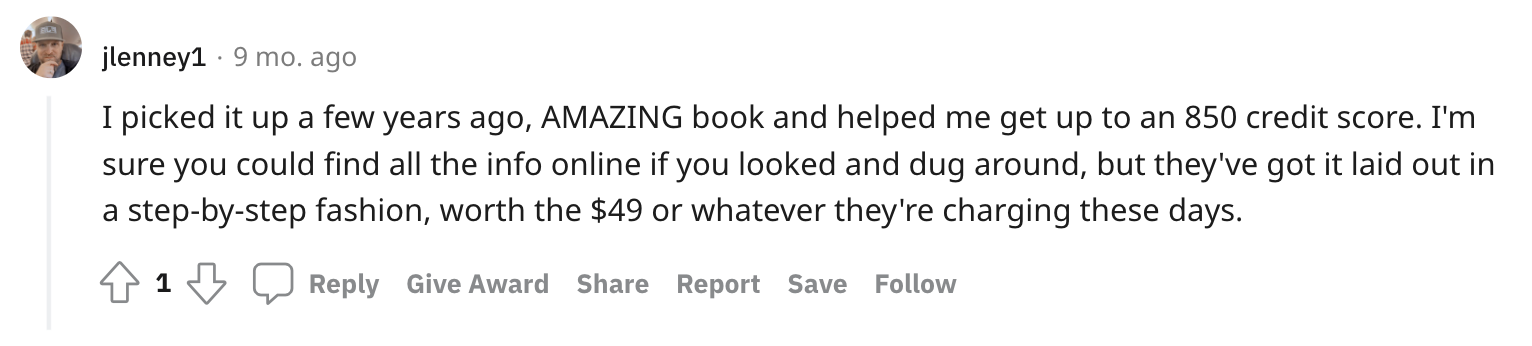
Redditors are mostly wary of the platform… however, those naysayers seem to be people who haven’t actually purchased the book and additions. Those who have used the system, say that it helped them increase their credit score.   

Credit secrets reviews

One reader even got their score up to 850, which is about as good as it gets. 

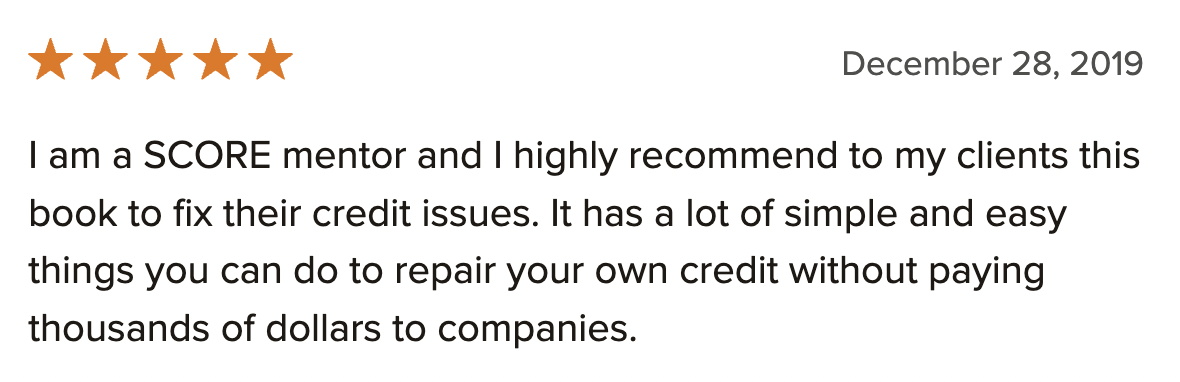
On Goodreads, Credit Secrets has a 4-star rating, with primarily rave reviews. Readers are saying that they got their FICO score up to 730, 779, and the “high 700s.”  One “score counselor” attests that he shares the book and system with his clients all the time. 

How can I get a 700 credit score in 3 months?

All-in-all, people who actually read the book and work the system are completely satisfied with Credit Secrets’ offer. 

What Questions Does the Book Answer? 

This book is a step-by-step guide for rebuilding credit, even in the most complicated scenarios. If you seek answers to questions like the following, you’ll find them in Credit Secrets.  

  • What is the best way to deal with defaulted loans and vehicle repossession? 
  • What can I do to recover from bankruptcy or foreclosure? 
  • Can I remove liens and judgments from my credit report?  
  • How do I file a credit dispute and what can be disputed? 
  • What is the fastest way to rebuild bad credit? 
  • How can I get out of ChexSystems? 
  • How can I raise my credit score? 
  • How long does it take to rebuild credit history?
  • What do I need to know about consumer protection laws? 

And, they’re not just general answers that you can already find online. Most chapters include step-by-step tutorials, including common legal loopholes, as well as letter templates to send to creditors and credit bureaus. 

Credit secrets book page 88

What Will You Learn About Consumer Protection Laws? 

Now, what really sets this book apart from other personal credit repair offers is that it lays out the steps you can take to file small claims lawsuits against creditors, credit bureaus, and collection agencies. The authors share 17 common reasons that you could legally take these parties to court, which laws you should understand to identify if you’ve been wronged, and the dollar amount of damages (fines) you could be able to collect in court. 

For example, credit bureaus are required to respond to certain consumer communications within a set amount of time. Creditors have caused injury if they report inaccurate information. Collection agencies must abide by strict laws that they often do not follow. Once you know your rights, you may find that certain negative aspects of your credit report are legally invalid. 

Credit secrets book free

In addition, the book includes courtroom tips that can better your chances of success. These tips are followed by real-life examples of lawsuits won by consumers, both anecdotal from Credit Secrets members and legal citations for specific cases. Finally, you will learn how to find a registered agent and when you must hire legal counsel. 

*Keep in mind that the authors of this book are not attorneys. You should always seek professional counsel when seeking legal advice. 

Still, what you learn by implementing the guidance shared in the Credit Secrets book can have a major positive impact on your financial health and personal credit scores; this book has all the information you need to see amazing results. In fact, it is better than many credit repair services, as long as you’re willing to put in the work.