• Home
  • Free Funding Guide
  • What We Offer
    • Products
    • Services
    • Free Guide
  • About Us
  • Contact
  • Sign Up

  • Ask Joe Any Question!
  • Business Credit Cards
  • Business Line of Credit
  • Topics

TIN vs. EIN: What’s the Difference and Why Do You Need Them? 

By Joe

TIN vs EIN

Key Takeaways

  • A TIN is any tax ID used for individuals or businesses.
  • An EIN is a type of TIN used to identify businesses.
  • Sole props and single-member LLCs may use an SSN as a TIN.
  • Most LLCs need an EIN to bank, file taxes, or get licenses.
  • The IRS issues EINs, ITINs, ATINs, and PTINs; the SSA issues SSNs.
  • You can apply for an EIN free on the IRS site.
  • TINs appear on tax forms, ID letters, and official records.
  • TINs are private, but some EINs show up in public filings.

In business, we throw a lot of acronyms around: LLC, SIC, KPI… TIN and EIN are two acronyms that look similar and are often confused, but they refer to different things. 

A TIN is a broad term, while an EIN is one specific type of TIN used for business purposes. Here, you’ll learn the key differences between the two as well as when and why you need a TIN vs. EIN.  

This is what’s in store: 

  • What is a TIN vs. EIN?
    • What is a TIN?
    • What is an EIN?
  • Do You Need a TIN for Your LLC?
  • Where to Find Your Tax ID Number
  • Frequently Asked Questions
  • Final Takeaway

Now, let’s learn! 

What is a TIN vs. EIN? 

In short, a TIN is a “Tax Identification Number,” and an EIN is an “Employer Identification Number.” Both are issued by U.S. federal agencies to individuals or businesses for tax purposes. Let’s take a closer look at each.

Disclaimer: This article is for general information only and isn’t tax advice. For help with your specific situation, talk to a qualified tax professional or accountant.

What is a TIN? 

How to get a Tax ID number

A Tax Identification Number (TIN) is a unique number the Internal Revenue Service (IRS) uses to identify individuals or businesses for tax purposes. It can refer to a Social Security Number (SSN), an Employer Identification Number (EIN), or an Individual Taxpayer Identification Number (ITIN), depending on the situation.

A TIN may be issued by the Social Security Administration (SSA) or the IRS. 

Type of TINIssued ByUsed For
Social Security Number (SSN)SSAIdentifying U.S. citizens and eligible residents for tax and employment.
Employer Identification Number (EIN)IRSIdentifying businesses, estates, and trusts for tax filing and reporting.
Individual Taxpayer Identification Number (ITIN)IRSIdentifying individuals not eligible for an SSN, often nonresident aliens.
Adoption Taxpayer Identification Number (ATIN)IRSTemporary ID for adopted children until an SSN is assigned.
Preparer Tax Identification Number (PTIN)IRSRequired for paid tax return preparers.

You might also like: Sole Proprietorship VS LLC: How to Choose Your Entity Wisely 

What is an EIN? 

Tax ID number for business

An EIN is a type of TIN that the IRS assigns to businesses. It’s used to identify a business entity. So, an EIN isn’t a separate concept from a TIN. It’s actually one specific type of TIN used for identifying businesses. 

Businesses may use an EIN when they: 

  • File tax returns
  • Open a business bank account
  • Apply for licenses and permits

Many business formation services offer EIN application services. I rarely recommend that you take advantage of this because you can apply for an EIN on the IRS website. It’s free and only takes a few minutes. The only catch is that online EIN applications are only available during IRS business hours, Monday through Friday. 

You might also like: Can (and Should) You Be Your Own Registered Agent? 

Do You Need a TIN for Your LLC? 

If your business will open a bank account or file taxes, yes, you need a TIN. Every LLC needs a TIN for tax and business purposes. In most cases, this means getting an EIN from the IRS—even if your LLC doesn’t have employees. 

If you’re a single-member LLC or sole proprietorship with no employees, the IRS may, in some cases, allow you to use your SSN instead of an EIN. 

Your business might not need an EIN if it meets all of the following conditions:

  • It’s a sole proprietorship or single-member LLC.
  • It has no employees.
  • It does not file any excise taxes (like fuel or alcohol taxes).
  • It does not withhold taxes for non-resident aliens.
  • It does not have a Keogh retirement plan.
  • It does not need to file employment, excise, or alcohol/tobacco/firearms tax returns.

In this case, the owner may be able to use their SSN as the business’s TIN for tax purposes. However, most banks and agencies still ask for an EIN. Some business owners co-mingle their personal and business finances, but this can lead to problems. Plus, when you manage business finances through a personal account, you aren’t generally eligible for business credit.  

You might also like: No-Doc Business Loans with EIN Only: Get Funds Without Proof of Income 

Where to Find Your Tax ID Number

Where you find your Tax ID Number (TIN) depends on the type of TIN you’re looking for.

How do I find my TIN?

The most common places to find your TIN are: 

  1. SSN → On your Social Security card, on tax documents like W-2s or past tax returns, and through the SSA. If you’ve lost it, you can request a replacement Social Security card. 
  2. EIN → On your EIN confirmation letter from the IRS (Form CP 575), on tax forms like your 1120, 1065, or payroll filings, and on business bank account documents or loan applications. If you can’t find it, call the IRS Business & Specialty Tax Line at 1-800-829-4933.
  3. ITIN → On your IRS ITIN assignment letter and on tax returns you’ve filed with the ITIN.

To look up someone else’s EIN (like a nonprofit), it may be listed on public records like Form 990s.

You might also like: InDinero Unveiled: A Detailed Accounting & Tax Platform Review 

Frequently Asked Questions

Can I use my SSN as my TIN?

When filing taxes as an individual, yes. As a business, maybe. If you’re a sole proprietor or single-member LLC with no employees, your SSN can serve as your TIN. But you’ll need an EIN to hire, open a business bank account, or get licenses.

How do I know if I have an EIN or TIN?

If you applied for an EIN from the IRS, you have one. An EIN is a type of TIN. If you use your SSN for taxes, that’s your TIN. Check past tax forms or your EIN confirmation letter to be sure.

How can I get an ITIN? 

To get an ITIN, file Form W-7 with the IRS, along with your federal tax return and proof of identity.

Is there a difference between EIN and ITIN?

Yes, an EIN is for businesses, while an ITIN is for individuals who can’t get an SSN, like some nonresident aliens.

How do I find out who a TIN belongs to?

You usually can’t because TINs are private. But, EINs for nonprofits or public businesses might appear on public tax documents like Form 990.

Final Takeaway

TINs and EINs might look similar, but they serve different roles in the world of taxes and business. A TIN is any tax ID used to track individuals or entities, while an EIN is the go-to ID for businesses. 

Whether you’re just starting out or growing your LLC, knowing which number you need—and how to get it—can help keep your finances legit, organized, and ready for whatever comes next.

Ready to learn how to obtain up to $100K in business credit in as few as 30 days? Join Business Credit Workshop today!
A Complete, Unfiltered Amex Business Gold Card Review 

By Joe

Amex Business Gold Review

Key Takeaways

  • Earn 4X points on your top 2 spending categories (up to $150,000/year), 1X on others.
  • Get 3X points on flights and hotels, no foreign fees, and trip delay insurance.
  • Manage expenses with QuickBooks, employee cards, and year-end summaries.
  • Annual fee is $375, with up to $240 in select service credits.
  • Requires good credit (700+ FICO score), $3,000+ monthly revenue, and solid business credit.
  • Includes cell phone protection, extended warranties, and purchase protection.

Have you considered applying for the Amex Business Gold card, but not sure what you’d be getting yourself into? In business, the sheer number of financial management options can be overwhelming, but let’s simplify to determine if this choice is right for you. 

In this Amex Business Gold card review, you’ll find what the card is, see a company overview, explore the benefits, and find out if (and when) it might be worth it to apply. 

This is what’s in store: 

  • What is the Amex Business Gold Card?
    • Amex Business Gold Requirements
    • Business Credit Score Impact
    • Amex Business Gold APR and Fees
  • Amex Business Gold Benefits Worth Exploring
    • 1. Amex Business Gold Rewards
    • 2. Expense Management Tools
    • 3. Travel Perks for Cardholders
    • 4. Business Services from Amex
  • Frequently Asked Questions
  • Conclusion: Is Amex Business Gold Worth it?

Now, let’s dive in. 

What is the Amex Business Gold Card? 

Why Should You Get the Amex Business Gold?

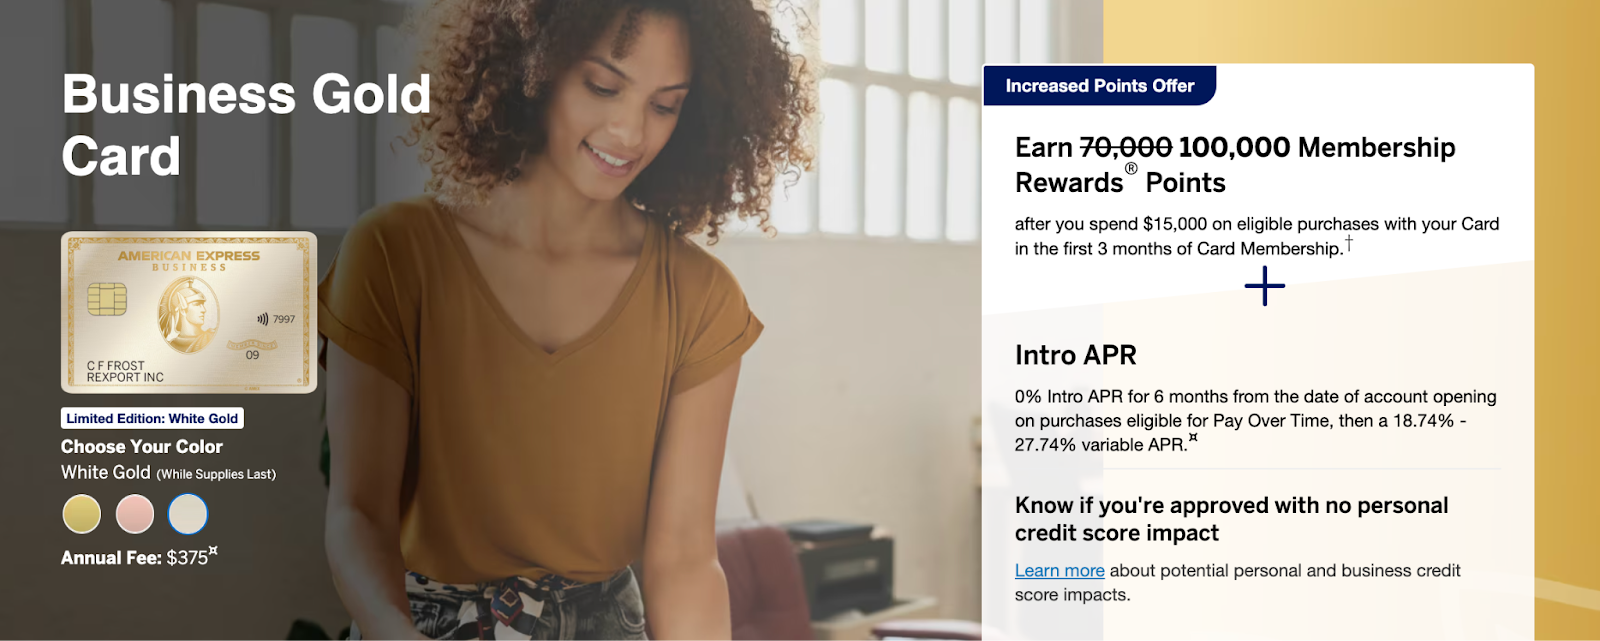
The Amex Business Gold card is a premium business credit card from American Express with a handful of standout features, including: 

  • Rewards on spending
  • Expense management tools
  • Travel perks 
  • Business services

It also offers cash flow flexibility with revolving credit, which you can pay over time when needed, along with no preset spending limit. When you apply for the card, it won’t impact your personal credit, because approval is based on your business credit score. 

You might also like: Amex Business Checking Review: What You Need to Know…Really 

Amex Business Gold Requirements

American Express Business gold card limit Reddit

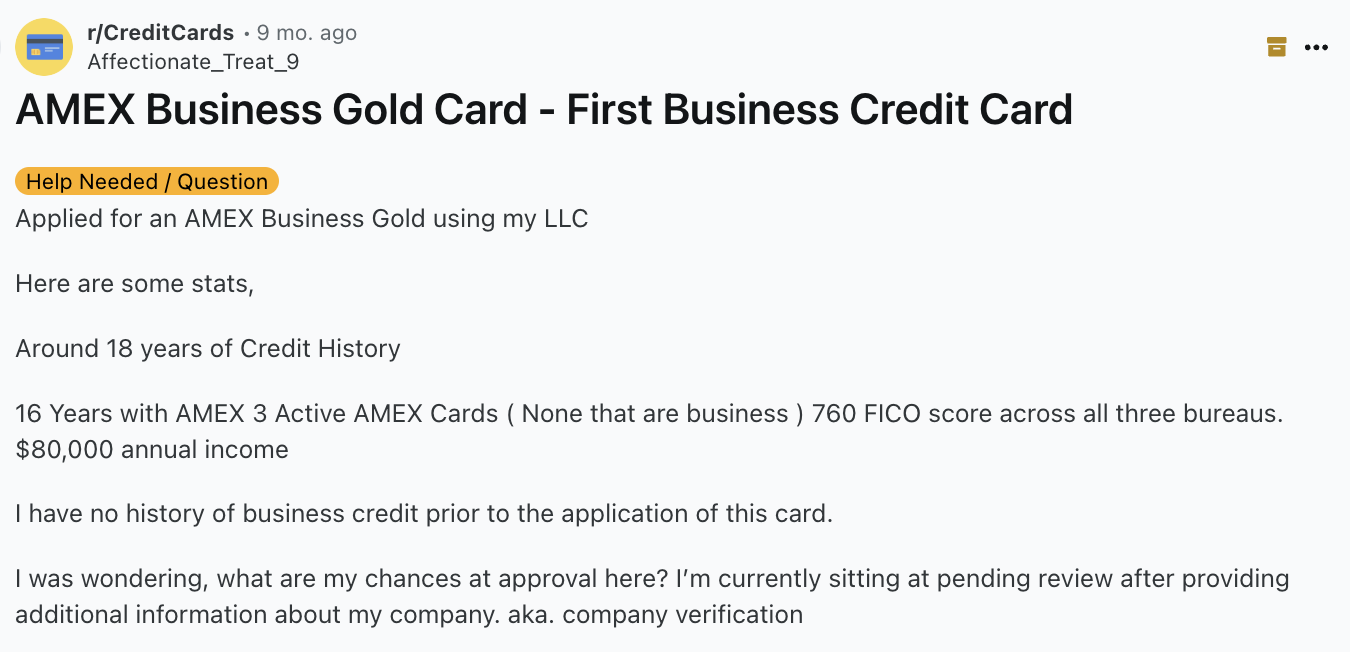
Wondering how to get an Amex Business Gold card? Well, as you may know, the requirements are fairly stringent. However, they’re not clearly specified anywhere. 

So, here’s what I know is required: 

  • Solid business credit score 
  • FICO (personal credit) score above 700
  • Average monthly revenue of at least $3K  

The more revenue you have and the higher your business and personal credit scores, the more likely you are to qualify for an Amex Business Gold card. 

Recommended: This is How to Build Business Credit Fast [Step-by-Step Guide] 

Business Credit Score Impact

When you apply for the Business Gold card from Amex, your business credit score might take a small hit because Amex may check it during the application process. Your personal credit score won’t be affected at this stage. 

However, If you’re approved and decide to accept the card, it may impact your personal credit, because you’ll likely need to guarantee the account. This means that, if the account defaults, you’re on the hook. 

This card could offer a good way to build business credit if you manage it well, but be sure you’re comfortable with any potential impact on your personal credit before accepting.

You might also like: Here’s How to [Actually] Get Business Credit With Just an EIN +More Options 

Amex Business Gold APR and Fees

Amex Gold Business review

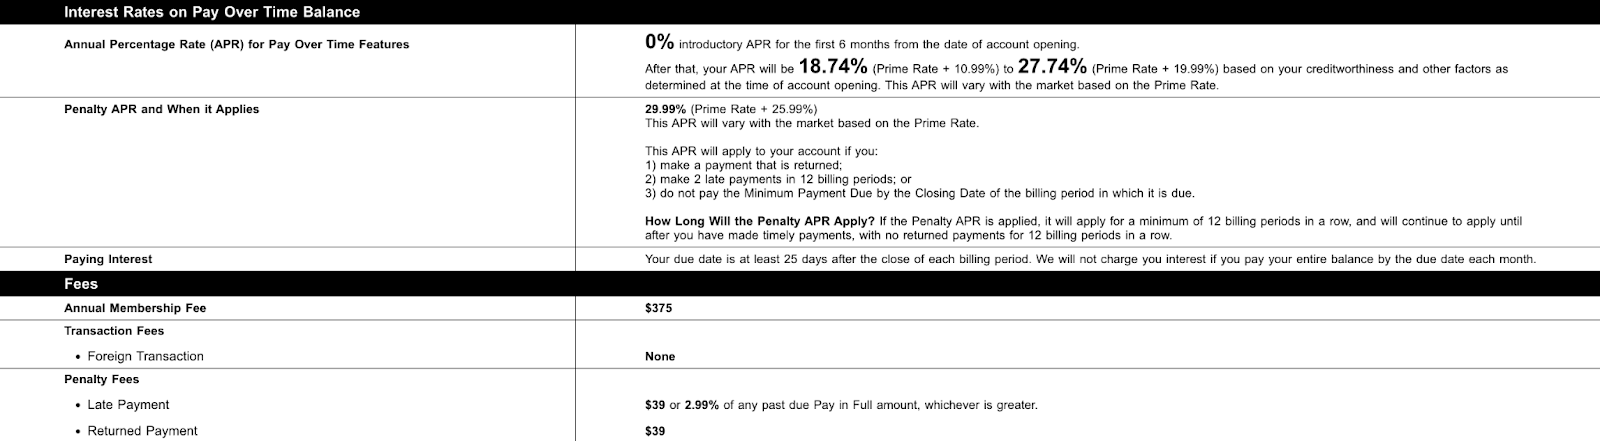
The Amex Business Gold Card offers 0% APR for the first 6 months, so no interest accrues during this time. Be mindful that the introductory 0% APR doesn’t apply to cash-like transactions or fees, and this is an intro offer, which can change any time.

After that, the APR will range from 18.74% to 27.74%, based on your credit and the Prime Rate, which can change with the market. Then, if you miss payments or have returned payments, a 29.99% Penalty APR might apply for at least a year. Paying on time helps you avoid this. 

Interest is calculated using the average daily balance method.

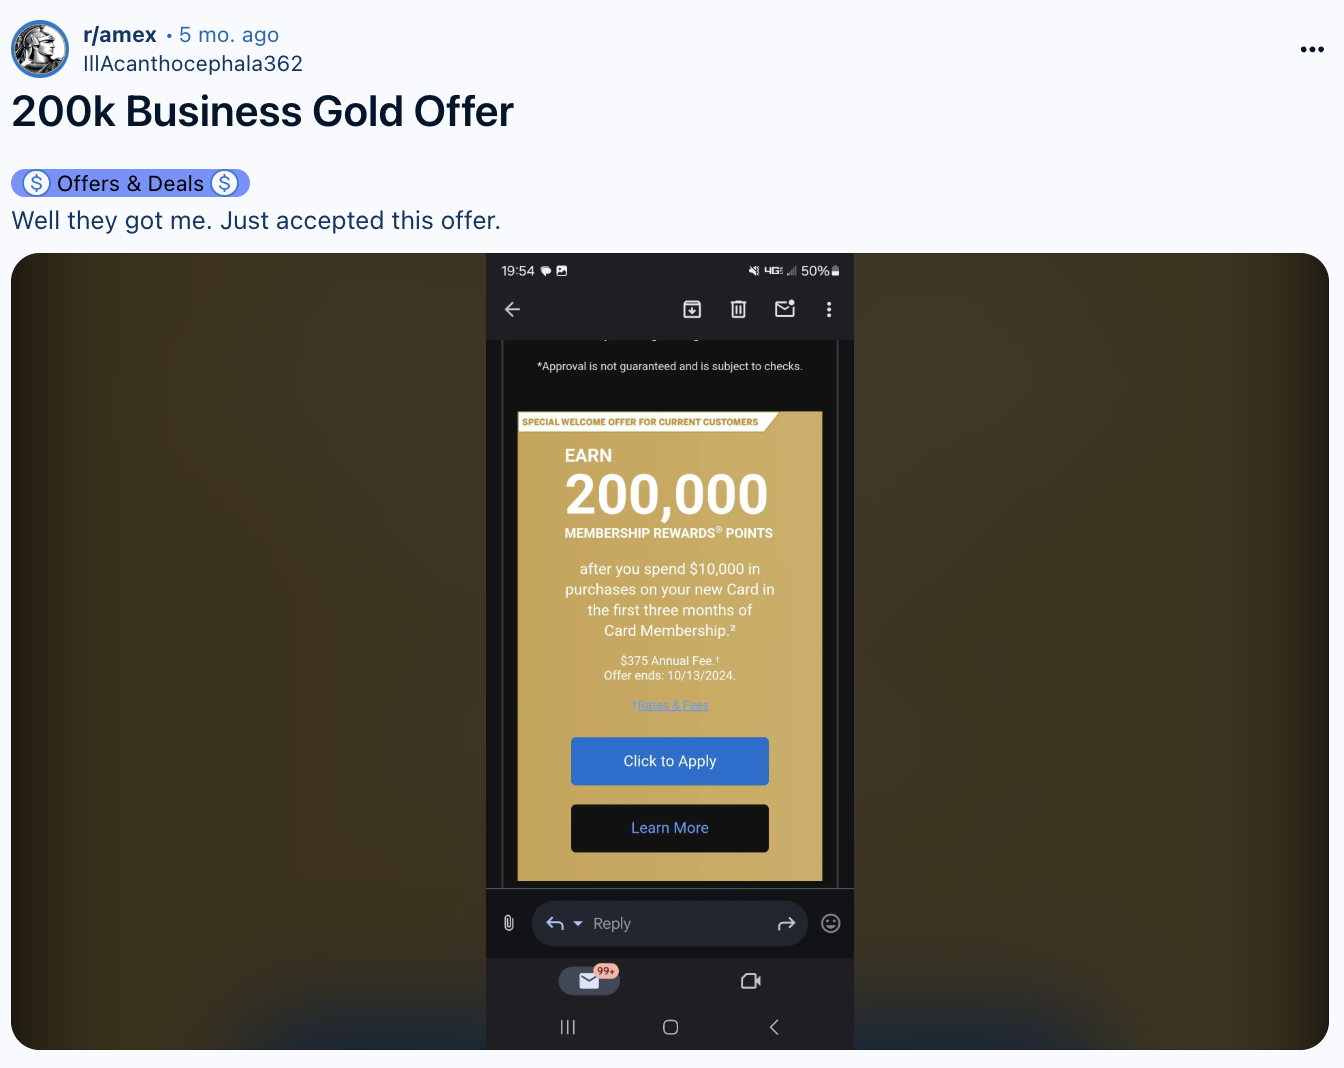
Amex Business Gold 200k

So, let’s say you spend $20,000 in a year using the Amex Business Gold Card and only make minimum payments—Here’s what you might expect: 

  • First 6 months: You pay 0% interest during the intro APR period. Assuming you spend evenly, your balance after making minimum payments (~$300/month) is about $8,200.
  • Next 6 months: The remaining balance and new charges start accruing interest at around 21.74% APR. You’d pay about $1,130 in interest over this time.
  • After a year: You’ll have paid about $5,300 in minimum payments but still owe $15,830, including interest.

Paying only the minimum can add up quickly. To save, pay more than the minimum, especially after the 0% intro APR period ends. And, to avoid interest, you can pay your balance in full by the due date, which is at least 25 days after the billing cycle closes. 

The card also has an annual fee of $375, but no foreign transaction fees. Late payments or returned payments can cost $39 or 2.99% of the past due amount, whichever is higher.

Amex Business Gold Benefits Worth Exploring

Is Amex Gold worth getting?

Now, let’s take a closer look at some of the benefits of being an Amex Business Gold cardholder, including rewards, tools, travel perks, and business services. 

1. Amex Business Gold Rewards

Amex Gold card benefits

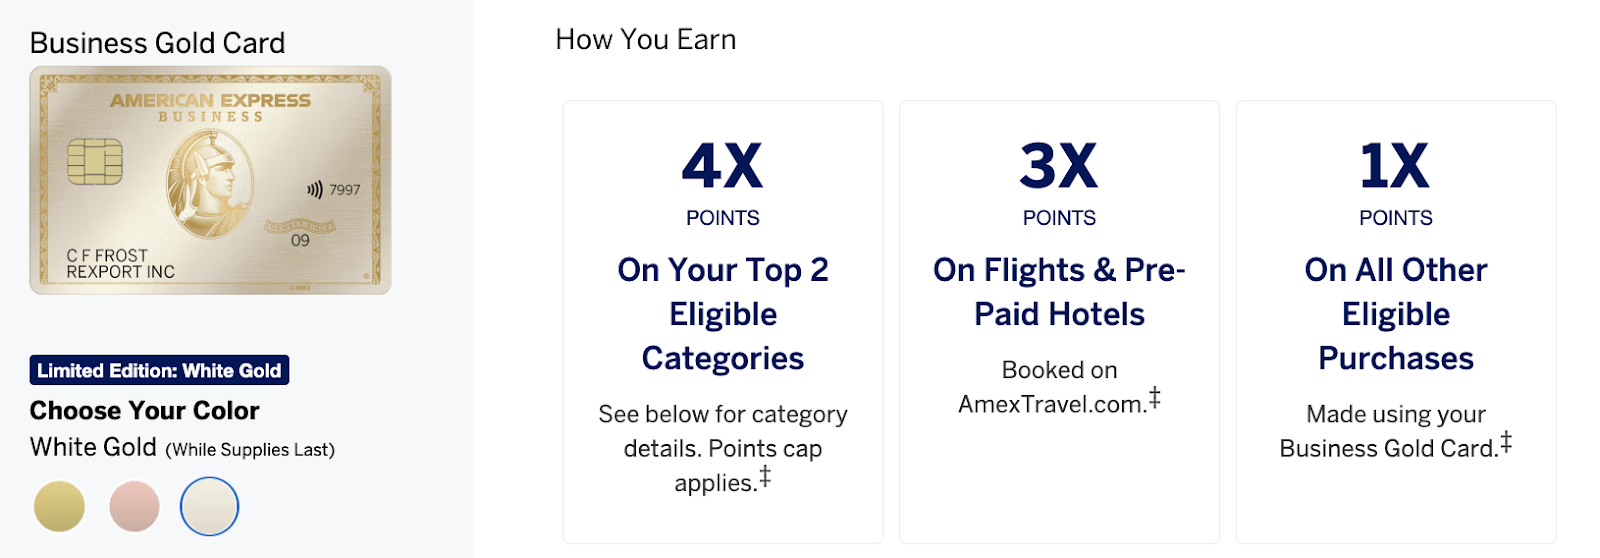
This card rewards you with 4X Membership Rewards points on the top 2 categories your business spends the most in each billing cycle, from options like restaurants, gas stations, transit, software providers, and more (up to $150,000 per year; 1X points after). All other purchases earn 1X points.

Here’s an example scenario of how this might stack up: 

  1. Let’s say your business spends $2,000 on software subscriptions and $1,500 at restaurants in a billing cycle. These would be your top 2 categories, so you’d earn 4X points on those purchases, giving you 14,000 points (4 points per dollar).
  2. If you also spend $500 on office supplies, you’d earn 1X points for that, adding 500 points.
  3. In total, you’d earn 14,500 Membership Rewards points for that billing cycle. The top 2 categories adjust each cycle based on where you spend the most.

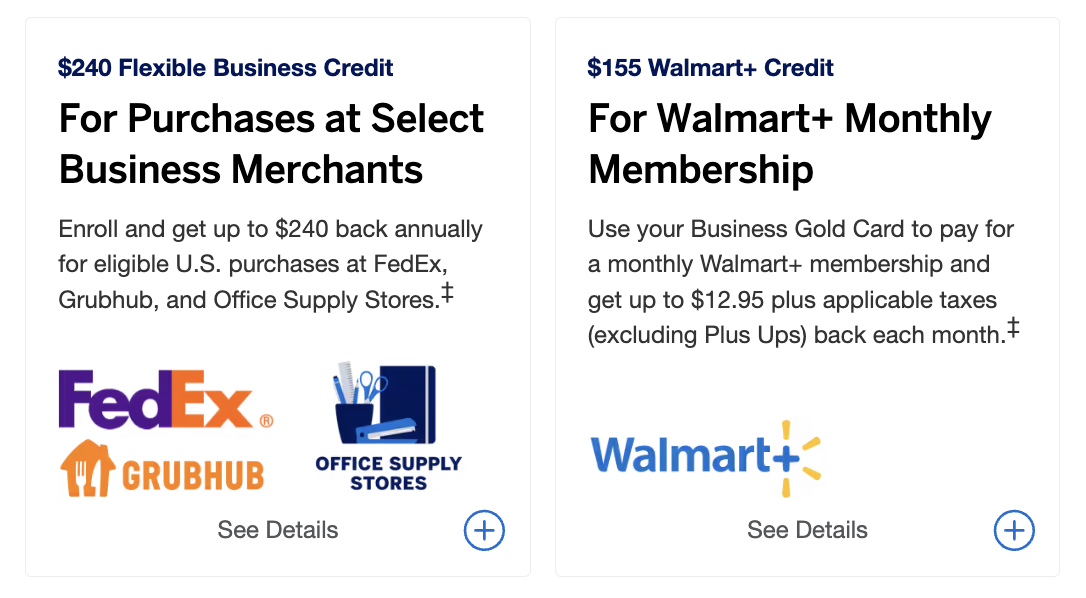
You can also get up to $240 annually in statement credits for eligible purchases at FedEx, Grubhub, and office supply stores, plus a monthly credit for a Walmart+ membership (up to $12.95/month). 

This could be a great way to earn points and save on business essentials.

2. Expense Management Tools

Amex Gold business card review

The Amex Business Gold Card offers tools to simplify expense management. 

With this card, here are the tools you could get:

  • A year-end summary to simplify expense tracking
  • Employee cards to control spending and earn rewards
  • QuickBooks integration to auto-categorize expenses

You can also take advantage of Vendor Pay by Bill.com to streamline payments and assign an Account Manager to handle tasks like payments and transaction reviews. Plus, you can stay on top of spending with account alerts, online statements, and the Amex app, which lets you track expenses and manage your account in real-time.

You might also like: BILL Spend & Expense Card Review (Formerly Divvy Credit Card) 

3. Travel Perks for Cardholders

Amex Business Gold card rewards review

The Amex Business Gold Card enhances travel with 3X Membership Rewards® points on: 

  • Flights
  • Prepaid hotels
  • Packages booked through AmexTravel.com

There are no foreign transaction fees, which can make international business travel seamless. 

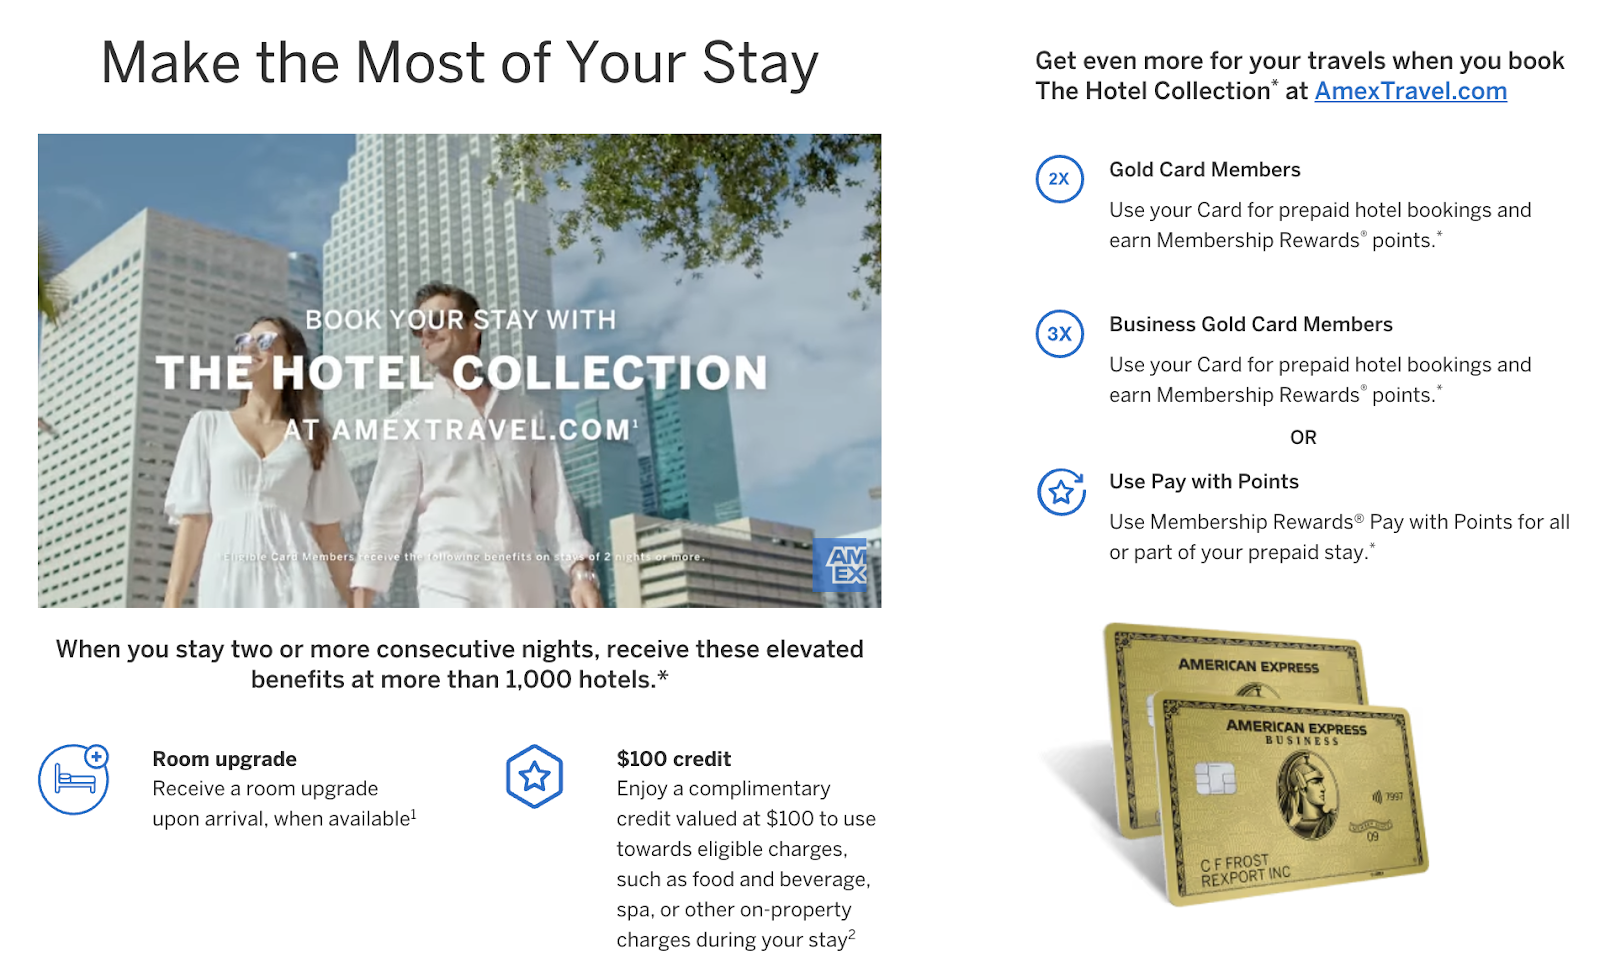
Plus, you can enjoy perks from The Hotel Collection (like a $100 experience credit and potential room upgrades for stays of two nights or more), Global Assist® Hotline for emergencies, baggage insurance for lost or damaged items, and car rental insurance for theft or damage (secondary coverage). 

Finally, If your trip is delayed by 12+ hours for a covered reason, Trip Delay Insurance may provide assistance. These features can make business travel smoother and more rewarding.

You might also like: What are the Best Business Credit Cards for Travel? 

4. Business Services from Amex

Amex cardholder cell phone protection

The card also offers valuable business services to protect and support your operations. 

Some of the services include: 

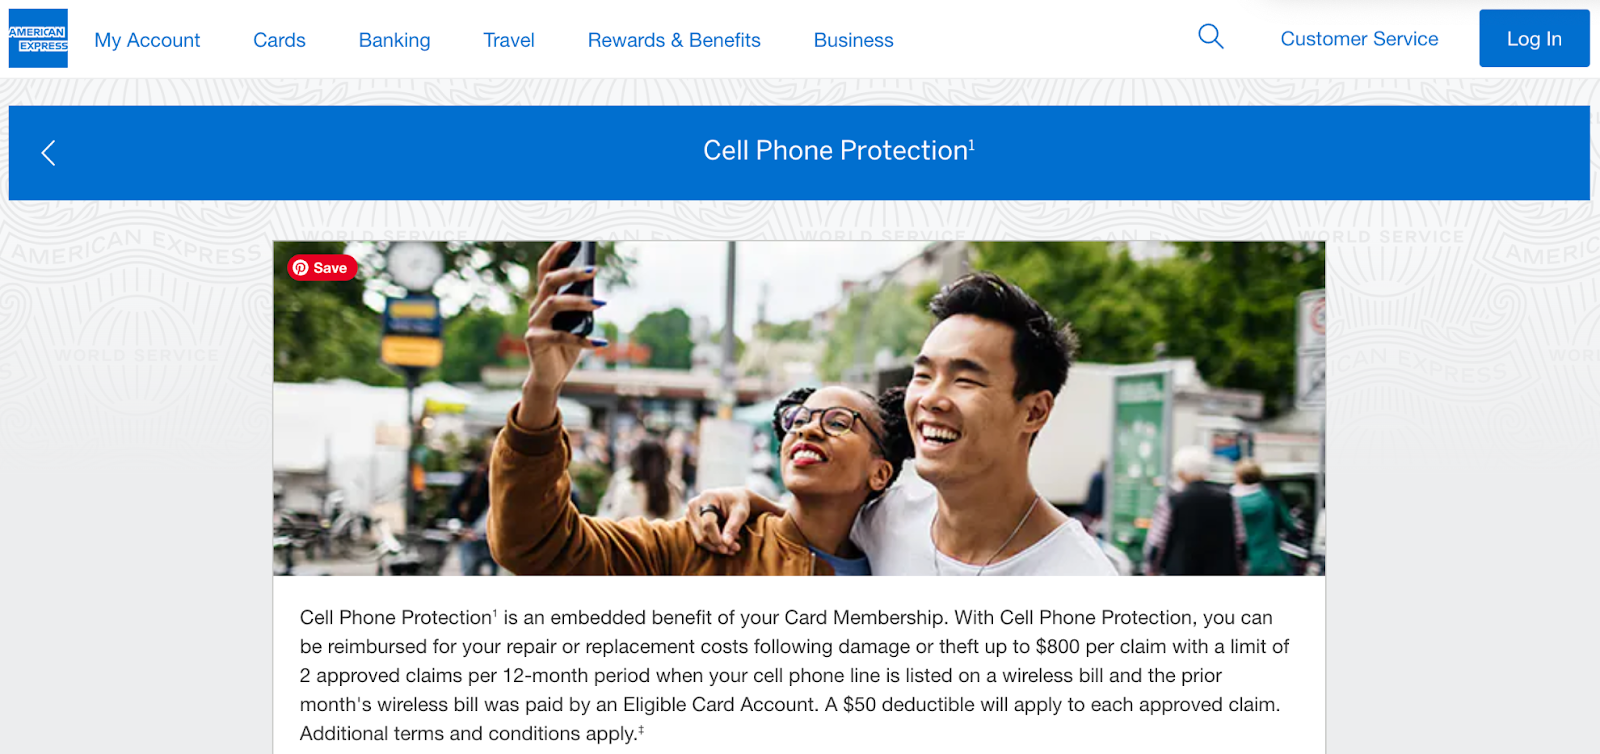
  • Cell phone protection up to $800 per claim
  • Dispute resolution for fraud and unauthorized charges
  • Extended warranties (up to 5 years) on eligible purchases
  • Annual purchase protection up to $50K per year
  • 24/7 support through Relationship Care® 
Amex business Gold Reddit

These features can help safeguard your purchases and simplify some aspects of managing your business.

You might also like: Comprehensive ZenBusiness Review: Is it Legit for LLCs? 

Frequently Asked Questions 

Does the Amex Business Gold card have a limit?

The Amex Business Gold card has a flexible spending limit that adjusts based on your usage, payment history, and other factors–This means your spending capacity can vary over time.

Is the Amex Gold a luxury card?

The American Express® Gold Card is considered a premium card, offering substantial rewards on dining and groceries. However, it doesn’t provide the extensive luxury perks found in higher-tier cards.

Does the Amex Gold Business have lounge access?

No, Amex Business Gold doesn’t include airport lounge access. But, it does offer other travel perks like trip delay, baggage claim, and car rental loss insurance. Lounge access is typically reserved for luxury cards like the Amex Platinum.

Is it hard to get approved for the Amex Business Gold card?

Amex Business Gold approval generally requires good to excellent credit. American Express evaluates credit history, income, and other factors during the application process.

What income is recommended for the Amex Business Gold card?

While American Express doesn’t specify a minimum income, higher revenue can improve your approval odds. They consider your overall financial profile, including income, existing debts, and both business and personal credit scores.

Conclusion: Is Amex Business Gold Worth it? 

The Amex Business Gold card offers a suite of features that can be worthwhile if you think you’ll take advantage of them. But, a $375 annual fee isn’t going to work for everyone. 

If you think the benefits can outweigh the cost for you, this is a high-value card from a reputable servicer. If you’re looking for more perks like lounge access, consider a platinum card instead. If you want something with no annual fee, keep shopping around—the right card is out there.   

Do you want to learn how to obtain up to $100K in business credit in as few as 30 days? Join Business Credit Workshop today!
Complete Ally Financial Review: No PG, No Credit Check Vehicle Loans +More

By Joe

Ally Financial Review

Key Takeaways

  • Ally Financial is a digital financial services company.
  • It offers banking, investment, and auto financing products.
  • Some customers report poor customer service on online review websites, and the company faces class-action lawsuits over data breaches and loan practices.
  • Ally offers no-personal-guarantee (no-PG) business vehicle loans that focus on business credit, not personal credit.
  • Their business vehicle loans have flexible terms and protect personal assets.

You can find a ton of Ally Financial reviews online. While their affiliates tend to talk them up, some of their customers are less impressed. So, what’s Ally Financial really all about? 

    Here, I’ll answer that and more. Let’s look at what Ally Financial offers, learn about the company, and get to know their no-credit check and no-PG business vehicle loans (which I love).

    This is what’s in store: 

    • What is Ally Financial?
      • What is Ally Financial Known for?
      • Company Overview
    • Ally Financial No PG Business Vehicle Loans Summary
      • 1. Approval Based on Business Credit
      • 2. Ideal for Fleet Management
      • 3. Flexible Loan Terms
      • 4. Competitive Interest Rates
      • 5. Personal Asset Protection
      • 6. Additional Costs to Consider
      • 7. Application Process
      • 8. Work With a Local Dealer
    • Frequently Asked Questions
    • Conclusion: Is Ally Financial Any Good?

    So, let’s dive in! 

    What is Ally Financial? 

    Ally Financial is a leading digital financial services company that offers a variety of banking and investment products. 

    Its core services include:

    • Ally Bank provides deposit products like savings and checking accounts, CDs, and money market accounts. It also offers mortgages and credit services.
    • Ally Invest allows users to manage investments with self-directed trading, robo portfolios, and personalized advice.
    • Ally Home offers home purchase and refinancing options.
    • Ally Auto provides auto financing, a key part of their offer.

    They emphasize customer care and transparency, with “no hidden fees” (according to themselves) on many of their products.

    You might also like: Low-Risk NAICS Codes +Best SIC Codes for Business Credit in 2024 

    What is Ally Financial Known for?

    Ally is known for being one of the first banks to eliminate overdraft fees and to make banking more accessible and customer-friendly. In the corporate world, they’re known for their no-PG business auto loans. 

    And, there are a few key aspects of their overall offer that people tend to love: 

    • As a fully online bank, Ally offers a wide range of services without physical branches.
    • Ally is a major player in consumer and business auto loans and financing.
    • In addition to banking, Ally offers investment options, home loans, and insurance products.

    As a one-stop-shop for personal finance, these factors tend to set Ally apart.

    You might also like: Business Credit Cards without Personal Guarantee 

    Company Overview

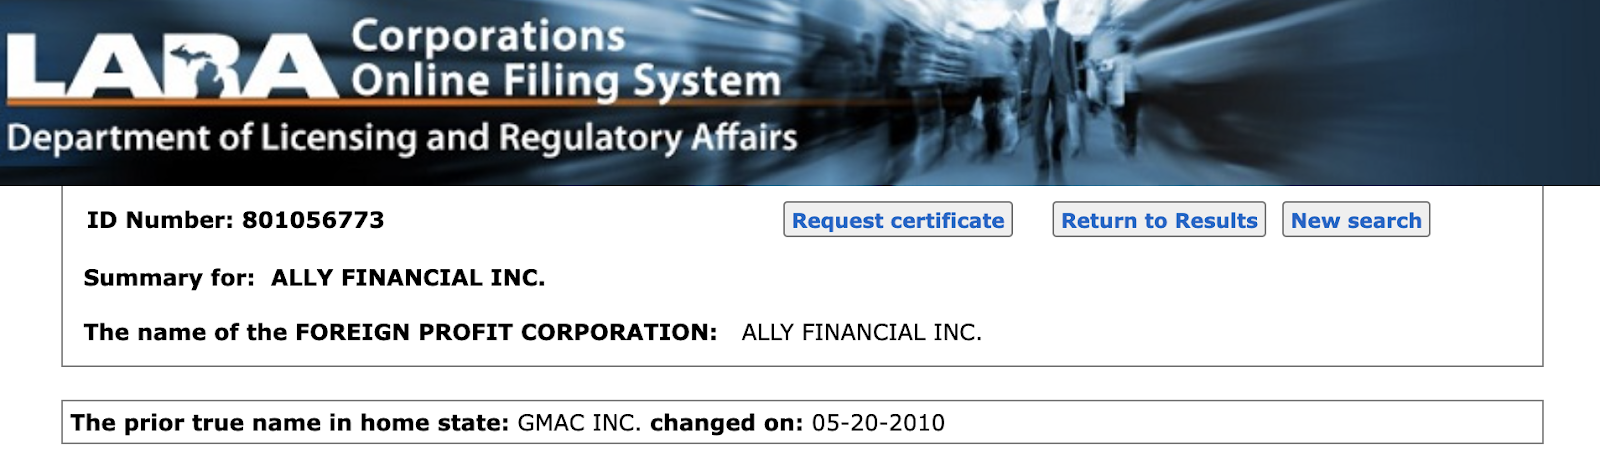
    Ally Financial Inc; GMAC Inc

    A Detroit, Michigan-based company, allegedly launched in 1919, Ally Corporate Finance, aka Ally Financial, aka Ally CF,  is listed on Crunchbase as an “automotive financial services company powered by a top direct banking franchise.” Both Ally Financial and Ally Financial Inc. were registered as entities in the state of Michigan in May, 2010, which seems to be when the trade name was changed from GMAC Inc. 

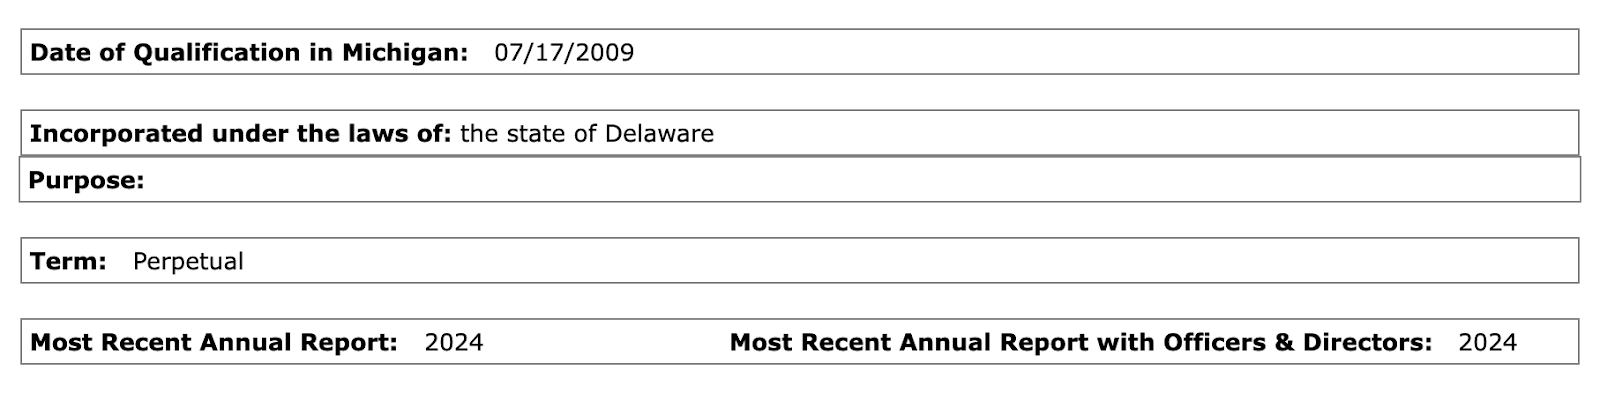
    However, GMAC Inc. was first registered in July, 2009. So, the 1919 founding date must be based on the fact that they’re a subsidiary of General Motors (founded in 1908).  

    Ally Financila Inc Delaware Company 2009

    Still, the company appears to be in good standing, and its most recent annual report was filed in 2024. 

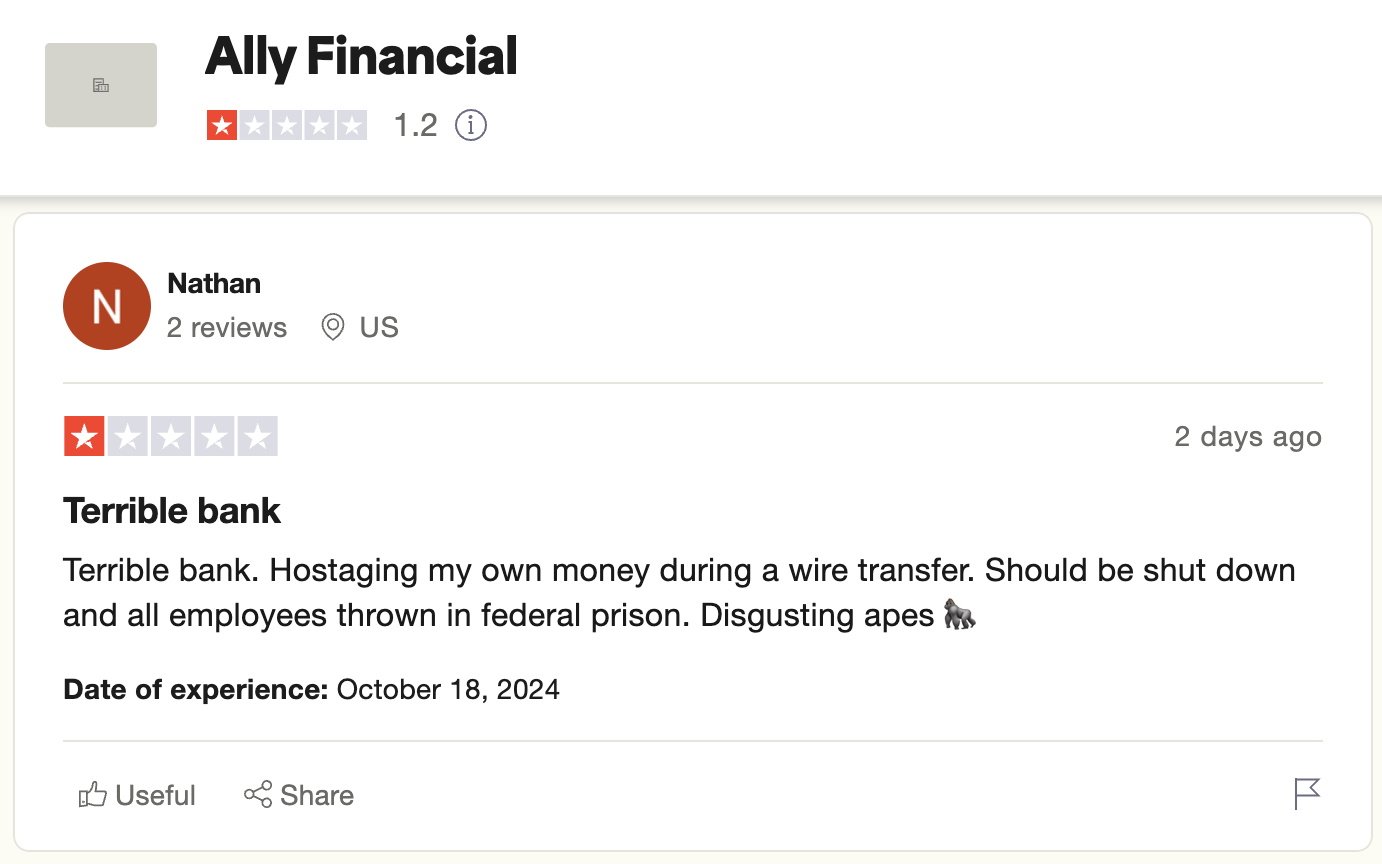
    Out of 762 Trustpilot reviews, Ally’s Trustscore™ is a low 1.2-stars. A lot of customers warn of poor, outsourced customer service, but some praise the banking. With an online-only bank, customer service shortcomings are almost expected. But, these are pretty poor.

    Ally financial review complaints

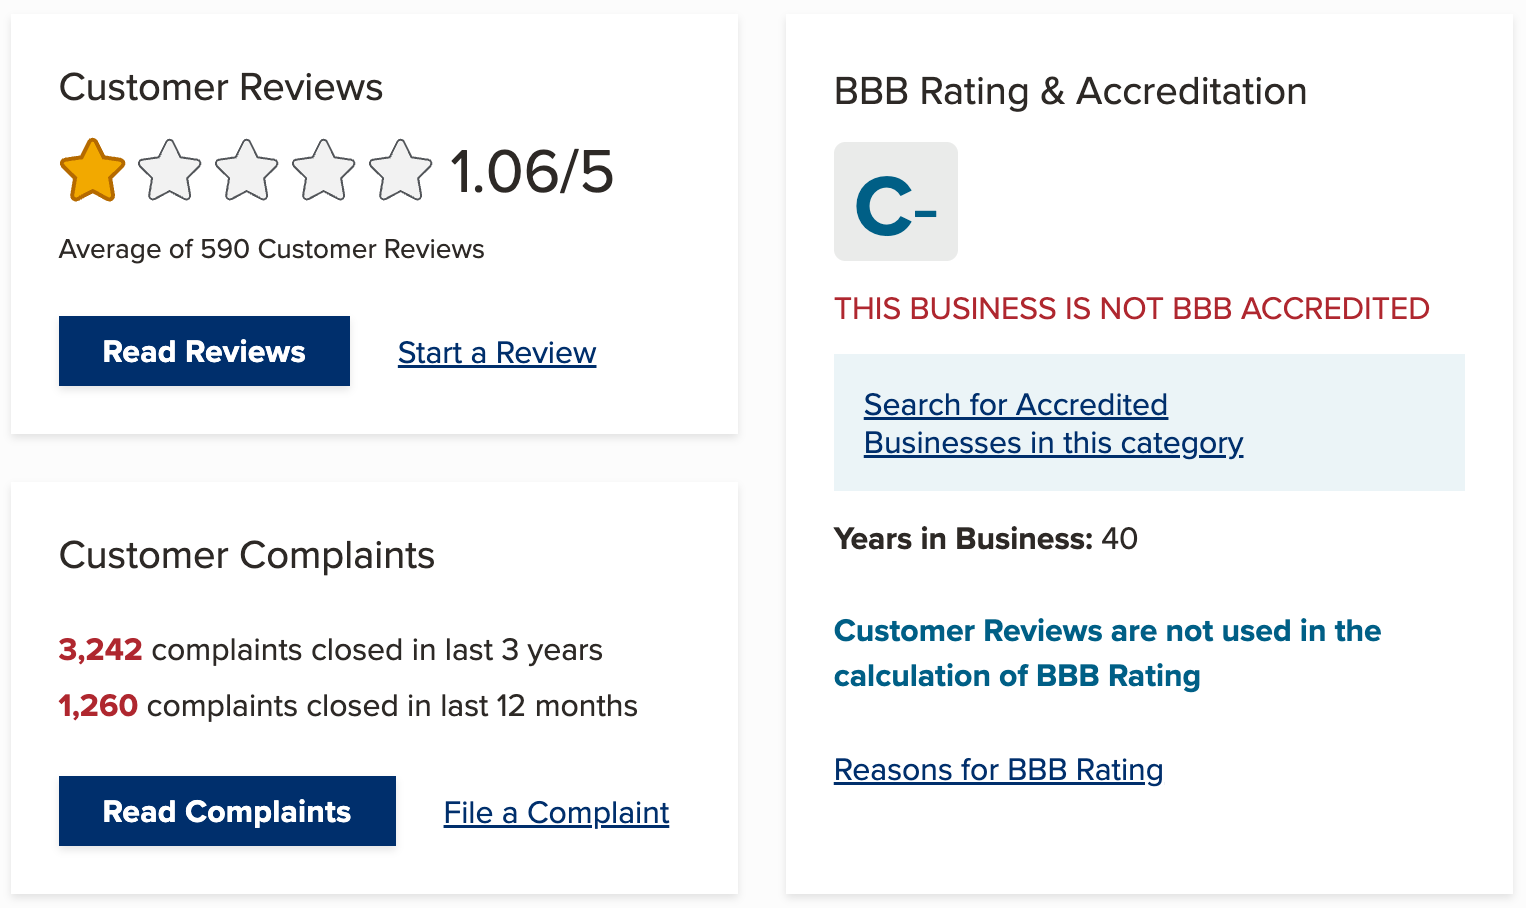
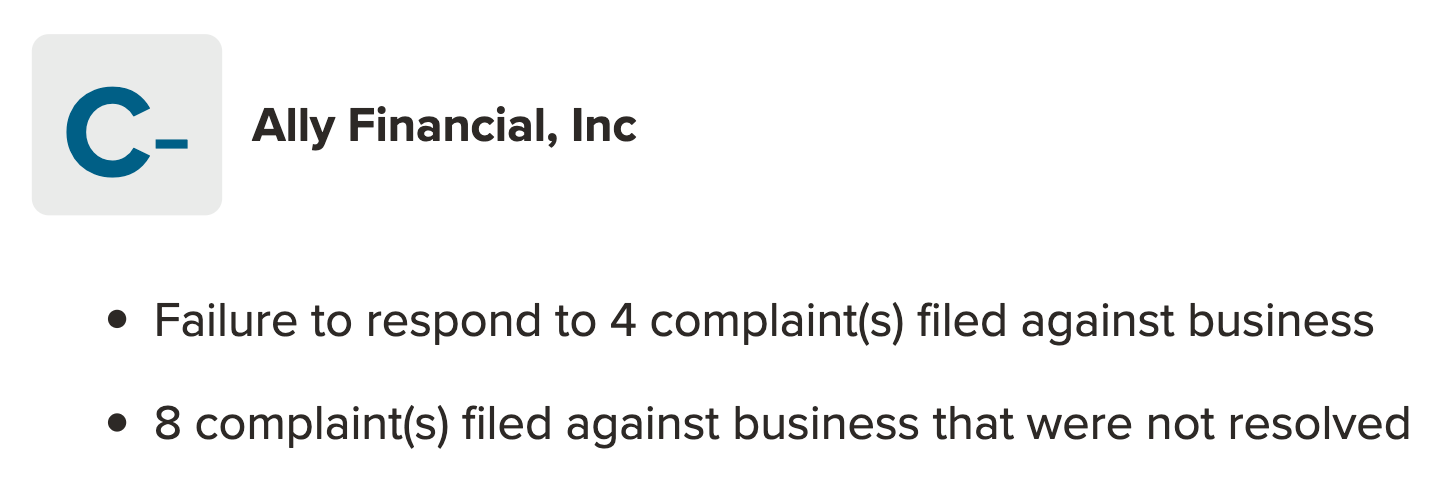
    With the Better Business Bureau (BBB), their reviews aren’t so promising either—Ally has a C- BBB rating with 1.06 out of 5 stars, and 1,260 complaints closed in the past 12 months, 

    Ally Bank Reviews BBB

    While the BBB lists them as being in business for 40 years, this doesn’t match up with the 1919 nor the 2009 founding dates that I found. 

    Moreover, the reason their BBB rating is low and they aren’t accredited isn’t because they failed to sign up to become accredited. Instead, they’ve been slacking and can’t be accredited because of failure to respond to four complaints and having left eight complaints unresolved. 

    My loan Ally reviews Consumer reports

    To make sure we’re being completely fair, it’s important to note that most financial service companies have a hard time maintaining positive reviews. And, an unsatisfied customer is way more likely to put in the effort to leave a review than someone who is satisfied. 

    So, I did a quick search to see if they had any open or past lawsuits, hoping to come up empty-handed. Sadly, that’s not the case. 

    Ally Financial is facing multiple class-action lawsuits, including: 

    • Allegations of failing to protect customer data during a breach.
      Accusations of discrimination related to its DEI policies.
    • Private lawsuits over improper collection practices during loan repossession.

    With a quick Google search, you can find more information about some of the legal complaints against the company. With that said, I know several people, with vehicle loans through the platform, who are having no problems whatsoever.  

    In sum, Ally Financial has a mixed reputation. It faces low customer ratings on Trustpilot and the BBB, along with class-action lawsuits over data breaches, discrimination, and loan collection practices. But, some customers still report positive experiences.

    You might also like: No-Doc Business Loans: Get Funds Without Proof of Income 

    Ally Financial No PG Business Vehicle Loans Summary

    My loan Ally reviews complaints

    One of my favorite offers from Ally is their business vehicle loans–They’re one of the select few lenders I know of to offer business vehicle loans that don’t require a personal guarantee (no-PG) and no credit check. 

    Learn more about the option to get vehicle loans in your business name through Ally! 

    1. Approval Based on Business Credit

    Ally’s no-PG business auto loans evaluate your business’s credit history rather than your personal credit. This process focuses on your company’s financial health, allowing you to keep your personal credit separate from your business.

    You might also like: This is How to Leverage Business Credit to Transform Your Life 

    2. Ideal for Fleet Management

    These loans are perfect for businesses needing multiple vehicles. Whether you need cars, trucks, or specialized vehicles, Ally provides flexible solutions tailored to your growing fleet.

    Recommended: Business Car Leasing 101: How to Lease a Vehicle With Your EIN 

    3. Flexible Loan Terms

    Ally offers various loan terms, usually ranging from 36 to 84 months. You can choose short-term or long-term financing to manage payments according to your cash flow and operational demands.

    You might also like: A Full OnDeck Review: All You Need to Know About This Business Funding Offer 

    4. Competitive Interest Rates

    With no personal guarantee required, business owners can protect their personal assets. This makes no-PG business auto loans a smart choice for companies looking to expand while minimizing personal financial risk.

    5. Personal Asset Protection

    With no personal guarantee required, business owners can protect their personal assets. This makes no-PG business auto loans a smart choice for companies looking to expand while minimizing personal financial risk.

    6. Additional Costs to Consider

    Buyers should be aware of potential costs, such as down payments, registration fees, and any modifications needed for the vehicles. Understanding these costs upfront can help you budget effectively.

    7. Application Process

    To start the financing process, you can download the commercial line of credit application from Ally’s website. It’s a straightforward process that allows you to get started quickly.

    8. Work With a Local Dealer

    Ally Bank Google reviews

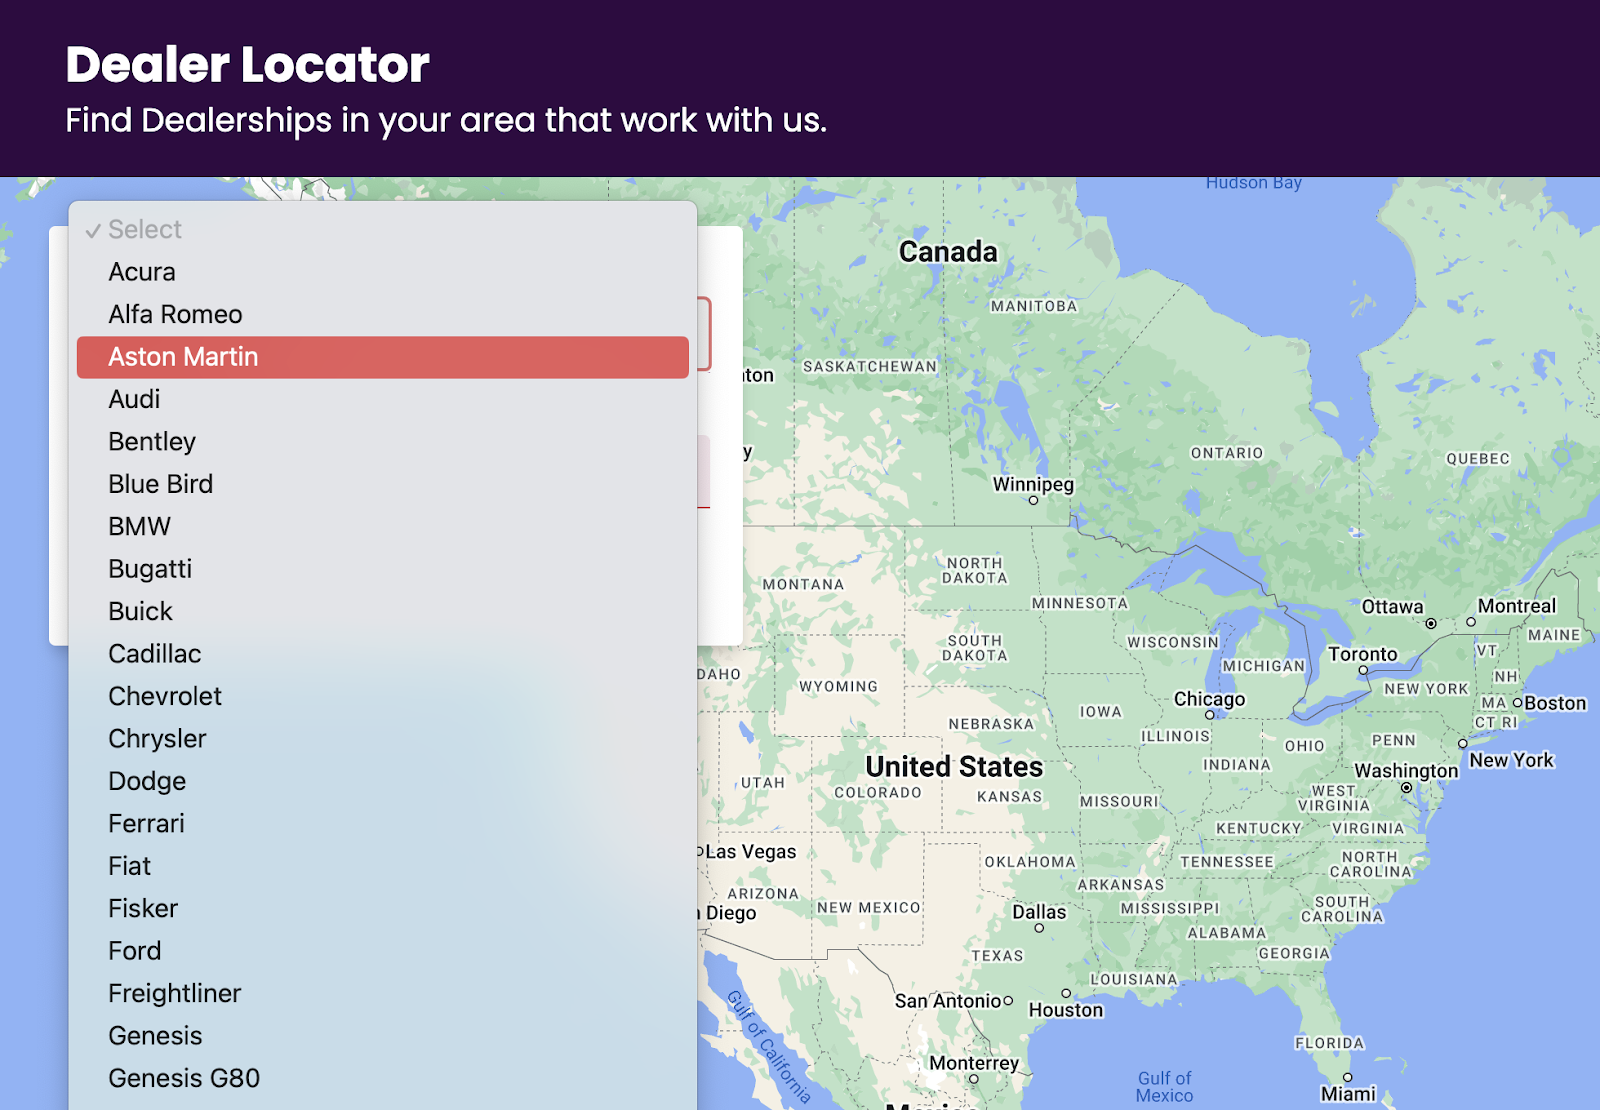
    Interested buyers should find a local dealer to learn more about eligibility, specific rates, and additional financing options available through Ally. To find dealers in your area that work with Ally Financial, see their dealer locator. 

    Frequently Asked Questions

    What bank owns Ally Financial?

    Ally Financial is an independent financial services company and does not have a parent bank. It was formerly known as GMAC Inc., a subsidiary of General Motors.

    Is Ally Bank FDIC insured?

    Yes, Ally Bank is FDIC insured. This means that deposits are protected up to the legal limit, which is currently $250,000 per depositor, per insured bank.

    Is Ally Bank 100% safe?

    While Ally Bank is FDIC insured, no bank can guarantee 100% safety. However, it is considered a reputable institution with security measures in place to protect customer information and funds.

    What credit score is needed for Ally Financial?

    Ally Financial typically requires a credit score of 620 or higher for its auto loans, but specific requirements may vary based on the type of loan and other factors. It’s best to check directly with Ally for the most accurate information.

    Conclusion: Is Ally Financial Any Good? 

    So, can Ally be trusted? Well, they present some appealing options, especially with their no-PG business vehicle loans—These loans allow business owners to secure financing without risking personal assets. 

    However, the company faces significant criticism regarding customer service and transparency, as shown by their low ratings on Trustpilot and with the BBB.

    While many customers do report positive experiences, the ongoing legal issues and mixed reviews warrant some level of caution. If you’re considering Ally Financial, weigh the benefits against the potential drawbacks. Conduct your own research and explore other financing options to be sure you make the best choice for your needs.

    If you’re interested in applying for Ally’s no PG business vehicle loan, watch my recent video: 

    Ready to learn how to obtain up to $100K in business credit in as few as 30 days? Join Business Credit Workshop today! 
    NAMYNOT Net 30: Marketing Services That Build Business Credit

    By Joe

    NAMYNOT net 30

    If you want a way to improve your business’s cash flow while better marketing your business, NAMYNOT’s Net 30 account could be what you need—This option lets you defer payments for up to 30 days, providing more financial flexibility. 

    Curious about how their Net 30 terms work and how they might benefit your business? Keep reading to find out everything you need to know.

    This is what’s in store: 

    • What is NAMYNOT?
      • Company Overview
    • What is a Net 30 Account?
    • NAMYNOT Net 30 Features & Benefits
      • 1. Pay Later
      • 2. Build Business Credit
      • 3. No Personal Guarantee Required
      • 4. Up to $10K Credit Line
      • 5. Easy Application Process
    • How to Qualify for NAMYNOT Net 30
    • Final Thoughts

    Now, let’s roll!

    What is NAMYNOT? 

    Namynot net-30

    NAMYNOT, aka “nmi,” offers businesses a range of marketing services to support growth and visibility. According to their own marketing message, they focus on clear communication and create strategies that fit each client’s specific needs. Whether you want to strengthen your online presence or reach new customers, NAMYNOT can help with practical marketing solutions.

    Here’s a quick look at what they offer:

    • Organic lead generation with content marketing.
    • Email marketing campaigns.
    • Custom marketing strategies, both online and offline.
    • Professional website design and maintenance.
    • Ad management.

    With experience across various industries, NAMYNOT works with businesses of all sizes—They provide straightforward, adaptable solutions that can help your business move toward their goals.

    And, they offer business bureau reporting, which means that you may be able to have your payments reported to help you establish or improve business credit. 

    You might also like: 41 Companies That Help Build Business Credit [Beyond Net 30 Vendors] 

    Company Overview

    namynot inc. 159 n sangamon st pmb 2726, chicago, il 60607, états-unis

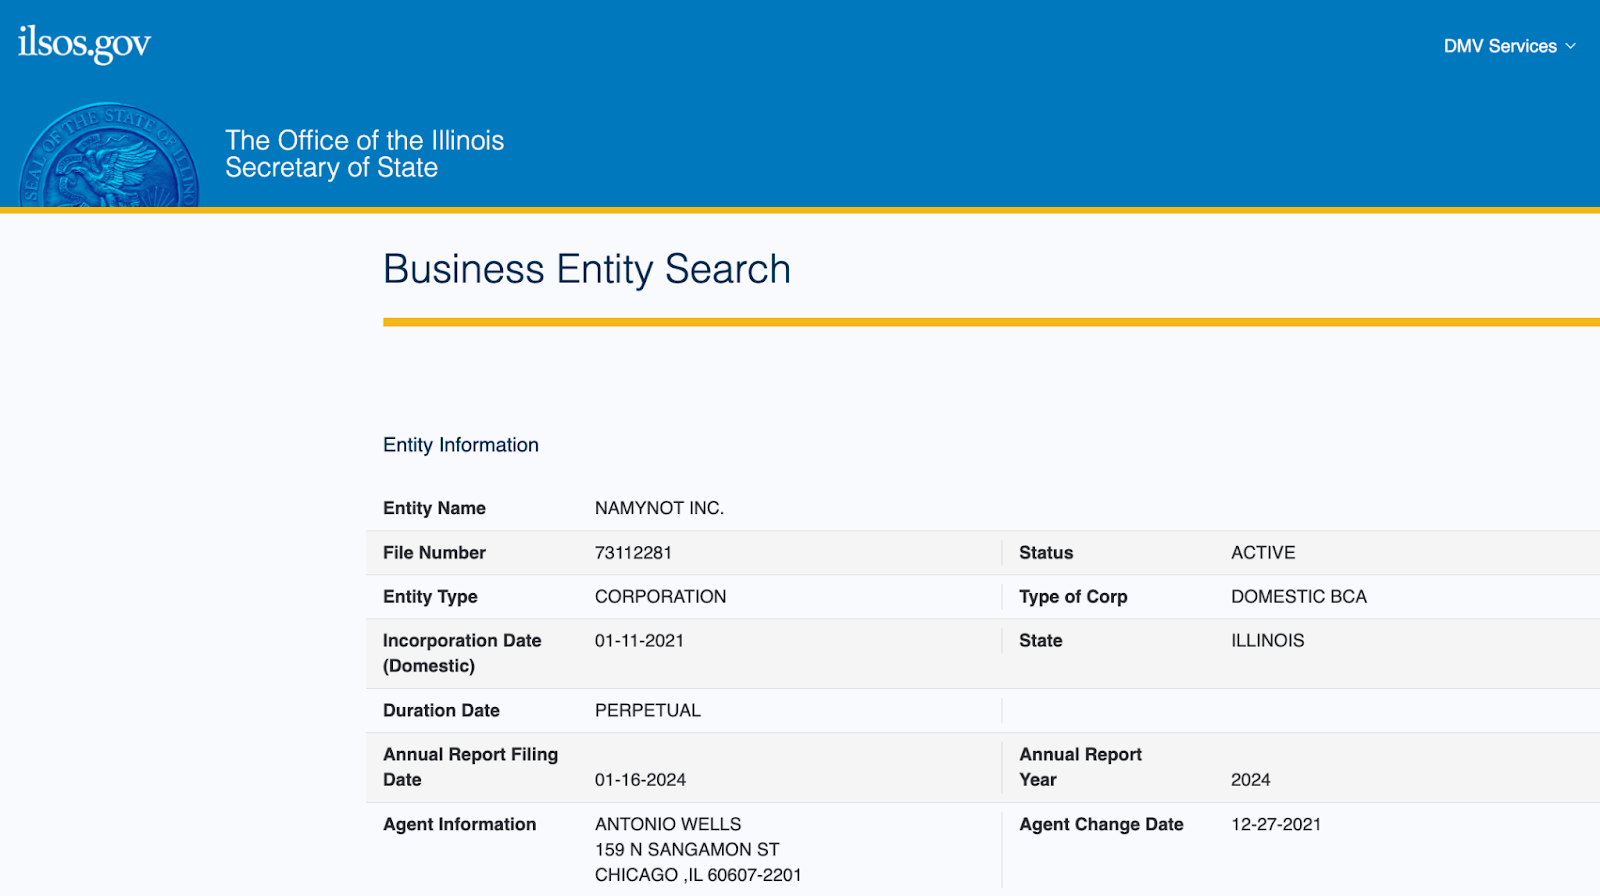
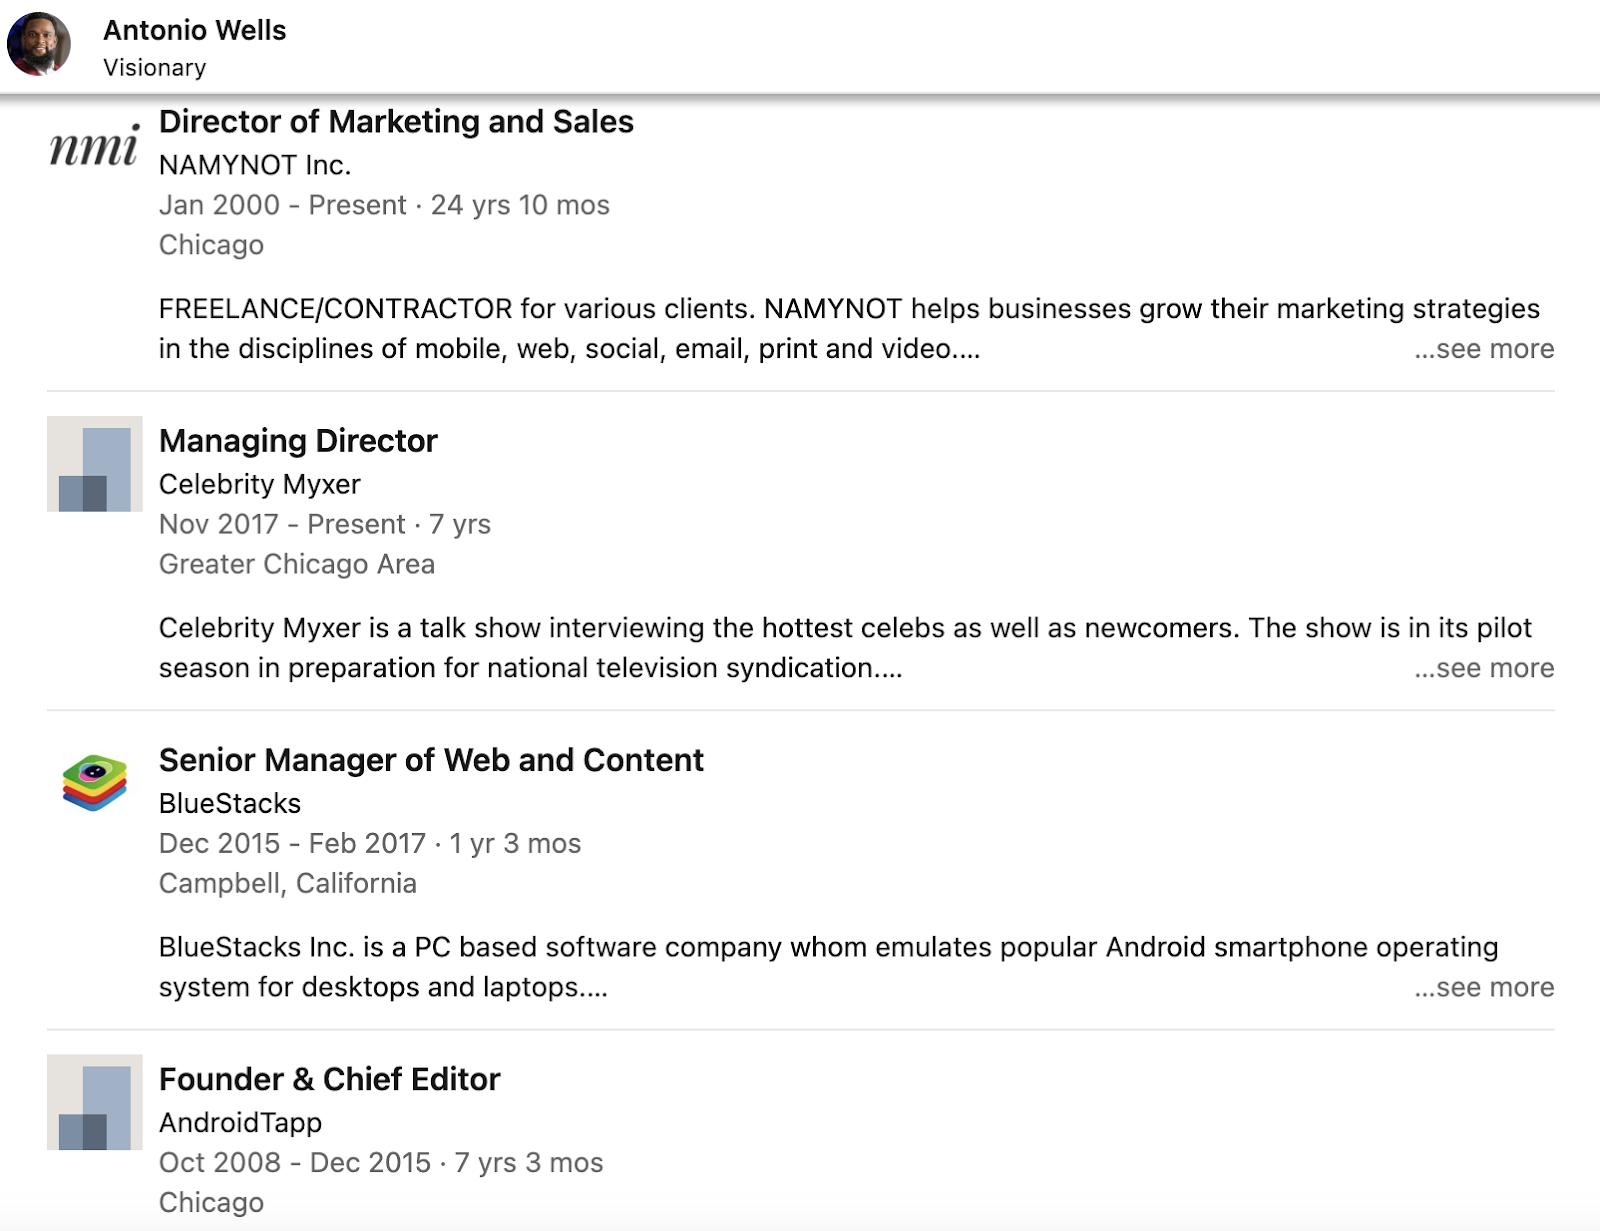
    NAMYNOT Inc. is a Chicago-based web services company that was allegedly founded in 1999 (according to Crunchbase) or 2000 (according to LinkedIn) by Antonio Wells. The company is active and in good standing in the state of Illinois, but their incorporation date was in 2021.

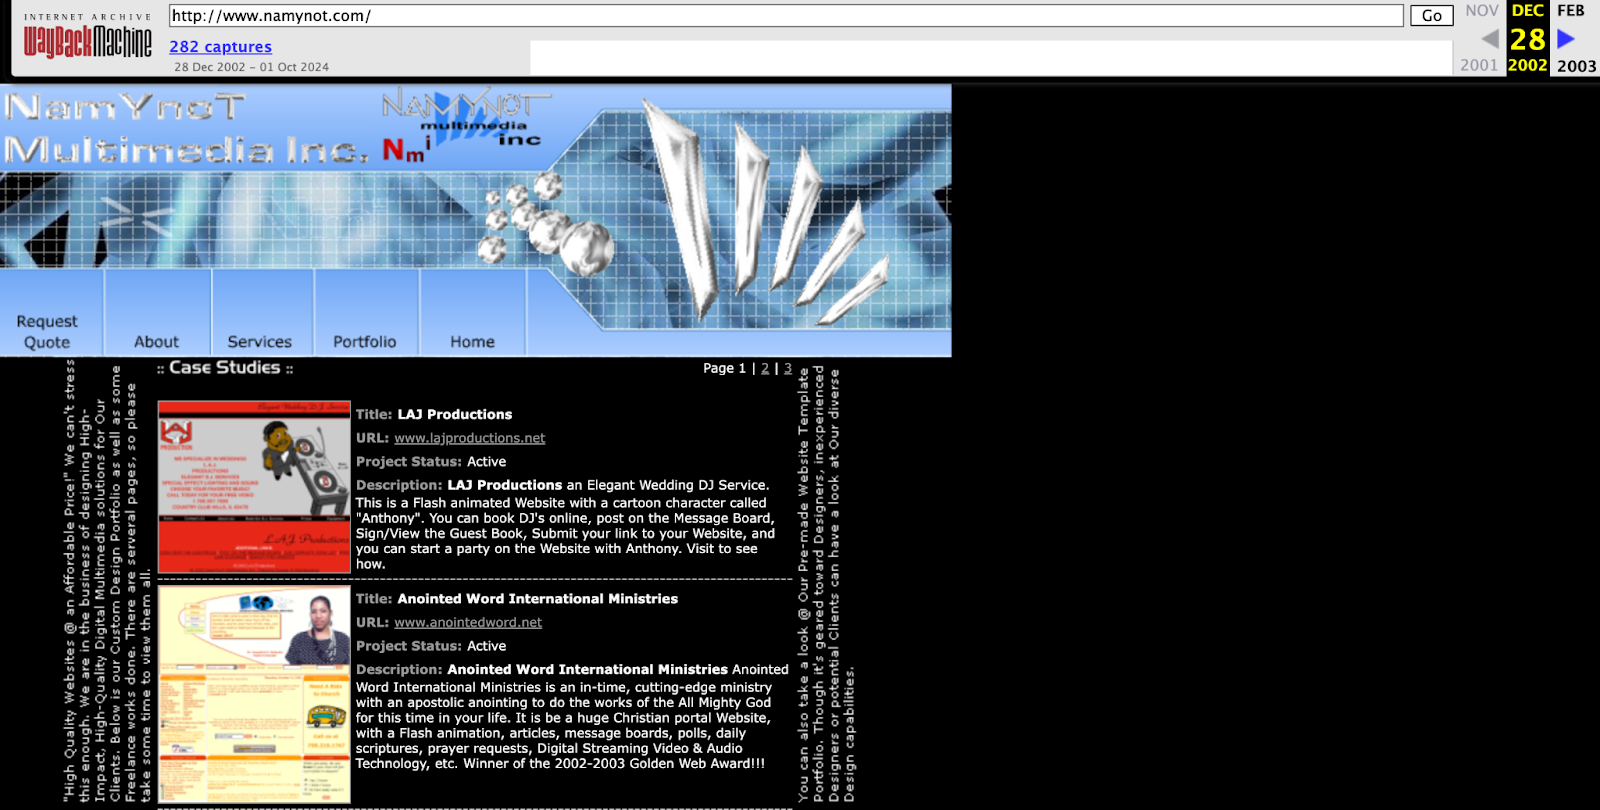
    Now, I did find namynot.com in the Wayback machine as early as 2002, which indicates that the company was probably in operation before that time. Based on the homepage screenshot saved over 20 years ago, the brand’s design trends were quite different at that time, with a focus on flash animation web design.  

    NAMYNOT web services in 2002

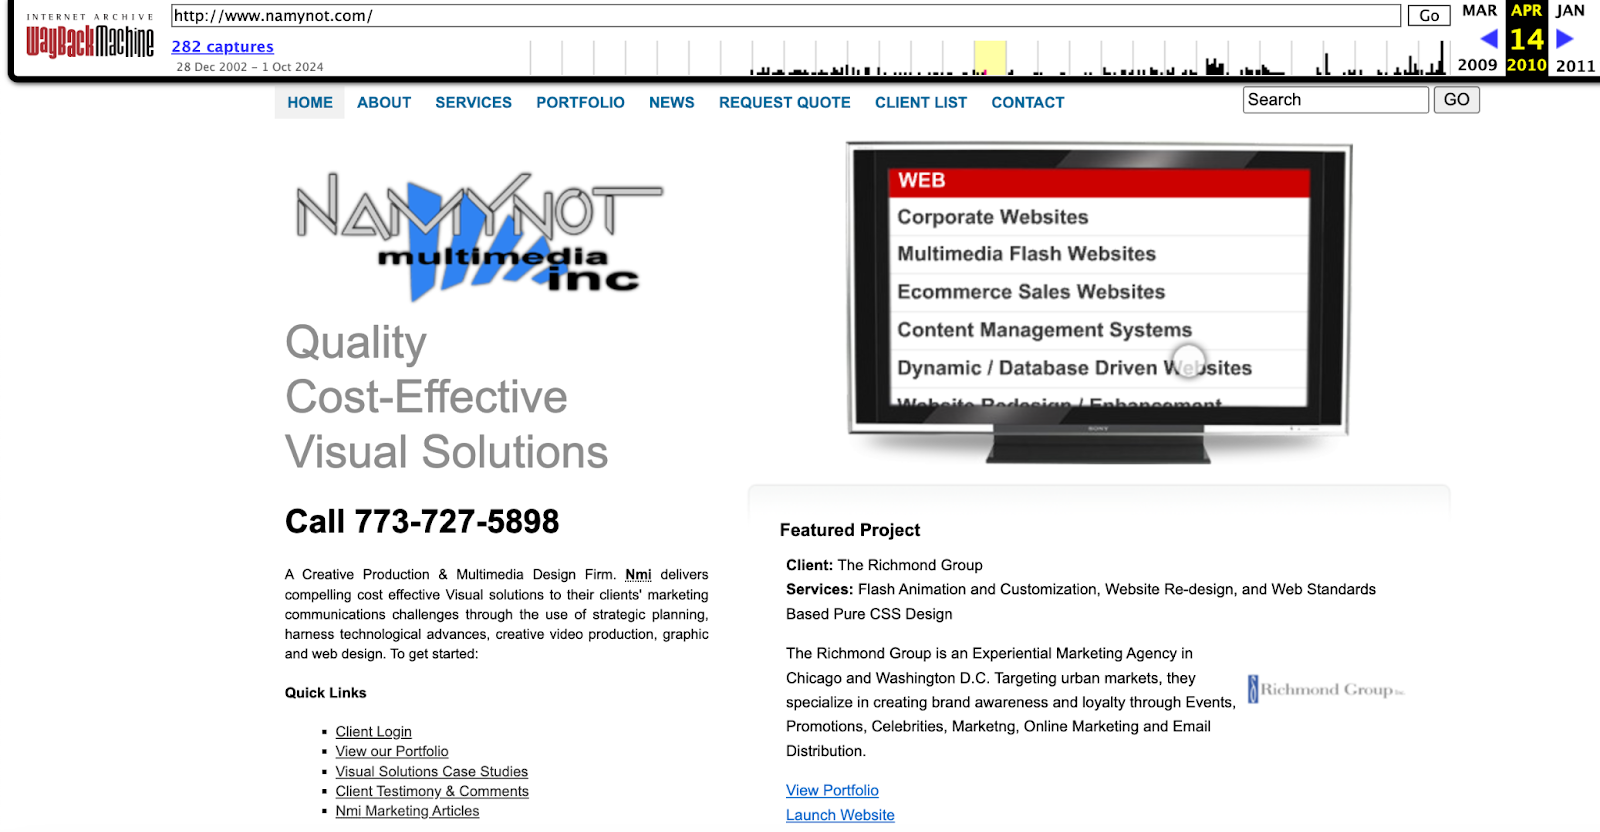
    For fun, I popped in to see what NAMYNOT’s website looked like in 2010, and there had been quite an improvement. 

    NAMYNOT in 2010

    Since the company’s launch, Wells has worn many hats. From 2017 to present, he’s been the Managing Director at Celebrity Myxer. From 2015 through 2017, he served as the Senior Manager of Web and Content at BlueStacks, and he was the Founder & Chief Editor at AndroidTapp for over seven years. It seems he’s an experienced entrepreneur with a focus on marketing. And, NAMYNOT is his longest-standing venture.  

    NAMYNOT CEO Antonio Wells

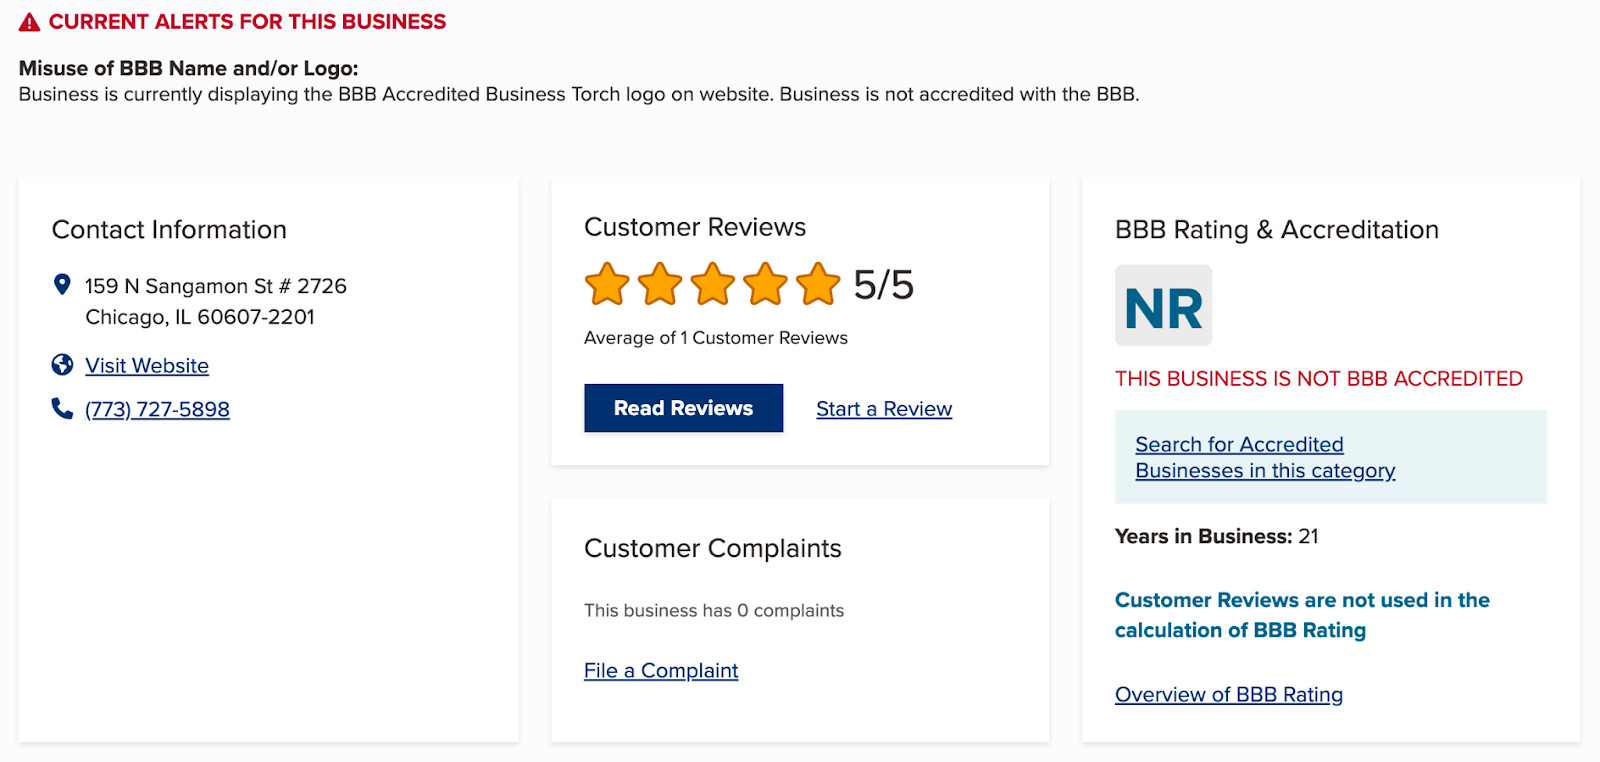
    While I didn’t see any past or open lawsuits against the company, the Better Business Bureau (BBB) warns that they misused the BBB brand logo in that they are not accredited with the BBB. Still, they maintain 5-star reviews on the platform. 

    Namynot reviews

    While I didn’t spend too much time searching for business aliases, I did not see NAMYNOT or nmi listed Trustpilot or Reddit. With a marketing service, this isn’t super alarming, but made me wonder if Wells had been freelancing through another platform to build clientele. 

    I did find wells on Upwork with 100% job success and great client reviews as far back as 2019. Clients consistently commend Antonio Wells for his SEO expertise, thorough research, and ability to create high-quality content that drives lasting results. 

    Antonio Wells Freelancer

    Upwork clients also value his professionalism, clear communication, and strategic insights, often noting how his work positively impacted their businesses. Many clients say that they plan to rehire him, describing him as reliable, knowledgeable, and easy to work with.

    So, despite some ambiguity around its founding date and lack of BBB accreditation, the brand maintains a strong reputation. With consistent positive feedback and a focus on marketing, NAMYNOT has quietly built trust and credibility over the years. In short, they’re likely legit.

    You might also like: How Can Crown Office Supplies Help You Build Business Credit? 

    What is a Net 30 Account?

    A net 30 account is a type of credit account that gives you 30 days to pay off a purchase after receiving an invoice. It’s pretty common in business-to-business transactions. 

    For example, if a company buys supplies from a vendor with net 30 terms, they don’t have to pay upfront—they’ll get an invoice and have 30 days to settle it. It helps businesses manage cash flow by giving them more time to pay for goods or services while still keeping operations running smoothly.

    And, many contemporary net 30 vendors offer payment reporting to business credit bureaus. 

    Recommended: How to Use 30 Day Net Vendors to Build Your Business Credit Score 

    NAMYNOT Net 30 Features & Benefits

    Again, NAMYNOT has a net 30 offer that’s worth a look. Here, explore the features and benefits of being approved for their net 30 terms. 

    1. Pay Later

    How many net 30 accounts should I have?

    With NAMYNOT’s net 30 business line of credit, you have the flexibility to purchase digital marketing services now and defer payment for up to 30 days—This means you can invest in essential services, like a website redesign or social media advertising, without immediate financial strain. 

    For example, if you need to launch a marketing campaign to promote a new product but are short on cash this month, you can use the net 30 option. You can focus on growing your business while managing your cash flow more effectively.

    2. Build Business Credit

    Who does Namynot report to?

    Timely payments on your Net 30 account contribute positively to your business credit profile. When you pay your invoices on time, your payment history is reported to Dun & Bradstreet (the leading business credit bureau). 

    This can improve your creditworthiness and open doors to better financing options in the future. As a business owner, you might become able to secure a higher credit line or more favorable loan terms, which makes it easier to fund your growth ambitions.

    Recommended: Everything You Need to Know About a DUNS Number – and Why You Should Care 

    3. No Personal Guarantee Required

    No PG net 30 account

    One of the significant advantages of our Net 30 account is that it does not require a personal guarantee or a credit check. This feature protects your personal credit score and separates your business finances from your personal finances. 

    For instance, if your business faces a financial hiccup, your personal assets remain safe. This can give you peace of mind as you focus on running and scaling your business.

    You might also like: Here’s How to [Actually] Get Business Credit With Just an EIN +More

    4. Up to $10K Credit Line

    Namynot customer service

    You can qualify for a credit line of up to $10,000, giving you ample resources to invest in your business. Whether you want to launch a new marketing initiative, hire freelance talent for a project, or upgrade your office equipment, a credit line can give you the flexibility you need. 

    Imagine having the capital to execute a comprehensive digital marketing strategy without immediate cash outflow—this could significantly boost your business visibility and sales.

    You might also like: What is the Best Credit Card for Ad Spend? Expert Insights 

    5. Easy Application Process

    NAMYNOT net 30 application

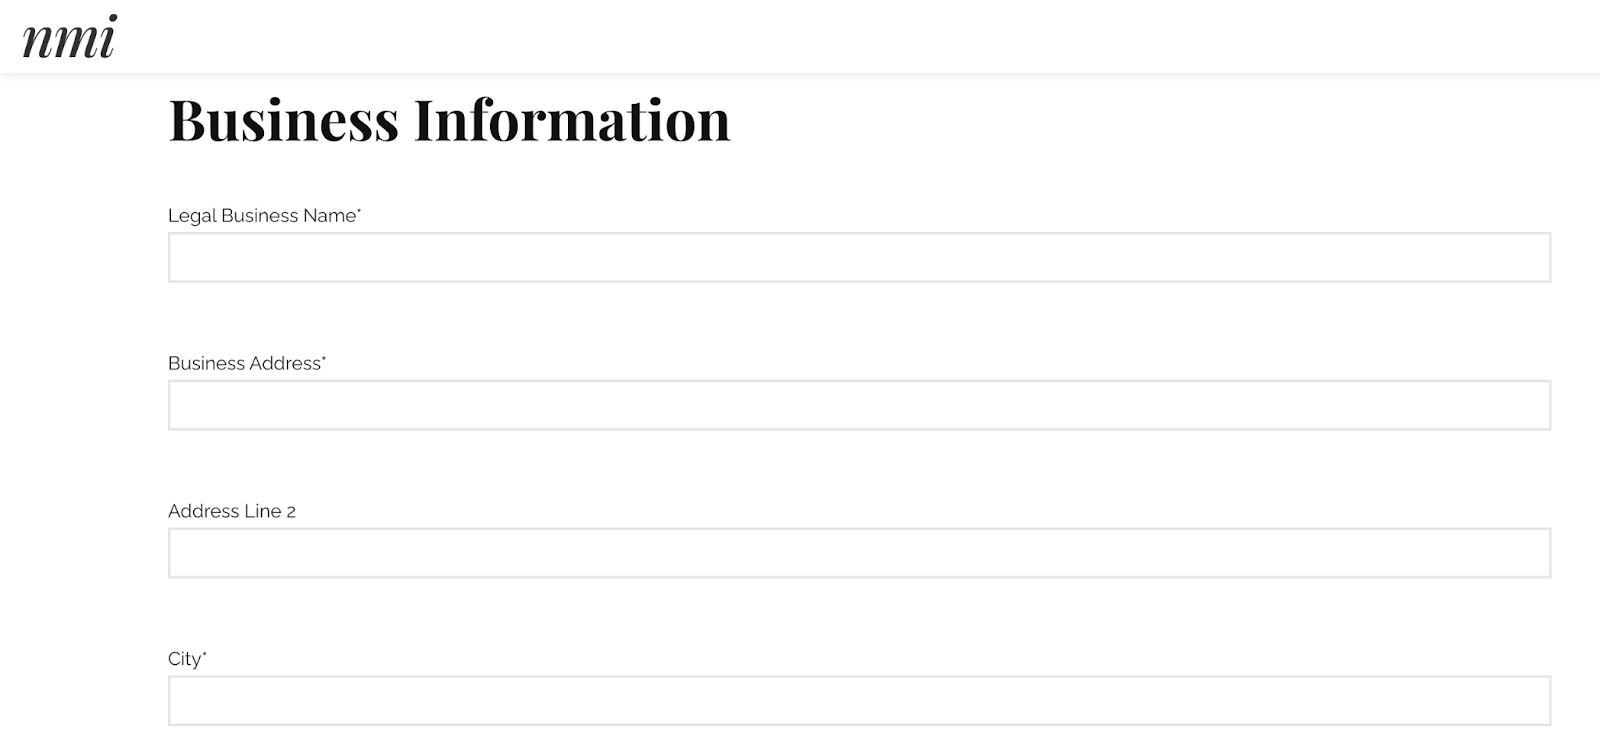
    Applying for a Net 30 account is straightforward and free of charge. This means you can get access to critical funding without the burden of complicated applications or hidden fees. The streamlined process allows you to focus on what matters most—growing your business. 

    Once your application is approved, you can start using your credit line almost immediately, which enables you to act quickly on new business marketing opportunities.

    You might also like: Free, Printable Business Credit Application Template (+How to Use it) 

    How to Qualify for NAMYNOT Net 30

    To qualify for a NAMYNOT net 30 account, make you meet the following requirements:

    • You own a profitable, U.S.-based business. 
    • Your business is active and was registered at least 90 days ago.  
    • You want to take advantage of NAMYNOT’s services. 
    • You own at least 25% of the business. 
    • Your business has an EIN and a DUNS Number. 
    • No past, negative payment history has been reported about your business. 
    • You have a professional website. 

    If you run a profitable business, have the title of Authorized Officer, and meet all the above requirements, you can confidently apply for a NAMYNOT Net 30 account. 

    Note: If you don’t yet have a professional website, NAMYNOT might be able to help. 

    You might also like: The CEO Creative Net 30 Review: Is it Worth Your Time? 

    Final Thoughts 

    NAMYNOT offers marketing services alongside a net 30 payment option, which can help you manage cash flow while investing in your business. Whether you need digital marketing, a website redesign, or want to build your business credit, their flexible terms can help without the pressure of upfront payments. 

    With an easy application process, no personal guarantee, and credit lines up to $10K, NAMYNOT’s Net 30 option could be a practical choice if you’re looking to expand your marketing efforts. What do you think? 

    Do you wanna learn how to obtain up to $100K in business credit in as few as 30 days? Join Business Credit Workshop today!