• Home
  • Free Funding Guide
  • What We Offer
    • Products
    • Services
    • Free Guide
  • About Us
  • Contact
  • Sign Up

  • Ask Joe Any Question!
  • Business Credit Cards
  • Business Line of Credit
  • Topics

What You Need to Know About PayPal LoanBuilder for Business

By Joe

PayPal Loan Builder

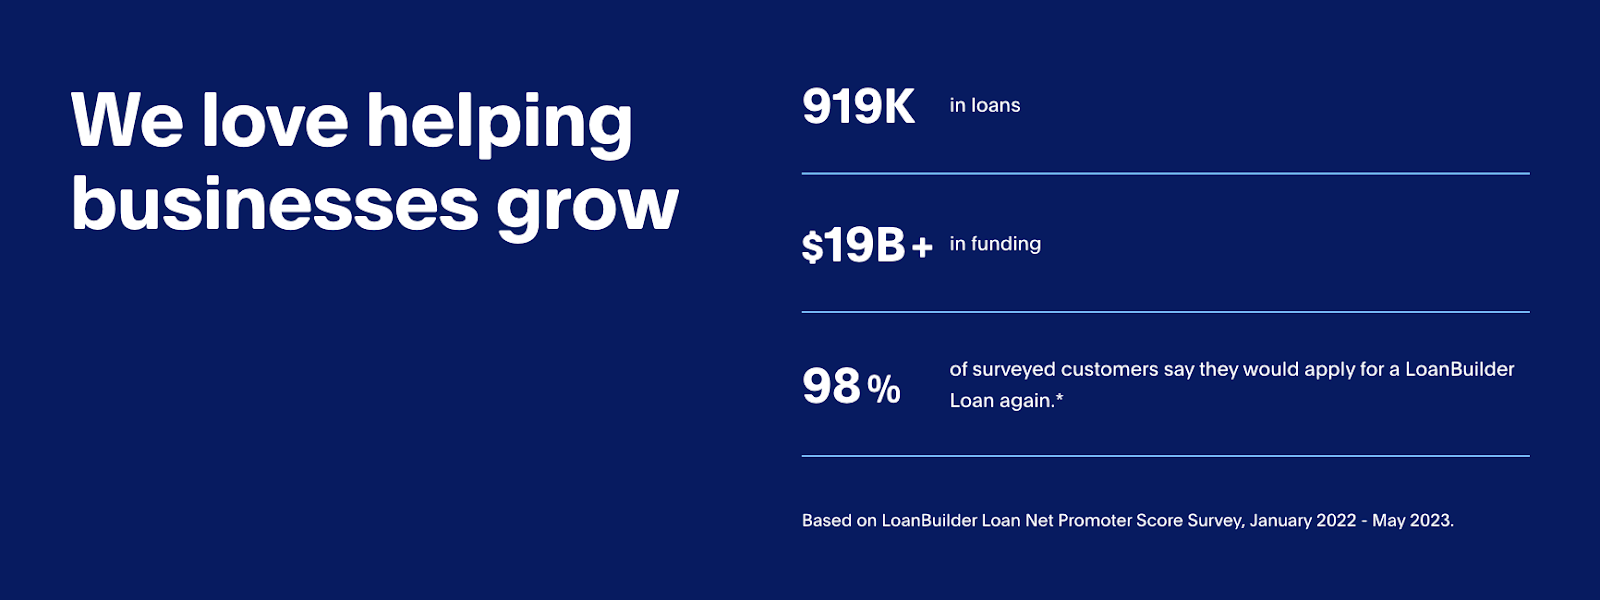
PayPal LoanBuilder is advertised as a quick, convenient way to get up to $100K in business funding. The company is more than reputable, and their marketing makes it sound like the easiest financing option in the world. But, what are the terms, how much does it cost, and is this really the best loan for your business? 

Let’s find out what LoanBuilder is, how it works, and explore exactly what you can expect if you apply. 

This is what’s in store: 

  • What is PayPal LoanBuilder?
    • How Much Does PayPal LoanBuilder Cost?
  • How Does PayPal LoanBuilder Loan Work?
    • 1. Apply With No Impact to Your Credit
    • 2. “Customizable” Funding
    • 3. Fixed-Fee Loan
    • 4. Fast Access to Funds
    • 5. Accessible Business Funding
    • 6. Weekly Repayment Terms Up to 12 Months
  • Frequently Asked Questions
  • Final Thoughts

Now, let’s get to it! 

What is PayPal LoanBuilder? 
Loan Builder PayPal

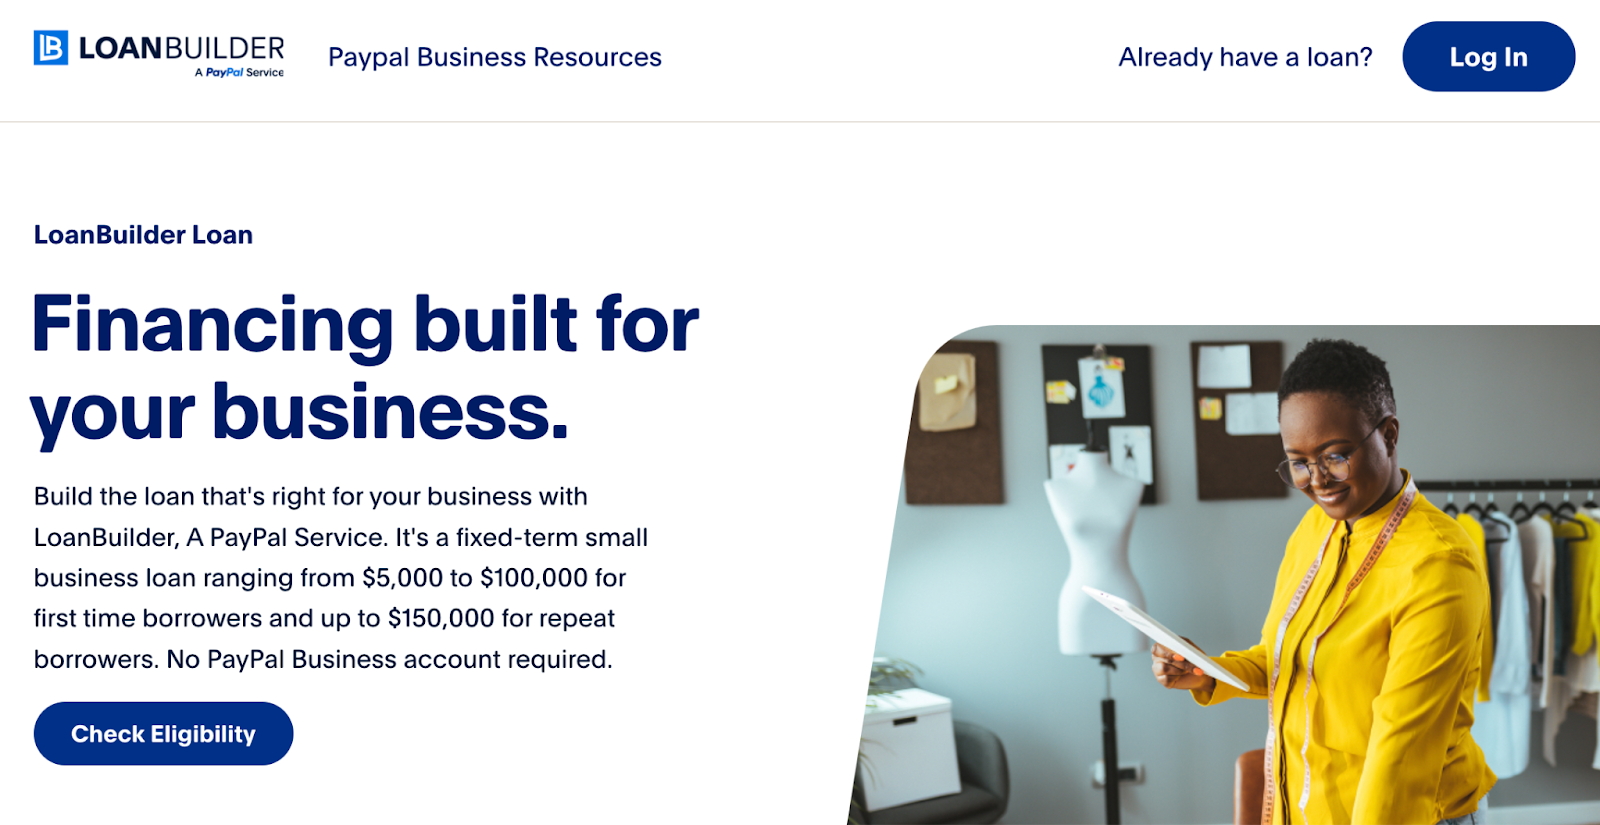
PayPal’s LoanBuilder is a service that offers fixed-term small business loans from $5,000 to $100,000 for first-time borrowers and up to $150,000 for repeat borrowers—the financing option is designed to be fast and flexible, with funds potentially available in your business bank account as soon as the next business day after approval.

The loan comes with transparent pricing, where you pay a clear, fixed fee along with a $20 Returned Item Fee if a payment is returned. There are no late fees, early repayment fees, or processing fees. You can choose a repayment term that suits your business needs, and payments are automatically deducted weekly.

To check if your business is eligible for a LoanBuilder Loan, you can complete a quick online questionnaire. This process won’t impact your personal credit score. If eligible and approved, you can customize your loan amount and term, sign the contract electronically, and receive the funds quickly.

To qualify, your business needs to have been operational for at least nine months with an annual revenue of at least $33,300. Keep in mind that LoanBuilder is a service provided by PayPal in partnership with WebBank. The loan application and approval process is designed to be straightforward and streamlined, aimed at helping businesses manage cash flow, finance projects, or tackle other business challenges.
paypal loanbuilder requirements

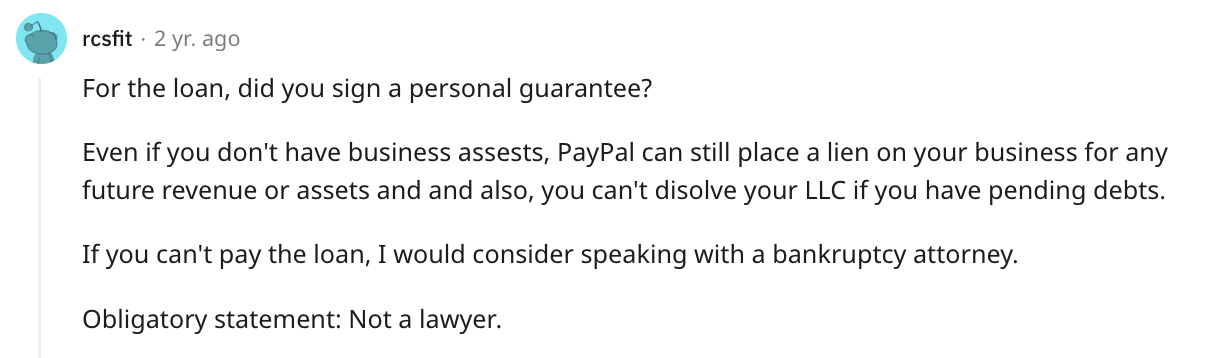
A LoanBuilder loan does require a personal guarantee. 

You might also like: Business Credit Cards without Personal Guarantee 

How Much Does PayPal LoanBuilder Cost? 

The cost of a LoanBuilder loan is determined by a single fixed fee known as the Total Loan Fee, which will be disclosed at the time of loan approval and remains consistent throughout the loan term. 

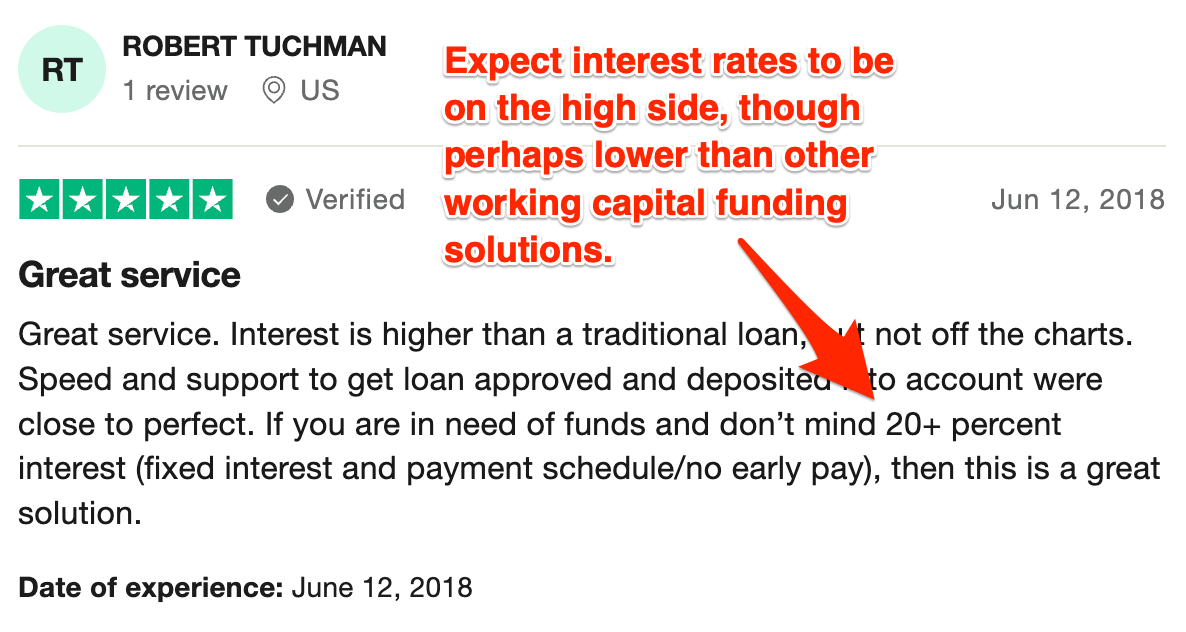
However, since this is a working capital-style loan, you should expect interest rates higher than you would get via, say, your business credit union. Still, they may be lower than other working capital solutions. 
PayPal Loan Builder interest rate

The specific amount of the Total Loan Fee varies based on: 

  1. The loan amount
  2. Repayment term
  3. Financial risk

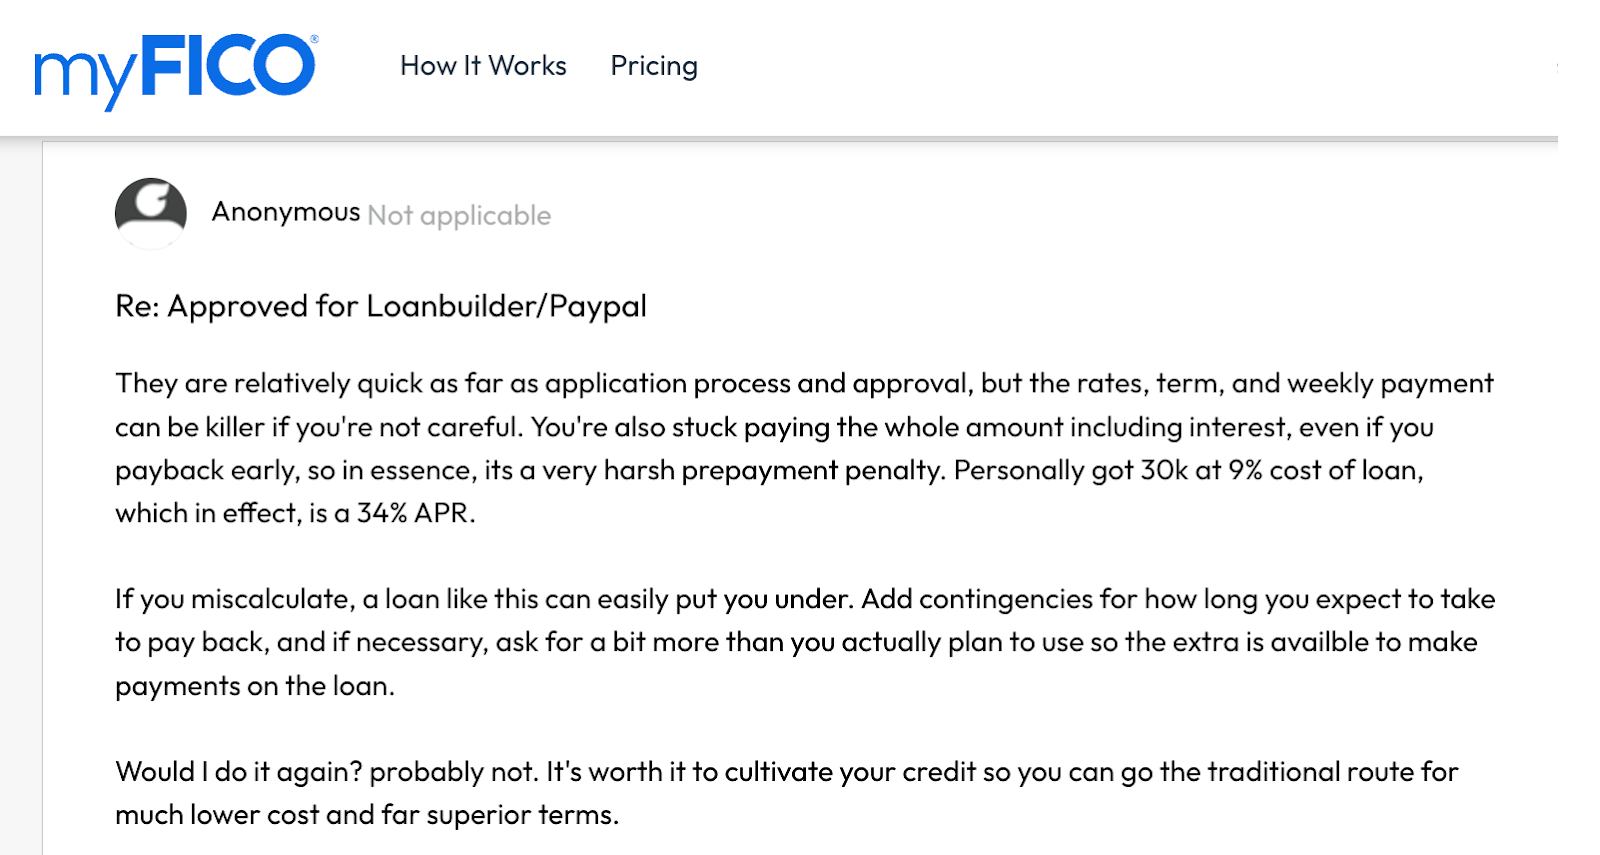
LoanBuilder Loans do not have additional fees such as late fees, early repayment fees, or processing fees—The Total Loan Fee is the primary cost associated with borrowing and is included in your repayment schedule.
Paypal loanbuilder review

To see your LoanBuilder cost, you’ll need to complete the loan application process and review the personalized terms.

Recommended: 3 Best Credit Unions for Small Business Banking

How Does PayPal LoanBuilder Loan Work? 

LoanBuilder from PayPal offers a pretty simple approach to business financing, providing you with a customizable loan experience tailored to your business needs. 

With LoanBuilder, you have the freedom to: 

  • Access funds quickly
  • Repay with clarity
  • Benefit from straightforward terms 

Let’s delve into the key features that will help you decide if LoanBuilder is the best choice for your business funding.

You might also like: A Deep-Dive National Funding Review: Should You Accept an Offer? 

1. Apply With No Impact to Your Credit
PayPal Loan Builder application

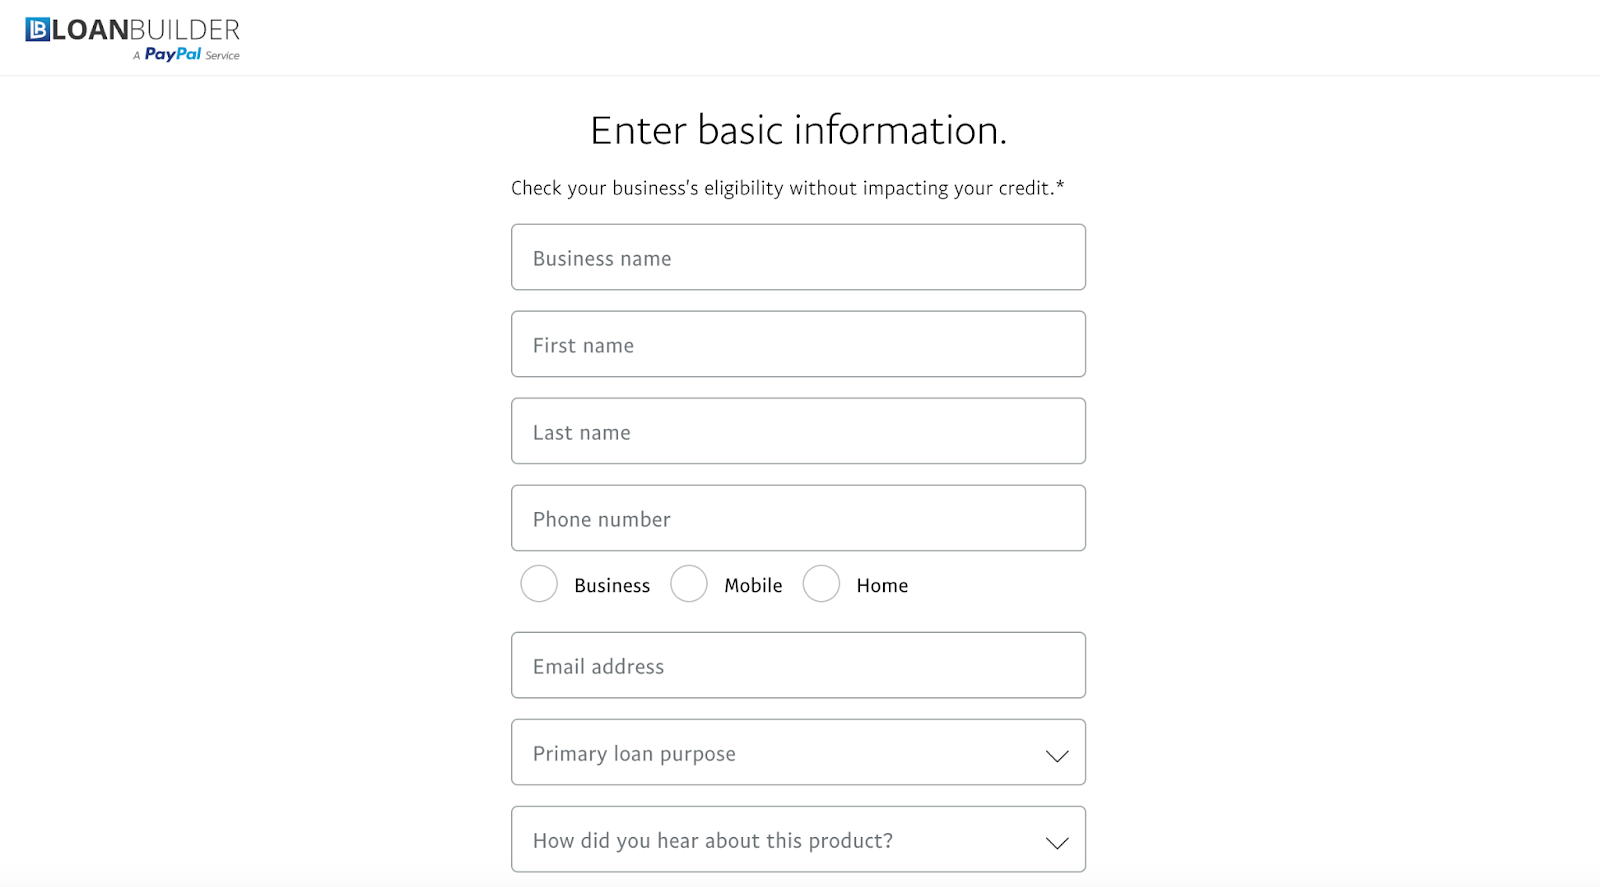
The PayPal LoanBuilder “application” is pretty straightforward. The questionnaire asks you for contact information, how you plan to use the funds, how you heard about the loan, business location, and business details. 

Details to have on-hand about your business include: 

  • Legal business name & DBA (if applicable)
  • Business address & website address
  • Entity type & state of incorporation
  • Annual revenue
  • Business start date
  • Number of employees
  • Industry & sub-industry
  • Percentage of ownership 

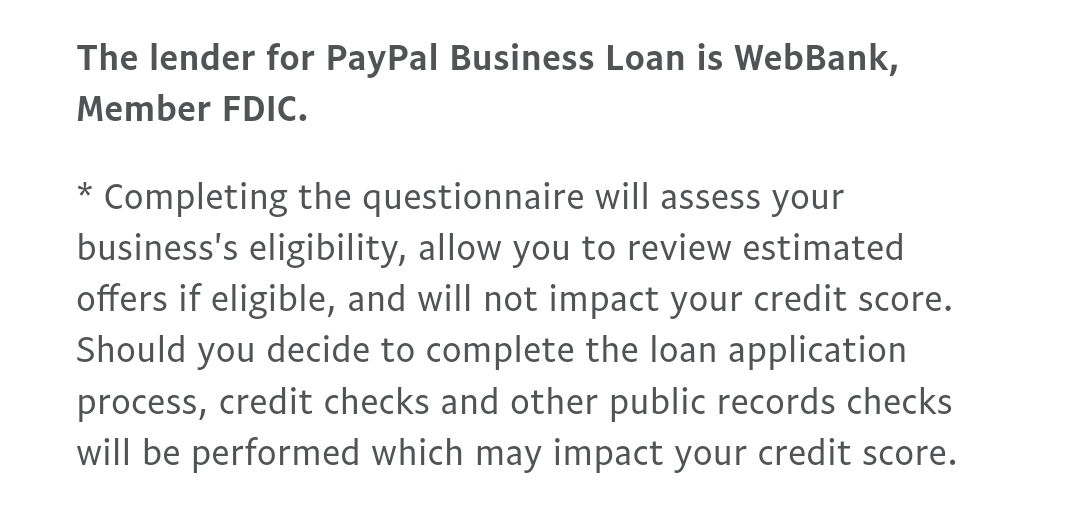
The application also asks for your Social Security Number and Employer Identification Number. Luckily, they do a soft inquiry into your personal credit for pre approval, which won’t negatively impact your credit score. 
PayPal Loan Builder soft inquiry

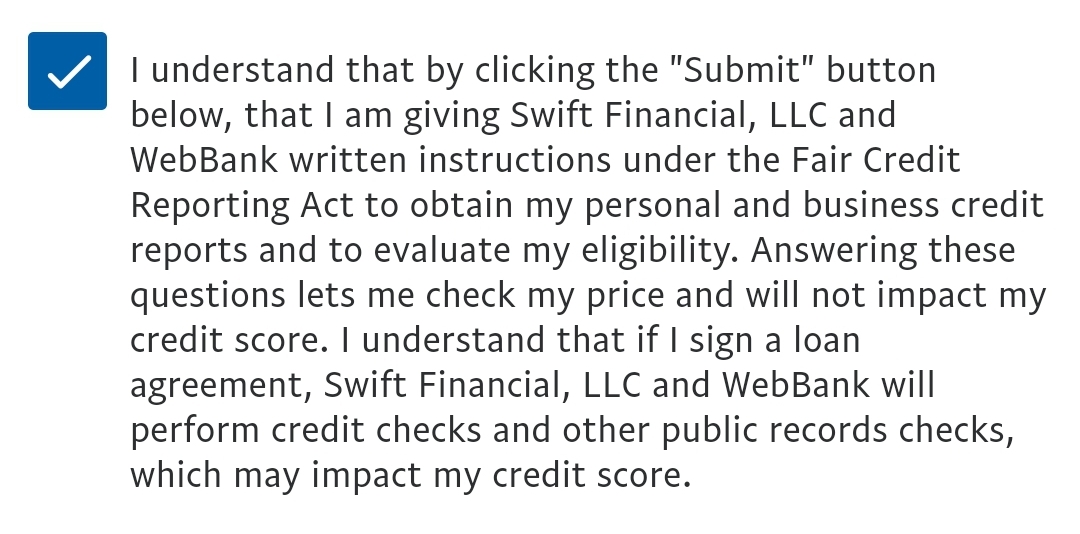
However, you will probably have to approve a hard pull for final approval. 
PayPal Loan Builder Hard Inquiry

Don’t move forward with that until you’re absolutely sure you want this loan.  

You might also like: Here’s How to [Actually] Get Business Credit With Just an EIN +More Options 

2. “Customizable” Funding
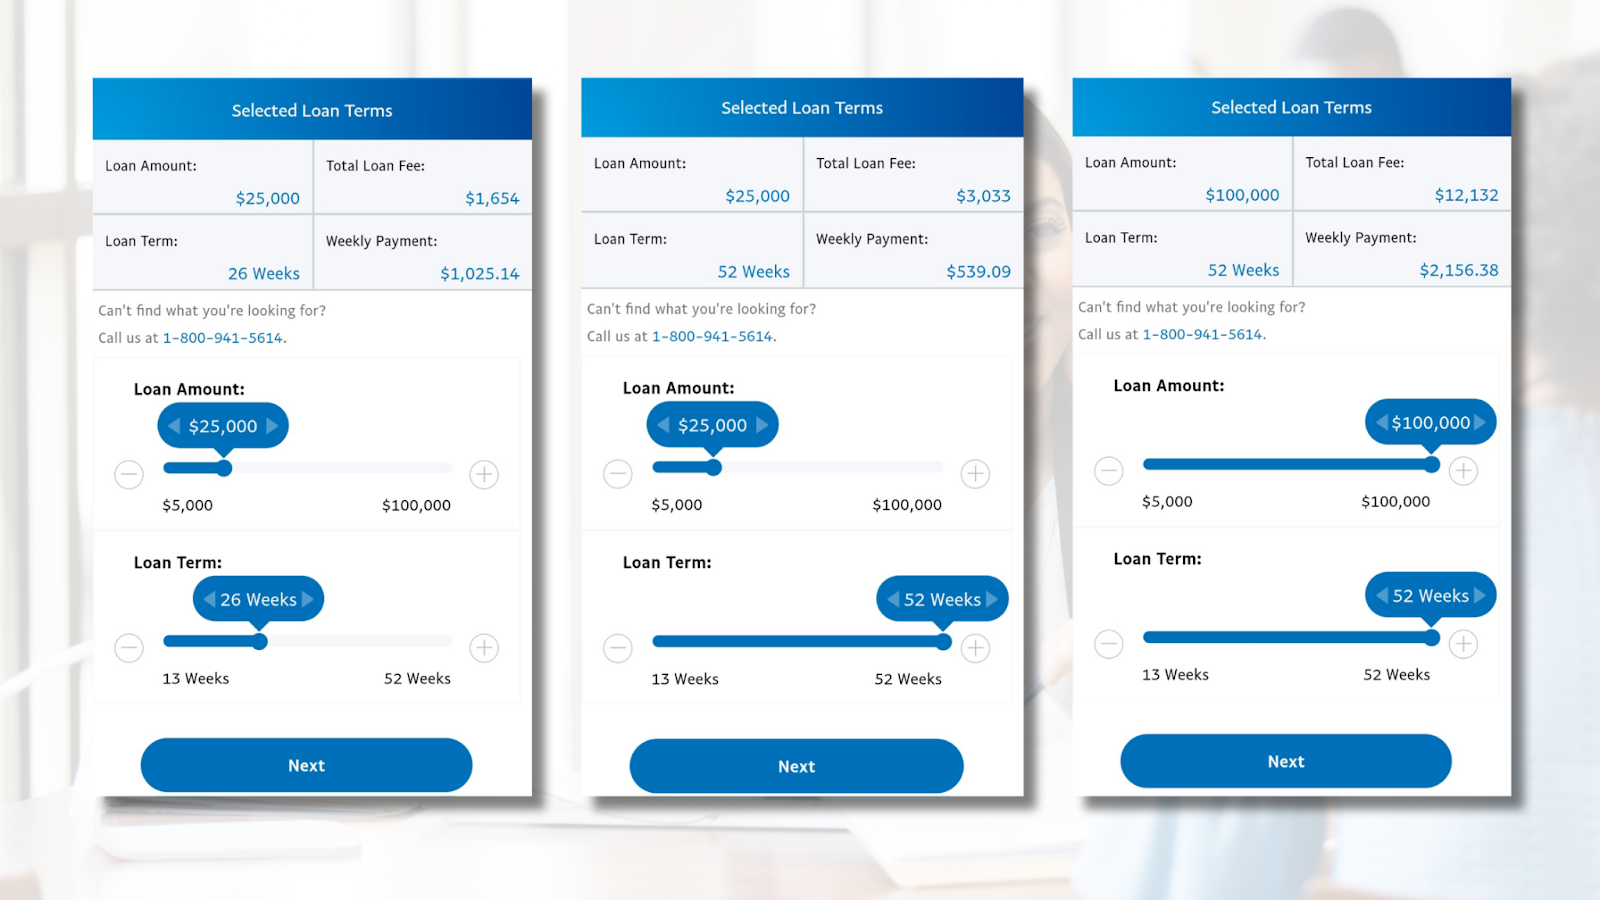
PayPal LoanBuilder Customized Loan

LoanBuilder advertises a “customizable” loan—This makes it sound as if you might get to choose your amount, terms, and rate, which would be pretty exciting. 

However, that’s not a realistic way to think about lending; lenders need to assess the financial risk before approving any type of financing. 

Still, after you’re pre-approved for a loan, you can choose your loan amount and repayment term. Your loan fee percentage will increase as your terms are extended. So, the longer you give yourself to pay off the loan, the higher your Total Loan Fee. 

If you do opt for this loan, consider giving yourself some extra time to pay it just in case something unexpected occurs, as you could be charged penalties for failing to pay on-time.  

3. Fixed-Fee Loan
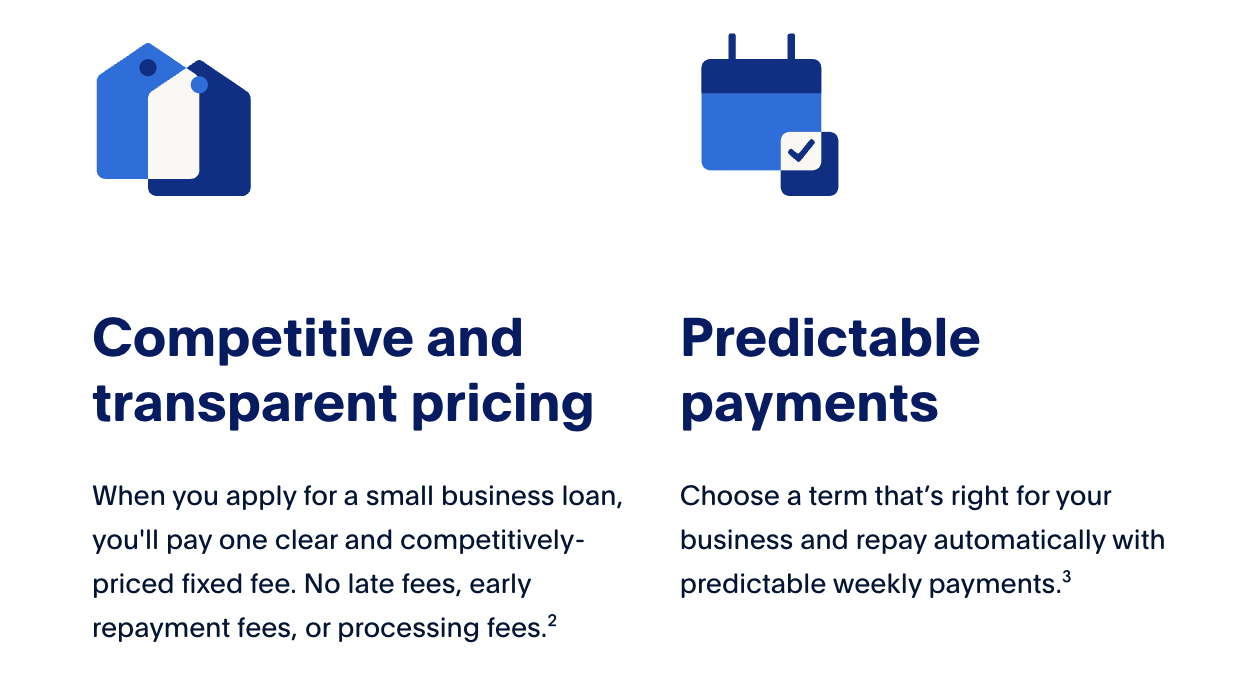
PayPal Business Loan Builder

When you take out a LoanBuilder Loan, you won’t have any upfront fees deducted from the loan amount you receive. Instead, the cost of borrowing—the single fixed fee, known as the “Total Loan Fee”—is spread out and paid gradually over the entire duration (life) of the loan.

Here’s a breakdown of what this means:

  • When you receive the loan amount, the full sum is deposited into your business bank account without any immediate deductions for fees or charges. This ensures that you have access to the entire loan amount upfront to use for your business needs.
  • The cost associated with borrowing the money is represented by a single fixed fee—This fee is agreed upon and disclosed at the time of loan approval; it does not change over the course of the loan.
  • Rather than paying a fee upfront or separately, it is integrated into your loan repayment schedule. Each time you make a repayment towards your loan (typically on a weekly basis), a portion of that payment goes towards covering the Total Loan Fee. This fee is gradually paid down along with the principal amount of the loan.

By structuring the loan this way, you get clarity on the total cost of borrowing from the outset, and you can plan your repayments knowing how much will be allocated towards the loan principal and how much towards the fixed fee. 

4. Fast Access to Funds
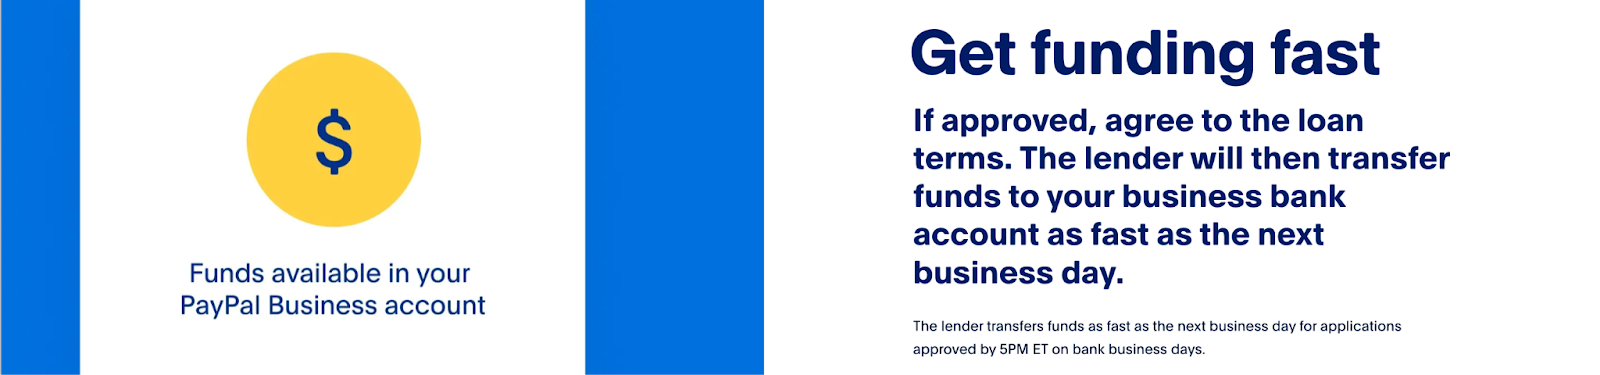
PayPal Builder Loan

The LoanBuilder lending process is designed to be fast… 

First, when you check your eligibility, it’s done through a quick online questionnaire. This initial eligibility check does not involve a hard inquiry on your personal credit report, which means it won’t affect your consumer credit score—This is helpful because you can explore loan options without worrying about potential negative impacts on your credit rating.

If your LoanBuilder Loan application is approved, the funds are transferred directly to your business bank account, often by the next business day after approval—This rapid transfer ensures that you can access the funds quickly to address business needs or capitalize on opportunities right away.

5. Accessible Business Funding
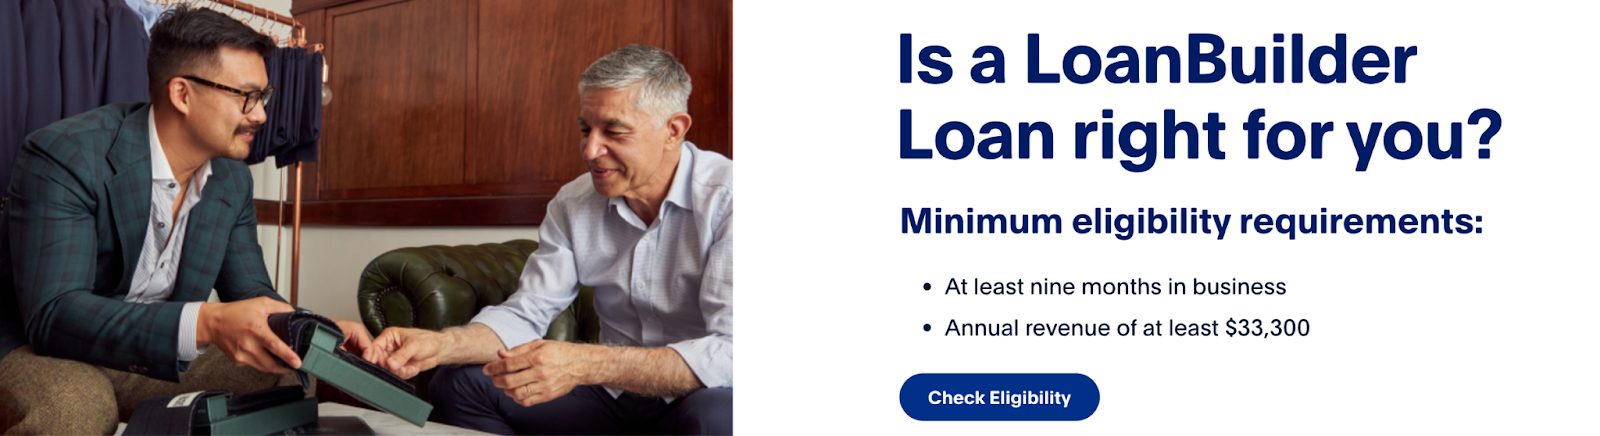
PayPal Loan Builder login

The eligibility requirements for a LoanBuilder Loan can be considered relatively low compared to some traditional business loans:

  • At least nine months in business
  • $33.3K annual revenue 

Requiring a minimum of nine months in business is relatively short compared to other types of business loans that might need several years in operation. Newer businesses can access financing sooner in their development stages.

While this amount varies depending on the size and industry of your business, $33,300 annual revenue is a moderate threshold—It’s achievable for many small businesses, including startups and those in their early stages of growth.

These requirements are inclusive and accessible to a wide range of small businesses, including startups and those with modest revenue streams. 

You might also like: Y Combinator: Fast Track to Success or Waste of Time? 

6. Weekly Repayment Terms Up to 12 Months
PayPal Loan Builder Funding

The repayment period for LoanBuilder Loans ranges from 17 weeks (approximately 4 months) to 52 weeks (approximately 12 months), depending on your eligibility and the loan amount you qualify for.

During the repayment period, you will make weekly payments towards your loan balance. 

The amount of each weekly repayment will be set based on: 

  1. The total loan amount
  2. The fixed fee associated with the loan
  3. The chosen repayment term

The weekly repayment amount remains consistent throughout the repayment period, providing predictability in your loan payments.

For example, if you have a loan with a 26-week repayment term, you will make 26 weekly payments until the loan is fully repaid. The amount of each weekly repayment is calculated to cover both the principal loan amount and the fixed fee—this helps you make sure the loan is paid off by the end of the chosen repayment term.

Frequently Asked Questions

Is PayPal legally a bank? 

No, PayPal is not a bank. It is a technology company that provides online payment services and financial solutions.

What bank does PayPal use for loans? 

LoanBuilder loans are provided by WebBank®, Member FDIC, in partnership with PayPal.

What is the minimum credit score for LoanBuilder? 

LoanBuilder does not disclose a specific minimum credit score requirement. Instead, eligibility is determined based on various business factors such as revenue and operational history—but the do require a personal guarantee

Does PayPal LoanBuilder report to credit bureaus? 

Yes, PayPal LoanBuilder reports payment activity to business credit bureaus, not personal credit bureaus. This can help businesses establish and build their business credit profile.

Final Thoughts

PayPal is a trustworthy financial company, with LoanBuilder being backed by a reputable bank. The loans they offer are pretty competitive in the working capital realm, but the high rates are a red flag for me. I never recommend my students take out a loan like this unless there is absolutely no better option—even with a flat fee, weekly repayments can eat at your profits.  

But, if you need to take out a high-interest loan and you’ve explored all of your options, this might be the way to go. If you have some time, I recommend you put some effort into your business credit so you can get loans and lines of credit with (much) better terms…it’s a game changer.  

Do you want to learn how to obtain up to $100K in business credit in as few as 30 days? Join Business Credit Workshop today! 

HD Supply Review: A Closer Look at This Vendor’s Net 30 Program

By Joe Lawrence

hd supply review and net 30 overview

One of the easiest ways to build business credit is by acquiring a Net 30 account. With such an account, you can establish your credit profile in 30 days. Since it typically involves tier-1 vendor tradelines, often dealing with large corporations or companies with a strong market presence, you can gain access to an account even with little credit history for your business.

This is where HD Supply comes in. HD Supply is a leading provider of maintenance, repair, and operations (MRO) products and services. With over 40 years of experience, the company has a good reputation for reliability, innovation, and quality, which is why it has become one of the trusted partners of businesses from many industries. There are also 40+ distribution centers in 25 states, making delivering quality, branded, and proprietary products right to your office or business address easy and quick.

You can choose from a diverse range of products at HD Supply, from HVAC to plumbing to janitorial supplies. The online platform is also where you can purchase building materials and tools for your next project. HD Supply caters to the needs of industry professionals, including contractors and facilities managers, providing necessities for the maintenance and upkeep of buildings, infrastructure, and commercial properties, among others.

HD Supply is also a top choice for many small business owners and startups because it offers flexible payment terms through the Net 30 vendor program. With this program, you can access a wide range of essential materials and supplies while deferring payment for up to 30 days. The company is known for giving customers valuable flexibility and cash flow management.

Let’s look at how HD Supply’s Net 30 vendor program works, its benefits, and how it can benefit your business’s procurement processes.

Contents

  • An Overview of HD Supply’s Net 30 Vendor Program
  • Product Range and Quality
  • Pricing, Payment Terms, and Conditions to Be Aware Of
  • FAQs

An Overview of HD Supply’s Net 30 Vendor Program

HD Supply’s Net 30 program is designed for businesses to benefit from the flexibility and convenience of purchasing essential supplies and tools while delaying payment. This gives them the ability to manage their cash flow efficiently.

hd supply net 30 account

The program comes with the following key features:

  • Flexible Payment Terms: You can pay purchases within 30 days of invoicing, letting you access products without providing immediate payment.
  • Extensive Product Range: There is a comprehensive variety of products in numerous categories, including appliances, cabinets and countertops, linens, HVAC, and plumbing. You can also purchase electronics, furniture and décor, and gas products from the online shop.
  • Broad Range of Services: HD Supply also provides custom products, from bi-fold doors to bypass doors, as well as rekeying services, bathroom vanities, window screens, and custom paint. Other services include renovations, financing, online solutions like e-procurement, online payment services, and many more.
  • Simplified Procurement Process: The Net 30 vendor program from HD Supply helps streamline buying and obtaining needed materials for your business. You can then place orders conveniently and receive your invoice, which you can pay within the 30-day timeframe.
  • Trusted Supplier: HD Supply is well-known for being a reliable supplier of quality MRO (maintenance, repair and operations) products and services that can support your operational requirements.
  • Convenient and Efficient: The online platform makes it easy to place your order, track shipments, and manage any invoices you may have. You get to save time and effort in keeping up-to-date with your orders, allowing you to focus on more important business activities.
  • Consolidated Purchasing: When you buy from HD Supply, you source a wide variety of products from a single supplier instead of purchasing from numerous other vendors. This approach simplifies the process, potentially reducing administrative costs for managing multiple vendors.
  • Credit Building: Net 30 programs like the one from HD Supply encourage you to pay your invoices on time consistently. Doing so can help you build a positive credit history, which can potentially lead to increased credit limits and more financing options for your business in the future.

Having tradelines with a tier-1 vendor like HD Supply is advantageous to your business’s credit profile. That’s because it demonstrates a strong and reliable payment history with this reputable supplier. Many lenders and credit agencies consider these tradelines with tier-1 vendors, such as HD Supply, as favorable, particularly when assessing your business’s creditworthiness. It indicates that you have the ability to manage financial obligations responsibly.

This Net 30 vendor program can contribute positively to your credit profile and get the chance to increase your access to financing and favorable terms in the future. Head here to apply for an account.

hd supply net 30 application

The application form is quite comprehensive compared to starter vendors, (such as companies that are listed in this article).

You will need to provide the following information:

  • Your business name
  • Business physical and email addresses
  • Contact numbers, including fax and phone
  • Your requested credit limit or equivalent to your anticipated monthly spend
  • Owner and management details
  • Your name, job title, and other information
  • Your bank account name, type, and number
  • Specific purchasing instructions

You also have to upload documents, including tax exemption and credit sheet.

upload items to get hd supply net 30 account

You must specify where to send invoices, whether via fax, email, or another option. Once completed, you can submit your application and wait for the response.

Product Range and Quality

HD Supply offers diverse products tailored to meet your needs, regardless of your business type and industry. There is a comprehensive selection of maintenance, repair, and operations (MRO) products, supplies, and materials, including:

  • Appliances such as dishwashers, microwaves, trash compactors, and ovens
  • Cabinets and countertops
  • Cleaning and janitorial items, including trash cans and bags, dispensers, and floor equipment
  • Doors and molding
  • Electrical equipment, tools, and accessories, as well as conduit, raceway, and fittings
  • Electronics like speakers, two-way radios, and TVs
  • Food service supplies like cookware, dinnerware, and kitchen kits

More products are available, along with services, such as the following:

  • Custom products like order forms, custom paint, signs, and custom-cut acrylic
  • RenovationsPlus for renovation and building consultation services with dedicated expert and project manager
  • Business services, including bin labels, customized reports, and strategic account management
  • Order services to make tracking more straightforward, including package tracking, special orders, and appliance delivery
  • Small business solutions, such as delivering nationwide the next day for free and flexible financing
  • Professional training, including live classes and certifications
  • Online solutions like electronic invoicing and online payment services

With all these offers, it is easy to see why HD Supply is often viewed as a one-stop shop for many businesses needing various supplies and equipment.

When it comes to quality, trusted companies like HD Supply always prioritize product quality to ensure their customers are happy. The company sources its items from reputable suppliers and manufacturers known for their durability and craftsmanship. Plus, HD Supply implements quality control measures on most of its products to assess and maintain product quality throughout the supply chain – that is, from procurement to delivery.

Pricing, Payment Terms, and Conditions to Be Aware Of

HD Supply provides competitive pricing on its products and services. The structure varies based on various factors, such as the type of product, quantity ordered, and other agreements. Be on the lookout for ongoing promotions and discounts to save more when buying supplies from HD Supply.

When it comes to building business credit, it can be an expensive strategy to use vendor tradelines. Some companies will ask for an application fee upon signing up for an account. Others will charge you a recurring membership fee so that you can continue to get access. But HD Supply is different. It is one of the few vendors that does not require any membership or application fees. All it needs is for you to pay the cost of the goods you buy, meaning there are no costs associated with this tradeline. Another great feature is that there is no minimum order requirement.

Now, on to the cautionary points:

  • While there is no minimum order, this benefit only applies to your very first order.
  • You will incur late fees if you do not pay off your balance on time.
  • A minimum of $2 or 1.5% (equivalent to 18% per year) will be charged for all your past-due invoices.
  • Not only will paying late cost you money, but it will also hurt your credit.
  • You need good credit standing for your business; otherwise, your application will get rejected, particularly if you do not have existing credit.
  • You can only pay toward your Net 30 account through a limited number of options: check, money order, ACH, and cash. This means you cannot use your credit card or any other payment method, which will incur a fee.

We hope you’ll consider our review about HD Supply’s Net 30 vendor program before you sign up. Having a Net 30 account with this company is an excellent choice, especially if you are a startup with a positive credit history or an established business. As it reports to Dun & Bradstreet, HD Supply is a great way to build your credit with this famous business credit bureau.

FAQs

What is HD Supply?

HD Supply is a leading maintenance, repair, and operations product distributor. You can also purchase construction supplies for use in a wide range of industries, such as hospitality, healthcare, government, and facilities maintenance.

How much does a Net 30 account from HD Supply cost?

Your HD Supply Net 30 account is absolutely free. However, you must be careful about the payment schedule to avoid late fees.

What are the benefits of applying for an HD Supply Net 30 account?

HD Supply reports to Dun & Bradstreet. You can also create an account even if you are a new business with no membership and application fees.

What can I buy from HD Supply?

HD Supply is where you can purchase industrial tools, equipment, supplies, and services to benefit your business.

What Does HD Supply Stand For?

It does not stand for anything specific as the company has been bought and sold and re-bought by Home Depot. But the company started in 1974 with the name of Maintenance Warehouse. In 2004, the name was changed to HD Supply.

Using NET 30 Vendors to Boost Your Business Credit

You may be looking to not only build a long term relationship with a vendor like HD supply but also enjoy the benefit of boosting your business credit score as well. We have a free report that can show you how to quickly build up your business credit score in just 30 days, click here to grab your copy.

How Long Does It Take to Build Business Credit? Fast Guide

By Joe Lawrence

how long does it take to build business credit

Building business credit is essential. After all, it directly influences a business’s ability to borrow money or obtain products or services on credit. Regardless of the business size, companies must actively build and maintain good business credit to gain access to financing. Additionally, it aids in achieving favorable terms with suppliers, thereby establishing creditworthiness in the market or industry where they operate.

The question is: How long does it take to build business credit? Some say it takes about a year, while others may tell you it is quicker than that. Although the answers vary depending on who you ask, one thing is for sure: You must start building business credit as early as possible.

  • Why Build Business Credit
  • Rapid Business Credit Boost Technique (as little as 30 days)
  • Using NET 30 Vendors
  • NAV Prime Card
  • FAQ

Why Build Business Credit

A survey in 2022 found that approval rates for business financing were extremely low during the pandemic. Even before that, almost 40% of businesses applying for financing did not get approved in 2020, according to the Federal Reserve statistics. Unfortunately, things did not get better, as it has become even more challenging for small businesses to access venture capital funding beginning in 2023. That’s why it is more important than ever to build strong business credit.

business owner building business credit

Strong business credit is achievable. Start with sufficient credit history; otherwise, poor or lacking history can become a major roadblock once you seek financing—even if it’s not a huge amount. With good business credit, your chances of getting approved for financing increase. That’s because it tells the lender that you have the ability and discipline to pay the amount you owe on time.

In general, many lenders look for a credit score of at least 500 for a business loan. However, this requirement increases depending on the institution you wish to work with. For instance, if you are applying for a business loan through a bank, you may need a credit score of about 700.

Here are the top motivating reasons to build your business credit today:

  • Capital Access: Potential investors like angel investors and venture capitalists are more likely to invest in your company if they see it has good credit. A good rating also opens your business to other financing options, including loans from traditional banks, alternative online lenders, and lines of credit.
  • Separation of Personal and Business Finances: This benefit is crucial for protecting personal assets if your business encounters legal issues or financial challenges. That’s why one of the very first steps you should take is to structure your business as a separate legal entity, like an LLC. That way, creditors cannot go after your personal assets, as they are not a part of your business.
  • Business Growth Opportunities: Because you have access to better credit terms and financing when you need it, you have the chance to seize options and openings for your business. Having a solid business credit profile allows financial flexibility, which is valuable in capitalizing on growth and expansion opportunities.
  • Cash Flow Management: Another benefit of good credit rating is that it improves cash flow, allowing you to have a fallback during economic downturns, for instance. You can get an influx of cash when needed to meet growing or continuous customer demand.
  • Negotiation Power: Gain leverage in contract and pricing negotiations with a good business credit standing. It’s helpful in industries such as professional services, where contracts are generally negotiated on an ongoing basis.

With the list above, you are probably ready to build your business credit. But how long will it take? And more importantly, how long does it take to build good business credit?

So, here’s our short answer to the question: It takes as few as 30 days to build business credit. However, building a solid profile with a positive and reliable credit history that reflects your business’s creditworthiness is a different kind of ballgame.

In order to have a solid profile, you must demonstrate responsible financial behavior, which includes making timely payments on loans and lines of credit. You must also never overspend, making sure to maintain a reasonable credit utilization level or the ratio of your business credit balances to your credit limits. In general, you should keep the credit utilization level below 30%.

Additionally, as a business, you most likely have several credit accounts. How you manage your various accounts can impact your business credit. Therefore, you should establish these credit accounts and use credit responsibly, which often involves monitoring the business credit report regularly. If there are any issues, they should be addressed immediately to maintain a solid credit profile over time.

Rapid Business Credit Boost in As Little As 30 Days

If you go to Google and search for “how long it takes to build business credit,” you will find a variety of answers, along with tips and how-to guides. Steps include formalizing your business and its structure, getting business insurance (if needed), licenses, and an Employer Identification Number (EIN), which you can use to apply for credit. You also need to open credit accounts that regularly report to business credit bureaus:

  • Dun & Bradstreet (D&B)
  • Experian Business
  • Equifax Business
  • Bureau Credit Reports, Inc. (BCR)

Perhaps the most important one is a Dun & Bradstreet number, commonly referred to as the DUNs number. This unique nine-digit number is generally used to identify a business. Typically, creditors ask for your DUNS number and EIN before agreeing to issue any business credit.

A checking account is also essential to building your credit profile. It’s important to maintain an adequate balance with no overdrafts and bounced checks to show creditors you are financially responsible. You should also network with banks and other professionals in the finance industry. This article provides a more detailed guide on how to build your credit.

Now, onto the more exciting part: building your business credit quickly. Here, I present two ways to fast-track building a solid foundation for your business credit.

First, register for relevant Net 30 accounts. These accounts let you purchase goods on credit, which you must pay back within 30 days. Suppliers demand that you have a separate Net 30 account. That’s why businesses usually only register with suppliers they use often. The significant requirement to bear in mind is to be consistent in paying off your Net 30 accounts on time. With this simple strategy, you don’t just accelerate your business credit building but also create a strong start for it.

Here’s how 30-day net vendors help with business credit building:

When you work with vendors who offer Net 30 terms, you establish trade references. These vendors typically report your payment history to Dun & Bradstreet, which helps you build a positive credit history for your company.

Let’s say you have business credit cards, loans, or other credit accounts on top of the trade references mentioned above. This means you have diversified your credit profile, which many creditors and lenders view more favorably. As a result, your business credit score has a bigger chance of seeing improvement within 30 days.

woman holding business credit card

As discussed in this article, you need to make timely payments with vendors, particularly those with Net 30 terms. Doing so demonstrates your company’s ability and reliability when it comes to managing credit. Pay invoices without delays consistently to strengthen your creditworthiness, and you will see a positive impact on your credit score in no time.

The next step is to expand your credit access by ensuring you have positive trade references with Net 30 vendors. This simple activity allows you to enhance your business’ creditworthiness, further increasing your access to credit and financing options over time.

Lastly, you need to build good relationships with vendors, starting with responsibly paying invoices on time and in full. That way, you get favorable terms and discounts that could benefit your business in the future, including contributing to your overall creditworthiness.

Utilizing 30-day net vendors is an effective strategy that could lead to a more solid business credit profile and establish a strong foundation for your company’s financial health and future.

Apart from 30-day net vendors, you can gain a quicker and bigger advantage when you have business credit cards. You have plenty of options here, but a top recommendation is a Nav Prime card. If you have doubts about whether this credit card is right for your business, this article can help you decide.

So, what exactly is the Nav Prime Card? It’s a charge card that costs $49.99 monthly. Although expensive, this card lets you manage your business credit, giving you access to reports each month. Unlike other credit cards, Nav Prime does not require an annual fee, personal guarantee, or security deposit. You can even link it to your business checking account, where you can add multiple cards and accounts with no extra charge.

With a Nav Prime card, you can build your business credit through the following:

Nav Prime issuers will generally report payment activity to business credit bureaus. That’s why it is significant that you make timely payments on the card, which is the key to establishing a positive payment history for your company. Paying on time and in full can benefit your business credit over time.

You are free to use your Prime card as needed. However, since the goal is to gain a positive impact on your credit history, it is advisable to keep your balances low. Consider your credit limit when determining the credit utilization ratio, which tells lenders, investors, and financial institutions that you can manage your credit. It also helps improve your credit score in the long run. Maintain a good credit utilization ratio for 30 to 90 days to build a strong profile.

The Nav Prime card aids in diversifying your business credit profile, which creditors and lenders always consider before approving financing. Having a diverse credit mix, which includes your Nav Prime card, other credit cards, trade lines, and loans, can help build your business credit within 30 days.

nav prime card

The next step is to aim for a credit limit increase. You need to demonstrate that you use your credit responsibly to get approved for an increase. As it improves your creditworthiness as a business, you may then become eligible for a card credit limit increase. The higher your credit limit, the better your credit utilization ratio. It then gives you more purchasing power, which is certainly beneficial for your business.

Nav Prime cards come with expense trackers, allowing you to monitor and manage your business spending. Use these tools for budgeting, controlling business finances, and financial planning.

Using the Nav Card, you can manage your business’ credit profile correctly and responsibly. Additionally, it enables access to business credit reports while gaining new trade-ins, which are vital to building positive business credit.

Building business credit is vital for every entrepreneur, operator, and owner. It establishes your business’ financial stability while allowing you access to financing and opening doors for long-term growth. With the tips above, you can build your business credit within 30 days.

Let us help you accelerate your business credit efficiently when you sign up for free business credit training today.

FAQ:

How long does it take to build business credit with net 30?

Using a 30-day net vendors report to Dun & Bradstreet can help build your business credit within 30-60 days. The more consistently you make purchases and pay invoices on time, the quicker you achieve a solid profile.

How long does it take for an LLC to get a credit score?

Engaging in credit-related activities, such as opening business credit cards and obtaining trade credit with your preferred suppliers, can help build a credit history quickly, often within 30 to 90 days.

How long does it take to build business credit to buy a car?

If you have proven your business’ creditworthiness by being consistent and responsible with your credit use, you can buy a car within 90 days or less.

What is the fastest way to build credit for an LLC?

Establish your business credit accounts, get a business credit card, pay on time, and work with vendors and suppliers who regularly report to credit bureaus to build credit fast.

Boosting up your business credit profiles takes a little bit of work, but it is very much worth it. Spend the time to create a strong foundation to take care of you and your business in the future.

Grab our FREE Report on How To Build Business Credit In Just 30 Days… Click Here

Corporate vs Business Credit Card: What’s the Difference? 

By Joe

Corporate vs Business Credit Card

I regularly review business credit cards and corporate card offers on this blog, and I often need to clear up the difference when I’m describing a corporate card offer. Here, I decided to create a resource that explains the differences between corporate vs business credit cards to refer readers and coaching students to. 

I’ll explain the differences in a way that’s super easy to understand, and point you to some relevant content so that you can learn more about specific card offers. And, I’ll answer the questions that I hear most often from my coaching students. 

This is what’s in store: 

  • The Difference Between Corporate Cards & Business Credit Cards
  • The Advantages of a Corporate Card
    • Can a Small Business Get a Corporate Credit Card?
  • The Advantages of a Business Credit Card
    • Is Your Business Card a Corporate Card?
  • Frequently Asked Questions
  • Final Thoughts

Let’s go! 

The Difference Between Corporate Cards & Business Credit Cards

Right out the gate, there is one core difference between corporate cards and business credit cards. What is the difference between a corporate card and a business credit card?

While both are used by businesses to improve cash flow, and may come with a line of credit to improve cash flow, the key distinction is in the payment terms: 

  • Business credit cards have a revolving credit line, so you can carry a balance each month and make a minimum payment if you choose. 
  • Corporate cards must be paid in full each billing cycle, whether that be every 30 days (net 30), 60 days (net 60), or a different time frame. 

At first glance, it may seem like an easy choice if you’re deciding which card to apply for. Who wants the obligation to pay off your balance when you could have the freedom to pay it off over time? 

…Right?

Well, it’s not that simple — Corporate cards are not inferior to business credit cards by any means. Let’s look closer. 

You might also like: 41 Companies That Help Build Business Credit [Beyond Net 30 Vendors] 

The Advantages of a Corporate Card

The point of a corporate credit card is to streamline financial transactions and manage expenses effectively. Rather than relying on personal credit cards for work-related costs, companies often issue corporate credit cards to employees. 

This not only provides a level of convenience by eliminating the need for individuals to front their own money but also facilitates a smoother expense tracking system. A corporate card typically comes equipped with features that helps businesses: 

  • Monitor and manage budgets
  • Ensure a transparent expense record 
  • Simplify reimbursements
  • Separate personal and business expenses
  • Get accurate financial reporting, taxation, and accounting

Furthermore, companies can implement access controls by setting spending limits and specifying where the card can be used, thereby ensuring that expenditures align with approved purposes. 

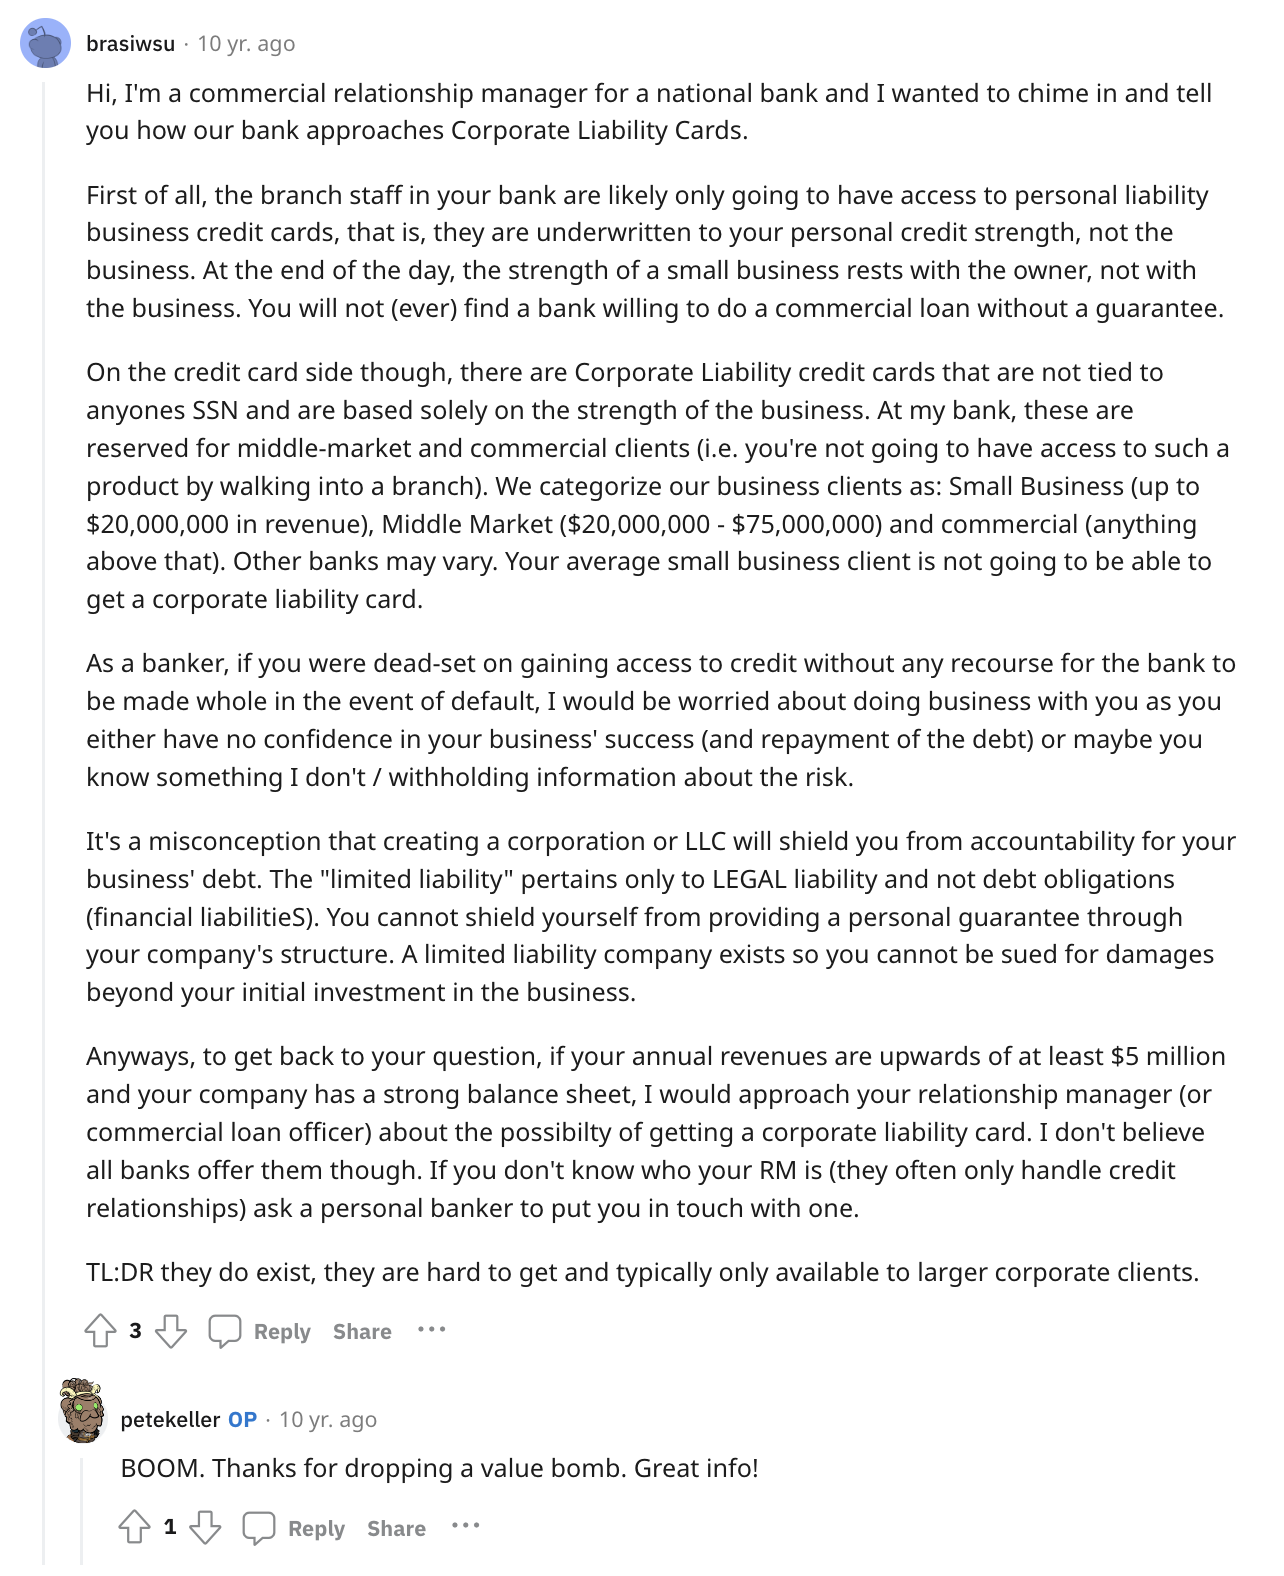
Business Credit card vs corporate credit card

In essence, a corporate credit card serves as a financial tool to enhance the efficiency of business operations, providing both convenience for employees and effective financial management for the company.

Plus, many corporate cards come with added perks like savings on software costs or ad spend. And, many of the newer corporate cards are completely free because of partnerships. So, obtaining one of these cards is like having a membership that offers exclusive access to discounts within a niche business network.  

You might also like: Have You Heard About the Free Stripe Corporate Card Cashback Benefits? 

Can a Small Business Get a Corporate Credit Card? 

Pros and cons of corporate credit cards

There is a widely-believed myth that corporate cards are for enterprises and credit cards are for small businesses. The truth is that small businesses can, absolutely, obtain corporate cards. 

Corporate cards are typically issued based on business income, not necessarily credit scores. So, if your small business meets the revenue requirements, and you want the card, you might as well apply. 

Many corporate cards require at least $4 millions in annual revenue, but some of the newer corporate cards will accept you with as little as $5K per month. 

You might also like: In-Depth Divvy (BILL) Credit Card Review: Read This Before You Apply 

The Advantages of a Business Credit Card

A business credit card is a line of credit crafted to meet the unique needs of a business. It functions similarly to a personal credit card but is tailored to streamline financial management for companies. 

The primary objective is to offer businesses a convenient and efficient way to: 

  • Make purchases
  • Cover expenses 
  • Maintain financial control
  • Free-up your personal credit
  • Get access to substantial lines of credit

Like its corporate counterpart, a business credit card usually provides features such as detailed expense tracking and a streamlined reimbursement process, which contribute to effective financial oversight. 

And, some business credit cards offer the ability to issue additional cards to employees with preset spending limits. 

The inclusion of rewards and incentives, specifically designed for business-related expenses, adds another layer of appeal. Moreover, responsible use of a business credit card contributes to building the credit profile of the business itself, separate from the personal credit of the business owner.

In a nutshell, a business credit card is a tailored financial tool that enhances the efficiency of business operations by simplifying expense management and providing flexibility in financial transactions.

You might also like: This is How to Leverage Business Credit to Transform Your Life 

Is Your Business Card a Corporate Card? 

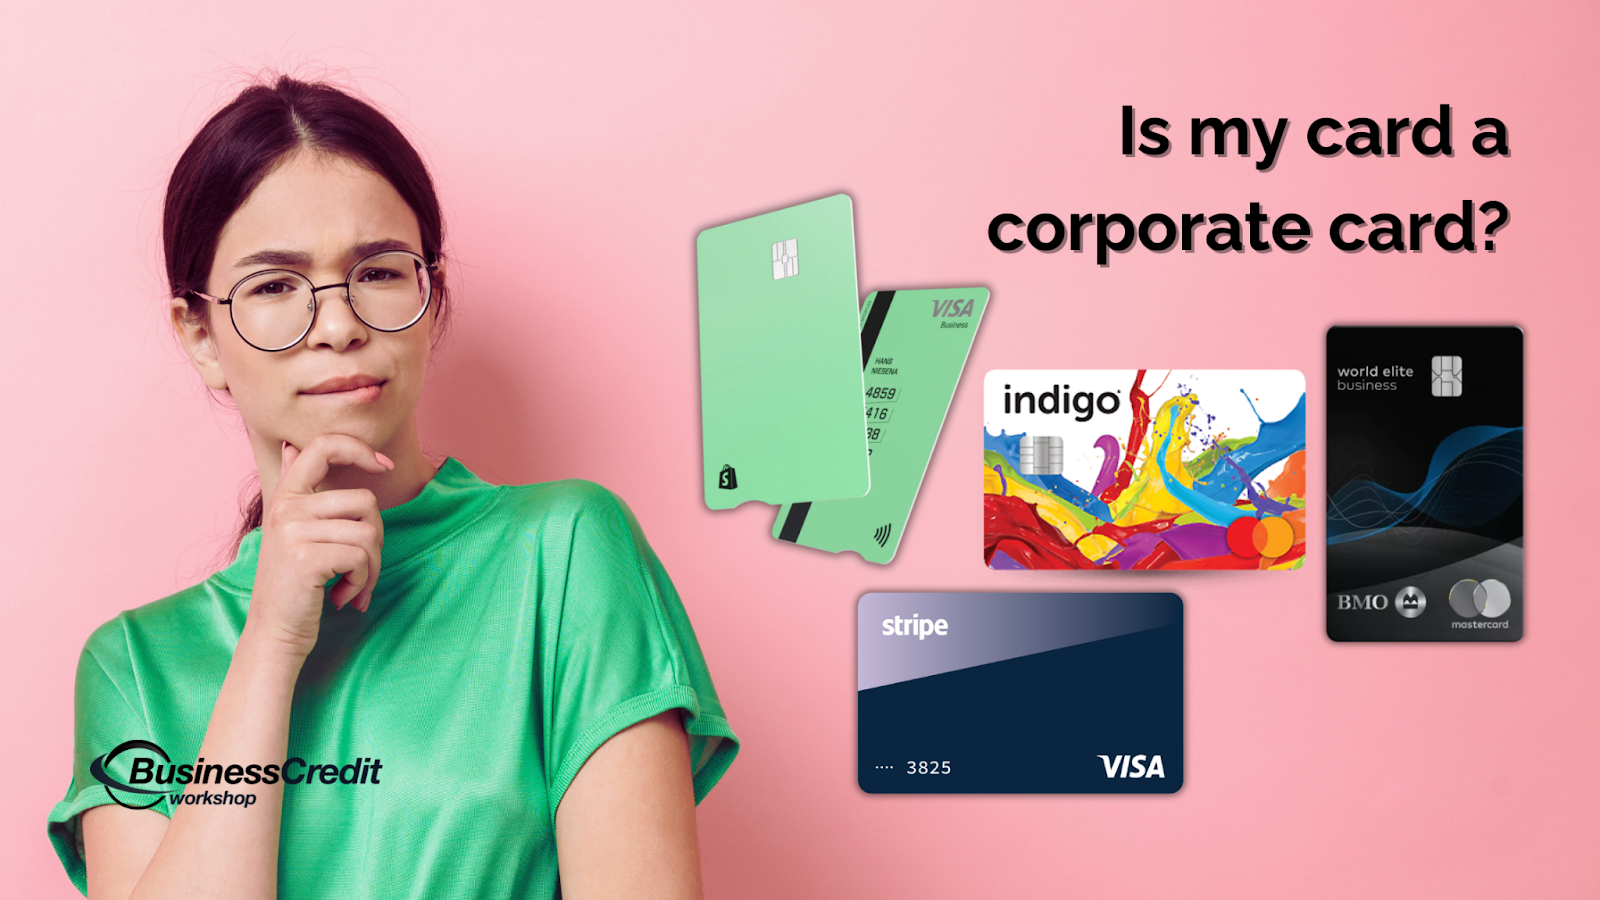
Small business credit vs corporate card

As a business owner, if your credit card is in your company’s name, features detailed expense tracking, and you pay the balance in full each billing cycle, it’s likely a corporate card. However, if it’s in your personal or business name, issued by a bank, and involves revolving reimbursement, it’s probably a business credit card. 

Keep in mind, if payments are due in full each billing cycle, it might be a secured business credit card – For clarification, check your card issuer’s information or contact customer service.

You might also like: The Ultimate Tillful Review (+New Secured Credit Offer for Businesses) 

Frequently Asked Questions

Does a corporate card hurt your credit score? 

No, a corporate credit card typically doesn’t impact your personal credit score. Since it’s usually issued in the company’s name and is the responsibility of the business for repayment, your personal credit history remains separate. However, if you do not pay as agreed, and the card comes with a personal guarantee, this could have a negative impact on your score.

Who is eligible for a corporate credit card? 

Businesses that meet the revenue requirements, which may be as high as $4 million per year, are eligible for corporate card accounts. The businesses can then implement their own eligibility requirements and spending limits for staff and employees. 

Can I use my corporate credit card for personal use? 

Using a corporate credit card for personal expenses is generally discouraged. Corporate cards are intended for business-related transactions. Mixing personal and business expenses can complicate accounting. And, it’s super important to follow company policies regarding card usage.

Who pays for the corporate credit card? 

The company is responsible for paying the expenses incurred on a corporate credit card. Corporate cards are issued by the company to streamline business-related transactions, and the company covers the costs directly.

What's a good credit card for a small business? 

There are several options for small business credit cards. Popular choices include the Chase Ink Business Preferred and several options from Bank of America. Some of my favorites are from small community banks and credit unions. The best card depends on your business’s specific needs, such as rewards, expense management features, and credit limits. See the best credit cards for entrepreneurs.