• Home
  • Free Funding Guide
  • What We Offer
    • Products
    • Services
    • Free Guide
  • About Us
  • Contact
  • Sign Up

  • Ask Joe Any Question!
  • Business Credit Cards
  • Business Line of Credit
  • Topics

The Revenued Business Card: What is it & Do You Need it? 

By Joe

Revenued Business Card

The Revenued business Visa® card is a popular new way for businesses manage their spending (and to get funding in as little as an hour after you apply). So, if not a loan or line of credit, what is it? And, is it worth it? 

Here, we’ll look at the details of the offer including an overview of the company, rates and fees, limits, and get answers to questions you might have about the Revenued business card. 

This is what’s in store: 

  • What is a Revenued Business Card?
    • What is Pearl Capital MCA Funding?
    • Revenued Business Card Requirements
    • Company Overview
  • How Does a Revenued Business Card Work?
    • 1. Flexible Line of Credit
    • 2. Control & Monitoring
    • 3. Super Quick Funding
    • 4. Dedicated Support
  • Frequently Asked Questions
  • Conclusion: Is the Revenued Business Card Legit?

Now, let’s roll! 

What is a Revenued Business Card?
Revenued business card review

The Revenued business card is a “fee-free,” 3% cash back, commercial prepaid card issued by Sutton Bank, designed specifically for business needs—It’s not a credit card, loan, or a gift card, and it’s meant to purchase goods and services related to your business activities.

There are no: 

  • Monthly maintenance fees
  • Card replacement fees 
  • Expedited delivery fees
  • Statement fees 

However, if you use an out-of-network ATM, additional fees might apply.

With the Revenued business card, you also get access to a “Flex Line” feature, providing you with a flexible “line of credit” up to $500K. And, it’s funded through a Pearl Capital account, using merchant cash advance (MCA) funds (Originally, this made me think the company was a white label solution for Pearl Capital funding). 

Within the flexible line of credit, there are spending limits: you can spend up to $10,000 per day, $50,000 per month, and no more than $10,000 per transaction.

You might also like: Is Carputty Legit? A Complete Auto Financing Review 

What is Pearl Capital MCA Funding?
Revenued business card login

For individuals considering a Revenued business card, Pearl Capital MCA funding offers a financial solution worth exploring. MCA, or Merchant Cash Advance, funding is essentially a factored loan, wherein a lump sum is provided upfront in exchange for a percentage of future credit card sales—This means that instead of a traditional loan with fixed payments, repayments are based on a percentage of daily credit card transactions. 

It’s a quick and flexible option for businesses in need of immediate cash flow, although it’s important to note that MCA funding typically comes with higher fees and shorter repayment terms compared to traditional loans. 

You might also like: A Deep-Dive Credibly Review: Is Their Financing Right for You? 

Revenued Business Card Requirements

To obtain a Revenued Business Card, you’ll need to meet certain requirements—Firstly, you must have a valid email address and reliable access to the internet. 

You also need: 

  • A legally registered LLC or corporation 
  • At least a year in business
  • A dedicated business checking account
  • At least $20K in monthly deposits

Other factors may limit your ability to obtain funding during the underwriting process. However, your credit shouldn’t impact your ability to obtain a Revenued business card.

You might also like: Could a Stripe Capital Loan Get Your Business Through a Rough Patch? 

Company Overview
Revenued loan

There are several companies at play here (Sutton Bank, Pearl Capital, Marqeta). For the sake of staying relevant, let’s peek behind the curtain at Revenued – the company presenting the actual product. According to their own marketing, “Revenued is a card that cares less about FICO and more about your business.”

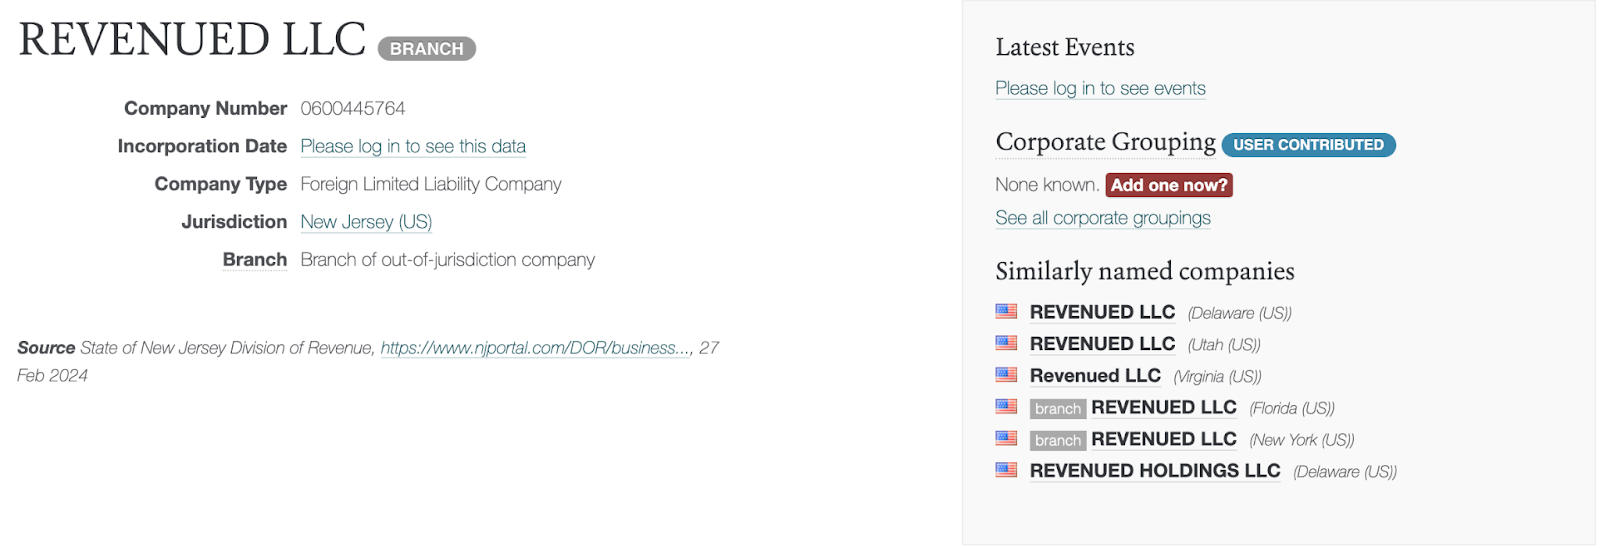
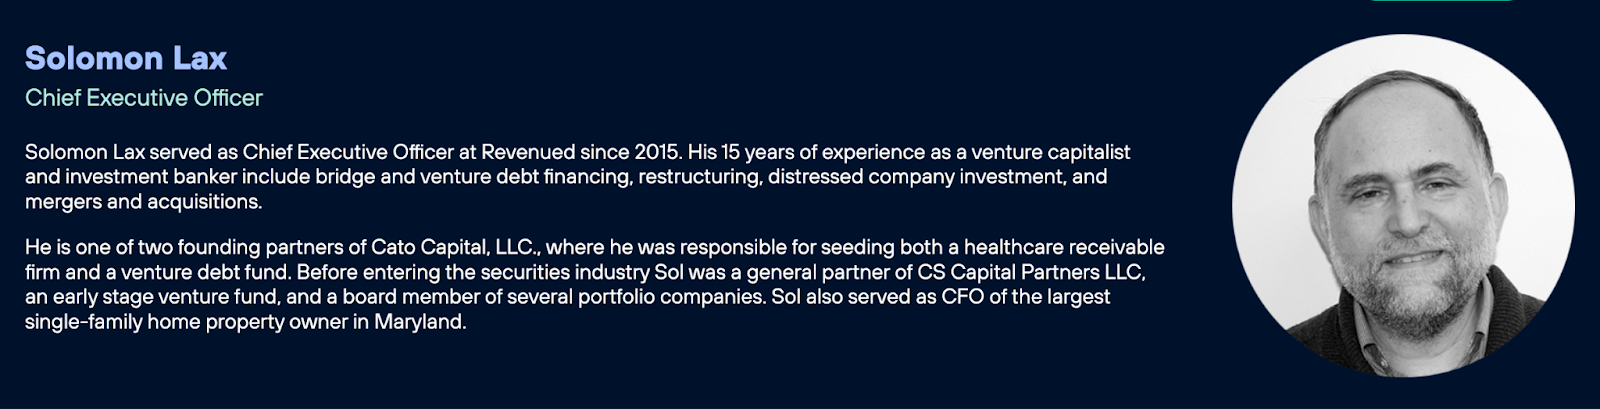
Revenued LLC is a New Jersey-based, private, for profit financial solution provider that was founded in 2017. The company’s current CEO, Solomon “Sol” Lax, is claimed to have been at his current position since 2015 (but the entity wasn’t officially established until a couple years after this). 
Revenued business card + flex line

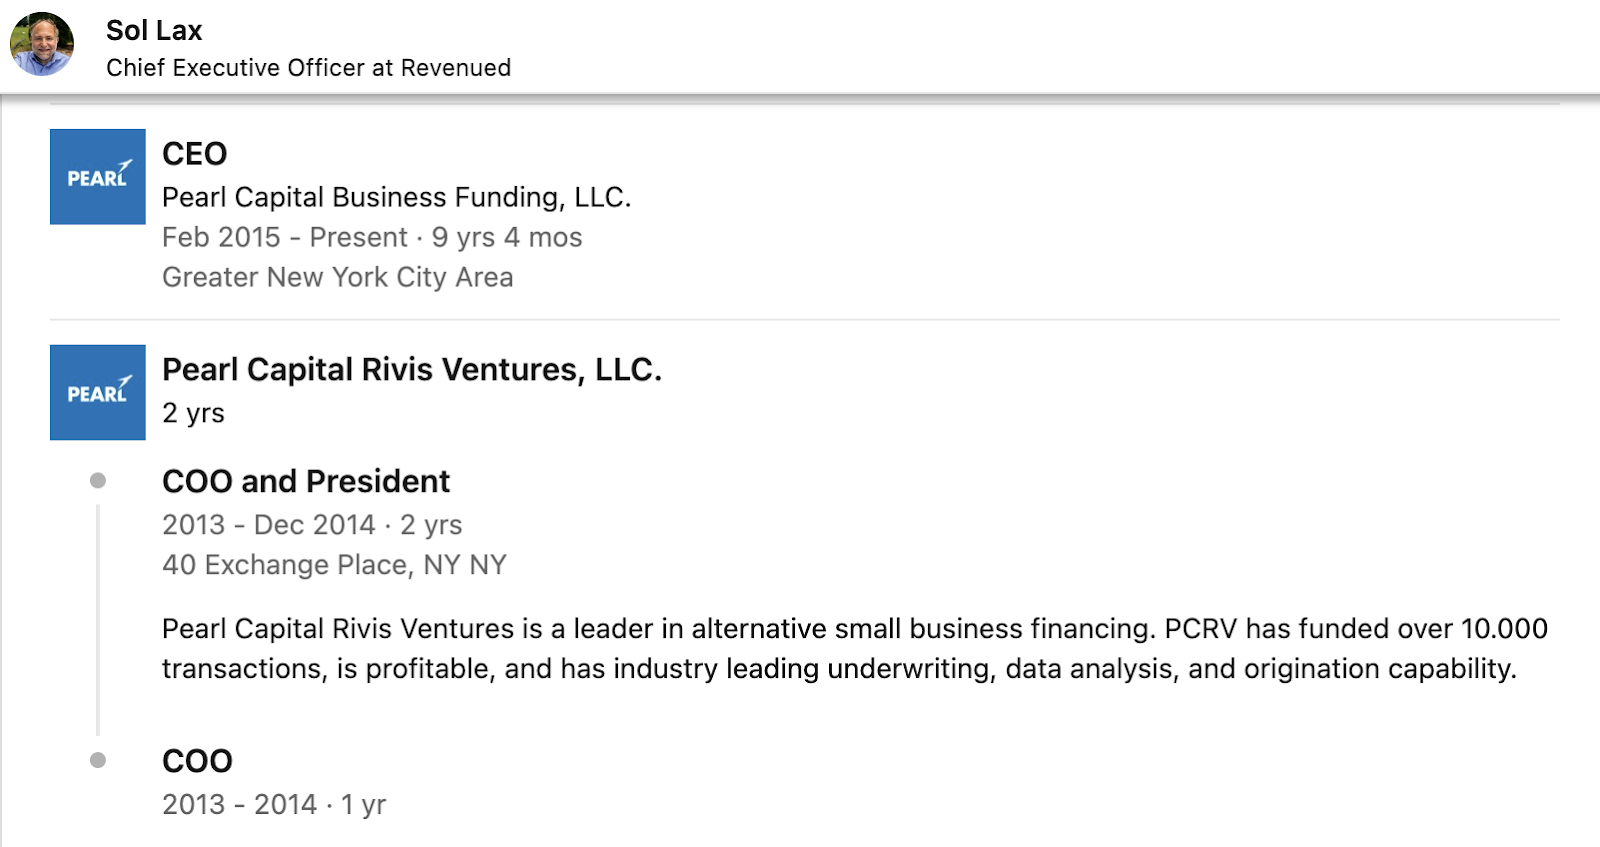
Now, what’s interesting is that, according to his LinkedIn profile, Sol became the CEO at Pearl Capital in 2015, where he moved up from COO—This shows that the two entities are very connected.
Business revenued credit card

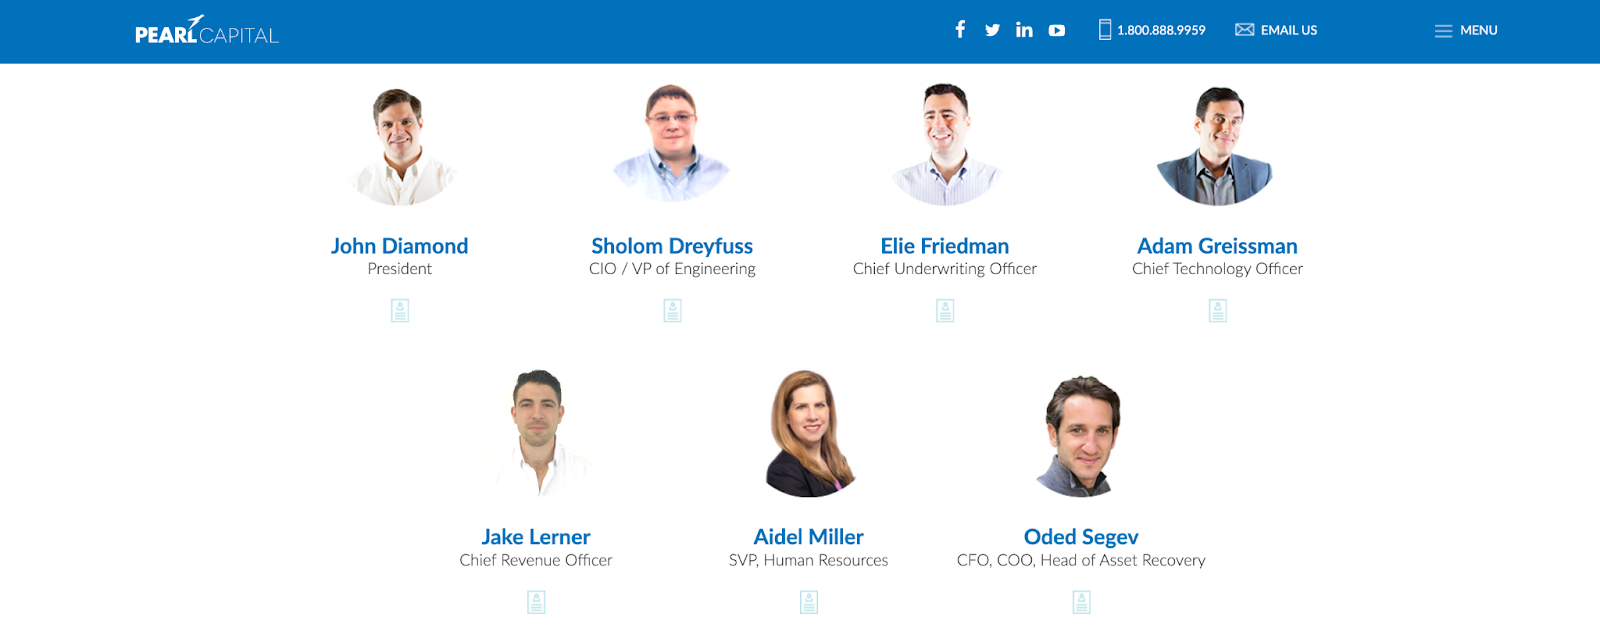
In fact, Revenued and Pearl Capital share most of the same company leadership. 
Revenued business card reviews

Technically, they are two different entities, so let’s not dwell too long on that subject. For 6 bucks or so, we could pull more info about the companies from Secretary of State records or Open Corporates. But, I think we have enough info to dig up the dirt. 

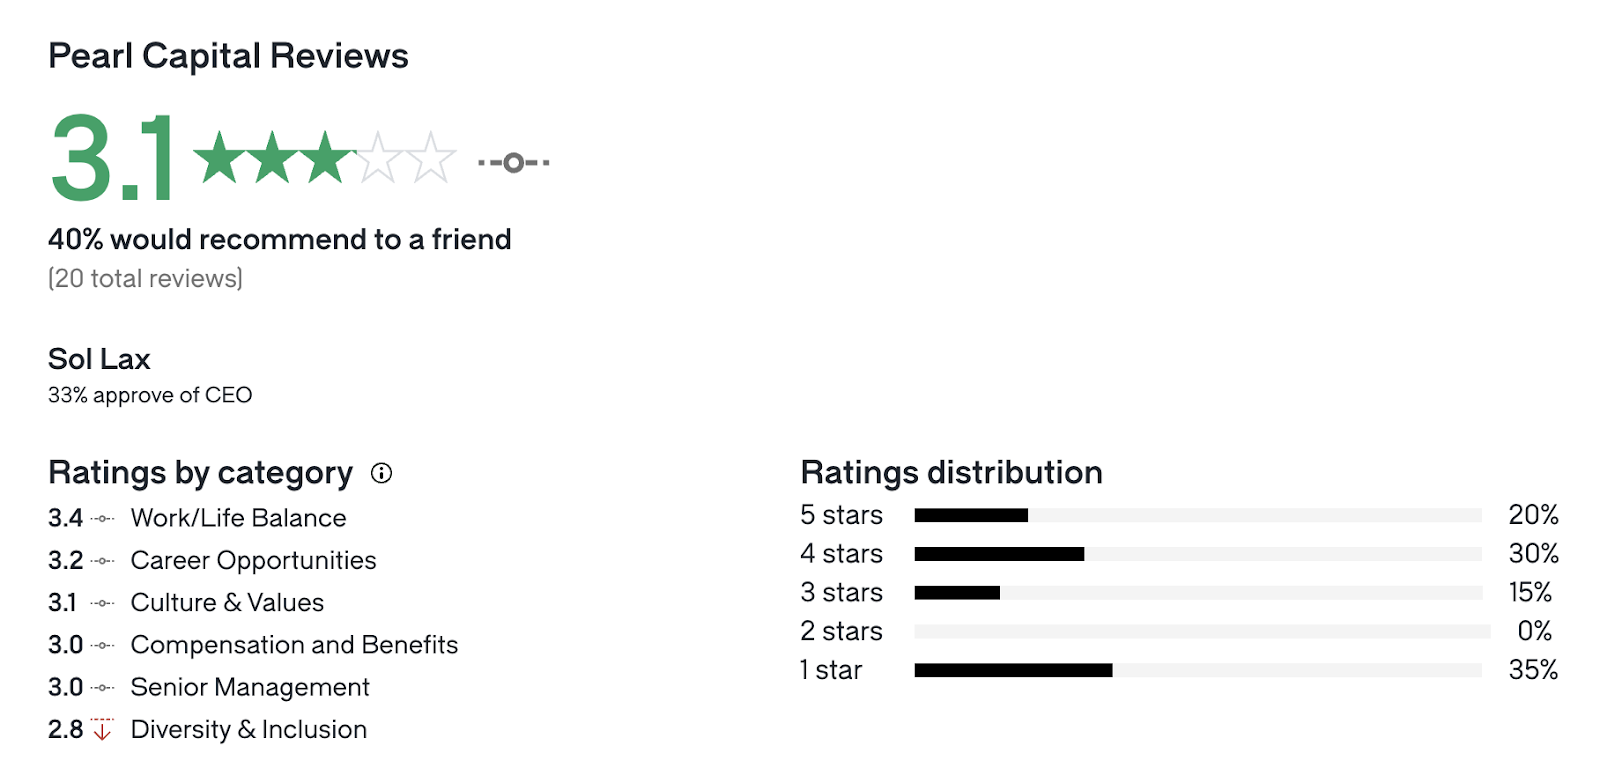
Revenued isn’t listed on Glassdoor, but Pearl Capital is. And, only about ⅓ of employee reviewers approve of Sol as the leader of the company. Staff rate diversity and inclusion efforts on the poor side and declining. What employees think of a company can imply a lot about the internal culture. 
Revenued business card reddit

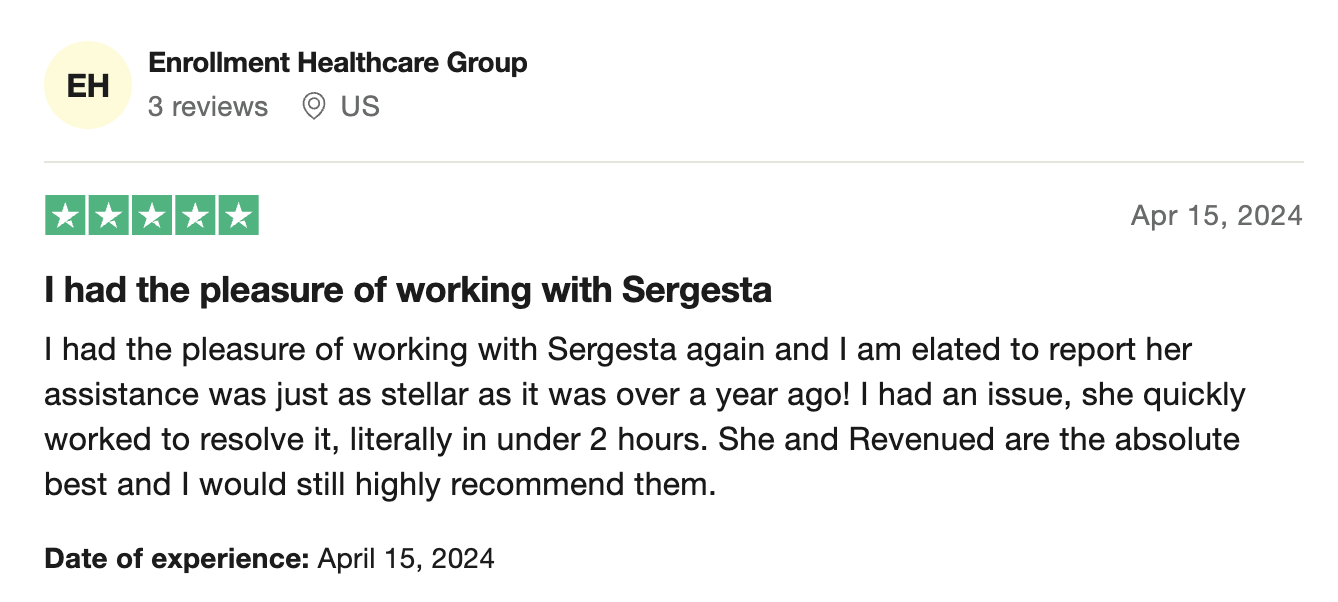
More importantly from a borrower’s perspective, existing customers can tell us more. On Trustpilot, The reviews for Revenued are overwhelmingly positive, with a TrustScore of 4.7 out of 5 and the majority of reviewers giving 5-star ratings. Customers praise the company for its easy application process, helpful customer service representatives, and quick issue resolution. 
Revenued customer service

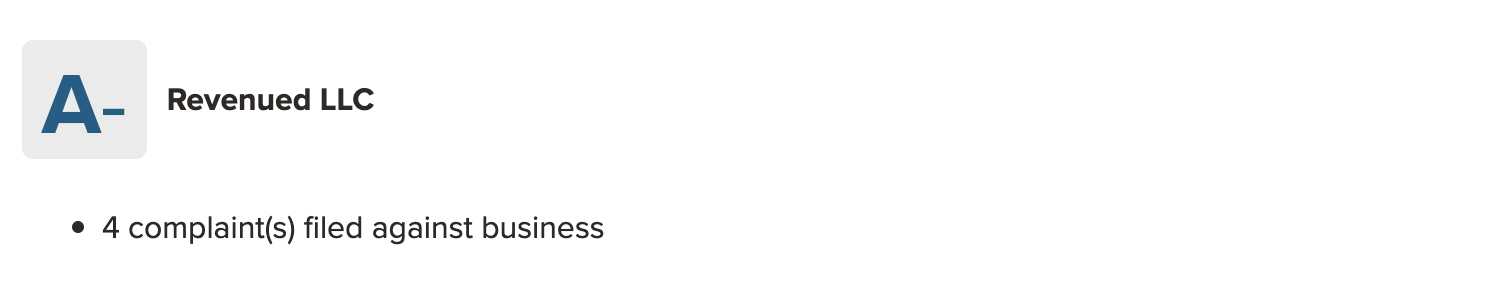
While they’re not accredited with the Better Business Bureau (BBB), they maintain an A- rating. Most if not all of their complaints must’ve been closed in a timely manner.
Revenued business card report to credit bureaus

I ran across a few open lawsuits where Revenued LLC was a party—they appeared to be the company filing breach of contract against business borrowers. It’s worth noting that they do collect on debts owed to them, which is completely understandable. 

In all, despite some internal concerns and a few disputes, Revenued LLC garners high customer satisfaction ratings for its efficient services, suggesting that it effectively meets the needs of its clientele.

You might also like: This is the Truth About LenCred’s Small Business Financing 

How Does a Revenued Business Card Work? 

From the card itself to the Flex Line and more, A Revenued business card is a simple, but powerful offer. Let’s take a look at the features and benefits of a Revenued business card. 

1. Flexible Line of Credit
Revenued business card limit

The Revenued business card offers access to a flex line of credit that adapts to your business’s revenue fluctuations. This feature allows you to borrow funds as needed, providing financial flexibility to cover unexpected expenses or seize growth opportunities. 

Unlike traditional loans with fixed repayment terms, the line of credit adjusts based on your business’s performance, ensuring that you have access to the capital you need when you need it most.

Moreover, the factor rate remains constant throughout the repayment period and usually falls within the range of 1.1 to 1.5.

You might also like: How to Get Approved for Amazon Net 30 Terms (“Pay by Invoice”) 

2. Control & Monitoring
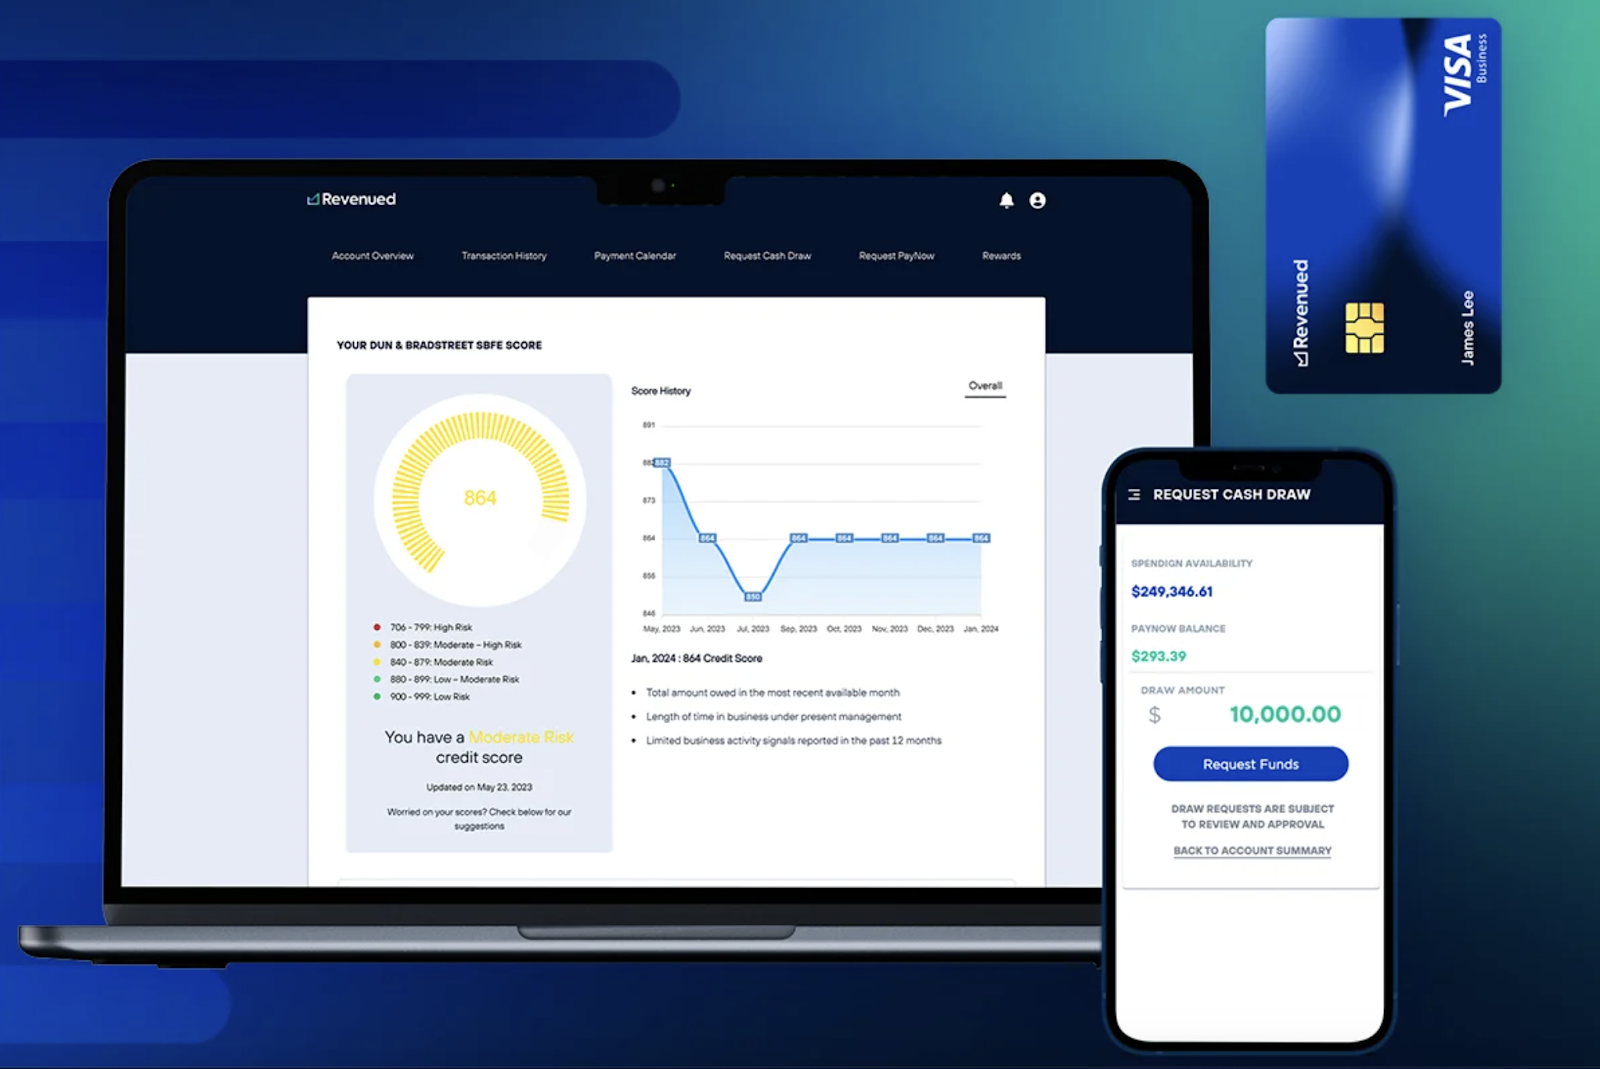
Revenued business credit card

Managing your spending and monitoring transactions is made simple with the Revenued business card. They use Marqeta (the same platform as Ramp and Divvy (Bill)) to issue cards and – in my experience – this technology is great. 

Through an intuitive online dashboard or mobile app, you can track your purchases, review transaction history, and monitor your available credit in real-time—This visibility and control level can empower you to make informed financial decisions, identify trends in your spending patterns, and proactively manage your cash flow.

Moreover, authorized users are allowed, which could be convenient or needed for some borrowers. 

You might also like: Can Tradeline Supply Reviews Be Trusted? The Full Picture 

3. Super Quick Funding
Revenued business card visa

One of the key advantages of the Revenued Business Card is its quick and streamlined funding process. When you apply for the card online, you can receive a funding decision in as little as an hour. 

Once approved, you’ll gain access to your funds within 24 hours, allowing you to address pressing business needs promptly—This rapid funding turnaround time ensures that you can seize opportunities for growth and respond to unexpected challenges without delay, which can help you keep your business operations running smoothly.

You might also like: Is Biz2Credit Legit? A Complete Review 

4. Dedicated Support
Revenued business card customer service number

As a Revenued business card holder, you’ll have access to dedicated support from a team of experienced professionals. From the moment you apply for the card, you’ll be assigned a dedicated Account Manager who will guide you through the application process and provide ongoing assistance with managing your account. 

However, live chat support is limited to certain hours and days of the week. 

You might also like: 41 Companies That Help Build Business Credit [Beyond Net 30 Vendors] 

Frequently Asked Questions

Does Revenued do a hard pull?

Revenued typically conducts a soft credit pull during the application process, which doesn’t impact your credit score. However, in some cases, they may perform a hard credit pull, which can affect your credit score.

Is there an annual fee for the Revenued business card?

As of January 2024, the Revenued Business Card is fee-free. It doesn’t charge an annual fee, monthly fee, application fee, or card replacement fee.

What is the minimum credit score for Revenued?

Revenued considers various factors beyond just your credit score when evaluating applications. While there isn’t a specified minimum credit score requirement, having a higher credit score may increase your chances of approval and potentially result in better terms.

Who does the Revenued business card report to?

The Revenued business card typically reports to the major credit bureaus, such as Experian Business, Equifax Business, and Dun & Bradstreet (D&B). This means that on-time payments can help you build business credit.

Conclusion: Is the Revenued Business Card Legit? 

I almost never recommend MCA funding unless there is no other choice because they are typically too expensive. While MCAs may not always be the preferred option for financing, the Revenued Business Card stands out for its potential to serve dual purposes. 

Not only does it offer a pathway to access working capital quickly, but it also presents an opportunity to build and strengthen your business credit profile. And, the potential for 3% cashback on MCA spending adds another layer of benefit, making it a compelling choice for businesses seeking flexible financing solutions while aiming to improve their creditworthiness.

Do you want to learn how to obtain up to $100K in business credit in as few as 30 days? Join Business Credit Workshop today!
3 Best Business Credit Cards for a New LLC +More Resources

By Joe

Business Credit Cards for New LLC

So, you’ve started a new LLC, and you’re interested in getting business credit cards. But, since your business is new, you haven’t established business credit yet. So, what are the most promising cards for you to apply for? 

Here, I’ll tell you what cards you might qualify for (along with their requirements), and explain exactly what I would do in your position. As a new business, you don’t automatically have business credit, so you may want to establish it now. 

Recommended: Download our Free Business Credit Checklist

Here’s what’s in store: 

  • What Are Business Credit Cards?
    • Can a Newly-Formed LLC Get a Credit Card?
  • Best Business Credit Cards for New LLCs
    • 1. Chase Ink Business Preferred
    • 2. Bank of America Executive Explorer
    • 3. Marriott Bonvoy Business
  • Corporate Cards to Consider
    • 1. Bill Spend & Expense (Formerly Divvy)
    • 2. PEX Expense
  • Best Loans for New Businesses
    • 1. Credibly
    • 2. LenCred
  • Frequently Asked Questions
  • Final Thoughts

Now, let’s roll!

What Are Business Credit Cards? 

Before we look at the cards you might qualify for, let’s make sure you’re clear on what you want. More often than not, business owners get other spending cards confused with business credit.  

Business credit cards are revolving lines of credit that can be used for business spending. Only a percentage of the total amount spent is required to be paid each billing cycle. Business credit cards accrue debt on any balance left unpaid. 

Meanwhile, corporate cards are either prepaid or must be paid in full at the end of each billing cycle. Corporate cards typically supplement robust business expense management software and tools. 

So, if you need funding, look at the credit cards below. And, If you need expense management, consider the recommended corporate cards. 

Recommended: Corporate vs Business Credit Card: What’s the Difference? 

Can a Newly-Formed LLC Get a Credit Card? 

So, how soon can you apply for a business credit card and do brand new LLCs get business credit? 

Getting a business credit card for a brand new LLC depends on factors like the business’s creditworthiness and the personal credit history of the owners. Typically, credit card issuers have a waiting period before a new business can apply, often a few months to a year (but this isn’t always the case). 

As a new LLC, it’s important to establish a clear separation between business and personal finances by: 

  • Obtaining an EIN
  • Opening a business bank account
  • Maintaining distinct records

The likelihood of approval is higher if the owners have a good personal credit score. As the business operates and builds a positive credit history, it becomes easier to qualify for business credit cards. Check with specific credit card issuers for their policies and requirements.

You might also like: Here’s How to [Actually] Get Business Credit With Just an EIN +More Options 

Best Business Credit Cards for New LLCs

Here, I’ll lay out my favorite business credit cards for new LLCs. You’ll see a summary of each offer (why I like it) and how long your business must be in operation before you apply. 

If you can’t get a business credit card yet, and you’re in need of immediate funding, scroll down to the loans section. Or, join Business Credit Workshop to learn how to get up to $100K in business credit in as few as 30 days. 

1. Chase Ink Business Preferred

credit cards for new businesses with no credit history

The Chase Ink Business Preferred card stands out as one of the top small business credit cards, thanks in part to its impressive sign-up bonus. Although it doesn’t offer a 0% APR and comes with an annual fee, there’s significant potential for savings and rewards. If you believe your business meets the qualifications, I recommend this one.

To qualify for the Chase Ink Business Preferred credit card, you don’t need a specific annual income or business history, but your revenue should cover the minimum monthly payment. 

Other requirements include: 

  • A FICO score of 670 or higher 
  • A minimum credit limit of $5,000

Chase evaluates your application using your personal credit score, with a recommended FICO score of 670 or higher. Keep in mind that while a good credit score is important, it doesn’t guarantee approval or denial. Whether you’re an incorporated business (LLC, corporation, partnership, non-profit, etc.) or a sole proprietor, you’re eligible to apply for the Chase Ink Business Preferred credit card.

Recommended: Chase Ink Business Preferred Credit Card: A Deep Dive Analysis 

2. Bank of America Executive Explorer

Startup business credit cards for new llc

Next, consider looking into the Bank of America Executive Explorer card. Despite its $375 annual fee, the card’s perks more than justify the cost. For instance, you receive a $600 Lounge Access credit annually and a $100 Airport Fast Track credit every four years. Moreover, you gain access to the Benefits on Us and Dinova Rewards programs. 

While a new LLC could be approved, it’s important to note that this isn’t a revolving credit line; rather, it functions as a “corporate credit card” that must be paid in full. To qualify, you must be an executive or owner of your company, and while there’s no minimum business history requirement, having an excellent credit score is crucial. 

Owners with FICO scores of 740 or higher stand the best chance of getting approved for Bank of America business credit cards.

Recommended: What is the Best Bank of America Business Credit Card for Your Needs? 

3. Marriott Bonvoy Business

Best business credit cards for new llc

I believe Marriott boasts one of the top hotel rewards card programs. The appealing part is that while you travel for work, the Marriott Bonvoy Business credit card helps you build business credit. If you meet the criteria, applying for and using this card is a smart move. 

Keep in mind that the Marriott Bonvoy Business Credit Card is exclusive to business owners and authorized representatives with a credit score of 700 or higher. 

Approval considerations also include factors like: 

  • Annual income 
  • Existing debts

Start earning travel rewards on your next hotel stay by applying now.

Recommended: Marriott Bonvoy Business Credit Card Review & Comparison 

Corporate Cards to Consider

If you’re looking for a spend card mainly to help with expense management, and you’ve got some revenue to back your account, a corporate card might be a better choice at this point – especially if your LLC is brand new, and your credit hasn’t been established. 

Now, my favorite thing about modern corporate cards is that many of them offer cash back on spending (some more than others). So, with these cards, you have a chance to earn on transactions that you or your employees make. Cool, right? 

Here are the two cards I would recommend…I’ll explain why.  

Recommended: 7 Best Cash Back Corporate Credit Cards to Explore in 2024 

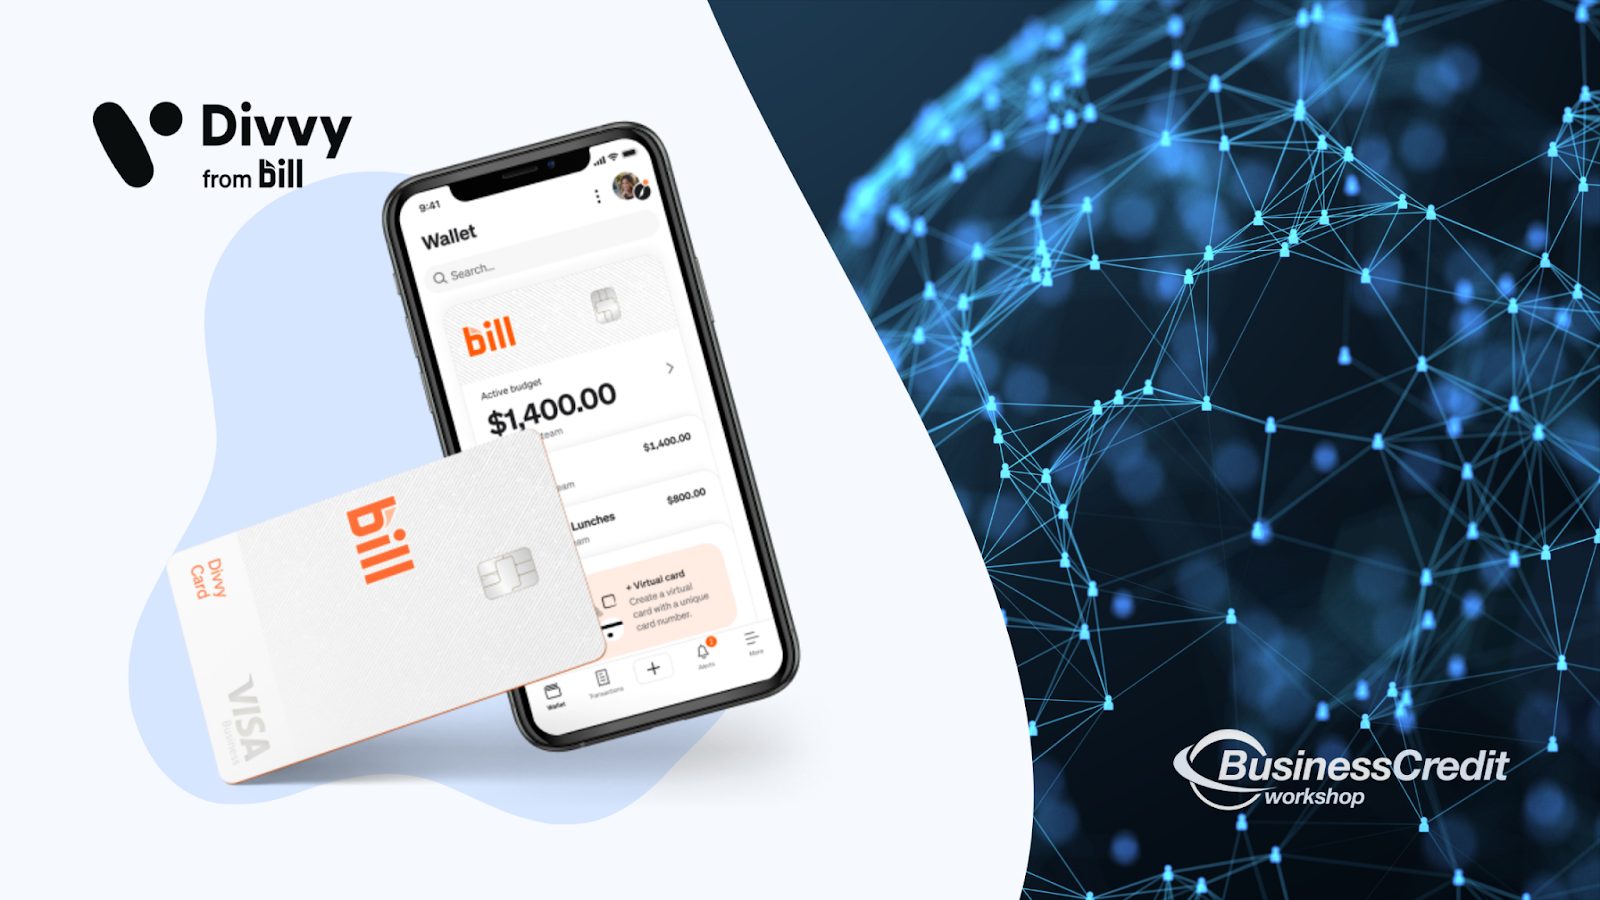
1. Bill Spend & Expense (Formerly Divvy)

business credit cards for new llc without personal guarantee

Bill Spend & Expense, formerly known as Divvy, comes with its own set of advantages and disadvantages. If you’re considering whether to take advantage of this offer, reflect on the following questions:

  • Is your monthly business spending more than $5K?
  • Does your business have multiple staff members with spending privileges?
  • Can you pay your expenses in full each month?

If you answered “yes” to these questions, the Bill Spend & Expense card could be an excellent fit for you. Now, to meet eligibility requirements, a business owner must have a minimum personal credit score of 580, and having a score of 640 or higher increases the chances of approval. Additionally, a higher annual revenue enhances the likelihood of approval.

I personally highly recommend checking it out, specifically for the tiered cashback rewards. Sign up on the Bill.com website to find out the credit line you may qualify for.

Recommended: In-Depth Divvy (BILL) Credit Card Review: Read This Before You Apply 

2. PEX Expense

startup business credit cards ein only

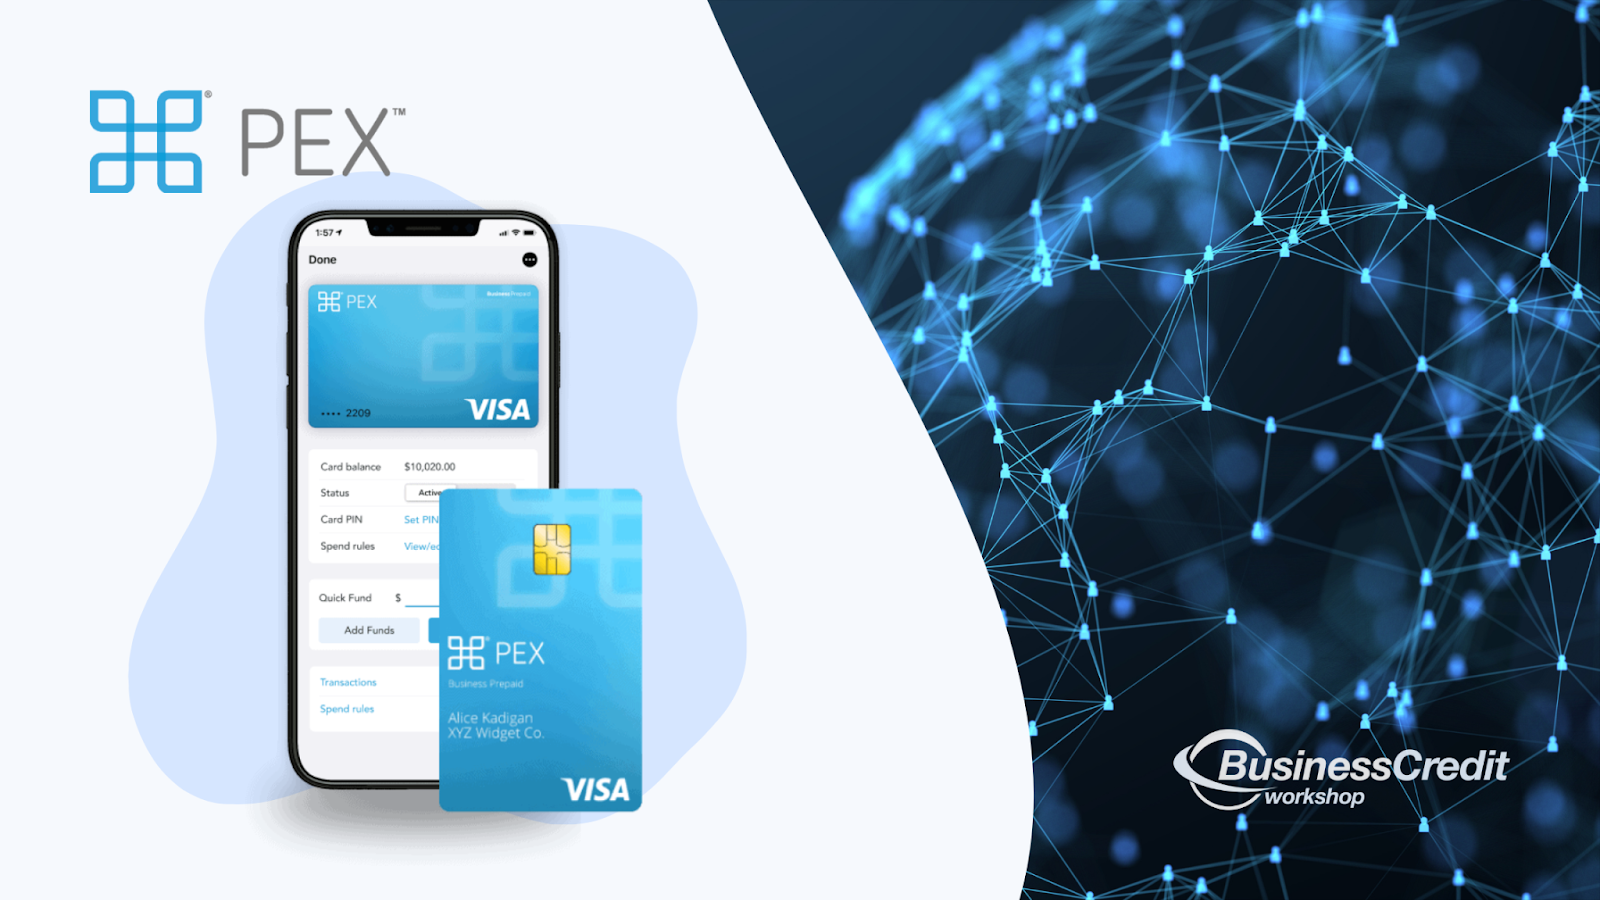
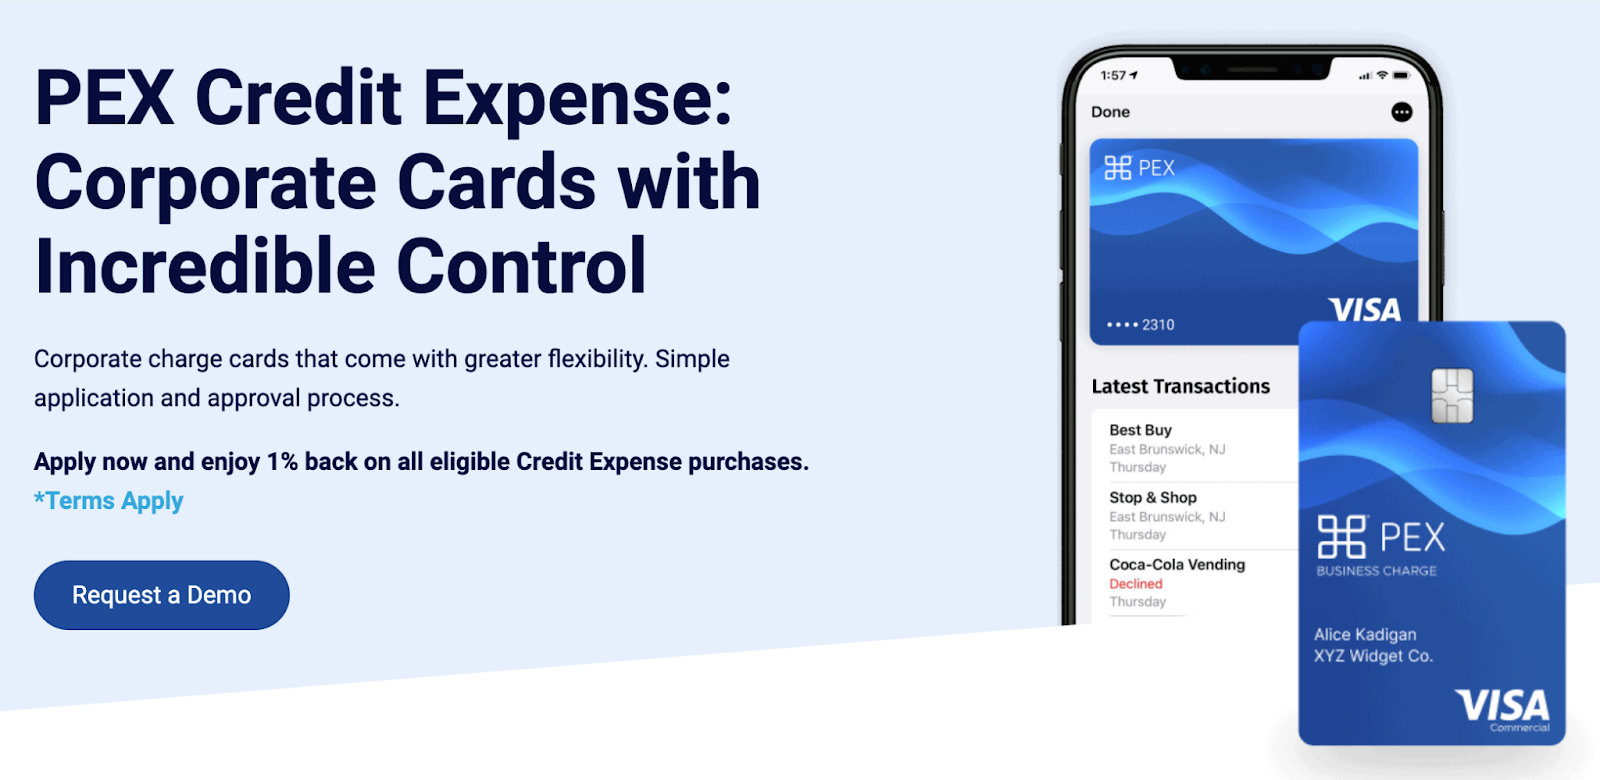
PEX is another solid corporate card with some cool features, making it a good pick for businesses and nonprofits looking to manage expenses smoothly. It’s got prepaid and dynamic credit cards, throws in 1% cash back, and has a handy app that fits different industry needs.

The user experience is made even better with seamless integrations, virtual/physical cards, and customizable controls, backed by PEX’s positive company vibe.

While PEX is a great choice, if you’re running a startup or an e-commerce gig, you might want to check out alternatives like Brex, Bill Expense, or Shopify Credit that could be more spot-on for your needs. Always a good move to weigh your priorities and compare a few options when it comes to any financial stuff.

Oh, and PEX cards are designed for businesses and organizations, and the cool part is you can get them without worrying about minimum funding requirements—they can even be issued inactive. Nice, right?

Recommended: The PEX Card: Is it the Best Corporate Card for Your Business? 

Best Loans for New Businesses

Now, if you’re looking for the funding aspect of a credit card, but you haven’t established business credit, you still have options. While your repayment terms aren’t ideal on most of the options available to you right now, you can use one of these offers in a pinch. 

Note: I don’t typically recommend factoring-type financing or loan brokers. The problem is that the rates are typically very high. Still, I know that sometimes you gotta do what you gotta do to pay for emergencies to seize an opportunity to grow your business. I have thoroughly reviewed the following loans, and I’ll tell you the truth about them. 

Recommended: How to Get an SBA Business Loan 

1. Credibly

Business credit cards for new llc ein only

Credibly’s rates, covering everything from interest and factor rates to origination fees and admin fees for merchant cash advances, lean towards the higher side. If your business is on the newer side, your credit isn’t stellar, and you’re pulling in at least $15,000 per month, Credibly might be a viable option for securing the funding needed to keep your business going or expand. 

It’s a relatively young company, but it’s legit, with enough satisfied customers indicating it’s doing something right. However, I won’t strongly recommend their loans unless your business is in a tight spot, and if it is, be cautious about the personal guaranty—it can be risky. 

Before committing to Credibly or any other company, it’s a good idea to shop around for quotes. You might be able to find comparable loans with better rates, especially if your business is more established or you have a solid credit score.

Recommended: A Deep-Dive Credibly Review: Is Their Financing Right for You? 

2. LenCred

business credit cards for new llc with bad credit

If you’re in need of working capital or startup funds, and you’ve got solid credit but aren’t in a position for traditional funding options, LenCred could be the solution you’re looking for – It’s especially handy if you’re not keen on unconventional routes like crowdfunding and are okay with dealing with a 9% origination fee. 

LenCred’s financing services might just be the boost you need.

However, if you’re aiming to build up your business credit and prefer securing funding without hefty origination fees, LenCred might not be the best fit. Since they don’t use your business credit profile in the funding process, their lenders are unlikely to report to the business credit bureaus. So, it’s a trade-off to consider.

Recommended: This is the Truth About LenCred’s Small Business Financing 

Frequently Asked Questions

What is the fastest way to get business credit for an LLC? 

You first need to make sure the owner’s personal credit is in check and the business is properly established for “credit readiness.” Then, open a bank account and establish relationships at the bank. After that, make sure the business has a DUNS number, establish your first tradelines of credit, and pay your accounts at the right time. Finally, you just need to monitor your business credit before you apply for a new loan or line of credit. 

Download our free Business Credit Checklist to start building business credit. 

Can a single-member LLC build credit? 

Yes, a single-member LLC can build business credit with an EIN and a DUNS number. 

Can you get a business credit card with no revenue? 

The short answer is no. However, there are exceptions, for example, you may be able to get a business credit card with a personal guarantee if your income meets underwriting requirements. 

Do LLCs start out with good credit? 

When LLCs are initially registered, they have no business credit. In this case, credit decisions may be based on the owner’s personal credit. Businesses can build credit by establishing their business properly, setting up accounts with the right tradelines, and paying accounts on-time as agreed. 

What happens if an LLC defaults on a credit card? 

If an LLC defaults on a credit card, the creditor can go after business assets, send debts to collections, and sue to liquidate the company. If the credit card has a personal guarantee, the creditor may hold the business owner personally liable to repay the debt. 

Final Thoughts

Now that you’ve explored the best business credit cards for your new LLC, consider all options like the Chase Ink Business Preferred and PEX Expense to find what suits your business needs. Distinguish between business credit and corporate cards, with corporate options like Bill Spend & Expense offering a smooth ride for your expense management.

For loans, check out Credibly and LenCred, weighing perks and alternatives. 

Are you ready to learn how to get up to $100K in business credit in as few as 30 days? Join Business Credit Workshop today!

The PEX Card: Is it the Best Corporate Card for Your Business? 

By Joe

PEX card review

The PEX Card is one of the most popular non-big-bank corporate cards on the market today. While the offer is legit, it’s not your only option. Before you sign up for any financial service, you should know exactly what you’re getting into. 

Here, I’ll break down the PEX offer in full (the good, the bad, and the ugly), and I’ll point you out to other options that may or may not be a better fit for your operations. 

This is what’s in store: 

  • What is a PEX Card Used For?
    • Where Can You Use a PEX Card?
    • How Much Does a PEX Account Cost?
    • PEX Company Overview
  • PEX Card Features & Benefits
    • 1. Prepaid & “Credit” Card Flexibility
    • 2. 1% Cash Back on All Purchases
    • 3. The PEX App
    • 4. Integrations & API
    • 5. Virtual & Physical Cards
    • 6. Customizable Rules & Spend Limits
    • 7. Simplified Grants Disbursement for Nonprofits
  • Frequently Asked Questions
  • Conclusion: Is PEX a Good Idea?

So, let’s break it down!

What is a PEX Card Used For? 

What is a PEX card?

PEX is a corporate expense management platform that offers a range of financial tools, including corporate charge cards (PEX Cards) with dynamic credit lines and 1% cash back – These cards are designed to help you manage: 

  • Employee spending
  • Payments to vendors
  • Fund distribution for various programs

PEX Cards provide businesses and nonprofits with a high degree of control and flexibility, which enables easy administration through automated reporting, mobile receipt capture, and real-time tracking. The platform includes features such as prepaid expense cards, virtual vendor cards for bill payments, and grants disbursement cards. 

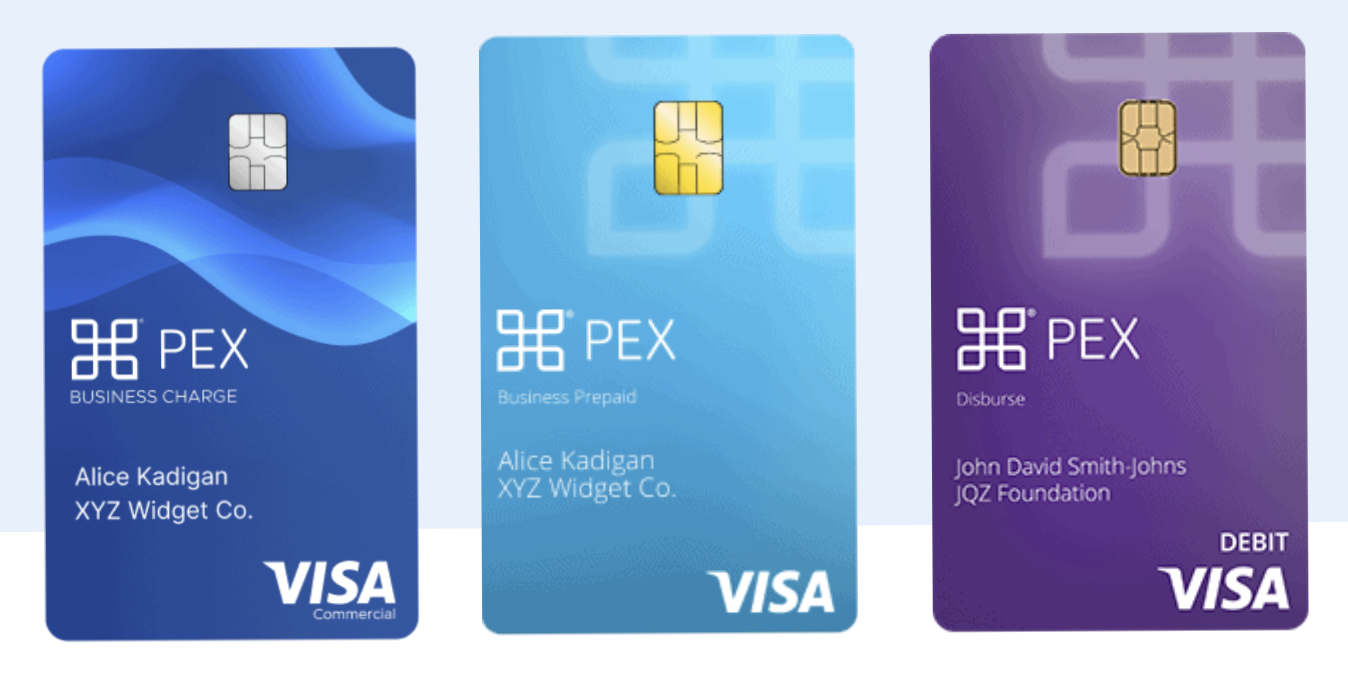
While they’re powered by Visa,® PEX “Expense” cards are not credit cards, they are prepaid, corporate cards. The platform also offers PEX “Credit” cards with dynamic limits based on the cash flow in and out of your connected business bank account, which I’ll explain more below. 

For a better understanding of the difference between the two types of spending, explore an in-depth comparison between credit cards and corporate cards. 

The PEX card also offers rewards and incentives cards for employee recognition. The PEX API allows you to customize and integrate solutions, generating cards and spending rules on the fly. 

As a brand, PEX Cards cater to a variety of industries and organizations, providing a comprehensive and adaptive financial management solution to streamline processes, eliminate paperwork, and simplify expense reports.

Recommended: 7 Best Cash Back Corporate Credit Cards to Explore This Year 

Where Can You Use a PEX Card? 

Who accepts PEX cards?

The PEX platform emphasizes the convenience and flexibility of its cards for various use cases, such as: 

  • Travel
  • Bill payments
  • Other on-the-go expenses 

The PEX Visa® Commercial Cards are designed to be accepted internationally (wherever Visa cards are recognized). So, you can use a PEX card at a wide range of merchants, both online and offline, that accept Visa® payments globally. 

Worldwide acceptance makes these cards suitable for businesses and organizations with international operations or employees who need to make purchases or payments abroad.

It’s important to check with individual suppliers or service providers during international transactions to ensure that they accept Visa cards, as specific acceptance may vary at the discretion of the merchant.

How Much Does a PEX Account Cost? 

PEX card pricing

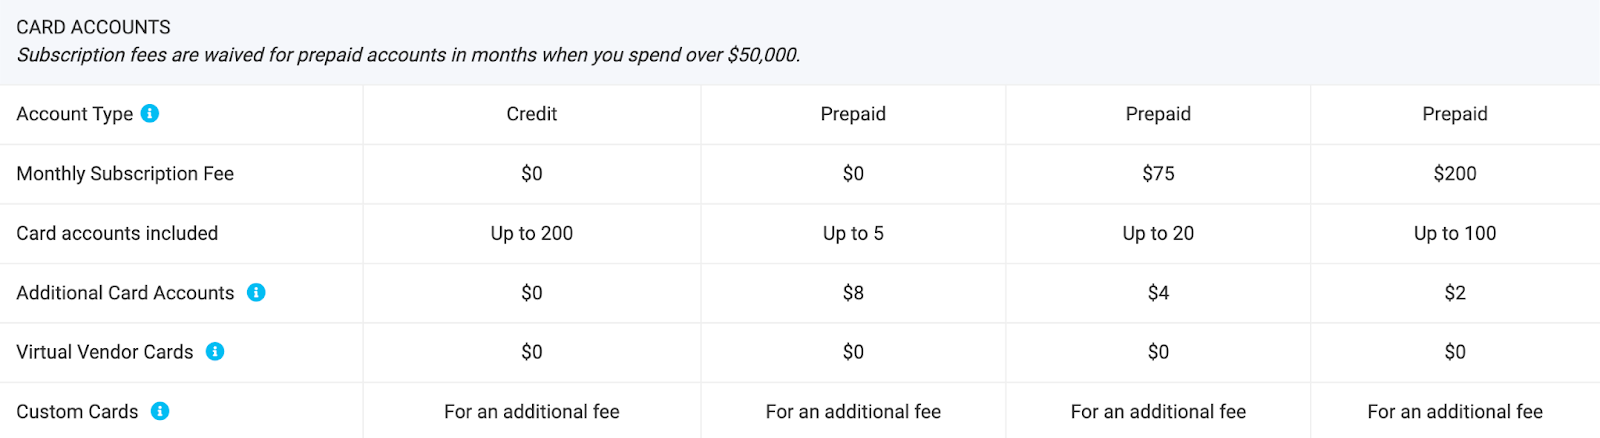
For PEX card accounts, the monthly subscription fees vary based on the account type. 

Credit accounts have a $0 monthly subscription fee, while prepaid accounts have different fees: 

  • $0 for accounts with monthly spending over $50,000
  • $75 for up to 20 card accounts
  • $200 for up to 100 card accounts. 

Additional card accounts for prepaid accounts incur extra charges, ranging from $2 to $8 per month, depending on the account type and the number of additional cards. 

Virtual Vendor Cards have no additional fee, and custom cards are available for an extra charge regardless of the account type.

PEX Company Overview

According to Crunchbase, Toffer Grant founded the New York-based financial services company, Prepaid Expense Card Solutions, Inc. (PEX), in 2007. The company does business as At the time the company was established, Grant – who is the current CEO of PEX – had been working in the prepaid card industry for 7 years, and had previous experience in entertainment and advertising. 

The company was successful enough to inspire Emburse to compete when they launched their corporate card offer in 2014; both expense management platforms and cards are still going strong today. 

PEX is a private, for-profit corporation (still owned and operated by Grant) that has received at least $4.9M in funding from at least four investors including New York Angels and Inovia Capital. 

PEX card customer service

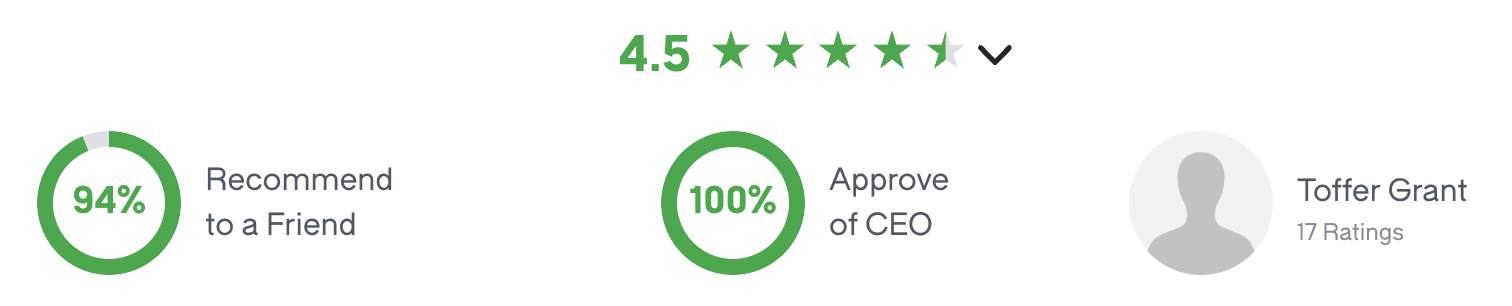
According to Glassdoor and based on 27 reviews, almost everyone who works for PEX approves of the CEO, and most of them would recommend this company to a friend – the way staff feels about a company is super telling of its general ethics, and 100% CEO approval is impressive. 

PEX card reviews

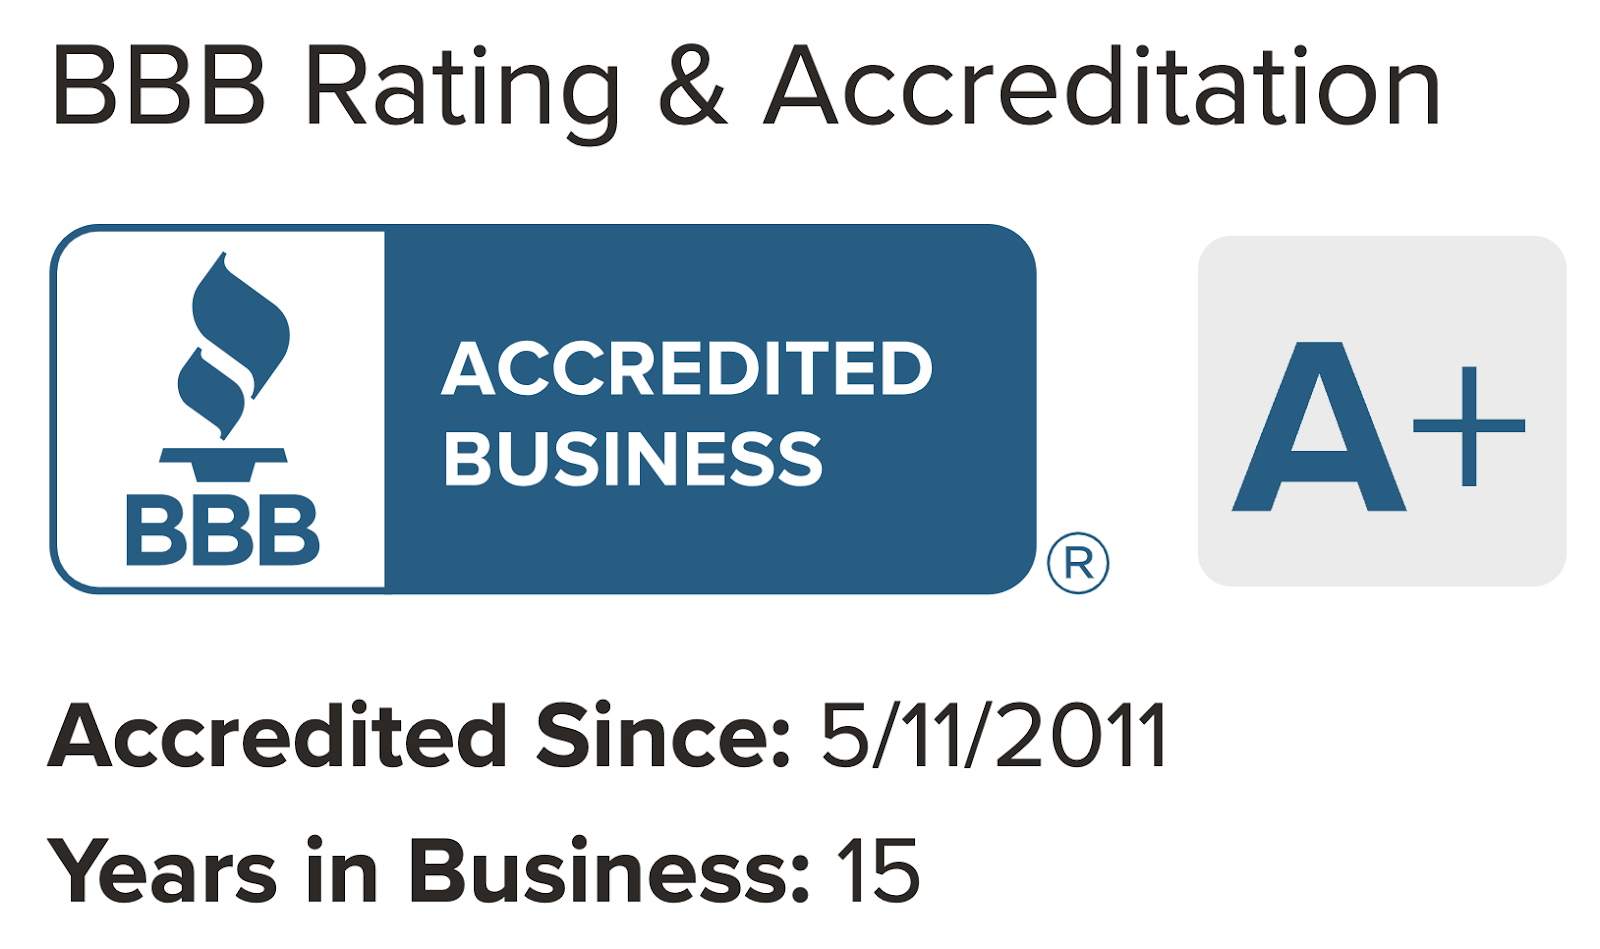
PEX is also accredited by the Better Business Bureau (BBB) with an A+ rating. The BBB lists only one complaint about the company since at least 2011 (also wildly impressive). Combined with the satisfied staff, this tells me they’re an honorable company – I’d give them my trust.    

You might also like: Meet the Emburse Card: An Inclusive Cash Back Corporate Card 

PEX Card Features & Benefits

Now, explore the functionalities of PEX Cards, the corporate expense management platform offering practical solutions. Whether you’re a small business or a larger enterprise, PEX offers a super flexible solution for streamlined and controlled expense management…Find out how, and exactly what you can expect. 

1. Prepaid & “Credit” Card Flexibility

PEX card prepaid

As you know, PEX offers business prepaid expense cards and business “credit” cards. 

The PEX Expense cards are paid in advance for business owners who want to manage employee expenses. Meanwhile, the PEX Credit cards are offered with a dynamic spending limit based on business cash flow. 

While the Credit card does provide a buy now, pay later (BNPL) offer, it is not a traditional business credit card – PEX does not check your personal or business credit, they do not report your company’s payments to business credit bureaus. 

So, you won’t get a business credit boost with Dun & Bradstreet or any other business credit bureau, but PEX will give you the chance to either prepay or pay monthly.  

Recommended: Here’s How to Check Your Business Credit Score, Step-by-Step 

2. 1% Cash Back on All Purchases

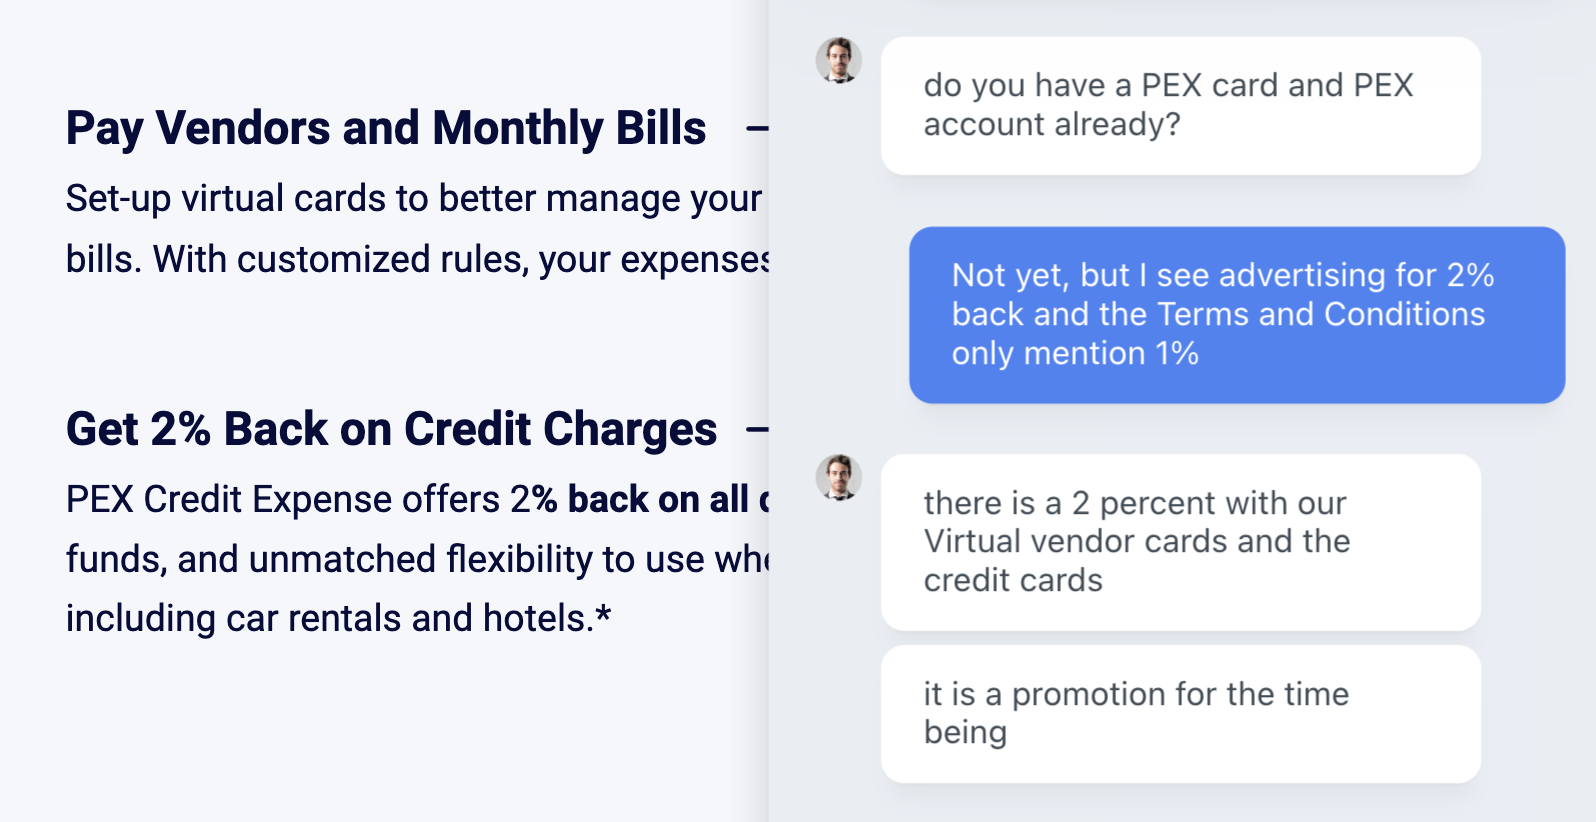
While some of PEX’s advertising claims that you can get up to 2% cash back on eligible expenses, the card’s terms and conditions don’t mention this rate – this is actually a promotion that’s happening with the virtual cards and credit cards. 

PEX prepaid card

PEX Credit Expense offers a compelling 1% cash back on all eligible purchases, providing businesses with a tangible incentive for using the platform. This cashback feature is applicable to a range of expenses, contributing to overall savings. The offer is designed to benefit businesses of all sizes, which makes it an attractive proposition for those looking to maximize the value of their corporate spending.

You might also like: Have You Heard About the Free Stripe Corporate Card Cashback Benefits? 

3. The PEX App

PEX card app

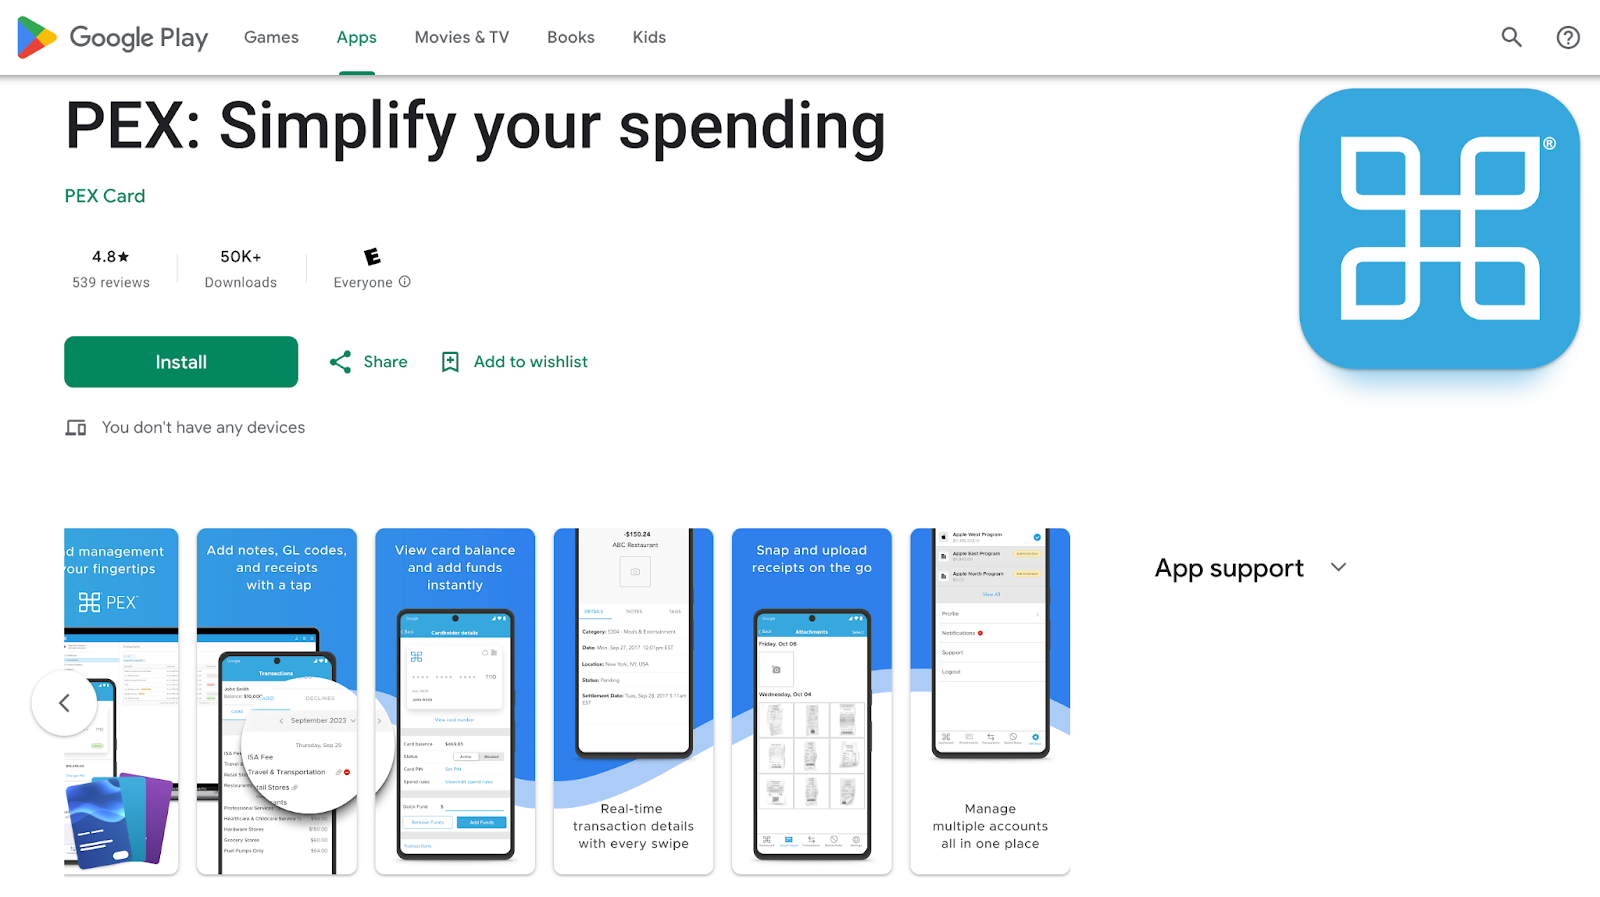
The PEX Card App is available on both GooglePlay and the iOS marketplace – it enhances the user experience by providing a convenient, efficient way to manage expenses on the go. 

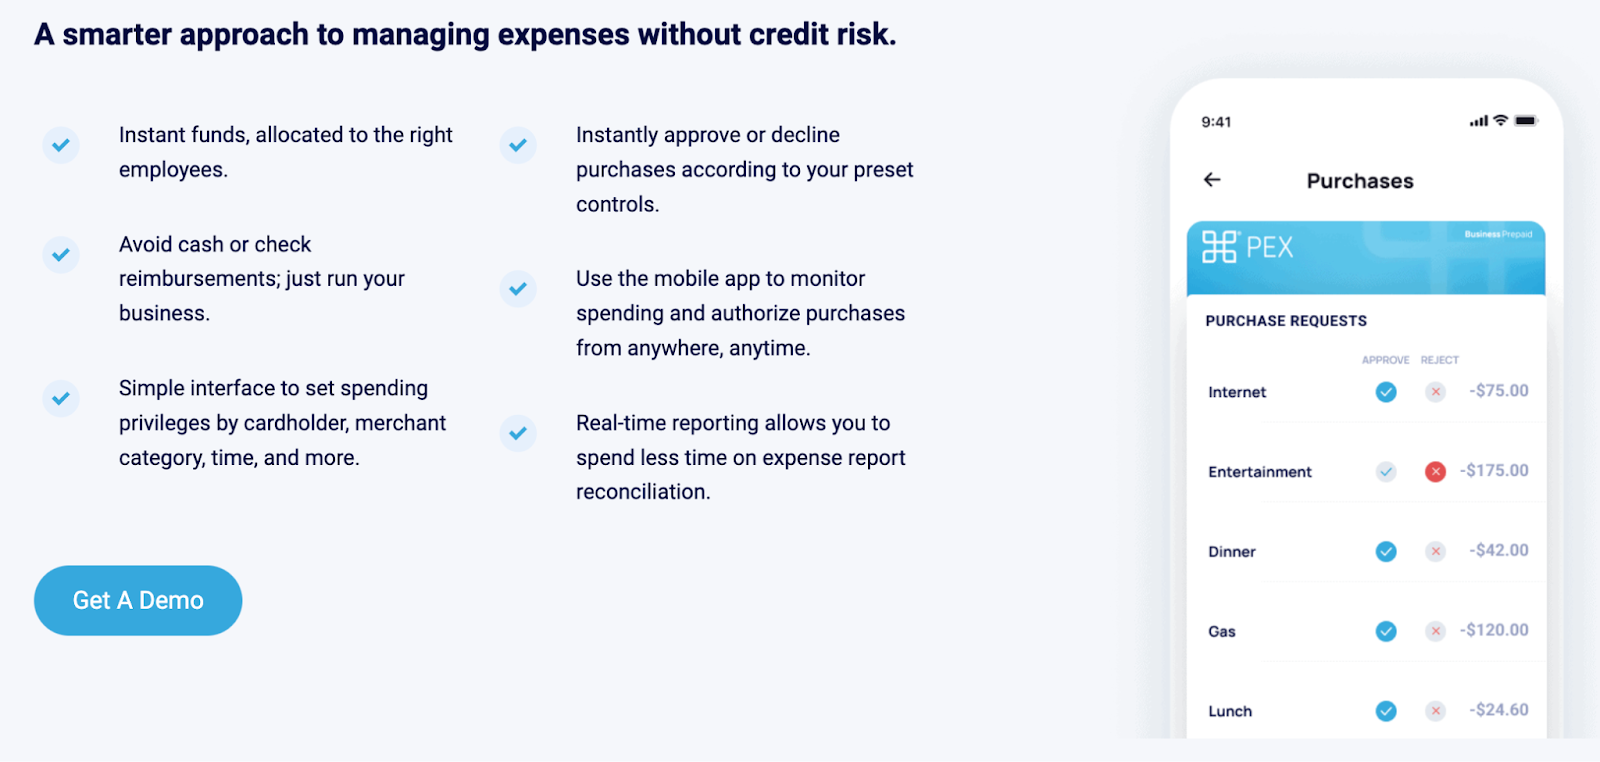
With real-time monitoring and authorization capabilities, cardholders can effortlessly submit receipts and accounting codes directly through the mobile app. This feature ensures that users have instant access to their financial data, enabling them to stay in control of their expenses anytime, anywhere. 

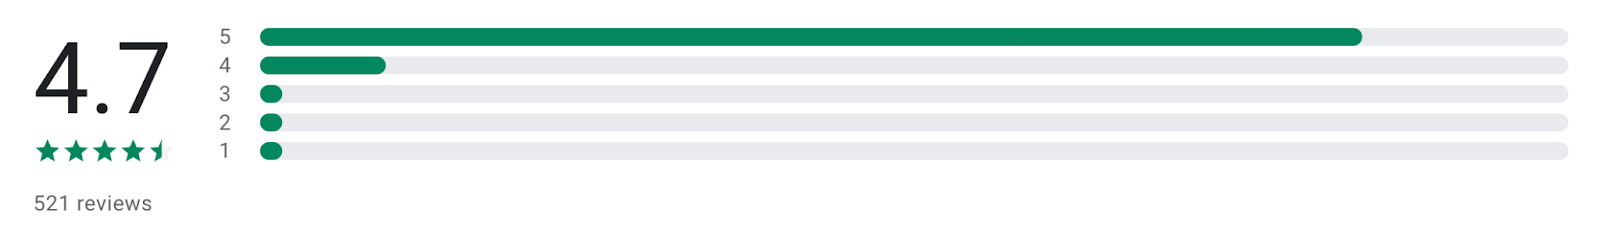
And, the app gets great ratings, with a 4.7 for both Android and Apple devices. 

PEX card login

The app’s user-friendly interface simplifies the expense management process, reducing the time and effort spent on reconciliation.

You might also like: In-Depth Divvy (BILL) Credit Card Review: Read This Before You Apply 

4. Integrations & API

PEX app integrations

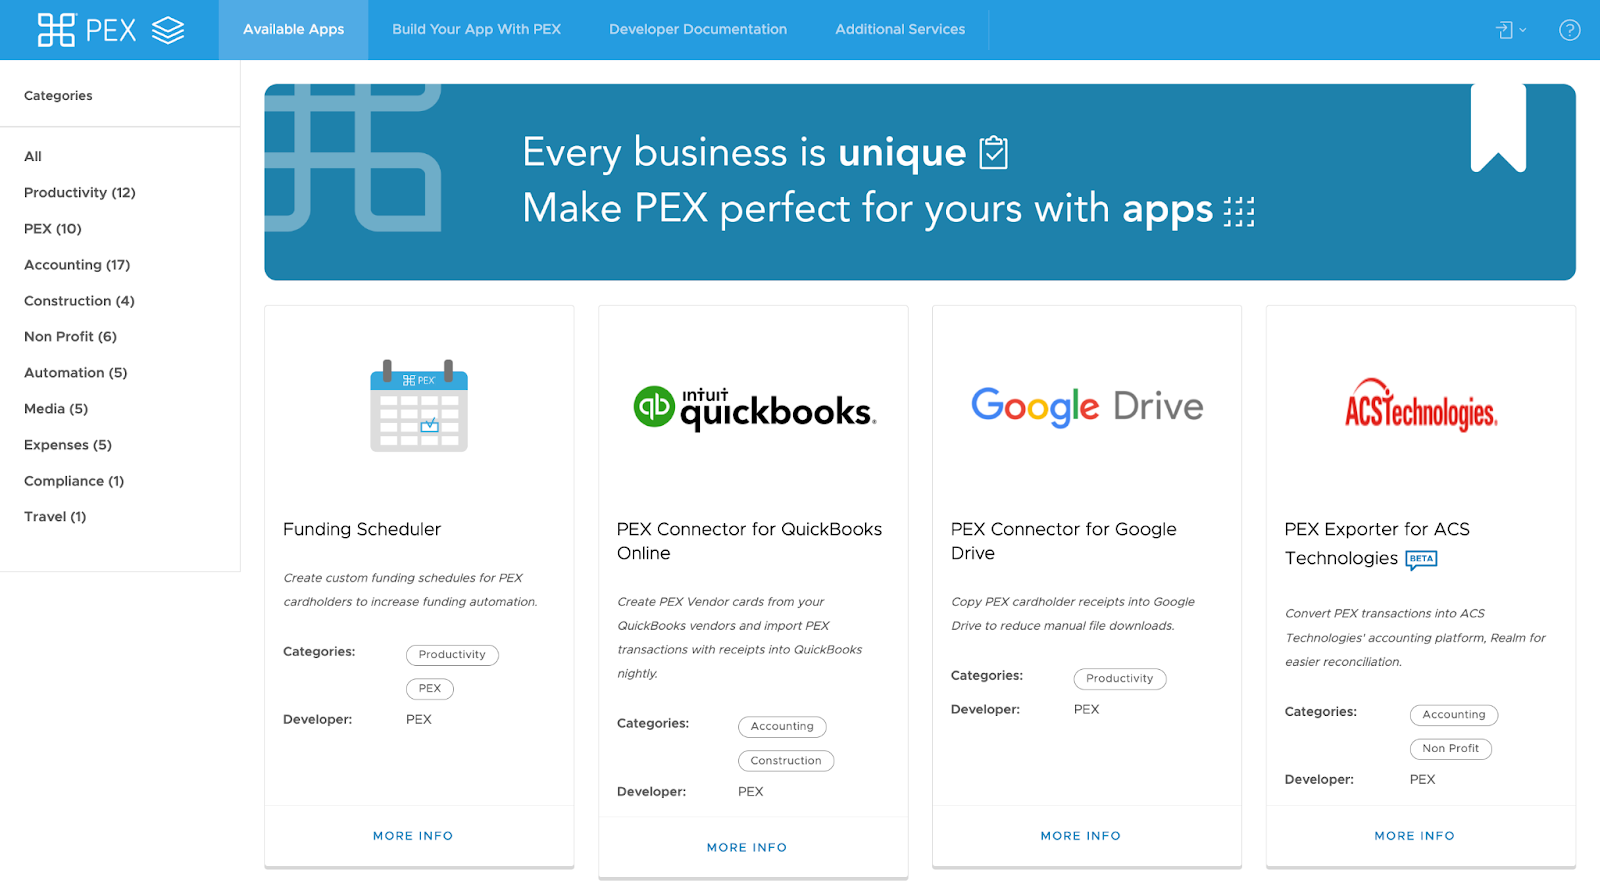
PEX’s seamless integration with accounting systems streamlines financial operations for businesses. The system integrates with over 60 popular software platforms, including Quickbooks.

By syncing transactions with existing accounting software, the PEX platform automates: 

  • Expense reporting
  • Allocations
  • Reconciliations

This integration not only saves time but also enhances accuracy by minimizing manual data entry. The deep reporting options provided by PEX ensure that businesses have comprehensive insights into their financial activities, fostering better decision-making and financial management.

And, if you don’t see your app in the PEX marketplace (for example, there aren’t a lot of payroll systems on the list), you can access the PEX application program interface (API) to make it happen.   

Recommended: Gusto Review: Let’s Really Evaluate This Famed Payroll Platform 

5. Virtual & Physical Cards

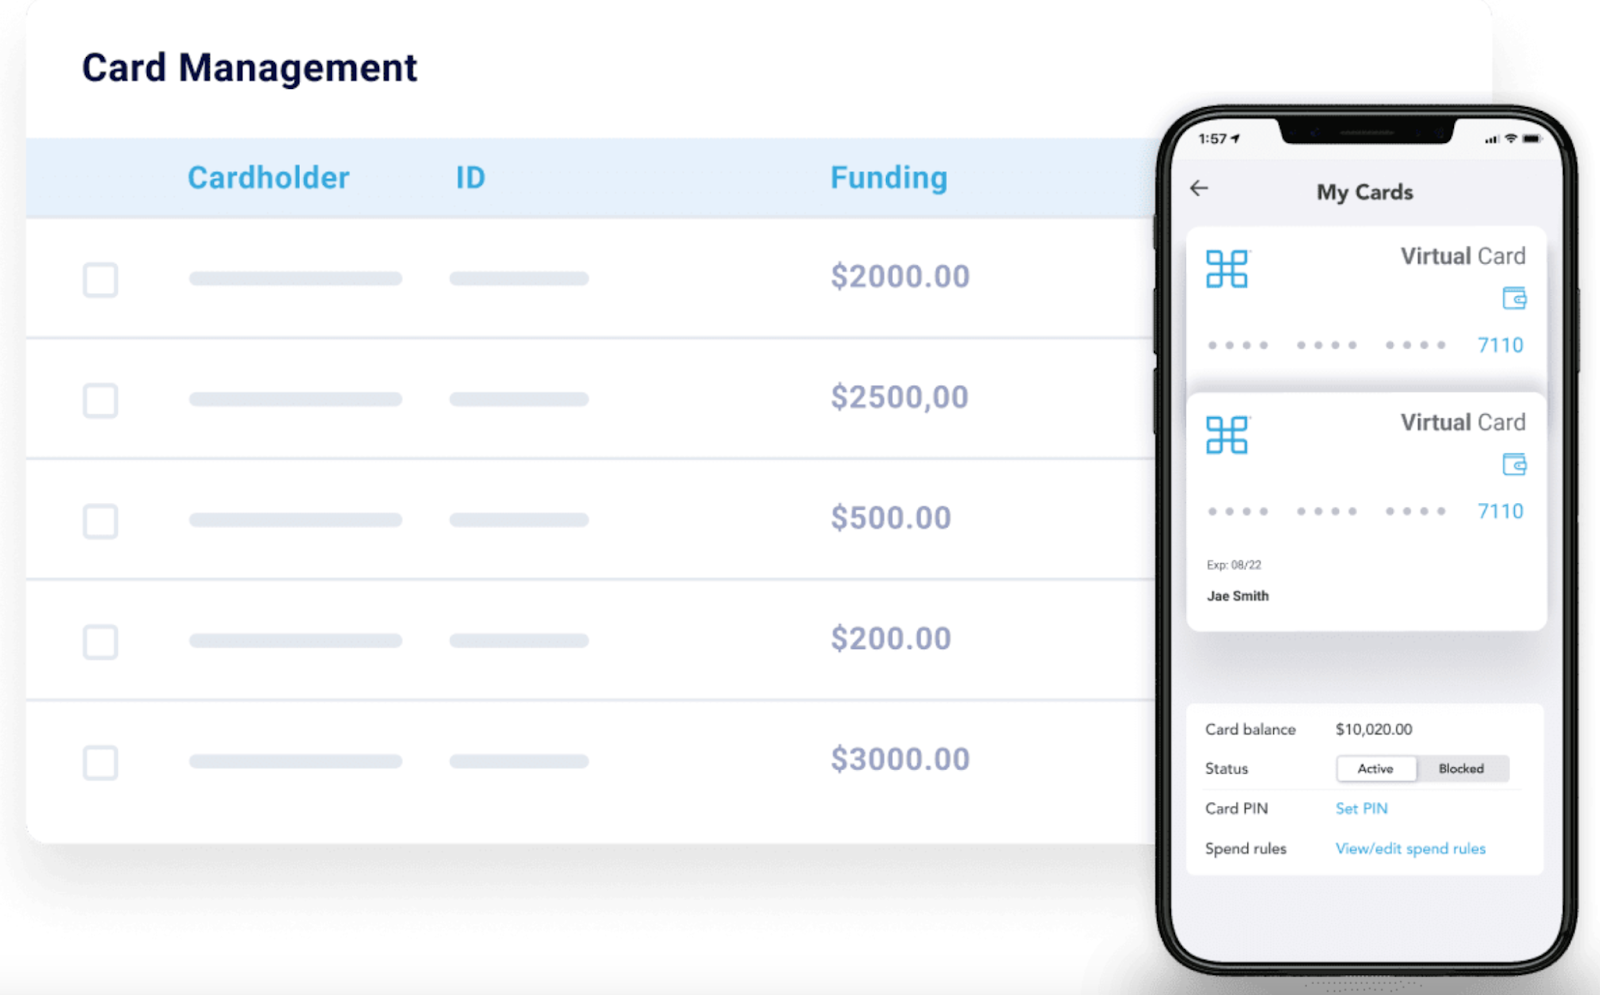
PEX card balance

PEX enables businesses to distribute both physical and virtual cards, offering flexibility in how expenses are managed. Physical cards can be given to staff and management, while virtual cards are ideal for bill payments, travel arrangements, and recurring expenses. 

This dual card option caters to diverse spending needs, providing a versatile solution for businesses. The ability to manage both types of cards seamlessly from desktop or mobile devices adds an extra layer of convenience.

You might also like: 6 Best Fintech Credit Cards to Apply for (Consumer & Business) 

6. Customizable Rules & Spend Limits

PEX card activation

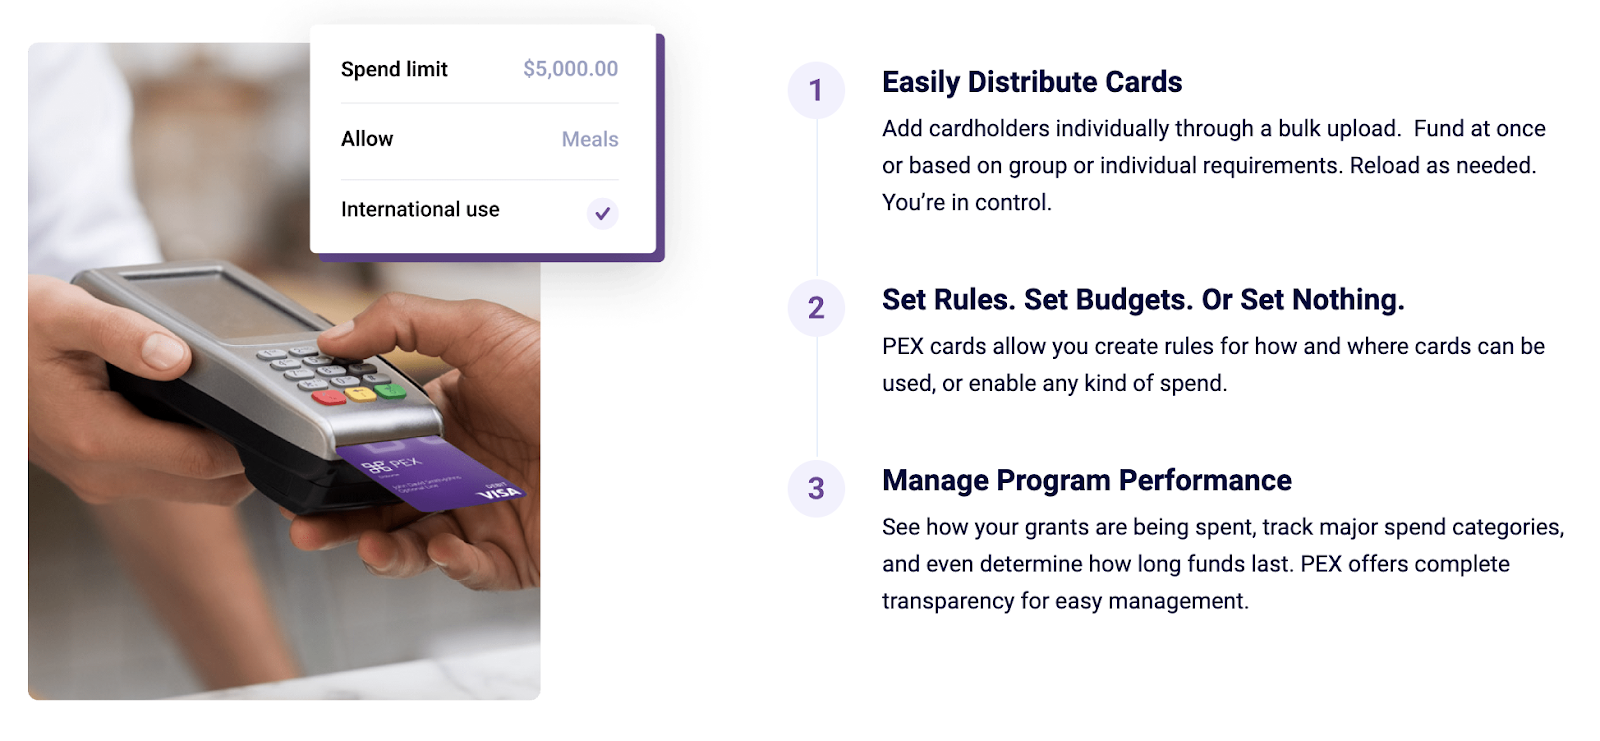
PEX allows businesses to set customizable rules and spending limits for each card or group. This feature provides granular control over how funds are utilized, ensuring that expenses align with organizational policies. 

Tailoring approved categories and spending limits allows businesses to adapt the platform to their specific needs, whether for individual employees or departments. PEX’s focus on customization empowers businesses to maintain financial discipline and allocate resources effectively.

You might also like: Should You Open a Citibank Commercial Card Account?… It Depends! 

7. Simplified Grants Disbursement for Nonprofits

PEX card grants

Moreover, PEX simplifies grant fund distribution with physical and digital Prepaid Visa® Cards. Administrators gain control through customizable rules, easy cardholder management via the mobile app, and bulk uploads for efficient card distribution. 

PEX’s transparency allows tracking of spending, major categories, and fund duration, ensuring effective grant program management.

Frequently Asked Questions

When should you not use PEX? 

If you’re looking to make personal purchases or handle transactions unrelated to your business or organization’s expenses, PEX may not be the right fit. PEX is designed for managing corporate spending and isn’t meant for personal use.

Can you use a PEX card at an ATM?

No, you can’t use a PEX card at an ATM. PEX cards are specifically designed for making purchases, payments, and managing expenses. If you need cash, it’s best to use other methods like a traditional bank debit card.

What is PEX payment? 

PEX payment refers to the financial transactions made using PEX cards. These cards are part of the PEX expense management platform, offering businesses a streamlined way to handle corporate spending, vendor payments, and other financial transactions.

How old do you have to be to use a PEX card? 

To use a PEX card, you generally need to be at least 18 years old. PEX cards are designed for businesses and organizations, and they are not typically issued for personal use by individuals who are under 18.

Conclusion: Is PEX a Good Idea? 

PEX is an excellent corporate card with robust features, making it ideal for businesses and nonprofits seeking streamlined expense management. The platform’s prepaid and dynamic credit cards, 1% cash back, and versatile app cater to various industry needs. 

Seamless integrations, virtual/physical cards, and customizable controls enhance the overall user experience. PEX’s positive company overview adds to its credibility.

While PEX is a great choice, businesses with specific needs, such as startups or e-commerce ventures, might find alternatives like Brex, Bill Expense, or Shopify Credit more tailored to their requirements. It’s always a good idea to evaluate your priorities and compare several options for any financial offer. 

Do you want to learn how to obtain up to $100K in business credit in as few as 30 days? Join Business Credit Workshop today!
Meet the Emburse Card: An Inclusive Cash Back Corporate Card 

By Joe

Emburse Card

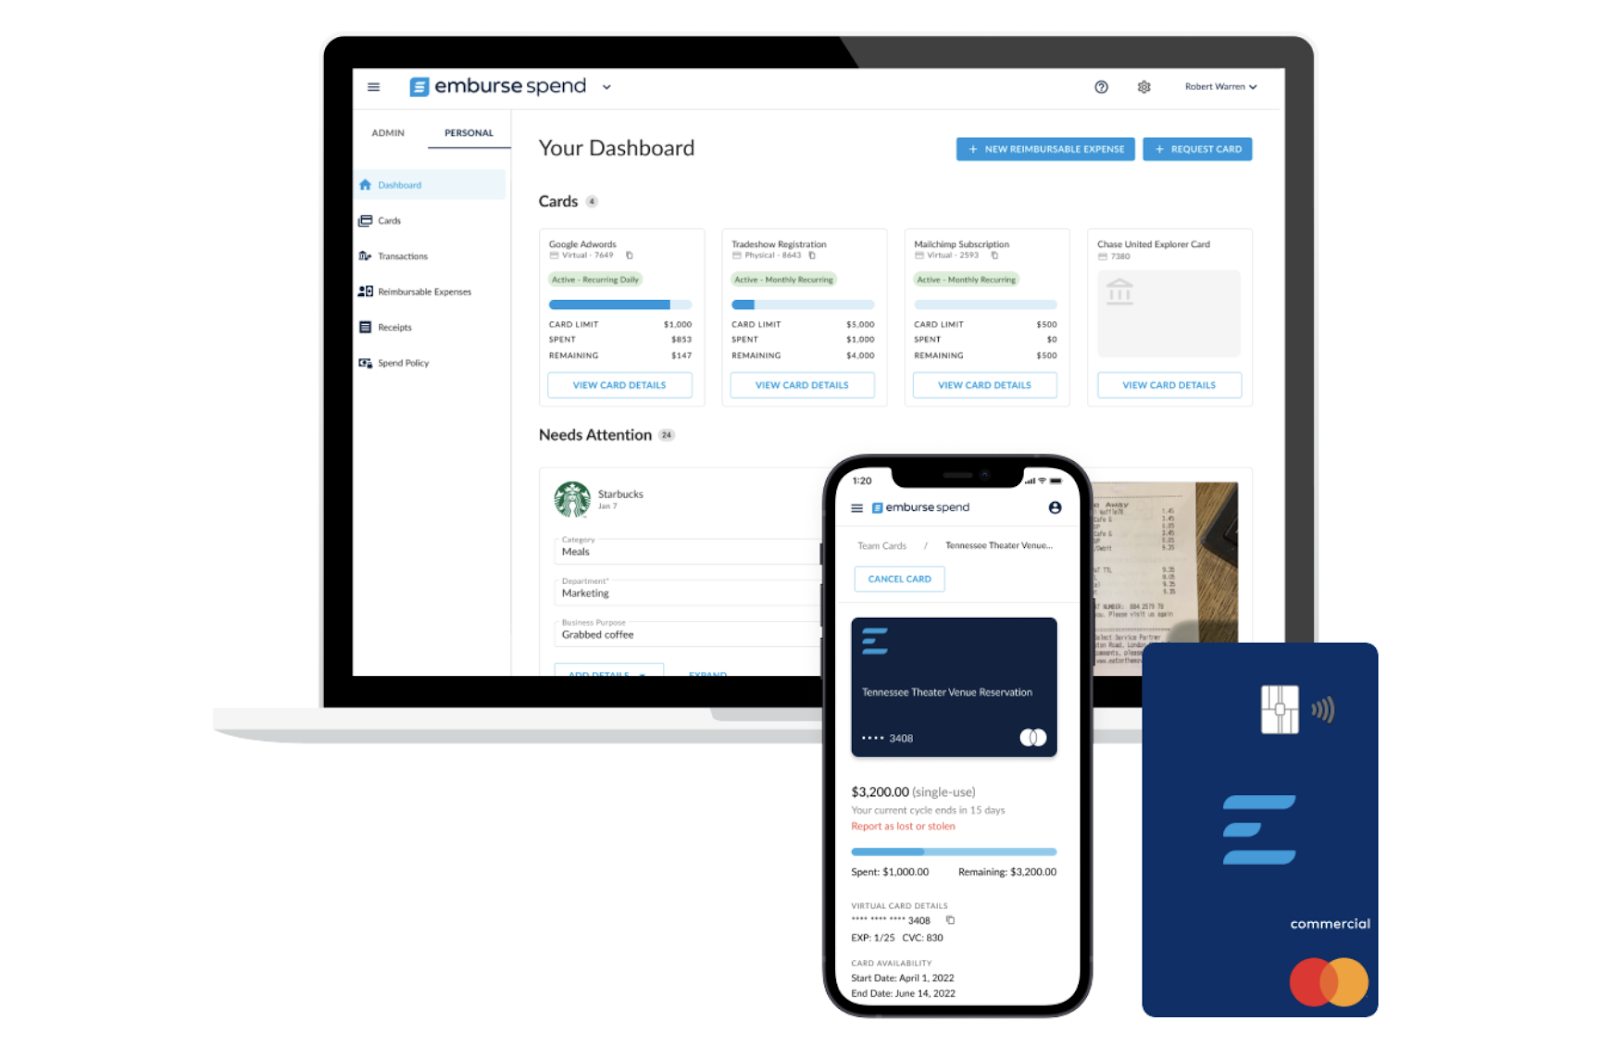
The Emburse card, aka Emburse Spend Card, is a cashback corporate card offered by a business expense management platform. If you use the platform or if you are on the hunt for a corporate card, you may have come across the name. Now, you’re probably wondering if this is a good offer for you. 

I’m here to help you decide – let’s explore the Emburse card offer, look at the cash back and other features, and see if it’s what you need. In the meantime, I’ll point you to various other offers you might like as well.  

Here’s what’s in store: 

  • What is an Emburse Card?
    • Emburse Company Overview
  • What Benefits Does Emburse Offer?
    • 1. Low-Risk Free Demo
    • 2. Corporate Cash Back (1%)
    • 3. Virtual & Physical Card Flexibility
    • 4. Real-Time Spend Management & Customizable Rules
    • 5. Mobile Receipt Capture & Permissions
    • 6. Detailed Insights & Reporting
    • 7. Tons of Integrations
  • Frequently Asked Questions
  • Conclusion

Let’s take the plunge! 

What is an Emburse Card? 

Emburse card login

The Emburse card is a smart and flexible solution for companies (of all sizes) to handle their spending – It comes in virtual and physical forms, making it easy for employees to buy things they need. 

What’s cool is that it has some built-in rules to keep spending in check, so you don’t have to worry about staff going over their budgets. Trusted by companies worldwide, the Emburse card doesn’t just help with transactions; it also makes keeping track of expenses super easy.

You can use it with Apple Pay for quick and safe payments. And, the card does a bunch of other helpful things too. For example, it can capture receipts on your phone, set different permissions for users, automatically sort expenses into categories, and protect against fraud. 

Plus, through a partnership with Wise, Emburse offers reimbursements on international transfers. Overall, it’s a handy tool for different parts of a company, like the human resources and finance teams.

And here’s a cool bonus – for every dollar you spend, you get 1% back! So, it’s not just a card; it’s a whole system that makes spending money smarter and more rewarding.

Recommended: 7 Best Cash Back Corporate Credit Cards to Explore 

Emburse Company Overview

Emburse Inc. is Los Angeles based, but was originally formed in Delaware. Delaware’s Division of Corporations website is a bit of a challenge to navigate, but I was able to see a merger on file (with Chrome River in 2019). The business’ first verified California business registration and the oldest online record of emburse.com are in 2015. 

I found out that Emburse went through Y Combinator in 2015, and – according to Crunchbase – they