• Home
  • Free Funding Guide
  • What We Offer
    • Products
    • Services
    • Free Guide
  • About Us
  • Contact
  • Sign Up

  • Ask Joe Any Question!
  • Business Credit Cards
  • Business Line of Credit
  • Topics

Giggle Finance: Instant Funding for Freelancers & Self Employed

By Joe

Key Takeaways

  • Giggle Finance provides up to $5K in fast funding for gig workers.
  • Giggle requires no credit checks,= and uses bank account activity to assess eligibility.
  • You can set up income-based, automatic repayment for flexible loan management.
  • Customer service is digital-only, with mixed reviews on responsiveness.
  • Accusations of predatory practices and unauthorized transactions raise red flags.
  • Some users value Giggle’s speed and simplicity for emergency financial needs.

Giggle Finance offers something a little different than what we usually review here, but maybe not as different as you might think. Before you apply, you’ll want to know what it is you’re signing up for. 

Here, explore what Giggle Finance is, learn more about the company, and understand key features of the offer. 

This is what’s in store: 

  • What is Giggle Finance?
    • Company Overview
  • How Does Giggle Finance Work?
    • 1. Apply Easily Online
    • 2. Get Instant Funding Anytime
    • 3. Repay Based on Your Income
    • 4. Access Funding Without a Credit Check
    • 5. Know Your Terms Before You Borrow
    • 6. Be Ready for Digital-Only Customer Support
  • Frequently Asked Questions
  • Conclusion: Is Giggle Finance Legit?

Now, let’s dive in! 

What is Giggle Finance? 
Giggle Finance

Giggle Finance provides fast and convenient funding solutions designed specifically for: 

  • Gig workers
  • Independent contractors
  • Self-employed individuals

They offer up to $5K in instant funding, their platform is fully automated, available 24/7, and requires no credit checks or lengthy application processes. 

The idea is that borrowers can access cash quickly to manage unexpected expenses or invest in opportunities. In theory, this can make it a flexible option for those in the gig economy who need immediate financial support.

You might also like: Torro Business Funding Review: Is This “Zero Hassle” Offer Legit? 

Company Overview
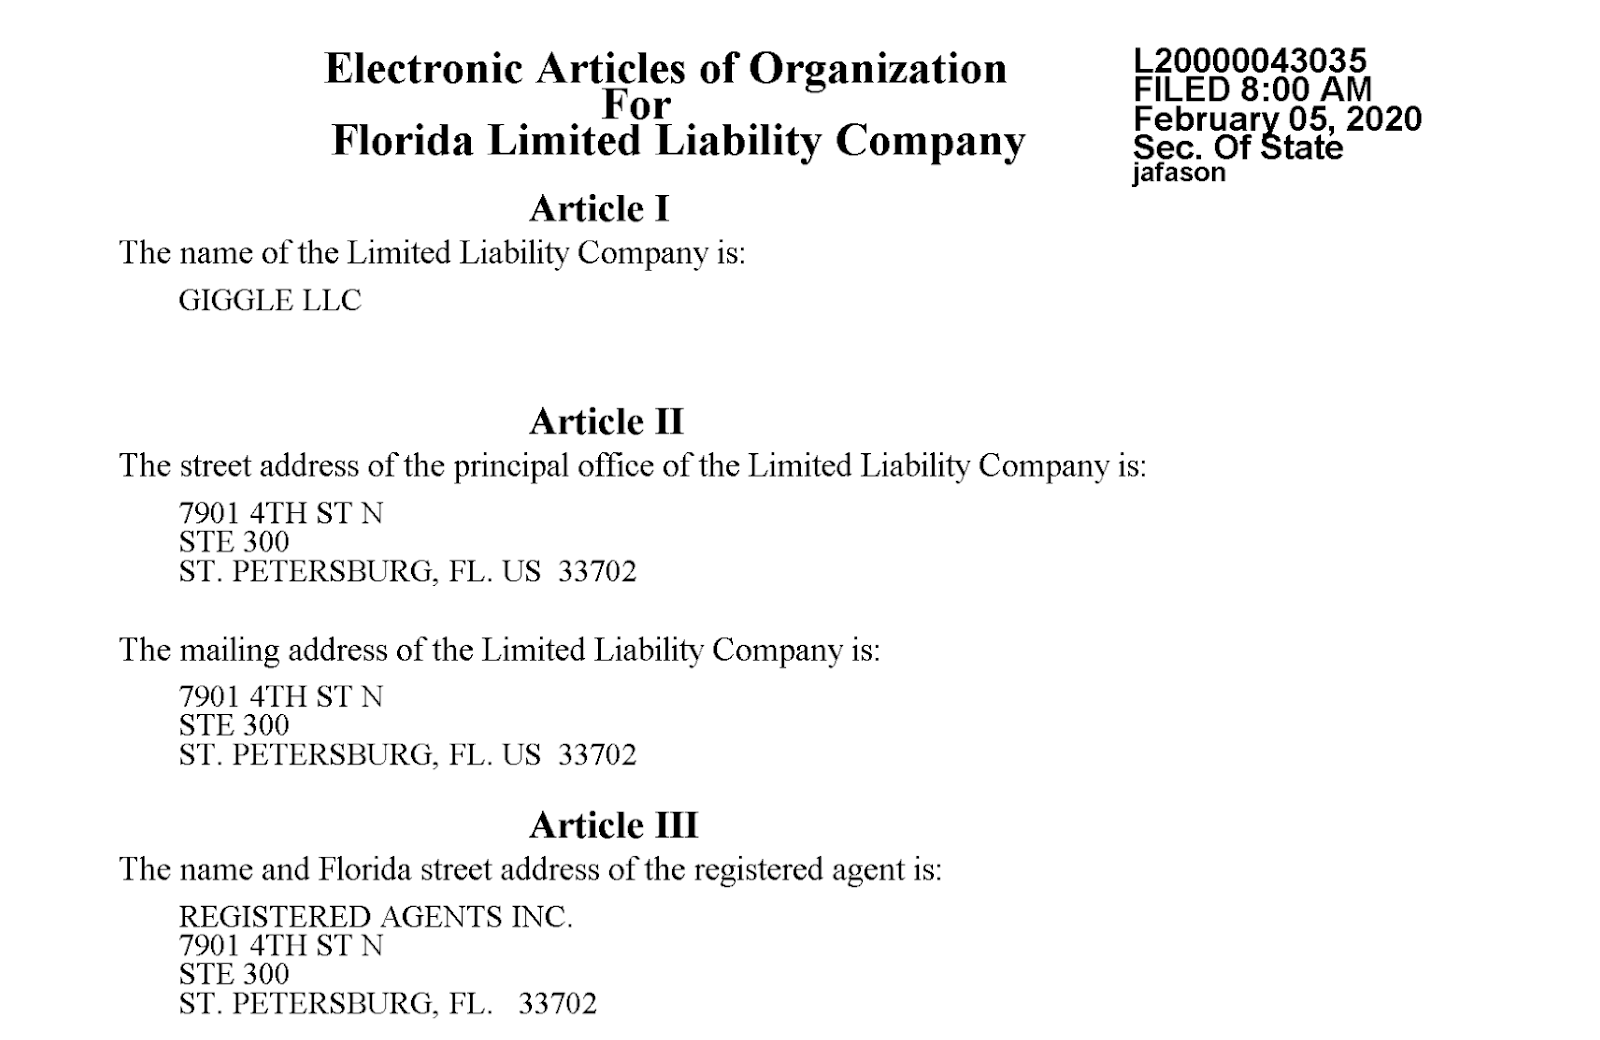
Giggle LLC

Giggle Finance, aka, Giggle LLC is a Florida-based, private, for-profit financial services entity that was founded in 2020 by Jared Kogan and Michael Zevallos. According to Florida’s SunBiz, the company is active, in good standing, and up-to-date with all their required filings with the state. 

Kogen previously spent 5+ years with OnDeck, as the Director of External Sales, and has held several high-level business consulting positions. Zavallos was the Manager of External Sales at OnDeck when Kogen was with the company, and he was the Co-Founder and COO at Idea Financial before the team launched Giggle. 
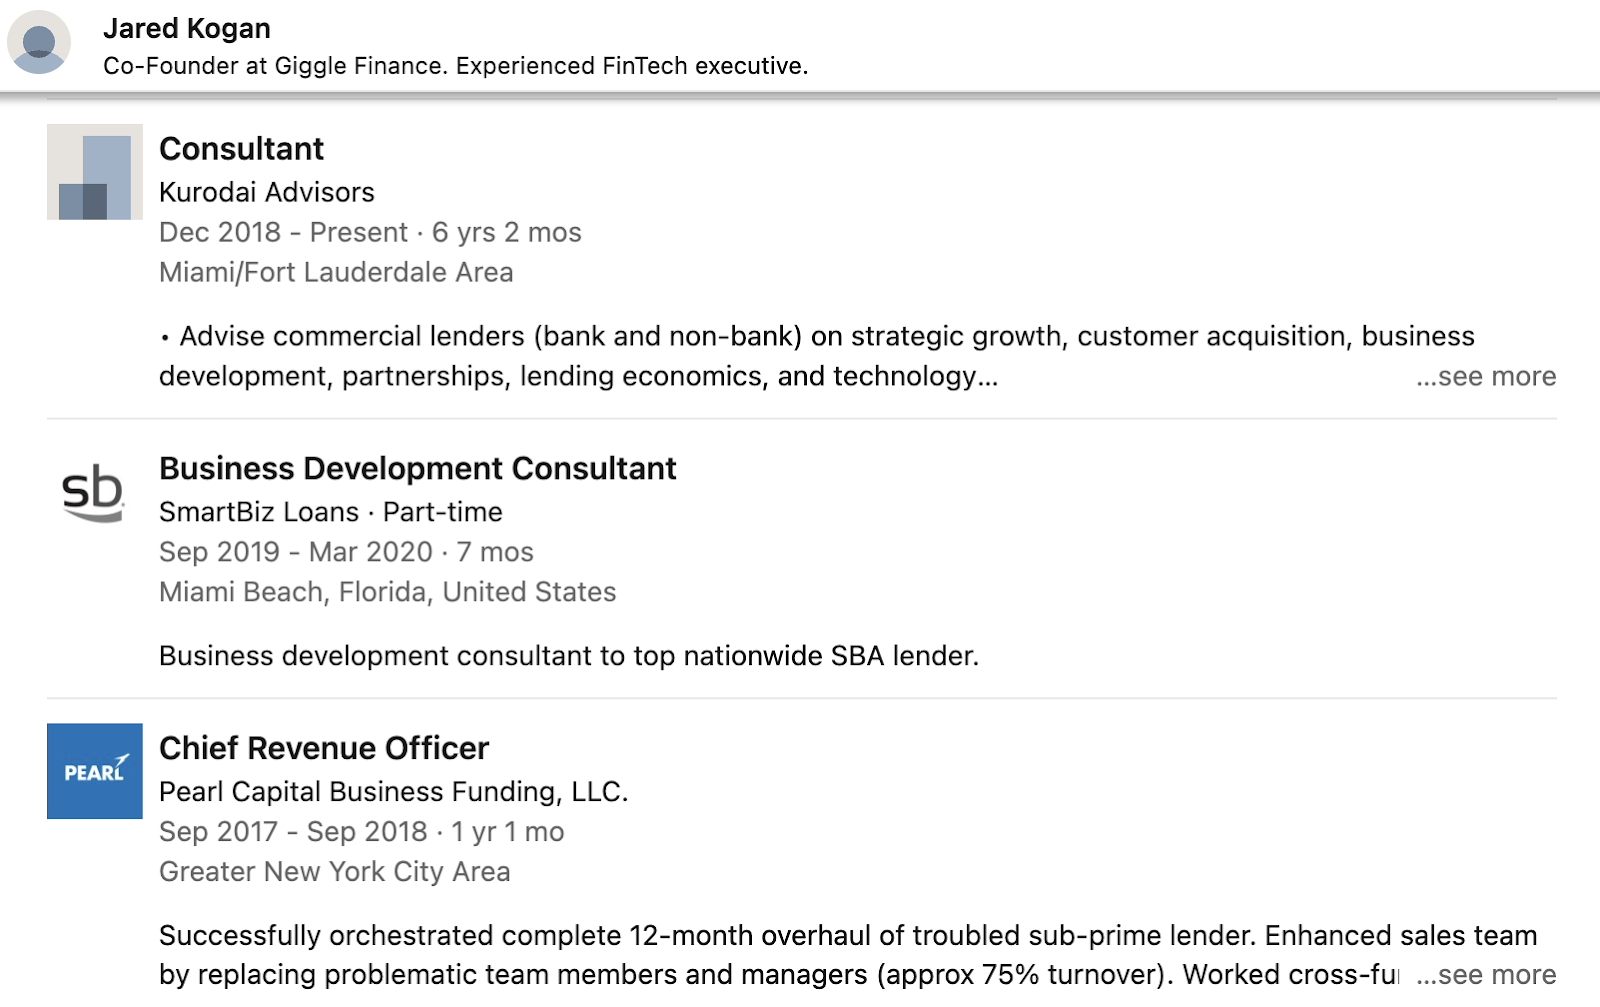
Who owns Giggle Finance?

In short, the leadership seems to be solid. However, it’s important to know what borrowers have to say. 

Currently, Giggle isn’t accredited with the Better Business Bureau (BBB), which I would almost let slide—not every legitimate business is accredited. But, they currently have an “F” BBB-rating and have failed to respond to 32 complaints filed on the platform. 
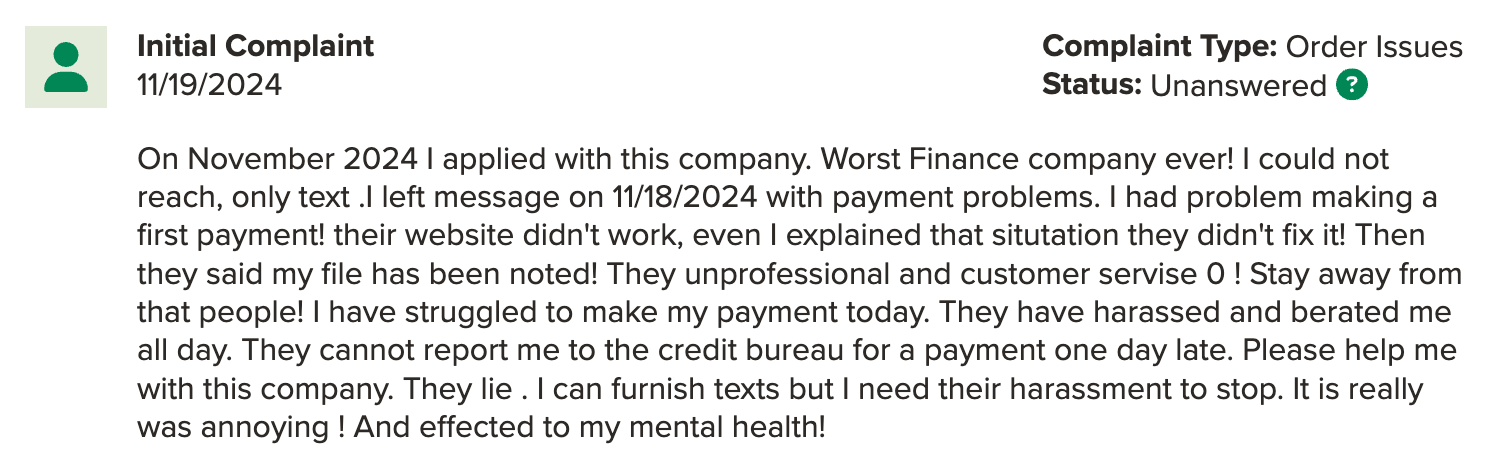
Giggle Finance complaint on BBB

Overall, TrustPilot reviews are a little more optimistic, with a 4.0 (out of 5.0) TrustScore.™  Even so, the 1-star reviews are pretty brutal. 
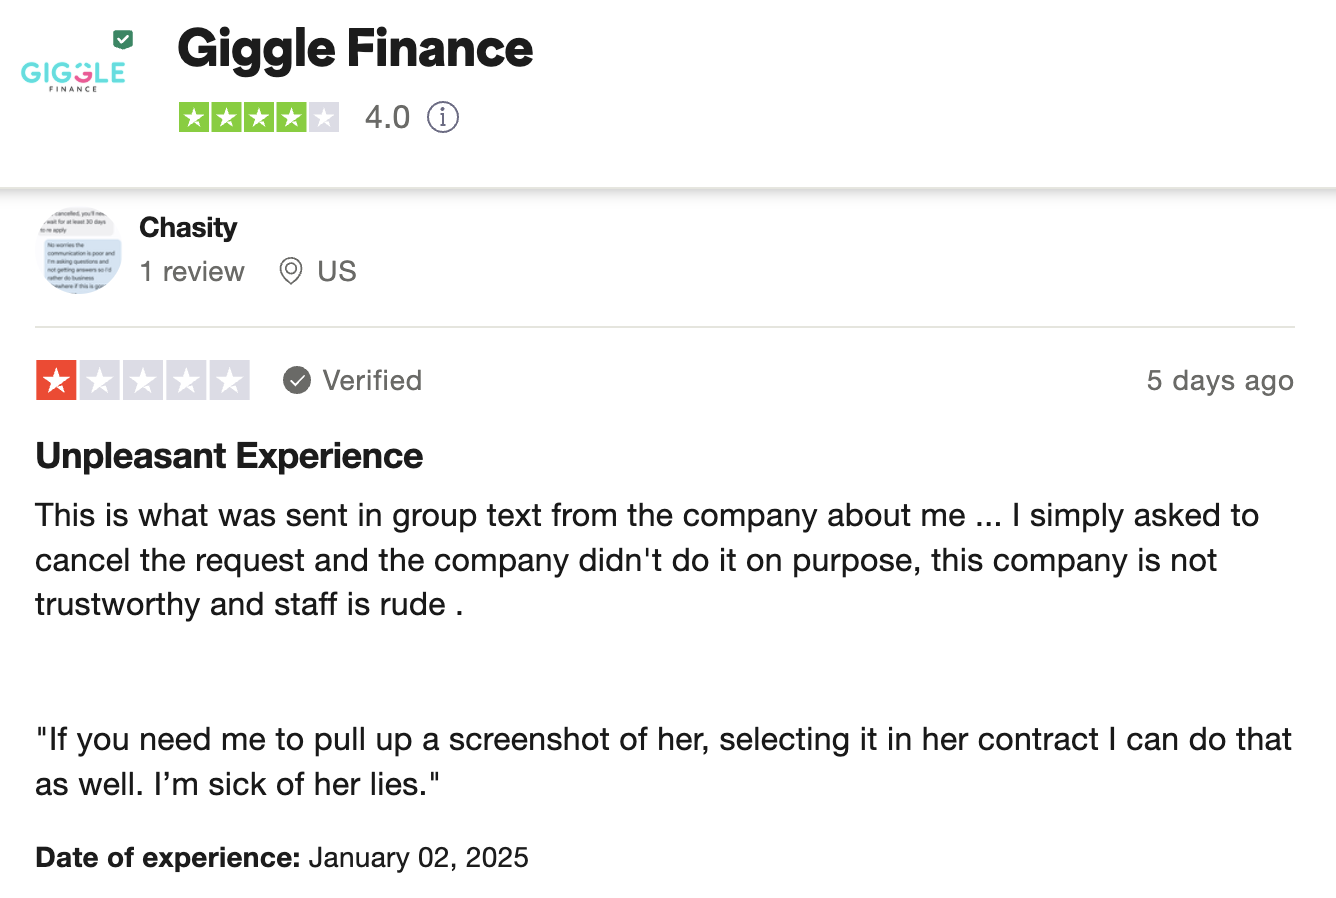
Giggle Finance Reviews

All in all, borrowers largely view Giggle Finance as an “unethical” lender, citing: 

  • Unauthorized transactions
  • Predatory practices
  • Poor customer service

Though, some people appreciate its fast funding for emergency needs.

These are some pretty weighty accusations, so I wanted to verify whether or not there are any open lawsuits against the company. And, I couldn’t find any current legal issues. 

However, Redditors also criticize Giggle Finance as deceptive, warning that its loans involve hidden fees and misrepresented terms, which has caused financial strain for gig workers.
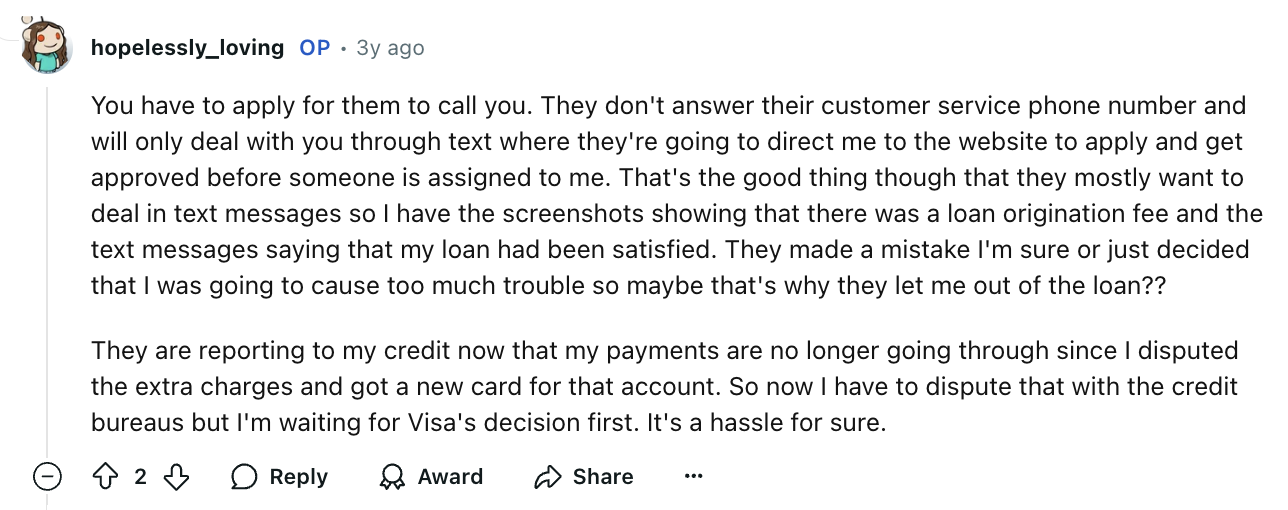
Giggle Finance reddit

Having no experience borrowing from the company myself, I would have to take others’ word. On one hand, Giggle Finance offers fast funding that some borrowers find helpful in emergencies, while on the other, reviews raise significant red flags.

 You might also like: How to Get a Business Credit Card – The Ultimate Guide 

How Does Giggle Finance Work? 

Giggle Finance offers gig workers and self-employed individuals fast funding options, but borrowers should weigh the potential risks. Here’s how it works.

1. Apply Easily Online
Giggle Finance Application

The process begins with a quick online application that takes just minutes to complete. By connecting your bank account, Giggle evaluates your eligibility based on income and account activity instead of credit scores. 
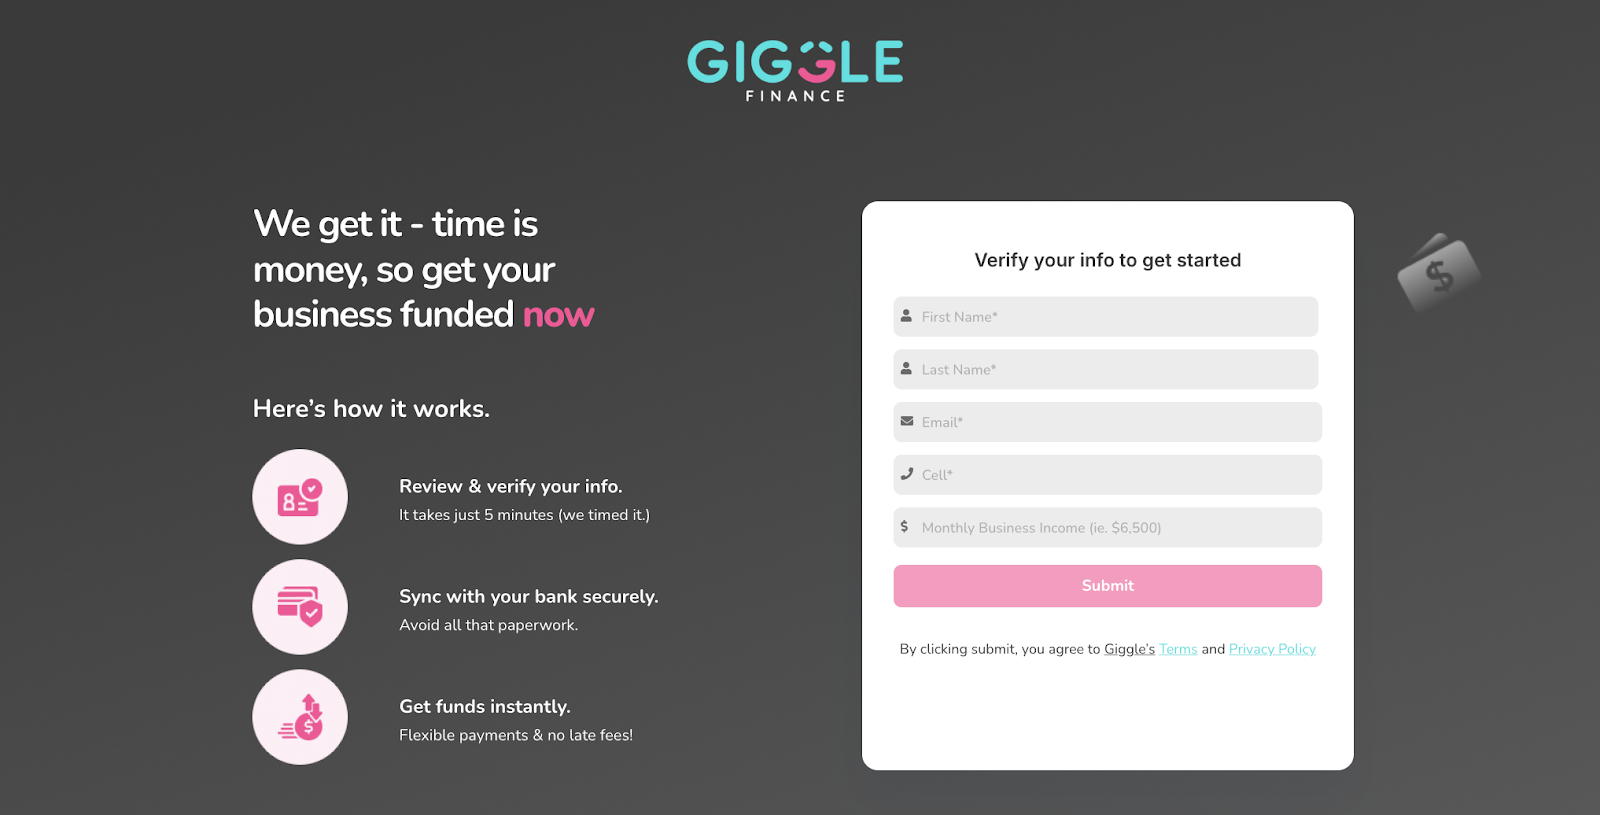
Giggle Finance login

While convenient, some users have expressed concerns about privacy and the security of their financial data. I know that they work with Plain, which I know to be a secure technology. 
Login Giggle Finance

If you’re working for a popular delivery service or selling on Shopify, you may be able to connect your account for immediate revenue info (this may be where the data security issue comes in). 

You might also like: No-Doc Business Loans: Get Funds Without Proof of Income 

2. Get Instant Funding Anytime
How long does Giggle Finance take?

Once your application is submitted, the automated system processes approvals in real time, with funds often deposited within minutes. This 24/7 availability is ideal for emergencies. 

However, some borrowers have reported delays or discrepancies in the amount funded compared to what was expected.

Recommended: Net 30 for New Business: 13 Vendors +Credit Building Insights 

3. Repay Based on Your Income
Giggle finance make a payment

Repayments are automatically deducted in line with your earnings, offering flexibility for those with variable incomes. Giggle also allows early payoffs to save on fees. Despite this, some users have faced challenges with rigid payment schedules and unexpected deductions.
Giggle finance dashboard

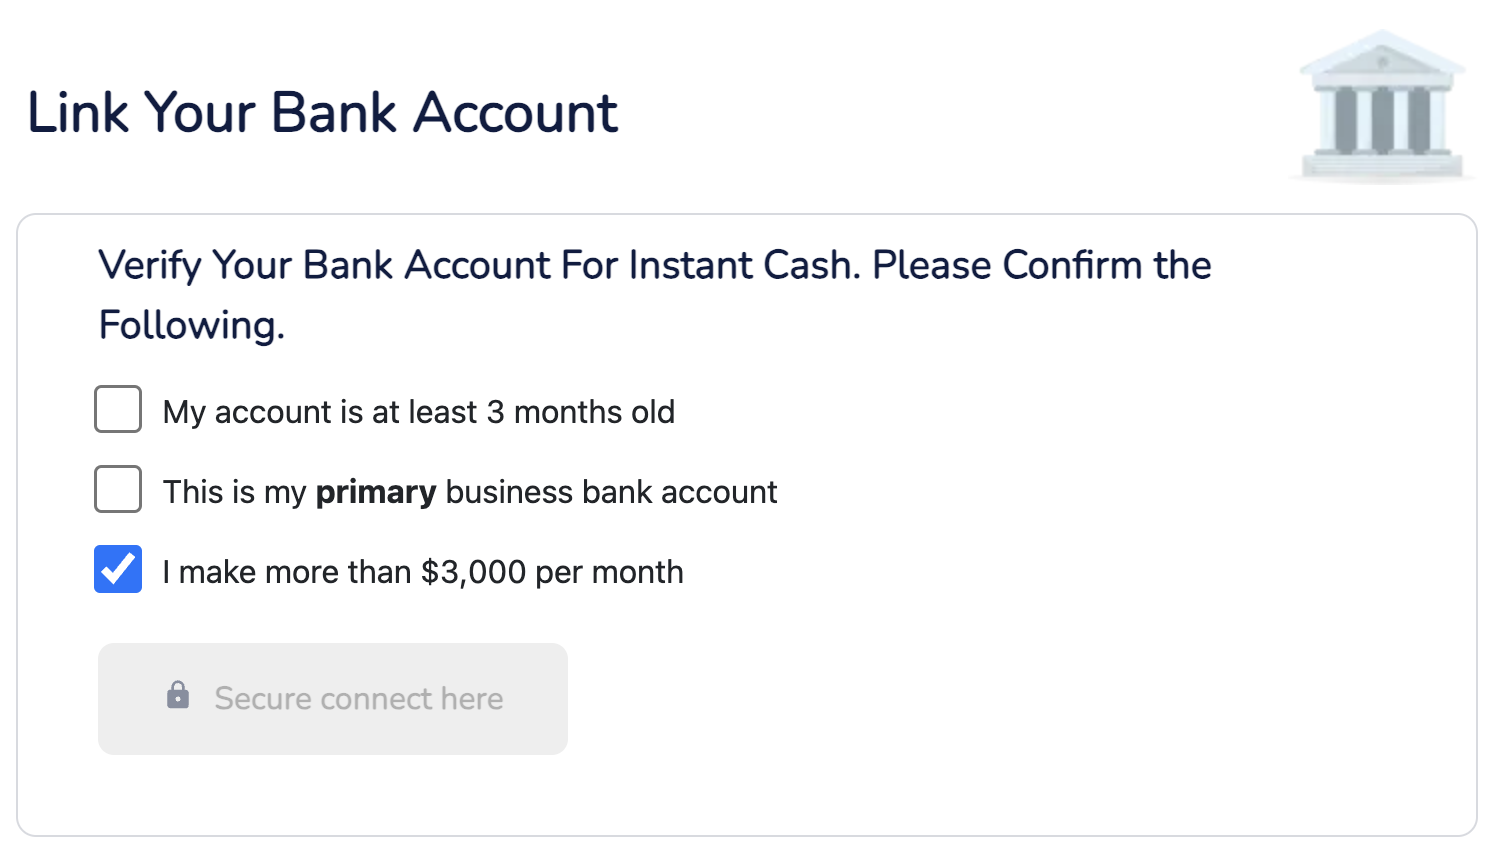
With this said, you will need to connect the platform to your primary business bank account. They’ll use it for income verification AND repayment. 

You might also like: 11 Alternate Ways for Entrepreneurs to Raise Capital with Online Lenders

4. Access Funding Without a Credit Check
no credit check loan for gig worker

Giggle Finance caters specifically to gig workers, freelancers, and independent contractors who may struggle to qualify for traditional loans. 

The no-credit-check feature makes the service widely accessible, but the high fees and unclear repayment terms reported by some borrowers warrant a careful review.

You might also like: A Full Skip Review: Business Grants, Funding, and More 

5. Know Your Terms Before You Borrow
Giggle Finance fees

Giggle Finance determines its fees and repayment terms based on the amount borrowed and the borrower’s risk profile. The company claims to maintain transparency to make sure borrowers understand the total cost before agreeing to the terms, with no hidden fees. 

However, some users report higher-than-average fees.

Keep in mind, Giggle calculates repayment amounts using a factor rate, which is a multiplier applied to the borrowed amount. For instance, a $5,000 loan with a factor rate of 1.5 would require $7,500 in total repayment. And, Giggle Finance doesn’t advertise their factor rates (I wish they did).

You might also like: Clover Capital Review: Read This Before You Accept an Offer 

6. Be Ready for SMS-Only Customer Support
Giggle finance phone number

To verify what some borrowers had said, I tried calling the phone number listed on the website and was redirected by a pre-recorded message instructing me to send a text. 

Customer service is entirely digital, with interactions through text or email. Some users have described their experiences as unprofessional or unhelpful, particularly when resolving disputes or addressing errors. But, depending on your preferences, this might be convenient. 

Frequently Asked Questions

What credit score do you need for Giggle Finance?

You don’t need a specific credit score to qualify for Giggle Finance. The platform does not rely on traditional credit checks and instead evaluates your eligibility based on your bank account activity and income.

What is the maximum loan amount for Giggle Finance?

The maximum loan amount offered by Giggle Finance is $5K— Your approved amount will depend on your verified income and banking activity.

Does Giggle Finance report to credit bureaus?

Yes, Giggle Finance does report to credit bureaus. This means your repayment activity (including any missed or late payments) can impact your credit score and appear on your credit report. Be mindful of this when you apply for a loan.

Conclusion: Is Giggle Finance Legit? 

Giggle Finance provides quick, easy access to cash, which can be invaluable in a pinch. However, recurring complaints (with no responses from the company) about aggressive practices, high costs, and poor communication highlight the importance of understanding the risks before borrowing.

If you carefully review the terms, you can make an informed decision about whether Giggle Finance is the right solution for your needs.

Do you want to learn how to obtain up to $100K in business credit in as few as 30 days? Join Business Credit Workshop today!
This is How to Buy a Franchise With No Money (Sort of)

By Joe

how to buy a franchise with no money

Key Takeaways

  • Franchises let you run a business using an established brand.
  • Most franchises need money upfront for fees, royalties, and other costs like location setup.
  • Online loans can help fund your franchise, though they may have higher interest rates.
  • Grants can provide free funding, but you must meet specific eligibility requirements.
  • Building business credit can help you finance a franchise without using your own money.
  • Some franchises, especially service-based ones, have lower startup costs.
  • Local franchises can be more affordable than big-name chains.
  • White label businesses may let you sell branded products with no upfront investment.

When you don’t have the cash upfront to invest in a business, but you really want to buy a franchise, what are your options? Unfortunately, there’s no such thing as free franchise opportunities in fast food or other brick and mortar chains. Still, you do have some options. 

Here, learn your options to buy a franchise with no money down, where to find low-cost franchises, and explore online opportunities that are comparable to franchising. 

This is what’s in store: 

  • What is a Franchise?
    • Do You Need Money to Buy a Franchise?
  • Ways to Buy a Franchise With None of Your Own Money Down
    • 1. Look Into Online Business Loans
    • 2. Apply for Business Grants
    • 3. Buy Into a Franchise With Business Credit
  • Where to Find Low-Cost Franchise Opportunities
  • Consider an Online White Label Businesses
  • Frequently Asked Questions
  • Final Takeaway

Now, let’s dive in! 

What is a Franchise? 

A franchise is a way to run your own business using someone else’s successful brand and system. 

The franchisor (the company) lets you, the franchisee, use their: 

  • Brand name
  • Products
  • Business plan

In return, you pay an upfront fee and a portion of your earnings.

For example, if you open a Chick-fil-A, you don’t have to come up with recipes or figure out marketing from scratch. Chick-fil-A provides you with everything you need—like training, branding, and a solid business plan. You run your location while they make sure the brand stays consistent across all their restaurants. 

Franchising can be a great way to start a business with the backing of a trusted name.

Do You Need Money to Buy a Franchise? 

In short, yes, you almost always need some money to buy a franchise. 

There are a few main costs you’ll need to cover: 

  1. The initial franchise fee
  2. Royalties
  3. Marketing costs
  4. Building or renovating

 And, it’s important to know about each before you get started.

The franchise fee is the upfront cost to buy into the franchise. It can be a few thousand dollars or much higher, depending on the brand.

After that, most franchises charge a regular fee, usually a small percentage of your sales, as royalties. This helps cover things like training and support from the franchisor.

In most cases, you’ll need to chip in for advertising. This is usually 1% to 5% of your sales, and it goes toward marketing the brand as a whole.

Finally, If the franchise needs a physical location, you might need to rent a space, build it, or remodel it to match the brand’s look. This can be one of the biggest expenses.

Recommended: How to Raise Money for Real Estate Investment: A Beginner’s Guide 

Ways to Buy a Franchise With None of Your Own Money Down

Most people bootstrap franchise startups with their own savings, loans, or partnerships to cover these costs. But, as a business, you may have some options. Here’s how to buy into a franchise with no money down. 

1. Look Into Online Business Loans 

how to buy a franchise with no money down

Online lenders offer a quick and convenient way to access funding for your franchise. These platforms often have flexible requirements, making them a good option if you don’t qualify for traditional bank loans. The application process is usually straightforward, and you can receive funds within days.

Online business loans typically come with higher interest rates, so make sure you have a plan to pay them back. Compare multiple lenders to find one that offers favorable terms.

You might also like: No-Doc Business Loans: Get Funds Without Proof of Income 

2. Apply for Business Grants 

Grants to start a franchise business

Business grants provide free money to help fund your franchise, but they often have strict eligibility requirements. Some are designed for specific groups, such as women, veterans, or minority business owners, while others support businesses in certain industries or locations.

Research grants offered by government programs, nonprofits, or private organizations. Although the application process can take time, securing a grant can significantly reduce your financial burden.

You might also like: A Full Skip Review: Business Grants, Funding, and More 

3. Buy Into a Franchise With Business Credit 

Can I get a loan to buy a franchise

Using business credit can help you finance a franchise without upfront cash. By building a strong business credit profile, you can qualify for credit lines, business loans, or vendor financing to cover franchise costs.

Start by establishing business credit if you don’t already have it. Pay attention to factors like your payment history and credit utilization. With good credit, you can leverage funding opportunities to buy into a franchise and grow your business.

Recommended: This is How to Leverage Business Credit to Transform Your Life

Where to Find Low-Cost Franchise Opportunities

cheap franchises under $5,000

If you’re looking for cheap franchises under $1,000, your options are slim. But, you don’t have to invest in a Chick-fil-A branch (which has a $10K initial franchise fee, and would probably cost somewhere in the $250K+ realm to launch) to become a franchise owner. From installing star-gazing ceilings to helping people plan dream vacations, there are other existing businesses you can buy into for less.   

Here are a handful of places to start your search:

  • Franchise marketplaces 
  • Service-based franchises 
  • Local opportunities 
  • The Small Business Administration (SBA)
  • Expos and trade shows. 

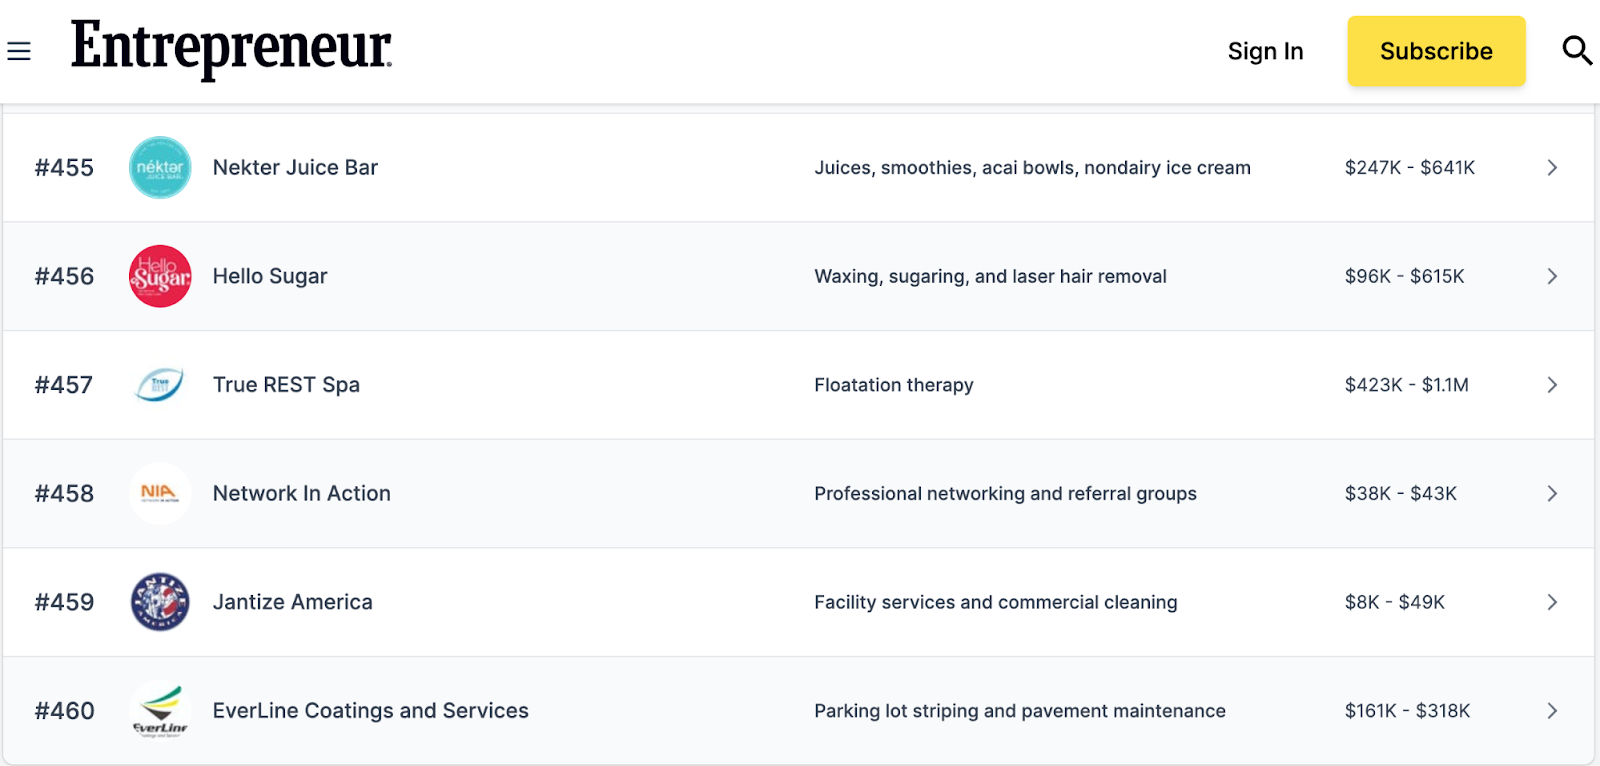
Sites like Franchise Direct, Franchise Gator, and Entrepreneur’s Franchise 500 list franchises by industry and cost. These platforms often have a “low-cost” filter to narrow down options under a certain budget.

Franchise cost list

Businesses like cleaning services, mobile repairs, or tutoring often have low startup costs. Examples include Jan-Pro or Cruise Planners.

Check for regional or smaller franchise opportunities near you. Many local businesses offer franchise options that might be more affordable than national chains.

The SBA’s franchise directory offers tools to research franchises, including ones eligible for SBA loans. This can help you identify cost-effective options with financing support.

Events like expos and tradeshows in your industry are a great place to meet franchisors directly. They often showcase a range of franchises, including budget-friendly ones.

Consider an Online White Label Businesses 

How to buy a franchise with no money online

Online white label businesses involve selling products or services that are created by another company but branded under your own name. This allows you to skip the production process and focus on selling and marketing the product. 

You can find white label online stores, software products, and service businesses. The white label business model is not the same, but has many shared benefits with franchising. 

how to buy a franchise with no money and bad credit

Plus, white label businesses tend to have low startup costs, and some even allow you to begin without any upfront investment. 

To run a white label business, you’ll typically need to set up an online store or platform where you can sell the products. 

Your main responsibilities will usually include: 

  • Marketing
  • Customer service
  • Sales management 

Meanwhile, the supplier will handle most of the production and fulfillment. It may be a lower-risk business model, but your success will largely depend on how well you market and brand the products.

You might also like: Is Credit Suite Legit? — A Business Credit Expert Review 

Frequently Asked Questions 

Do franchises pay a monthly fee?

Yes, most franchise owners pay royalties, which are typically 4% to 10% of sales. Some brands also require contributions to a marketing fund.

What’s the cheapest company to franchise?

Service-based franchises, like cleaning services or vending machines, often have low startup costs, sometimes under $10K.

How do I open a franchise with no money near me?

You can explore financing options like business loans or investors. Some franchisors also offer financing or low upfront costs.

What franchise is the easiest to own?

Franchises with simple operations and strong support, like fast food or cleaning services, are often easiest for first-time owners.

How much do Chick-fil-A owners make?

Chick-fil-A owners can make $200K to $300K annually, depending on location and sales.

Final Takeaway

If you want to buy a franchise business with no money, it’s possible through alternative financing. However, there isn’t a get rich quick scheme to follow. Consider financing, grants, and business credit. If you’d rather explore an opportunity with less initial investment upfront, consider a white label business instead. 

Are you ready to learn how to obtain up to $100K in business credit in as few as 30 days? Join Business Credit Workshop today!
Sidney Federal Credit Union: NY Business Financial Options

By Joe

Sidney Federal Credit Union

As far as financial institutions are concerned, Sidney Federal Credit Union (SFCU) stands out as a beacon of community-focused banking. They offer tailored solutions to meet the needs of both individuals and businesses. 

Unlike traditional big banks, credit unions like SFCU are member-owned cooperatives, which means that profits are reinvested into services. In turn, they’re usually able to offer exemplary products and rates for members. From a business credit perspective, SFCU has some interesting offers. Let’s take a closer look here. 

This is what’s in store: 

  • What is SFCU?
    • Locations Served
    • Membership & Eligibility Requirements
  • SFCU Business Financial Products & Services
    • Business Banking/Checking
    • Business Platinum Mastercard Credit Card
    • Business Loans & Lines of Credit
    • Business Savings & Investment Opportunities
  • SFCU Customer Service
  • SFCU Community Involvement
  • Frequently Asked Questions
  • Final Thoughts

Now, let’s roll!

What is SFCU?

What is Sidney FCU?

SFCU originated when a group of employees from Scintilla Magneto Corp. gathered in Sidney, NY, to form a credit union. In 1949, they secured a charter from the Bureau of Credit Unions, officially establishing Sidney FCU, later known as Sidney Federal Credit Union.

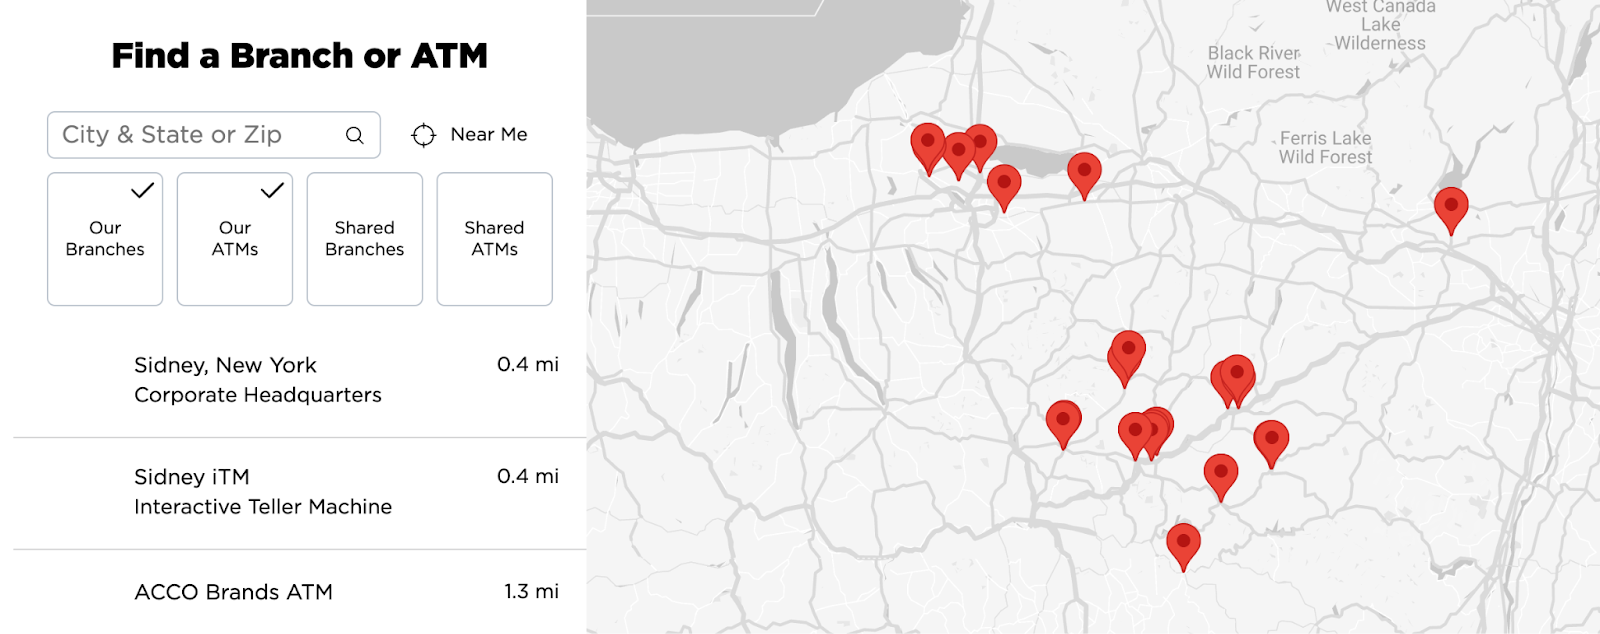
Today, SFCU boasts 11 branches across several counties in New York state, including parts of Broome, Oneida, Herkimer, Chenango, Delaware, Otsego, Cortland, Onondaga, Madison, Schoharie, Montgomery, Fulton, Hamilton, and Essex. The credit union is governed by a Board of Directors comprising individuals who live and work within the communities SFCU serves.

Established with a mission to serve the local community, Sidney Federal Credit Union has been a cornerstone of financial support since its inception. With a strong commitment to assisting small businesses, SFCU provides a range of specialized financial products and services designed to fuel entrepreneurial growth.

Recommended: 3 Best Credit Unions for Small Business Banking in 2024 

Locations Served

sidney federal credit union locations

SFCU extends its services to individuals and businesses across various counties and towns in New York state. 

These areas include:

  • Chenango
  • Cortland
  • Delaware
  • Essex
  • Fulton
  • Hamilton
  • Madison
  • Montgomery
  • Onondaga
  • Otsego
  • Schoharie

In addition to these counties, specific towns within Broome, Oneida, and Herkimer counties are also within the field of membership. 

These towns include:

  • Colesville, Sandford, and Windsor Towns in Broome County
  • Sangerfield, Bridgewater, Augusta, Marshall, Paris, Vernon, and Kirland Towns in Oneida County
  • Winfield, Litchfield, Columbia, Warren, Stark, Danube, Frankfort, and German Flats Towns in Herkimer County

If you reside, work, attend school, worship, or conduct regular business activities within these areas, you may be able to take advantage of SFCU’s services and benefits.

SFCU Membership & Eligibility Requirements

How to Join Sidney Federal Credit Union

Becoming a member of SFCU is a straightforward process designed to be accessible to all eligible individuals. 

Here’s how you can join:

  1. To initiate your membership, open a savings account with SFCU online. The minimum deposit required is only $5, making it easy for individuals to get started.
  2. Once your savings account is opened, deposit at least $5 to fulfill the membership requirement.
  3. With your membership established, you are now eligible to apply for and access a wide range of financial services offered by SFCU, including banking services, business accounts, lending services, and more.

SFCU welcomes not only individuals residing within the specified counties and towns but also extends membership eligibility to employees of SFCU, immediate family or household members, organizations of such persons, and corporate or other legal entities—This inclusive approach ensures that a diverse range of individuals and entities can benefit from the superior service and exceptional financial services offered by SFCU.

SFCU Business Financial Products & Services

Now, let’s take a look at the business financial products offered at SFCU—We’ll look at the checking, credit cards, loans, and savings accounts that small business owners can take advantage of.

SFCU Business Banking/Checking

sidney federal credit union online banking

SFCU offers a few different business checking accounts:

  • Basic Business Checking
  • Community Checking (for nonprofits)
  • Business Dividend Checking  

With all business checking accounts, you’ll get a Mastercard debit card, free online and mobile banking with e-statements, and unlimited transactions. You’ll also get free bill pay and be able to access overdraft protection options. 

With Basic Business Checking, there are no added fees and no minimum opening deposit. You can avoid the $5 monthly maintenance fee if you maintain a $500 minimum balance. 

For not-for-profits, SFCU provides the Community Checking account. There is no minimum initial deposit requirement and no monthly maintenance fee. 

Businesses looking to earn dividends on their checking balance can opt for the Business Dividend Checking account. With no minimum initial deposit requirement, businesses must maintain a $5K ADB to earn dividends, and to avoid the $5 monthly maintenance fee—This account offers a competitive .25% APY on balances. 

FeatureBasic Business CheckingCommunity CheckingBusiness Dividend Checking
Minimum ADB to Earn DividendsN/AN/A$5,000
Minimum ADB to Avoid Monthly Maintenance Fee$500N/A$5,000
Dividend Rate *N/AN/A.25% APY
Monthly Maintenance Fee *$0 to $5$0$0 to $5

At SFCU, there seems to be a checking option for nearly any small business.

You might also like: Amex Business Checking Review: What You Need to Know…Really 

SFCU Business Platinum Mastercard Credit Card

Sidney Federal Credit Union login

The SFCU Platinum Mastercard® offers a competitive APR starting as low as 13.15%, with a maximum APR of 17.99%. What’s great? There are no annual fees, making it an attractive option for businesses looking to stretch their dollars further. 

With this card, you can earn rewards on everyday purchases. 

The SFCU credit card earns a flat 1% back that can be redeemed for: 

  • Cash back
  • Travel
  • Gift cards
  • Charity donations

Plus, there’s no balance transfer fees, and you can enjoy the convenience of tap-to-pay contactless payment. There’s also 24/7 fraud monitoring. If you need to increase your credit limit, you can apply for a limit increase hassle-free. 

Recommended: Corporate vs Business Credit Card: What’s the Difference? 

SFCU Business Loans & Lines of Credit

Sidney Federal Credit Union Business Credit Card

SFCU also has an array of business loans, including term loans, lines of credit (revolving), and real estate loans. All of their loans have competitive rates, flexible terms, and come with no prepayment penalties. 

If you’re looking to expand or cover expenses, SFCU’s business term loans provide the financing you might need to keep operations running smoothly. Use them for inventory, equipment, or services. Plus, with fixed rates and the option to choose loan terms between 1 and 7 years, budgeting is pretty simple.

For when you need ongoing access to funds, SFCU also provides business lines of credit. These lines of credit offer financial flexibility for various purposes, including cash flow gaps and overdraft protection. With options for both secured and unsecured lines of credit, you can choose the option that best fits your needs and goals. 

If commercial or investment real estate properties are on your radar, SFCU offers commercial real estate loans with flexible terms and structures—These loans come with both fixed and variable rates and can be customized to fit your unique needs and goals. 

Recommended: How to Get Money for Real Estate Investing: 18 Practical Ideas 

SFCU Business Savings & Investment Opportunities 

Sidney Federal Credit Union CD Rates

SFCU offers a few business savings options tailored to suit different financial needs and goals.

  1. Business savings account
  2. Business money management account
  3. Business share certificates

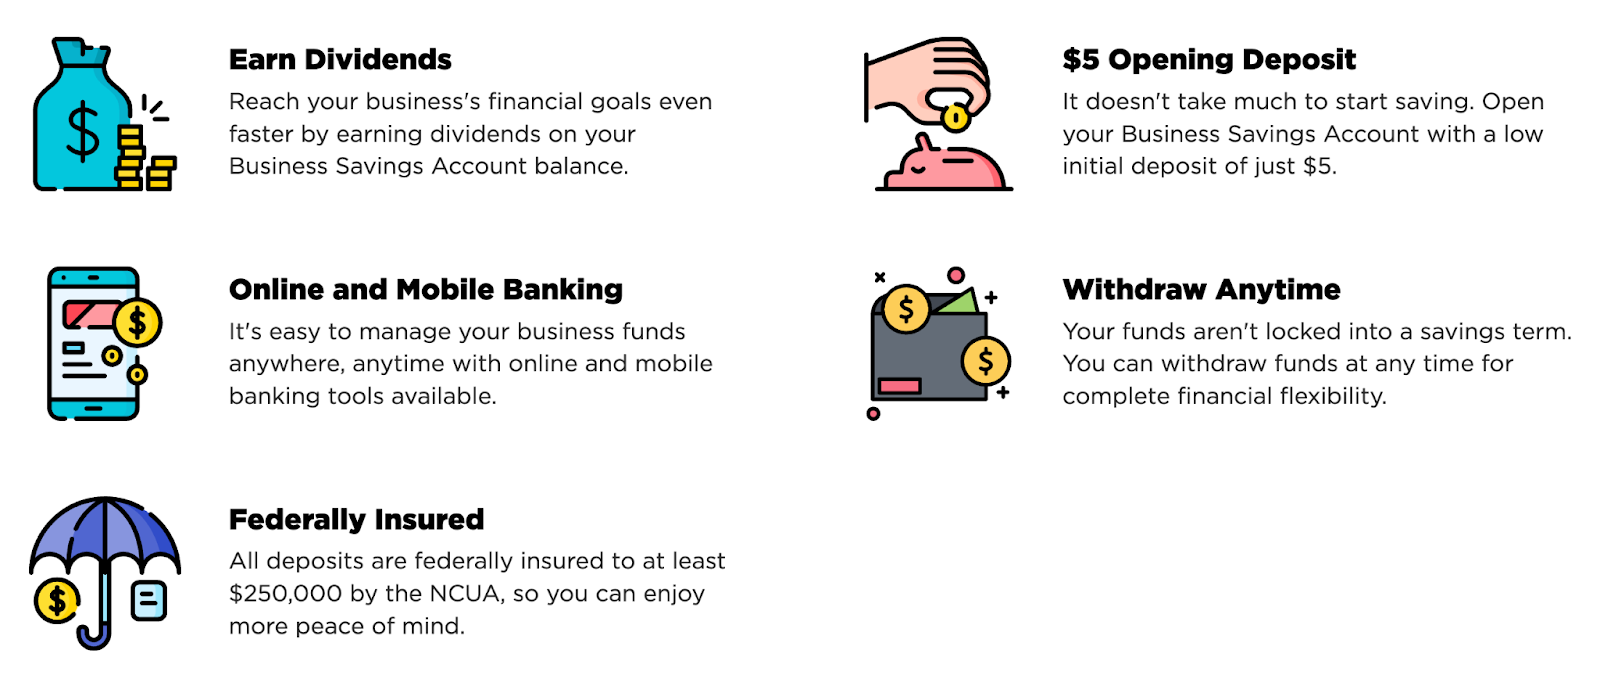
The SFCU Business Savings Account is ideal if you’re looking to build up savings and maintain easy access to funds. With just a $5 minimum opening deposit, you can earn dividends on your balance (up to 0.05% APY)—This account might be good if you want to earn a little extra while saving for short-term business goals or emergencies. 

Now, if you want to maximize your savings potential without sacrificing liquidity, SFCU’s Business Money Management Account might be a better choice. With higher dividends and no withdrawal penalties, this account offers flexibility while allowing your savings to grow. It’s suitable when you want to earn more on your funds and retain the ability to access them when needed.

When you’re aiming for long-term savings goals, such as expansion plans or major investments, the Business Share Certificates offer higher savings rates with flexible terms. With terms ranging from 31 days to 60 months and competitive rates as high as 2.53% APY, SFCU’s certificates provide an opportunity to earn more on your savings over time.

In all, SFCU’s business savings options provide opportunities to earn dividends and grow your funds. However, these aren’t the best rates I’ve ever seen. 

Recommended: Bluevine Review: Free, High Yield Small Business Checking! Are They Serious? 

SFCU Customer Service

Sidney Federal Credit Union customer service

Sidney Federal Credit Union (SFCU) provides various customer service channels for members’ convenience:

  • Live chat – Immediate assistance is available via live chat
  • Email – Members can send messages for non-urgent inquiries
  • Phone support – Accessible at 877-642-7328 (SFCU)
  • SMS text messaging – Support for lost or stolen cards—24/7
  • Text message alerts – Receive important notifications via text

These channels ensure members can access assistance promptly and efficiently. Keep in mind, they’re typically available during normal “banking hours” (9 to 5 Monday through Friday). 

sidney federal credit union 24 hour customer service

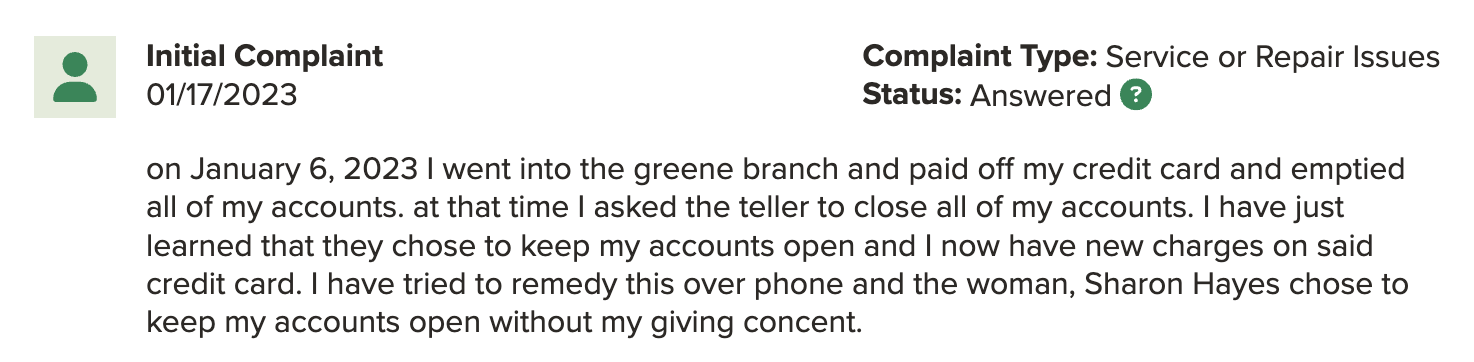
Of course, as with all services, you might expect mistakes to happen from time to time…But, SFCU has apparently closed all of their *minimal* complaints with the Better Business Bureau promptly. They maintain an A-rating on the platform despite not being accredited.  

SFCU reviews BBB

In all, you should be able to get in touch with someone when you need help. 

You might also like: 6 Best 0% APR Business Credit Cards to Check Out 

SFCU Community Involvement

Sidney Federal Credit Union in the community

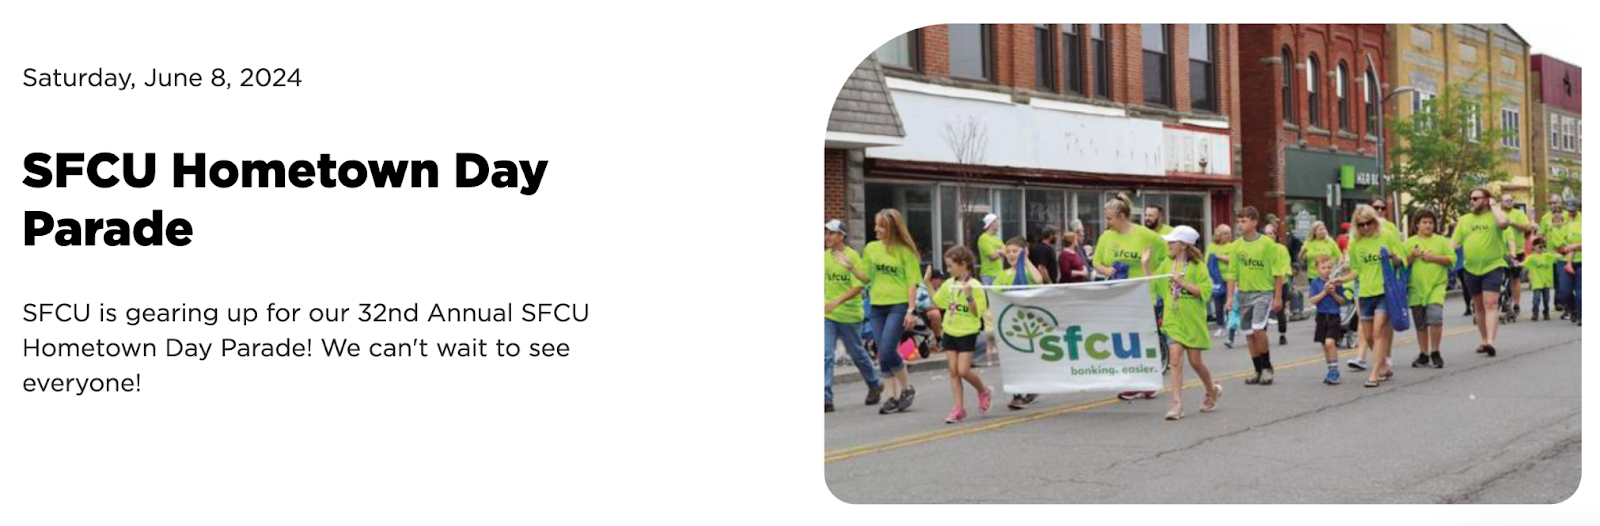
Sidney Federal Credit Union (SFCU) is rooted in community spirit—they pioneer local events like the SFCU Hometown Day Parade. It’s a blast, stretching over 1.2 miles, starting at Sidney Central School and winding down to Keith Clark Park for a lively celebration. Locals are invited to be part of the tradition, soaking in the community vibes and enjoying the festivities.

Ever heard of the Fraud Seminar? SFCU teams up with the Montgomery County Sheriff’s Office to bring the community this eye-opening event. Scams are everywhere nowadays, but staying informed is key to protecting yourself. SFCU teaches the ins and outs of how to spot scams, protect your finances, and what to do if you fall victim to fraud. 

And, if you feel a bit lost in the budgeting department, SFCU’s got your back. At their Budgeting 101 workshop at their Cicero branch, they’ll hook you up with all the tips and tricks to create a budget that actually works for you. Plus, there’ll be snacks and beverages to keep you fueled up while you learn.

You might also like: BILL Spend & Expense Card Review (Formerly Divvy Credit Card) 

Frequently Asked Questions

Does Sidney Federal Credit Union have Zelle®? 

Yes, Sidney Federal Credit Union does offer Zelle®. Simply log into the Sidney Federal Credit Union mobile app and select “Send Money with Zelle®.” From there, follow the prompts to enter the necessary information, accept the terms and conditions, and begin sending and receiving money.

What is the grace period at Sidney Federal Credit Union? 

For most products, the grace period for Sidney Federal Credit Union is 10 days—This means that you have a window of 10 days after your due date to make payments without incurring any late fees. However, any payments received after this 10-day grace period will incur fees.

What is Sidney Federal Credit Union’s address? 

SFCU’s main office is situated at 42 Union St., Sidney, NY 13838. Additionally, SFCU operates 11 branches across several counties in New York, including parts of Broome, Oneida, and Herkimer, as well as the entirety of Chenango, Delaware, Otsego, Cortland, Onondaga, Madison, Schoharie, Montgomery, Fulton, Hamilton, and Essex counties.

What is Sidney Federal Credit Union’s routing number? 

The routing number for SFCU accounts is 221379905. 

Final Thoughts

In summary, Sidney Federal Credit Union (SFCU) offers a range of financial products and services tailored to meet the needs of businesses in New York state. From business checking accounts and credit cards to loans, lines of credit, and savings options, SFCU provides comprehensive solutions to support entrepreneurial growth. 

Additionally, their community involvement initiatives, such as the Hometown Day Parade and educational events like the Fraud Seminar and Budgeting 101 workshop, demonstrate their commitment to supporting and empowering local communities. 

With accessible membership requirements and convenient customer service channels, SFCU strives to be a reliable partner in the financial success of its members—Just be sure to shop around and make sure you take advantage of the business financial products that best meet your needs and goals. 

Do you want to learn how to obtain up to $100K in business credit in as few as 30 days? Join Business Credit Workshop today!
What You Need to Know About PayPal LoanBuilder for Business

By Joe

PayPal Loan Builder

PayPal LoanBuilder is advertised as a quick, convenient way to get up to $100K in business funding. The company is more than reputable, and their marketing makes it sound like the easiest financing option in the world. But, what are the terms, how much does it cost, and is this really the best loan for your business? 

Let’s find out what LoanBuilder is, how it works, and explore exactly what you can expect if you apply. 

This is what’s in store: 

  • What is PayPal LoanBuilder?
    • How Much Does PayPal LoanBuilder Cost?
  • How Does PayPal LoanBuilder Loan Work?
    • 1. Apply With No Impact to Your Credit
    • 2. “Customizable” Funding
    • 3. Fixed-Fee Loan
    • 4. Fast Access to Funds
    • 5. Accessible Business Funding
    • 6. Weekly Repayment Terms Up to 12 Months
  • Frequently Asked Questions
  • Final Thoughts

Now, let’s get to it! 

What is PayPal LoanBuilder? 

Loan Builder PayPal

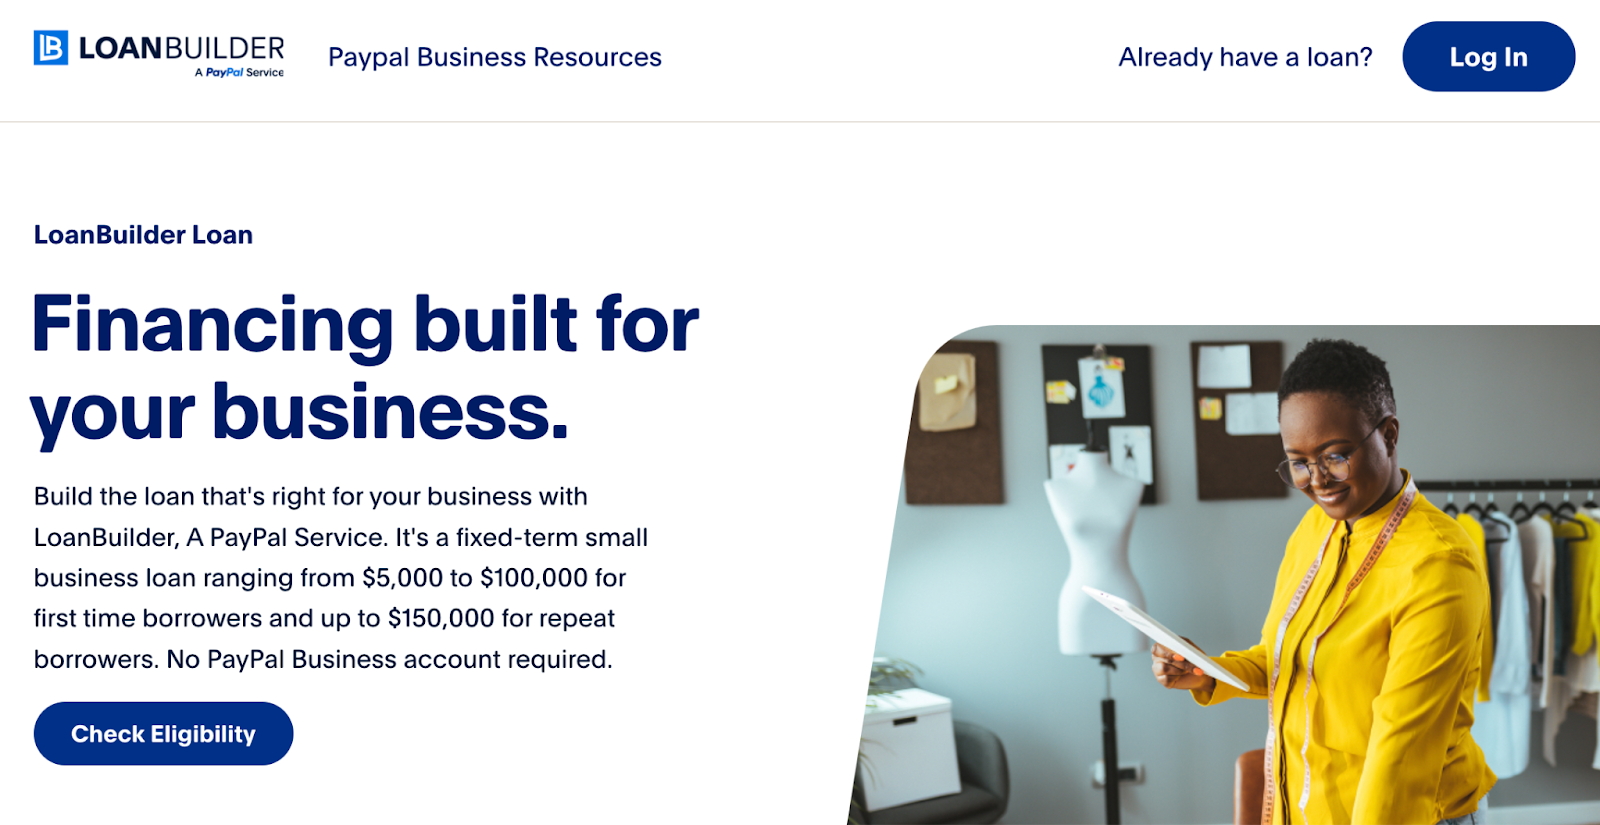
PayPal’s LoanBuilder is a service that offers fixed-term small business loans from $5,000 to $100,000 for first-time borrowers and up to $150,000 for repeat borrowers—the financing option is designed to be fast and flexible, with funds potentially available in your business bank account as soon as the next business day after approval.

The loan comes with transparent pricing, where you pay a clear, fixed fee along with a $20 Returned Item Fee if a payment is returned. There are no late fees, early repayment fees, or processing fees. You can choose a repayment term that suits your business needs, and payments are automatically deducted weekly.

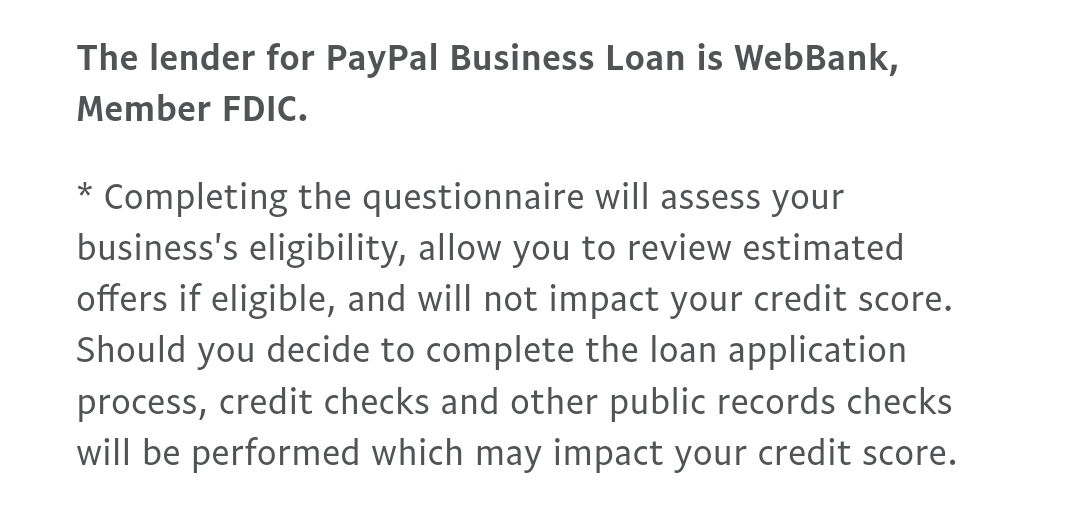
To check if your business is eligible for a LoanBuilder Loan, you can complete a quick online questionnaire. This process won’t impact your personal credit score. If eligible and approved, you can customize your loan amount and term, sign the contract electronically, and receive the funds quickly.

To qualify, your business needs to have been operational for at least nine months with an annual revenue of at least $33,300. Keep in mind that LoanBuilder is a service provided by PayPal in partnership with WebBank. The loan application and approval process is designed to be straightforward and streamlined, aimed at helping businesses manage cash flow, finance projects, or tackle other business challenges.

paypal loanbuilder requirements

A LoanBuilder loan does require a personal guarantee. 

You might also like: Business Credit Cards without Personal Guarantee 

How Much Does PayPal LoanBuilder Cost? 

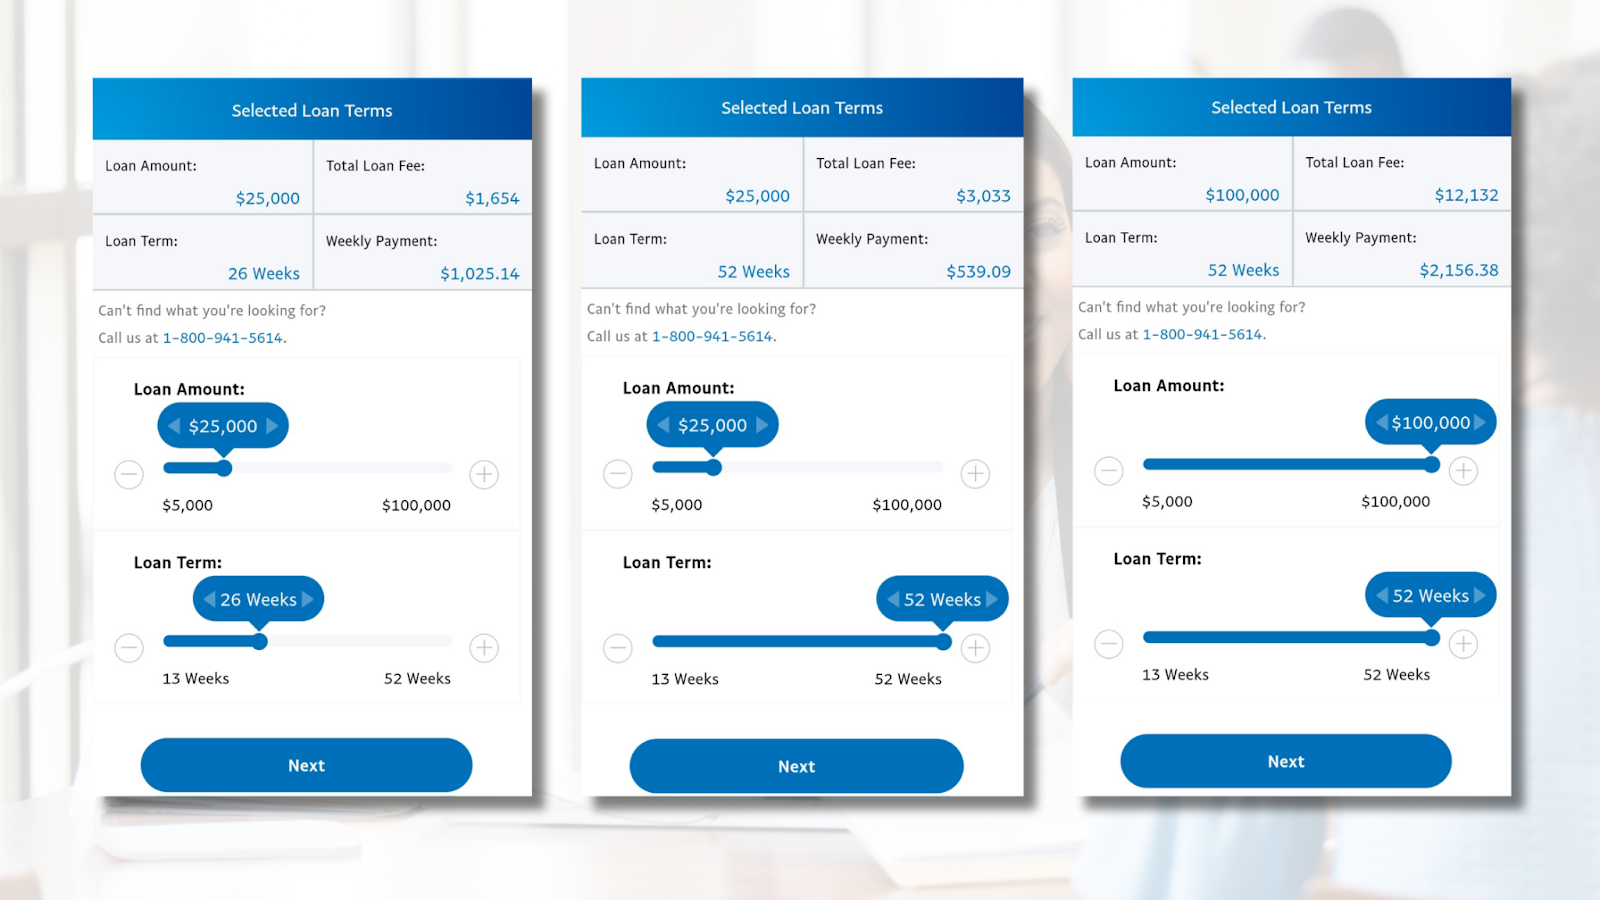
The cost of a LoanBuilder loan is determined by a single fixed fee known as the Total Loan Fee, which will be disclosed at the time of loan approval and remains consistent throughout the loan term. 

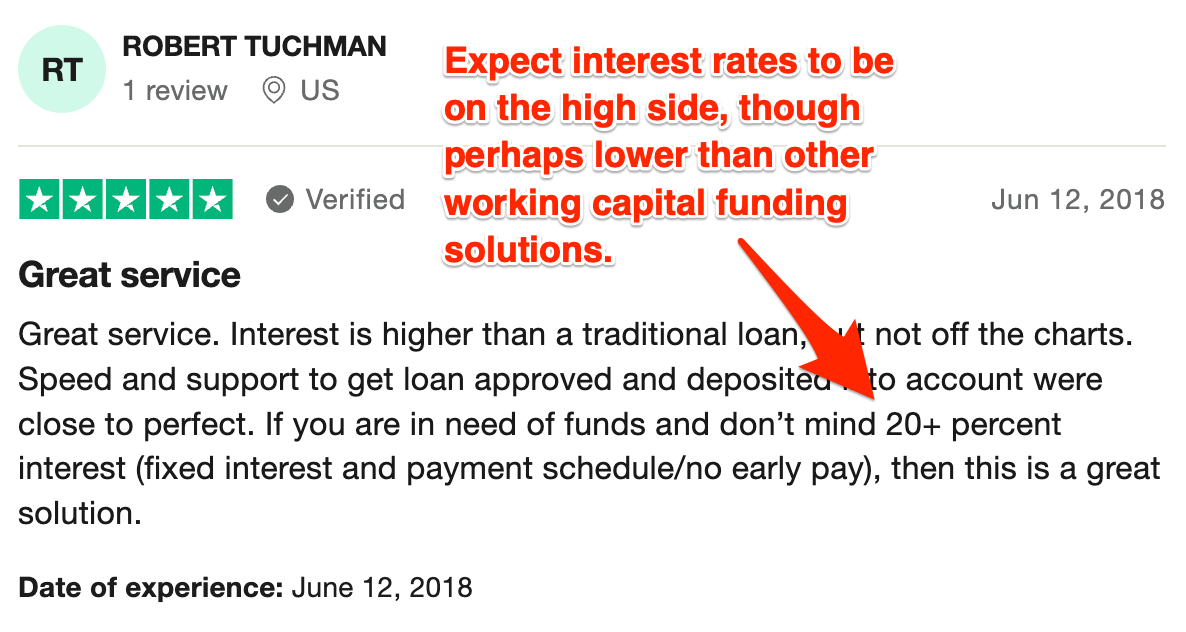
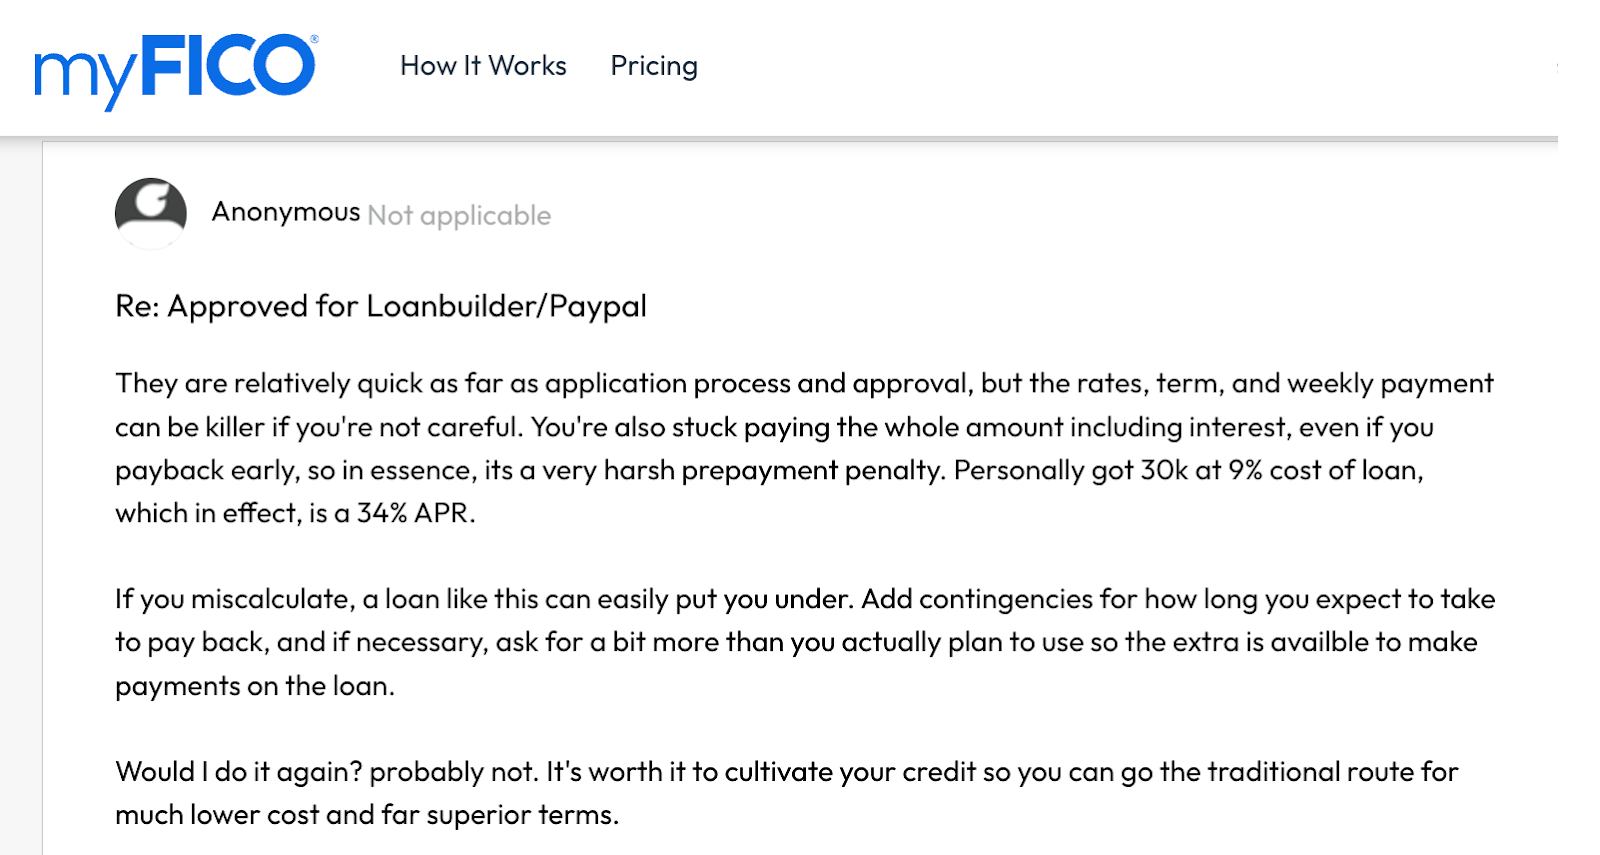
However, since this is a working capital-style loan, you should expect interest rates higher than you would get via, say, your business credit union. Still, they may be lower than other working capital solutions. 

PayPal Loan Builder interest rate

The specific amount of the Total Loan Fee varies based on: 

  1. The loan amount
  2. Repayment term
  3. Financial risk

LoanBuilder Loans do not have additional fees such as late fees, early repayment fees, or processing fees—The Total Loan Fee is the primary cost associated with borrowing and is included in your repayment schedule.

Paypal loanbuilder review

To see your LoanBuilder cost, you’ll need to complete the loan application process and review the personalized terms.

Recommended: 3 Best Credit Unions for Small Business Banking

How Does PayPal LoanBuilder Loan Work? 

LoanBuilder from PayPal offers a pretty simple approach to business financing, providing you with a customizable loan experience tailored to your business needs. 

With LoanBuilder, you have the freedom to: 

  • Access funds quickly
  • Repay with clarity
  • Benefit from straightforward terms 

Let’s delve into the key features that will help you decide if LoanBuilder is the best choice for your business funding.

You might also like: A Deep-Dive National Funding Review: Should You Accept an Offer? 

1. Apply With No Impact to Your Credit

PayPal Loan Builder application

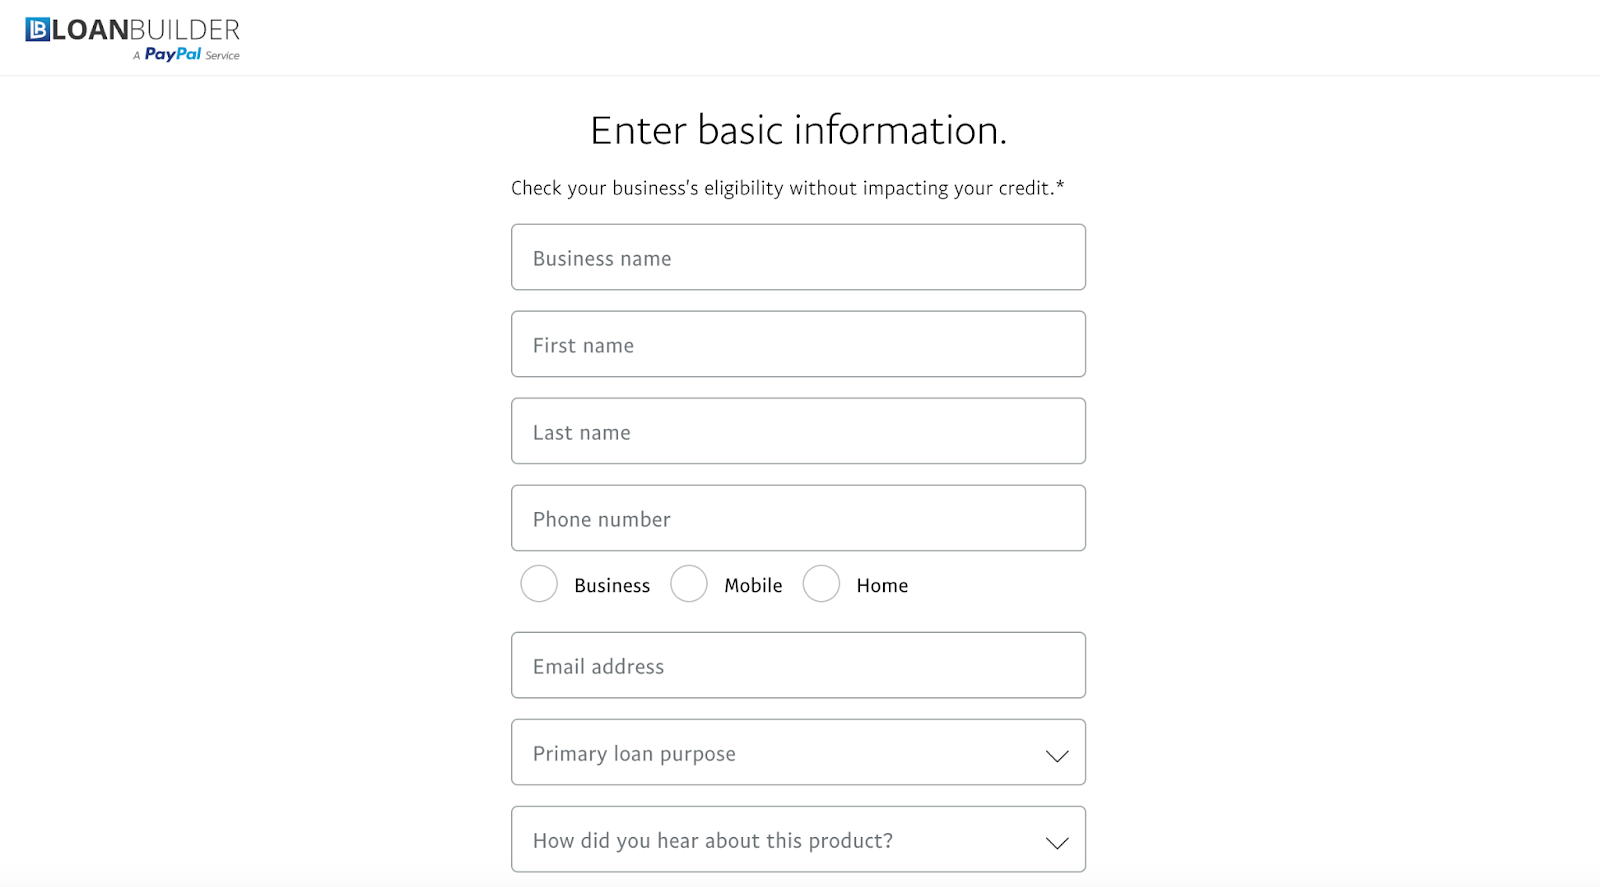
The PayPal LoanBuilder “application” is pretty straightforward. The questionnaire asks you for contact information, how you plan to use the funds, how you heard about the loan, business location, and business details. 

Details to have on-hand about your business include: 

  • Legal business name & DBA (if applicable)
  • Business address & website address
  • Entity type & state of incorporation
  • Annual revenue
  • Business start date
  • Number of employees
  • Industry & sub-industry
  • Percentage of ownership 

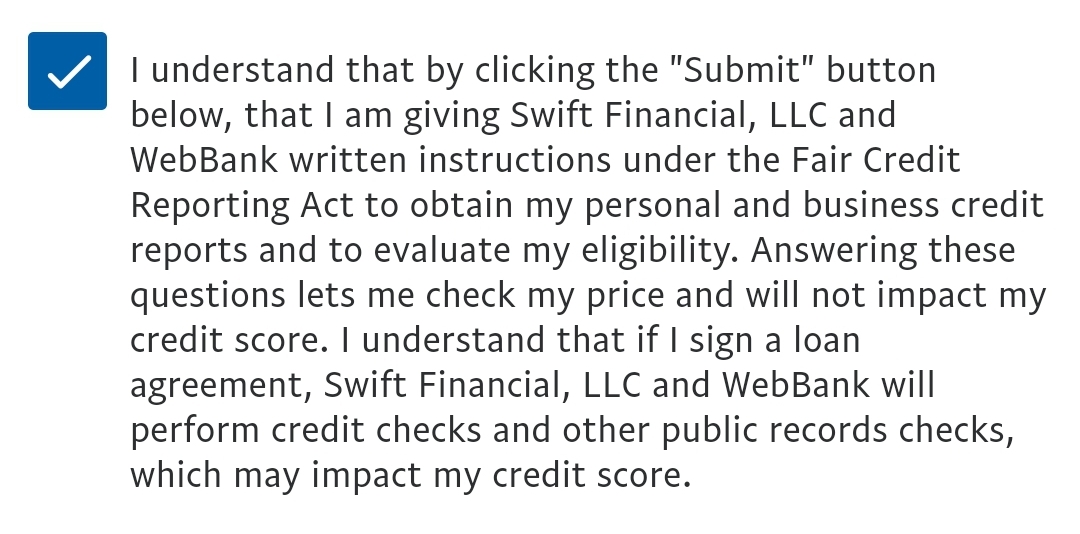
The application also asks for your Social Security Number and Employer Identification Number. Luckily, they do a soft inquiry into your personal credit for pre approval, which won’t negatively impact your credit score. 

PayPal Loan Builder soft inquiry

However, you will probably have to approve a hard pull for final approval. 

PayPal Loan Builder Hard Inquiry

Don’t move forward with that until you’re absolutely sure you want this loan.  

You might also like: Here’s How to [Actually] Get Business Credit With Just an EIN +More Options 

2. “Customizable” Funding

PayPal LoanBuilder Customized Loan

LoanBuilder advertises a “customizable” loan—This makes it sound as if you might get to choose your amount, terms, and rate, which would be pretty exciting. 

However, that’s not a realistic way to think about lending; lenders need to assess the financial risk before approving any type of financing. 

Still, after you’re pre-approved for a loan, you can choose your loan amount and repayment term. Your loan fee percentage will increase as your terms are extended. So, the longer you give yourself to pay off the loan, the higher your Total Loan Fee. 

If you do opt for this loan, consider giving yourself some extra time to pay it just in case something unexpected occurs, as you could be charged penalties for failing to pay on-time.  

3. Fixed-Fee Loan

PayPal Business Loan Builder

When you take out a LoanBuilder Loan, you won’t have any upfront fees deducted from the loan amount you receive. Instead, the cost of borrowing—the single fixed fee, known as the “Total Loan Fee”—is spread out and paid gradually over the entire duration (life) of the loan.

Here’s a breakdown of what this means:

  • When you receive the loan amount, the full sum is deposited into your business bank account without any immediate deductions for fees or charges. This ensures that you have access to the entire loan amount upfront to use for your business needs.
  • The cost associated with borrowing the money is represented by a single fixed fee—This fee is agreed upon and disclosed at the time of loan approval; it does not change over the course of the loan.
  • Rather than paying a fee upfront or separately, it is integrated into your loan repayment schedule. Each time you make a repayment towards your loan (typically on a weekly basis), a portion of that payment goes towards covering the Total Loan Fee. This fee is gradually paid down along with the principal amount of the loan.

By structuring the loan this way, you get clarity on the total cost of borrowing from the outset, and you can plan your repayments knowing how much will be allocated towards the loan principal and how much towards the fixed fee. 

4. Fast Access to Funds

PayPal Builder Loan

The LoanBuilder lending process is designed to be fast… 

First, when you check your eligibility, it’s done through a quick online questionnaire. This initial eligibility check does not involve a hard inquiry on your personal credit report, which means it won’t affect your consumer credit score—This is helpful because you can explore loan options without worrying about potential negative impacts on your credit rating.

If your LoanBuilder Loan application is approved, the funds are transferred directly to your business bank accoun