• Home
  • Free Funding Guide
  • What We Offer
    • Products
    • Services
    • Free Guide
  • About Us
  • Contact
  • Sign Up

  • Ask Joe Any Question!
  • Business Credit Cards
  • Business Line of Credit
  • Topics

6 Best 0% APR Business Credit Cards to Check Out 

By Joe

0 apr business credit cards

As a business owner, there’s no end to how you can use credit to grow your business. But, one of the downsides to using credit versus cash is the fact that it can cost you. If you fail to pay credit in full each billing cycle, annual percentage rate (APR) interest can add up fast—But, not if the APR is 0%. 

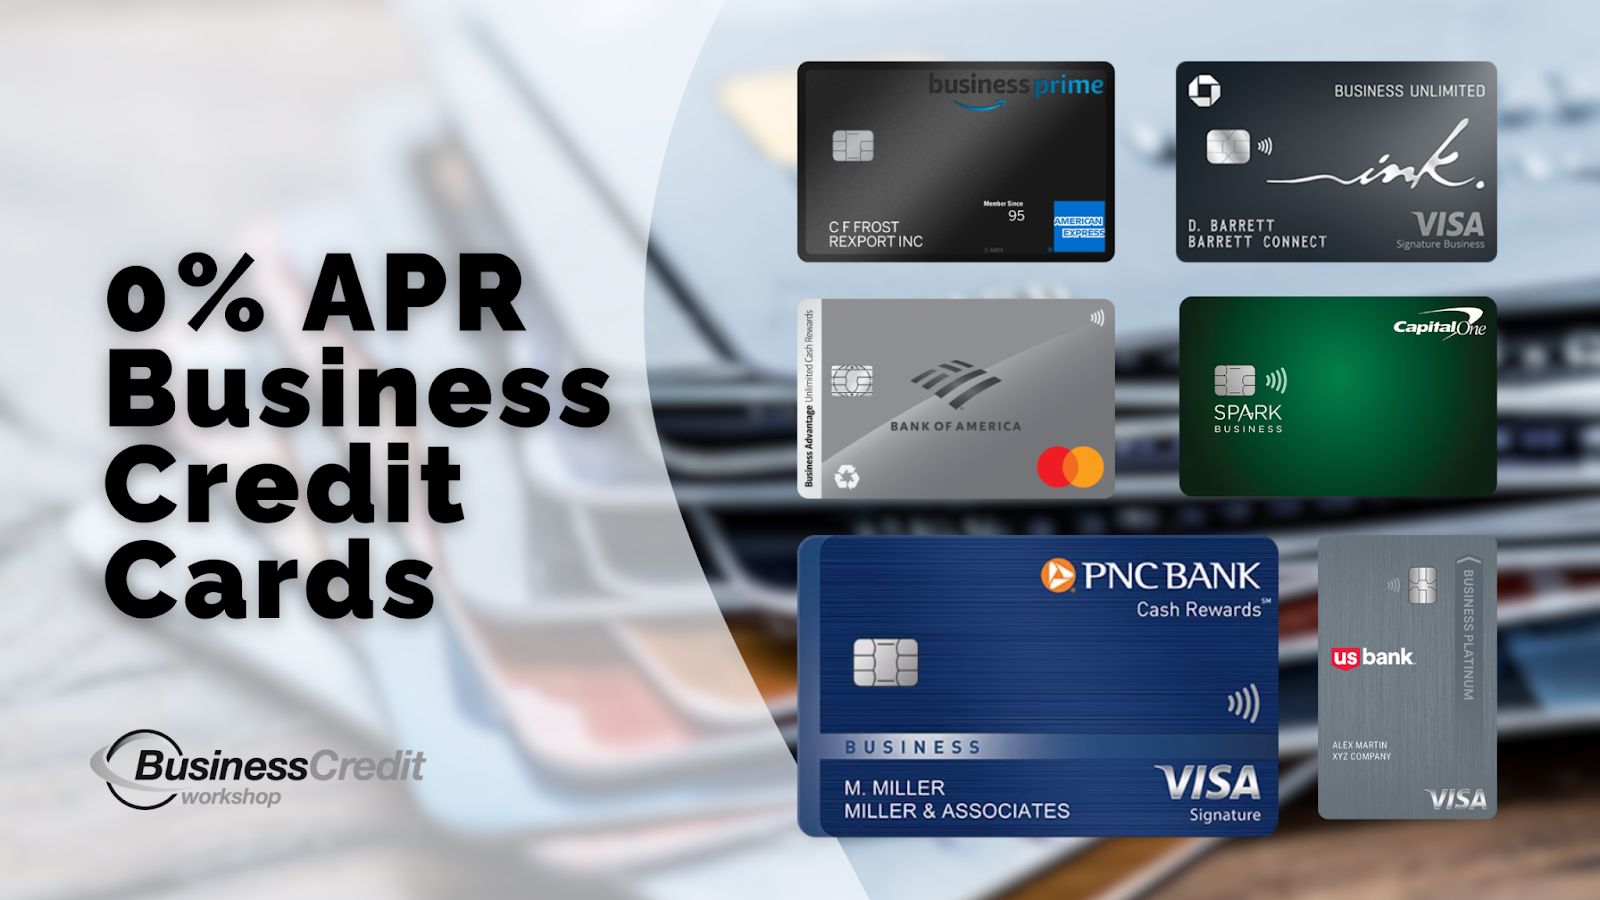
0% APR business credit cards can save you a ton of interest, if used responsibly. But, where can you find them? There are needles in a haystack with no interest ever, and others you can leverage at 0% introductory rates. Simply put, here are the top business credit cards with 0% APR that I know of right now. 

This is what’s in store: 

  • What is a Good APR for a Business Credit Card?
    • Can You Get a Credit Card with 0% APR?
  • The Best Business Credit Cards With 0% APR
    • 1. PNC Cash Rewards Visa Signature Business
    • 2. U.S. Bank Business Platinum Card
    • 3. Capital One Spark Business 1.5% Cash Select
    • 4. BofA Business Unlimited Cash Rewards
    • 5. Chase Ink Business Unlimited
    • 6. Amex Amazon Business Prime
  • Frequently Asked Questions
  • Final Thoughts

Now, let’s roll!! 

What is a Good APR for a Business Credit Card? 

Generally speaking, the lower the APR on a business credit card the better — this is if you plan to carry a balance. The lower the rate, the less you’ll pay. Think of it like this: With credit cards, you’ll be charged interest on any money that you owe at the end of a billing cycle. 

So, if you spend $1,000 on your credit card, and you only pay $100 at the end of the month, you will still owe $900 to the card issuer. The issuer will charge interest on that $900. The lower the interest rate/APR the less you will pay. 

According to data collected by the Federal Reserve, the average interest rate on credit cards issued by commercial banks was 21.47%, which increases over time – So, anything lower than this might be considered a “good” APR. However, this doesn’t account for cards issued by credit unions nor separate business products from those issued to consumers. 

Keep in mind, if you pay the balance on your business cards in full each month, you won’t have to worry about APR. 

You might also like: 3 Best Credit Unions for Small Business Banking in 2024 

Can You Get a Credit Card with 0% APR?

You can absolutely get a credit card with no annual interest rate—Both 0% APR business credit cards and 0% APR consumer credit cards can be found on the market. 

In most cases, when a business credit card comes with no annual fee, this is an introductory rate…A 0% introductory rate means that you will pay no interest for a specified period, which is usually 6, 12, 18, or 24 months. After this, the interest rate will revert back to its normal rate. At this point, you will be charged the full interest for any balance still owed, no matter when the debt accrued. 

Another business financial product that people sometimes refer to as a business credit card is a corporate card. Many corporate cards come with 0% APR, and several even offer cash back on purchases. However, a corporate card is not technically a business credit card.  

You might also like: Corporate vs Business Credit Card: What’s the Difference? 

The Best Business Credit Cards With 0% APR

Let’s take a look at the top business credit cards you can get today with 0% APR. 

Note: Credit cards rates can vary – always check with the card issuer before you apply. 

You might also like: 6 Best Business Credit Cards for Entrepreneurs: Fuel Your Growth 

1. PNC Cash Rewards Visa Signature Business
0 apr business credit cards no annual fee

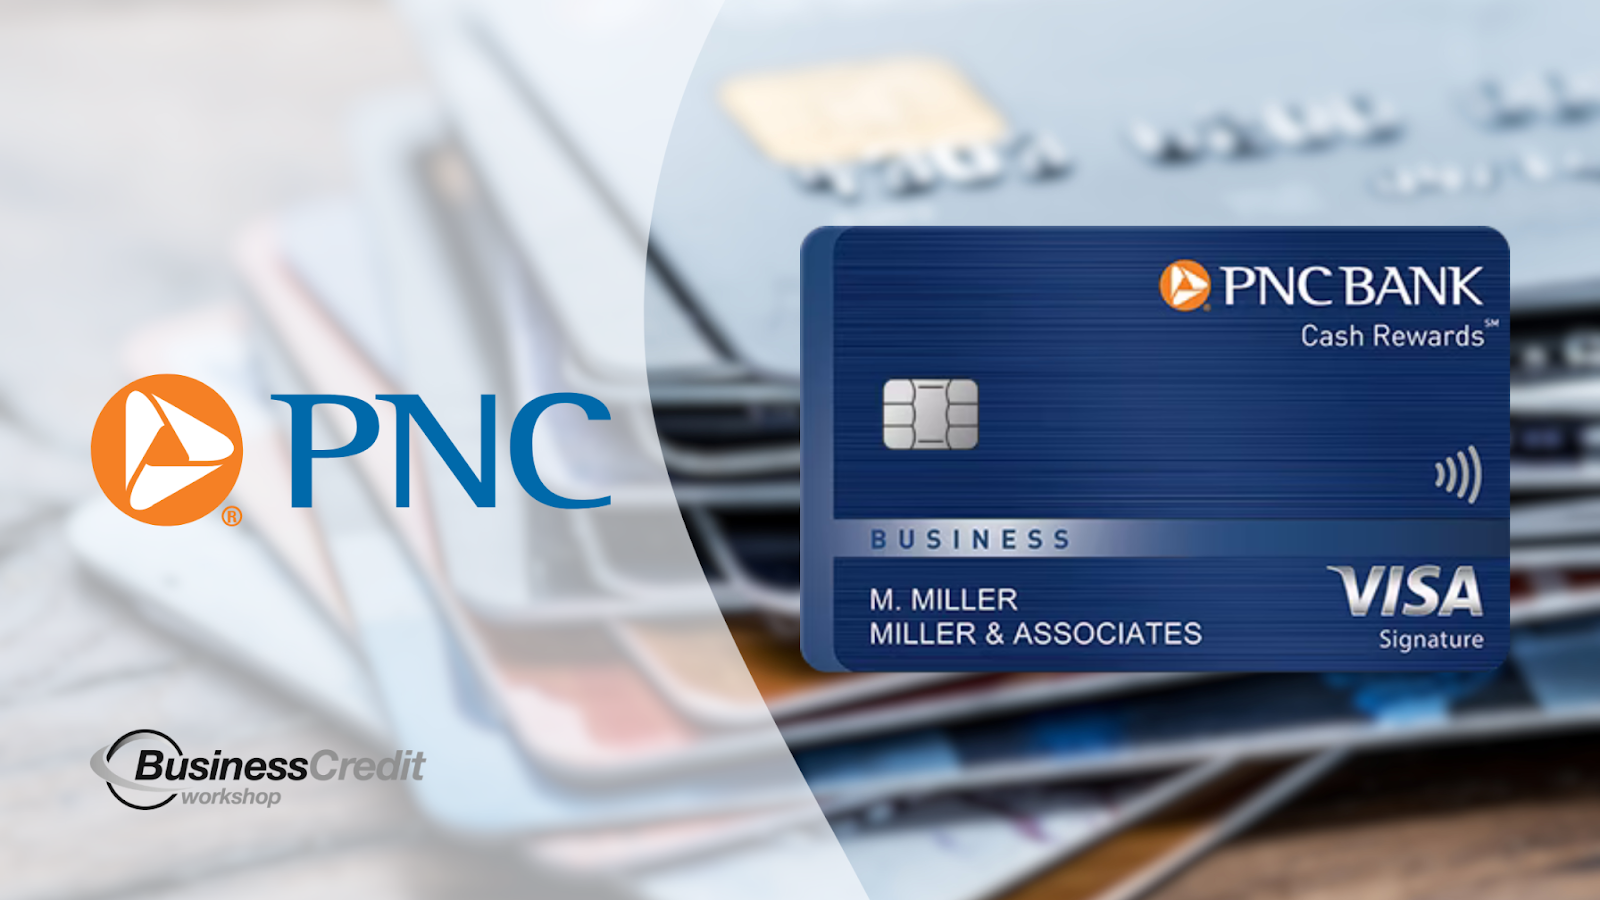
The PNC Cash Rewards Visa Signature Business Credit Card offers a $400 bonus when you open a new account and make at least $3,000 in qualifying purchases within the first three billing cycles—It also features an introductory 0% APR for the first 9 billing cycles (9 months), with a variable APR of 19.24% to 27.24% afterward. 

With this card, you earn 1.5% cash back on net purchases, with no limits on your earning potential. You can easily manage your account online with various tools provided. Additionally, as a Visa Signature cardholder, you’ll enjoy travel benefits and purchase protection.

There’s no annual fee, and for balance transfers, you’ll pay either $5 or 3% of the transfer amount, whichever is greater. Cash advance fees are either $10 or 4% of the advance amount, with a maximum fee of $75. Late payment and over-the-credit-limit fees may apply.

A noteworthy perk: if you have a PNC business checking account, using this credit card could help offset your monthly maintenance fee.

Recommended: PNC Bank Business Credit Card Review & Comparison 

2. U.S. Bank Business Platinum Card

u.s. bank business credit card

The U.S. Bank Business Platinum Card offers a 0% introductory APR on purchases and balance transfers for 18 billing cycles (a year and a half), making it ideal for managing expenses and consolidating debt. After the introductory period, a variable APR applies.

This card comes with a low annual fee and provides cards for both you and your employees–This U.S. Bank business credit card gives you access to a dedicated domestic servicing center with 24/7 customer support, which ensures assistance whenever you need it.

With Visa Spend Clarity™, you can track spending and manage expenses more effectively. The card has received honors, including being named Best 0% APR Credit Card by WalletHub and Best Business Cash Back Card for Gas by Forbes.

Furthermore, the U.S. Bank Business Platinum Card allows you to pay over time with U.S. Bank ExtendPay® Plan, and new cardmembers can take advantage of a $0 fee offer on ExtendPay Plans opened within the first 60 days after account opening.

You might also like: What are the Best Unsecured Business Credit Cards for Startups? 

3. Capital One Spark Business 1.5% Cash Select
best 0 apr business credit cards

The Spark 1.5% Cash Select credit card from Capital One is tailored for businesses with good credit. It offers unlimited 1.5% cash back on all purchases, with no category restrictions, and an additional unlimited 5% cash back on hotels and rental cars booked through Capital One Travel. 

There’s a $0 annual fee, and for the first 12 months, there’s a 0% introductory APR, followed by a variable APR ranging from 21.24% to 29.24%, based on your creditworthiness.

The card provides benefits like: 

  • Automatic payments
  • $0 fraud liability
  • Year-end summaries for simplified budgeting and tax preparation
  • Account managers for assistance with purchases and payments
  • Purchase record downloads in various formats
  • Virtual card numbers for enhanced online security

The application process takes about 10 minutes, and decisions are typically made in seconds. 

To apply, you’ll need to provide information about all business owners, including legal names, addresses, and Social Security Numbers, as well as details about your business, such as its legal name, address, and tax identification number (EIN).

You might also like: What are the Best Business Credit Cards for Travel? 

4. BofA Business Unlimited Cash Rewards

bank of america business credit card

The BofA Business Unlimited Cash Rewards credit card by Bank of America offers a $300 online statement credit bonus after spending at least $3,000 within the first 90 days of opening an account. It allows you to earn unlimited 1.5% cash back on all purchases, with no annual cap and no expiration on rewards. 

Moreover, if you have a Bank of America business checking account and qualify for the Preferred Rewards for Business Platinum Honors tier, you can earn up to 75% more cash back, up to an unlimited 2.62% cash back on purchases.

This card features flexible redemption options, including depositing cash rewards into your Bank of America checking or savings account, receiving a statement credit, or getting a check mailed to you. 

There’s no annual fee, and it offers a 0% introductory APR on purchases for the first 9 billing cycles, followed by a variable APR ranging from 18.49% to 28.49%—The card provides various features to manage cash flow, online and mobile access for account management, travel and emergency services including travel accident insurance, free access to business credit scores, security measures such as zero liability protection and fraud monitoring. 

Notable: It also offers Balance Connect® for overdraft protection when linked to a Bank of America business checking account.

Recommended: What is the Best Bank of America Business Credit Card You Can Get? 

5. Chase Ink Business Unlimited
Best business credit cards 0 apr

The Ink Business Unlimited® Credit Card from Chase offers a substantial new cardmember bonus of $750 cash back after spending $6,000 on purchases within the first 3 months of opening an account. With no annual fee, this Chase business credit business card allows you to earn unlimited 1.5% cash back on every purchase made for your business.

For the first 12 months from account opening, there’s a 0% introductory APR on purchases, which then transitions to a variable APR of 18.49%–24.49%. You can redeem your rewards on this card for cash back, gift cards, travel, and more through Chase Ultimate Rewards®.

Employee cards come at no additional cost and allow you to set individual spending limits while helping you earn rewards faster. Additionally, until March 2025, you can earn a total of 5% cash back on Lyft rides with your Chase Ink Unlimited card, which includes an extra 3.5% on top of the 1.5% you already earn on travel.

Chase also offers referral incentives for existing cardholders, allowing them to earn up to 200,000 points per year by referring businesses for any Chase Ink® Credit Card.

You might also like: Chase Ink Business Preferred Credit Card: A Deep Dive Analysis 

6. Amex Amazon Business Prime 

0% business credit card

The Amazon Business Prime Card, offered by American Express, comes with a $0 annual fee and offers a $125 Amazon.com Gift Card upon approval. It features a variable APR ranging from 19.49% to 27.49% on purchases, based on creditworthiness.

This card rewards your business with:

  • 5% cash back or 90-day terms on select U.S. purchases at Amazon Business, AWS, Amazon.com, and Whole Foods Market, with a cap of $120,000 in purchases each calendar year with eligible Prime Membership, and 1% back thereafter.
  • 2% cash back on U.S. purchases at restaurants, gas stations, and wireless phone services purchased directly from service providers.
  • 1% cash back on all other eligible purchases.

Additional benefits include Amazon Business Enhanced Data Views for detailed expense tracking, Amazon Shop with Points for flexible reward redemption, and no foreign transaction fees.

You can manage expenses efficiently with features like Account Manager, Employee Cards with spending limits, and integration with QuickBooks® for auto-expense categorization – Moreover, cardholders receive baggage insurance, car rental loss and damage insurance, extended warranty protection, purchase protection, and access to Amex Offers for additional rewards.

Recommended: Amazon Business Prime Credit Card: Full Review +How to Get One  

Frequently Asked Questions

What credit score do you need for 0% APR? 

Typically, you need a good to excellent credit score (usually 670 or higher) to qualify for a 0% APR offer on a credit card. Each card issuer has their own underwriting and qualification terms. 

Why 0% APR offers might not be good for your credit? 

0% APR offers can impact credit negatively if not managed properly. They may encourage overspending, leading to higher debt levels. Additionally, opening new credit accounts can temporarily lower your credit score due to inquiries and reduced average account age.

Is 23% APR high for a credit card? 

Yes, a 23% APR is slightly above the average for credit card APRs, which was around 21.47% according to Federal Reserve data.

Is 29% APR high? 

Yes, a 29% APR is significantly higher than the average credit card APR, indicating high-risk lending.

Final Thoughts

Leveraging 0% APR business credit cards can be a savvy financial move for entrepreneurs – It provides a valuable opportunity to manage expenses without accruing interest. With a clear understanding of what constitutes a good APR for a business credit card, the availability of 0% APR cards, and the top options currently on the market, you’re better equipped to make informed decisions tailored to your business needs. 

Remember to consider factors like introductory periods, ongoing APR rates, and additional perks and benefits when selecting the right card for your business. With careful management and responsible use, these cards can serve as valuable tools for financial flexibility and growth.

Do you want to learn how to obtain up to $100K in business credit in as few as 30 days? Join Business Credit Workshop today!
Can You Open a SoFi Business Account? SoFi at Work Review

By Joe

SoFi Business Account SoFi at Work

So, you’re looking to open a business account…No doubt SoFi® has come up on your radar, especially if you already have a personal account with them. Maybe you’re launching a new company or you’ve been operating awhile and need financial products. 

Either way, you’re here because you wanna know what business services you can get. Well, SoFi® doesn’t offer traditional business checking or savings accounts, but they do have a cool product called SoFi at Work®. And, they offer business funding — Let’s talk about both. 

This is what’s in store: 

  • What is SoFi®?
    • Company Overview
  • SoFi at Work® Features
    • 1. Student Loan Verification & Repayment
    • 2. 529 College Savings Program
    • 3. Emergency Vault™ Savings
    • 4. Education Assistance Benefits
  • SoFi® Small Business Funding
    • Application Requirements
  • Frequently Asked Questions?
  • Final Takeaway

Now, let’s get poppin! 

What is SoFi®? 

SoFi business account

SoFi® is a bank known for its personal checking, savings, and loans. With personal loans ranging from $5,000 to $100,000 and fixed rates from 8.99% APR to 29.49% APR, members can consolidate high-rate debt or fund projects. But, the institution offers a much wider variety of financial products.

SoFi® personal loans come with no fees—no origination fees, late fees, or prepayment penalties—and flexible repayment terms from 2 to 7 years. Plus, with options for student loan refinancing, private student loans, mortgages, investments, insurance, and more, SoFi® provides broad solutions to meet a spectrum of financial needs. 

Today, we’re going to focus on their business offers: SoFi at Work® and small business funding.  

You might also like: An Unbiased LendingClub Review for Borrowers and Investors 

Company Overview

SoFi business account review

Before we explore how you can leverage SoFi® as a business owner. Let’s learn a bit more about the company itself. 

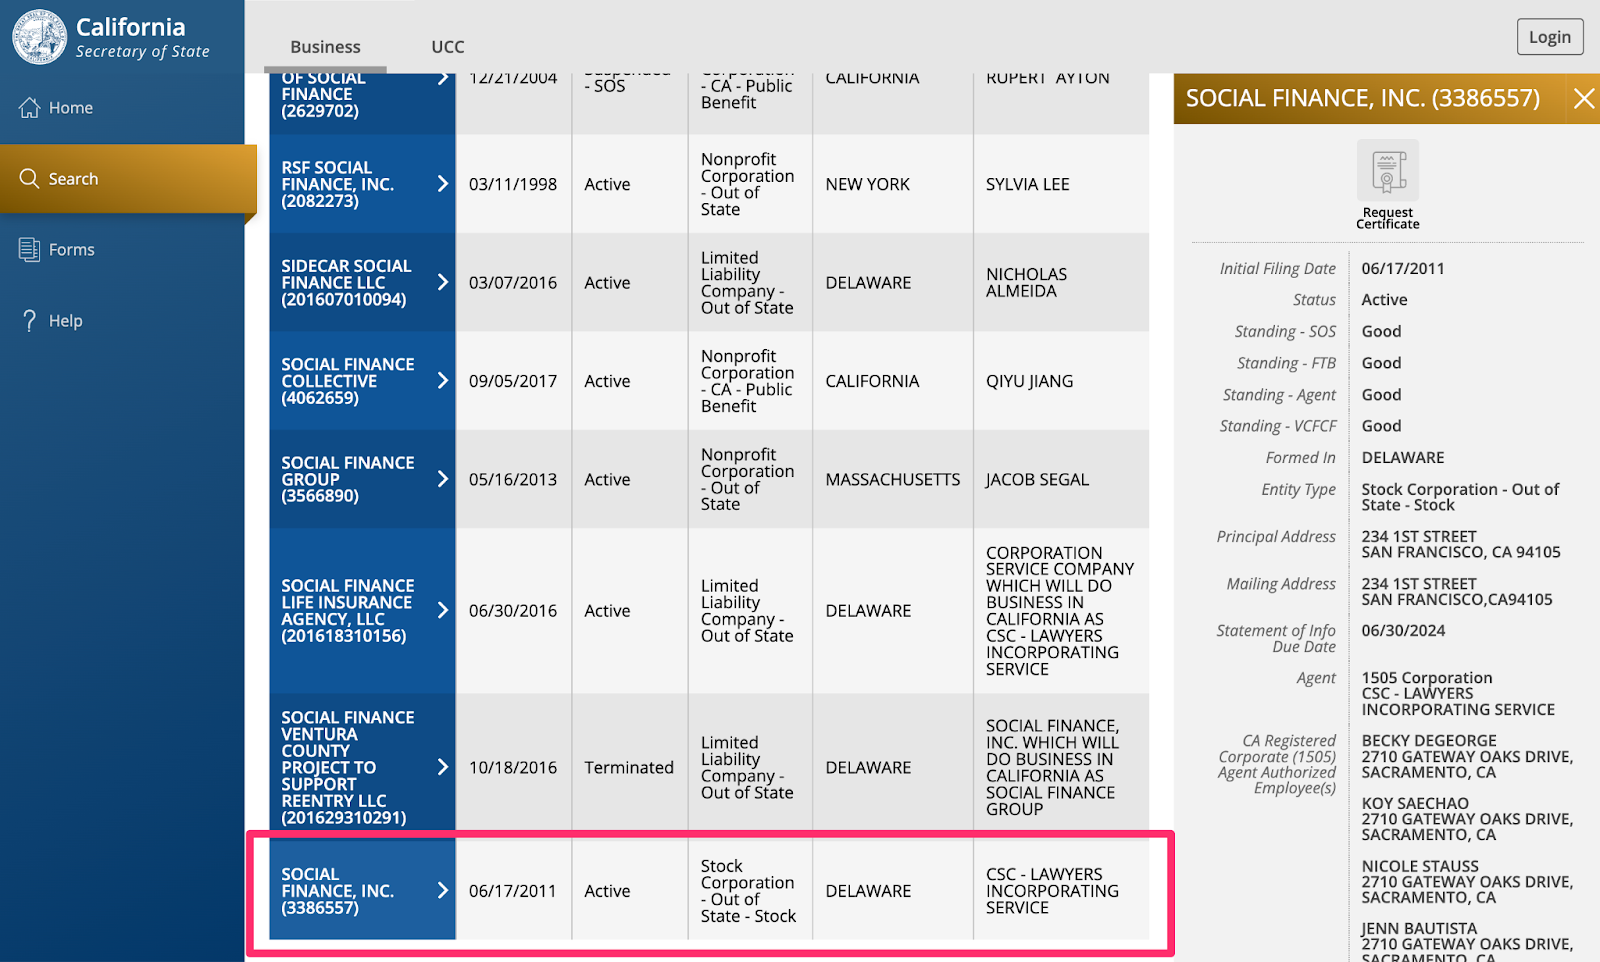
SoFi®, aka Social Finance, Inc., is a San Francisco-based, public, for-profit company with headquarters scattered across the U.S. The company was founded in 2011 by Mike Cagney, Dan Macklin, James Finnigan, and Ian Brady. At the time, these guys were graduate students at Stanford. 

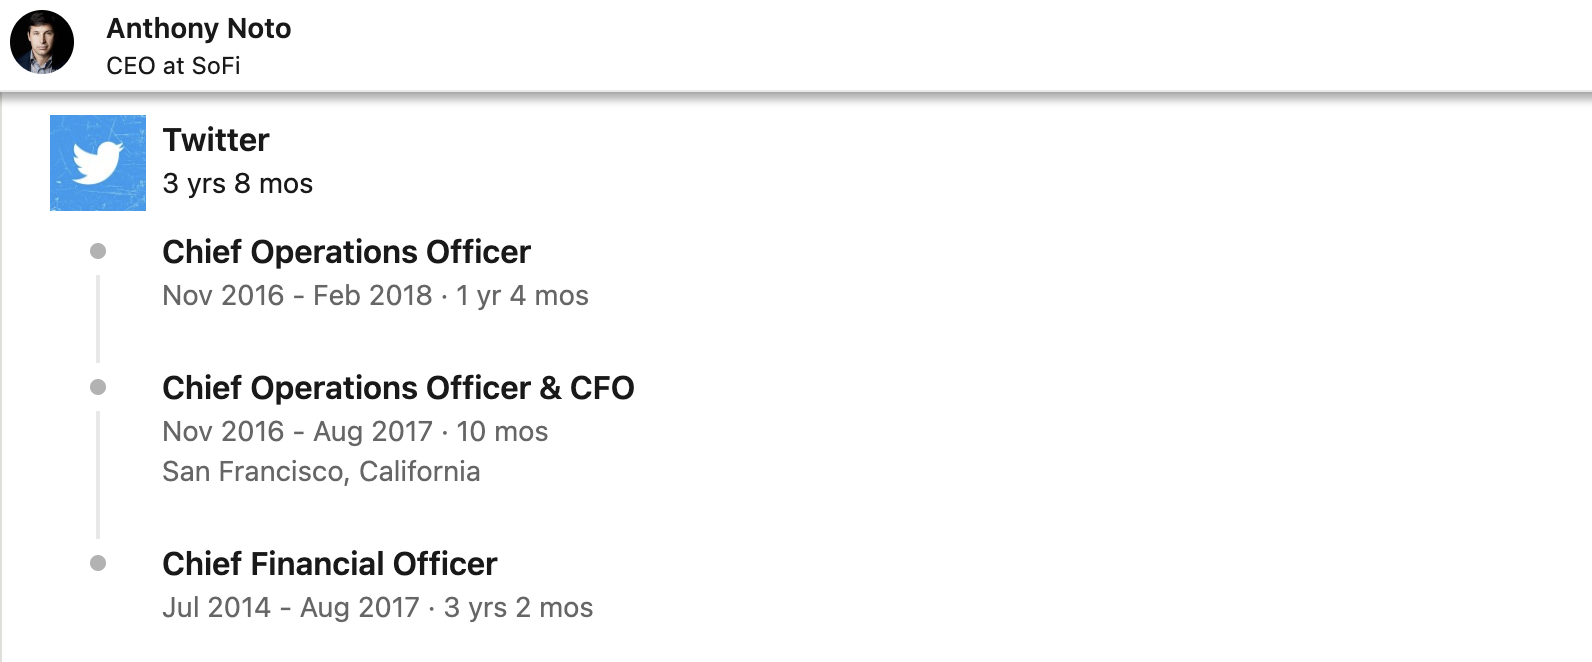
The current CEO of SoFi® is Anthony Noto, who served as the Chief Operations Officer of Twitter until 2018. Before that, he was the Co-Head of Global TMT Investment Banking at Goldman Sachs—The man is experienced in the right ways. 

Is SoFi a real bank account?

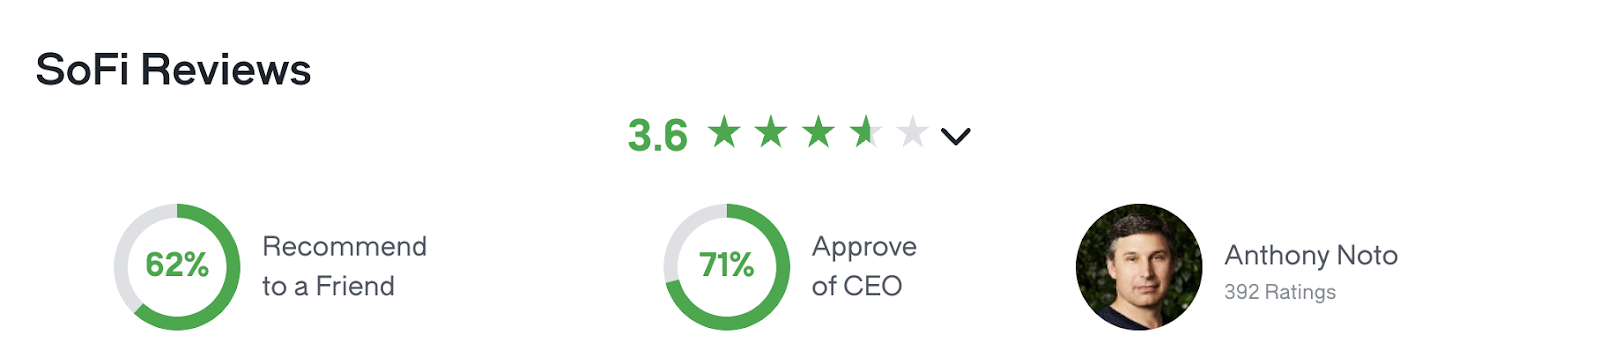
According to Glassdoor, a majority of employees are satisfied with the company. 62% of employees would recommend them to a friend, and 77% approve of Noto as the CEO. While this isn’t the most enthusiastic rating I’ve seen on Glassdoor, at 3.6 stars, the team seems to have a generally positive experience in-house…this says a lot.

How credible is SoFi?

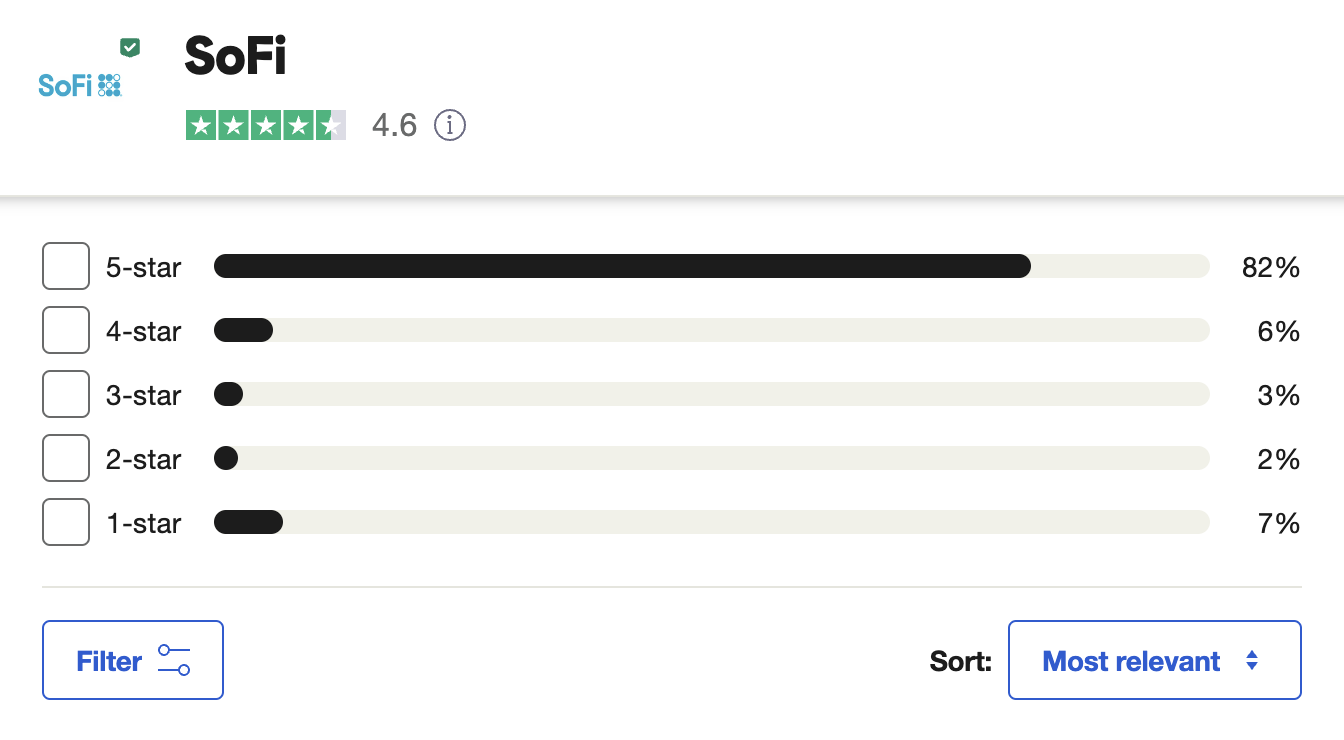
SoFi® is verified with a 4.6-star rating on Trustpilot, which is impressive for a financial offer. 82% of the more than 8,104 reviewers give the bank 5 stars. According to this, account holders are even more satisfied with the platform than staff, which is everything. 

Open a sofi business account

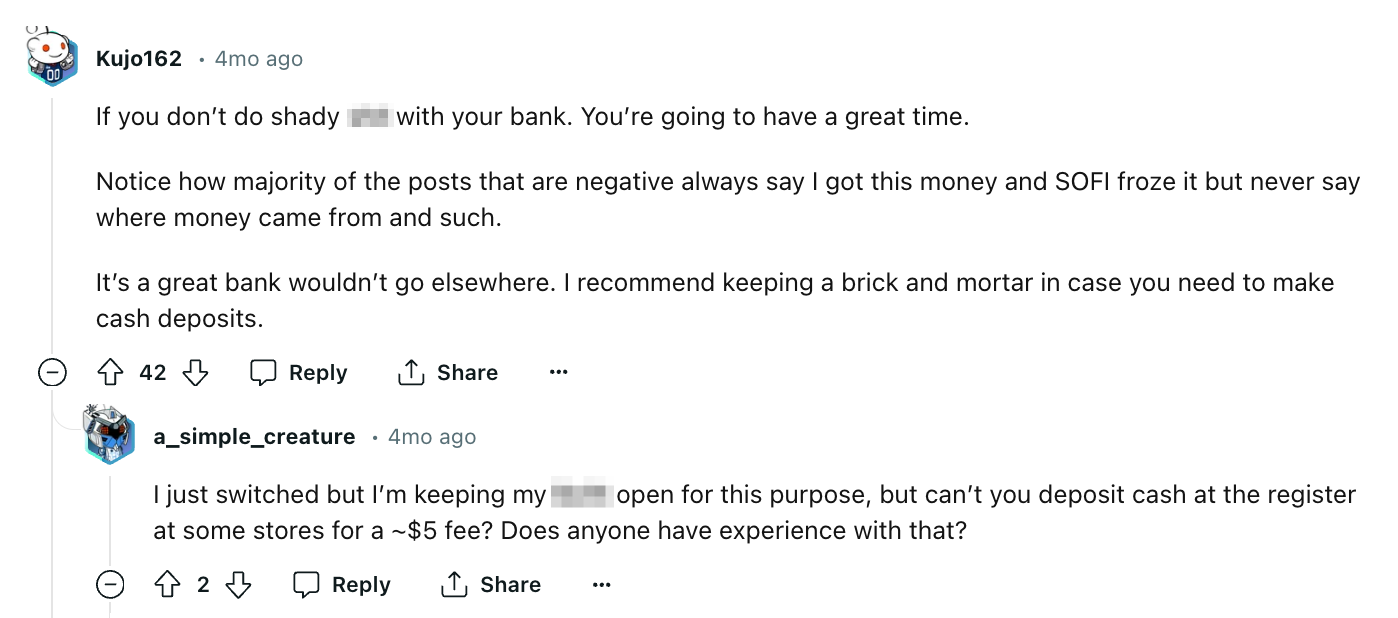
Some loyal members will go so far as to say the only people leaving negative reviews of SoFi® are those who may be doing shady trade with their account. But, one legitimate potential downside is that it’s an online-only bank, which usually infers limits on cash deposits. In sum, even Redditors have nice things to say. 

sofi business account reddit

Now, depending on how ethically-conscious you are, you may want to know that SoFi® filed a lawsuit against the Department of Education in March 2023. According to NASFAA, Their stance was that the Biden administration’s extended pause on student loan repayment was unlawful and caused harm to their business. However, they withdrew the lawsuit when the bipartisan ceiling debt deal was signed into place and a clear timeline for payment reopening was presented.  

All in all, I think SoFi® appears to be a great bank for personal financial products. But, I always recommend you do your due diligence before you sign-on to any offer. Now, let’s explore exactly what they can offer small business owners. 

You might also like: Here’s How to [Actually] Get Business Credit With Just an EIN +More Options 

SoFi at Work® Features

SoFi business account login

Again, SoFi® doesn’t offer business checking or savings accounts (yet). However, this may change in the future—one Reddit moderator for the company said that business banking is a common request and insinuated that the company might be mulling over the idea…But, they do offer something called SoFi at Work®. 

Is SoFi financially stable?

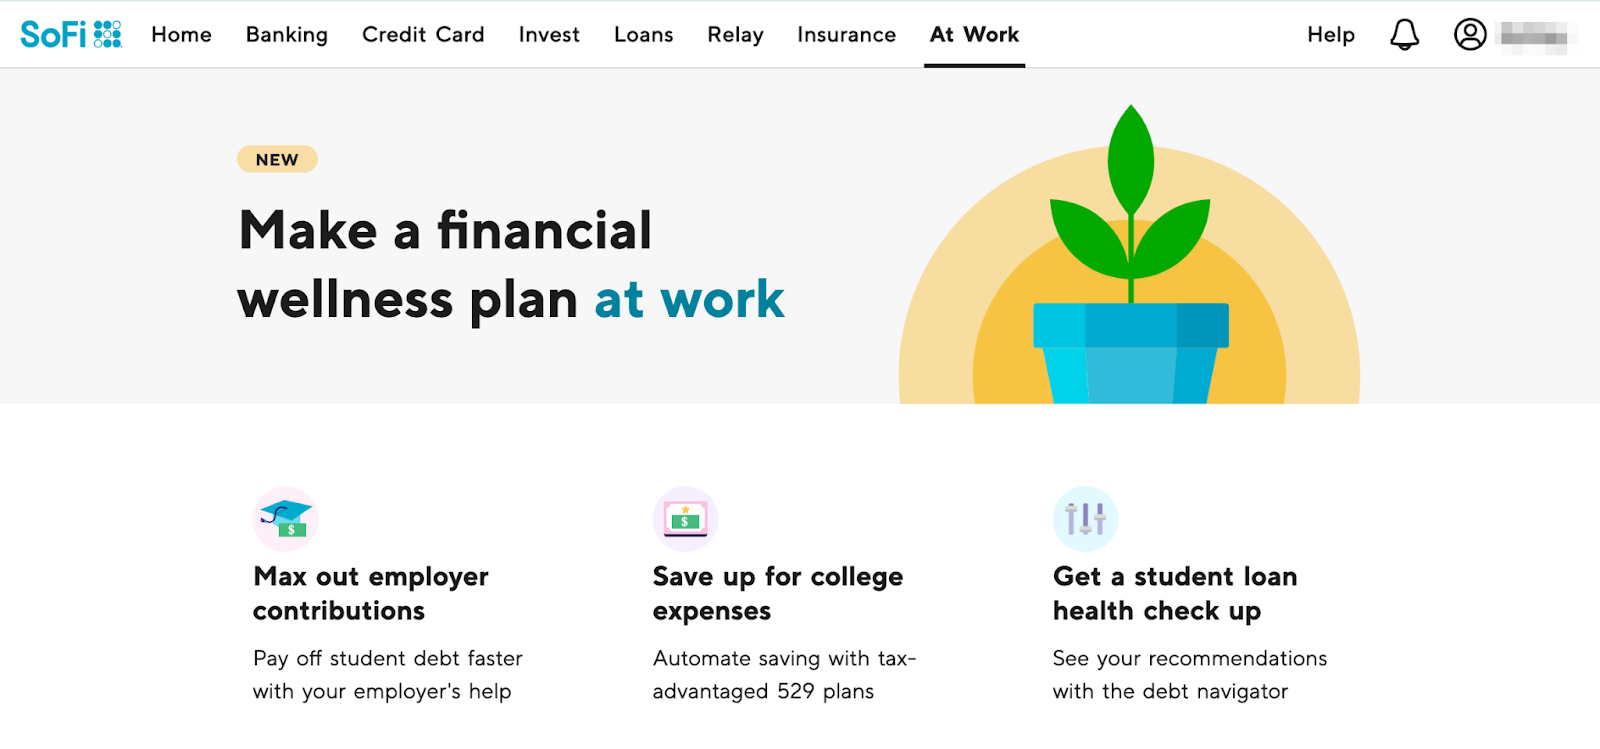
In a nutshell, SoFi at Work® is an employee benefits platform from SoFi®. 

As a business owner, SoFi at Work®  can be a valuable resource for your employees’ financial well-being. With this program, you can provide a range of perks to support your team in managing their finances. 

For starters, your employees can access various financial products like: 

  • 529 college savings 
  • Emergency savings 
  • Retirement products
  • Student loans 
  • Personal loans
  • Home loans

Moreover, SoFi at Work®, offers financial education resources and access to financial planners, giving your employees the tools they need to achieve financial freedom and reduce stress. The program also includes contribution benefits like student loan and 529 contributions, which can serve as attractive incentives.

And, they do it all in one dashboard — you can make it easier for your staff to save for education, plan for retirement, get financing, or prepare for unexpected expenses. 

By offering financial benefits, you can demonstrate your commitment to supporting your employees’ financial well-being, which can lead to workplace satisfaction and loyalty within your team. 

You might also like: Gusto Review: Let’s Really Evaluate This Famed Payroll Platform 

1. Student Loan Verification & Repayment

Sofi business account benefits

In mid 2023, SoFi at Work® rolled out a cool new thing called Student Loan Verification (SLV) to help you and your employees tackle student loan debt while still saving up for retirement. Basically, Congress passed SECURE 2.0 in 2022, which lets employers match student loan payments with contributions to retirement plans. 

So, SLV makes it super easy for you to link up those matching contributions with your employees’ loan repayments. It’s all about dealing with the impact of student loan debt on retirement savings, which has been a big issue lately. 

By teaming up with financial groups and record keepers, SoFi at Work® handles the nitty-gritty to make sure eligible loan payments are verified and retirement contributions are sorted. 

You might also like: Is the National Debt Relief Program Legit? The Honest Answer 

2. 529 College Savings Program  

Sofi business account opening

The SoFi at Work 529 College Savings Program offers a tax-advantaged investment opportunity for employees, demonstrating your commitment to supporting their families’ financial futures—By investing in a 529 plan, staff can potentially see greater gains over time while enjoying the benefit of federal tax-free earnings. 

The program provides a low-cost and hassle-free way for employees to save, with automatic payroll deductions and no extra administrative burden for you as the employer. With SoFi at Work handling the setup and management, including plan design and reporting, your team can easily link and contribute to existing 529 plans. 

You might also like: How to Raise Money for Real Estate Investment: A Beginner’s Guide 

3. Emergency Vault™ Savings 

sofi business savings account interest rate

The SoFi at Work® Emergency Vault™ is a comprehensive emergency savings program designed to alleviate financial stress for both you and your employees. It provides powerful financial tools, knowledge, and support to help employees build emergency savings effectively. 

With easy setup, automated processes, and stress-free administration managed by SoFi at Work, the Emergency Vault ensures a resilient workforce with reduced financial stress and improved mental well-being. Additionally, the program includes activity reporting for program evaluation and active engagement to enhance employee benefit awareness. 

4. Education Assistance Benefits

Sofi business savings account

The education assistance benefits platform by SoFi at Work ® offers a comprehensive solution for employers who want to support their employees’ educational needs. This platform consolidates various educational benefit and contribution programs into one user-friendly interface—this grants streamlined access for both employers and employees. 

With a focus on speed, cost-effectiveness, and compliance, the platform offers: 

  • End-to-end education assistance
  • Digital plan design
    Account administration

You can leverage SoFi at Work® to provide low-cost solutions for funding student debt, tuition expenses, and future education investments. 

SoFi® Small Business Funding 

sofi business account fees

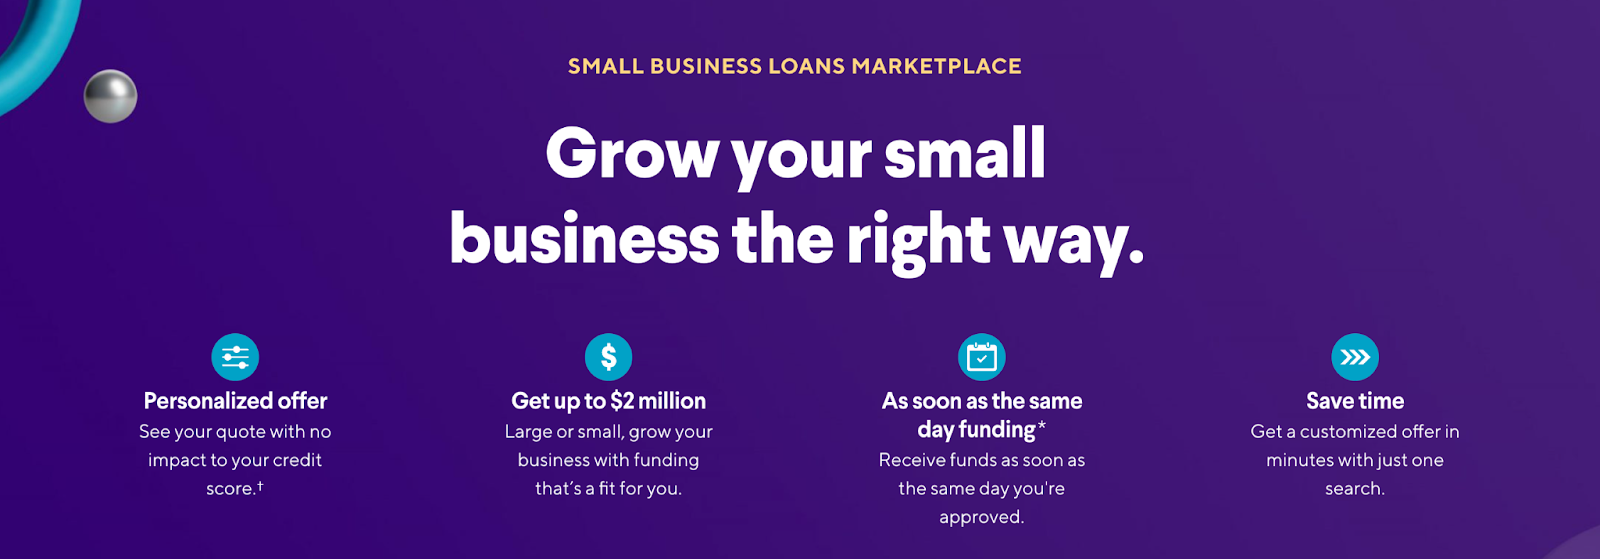
As a small business owner, SoFi’s® small business loans marketplace offers you a streamlined and efficient way to access the capital you might need to grow your business—You can easily see personalized loan offers without worrying about impacting your credit score, which allows you to explore your options freely. 

They provide convenient access to loans up to $2 million with same-day approval potential.  Terms and fees will vary based on the lender(s) you’re matched with. 

Business loan offers include: 

  • Equipment loans
  • Working capital
  • Payroll financing
  • Startup financing
  • Expansion loans 

With this type of loan, you typically pay a factor rate in place of an interest rate – these loans are typically much more expensive than traditional business loans in the long run. 

However, they are convenient. You can sometimes pay back factored loans as a percentage of daily sales. 

You might also like: No-Doc Business Loans: Get Funds Without Proof of Income 

Application Requirements 

SoFi business account requirements

When you apply for a loan through the SoFi® marketplace, the platform will ask for some basic contact information before they prequalify you (which should have no impact on your credit score). 

There will be a soft pull to your personal credit report during the application process. SoFi doesn’t seem to check business credit. 

Gather the following info before you apply: 

  • Name, address and contact info
  • Business name, address, and info
  • Type of business (sole proprietorship, LLC, etc.)
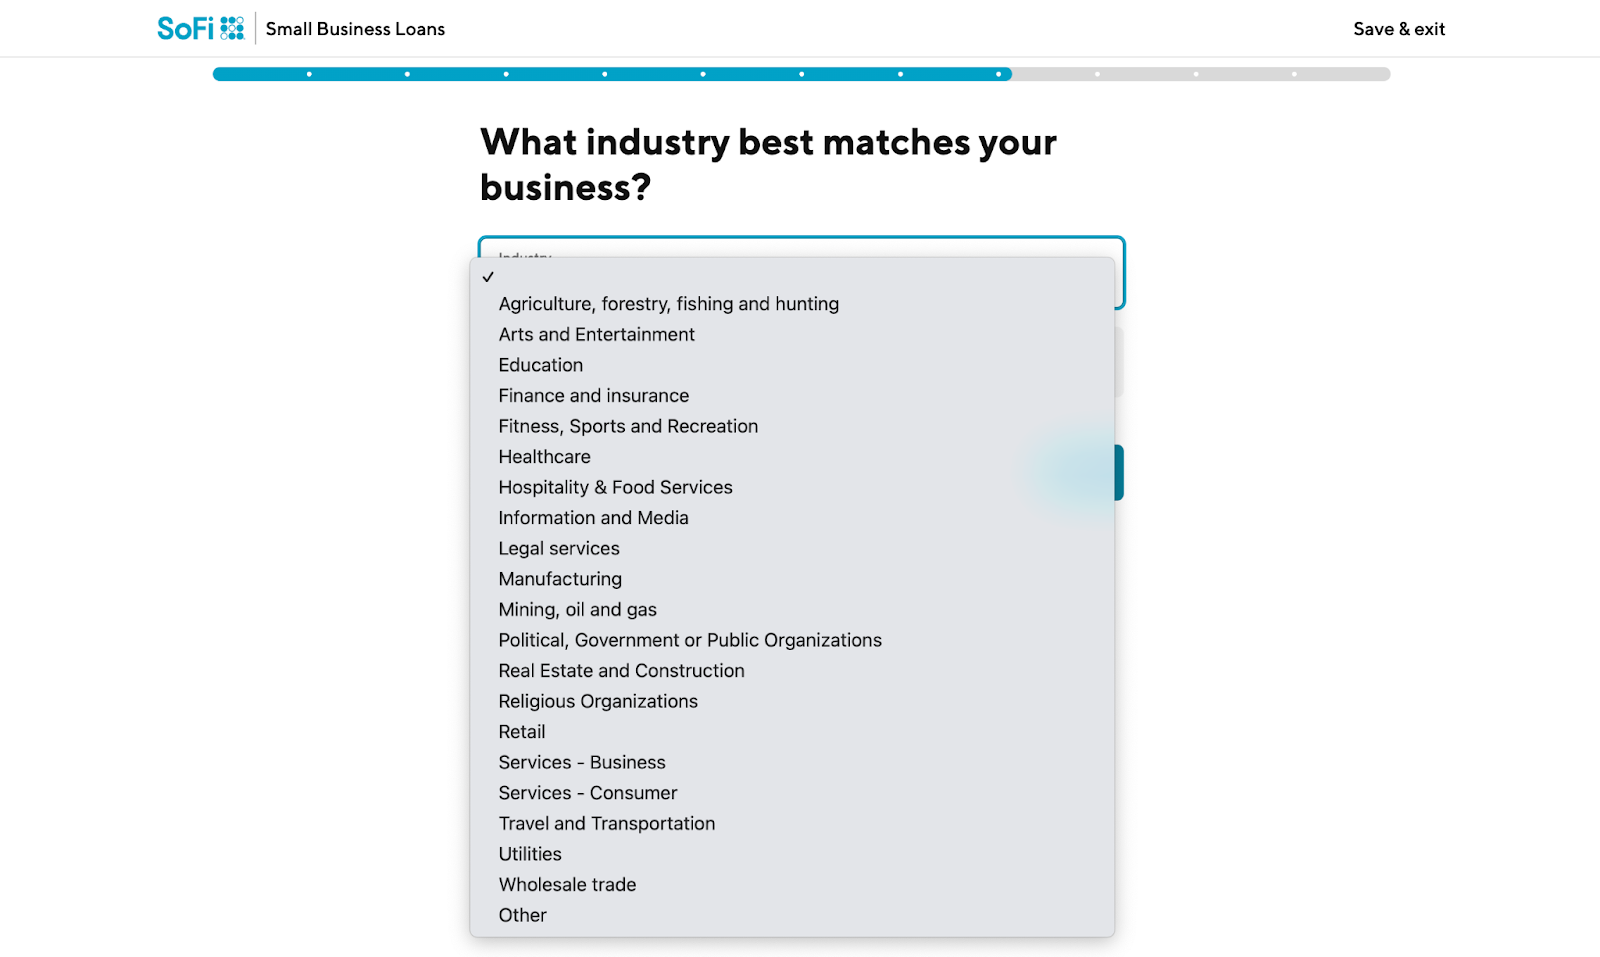
  • Business industry info
  • Credit score range

You will need to provide permission for access to your credit report, but this should be a soft pull. Once you’re matched with a lender, you’ll still have to apply (think of Credit Karma’s® referral program, but with business loan offers). And, this is when your actual FICO credit score will likely be pulled.   

You might also like: A Deep-Dive National Funding Review: Should You Accept an Offer? 

Frequently Asked Questions 

Is my money safe in SoFi Bank®?

Yes, your money is safe with SoFi Bank®—as safe as in any other bank. It’s FDIC-insured, offering protection for your deposits up to the maximum amount allowed by law.

What bank is SoFi® associated with?

SoFi® was granted a national bank charter by the Office of the Comptroller of the Currency (OCC) in January 2022. In February 2022, SoFi® acquired Golden Pacific Bancorp, the parent company of Golden Pacific Bank®.

Does SoFi® have a business account?

Yes, SoFi offers business accounts tailored for small business owners via SoFi at Work® (an employee benefits platform) and their business funding platform, Relay.™ They do not offer business checking or savings accounts. 

What is the downside of SoFi®?

While SoFi® offers competitive rates and features, it may have a narrower range of products compared to traditional banks, and eligibility requirements for some services can be stricter. Plus, they currently have no business banking. 

Does SoFi® have a business card?

No, SoFi® does not have a business credit card. They do provide a personal credit card with cashback and travel rewards, no annual fees, and expense tracking tools.

Final Takeaway

While SoFi doesn’t offer traditional business checking or savings accounts, it provides financial products for business owners through SoFi at Work® and its small business funding platform. 

SoFi at Work® offers a range of financial products and educational resources to support employee financial well-being. It could be pretty cool for the right company. 

The small business funding platform provides streamlined access to loans of up to $2 million with possible same-day approval. However, the loans are likely to come with factor rates instead of interest rates, which can make them more expensive in the long run. 

While SoFi® may have a narrower range of products compared to traditional banks, its innovative approach and generally high consumer opinion make me think the company is reliable overall. 

Ready to learn how to obtain up to $100K in business credit in as few as 30 days? Join Business Credit Workshop today!
Should You Take Fora Financial Reviews With a Grain of Salt? 

By Joe

Fora Financial Reviews

Fora Financial is a pretty well-known source of small business funding. And, according to Trustpilot and other review sources, they’re also super well-rated. But, you and I both know that you can’t necessarily trust that all user reviews you see online are real…and not all online loans are legit. 

So, let’s dive deep into Fora Financial’s offer, and see if we can get to the bottom of the issue. Find out if Fora’s offer is right for you. 

Here’s what’s in store: 

  • What is Fora Financial?
    • Fora Financial Loan Requirements
    • Is Fora Financial a Real Company?
  • What Does Fora Financial Do?
    • 1. Simple Application Process
    • 2. Speedy Turnaround
    • 3. Convenient Online Portal
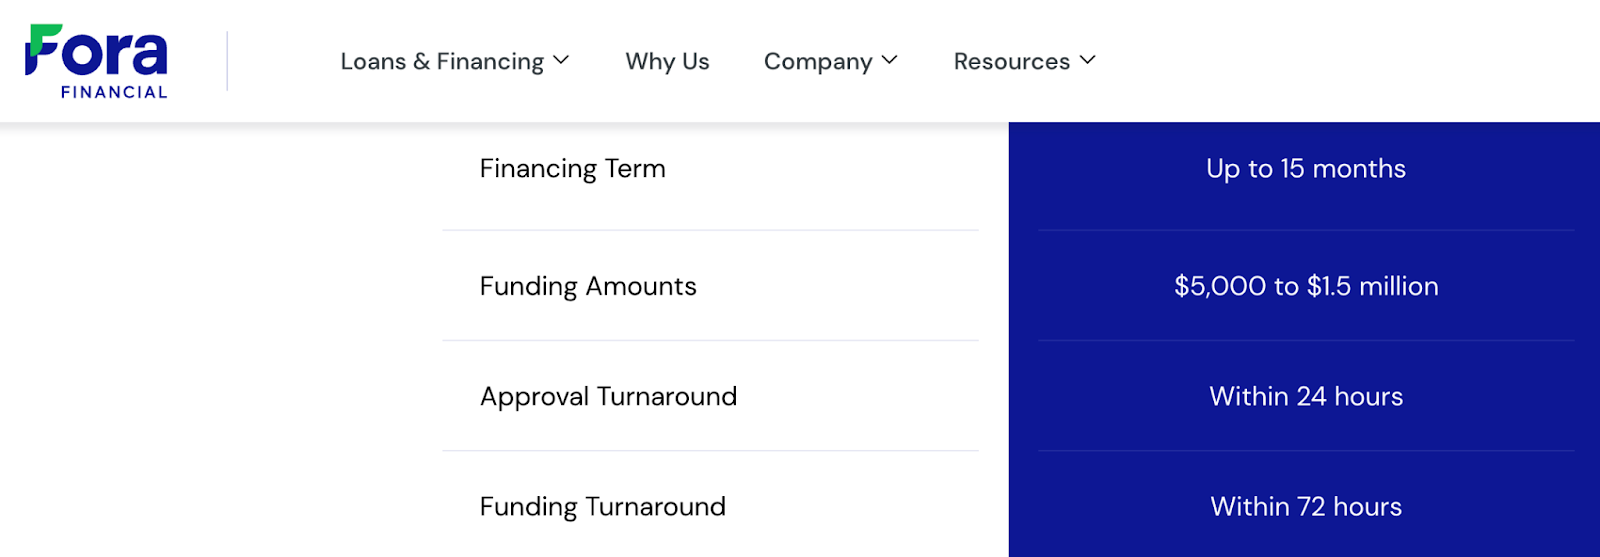
    • 4. Repayment Terms up to 15 Months
    • 5. Small Business Loans
    • 6. Revenue Advances
  • Frequently Asked Questions
  • Conclusion

Now, let’s go!

What is Fora Financial? 

Fora Financial

Fora Financial is a financial services provider or alternative lender that specializes in funding solutions for small and medium-sized businesses — They provide options like small business loans with fixed payback schedules and revenue advances that adjust based on sales. 

The application process is straightforward, typically involving an online application followed by a discussion with a “Capital Specialist” and, upon approval, receiving funds within a few days.

Their funding amounts range from a few thousand dollars up to $1.5 million (with no restrictions on how you use it). You might be able to qualify for 75 percent to 125 percent of your monthly gross sales. 

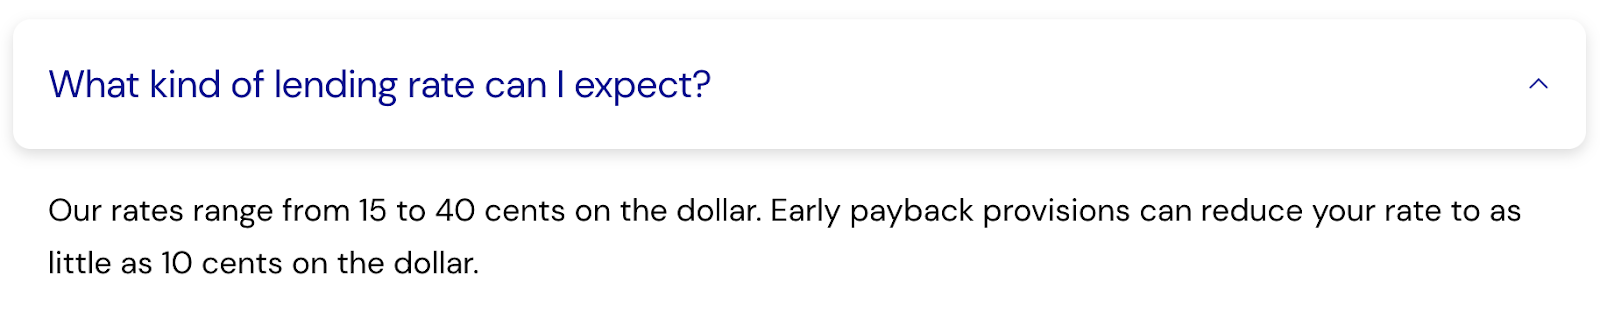
And, you’ll probably pay between 15 and 20 cents per dollar with their repayment terms.

Fora Financial interest rates

Fora Financial caters to various industries and business needs, including cash flow management, equipment purchases, expansion, and more. Overall, they provide accessible financing options for businesses looking to address their funding needs.

You might also like: Could a Stripe Capital Loan Get Your Business Through a Rough Patch? 

Fora Financial Loan Requirements

Like other alternative funding, and compared to traditional business loans, Fora Financial’s requirements are fairly relaxed. You do need to meet some requirements, but the appeal is that these loans are pretty easy to get (In exchange, you pay higher fees over the duration of the loan).

Fora Financial reviews Reddit

You will need a personal credit score of at least 500 (with no open bankruptcies) to qualify. Most people can meet this requirement easily. 

And, according to anecdotal evidence (what I found in various forums), your business must have at least $12K to $15K in gross monthly income and to have been established for at least three months. 

Some lenders require several years in business, so their business requirements are nice. However, conventional business loans look at your business credit score, so there’s no impact to your personal credit utilization as long as you pay as agreed. 

Recommended: Here’s How to [Actually] Get Business Credit With Just an EIN +More Options 

Is Fora Financial a Real Company? 

Fora Financial LLC New York

I was surprised that people are wondering if the company is real. This one is easy to answer – yes, Fora Financial is an established business. 

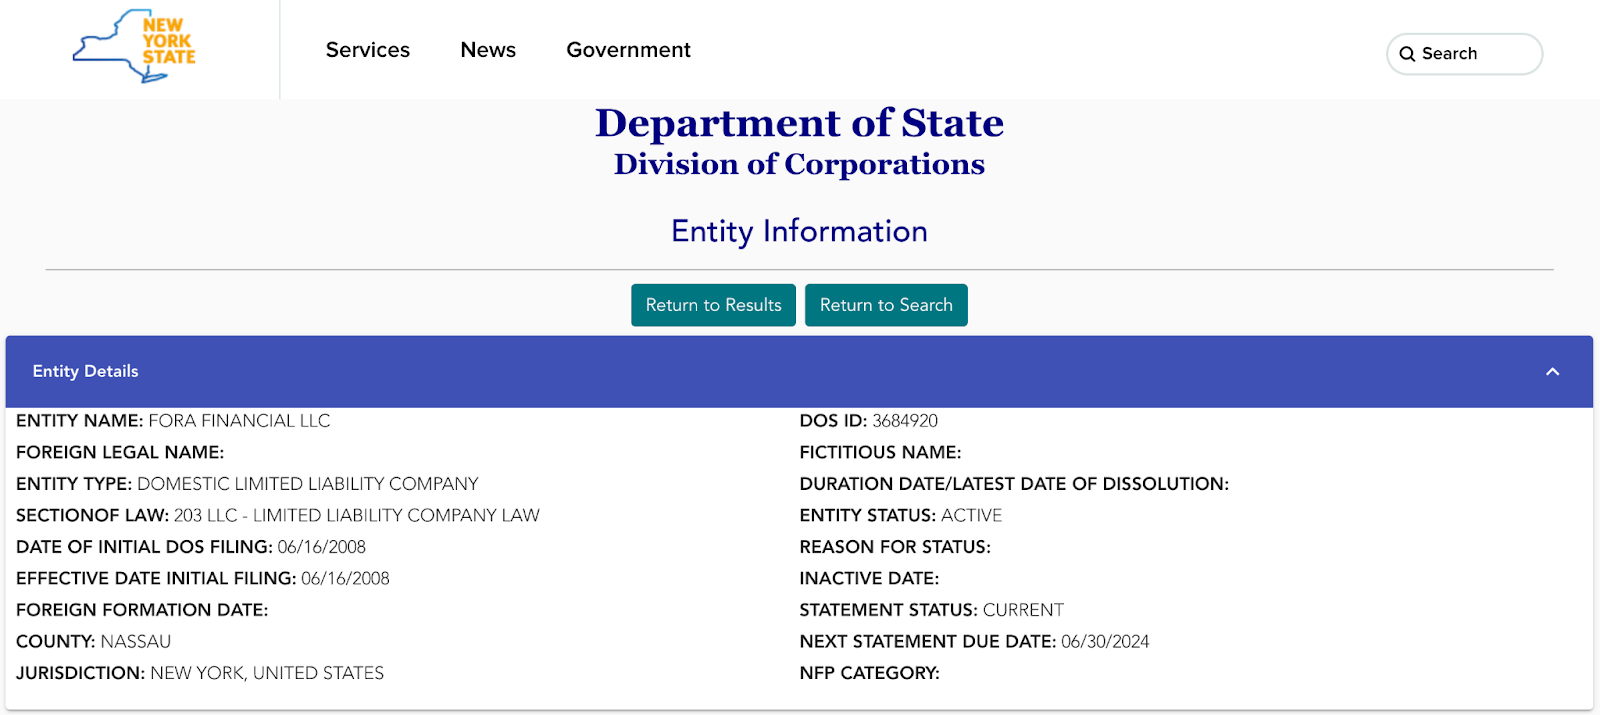
In fact, New York-based Fora Financial LLC was founded in 2008 by Daniel Smith and Jared Feldman. Back then, it was called Paramount Merchant Funding LLC (no relation to Paramount Payment Systems), and the name was changed in 2013. 

Today, it’s a private-equity backed company that seems to be thriving. 

Feldman is the current CEO of Fora, where he’s been for almost 16 years. Smith is also still with the company and previously spent 7 years as a board member of the Small Business Finance Association. 

Who owns Fora Financial?

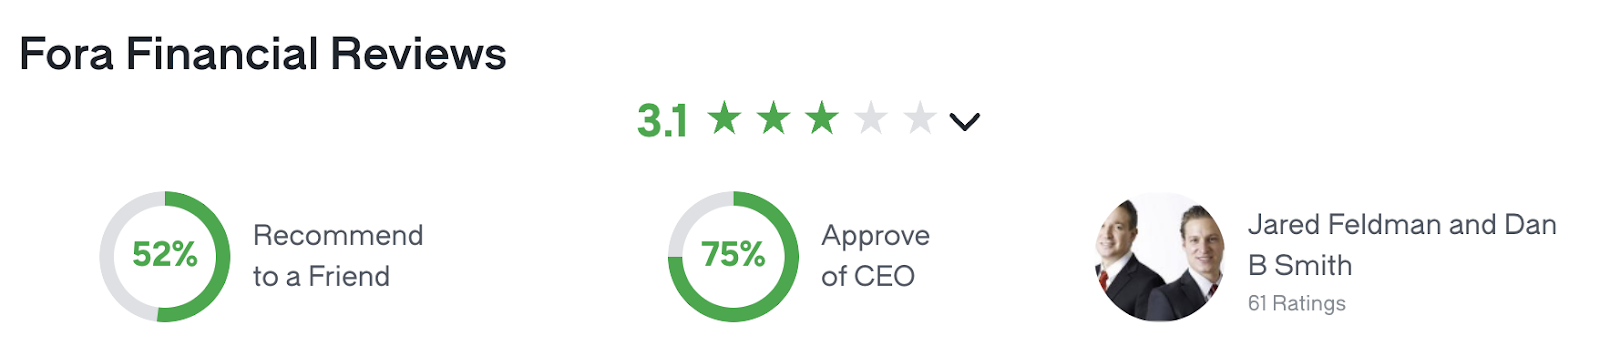
And, according to Glassdoor, most of Fora’s employees would refer a friend to the company and even more approve of company leadership. 

Fora Financial employee reviews Glassdoor

How employees view a company really says a lot about its practices and overall internal ethics – in general, this one seems to have strong leadership. 

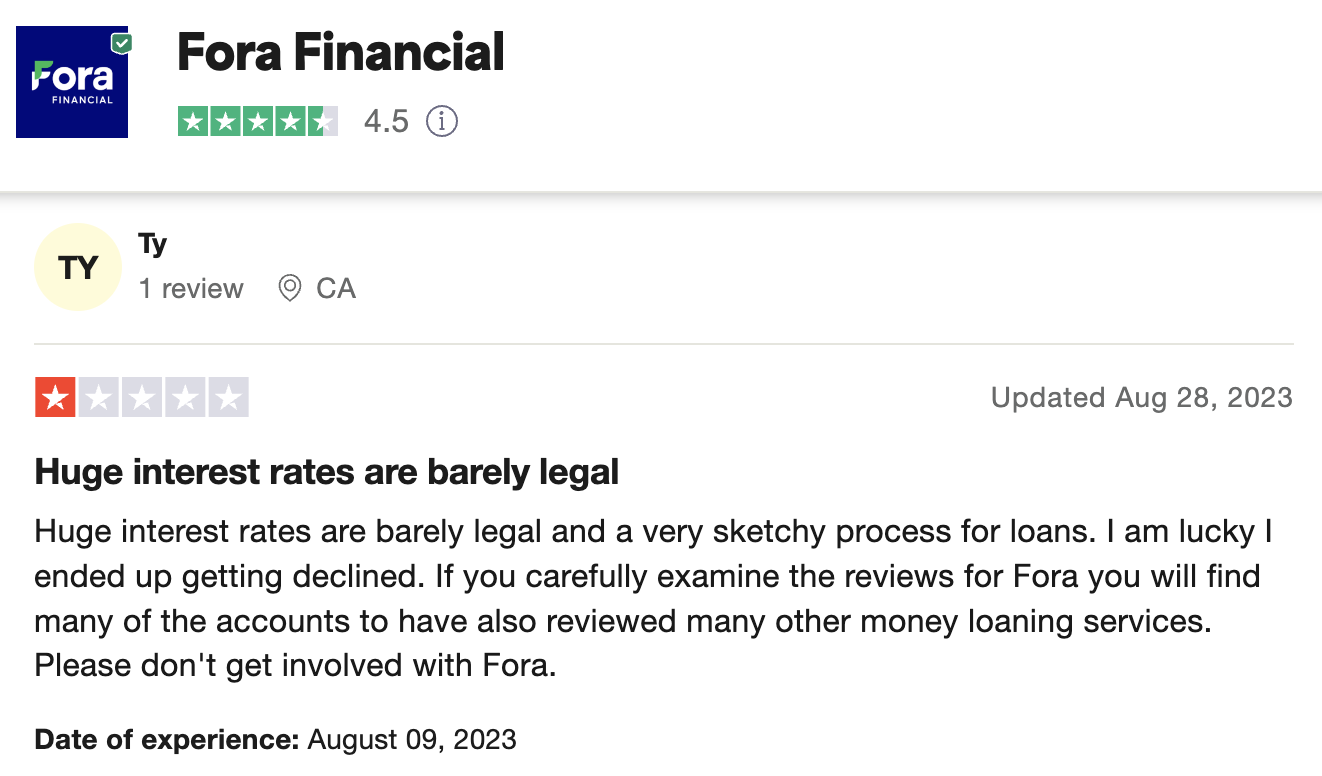
But, how customers see a business can tell us even more. With that said, Fora maintains a 4.5-star rating on Trustpilot, where most of the poor reviews come from people who don’t have loans with the company. 

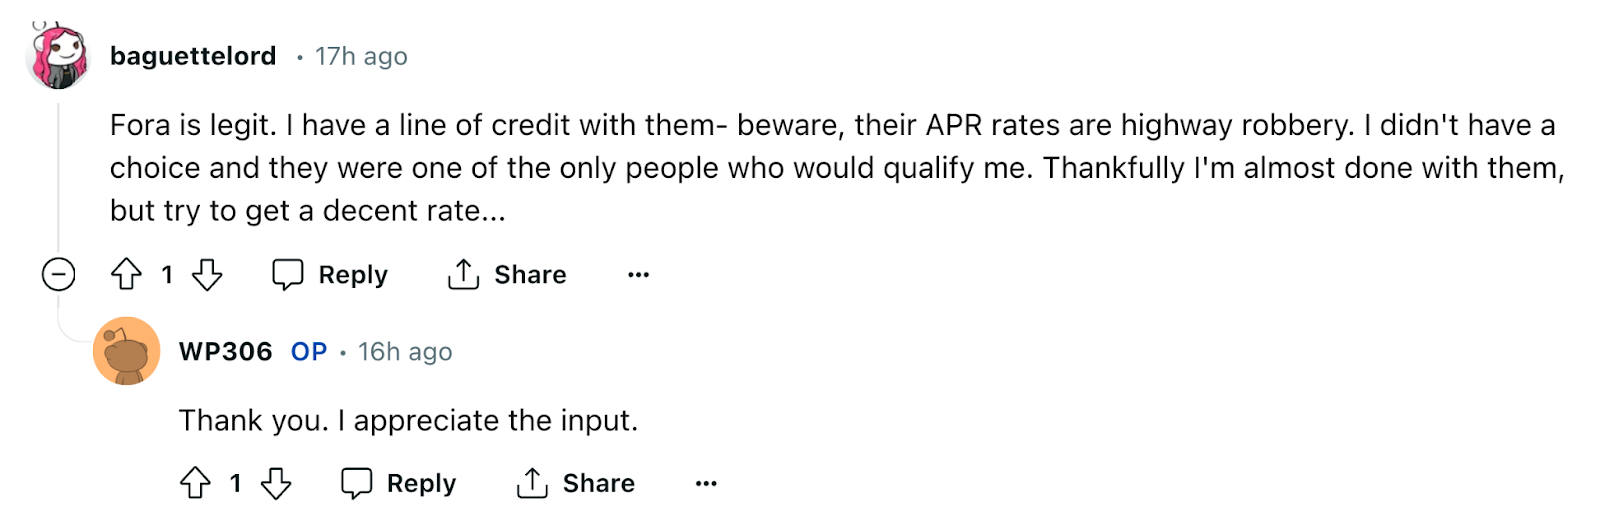
On this platform, the most common complaints are the loan interest rates and difficulty getting in touch with a representative. 

Fora Financial business loan reviews

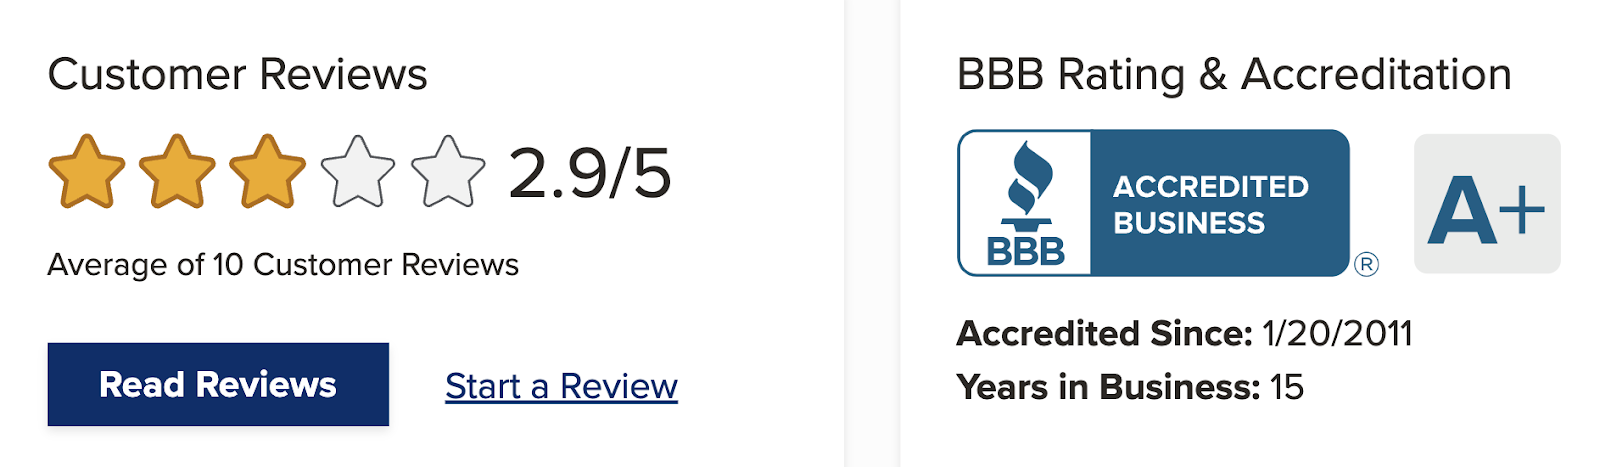
 Now, when you check out Fora Financial’s standing with the Better Business Bureau, you’ll find that they are an accredited business with an A+ Rating. They have had seven customer complaints in the past three years (this is a relatively low number). 

Fora Financial BBB

In sum, they appear to have a legit offer that could be worth checking out if you’d have trouble with approval from a more conventional lender. 

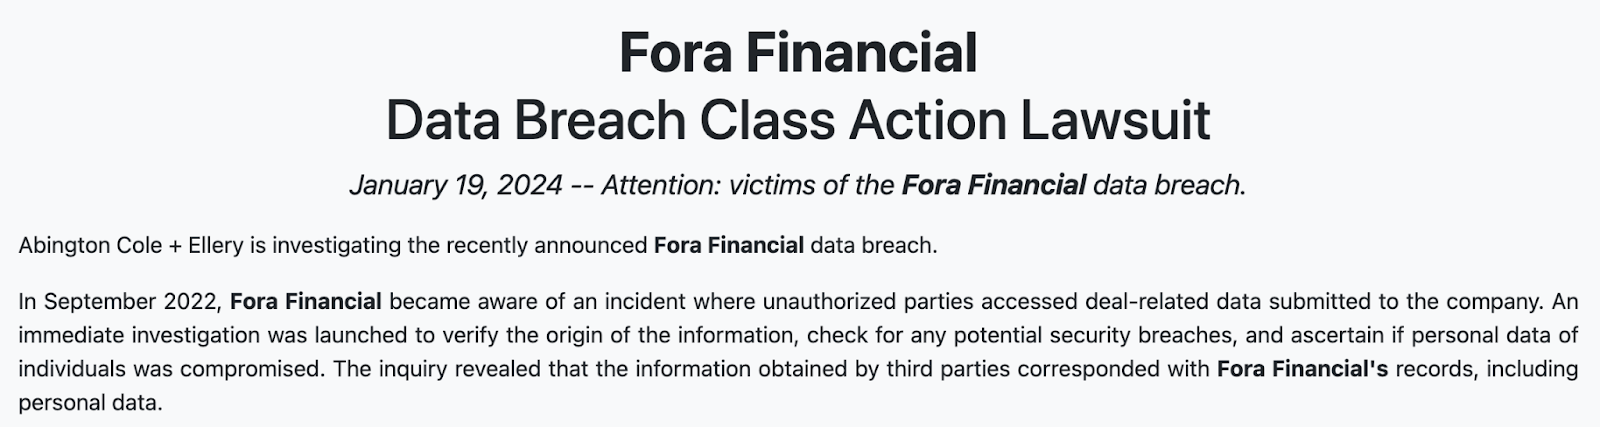
But, before you take that as a green light to go apply, you should know that – as of January 2024 – there is an open class action against Fora in which a data breach is being investigated. 

Fora Financial Lawsuit

In Fora’s defense, one of the world’s largest banks and even one of the three major credit bureaus have suffered data breaches. 

You might also like: Is BHG Financial Legit? Personal & Business Loans, VC, & More 

What Does Fora Financial Do? 

In a nutshell, Fora offers small business loans and revenue advances quickly through a fast application and approval process. But, let’s take a closer look at each major facet of the offer so you can understand exactly what you’re considering signing up for. 

You might also like: Torro Business Funding Review: Is This Zero Hassle Offer Legit? 

1. Simple Application Process 

Fora Financial loan application

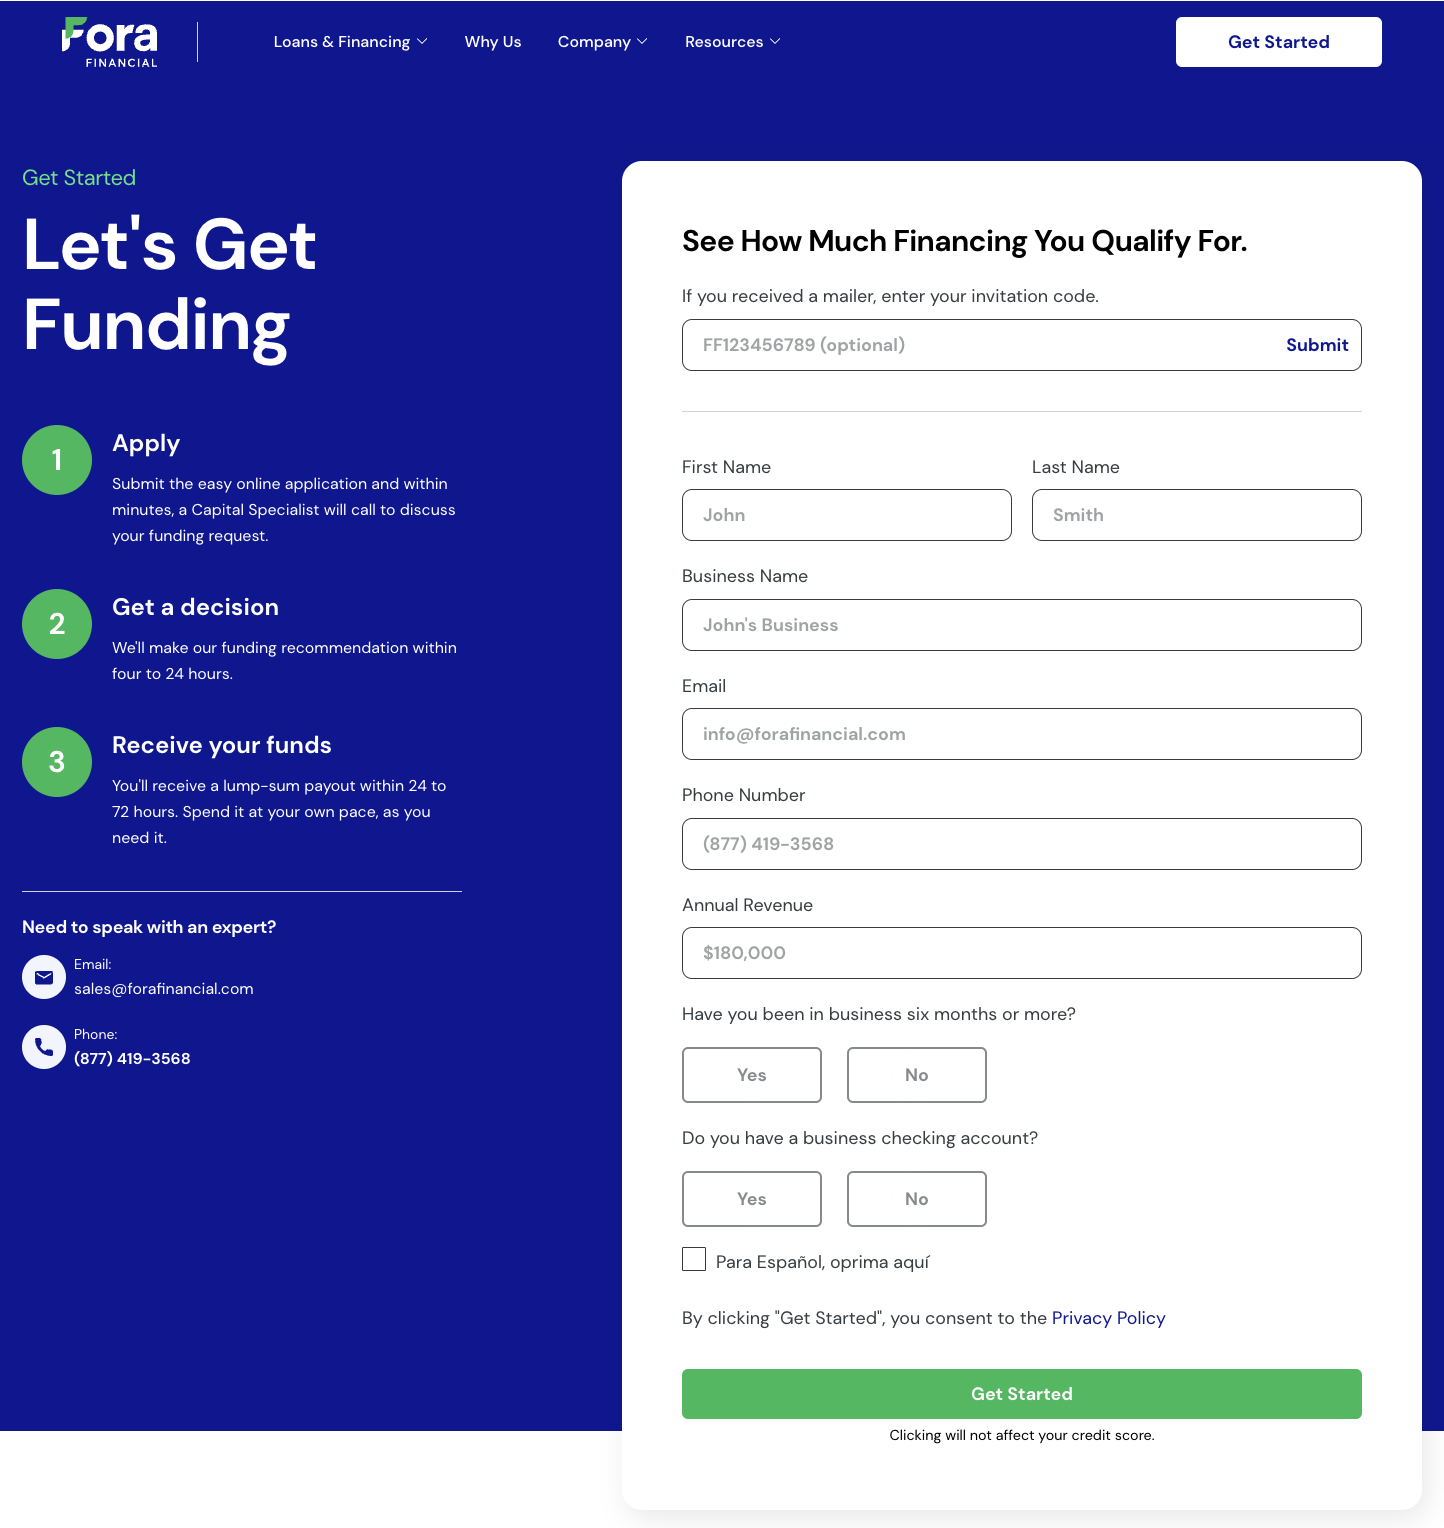
The application process with Fora Financial is straightforward and designed for convenience. First, you’ll need to fill out their easy online application form, which only takes a few minutes. Shortly after submitting your application, expect a call from one of their Capital Specialists to discuss your funding request in detail. 

It’s important to note that Fora Financial will conduct a credit check as part of their review process, but only upon pre-approval. 

Recommended: Free, Printable Business Credit Application Template (Plus, How to Use it Correctly) 

2. Speedy Turnaround 

Prism by Fora Financial reviews

Within four to 24 hours of your application submission, if you seem to be a good candidate, Fora Financial will provide you with a funding recommendation. Once approved, you can expect to receive your funds in a lump sum within 24 to 72 hours – This allows you to start utilizing the funds for your business needs straight away.

Be sure to read terms and conditions carefully for any offer Fora might send. You need to be sure your business has the ability to pay back the loan on-time as agreed. 

Recommended: This is How to Build Business Credit Fast [Step-by-Step Guide] 

3. Convenient Online Portal

Fora Financial login

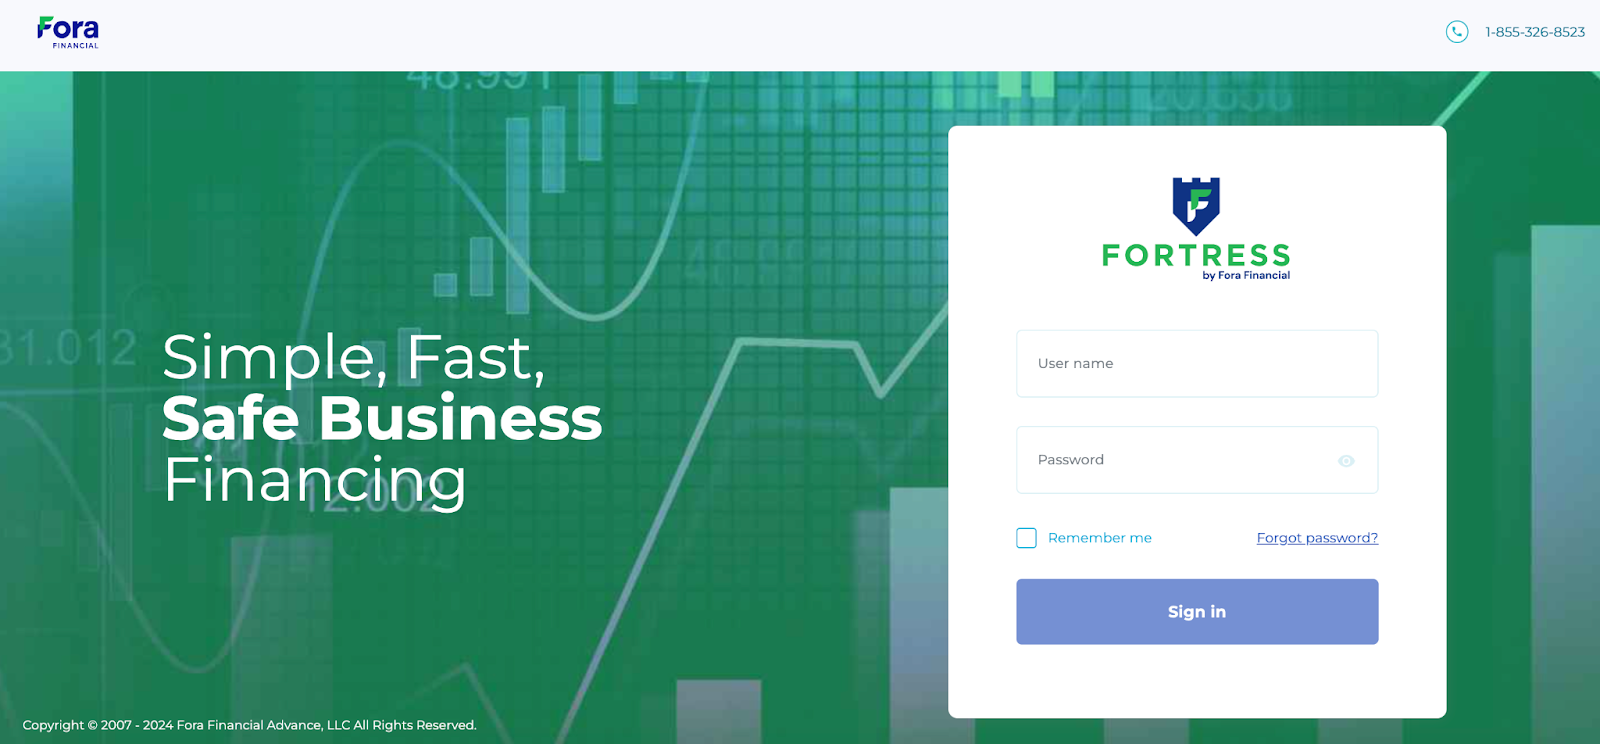
When it comes to applying and repayment, Fora has a convenient online portal that you can access through their website. 

An online portal is convenient for business borrowers because it offers easy access to loan information, application processes, and account management from anywhere with internet access. 

This means you can apply for loans, check your account status, and manage payments without needing to visit a physical location or wait on hold for customer service. It saves time and offers flexibility.

You might also like: How to Convert Credit Cards into Cash 

4. Repayment Terms up to 15 Months

Fora Financial repayment terms

Fora offers loans from $5K to $1.5M and repayment terms up to 15 months. This means that you will have over a year to either repay your loan or find a way to refinance it through a lower-interest lender. 

And, Fora doesn’t penalize early repayment – in fact, Fora rewards responsible payment behavior. If you pay off your loan early, you’ll save money in most cases. 

While this seems like a loan feature that should be standard, it’s not something you see with all online loans. 

You might also like: 11 Alternate Ways for Entrepreneurs to Raise Capital with Online Lending Platforms 

5. Small Business Loans

Fora Financial approval

Fora Financial offers small business loans that can turn your entrepreneurial dreams into reality. With loan amounts ranging from $5K to $1.5 million in working capital, you have the financial flexibility to pursue opportunities and grow your business. 

What’s great is that they don’t do hard credit pulls; just one soft inquiry when you apply, saving you from potential credit score damage. Plus, they offer pre-payment discounts and the chance to increase your borrowed amount after paying at least 60% of the original loan, providing ultimate flexibility.

And, you’re free to use the funds for almost any business expense, whether it’s expanding your operations, hiring more staff, or investing in equipment.

Recommended: How to Get an SBA Business Loan 

6. Revenue Advances

Fora Financial com activate rewards

Fora Financial’s Revenue Advance is designed to provide flexible terms for businesses experiencing variable cash flow. With this option, you can borrow anywhere from $5K to $1.5 million against your future revenue. 

The repayment structure is tailored to your business’s sales performance, making it easier to manage during both prosperous and lean times.

Here’s how it works: 

  • Instead of fixed monthly payments, you repay a fixed percentage of your daily or weekly sales. 
  • When your sales are booming, you’ll pay off your advance faster, but during slower periods, you’ll benefit from reduced payments (this gives you breathing room when you need to navigate challenging times).

In essence, this is a working capital loan or merchant cash advance. Again, I only recommend this type of financing if you have no other option. 

You might also like: This is the Truth About LenCred’s Small Business Financing 

Frequently Asked Questions

Does Fora Financial do credit checks? 

Fora Financial conducts a soft credit inquiry when you apply for financing. This inquiry does not impact your credit score. However, they do not perform hard credit checks, so your credit score remains unaffected during the initial application process.

Is Fora Financial a direct lender? 

Yes, Fora Financial is a direct lender. This means that they provide funding directly to borrowers without involving intermediaries or brokers. Working with a direct lender like Fora Financial can often streamline the loan process and offer more personalized service.

How do I get approved for financing with Fora Financial? 

To get approved for financing with Fora Financial, you can start by filling out an online application on their website. Your personal credit score must be at least 500. The application process is straightforward and typically requires basic information about your business, such as revenue history and desired loan amount. Approval is based on various factors including your business’s financial health and creditworthiness.

Does Fora Financial report to credit bureaus? 

No, Fora Financial does not report your payment history to major credit bureaus. This means that your loan with Fora Financial will not impact your business or consumer credit profile (unless you default on your loan). 

Conclusion

As far as alternative lenders go, Fora is one of the good ones. While their rates are way too high for me to recommend the offer (I never recommend this type of loan unless the situation is so urgent and dire that there is no other choice). 

This may seem like a natural benefit if you’re not versed in alternative loans, but the fact that Fora doesn’t have a prepayment penalty is fantastic – many online lenders will penalize you if you pay off your loan before the repayment date. 

*Which is why it’s so important to read the terms and conditions. 

Ready to learn how to obtain up to $100K in business credit in as few as 30 days? Join Business Credit Workshop today!
Is BHG Financial Legit? Personal & Business Loans, VC, & More

By Joe

BHG Financial

While not a new company, BHG Financial started becoming wildly more popular than ever in 2022. Since then, they’ve been garnering attention with rumors that owners can get pre-revenue ($0 income) business loans with no personal guarantee. While applicant’s can expect a ton of phone calls from the moment they share their contact info with the company, this is true for most modern lenders. 

Most of all, people want to know if BHG Financial is legit. Keep reading to get the answer. 

Here’s what’s in store: 

  • What is BHG Financial?
    • Is BHG Financial Legit?
  • What Does BHG Financial Do?
    • 1. BHG Money Loans
    • 2. Fund-Ex Solutions Group
    • 3. BHG Bank Network
    • 4. NaluPay
    • 5. Risk Management Solutions Group
    • 6. BHG Connect
    • 7. BHG VC
  • Frequently Asked Questions
  • Conclusion: Is BHG a Legitimate Company?

Now, let’s get down to it! 

What is BHG Financial? 

BHG Financial is a financial company that offers various solutions for small and medium-sized businesses (SMBs) as well as consumers across the U.S.

Their approach involves using data analytics and technology to market and underwrite small business and unsecured consumer loans. They claim to be a disruptor in the industry, with a focus on providing innovative financial solutions. BHG operates with a proprietary online auction platform to sell loans to a large network of bank members.

Is BHG Financial Legit? 

According to the company website, BHG Financial started back in 2001 with a modest $25K and a small team. Fast forward to today, they’ve grown significantly. The numbers they highlight include over $15 billion in loan solutions, processing around 31,000 applicants each month, with 1,450 bank members and a team of 1,500 employees.

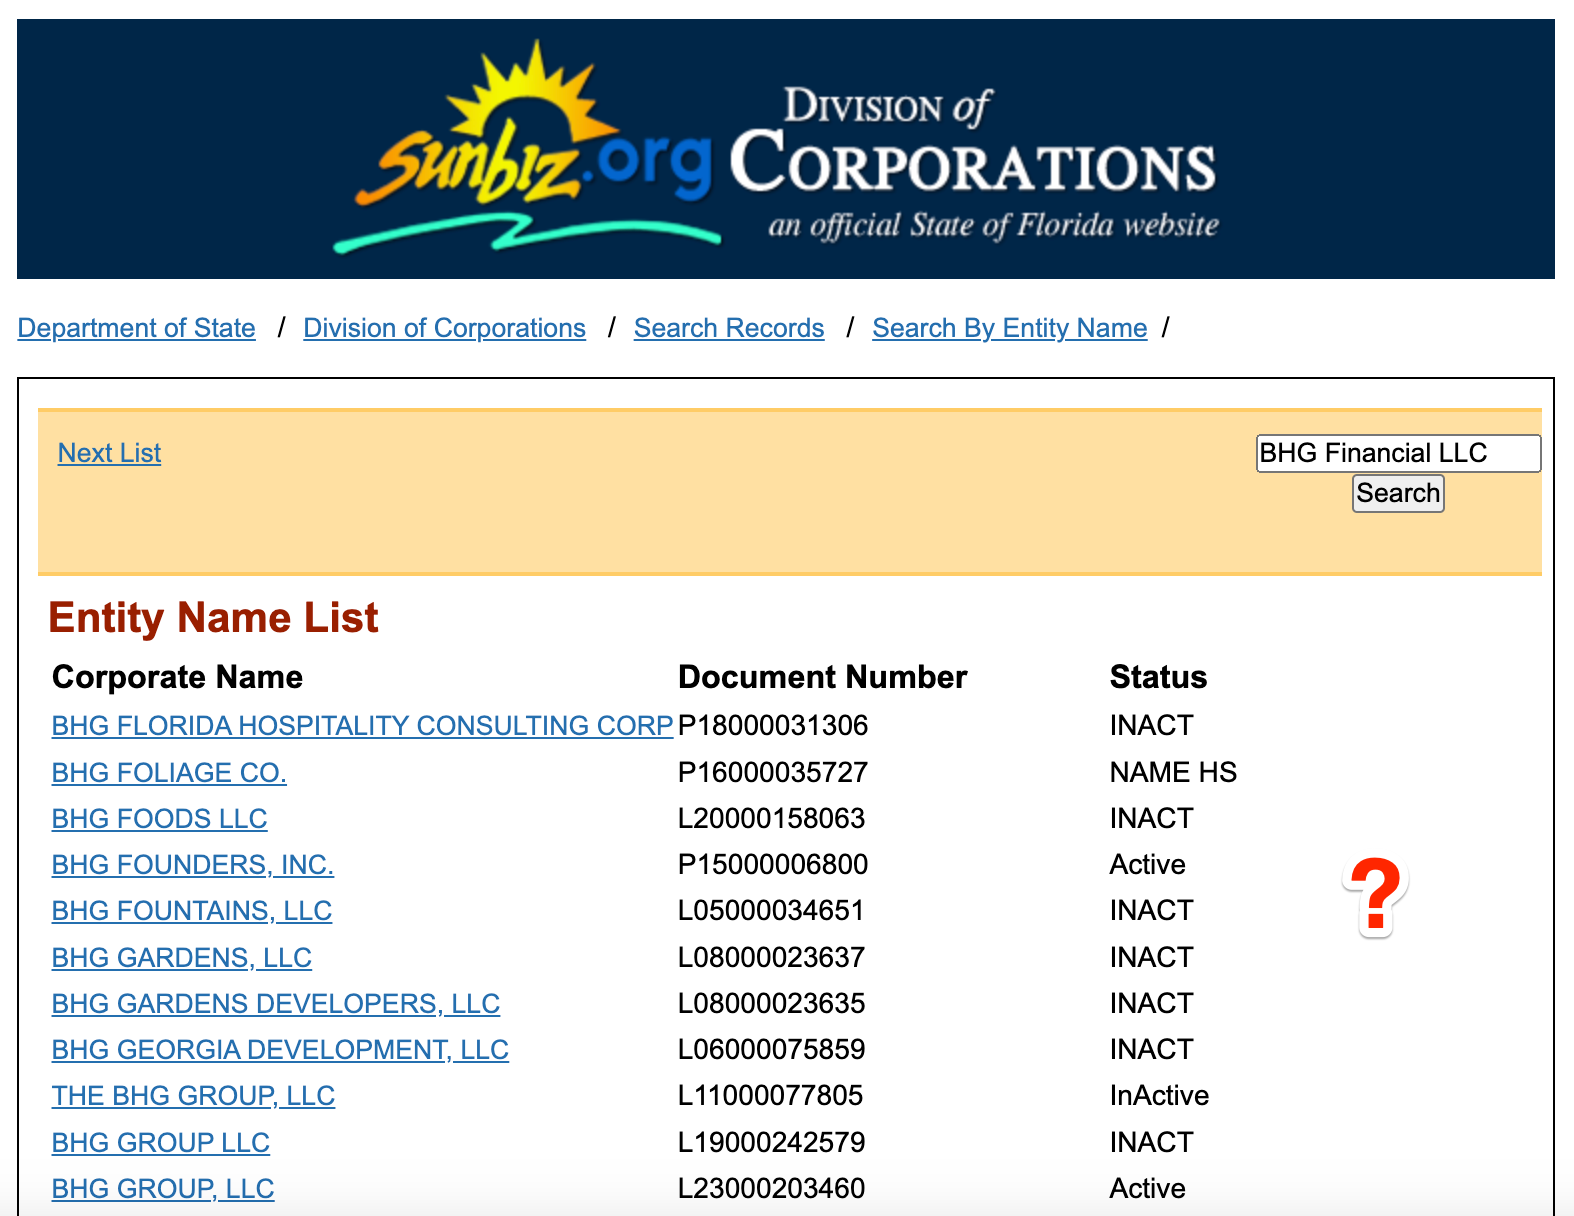
According to Crunchbase, BHG Financial (aka “BHG Financial LLC”) is a Ft. Lauderdale, Florida-based, for-profit company. 🚩However, according to Sunbiz.org (Florida’s Division of Corporations website), no such-named business is registered in the state. 

Who owns BHG Financial?

However, Banker’s Healthcare Group LLC. (per bngfinancial.com Terms & Conditions) is active and registered to Albert (Al) Crawford in Davie, Florida. Crawford is the current Co-Founder, Chairman, and CEO at BHG Financial where he’s been since the company’s humble beginnings. 

Bankers Healthcare Group is known to directly lend funds and offer financing, credit cards, and patient financing tailored for healthcare professionals for the past 20+ years.  

🚩 In digging deeper, I found that, as of November 2023, Bankers Healthcare Group is facing a proposed class action lawsuit that alleges they disguise consumer loans as business loans to cover up unlawful lending practices. If you follow along, you might be able to find out if this allegation has legs – it will be interesting to find out.

Who is BHG Financial?

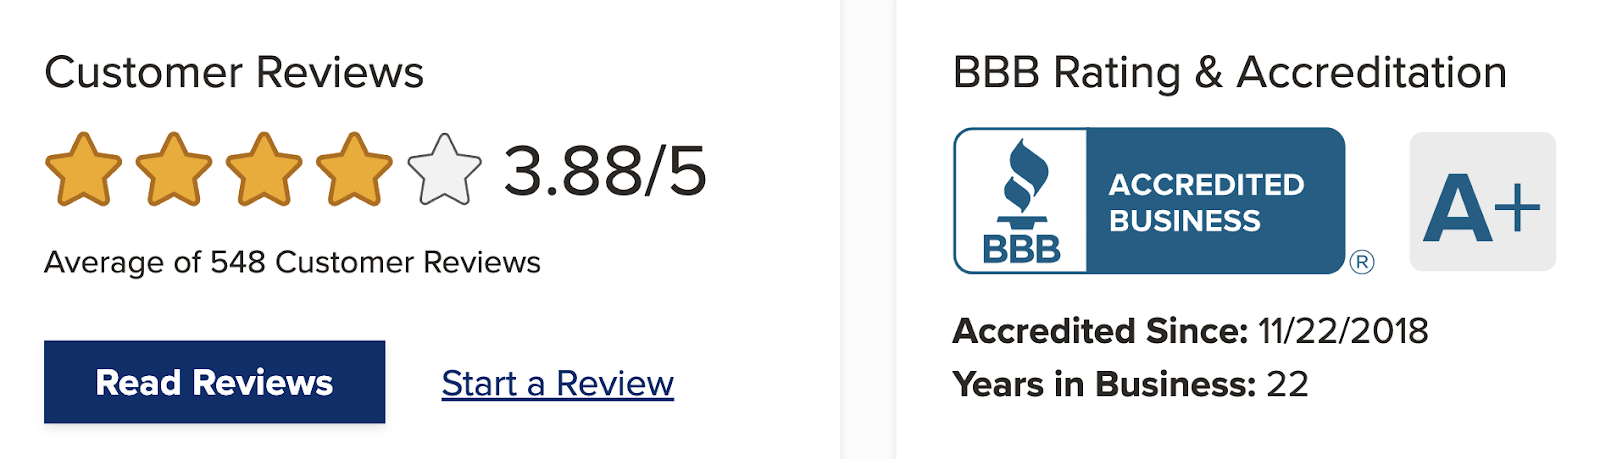
Despite 522 complaints in the past 3 years (175 closed in the past 12 months), BHG Financial maintains an A+ rating with the Better Business Bureau (BBB), where they’ve been accredited since 2018. 

BHG Financial Reviews BBB

Now, if the class action previously mentioned happens to stick, this rating might go down. 

As reported by at least Redditor, as a lender, BHG reps might try high-pressure tactics to get someone to take a loan offer, but they’re legit and their financial products are negotiable.