• Home
  • Free Funding Guide
  • What We Offer
    • Products
    • Services
    • Free Guide
  • About Us
  • Contact
  • Sign Up

  • Ask Joe Any Question!
  • Business Credit Cards
  • Business Line of Credit
  • Topics

Shopify Capital Review: What are the Benefits & is it Worth it? 

By Joe

Shopify Capital Review

eCommerce merchants who need a boost in cash flow have probably considered Shopify Capital as a source of funds. Are you wondering if you should accept a funding offer from Shopify? …I can help you decide!

In this post, I’m going to dive into exactly what Shopify Capital is, eligibility requirements, why you may or may not want to apply for an offer, and introduce some alternatives you may want to consider. 

Here’s what’s in store: 

  • What is Shopify Capital?
    • Company Overview
    • What are the Benefits of Shopify Capital?
  • Shopify Capital Loan Summary
    • Shopify Capital Eligibility Requirements
    • Shopify Capital Terms & Repayment
    • How to Apply for Shopify Capital
  • Shopify Capital Alternatives
  • Frequently Asked Questions
  • Conclusion: Is Shopify Capital Funding Worth it?

So, let’s roll! 

What is Shopify Capital? 
Does Shopify Capital charge interest?

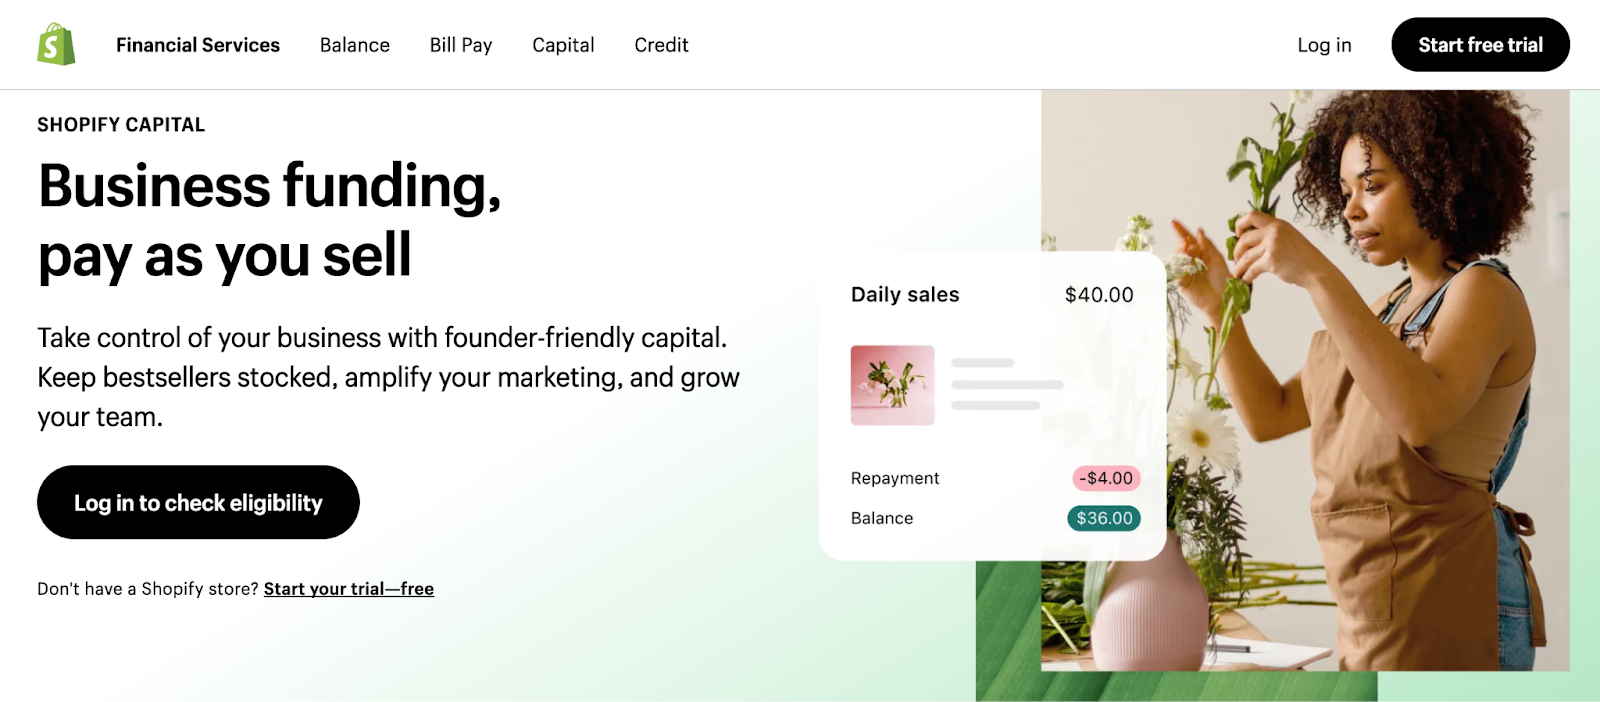
Shopify Capital is like your online store’s financial wingman. It swoops in to offer cash advances to businesses that are rockin’ it on Shopify. If your store has a good track record and plays nicely with the Shopify platform, you might just be eligible to request a cash boost. 

This extra dough can be a game-changer – you can use it for all sorts of things like: 

  • Investing in more inventory
  • Revving up your marketing
  • Setting up shop in a physical store
  • Bringing in some extra hands to help out

So, Shopify Capital is essentially designed to help you scale your business.

But, there are tons of financial offers out there that can help you do this. How do you know if this is the one? Keep reading. 

Recommended: Behind the Scenes of Become.co: A Comprehensive Review 

Company Overview
Is Shopify a billion dollar company?

Founded in 2004, Shopify, aka Shopify Payments, aka Shopify Data Processing is a Canada-based, publicly-traded for profit company worth $1.3B. The company is leading the eCommerce game with their token online sales platform (but you already knew that, didn’t you?). 

I won’t delve too deep into Shopify’s app store or Shopify Plus – the enterprise eCommerce platform – but, I do want to take a quick look at the history of Shopify Capital. 

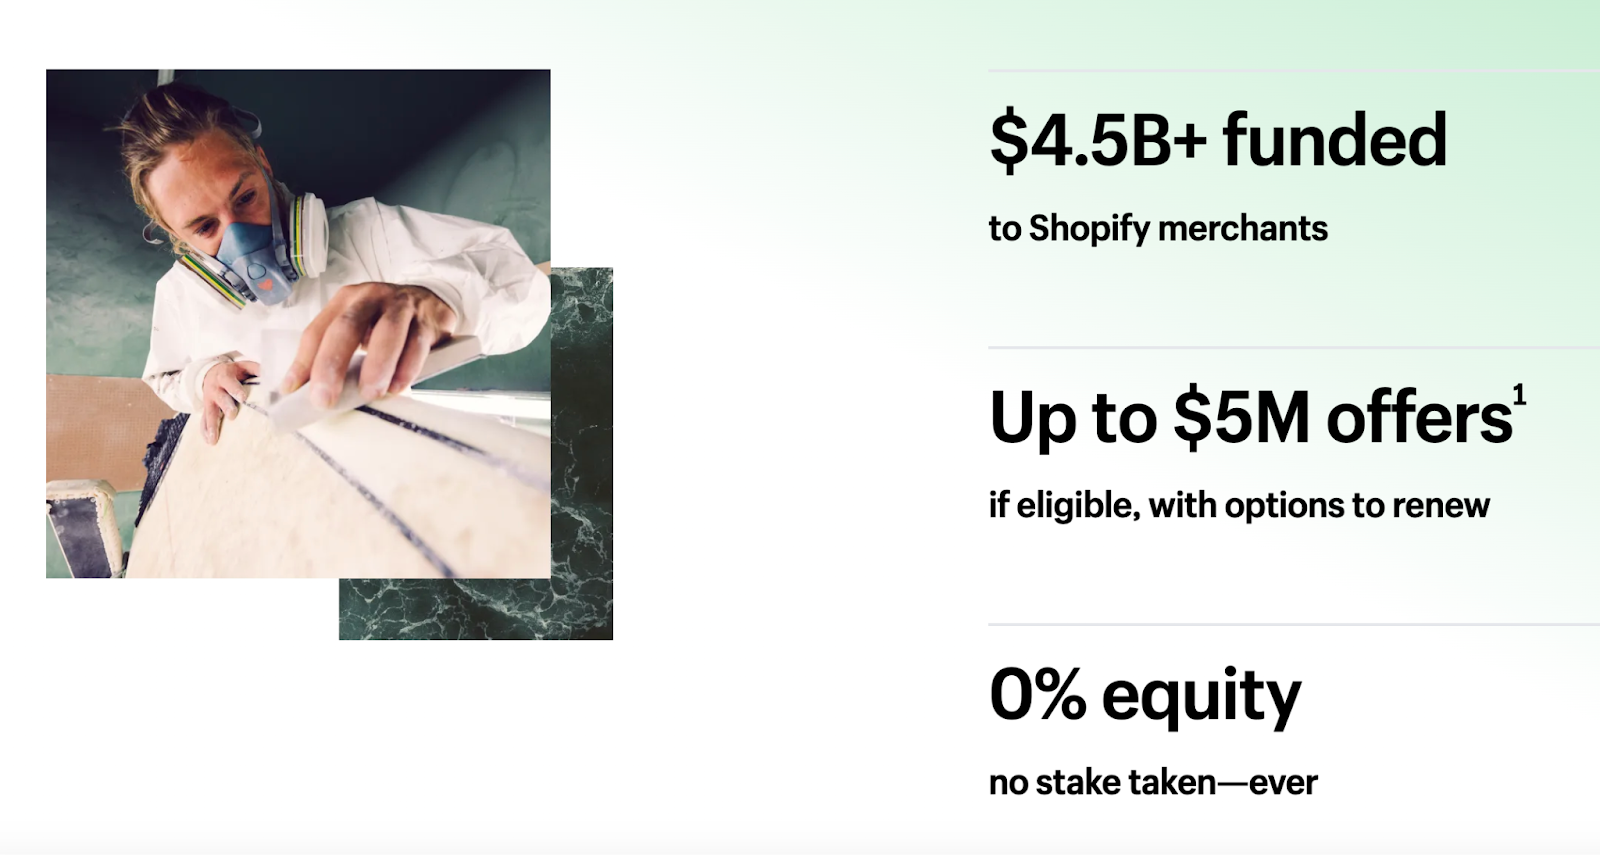
The company launched Shopify Capital in April 2016, as a merchant cash advance offer. Since then, they’ve provided billions of dollars in funding to their sellers worldwide. 

All Shopify Capital loans are funded by WebBank, which is also affiliated with Dell Business Credit, LendingClub, and Capital on Tap. While these aren’t my favorite funding offers for business owners, they are legitimate offers. 

Recommended: 41 Companies That Help Build Business Credit [Beyond Net 30 Vendors] 

What are the Benefits of Shopify Capital? 
Shopify Capital cash advance

Shopify Capital offers several benefits to eligible businesses:

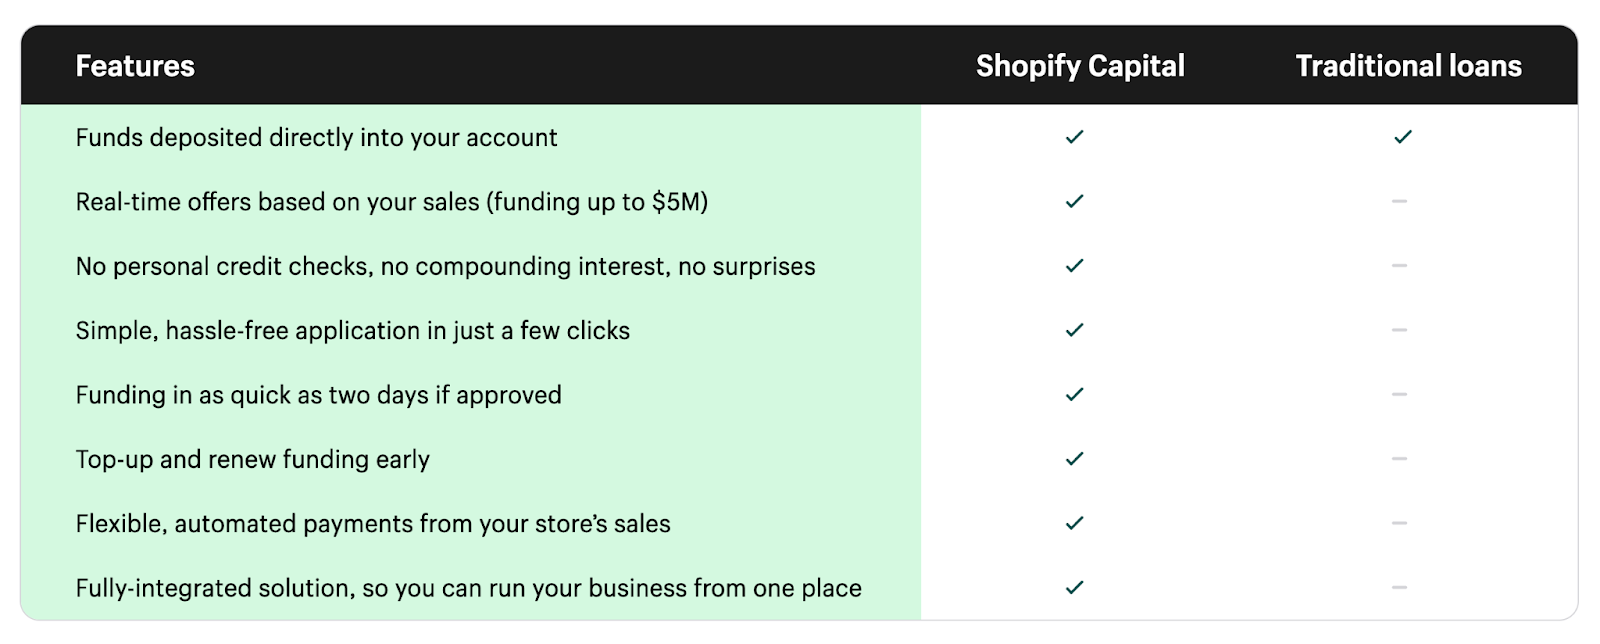
  1. Quick, easy access to up to $5M – Shopify Capital simplifies the funding process. If your business qualifies, you can access the funds you need swiftly, which allows you to capitalize on opportunities or address financial challenges without lengthy approval processes.
  2. No fixed repayment schedule – One of the perks is that repayments are tied to your daily sales. This means that when your sales are high, you’ll pay back more. But, during slower periods, the repayment amount decreases, making it more manageable.
  3. No personal guarantees – Unlike some traditional loans, Shopify Capital doesn’t typically require personal guarantees (PGs), which reduces your personal financial risk.
  4. Customized funding – Shopify Capital tailors the funding amount to your business needs based on factors like your store’s history and performance.
  5. Invest in business growth – You can use the funds to invest in your business, with the goal being to increase your future profits.
  6. Transparent fees – The costs associated with Shopify Capital are straightforward, so you won’t encounter hidden fees or surprises.

These benefits make Shopify Capital an attractive option for Shopify merchants looking to fuel their business growth and address financial needs with flexibility and convenience. Now, let’s take a look at the actual details of the loan and how it stacks up in the lender marketplace. 

Now, let’s explore the cash advance offer in more detail. 

You might also like: What’s the Best Payment Processor for a Small Business? Really

Shopify Capital Loan Summary
Shopify Capital loan overview

When deciding whether a Shopify Capital loan is right for you, I think it’s most important to look at eligibility requirements, terms and repayment, and alternatives. So, let’s look at each of these facets of the offer.

Note: These details relate to the U.S. offer only. For other countries, see the Shopify help center. 

Shopify Capital Eligibility Requirements

Shopify Capital has certain eligibility requirements to qualify for its merchant cash advances in the U.S. 

To be eligible, your business should meet the following criteria:

  • Use Shopify as your sales platform – You need to be a Shopify merchant, which means your business should operate on the Shopify platform to apply for Shopify Capital.
  • Location – This program is available specifically for businesses in the United States, so you should be operating within the U.S. to be eligible (comparable offers are available for businesses in Canada, Australia, and the U.K. as well).  
  • Sales history – Shopify Capital considers your store’s history, which means businesses with a track record of sales on the platform are more likely to qualify.
  • Risk profile – The amount you can receive and the remittance rate depend on your risk profile. Factors like your store’s performance, sales, and other business metrics are assessed to determine this.

Remember that eligibility doesn’t guarantee funding, but meeting these criteria is a good start if you’re looking to access funds through Shopify Capital. It’s like a helping hand for businesses that are already up and running on Shopify in the United States.

If you have more questions or need further information, feel free to ask!

Shopify Capital Terms & Repayment

When Shopify Capital offers you a cash advance, it’s like giving your business a boost of cash. They’ll hand you a lump sum of money, and you pay it back from your daily sales. No need to stress about a fixed schedule for repayments. Instead, it’s a percentage of your daily sales, which is called the remittance rate.

Now, about those fees – the terms are pretty straightforward. 
Shopify Capital Trustpilot

Shopify Capital tells you upfront how much they’ll take for the cash they give you. So, let’s say they give you $5,000, and the fee is 10%. You’ll pay back a total of $5,650, which includes the initial $5,000 plus the 10% fee. 

Payments are automatically deducted from your daily sales, so you don’t have to worry about missing an installment. You can also choose to pay off the balance whenever you like – it’s all pretty flexible.

And the best part? 

No rush to pay it all back…there’s no set deadline. It’s all based on your daily sales, so when business is good, you pay more, and when it’s slower, you pay less. 

Easy peasy, right? Well…not so fast. 

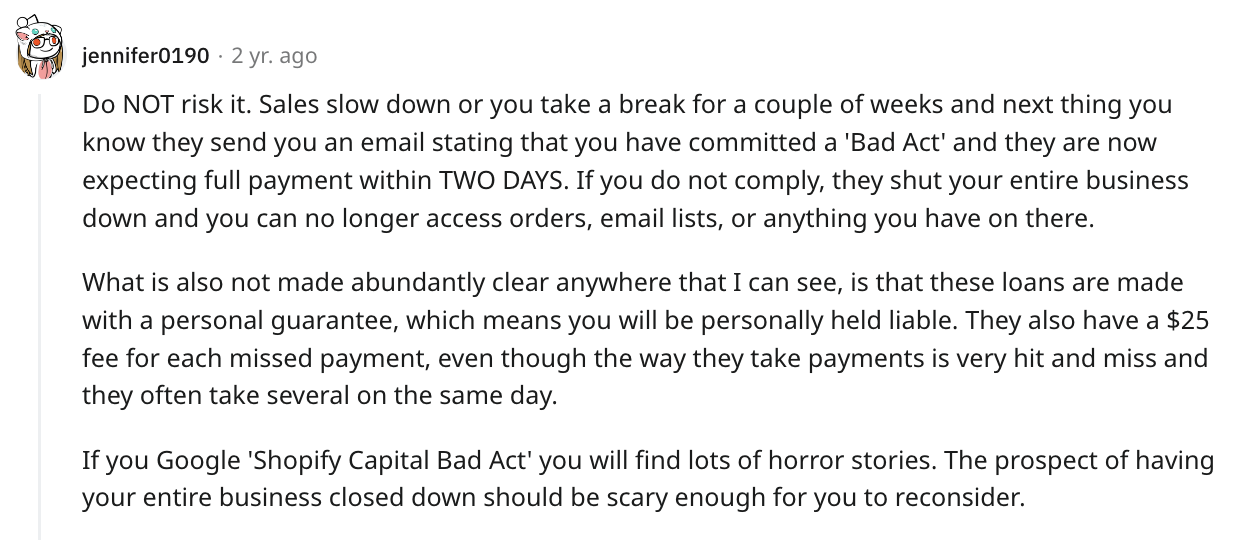
Before you jump in head-first, consider how consistent your sales have been, and whether or not you anticipate any slow periods. 
Shopify Capital Reddit

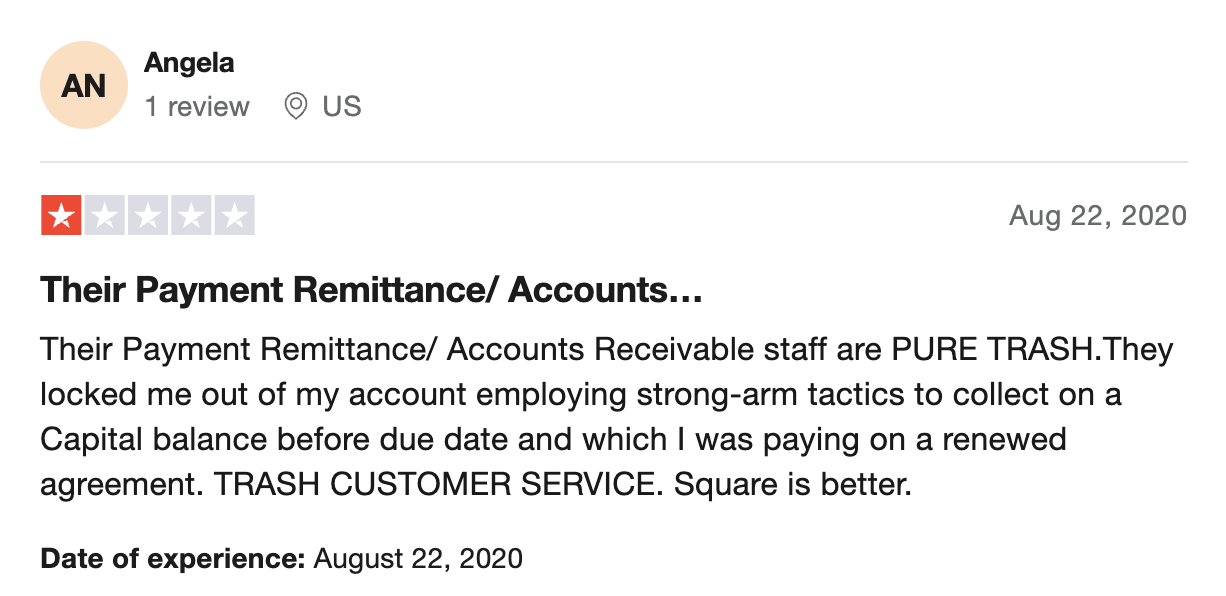
If you’re unsure, you may not want to get in over your head. Shopify does have the right to collect their funds, even if your customers decide to hit the road and go somewhere else (it would be unfair if they didn’t).

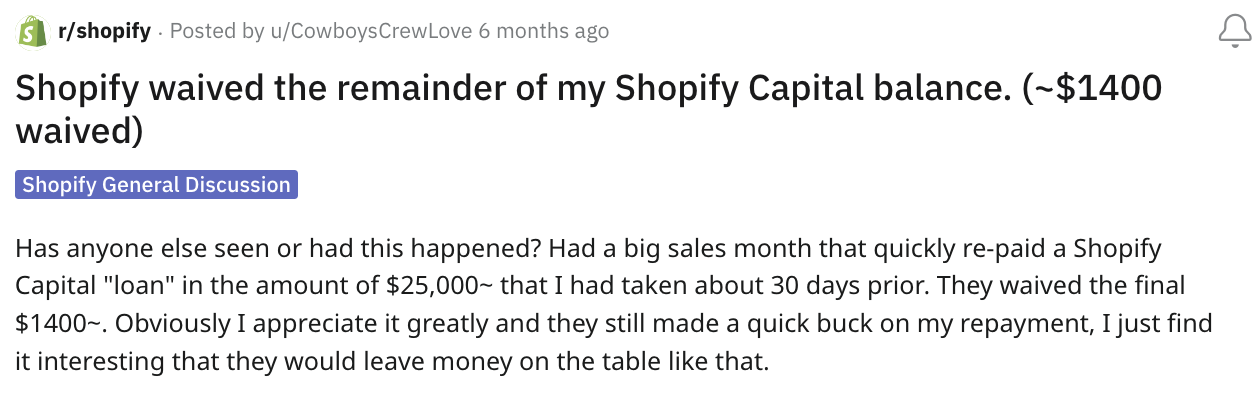
Overall, Shopify Capital’s terms are what I would expect from any cash advance offer. And, their factor rates of 1.1 and 1.13 are reasonable, with other offers being as high as 1.5 and beyond.  

How to Apply for Shopify Capital 
Shopify Capital customer service

Applying for a Shopify Capital cash advance is a super straightforward process: 

  1. Log In to Shopify – If you have a Shopify store, log in to your account.
  2. Find Capital – Look for the “Capital” section in your Shopify settings.
  3. Pick an option – They’ll show you choices for how much money you want and how you’ll pay it back. Choose the one that works for you.
  4. Verify who you are – They’ll need to make sure you’re really you, so be ready to confirm your identity.
  5. Say yes to the rules – Read and accept the rules they give you. It’s like agreeing to the terms.
  6. Switch to Shopify Payments (if needed) – If you’re not already using Shopify Payments, they might ask you to switch to it.
  7. Submit your request – Hit the button to send in your request. Now, wait a bit for them to look it over (usually 1-3 business days).
  8. Get your money – If they say yes, they’ll put the money in your business bank account within two business days.

That’s it!…Ready to explore other options before you make that final decision?  

Shopify Capital Alternatives

While there are a ton of merchant cash advance options available, I’m most familiar with three of the most reputable. So, let’s compare Shopify Capital, Stripe Capital, and Credibly’s offers. 

Shopify CapitalStripe CapitalCredibly Financing
PlatformExclusively for Shopify merchantsAvailable for Stripe usersOpen to various businesses
EligibilityRequires a history with ShopifyBased on your Stripe activityOpen to businesses with requirements
Funding SpeedQuick approval and fundingRapid approval and fundingQuick funding decisions
RepaymentDaily percentage from salesDaily percentage from salesFixed daily or weekly payments
Repayment FlexibilityFlexible based on daily salesAdjusted based on salesFixed repayment schedule
FeesFixed fee determined upfrontFixed fee determined upfrontFees based on risk and terms

Each of these cash advance options has its own strengths and caters to different business needs. 

Shopify Capital is ideal for Shopify store owners seeking flexible, sales-based repayments. Stripe Capital is for Stripe users and offers rapid funding. Credibly offers financing to a broader range of businesses but with varying terms based on risk.

Now, a merchant cash advance has never been my go-to for business funding – You have many other options that are often more ideal. 

For one, traditional loans are like the ones you get from banks and credit unions, often cheaper but harder to secure because they require a strong credit history and collateral. And, business lines of credit work like credit cards for your business, offering flexibility, but interest rates can fluctuate. Both of these are pretty standard, and you can get into these types of funding when you maximize your business credit. 

Recommended: This is How to Leverage Business Credit to Transform Your Life 

Next, SBA loans, backed by the government, come with good rates and reasonable monthly payments, but their complex application process can be challenging. Then, online business loans, like offers from Become, Lendio, or Fundbox – provide quick funding but may have fairly high costs. 

Moreover, crowdfunding and peer-to-peer lending let you seek funds online, but success isn’t guaranteed. Finally, if you have personal savings or assets, you can use them, but it involves a risk to your personal finances.

Recommended: Y Combinator: Fast Track to Success or Waste of Time? 

Remember, the best choice depends on your specific business situation and preferences. So, consider your needs and the terms that suit you best when deciding.

Frequently Asked Questions

Can you negotiate Shopify Capital? 

No. Shopify Capital offers fixed terms, including fees and repayment percentages, which are not negotiable.

How long does it take for Shopify Capital to be approved? 

The approval process typically takes 1-3 business days, but in some cases, it might take longer.

What percentage of profits does Shopify take? 

Shopify Capital takes a fixed fee, which is determined upfront. The percentage varies based on your specific cash advance offer.

What company owns Shopify? 

Shopify is an independent company, and it’s publicly traded on the New York Stock Exchange and the Toronto Stock Exchange. It has been shareholder-owned since 2015. 

Conclusion: Is Shopify Capital Funding Worth it? 

In most cases, I don’t recommend merchant cash advances for business funding, because the fees tend to be super steep, and better options are usually available. With that said, Shopify Capital does have a reputable offer with fair terms…Plus, it’s super easy to pay back one of these cash advances (how long that takes will depend on your sales). 

So, if you like the offer, your business is located in a region where it’s available, you meet the other eligibility criteria, and you really need the money now, go ahead and apply. 

Also, If you’re interested in learning how to get up to $100K in business credit in as few as 30 days, join Business Credit workshop today.  
Is the Nav Prime Card Right for Your Business? Let’s Find Out!

By Joe

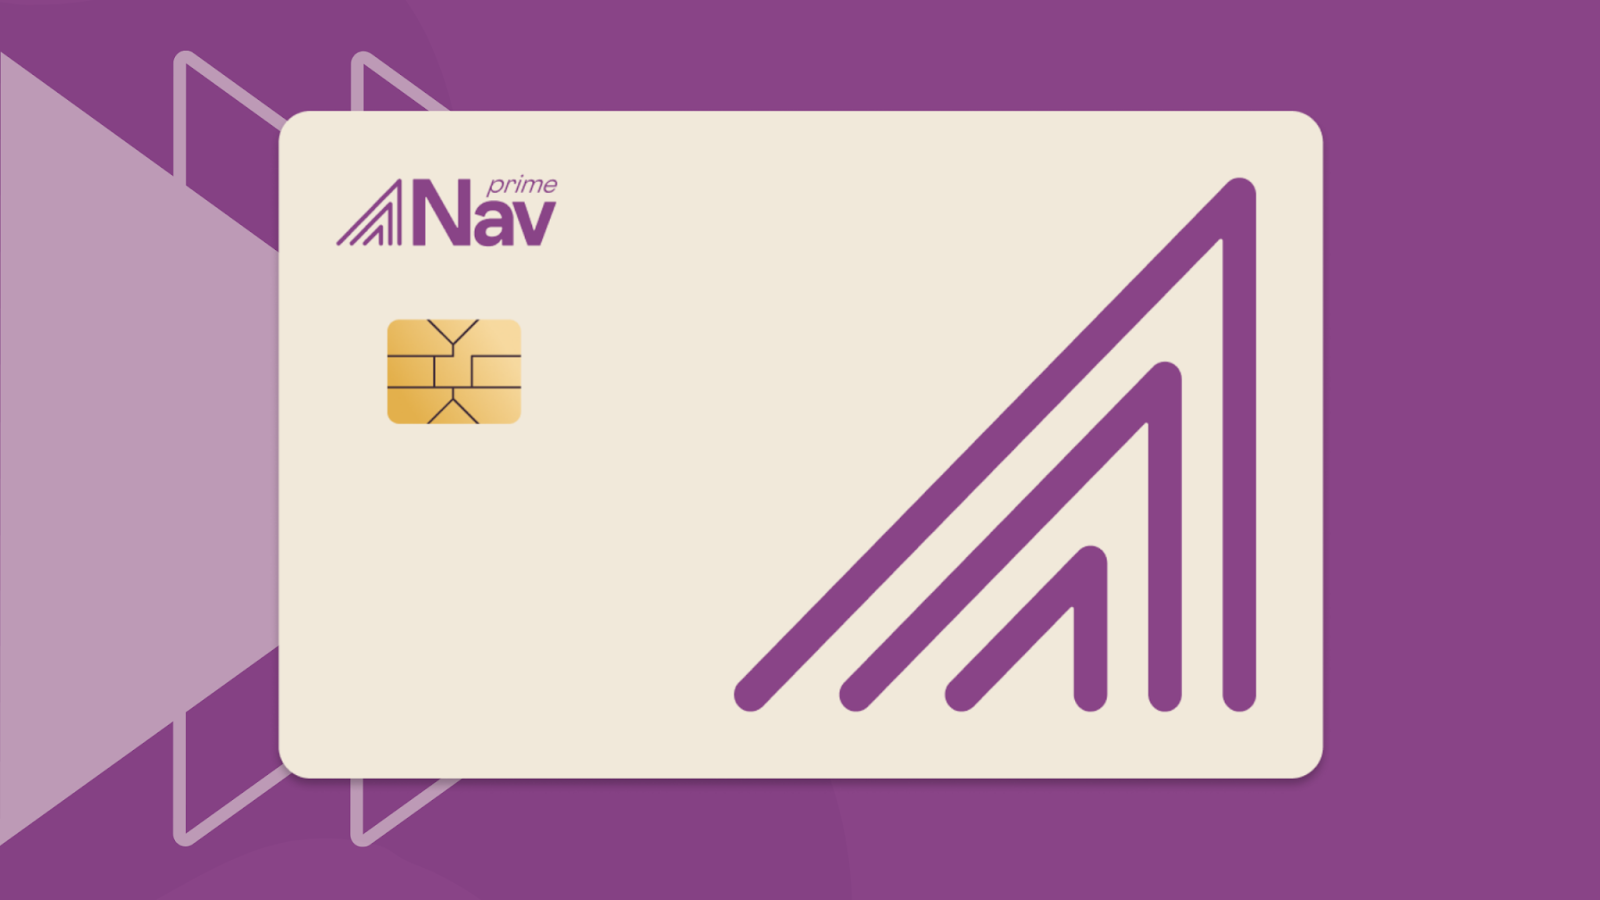
Nav Prime Business Credit Card

In the world of small business, access to credit can be a game-changer. Whether you’re a seasoned entrepreneur or just starting, the financial flexibility to seize opportunities, manage cash flow, and fuel growth is essential. 

That’s where the Nav Prime Card might step in as a compelling tool to help you navigate the complex landscape of business credit. 

But, is it right for you?…That’s what I’m going to answer here.

This is what’s in store: 

  • What is the Nav Prime Card?
  • Nav Prime Card Overview
    • Business Credit Building Features
    • No Security Deposit Required
    • Daily Autopay Feature
    • Second Monthly Tradeline
  • Who Wouldn’t Want a Nav Prime Card?
  • How to Get Started with the Nav Prime Card
  • Frequently Asked Questions
  • So, is the Nav Prime Card legit?

Now, let’s roll! 

What is the Nav Prime Card?

The Nav Prime Card is a charge card offered by Nav Prime ($49.99/month), designed for small businesses. It allows users to build business credit without an annual fee or personal guarantee. Unlike a credit card, it requires no security deposit and is linked to the user’s business checking account for daily use.

Nav Product Plans & Pricing

Nav can boost your business credit score and provide personalized funding recommendations for your small business you can't find anywhere else.

Start Now
Lasso Brag

This card is more than just a piece of plastic. It can be a financial lifeline for small businesses, offering a range of benefits designed to help you build, strengthen, and leverage your business credit profile. 

The Prime Card is issued by Blue Ridge Bank, N.A., adding a layer of credibility. Moreover, Nav, the company behind Nav Prime, is a well-established player in the business credit space, offering a range of financial tools and resources for businesses.  

Nav Prime Business Credit Card Review

Before Nav became Nav in 2012, the company was called Creditera, and was helping to boost business credit scores before most of the other players in the game.

Let’s dive into the details and explore why the Nav Prime Card is becoming a top choice for savvy entrepreneurs.

→ Recommended: Nav Review: A Tool that Helps Build Up Your Business Credit Score 

Nav Prime Card Overview

When it comes to the financial success of small businesses, one element often stands out: building a robust business credit profile. But, this isn’t always straightforward to achieve, especially if you’re just getting started or have limited credit history. 

Nav Business Credit Card

That’s where the Nav Prime Card steps in, offering a solution to this common challenge.

Business Credit Building Features

Building a robust business credit profile is a cornerstone of financial success for small businesses. However, it’s not always easy, especially if you’re just starting or have limited credit history. 

The Nav Prime Card is specifically designed to address this challenge.

Here’s how it works: 

  • It’s a charge card – Unlike traditional credit cards, the Nav Prime Card is a charge card, which means you need to pay your balance in full every month.
  • There’s no credit check – One of the hurdles many small business owners face is the dreaded credit check. The Nav Prime Card removes this barrier by not requiring a credit check for approval. This is fantastic news for those with less-than-perfect credit or those looking to avoid inquiries on their personal credit reports.
  • The account reports as a tradeline – The Nav Prime Card reports your payment activity as a tradeline to major credit bureaus. This is where the magic happens; your responsible card usage translates into positive data on your business credit report, gradually boosting your business credit scores.

→ Recommended: Using 30 Day Net Vendors to Build Your Business Credit Score 

No Security Deposit Required

Securing a traditional business credit card often involves putting down a security deposit, which ties up your capital. The Nav Prime Card eliminates this requirement, giving you access to credit without tying up your cash. It’s a win-win for your business’s financial health.

Daily Autopay Feature

Managing your credit card balance can be a juggling act. The Nav Prime Card simplifies this process with its daily autopay feature. Instead of fretting over a big monthly bill, your card balance is automatically paid down daily, which reduces the risk of carrying a high credit balance and potential interest charges.

Second Monthly Tradeline

In the world of credit building, tradelines are your best friends – The Nav Prime Card provides a unique advantage by automatically sending two monthly tradelines to all three major credit bureaus. This means your positive payment history is widely reported, strengthening your business credit profile faster.

But, it’s not right for everyone. 

→ Recommended: Here’s How to [Actually] Get Business Credit With Just an EIN +More Options 

Who Wouldn’t Want a Nav Prime Card? 

Nav Prime Business Credit Card Reviews

While while Nav Prime has a good offer, here are some of the groups who might not want to take advantage of the card offer:

  1. Budget-savvy startups – If you’re a fresh-faced startup trying to make every dollar count and the Nav Prime Card asks for a monthly fee of $49.99 for Nav Prime, this could throw a curveball into your penny-pinching game. Early-stage businesses might steer clear to keep their costs in check
  2. Privacy buffs – If you need to guard their data like a treasure chest, keep in mind that the Nav Prime Card wants access to your bank accounts to set a credit limit. If you need to be all about data security and privacy, you might go, “No way!” and opt for another option. (But, nearly all card offers will require that you share at least some identifying info).
  3. Geographically-challenged folks – Is your business California, Nevada, North Dakota, or South Dakota? Unfortunately, the Nav Prime Card doesn’t roll out the welcome mat in these states. So, if you’re doing business in any of these areas, it’s a no-go. 
  4. Owners looking for a credit card – If you’re in the market for an unsecured credit card that you can use to expand and grow your business, you don’t need a business credit builder card (you might check out one of these instead). 

These are the kinds of folks who might give the Nav Prime Card a polite pass. Whether they’re all about frugality, data security, or just prefer a different financial vibe, they’ve got their reasons to set their eyes on a different offer.

→ Recommended: Torro Business Funding Review: Is This “Zero Hassle” Offer Legit?

How to Get Started with the Nav Prime Card

Now that you’re intrigued by the Nav Prime Card’s benefits, you might be wondering how to get your hands on one. 

Here’s a step-by-step guide to kickstart your journey to building and leveraging business credit with Nav Prime:

  • Step 1: Check your eligibility

Before applying for the Nav Prime Card, ensure that you meet the eligibility criteria. While the card is designed to be accessible, it’s essential to confirm that your business qualifies.

In simple terms, if you want to sign up for a Platform Account, you need to meet some requirements:

  • Your business must be based in the United States.
  • You should have an active Nav Prime subscription.
  • You have to complete identity verification, which means proving who you are.
  • Your business can’t be involved in certain activities like adult entertainment, selling cannabis, dealing with cryptocurrency, running gambling or online gaming, or anything else that doesn’t go well with this card.
  • The person applying for the account must be at least 18 years old and allowed to do this on your behalf.
  • They might look at some other things to decide if you can get an account or the card, but that’s up to them.
  • Step 2: Apply online

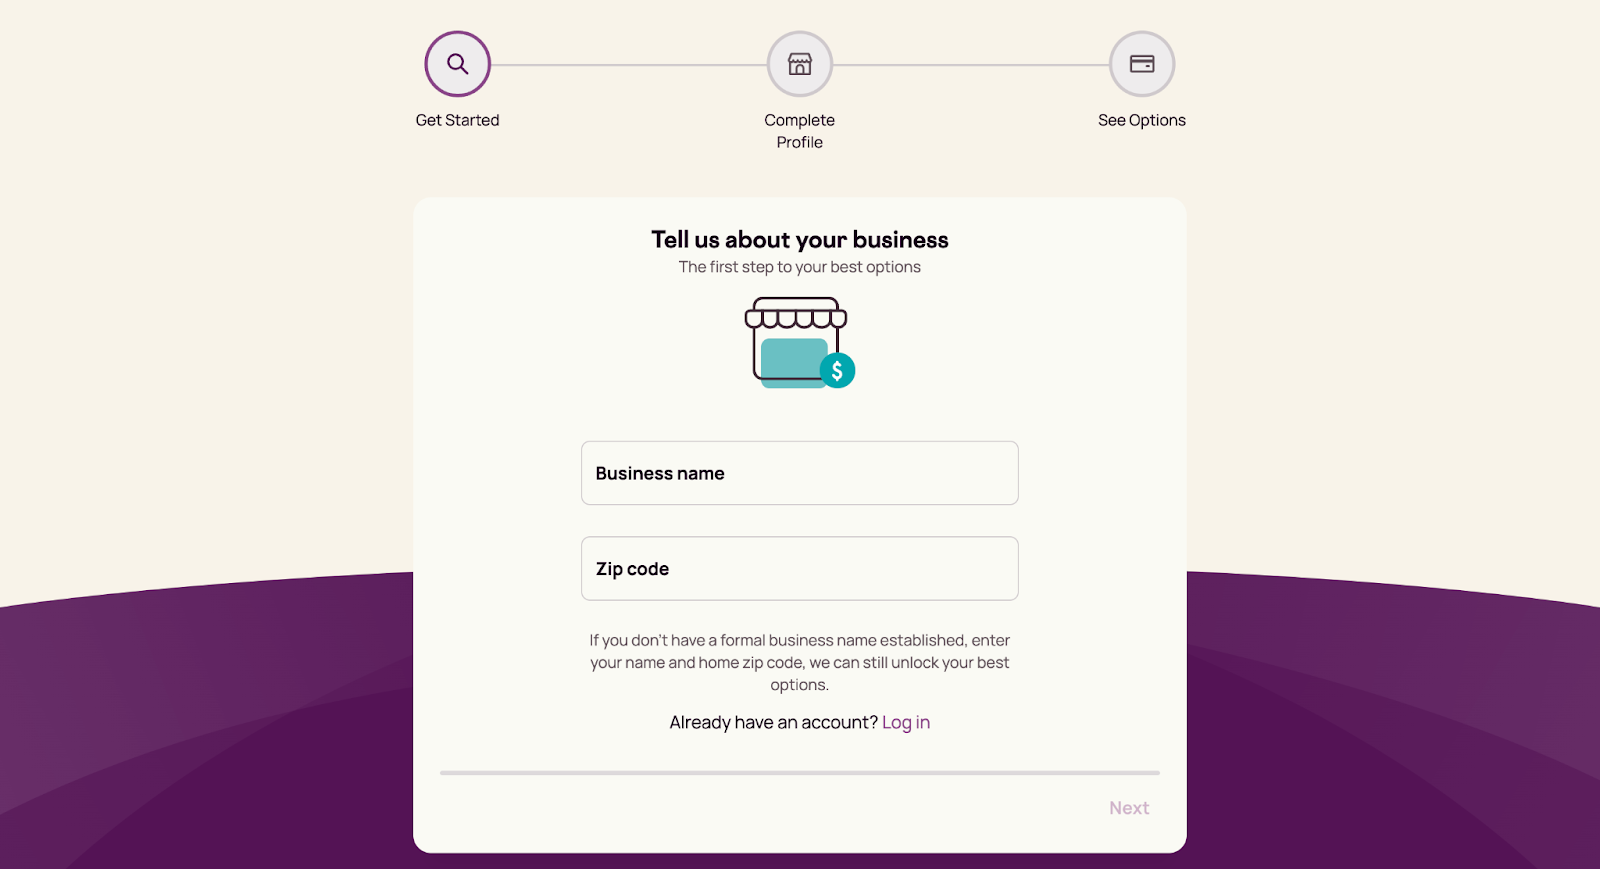
The application process for the Nav Prime Card is straightforward and can be completed online. Be prepared to provide basic information about your business, such as its legal structure and industry.

Nav Prime Business Credit Card Application
  • Step 3: Link your bank account

To set your credit limit and enable daily autopay, you’ll need to link your business bank account to your Nav Prime Card account – This step streamlines your finances, providing insights you can’t get from your bank alone.

  • Step 4: Use your card responsibly

Once you receive your Nav Prime Card, it’s time to put it to work. Use it for your everyday business expenses…but remember that it’s a charge card, so paying your balance in full each month is crucial.

  • Step 5: Watch your business credit grow

As you consistently use your Nav Prime Card and make on-time payments, you’ll start to see the positive impact on your business credit profile. Over time, your business credit scores will rise, opening doors to better financing options.

Nav Prime Business Credit Card Login

Frequently Asked Questions

What's the difference between a charge card and a credit card?

While both types of cards allow you to make purchases, there’s a key distinction. A charge card requires you to pay your balance in full each month, while a credit card allows you to carry a balance and make minimum payments. The Nav Prime Card is a charge card, offering the benefits of credit without the risk of long-term debt.

Can the Nav Prime Card help me secure business financing?

Yes, absolutely. By consistently using and managing your Nav Prime Card responsibly, you’ll build a strong business credit profile. This, in turn, enhances your eligibility for various financing options, including business loans, lines of credit, and more favorable terms.

Is the Nav Prime Card available nationwide?

Nav Prime Card is available in most states; however, it’s not currently offered in California, Nevada, North Dakota, or South Dakota.

How long does it take to see improvements in my business credit scores with the Nav Prime Card?

The timeline for credit score improvement can vary based on several factors. According to data tracking Experian® Intelliscore Plus business credit scores, many users have seen improvements of up to 50% in the first three months of having Nav tradeline reporting. Results may vary, but responsible card usage is key to achieving these improvements.

So, is the Nav Prime Card legit? 

The Nav Prime Card is more than just a business charge card; it can be a powerful tool for building, strengthening, and leveraging your business credit profile.

 With its unique features, including no credit checks, no security deposit, daily autopay, and the reporting of two monthly tradelines, it’s a valuable asset for small business owners looking to secure better financing options and improve their financial health. 

If you’re ready to take control of your business credit journey, you can spare $49 per month for full access to Nav Prime, and if you’re in a region where the offer is available, the Nav Prime Card is probably worth looking into.

Do you want to learn how to get up to $100K in business credit in as few as 30 days? Join Business Credit Workshop today!

nav-try-2

Behind the Scenes of Become.co: A Comprehensive Review

By Joe

Become.co review

Become.co – aka “Become” – is a relatively new player in the online lending field, offering financial solutions for owners looking to optimize profits and obtain funding to grow their business. 

The offer has received mostly positive reviews with a Trustpilot rating of 4.6 (believe it or not, this is impressive for a financial offer). Users have praised their services, highlighting quick and effective funding solutions. They’ve also mentioned friendly and professional staff, as well as seamless processes.

Become seems to go above and beyond traditional business lenders, but is the offer real or hype? 

That’s what I intend to explain (in detail). Let’s explore everything Become might be able to help you achieve, and see how they stack up next to competitors. 

Here’s what’s in store: 

  • What is Become.co?
  • What Type of Business Loan Can You Get Through Become?
    • How to Qualify for Funding
  • eCommerce Loans
    • The BeProfit™ App for Online Sellers
  • Industry-Specific Loans
  • LendingScore™ & MatchScore™
  • Frequently Asked Questions
  • Conclusion

Let’s begin! 

What is Become.co? 

Become was founded in 2016 by Amir Leitersdorf, Daniel Katz, Eden Amirav, Guy Zipori, Iri Amirav, Ofer Ariel, and Uri Sittan. The company is based in San Mateo, California, and has received Series A funding totaling $15.2 million. 

The offer is an end-to-end financial optimization platform and loan marketplace for small and medium-sized businesses (SMBs). In a word, it uses advanced algorithms to provide customized funding offers to SMBs, helping them scale and grow their businesses.

Become.co login

We’ve seen comparable business funding algorithms before – from companies like Divvy (credit card), Fundbox (loans/credit lines), and Lendio (funding marketplace), to name a few. But, Become doesn’t just use technology to match business owners with lenders.

Become goes a bit farther with their offer, and gives business owners access to solutions that help them scale: 

  • A vast array of business loans from various lenders
  • Transparent LendingScore™ dashboard
  • MatchScore™ to pair SMBs with lenders 
  • Automated application review
  • The BeProfit app (to help track and analyze eCommerce profits)

Let’s peek behind the curtain at the solutions you might want to take advantage of. 

Recommended: 6 Best Fintech Credit Cards to Apply for (Consumer & Business)  

What Type of Business Loan Can You Match With Through Become? 

As I said, Become can get you access to an array of loans. But, in straightforward terms, what’s this mean for you? 

Here are the types of business loans Become can match you with:  

  • Commercial vehicle loans
  • Startup business loans
  • Asset-based loans
  • SBA loans
  • Lines of credit 
  • Business equipment loans
  • Unsecured business loans
  • Invoice factoring & merchant cash advances (MCAs)

As you first dive-in to the offer, it appears that Become is like a Credit Karma for business (though they’ve referred to themselves as the “Tinder” for business). 

You might also like: Torro Business Funding Review: Is This “Zero Hassle” Offer Legit?

How to Qualify for Funding

In sum, Become wants to see your credit score (it seems that they use their own proprietary LendingScore™ as opposed to Paydex or FICO), time in business, and revenue. 

Keep in mind that since Become works with so many lenders, a poor credit score won’t necessarily disqualify you from obtaining funding. But, it might limit you to certain types of loans (probably high-interest funding like MCAs or invoice factoring). 

If you’re based in America, you’ll need a business that’s been operational for at least 3 months. This qualification doesn’t seem to be negotiable, and the only way around it would be a creative solution like purchasing a shelf company. 

Finally, Become wants to see that your business brings in an average of $5K in revenue per month.

Now, if you don’t qualify for funding through the platform, you will be informed about why, and shown how you might improve your business health and improve your LendingScore.™  

eCommerce Loans 

Working in the eCommerce space? If you sell on Amazon or Shopify, you can connect your store to the platform (no paperwork required) and find out if you qualify for funding – you can potentially receive up to $100K within a day. 

You may also need to connect to your online advertising channels to rate your marketing efforts. 

Currently, Become partners with Kapitus, Everlasting Capital, and Pearl Capital to match funding offers with online sellers who qualify. 

Here’s what you should know about these partners:

  • Kapitus requires a 625 credit score, 2+ years in business, and $250K annual revenue 
  • Everlasting Capital primarily offers MCAs & equipment financing, which are likely high-interest
  • Pearl Capital is a technology partner that probably makes Become’s business analysis possible
Become review

This should give you an idea whether or not it’s worth applying for an eCommerce loan through Become – Keep in mind that the platform will show you personalized areas for improvement if you aren’t currently eligible for financing through one of their partners. 

The BeProfit™ App for Online Sellers  

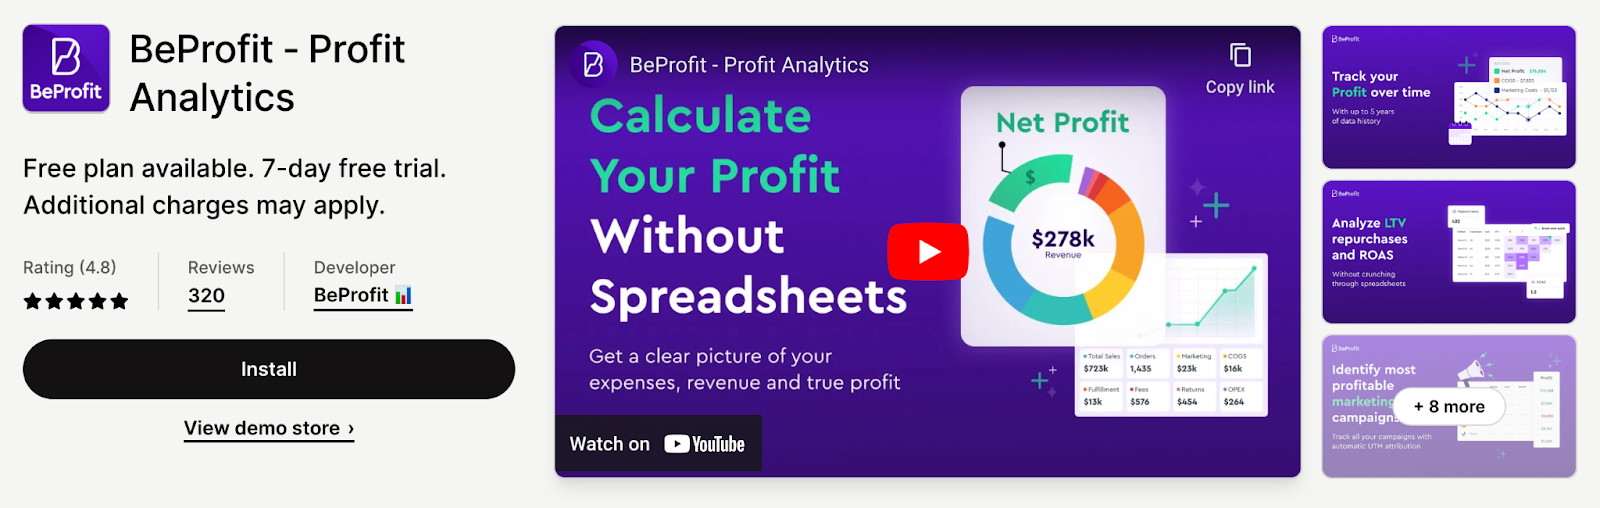
Next, let me introduce BeProfit: It’s an app that helps you dig deep into your online sales profits, so you’re not just guessing about your financial health.

BeProfit app

BeProfit gets all your expenses, from shipping to discounts, neatly organized in one place. You can quickly spot what’s boosting your profit and what’s dragging it down, so you can make smart decisions.

Plus, it’s super user-friendly. No need to drown in complicated numbers and reports. BeProfit simplifies everything into easy-to-understand reports, giving you more time to focus on growing your business.

Now, is it relevant or right for you? 

BeProfit is available on Shopify, Woo, and Amazon, and costs from $20 to $2000 per month to use (though you can use it for free on Shopify if you have fewer than 5 monthly orders).  

Note: All plans include features related to shipping, discount, products, inventory, marketing, and returns. 

Monthly PriceYearly PriceOrdersShopsFeatures
Basic$20$2402001Profit Dashboard, Custom Expenses 
Advanced$60$7206001Advanced Analytics, 3 Team Members
Pro$120$144012001Retention Analytics, 5 Team Members
Plus (Custom)Starts at $200–UnlimitedUnlimitedDeep Analytics, VIP Support

Please note that the prices mentioned are subject to change, and it’s always a good idea to check the latest pricing for the most up-to-date information.

Industry-Specific Loans

While their offer for online sellers stands out, eCommerce isn’t the only niche that Become caters to. The company is all about helping businesses get the right funding they need. They offer tailored loans for various industries. 

Become business loan

Whether you’re in the hotel business, a contractor, a realtor, or even run a restaurant, they’ve got you covered. Construction companies can find financing options that suit their needs, and the same goes for trucking businesses. It’s like a one-stop-shop for business funding.

What’s cool is that they use technology to match you with the best lender for your specific industry. So, you’re not dealing with a generic loan but one that understands the challenges and opportunities in your field.

Plus, they make it easy to apply, and you can compare offers to choose what works best for your business. So, if you’re in one of these industries and need financing, it might be worth checking out – It’s all about making business funding as simple as walking into a convenience store.

LendingScore™ & MatchScore™  

Before we wrap up, let’s get a quick overview of how LendingScore and MatchScore work.

LendingScore is like a financial fitness tracker for your business. It delves into your financial details, analyzing your credit, income, and history to determine how prepared you are for a loan. Instead of filling out numerous loan applications, LendingScore™ streamlines the process by allowing you to submit just one. Then, it takes on the role of matchmaker, connecting you with top lenders who are more likely to approve your loan application. It’s akin to having a personal coach for your business finances, helping you navigate the world of loans with ease.

On the other hand, MatchScore is your loan cupid. This tool takes your business’s financial profile and starts swiping right on lenders who are a perfect fit. Think of it as a dating app, but for loans! Instead of you scouring the market for lenders, MatchScore does the legwork for you. Its primary goal is to find the loan that aligns perfectly with your business needs. No more blind dates with banks – MatchScore ensures that you and the lender are a match made in financial heaven.

In summary, LendingScore assesses your loan readiness, while MatchScore acts as your personal loan matchmaker. With these handy tools, you can navigate the loan application process effortlessly and discover the ideal financing option that suits your business like a glove. 

Frequently Asked Questions

Can you get a loan for eCommerce?

Yes, you can get a loan for your eCommerce business. Many lenders offer small business loans for eCommerce, like Become and Stripe Capital.

Can you do eCommerce with no money down?

It’s tough but possible. Consider options like drop shipping or print-on-demand, where you don’t need upfront funds for inventory. And, some people who don’t want to pay to host a website, sell manually on Instagram, Facebook Marketplace, and Craigslist.

How to get a loan to start an eCommerce business?

To get an eCommerce loan, prepare a solid business plan, demonstrate your ability to repay, and find a lender that fits your needs.

How much money do you need for eCommerce?

The amount varies, depending on your niche and plans. Costs can include website development, inventory, and marketing.

Do you need a lot of money to start eCommerce?

Not necessarily. Many start small and reinvest profits to grow over time. Careful planning can help you start with a lean budget.

Conclusion

So, is Become the real deal or just a bunch of hype? 

My opinion: it appears to be a promising financial optimization and funding platform for SMBs – Their tailored funding solutions and the positive Trustpilot reviews are strong indicators of their effectiveness in helping businesses grow.

However, as with any financial service, you need to do your due diligence and thoroughly assess whether Become’s offer aligns with your needs, and if it’s necessary. 

So, do you prefer convenience or control – In my opinion, Become is one of the most convenient business funding offers out there, but it doesn’t give SMBs the ultimate control over their finances. 

Would you be better off to raise money through Kickstarter, explore an offer like Fund&Grow or Lendcred…or build your business credit and hand-pick the offers you want to apply for?  


Want to learn how to obtain up to $100K in business credit in as few as 30 days? Join Business Credit Workshop today.

6 Best Fintech Credit Cards to Apply for (Consumer & Business)

By Joe

best fintech credit card

Are you an individual considering a slick, new way to use credit? Or, a business owner looking to supercharge your finances with the perfect fintech credit card? Look no further! 

Here, we’ll dive into the exciting world of fintech credit cards, introducing you to top contenders like Divvy, CredAI (the illustrious Unicorn Card), Bluevine, Stripe, Ramp, and Brex – essentially free credit cards for everyone. 

Fintech is making credit cards weirder, but also a lot more fun…Whether you’re a student or seasoned entrepreneur, you can navigate the fintech card landscape, making sure you’re armed with the right knowledge to make the best decision for your situation. 

Here’s what’s in store: 

  • What is a Fintech Credit Card?
  • Explore the 6 Best Fintech Credit Cards
    • 1. Brex – Your Stealthy Fintech Ally
    • 2. Divvy – The Power Credit Card
    • 3. Bluevine – Fintech Business Checking & Credit
    • 4. Stripe Corporate Card – Cashback and More
    • 5. Ramp – Redefining Fintech Credit Cards
    • 6. Meet the Unicorn Card – CredAI
  • Frequently Asked Questions
  • Conclusion

Now, let’s get crackin! 

What is a Fintech Credit Card?

In simple terms, a fintech credit card combines the innovation of financial technology (fintech) with the convenience and power of credit cards. Fintech credit cards often come with unique features, competitive rates, and advanced tools that empower business owners to manage their finances efficiently.

Explore the 6 Best Fintech Credit Cards

Let’s take a closer look at some of the leading fintech credit cards that are revolutionizing the way individuals and business owners manage their finances. 

1. Brex – Your Stealthy Fintech Ally

fintech credit card processing

For: Businesses seeking a free corporate card

The Brex Corporate Card is an enticing choice for businesses seeking a no-personal-guarantee credit card with rewards. The card, issued through Brex’s financial operating system, caters to tech, life sciences, and eCommerce companies. I

t’s characterized by its absence of annual fees, interest charges, and personal credit checks. Instead, creditworthiness is determined based on the company’s likelihood to repay funds. Brex offers various account options, including Cash, Card, and Cash & Card, tailored to different financial needs.

The card boasts rewards such as up to 30K bonus points, points per dollar spent, and partner perks, including discounts with industry giants like AWS, Slack, and Google Ads. With a focus on expense management, the card offers real-time tracking tools, virtual cards, and expense automation. Qualification requires a US-based business with an EIN and a business bank account.

Learn more: Brex Card Review: Is This Corporate Card Offer Too Good to be True? 

2. Divvy – The Power Credit Card

fintech credit builder

For: Business owners

Divvy is not just a business credit card; it’s a comprehensive financial solution tailored for businesses of all sizes. With Divvy’s innovative features, you gain access to budgeting tools, virtual cards, and enticing rewards. 

This high-tech card isn’t just a piece of plastic; it’s a gateway to efficient expense management, AP automation, and seamless spending control. Divvy’s user-friendly platform empowers businesses to allocate budgets, set spending limits, and automate payment approvals. 

The virtual card feature adds an extra layer of security for online and high-risk transactions. Additionally, Divvy offers a tiered rewards system, giving you the opportunity to earn points for your spending habits. These points can be redeemed for travel, gift cards, statement credits, or cash back. 

While Divvy’s customer service receives mixed reviews, the platform’s help center and communication tools aim to provide comprehensive assistance. If you’re a business owner seeking advanced financial tools that streamline your operations and enhance your financial management, the Divvy credit card might just be the power boost your business needs.

Learn more: In-Depth Divvy Credit Card Review: Read This Before You Apply 

3. Bluevine – Fintech Business Checking & Credit 

fintech credit union

For: Small business owners

Bluevine presents a game-changing solution for small business owners with its high-yield free business checking account. With the ability to earn 50X the national average interest on balances up to $100K, this offering stands out in the financial landscape. 

The account comes with no monthly fees or minimum deposits, making it particularly appealing for digitally-focused businesses, freelancers, and service providers. While Bluevine’s single-account holder policy and minimum requirements to collect interest might not suit all businesses, the benefits are noteworthy. 

The platform’s integration of sub-accounts, dedicated account numbers, and unlimited fee-free transactions adds to its appeal. Bluevine’s strategic partnership with MoneyPass ATM network provides widespread access to surcharge-free ATMs. However, cash deposits made at ATMs incur a fee. The option to grant access to your account without sharing login credentials is a unique feature, enhancing collaboration with bookkeepers and accountants.

Moreover, Bluevine’s line of revolving credit up to $250K, coupled with competitive rates, can offer additional financial support for qualifying businesses. Overall, Bluevine’s innovative offerings make it a compelling choice for businesses that prioritize digital transactions and aim to make the most of their account balances.

Learn more: Bluevine Review: Free, High Yield Small Business Checking! Are They Serious? 

4. Stripe Corporate Card – Cashback and More

Stripe credit card

For: Business owners using Stripe Payments

The Stripe Corporate Card offers a compelling credit card option for existing Stripe Payments users. This card comes with unique advantages, including no fees, 0% interest, and an appealing 2% cashback on spending in top two categories. 

Notably, with a spending of $5,000 on the Stripe Corporate Card, users gain access to $50,000 in free transactions on the platform. Furthermore, the card allows users to customize their logo, create branded cards, and even originate credit cards for their customers. 

The card is available as both virtual and physical options, with the latter delivered within days. Stripe’s innovative approach is fueled by its primary revenue source—