• Home
  • Free Funding Guide
  • What We Offer
    • Products
    • Services
    • Free Guide
  • About Us
  • Contact
  • Sign Up

  • Ask Joe Any Question!
  • Business Credit Cards
  • Business Line of Credit
  • Topics

Grasshopper Bank Review for Business Banking, Lending, & More 

February 22, 2025 By Joe

Grasshopper Bank

Key Takeaways

  • Grasshopper Bank is a digital-only, FDIC-insured institution.
  • Business accounts earn interest with no monthly fees.
  • SBA 7(a) and 504 loans support business growth.
  • Sponsor finance loans help with buyouts and acquisitions.
  • Commercial real estate and yacht loans start at $1 million.
  • API banking allows businesses to automate transactions.
  • Grasshopper has an A+ BBB rating but mixed reviews.
  • Recent legal challenges may be a concern for some.

If you’re an owner with an interest in digital banking for your small or medium-sized business, Grasshopper bank may have shown up on your radar. If so, surely you have questions about the offer. 

When an institution seems like it might be a little too new or a slightly more unconventional than what you’re familiar with, it’s smart to do your research. Here, I lay out everything you need to know about what to expect if you open an account. From a summary of the business banking and funding offer to info about leadership, trust signals, and Grasshopper Bank reviews, here’s the scoop. 

This is what’s in store: 

  • What is Grasshopper Bank?
    • Company Overview
  • How Does Grasshopper Bank Work?
    • 1. Open an Interest-Earning Business Bank Account
    • 2. Apply for Small Business Administration Loans
    • 3. Make Use of “Sponsor Finance” (Secured Loans)
    • 4. Get Funding for Commercial Real Estate or a Yacht
    • 5. Integrate the Grasshopper System With Your Tech
  • What are the main differences between Brex and Grasshopper Bank?
  • Frequently Asked Questions
  • Conclusion: Is Grasshopper Bank Legit?

Now, let’s dive in! 

What is Grasshopper Bank? 

Grasshopper bank review

Grasshopper Bank is a digital financial institution serving small businesses, startups, and investors in the so-called “innovation economy”—companies driven by technology, digital tools, and entrepreneurship.

Whether this term reflects tailored services for tech-driven businesses or is just marketing language is unclear. 

Either way, the bank offers:

  • Business checking and savings accounts
  • SBA lending
  • Fintech solutions like embedded finance and API banking

You won’t find Grasshopper Bank locations because they’re an online-only institution. Grasshopper emphasizes their client-first approach and use of technology to deliver secure and efficient banking experiences.

You might also like: 6 Best Fintech Credit Cards to Apply for (Consumer & Business) 

Company Overview

How long has Grasshopper Bank been in business?

According to Crunchbase, Grasshopper Bancorp, Inc. is a privately-owned, New York-based, “woman-led,” for-profit company that was launched by Judith Erwin in 2016. 

However, neither Grasshopper nor Judith Erwin are listed in New York’s Doing Business Portal. However, the company is listed in Delaware’s corporate directory, the FDIC approved their application for insurance in 2018, and they’re headquartered at 915 Broadway, 7th Floor, New York, New York. 

Erwin seems to have left Grasshopper in 2021 to pursue private, strategic business consulting. The company’s current CEO is Mike Butler. So, while the company was founded by a woman, it’s not currently woman-led. 

Prior to taking the reins at Grasshopper, Butler served as the President of Consumer Finance at KeyCorp and spent nearly 14 years as the President and CEO at Radius Bank. 

Who is the CEO of Grasshopper Bank?

While Butler seems like he would be a good leader, based on his experience, I was disappointed to see that I couldn’t find specific information about how employees feel about him on Glassdoor. 

Still, they’re A+ rated with the Better Business Bureau (BBB), with only 4 total complaints—This is super rare. However, some customer reviews on the BBB website express dissatisfaction, citing issues such as unexpected account closures, lack of communication, and delays in fund returns. They’ve been BBB-accredited since 2024. 

Who is the CEO of Grasshopper Bank?

And, over on Trustpilot, their TrustScore is above middling at 4.1 stars out of 5, where most reviews are outstanding. Positive feedback highlights knowledgeable and responsive customer service, with 68% of reviewers awarding 5 stars. However, 23% of reviewers rate the bank at 1 star, citing issues like unexpected account closures and “unhelpful security practices.”

Grasshopper Bank Review Trustpilot

And, Reddit reviews (usually the most critical) on Grasshopper Bank are mixed. Some users find it better than traditional banks, but others report slow transactions, account access issues, and poor communication. Common complaints include long mobile deposit times, unexpected fees, and difficulties resolving account problems. 

Grasshopper bank Reddit

After a quick search for lawsuits, I found that, as of February 16, 2025, Grasshopper Bank is facing legal disputes, including an $8 million loan default lawsuit and a contract-related case in Florida. While lawsuits aren’t unusual for banks, you may want to consider how these issues could impact service, lending policies, or financial stability.

In sum, Grasshopper Bank has been around for at least seven years (as of 2018 when their FDIC insurance was approved), led by experienced executives with mostly positive but mixed customer feedback. While many praise its service, some report account closures and fund access issues. It holds an A+ BBB rating and a solid Trustpilot score, but recent lawsuits are something to keep in mind.

You might also like: Best Business Bank Accounts: 5 Top Picks for Small Businesses 

How Does Grasshopper Bank Work? 

Now, for the meat and potatoes—What, exactly, can you get if you open a Grasshopper Bank account? And, how is it different from other offers? 

1. Open an Interest-Earning Business Bank Account 

Grasshopper Bank wiki

A business bank account that earns interest can help maximize your idle cash while your funds stay accessible. Grasshopper Bank offers digital-first checking and savings solutions for small businesses and startups. With competitive interest rates and no monthly fees, it provides an easy way to grow your money while managing business expenses.

Here’s what you get with a Grasshopper business bank account:

  • Up to 1.80% APY on checking balances 
  • Up to 3.55% APY on savings balances over $25K
  • No monthly fees or overdraft charges
  • Unlimited ACH transfers and fee-free transactions
  • 1% cashback on online and signature-based debit card purchases
  • 24/7 mobile and online banking with instant-issue virtual debit cards

Opening an account takes just a few minutes online, which can give you immediate access to digital banking tools to streamline payments, automate bookkeeping, and simplify cash flow management.

Grasshopper Bank Login

In addition, Grasshopper advertises enhanced security features that include fraud monitoring, encryption, and dual approvals for transactions.

*Grasshopper also offers specialized banking for venture capital and private equity firms. 

You might also like: 3 Best Credit Unions for Small Business Banking in 2024 

2. Apply for Small Business Administration Loans

Grasshopper Bank SBA lending

As an SBA Preferred Lender, Grasshopper streamlines the loan process with a digital-first application, which can potentially reduce documentation requirements and accelerate approval times. Businesses can qualify for an SBA 7(a) loan in less than 10 minutes, making it easier to access financing for working capital, acquisitions, real estate, partner buyouts, and debt refinancing.

The bank provides two primary SBA loan options:

  • SBA 7(a) Loan – The most flexible SBA loan, used for general business expenses, acquisitions, refinancing, and more
  • SBA 504 Loan – Long-term, fixed-rate financing for purchasing commercial real estate, construction, or major equipment

You may be able to leverage Grasshopper’s SBA loans for expansion, succession planning, or debt consolidation. 

You might also like: This is the Truth About LenCred’s Small Business Financing 

3. Make Use of “Sponsor Finance” (Secured Loans)

Grasshopper bank secured term loans

Grasshopper Bank offers sponsor finance solutions designed to help businesses secure funding for acquisitions, buyouts, and working capital needs. Whether you want to expand operations or manage investment cycles, these lending options can provide structured, flexible financing to support your goals.

Sponsored finance options include: 

  • Senior Secured Term Loans – Might be Ideal for leveraged buyouts and add-on acquisitions
  • Revolving Lines of Credit – Can help cover working capital and corporate expenses
  • Delayed Draw Term Loans – Funding for acquisitions, growth capital, or deferred payments
  • Capital Call Lines – May bridge timing gaps between investments and capital inflows
  • Fund NAV Facilities – Use a fund’s portfolio as collateral to improve liquidity and returns

Grasshopper works with lower middle-market companies, typically those generating at least $8 million in annual revenue and $1 million in earnings (before interest taxes depreciation and amortization). The process is streamlined with digital banking tools to help make sure your transactions are efficient.

Grasshopper focuses on building long-term relationships by combining expert underwriting with technology-driven banking solutions to make the financing process smooth and efficient.

You might also like: The Ultimate Tillful Review (+Secured Credit Offer for Businesses) 

4. Get Funding for Commercial Real Estate or a Yacht

Grasshopper bank commercial real estate lending

If you need financing for commercial real estate or a yacht, there are specialized loan options that can help. For commercial properties, loans start at $1 million and are available for stabilized properties like multi-family buildings, medical offices, warehouses, retail spaces, and flex spaces. 

These loans are primarily offered in: 

  • New York
  • New Jersey
  • Eastern Pennsylvania

Borrowers can also access liquidity lines of credit to manage cash flow.

For yacht purchases, loan amounts range from $1 million to $10 million, with terms up to 20 years—Both fixed and adjustable-rate options are available. Some loans may also allow foreign registration or limited charter use. 

Both types of loans are designed to provide clear terms and a straightforward application process when you want to finance a major purchase.

You might also like: How to Get Money for Real Estate Investing: 18 Practical Ideas 

5. Integrate the Grasshopper System With Your Tech

Grasshopper Bank API

Grasshopper’s banking system can integrate directly with your technology, which can enable you to make financial transactions more seamlessly. With API banking and embedded finance solutions, you may be able to automate payments, transfers, and financial data within their own platforms.

Grasshopper’s Banking-as-a-Service (BaaS) and API banking provide tools to automate transactions like:

  • ACH
  • Wires
  • Real-time fund transfers

You can manage payments and bill pay from within your own software, monitor account balances and transaction details in real time, and even issue branded VISA® debit cards for customer transactions. 

Grasshopper bank branded Visa debit cards

These solutions can work for a wide range of industries, including fintech startups, B2B marketplaces, and manufacturers, which can help you streamline your financial operations.

Security and compliance are built into the system, with bank-level fraud prevention and regulatory protections. As a nationally chartered bank and FDIC member, Grasshopper makes sure all transactions meet strict risk management standards. 

You might also like: The PEX Card: Is it the Best Corporate Card for Your Business? 

What are the main differences between Brex and Grasshopper Bank? 

While I would think that online-only like Bluevine and Novo are more like direct competitors on the banking front, more people seem to want to know how Grasshopper stacks up against Brex.  

As of today, the popular search engine overview completely misses the mark on this front, with a seemingly outdated comparison.  

Grasshopper Bank vs Brex

As of February 16, 2025, Brex and Grasshopper Bank offer distinct financial services tailored to businesses, each with unique features and benefits:

  • Brex is a fintech platform that offers corporate cards, expense management, and high-yield business accounts—tailored for startups and high-growth companies.
  • Grasshopper Bank is a digital bank with interest-bearing accounts, cash-back debit cards, and SBA lending—more for small businesses that need straightforward banking with access to funding.
Brex LogoGrasshopper Bank Logo
Business accounts with spend management1.80% APY checking, 3.55% APY savings
Corporate credit cards with rewards1% cash-back Visa debit card
No monthly fees, no minimumsNo monthly fees, $100 minimum deposit
AI-powered expense automationBill Pay, invoicing, and bookkeeping
No lending; high-yield accountsSBA loans, SaaS funding via Capchase

In sum, Brex may be a good option if your main goal is financial automation and expense control. Meanwhile, Grasshopper may be better if you want small business banking with high-yield accounts and lending options. Both seem to cater to startups. 

Recommended: Brex Card Review: Is This Corporate Card Offer Too Good to be True? 

Frequently Asked Questions 

Is Grasshopper a real bank?

Yes, Grasshopper is a real, FDIC-insured digital bank that primarily serves small businesses, startups, and fintech companies. It operates as an online-only financial institution.

Is Grasshopper FDIC-insured?

Yes, Grasshopper Bank is FDIC-insured, meaning deposits are protected up to $250,000 per depositor, per account category.

Does Grasshopper Bank use Zelle?

No, Grasshopper Bank does not currently support Zelle for person-to-person payments. However, it offers other digital payment solutions for businesses.

How big is Grasshopper Bank?

Grasshopper Bank is a relatively small, digital-first financial institution focused on business banking. While it does not have physical branches, it provides banking services nationwide.

What is Grasshopper Bank’s routing number?

Grasshopper Bank’s routing number is 026013303.

Conclusion: Is Grasshopper Bank Legit? 

Grasshopper Bank is a legitimate, FDIC-insured digital bank that offers business banking, SBA loans, sponsor finance, and embedded finance solutions. They have competitive interest rates, no monthly fees, and digital tools for seamless transactions. While many businesses appreciate its features, some customers report issues with account closures and fund access.

Grasshopper may be a good fit for small businesses, startups, and investment firms looking for online banking with lending options and API integrations. However, businesses that need in-person banking or prefer traditional financial institutions might find other options more suitable. And, it’s always smart to review terms carefully before you open an account anywhere.

Are you ready to learn how to obtain up to $100K in business credit in as few as 30 days? Join Business Credit Workshop today!

3 Best Credit Unions for Small Business Banking in 2025

February 16, 2025 By Joe

Best Credit Union for Small Business 2020

Key Takeaways

  • Credit unions often offer lower fees, better interest rates, and flexible lending terms.
  • They provide personalized service and easier access to business credit.
  • Navy Federal, Financial Resources, and Sound Credit Union are our top choices.
  • Other options include Alliant, Consumers, America First, and Digital Federal.
  • Small community banks can also offer lower fees and flexible terms.
  • Research and compare options to find the best fit for your business.

As a small business owner or founder, where you choose to do your banking can have a major impact on your long-term operations. And, when researching the best bank or credit union for small businesses, you may have realized that you would rather work with a credit union. Now, let’s look at the top credit unions for small business banking. 

What you’ll find here: 

  • Are Credit Unions Better Thank Banks?
    • Are Credit Unions Better for Business Accounts?
  • The Best Credit Unions for Small Business
    • 1. Navy Federal Credit Union
    • 2. Financial Resources Credit Union
    • 3. Sound Credit Union
    • +Honorable Mentions
  • Final Thoughts

So, let’s get to it. 

First, Are Credit Unions Better Than Banks? 

There’s a longstanding debate about whether banks or credit unions are “better.” And, it’s important to understand the difference to answer this question. A bank is a for-profit institution and a credit union is a nonprofit organization that provides comparable financial services. So, what are the advantages of credit unions? 

At most credit unions, the shareholders are the members while banks funnel their profits to up the chain to its owners. This means that there is more opportunity for members to save on services and earn a larger percentage of total interest accrued with savings accounts and other investments. 

As a credit union member, you typically end up with lower interest rates and fees (a major plus). On the flip side, major banks typically have more branch locations where customers can do business and invest more in apps and convenience services. So, you could say that which is the best is a matter of preference. 

But, I have a tie-breaker: credit unions have less stringent and often flexible qualification terms for credit. You can’t walk into a bank like Wells Fargo and negotiate the terms of business banking fees, loans, or credit cards. At a credit union, more than not, you can because credit union underwriters usually work in-house and can modify terms and conditions of business and individual financial services. 

So, I say that credit unions are in-fact better than banks. Now, let’s move forward. 

But, Are Credit Unions Better for Business Accounts? 

Best Bank for Small Business

Aside from the general advantages above, there is another aspect of business banking with credit unions worth considering. When you bank with a credit union, you can leverage the perks above when obtaining business credit. For this reason, we prefer to work with credit unions. Alternatively, small community banks can be better for businesses than large banks. 

How to Leverage Business Credit to Transform Your Life 

Now, the Best Credit Unions for Small Business 

You should have a solid understanding of why or why not a credit union might be best for your small business banking. And, here are the top credit unions to join. 

1. Navy Federal Credit Union

With tons of free ATMs sprinkled throughout the United States and several other countries, Navy Federal Credit Union was created for members of the armed forces, DoD, or the National Guard. While you don’t necessarily have to be an active member to join, you must have ties to the military. So, if you are an active member, veteran, or a spouse, parent, grandparent, sibling, child, or grandchild of someone who qualifies, you can qualify for membership. 

If you are not a service member, you will have to apply in-person at a branch location. Once you are approved for a personal account, you can then apply for a business membership. And, Navy Federal has excellent offers for businesses.

  • 3 types of checking accounts (Basic, Plus, & Premium)
  • 3 types of savings accounts (Basic and Jumbo Money Market & Certificate)
  • Real estate, vehicle, and term loans
  • Business lines of credit 

Navy Federal is one of the best credit unions with the lowest rates and fees. Minimum deposits for business savings accounts start as low as $100. And, transaction fees range from $0 to $0.25. And, all accounts earn dividends. 

2. Financial Resources Credit Union

With 13 branch locations in New Jersey and New York, Financial Resources Credit Union has been the top SBA Lender in New Jersey since 2013. So, you know their business financial services are dependable.   

Here’s what you can leverage with Financial Resources Credit Union:

  • 2 types of checking accounts
  • 3 types of savings accounts (Business Purple, Money Market, & Certificates)
  • Real estate, equipment, and term loans
  • Lines of credit 

So, whether you’re investing in real estate or you simply want checking and savings accounts to process your business finances, Financial Resources gives you options. Here, terms are flexible and you can get expedited approval on SBA-backed loans because the institution is a preferred lender. 

3. Sound Credit Union

With 29 locations in the Puget Sound area of Washington State, Sound Credit Union is self-labeled “Washington’s Favorite Credit Union.” And, they stand out from most financial institutions in more than one way. 

For one, they cater to cannabis businesses, which isn’t common. Next, they offer low interest rates, cashback options on certain loans, and they do a lot to support the local community. Furthermore, they have over 5,000 shared branch locations and 30K+ free ATMs nationwide. 

And, businesses can take advantage of the following:

  • Checking accounts
  • Savings and certificate accounts
  • Cannabis (I-502 Analysis) business checking accounts 
  • Business loans
  • Business credit cards 

In addition, with Sound CU, you can access a full suite of business services that includes terminals and point of sale systems, eCommerce payment solutions, mobile card readers, payment acceptance, gift card, reward, and incentive programs, and mobile apps and software. The institution’s tech is as advanced as you can get with most major banks. 

+Honorable Mentions

Obviously, these three credit unions are only a small drop in the ocean of options. So, in case you aren’t able to select one of these three, I want to share four more credit unions that you can research yourself: 

  • Alliant Credit Union – 2 branch locations in Illinois and 80K+ free ATMs
  • Consumer Credit Union – 8 branch locations in Tennessee
  • America First Credit Union – Located in Ogden, Utah
  • Digital Federal Credit Union – 23 branch locations in Massachusets and New Hampshire, 5.9K shared branches, and 80K+ free ATMs 

Why choose a credit union instead of a bank?

Compared to a major bank, a credit union or small local community bank is likely to offer lower fees, increased savings, and more lenient qualification terms for lending. 

What are the disadvantages of credit unions?

Typically, credit unions run operations from their own funds, so they might offer less in the way of mobile apps, online banking features, and other conveniences. But, they still have many valuable perks. 

Are credit unions good for small business?

Credit unions can be beneficial for your small business. They offer lower fees and interest rates, personalized service, a local focus, easier access to credit, and the opportunity for relationship building. Research and compare different credit unions to find the one that suits your specific business needs.

Which bank is best for small businesses?

A small local community bank or credit union can be the best choice for small business banking. Fees are typically lower than those at major banks and lending qualification terms have more wiggle room. These institutions tend to have more control over their terms and conditions.  

How do I choose a bank for my company?

First, create a list of local small community banks and credit unions in your area. Then, call each institution on your list and ask about business checking and savings options as well as underwriting terms for business loans and lines of credit. Finally, choose the option that is the best fit for your operations and goals. 

Final Thoughts

The above-listed credit unions offer the best financial services for businesses. If you want your operations to run smoothly, you can’t go wrong with one of these choices. But, do your homework to make sure you choose the best institution to fit your needs.

To find out which banks and credit unions we’re currently working with to obtain lines of credit up to $100K in as few as 30 days, join Business Credit Workshop today. 

Honeycomb Credit Review: How Does Honeycomb Investment Work? 

February 9, 2025 By Joe

Honeycomb Credit Review

Key Takeaways 

  • Honeycomb Credit funds small businesses through debt-based crowdfunding.
  • Businesses can raise $25K to over $1 million from investors who earn interest.
  • Approval requires a personal credit check to assess financial health.
  • Owners must promote their campaigns to attract investors.
  • Investors have no control over business decisions.
  • Repayments are fixed monthly over 3 to 5 years.
  • Honeycomb takes a small cut of the funds raised.

Do you need funding to expand your small business? Or, are you interested in investing small amounts into smaller, local businesses? If so, Honeycomb Credit might be a real treat. 

Honeycomb Credit’s offer is a unique offer that enables businesses to grow and investors to earn interest through crowdfunding. Here, I’ll explain exactly what they’re offering, how it might benefit you, and turn you on to some potential alternatives. 

This is what’s in store: 

  • What is Honeycomb Credit?
    • Company Overview
  • How Does Honeycomb Credit Work?
    • Step 1: Sign Up for an Account
    • Step 2: Apply and Get a Credit Analysis
    • Step 3: Accept Your Funding Terms
    • Step 4: Prepare a Winning Investment Campaign
    • Step 5: Launch and Promote Your Campaign
    • Step 6: Get Funded and Repay Investors
  • Do Honeycomb Investors Get a Say in How Your Business Operates?
  • Frequently Asked Questions
  • Conclusion: Is Honeycomb Credit Legit?

So, let’s rock! 

What is Honeycomb Credit? 

Honeycomb Credit Website

Honeycomb Credit is a peer-to-peer platform that helps small businesses raise the capital they need to grow. Whether you’re looking to open a new location, upgrade equipment, or expand operations, you may be able to use Honeycomb to secure funding directly from your customers and community. 

Instead of relying on traditional bank loans, the platform connects you with everyday investors who believe in your business. 

And, according to Honeycomb’s advertising, small businesses that raise funds through Honeycomb Credit often experience significant growth—On average, businesses apparently see a 60% increase in revenue year over year after a successful funding round. 

Last year, they offered the Honeycomb Credit Golden Summer Grant, a $5K small business grant through the Skip platform.  

Honeycomb Credit Grant

To date, the Honeycomb Credit platform has helped over 400 business owners secure more than $30 million in investments, which supports over 1,100 jobs.

You might also like: A Full Skip Review: Business Grants, Funding, and More 

Company Overview

Honeycomb Credit Inc. is a Great Lakes-based, privately-held, for-profit corporation that was co-founded in 2017 by George Cook and Ken Martin. 

Prior to launching Honeycomb, Cook worked as an economist for the Bureau of Labor Statistics, then held marketing roles at Transunion and ZestFinance. 

Who owns Honeycomb Credit?

Meanwhile, Martin has a strong background in finance with experience as an analyst and executive at companies like RBS, Barclays Investment Bank, Uber, and RBC Capital Markets. 

As a team, these two are united by the vision to allow anyone to invest in the entrepreneurs and businesses that are most important to them, small ventures. 

While Honeycomb is not accredited by the Better Business Bureau (BBB), they still have an A+ rating on the platform with zero complaints—This is rare, especially for a financial offer that’s been around for 8 years. 

Honeycomb Credit Review BBB

Their Trustpilot Trustscore is telling too, at 4.5-stars out of 5, based on 92 reviews. Most people seem to be super stoked about the offer, while there are some complaints from investors. The main complaint is about issues with the repayment of their invested funds. To play devil’s advocate, here, small business investment is always risky. 

Honeycomb Credit Reviews

Since I didn’t see 100% satisfaction, I decided to hop over and check out Honeycomb Credit Reddit reviews. Again, the only complaints I found were from investors who didn’t see great returns, not small business owners. And, some investors love Honeycomb for the community involvement.  

Honeycomb Credit Review Reddit

In a nutshell, Honeycomb Inc. is a legitimate, well-rated company, yet it hasn’t been around for a full ten years, which can be telling that a company is going to last. Still, in the time it’s been in operation, it’s already gained a positive reputation. So, I think it’s definitely worth considering if you might benefit from the offer, especially as a small business. 

You might also like: Y Combinator: Fast Track to Success or Waste of Time? 

How Does Honeycomb Credit Work? 

Honeycomb Credit is essentially a crowdfunding platform that can help you raise capital for your small business from investors in your community. With these steps, you may be able to secure the funding you need. 

You might also like: A Full Skip Review: Business Grants, Funding, and More 

Step 1: Sign Up for an Account

Honeycomb Login

First, create an account on Honeycomb Credit by entering your email and password or use your Google or Facebook account. Verify your email, then provide basic details like your name, business name, address, phone number, and other necessary information. This sets up your profile so you can start the funding process.

⚠️ I don’t love that a Social Security number is required before the application process starts. To protect your financial info, don’t sign up until you’re sure you’re ready to invest or seek funding. 

Step 2: Apply and Get a Credit Analysis

Honeycomb Funding Application

Next, submit an application (via Loanwell’s loan origination technology) with details about your business, financials, and funding goals. Honeycomb Credit will review your financial history, check your creditworthiness, and evaluate your ability to repay the investment. This step usually takes 24 to 48 hours.

Recommended: Here’s How to Check Your Business Credit Score, Step-by-Step 

Step 3: Accept Your Funding Terms

Honeycomb Financial Strategies

Then, if approved, you’ll receive a term sheet outlining your loan details, including the amount you can raise ($25K to over $1 million), interest rates, and repayment terms. You’ll have the chance to review and accept the best terms for your business.

Recommended: No-Doc Business Loans: Get Funds Without Proof of Income 

Step 4: Prepare a Winning Investment Campaign

Honeycomb Investment

After that, work with a Honeycomb campaign manager to create a compelling pitch for investors. This includes crafting your campaign page, developing a marketing strategy, and producing promotional materials like a video to attract investors.

You might also like: The CEO Creative Net 30 Review: Is it Worth Your Time? 

Step 5: Launch and Promote Your Campaign

Honeycomb Credit Voodoo

Once your campaign goes live, investors can start contributing, typically with a minimum investment of $100. To maximize funding, engage your community, reach out to customers, and promote your campaign through email and social media.

You might also like: This is How to Build Business Credit Fast [Step-by-Step Guide] 

Step 6: Get Funded and Repay Investors

Finally, after you reach your minimum funding goal, Honeycomb will disburse the funds to your business. You’ll then make fixed monthly repayments over a 3 to 5-year term, with a 30-day grace period before payments begin. Honeycomb handles the repayment process, distributing payments to investors automatically.

You might also like: A Deep-Dive National Funding Review: Should You Accept an Offer? 

Do Honeycomb Investors Get a Say in How Your Business Operates? 

When researching Honeycomb Credit, my main question was whether investors have control over the businesses they fund. This is especially relevant to Business Credit Workshop since we teach small business owners how to secure funding without giving up control or ownership.

The good news is that Honeycomb investors don’t influence business decisions. Unlike venture capital or equity funding, where investors may demand a say, Honeycomb Credit uses a debt-based crowdfunding model. Businesses receive funding as a loan, repay it with interest, and retain full control.

You might also like: This is How to Buy a Franchise With No Money (Sort of) 

Frequently Asked Questions

How does Honeycomb Credit make money?

Honeycomb Credit generates revenue by charging a percentage of the funds raised by businesses on its platform. This fee helps cover operational costs, marketing, and support for both business owners and investors.

How do I contact Honeycomb Credit?

You can reach Honeycomb Credit via the form at the bottom of their Business Owners page or email them at hello@honeycombcredit.com.

What is the minimum investment for Honeycomb Credit?

The minimum investment on Honeycomb Credit is typically $100. This allows individuals to support small businesses with a relatively low entry point while diversifying their investments.

Conclusion: Is Honeycomb Credit Legit? 

Honeycomb Credit doesn’t guarantee returns for investors—most investments can’t. But for small business owners, it provides a unique, highly rated way to access funding and grow without giving up control.

Compared to a business accelerator, a Honeycomb investment campaign likely requires less time than a pitch, which can be a major advantage. You also maintain full ownership of your operations, something most business owners prefer.

However, you still need to pitch your business and growth strategy to attract investors in your community. Depending on your situation, this could be an exciting opportunity or a time commitment that doesn’t fit your needs.

It’s also important to note that Honeycomb takes a percentage of the funds raised—after all, they need to generate revenue, too.  

If you want to secure up to $100K in business credit within 30 days—without pitching to investors or giving up control over your business— join Business Credit Workshop today.

American Express Business Blueprint Review (Formerly Kabbage)

February 2, 2025 By Joe

American Express Business Blueprint Review

Key Takeaways

  • Kabbage became Amex Business Blueprint, from lending to a full financial platform.
  • Blueprint combines banking, lending, and cash flow insights in one dashboard.
  • Amex Lines of Credit have lower fees than Kabbage (0.95% to 27%, depending on the term).
  • Business Checking offers higher (1.3%) APY, no fees, and a rewards debit card.
  • The iOS app is highly rated, but Android users report issues and bugs.
  • Payment Accept replaced Kabbage Payments, but new customer availability is unclear.
  • The Resource Center provides business insights and financial tools.

Kabbage was once a popular online lender and one of the SBA’s approved PPP loan providers. American Express quietly acquired Kabbage’s platform in 2020, and reworked it to create Business Blueprint—a comprehensive business cashflow dashboard. 

So, what’s changed? And, is American Express Business Blueprint worth checking out? Here, we’ll take a quick peek at why Kabbage might have exited from their operations and learn everything you need to know about the new and expanded offer from Amex. 

This is what’s in store: 

  • What Was Kabbage?
  • What is American Express Business Blueprint?
    • Company Overview
  • How Does American Express Business Blueprint Work?
    • 1. Business Lines of Credit
    • 2. Business Banking Accounts
    • 3 Cashflow Management
    • 4. American Express Business Blueprint App
    • 5. American Express Invoicing & Payments
    • 6. American Express Financial Resources
  • Frequently Asked Questions
  • Final Takeaway

Now, let’s dive in! 

What Was Kabbage? 

What is Kabbage?

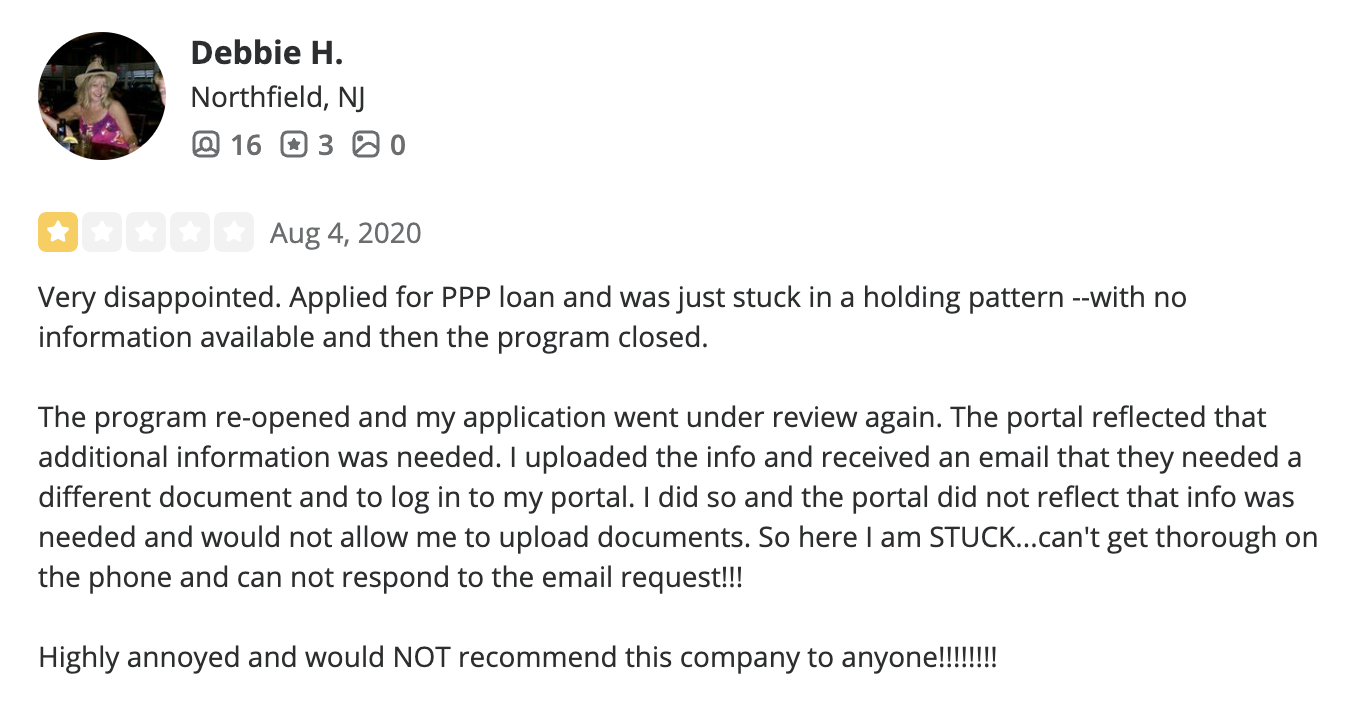
Kabbage, founded in 2009, was an automated lending platform offering quick loans up to $250K for small businesses. Known for convenience but high fees, it paused lending during COVID-19 to focus on PPP loans, earning mostly low ratings. 

Kabbage Reviews

Later, a few years after the purchase by American Express, it transitioned into Amex Business Blueprint, discontinuing its original offer. 

Near the end, Kabbage offered tools like: 

  • Kabbage Checking (competitive APY)
  • Kabbage Payments (low invoicing fees)
  • Kabbage Insights (cash flow tracking)

While useful, these services faced some technical issues before the transition. The hiccups near the end may have made selling the company the wise choice. 

You might also like: No-Doc Business Loans: Get Funds Without Proof of Income 

What is American Express Business Blueprint? 

American Express Business Blueprint

When I first heard that Amex had acquired Kabbage (whose lending funds used to come from Celtic Bank), I said, “If the brand does bring back working capital in the future, it will most likely come directly from Amex itself. We’ll just have to wait around to see.”  

Well, that future is now. 

American Express Business Blueprint is a free platform positioned to help small businesses manage their cash flow. It lets you view your American Express business products and linked external accounts in one place. Then, it provides personalized insights to help you make informed financial decisions. 

With the tool, you can access features like a 30-day bank account balance projection, which uses data from your linked accounts to help you anticipate future balances. In a nutshell, business Blueprint aims to simplify financial management for small business owners.

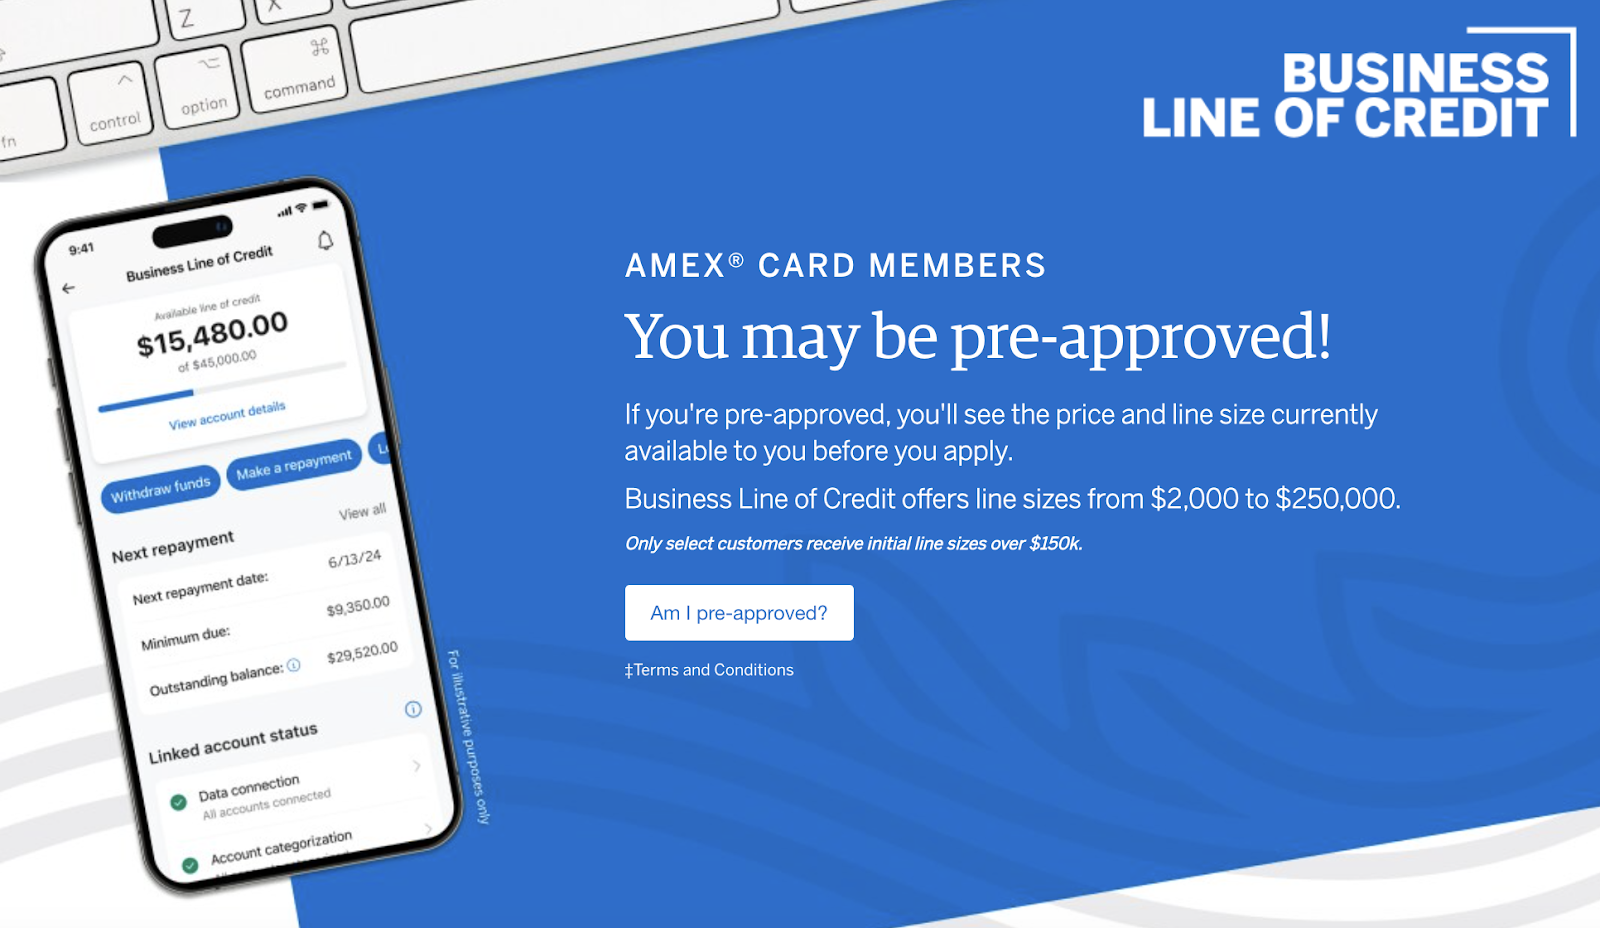
Moreover, Amex is offering a Business Line of Credit up to $250K (same as Kabbage), with no mention of Celtic Bank. Today, these loans are serviced directly by American Express National Bank.  

Recommended: Amex Business Checking Review: What You Need to Know…Really 

Company Overview

American Express Business Blueprint Benefits

American Express, aka Amex, is a global financial services company with roots dating back to 1850. Founded by Henry Wells, John Butterfield, and William Fargo—names you might recognize from Wells Fargo—Amex has built a reputation for reliability and innovation in finance. 

Initially known for credit cards, charge cards, and traveler’s checks, the company has since expanded its offerings to include business checking accounts (and, now working capital) further solidifying its leading position in the financial world.

Headquartered in New York and led by CEO Stephen Squeri, Amex stands out as a trusted name in American finance. It’s publicly traded and has endured as a stable force in a fast-evolving industry. 

You might also like: A Complete, Unfiltered Amex Business Gold Card Review 

How Does American Express Business Blueprint Work? 

American Express Business Blueprint login

As I said before, American Express Business Blueprint is free. And, you can log in with existing credentials, if you’re already an American Express member, or create an account. 

Once you’re in, you’ll have access to a lot of the same features and services that were available with Kabbage, but with some notable improvements. 

1. Business Lines of Credit

american express business line of credit

Kabbage’s fixed-rate loan fees were steep, ranging from 24-99% APR, with no savings for early repayment, no long-term options, and approval limited to businesses with online checking or PayPal. 

In contrast, Amex Business Lines of Credit offer a more affordable alternative, with funding from $2K to $250K secured by business assets and personal guarantees. 

Amex’s fees range from:  

  • 0.95% to 6.05% for single repayment loans (1 to 3 months)
  • 3% to 27% for installment loans (6 to 24 months)

So, Amex offers a much less expensive business lending option than Kabbage was able to. They also offer reduced costs with early repayment on installment plans. However, you must be an Amex cardholder to apply.

2. Business Banking Accounts

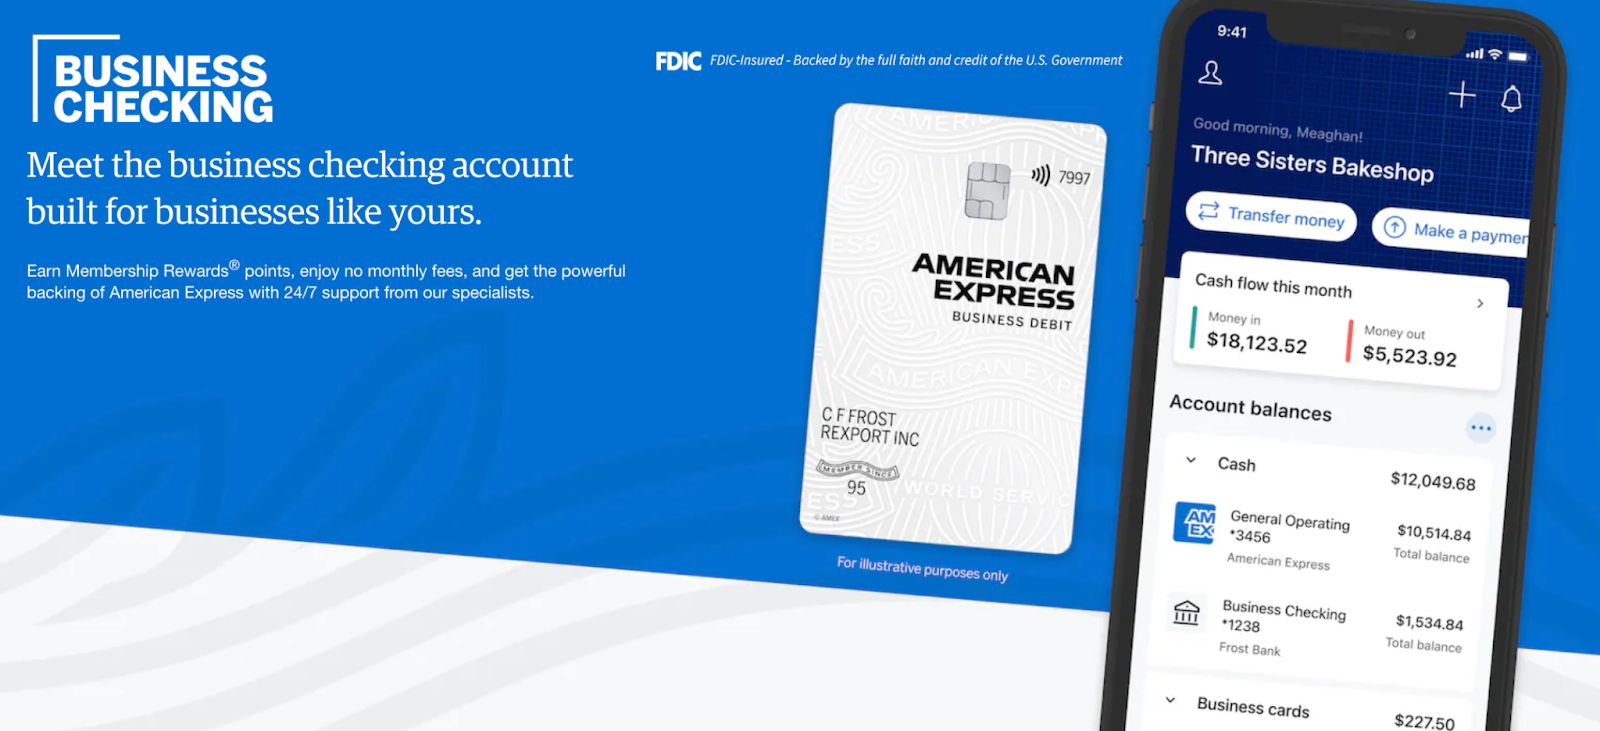
American Express Business Checking

Before the transition, there was no such thing as a Kabbage business savings account. Likewise, there is no American Express business savings account (though they do have a consumer savings option). 

Kabbage Checking offered FDIC-insured banking with 1.10% APY earned on funds, which they declared was the best deal you’ll find. This wasn’t true with 2% earnings from