• Home
  • Free Funding Guide
  • What We Offer
    • Products
    • Services
    • Free Guide
  • About Us
  • Contact
  • Sign Up

  • Ask Joe Any Question!
  • Business Credit Cards
  • Business Line of Credit
  • Topics

Robins Federal Credit Union: Mid Georgia Business Banking

By Joe

Robins Federal Credit Union

Let’s talk about Robins Federal Credit Union: They’re a financial institution that’s all about supporting members and businesses like yours. What sets them apart from those big banks? Well, they’re focused on member success, not just making money. They offer fair rates, personalized service, and they’re all about building strong relationships.

When it comes to your business, they’ve got a range of credit solutions. From credit cards to loans and other financial options. So, let’s take a closer look at their business credit cards, loans, and other small business products—I’ll discuss what they offer and why you might find them useful. 

This is what’s in store: 

  • What is Robins Federal Credit Union?
    • Locations Served
    • Robins Federal Credit Union Membership Requirements
  • Robins Federal Business Financial Products & Services
    • 1. Robins Federal Business Banking/Checking
    • 2. The Business Visa® Platinum Credit Card
    • 3. Robins Federal Commercial Loans
    • 4. Business Savings & Investment Opportunities
    • 5. Robins Federal Business Treasury Services
    • 6. The Robins Federal Mobile App
  • Robins Federal Credit Union Customer Service
  • Robins Federal Credit Union Community Involvement
  • Frequently Asked Questions
  • Final Thoughts

Now, let’s take a closer look!

What is Robins Federal Credit Union?
Robins Federal Credit Union Business Login

Originally founded in 1954 as the “Warner Robins Air Force Base Federal Credit Union,” Robins Financial Credit Union later expanded its membership to include several communities in Middle Georgia—It’s been committed to serving members and communities since the beginning. 

As a not-for-profit cooperative, Robins Financial operates with the principle of “People Helping People,” which highlights its dedication to support members to achieve their financial goals.
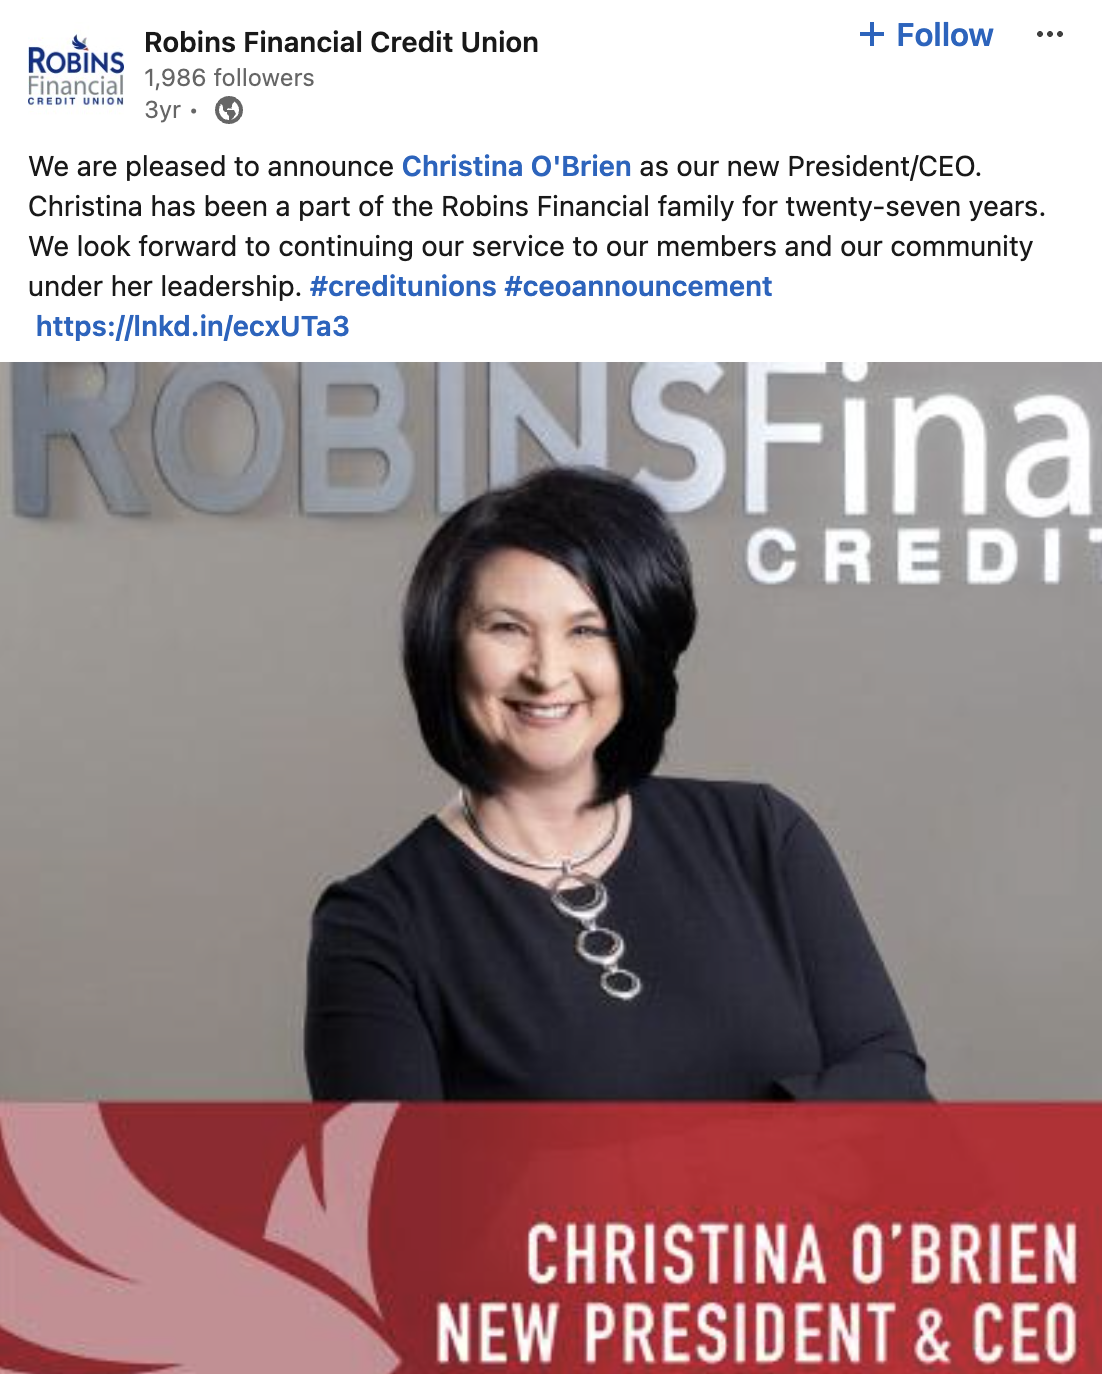
Who is the CEO of Robins Financial Credit Union?

In line with this mission, the credit union has extended its commitment to small businesses within its membership base. Small businesses drive local economies and create jobs. And, Robins Financial offers tailored financial products and services to support their growth and success.

The credit union offers a range of business banking solutions: 

  • Business checking and savings accounts
  • Business loans and credit cards
  • Business treasury and merchant services
  • Business prestige money market accounts

Despite their 1-star customer rating with the Better Business Bureau (BBB), they have been BBB accredited since 1990 and maintain an A+ platform rating. As far as the customer ratings are concerned, most people go to the BBB site when they have complaints, not when they’re happy.  
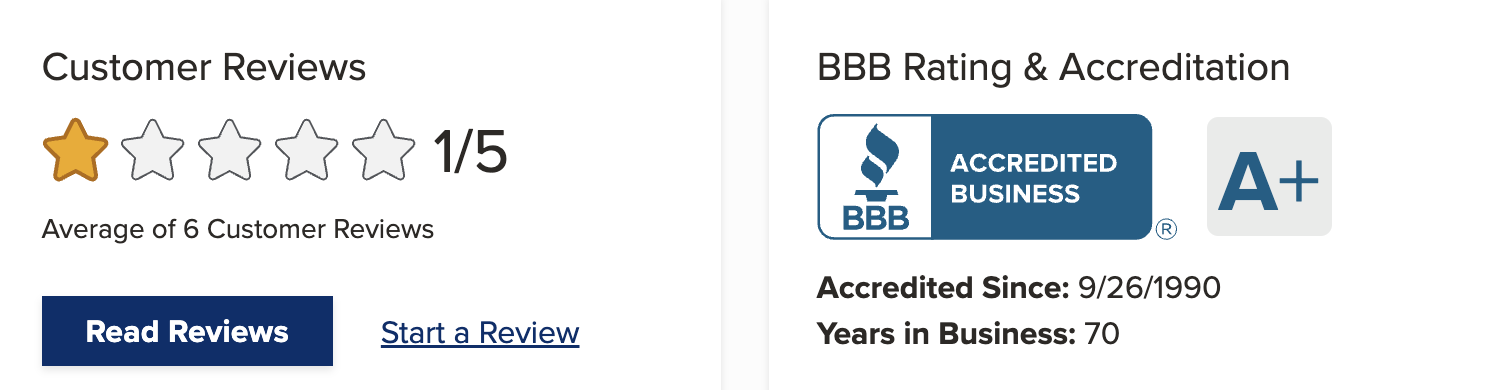
Robins federal credit union review bbb

Business members can benefit from personalized financial guidance and support from experienced advisors who understand small business challenges and opportunities.

Recommended: 3 Best Credit Unions for Small Business Banking in 2024 

Locations Served
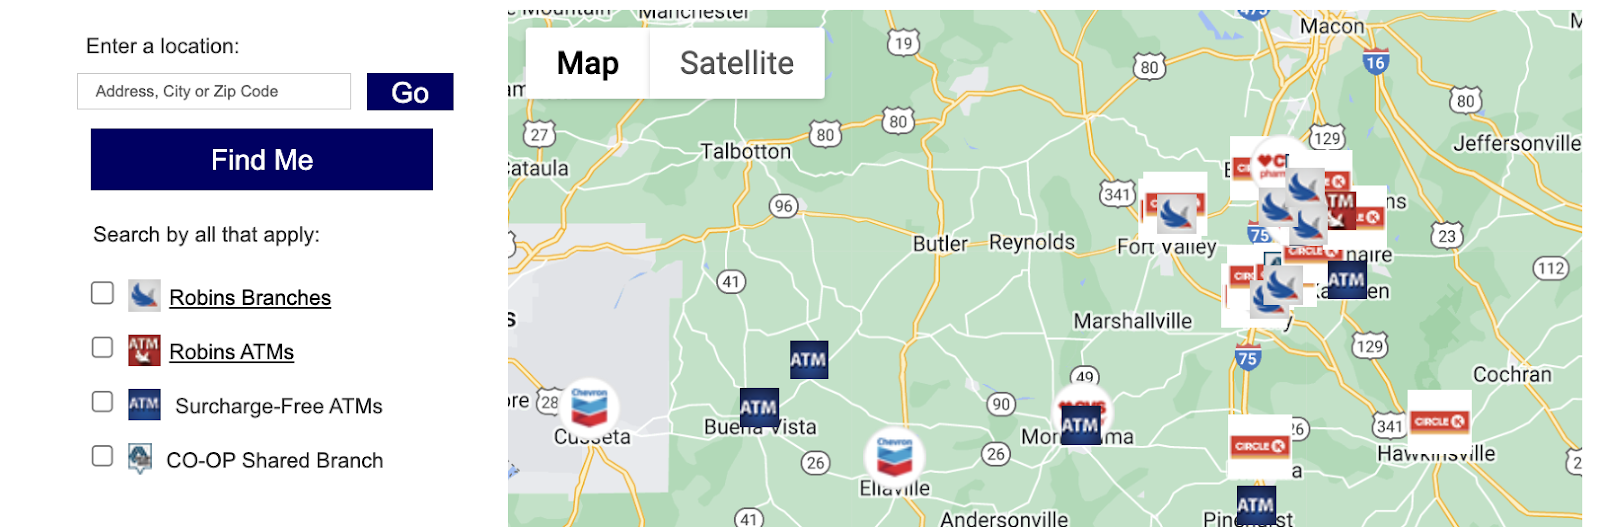
Robins Federal Credit Union branch locations

Robins Financial Credit Union serves businesses across Middle Georgia, primarily focusing on cities and towns within the region. 
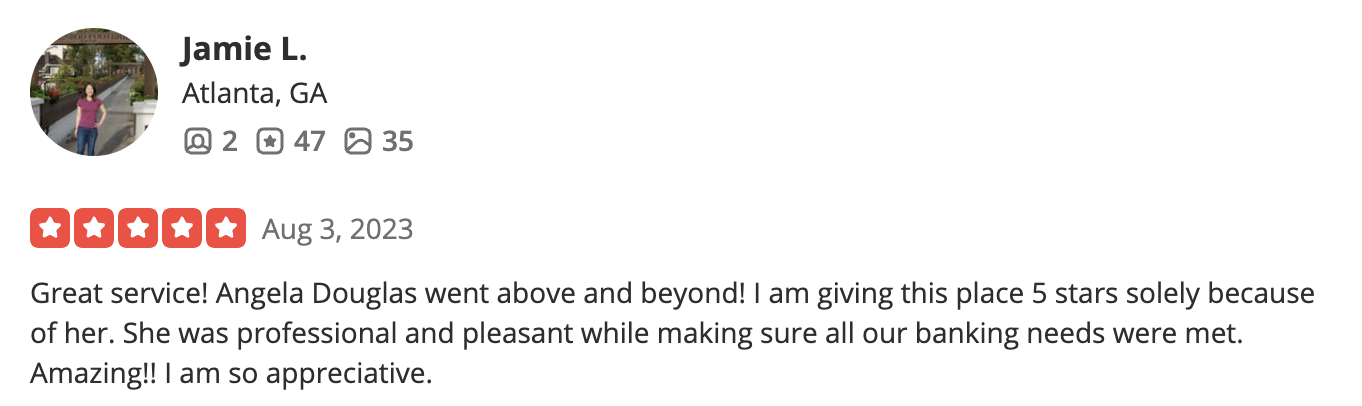
Robins federal credit union review yelp

Some of the locations where the credit union has branches include:

  • Warner Robins – With branches like Houston Road, Chantilly, Watson, Robins Air Force Base, Russell Parkway, and Hwy 96, businesses in Warner Robins and its vicinity have multiple locations to access the credit union’s services.
  • Macon – With branches such as Zebulon, Riverside, Log Cabin, Downtown, and Hartley Bridge, businesses in Macon and its surrounding areas have convenient access to services.
  • Gray, Forsyth, Perry, Ft. Valley, and Midgeville – With branches that serve these towns and surrounding areas. 

While Robins Financial best serves businesses in these and nearby towns, it also offers online banking services for nationwide accessibility—Through the credit union’s online platform, businesses can access a range of banking services, including account management, bill pay, e-statements, and mobile banking. 

You might also like: Sidney Federal Credit Union: NY Business Financial Options 

Robins Federal Credit Union Membership Requirements
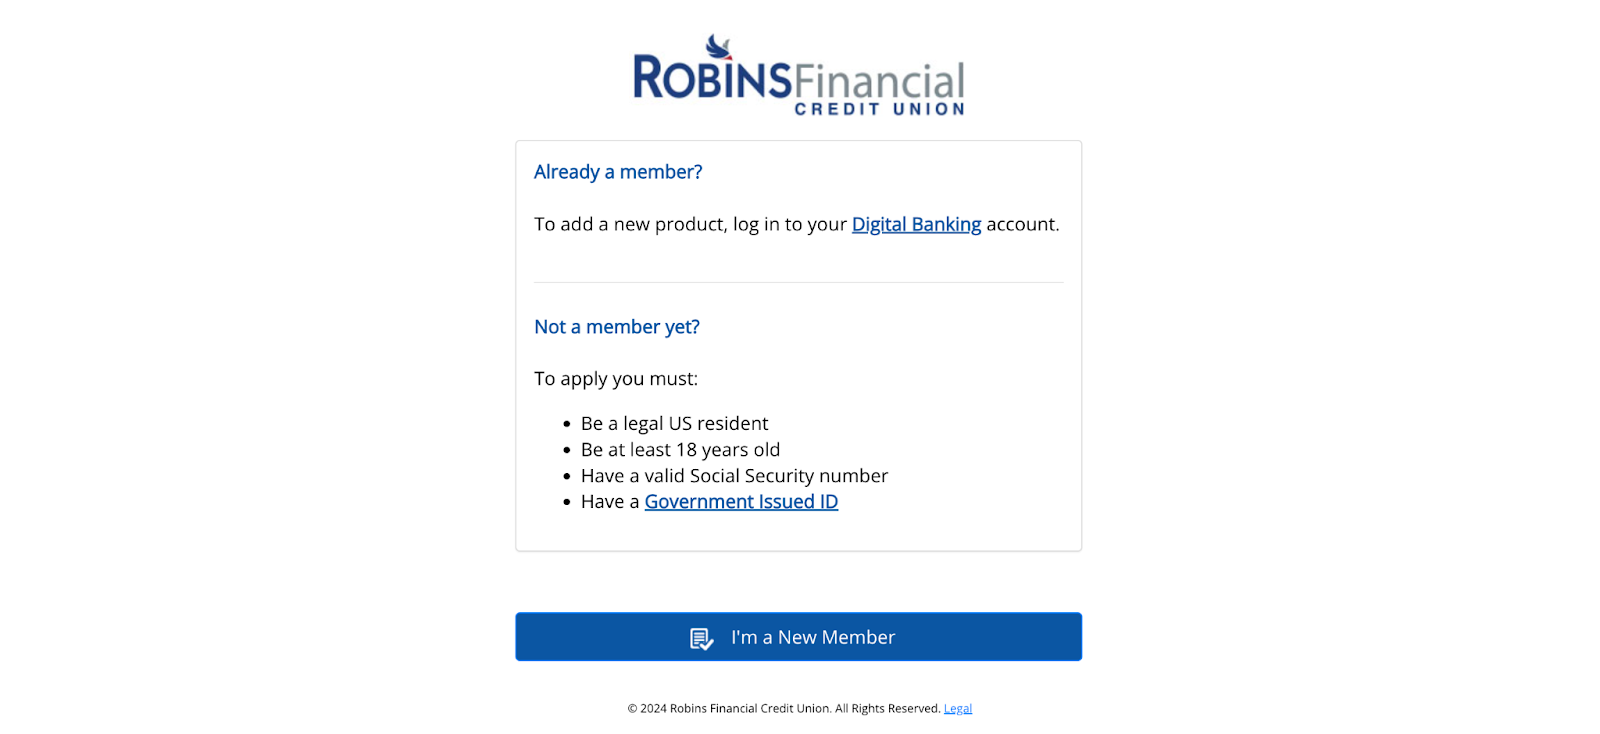
What do I need to open a bank account with Robins Federal credit union?

If you want to join Robins Financial, you’ll need to meet a few criteria…You must:

  • Be a legal US resident
  • Be at least 18 years old
  • Have a valid Social Security number

Businesses need to have two forms of government-issued ID handy, like a driver’s license, state ID card, passport, or permanent resident card. To get started, you’ll need to deposit a minimum of $100 ($25 for individual checking). 

You’ll also need documentation, depending on your business structure: 

  • Articles of Organization or Incorporation
  • Certification of Beneficial Owner(s) form
  • IRS EIN assignment letter (if using EIN)
  • Business resolution form (except for sole proprietorships)
  • Secretary of State registration (if applicable)
  • Letter authorizing use of TIN (if applicable)
  • DBA trade name registration (if applicable)
  • Business license (if applicable)
  • Statement of partnership or partnership agreement (for partnerships)
  • Current meeting minutes (for associations/organizations/non-profits) 

You can open an account either online through their website or by swinging by any branch location. Non-members can apply for Robins Financial’s loans and credit cards, but members may be more likely to be approved.

Now, let’s explore this credit union’s business offers! 

Recommended: Here’s How to [Actually] Get Business Credit With Just an EIN +More Options 

Robins Federal Business Financial Products & Services

Robins Financial Credit Union’s business solutions include business checking and savings accounts, loans and credit cards, as well as treasury and merchant services. Moreover, you can take advantage of money market accounts to optimize returns on surplus funds. 

1. Robins Federal Business Banking/Checking
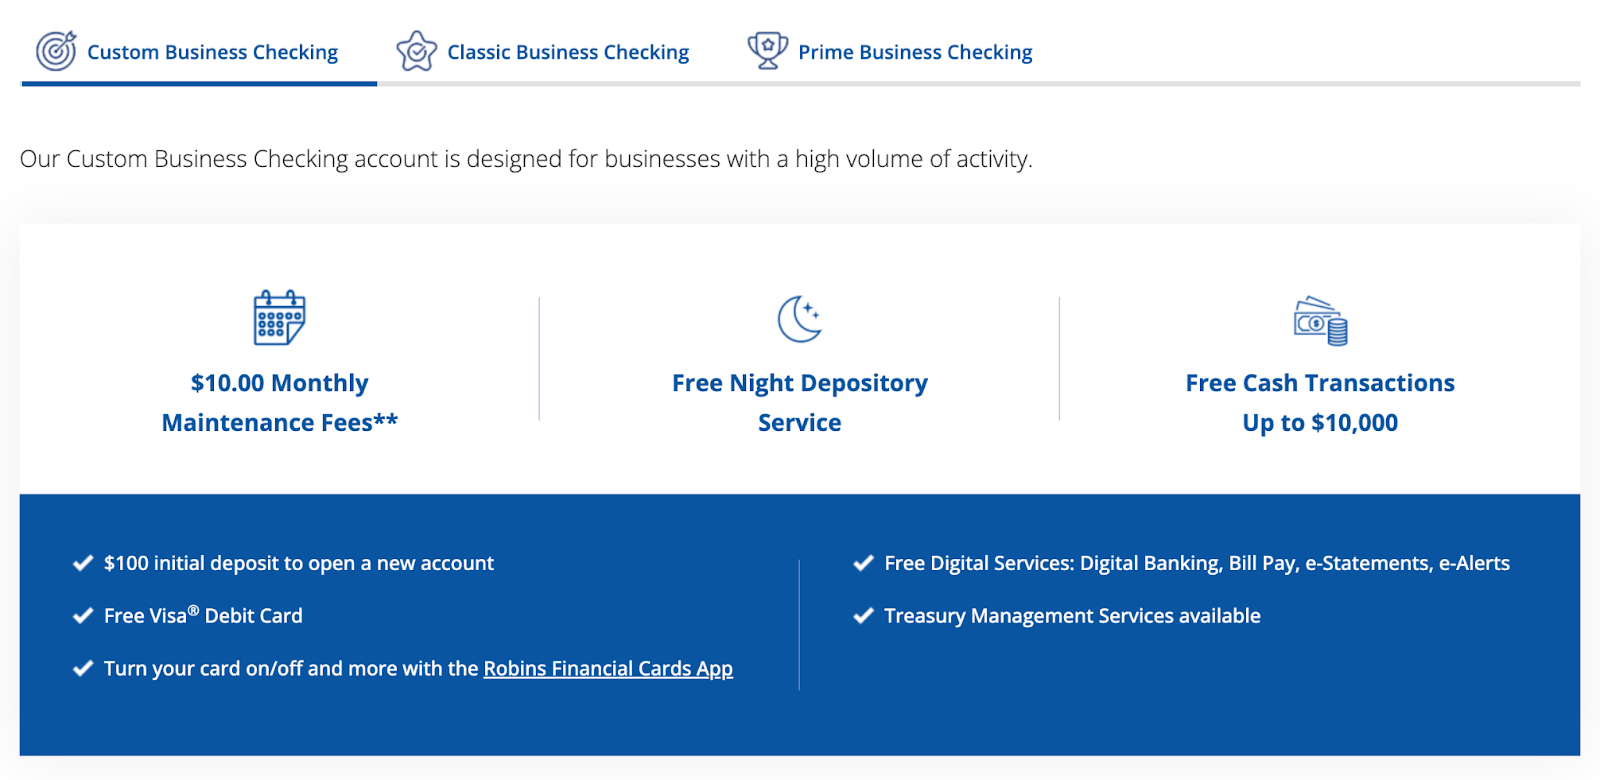
Robins federal credit union business checking

Robins Financial Credit Union offers three business checking accounts: 

  • Custom Business Checking 
  • Classic Business Checking 
  • Prime Business Checking 

All business checking accounts come with online banking and digital services, access to treasury management services, and a Visa® debit card. Again, the initial deposit is $100. 

The Custom Business Checking account is designed for businesses with a high volume of activity. It has a $10.00 monthly maintenance fee and accommodates free cash transactions up to $10K. 

For businesses with a moderate level of activity, the Classic Business Checking account provides a free solution. You’ll need to maintain a minimum balance of $500, and this account offers 250 free items per month and allows free cash transactions up to $5K. 

The Prime Business Checking account caters to businesses maintaining higher balances with lower transaction volumes. It requires a minimum balance of $1,500, and it pays dividends on the account balance with free cash transactions up to $5K. 

FeaturesCustom Business CheckingClassic Business CheckingPrime Business Checking
Monthly Fee$10.00NoneNone
Minimum BalanceNone$500$1,500
Free Cash TransactionsUp to $10KUp to $5KUp to $5K
Free Items Per MonthN/A250100
Dividend RateN/AN/A~0.399 (0.4% APY)

The dividends paid on Prime Business Checking accounts at Robins Financial aren’t publicly disclosed—This tells me that they are either variable or the same as the individual Advantage Checking account (0.4% APY). If you decide to open a Prime account, make sure to ask a banker about your expected dividends.  

You might also like: Bluevine Review: Free, High Yield Small Business Checking! Are They Serious? 

2. The Business Visa® Platinum Credit Card
robins federal credit union business credit card

The Business Visa® Platinum card from Robins Financial Credit Union has credit limits that exceed $25K and low variable rates starting at Prime + 5.7% APR* (right now, prime is 8.5%, so these cards have interest as low as 14.2%—This is fairly low). 
Robins Federal Reddit

There’s no annual fee, and the contactless chip cards come with optional spending blocks for specific merchant types. 

You’ll also get benefits like: 

  • Zero liability for unauthorized charges 
  • Overdraft protection (to the linked business checking account)
  • 1 point for every $1 spent (via the ScoreCard® Rewards Program)
  • Travel insurance and auto rental collision damage coverage

The Robins Financial Business Visa® Platinum card offers full financial support for businesses.

Recommended: Corporate vs Business Credit Card: What’s the Difference? 

3. Robins Federal Commercial Loans 
robins federal credit union business loan

Robins Financial Credit Union provides a diverse range of business loans. 

These include: 

  • Construction loans
  • Commercial equipment loans
  • Business automobile loans
  • Commercial real estate loans for purchase or refinance
  • SBA 504 and SBA 7(a) loans
  • Secured and unsecured revolving lines of credit 

Interest rates and terms for these loans vary based on factors like the type of loan, business creditworthiness, and market conditions. 

Recommended: Business Car Leasing 101: How to Lease a Vehicle With Your EIN 

4. Business Savings & Investment Opportunities 
robins federal credit union interest rates

You can also take advantage of business savings solutions—-Robins Financial offers regular savings accounts and money market accounts. You can maximize your returns with competitive dividend rates – from 0.60% to 1.50% APY* – depending on the average daily balance maintained in the Prestige Money Market account.

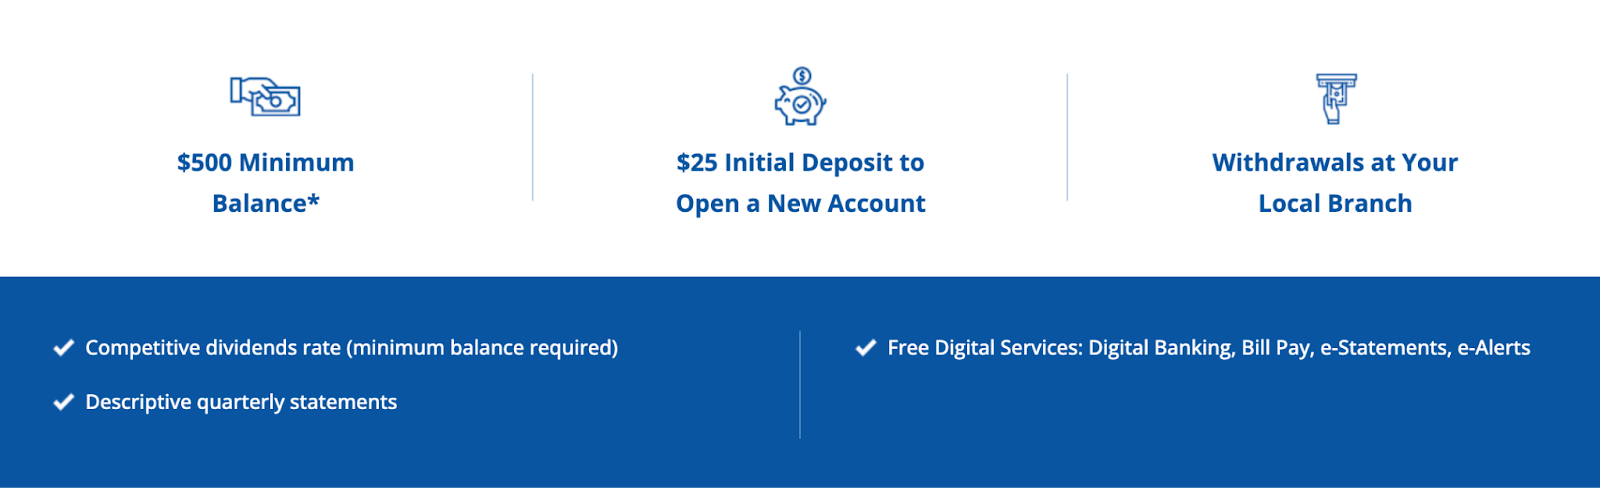
The business savings account requires a minimum balance of $500, with an initial deposit of $25 to open a new account. Dividends are compounded and credited quarterly. And, the savings account offers descriptive quarterly statements and free digital banking, bill pay, e-statements, and e-alerts. Withdrawals can be made conveniently at local branches.

For businesses seeking higher dividends, the Business Prestige Money Market Account (MMA) has no monthly maintenance fee and needs a minimum deposit of $2,500 to open. 

In all, you can get overdraft protection, withdrawals at local branches, 40 free checks per year, and free digital services, but some limits apply. For example, you get six penalty-free transfers or withdrawals per month on savings accounts. 

You might also like: How to Get Money for Real Estate Investing: 18 Practical Ideas 

5. Robins Federal Business Treasury Services 
robins financial credit union business account

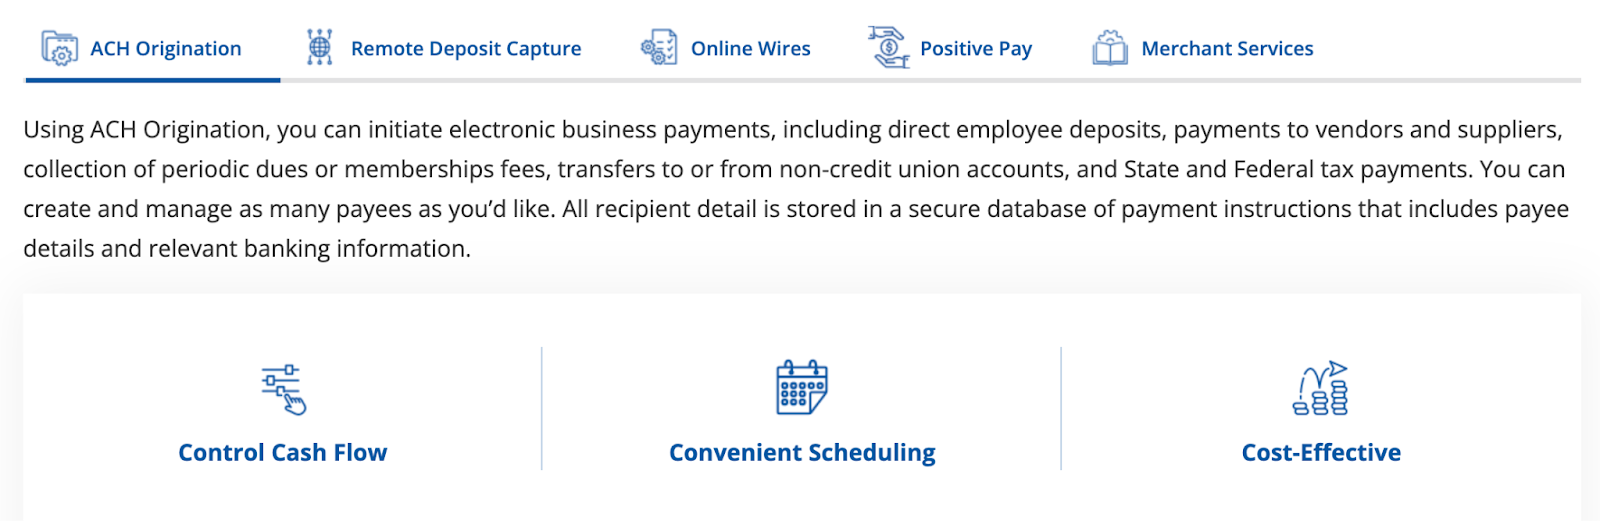
Robins Financial offers a handful of business treasury services, including: 

  • ACH origination
  • Remote deposit capture
  • Online wire transfers
  • Positive pay 
  • Merchant services

With ACH origination, you can conveniently initiate electronic payments, manage payees, and control cash flow, all while reducing transaction fees and mitigating the risks associated with paper checks. Remote Deposit Capture allows you to deposit checks from your office, saving time and reducing collection float. 

Online wires provide a secure and efficient way to transfer funds across borders, with real-time tracking and the flexibility to manage payees and templates. And, with ‘Positive Pay,’ you can safeguard against check and ACH fraud, which ensures only valid transactions are processed.

Finally, merchant services offer secure payment processing and personalized support, including: 

  • Point-of-sale terminals
  • Mobile products
  • Specialty cards

Be sure to discuss fees with a business banker at Robins Financial if you opt to take advantage of the credit union’s treasury services. 

Recommended: What’s the Best Payment Processor for a Small Business? Really 

6. The Robins Federal Mobile App 
robins federal credit union app

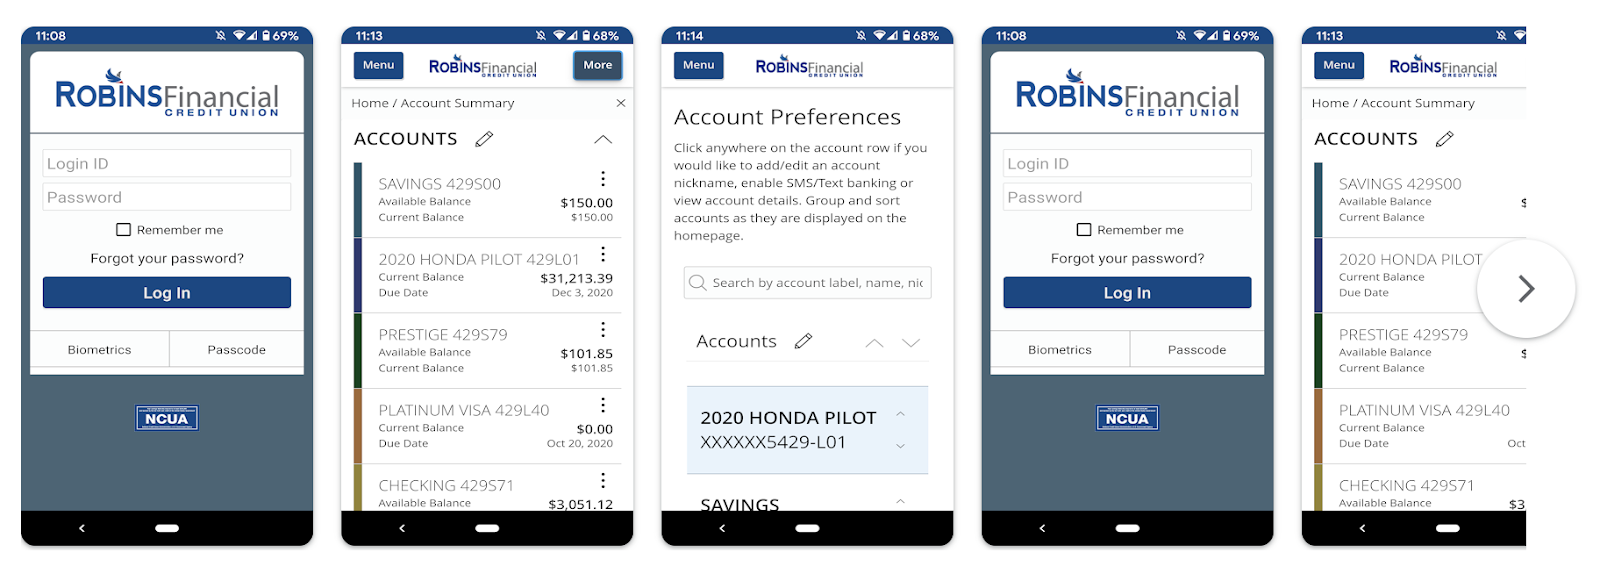
You can conveniently bank from anywhere via any smartphone via Robins Financial’s mobile app. It’s available on Google Play and the Apple marketplace, where it has 4.1 and 4.9 star ratings respectively. 

With the mobile app, you have convenient access to a range of banking features right at your fingertips. You can easily pay bills, transfer funds, and check balances and account history from anywhere, at any time. Plus, you can send and view secure messages for added peace of mind.
Robins federal credit union review complaints

The app is designed with a tablet-first approach and offers a unified look across all devices. Recent updates have brought improved performance and security enhancements, ensuring a seamless and secure banking experience for users. 

You might also like: The PEX Card: Is it the Best Corporate Card for Your Business? 

Robins Federal Credit Union Customer Service
robins federal credit union 24-hour customer service

Robins Financial offers various customer service options to address their needs anytime, anywhere. 

For inquiries regarding annual tax documents or general questions about services, members can visit the tax forms page or reach out via secure message through your banking dashboard. 

The credit union’s ‘Digital Banking Guide’ provides assistance with:

  • Step-by-step instructions
  • Troubleshooting tips
  • FAQs related to digital banking and mobile apps

When it comes to making loan payments, you can utilize the loan payments portal for online payments from other financial institutions or call 833-886-6110 for phone payments—Branch appointments are available for expedited help, whether for a phone or in-person visit. 

For issues related to debit or credit cards, you can report lost or stolen cards through your banking dashboard or by contacting customer service. Members seem to be super happy with the level of care Robins Financial provides. 
robins federal credit union customer service

In the event of a dispute with a merchant or unrecognized charges on a statement, you can reach out during normal business hours or schedule a branch appointment. 

Robins Federal Credit Union Community Involvement
Robins Federal Nonprofit financing

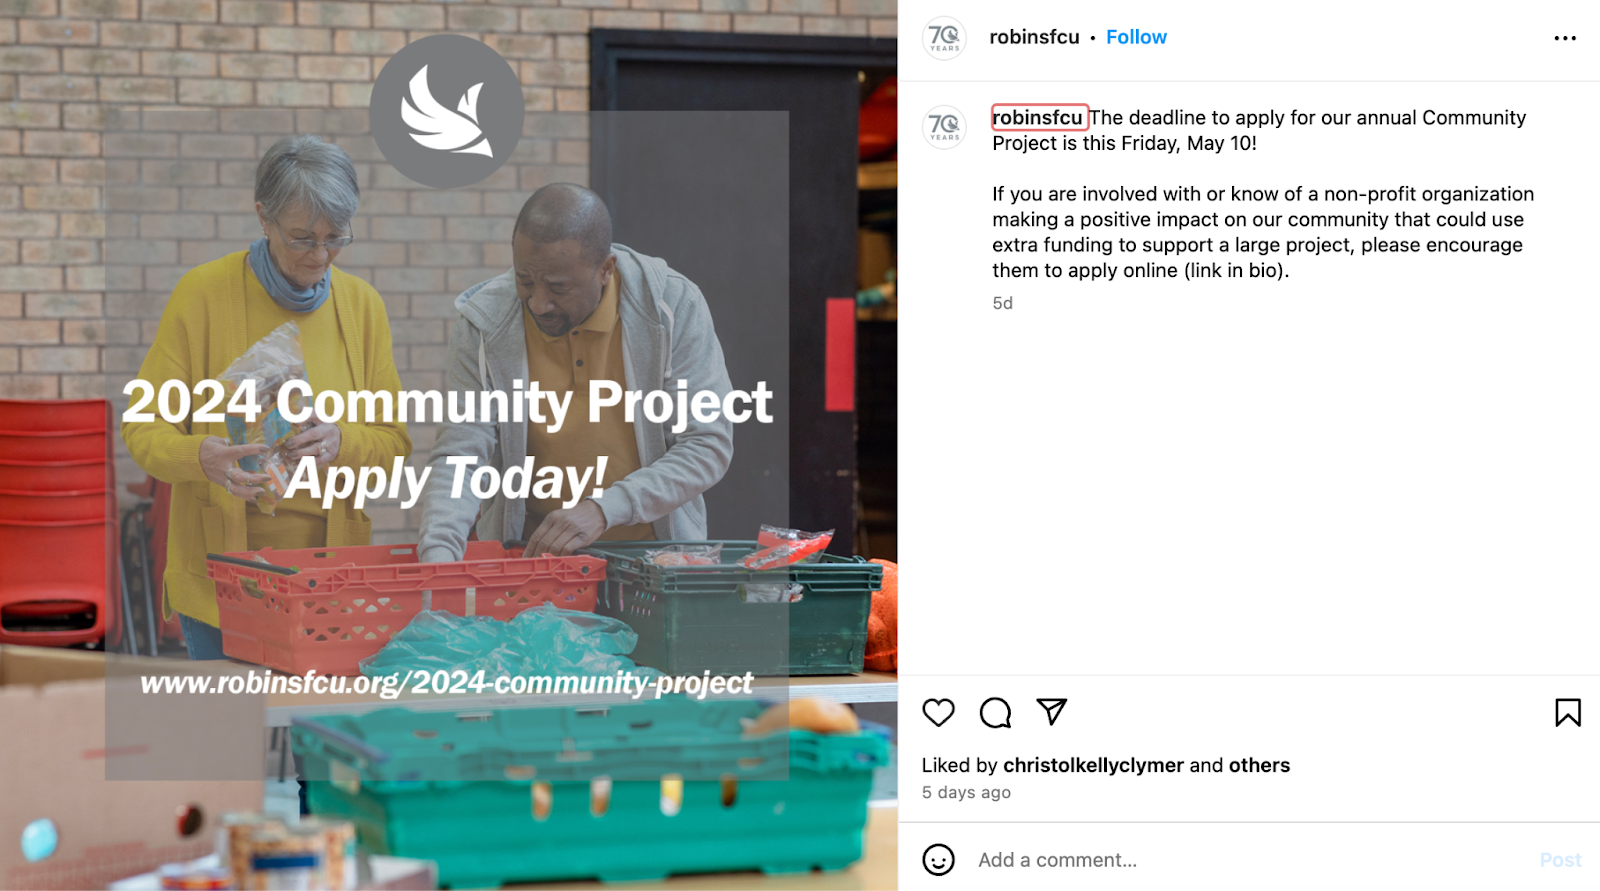
Robins Financial is committed to giving back to the community and supporting local initiatives. One notable aspect of their community involvement is their dedication to financing nonprofits—By providing funds to nonprofits, the credit union contributes to various causes and organizations that make a positive impact on the community. 

Additionally, their participation in “Miracle May” fundraising for the Children’s Miracle Network showcases their commitment to supporting children’s healthcare and wellness.

While there may not be specific community initiatives catered exclusively to the small business community, Robins Federal Credit Union’s overall community involvement indirectly benefits small businesses. By supporting nonprofits and organizations that address community needs, the credit union contributes to creating a more vibrant and thriving local environment.

You might also like: Y Combinator: Fast Track to Success or Waste of Time? 

Frequently Asked Questions

Who owns Robins Financial Credit Union?

Robins Financial Credit Union is owned by its members, who are also its customers. It operates as a not-for-profit financial cooperative, meaning that its members share ownership and participate in the credit union’s decision-making processes.

Is Robins Financial Credit Union FDIC insured?

No, Robins Financial Credit Union is not FDIC insured. Credit unions like Robins Federal are insured by the National Credit Union Administration (NCUA), which provides similar insurance coverage for deposits. NCUA insurance protects members’ deposits up to $250K per individual depositor.

What credit score does Robins Financial Credit Union use?

Robins Financial Credit Union typically uses credit scores from major credit bureaus like Equifax, Experian, and TransUnion to evaluate loan applications and determine creditworthiness. Learn more about DUNS numbers for business credit reporting. 

Final Thoughts

Robins Financial Credit Union provides a solid suite of financial solutions for businesses in Middle Georgia—With a focus on member success and community involvement, they offer fair rates, personalized service, and support for local initiatives like nonprofit funding and children’s healthcare.

Their business offerings include checking and savings accounts, loans, credit cards, and treasury services, which caters to a variety of needs. While specific initiatives for small businesses may be limited, their overall commitment to community well-being indirectly benefits local businesses, which makes them an ideologically sound choice for financial support in the area.

Do you want to learn how to obtain up to $100K in business credit in as few as 30 days? Join Business Credit Workshop today!
Truist Business Credit Card Review: Is it Really That Good? 

By Joe

Truist Business Credit Card

A lot of my students at Business Credit Workshop have been approved for the Truist business credit card recently. After hearing their stories, I want to share everything I know about the offer and what I’ve learned (including whether the rewards are worth it if you don’t have a Truist checking account). 

There are three Truist business credit cards currently available, each with their own unique set of features. We’ll explore them here, along with more info about Truist bank and how well they cater to small businesses. Find out if the card is worthwhile in your situation.

This is what’s in store: 

  • What is a Truist Business Credit Card?
    • Truist Business Credit Card Pre-Approval
    • Truist Business Credit Card Requirements
    • Company Overview
  • The 3 Truist Business Credit Cards
    • 1. Truist Business Cash Rewards
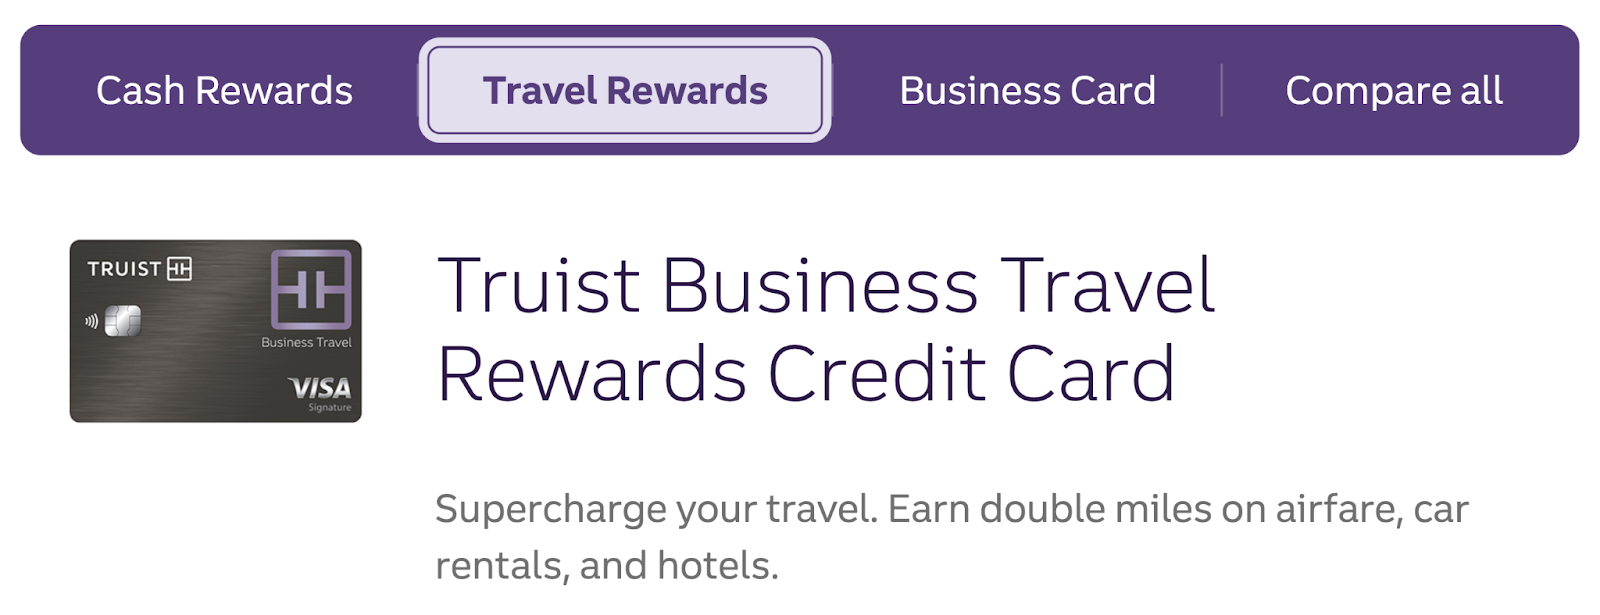
    • 2. Truist Business Travel Rewards
    • 3. Truist Business
  • More Truist Small Business Products
  • Frequently Asked Questions
  • Conclusion

Now, let’s roll! 

What is a Truist Business Credit Card? 

Truist business credit card review

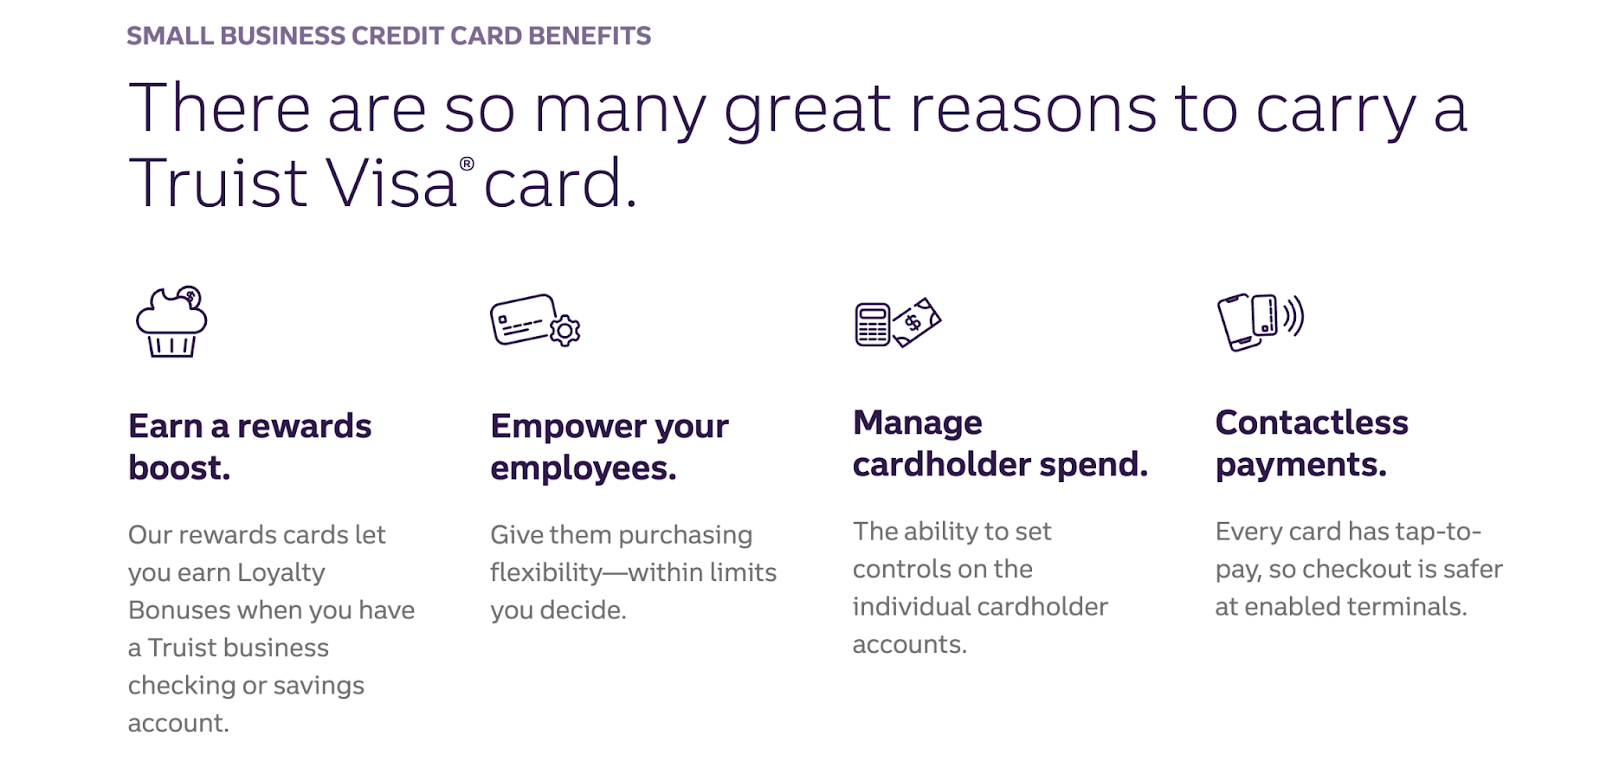
A Truist business credit card is designed to meet the credit needs of small businesses. It offers various benefits tailored to business spending, like cash back rewards on purchases. Plus, you’ll get a Loyalty Cash Bonus when you deposit your cash rewards into an eligible Truist business checking, savings, or money market account.

Truist has three business credit cards for varying needs—there’s a card for: 

  • Cash rewards
  • Travel rewards
  • General business expenses

Each card has its own set of features, fees, and rewards structure. So you’ll want to compare them to find the best fit for your business (which we’ll do below).

These cards also provide flexibility for your employees with customizable spending limits and controls on individual cardholder accounts. And, they come with contactless payment options for added convenience and security at enabled terminals.

You can manage your Truist business credit card online to access your account, redeem rewards, view transactions, and set up alerts. You can also manage employee cards, integrate with accounting software, and get resources for better business strategies.

You might also like: 6 Best 0% APR Business Credit Cards to Check Out 

Truist Business Credit Card Pre-Approval 

Truist business credit card reddit

At some point, Truist had a pre-qualification page for business owners to see if they could obtain credit through Truist—This apparently triggered a soft pull, which would protect your credit from the ding on your credit report. 

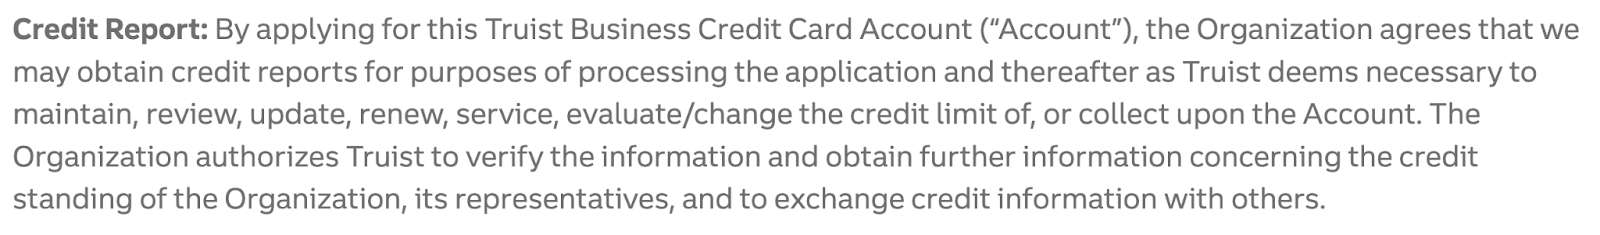
But, does Truist still have pre-approval? Today, I can’t find any sign of such a page on the company website. Instead, I do see a disclaimer that by applying, you give Truist permission to access and update your credit report. So, when you apply, it will likely have a slight impact on your credit score. 

Truist pre approval business credit card

Truist evaluates both personal and business credit. When considering business cards, Truist utilizes Equifax personal credit reports, but claims to prioritize business credit scores over personal credit scores on applications for business products. 

Recommended: Here’s How to [Actually] Get Business Credit With Just an EIN +More Options 

Truist Business Credit Card Requirements

Truist business credit card application status

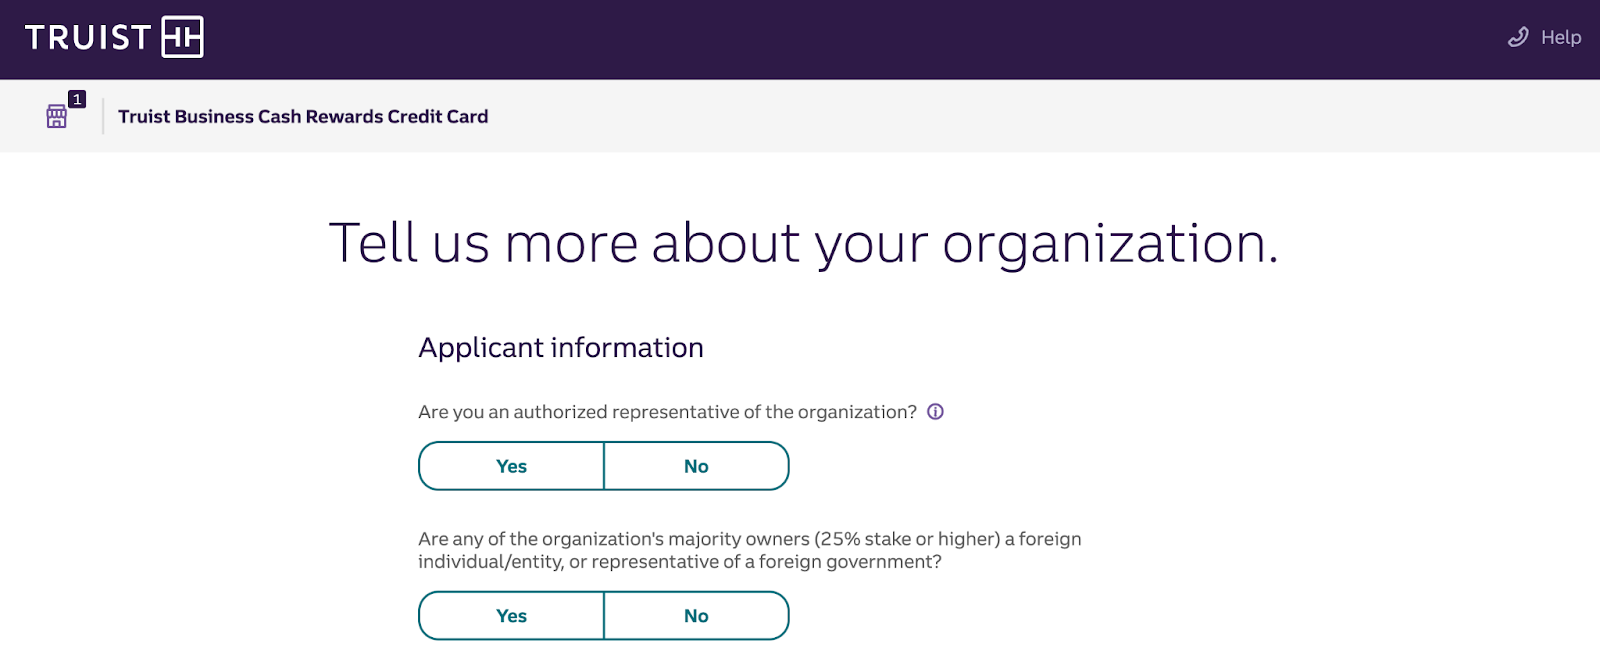
Before you move forward and learn more, you should know what you need to Apply for a Truist business credit card. 

Note: Truist does offer secured cards, so a low credit score (below 640) won’t necessarily disqualify you from obtaining credit through the bank…you will just have to work toward it.  

To qualify, Truist wants you to have excellent personal and business credit—you’ll need: 

  • Basic details about your business
  • Business Tax ID 
  • Your personal street address
  • Phone number
  • Social Security number
  • Names and emails of people involved in the application

You can apply online with electronic signatures and email communication or visit a branch to complete the Truist business credit card application. For-profit businesses will need at least one Guarantor. And, nonprofits don’t need a Guarantor. 

You might also like: Everything You Need to Know About a DUNS Number +Why You Should Care 

Company Overview 

Truist small business credit card

Truist Financial, or Truist Financial Corporation, is a Charlotte North Carolina-based, for-profit investment bank. In 2019, Truist Financial was formed from the merger of BB&T and SunTrust. With a combined history spanning 275 years, Truist serves approximately 12 million households, holding significant market share in key growth regions across the country. 

Their diverse range of services includes: 

  • Retail, small business, and commercial banking
  • Asset and wealth management
  • Capital markets
  • Real estate
  • Insurance
  • Mortgage
  • Payments
  • Specialized lending

Truist apparently ranks as the sixth-largest commercial bank in the United States, operating as “Truist Bank” under FDIC membership.

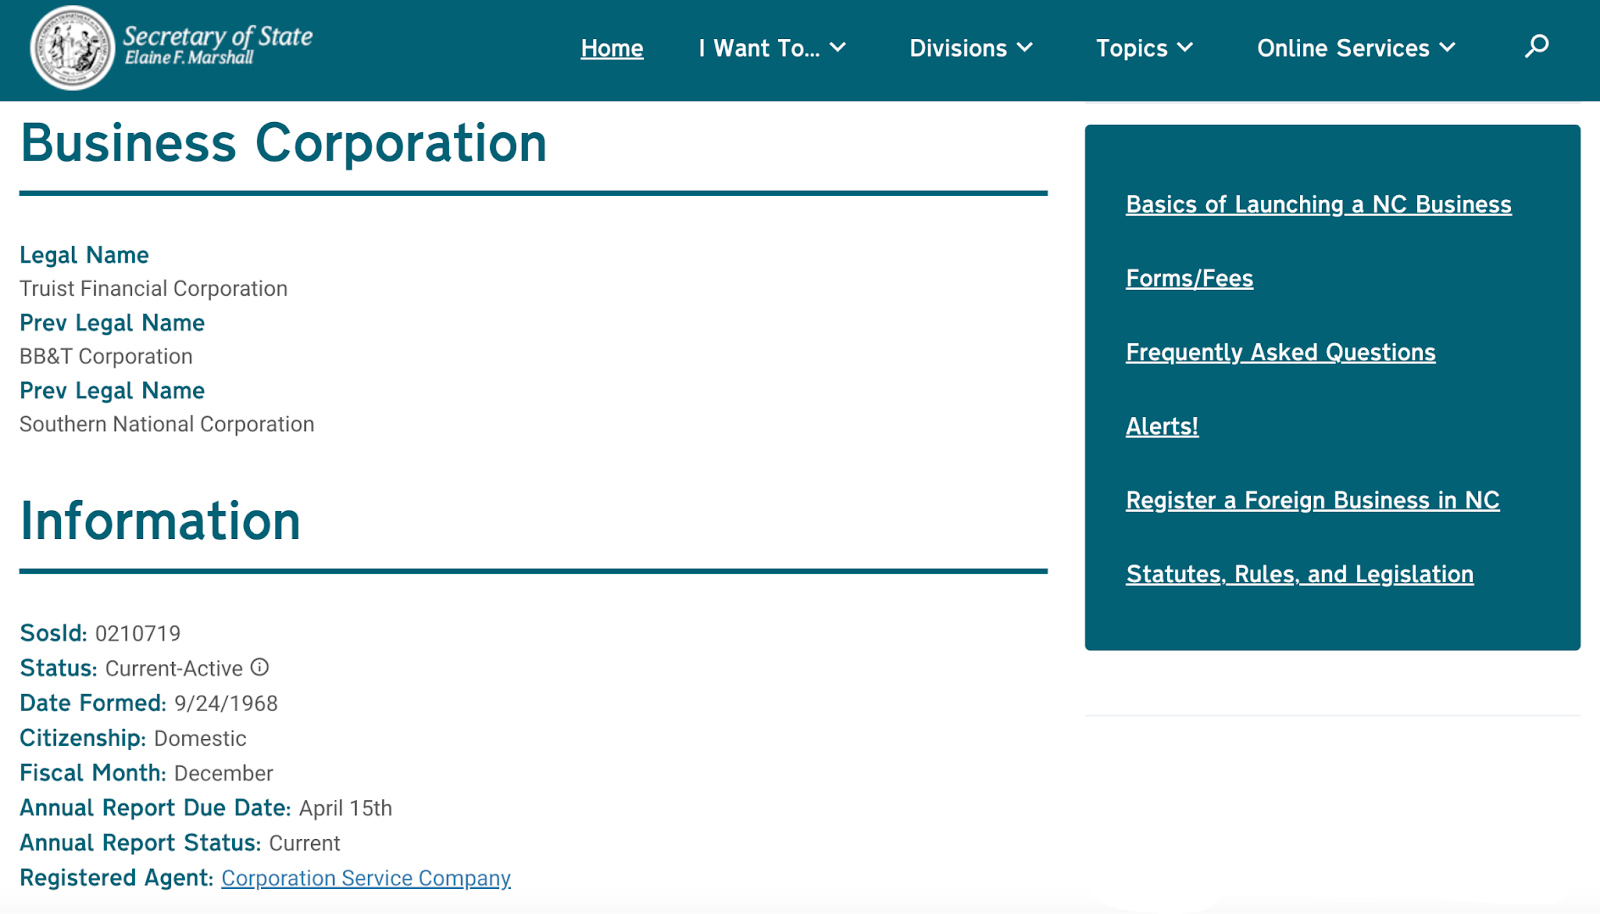
According to the North Carolina Secretary of State, the company is active and in good standing—they’re current with their annual reporting. 

Truist credit card business

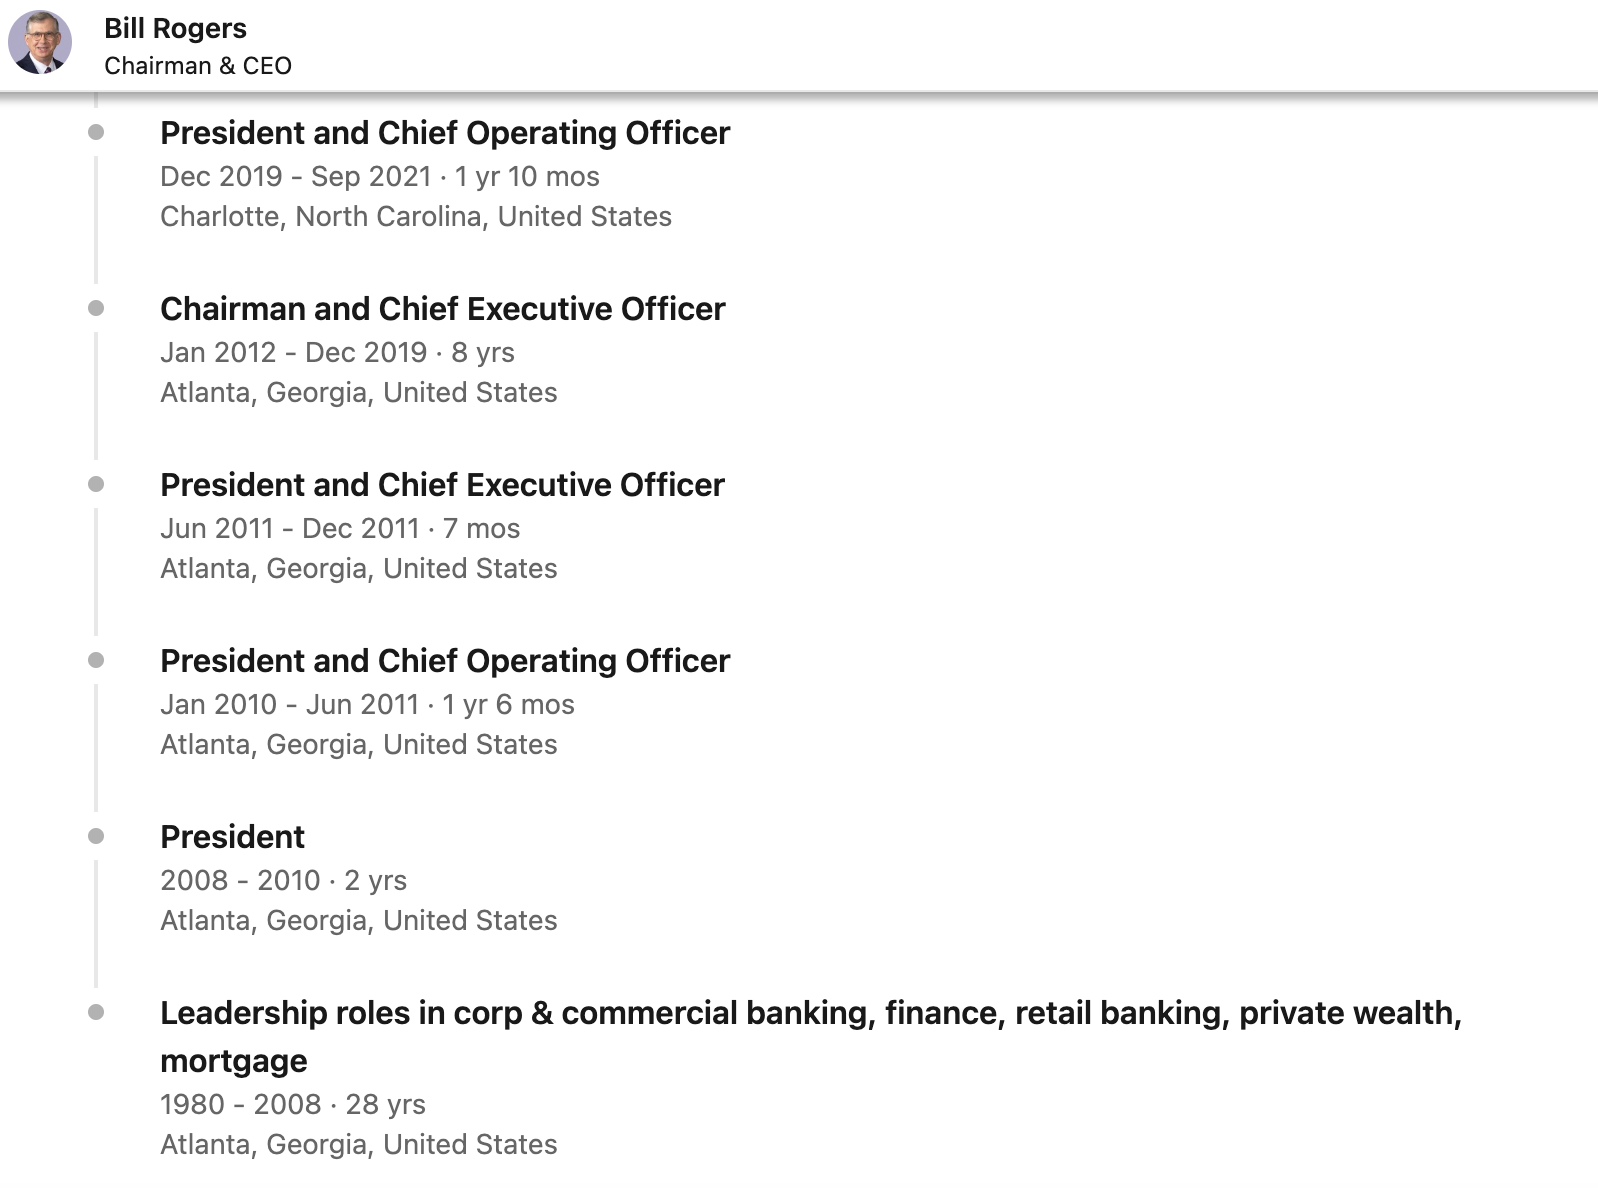
Truist Financial’s current CEO is William H. Rogers Jr., aka “Bill” Rogers. Bill has led the company, in one position or another, since 1980. It’s safe to say, he’s been a decision maker since at least 2008, when he took the role of President. 

Business credit card Truist CEO

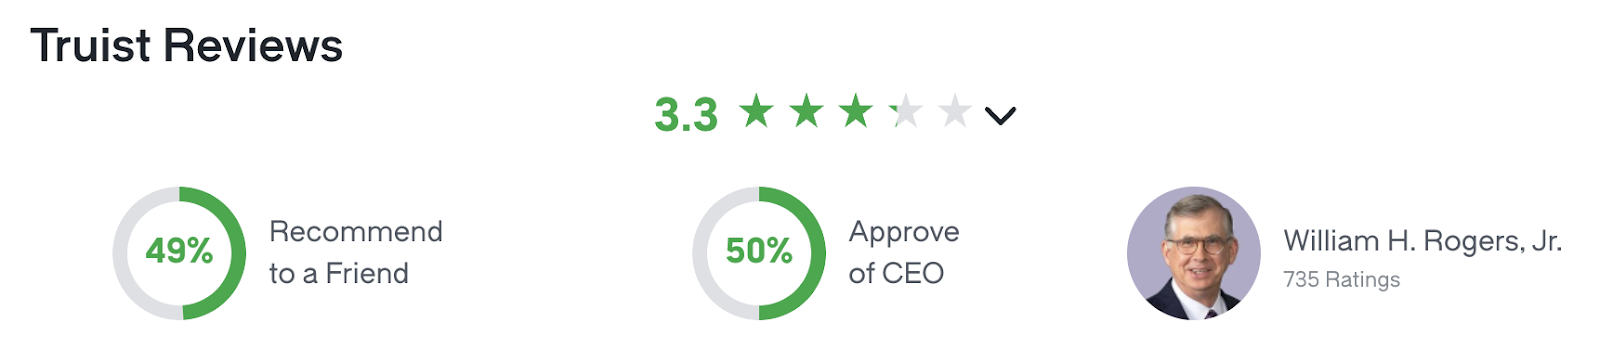
According to Glassdoor, less than half of employees would recommend a job at the company with a friend. And, about half approve of Rogers as CEO. So, while some people love working here, others aren’t so fond of the company, which speaks to their internal ethics. 

Truist business credit card soft pull

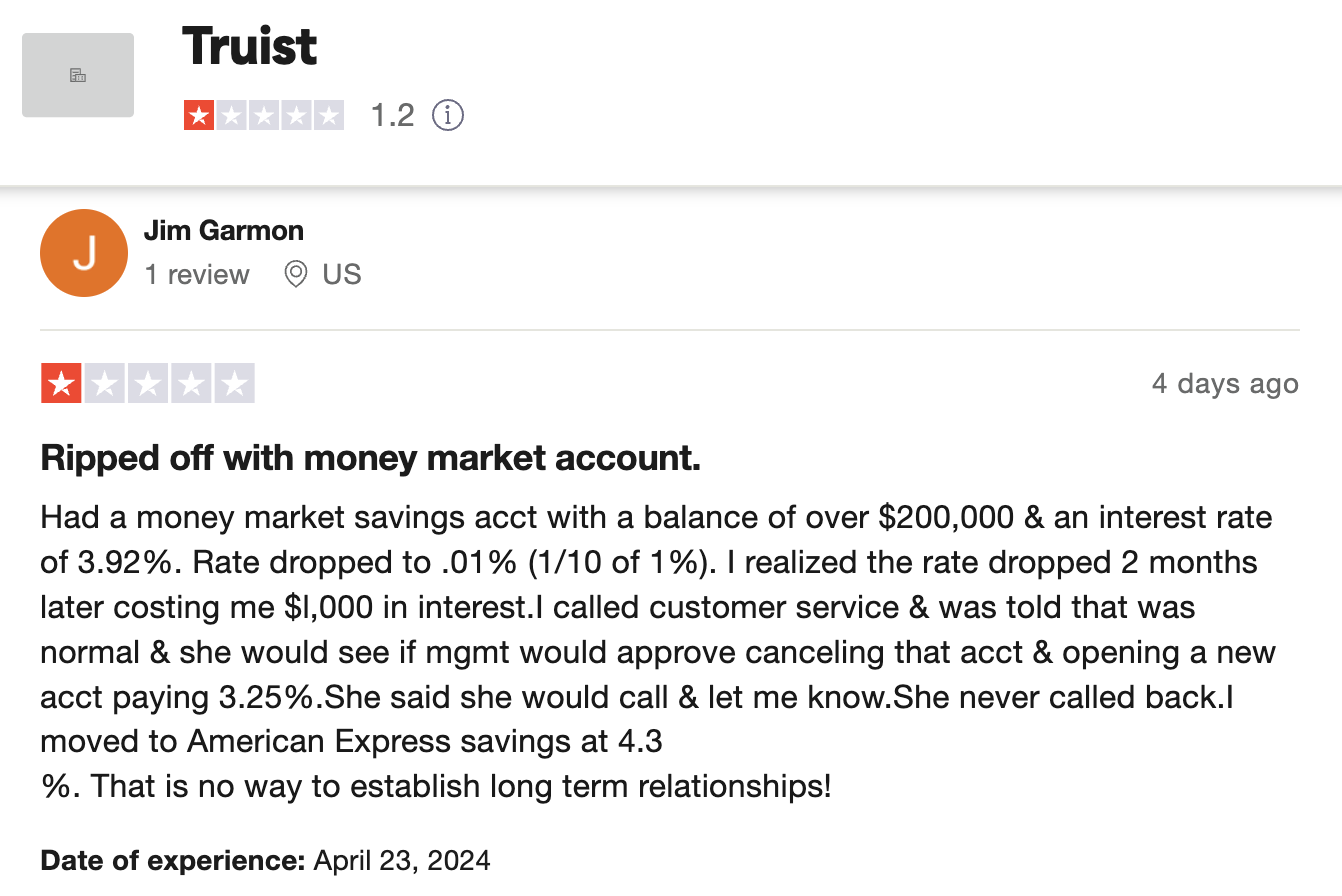
Even more important is what their customers think. Out of X,XXX reviewers on Trustpilot, Truist has an average 1-star (bad) rating. Most of the complaints point to customer service, but some people are completely dissatisfied with the financial products as well. 

Truist business credit card customer service

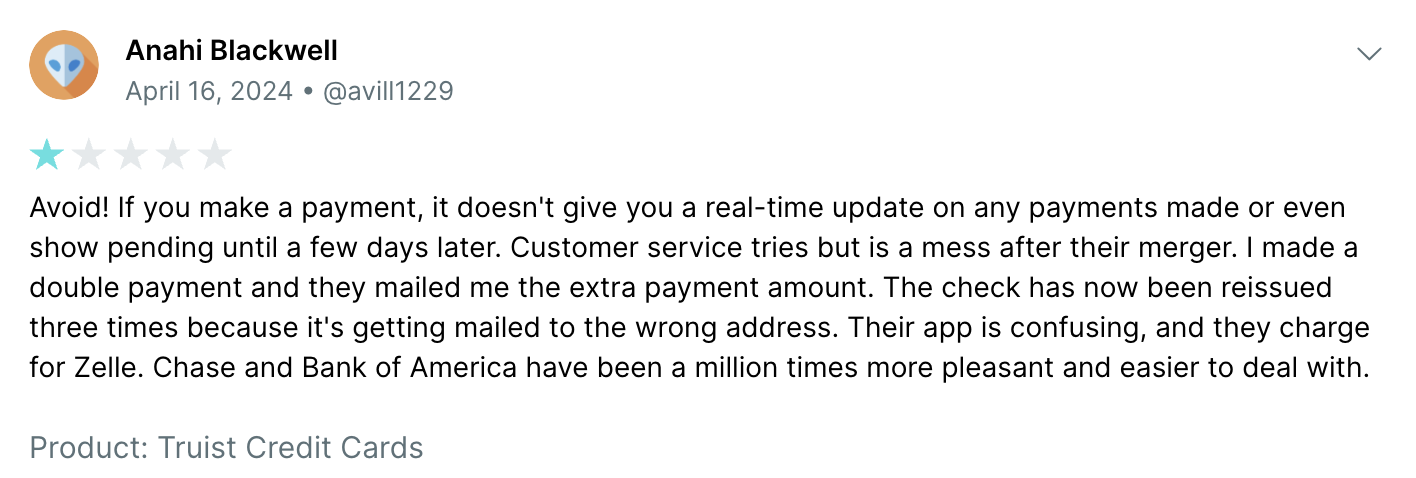
In general, Wallethub reviewers seem to have similar sentiments about Truist. Most people have complaints about customer service. Some people have said that their experience with Suntrust Bank was better before the 2019 merger. 

Truist business credit card customer service number

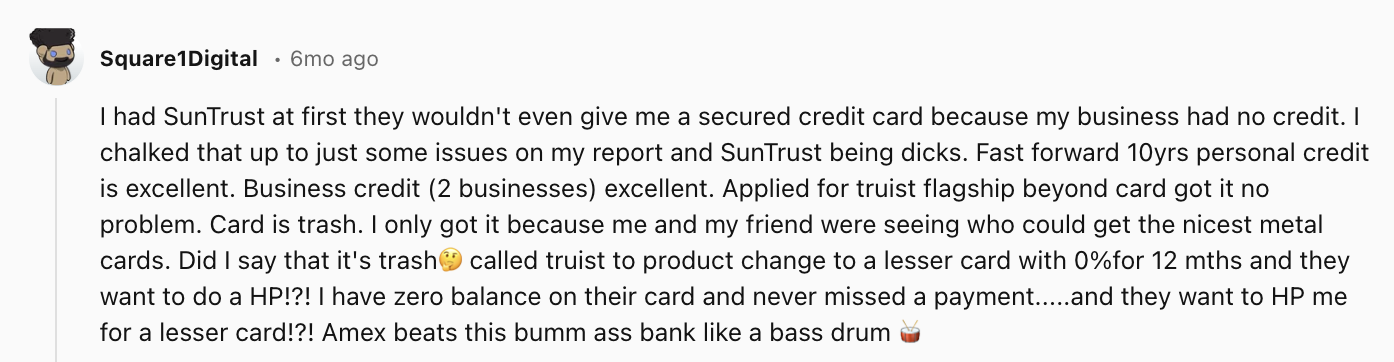
And, Redditors seem to believe the company is understaffed to handle all of their customers responsibly. However, at least one has reported that they were able to get a Truist Bank business credit card when they were unable to qualify through Suntrust—This tells me the qualifications may be less stringent now. 

Truist business credit card phone number

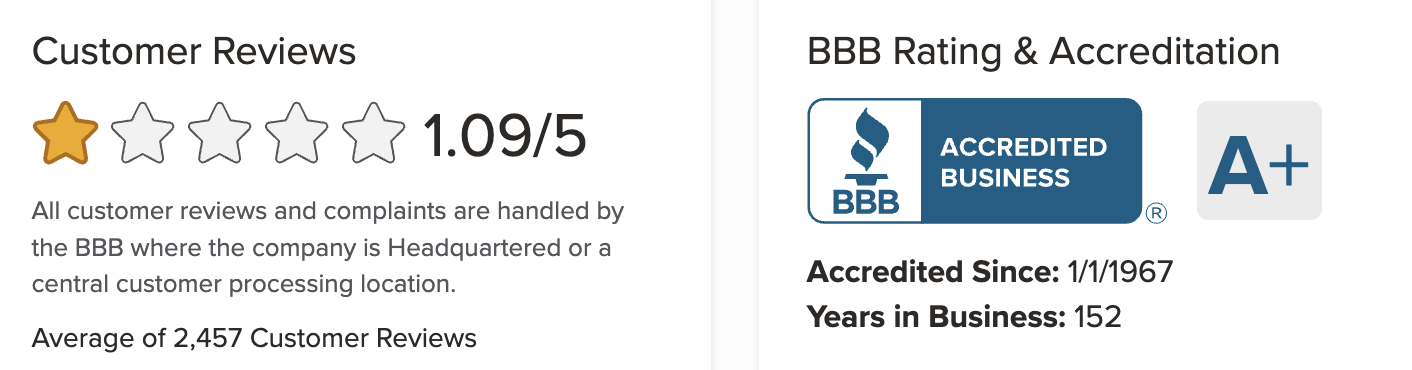
Despite their 1-star rating with the Better Business Bureau (BBB), Truist Bank maintains an A+ rating on the platform. And, they’ve been BBB accredited for nearly 60 years. 

Truist business credit card reviews BBB

Now, in response to all of the negative reviews, I’ve only heard good things from my Business Credit Workshop students.

Finally, as far as legal problems, the bank isn’t squeaky clean—Truist Financial Corp. recently settled a case for $6.3 million, concerning allegations of unjustly reducing interest rates on high-yield money market accounts opened by customers 30+ years ago.

With all of this, it’s not easy to make a recommendation for this bank, but some business credit card holders I know have been satisfied.

Recommended: 6 Best Business Credit Cards for Entrepreneurs: Fuel Your Growth 

The 3 Truist Business Credit Cards

Truist Bank business credit card requirements

Now, Truist offers three business credit cards:

  1. Truist Business Cash Rewards Credit Card
  2. Truist Business Travel Rewards Credit Card
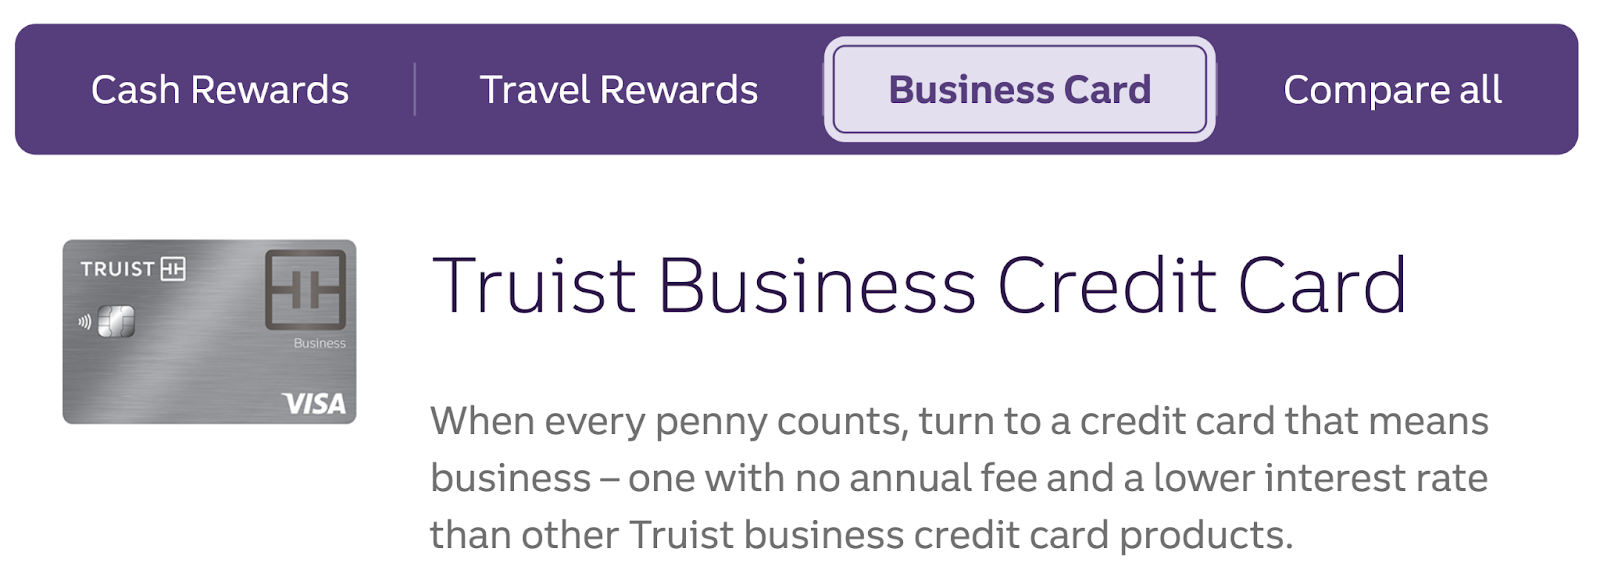
  3. Truist Business Credit Card

Let’s take a closer look at each of them! 

1. Truist Business Cash Rewards

Truist business cash credit card

Truist Business Cash Rewards Credit Card comes with no annual fee and an introductory APR of 0% on purchases for the first 9 months (which later ranges from 17.49% to 26.49% variable APR). 

This card offers cash back rewards, including: 

  • 3% on gas
  • 2% at restaurants and office supply stores (up to $2,000 in combined spend per month)
  • 1% on all other eligible purchases 

Additionally, cardholders can earn a Loyalty Cash Bonus of 10%, 25%, or 50% when depositing cash rewards into an eligible Truist business checking, savings, or money market account. 

This card is ideal for businesses that spend a significant amount of time on the road entertaining clients or making everyday business purchases. It could provide cash back rewards on common business expenses like gas and dining.

You might also like: 7 Best Cash Back Corporate Credit Cards to Explore

2. Truist Business Travel Rewards

Truist business credit card limit

The Truist Business Travel Rewards Credit Card comes with an annual fee of $49, waived for the first year. The APR ranges from 17.49% to 26.49% variable on purchases and balance transfers. 

It offers rewards of: 

  • 2 miles per dollar spent on airfare, hotels, and car rentals
  • 1 mile per dollar spent on all other eligible purchases 

Cardholders can also earn a Loyalty Travel Bonus of 10%, 25%, or 50% when redeeming miles for travel with a Truist business checking, savings, or money market account. 

This card is tailored for businesses with frequent fliers or international travelers. It allows you to earn rewards specifically for travel expenses such as flights, accommodations, and rental cars.

You might also like: What are the Best Business Credit Cards for Travel? 

3. Truist Business

Truist secured business credit card

The Truist Business Credit Card has no annual fee and an introductory APR of 0% on purchases for the first 12 months (which later ranges from 15.49% to 24.49% variable APR). 

Unlike the other cards, it does not offer any loyalty bonuses. 

This card is suitable for businesses with low monthly expenses or those who typically carry a balance on their credit cards, offering an introductory 0% APR period and no annual fee.

You might also like: What is the Best Bank of America Business Credit Card for Your Needs?

More Truist Small Business Products 

Truist business credit card payment

The monthly spending limit on cash back for restaurant and office supply spending on Truist’s Business Cash Rewards Card caught my attention—Once you reach the $2,000 combined limit on purchases within the two main cash back categories, things start to decline. 

However, if you’re a Truist business banking customer and meet the requirements for the Loyalty Cash Bonus booster, it could improve your situation. So, you might want to know that, in addition to their business credit cards, Truist also offers a suite of financial services. 

With Truist, you can access various business banking solutions like: 

  • Checking accounts (including Simple Checking, Dynamic Checking, and Community Checking)
  • Savings options (including Simple Business Savings, Business Money Market, and Business CDs)
  • Online banking
  • Payroll management
  • Merchant services
  • Small business loans (including Simple Business Loan, Auto Loan, Equipment Loan, Real Estate Loan, and Line of Credit)
  • Employee benefits
  • Insurance options
  • A resource center featuring a blog and webinars

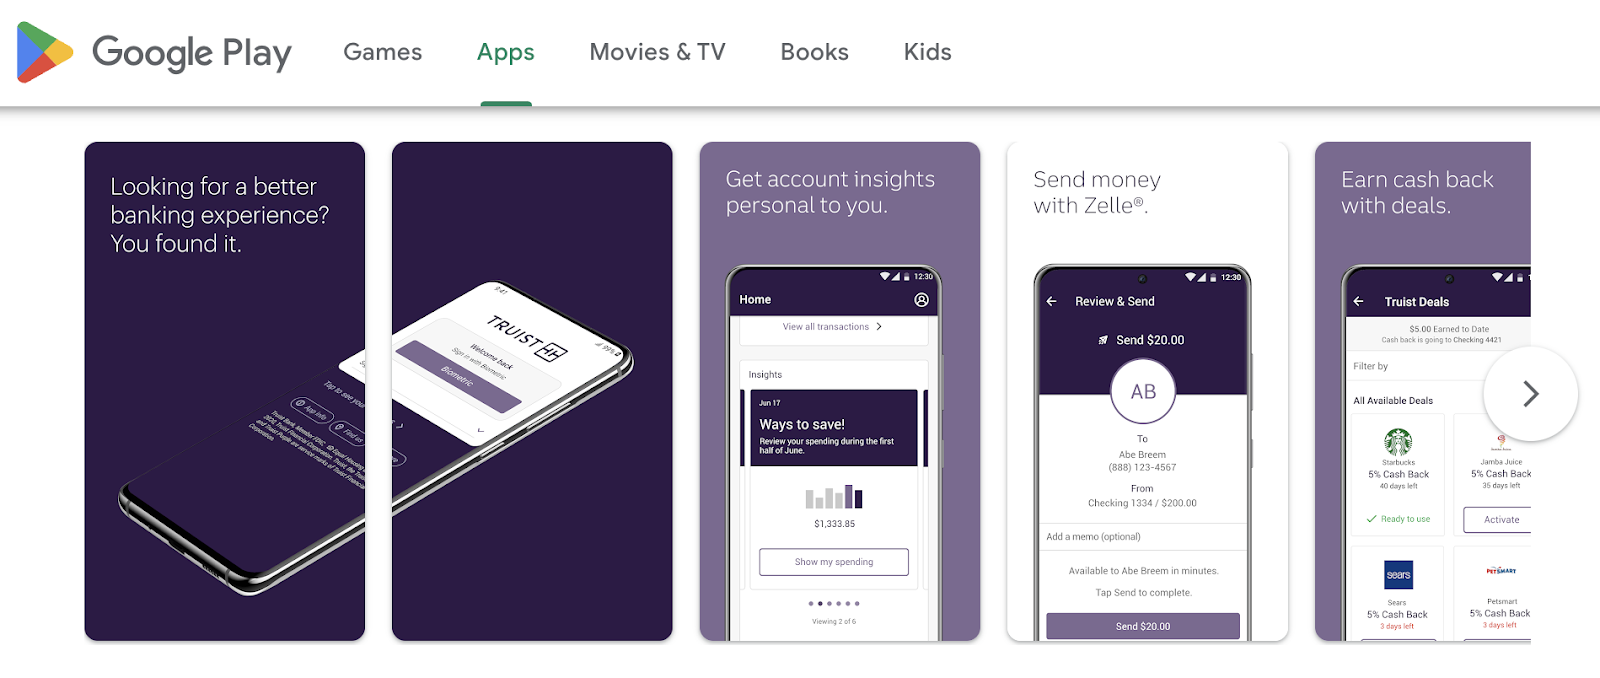
Plus, their mobile app is highly rated on the Google Play store and the iOS app store—this might be the highlight of their offer, and it’s worth looking into. 

Truist business credit card login

So, if you’re feeling like this might be a good place to seek credit cards, consider Truist’s other banking and business resources. 

You might also like: Novo Bank Review: First-Rate Small Business Banking or Scam? 

Frequently Asked Questions 

Can I get a business credit card using my EIN number?

Yes, you can apply for a business credit card using your Employer Identification Number (EIN). Truist and many other banks allow businesses to apply for credit cards using their EIN rather than their personal Social Security number.

Do I need a business credit card for an LLC? 

While not mandatory, having a business credit card for your LLC can help separate your personal and business finances, track expenses, and build credit for your business.

What credit score do you need for a Truist credit card? 

Truist does not publicly disclose specific credit score requirements for their credit cards. However, generally, a good to excellent credit score is typically needed to qualify for a Truist credit card.

Does Truist business credit card report to personal credit? 

Truist business credit cards may report to personal credit bureaus, depending on the card and your usage. They will typically report activity to both business and personal credit bureaus

What is the minimum credit limit for Truist? 

Truist does not specify a minimum credit limit publicly. Credit limits are determined based on various factors including creditworthiness, income, and other financial considerations.

Conclusion 

Truist Business Credit Cards offer diverse options tailored to small businesses’ needs. With features like cash back rewards, travel rewards, and no annual fees on select cards, Truist aims to provide valuable solutions for businesses of all sizes. In general, existing Truist customers tend to send more warnings than inviting recommendations—this says a lot. 

My students like the card and I haven’t heard any complaints from them.

However, you should carefully consider your specific business needs and financial situation before applying. While Truist does not publicly disclose specific credit score requirements or minimum credit limits, having a good to excellent credit score is generally advisable for approval. 

Keep in mind, Truist business credit cards may impact your personal credit score as they may report to personal credit bureaus. 

Overall, Truist offers a comprehensive suite of financial products and services beyond credit cards, including checking and savings accounts, online banking, small business loans, and more. Whether Truist is the right fit for your business ultimately depends on your individual needs and preferences.

Do you want to learn how to get up to $100K in business credit in as few as 30 days? Join Business Credit Workshop today!
6 Best 0% APR Business Credit Cards to Check Out 

By Joe

0 apr business credit cards

As a business owner, there’s no end to how you can use credit to grow your business. But, one of the downsides to using credit versus cash is the fact that it can cost you. If you fail to pay credit in full each billing cycle, annual percentage rate (APR) interest can add up fast—But, not if the APR is 0%. 

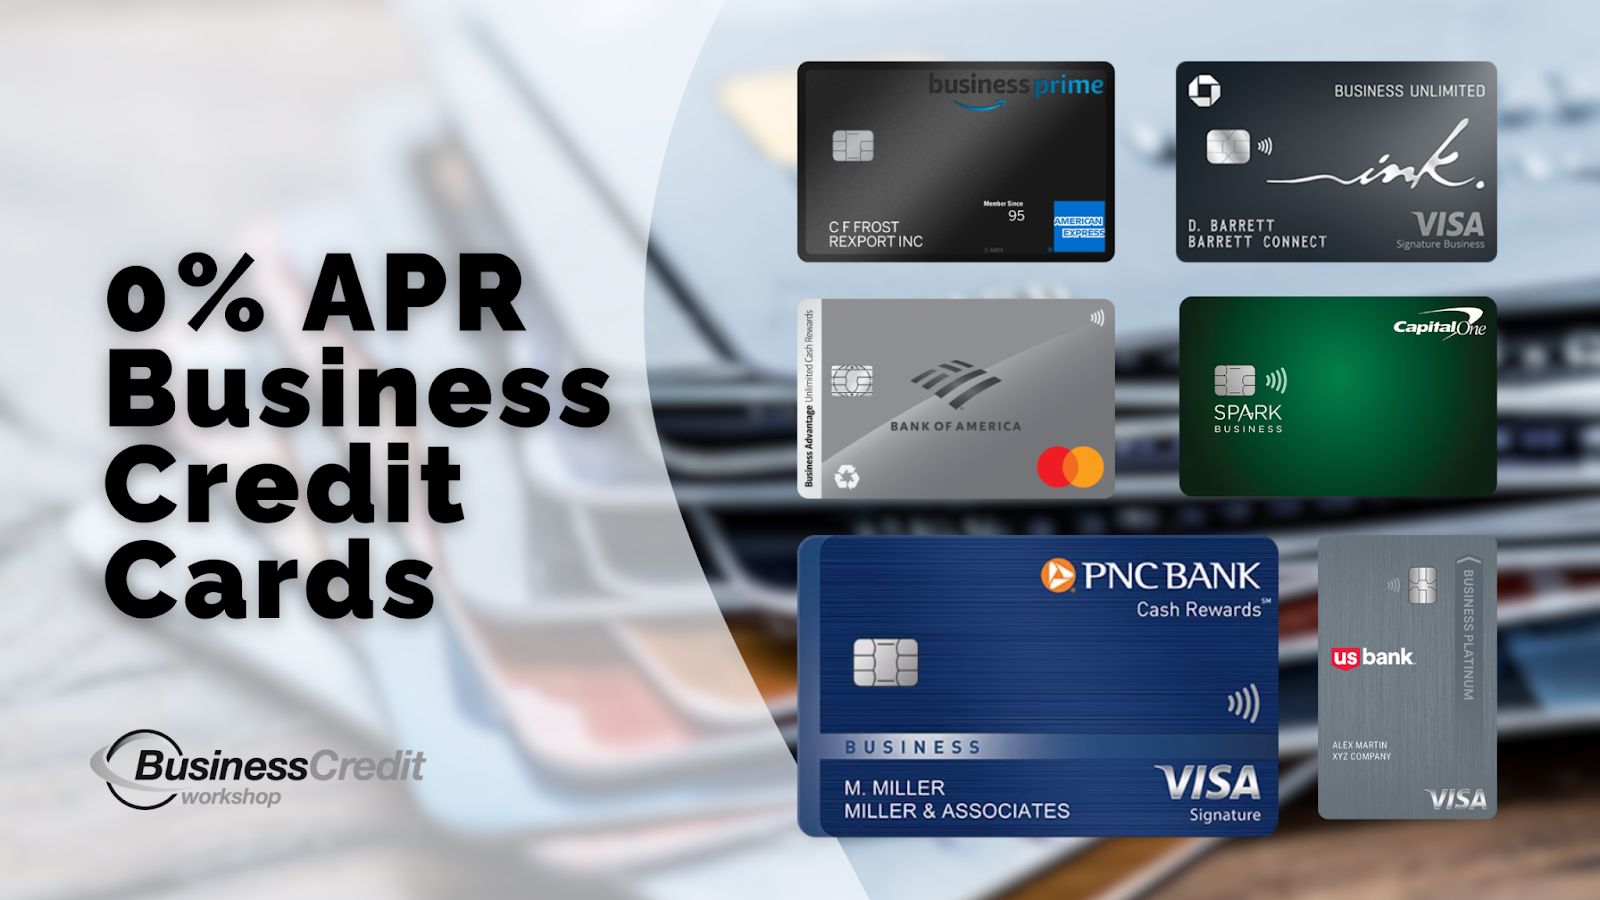
0% APR business credit cards can save you a ton of interest, if used responsibly. But, where can you find them? There are needles in a haystack with no interest ever, and others you can leverage at 0% introductory rates. Simply put, here are the top business credit cards with 0% APR that I know of right now. 

This is what’s in store: 

  • What is a Good APR for a Business Credit Card?
    • Can You Get a Credit Card with 0% APR?
  • The Best Business Credit Cards With 0% APR
    • 1. PNC Cash Rewards Visa Signature Business
    • 2. U.S. Bank Business Platinum Card
    • 3. Capital One Spark Business 1.5% Cash Select
    • 4. BofA Business Unlimited Cash Rewards
    • 5. Chase Ink Business Unlimited
    • 6. Amex Amazon Business Prime
  • Frequently Asked Questions
  • Final Thoughts

Now, let’s roll!! 

What is a Good APR for a Business Credit Card? 

Generally speaking, the lower the APR on a business credit card the better — this is if you plan to carry a balance. The lower the rate, the less you’ll pay. Think of it like this: With credit cards, you’ll be charged interest on any money that you owe at the end of a billing cycle. 

So, if you spend $1,000 on your credit card, and you only pay $100 at the end of the month, you will still owe $900 to the card issuer. The issuer will charge interest on that $900. The lower the interest rate/APR the less you will pay. 

According to data collected by the Federal Reserve, the average interest rate on credit cards issued by commercial banks was 21.47%, which increases over time – So, anything lower than this might be considered a “good” APR. However, this doesn’t account for cards issued by credit unions nor separate business products from those issued to consumers. 

Keep in mind, if you pay the balance on your business cards in full each month, you won’t have to worry about APR. 

You might also like: 3 Best Credit Unions for Small Business Banking in 2024 

Can You Get a Credit Card with 0% APR?

You can absolutely get a credit card with no annual interest rate—Both 0% APR business credit cards and 0% APR consumer credit cards can be found on the market. 

In most cases, when a business credit card comes with no annual fee, this is an introductory rate…A 0% introductory rate means that you will pay no interest for a specified period, which is usually 6, 12, 18, or 24 months. After this, the interest rate will revert back to its normal rate. At this point, you will be charged the full interest for any balance still owed, no matter when the debt accrued. 

Another business financial product that people sometimes refer to as a business credit card is a corporate card. Many corporate cards come with 0% APR, and several even offer cash back on purchases. However, a corporate card is not technically a business credit card.  

You might also like: Corporate vs Business Credit Card: What’s the Difference? 

The Best Business Credit Cards With 0% APR

Let’s take a look at the top business credit cards you can get today with 0% APR. 

Note: Credit cards rates can vary – always check with the card issuer before you apply. 

You might also like: 6 Best Business Credit Cards for Entrepreneurs: Fuel Your Growth 

1. PNC Cash Rewards Visa Signature Business

0 apr business credit cards no annual fee

The PNC Cash Rewards Visa Signature Business Credit Card offers a $400 bonus when you open a new account and make at least $3,000 in qualifying purchases within the first three billing cycles—It also features an introductory 0% APR for the first 9 billing cycles (9 months), with a variable APR of 19.24% to 27.24% afterward. 

With this card, you earn 1.5% cash back on net purchases, with no limits on your earning potential. You can easily manage your account online with various tools provided. Additionally, as a Visa Signature cardholder, you’ll enjoy travel benefits and purchase protection.

There’s no annual fee, and for balance transfers, you’ll pay either $5 or 3% of the transfer amount, whichever is greater. Cash advance fees are either $10 or 4% of the advance amount, with a maximum fee of $75. Late payment and over-the-credit-limit fees may apply.

A noteworthy perk: if you have a PNC business checking account, using this credit card could help offset your monthly maintenance fee.

Recommended: PNC Bank Business Credit Card Review & Comparison 

2. U.S. Bank Business Platinum Card

u.s. bank business credit card

The U.S. Bank Business Platinum Card offers a 0% introductory APR on purchases and balance transfers for 18 billing cycles (a year and a half), making it ideal for managing expenses and consolidating debt. After the introductory period, a variable APR applies.

This card comes with a low annual fee and provides cards for both you and your employees–This U.S. Bank business credit card gives you access to a dedicated domestic servicing center with 24/7 customer support, which ensures assistance whenever you need it.

With Visa Spend Clarity™, you can track spending and manage expenses more effectively. The card has received honors, including being named Best 0% APR Credit Card by WalletHub and Best Business Cash Back Card for Gas by Forbes.

Furthermore, the U.S. Bank Business Platinum Card allows you to pay over time with U.S. Bank ExtendPay® Plan, and new cardmembers can take advantage of a $0 fee offer on ExtendPay Plans opened within the first 60 days after account opening.

You might also like: What are the Best Unsecured Business Credit Cards for Startups? 

3. Capital One Spark Business 1.5% Cash Select

best 0 apr business credit cards

The Spark 1.5% Cash Select credit card from Capital One is tailored for businesses with good credit. It offers unlimited 1.5% cash back on all purchases, with no category restrictions, and an additional unlimited 5% cash back on hotels and rental cars booked through Capital One Travel. 

There’s a $0 annual fee, and for the first 12 months, there’s a 0% introductory APR, followed by a variable APR ranging from 21.24% to 29.24%, based on your creditworthiness.

The card provides benefits like: 

  • Automatic payments
  • $0 fraud liability
  • Year-end summaries for simplified budgeting and tax preparation
  • Account managers for assistance with purchases and payments
  • Purchase record downloads in various formats
  • Virtual card numbers for enhanced online security

The application process takes about 10 minutes, and decisions are typically made in seconds. 

To apply, you’ll need to provide information about all business owners, including legal names, addresses, and Social Security Numbers, as well as details about your business, such as its legal name, address, and tax identification number (EIN).

You might also like: What are the Best Business Credit Cards for Travel? 

4. BofA Business Unlimited Cash Rewards

bank of america business credit card

The BofA Business Unlimited Cash Rewards credit card by Bank of America offers a $300 online statement credit bonus after spending at least $3,000 within the first 90 days of opening an account. It allows you to earn unlimited 1.5% cash back on all purchases, with no annual cap and no expiration on rewards. 

Moreover, if you have a Bank of America business checking account and qualify for the Preferred Rewards for Business Platinum Honors tier, you can earn up to 75% more cash back, up to an unlimited 2.62% cash back on purchases.

This card features flexible redemption options, including depositing cash rewards into your Bank of America checking or savings account, receiving a statement credit, or getting a check mailed to you. 

There’s no annual fee, and it offers a 0% introductory APR on purchases for the first 9 billing cycles, followed by a variable APR ranging from 18.49% to 28.49%—The card provides various features to manage cash flow, online and mobile access for account management, travel and emergency services including travel accident insurance, free access to business credit scores, security measures such as zero liability protection and fraud monitoring. 

Notable: It also offers Balance Connect® for overdraft protection when linked to a Bank of America business checking account.

Recommended: What is the Best Bank of America Business Credit Card You Can Get? 

5. Chase Ink Business Unlimited

Best business credit cards 0 apr

The Ink Business Unlimited® Credit Card from Chase offers a substantial new cardmember bonus of $750 cash back after spending $6,000 on purchases within the first 3 months of opening an account. With no annual fee, this Chase business credit business card allows you to earn unlimited 1.5% cash back on every purchase made for your business.

For the first 12 months from account opening, there’s a 0% introductory APR on purchases, which then transitions to a variable APR of 18.49%–24.49%. You can redeem your rewards on this card for cash back, gift cards, travel, and more through Chase Ultimate Rewards®.

Employee cards come at no additional cost and allow you to set individual spending limits while helping you earn rewards faster. Additionally, until March 2025, you can earn a total of 5% cash back on Lyft rides with your Chase Ink Unlimited card, which includes an extra 3.5% on top of the 1.5% you already earn on travel.

Chase also offers referral incentives for existing cardholders, allowing them to earn up to 200,000 points per year by referring businesses for any Chase Ink® Credit Card.

You might also like: Chase Ink Business Preferred Credit Card: A Deep Dive Analysis 

6. Amex Amazon Business Prime 

0% business credit card

The Amazon Business Prime Card, offered by American Express, comes with a $0 annual fee and offers a $125 Amazon.com Gift Card upon approval. It features a variable APR ranging from 19.49% to 27.49% on purchases, based on creditworthiness.

This card rewards your business with:

  • 5% cash back or 90-day terms on select U.S. purchases at Amazon Business, AWS, Amazon.com, and Whole Foods Market, with a cap of $120,000 in purchases each calendar year with eligible Prime Membership, and 1% back thereafter.
  • 2% cash back on U.S. purchases at restaurants, gas stations, and wireless phone services purchased directly from service providers.
  • 1% cash back on all other eligible purchases.

Additional benefits include Amazon Business Enhanced Data Views for detailed expense tracking, Amazon Shop with Points for flexible reward redemption, and no foreign transaction fees.

You can manage expenses efficiently with features like Account Manager, Employee Cards with spending limits, and integration with QuickBooks® for auto-expense categorization – Moreover, cardholders receive baggage insurance, car rental loss and damage insurance, extended warranty protection, purchase protection, and access to Amex Offers for additional rewards.

Recommended: Amazon Business Prime Credit Card: Full Review +How to Get One  

Frequently Asked Questions

What credit score do you need for 0% APR? 

Typically, you need a good to excellent credit score (usually 670 or higher) to qualify for a 0% APR offer on a credit card. Each card issuer has their own underwriting and qualification terms. 

Why 0% APR offers might not be good for your credit? 

0% APR offers can impact credit negatively if not managed properly. They may encourage overspending, leading to higher debt levels. Additionally, opening new credit accounts can temporarily lower your credit score due to inquiries and reduced average account age.

Is 23% APR high for a credit card? 

Yes, a 23% APR is slightly above the average for credit card APRs, which was around 21.47% according to Federal Reserve data.

Is 29% APR high? 

Yes, a 29% APR is significantly higher than the average credit card APR, indicating high-risk lending.