• Home
  • Free Funding Guide
  • What We Offer
    • Products
    • Services
    • Free Guide
  • About Us
  • Contact
  • Sign Up

  • Ask Joe Any Question!
  • Business Credit Cards
  • Business Line of Credit
  • Topics

Can you transfer a personal credit card to your business?

By Joe Lawrence

can you transfer personal credit card to business

In the world of business, the lines between personal and business finances can sometimes blur. This is particularly true during the early stages of entrepreneurship. Many business owners rely on credit cards or funds to support their ventures. Unfortunately, this approach poses several challenges, especially relating to increased personal liability and potential tax issues down the line.

While it is true that you can use your personal credit card for business expenses, have you considered transferring personal debt to your business? This post explores the distinctions between personal and business credit and offers practical steps to transfer personal credit to your business effectively.

Personal vs. Business Credit: What are the Differences?

To understand the process better, let us quickly examine the differences between personal and business credit. Here are some facts about personal credit:

  • Used for personal expenses like buying a car and home
  • Personal liability for any debts incurred
  • Connected to the Social Security Number (SSN)
  • Reported to consumer credit reporting agencies like Equifax, TransUnion, and Experian
  • Credit scores range from 300 to 850
  • Subject to consumer protection laws, including the Fair Credit Reporting Act (FCRA) and the Fair Debt Collection Practices Act (FDCPA)

Meanwhile, here are some things to know about business credit:

  • Used for business expenses like purchasing equipment and inventory
  • Utilized for managing operational costs and cash flow
  • Tied to Employer Identification Number (EIN) or Tax Identification Number (TIN)
  • Liability for debts is on the business and not the individual owner
  • Reported to business credit bureaus like Dun & Bradstreet, Equifax Business, and Experian Business
  • Credit scores range from 0 to 100 (or 0 to 300, depending on the credit reporting bureau)

Payment history and length of that history, credit utilization, and types of credit used are some of the factors that affect both personal and business credit.

Can You Use Your Personal Credit Card for Business Expenses?

Keeping track of expenses can be challenging, so some people opt to use a personal card for both personal and business-related purchases. To address the question above, yes, you can use your personal card for business expenses.

You might choose to do so for several reasons, including the enhanced protection offered by the Credit Card Accountability Responsibility and Disclosure Act of 2009 (Credit CARD Act). This legislation provides better safeguards for cardholders by requiring written disclosures and imposing limits on fees and interest rates.

Why Transfer Your Personal Debt Over to Your Business

While you can use your credit card for business expenses, it lacks the same legal protections as business credit. If your company is set up as an LLC or a corporation, you automatically obtain legal protections based on your chosen business structure. However, intertwining your personal and business expenses can diminish or even nullify those protections you would otherwise enjoy.

If that’s not convincing enough, here are additional reasons why transferring personal credit to business is a smart financial move:

  • If there are ever any legal or financial issues, minimize your personal financial risk, even as the business owner.
  • Transferring personal debt to business credit helps establish your business’s credit profile and history, which is crucial for accessing credit lines and loans.
  • Business credit, when used for business expenses, aids in simplifying tax reporting. This activity can also maximize tax deductions, potentially reducing tax liabilities and taxable income.
  • Building strong credit for your business shows professionalism and credibility as it is a demonstration of how responsible and stable your business is. These traits are essential to other entities you will likely work with, such as suppliers, partners, lenders, and even your customers.
  • Separating business from personal credit allows access to more credit and financing options based on your company’s creditworthiness. That way, you do not have to rely solely on personal credit limits, which are often lower.

Creating a clear distinction between your personal and business credit profiles is significant in defining the company as a separate legal entity. By using business credit accounts, such as business credit cards or lines of credit, when incurring business-related expenses, you begin to build your company’s own credit history. However, just like personal credit, you should always make on-time payments and manage your business credit responsibly to create a positive credit history for your company.

How to Transfer Personal Credit to Business: The Different Methods

One standard method for transferring personal credit to a business is to apply for business credit cards, which should be under the business’s name. Doing so lets you establish your business’s credit history while separating its usage from your credit cards. Other ways to go about it include the following:

  • Applying for business lines of credit to access funds for your ongoing expenses
  • Applying for business loans from banks or alternative lenders when in need of funding for expansion and other more significant investments
  • Establishing trade credit accounts with vendors and suppliers, such as Net 30 vendors, that allow your business to make purchases on credit
  • Using alternative financing solutions specific to businesses, including merchant cash advances and invoice factoring
  • Exploring rental or lease agreements for vehicles, real estate, or equipment to build a credit profile

It may also be an option to cosign with a personal guarantee, mainly if you first must use personal credit to secure business loans or business credit cards. This method, however, involves personal credit. Nevertheless, it still contributes to building your business’ credit history.

With the choices above, picking the proper method for you may be a little confusing. The best way to do it is to select the option based on your creditworthiness and business requirements. For example, you can consider your short-term and long-term goals, such as whether you want to finance immediate expenses. Perhaps you wish to build credit for the future or invest in growth opportunities. Whatever your goal, you can align it with the best method for your business.

Other factors to consider include:

  • Your business’s creditworthiness
  • Payment history
  • Debt-to-income ratio
  • Credit score
  • Existing credit accounts, if any
  • Type and size of funding you need
  • Interest rates and fees
  • Repayment terms

The method you choose can impact your credit and liability as an individual, such as if it requires cosigning or a personal guarantee, so consider that as well. It is also helpful to assess the method’s long-term sustainability, especially if it will benefit your business’s financial growth and stability in the long run.

Steps to Take

Regardless of the method you see fit for transferring personal credit to business credit, the entire process involves a few steps, which often include the following:

If you have not done so, you will first have to incorporate a legal business entity. This means picking whether you have a partnership, a Limited Liability Company (LLC), a corporation, or any other type of business structure. You will also have to register it with the local and state government. From here, you can obtain an Employer Identification Number (EIN) from the Internal Revenue Service (IRS).

You will then need to open a business bank account in the name of your business. This account will be used for all your business-related purchases and transactions. That way, there is a clear separation between your personal and business expenses.

The next useful step is to have a business credit card. Make sure that you do comprehensive research by comparing various card options. Don’t just look at offers from banks; explore other products from financial institutions and credit unions. When applying, you must use the legal name of your business and provide its EIN and other relevant information. Once you have a credit card, you should always pay your debt on time whenever you use it for business expenses. This is the key to establishing a positive credit history for your company.

business credit card

Some businesses may skip this step, but it is helpful in many ways. You need trade credit accounts as you continue to grow as a business. Be sure to foster relationships with trade partners and suppliers that use trade credit terms. You may also request to open a trade credit account under your business and use it for purchases on credit. Once again, you need to pay net 30 invoices promptly, which will show suppliers and vendors your creditworthiness. It also establishes trust, making it easier for you to access larger financing in the future.

You can apply for lines of credit or business loans from online lenders or banks using your business information. At this stage, you will typically be asked to provide financial data, such as a business plan, revenue, and cash flow. Once approved, you can use the lines of credit and loans for operational, investment, and expansion investments. Just like other debts, you should always maintain responsible repayment to help build your business’s credit profile.

At this stage, you can use the balance transfer option with the new business credit card / business line of credit to transfer your debt over. Some banks will also allow you to use “convenience checks” where you can write a check using your business credit card available balance to your personal credit card company to payoff the balance (and avoid a cash advance fee). You can also look into programs like Plastiq and Melio Payments to get cash off your business credit card.

Your work is incomplete, as you must still monitor and manage your business credit. It always helps to review your business credit reports regularly. If you find any errors, dispute them, as they will not fix themselves. You must ensure accuracy in reporting all your credit activities. Don’t forget to maintain a low credit utilization rate while avoiding accumulating excessive debt under the name of your business.

You might also like: Our Review of NAV, a service that boosts, tracks and monitors business credit scores

Using your business credit accounts involves being responsible for you to build a positive credit history for your company. As you keep your credit utilization low, it helps to increase your credit limits. Do so gradually as your credit history improves and your finances stabilize.

Common Pitfalls to Avoid

As the process ensues, you will realize that some difficulties may arise that could add to the challenge. Therefore, it is crucial to be on the lookout for the following pitfalls:

Many businesses fail to separate business and personal expenses, which typically leads to confusion and inaccuracies, particularly in their financial records. If there is no clear distinction between the two, tracking deductible expenses can pose a challenge, resulting in paying more taxes than you should. Always talk to a tax qualified professional when considering getting credit and moving debt from person to business.

Another issue is relying on personal credit when making business purchases. Although this is the more convenient option for some people, it hinders their businesses’ ability to build a strong credit profile.

One more problem is operating as a sole proprietorship without forming a legal business entity. Unfortunately, this approach exposes the owner to personal liability, especially given the rising business debts and obligations.

Not having a business bank account is another issue to address as you progress with the transfer. That way, you avoid complicating the accounting procedures and tax reporting, making it easier to track income and expenses.

Legal and Financial Implications to Consider

While there are benefits to transferring personal to business credit, it is vital to understand the potential legal and financial implications of the activity for both the business and the owner. These include the following:

You can get legal liability protection as a business owner when you move your personal credit to business credit rather than having it all in one account. However, you must operate as a single entity, such as an LLC, to shield your personal assets from possible debts and lawsuits.

Some lenders require a personal guarantee, particularly if you have a new business. Typically, this means you do not have an extensive credit history. With a personal guarantee, you should know that you, as the business owner, will be held liable for any financial obligations. That includes if your business defaults on credit payments.

While a personal credit to business credit transfer establishes a separate credit profile and history for your company, it can also result in negative credit activity. Late payments and other mistakes can adversely affect your business’s creditworthiness. You must continuously build and protect your credit profile so that you do not have to worry about accessing financing in the long run.

visa-credit-card

The transfer requires careful documentation and recordkeeping. Otherwise, you could risk complying with tax laws and missing proper business deductions.

Compliance with the rules and requirements is important when using business credit. It mitigates potential issues and ensures legal adherence, so be sure to be mindful of your business’s legal structure and registration. Your business must have the appropriate licenses and permits to operate legally. Talk to a representative or local authorities if you require more information.

Finally, it is valuable to understand the reporting requirements of business credit bureaus, such as Experian Business and Dun & Bradstreet. You should always have your business credit activity report accurately, including your timely payments and credit utilization, for a favorable credit profile and history.

Conclusion

Transferring your personal credit to business credit is a smart move that can yield significant benefits. The biggest benefit is the potential to improve your personal credit utilization, which can really boost your personal credit score a lot. With a distinct separation between business and personal finances, you can protect your personal assets while aiming to access financing options and build a good credit profile for your company. Take the first step toward building your business credit profile by signing up for free business credit training today!

FAQ

Why should I transfer my personal credit to my business?

It can boost your personal credit score by lowering your utilization. Plus establishing a separate credit profile for yourself and your business can give your business access to more financing options while protecting your personal assets against potential company-related debts and obligations.

How do I transfer personal credit to my business?

You can apply for business credit cards, open a trade credit account with a supplier, or apply for a business loan. Then use a balance transfer or convenience checks.

Why should you not mix personal and business credit?

It is often difficult to separate expenses, making it difficult to track expenses. This can also be a problem when reporting business credit activities. Not mixing personal and business expenses on your personal credit profile can also help with asset protection.

How do I ensure compliance with legal and regulatory requirements when using business credit?

It helps to be knowledgeable about the Truth in Lending Act and Fair Credit Reporting Act, as well as other regulations that may be specific to your business and industry. That way, compliance is much easier as you continue to grow your company. You should also spend the time to speak to an attorney and a tax qualified professional, like a Certified Public Accountant (CPA).
Is the National Debt Relief Program Legit? The Honest Answer

By Joe

National Debt Relief

If your debt is stressing you out, you’re not alone. According to Forbes, 54% of Americans are stressed about their debt. And, if you’re in this boat, you may have come across National Debt Relief – which sounds almost like a way to eliminate debt altogether. 

As with any offer that affects your finances, you need to know whether this is a legitimate offer before you sign up. So, I’m going to share everything I know. We’ll look at what National Debt Relief is, what they can do for you, and the services they offer. By the end, you should know if this is the right offer for you. 

This is what’s in store: 

  • What is National Debt Relief?
    • Where Does National Debt Relief Operate?
    • How Does National Debt Relief Work?
    • How Much Does National Debt Relief Get Paid?
    • Company Overview
  • What Does National Debt Relief Do?
    • 1. Free Consultation
    • 2. Personalized Debt Relief Plan
    • 3. Credit Counseling & Education
    • 4. Debt Negotiation With Creditors
    • 5. Debt Consolidation Loans
    • 6. Bankruptcy Referrals
  • Frequently Asked Questions
  • Conclusion: Is National Debt Relief Legit?

Now, let’s set sail! 

What is National Debt Relief? 

National Debt Relief reviews

National Debt Relief is a company that helps people tackle their debt through various debt relief services. 

Depending on your situation, services might include: 

  • Negotiation with creditors
  • Debt consolidation loans
  • Credit counseling services
  • Bankruptcy referrals 

They provide a free consultation where you can discuss your financial situation and explore your options…allegedly without any obligation. 

While they don’t offer tax debt relief or any government loans, they cover nearly every other type of debt you can think of. 

National Debt Relief commercial

This includes relief from: 

  • Credit card debt
  • Personal loans
  • Bad credit debt
  • Medical debt
  • Unemployment debt
  • Retirement debt
  • Veteran debt
  • Business debt
  • Private student loans
  • Marital debt (wedding or divorce) 

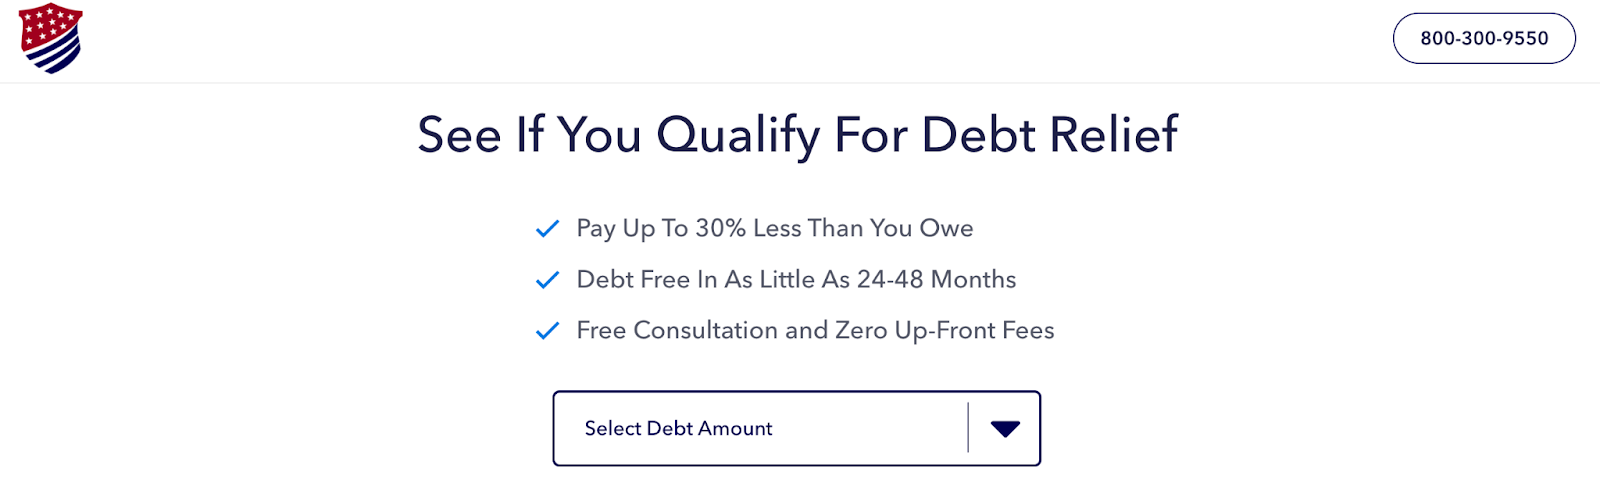
Ultimately, National Debt Relief aims to help you become debt-free within a reasonable timeframe, typically within 24-48 months. They emphasize affordability and customization, ensuring that their solutions align with your budget and financial goals.

Recommended: Credit Secrets Book Review: Can You Erase Bad Credit History? 

Where Does National Debt Relief Operate? 

National Debt Relief New Hampshire

As of March, 2024, and despite what the brand’s name implies, National Debt Relief doesn’t operate in all 50 states (I wouldn’t have known this if I didn’t call in to ask a few questions about pricing). When I asked which states they do operate in, the rep advised that I do a search for debt relief specifically in my state so I didn’t get a straight answer…not right away. 

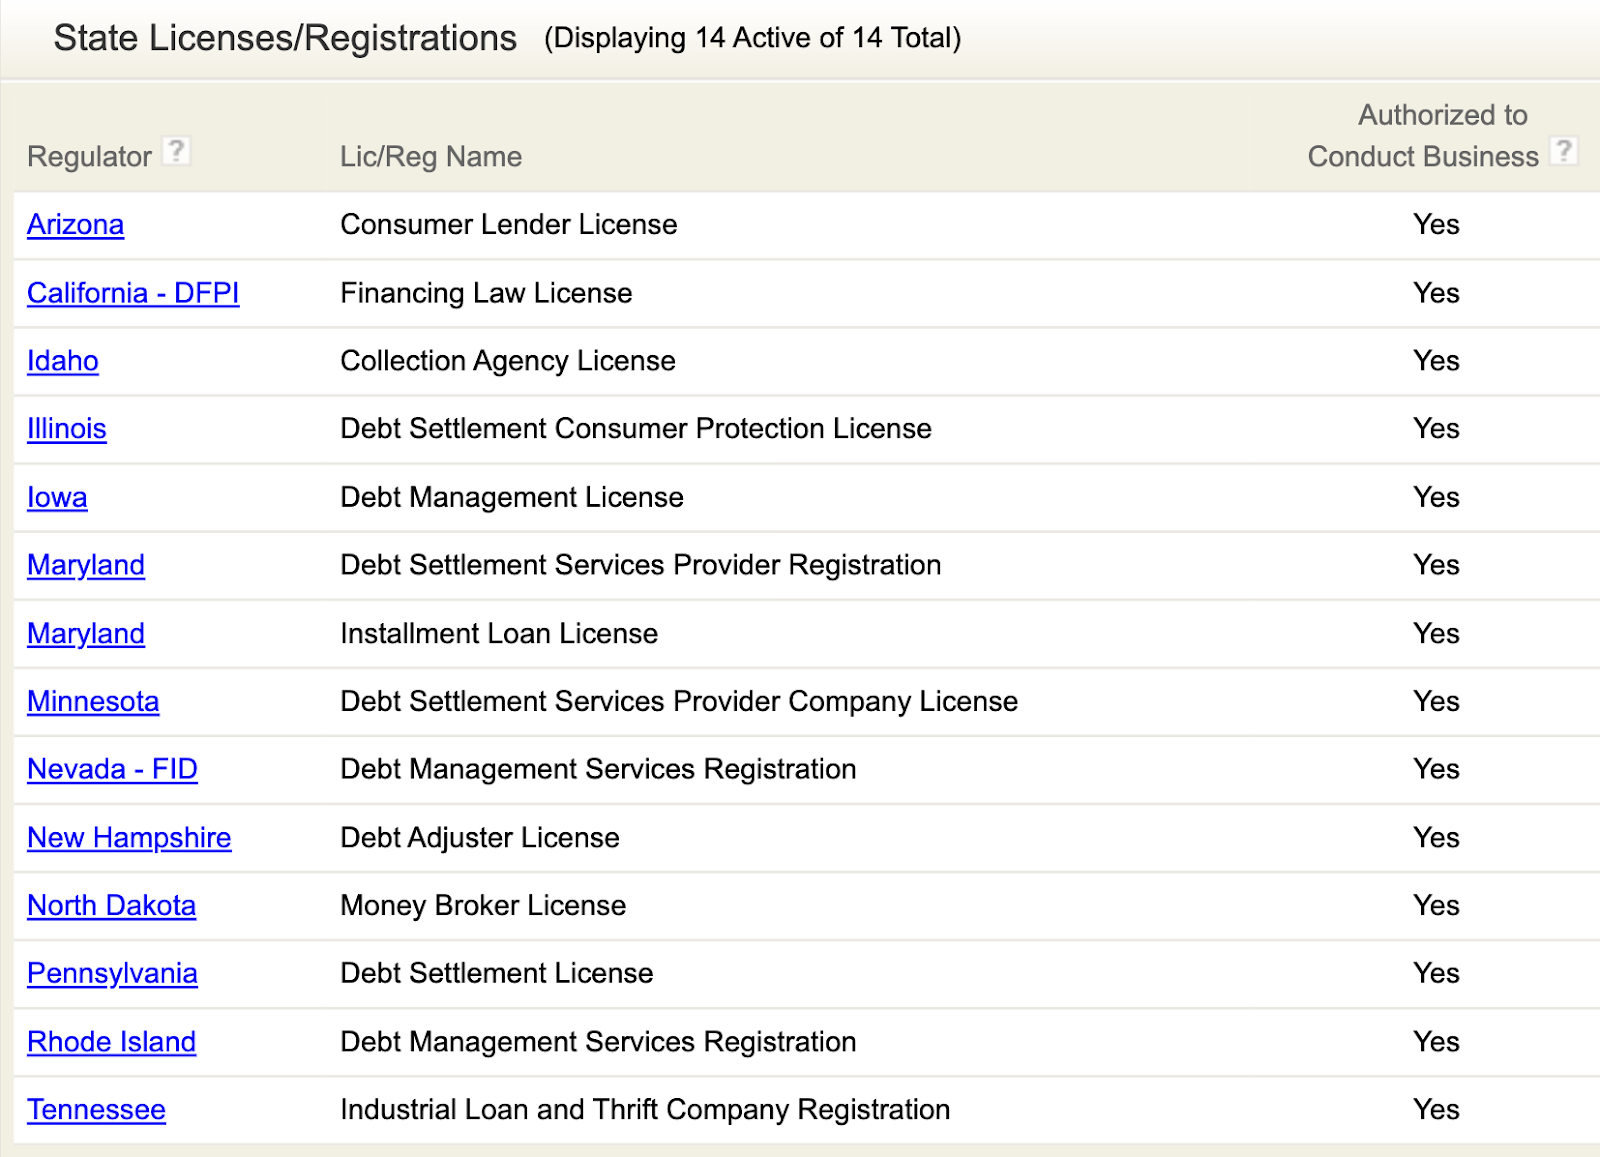
So, after the call, I put my research cap back on and checked with the Nationwide Multistate Licensing System. I found that National Debt Relief holds 14 state licenses in 13 states. 

I can verify that they do legally operate in: 

  1. Arizona
  2. California
  3. Idaho
  4. Illinois
  5. Iowa
  6. Maryland
  7. Minnesota
  8. Nevada
  9. New Hampshire
  10. North Dakota
  11. Pennsylvania
  12. Rhode Island
  13. Tennessee

And, in Illinois, Iowa, Maryland, Minnesota, New Hampshire, Pennsylvania, and Rhode Island, the company actively holds debt-specific licensing. 

While you can apply for a consultation regardless of your location, you may be limited in the scope of services offered if you live outside of the states where they maintain licensure.

How Does National Debt Relief Work? 

National debt relief actor

At first glance, it may seem like you’ll sign up to have your debt reduced without any work. But, that is not how these programs work. 

So, here’s how national debt relief really works…

…First of all, their approach starts with a personalized debt relief plan tailored to your unique circumstances. 

This might include negotiating with creditors to reduce the amount you owe and setting up a dedicated savings account where you make monthly deposits. These funds are then used to pay off your creditors at the negotiated reduced amounts.

Some participants might be offered a debt consolidation loan. The idea is that you would consolidate your high-interest debts into a new loan with a lower interest rate and pay less over time. 

While the company boasts that you can be back to financial freedom and living your life within 24-48 months, that doesn’t mean you will be out of debt within 4 years. For example, a consolidation loan might take 7 years to pay off, but your payments or interest would hopefully be lowered. 

There’s even a chance you’ll be referred to a bankruptcy attorney. In this case, some or all of your debt may be wiped out, but this could have a negative impact on your credit score for several years. 

Keep in mind, debt relief is not the same as credit repair, and may have a negative impact on your credit score (many so-called credit repair programs can have a negative impact on your credit as well). And, you will need at least $7.5K in debt to qualify for their services. 

You might also like: Superior Tradelines Review: Is it a Scam or Legit Way to Build Credit? 

How Much Does National Debt Relief Get Paid? 

National Debt Relief Illinois

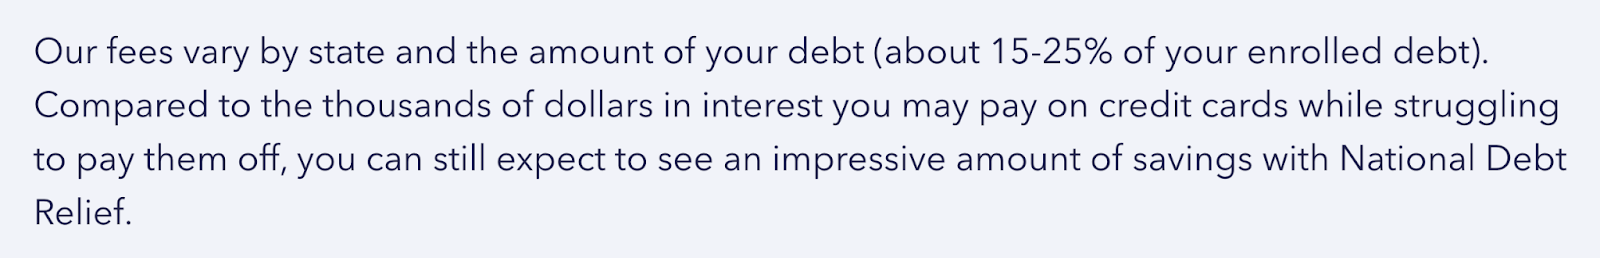
National Debt Relief charges a fee for their services, which is typically based on a percentage of the enrolled debt. This fee can vary depending on factors such as the state you reside in and the total amount of debt you owe.

On average, the fee usually falls within the range of 15% to 25% of the total enrolled debt. For example, if you enroll $10,000 in debt and the fee is 20%, then the fee would amount to $2,000.

Now, when I called in and asked specifics about the costs, the rep that I spoke with only disclosed that the fee is “built-in” to the plan and no services are rendered until all fees are agreed to.

So, if you make it to the proposal stage, do your own math before you sign up — Make sure that the amount you pay will in-fact be less than the interest and principal you would otherwise pay on your debts. And, keep in mind that debt settlement often has a negative impact on your credit report, and negative marks can remain for up to seven years.

It’s important to note that National Debt Relief operates on a performance-based fee structure – This means they are only supposed to collect their fee after they successfully negotiate a settlement with your creditors. Again, you will have the chance to approve the cost and the savings. 

You might also like: A Credit Stacking Breakdown: What it is & How it Works 

Company Overview

National debt relief, 180 maiden ln 30th floor, new york, ny 10038

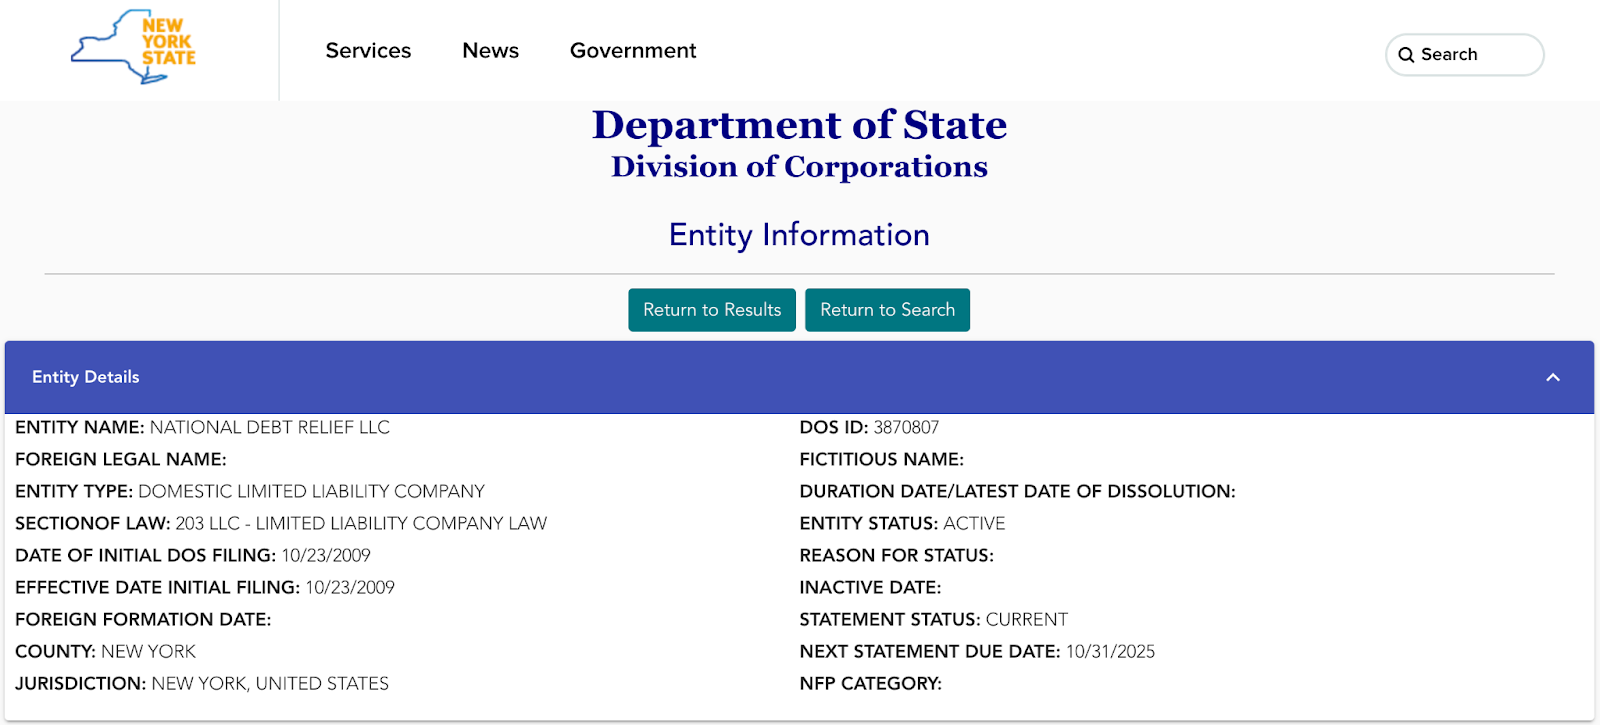
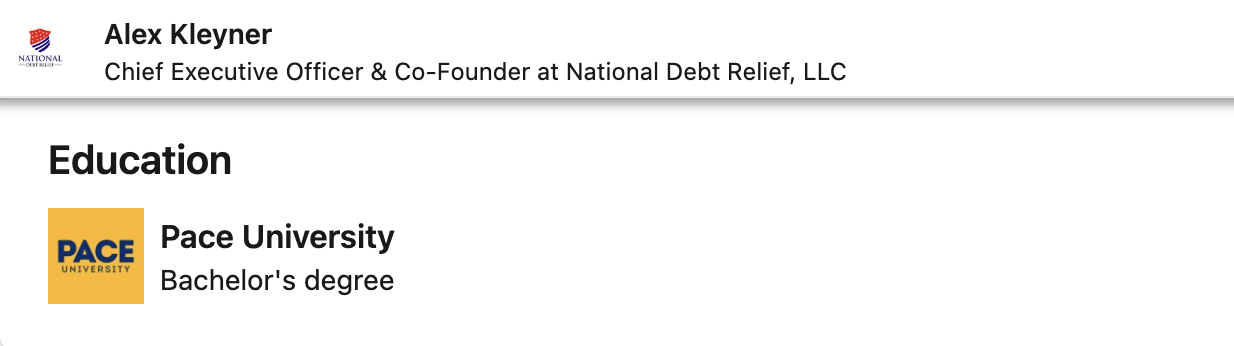
National Debt Relief LLC is a New York-based company that was founded in 2009 by Alex Kleyner, Daniel Tilipman, Tom Leydiker. Kleyner is the current CEO, where he’s been full-time for the past 15+ years. 

Prior to launching the company, Kleyner received a Bachelor’s degree from Pace University

Alex Kleyner national debt relief

Tilipman remains on National Debt Relief’s executive board, and went on to found Reach Financial — a debt consolidation loan provider  — in 2022. This makes me wonder if National Debt Relief offers consolidation loans in partnership with Reach. 

Leydiker is also still with the company. Before co-founding the company, he was a branch manager at Citibank and President and CEO of Continental Funding, LLC. 

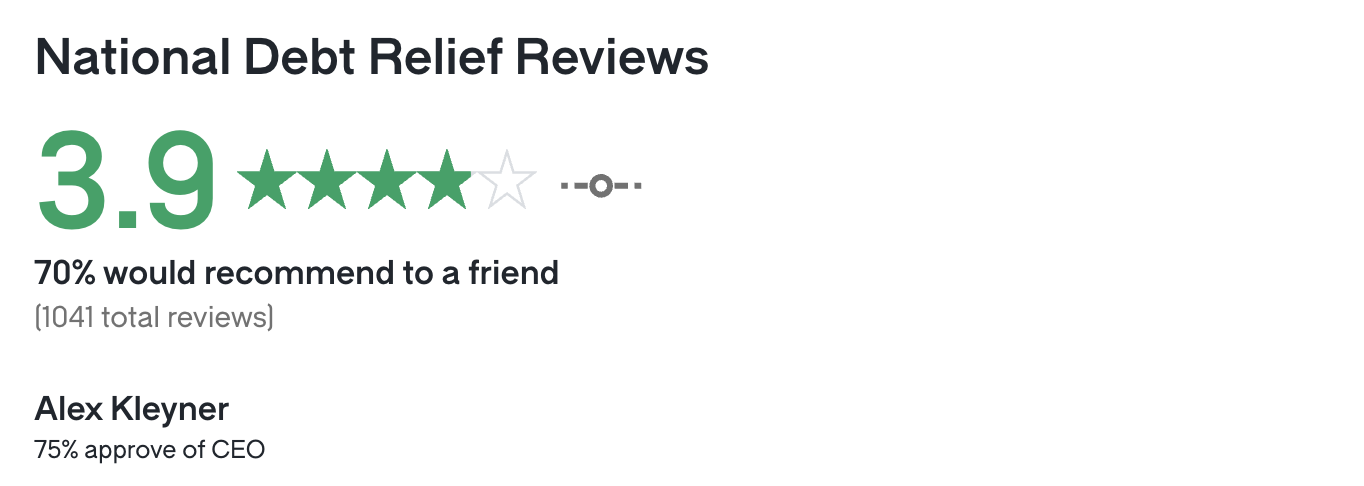
The leadership seems strong, especially considering that most employees (according to Glassdoor) would recommend the company to a friend in need of a job. What staff thinks of a company speaks volumes, and 75% of National Debt Relief’s Workers approve of the CEO. 

National debt relief Glassdoor

With that said, you also have to look at what clients think of a company before you can really judge. Like all financial offers, National Debt Relief gets mixed reviews. 

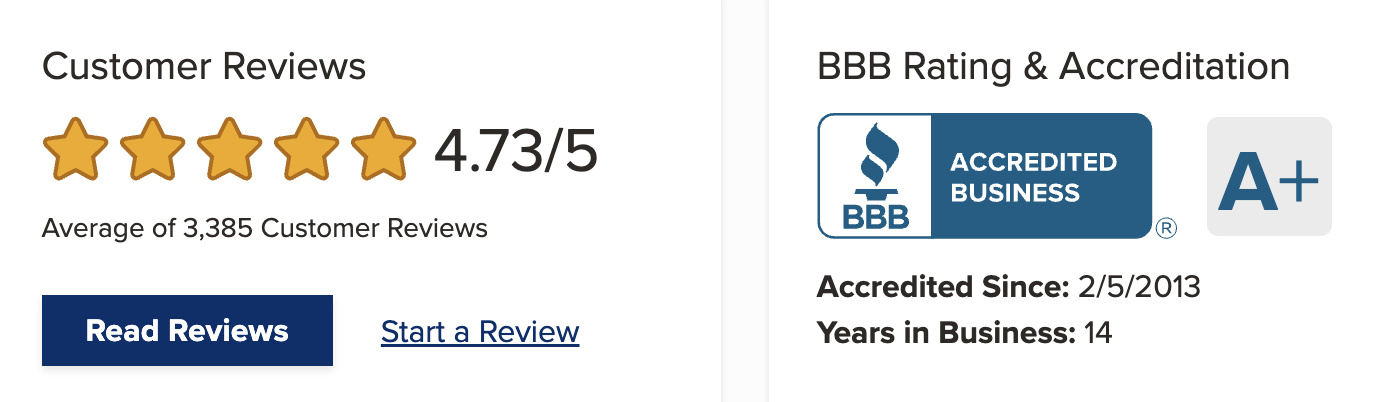
They are A+ rated and accredited with the Better Business Bureau (BBB), but this is despite 124 complaints in the past year. Still, 3,385 customers give them a 4.73-star rating. I do like these numbers. 

National debt relief reviews bbb

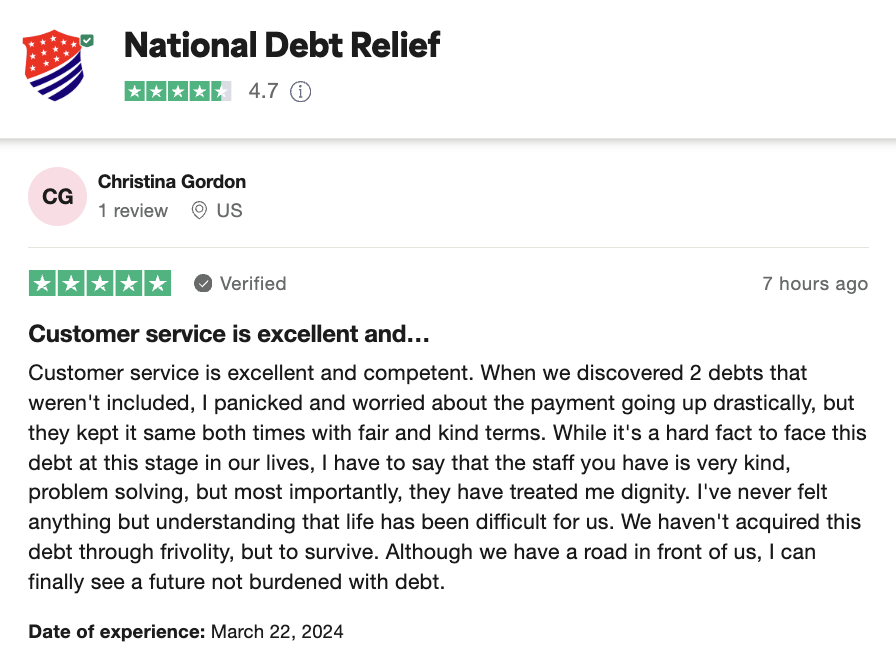
National Debt Relief is rated nearly as high on Trustpilot (4.7 stars) and platform reviewers are mostly very satisfied with the services they receive. 

National debt relief screwed me

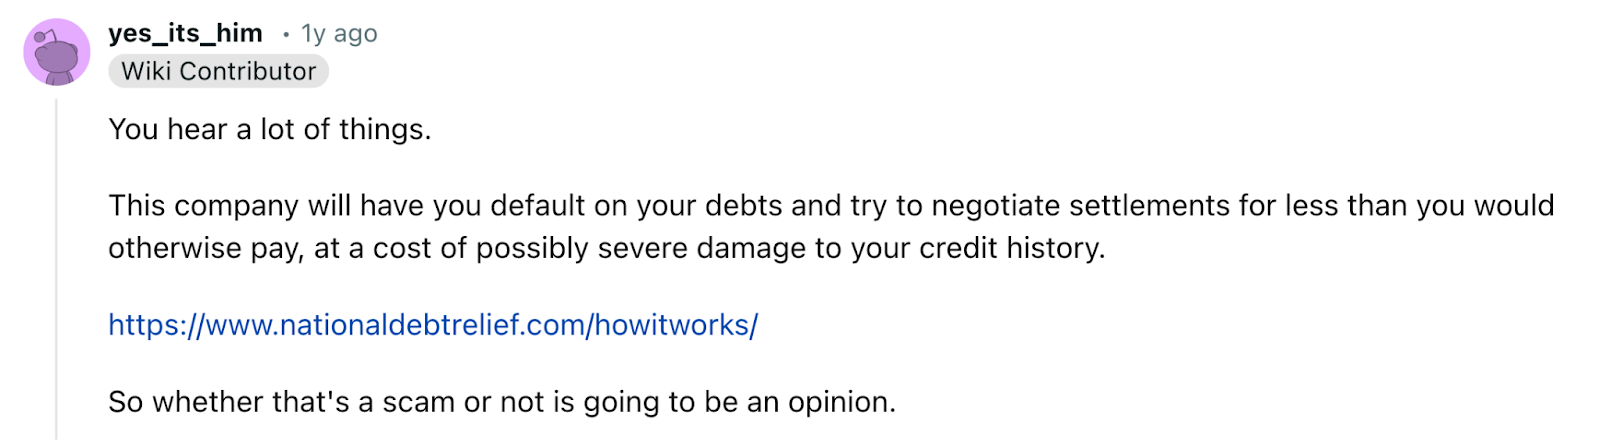
Plus, even Redditors have generally objective opinions about the company – they are typically the toughest crowd on the internet to impress. 

National Debt Relief Reddit

Note that some anonymous commenters do recommend you side-step these guys and go straight to a government agency or attorney for your own protection (which are definitely avenues worth exploring). 

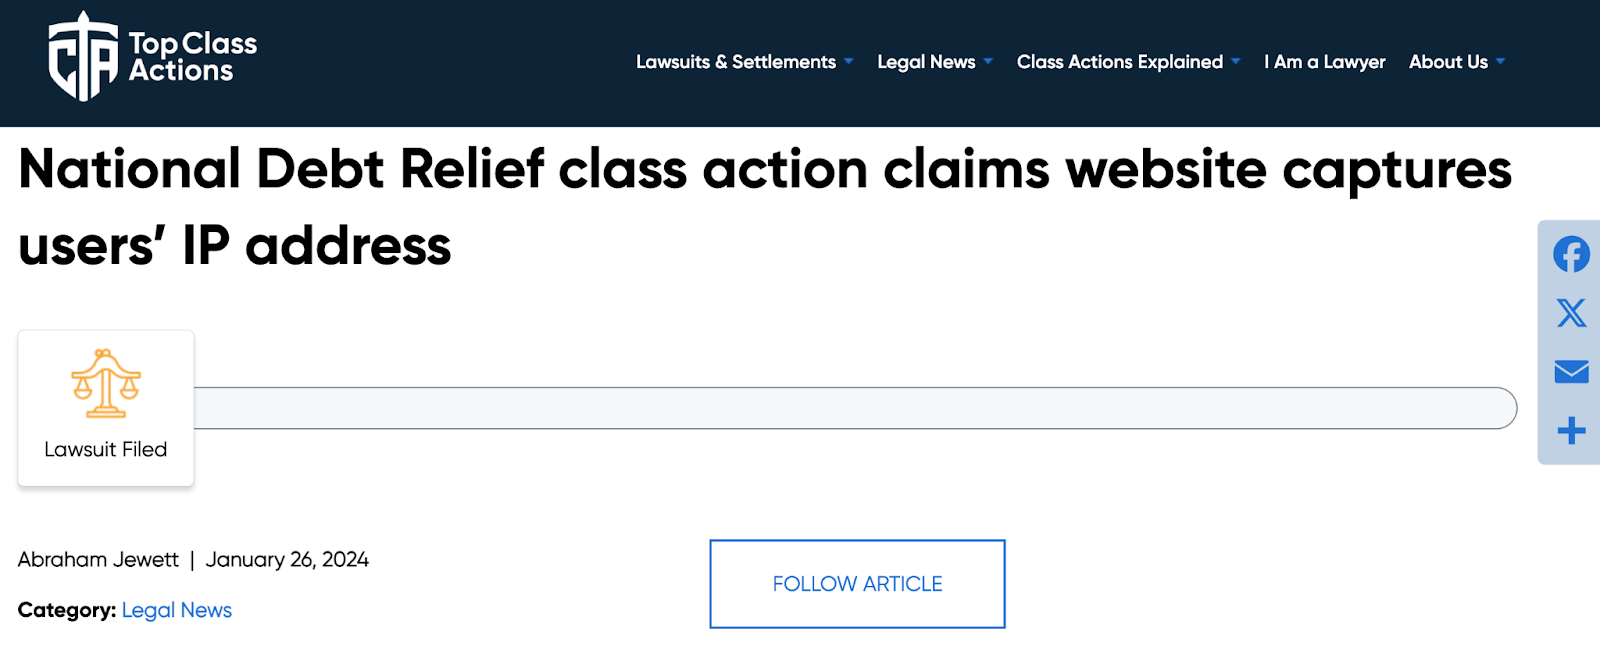
Now, there is a new class action lawsuit against National Debt Relief that claims they collect users’ IP addresses without consent – note, this has nothing to do with the way they handle clients’ finances. And, keep in mind, the jury is still out…literally. 

National debt relief class action lawsuit

Before you decide if this is the offer for you, find out exactly what National Debt Relief can do to help provide relief from debt. 

You might also like: 41 Companies That Help Build Business Credit [Beyond Net 30 Vendors] 

What Does National Debt Relief Do? 

Some of National Debt Relief’s services are offered in-house and other advertised relief solutions are made by referral. Now, I didn’t see any affiliate links or affiliate disclosures on their site – this could mean that they will refer you out to someone without earning any commission, but I can’t be sure. 

Here’s what you might expect if you sign up. 

You might also like: No-Doc Business Loans: Get Funds Without Proof of Income 

1. Free Consultation 

National debt relief login portal

If you reach out and apply for services from National Debt Relief, the first thing you can expect is a call from a rep who will listen to your situation, ask questions and start to formulate a plan. 

At this stage, I only recommend you watch out for high-pressure sales tactics. This is always a bad sign. But, a phone call is a low-risk way to explore whether an offer is going to be a good fit for you. Your mantra for any sales call should be, “I’m in the driver’s seat.” 

2. Personalized Debt Relief Plan 

How to cancel national debt relief

National Debt Relief will need to know about all of your debts before they can make a recommendation on how to tackle them.  

So, list out all of your debts: 

  • Credit cards
  • Lines of credit
  • Personal loans
  • Medical bills
  • Collections
  • Repossessions
  • Student loans
  • Business debts

And, be prepared to let the rep take some time to come up with a tailored plan. 

3. Credit Counseling & Education 

National debt relief email

Credit counseling might be beneficial if you are able to make monthly payments, but struggle with debt management. It’s ideal if you’re seeking a structured plan to handle debt effectively, negotiate lower interest rates, and consolidate payments. 

Additionally, counseling offers valuable financial education on budgeting and responsible credit use. Credit counseling might be suitable if you want to avoid bankruptcy and are willing to actively participate in the counseling process to achieve financial stability.

In addition to the counseling services they offer, National Debt Relief offers quite a few educational resources – primarily a comprehensive blog that discusses all matters debt, lifestyle, and financial wellness-related. If you want to learn about debt consolidation, or bankruptcy, their blog is full of useful information. 

Plus, their articles are laid out in a way that’s simple to navigate and written in an easy-to-understand tone.  

Moreover, they have quite a few calculators to help you figure out your situation. 

National debt relief cancellation form

Calculators include accelerated debt payoff, consolidation loan investment, cost of debt, credit card minimum payment, and more. 

If you decide to take a DIY approach, or even if you choose another service, I do recommend you peek in at National Debt Relief’s resources. They share most of the basics of debt and finances – And, I think this is a great knowledge base for anyone looking to sharpen their debt and financial wellness chops. 

4. Debt Negotiation With Creditors 

National debt relief scholarship

Debt negotiation, or debt settlement, might be a good fit if you have significant unsecured debt you can’t fully repay – this could be due to financial hardship like job loss or medical emergencies. It’s suitable for those unable to qualify for consolidation loans or facing collections or legal action. 

Debt negotiation provides an alternative to bankruptcy, helping stop collection calls and lawsuits by reaching settlements with creditors. However, it’s not ideal for everyone, and careful evaluation of your financial situation is essential before pursuing this option. 

5. Debt Consolidation Loans

National debt relief bbb consolidation loans

Debt consolidation can be a suitable option if you have multiple debts, such as credit card balances, personal loans, or medical bills…and are looking for a more manageable way to repay them. It might be beneficial if you want to streamline your debt by combining multiple payments into a single monthly payment (usually at a lower interest rate). 

This type of debt relief can help you simplify your finances and potentially save money on interest payments over time. And, it’s a good fit if you have a steady income and can afford to make consistent monthly payments towards your consolidated debt. 

6. Bankruptcy Referrals 

National debt relief vs bankruptcy

Bankruptcy might be a viable option if you’re facing overwhelming debt that you cannot repay, even with debt management strategies like credit counseling or debt negotiation. It might also be good if you’re experiencing severe financial hardship, such as job loss, medical expenses, or divorce. Sometimes, these situations can make it impossible to meet debt obligations. 

Bankruptcy provides a legal process for individuals to eliminate or restructure debts and obtain a fresh financial start. It may also be appropriate if you’re at risk of foreclosure or wage garnishment. However, bankruptcy has long-term consequences, including a negative impact on your credit score and potential loss of assets. So, it’s essential to carefully consider the decision and seek legal advice before filing.

You might also like: Cred AI Review: Are You Really Better Than Your Bank? 

Frequently Asked Questions

Can you cancel National Debt Relief? 

Yes, you can cancel your enrollment with National Debt Relief at any time. They understand that circumstances may change, and you have the right to discontinue their services if you wish.

How can you cancel National Debt Relief? 

To cancel National Debt Relief, you can contact their customer service team either by phone or email. They will guide you through the cancellation process and provide any necessary documentation or instructions.

Do I get my money back if I cancel National Debt Relief? 

If you cancel National Debt Relief, you may be entitled to a refund of funds you’ve deposited into your dedicated savings/escrow account, minus any fees earned for services rendered up to that point. The specific refund policy may vary depending on the terms outlined in your agreement.

Does National Debt Relief hurt your credit? 

When you stop making payments to creditors and enter into negotiations for debt settlement, it can be reflected on your credit report. The long-term effects of debt settlement on your credit score can vary depending on your circumstances. Discuss the potential impact with a legal and financial professional and consider all your options before enrolling.

Conclusion: Is National Debt Relief Legit? 

The percentage-based pricing model seems higher than what you might expect from a debt relief program. If you paid a separate credit repair company to clean up your report for, say, $170 per month, the cost could add up fast. But, if you save 25% off your debt, and National Debt Relief charges you 20% of your enrolled debt to do it, is it really worth it? 

In the case that you’ll save 50%, a 25% fee might make sense. Be sure to read the fine print before you make any commitments.  I don’t know whether National Debt Relief charges before or after debt is negotiated, which could vary on a case-by-case basis.

If you’ve got a lot of collections that you want to clear up or negative items you need removed from your report, a credit repair company, an attorney, or a DIY approach might be cheaper alternatives. 

In all, though, I like this offer. The company seems to be legit, they’ve been in business long enough to be reputable, and the BBB likes them. Other than the potential expense, I don’t see any glaring red flags that would make me tell you to run for the hills. 

My only advice is to do your research. Learn about all of your options before you apply for relief from debt. And, if you don’t have at least $7.5K in debt, you will need to look elsewhere. Good luck on your journey to financial freedom.  

Do you want to learn how to obtain up to $100K in business credit that won’t impact your personal credit, in as few as 30 days? If so, join Business Credit Workshop today!

Is it Illegal to Use a Business Credit Card for Personal Use? +More Answers

By Joe

Have you ever wondered whether you can use your business credit card for personal expenses? 

It’s a common question among business owners, but the answer can be a bit tricky. 

While we can’t give legal advice (if you need that, please talk to your attorney and your CPA), we’re here to provide you with helpful information that can guide you in making informed decisions for your business — One interesting thing we found out is that using your business credit card to pay yourself a salary as an employee of your own business can be considered a legitimate expense. 

Pretty cool, huh? 

We’ll delve into this and other commonly asked questions about business credit card use in this article, so keep reading to find out more!

Here’s what’s in store: 

  • Scenario: Employee Uses Company Credit Card for Personal Use
    • How to Prevent Personal Spending on Company Credit Cards
  • General Rules for Business Credit Cards
    • What Can You Use Business Credit For?
      • Paying Yourself With Business Credit When
    • Is It Illegal to Use Business Funds for Personal Use?
  • How Business Credit Affects Personal Credit
    • Is it Better to Use Business Credit Card Points for Personal Things?
  • Conclusion: Is it Illegal?

Let’s rock and roll!

Scenario: Employee Uses Company Credit Card for Personal Use

While most of our content is targeted at business owners, you might be reading this because you’re wondering if you can add a pair of shoes to your business order, and still pay with your company’s corporate card. Here’s what I can tell you. 

When an employee uses a company credit card for personal expenses, it can cause a lot of problems. 

First off, it’s usually against company policy, which means the employee could face some serious consequences like getting in trouble with the boss or even losing their job. From a legal standpoint, this is risky for all parties because if the expenses are shady or illegal, both the employee and the company could face a run-in with the law. 

Next, staff members that use a company’s card for non-business expenditures can complicate finances because it’s hard to keep track of personal expenses and separate them from business expenses — it could cause some major issues with taxes and budgets down the road. 

Lastly, if personal spending exceeds the credit limit on the card, it can result in fees or penalties, which will hurt the company’s bottom line.

Can you use business credit card for personal use Reddit

Image source: Reddit

So, if you accidentally used a company credit card when you didn’t intend to, or if you notice that an employee used your business credit card for something questionable, it’s best to act fast. 

How to Prevent Personal Spending on Company Credit Cards

Q: Why does our Amazon business report show an order for a gold-plated toilet seat? 

A: Someone wanted to feel like a VIP on the company’s dime. 

In all seriousness, it’s crucial to make sure that employees use company credit cards responsibly and only for legitimate business expenses. Otherwise, the company could end up footing the bill for some pretty outrageous purchases!

Here are some actions you can take to avoid personal employee spending on your business credit cards:

  • Create clear policies — Make sure everyone knows the rules when it comes to using company credit cards. This means setting out clear policies on what expenses are allowed and what expenses are not allowed.
  • Set spending limits — Give your employees some guardrails by setting limits on how much they can spend with the company credit card. You can also set daily or weekly limits to help control spending.
  • Monitor transactions — Keep a close eye on credit card transactions to make sure there are no unauthorized or personal expenses. This means setting up alerts to notify you of any unusual transactions or spending patterns.
  • Require receipts — Make sure your employees know that they need to submit receipts for all credit card expenses. This helps ensure that all expenses are legitimate and for business purposes.
  • Provide training — Never assume that everyone just knows how to use a company credit card. Provide training that covers your company’s spending policies, guidelines, and best practices for managing credit card expenses.

By doing these things, you can help prevent personal employee spending on company credit cards…. and ensure that all credit card expenses are legitimate and for business purposes only.

General Rules for Business Credit Cards

First and foremost, you need to understand that business credit cards are intended for business expenses…legit ones! This means that you should only use the card to pay for things that are related to your business, like office supplies, travel expenses, and other business-related costs.

Next, it’s vital to keep your personal and business expenses separate (i.e. you should never use your business credit card to pay for personal expenses, like groceries, clothing, or personal entertainment). 

On a similar note, you need to keep track of your spending. You should monitor your credit card statement regularly to ensure that all charges are legitimate and for business purposes. When issuing business credit cards or corporate cards, it’s also a good idea to set spending limits for yourself and your employees to prevent overspending.

Lastly, be sure to pay your credit card bill on time and in full every month — Late payments can devastate your business credit score and result in hefty late fees and interest charges (remember, you should credit card funds to invest in assets, not squander on liabilities).

Note, that business credit card policies vary between credit card companies and businesses have a right to set unique spending policies within legal guidelines in their jurisdiction. 

Amex business card for personal use

By following these general rules, you can use your business credit card responsibly and avoid any potential issues down the road.

What Can You Use Business Credit For?

In a word, you need to use your business credit for business expenses. 

However, in some industries, expenses that seem frivolous can be completely above board — for example, stylists in the beauty business need to look nice, so they can buy makeup, clothing, and haircare products. And, for businesses with dress codes, you might have a green light on that Armani suit you’ve been eyeballing. 

So, what constitutes a business expense? 

A business expense is any cost incurred as part of running your business, most commonly: 

  • Rent for your office space
  • Equipment purchases
  • Employee salaries
  • Marketing expenses
  • Travel costs.

In addition to these more obvious expenses, there are also many other items that can be considered legitimate business expenses, depending on your industry and specific needs. For example, as previously mentioned, in certain industries, expenses like clothing, makeup, and hair care products can be considered legitimate business expenses.

Other examples might include: 

  • Home office expenses
  • Professional development courses or certifications
  • Certain meals and entertainment expenses (if they are related to business activities)

It’s important to note, however, that not all expenses will be considered legitimate business expenses. Any personal expenses, such as vacations or personal entertainment, should never be charged to your business credit card.

In general, it’s always a good idea to consult with a financial professional, like an accountant or tax advisor, to ensure that you are using your business credit card appropriately (and taking advantage of all eligible tax deductions).

Paying Yourself With Credit When You Own a Business

As a business owner, there are a few different ways you can pay yourself. One common method is to pay yourself a salary, which you can do using a number of different payment methods including checks, direct deposit, or even a credit card. 

Yes, you read that right – you can pay yourself a salary with a credit card!

Now, before you go swiping that plastic, it’s important to understand the pros and cons of each payment method. 

For example, paying yourself with a credit card may be convenient, but it can also come with high interest rates and fees if you don’t pay off the balance each month…while other payment methods like checks and direct deposit may be more traditional, they might also require more effort and may not be as flexible. 

Regardless of which payment method you choose, it’s important to manage your business finances wisely: 

  • Create a budget
  • Keep track of expenses
  • Set aside money for taxes and emergencies.

By taking these steps, you can ensure that you are paying yourself in a sustainable way that supports both your personal and business financial goals.

So, is It Illegal to Use Business Funds for Personal Use?

In general, it can be illegal to use business funds for personal use, especially for employees whose companies prohibit it; this includes paying personal expenses and withdrawing cash from a business account to spend on personal items. 

Is using a company credit card for personal use embezzlement?

How often people get caught doing this, I can’t begin to guess. And, the penalties would surely vary depending on the severity of the crime — which is why you should consult with an attorney or CPA to ensure legal compliance. 

Using business funds for personal expenses can sometimes be considered embezzlement or fraud, and can result in serious legal consequences…It can also damage your business’s financial stability and reputation.

That being said, in my experience, there are some exceptions to this (like a business owner paying their own salary). 

How Business Credit Affects Personal Credit

As a business owner, you need to understand the relationship between your personal and business credit. While they are technically separate, your personal credit can still impact your LLC in a few different ways. 

If you have a poor personal credit score, it may be harder to get approved for business loans or credit cards…On the other hand, a strong personal credit score can make it easier to access funding and other resources for your business.

To manage both your personal and business credit effectively, there are a few key tips to keep in mind: 

First, make sure to keep your personal and business finances separate as much as possible: open separate bank accounts and credit cards for your business and avoid using your personal credit to cover business expenses.

Next, be sure to monitor your credit scores regularly and address any errors or issues that arise promptly.

And, you need to maintain a good credit utilization ratio – that is, the amount of credit you are using compared to the amount you have available…Both personal and business credit scores are impacted by this ratio, so it’s important to keep your balances low and avoid maxing out your credit cards.

Recommended: Credit Secrets: Can You Erase Bad Credit History? 

Is it Better to Use Business Credit Card Points for Personal Things? 

While I wouldn’t encourage you to spend business credit on personal items, rewards redemption is another story. 

Using your business credit card points for personal things can be a tempting proposition, especially if you’ve been racking up rewards points with your business purchases. 

I’ve redeemed my Marriott Bonvoy rewards on more than one family vacation. 

However, whether it’s better to use those points for personal use ultimately depends on your business’s financial situation and your personal financial goals.

Here are some things to consider:

  • If your business has a cash flow problem and you’re relying on credit card rewards to make ends meet, it’s probably not a good idea to use those points for personal purchases. Instead, you should focus on using your rewards to offset your business expenses.
  • On the other hand, if your business is doing well and you have plenty of cash on hand, using your rewards for personal purchases can be a great way to enjoy some extra perks. Just be sure to keep careful track of your expenses and make sure you’re not putting your business at risk by overspending.
  • If you have a specific personal financial goal, such as saving up for a down payment on a home or a car, using your business credit card rewards to help achieve that goal can be a smart move. Just be sure to weigh the potential benefits of using your rewards against any fees or interest charges associated with cashing them in.

The bottom line is that you should consider the financial health of your business and your personal financial goals before making a decision.

Conclusion: Is it Illegal?

I’ve already said this a few times, but I would rather sound like a broken record than steer you down the wrong path: when in doubt about business credit spending, consult an attorney or CPA. 

The short answer is that business credit spending for personal use can be risky and it’s likely to complicate your business budget. Yet, there are plenty of totally above-water business credit spending categories you might not have considered (paying yourself a salary) — I tried to cover them here. 

If you want to learn how to obtain up to $100K in business credit in as few as 30 days, join Business Credit Workshop today.

Superior Tradelines Review: Is it a Scam or Legit Way to Build Credit?  

By Ashton Kim


Disclaimer: Business Credit Workshop does not recommend or endorse tradeline brokering. However, there are several people in the business credit community who have leveraged Superior Tradelines’ services and reported good results. So, we wanted to learn everything we can about the offer and, of course, share our findings here.

Please, do your own due diligence, as this post is only meant to provide more information. 

Now, in a nutshell, Superior Tradelines rents out tradelines (credit accounts) to boost credit scores by increasing the age and credit limit on users’ credit profiles. 

So, is it a scam? Or, is it a good way to boost your credit score? 

Here’s what you’ll learn: 

  • What is a Tradeline Broker?
    • Why Would You Want to Buy/Rent a Tradeline?
    • How Long Do Tradelines Last?
    • How Much Do Tradelines Increase Credit?
    • Can Tradelines Hurt Your Credit?
  • Superior Tradelines Company Overview
    • Superior Tradelines Features & Benefits
      • 1. Credit report analysis
      • 2. Buy and sell tradelines
      • 3. Join the referral program
      • 4. Get financial education
  • What to Expect When You Become a Superior Tradelines Member
  • Conclusion

Now, let’s explore the offer in full. 

What is a Tradeline Broker? 

A tradeline broker like Superior Tradelines is a company that brokers tradelines between the original account holders and those looking to piggyback off the accounts to boost their credit. 

The idea is that the end user pays a fee to have their name and social security number added to an existing credit account in good standing. 

Companies like Superior tradelines offer a credit-boosting service that connects those without high-limit, mature accounts instant access to them for a fee. 

Why Would You Want to Buy/Rent a Tradeline? 

Imagine that someone wants to get a business line of credit, but they don’t have a very strong personal credit profile. On the other hand, their spouse happens to have a ten-year-old Amex account with a $0 balance and a $20K credit limit. By adding themself as an authorized user on the account, it will lower their credit utilization and increase their average account age to increase their credit score and approval odds for a business line of credit. 

So, as you can see, someone might want to add a tradeline to their credit profile w