• Home
  • Free Funding Guide
  • What We Offer
    • Products
    • Services
    • Free Guide
  • About Us
  • Contact
  • Sign Up

  • Ask Joe Any Question!
  • Business Credit Cards
  • Business Line of Credit
  • Topics

How Helpful is CreditSafe for Building Business Credit? 

By Joe

CreditSafe Review

Key Takeaways

  • CreditSafe is a business credit bureau but not widely used in the U.S.
  • Major U.S. lenders rely on D&B, Experian, and Equifax instead.
  • CreditSafe specializes in international credit risk assessment.
  • Companies like Neiman Marcus and Accenture use CreditSafe.
  • It does not report to major U.S. business credit bureaus.
  • Pricing is unclear and varies from $15 to $100+ per month.
  • You can request a free report by speaking with a rep.
  • It’s useful for global business but not essential in the U.S.

CreditSafe, like Dun & Bradstreet, is a business credit bureau. If you’re on a business credit building journey, you’ve likely seen the brand pop up in your research. But, how does CreditSafe impact your ability to obtain business credit? Where do they get their data? And, how applicable is the platform for small business owners? 

Here, I’ll give you a rundown of what I’ve dug up about CreditSafe, share some of their features, and compare their small business relevance to other business credit bureaus. 

This is what’s in store: 

  • What is a Business Credit Bureau?
  • What is CreditSafe?
    • How Much Does CreditSafe Cost?
    • What Does CreditSafe Do?
    • What Companies Use CreditSafe?
  • CreditSafe Competitor Overview
  • Frequently Asked Questions
  • Conclusion: Is CreditSafe Helpful to Build Business Credit?

Now, let’s jump in! 

What is a Business Credit Bureau? 

A business credit bureau is an agency that collects and maintains information about the creditworthiness of businesses. Similar to personal credit bureaus that track individuals’ credit histories, business credit bureaus collect and share data about businesses’ credit behavior and financial performance.

The key functions of a business credit bureau include:

  1. Credit reporting
  2. Credit scoring
  3. Risk management
  4. Business verification
  5. Business credit monitoring

Overall, a business credit bureau is a valuable resource for businesses, lenders, and suppliers because it provides standardized data to support educated decisions and risk management practices.

Recommended: Here’s How to Check Your Business Credit Score, Step-by-Step 

What is CreditSafe? 

CreditSafe reviews

CreditSafe is a global business intelligence company specialized in credit and business information services. They promote their offer to businesses of all sizes. The platform offers comprehensive credit reports and data on millions of businesses and business owners worldwide. 

CreditSafe offers to help mitigate credit risk, improve cash flow, and identify new business opportunities with data-driven insights.

They provide business credit reports, with insights into:

  • Creditworthiness
  • Financial stability
  • Payment behaviors
  • Other relevant factors that can impact credit risk assessment

The CreditSafe algorithm calculates business credit scores based on the information in their credit reports – These scores help lenders and suppliers inform decisions about extending credit or forming partnerships. They also offer tools and resources to manage credit risk effectively—monitor credit profiles, assess risk exposure, and set fitting credit limits.

With access to information from various countries, CreditSafe can enable institutions to assess the credit risk of international partners and customers.

Some lenders and suppliers choose to rely on D&B for North American borrower risk assessment while using CreditSafe for international applicants.

What is CreditSafe used for?

Moreover, CreditSafe offers application programming interface (API) solutions that let institutions integrate credit data directly into their existing systems. Many companies rely on CreditSafe’s services to streamline credit management processes and make confident business decisions.

Let’s continue this exploration from the perspective of small business and corporate borrowers. 

You might also like: eCredable: A Deep Dive Into the Business Credit Reporting Platform 

How Much Does CreditSafe Cost? 

As of today, CreditSafe does not advertise pricing on their website. In fact, you need to speak with a sales rep to even take advantage of a free trial of the back end. 

However, I did some digging and found that Capterra claims a CreditSafe account starts at $100 per month. One BBB complaint from 2022 cites a $40 membership charge. I’ve seen other sources that say a membership starts at $15. None of CreditSafe’s 294 reviewers on Trustpilot have disclosed what they pay, but one user described the platform as “inexpensive”—At least one Redditor has said the same. 

Is Creditsafe accurate?

CrediSafe does offer a free trial. So, if you sign up, you can decide for yourself whether or not the information is worthwhile. 

You might also like: 41 Companies That Help Build Business Credit [Beyond Net 30 Vendors]  

What Does CreditSafe Do? 

CreditSafe login

Apparently geared primarily toward lenders and suppliers, CreditSafe offers a handful of products in their member dashboard: 

  1. Domestic credit reports and company monitoring
  2. International credit reports
  3. Automated credit decisioning 
  4. APIs/ERP integrations with CRMs 
  5. Due diligence and compliance

Of these, I only see the first being applicable to small business owners. They do offer a free business credit report. 

To get a CreditSafe business credit report and score, you need to submit a request through their website or contact their team directly. After that, a CreditSafe representative will call you to verify your request and ask what you’re looking for.

I went through this process myself, and submitted a few requests on behalf of a new business before I got a call back. This makes me wonder if they are quicker or more interested in potential lenders or companies with higher revenues. 

When CrediSafe called me, I was expecting a hard sales pitch, but that didn’t happen. The rep just asked what I needed, and when I told them I wanted to see a credit report, they pulled it up and sent it over immediately—no pressure, no hassle.

If you’re requesting a report for a newer business, keep in mind that CreditSafe might not have much data, depending on what they’ve collected from vendors, lenders, and public records. 

If you’re curious about what a CreditSafe report looks like for a nearly new business, here’s an example of the front page:

CreditSafe Example business credit report

If you wanted to monitor your business’ CreditSafe credit report, you could theoretically sign up for a membership and do so. I’ll wager this would cost somewhere in the realm of $15 to $40 per month, but you would have to speak to a sales rep to know for sure—it seems like their pricing varies. 

You might also like: Business Credit Report – Run a Free Company Search | Experian 

What Companies Use CreditSafe? 

Credit Score Companies

As far as lenders and suppliers go, there are 100,000+ businesses globally that use CreditSafe for lending decisions. They claim that the top 10 credit card issuers rely on their data.

CreditSafe’s platform is widely used by multinational corporations and financial institutions to assess business credit risk, particularly for international transactions. Companies like Neiman Marcus, Accenture, Hermès International, Cognizant, and Wipro leverage CreditSafe’s reports to evaluate global partners. 

The database allegedly covers over 430 million businesses across 200+ countries, making it a strong resource for international credit evaluations. However, CreditSafe is not a primary player in U.S. domestic business credit decisions. 

Major U.S. lenders and suppliers typically rely on: 

  • Dun & Bradstreet
  • Experian
  • Equifax 

This makes CreditSafe more useful for companies involved in global trade rather than small businesses looking to establish U.S. business credit.

If your business operates internationally or works with global suppliers, CreditSafe may provide valuable insights. But for domestic business credit building, focusing on bureaus that lenders actually check—like D&B, Experian, and Equifax—will be more effective.

You might also like: What is the SBFE & How Do They Impact Small Businesses? 

CreditSafe Competitor Overview

Again, the three main business credit bureaus that small businesses rely on to build credit in the U.S. are Dun & Bradstreet (D&B), Equifax, and Experian. Another key player, though not a credit bureau itself, is the Small Business Financial Exchange (SBFE), which collects data and shares it with these bureaus.

CreditSafe is not typically used for business credit building in the U.S. Major lenders and suppliers do not rely on its reports the same way they do with D&B, Experian, or Equifax. However, it does appear in various resources, and some small business owners come across it while researching business credit.

Let’s peek at how these platforms compare for small business offers:

Starting PriceFree Business Credit ReportFree Business Credit Score
CreditSafe logo$0✅✅
D&B logo$0✅⛔
Equifax logoNA⛔⛔
Experian Logo$99⛔⛔
SBFE LogoNA⛔⛔

CreditSafe offers free business credit reports and scores through limited-time trials or partnerships.

D&B provides a free basic profile and DUNS number, but full reports require payment.

Equifax does not typically offer free business credit reports or scores—Access to this info usually requires that you apply for financing.

Experian offers business credit reports starting at $99 and up, while free reports or scores are not typically available.

SBFE acts as a data aggregator and does not provide reports or scores directly to businesses.

Another item worth mentioning is that, while the other bureaus provide financial reports on 25 to 40+ million businesses, CreditSafe doesn’t disclose exactly how many U.S. businesses they carry data on. 

Recommended: Nav Review: A Tool that Helps Build Up Your Business Credit Score 

Frequently Asked Questions

Who does CreditSafe report to?

CreditSafe does not report business credit data to major U.S. credit bureaus like Dun & Bradstreet, Experian, or Equifax. Instead, it compiles business credit information from various sources and provides reports directly to its customers, which include lenders and suppliers.

What is CreditSafe used for?

CreditSafe is primarily used for business credit risk assessment. Lenders, suppliers, and companies use it to check the creditworthiness of businesses, monitor financial stability, and make informed credit decisions. It also offers international credit reports, automated credit decisioning, and compliance tools.

Is CreditSafe a real company?

Yes, CreditSafe is a legitimate business credit reporting agency. Founded in 1997, it operates in multiple countries and serves thousands of businesses globally. Its U.S. headquarters is in Allentown, Pennsylvania.

Can I run a credit check on an individual with CreditSafe?

No, CreditSafe does not provide consumer credit reports. It focuses on business credit data, so it cannot be used to check an individual’s personal credit score.

Conclusion: Is CreditSafe Helpful to Build Business Credit? 

CreditSafe provides free business credit reports and scores, but its impact on U.S. small business credit building is limited. Major lenders and suppliers rely more on Dun & Bradstreet, Experian, and Equifax for credit decisions.

For small business owners, the best approach is to pay vendors that report to major bureaus, monitor credit across platforms, and use tools like Nav for easy access. While CreditSafe offers global credit insights, it’s not a key player in U.S. business credit building.

If you work internationally, CreditSafe may be useful. Otherwise, focus on bureaus that lenders trust for financing decisions.

Do you want to learn how to obtain up to $100K in business credit in as few as 30 days? Join Business Credit Workshop today!

American Express Business Blueprint Review (Formerly Kabbage)

By Joe

American Express Business Blueprint Review

Key Takeaways

  • Kabbage became Amex Business Blueprint, from lending to a full financial platform.
  • Blueprint combines banking, lending, and cash flow insights in one dashboard.
  • Amex Lines of Credit have lower fees than Kabbage (0.95% to 27%, depending on the term).
  • Business Checking offers higher (1.3%) APY, no fees, and a rewards debit card.
  • The iOS app is highly rated, but Android users report issues and bugs.
  • Payment Accept replaced Kabbage Payments, but new customer availability is unclear.
  • The Resource Center provides business insights and financial tools.

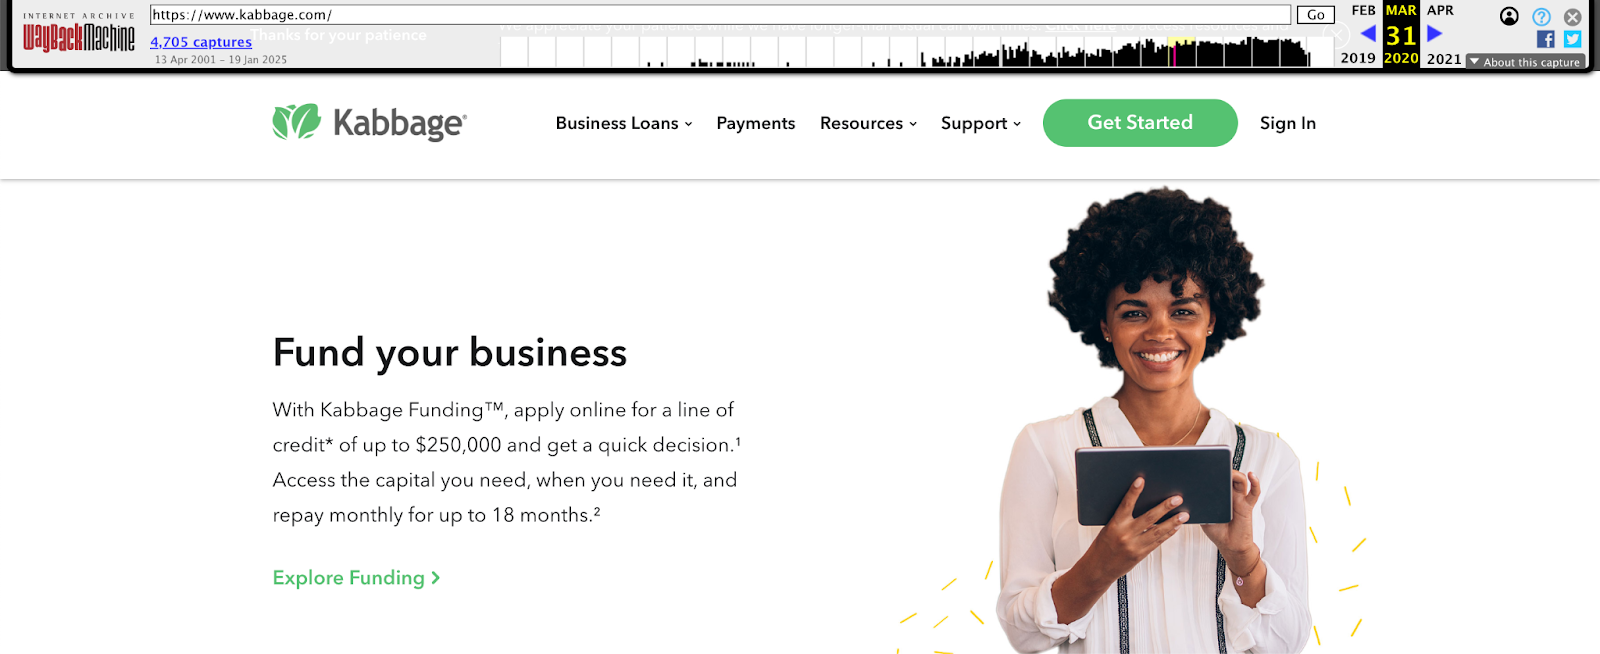
Kabbage was once a popular online lender and one of the SBA’s approved PPP loan providers. American Express quietly acquired Kabbage’s platform in 2020, and reworked it to create Business Blueprint—a comprehensive business cashflow dashboard. 

So, what’s changed? And, is American Express Business Blueprint worth checking out? Here, we’ll take a quick peek at why Kabbage might have exited from their operations and learn everything you need to know about the new and expanded offer from Amex. 

This is what’s in store: 

  • What Was Kabbage?
  • What is American Express Business Blueprint?
    • Company Overview
  • How Does American Express Business Blueprint Work?
    • 1. Business Lines of Credit
    • 2. Business Banking Accounts
    • 3 Cashflow Management
    • 4. American Express Business Blueprint App
    • 5. American Express Invoicing & Payments
    • 6. American Express Financial Resources
  • Frequently Asked Questions
  • Final Takeaway

Now, let’s dive in! 

What Was Kabbage? 

What is Kabbage?

Kabbage, founded in 2009, was an automated lending platform offering quick loans up to $250K for small businesses. Known for convenience but high fees, it paused lending during COVID-19 to focus on PPP loans, earning mostly low ratings. 

Kabbage Reviews

Later, a few years after the purchase by American Express, it transitioned into Amex Business Blueprint, discontinuing its original offer. 

Near the end, Kabbage offered tools like: 

  • Kabbage Checking (competitive APY)
  • Kabbage Payments (low invoicing fees)
  • Kabbage Insights (cash flow tracking)

While useful, these services faced some technical issues before the transition. The hiccups near the end may have made selling the company the wise choice. 

You might also like: No-Doc Business Loans: Get Funds Without Proof of Income 

What is American Express Business Blueprint? 

American Express Business Blueprint

When I first heard that Amex had acquired Kabbage (whose lending funds used to come from Celtic Bank), I said, “If the brand does bring back working capital in the future, it will most likely come directly from Amex itself. We’ll just have to wait around to see.”  

Well, that future is now. 

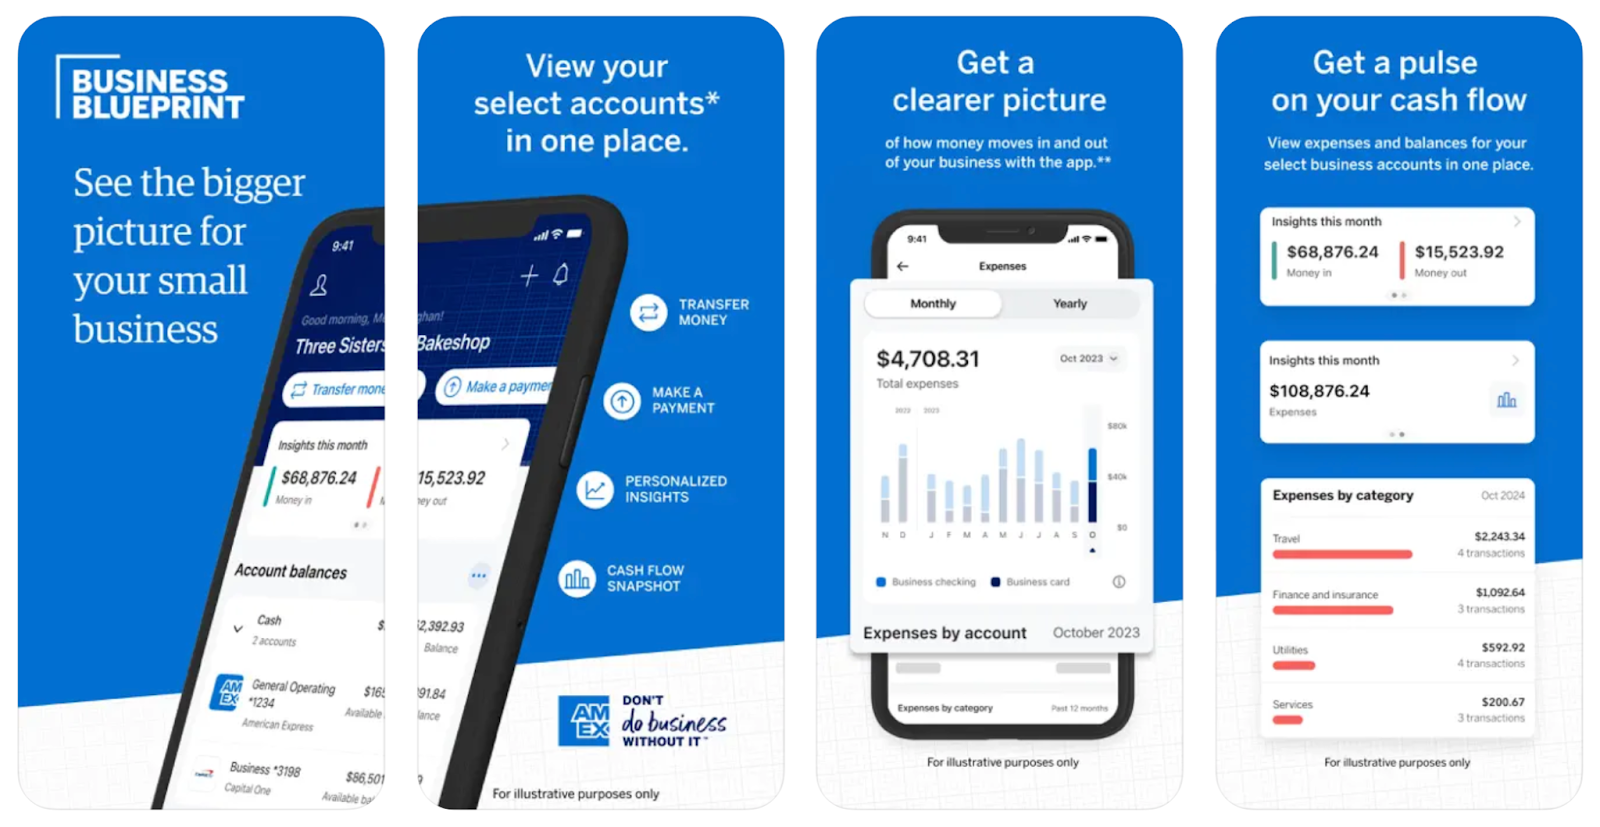
American Express Business Blueprint is a free platform positioned to help small businesses manage their cash flow. It lets you view your American Express business products and linked external accounts in one place. Then, it provides personalized insights to help you make informed financial decisions. 

With the tool, you can access features like a 30-day bank account balance projection, which uses data from your linked accounts to help you anticipate future balances. In a nutshell, business Blueprint aims to simplify financial management for small business owners.

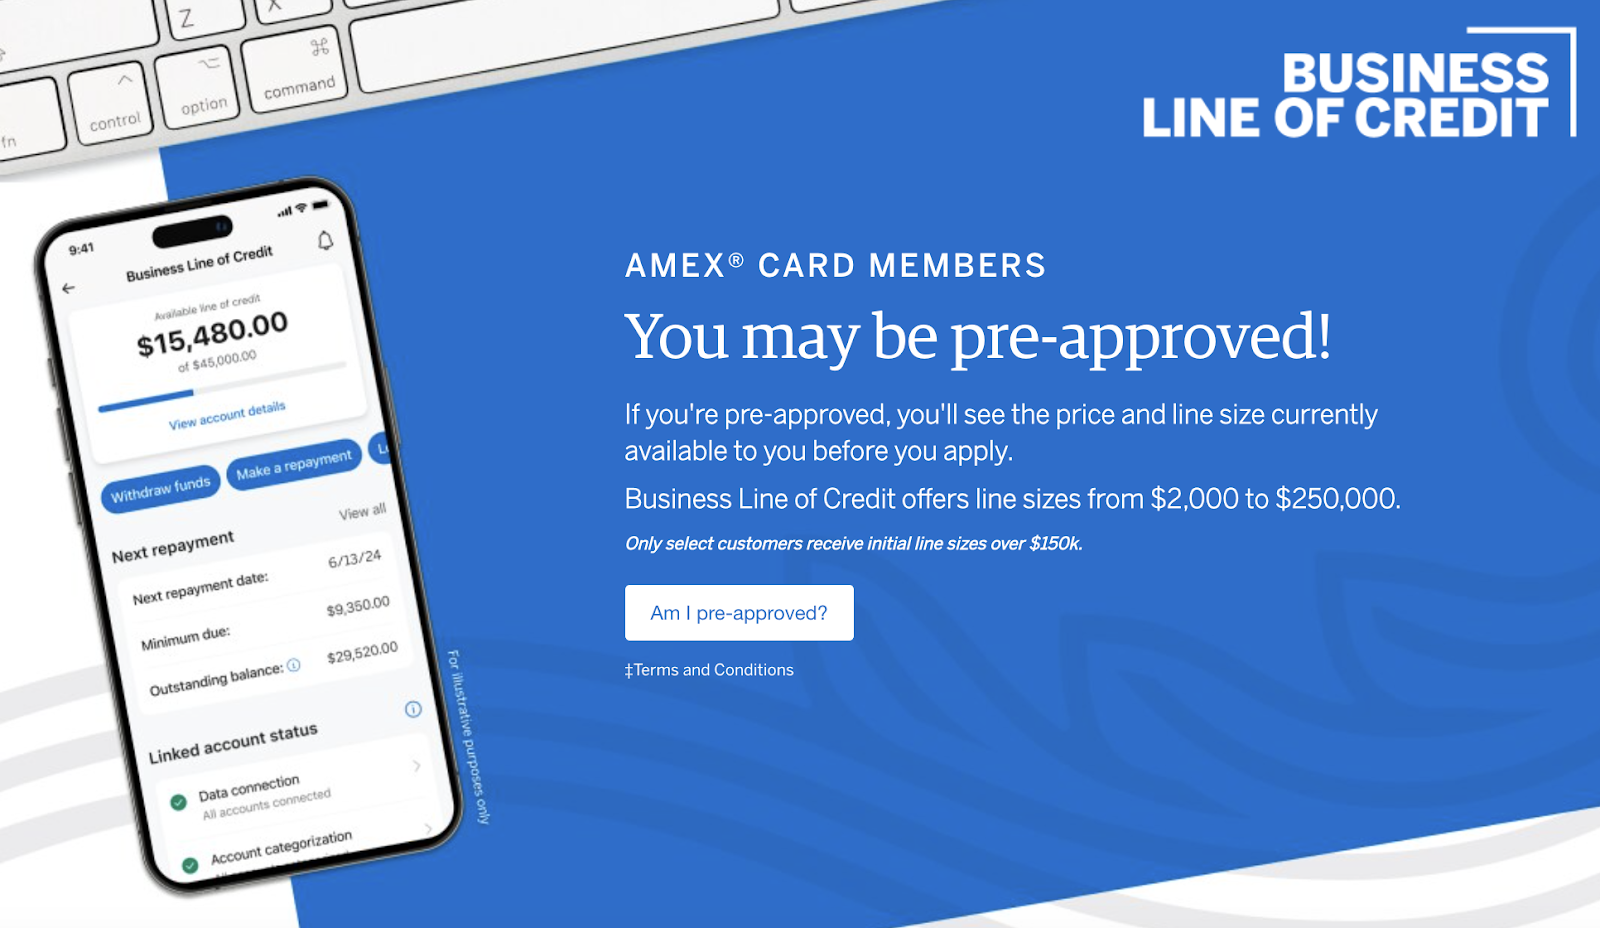
Moreover, Amex is offering a Business Line of Credit up to $250K (same as Kabbage), with no mention of Celtic Bank. Today, these loans are serviced directly by American Express National Bank.  

Recommended: Amex Business Checking Review: What You Need to Know…Really 

Company Overview

American Express Business Blueprint Benefits

American Express, aka Amex, is a global financial services company with roots dating back to 1850. Founded by Henry Wells, John Butterfield, and William Fargo—names you might recognize from Wells Fargo—Amex has built a reputation for reliability and innovation in finance. 

Initially known for credit cards, charge cards, and traveler’s checks, the company has since expanded its offerings to include business checking accounts (and, now working capital) further solidifying its leading position in the financial world.

Headquartered in New York and led by CEO Stephen Squeri, Amex stands out as a trusted name in American finance. It’s publicly traded and has endured as a stable force in a fast-evolving industry. 

You might also like: A Complete, Unfiltered Amex Business Gold Card Review 

How Does American Express Business Blueprint Work? 

American Express Business Blueprint login

As I said before, American Express Business Blueprint is free. And, you can log in with existing credentials, if you’re already an American Express member, or create an account. 

Once you’re in, you’ll have access to a lot of the same features and services that were available with Kabbage, but with some notable improvements. 

1. Business Lines of Credit

american express business line of credit

Kabbage’s fixed-rate loan fees were steep, ranging from 24-99% APR, with no savings for early repayment, no long-term options, and approval limited to businesses with online checking or PayPal. 

In contrast, Amex Business Lines of Credit offer a more affordable alternative, with funding from $2K to $250K secured by business assets and personal guarantees. 

Amex’s fees range from:  

  • 0.95% to 6.05% for single repayment loans (1 to 3 months)
  • 3% to 27% for installment loans (6 to 24 months)

So, Amex offers a much less expensive business lending option than Kabbage was able to. They also offer reduced costs with early repayment on installment plans. However, you must be an Amex cardholder to apply.

2. Business Banking Accounts

American Express Business Checking

Before the transition, there was no such thing as a Kabbage business savings account. Likewise, there is no American Express business savings account (though they do have a consumer savings option). 

Kabbage Checking offered FDIC-insured banking with 1.10% APY earned on funds, which they declared was the best deal you’ll find. This wasn’t true with 2% earnings from Bluevine and varying larger amounts from several credit unions. 

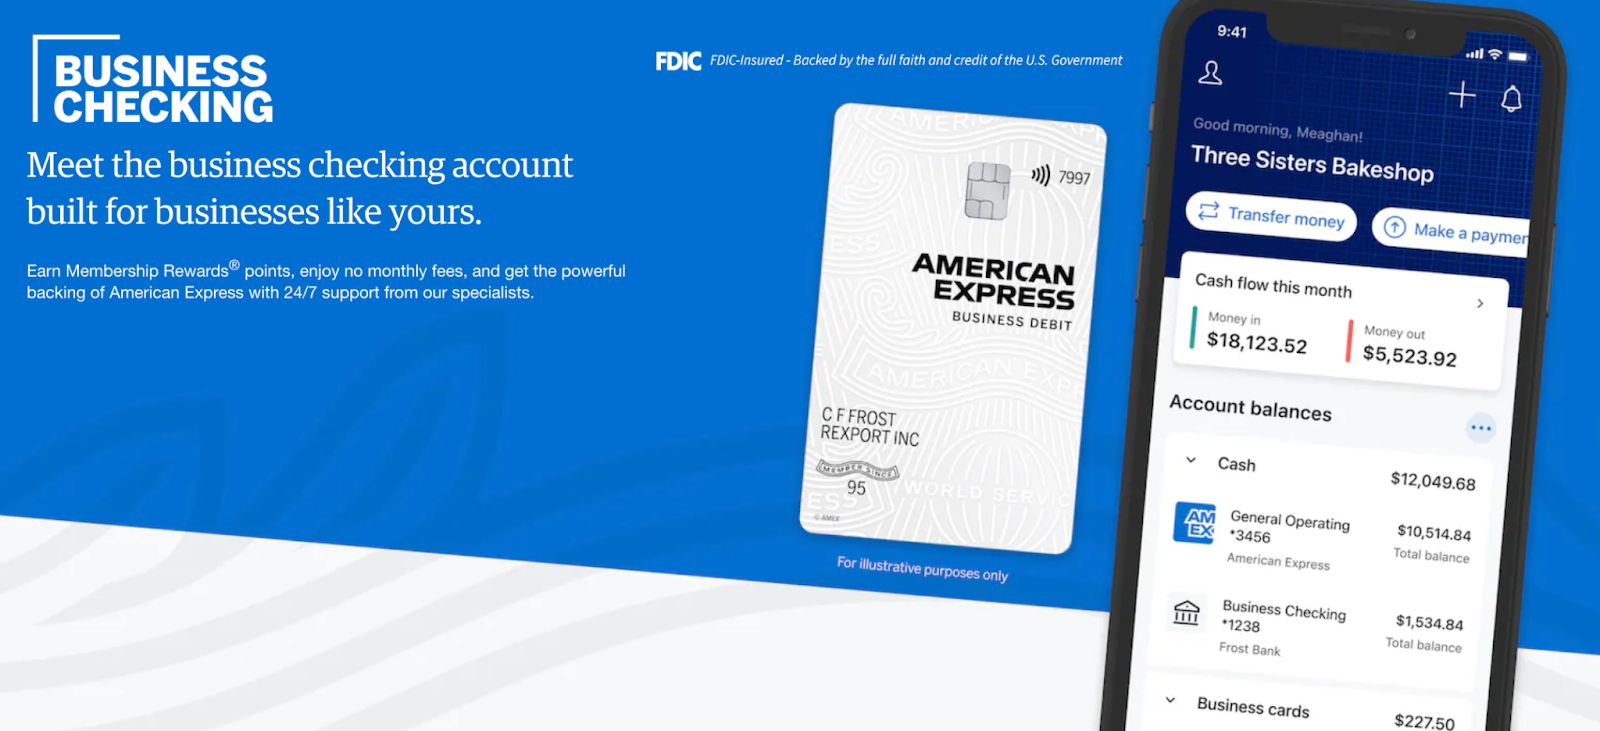
Today, American Express Business Checking is worth taking a look at.  Their business checking account earns 1.3% APY on balances up to $500K and charges no  monthly maintenance fee—They also offer a rewards debit card that earns 1 point with every $2 spent, and their high deposit limits can house balances up to $5 million. 

However, they lack integrations for tools like QuickBooks and don’t accommodate cash deposits (despite free MoneyPass™ ATM access). Currently, they don’t offer virtual cards, either. 

Recommended: Best Business Bank Accounts: 5 Top Picks for Small Businesses   

3. American Express Business Blueprint Cashflow Management 

Amex Cashflow Management

Kabbage Insights, in my opinion, was comparable to Quickbooks. While it did deliver visual reports, it was basically an accounting platform. Theoretically, it allowed users to view all their accounts in one place for a clearer picture of cash flow and revenue. 

Users could link the system to various banks, including smaller credit unions. PayPal and Stripe integrations were unavailable when I reviewed Kabbage, despite being advertised. 

Today, Business Blueprint™ is the core of Amex’s small business offer, with a real-time financial dashboard that consolidates Amex business products and linked external accounts. 

It offers: 

  • Personalized cash flow insights
  • Business  income and expense tracking
  • 30-day balance projections
  • A bird’s-eye view of your financial health

You can get all of this in one place. It’s designed to help you focus on growth instead of spreadsheets. The platform is free, but individual Amex financial products have their own fees and eligibility requirements.

You might also like: Plastiq Review: Can Plastiq Really Simplify Your Finances? 

4. American Express Business Blueprint App 

American Express Business Blueprint App

Back in September 2020, I noted that Kabbage’s web app and mobile app both seemed a little wonky. I assumed this was because they had recently furloughed staff and cut back on their service offer for the time being. 

Today, the American Express Business Blueprint app, available on both iOS and Google Play marketplaces, seems upgraded. 

Apple users give The Amex Business Blueprint™ app a 4.8 out of 5 rating, based on 8,500 reviews. Users appreciate its convenience and ease of use. However, some have reported limitations in banking functionalities, like viewing canceled checks and scheduling payments. 

However, most Android users seem find the Amex Business Blueprint app frustrating due to: 

  • Persistent login issues
  • Slow transfers
  • Frequent glitches
  • Poor support

Many of them prefer using the web instead.

You might also like: What is the Best Personal Finance Software? Free and Paid Options 

5. American Express Invoicing & Payments 

American Express Business Blueprint Payments

Kabbage Payments was an online invoicing platform with competitive rates at 2.9% + $0.25 per transaction, slightly lower than most major competitors. It supported email and web link billing, with next-day deposits for transactions processed before 5 PM. 

Users could also create a unique URL to sell gift certificates ranging from $15 to $500. 

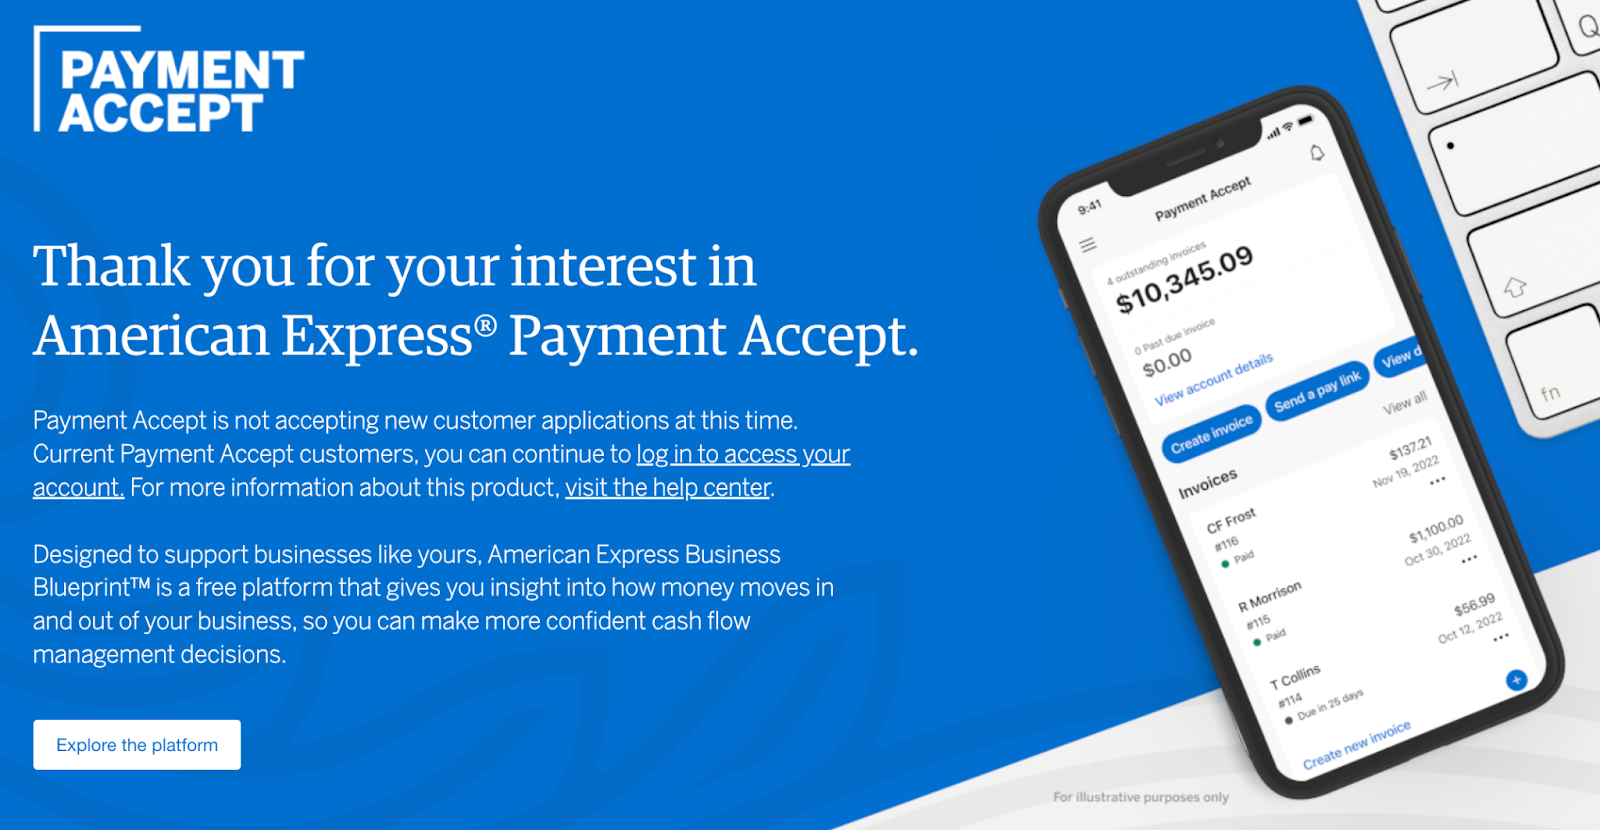
Today, American Express Payment Accept is a service designed to help small businesses process card payments online efficiently. It offers a straightforward solution with transparent pricing, aiming to make payment processing simple and quick.

*But, they may not be accepting new customer applications at this time—Check with Amex for Updated info. 

You might also like: Melio Payments Review: Can It Make Business Payments and Getting Paid Easier? 

6. American Express Financial Resources 

American Express Business Blueprint Customer Service

Kabbage’s “Resource Center” was a blog dedicated to financial advice for business owners. I found the articles to be pretty useful, easy-to-understand, and worth a look. 

Kabbage Funding Reviews

American Express, on the other hand, has a full suite of resources for small business owners through its Business Blueprint™ platform. 

This includes a Resource Center featuring: 

  • Articles on various small business topics
  • Customer success stories
  • A massive help center 

It provides not just articles but also tools, customer success stories, and guided resources to help business owners manage and grow their finances more effectively.

You might also like: 41 Companies That Help Build Business Credit [Beyond Net 30 Vendors] 

Frequently Asked Questions

Is it hard to get an American Express business line of credit?

Approval for an Amex business line of credit depends on factors like your business’s financial health, credit score, and cash flow. While the process isn’t overly difficult for well-qualified applicants, Amex does require a personal guarantee and evaluates your business assets carefully.

Does Amex business report to Dun & Bradstreet?

Yes, American Express reports business credit activity to Dun & Bradstreet as well as other major credit bureaus, helping you build your business credit profile.

Why do so many businesses refuse Amex?

Some businesses avoid accepting Amex due to higher transaction fees compared to other credit card providers. These fees can cut into profit margins, especially for small businesses.

Is American Express business hard to get?

Obtaining an Amex business card or account generally requires a good to excellent credit score and stable business finances. While not excessively hard, it may be challenging for newer businesses or those with weaker credit profiles.

What is the minimum income for Amex Business Platinum?

American Express doesn’t specify a minimum income requirement for the Business Platinum Card. But, MyFico forums have a lot of anecdotal stories that suggest that they expect applicants to demonstrate significant income or business revenue to justify approval.

Final Takeaway

American Express Business Blueprint took what Kabbage started and expanded it into a full-scale financial platform. With better lending terms, a solid business checking account, and improved cash flow tools, it’s a clear upgrade. 

However, some drawbacks remain, like limited integrations and an inconsistent mobile app experience. If you’re an Amex cardholder looking for streamlined business banking and financing, it’s worth considering—just be aware of its gaps.

Are you ready to learn how to obtain up to $100K in business credit in as few as 30 days? Join Business Credit Workshop today!
Giggle Finance: Instant Funding for Freelancers & Self Employed

By Joe

Key Takeaways

  • Giggle Finance provides up to $5K in fast funding for gig workers.
  • Giggle requires no credit checks,= and uses bank account activity to assess eligibility.
  • You can set up income-based, automatic repayment for flexible loan management.
  • Customer service is digital-only, with mixed reviews on responsiveness.
  • Accusations of predatory practices and unauthorized transactions raise red flags.
  • Some users value Giggle’s speed and simplicity for emergency financial needs.

Giggle Finance offers something a little different than what we usually review here, but maybe not as different as you might think. Before you apply, you’ll want to know what it is you’re signing up for. 

Here, explore what Giggle Finance is, learn more about the company, and understand key features of the offer. 

This is what’s in store: 

  • What is Giggle Finance?
    • Company Overview
  • How Does Giggle Finance Work?
    • 1. Apply Easily Online
    • 2. Get Instant Funding Anytime
    • 3. Repay Based on Your Income
    • 4. Access Funding Without a Credit Check
    • 5. Know Your Terms Before You Borrow
    • 6. Be Ready for Digital-Only Customer Support
  • Frequently Asked Questions
  • Conclusion: Is Giggle Finance Legit?

Now, let’s dive in! 

What is Giggle Finance? 

Giggle Finance

Giggle Finance provides fast and convenient funding solutions designed specifically for: 

  • Gig workers
  • Independent contractors
  • Self-employed individuals

They offer up to $5K in instant funding, their platform is fully automated, available 24/7, and requires no credit checks or lengthy application processes. 

The idea is that borrowers can access cash quickly to manage unexpected expenses or invest in opportunities. In theory, this can make it a flexible option for those in the gig economy who need immediate financial support.

You might also like: Torro Business Funding Review: Is This “Zero Hassle” Offer Legit? 

Company Overview

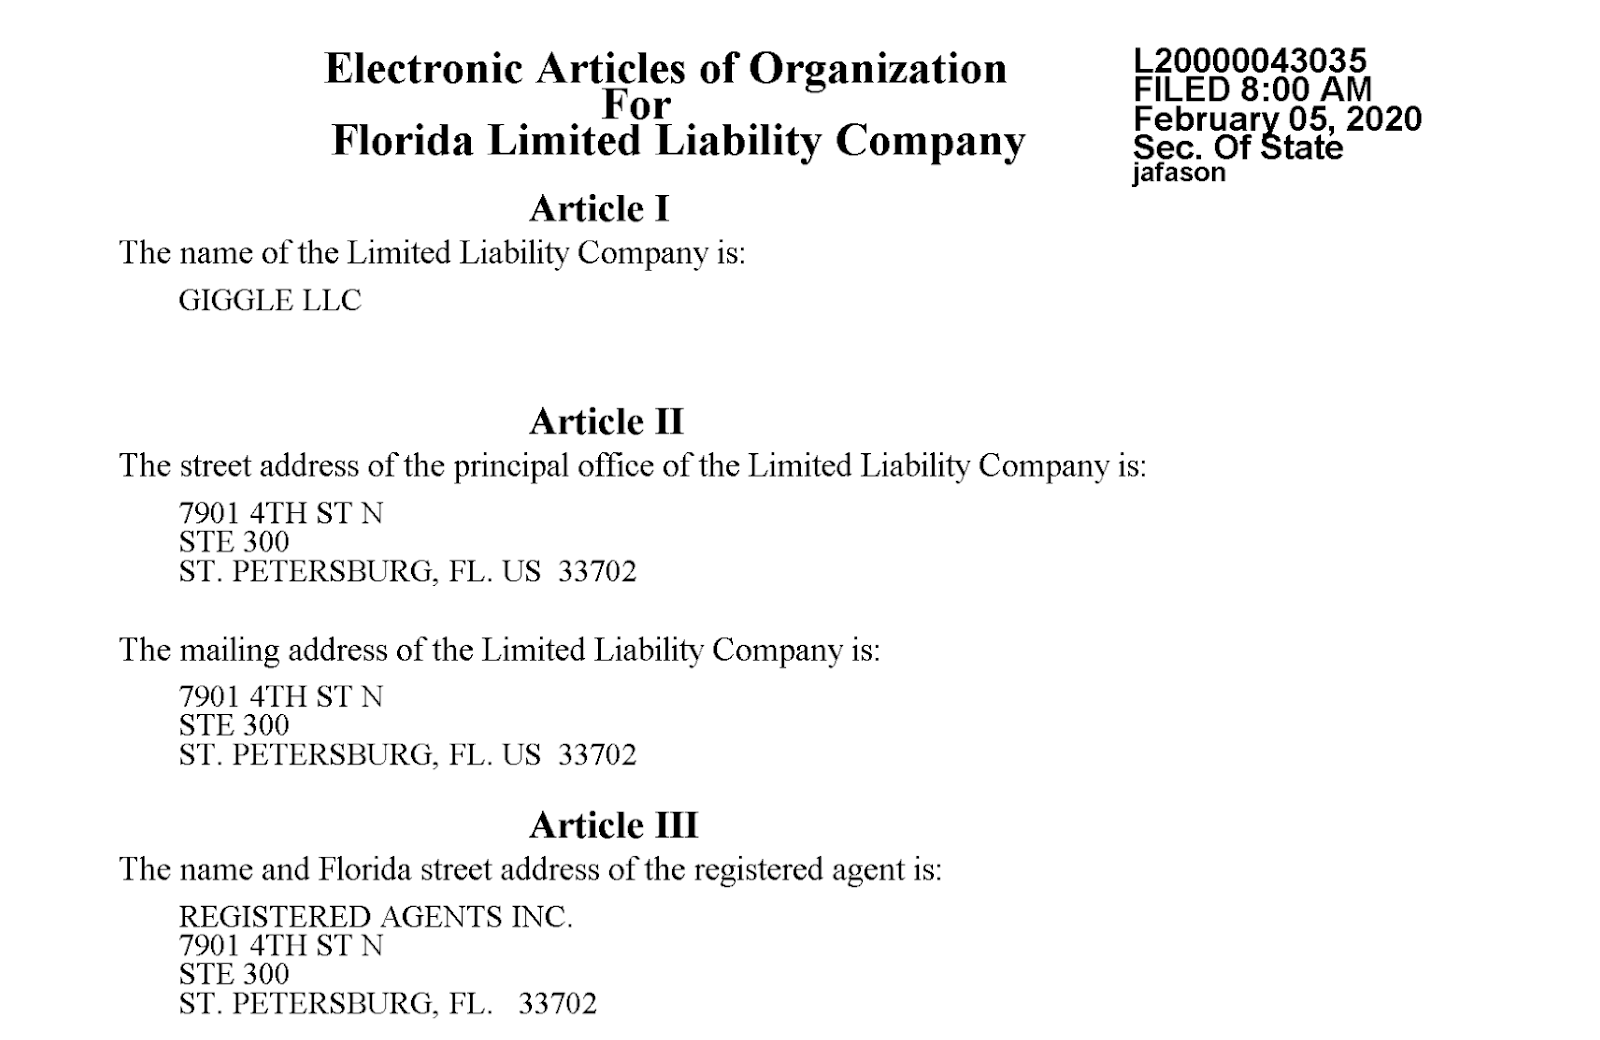
Giggle LLC

Giggle Finance, aka, Giggle LLC is a Florida-based, private, for-profit financial services entity that was founded in 2020 by Jared Kogan and Michael Zevallos. According to Florida’s SunBiz, the company is active, in good standing, and up-to-date with all their required filings with the state. 

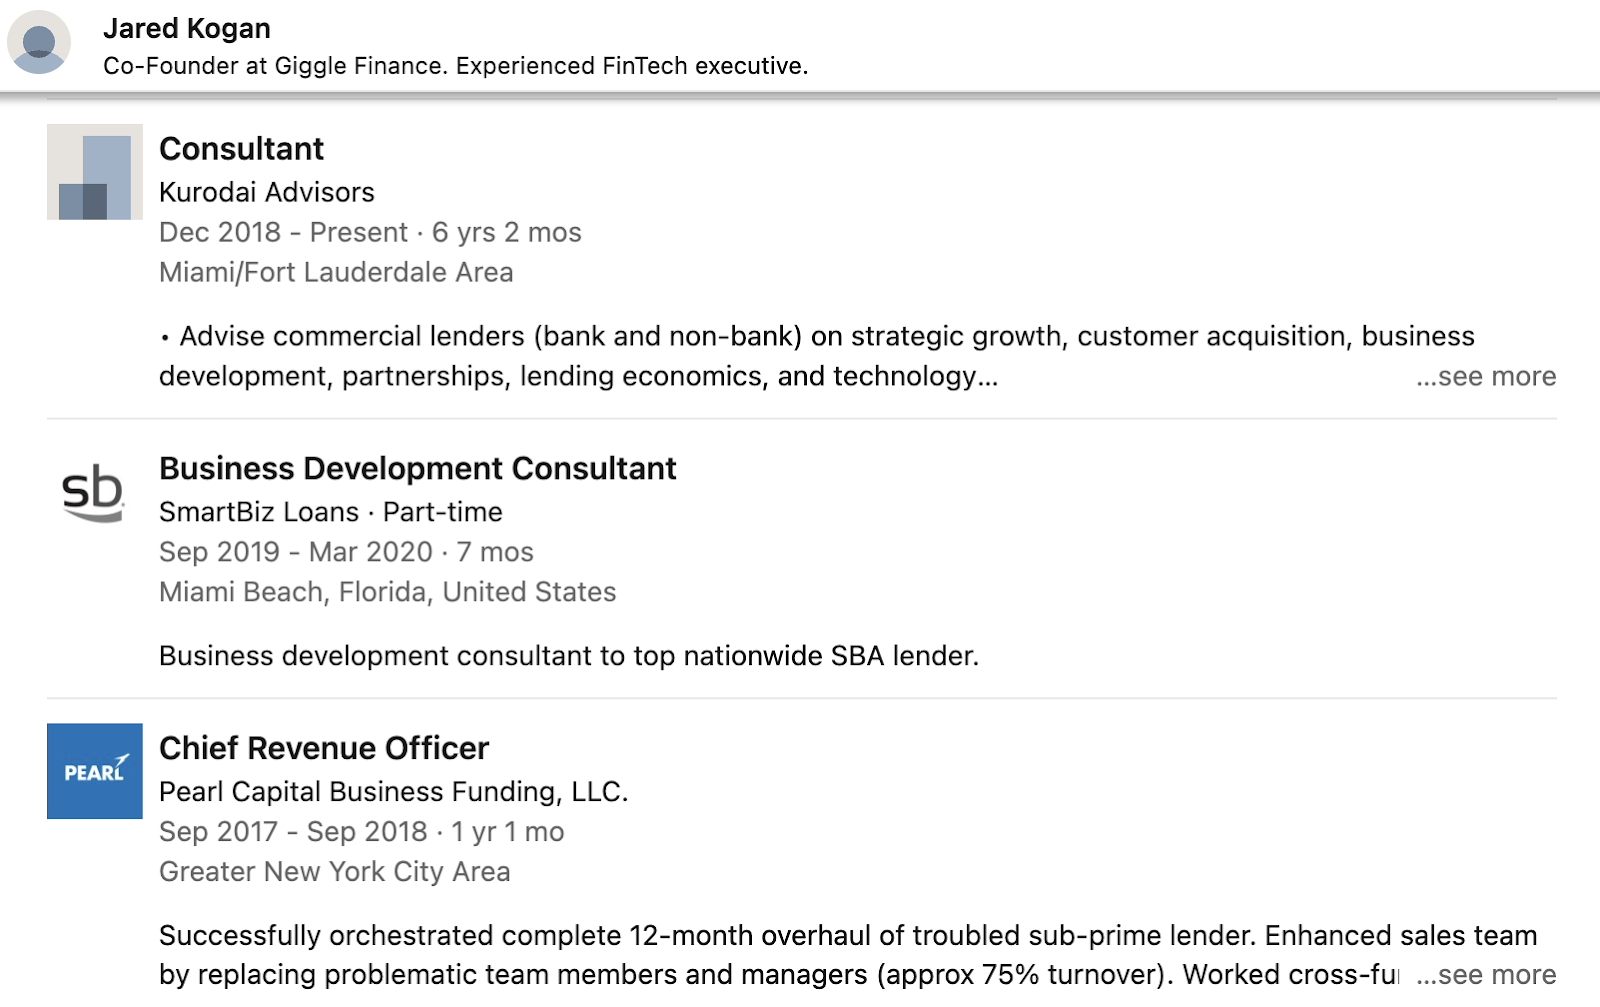
Kogen previously spent 5+ years with OnDeck, as the Director of External Sales, and has held several high-level business consulting positions. Zavallos was the Manager of External Sales at OnDeck when Kogen was with the company, and he was the Co-Founder and COO at Idea Financial before the team launched Giggle. 

Who owns Giggle Finance?

In short, the leadership seems to be solid. However, it’s important to know what borrowers have to say. 

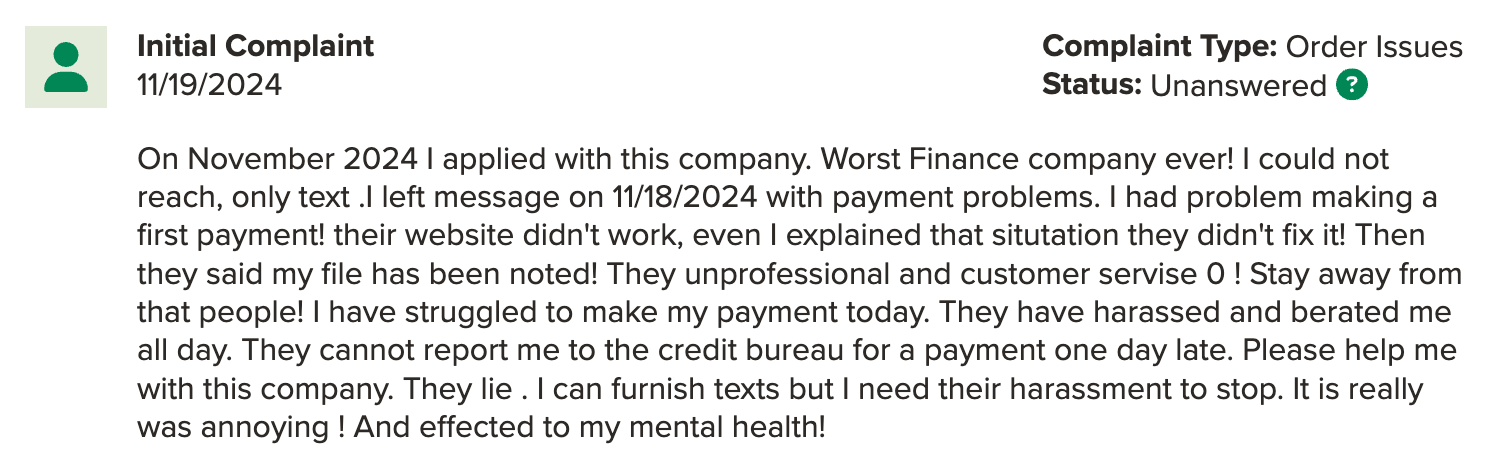
Currently, Giggle isn’t accredited with the Better Business Bureau (BBB), which I would almost let slide—not every legitimate business is accredited. But, they currently have an “F” BBB-rating and have failed to respond to 32 complaints filed on the platform. 

Giggle Finance complaint on BBB

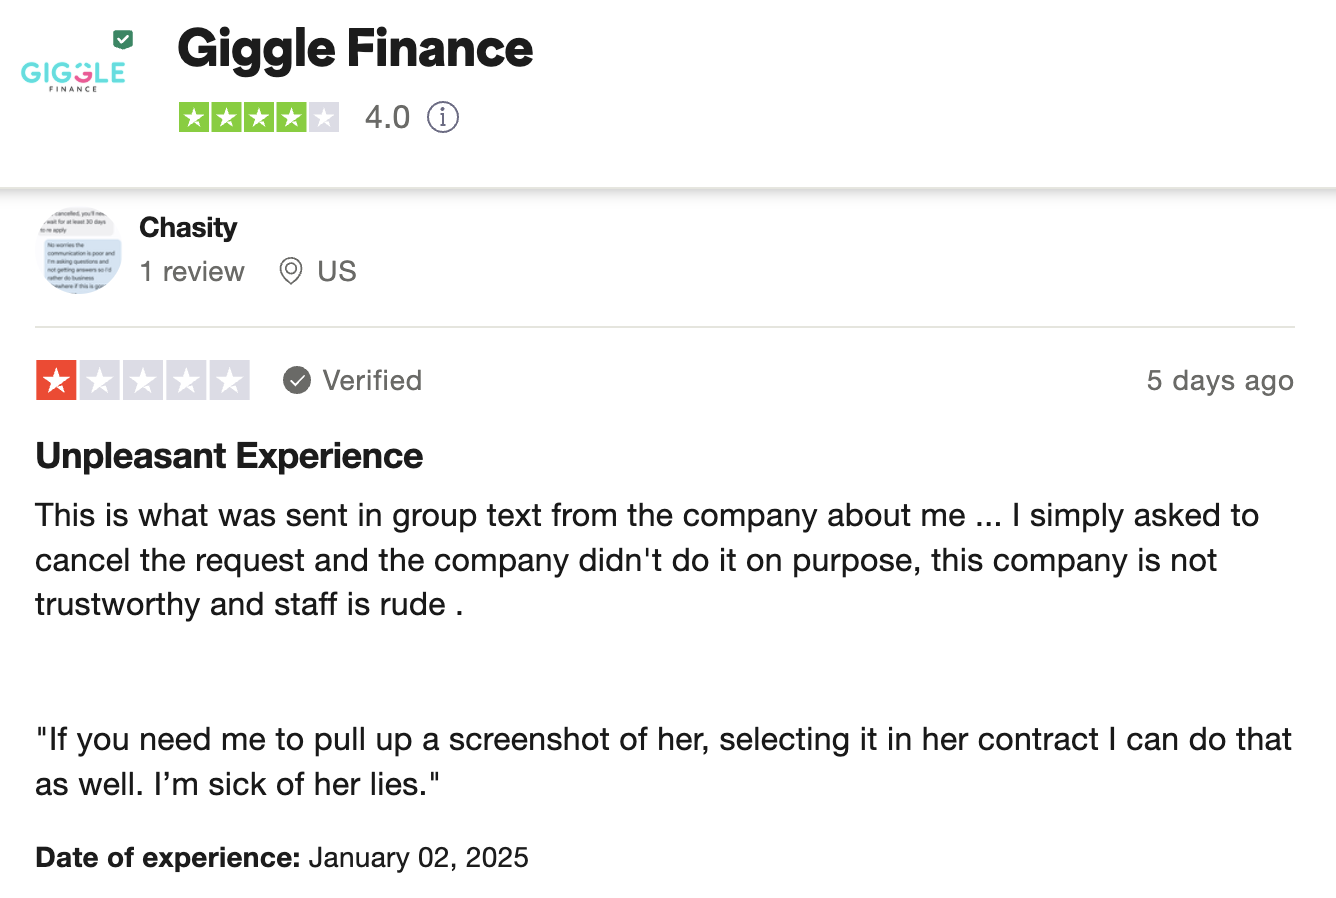
Overall, TrustPilot reviews are a little more optimistic, with a 4.0 (out of 5.0) TrustScore.™  Even so, the 1-star reviews are pretty brutal. 

Giggle Finance Reviews

All in all, borrowers largely view Giggle Finance as an “unethical” lender, citing: 

  • Unauthorized transactions
  • Predatory practices
  • Poor customer service

Though, some people appreciate its fast funding for emergency needs.

These are some pretty weighty accusations, so I wanted to verify whether or not there are any open lawsuits against the company. And, I couldn’t find any current legal issues. 

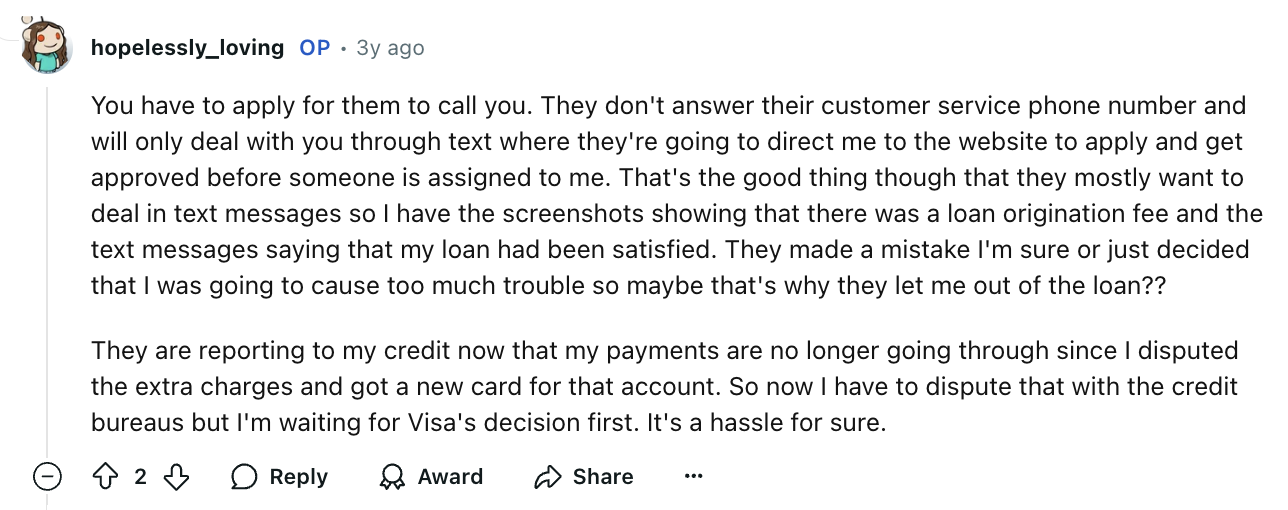
However, Redditors also criticize Giggle Finance as deceptive, warning that its loans involve hidden fees and misrepresented terms, which has caused financial strain for gig workers.

Giggle Finance reddit

Having no experience borrowing from the company myself, I would have to take others’ word. On one hand, Giggle Finance offers fast funding that some borrowers find helpful in emergencies, while on the other, reviews raise significant red flags.

 You might also like: How to Get a Business Credit Card – The Ultimate Guide 

How Does Giggle Finance Work? 

Giggle Finance offers gig workers and self-employed individuals fast funding options, but borrowers should weigh the potential risks. Here’s how it works.

1. Apply Easily Online

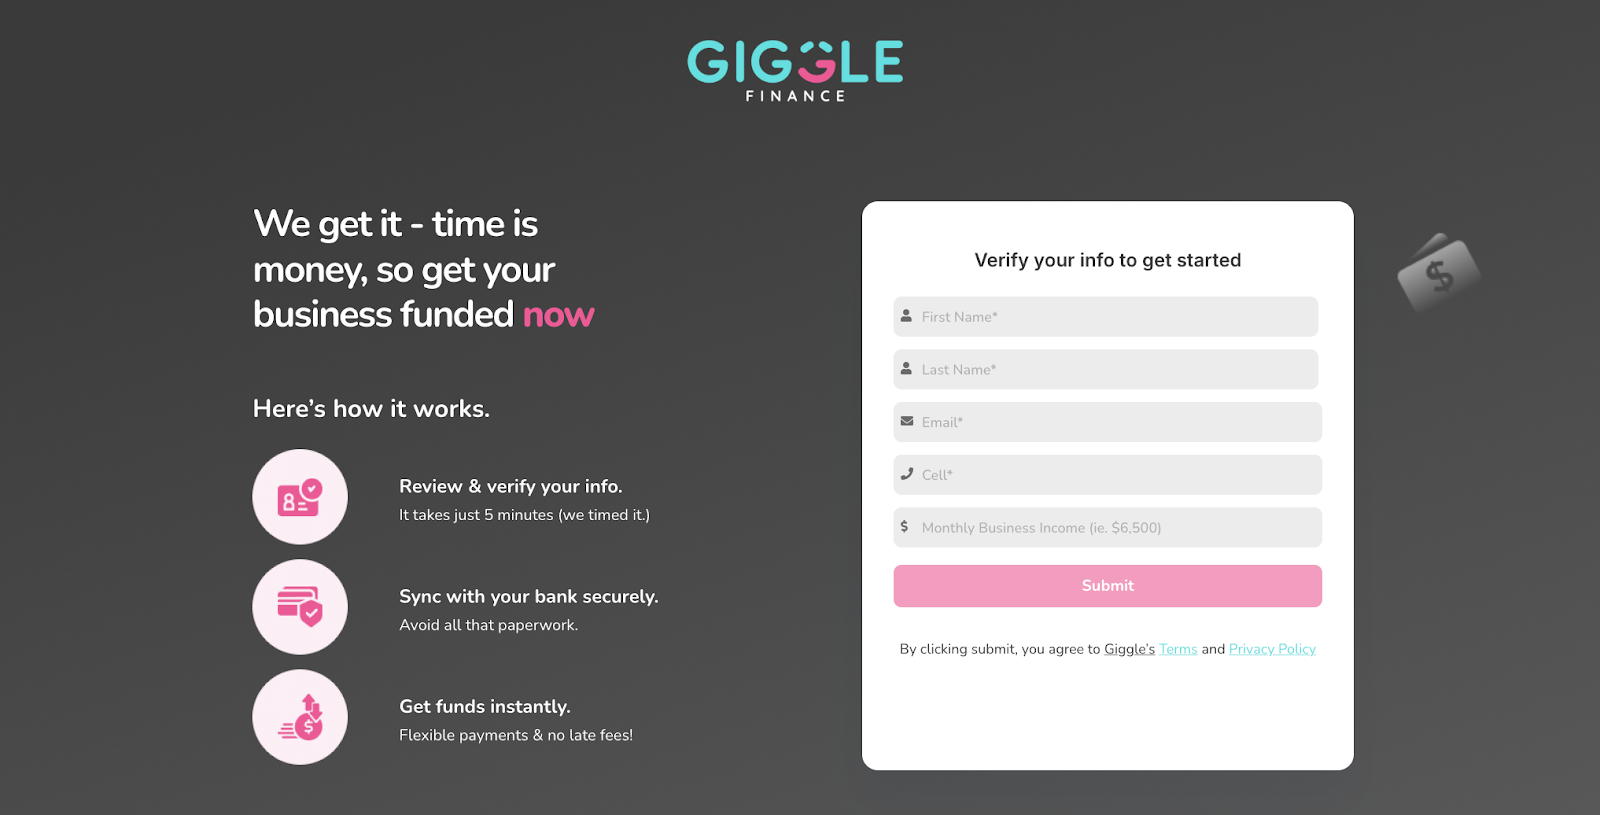
Giggle Finance Application

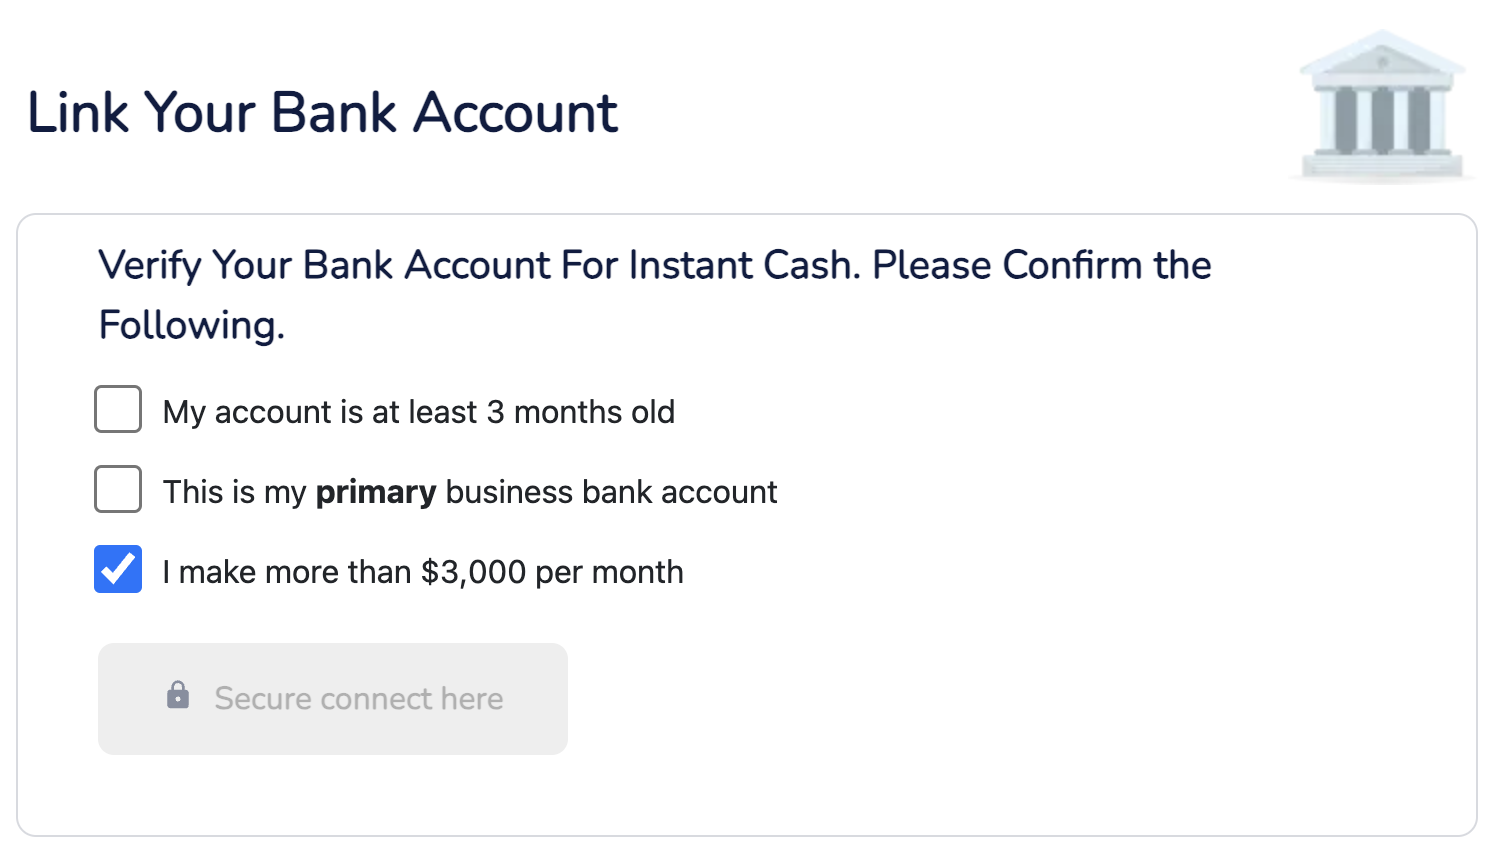
The process begins with a quick online application that takes just minutes to complete. By connecting your bank account, Giggle evaluates your eligibility based on income and account activity instead of credit scores. 

Giggle Finance login

While convenient, some users have expressed concerns about privacy and the security of their financial data. I know that they work with Plain, which I know to be a secure technology. 

Login Giggle Finance

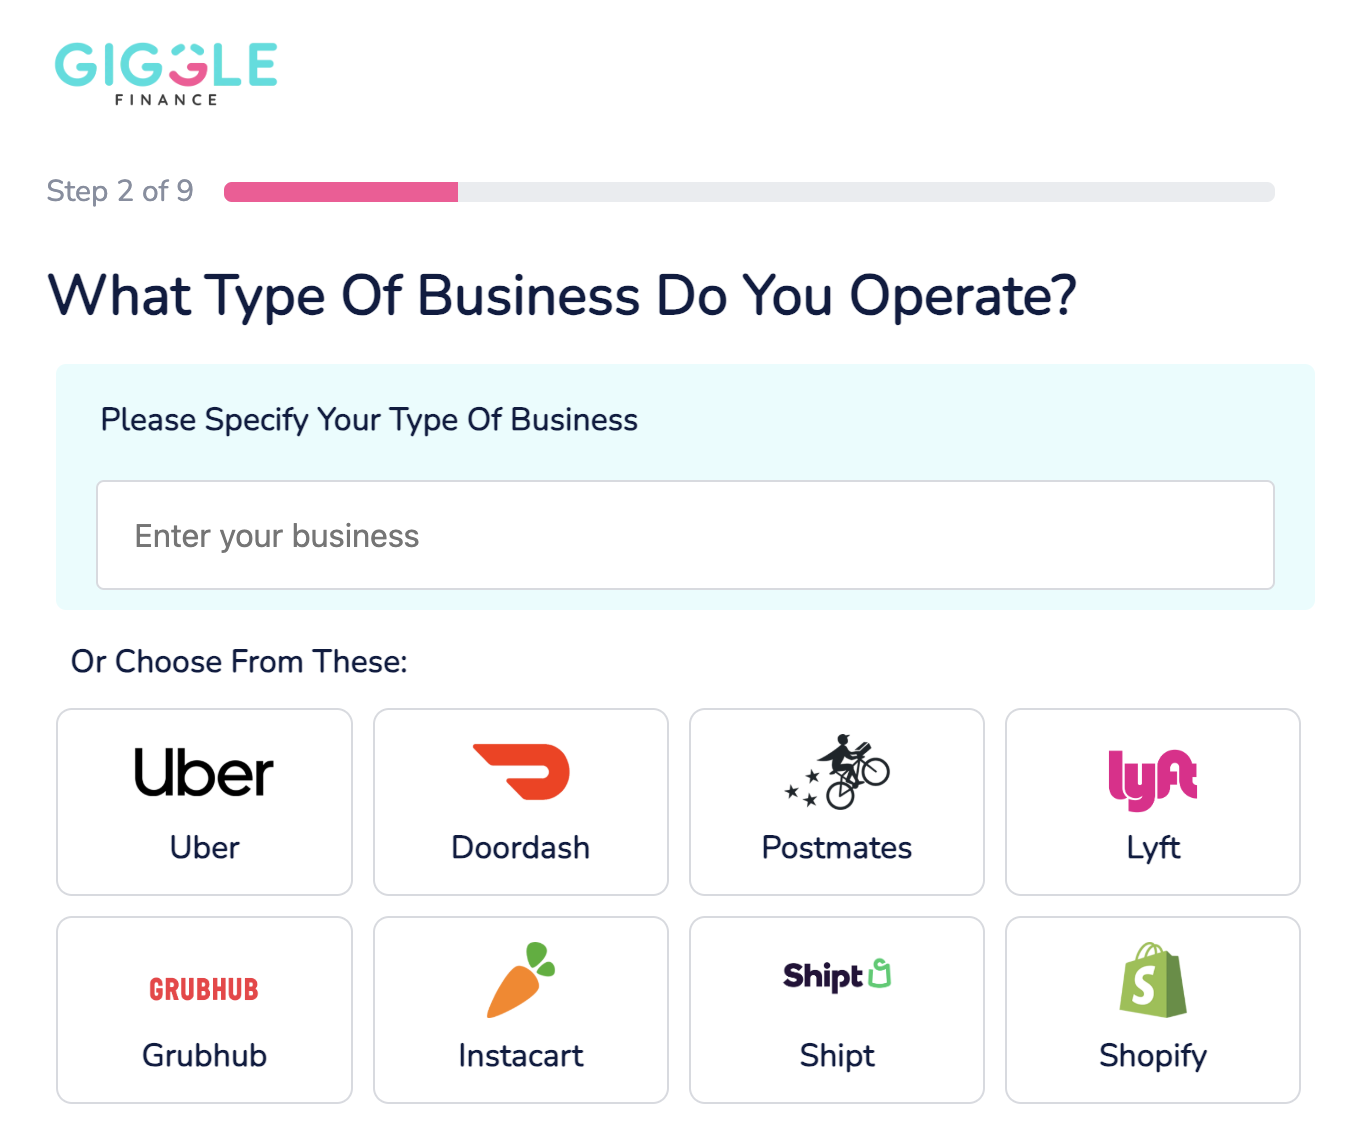
If you’re working for a popular delivery service or selling on Shopify, you may be able to connect your account for immediate revenue info (this may be where the data security issue comes in). 

You might also like: No-Doc Business Loans: Get Funds Without Proof of Income 

2. Get Instant Funding Anytime

How long does Giggle Finance take?

Once your application is submitted, the automated system processes approvals in real time, with funds often deposited within minutes. This 24/7 availability is ideal for emergencies. 

However, some borrowers have reported delays or discrepancies in the amount funded compared to what was expected.

Recommended: Net 30 for New Business: 13 Vendors +Credit Building Insights 

3. Repay Based on Your Income

Giggle finance make a payment

Repayments are automatically deducted in line with your earnings, offering flexibility for those with variable incomes. Giggle also allows early payoffs to save on fees. Despite this, some users have faced challenges with rigid payment schedules and unexpected deductions.

Giggle finance dashboard

With this said, you will need to connect the platform to your primary business bank account. They’ll use it for income verification AND repayment. 

You might also like: 11 Alternate Ways for Entrepreneurs to Raise Capital with Online Lenders

4. Access Funding Without a Credit Check

no credit check loan for gig worker

Giggle Finance caters specifically to gig workers, freelancers, and independent contractors who may struggle to qualify for traditional loans. 

The no-credit-check feature makes the service widely accessible, but the high fees and unclear repayment terms reported by some borrowers warrant a careful review.

You might also like: A Full Skip Review: Business Grants, Funding, and More 

5. Know Your Terms Before You Borrow

Giggle Finance fees

Giggle Finance determines its fees and repayment terms based on the amount borrowed and the borrower’s risk profile. The company claims to maintain transparency to make sure borrowers understand the total cost before agreeing to the terms, with no hidden fees. 

However, some users report higher-than-average fees.

Keep in mind, Giggle calculates repayment amounts using a factor rate, which is a multiplier applied to the borrowed amount. For instance, a $5,000 loan with a factor rate of 1.5 would require $7,500 in total repayment. And, Giggle Finance doesn’t advertise their factor rates (I wish they did).

You might also like: Clover Capital Review: Read This Before You Accept an Offer 

6. Be Ready for SMS-Only Customer Support

Giggle finance phone number

To verify what some borrowers had said, I tried calling the phone number listed on the website and was redirected by a pre-recorded message instructing me to send a text. 

Customer service is entirely digital, with interactions through text or email. Some users have described their experiences as unprofessional or unhelpful, particularly when resolving disputes or addressing errors. But, depending on your preferences, this might be convenient. 

Frequently Asked Questions

What credit score do you need for Giggle Finance?

You don’t need a specific credit score to qualify for Giggle Finance. The platform does not rely on traditional credit checks and instead evaluates your eligibility based on your bank account activity and income.

What is the maximum loan amount for Giggle Finance?

The maximum loan amount offered by Giggle Finance is $5K— Your approved amount will depend on your verified income and banking activity.

Does Giggle Finance report to credit bureaus?

Yes, Giggle Finance does report to credit bureaus. This means your repayment activity (including any missed or late payments) can impact your credit score and appear on your credit report. Be mindful of this when you apply for a loan.

Conclusion: Is Giggle Finance Legit? 

Giggle Finance provides quick, easy access to cash, which can be invaluable in a pinch. However, recurring complaints (with no responses from the company) about aggressive practices, high costs, and poor communication highlight the importance of understanding the risks before borrowing.

If you carefully review the terms, you can make an informed decision about whether Giggle Finance is the right solution for your needs.

Do you want to learn how to obtain up to $100K in business credit in as few as 30 days? Join Business Credit Workshop today!
A Complete, Unfiltered Amex Business Gold Card Review 

By Joe

Amex Business Gold Review

Key Takeaways

  • Earn 4X points on your top 2 spending categories (up to $150,000/year), 1X on others.
  • Get 3X points on flights and hotels, no foreign fees, and trip delay insurance.
  • Manage expenses with QuickBooks, employee cards, and year-end summaries.
  • Annual fee is $375, with up to $240 in select service credits.
  • Requires good credit (700+ FICO score), $3,000+ monthly revenue, and solid business credit.
  • Includes cell phone protection, extended warranties, and purchase protection.

Have you considered applying for the Amex Business Gold card, but not sure what you’d be getting yourself into? In business, the sheer number of financial management options can be overwhelming, but let’s simplify to determine if this choice is right for you. 

In this Amex Business Gold card review, you’ll find what the card is, see a company overview, explore the benefits, and find out if (and when) it might be worth it to apply. 

This is what’s in store: 

  • What is the Amex Business Gold Card?
    • Amex Business Gold Requirements
    • Business Credit Score Impact
    • Amex Business Gold APR and Fees
  • Amex Business Gold Benefits Worth Exploring
    • 1. Amex Business Gold Rewards
    • 2. Expense Management Tools
    • 3. Travel Perks for Cardholders
    • 4. Business Services from Amex
  • Frequently Asked Questions
  • Conclusion: Is Amex Business Gold Worth it?

Now, let’s dive in. 

What is the Amex Business Gold Card? 

Why Should You Get the Amex Business Gold?

The Amex Business Gold card is a premium business credit card from American Express with a handful of standout features, including: 

  • Rewards on spending
  • Expense management tools
  • Travel perks 
  • Business services

It also offers cash flow flexibility with revolving credit, which you can pay over time when needed, along with no preset spending limit. When you apply for the card, it won’t impact your personal credit, because approval is based on your business credit score. 

You might also like: Amex Business Checking Review: What You Need to Know…Really 

Amex Business Gold Requirements

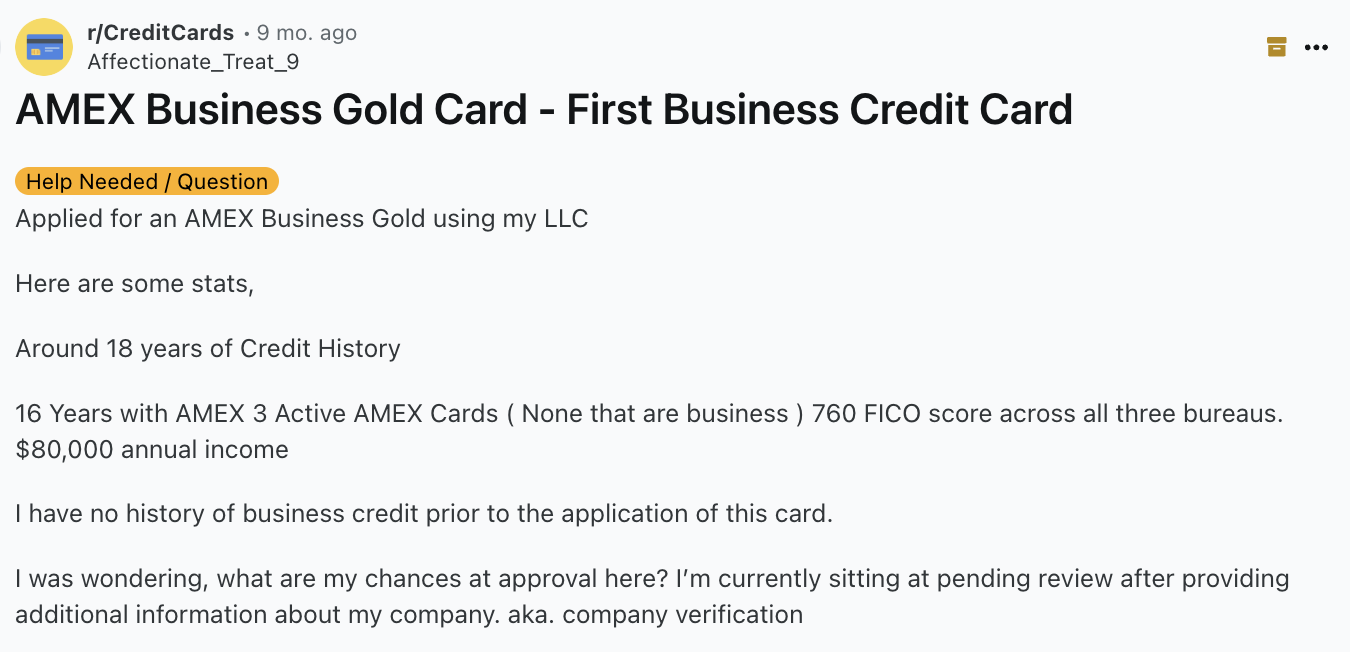
American Express Business gold card limit Reddit

Wondering how to get an Amex Business Gold card? Well, as you may know, the requirements are fairly stringent. However, they’re not clearly specified anywhere. 

So, here’s what I know is required: 

  • Solid business credit score 
  • FICO (personal credit) score above 700
  • Average monthly revenue of at least $3K  

The more revenue you have and the higher your business and personal credit scores, the more likely you are to qualify for an Amex Business Gold card. 

Recommended: This is How to Build Business Credit Fast [Step-by-Step Guide] 

Business Credit Score Impact

When you apply for the Business Gold card from Amex, your business credit score might take a small hit because Amex may check it during the application process. Your personal credit score won’t be affected at this stage. 

However, If you’re approved and decide to accept the card, it may impact your personal credit, because you’ll likely need to guarantee the account. This means that, if the account defaults, you’re on the hook. 

This card could offer a good way to build business credit if you manage it well, but be sure you’re comfortable with any potential impact on your personal credit before accepting.

You might also like: Here’s How to [Actually] Get Business Credit With Just an EIN +More Options 

Amex Business Gold APR and Fees

Amex Gold Business review

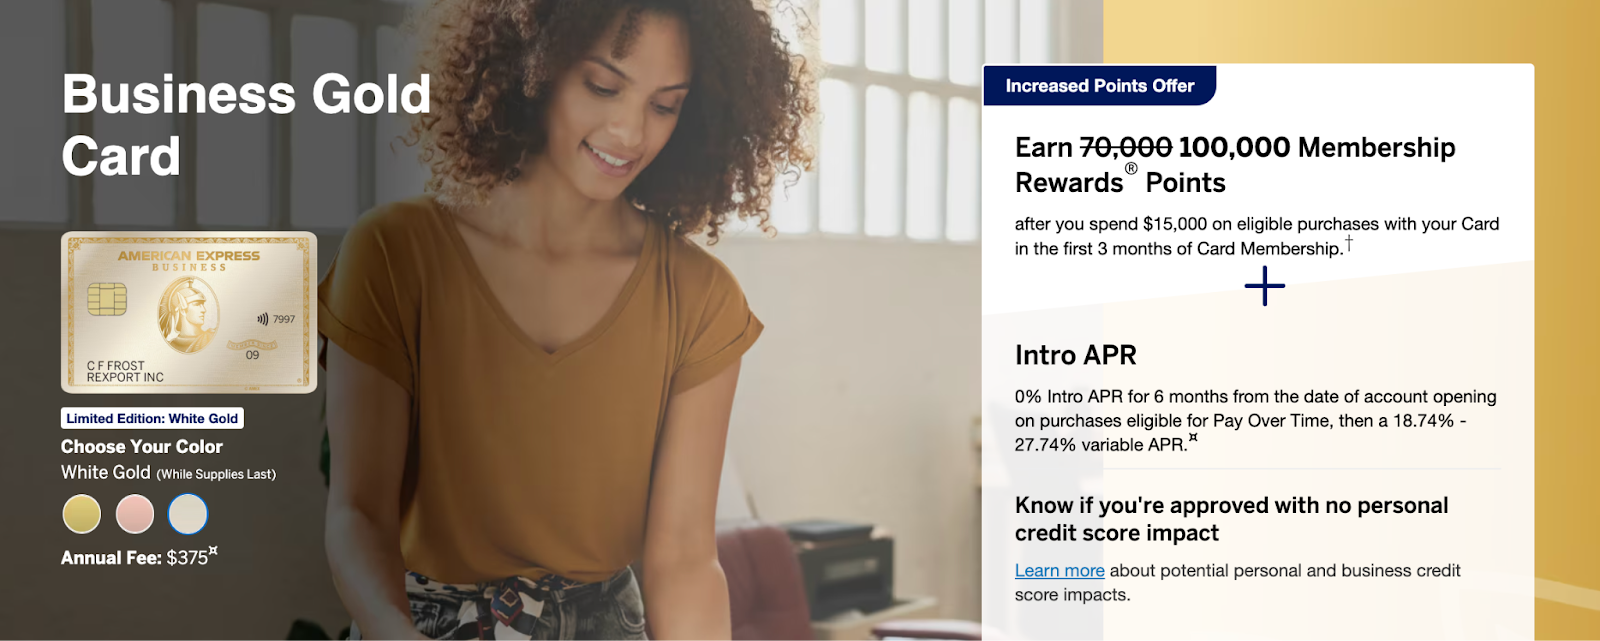
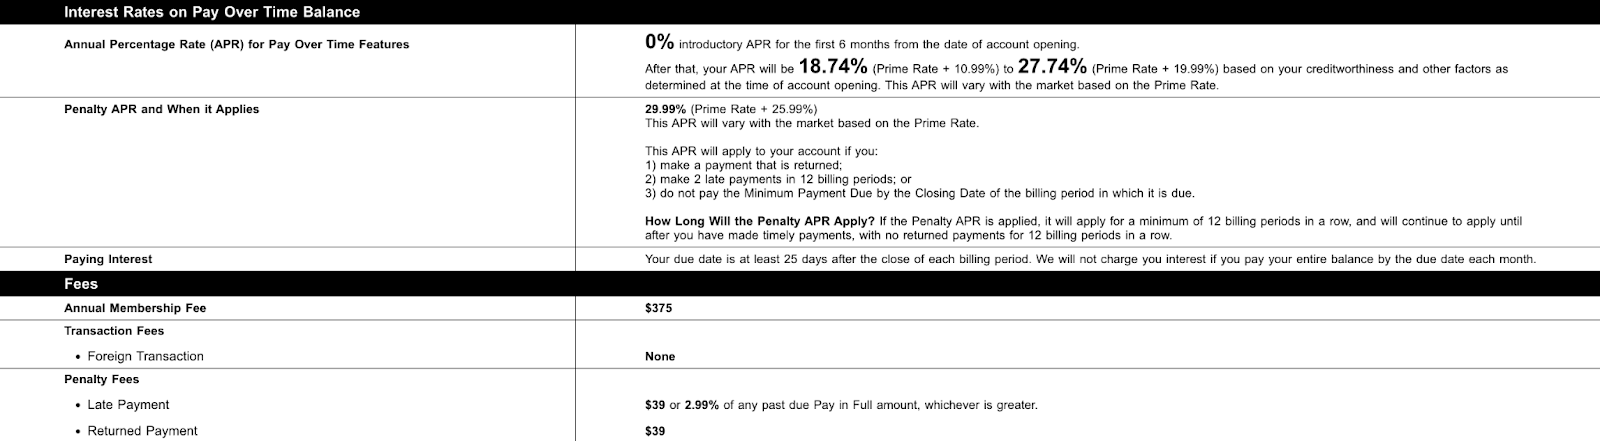
The Amex Business Gold Card offers 0% APR for the first 6 months, so no interest accrues during this time. Be mindful that the introductory 0% APR doesn’t apply to cash-like transactions or fees, and this is an intro offer, which can change any time.

After that, the APR will range from 18.74% to 27.74%, based on your credit and the Prime Rate, which can change with the market. Then, if you miss payments or have returned payments, a 29.99% Penalty APR might apply for at least a year. Paying on time helps you avo