• Home
  • Free Funding Guide
  • What We Offer
    • Products
    • Services
    • Free Guide
  • About Us
  • Contact
  • Sign Up

  • Ask Joe Any Question!
  • Business Credit Cards
  • Business Line of Credit
  • Topics

Grasshopper Bank Review for Business Banking, Lending, & More 

By Joe

Grasshopper Bank

Key Takeaways

  • Grasshopper Bank is a digital-only, FDIC-insured institution.
  • Business accounts earn interest with no monthly fees.
  • SBA 7(a) and 504 loans support business growth.
  • Sponsor finance loans help with buyouts and acquisitions.
  • Commercial real estate and yacht loans start at $1 million.
  • API banking allows businesses to automate transactions.
  • Grasshopper has an A+ BBB rating but mixed reviews.
  • Recent legal challenges may be a concern for some.

If you’re an owner with an interest in digital banking for your small or medium-sized business, Grasshopper bank may have shown up on your radar. If so, surely you have questions about the offer. 

When an institution seems like it might be a little too new or a slightly more unconventional than what you’re familiar with, it’s smart to do your research. Here, I lay out everything you need to know about what to expect if you open an account. From a summary of the business banking and funding offer to info about leadership, trust signals, and Grasshopper Bank reviews, here’s the scoop. 

This is what’s in store: 

  • What is Grasshopper Bank?
    • Company Overview
  • How Does Grasshopper Bank Work?
    • 1. Open an Interest-Earning Business Bank Account
    • 2. Apply for Small Business Administration Loans
    • 3. Make Use of “Sponsor Finance” (Secured Loans)
    • 4. Get Funding for Commercial Real Estate or a Yacht
    • 5. Integrate the Grasshopper System With Your Tech
  • What are the main differences between Brex and Grasshopper Bank?
  • Frequently Asked Questions
  • Conclusion: Is Grasshopper Bank Legit?

Now, let’s dive in! 

What is Grasshopper Bank? 

Grasshopper bank review

Grasshopper Bank is a digital financial institution serving small businesses, startups, and investors in the so-called “innovation economy”—companies driven by technology, digital tools, and entrepreneurship.

Whether this term reflects tailored services for tech-driven businesses or is just marketing language is unclear. 

Either way, the bank offers:

  • Business checking and savings accounts
  • SBA lending
  • Fintech solutions like embedded finance and API banking

You won’t find Grasshopper Bank locations because they’re an online-only institution. Grasshopper emphasizes their client-first approach and use of technology to deliver secure and efficient banking experiences.

You might also like: 6 Best Fintech Credit Cards to Apply for (Consumer & Business) 

Company Overview

How long has Grasshopper Bank been in business?

According to Crunchbase, Grasshopper Bancorp, Inc. is a privately-owned, New York-based, “woman-led,” for-profit company that was launched by Judith Erwin in 2016. 

However, neither Grasshopper nor Judith Erwin are listed in New York’s Doing Business Portal. However, the company is listed in Delaware’s corporate directory, the FDIC approved their application for insurance in 2018, and they’re headquartered at 915 Broadway, 7th Floor, New York, New York. 

Erwin seems to have left Grasshopper in 2021 to pursue private, strategic business consulting. The company’s current CEO is Mike Butler. So, while the company was founded by a woman, it’s not currently woman-led. 

Prior to taking the reins at Grasshopper, Butler served as the President of Consumer Finance at KeyCorp and spent nearly 14 years as the President and CEO at Radius Bank. 

Who is the CEO of Grasshopper Bank?

While Butler seems like he would be a good leader, based on his experience, I was disappointed to see that I couldn’t find specific information about how employees feel about him on Glassdoor. 

Still, they’re A+ rated with the Better Business Bureau (BBB), with only 4 total complaints—This is super rare. However, some customer reviews on the BBB website express dissatisfaction, citing issues such as unexpected account closures, lack of communication, and delays in fund returns. They’ve been BBB-accredited since 2024. 

Who is the CEO of Grasshopper Bank?

And, over on Trustpilot, their TrustScore is above middling at 4.1 stars out of 5, where most reviews are outstanding. Positive feedback highlights knowledgeable and responsive customer service, with 68% of reviewers awarding 5 stars. However, 23% of reviewers rate the bank at 1 star, citing issues like unexpected account closures and “unhelpful security practices.”

Grasshopper Bank Review Trustpilot

And, Reddit reviews (usually the most critical) on Grasshopper Bank are mixed. Some users find it better than traditional banks, but others report slow transactions, account access issues, and poor communication. Common complaints include long mobile deposit times, unexpected fees, and difficulties resolving account problems. 

Grasshopper bank Reddit

After a quick search for lawsuits, I found that, as of February 16, 2025, Grasshopper Bank is facing legal disputes, including an $8 million loan default lawsuit and a contract-related case in Florida. While lawsuits aren’t unusual for banks, you may want to consider how these issues could impact service, lending policies, or financial stability.

In sum, Grasshopper Bank has been around for at least seven years (as of 2018 when their FDIC insurance was approved), led by experienced executives with mostly positive but mixed customer feedback. While many praise its service, some report account closures and fund access issues. It holds an A+ BBB rating and a solid Trustpilot score, but recent lawsuits are something to keep in mind.

You might also like: Best Business Bank Accounts: 5 Top Picks for Small Businesses 

How Does Grasshopper Bank Work? 

Now, for the meat and potatoes—What, exactly, can you get if you open a Grasshopper Bank account? And, how is it different from other offers? 

1. Open an Interest-Earning Business Bank Account 

Grasshopper Bank wiki

A business bank account that earns interest can help maximize your idle cash while your funds stay accessible. Grasshopper Bank offers digital-first checking and savings solutions for small businesses and startups. With competitive interest rates and no monthly fees, it provides an easy way to grow your money while managing business expenses.

Here’s what you get with a Grasshopper business bank account:

  • Up to 1.80% APY on checking balances 
  • Up to 3.55% APY on savings balances over $25K
  • No monthly fees or overdraft charges
  • Unlimited ACH transfers and fee-free transactions
  • 1% cashback on online and signature-based debit card purchases
  • 24/7 mobile and online banking with instant-issue virtual debit cards

Opening an account takes just a few minutes online, which can give you immediate access to digital banking tools to streamline payments, automate bookkeeping, and simplify cash flow management.

Grasshopper Bank Login

In addition, Grasshopper advertises enhanced security features that include fraud monitoring, encryption, and dual approvals for transactions.

*Grasshopper also offers specialized banking for venture capital and private equity firms. 

You might also like: 3 Best Credit Unions for Small Business Banking in 2024 

2. Apply for Small Business Administration Loans

Grasshopper Bank SBA lending

As an SBA Preferred Lender, Grasshopper streamlines the loan process with a digital-first application, which can potentially reduce documentation requirements and accelerate approval times. Businesses can qualify for an SBA 7(a) loan in less than 10 minutes, making it easier to access financing for working capital, acquisitions, real estate, partner buyouts, and debt refinancing.

The bank provides two primary SBA loan options:

  • SBA 7(a) Loan – The most flexible SBA loan, used for general business expenses, acquisitions, refinancing, and more
  • SBA 504 Loan – Long-term, fixed-rate financing for purchasing commercial real estate, construction, or major equipment

You may be able to leverage Grasshopper’s SBA loans for expansion, succession planning, or debt consolidation. 

You might also like: This is the Truth About LenCred’s Small Business Financing 

3. Make Use of “Sponsor Finance” (Secured Loans)

Grasshopper bank secured term loans

Grasshopper Bank offers sponsor finance solutions designed to help businesses secure funding for acquisitions, buyouts, and working capital needs. Whether you want to expand operations or manage investment cycles, these lending options can provide structured, flexible financing to support your goals.

Sponsored finance options include: 

  • Senior Secured Term Loans – Might be Ideal for leveraged buyouts and add-on acquisitions
  • Revolving Lines of Credit – Can help cover working capital and corporate expenses
  • Delayed Draw Term Loans – Funding for acquisitions, growth capital, or deferred payments
  • Capital Call Lines – May bridge timing gaps between investments and capital inflows
  • Fund NAV Facilities – Use a fund’s portfolio as collateral to improve liquidity and returns

Grasshopper works with lower middle-market companies, typically those generating at least $8 million in annual revenue and $1 million in earnings (before interest taxes depreciation and amortization). The process is streamlined with digital banking tools to help make sure your transactions are efficient.

Grasshopper focuses on building long-term relationships by combining expert underwriting with technology-driven banking solutions to make the financing process smooth and efficient.

You might also like: The Ultimate Tillful Review (+Secured Credit Offer for Businesses) 

4. Get Funding for Commercial Real Estate or a Yacht

Grasshopper bank commercial real estate lending

If you need financing for commercial real estate or a yacht, there are specialized loan options that can help. For commercial properties, loans start at $1 million and are available for stabilized properties like multi-family buildings, medical offices, warehouses, retail spaces, and flex spaces. 

These loans are primarily offered in: 

  • New York
  • New Jersey
  • Eastern Pennsylvania

Borrowers can also access liquidity lines of credit to manage cash flow.

For yacht purchases, loan amounts range from $1 million to $10 million, with terms up to 20 years—Both fixed and adjustable-rate options are available. Some loans may also allow foreign registration or limited charter use. 

Both types of loans are designed to provide clear terms and a straightforward application process when you want to finance a major purchase.

You might also like: How to Get Money for Real Estate Investing: 18 Practical Ideas 

5. Integrate the Grasshopper System With Your Tech

Grasshopper Bank API

Grasshopper’s banking system can integrate directly with your technology, which can enable you to make financial transactions more seamlessly. With API banking and embedded finance solutions, you may be able to automate payments, transfers, and financial data within their own platforms.

Grasshopper’s Banking-as-a-Service (BaaS) and API banking provide tools to automate transactions like:

  • ACH
  • Wires
  • Real-time fund transfers

You can manage payments and bill pay from within your own software, monitor account balances and transaction details in real time, and even issue branded VISA® debit cards for customer transactions. 

Grasshopper bank branded Visa debit cards

These solutions can work for a wide range of industries, including fintech startups, B2B marketplaces, and manufacturers, which can help you streamline your financial operations.

Security and compliance are built into the system, with bank-level fraud prevention and regulatory protections. As a nationally chartered bank and FDIC member, Grasshopper makes sure all transactions meet strict risk management standards. 

You might also like: The PEX Card: Is it the Best Corporate Card for Your Business? 

What are the main differences between Brex and Grasshopper Bank? 

While I would think that online-only like Bluevine and Novo are more like direct competitors on the banking front, more people seem to want to know how Grasshopper stacks up against Brex.  

As of today, the popular search engine overview completely misses the mark on this front, with a seemingly outdated comparison.  

Grasshopper Bank vs Brex

As of February 16, 2025, Brex and Grasshopper Bank offer distinct financial services tailored to businesses, each with unique features and benefits:

  • Brex is a fintech platform that offers corporate cards, expense management, and high-yield business accounts—tailored for startups and high-growth companies.
  • Grasshopper Bank is a digital bank with interest-bearing accounts, cash-back debit cards, and SBA lending—more for small businesses that need straightforward banking with access to funding.
Brex LogoGrasshopper Bank Logo
Business accounts with spend management1.80% APY checking, 3.55% APY savings
Corporate credit cards with rewards1% cash-back Visa debit card
No monthly fees, no minimumsNo monthly fees, $100 minimum deposit
AI-powered expense automationBill Pay, invoicing, and bookkeeping
No lending; high-yield accountsSBA loans, SaaS funding via Capchase

In sum, Brex may be a good option if your main goal is financial automation and expense control. Meanwhile, Grasshopper may be better if you want small business banking with high-yield accounts and lending options. Both seem to cater to startups. 

Recommended: Brex Card Review: Is This Corporate Card Offer Too Good to be True? 

Frequently Asked Questions 

Is Grasshopper a real bank?

Yes, Grasshopper is a real, FDIC-insured digital bank that primarily serves small businesses, startups, and fintech companies. It operates as an online-only financial institution.

Is Grasshopper FDIC-insured?

Yes, Grasshopper Bank is FDIC-insured, meaning deposits are protected up to $250,000 per depositor, per account category.

Does Grasshopper Bank use Zelle?

No, Grasshopper Bank does not currently support Zelle for person-to-person payments. However, it offers other digital payment solutions for businesses.

How big is Grasshopper Bank?

Grasshopper Bank is a relatively small, digital-first financial institution focused on business banking. While it does not have physical branches, it provides banking services nationwide.

What is Grasshopper Bank’s routing number?

Grasshopper Bank’s routing number is 026013303.

Conclusion: Is Grasshopper Bank Legit? 

Grasshopper Bank is a legitimate, FDIC-insured digital bank that offers business banking, SBA loans, sponsor finance, and embedded finance solutions. They have competitive interest rates, no monthly fees, and digital tools for seamless transactions. While many businesses appreciate its features, some customers report issues with account closures and fund access.

Grasshopper may be a good fit for small businesses, startups, and investment firms looking for online banking with lending options and API integrations. However, businesses that need in-person banking or prefer traditional financial institutions might find other options more suitable. And, it’s always smart to review terms carefully before you open an account anywhere.

Are you ready to learn how to obtain up to $100K in business credit in as few as 30 days? Join Business Credit Workshop today!

3 Best Credit Unions for Small Business Banking in 2025

By Joe

Best Credit Union for Small Business 2020

Key Takeaways

  • Credit unions often offer lower fees, better interest rates, and flexible lending terms.
  • They provide personalized service and easier access to business credit.
  • Navy Federal, Financial Resources, and Sound Credit Union are our top choices.
  • Other options include Alliant, Consumers, America First, and Digital Federal.
  • Small community banks can also offer lower fees and flexible terms.
  • Research and compare options to find the best fit for your business.

As a small business owner or founder, where you choose to do your banking can have a major impact on your long-term operations. And, when researching the best bank or credit union for small businesses, you may have realized that you would rather work with a credit union. Now, let’s look at the top credit unions for small business banking. 

What you’ll find here: 

  • Are Credit Unions Better Thank Banks?
    • Are Credit Unions Better for Business Accounts?
  • The Best Credit Unions for Small Business
    • 1. Navy Federal Credit Union
    • 2. Financial Resources Credit Union
    • 3. Sound Credit Union
    • +Honorable Mentions
  • Final Thoughts

So, let’s get to it. 

First, Are Credit Unions Better Than Banks? 

There’s a longstanding debate about whether banks or credit unions are “better.” And, it’s important to understand the difference to answer this question. A bank is a for-profit institution and a credit union is a nonprofit organization that provides comparable financial services. So, what are the advantages of credit unions? 

At most credit unions, the shareholders are the members while banks funnel their profits to up the chain to its owners. This means that there is more opportunity for members to save on services and earn a larger percentage of total interest accrued with savings accounts and other investments. 

As a credit union member, you typically end up with lower interest rates and fees (a major plus). On the flip side, major banks typically have more branch locations where customers can do business and invest more in apps and convenience services. So, you could say that which is the best is a matter of preference. 

But, I have a tie-breaker: credit unions have less stringent and often flexible qualification terms for credit. You can’t walk into a bank like Wells Fargo and negotiate the terms of business banking fees, loans, or credit cards. At a credit union, more than not, you can because credit union underwriters usually work in-house and can modify terms and conditions of business and individual financial services. 

So, I say that credit unions are in-fact better than banks. Now, let’s move forward. 

But, Are Credit Unions Better for Business Accounts? 

Best Bank for Small Business

Aside from the general advantages above, there is another aspect of business banking with credit unions worth considering. When you bank with a credit union, you can leverage the perks above when obtaining business credit. For this reason, we prefer to work with credit unions. Alternatively, small community banks can be better for businesses than large banks. 

How to Leverage Business Credit to Transform Your Life 

Now, the Best Credit Unions for Small Business 

You should have a solid understanding of why or why not a credit union might be best for your small business banking. And, here are the top credit unions to join. 

1. Navy Federal Credit Union

With tons of free ATMs sprinkled throughout the United States and several other countries, Navy Federal Credit Union was created for members of the armed forces, DoD, or the National Guard. While you don’t necessarily have to be an active member to join, you must have ties to the military. So, if you are an active member, veteran, or a spouse, parent, grandparent, sibling, child, or grandchild of someone who qualifies, you can qualify for membership. 

If you are not a service member, you will have to apply in-person at a branch location. Once you are approved for a personal account, you can then apply for a business membership. And, Navy Federal has excellent offers for businesses.

  • 3 types of checking accounts (Basic, Plus, & Premium)
  • 3 types of savings accounts (Basic and Jumbo Money Market & Certificate)
  • Real estate, vehicle, and term loans
  • Business lines of credit 

Navy Federal is one of the best credit unions with the lowest rates and fees. Minimum deposits for business savings accounts start as low as $100. And, transaction fees range from $0 to $0.25. And, all accounts earn dividends. 

2. Financial Resources Credit Union

With 13 branch locations in New Jersey and New York, Financial Resources Credit Union has been the top SBA Lender in New Jersey since 2013. So, you know their business financial services are dependable.   

Here’s what you can leverage with Financial Resources Credit Union:

  • 2 types of checking accounts
  • 3 types of savings accounts (Business Purple, Money Market, & Certificates)
  • Real estate, equipment, and term loans
  • Lines of credit 

So, whether you’re investing in real estate or you simply want checking and savings accounts to process your business finances, Financial Resources gives you options. Here, terms are flexible and you can get expedited approval on SBA-backed loans because the institution is a preferred lender. 

3. Sound Credit Union

With 29 locations in the Puget Sound area of Washington State, Sound Credit Union is self-labeled “Washington’s Favorite Credit Union.” And, they stand out from most financial institutions in more than one way. 

For one, they cater to cannabis businesses, which isn’t common. Next, they offer low interest rates, cashback options on certain loans, and they do a lot to support the local community. Furthermore, they have over 5,000 shared branch locations and 30K+ free ATMs nationwide. 

And, businesses can take advantage of the following:

  • Checking accounts
  • Savings and certificate accounts
  • Cannabis (I-502 Analysis) business checking accounts 
  • Business loans
  • Business credit cards 

In addition, with Sound CU, you can access a full suite of business services that includes terminals and point of sale systems, eCommerce payment solutions, mobile card readers, payment acceptance, gift card, reward, and incentive programs, and mobile apps and software. The institution’s tech is as advanced as you can get with most major banks. 

+Honorable Mentions

Obviously, these three credit unions are only a small drop in the ocean of options. So, in case you aren’t able to select one of these three, I want to share four more credit unions that you can research yourself: 

  • Alliant Credit Union – 2 branch locations in Illinois and 80K+ free ATMs
  • Consumer Credit Union – 8 branch locations in Tennessee
  • America First Credit Union – Located in Ogden, Utah
  • Digital Federal Credit Union – 23 branch locations in Massachusets and New Hampshire, 5.9K shared branches, and 80K+ free ATMs 

Why choose a credit union instead of a bank?

Compared to a major bank, a credit union or small local community bank is likely to offer lower fees, increased savings, and more lenient qualification terms for lending. 

What are the disadvantages of credit unions?

Typically, credit unions run operations from their own funds, so they might offer less in the way of mobile apps, online banking features, and other conveniences. But, they still have many valuable perks. 

Are credit unions good for small business?

Credit unions can be beneficial for your small business. They offer lower fees and interest rates, personalized service, a local focus, easier access to credit, and the opportunity for relationship building. Research and compare different credit unions to find the one that suits your specific business needs.

Which bank is best for small businesses?

A small local community bank or credit union can be the best choice for small business banking. Fees are typically lower than those at major banks and lending qualification terms have more wiggle room. These institutions tend to have more control over their terms and conditions.  

How do I choose a bank for my company?

First, create a list of local small community banks and credit unions in your area. Then, call each institution on your list and ask about business checking and savings options as well as underwriting terms for business loans and lines of credit. Finally, choose the option that is the best fit for your operations and goals. 

Final Thoughts

The above-listed credit unions offer the best financial services for businesses. If you want your operations to run smoothly, you can’t go wrong with one of these choices. But, do your homework to make sure you choose the best institution to fit your needs.

To find out which banks and credit unions we’re currently working with to obtain lines of credit up to $100K in as few as 30 days, join Business Credit Workshop today. 

Amex Business Checking Review: What You Need to Know…Really

By Joe

Amex business checking review

Key Takeaways

  • Amex Business Checking earns 1.3% APY on balances up to $500K (and a longstanding 30K-point intro bonus for meeting account requirements).
  • No monthly maintenance fees and free MoneyPass™ ATM access.
  • Rewards debit card earns 1 point for every $2 spent, to help you accumulate rewards.
  • High deposit limits accommodate balances up to $5 million, surpassing many competitors.
  • No QuickBooks integration, no cash deposits, and limited support for Android users.
  • Competitors like Bluevine and Novo offer higher APY, cash deposits, and additional features like virtual cards.

I first came across Amex’s new business checking account in a private Facebook group post back in 2023. While the company has been around for decades, American Express previously only serviced credit card and travel-related offers. Now, they’ve got a checking account that earns interest on up to $500K with enticing introductory bonus points for new accounts. 

So, let’s explore the new offer in full, and find out what you need to know whether this is the right checking account for your business. 

Here’s what’s in store: 

  • Amex Company Overview
  • The Amex Business Checking Account
    • The Introductory Bonus
    • Amex Checking Account Features
    • What is the Downside of American Express Checking?
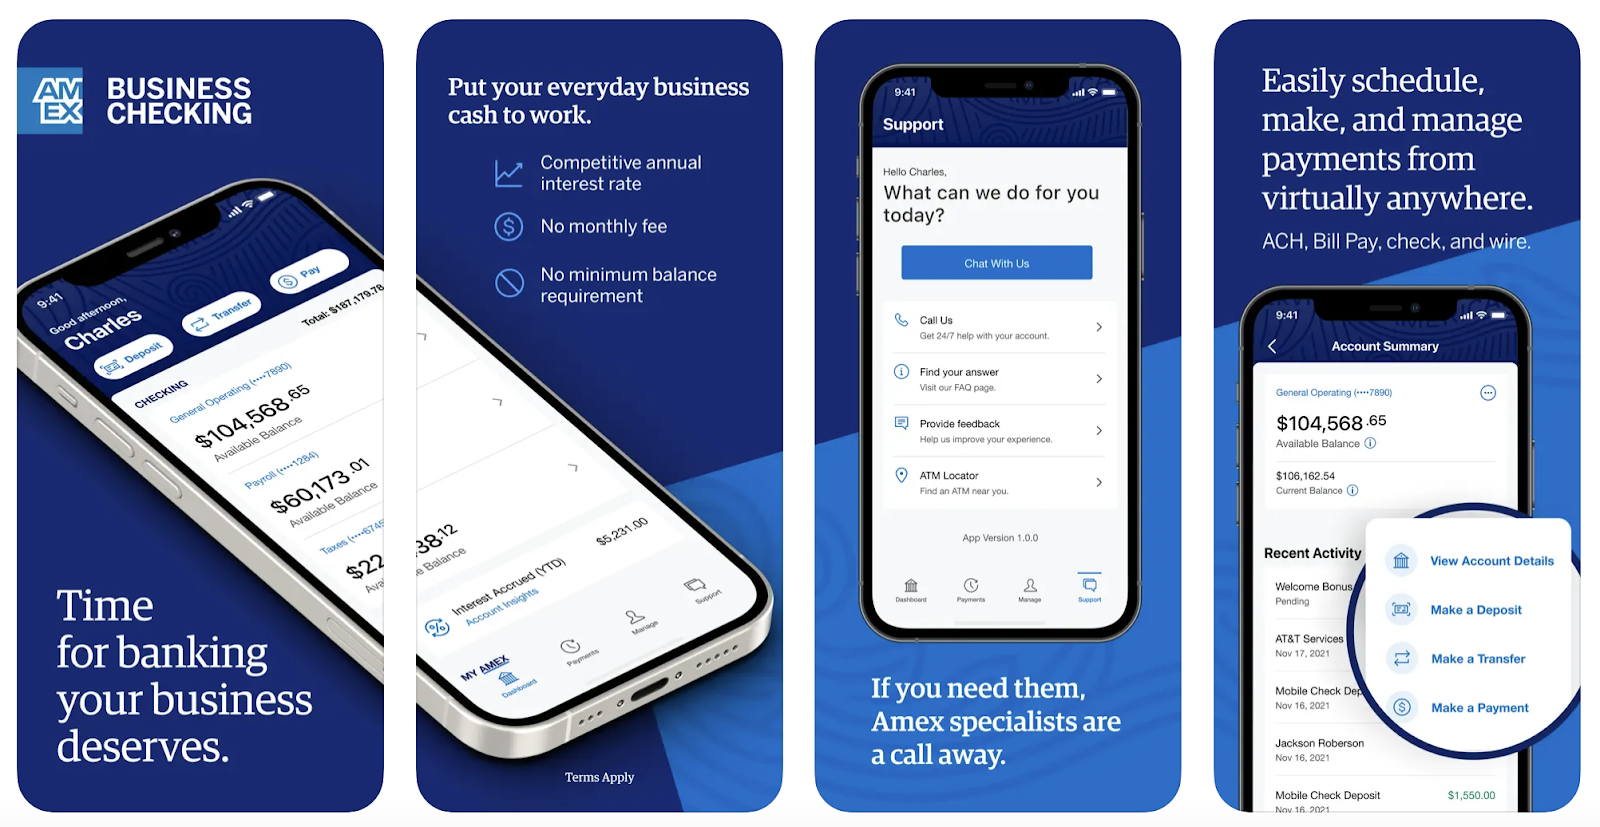
    • Amex Business Checking App
  • Amex Business Checking Competitor Overview
  • Frequently Asked Questions
  • The Takeaway

So, let’s get to it! 

Amex Company Overview

Is Amex good for a business checking account?

So, why is Amex so popular? Well, this NY-based institution has been around since 1850, servicing consumer and business credit, expense management, and travel products. The founders were Henry Wells, Irene Tserkovny, John Butterfield, and William Fargo. 

Do any of these names sound familiar? As you might have guessed while reading (if you didn’t already know), Butterfield, Wells, and Fargo are the same people who founded Wells Fargo in the mid-1800s.    

While big banks don’t tend to inspire everyone’s confidence, the fact that the company has been around for over a century is telling. Amex is a trusted name in American finance, and the odds are that they’re going to stick around for many years to come; this is important in an age where new, cutting-edge financial products are in and out of existence after a year or two in the marketplace. 

Currently, American Express is a publicly-traded, for-profit global financial services company led by CEO Stephen Squeri. They’re best known for their credit cards, charge cards, and traveler’s checks. Lately, their checking accounts are quickly rising in reputation.   

You might also like: A Complete, Unfiltered Amex Business Gold Card Review

The Amex Business Checking Account 

In short, an Amex business account gives you the opportunity to earn interest and introductory rewards with free, online checking. Since every business needs a bank account, it may seem like you’ve nothing to lose by signing up.  

And, while there are some great features with Amex business checking, there are some missing features…not all contemporary online checking accounts are the same. Read everything below to weigh the pros and cons for yourself. 

The Introductory Bonus

American Express business checking login

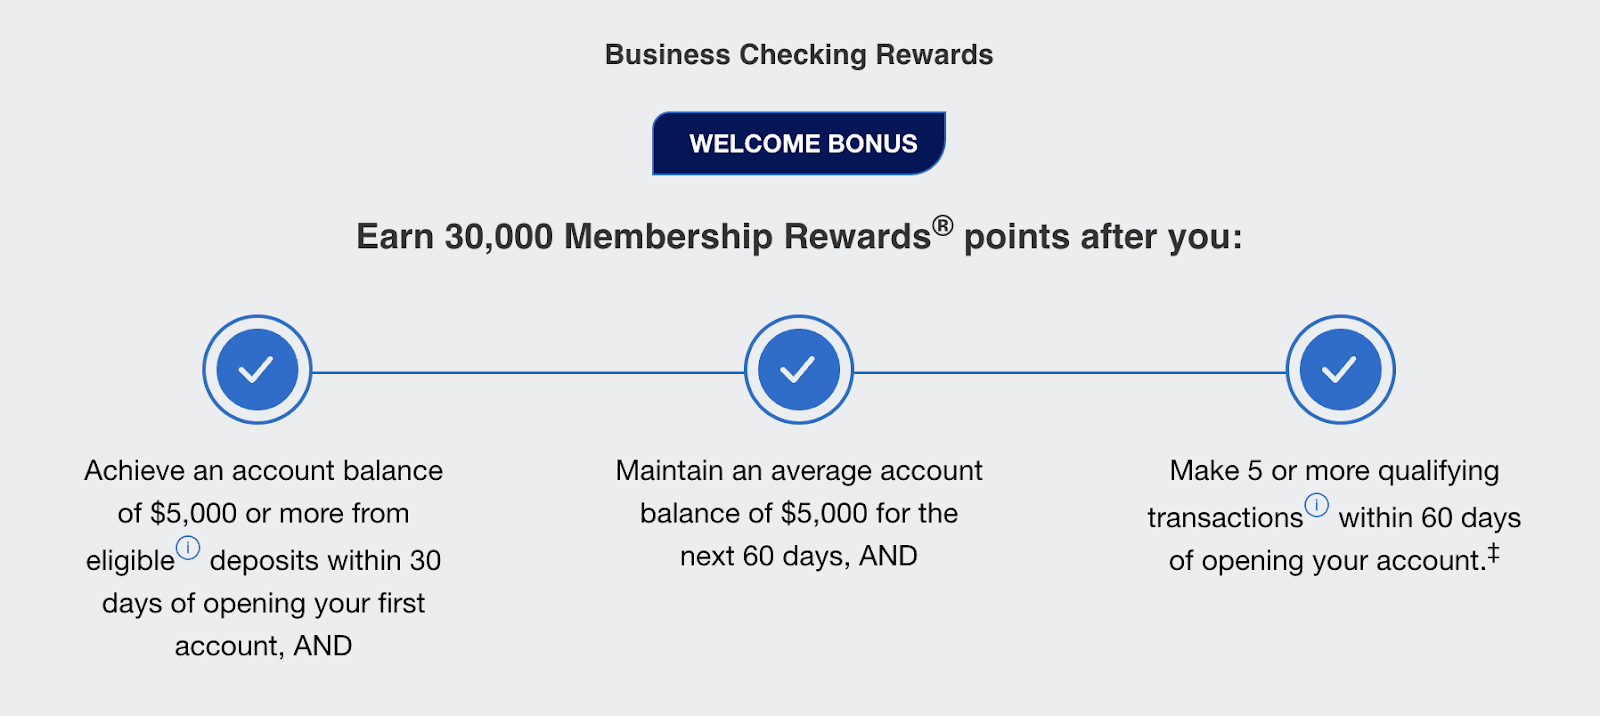
One of the most hyped benefits of an Amex business checking account is the intro offer. Currently, they’re giving away 30K rewards points (worth about $300 total) with qualifying activities on a new account. And, this offer has been in play since 2023, so they may stick with it.

Here’s what you’ll have to achieve to get the bonus points: 

  • Account balance of $5K within 30 days of opening your account
  • An average account balance of $5K for the following 60 days
  • 5 or more “qualifying transactions” within 60 days of opening your account

If you apply, are approved, and meet these requirements, the points should be distributed to your account at the end of the 90-day wait. Keep in mind that the intro offer is likely to change — some people got in when they promised 20K points and others were offered 60K. 

So, what are “qualifying transactions?” 

✅ Mobile deposits

✅ Check deposits by mail

✅ Electronic/online transactions (ACH, wire, and bill payments)

And, what are not qualifying transactions? 

❌ Business debit card transactions

❌ Deposits using the “Redeem for Deposits” feature

We’ve seen other brands like Wells Fargo and Chase offer anywhere from $200 to $500 for new individual and business accounts with qualifying activities. The key difference with this offer is that Amex is delivering an online bank account, which is best compared to offers like Bluevine and Novo.  

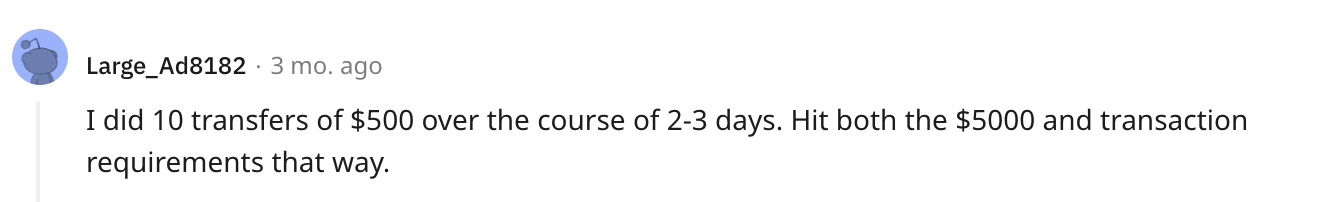
You might be wondering how hard it would be to get 5 or more qualifying transactions within 60 days (if this won’t be your primary account), and the answer is, ‘it would be pretty easy.’

Amex business checking Reddit

All you would have to do is divide your deposit amount requirement ($5K) by the number of transactions you need (5) and make the appropriate number of mobile, check, or ACH payments into your new account (5 X $1K deposits) within the first month of opening the account. 

But, don’t get ahead of yourself trying to work the system…you might actually decide to keep your account once you get in and realize the benefits. 

Amex Checking Account Features

Does Amex have a limit?

In a word, Amex checking accounts have some pretty cool benefits: 

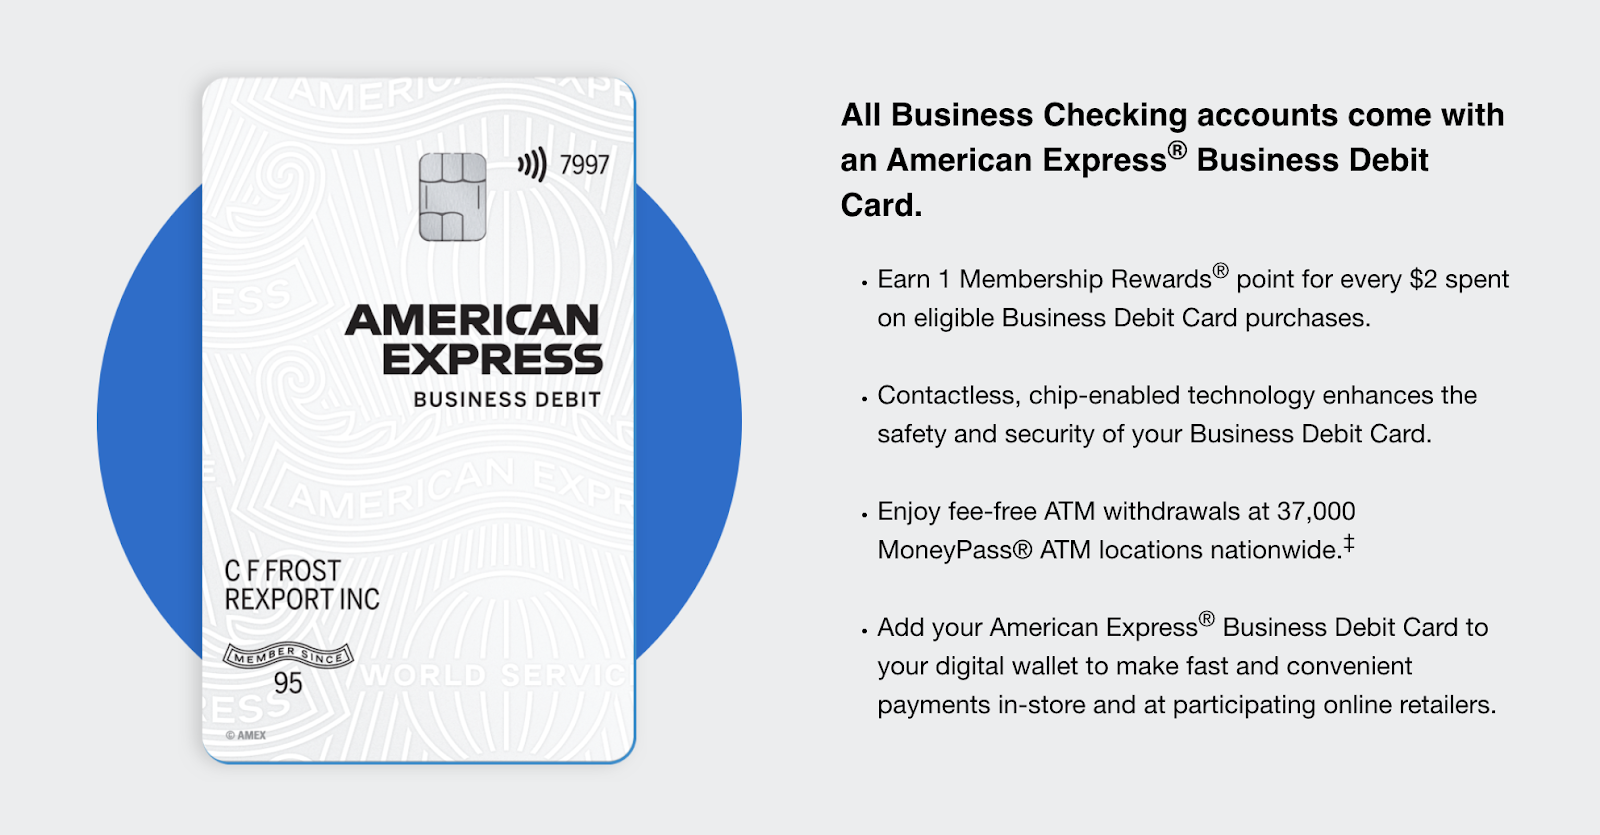
  • Earn interest on checking account balance
  • Get 1 Amex point for every $2 spent
  • Pay no monthly maintenance fees
  • Gain fee-free MoneyPass™ access 
  • Take advantage of high deposit limits
  • Get free, fast outgoing ACH 
  • Send free eChecks and use fee-free checkbooks
  • Keep your Amex MR points alive

Just for fun, let’s explore the offer a bit more in-depth. 

In addition to the intro points offer, Amex business checking accounts earn 1.3% variable APY on balances up to $500K.

So, you have a chance to earn a bit — an account with an average balance of $5K could be earning $65 each month. While most savings accounts offer the opportunity to earn, this isn’t a standard feature with checking accounts. With that said, Bluevine offers a 2% fixed APY on accounts that carry up to $100K, so that part of their offer outshines Amex. 

Amex is the only popular online bank account with a rewards debit card that earns 1 point for every $2 spent. If you use your debit card to spend $200, you can earn $1. This may not sound like a lot, but rewards can add up quickly.  

Plus, you’ll pay no monthly maintenance fees for an Amex business checking account. While most business bank accounts charge anywhere from $10 — like NorthOne, for example — to $30 per month, Amex checking is free (note: so are Novo and Bluevine’s offers).   

With an Amex business checking account, you’ll incur no ATM fees within the MoneyPass™ network. You might, however, have to pay third-party fees. Note that Novo bank refunds third-party ATM fees at the end of each billing cycle, though there’s no telling how long this reimbursement offer will last since the company is in the earlier stages.  

Furthermore, they have high deposit limits, which we can’t say for other online bank accounts and neobanks; most online checking offers are capped at $1K or $5K per day while Amex won’t cap your deposits — You can keep up to $5 million in your account. 

And, you’ll never pay the typical fees you see with business checking accounts. So far, users have been satisfied with outgoing ACH, citing that it’s fast (usually same-day) and free to send money to external accounts. Checks are also free, and there are no fees for NSF, stop pay, billing inquiries, replacement cards, late fees, or admin processing. 

Finally, you can save your existing Amex reward points, even if you plan to close out credit card accounts to bypass annual fees. Automatically redeem existing MR points in your Amex checking account. 

All-in-all, an Amex checking account could save you some money while it expands opportunities to earn and grow your business. 

What is the Downside of American Express Checking? 

As with all financial offers, there are some downsides for Amex checking account holders. 

One of the most glaring issues for me is that there is no Quickbooks integration with an Amex checking account yet. However, you can connect an Amex account to Quickbooks online. 🤷

Furthermore, if you want to deposit cash, you’ll first have to exchange it for a money order or check, then transfer the funds to your account. No cash deposits could be extremely inconvenient for cash businesses. You can withdraw cash from an Amex account via ATM using your debit card. 

And, as with all online bank accounts, you won’t be able to walk into a branch — they don’t exist. If this is important to you, choose a local branch to open your business bank account. 

There’s also a rumor floating around that Amex checking accounts don’t offer wire transfers, but it isn’t true; incoming wires are free while outgoing wire transfers cost $20. And, this price is pretty typical.

Where Amex checking accounts actually fall short is in the fact that they facilitate no INTERNATIONAL wire transfers. If you really want to go with Amex, you can look into solutions from Wise or Plastiq for this — these platforms are more user-friendly than your typical wire process anyway. 

Finally, if your business credit card is serviced through Amex, and you have any issues that arise at no fault of your own (overdrafts, chargebacks, etc.), these could negatively impact your credit accounts. 

Some business owners opt to use different institutions for business credit and business banking because of this, though I recommend a different approach. 

Amex Business Checking App 

Amex business checking app

The Amex business checking app is only available on iOS (they do have an Android app for credit accounts), so any Android users will need to access their account from another device. 

As a Google Play person myself, this seems a bit silly to me — there are lots of apps available for Apple while unavailable on Android, but I would think an online banking account would see the importance of serving customers across all devices.

But, if you’re an iOS user, keep reading… 

The Amex business checking app allows you to create and schedule payments on the go, and it’s pretty slick. In addition to the usual app features like mobile deposits, transfers, and payments, you can manage and redeem Amex rewards points.  

I mentioned this previously, but you may have missed it: existing Amex rewards members’ rewards points are automatically added to your checking account. I think this is pretty cool. 

With this said, the app doesn’t have the best user ratings, so I have a quick tip for ya: if you find that your two-factor authentication is wonky, delete and reinstall the app — this seems to be solving the issue for existing app users (Plus, my bet is that the developers are getting this worked out as we speak). 

Amex Business Checking Competitor Overview

The two brands with the closest offers to Amex’s current small business checking are Novo Bank and Bluevine. So, let’s look at how these three accounts stack up next to one another:

Amex Business Checking Competitors — Amex vs Bluevine vs Novo

The most enticing competitive advantage is that Amex currently has the highest deposit limit. If you’re earning more than $5K via a website, app, or your POS, then neither Novo nor Bluevine will work for you — In this case, Amex would be a natural choice. 

If you’re earning a little less, Bluevine might give you the opportunity to earn more on your monthly balance with 2% interest vs 1.3% with Amex; plus, they are the only solution that offers cash deposits. 

And, Novo’s got the monopoly on virtual cards, reimbursed third-party ATM fees, and built-in invoicing (for now). 

Keep in mind, you don’t have to choose an online business checking account. In fact, I typically recommend small business owners bank with small, local community banks for the best business credit opportunities (among additional interpersonal benefits). 

Recommended: ​​3 Best Credit Unions for Small Business Banking

Frequently Asked Questions

Does Amex business checking pull credit?

No. When you apply for an Amex business checking account, you’ll be shown a consumer reporting disclaimer. This does not mean that opening an account will affect your credit score. 

Does American Express business checking use Zelle?

No. Most business checking accounts are incompatible with Zelle. However, Bank of America and PNC Bank might be Zelle-compatible. Please check with the Banks for an up-to-date answer.

Can you use Venmo with American Express?

Yes! You can use the Send & Split™ feature in the Amex app to send money with Venmo.  

How do I deposit cash into my American Express business checking account?

Unfortunately, American Express doesn’t support cash deposits. So, you will have to somehow convert any cash into a check or money order to make a deposit into an Amex checking account. 

How much is 60K Amex points worth?

60,000 Amex points are worth roughly $600. Though, they can be redeemed for more through American Express’ promotional and travel offers. 

Final Takeaway: Is Amex Worth the Hype?

If you’re an Android user, you run a cash business, or you expect a Quickbooks integration with your account, American Express might not be your top choice for business checking—But, it does have some pretty cool features. 

If you’ll be depositing tens of thousands of dollars into your account, Amex is clearly the best online banking option, though I still recommend local community banks and credit unions where you can walk into a branch and build a relationship with the banker. 

If you want to learn how to obtain up to $100K in business credit in as few as 30 days, join Business Credit Workshop today. 

Can You Open a SoFi Business Account? SoFi at Work Review

By Joe

SoFi Business Account SoFi at Work

So, you’re looking to open a business account…No doubt SoFi® has come up on your radar, especially if you already have a personal account with them. Maybe you’re launching a new company or you’ve been operating awhile and need financial products. 

Either way, you’re here because you wanna know what business services you can get. Well, SoFi® doesn’t offer traditional business checking or savings accounts, but they do have a cool product called SoFi at Work®. And, they offer business funding — Let’s talk about both. 

This is what’s in store: 

  • What is SoFi®?
    • Company Overview
  • SoFi at Work® Features
    • 1. Student Loan Verification & Repayment
    • 2. 529 College Savings Program
    • 3. Emergency Vault™ Savings
    • 4. Education Assistance Benefits
  • SoFi® Small Business Funding
    • Application Requirements
  • Frequently Asked Questions?
  • Final Takeaway

Now, let’s get poppin! 

What is SoFi®? 

SoFi business account

SoFi® is a bank known for its personal checking, savings, and loans. With personal loans ranging from $5,000 to $100,000 and fixed rates from 8.99% APR to 29.49% APR, members can consolidate high-rate debt or fund projects. But, the institution offers a much wider variety of financial products.

SoFi® personal loans come with no fees—no origination fees, late fees, or prepayment penalties—and flexible repayment terms from 2 to 7 years. Plus, with options for student loan refinancing, private student loans, mortgages, investments, insurance, and more, SoFi® provides broad solutions to meet a spectrum of financial needs. 

Today, we’re going to focus on their business offers: SoFi at Work® and small business funding.  

You might also like: An Unbiased LendingClub Review for Borrowers and Investors 

Company Overview

SoFi business account review

Before we explore how you can leverage SoFi® as a business owner. Let’s learn a bit more about the company itself. 

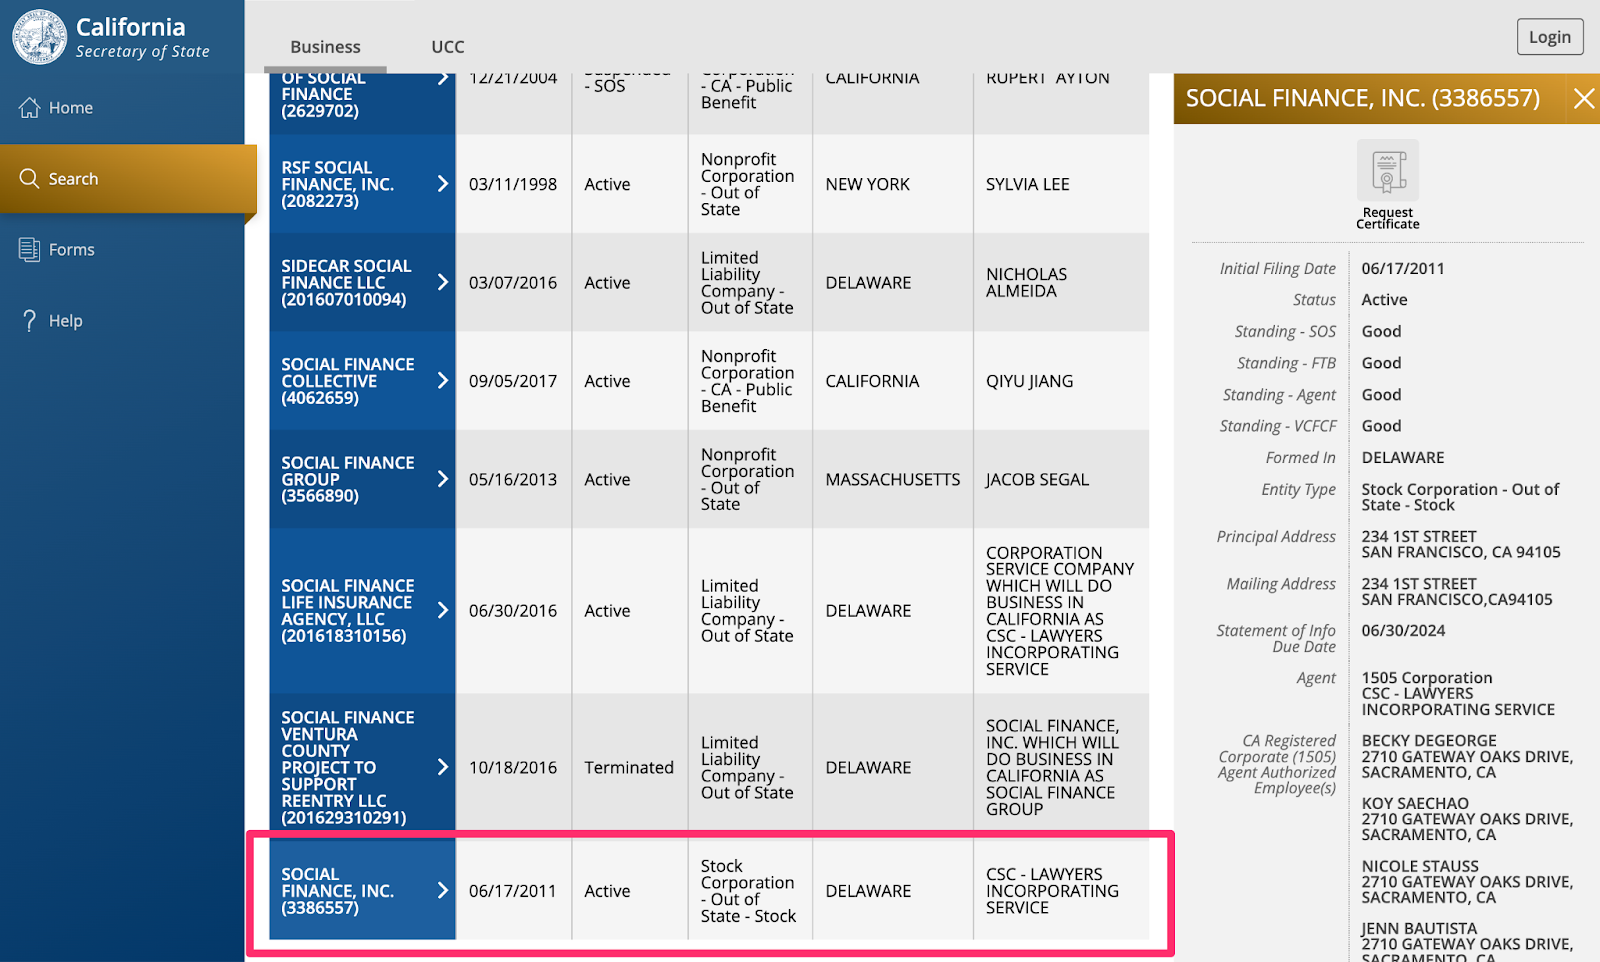
SoFi®, aka Social Finance, Inc., is a San Francisco-based, public, for-profit company with headquarters scattered across the U.S. The company was founded in 2011 by Mike Cagney, Dan Macklin, James Finnigan, and Ian Brady. At the time, these guys were graduate students at Stanford. 

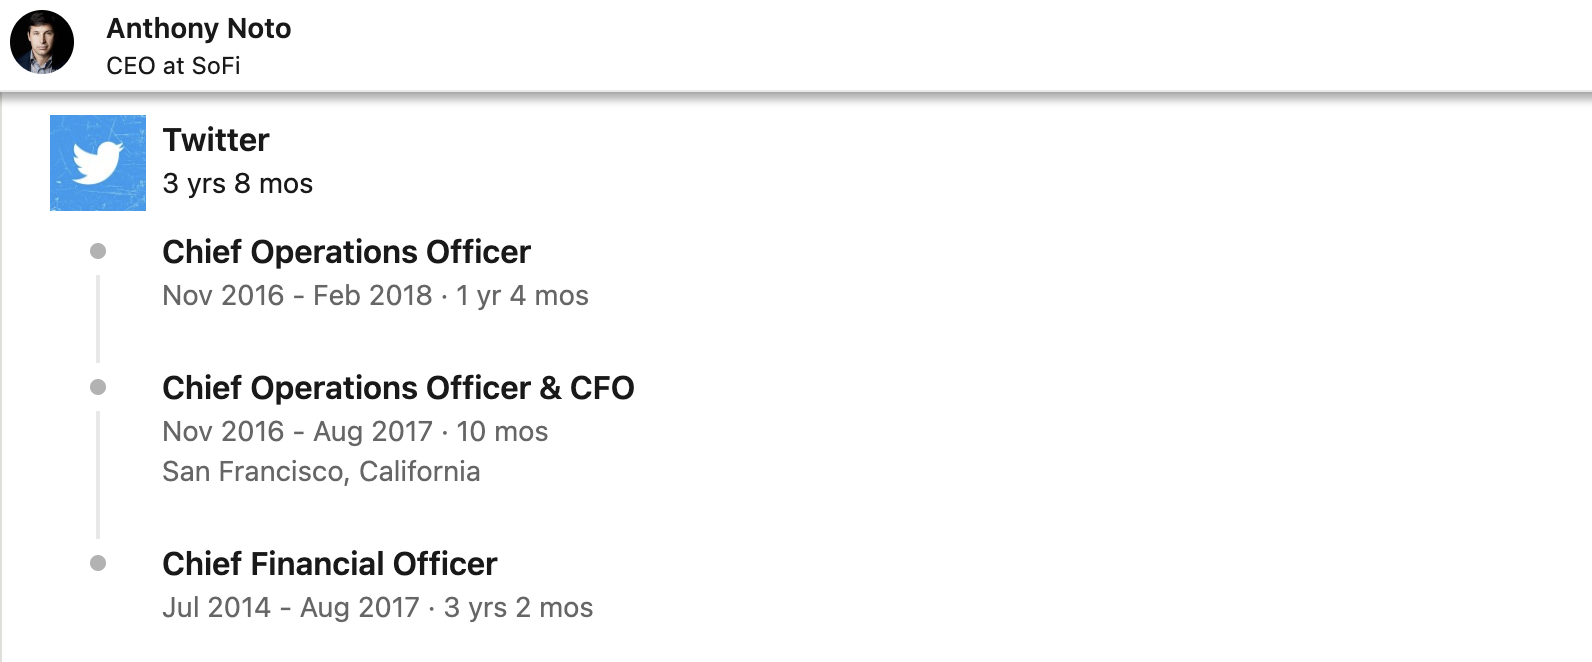
The current CEO of SoFi® is Anthony Noto, who served as the Chief Operations Officer of Twitter until 2018. Before that, he was the Co-Head of Global TMT Investment Banking at Goldman Sachs—The man is experienced in the right ways. 

Is SoFi a real bank account?

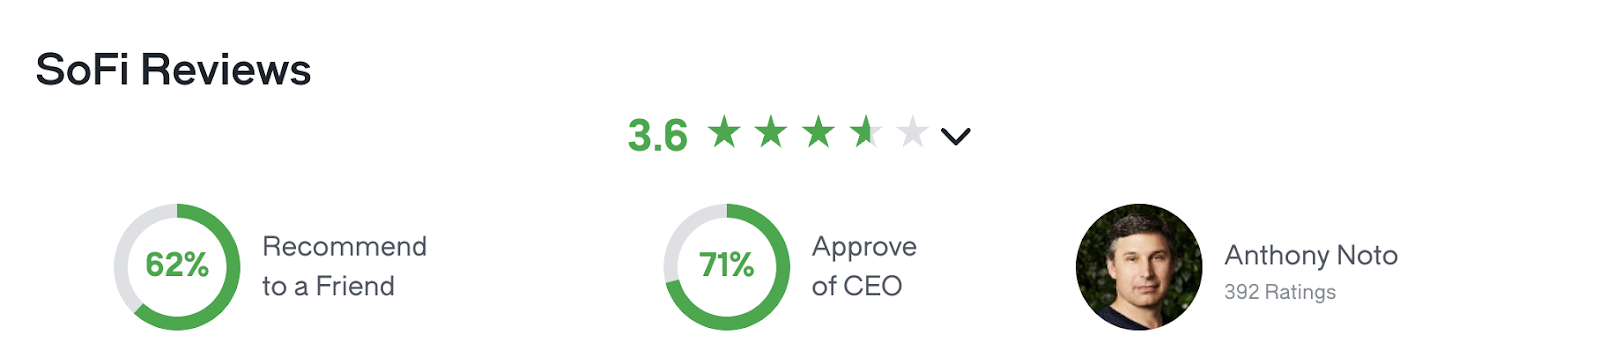
According to Glassdoor, a majority of employees are satisfied with the company. 62% of employees would recommend them to a friend, and 77% approve of Noto as the CEO. While this isn’t the most enthusiastic rating I’ve seen on Glassdoor, at 3.6 stars, the team seems to have a generally positive experience in-house…this says a lot.

How credible is SoFi?

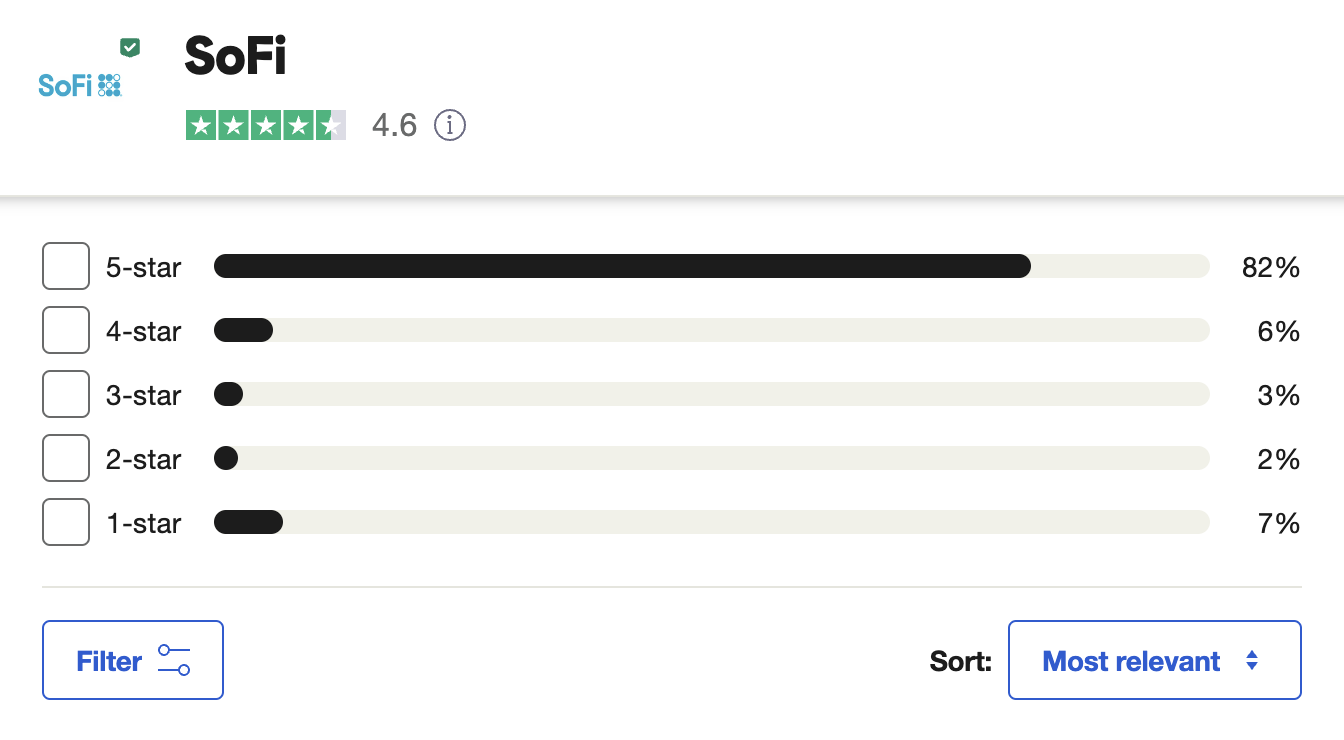
SoFi® is verified with a 4.6-star rating on Trustpilot, which is impressive for a financial offer. 82% of the more than 8,104 reviewers give the bank 5 stars. According to this, account holders are even more satisfied with the platform than staff, which is everything. 

Open a sofi business account

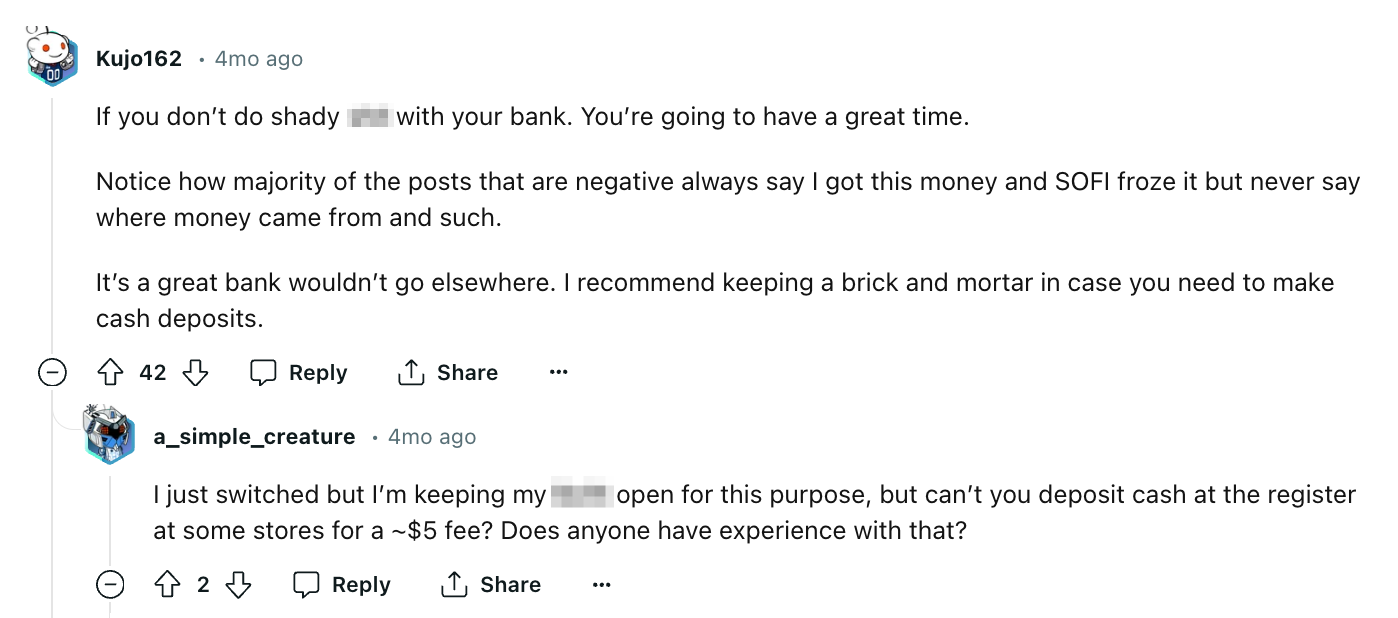
Some loyal members will go so far as to say the only people leaving negative reviews of SoFi® are those who may be doing shady trade with their account. But, one legitimate potential downside is that it’s an online-only bank, which usually infers limits on cash deposits. In sum, even Redditors have nice things to say. 

sofi business account reddit

Now, depending on how ethically-conscious you are, you may want to know that SoFi® filed a lawsuit against the Department of Education in March 2023. According to NASFAA, Their stance was that the Biden administration’s extended pause on student loan repayment was unlawful and caused harm to their business. However, they withdrew the lawsuit when the bipartisan ceiling debt deal was signed into place and a clear timeline for payment reopening was presented.  

All in all, I think SoFi® appears to be a great bank for personal financial products. But, I always recommend you do your due diligence before you sign-on to any offer. Now, let’s explore exactly what they can offer small business owners.