• Home
  • Free Funding Guide
  • What We Offer
    • Products
    • Services
    • Free Guide
  • About Us
  • Contact
  • Sign Up

  • Ask Joe Any Question!
  • Business Credit Cards
  • Business Line of Credit
  • Topics

Behind the Scenes of Become.co: A Comprehensive Review

By Joe

Become.co review

Become.co – aka “Become” – is a relatively new player in the online lending field, offering financial solutions for owners looking to optimize profits and obtain funding to grow their business. 

The offer has received mostly positive reviews with a Trustpilot rating of 4.6 (believe it or not, this is impressive for a financial offer). Users have praised their services, highlighting quick and effective funding solutions. They’ve also mentioned friendly and professional staff, as well as seamless processes.

Become seems to go above and beyond traditional business lenders, but is the offer real or hype? 

That’s what I intend to explain (in detail). Let’s explore everything Become might be able to help you achieve, and see how they stack up next to competitors. 

Here’s what’s in store: 

  • What is Become.co?
  • What Type of Business Loan Can You Get Through Become?
    • How to Qualify for Funding
  • eCommerce Loans
    • The BeProfit™ App for Online Sellers
  • Industry-Specific Loans
  • LendingScore™ & MatchScore™
  • Frequently Asked Questions
  • Conclusion

Let’s begin! 

What is Become.co? 

Become was founded in 2016 by Amir Leitersdorf, Daniel Katz, Eden Amirav, Guy Zipori, Iri Amirav, Ofer Ariel, and Uri Sittan. The company is based in San Mateo, California, and has received Series A funding totaling $15.2 million. 

The offer is an end-to-end financial optimization platform and loan marketplace for small and medium-sized businesses (SMBs). In a word, it uses advanced algorithms to provide customized funding offers to SMBs, helping them scale and grow their businesses.
Become.co login

We’ve seen comparable business funding algorithms before – from companies like Divvy (credit card), Fundbox (loans/credit lines), and Lendio (funding marketplace), to name a few. But, Become doesn’t just use technology to match business owners with lenders.

Become goes a bit farther with their offer, and gives business owners access to solutions that help them scale: 

  • A vast array of business loans from various lenders
  • Transparent LendingScore™ dashboard
  • MatchScore™ to pair SMBs with lenders 
  • Automated application review
  • The BeProfit app (to help track and analyze eCommerce profits)

Let’s peek behind the curtain at the solutions you might want to take advantage of. 

Recommended: 6 Best Fintech Credit Cards to Apply for (Consumer & Business)  

What Type of Business Loan Can You Match With Through Become? 

As I said, Become can get you access to an array of loans. But, in straightforward terms, what’s this mean for you? 

Here are the types of business loans Become can match you with:  

  • Commercial vehicle loans
  • Startup business loans
  • Asset-based loans
  • SBA loans
  • Lines of credit 
  • Business equipment loans
  • Unsecured business loans
  • Invoice factoring & merchant cash advances (MCAs)

As you first dive-in to the offer, it appears that Become is like a Credit Karma for business (though they’ve referred to themselves as the “Tinder” for business). 

You might also like: Torro Business Funding Review: Is This “Zero Hassle” Offer Legit?

How to Qualify for Funding

In sum, Become wants to see your credit score (it seems that they use their own proprietary LendingScore™ as opposed to Paydex or FICO), time in business, and revenue. 

Keep in mind that since Become works with so many lenders, a poor credit score won’t necessarily disqualify you from obtaining funding. But, it might limit you to certain types of loans (probably high-interest funding like MCAs or invoice factoring). 

If you’re based in America, you’ll need a business that’s been operational for at least 3 months. This qualification doesn’t seem to be negotiable, and the only way around it would be a creative solution like purchasing a shelf company. 

Finally, Become wants to see that your business brings in an average of $5K in revenue per month.

Now, if you don’t qualify for funding through the platform, you will be informed about why, and shown how you might improve your business health and improve your LendingScore.™  

eCommerce Loans 

Working in the eCommerce space? If you sell on Amazon or Shopify, you can connect your store to the platform (no paperwork required) and find out if you qualify for funding – you can potentially receive up to $100K within a day. 

You may also need to connect to your online advertising channels to rate your marketing efforts. 

Currently, Become partners with Kapitus, Everlasting Capital, and Pearl Capital to match funding offers with online sellers who qualify. 

Here’s what you should know about these partners:

  • Kapitus requires a 625 credit score, 2+ years in business, and $250K annual revenue 
  • Everlasting Capital primarily offers MCAs & equipment financing, which are likely high-interest
  • Pearl Capital is a technology partner that probably makes Become’s business analysis possible
Become review

This should give you an idea whether or not it’s worth applying for an eCommerce loan through Become – Keep in mind that the platform will show you personalized areas for improvement if you aren’t currently eligible for financing through one of their partners. 

The BeProfit™ App for Online Sellers  

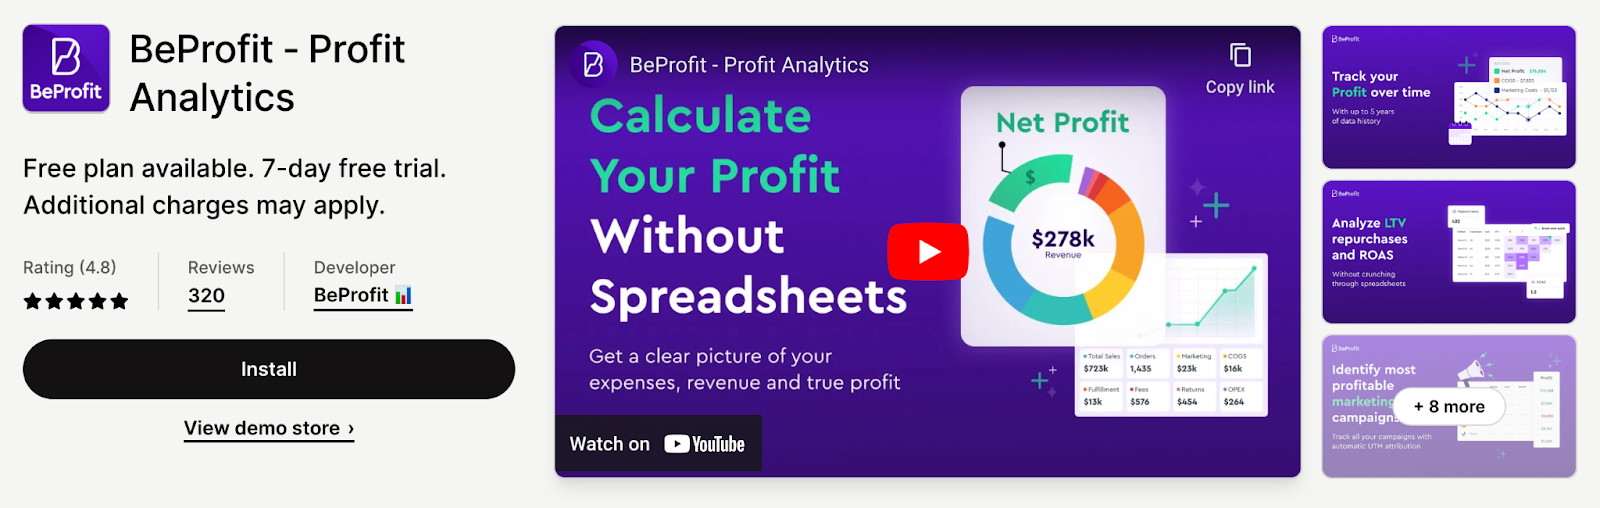
Next, let me introduce BeProfit: It’s an app that helps you dig deep into your online sales profits, so you’re not just guessing about your financial health.
BeProfit app

BeProfit gets all your expenses, from shipping to discounts, neatly organized in one place. You can quickly spot what’s boosting your profit and what’s dragging it down, so you can make smart decisions.

Plus, it’s super user-friendly. No need to drown in complicated numbers and reports. BeProfit simplifies everything into easy-to-understand reports, giving you more time to focus on growing your business.

Now, is it relevant or right for you? 

BeProfit is available on Shopify, Woo, and Amazon, and costs from $20 to $2000 per month to use (though you can use it for free on Shopify if you have fewer than 5 monthly orders).  

Note: All plans include features related to shipping, discount, products, inventory, marketing, and returns. 

Monthly PriceYearly PriceOrdersShopsFeatures
Basic$20$2402001Profit Dashboard, Custom Expenses 
Advanced$60$7206001Advanced Analytics, 3 Team Members
Pro$120$144012001Retention Analytics, 5 Team Members
Plus (Custom)Starts at $200–UnlimitedUnlimitedDeep Analytics, VIP Support

Please note that the prices mentioned are subject to change, and it’s always a good idea to check the latest pricing for the most up-to-date information.

Industry-Specific Loans

While their offer for online sellers stands out, eCommerce isn’t the only niche that Become caters to. The company is all about helping businesses get the right funding they need. They offer tailored loans for various industries. 
Become business loan

Whether you’re in the hotel business, a contractor, a realtor, or even run a restaurant, they’ve got you covered. Construction companies can find financing options that suit their needs, and the same goes for trucking businesses. It’s like a one-stop-shop for business funding.

What’s cool is that they use technology to match you with the best lender for your specific industry. So, you’re not dealing with a generic loan but one that understands the challenges and opportunities in your field.

Plus, they make it easy to apply, and you can compare offers to choose what works best for your business. So, if you’re in one of these industries and need financing, it might be worth checking out – It’s all about making business funding as simple as walking into a convenience store.

LendingScore™ & MatchScore™  

Before we wrap up, let’s get a quick overview of how LendingScore and MatchScore work.

LendingScore is like a financial fitness tracker for your business. It delves into your financial details, analyzing your credit, income, and history to determine how prepared you are for a loan. Instead of filling out numerous loan applications, LendingScore™ streamlines the process by allowing you to submit just one. Then, it takes on the role of matchmaker, connecting you with top lenders who are more likely to approve your loan application. It’s akin to having a personal coach for your business finances, helping you navigate the world of loans with ease.

On the other hand, MatchScore is your loan cupid. This tool takes your business’s financial profile and starts swiping right on lenders who are a perfect fit. Think of it as a dating app, but for loans! Instead of you scouring the market for lenders, MatchScore does the legwork for you. Its primary goal is to find the loan that aligns perfectly with your business needs. No more blind dates with banks – MatchScore ensures that you and the lender are a match made in financial heaven.

In summary, LendingScore assesses your loan readiness, while MatchScore acts as your personal loan matchmaker. With these handy tools, you can navigate the loan application process effortlessly and discover the ideal financing option that suits your business like a glove. 

Frequently Asked Questions

Can you get a loan for eCommerce?

Yes, you can get a loan for your eCommerce business. Many lenders offer small business loans for eCommerce, like Become and Stripe Capital.

Can you do eCommerce with no money down?

It’s tough but possible. Consider options like drop shipping or print-on-demand, where you don’t need upfront funds for inventory. And, some people who don’t want to pay to host a website, sell manually on Instagram, Facebook Marketplace, and Craigslist.

How to get a loan to start an eCommerce business?

To get an eCommerce loan, prepare a solid business plan, demonstrate your ability to repay, and find a lender that fits your needs.

How much money do you need for eCommerce?

The amount varies, depending on your niche and plans. Costs can include website development, inventory, and marketing.

Do you need a lot of money to start eCommerce?

Not necessarily. Many start small and reinvest profits to grow over time. Careful planning can help you start with a lean budget.

Conclusion

So, is Become the real deal or just a bunch of hype? 

My opinion: it appears to be a promising financial optimization and funding platform for SMBs – Their tailored funding solutions and the positive Trustpilot reviews are strong indicators of their effectiveness in helping businesses grow.

However, as with any financial service, you need to do your due diligence and thoroughly assess whether Become’s offer aligns with your needs, and if it’s necessary. 

So, do you prefer convenience or control – In my opinion, Become is one of the most convenient business funding offers out there, but it doesn’t give SMBs the ultimate control over their finances. 

Would you be better off to raise money through Kickstarter, explore an offer like Fund&Grow or Lendcred…or build your business credit and hand-pick the offers you want to apply for?  


Want to learn how to obtain up to $100K in business credit in as few as 30 days? Join Business Credit Workshop today.
6 Best Fintech Credit Cards to Apply for (Consumer & Business)

By Joe

best fintech credit card

Are you an individual considering a slick, new way to use credit? Or, a business owner looking to supercharge your finances with the perfect fintech credit card? Look no further! 

Here, we’ll dive into the exciting world of fintech credit cards, introducing you to top contenders like Divvy, CredAI (the illustrious Unicorn Card), Bluevine, Stripe, Ramp, and Brex – essentially free credit cards for everyone. 

Fintech is making credit cards weirder, but also a lot more fun…Whether you’re a student or seasoned entrepreneur, you can navigate the fintech card landscape, making sure you’re armed with the right knowledge to make the best decision for your situation. 

Here’s what’s in store: 

  • What is a Fintech Credit Card?
  • Explore the 6 Best Fintech Credit Cards
    • 1. Brex – Your Stealthy Fintech Ally
    • 2. Divvy – The Power Credit Card
    • 3. Bluevine – Fintech Business Checking & Credit
    • 4. Stripe Corporate Card – Cashback and More
    • 5. Ramp – Redefining Fintech Credit Cards
    • 6. Meet the Unicorn Card – CredAI
  • Frequently Asked Questions
  • Conclusion

Now, let’s get crackin! 

What is a Fintech Credit Card?

In simple terms, a fintech credit card combines the innovation of financial technology (fintech) with the convenience and power of credit cards. Fintech credit cards often come with unique features, competitive rates, and advanced tools that empower business owners to manage their finances efficiently.

Explore the 6 Best Fintech Credit Cards

Let’s take a closer look at some of the leading fintech credit cards that are revolutionizing the way individuals and business owners manage their finances. 

1. Brex – Your Stealthy Fintech Ally

fintech credit card processing

For: Businesses seeking a free corporate card

The Brex Corporate Card is an enticing choice for businesses seeking a no-personal-guarantee credit card with rewards. The card, issued through Brex’s financial operating system, caters to tech, life sciences, and eCommerce companies. I

t’s characterized by its absence of annual fees, interest charges, and personal credit checks. Instead, creditworthiness is determined based on the company’s likelihood to repay funds. Brex offers various account options, including Cash, Card, and Cash & Card, tailored to different financial needs.

The card boasts rewards such as up to 30K bonus points, points per dollar spent, and partner perks, including discounts with industry giants like AWS, Slack, and Google Ads. With a focus on expense management, the card offers real-time tracking tools, virtual cards, and expense automation. Qualification requires a US-based business with an EIN and a business bank account.

Learn more: Brex Card Review: Is This Corporate Card Offer Too Good to be True? 

2. Divvy – The Power Credit Card

fintech credit builder

For: Business owners

Divvy is not just a business credit card; it’s a comprehensive financial solution tailored for businesses of all sizes. With Divvy’s innovative features, you gain access to budgeting tools, virtual cards, and enticing rewards. 

This high-tech card isn’t just a piece of plastic; it’s a gateway to efficient expense management, AP automation, and seamless spending control. Divvy’s user-friendly platform empowers businesses to allocate budgets, set spending limits, and automate payment approvals. 

The virtual card feature adds an extra layer of security for online and high-risk transactions. Additionally, Divvy offers a tiered rewards system, giving you the opportunity to earn points for your spending habits. These points can be redeemed for travel, gift cards, statement credits, or cash back. 

While Divvy’s customer service receives mixed reviews, the platform’s help center and communication tools aim to provide comprehensive assistance. If you’re a business owner seeking advanced financial tools that streamline your operations and enhance your financial management, the Divvy credit card might just be the power boost your business needs.

Learn more: In-Depth Divvy Credit Card Review: Read This Before You Apply 

3. Bluevine – Fintech Business Checking & Credit 

fintech credit union

For: Small business owners

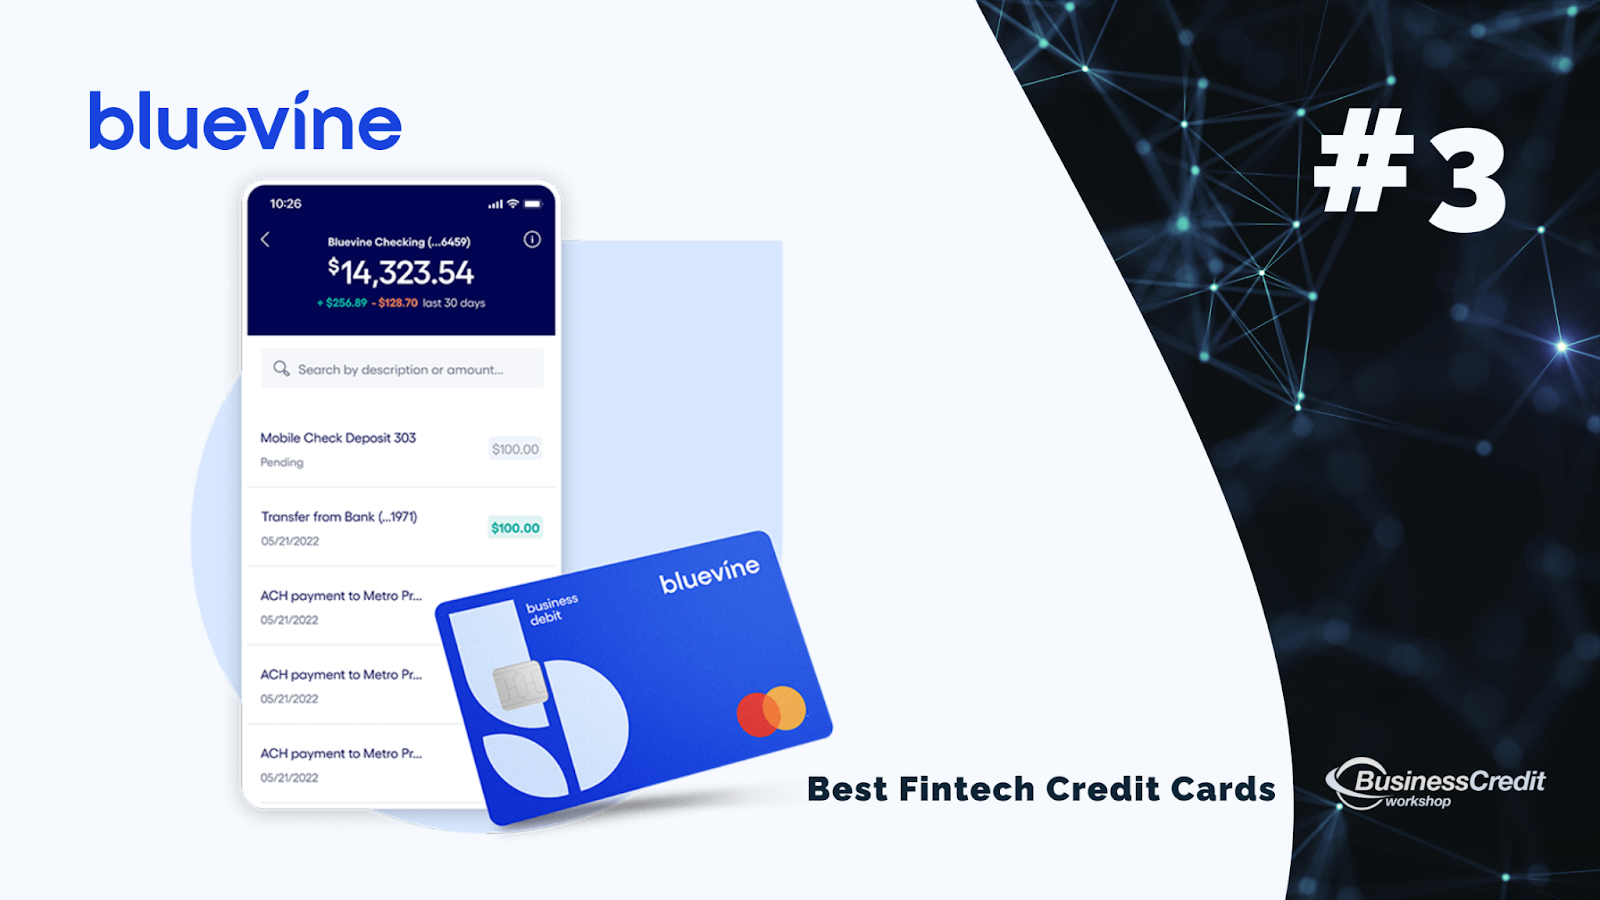
Bluevine presents a game-changing solution for small business owners with its high-yield free business checking account. With the ability to earn 50X the national average interest on balances up to $100K, this offering stands out in the financial landscape. 

The account comes with no monthly fees or minimum deposits, making it particularly appealing for digitally-focused businesses, freelancers, and service providers. While Bluevine’s single-account holder policy and minimum requirements to collect interest might not suit all businesses, the benefits are noteworthy. 

The platform’s integration of sub-accounts, dedicated account numbers, and unlimited fee-free transactions adds to its appeal. Bluevine’s strategic partnership with MoneyPass ATM network provides widespread access to surcharge-free ATMs. However, cash deposits made at ATMs incur a fee. The option to grant access to your account without sharing login credentials is a unique feature, enhancing collaboration with bookkeepers and accountants.

Moreover, Bluevine’s line of revolving credit up to $250K, coupled with competitive rates, can offer additional financial support for qualifying businesses. Overall, Bluevine’s innovative offerings make it a compelling choice for businesses that prioritize digital transactions and aim to make the most of their account balances.

Learn more: Bluevine Review: Free, High Yield Small Business Checking! Are They Serious? 

4. Stripe Corporate Card – Cashback and More

Stripe credit card

For: Business owners using Stripe Payments

The Stripe Corporate Card offers a compelling credit card option for existing Stripe Payments users. This card comes with unique advantages, including no fees, 0% interest, and an appealing 2% cashback on spending in top two categories. 

Notably, with a spending of $5,000 on the Stripe Corporate Card, users gain access to $50,000 in free transactions on the platform. Furthermore, the card allows users to customize their logo, create branded cards, and even originate credit cards for their customers. 

The card is available as both virtual and physical options, with the latter delivered within days. Stripe’s innovative approach is fueled by its primary revenue source—transaction fees for processing payments, allowing them to offer these enticing features. However, the card is exclusively available to existing Stripe Payments users, requiring those interested to request an invitation. 

In comparison to similar offerings like Brex, the Stripe Corporate Card stands out with its cashback rewards. Stripe’s broader suite of financial services and its reputation as a payment processor further contribute to the appeal of the Corporate Card. This review aims to provide a comprehensive overview for business owners seeking a flexible and rewarding credit card solution.

Learn more: Have You Heard About the Free Stripe Corporate Card Cashback Benefits? 

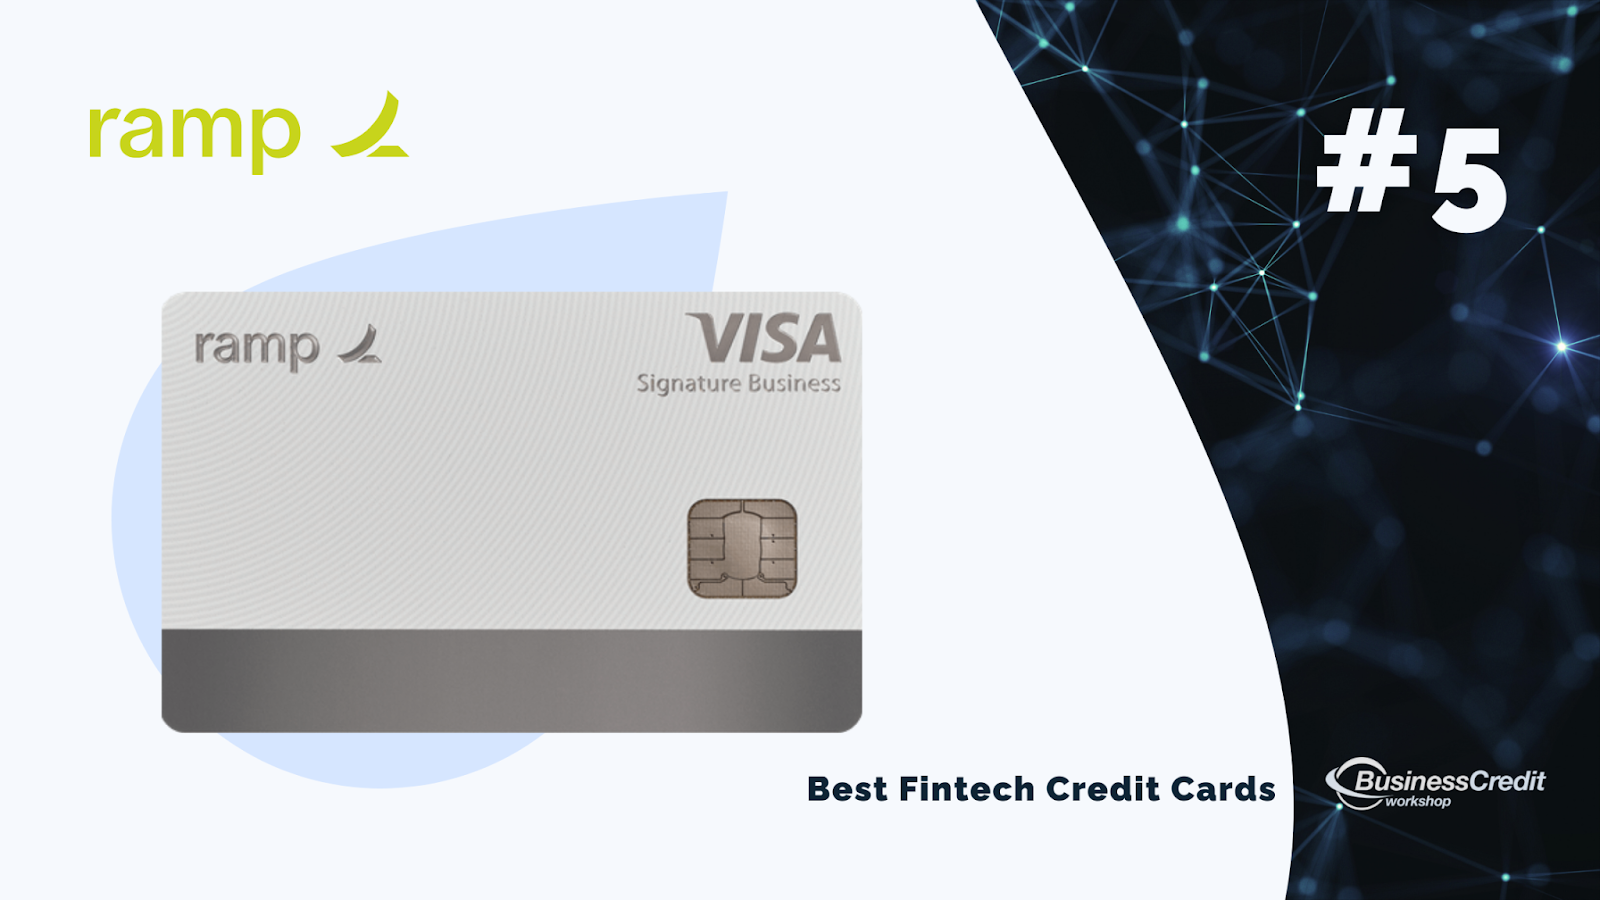
5. Ramp – Redefining Fintech Credit Cards

fintech debit card

For: Businesses seeking a frde corporate card

The Ramp Corporate Card, provided by Ramp Financial, is a corporate credit card designed to help businesses save money. With an emphasis on cost reduction and rewards, the card offers a range of features that can benefit businesses of various sizes. This review delves into the offerings and highlights of the Ramp Corporate Card.

The card allows businesses to issue unlimited staff cards, each with customizable spending limits. Additionally, Ramp’s algorithm identifies potential savings opportunities by analyzing spending patterns.

The Ramp Corporate Card comes with no foreign transaction fees, late fees, interest fees, or annual fees. It offers a flat 1.5% cashback on all spending, allowing businesses to earn rewards across various expense categories – Ramp has partnered with various service providers, offering potential savings of up to $175K for cardholders who leverage these partnerships. These rewards encompass a range of services, from advertising credits to discounts on software subscriptions.

While specific requirements are not fully transparent, Ramp’s underwriting process seems to consider factors such as business size, average monthly card spending, and the presence of over $250K in the business account.

Learn More: Ramp Credit Card Review: Is This the Corporate Card for Your Business? 

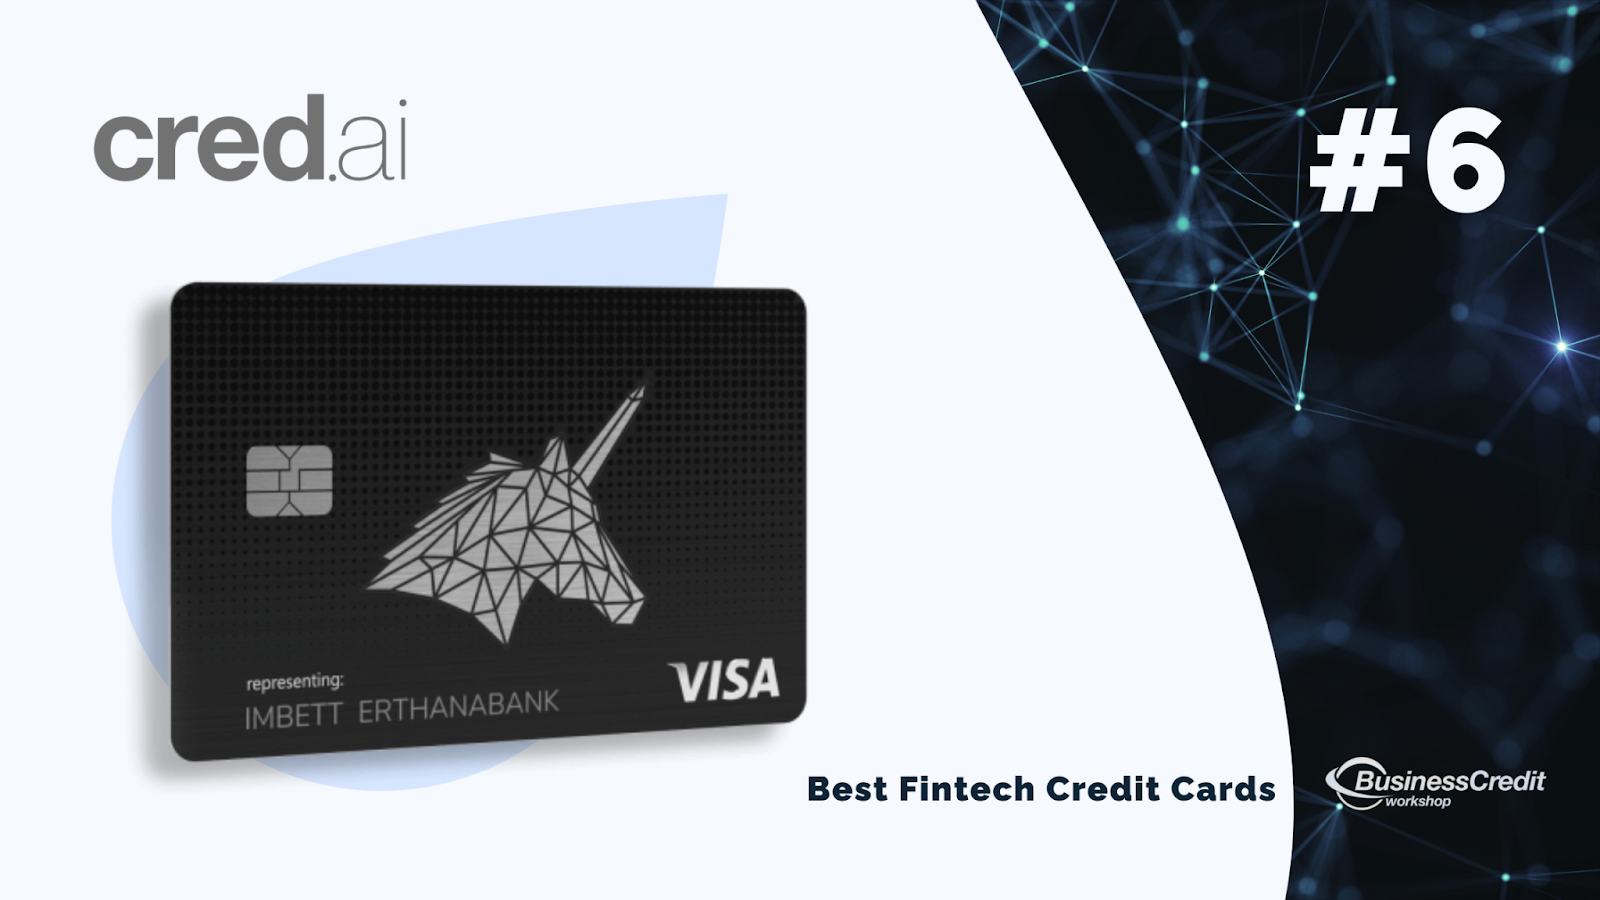
6. Meet the Unicorn Card – CredAI

fintech credit card

For: Consumers

Cred AI is not your average credit card – It’s a fintech sensation offering a premium, mobile, fee-free metal credit card that packs a punch. With innovative technology, Cred AI helps you manage finances, build credit, and guard against fraud. 

You can spend like a debit card while building your credit score, and access your paycheck up to two days early. The virtual Stealth Card™ and High-Security Mode™ provide added protection. Backed by AI, Cred AI learns your spending patterns and safeguards you from overspending. 

The Unicorn Card™ extends credit based on upfront deposits and pays off your monthly balance using those funds. With Cred AI, you’re not just getting a credit card; you’re getting a comprehensive financial tool that combines convenience, security, and credit-building opportunities.

Learn more: Cred AI Review: Are You Really Better Than Your Bank? 

→ You might also want to check out: They Do What?! Is the X1 Card Just a Bunch of Hype…? 

Frequently Asked Questions

What is a Stealth Card?

Operating under the radar with a minimalist design, a stealth card offers enhanced security by concealing sensitive information. Unlike traditional cards that display critical details like card numbers and CVVs, a stealth card keeps these particulars hidden until needed, thwarting potential security breaches and ensuring peace of mind during transactions.

How does fintech make money?

Fintech credit card companies’ revenue-generation strategies can include transaction fees incurred during financial activities and subscription models that offer premium services for a recurring fee. But, the key money-maker is strategic partnerships that cater to the unique financial needs of their clientele. 

What are the Big 4 credit card networks?

The “Big 4” credit card networks refer to the major players that dominate the credit card industry: Visa, MasterCard, American Express, and Discover – Fintech credit cards (as of now), tend to fall outside the realm of these established networks; 

Who is eligible for fintech credit cards?

Fintech credit cards cater to a diverse spectrum of individuals and business owners, spanning from students with no credit to fledgling startups to well-established enterprises. Nearly anyone at any stage of the credit journey can find a fintech card to suit their situation. 

How do you qualify for fintech credit cards?

The criteria for qualifying for fintech credit cards can vary from one offer to another, reflecting each company’s individual assessment strategies. Generally, consumers and businesses that maintain a consistent and reliable income stream stand a strong chance of meeting the eligibility requirements. Lenders typically evaluate the money going into and out of the applicant’s bank account to see if they qualify.

Is Zelle a fintech company?

Absolutely! Zelle falls squarely within the realm of fintech companies (though they have no credit card offer). The pioneering digital payment platform epitomizes the convergence of finance and technology. Zelle’s core mission revolves around facilitating swift and secure monetary transfers between individuals and businesses. 

Recommended: Real-Time Payments: A Business Owner’s Guide to Current Tech 

Conclusion

Congratulations, you’re now equipped with the knowledge to choose the best fintech credit card for your needs! Remember, these cards aren’t just about transactions; they’re about transforming the way you manage your finances. 

So, why wait? Take the next step in boosting your business’s financial prowess by applying for one of these fintech credit cards today! 

And, if you’re hungry for more credit knowledge, don’t forget to check out our Business Credit Workshop, where anyone can learn how to secure up to $100K in business credit within just 30 days…Your journey to financial empowerment starts now!

→ Join Business Credit Workshop today.
The Best Credit Cards for Landlords: A Comprehensive Guide

By Joe

best credit card for landlords

As a landlord, managing rental properties and maximizing profits is your top priority. One tool that can significantly aid in achieving this goal is the right credit card. 

In this extensive guide, we’ll explore the best credit cards for landlords. Whether you’re a seasoned property owner or just starting out, these credit cards can provide valuable benefits and rewards tailored to your needs. 

We’ll also address common questions about credit cards for landlords and provide insights into building business credit.

Here’s what’s in store:

  • Why Should Landlords Choose Business Credit Cards?
    • How to Grow Your Profits with Business Credit
  • Key Factors to Consider When You Choose a Credit Card
  • The Best Business Credit Cards for Landlords
    • 1. Chase Ink Business Preferred Card
    • 2. Amex Blue Business® Plus Credit Card
    • 3. Amex Business Platinum Card
    • 4. Amex Business Gold Card
    • 5. Chase Ink Business Unlimited Card
  • Frequently Asked Questions
  • Final Thoughts

Let’s get crackin’!

Why Should Landlords Choose Business Credit Cards?

Running a successful rental property business requires effective financial management. Compared to consumer credit cards, business credit cards tend to come with higher limits, yes. But, that’s not the only advantage.

Business credit cards offer several benefits that can simplify your operations:

First, with business credit cards, you can separate personal and business expenses effortlessly, making tax season a breeze.

Next, you can enjoy flexible credit limits to cover property-related costs and unexpected repairs.

And, you can earn valuable rewards, cash back, and discounts on everyday expenses associated with rental properties.

Finally, you can benefit from purchase protection and extended warranty coverage for appliances and equipment with a business credit card.

Furthermore, when you establish and strengthen your business credit profile, it can lead to better financing options in the future.

How to Grow Your Profits with Business Credit

Building strong business credit can be invaluable for a thriving landlord venture. 

To build your business credit, here’s what you can do:

  1. Lay a Solid Foundation – Choose your name and business category strategically. Establish your business entity and ensure consistency.
  2. Prepare Your Business for Credit – Secure an address, insurance, and licenses. Create an online presence and dedicated business account.
  3. Foster Financial Relationships – Network with local banks and credit unions. Understand financing programs and underwriting processes.
  4. Develop Strong Credit Profiles – Obtain a DUNS number and monitor your credit scores. Use tools like Nav for credit profile strength.
  5. Establish the Right Trade Lines Start with trade lines like store cards, net 30 accounts, and gas cards. Build a stable credit profile so you can continue to grow. 

And, here are some relevant companies that can help you build business credit: 

  1. Home Depot
  2. Floor & Decor
  3. Crown Office Supplies
  4. Shirtsy
  5. AtoB Gas Card

(Learn more about the process in our 7-step Business Credit Workshop.)

Key Factors to Consider When You Choose a Credit Card

To choose the right credit card for your landlord venture needs, here’s what you need to consider: 

  1. Rewards & Cash Back – Look for cards that offer rewards categories relevant to your rental business, such as office supplies or home improvement purchases.
  2. Annual Fees – Choose a card with no annual fee or a fee where rewards redemption will make it worthwhile. 
  3. 0% Intro APR Offers – If you plan to carry a balance, seek out cards with a 0% introductory APR period.
  4. Credit Limit: Make sure the credit limit lines up with your monthly expenses.
  5. Benefits and Perks – Consider additional benefits that align with your business.

The Best Business Credit Cards for Landlords

Here are the best credit cards for landlords, each offering unique advantages tailored to your rental property business – These credit cards cater to landlords by providing rewards, expense management tools, and cash flow flexibility that align with the ongoing nature of property management.

1. Chase Ink Business Preferred Card

credit card for rental property

The Chase Ink Business Preferred Card’s specialized bonus categories and advantageous point value for travel redemptions make it particularly valuable for landlords, addressing a range of expenses and travel requirements.

Plus, landlords usually have ongoing expenses related to property maintenance and management, which makes the card’s rewards on shipping and business categories worthwhile. The elevated redemption value for travel will benefit landlords who travel to manage properties in different locations.

  • Rewards – Earn 3X points on shipping and certain business categories, and 1X on all other purchases.
  • Redemption – Points gain a 25% boost in value when used for travel via Chase Ultimate Rewards.
  • Additional Benefits – Employee cards available, along with 5X points on Lyft rides.

Learn More: Chase Ink Business Preferred Credit Card: A Deep Dive Analysis 

2. Amex Blue Business® Plus Credit Card

amex blue business for landlords

The Amex Blue Business Plus Credit Card offers straightforward rewards for every purchase, coupled with useful tools for expense management that enhance a landlord’s ability to efficiently oversee their business finances.

The card’s straightforward rewards structure and expense management tools make it useful for keeping track of expenses associated with managing multiple rental properties.

  • Rewards – Gain 2X Membership Rewards® points on the initial $50,000 spent annually, followed by 1X points for subsequent purchases.
  • Cash Flow Flexibility – Experience Expanded Buying Power, with no preset spending limit.
  • Expense Management Tools – Benefit from employee cards, integration with QuickBooks®, Vendor Pay through Bill.com, and more.

3. Amex Business Platinum Card 

best credit card for real estate investors

The Amex Business Platinum Card stands out with one of the most robust rewards programs, many of which are relevant to property management, specifically those with properties in various locations.

Additionally, the card’s rewards on construction materials, hardware suppliers, and shipping providers align with landlords’ purchasing needs.

  • Rewards – Earn 1.5X points on eligible purchases at U.S. construction material & hardware suppliers, electronics, software & cloud providers, and shipping providers, plus on purchases of $5,000 or more elsewhere.
  • Travel Benefits – Take advantage of an array of travel rewards, such as:
    • Get a statement credit for Global Entry or TSA PreCheck® application fees. 
    • Earn 5X Membership Rewards® points for flights and prepaid hotels booked via AmexTravel.com. 
    • Access over 1,400 airport lounges through the Global Lounge Collection. 
    • Gain 35% of points back with Membership Rewards® Pay with Points for eligible flights via American Express Travel. 
    • Enjoy perks and earn 5X points on prepaid hotel and resort stays.
    • Receive up to $200 in statement credits annually for qualifying airline incidental fees.
    • Taka advantage of the Premium Private Jet program, premium car rental perks, Business Platinum travel service, trip delay and cancellation insurance, and more.
  • No Foreign Transaction Fees – Make purchases outside the U.S. without incurring foreign transaction fees.

Recommended: Best Credit Card for House Flippers: The Ultimate Guide

4. Amex Business Gold Card

best credit card for short term rental business

The Amex Business Gold card’s bonus categories encompass a wide spectrum of business expenditures, rendering it a valuable tool for various aspects of managing properties. Ans, the pay over time option provides cashflow flexibility, particularly when rental income is inconsistent.

Similar to the Business Platinum Card, the Business Gold Card’s rewards categories cover a broad range of expenses, including advertising, utilities, and shipping, which are often relevant to landlords. 

  • Rewards – Earn 4X Membership Rewards® points on the top 2 categories where your business spends the most in each billing cycle from a selection of options.
  • Cash Flow Flexibility – Take advantage of the option to pay over time with no preset spending limit.
  • Additional Benefits – Access expense management tools, employee cards, integration with QuickBooks®, Vendor Pay through Bill.com, and more.

5. Chase Ink Business Unlimited Card

best credit card for home improvement

The Chase Ink Business Unlimited Card delivers straightforward cash back on all purchases, which can offset a variety of expenses linked to property management activities, including supplies, renovations, and transportation.

The flat cash back rate on all purchases is beneficial for ongoing maintenance and home improvement expenses. Plus, the introductory 0% APR period can help manage large expenditures without incurring immediate interest.

  • Unlimited Cash Back – Secure 1.5% cash back on every purchase.
  • Intro APR – Enjoy a 0% introductory APR for 12 months on purchases.
  • Additional Benefits – Offer staff cards and earn 5% cash back on Lyft rides.

Recommended: 6 Best Business Credit Cards for Entrepreneurs: Fuel Your Growth 

Frequently Asked Questions

Can a landlord get business credit?

Yes, landlords can get a business credit card to build business credit. This helps separate personal and property expenses. Despite having a single property, you can qualify by using your business’s Employer Identification Number (EIN) instead of your Social Security Number (SSN). 

How do I use my EIN number for credit?

Using your Employer Identification Number (EIN) for credit involves applying for business credit cards and loans. Lenders use your EIN to assess your business’s creditworthiness.

Which bank credit card is best with no annual fee?

The Ink Business Unlimited® Credit Card from Chase is an excellent option, offering no annual fee and straightforward cash back rewards.

Which credit card is easy to get?

The Ink Business Cash® Credit Card from Chase is relatively accessible and offers tiered rewards, making it suitable for landlords.

What credit score do most rental companies use?

Most rental companies use a FICO credit score, with a score of around 650 or higher typically being considered a good credit score for rental applications.

Recommended: This is How to Pay Rent with a Credit Card (Home or Business) 

Final Thoughts

Selecting the right credit card for your rental property business can significantly impact your financial success – By considering factors like rewards, annual fees, and purchase protections, you can choose a card that aligns with your unique needs. 

The top business credit cards for landlords, along with their alternatives, provide valuable rewards and benefits that can enhance your rental property operations. 

Ready to take your property management business to the next level? Explore the possibilities with Business Credit Workshop and learn how to secure up to $100K in business credit within as few as 30 days. 

→ Join Business Credit Workshop today.
The Best Credit Cards for Truckers: Save Big on the Road!

By Joe

best credit cards for truckers

Hey there, truckers! Ready to hit the road and save some serious cash? In the fast-paced world of trucking, managing your finances is key to success. 

And guess what? 

The secret weapon to cut down expenses, earn rewards, and stay on top of your game is none other than the right credit card! Buckle up, ’cause in this guide, I’ll walk you through the best credit card options for truckers, spilling all the benefits and rewards. 

Plus, we’ll answer those burning questions you’ve got about credit cards, making sure you’re all set to make smart choices.

Here’s what’s in store: 

  • Fuel Cards & Business Credit: Gas Up to Save Big!
  • The Benefits of Fuel Cards for Long-Haul Drivers
    • Expense Reduction and Rewards
    • Improved Cash Flow
    • Expense Tracking and Simplified Bookkeeping
  • The Top Credit Cards for Truckers: Your Highway to Savings!
    • 1. WEX Fleet Card
    • 2. Shell Fleet Navigator Card
    • 3. Exxon Mobil FleetPro Card
    • 4. Fuelman
    • 5. Shell Small Business Card
    • 6. Discover It Secured Card
    • 7. Hilton Amex Surpass Card
  • Frequently Asked Questions
  • Final Thoughts

Now, let’s make tracks!

Fuel Cards & Business Credit: Gas Up to Save Big!

Fuel cards can be like gold for truckers. Not only do they give you discounts on fuel, but they also work wonders in slashing maintenance and truck-related expenses.

But, here’s the thing: not all fuel cards are created equal (some might not even report your credit history). So, to build that strong credit score, you might to consider business credit cards that do report to credit agencies. 

Recommended: This is How to Leverage Business Credit to Transform Your Life 

Fortunately, there are quite a few fuel cards tailor-made for truckers with no credit checks or options for those with not-so-perfect credit. Score!

Now, let’s talk savings! With fuel cards in hand, you can kiss a lot of sky-high fuel costs goodbye. Get ready to save big on gas and keep those hard-earned dollars where they belong – in your pocket! 

Some fuel cards give you massive discounts and rewards, but that’s not all. Combine it with fuel-efficient driving and comparing prices at different fuel stations – boom, more savings! 

And, you don’t have to worry if your credit history isn’t spotless. Some fuel cards for truckers are more forgiving, giving you a shot at the good stuff.

Recommended: Credit Secrets Book Review: Can You Erase Bad Credit History? 

The Benefits of Fuel Cards for Long-Haul Drivers 

Before we dive into the credit card options, let’s learn why fuel cards are the real deal.

Expense Reduction and Rewards

Picture this: you’re getting cash back and rewards on your fuel, maintenance, and truck-related expenses. Sounds like a dream, right? 

Well, dream no more! 

Finding the right card is all about getting you those juicy rewards, which means cutting down expenses and boosting your bottom line. Hello, more money in your pocket!

Improved Cash Flow

Life on the road can be unpredictable – I get it. But, worry not! Credit cards can be your financial cushion when payments are delayed or surprise expenses pop up. 

With that flexible plastic in your wallet, you can keep on truckin’ without any hiccups.

Expense Tracking and Simplified Bookkeeping

Nobody likes a mountain of receipts and confusing spreadsheets. Real-time spend tracking and analytics to the rescue! 

Many cards give you all the nitty-gritty details of your transactions on the same day spending takes place, making bookkeeping a breeze. 

You might also like: How to Use Business Gas Cards to Build Your Business Credit

The Top Credit Cards for Truckers: Your Highway to Savings!

Now, let’s hit the gas and check out the best credit cards just for truckers.

1. WEX Fleet Card

fuel cards for truckers with no credit check

The WEX Fleet Card is an ideal choice for growing businesses seeking real savings and efficient fuel expense management. Accepted at 95% of U.S. fuel stations, the card offers automatic fuel expense tracking, employee spending controls, purchase alerts, and exclusive discounts in the WEX EDGE savings network. 

The card’s fuel anywhere feature eliminates the need to plan routes around specific fuel stations, making it convenient for truckers. Advanced spending controls allow businesses to customize purchase restrictions, and detailed, custom reports aid in smart decision-making. 

This card also offers a mobile app for easy account access and provides excellent customer service.

Best for: Growing businesses with mixed fleets looking for comprehensive fuel expense management, robust controls, and access to exclusive discounts.

2. S