• Home
  • Free Funding Guide
  • What We Offer
    • Products
    • Services
    • Free Guide
  • About Us
  • Contact
  • Sign Up

  • Ask Joe Any Question!
  • Business Credit Cards
  • Business Line of Credit
  • Topics

Are the Kwak Brothers Legit? What the Kwak Brothers Reviews Tell You

By Joe

Kwak Brothers

If you’re diving into the world of real estate investment, you might have come across the Kwak Brothers. Sam and Daniel Kwak are well-known in this space, but you might be wondering whether they’re truly worth your attention. 

Here, I explore who the Kwak Brothers are, what they do, and what reviews and other sources say about them to help you decide if they’re a good fit for your investment goals.

This is what’s in store: 

  • Who are the Kwak Brothers?
    • Who is Sam Kwak?
    • Who is Daniel Kwak?
    • Company Overview
  • What Do the Kwak Brothers Do?
    • 1. Learn to Pay Off Your Mortgage Early
    • 2. Create and Scale Your Passive Income
    • 3. Learn the Infinite Banking Concept
  • Frequently Asked Questions
  • Conclusion: Are the Kwak Brothers Legit?

Who are the Kwak Brothers?
Kwak brothers lookism

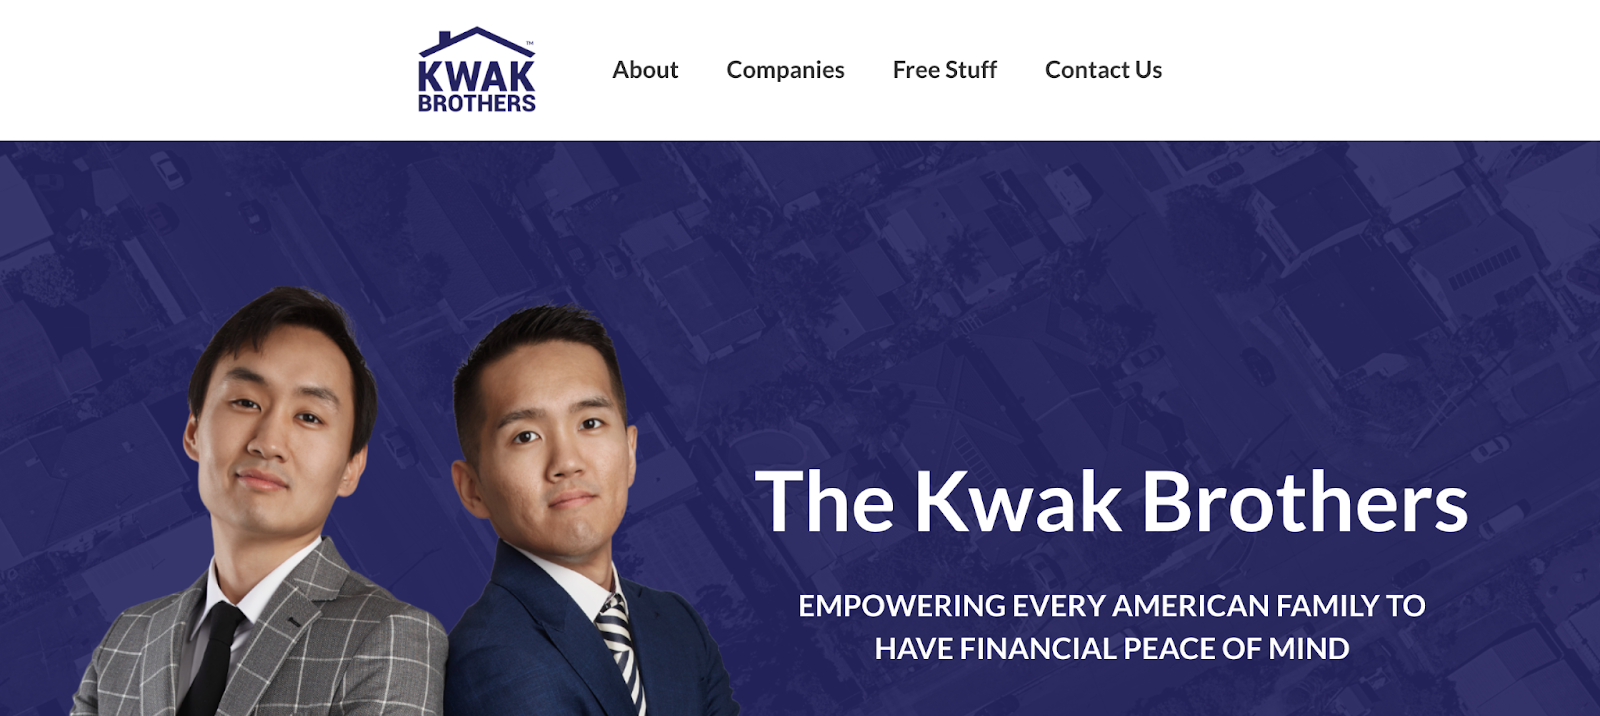
The Kwak Brothers, Sam and Daniel, are prominent entrepreneurs, real estate investors, mentors, and authors dedicated to helping you achieve financial peace of mind. They’ve made a name for themselves through their work teaching real estate investing and personal finance. 

Their companies include: 

  • Accelerated Banking, which helps homeowners pay off their mortgages faster using a proprietary strategy. 
  • The Passive Income Mastery Program that coaches new investors to help them achieve substantial monthly income in a short period. 
  • IBC Jumpstart, which offers an educational approach to financial independence through life insurance products.

Their expertise is widely-shared through social platforms like YouTube, where they provide valuable insights. They also host live speaking engagements where they motivate and educate prospective investors and those who want to increase their net worth.

In this case, “real estate investment” refers to a focus on raising capital and acquiring rental properties through owner financing—They also offer training on how to implement these strategies effectively. 

Beyond investing, they serve as mentors, specializing in personal finance and real estate to help individuals secure a stable financial future. 

You might also like: A Credit Stacking Breakdown: What it is & How it Works 

Who is Sam Kwak?
The Kwak Brothers net worth

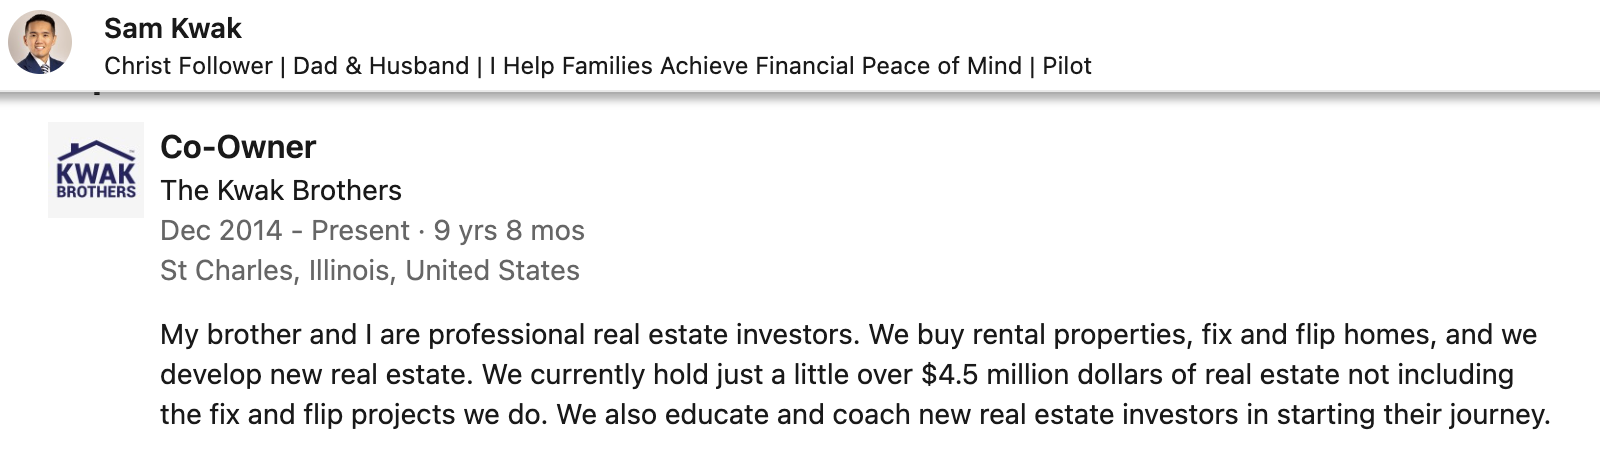
Sam Kwak is a prominent real estate investor and frontman of The Kwak Brothers. Before his career, he prioritizes being a devoted Christ-follower, father, and husband. Based in Chicago, Sam and his brother Daniel manage a real estate portfolio worth over $4.5 million.

Sam’s entry into real estate was sparked by a desire for financial freedom, and inspired by Rich Dad Poor Dad—He started by volunteering for a local investor, which he views as a shortcut to success. His first major deal came through social media, where he used owner financing to acquire a portfolio of single-family homes.

In 2017, Sam experienced significant growth, expanding his rental properties from zero to 75 units in just one year. His success is attributed to effective capital raising and seller financing. Sam also leverages his marketing and technology background to help property managers automate their businesses.
Kwak Brothers Youtube

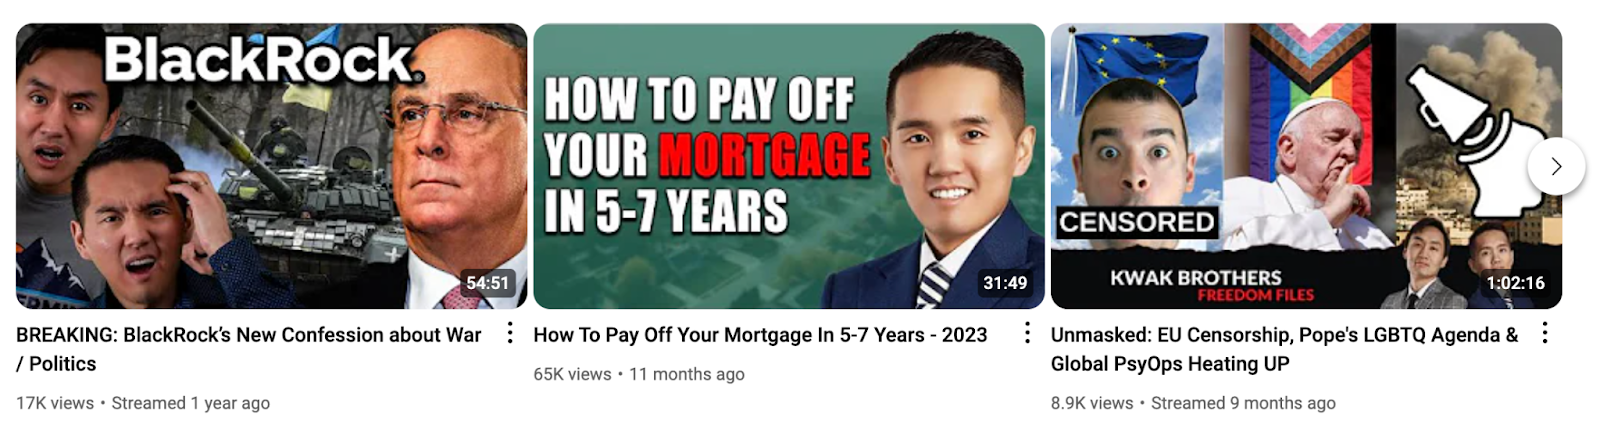
Sam’s YouTube channel, which was initially a real estate resource, now has over 780 videos and 348K followers. The Kwak Brothers channel now also includes political commentary, aimed at a conservative audience while subtly introducing real estate concepts. 

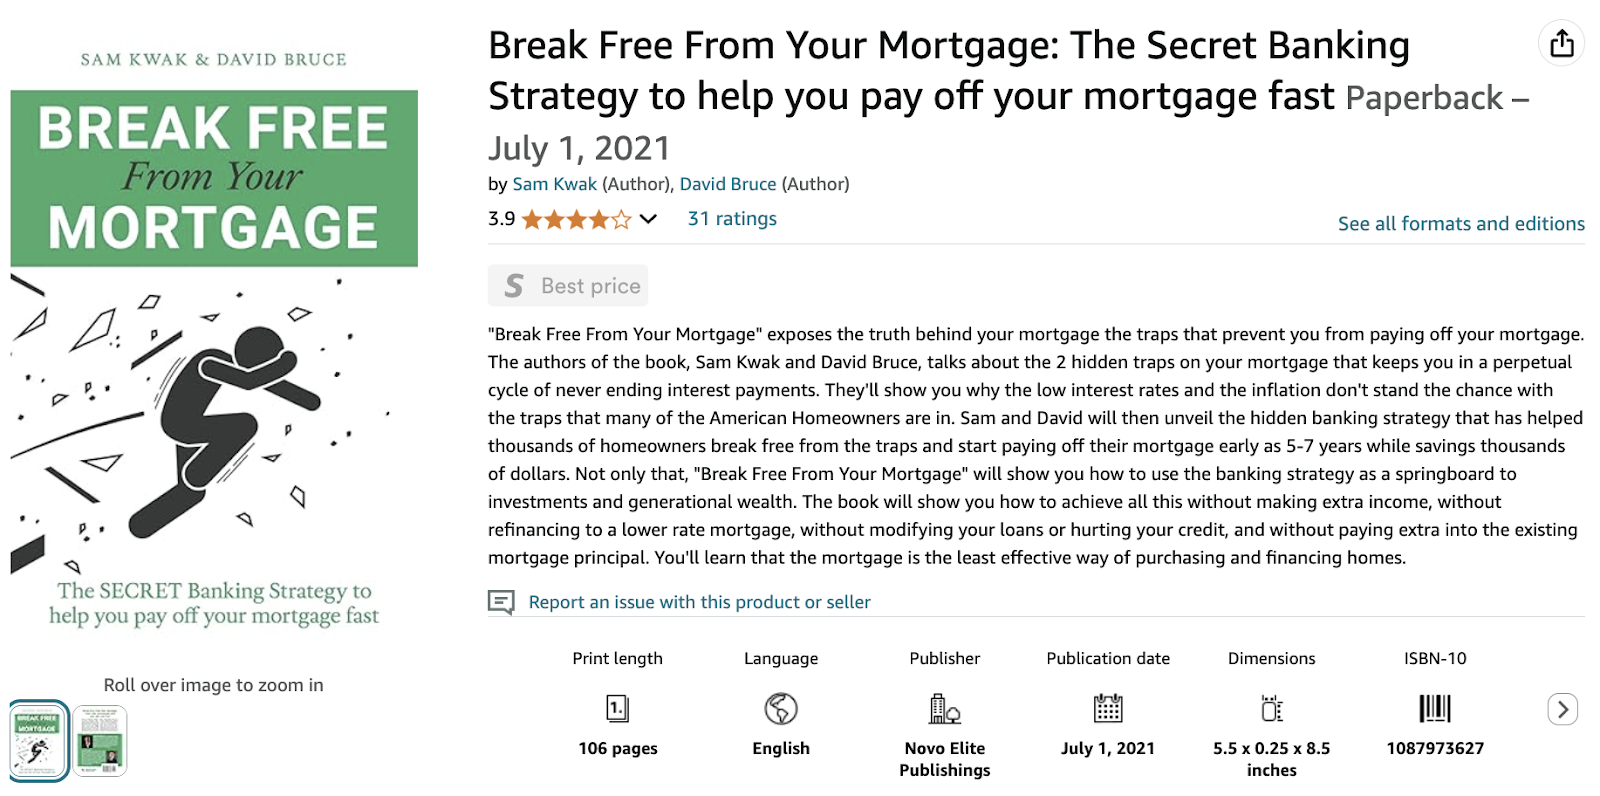
Sam Kwak has co-authored at least one book. Break Free From Your Mortgage: The Secret Banking Strategy to Help You Pay Off Your Mortgage Fast by Sam Kwak and David Bruce reveals hidden traps in mortgages that keep homeowners in a cycle of endless interest payments. The book introduces a banking strategy that promises to help you pay off your mortgage in as little as 5-7 years without extra income, refinancing, or modifying loans.
Kwak Brothers Book

Reviews on the book are mixed, and it has a 3.9-star rating overall. Some readers appreciate the powerful financial insights, while others feel the book focuses too much on upselling the authors’ services. 

Recommended: 9 Best Business Credit Books Worth Reading

Who is Daniel Kwak? 

The Kwak Brothers ethnicity

In addition to co-managing The Kwak Brothers’ ventures, Daniel Kwak is the founder and Chief Investment Officer (CIO) of Miotti Partners Capital. Founded by Daniel at 26, Miotti Partners Capital is a core-satellite fund that pioneered the equities fund management model in the real estate industry.

His role at Miotti Partners Capital involves overseeing investments and building strategic relationships, complementing his responsibilities within The Kwak Brothers. 

Daniel’s focus on raising capital and fostering relationships has been instrumental in the growth of their real estate ventures. Like his brother Sam, Daniel is deeply involved in both real estate investment and education. 
Kwak Brothers Google Reviews

Their partnership leverages Daniel’s strengths in capital raising and networking, while Sam focuses on marketing and systematizing their operations. Their combined efforts have established a robust platform for educating and empowering others in the realm of real estate investing.

Recommended: How to Get Money for Real Estate Investing: 18 Practical Ideas 

Company Overview
Kwak Brothers Novo Elite Inc.

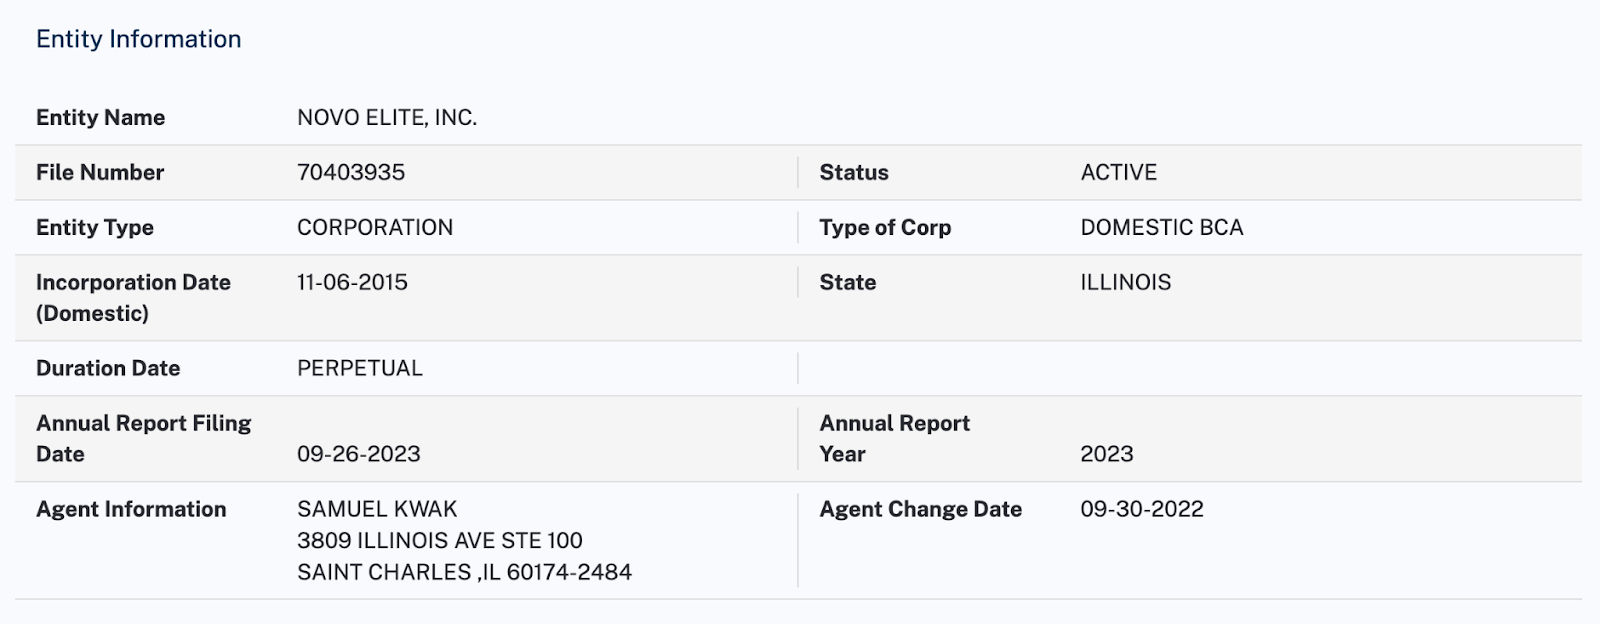
While brothers began their real estate venture over a decade ago, Novo Elite Inc., the company doing business as The Kwak Brothers, is an Illinois-based corporation that’s been around since 2015, and is officially registered to Samuel Kwak. The company is active and in good standing with the Office of the Illinois Secretary of State.

Over the past decade, the business has evolved to offer a range of educational resources and services aimed at aspiring investors—They’ve maintained a strong presence in the real estate field for several years, continuously updating their content and services to reflect current market trends.
Kwak brothers wikipedia

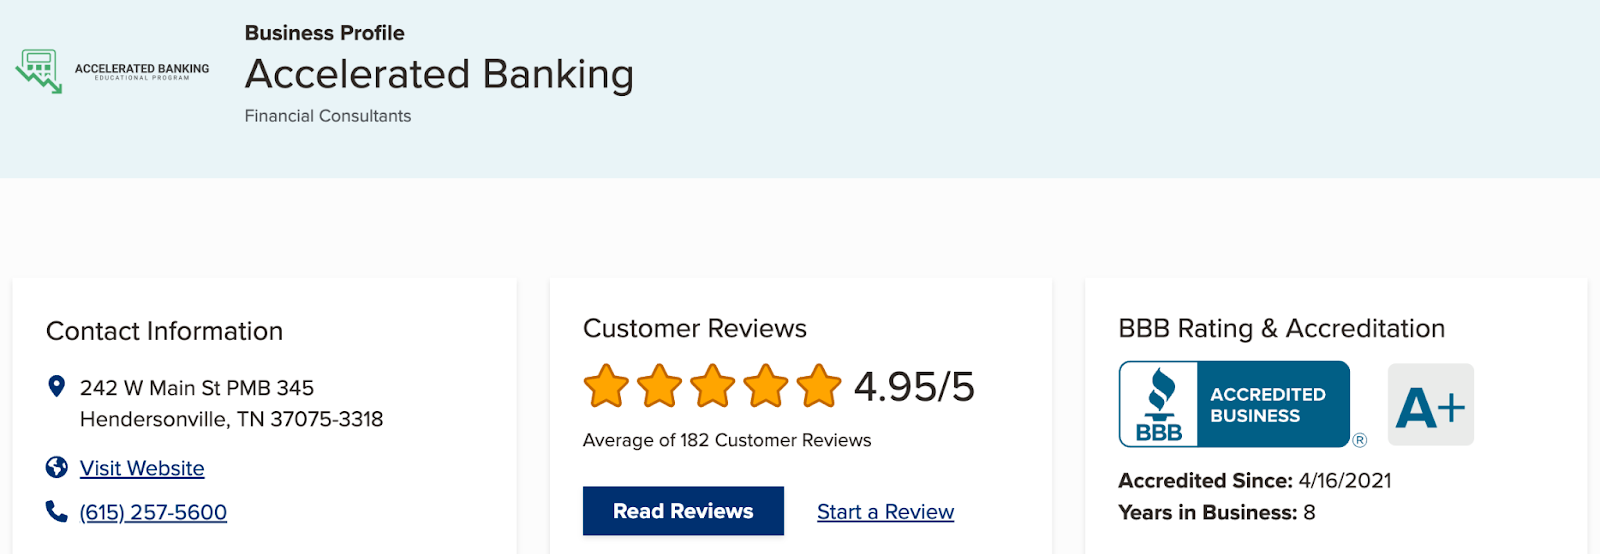
Reviews on sites like the Better Business Bureau (BBB) are mostly positive. A majority of clients find their advice and training beneficial, while a few express concerns about the value and effectiveness of their offerings.

At any rate, they run a real business, registered and in good standing across the board. And, I couldn’t find any major complaints or lawsuits against Novo Elite, which is a good sign.

You might also like: The Ultimate Guide to Fix and Flip Loans: Fund Your Next Venture 

What Do the Kwak Brothers Do?

The Kwak Brothers offer several services designed to help individuals succeed in real estate investing and financial management. Here’s a closer look:

1. Learn to Pay Off Your Mortgage Early
Kwak Brothers Accelerated Banking

The Kwak Brothers’ key offer is a program called Accelerated Banking—the value proposition is that you can pay off your mortgage in five to seven years. Accelerated Banking promises a practical way to pay off your mortgage early using a Home Equity Line of Credit (HELOC). It’s run by Sam and Daniel Kwak and David Bruce (co-author of Break Free From Your Mortgage). Allegedly, the group has a combined 70 years of investment experience. 

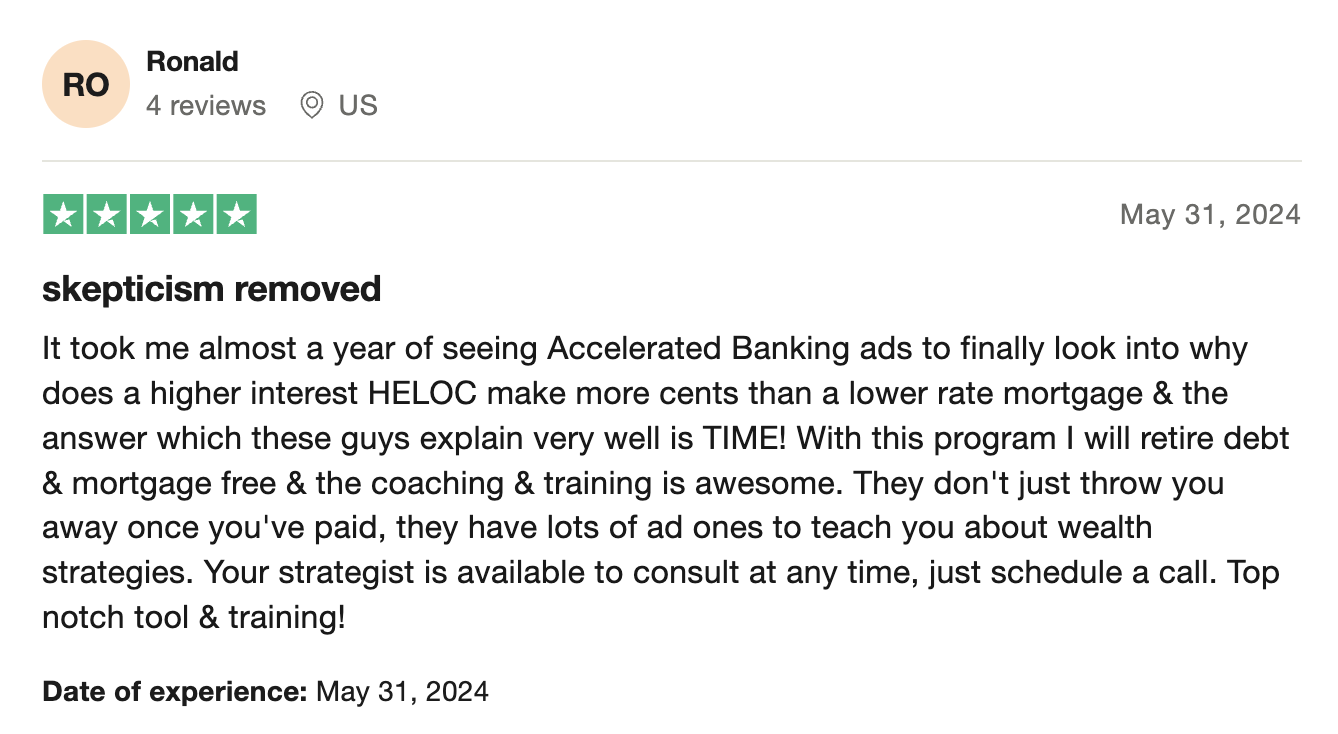
According to real user reviews, students seem to learn how to use HELOCs to reduce their mortgage term, manage their finances better, and save significantly on interest payments—Reviewers mention the program’s detailed guidance, personalized strategies, and accessible educational resources. 
Kwak Brothers reviews

So, you should be able to expect a tailored approach that aligns with your financial goals, ongoing support from knowledgeable advisors, and a community of like-minded individuals all working towards financial freedom.
Kwak Brothers Facebook Accelerated Banking

Accelerated Banking’s facebook page has 1.2K followers and a bit of engagement on their posts. Their free webinar introduces what they will teach in their training. And, rather than paying off your mortgage in five to years, the cited results are actually of people who cut five to seven years off their mortgages. 

My first impression in that the offer is a bit misleading, but still could be valuable. 

Recommended: The BRRRR Method: A Real Estate Portfolio-Building Blueprint 

2. Create and Scale Your Passive Income 
Kwak Brothers Passive Income Mastery

Passive Income Mastery promises hands-on coaching, an inspirational community, and virtual education to help you achieve your real estate goals. According to trainee reviews, students find the coaching effective and appreciate the supportive community—They feel empowered by the expert guidance and resources available. 

When you join, as with Accelerated Banking, you can expect personalized coaching, access to proven strategies, and a network of like-minded individuals working toward financial freedom through real estate investing.

The program starts with a free training webinar that covers: 

  • Creative financing ideas
  • How to fund down-payments owner financing
  • How to create your passive income stream
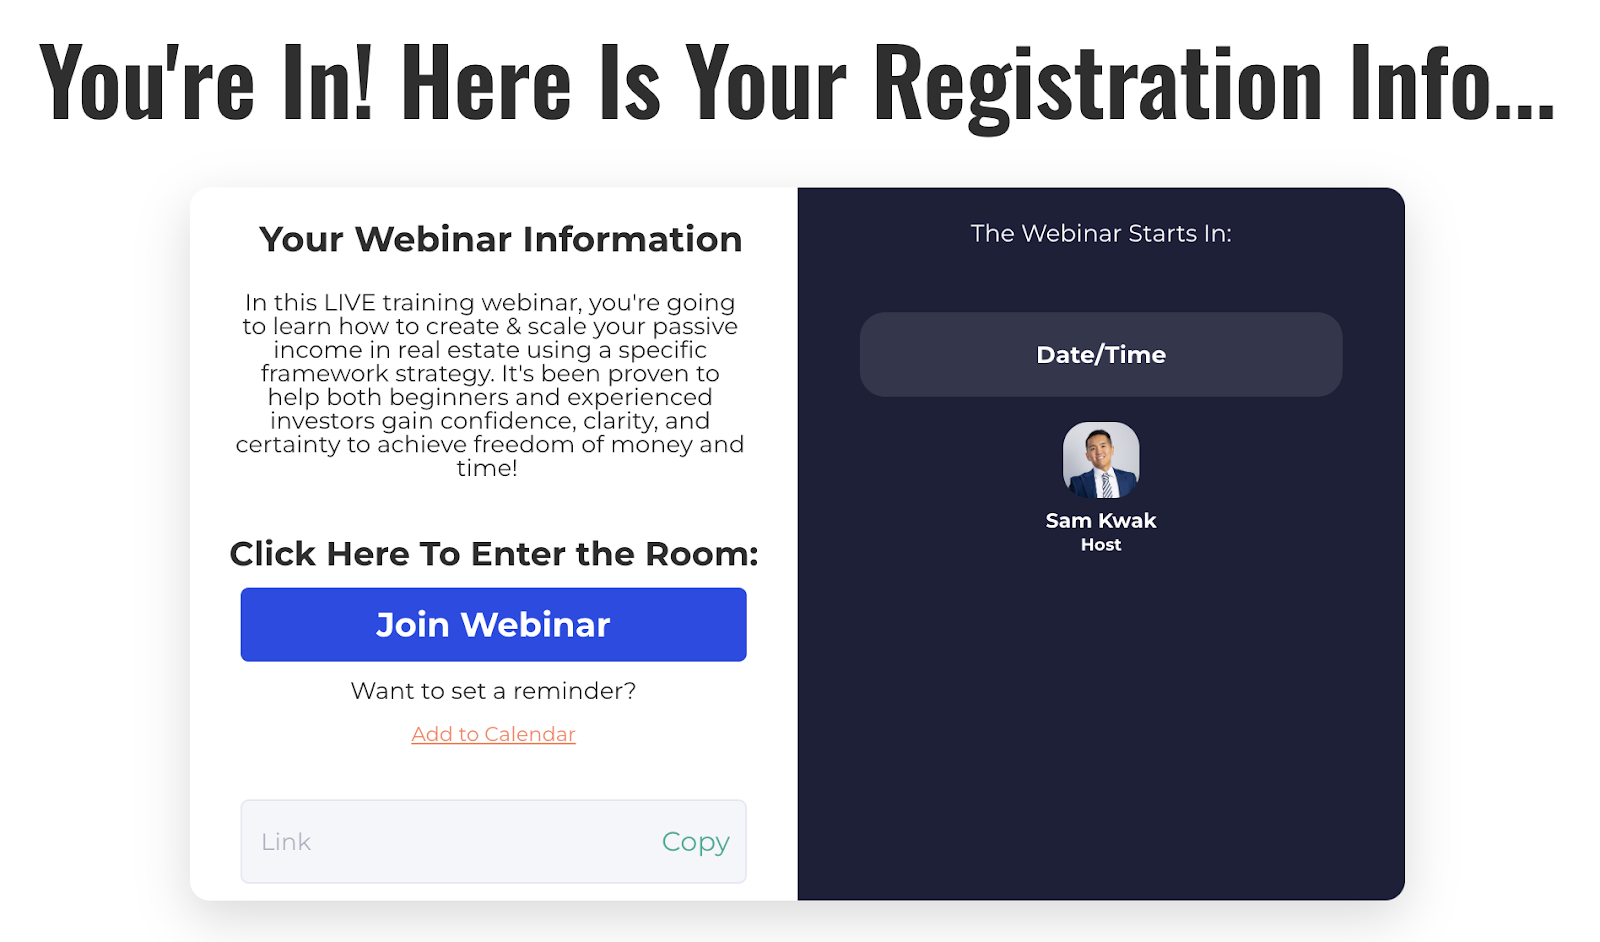
Passive Income Mastery Registration

I popped into the webinar myself, and I didn’t like that it was set up to appear like a “live training” with over 100 viewers (Passive Income Mastery’s Facebook page only has 260 total followers). I could tell the training was pre-recorded and that Alonzo T and Britt P were fake viewers—And, I don’t love a lack of transparency. 

Be that as it may, the webinar did provide a solid intro to what the training should cover, and it was completely free to check out.   

You might also like: Read This Before You Hire a Business Credit Coach [Quick Guide] 

3. Learn the Infinite Banking Concept 
Kwak Brothers IBC Jumpstart

The Kwak Brothers’ IBC Jumpstart is a deep dive into the infinite banking concept (IBC). IBC is a financial strategy that uses whole life insurance policies to create your own personal banking system. 

Originally coined by Nelson Nash, the IBC lets you borrow against the cash value of your life insurance instead of going to a bank for loans—This way, you can finance big expenses, like buying a car or starting a business, while your policy continues to grow. The idea is to build wealth with your policy’s cash value, which you can access tax-free and pay back on your schedule.
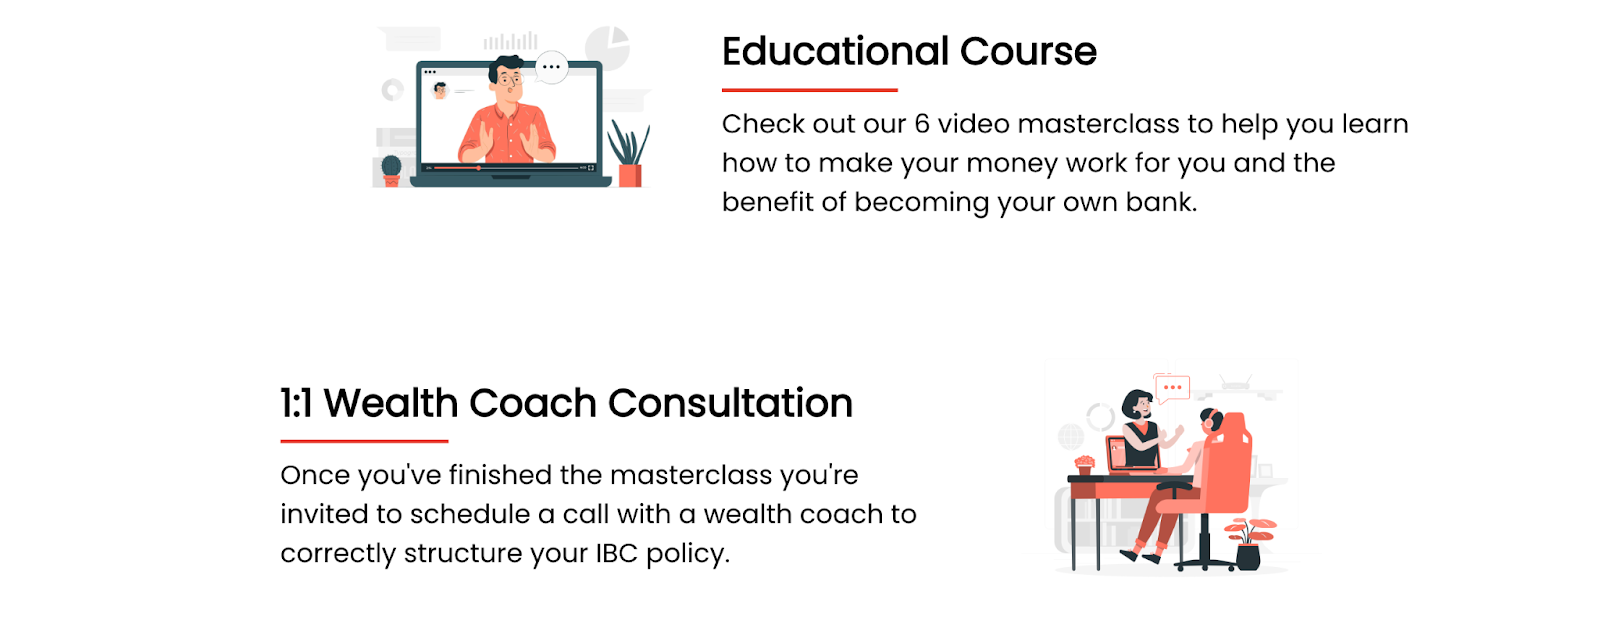
IBC Jumpstart Infinite Banking Concept

IBC Jumpstart offers free access to their Infinite Banking Masterclass. This includes a 6-video course to teach you how to manage your finances by becoming your own bank. After completing the course, you can schedule a one-on-one consultation with a wealth coach to set up your IBC policy. 
Sam Kwak Infinite Banking

The aim of the masterclass is to help you understand and implement the Infinite Banking Concept for better financial control.

You might also like: Complete Guide to Small Business Insurance in New Jersey 

Frequently Asked Questions

Who are the Kwak Brothers?

Sam and Daniel Kwak are well-known for their work in real estate and financial education. They focus on providing training, coaching, and resources to help individuals achieve financial success through real estate investment.

What is the Kwak Brothers’ net worth?

Exact figures on their net worth are not publicly available. However, they are recognized as successful entrepreneurs in the real estate sector, with at least $4.5 million in combined real estate holdings.

What do the Kwak Brothers reviews say?

Reviews about the Kwak Brothers are mostly positive. Some people appreciate their detailed advice and practical tips, while the minority question their marketing practices and the effectiveness of their programs.

Conclusion: Are the Kwak Brothers Legit?

The first thing I will say that I don’t love about these offers is that it’s very difficult to find the pricing for all of the Kwak Brothers’ offers. Moreover, their training intros are slightly misleading. 

With that said, The Kwak Brothers have made a significant impact in real estate and financial education. They offer a few different resources and services aimed at helping you succeed. While they have a notable online presence and their reviews are resoundingly positive, I’m on the fence with this one. 

If you’re thinking about signing on to one of the Kwak Brothers’ offers, research thoroughly, weigh the feedback from different sources, and determine if their approach aligns with your investment goals.

Do you want to learn how to obtain up to $100K in business credit in as few as 30 days so you can invest in your financial future? Join Business Credit Workshop today! 
The Ultimate Guide to Fix and Flip Loans: Fund Your Next Venture

By Joe

Fix and Flip loans

Fix and flip or “flipping houses” involves buying properties, renovating them, and selling them quickly for a profit. It’s an exciting way to invest in real estate and offers the potential for significant profits. But, the right financing is crucial. 

Thinking about diving into the flipping market? Here, I want to walk you through everything you need to know about fix and flip loans so you can make informed decisions and boost your investment potential.

This is what’s in store: 

  • What Are Fix and Flip Loans?
  • How Fix & Flip Loans Work
    • The Risks & Challenges of Fix & Flip Loans
    • The Benefits of Fix & Flip Loans
  • Types of Fix & Flip Loans to Consider
    • Hard Money Loans
    • Business Lines of Credit
    • Home Equity Loans
    • Personal Loans
    • 401(k) Loans
    • Seller Financing
  • This is How to Qualify for a Fix & Flip Loan
    • 1. Get Your Credit in Check
    • 2. Network With Other Real Estate Investors
    • 3. Learn How to Evaluate Properties Effectively
    • 4. Get Really Good at Organizing Your Documents
  • Common Alternatives to Fix and Flip Loans
  • Frequently Asked Questions
  • Conclusion

Now, let’s dive in! 

What Are Fix and Flip Loans?

Fix and Flip Loans Florida

Fix and flip loans are short-term financing options designed for investors looking to buy, renovate, and sell properties quickly. Unlike traditional mortgages, these loans focus more on the property’s potential value after renovations rather than your credit history. They typically have higher interest rates and shorter repayment terms but provide fast access to capital—exactly what you need when timing is critical.

Understanding the various funding types can help you choose the best option for your needs.

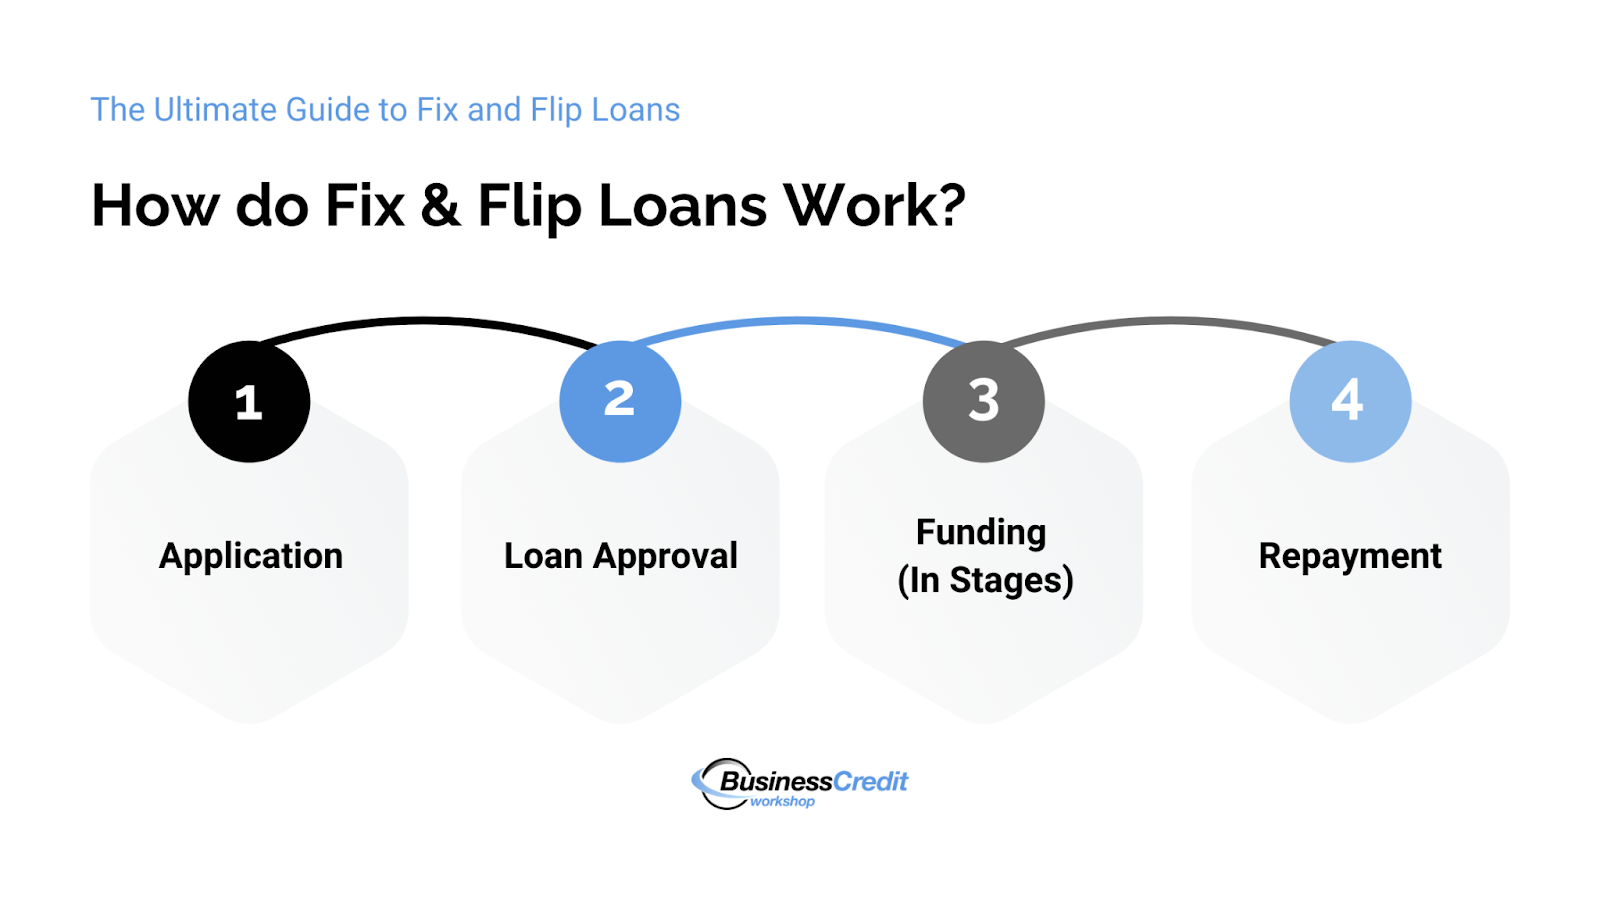
How Fix & Flip Loans Work

Fix and flip loans reviews

For the sake of relevance, we’ll talk about hard money loans that are dedicated to property flipping. 

To get started, you apply for a loan by submitting a detailed plan that includes: 

  1. How much the property will be worth after renovations (ARV)
  2. What the renovations will cost
  3. When you plan to finish them

Once the lender approves your plan, they give you the money in stages, called “draws,” as you finish different parts of the renovations. This helps manage your budget and lowers the risk for the lender.

These loans usually need to be paid back quickly, often within 6 to 18 months. So, it’s important to have a clear plan for how you’ll either sell the property or get long-term financing before the loan term ends. This way, you can pay back what you borrowed and any interest on time.

You might also like: How to Raise Money for Real Estate Investment: A Beginner’s Guide 

The Risks & Challenges of Fix and Flip Loans

While fix and flip loans can definitely be lucrative, they come with inherent risks, like: 

  • Short repayment periods 
  • High interest rates or fees
  • Market volatility
  • Renovation overruns 

Fix and flip loans have short repayment periods, typically six months to a year, aimed at minimizing interest costs but requiring precise project planning and timely property sales to avoid financial penalties. 

These loans often incur higher costs than traditional mortgages, impacting profitability, particularly if renovations are extensive or sales are delayed. 

Plus, economic shifts and unforeseen events like recessions can affect project profitability, which is why you need market awareness, thorough research, a contingency fund, and experienced contractors to manage risks effectively.

You might also like: The BRRRR Method: A Real Estate Portfolio-Building Blueprint 

The Benefits of Fix & Flip Loans

Despite the risks involved, fix and flip loans offer several benefits:

  • Quick access to capital 
  • Flexible options
  • Potential for high returns 

Fix and flip loans provide you with quick approval and funding, essential for seizing real estate opportunities swiftly, especially in competitive markets. You’ll find a variety of loan options tailored to different financial needs and project sizes, accommodating both single property ventures and larger portfolios. 

With strategic property choices, renovations, and marketing efforts, fix and flip investments can yield substantial profits in a relatively short period, which makes them a potentially lucrative path to build wealth through real estate.

Recommended: How to use Business Credit to Buy Real Estate! 

Types of Fix & Flip Loans to Consider

In general, people are talking about “hard money loans” when they talk about applying for a fix and flip loan. But, this isn’t the only type of financing you can use to fund a property flip. So, let’s explore your best options. 

Hard Money Loans

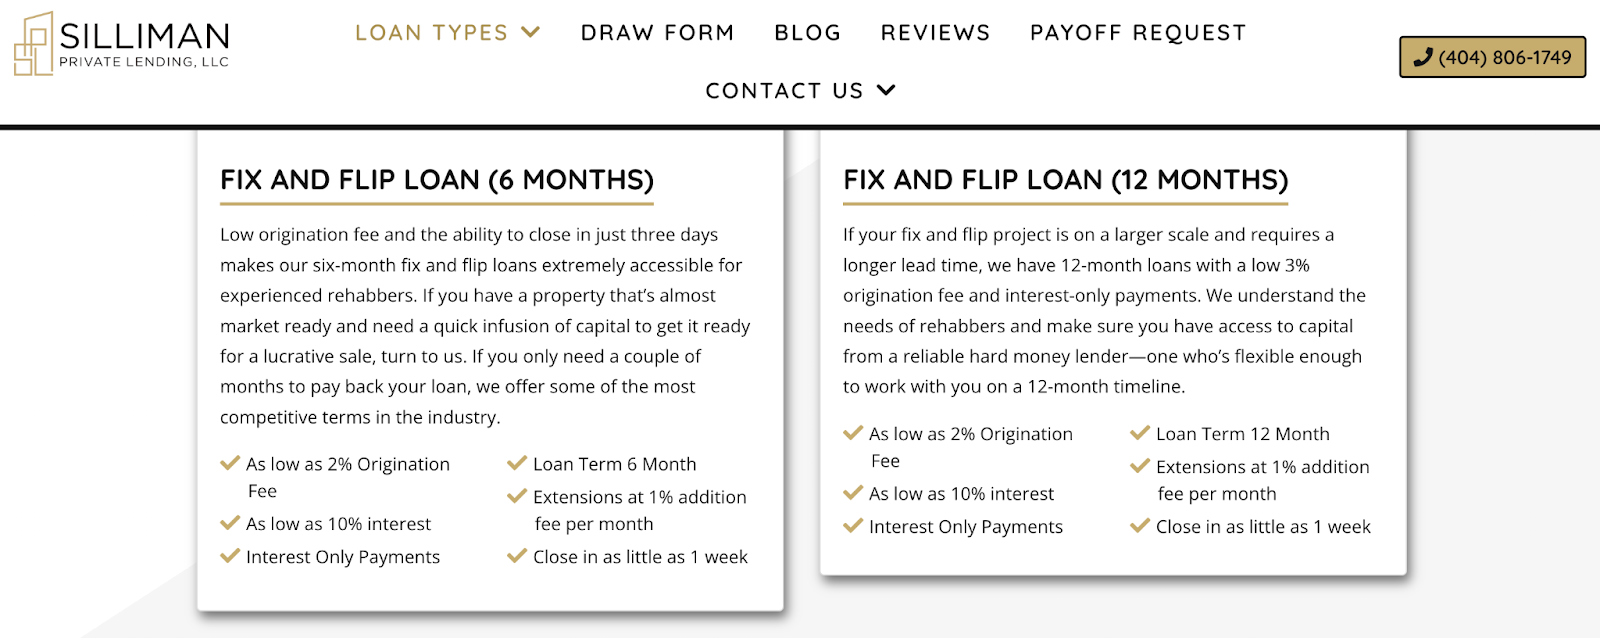
Fix and flip loans roswell ga

Hard money loans are the most common type of fix and flip loan. They’re popular for their quick approval process. 

These loans are secured by the property itself, making them ideal for investors who may not have perfect credit. They’re based more on the property’s after-repair value (ARV) than on your financial history. 

While hard money loans offer flexibility and speed, keep in mind that they often come with higher costs. 

Fix and flip loans Reddit

Hard money lenders usually charge “origination points,” which are upfront fees calculated as a percentage of the loan amount. It’s best to try to negotiate with the lender to reduce this percentage and lower your initial costs—Negotiation can be critical to minimize expenses and improve the financial viability of your fix and flip project.

Before you choose this route, consider whether the speed of access to capital outweighs the cost.

You might also like: A Review of Alpha Funding Partners – Are Their Solutions Right for You? 

Business Lines of Credit

Fix and flip loans no money down

Business lines of credit aren’t a loan, per se. Still, they can be used in much the same way, particularly in real estate investing—This option provides flexible access to funds whenever you need them. 

Business lines of credit function similarly to revolving loans. They offer flexible access to funds as needed, making them ideal for covering project expenses without borrowing a lump sum upfront. If you have a strong credit history, securing a business line of credit can be advantageous due to its cost-effective nature—you only pay interest on the amount you draw. 

Here’s a tip: Some lenders may offer promotional periods with lower interest rates or waived fees initially. It’s worth exploring these options to maximize savings on your real estate investment projects.

Recommended: This is How to Leverage Business Credit to Transform Your Life 

Home Equity Loans

No money down fix and flip loans

Using the equity in your home is a cost-effective strategy for financing fix and flip projects. Home equity loans and HELOCs generally come with lower interest rates than hard money loans, making them attractive options for funding. 

However, it’s important to understand that defaulting on these loans puts your home at risk. So, you need careful financial management and a solid exit strategy—This approach is particularly beneficial for experienced investors who are adept at managing risks and timelines in real estate projects. 

For those considering real estate investor lines of credit (REILOC), these specialized credit lines offer tailored financing options designed specifically for ongoing real estate investments, providing further flexibility and potential cost savings compared to traditional funding methods.

You might also like: Should You Use a Real Estate Investor Line of Credit to Renovate Property? 

Personal Loans

100 percent fix and flip loans

Personal loans can be a viable option for funding fix and flip projects, particularly if you need a smaller amount of capital and have a good credit history. Here are some common types:

  • Unsecured personal loans – These loans don’t require collateral, which makes them less risky for your assets. They’re typically based on your creditworthiness and income. While they may come with higher interest rates, they offer flexibility and quick access to funds.
  • Peer-to-peer (P2P) loans – P2P lending platforms connect borrowers directly with individual lenders willing to fund their projects. These loans often have competitive rates and terms, depending on your credit profile and the platform’s requirements.
  • Revolving credit lines – Using revolving credit to finance renovations can be convenient, but it’s important to manage interest rates and repayment terms carefully. Some credit cards offer promotional periods with low or zero interest rates, which can be advantageous if you can pay off the balance before the promotional period ends.

When considering personal loans for fix and flip projects, compare rates, terms, and repayment schedules from different lenders to find the option that best fits your financial situation and investment goals.

You might also like: 11 Alternate Ways for Entrepreneurs to Raise Capital with Online Lenders 

401(k) Loans

100% fix and flip loans no credit check

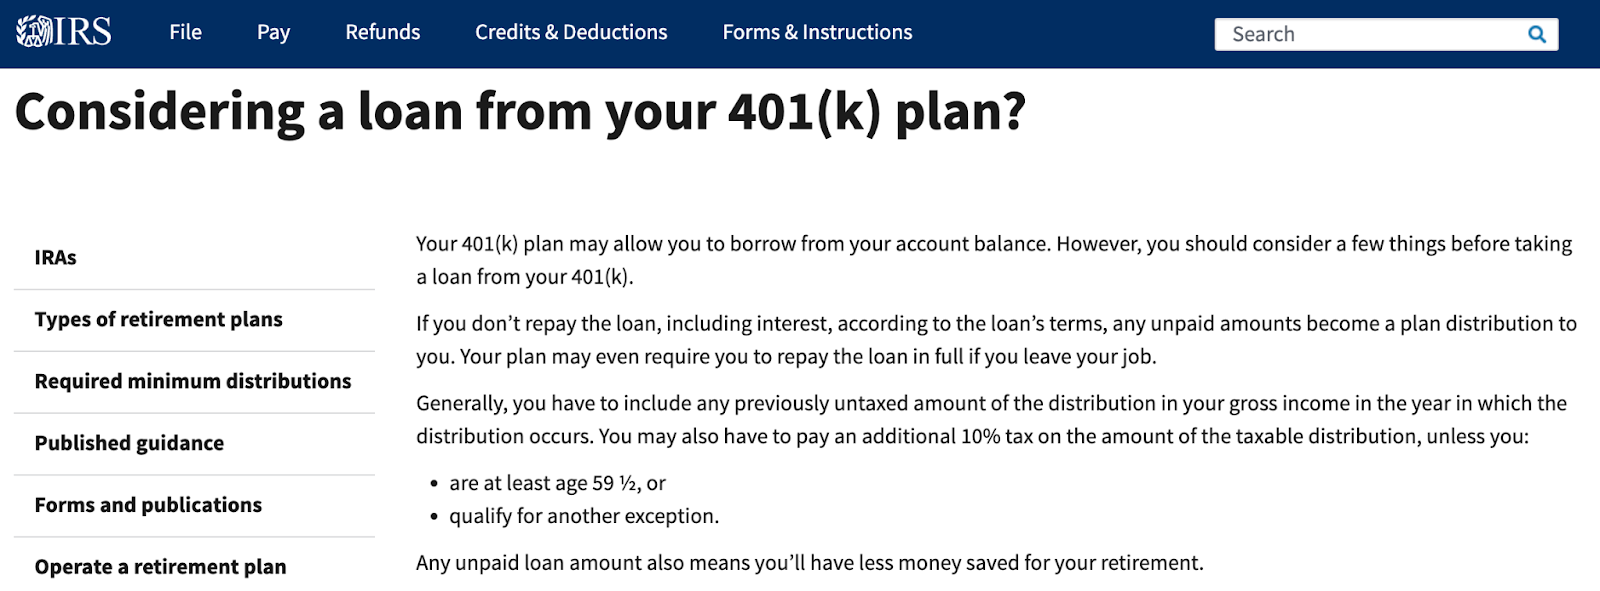
Borrowing from your retirement fund can provide a convenient source of financing for fix and flip projects, allowing you to avoid external lenders. Since you’re essentially borrowing from yourself, the interest payments contribute back into your account. 

However, it’s important you make some important considerations based on IRS guidelines:

  • If you fail to repay the loan according to its terms, any unpaid amounts may be treated as a distribution from your retirement plan.
  • You may need to include the previously untaxed amount in your gross income for the year of the distribution
  • Unless you meet exceptions, You might face an additional 10% tax.
  • Not repaying the loan can reduce your retirement savings.

To mitigate these risks:

  1. Ensure your repayment plan aligns with your project timelines and financial capabilities.
  2. Consider consulting a financial advisor to navigate the complexities of using retirement funds for real estate investments.

These steps are crucial to assess whether borrowing from your retirement fund is the best choice to fund your fix and flip projects.

You might also like: 1-800Accountant Reviews: Expectations vs Reality 

Seller Financing

Fix and flip loans for new investors

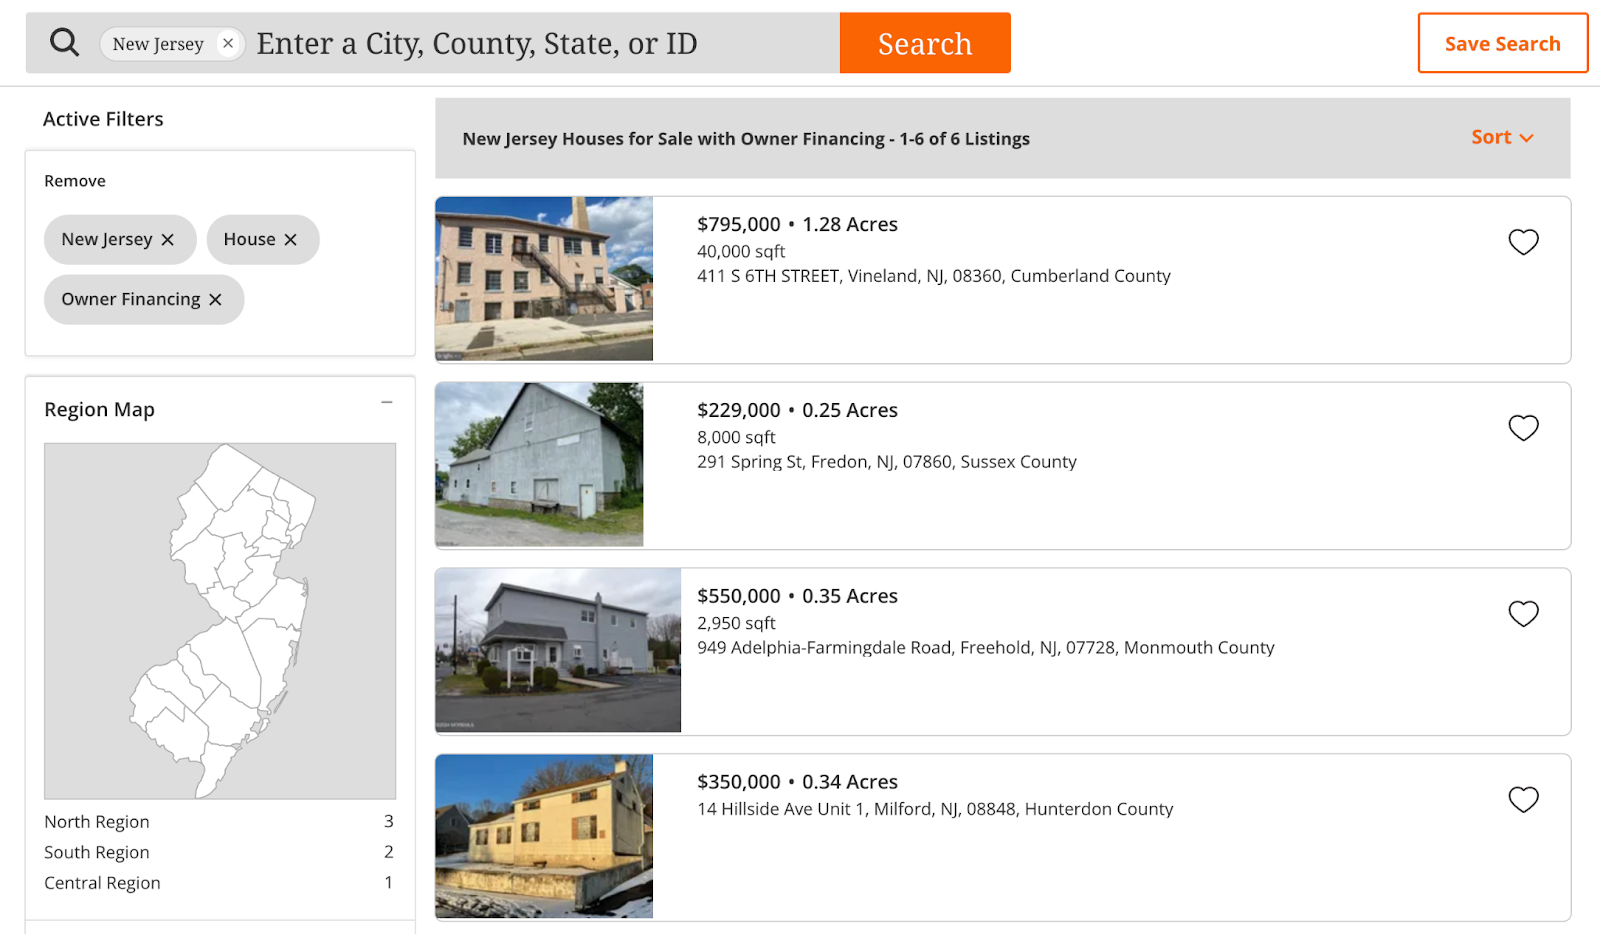
You may be able to leverage seller financing, also known as owner financing or seller carryback, when the property seller provides financing instead of or alongside a traditional mortgage lender—This arrangement can offer flexibility in terms, potentially lower costs, and a streamlined approval process. It’s particularly attractive if you may not qualify for a conventional loan. 

Now, while it seems like a great idea, it’s super important  to approach seller financing with caution. Conduct thorough due diligence on the property and negotiate clear terms with the seller to avoid misunderstandings or disputes later. 

Weigh the benefits against potential risks and consider seeking legal advice to ensure all agreements are legally sound and in your best interest. 

This is How to Qualify for a Fix & Flip Loan

Best fix and flip loans

Qualifying for a fix and flip loan hinges on several key factors that can significantly influence your ability to meet fix and flip loan requirements. 

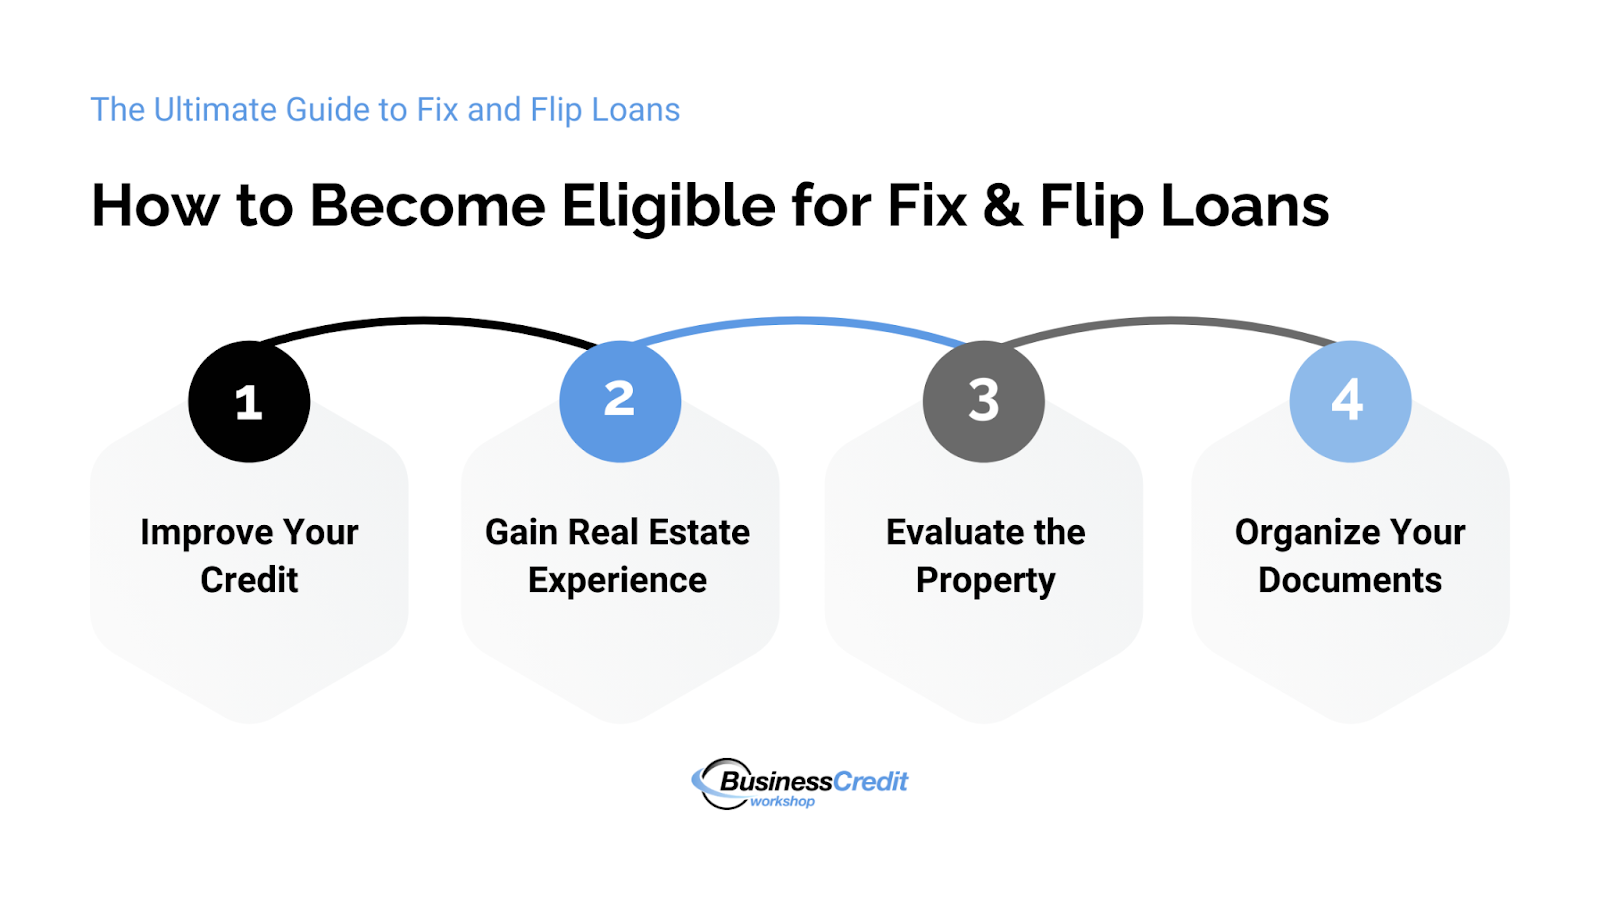
To enhance your chances of qualifying for a fix and flip loan and secure favorable terms:

  • Work on your credit score 
  • Build your real estate experience
  • Invest in the property evaluation process 
  • Get your documents organized 

By taking proactive steps to strengthen your financial profile and project plan, you can position yourself as a strong candidate for a fix and flip loan. Here’s a deeper dive into each factor to help you navigate the process effectively.

1. Get Your Credit in Check 

Improving your credit score is crucial before applying for a fix and flip loan. 

For personal credit, focus on paying down debts, correcting any errors in your credit report, and ensuring timely payments on all obligations—A higher personal credit score generally leads to better loan terms and lower interest rates, reflecting your financial reliability to lenders.

For business credit, maintain a good payment history with vendors and suppliers, and ensure your business accounts are separate from personal finances. A strong business credit profile demonstrates stability and can improve your chances of favorable terms for fix and flip loans. 

Lenders often consider both personal and business credit when evaluating your loan application, so strengthening both can enhance your borrowing options and overall financial position.

Recommended: This is How to Build Business Credit Fast [Step-by-Step Guide] 

2. Network With Other Real Estate Investors 

If you’re just starting with fix and flip projects, team up with seasoned investors or tackle smaller projects first to establish a track record. This builds credibility and gives you hands-on experience in real estate investing.

Having prior experience in real estate investment can significantly strengthen your standing with lenders. They often prefer borrowers who have successfully completed fix and flip projects before. This track record demonstrates your ability to handle property renovations and sales effectively, reassuring lenders about your capability to manage projects and repay loans on schedule. 

Note that, in some cases, lenders may even stipulate a minimum number of completed projects as a qualification requirement.

You might also like: The Best Credit Cards for Landlords: A Comprehensive Guide 

3. Learn How to Evaluate Properties Effectively

Make sure the property undergoes a thorough evaluation by a specialized real estate appraiser. A precise estimate of its after-repair value (ARV) supports your loan application and may increase your borrowing potential.

Lenders rely heavily on the ARV, which forecasts the property’s post-renovation worth. A professional appraisal is typically required to accurately determine the ARV, guiding the maximum loan amount based on future value. This calculation influences the loan-to-value (LTV) ratio, crucial for securing financing. Lenders also assess the property’s current state and location to gauge renovation feasibility and market potential.

Real estate investors commonly use two strategies to assess potential fix and flip profitability:

  • The 70% rule advises not paying more than 70% of the ARV minus repair costs. For instance, if a property’s ARV is $200,000 and repairs cost $40,000, the maximum purchase price should not exceed $100,000.
  • The 2% rule suggests that monthly rent should ideally be at least 2% of the property’s purchase price, primarily used for rental property evaluations.

These strategies help investors make informed decisions to optimize returns and minimize risks in real estate investment.

You might also like: Y Combinator: Fast Track to Success or Waste of Time? 

4. Get Really Good at Organizing Your Documents

Ensure you gather all required financial documents early in your loan application process. A well-organized project plan is crucial to show your readiness and dedication.

Thorough financial documentation is vital when applying for a fix and flip loan. Include recent tax returns, bank statements, and a detailed project plan outlining your renovation strategy and projected costs. 

Transparency about your financial status demonstrates your ability to manage the loan responsibly and gives lenders confidence in your financial management skills—This can enhance your chances of approval and may result in more favorable loan terms.

You might also like: Free, Printable Business Credit Application Template

Common Alternatives to Fix and Flip Loans

When traditional options won’t work, consider alternative funding options like cash reserves, crowdfunding, or joint ventures for your fix and flip project.

ProsCons
Cash Reserves No loan interest costs.Best for financial stability.No new debt obligations.Ties up liquidity.May limit opportunities.May reduce emergency funds.
CrowdfundingSpreads risk by pooling funds.Access to larger projects.Increases diversification.Limits control over choices.Potential project delays if goals are unmet.
Joint VenturesCosts shared with partnersRisks shared with partners.Access to capital and experience.Requires clear agreements.Highest potential for conflict or disagreements with partners.

In some cases, these alternatives can provide flexibility and leverage in financing your fix and flip ventures beyond traditional loan options.

With cash reserves or “personal capital,” you can use your personal savings to avoid loan interest costs. But, this may tie up liquidity, which can limit other investment opportunities or emergency funds. 

Crowdfunding platforms like Fundrise let you pool funds with others, spreading risk and accessing larger projects. It offers diversification, but may limit control over property choices.

Partnering with investors allows you to share costs and risks, which is beneficial if you lack experience or capital. Just make sure to establish clear agreements to manage expectations and ensure a successful partnership.

You might also like: Torro Business Funding Review: Is This Zero Hassle Offer Legit? 

Frequently Asked Questions

Can you get a fix and flip loan with bad credit?

Yes, but expect higher rates. Hard money loans may be an option as they focus more on the property’s value than the borrower’s credit score.

How do fix and flip loans differ from traditional mortgages?

They are shorter-term, have higher interest rates, and focus more on the property’s potential value rather than just your credit score and income.

What happens if you default on a fix and flip loan?

You may lose the property, and it can impact your credit score. It’s essential to have a solid exit strategy to avoid default.

How do you avoid taxes on a fix and flip?

Consider reinvesting profits into another property through a 1031 exchange to defer taxes. Consult a tax professional to understand your options.

Conclusion

Deciding on fix and flip loans comes with challenges and rewards. Understanding these loans—from hard money to personal funds—helps you fund projects wisely for better profits. Each loan type has things to think about, like fast cash or higher rates. Pick what matches your goals and risk level.

As you start your fix and flip journey, keep learning about markets, property checks, and money plans. This helps you make smart choices, lower risks, and grab good deals in real estate. Whether you’re new or a pro, using the right loans can make your fix and flip projects successful.

Ready for more? Look into loans, plan your investments, and jump into fix and flip real estate. Your path to money growth and real estate wins starts now!

Interested in using business credit to fund your fix and flip venture? To learn how to obtain up to $100K in business credit, join Business Credit Workshop today!
How to Get Money for Real Estate Investing: 18 Practical Ideas

By Joe

how to get money for real estate investing

When you want to invest in real estate, there are tons of guides out there to help you learn how to make money in real estate for beginners – and it’s easy to find information on rental income, real estate investment trusts (REITs), and property flipping. What isn’t so readily available is how to fund real estate investment or get money for real estate investing with little money. 

The knowledge is out there, but it’s typically scattered or comes in lists with very few details about how each funding option works. Here, I want to lay out the ways you can actually get money to start investing in real estate as soon as possible.

This is what’s in store: 

  • Do You Need to be Rich to Invest in Real Estate?
    • How Long Does it Take to Make Money From Real Estate Investments?
  • 18 Ways to Get Money for Real Estate Investing
    • 1. Conventional Mortgage
    • 2. Government-Guaranteed Mortgage
    • 3. Business Credit
    • 4. Home Equity Funding
    • 5. Real Estate Investor Line of Credit
    • 6. Installment Sale or Lease to Own (Seller Financing)
    • 7. Private or Hard Money Lender
    • 8. Wholesale
    • 9. Equity Partner
    • 10. Rent, Lease, or Sublet
    • 11. Rent Out Your Assets
    • 12. Renovate Your Budget
    • 13. Ask for a Raise
    • 14. Get a Second Job
    • 15. Save Every Penny
    • 16. Start a Business
    • 17. Network and Learn
    • 18. Research Local Grants
  • Frequently Asked Questions
  • The Bottom Line

Now, let’s get to it! 

Do You Need to be Rich to Invest in Real Estate? 

How to get money for real estate investing online

First things first: It might seem like the wealthy have the real estate investing market cornered. Whether individuals put their “riches” into real estate or they build fortunes by investing in properties isn’t important – there’s money in real estate. 

The good news is that you do not have to be rich to invest in real estate. Actually, the majority of Americans – 65.7% – own a home. And, this doesn’t account for those who have money in real estate investment pools and REITs, which require less investment than an outright property purchase.   

The bottom line is that anyone with a willingness to learn can invest in real estate. 

You might also like: This is How to Leverage Business Credit to Transform Your Life 

How Long Does it Take to Make Money From Real Estate Investments? 

How to get money for real estate investing without a

Real estate investment timelines vary depending on your strategy. If you’re flipping properties, you could see quick profits in a few months to a year—This involves buying distressed properties, renovating them, and then selling them for a profit. 

On the other hand, if you’re pursuing a buy-and-hold strategy, it may take longer to see significant returns. With this approach, you’re renting out properties for passive income and waiting for equity growth over time. You might start seeing positive cash flow within months to a year, but the real appreciation typically happens over years or even decades. 

Wholesaling is another option, where you find off-market deals and assign contracts for a fee—This can have a shorter timeline, sometimes just weeks to months. Lastly, investing in Real Estate Investment Trusts (REITs) offers immediate dividends from publicly traded real estate companies, with potential capital appreciation over time. 

Ultimately, your timeline will depend on your chosen strategy, market conditions, and the type of property you invest in.

You might also like: The BRRRR Method: A Real Estate Portfolio-Building Blueprint 

18 Ways to Get Money for Real Estate Investing

how to invest in real estate with no money

Now, explore the ways you can get more money to invest in real estate. From traditional methods to others you may not have heard of, here’s where you might be able to find the funds. 

Keep in mind that real estate, as with all other investment channels, comes with risks. You should always consult professionals when making investment decisions. 

You might also like: How to Raise Money for Real Estate Investment: A Beginner’s Guide 

1. Conventional Mortgage

A conventional mortgage is a loan offered by traditional financial institutions like banks or credit unions. It’s probably the most common funding option for real estate investing. 

 To qualify, you typically need: 

  • A good credit score
  • Stable income
  • A down payment (up to 20% of the property’s purchase price) 

This option won’t work for those with poor credit or limited savings for a down payment.

You might also like: Can You Pay a Mortgage with a Credit Card? The Answer is… Complicated 

2. Government-Guaranteed Mortgage

Government-guaranteed mortgages, like USDA loans, FHA loans, or VA loans, are backed by government agencies—This makes them more accessible if you have a lower credit score or smaller down payment. 

Qualification criteria vary depending on the specific program, but they generally have less stringent requirements compared to conventional mortgages. 

  • See if you qualify for a USDA loan. 
  • See if you qualify for an FHA loan. 
  • See if you qualify for a VA loan (veterans only). 

These mortgages may not be suitable if your income is on the high side or you don’t meet the criteria.

Another option in this realm worth looking into is Habitat for Humanity’s homeownership program. However, there is the caveat that you must live in the home for a set amount of time and it must be your primary residence—This may not be suitable if you want to invest in multiple properties or implement a short-term investment strategy. 

3. Business Credit

Using business credit to fund real estate investments involves obtaining loans or lines of credit in the name of a business entity. Qualifying often requires a solid business plan, good credit history for the business, and potentially collateral. 

This method won’t be workable if you don’t yet have an established business or you’re unable to meet the credit requirements. But, here at Business Credit Workshop, we teach you how to set up your business to be “credit ready” and how to obtain up to $100K in business credit.

Recommended: How to use Business Credit to Buy Real Estate! 

4. Home Equity Funding

Home equity funding involves borrowing against the equity in your primary residence. Qualifying typically requires sufficient equity in your home and a good credit score. Look into home equity loans and home equity lines of credit (HELOCs). 

If you don’t own a property, you won’t be able to qualify for home equity funding. And, this option may not be suitable if you have little equity or are uncomfortable risking your primary residence as collateral.

5. Real Estate Investor Line of Credit

A real estate investor line of credit provides flexible financing for real estate investments. 

Qualifying may require: 

  • A good credit score
  • A track record of successful real estate investments
  • Possibly collateral

This option might not work for inexperienced investors or those with poor credit. It’s better-suited to seasoned investors. 

6. Installment Sale or Lease to Own (Seller Financing)

An installment sale, also known as seller financing, involves the seller acting as the lender and financing the purchase of the property for the buyer. You may think this is an impossible strategy if you’ve never done it, but you’d be surprised at how often this actually happens.

You’ll typically need to negotiate with the seller and agree on terms—Most sellers would want to see that you can get a conventional mortgage or some other way to make a balloon payment at the end of the terms. 

Related to seller financing, lease-to-own financing allows a buyer to rent a property with the option to purchase it later. In contrast, an installment sale involves buying property through periodic payments, with the buyer gaining ownership gradually. 

The main difference is that in lease-to-own, ownership transfers after the final purchase, while with seller financing, the buyer typically has equitable ownership from the start. These methods may not be feasible if the seller is unwilling or unable to offer an agreement like this or if the buyer cannot negotiate favorable terms.

7. Private or Hard Money Lender

Private money lenders and hard money lenders are typically private companies or individuals that offer short-term loans secured by real estate. 

Qualifying may require: 

  • A solid investment strategy
  • Collateral
  • A realistic plan for repayment

This option might not work when you’re unable to meet the lender’s requirements or if you’re seeking long-term financing.

You might also like: A Review of Alpha Funding Partners – Are Their Solutions Right for You? 

8. Wholesale

Wholesaling involves finding discounted properties and assigning the purchase contract to another buyer for a fee. 

Qualifying doesn’t typically require a large amount of capital but does require finding motivated sellers and buyers—you have to flex your sales muscles. 

This method may not be suitable if you don’t have strong negotiation skills or you’re unable to find profitable deals.

9. Equity Partner

An equity partner is someone who invests capital in a real estate venture in exchange for a share of the profits. You have to find a suitable partner and negotiate terms. 

Think of it like an angel investor or similar situation wherein you do most of the hands-on work and the investor takes a cut of your profit in exchange for an initial payment. 

This option may not work if you’re uncomfortable sharing ownership or decision-making authority.

10. Rent, Lease, or Sublet

Renting, leasing, or subletting property to generate rental income requires being in control of real estate assets. In most cases, you must own the property. But, if the owner or property manager approves, you can lease or rent then sublet for profit. 

You might earn rental income off of: 

  • Residential homes
  • Commercial properties
  • Rooms or office space
  • Empty lots

You’ll need to take control over suitable properties, market them to tenants, and manage the property. 

This option only works if you can access investment properties and you need to be able to manage rental properties effectively.

You might also like: The Best Credit Cards for Landlords: A Comprehensive Guide 

11. Rent Out Your Assets

Renting out assets like a car, truck, trailer, or tool can generate additional income. You can use online platforms and marketplaces to list your assets, or even create your own website. And, you will need to make sure you’re properly insured to cover any damages and licensed if this is required in your location. 

You’ll need suitable assets available for rent and to market them effectively. People might be interested in renting anything from utility trailers to bounce houses and power tools.  

This won’t work if you don’t have assets to rent or you’re uncomfortable with others using your possessions.

12. Renovate Your Budget

Renovating your budget involves cutting unnecessary expenses and reallocating funds toward real estate investments. You just need to assess your current financial situation and make adjustments to prioritize saving and investing. 

If you have limited disposable income or you’re unwilling to make sacrifices to fund investments, this may not help you—In some cases, budget readjustment will only help you get money for real estate investing after you increase your income. 

You might also like: Meet the Ava Card: An Uncut Credit Builder Review 

13. Ask for a Raise

Asking for a raise at your current job can increase your income and potentially provide additional funds for real estate investments. You’ll need to demonstrate your value to your employer and negotiate a salary increase. 

This option may not work if you’re in an industry with limited salary growth potential or you’re too uncomfortable to negotiate with your employer.

14. Get a Second Job

Taking on a second job can provide extra income to fund real estate investments. All you need is a suitable employment opportunity and to balance the demands of multiple jobs. 

This option may not be feasible if you have limited availability or you aren’t able to secure additional employment. But, skills training can help you get there. 

15. Save Every Penny

Saving aggressively by cutting expenses and increasing savings contributions can help accumulate funds for real estate investments over time.You’ll need discipline and commitment to a savings plan. 

This option may not be the best fit if you have high living expenses or you’re not willing to make sacrifices to save money.

16. Start a Business

Starting a business that generates income can provide capital for real estate investments. You’ll have to identify a viable business opportunity and secure funding or investment capital. But, you might be able to start without much initial investment if you leverage assets that are right in front of you. 

The business will need to fit your skill set. But, I’ve seen people create businesses from scratch with nothing. As an idea, you could find free furniture on Craigslist, paint it, and resell it for a profit. Or, you could resell used books or other small items on an online marketplace.  

This option isn’t great if you don’t have entrepreneurial skills or you aren’t able to manage the demands of starting and running a business.

You might also like: How to Create a Business Credit “Entity” 

17. Network and Learn

Networking with experienced real estate investors and learning from their expertise can provide valuable insights and opportunities for partnerships or joint ventures. Look to local real estate investing groups, the Chamber of Commerce, and other related groups to get started. 

To make this work, you’ll need to actively participate in networking events and seek mentorship. You have to be willing to invest time and effort into building relationships and acquiring knowledge.

18. Research Local Grants

Researching local grants or assistance programs for real estate investors can provide funding opportunities or incentives for investment projects. Local nonprofits are a good place to start.

You’ll need to identify relevant grant programs and meet their eligibility criteria. 

This option won’t work out if you or your property is located in areas with limited grant availability or you’re ineligible for the specific programs. But, particularly in low-income or rural areas, you could be pleasantly surprised at what you can unearth—it’s definitely worth looking into. 

You might also like: A Full Skip Review: Business Grants, Funding, + More 

Frequently Asked Questions

What is the smartest way to invest in real estate? 

The smartest way to invest in real estate depends on your financial goals, risk tolerance, and available resources. Generally, strategies like buy-and-hold rental properties, house hacking, or investing in REITs are considered “smart” options to build long-term wealth.