• Home
  • Free Funding Guide
  • What We Offer
    • Products
    • Services
    • Free Guide
  • About Us
  • Contact
  • Sign Up

  • Ask Joe Any Question!
  • Business Credit Cards
  • Business Line of Credit
  • Topics

What You Need to Know About PayPal LoanBuilder for Business

By Joe

PayPal Loan Builder

PayPal LoanBuilder is advertised as a quick, convenient way to get up to $100K in business funding. The company is more than reputable, and their marketing makes it sound like the easiest financing option in the world. But, what are the terms, how much does it cost, and is this really the best loan for your business? 

Let’s find out what LoanBuilder is, how it works, and explore exactly what you can expect if you apply. 

This is what’s in store: 

  • What is PayPal LoanBuilder?
    • How Much Does PayPal LoanBuilder Cost?
  • How Does PayPal LoanBuilder Loan Work?
    • 1. Apply With No Impact to Your Credit
    • 2. “Customizable” Funding
    • 3. Fixed-Fee Loan
    • 4. Fast Access to Funds
    • 5. Accessible Business Funding
    • 6. Weekly Repayment Terms Up to 12 Months
  • Frequently Asked Questions
  • Final Thoughts

Now, let’s get to it! 

What is PayPal LoanBuilder? 
Loan Builder PayPal

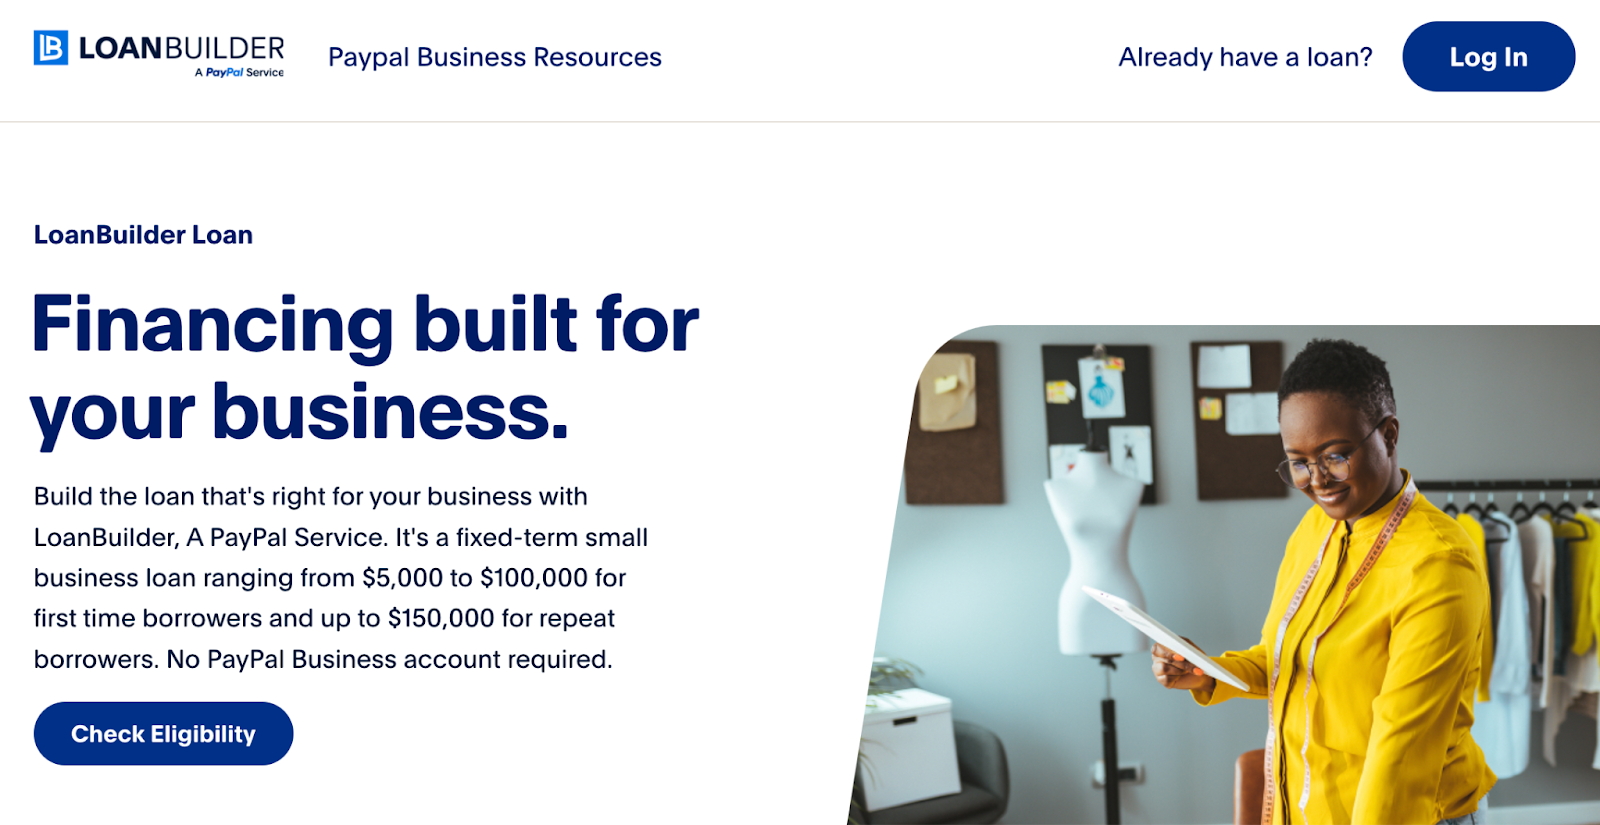
PayPal’s LoanBuilder is a service that offers fixed-term small business loans from $5,000 to $100,000 for first-time borrowers and up to $150,000 for repeat borrowers—the financing option is designed to be fast and flexible, with funds potentially available in your business bank account as soon as the next business day after approval.

The loan comes with transparent pricing, where you pay a clear, fixed fee along with a $20 Returned Item Fee if a payment is returned. There are no late fees, early repayment fees, or processing fees. You can choose a repayment term that suits your business needs, and payments are automatically deducted weekly.

To check if your business is eligible for a LoanBuilder Loan, you can complete a quick online questionnaire. This process won’t impact your personal credit score. If eligible and approved, you can customize your loan amount and term, sign the contract electronically, and receive the funds quickly.

To qualify, your business needs to have been operational for at least nine months with an annual revenue of at least $33,300. Keep in mind that LoanBuilder is a service provided by PayPal in partnership with WebBank. The loan application and approval process is designed to be straightforward and streamlined, aimed at helping businesses manage cash flow, finance projects, or tackle other business challenges.
paypal loanbuilder requirements

A LoanBuilder loan does require a personal guarantee. 

You might also like: Business Credit Cards without Personal Guarantee 

How Much Does PayPal LoanBuilder Cost? 

The cost of a LoanBuilder loan is determined by a single fixed fee known as the Total Loan Fee, which will be disclosed at the time of loan approval and remains consistent throughout the loan term. 

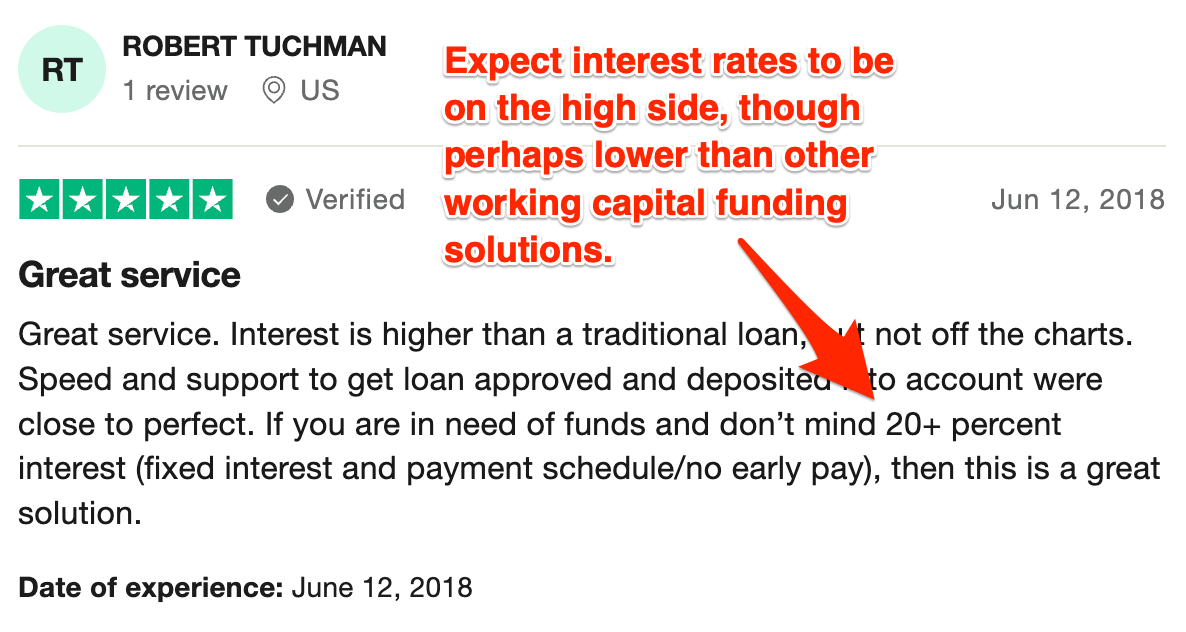
However, since this is a working capital-style loan, you should expect interest rates higher than you would get via, say, your business credit union. Still, they may be lower than other working capital solutions. 
PayPal Loan Builder interest rate

The specific amount of the Total Loan Fee varies based on: 

  1. The loan amount
  2. Repayment term
  3. Financial risk

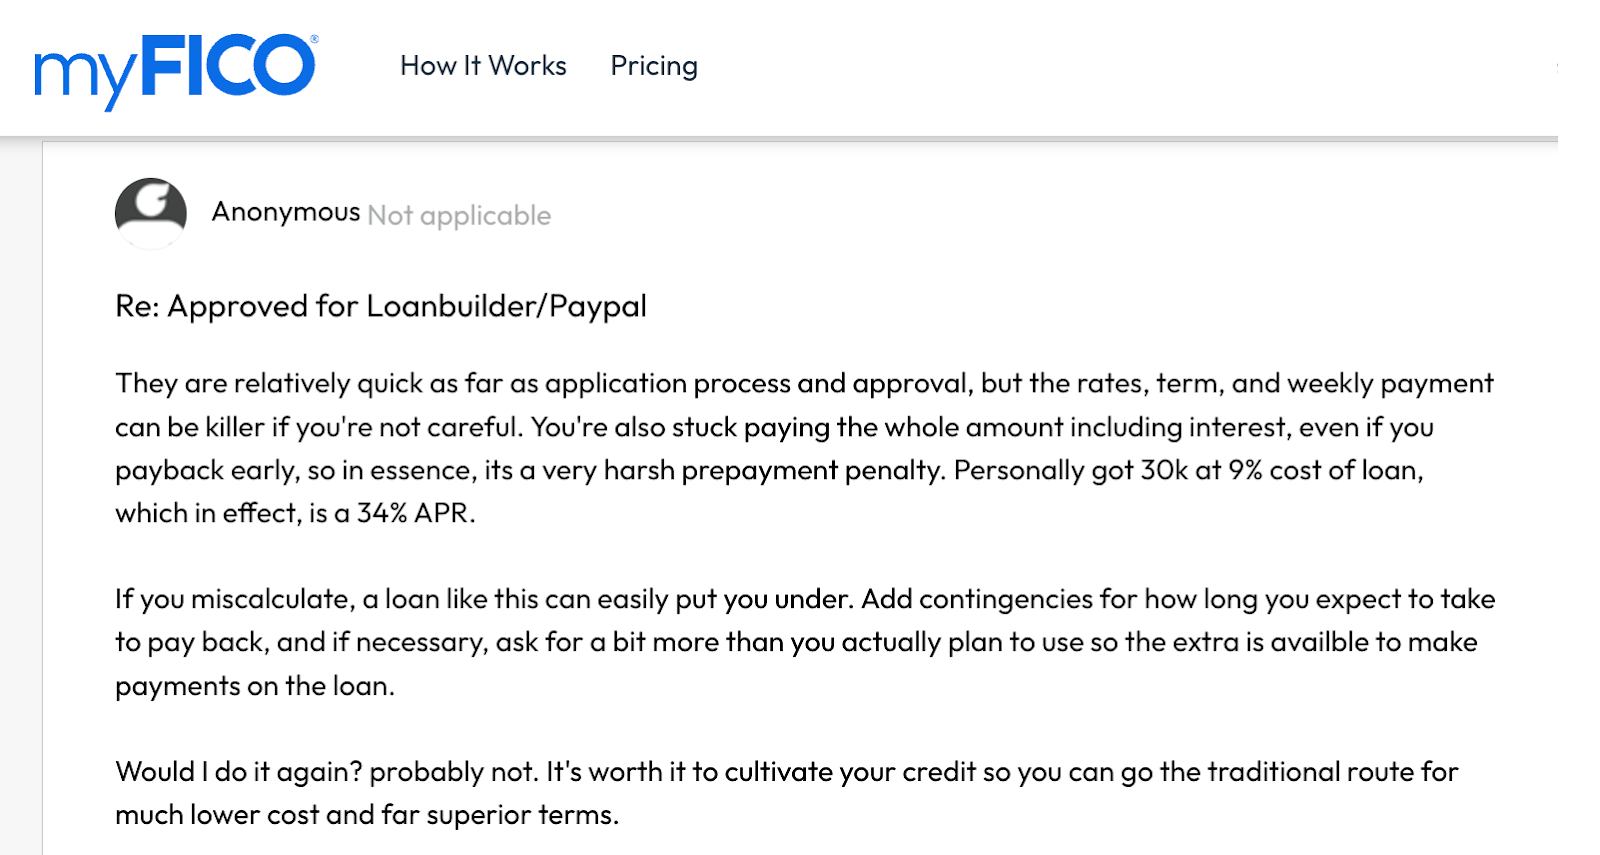
LoanBuilder Loans do not have additional fees such as late fees, early repayment fees, or processing fees—The Total Loan Fee is the primary cost associated with borrowing and is included in your repayment schedule.
Paypal loanbuilder review

To see your LoanBuilder cost, you’ll need to complete the loan application process and review the personalized terms.

Recommended: 3 Best Credit Unions for Small Business Banking

How Does PayPal LoanBuilder Loan Work? 

LoanBuilder from PayPal offers a pretty simple approach to business financing, providing you with a customizable loan experience tailored to your business needs. 

With LoanBuilder, you have the freedom to: 

  • Access funds quickly
  • Repay with clarity
  • Benefit from straightforward terms 

Let’s delve into the key features that will help you decide if LoanBuilder is the best choice for your business funding.

You might also like: A Deep-Dive National Funding Review: Should You Accept an Offer? 

1. Apply With No Impact to Your Credit
PayPal Loan Builder application

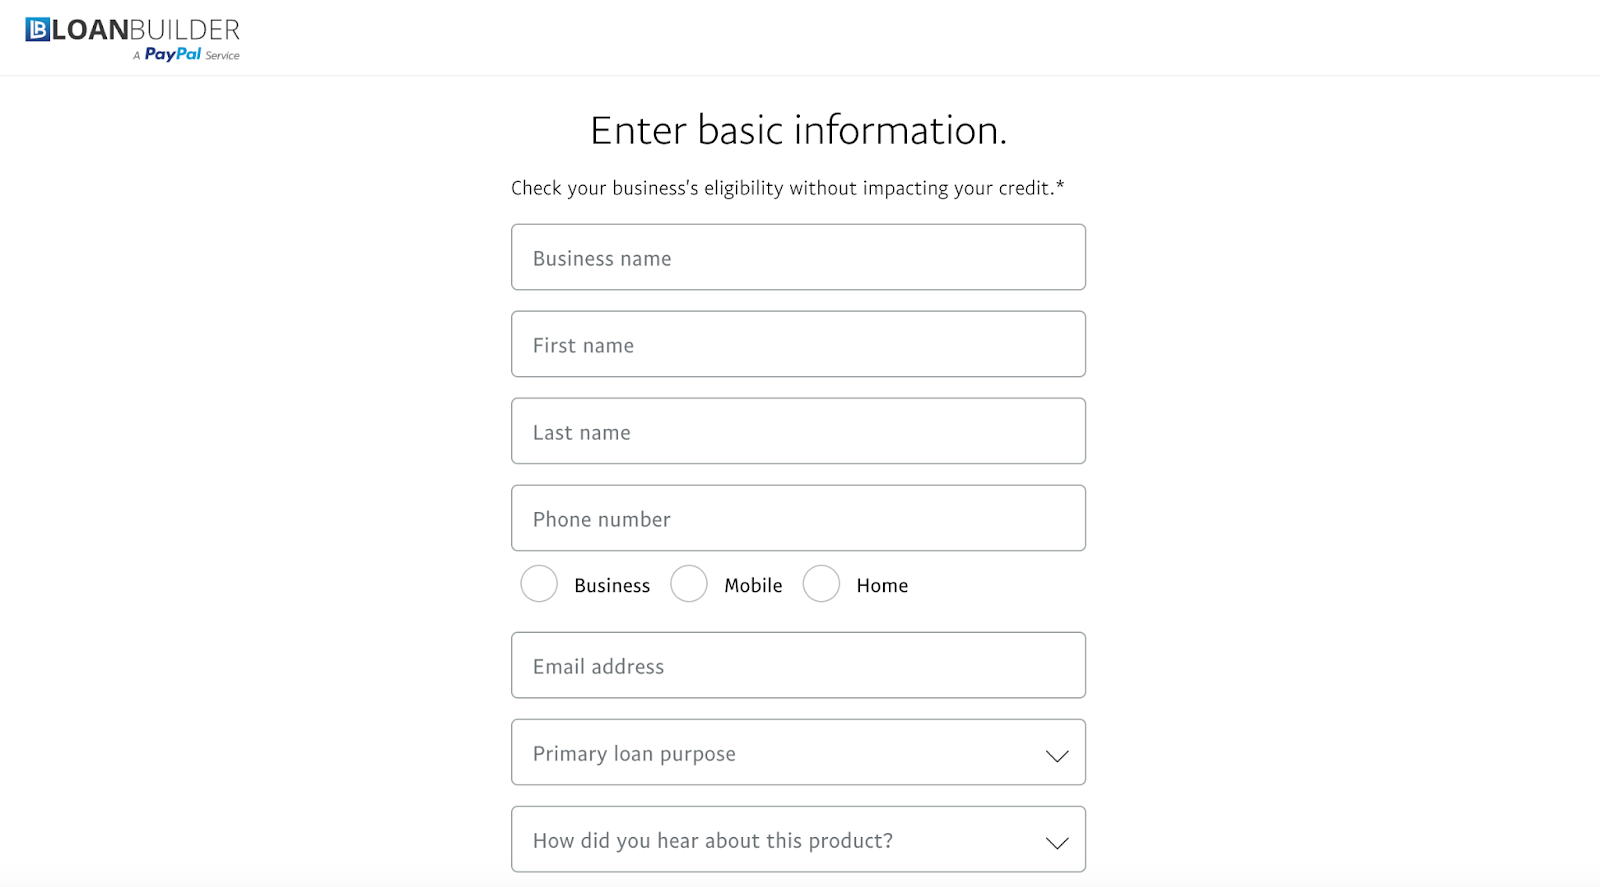
The PayPal LoanBuilder “application” is pretty straightforward. The questionnaire asks you for contact information, how you plan to use the funds, how you heard about the loan, business location, and business details. 

Details to have on-hand about your business include: 

  • Legal business name & DBA (if applicable)
  • Business address & website address
  • Entity type & state of incorporation
  • Annual revenue
  • Business start date
  • Number of employees
  • Industry & sub-industry
  • Percentage of ownership 

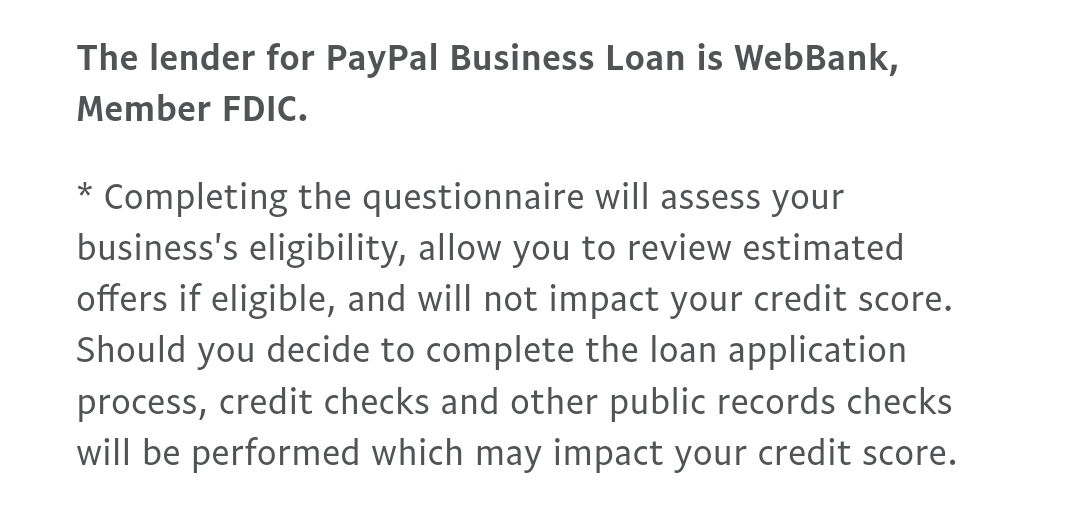
The application also asks for your Social Security Number and Employer Identification Number. Luckily, they do a soft inquiry into your personal credit for pre approval, which won’t negatively impact your credit score. 
PayPal Loan Builder soft inquiry

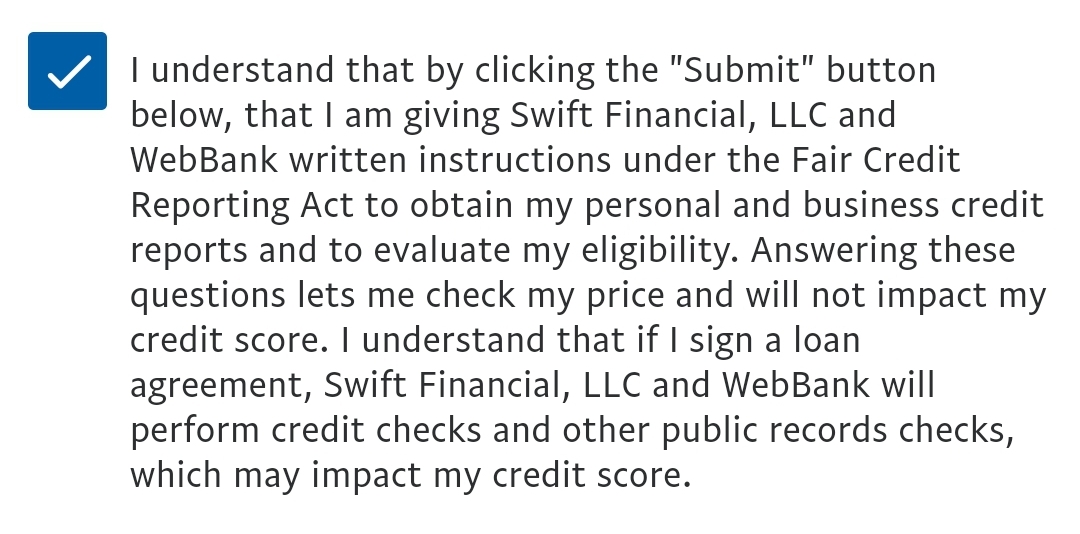
However, you will probably have to approve a hard pull for final approval. 
PayPal Loan Builder Hard Inquiry

Don’t move forward with that until you’re absolutely sure you want this loan.  

You might also like: Here’s How to [Actually] Get Business Credit With Just an EIN +More Options 

2. “Customizable” Funding
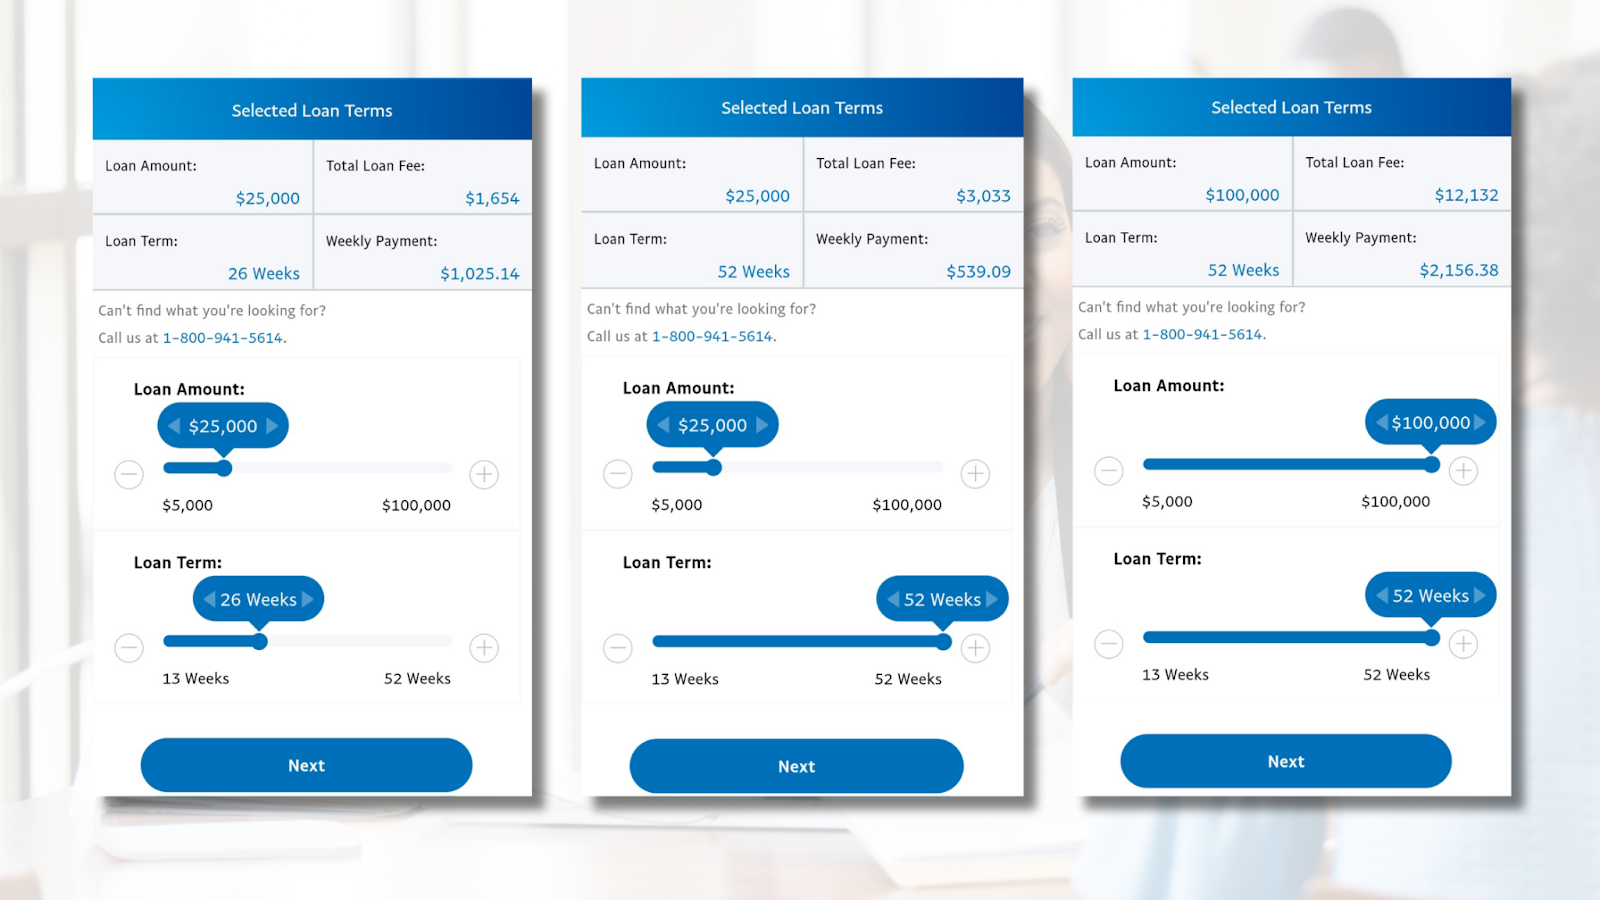
PayPal LoanBuilder Customized Loan

LoanBuilder advertises a “customizable” loan—This makes it sound as if you might get to choose your amount, terms, and rate, which would be pretty exciting. 

However, that’s not a realistic way to think about lending; lenders need to assess the financial risk before approving any type of financing. 

Still, after you’re pre-approved for a loan, you can choose your loan amount and repayment term. Your loan fee percentage will increase as your terms are extended. So, the longer you give yourself to pay off the loan, the higher your Total Loan Fee. 

If you do opt for this loan, consider giving yourself some extra time to pay it just in case something unexpected occurs, as you could be charged penalties for failing to pay on-time.  

3. Fixed-Fee Loan
PayPal Business Loan Builder

When you take out a LoanBuilder Loan, you won’t have any upfront fees deducted from the loan amount you receive. Instead, the cost of borrowing—the single fixed fee, known as the “Total Loan Fee”—is spread out and paid gradually over the entire duration (life) of the loan.

Here’s a breakdown of what this means:

  • When you receive the loan amount, the full sum is deposited into your business bank account without any immediate deductions for fees or charges. This ensures that you have access to the entire loan amount upfront to use for your business needs.
  • The cost associated with borrowing the money is represented by a single fixed fee—This fee is agreed upon and disclosed at the time of loan approval; it does not change over the course of the loan.
  • Rather than paying a fee upfront or separately, it is integrated into your loan repayment schedule. Each time you make a repayment towards your loan (typically on a weekly basis), a portion of that payment goes towards covering the Total Loan Fee. This fee is gradually paid down along with the principal amount of the loan.

By structuring the loan this way, you get clarity on the total cost of borrowing from the outset, and you can plan your repayments knowing how much will be allocated towards the loan principal and how much towards the fixed fee. 

4. Fast Access to Funds
PayPal Builder Loan

The LoanBuilder lending process is designed to be fast… 

First, when you check your eligibility, it’s done through a quick online questionnaire. This initial eligibility check does not involve a hard inquiry on your personal credit report, which means it won’t affect your consumer credit score—This is helpful because you can explore loan options without worrying about potential negative impacts on your credit rating.

If your LoanBuilder Loan application is approved, the funds are transferred directly to your business bank account, often by the next business day after approval—This rapid transfer ensures that you can access the funds quickly to address business needs or capitalize on opportunities right away.

5. Accessible Business Funding
PayPal Loan Builder login

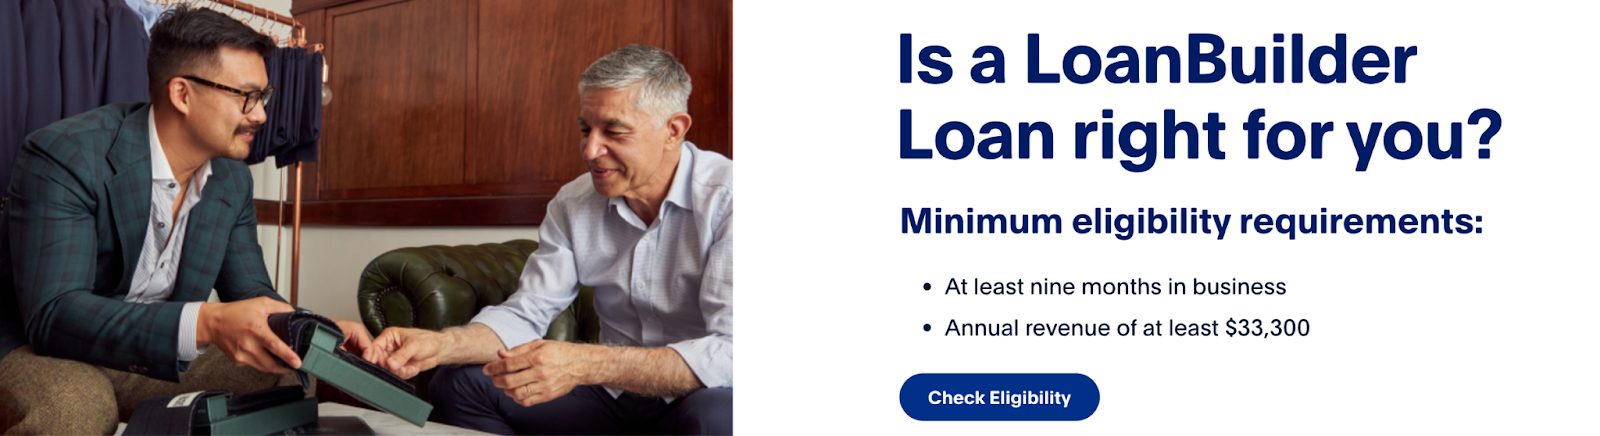
The eligibility requirements for a LoanBuilder Loan can be considered relatively low compared to some traditional business loans:

  • At least nine months in business
  • $33.3K annual revenue 

Requiring a minimum of nine months in business is relatively short compared to other types of business loans that might need several years in operation. Newer businesses can access financing sooner in their development stages.

While this amount varies depending on the size and industry of your business, $33,300 annual revenue is a moderate threshold—It’s achievable for many small businesses, including startups and those in their early stages of growth.

These requirements are inclusive and accessible to a wide range of small businesses, including startups and those with modest revenue streams. 

You might also like: Y Combinator: Fast Track to Success or Waste of Time? 

6. Weekly Repayment Terms Up to 12 Months
PayPal Loan Builder Funding

The repayment period for LoanBuilder Loans ranges from 17 weeks (approximately 4 months) to 52 weeks (approximately 12 months), depending on your eligibility and the loan amount you qualify for.

During the repayment period, you will make weekly payments towards your loan balance. 

The amount of each weekly repayment will be set based on: 

  1. The total loan amount
  2. The fixed fee associated with the loan
  3. The chosen repayment term

The weekly repayment amount remains consistent throughout the repayment period, providing predictability in your loan payments.

For example, if you have a loan with a 26-week repayment term, you will make 26 weekly payments until the loan is fully repaid. The amount of each weekly repayment is calculated to cover both the principal loan amount and the fixed fee—this helps you make sure the loan is paid off by the end of the chosen repayment term.

Frequently Asked Questions

Is PayPal legally a bank? 

No, PayPal is not a bank. It is a technology company that provides online payment services and financial solutions.

What bank does PayPal use for loans? 

LoanBuilder loans are provided by WebBank®, Member FDIC, in partnership with PayPal.

What is the minimum credit score for LoanBuilder? 

LoanBuilder does not disclose a specific minimum credit score requirement. Instead, eligibility is determined based on various business factors such as revenue and operational history—but the do require a personal guarantee

Does PayPal LoanBuilder report to credit bureaus? 

Yes, PayPal LoanBuilder reports payment activity to business credit bureaus, not personal credit bureaus. This can help businesses establish and build their business credit profile.

Final Thoughts

PayPal is a trustworthy financial company, with LoanBuilder being backed by a reputable bank. The loans they offer are pretty competitive in the working capital realm, but the high rates are a red flag for me. I never recommend my students take out a loan like this unless there is absolutely no better option—even with a flat fee, weekly repayments can eat at your profits.  

But, if you need to take out a high-interest loan and you’ve explored all of your options, this might be the way to go. If you have some time, I recommend you put some effort into your business credit so you can get loans and lines of credit with (much) better terms…it’s a game changer.  

Do you want to learn how to obtain up to $100K in business credit in as few as 30 days? Join Business Credit Workshop today! 

Plastiq Review: Can Plastiq Really Simplify Your Finances?

By Joe Lawrence

plastiq review

As you juggle numerous responsibilities, managing finances and making payments can often feel like a tightrope walk. This is where Plastiq comes into the picture. Plastiq is a platform offering financial services that promises to simplify bill payments and streamline financial transactions for both individuals and businesses.

In this Plastiq review, we will delve into the platform’s benefits, features, and more to help you decide whether it is worth considering or if you should explore other options. Let’s begin!

Contents

  • What is Plastiq?
  • Who Can Use Plastiq?
  • Features and Benefits of Using Plastiq
  • How Much Does Plastiq Cost?
  • Privacy and Security Concerns
  • Some Limitations and Other Considerations to Be Aware Of
  • Verdict

What is Plastiq?

Plastiq aims to streamline cash flow management for businesses (and individuals) by providing instant access to working capital. Utilizing the platform enables you to make payments with credit cards, even if the merchant or supplier doesn’t accept cards. This flexibility allows you to cover a variety of expenses, from rent to taxes, as well as supplier payments, while leveraging existing credit card rewards and favorable payment terms.

To use Plastiq, you’ll need to first sign up and verify your account. Additionally, you’ll need to add a payment method, such as a credit card, bank account, or debit card. Here’s a step-by-step guide to making a payment:

Input the payment details, including the recipient’s information and the amount.

Choose the recipient, who can range from contractors and government agencies to suppliers and landlords. Plastiq accommodates various payment types, including bills, invoices, and other obligations.

Select the payment method, typically a credit card such as Visa, Mastercard, Discover, or American Express—all of which Plastiq accepts. Alternatively, you can use debit cards, checks, or bank transfers.

After choosing the payment method, schedule the payment or set up recurring payments for your bills.

Once confirmed and scheduled, Plastiq will process the payment on your behalf, charging the amount to your credit card and any applicable fees. The payment is then automatically sent to the recipient via their preferred method, such as a physical check, wire transfer, or ACH transfer.

Track your payment status on the platform and access your payment history to maintain organized records of your financial transactions involving Plastiq.

Unlocking working capital while automating your payables operation can help you maintain a healthy cash flow. This saves you valuable time that would otherwise be spent manually entering bills and making individual payments. With Plastiq, you can pay your suppliers promptly using their preferred payment methods while choosing the one that best suits your needs.

Who Can Use Plastiq?

Plastiq can be utilized by a wide range of individuals and businesses, but it is particularly well-suited for the following:

Business Owners: If you operate a business and wish to leverage credit card rewards and benefits for your expenses, Plastiq is an excellent option. You can use it to pay for expenses traditionally not accepted via credit cards, such as utility bills, taxes, and rent.

Real Estate Investors: You can use a business credit card as a down payment to buy real estate by sending the money from your credit card to the title company for the closing. Many readers ask how to pull cash off credit cards and this is one option to do it.

You might also like: The BRRRR Method: A Real Estate Portfolio-Building Blueprint

Individuals: Plastiq is beneficial for individuals managing significant expenses. For example, real estate investors who need to make real estate-related payments can streamline their transactions with Plastiq while earning credit card points.

Small Business Owners and Freelancers: Whether you’re a freelancer or run a small business, maximizing cash flow is essential. Plastiq allows you to extend payment terms using a credit card, freeing up cash for other business needs while covering expenses on credit.

Individuals or Entrepreneurs Seeking to Streamline Payables: Simplifying payable processes is crucial in today’s fast-paced world. Plastiq’s integration with Automatic Data Processing (ADP), a leading provider of payroll and human resource management solutions, enables you to fund your business’s payroll with a credit card. The funds are then automatically processed through ADP’s payroll system, facilitating employee payments.

Merchants and Service Providers: Plastiq Accept, discussed below, allows users to receive credit card payments from customers. This service enhances transaction convenience for buyers and customers who prefer credit card payments.

Plastiq is an excellent option for individuals and businesses seeking to leverage their credit card’s credit line for various types of payments. It facilitates transactions where credit cards are generally not accepted.

Features and Benefits of Using Plastiq

Plastiq has a set of features for facilitating payments and managing cash flow, which include:

Plastiq Pay: Businesses and individuals can use Plastiq Pay to pay via credit cards. You can pay by card, such as your credit card, allowing you to fund payments automatically. These payments can be anything from vendor payments to payroll. This feature is particularly useful if you run a business and are looking to leverage credit card rewards. You can also use Plastiq Pay to extend your payment terms without needing the recipient to accept credit card payments directly.

plastiq-accept

Plastiq Accept: If you need to accept payments, Plastiq also has this feature for receiving payments from customers wanting to pay by credit card. Use Plastiq Accept so you can streamline the receivables process of your business. Accept is great for landlords, contractors, and other merchants or small businesses that do not usually take credit cards as a payment method.

If you wish to use both Pay and Accept, you can get more with Plastiq Connect, which is more comprehensive than the two products mentioned. There are also Pro and Enterprise plans, which you may be interested in, as they can benefit your business transactions. For a monthly fee, you can sync up your accounting software and make payments even more straightforward with scheduled bulk payments.

Plastiq offers plenty of benefits to its users, including payment flexibility. Users can pay bills and expenses with credit cards, manage their cash flow, and even leverage credit card perks, benefits, and rewards.

Plastiq also gives you more payment options in transactions where you typically cannot pay with a credit card. You can use Plastiq to pay for the following expenses:

  • Bills and utilities, such as gas, water, electricity, Internet, and phone
  • Rent
  • Mortgage
  • Tuition
  • Taxes, such as income taxes and property taxes
  • Government fees
  • Suppliers, vendors, contractors, and service providers
  • Subscription services, including subscriptions to streaming platforms, software, and gym membership
  • Business expenses, such as office supply and equipment purchases, as well as advertising and travel costs

Plastiq is not only for businesses but also for personal expenses. You can use it to pay for groceries, entertainment, charitable donations, and shopping.

paying vendors and credit cards with plastiq

Here is another reason why you will like Plastiq. Plastiq’s platform is easy to use and understand, even if you are a new user. The interface is uncomplicated, so you can complete the payment process in just a few minutes by providing the payment details and the merchant’s choice method.

One more benefit is that Plastiq prioritizes the security of the users. The platform has robust encryption and other security measures. That is to ensure your personal and financial data stays protected in every transaction. We talk more about this subject later in the article.

If you have a small business, you will surely benefit from Plastiq’s short-term financing offers, which typically come with extended payment terms. You can immediately get funding for lines up to $100,000, which you can pay for up to 90 days. If you are qualified and accept the additional review Plastiq requires for loans, you may be able to borrow more, even up to $750,000.

How Much Does Plastiq Cost?

Unfortunately, Plastiq is not free, but there is a free trial for the first 60 days when you sign up for either Pay or Accept. But free does not mean completely free because charges apply for all transactions done via Plastiq. You will have to pay a convenience fee, which depends on various factors, including the payment amount, recipient, and method. Don’t worry; you will know how much the fees will be before you complete a payment transaction. That way, you can cancel the payment if you are unhappy with the additional charge.

plastiq pricing

Plastiq’s pricing model, as mentioned, is based on a per-transaction fee. Let us break it down:

Plastiq Pay: Unlike some competitors, this service starts at a $0 one-time purchase, meaning you do not have to pay to subscribe. However, you will incur transaction fees every time you use your credit card to pay an expense or bill.

Plastiq Accept: There is also no subscription cost for the Accept service, but transaction fees apply whenever you use Plastiq to accept payments.

The transaction fee is typically a percentage of the total payment amount, although it can vary based on the payment method and recipient. You can expect to pay anywhere from 1.5% to 2.85% of the amount you paid the merchant.

Other fees you should know about include:

Credit Card Processing Fee: You have other payment options with Plastiq aside from credit cards. However, if you choose credit, the platform may charge an additional processing fee, which your credit card network or processor charges you. Note that this is separate from the transaction fee imposed by Plastiq. The processing fee depends on your credit card and may range from two to three percent of the payment amount, but typically around 2.90%

Domestic Wire Transfers: Sending money to anywhere in the US costs $5 to $8.99.

Currency Conversion Fee: If you plan to pay in another currency, you must be aware that you could be charged a conversion fee. Once again, this fee is based on the percentage of the amount of payment you need to make, covering the cost of converting your transaction into another currency. Expect to be charged anywhere from one to three percent of the payment amount for this fee, or $39, whichever is higher.

Late Payment Fee: Plastiq may charge you a late payment fee, which is generally assessed if the payment is not processed on time or if you fail to pay by the scheduled payment date. Not only that, you also ding your credit score. The good news is that Plastiq offers earning Fee-Free Dollars (FFDs), which are usable for making payments without extra fees. FFDs can be earned through referrals or promotions. However, you must use them right away as they expire after 90 days. You can prevent the expiration by simply earning more, so be sure to keep an eye on the expiration date.

Refund Fee: If you request a refund, you may be charged a refund fee. This fee may be deducted directly from the refunded amount, covering the cost of the transaction automatically.

Short-Term Financing: If you borrow quick funds from Plastiq, you will need to pay 2.75% up to 10.65% on top of the amount you borrowed. The great thing about this offer is that you can choose terms from 30, 60, to 90 days.

Be on the lookout for discounts and promotions, which may appear from time to time. These offers, which are advertised on Plastiq’s website or through promotional emails, can reduce or even waive transaction fees for specific payment types. Make sure to read the terms and conditions before participating.

ACH bank transfers, electronic funds transfers, and BillPay are provided for just 99 cents. Mailed checks cost about $1.49.

Privacy and Security Concerns

As a user relying on Plastiq to make or accept payments, you want to ensure the platform is secure. The good news is that Plastiq utilizes advanced encryption technologies to keep financial and personal user information safe during transactions. All transmitted data is encrypted to certify protection against unauthorized access and other potential security threats.

is plastiq secure

You will also not have any issues with regulatory compliance, as Plastiq meets industry standards and regulatory requirements for data privacy and security, such as the Payment Card Industry Data Security Standard (PCI DSS). The platform undergoes security checks and audits regularly to continue complying with those standards, ensuring the highest level of data protection for users.

Another way that Plastiq addresses common security concerns is that it only partners with trusted payment processors and financial organizations. All payments made through the platform are processed on safe and reliable channels to significantly reduce the risk of fraud. Plastiq also uses robust security measures, which help detect and prevent unauthorized and fraudulent activities.

Additionally, Plastiq has a transparent privacy policy outlining the methods of collecting, using, and storing users’ personal and financial information. This privacy policy provides all details, including data processing, as well as your rights and options.

Finally, the platform employs multi-factor authentication among its many other security measures to verify user identities. You may need to provide additional verification steps, including one-time passcodes sent to your mobile device or email address.

If you have other issues or require assistance, Plastiq offers dedicated customer support for all concerns, including security-related inquiries.

Some Limitations and Other Considerations to Be Aware Of

While you can get rewards when you use your credit card via the Plastiq platform, there are cases where the payment fee, which can be around 2.9%, is higher than any rewards you get.

Sure, you can use Plastiq for various transactions, including those where credit cards are not typically allowed. However, there are also numerous other products that you cannot use the platform for, such as investments and paying for credit card debts. Also, you can only make mortgage payments using a Diners Club Card, Discover, or Mastercard. As of February 2023, you can no longer pay with American Express.

It should also be noted that Plastiq filed for bankruptcy in Delaware in May 2023. The company is still operating normally but is restructuring.

Frequently Asked Questions

What is Plastiq?

Plastiq is an online platform that allows you to pay bills with a credit card.

How does Plastiq work?

Plastiq works by you entering information of legitimate businesses to receive payments from you. Plastiq will then charge your credit card (personal or business) and send a check or ACH directly to the business of your choosing.

How much does Plastiq Charge?

Plastiq charges a fee of 2.9% plus a small delivery fee. They have monthly plans ranging from free to $119/mo.

What is Plastiq used for?

You can use plastiq to pay bills (using your credit card) from vendors that do not normally accept credit cards.

Verdict

Plastiq may be the right option for you. If one or more of the following speak for you, it may be a platform to consider:

  • You need more time to gather cash but have credit available
  • You run a small business and are planning to pay vendors with a credit card
  • You want to accept credit cards for payment

Plastiq may not be worth considering for individuals, especially with the 2.9% credit card payment fee. This is especially true because credit card rewards are lower than the mentioned rate. Therefore, you lose money.

However, if you are a business (or even an individual) who requires assistance in financing a purchase or bill payment, Plastiq can benefit you. Don’t worry about not having immediate cash on hand, as you can get a few weeks to pay off your credit card balance and pay for your purchase with Plastiq.

As a small business owner, you also get several services that you may find interesting and worth exploring. For example, Plastiq Accept and Pay are services where you can accept payments and make payments, respectively. With Accept, customers can pay via credit card without worrying about merchant fees. You can also apply for short-term financing.

All in all, Plastiq is an excellent option for small and medium-sized businesses, thanks to its business-friendly features and services. It does help simplify your finances, from managing to making timely payments you can schedule. However, if you plan to use it as an individual wanting to take advantage of credit card rewards, you may want to look elsewhere.

Did You Know?

There is a little-known-way to get up to $100,000 in business credit cards without showing any financials…You can use this money to pay off debt, do more deals, grow your business or even run ads. Click Here to Download the Free Report and Discover How It’s Done!

6 Best 0% APR Business Credit Cards to Check Out 

By Joe

0 apr business credit cards

As a business owner, there’s no end to how you can use credit to grow your business. But, one of the downsides to using credit versus cash is the fact that it can cost you. If you fail to pay credit in full each billing cycle, annual percentage rate (APR) interest can add up fast—But, not if the APR is 0%. 

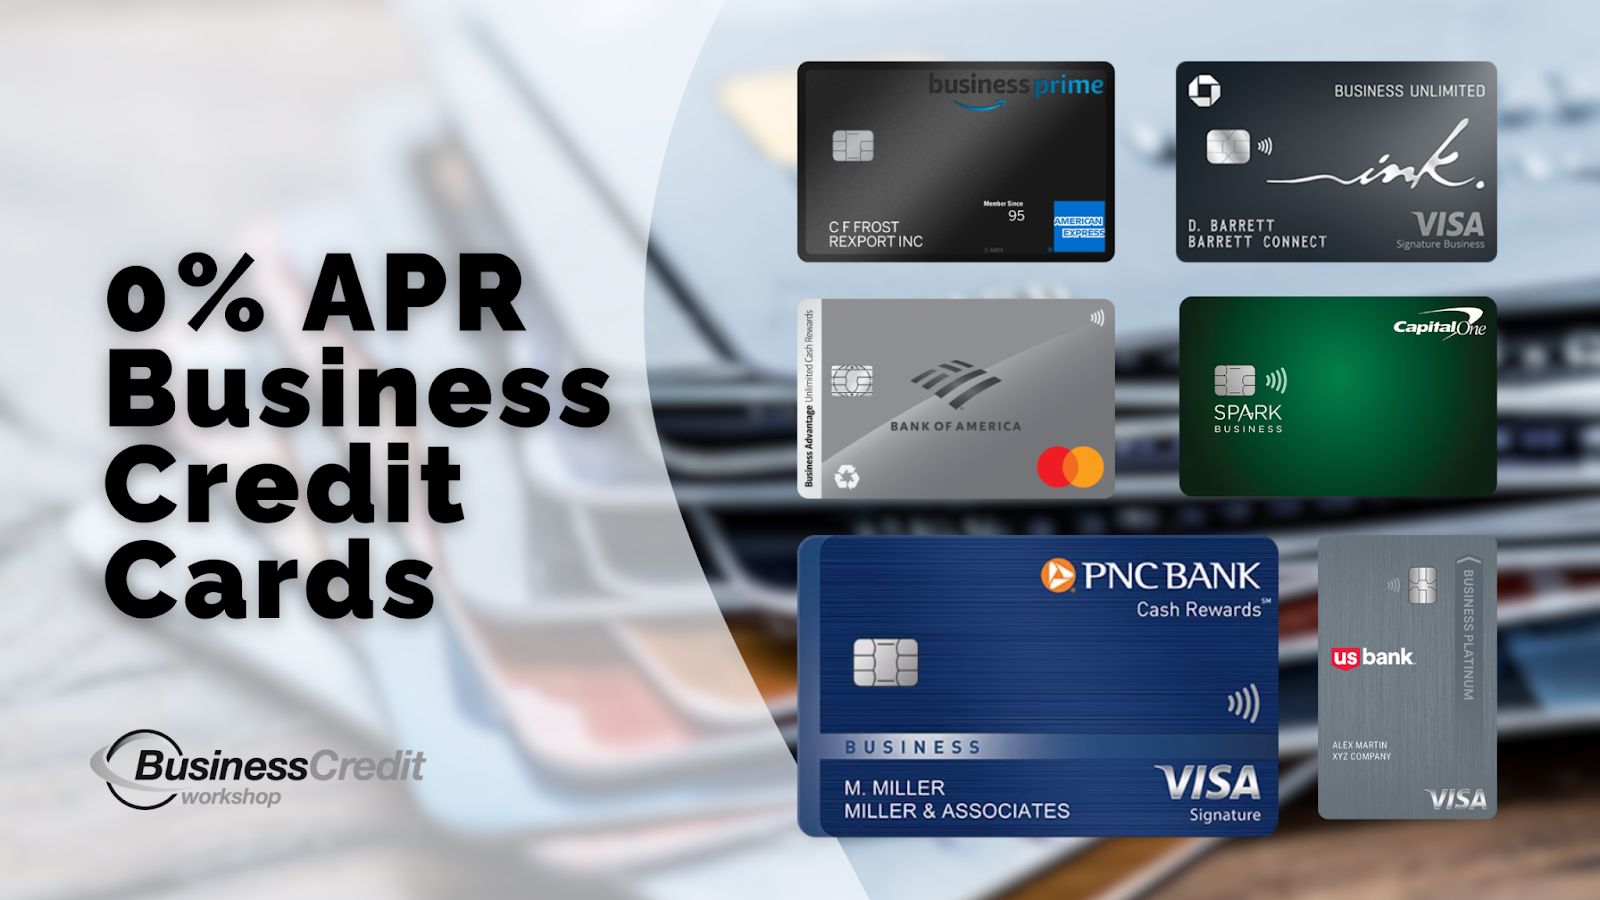
0% APR business credit cards can save you a ton of interest, if used responsibly. But, where can you find them? There are needles in a haystack with no interest ever, and others you can leverage at 0% introductory rates. Simply put, here are the top business credit cards with 0% APR that I know of right now. 

This is what’s in store: 

  • What is a Good APR for a Business Credit Card?
    • Can You Get a Credit Card with 0% APR?
  • The Best Business Credit Cards With 0% APR
    • 1. PNC Cash Rewards Visa Signature Business
    • 2. U.S. Bank Business Platinum Card
    • 3. Capital One Spark Business 1.5% Cash Select
    • 4. BofA Business Unlimited Cash Rewards
    • 5. Chase Ink Business Unlimited
    • 6. Amex Amazon Business Prime
  • Frequently Asked Questions
  • Final Thoughts

Now, let’s roll!! 

What is a Good APR for a Business Credit Card? 

Generally speaking, the lower the APR on a business credit card the better — this is if you plan to carry a balance. The lower the rate, the less you’ll pay. Think of it like this: With credit cards, you’ll be charged interest on any money that you owe at the end of a billing cycle. 

So, if you spend $1,000 on your credit card, and you only pay $100 at the end of the month, you will still owe $900 to the card issuer. The issuer will charge interest on that $900. The lower the interest rate/APR the less you will pay. 

According to data collected by the Federal Reserve, the average interest rate on credit cards issued by commercial banks was 21.47%, which increases over time – So, anything lower than this might be considered a “good” APR. However, this doesn’t account for cards issued by credit unions nor separate business products from those issued to consumers. 

Keep in mind, if you pay the balance on your business cards in full each month, you won’t have to worry about APR. 

You might also like: 3 Best Credit Unions for Small Business Banking in 2024 

Can You Get a Credit Card with 0% APR?

You can absolutely get a credit card with no annual interest rate—Both 0% APR business credit cards and 0% APR consumer credit cards can be found on the market. 

In most cases, when a business credit card comes with no annual fee, this is an introductory rate…A 0% introductory rate means that you will pay no interest for a specified period, which is usually 6, 12, 18, or 24 months. After this, the interest rate will revert back to its normal rate. At this point, you will be charged the full interest for any balance still owed, no matter when the debt accrued. 

Another business financial product that people sometimes refer to as a business credit card is a corporate card. Many corporate cards come with 0% APR, and several even offer cash back on purchases. However, a corporate card is not technically a business credit card.  

You might also like: Corporate vs Business Credit Card: What’s the Difference? 

The Best Business Credit Cards With 0% APR

Let’s take a look at the top business credit cards you can get today with 0% APR. 

Note: Credit cards rates can vary – always check with the card issuer before you apply. 

You might also like: 6 Best Business Credit Cards for Entrepreneurs: Fuel Your Growth 

1. PNC Cash Rewards Visa Signature Business

0 apr business credit cards no annual fee

The PNC Cash Rewards Visa Signature Business Credit Card offers a $400 bonus when you open a new account and make at least $3,000 in qualifying purchases within the first three billing cycles—It also features an introductory 0% APR for the first 9 billing cycles (9 months), with a variable APR of 19.24% to 27.24% afterward. 

With this card, you earn 1.5% cash back on net purchases, with no limits on your earning potential. You can easily manage your account online with various tools provided. Additionally, as a Visa Signature cardholder, you’ll enjoy travel benefits and purchase protection.

There’s no annual fee, and for balance transfers, you’ll pay either $5 or 3% of the transfer amount, whichever is greater. Cash advance fees are either $10 or 4% of the advance amount, with a maximum fee of $75. Late payment and over-the-credit-limit fees may apply.

A noteworthy perk: if you have a PNC business checking account, using this credit card could help offset your monthly maintenance fee.

Recommended: PNC Bank Business Credit Card Review & Comparison 

2. U.S. Bank Business Platinum Card

u.s. bank business credit card

The U.S. Bank Business Platinum Card offers a 0% introductory APR on purchases and balance transfers for 18 billing cycles (a year and a half), making it ideal for managing expenses and consolidating debt. After the introductory period, a variable APR applies.

This card comes with a low annual fee and provides cards for both you and your employees–This U.S. Bank business credit card gives you access to a dedicated domestic servicing center with 24/7 customer support, which ensures assistance whenever you need it.

With Visa Spend Clarity™, you can track spending and manage expenses more effectively. The card has received honors, including being named Best 0% APR Credit Card by WalletHub and Best Business Cash Back Card for Gas by Forbes.

Furthermore, the U.S. Bank Business Platinum Card allows you to pay over time with U.S. Bank ExtendPay® Plan, and new cardmembers can take advantage of a $0 fee offer on ExtendPay Plans opened within the first 60 days after account opening.

You might also like: What are the Best Unsecured Business Credit Cards for Startups? 

3. Capital One Spark Business 1.5% Cash Select

best 0 apr business credit cards

The Spark 1.5% Cash Select credit card from Capital One is tailored for businesses with good credit. It offers unlimited 1.5% cash back on all purchases, with no category restrictions, and an additional unlimited 5% cash back on hotels and rental cars booked through Capital One Travel. 

There’s a $0 annual fee, and for the first 12 months, there’s a 0% introductory APR, followed by a variable APR ranging from 21.24% to 29.24%, based on your creditworthiness.

The card provides benefits like: 

  • Automatic payments
  • $0 fraud liability
  • Year-end summaries for simplified budgeting and tax preparation
  • Account managers for assistance with purchases and payments
  • Purchase record downloads in various formats
  • Virtual card numbers for enhanced online security

The application process takes about 10 minutes, and decisions are typically made in seconds. 

To apply, you’ll need to provide information about all business owners, including legal names, addresses, and Social Security Numbers, as well as details about your business, such as its legal name, address, and tax identification number (EIN).

You might also like: What are the Best Business Credit Cards for Travel? 

4. BofA Business Unlimited Cash Rewards

bank of america business credit card

The BofA Business Unlimited Cash Rewards credit card by Bank of America offers a $300 online statement credit bonus after spending at least $3,000 within the first 90 days of opening an account. It allows you to earn unlimited 1.5% cash back on all purchases, with no annual cap and no expiration on rewards. 

Moreover, if you have a Bank of America business checking account and qualify for the Preferred Rewards for Business Platinum Honors tier, you can earn up to 75% more cash back, up to an unlimited 2.62% cash back on purchases.

This card features flexible redemption options, including depositing cash rewards into your Bank of America checking or savings account, receiving a statement credit, or getting a check mailed to you. 

There’s no annual fee, and it offers a 0% introductory APR on purchases for the first 9 billing cycles, followed by a variable APR ranging from 18.49% to 28.49%—The card provides various features to manage cash flow, online and mobile access for account management, travel and emergency services including travel accident insurance, free access to business credit scores, security measures such as zero liability protection and fraud monitoring. 

Notable: It also offers Balance Connect® for overdraft protection when linked to a Bank of America business checking account.

Recommended: What is the Best Bank of America Business Credit Card You Can Get? 

5. Chase Ink Business Unlimited

Best business credit cards 0 apr

The Ink Business Unlimited® Credit Card from Chase offers a substantial new cardmember bonus of $750 cash back after spending $6,000 on purchases within the first 3 months of opening an account. With no annual fee, this Chase business credit business card allows you to earn unlimited 1.5% cash back on every purchase made for your business.

For the first 12 months from account opening, there’s a 0% introductory APR on purchases, which then transitions to a variable APR of 18.49%–24.49%. You can redeem your rewards on this card for cash back, gift cards, travel, and more through Chase Ultimate Rewards®.

Employee cards come at no additional cost and allow you to set individual spending limits while helping you earn rewards faster. Additionally, until March 2025, you can earn a total of 5% cash back on Lyft rides with your Chase Ink Unlimited card, which includes an extra 3.5% on top of the 1.5% you already earn on travel.

Chase also offers referral incentives for existing cardholders, allowing them to earn up to 200,000 points per year by referring businesses for any Chase Ink® Credit Card.

You might also like: Chase Ink Business Preferred Credit Card: A Deep Dive Analysis 

6. Amex Amazon Business Prime 

0% business credit card

The Amazon Business Prime Card, offered by American Express, comes with a $0 annual fee and offers a $125 Amazon.com Gift Card upon approval. It features a variable APR ranging from 19.49% to 27.49% on purchases, based on creditworthiness.

This card rewards your business with:

  • 5% cash back or 90-day terms on select U.S. purchases at Amazon Business, AWS, Amazon.com, and Whole Foods Market, with a cap of $120,000 in purchases each calendar year with eligible Prime Membership, and 1% back thereafter.
  • 2% cash back on U.S. purchases at restaurants, gas stations, and wireless phone services purchased directly from service providers.
  • 1% cash back on all other eligible purchases.

Additional benefits include Amazon Business Enhanced Data Views for detailed expense tracking, Amazon Shop with Points for flexible reward redemption, and no foreign transaction fees.

You can manage expenses efficiently with features like Account Manager, Employee Cards with spending limits, and integration with QuickBooks® for auto-expense categorization – Moreover, cardholders receive baggage insurance, car rental loss and damage insurance, extended warranty protection, purchase protection, and access to Amex Offers for additional rewards.

Recommended: Amazon Business Prime Credit Card: Full Review +How to Get One  

Frequently Asked Questions

What credit score do you need for 0% APR? 

Typically, you need a good to excellent credit score (usually 670 or higher) to qualify for a 0% APR offer on a credit card. Each card issuer has their own underwriting and qualification terms. 

Why 0% APR offers might not be good for your credit? 

0% APR offers can impact credit negatively if not managed properly. They may encourage overspending, leading to higher debt levels. Additionally, opening new credit accounts can temporarily lower your credit score due to inquiries and reduced average account age.

Is 23% APR high for a credit card? 

Yes, a 23% APR is slightly above the average for credit card APRs, which was around 21.47% according to Federal Reserve data.

Is 29% APR high? 

Yes, a 29% APR is significantly higher than the average credit card APR, indicating high-risk lending.

Final Thoughts

Leveraging 0% APR business credit cards can be a savvy financial move for entrepreneurs – It provides a valuable opportunity to manage expenses without accruing interest. With a clear understanding of what constitutes a good APR for a business credit card, the availability of 0% APR cards, and the top options currently on the market, you’re better equipped to make informed decisions tailored to your business needs. 

Remember to consider factors like introductory periods, ongoing APR rates, and additional perks and benefits when selecting the right card for your business. With careful management and responsible use, these cards can serve as valuable tools for financial flexibility and growth.

Do you want to learn how to obtain up to $100K in business credit in as few as 30 days? Join Business Credit Workshop today!

Melio Payments Review: Can It Make Business Payments and Getting Paid Easier?

By Joe Lawrence

Melio Payments Review

Any business requires managing finances, but it can be challenging. With the complexities involving accounts payable and receivable, keeping up with the payments is often difficult. Thankfully, there are solutions that you can try to streamline your finances and take control of your cash flow. Consider looking into Melio Payments, a platform that offers a comprehensive range of features, from making bill payments to invoicing and payment processing.

In this review, we will explore the platform’s features, benefits, and workings. Read on to determine whether it is what you need to optimize your business’s financial operations.

Contents

  • What is Melio Payments?
  • Melio Payments Key Features and Functionalities
  • The Benefits of Using Melio Payments for Your Business
  • How Melio Payments Works
  • Accounting Software Integration
  • How Much Does Melio Cost?
  • User Experience and Reviews
  • Conclusion

What is Melio Payments?

Melio Payments is a platform created by a financial technology company with the same name. This platform is designed for businesses to manage their accounts payable and receivable processes. If you utilize the platform, you can take advantage of various features to help you manage your finances more efficiently.

Melio Payments Key Features and Functionalities

When you sign up for Melio Payments, you can get a suite of financial tools and services that make your accounts payable and receivable processes much more straightforward.

melio chose when and how to pay vendors

For example, Melio allows you to pay your bills electronically. You can accomplish this task using bank transfers or debit cards. The best part about this feature is that it does not require the merchant or vendor to accept electronic payments. You can pay through the payment method you choose without actually using it. This means you do not have to write and mail physical checks, which can save a lot of time and even decrease administrative overhead.

Here are other key features that you can get out of Melio Payments:

Invoicing: You can use Melio to create and send professional invoices directly to your customers using the platform itself. To do this, log in to your Melio account and go to the Invoices tab in the dashboard. From there, you can access the existing invoicing features, which include creating a new invoice. You can then fill in the invoice details, including the recipient’s contact information, date, and number. You can also add line items in the dashboard with their own costs and quantities. You can then set the payment terms for the invoice, including the payment method and due date. Before sending, make sure to review and confirm.

better cash flow

Scheduling of Payments Including Recurring Payments: Melio allows you to set up recurring and one-time payment schedules in advance conveniently. That way, you can ensure all your bills are paid on time. This feature also helps manage cash flow, as you can plan and be sure that the funds will be readily available when the due date comes. You can set up recurring payments, such as rent and utilities, on the platform. They will automatically be paid on a weekly or monthly basis.

Accounting Software Integration: You can use Melio together with your favorite accounting software platform. It is popular with Xero and QuickBooks, two of today’s most used accounting solutions. Melio allows you to sync your financial data between the accounting software platform and the payment platform. That way, these platforms can automatically update the payment information and invoices. This saves you time as you no longer have to enter financial data manually. The integration with Xero or QuickBooks and other accounting software will be further explained later in this blog.

Management of Your Vendor Transactions: Melio has tools that allow you to manage vendor transactions easily. These tools are designed to help you gain better control and visibility of your accounts payable. For example, you can use Melio to centralize vendor information on the platform. This means you can manage and track transactions when dealing with different vendors, as you can quickly add new vendors and update vendor details, among many other features.

Payment Tracking: A crucial feature that you can find on the Melio platform is payment tracking, which gives you a real-time glimpse of the status of the payments you have made. You can also look at your payment history in the dashboard, which has detailed records of your past payments, including payment dates, recipients, and amounts. Tracking of payment involves not just the past but also the future. You can have Melio give you payment reminders to stay on top of your payment obligations, helping you avoid penalties and late fees.

Melio is excellent for businesses with more than one department or user who may oversee the payment processes. The platform has customizable approval workflows where you can create custom approval chains that outline the approval sequence for your payments. It makes it easier for your departments or users to determine who should approve payments in the correct order to complete the process.

The Benefits of Using Melio Payments for Your Business

The primary purpose of Melio is to simplify accounts payable processes. It provides robust tools enabling users like you to create invoices, schedule payments, and manage vendors in just one simple and easy-to-use platform.

Here are the other advantages of using Melio for your business:

The ability to set up payment schedules helps improve your business’s cash flow management. By maintaining control over the timing of your payments, you can be sure that your bills are paid on time.

You Might Also Like: This is How to Leverage Business Credit to Transform Your Life

The same feature as above also helps extend payment terms with contractors, vendors, or suppliers. That’s why payment scheduling is beneficial for your business: You can have more time to pay your bills while preserving working capital.

control payments

Unlike other platforms or methods of payment, you do not have to worry about paying your dues early. Early payment discounts from vendors may be available, and you can take advantage of them. These discounts can save money on your expenses, which is useful for improving cash flow.

Repetitive tasks are time-consuming. Eliminating them and relying on Melio for invoice creation and payment reminders can free up your employees’ time to focus on other strategic activities that can help drive business growth.

Melio makes invoice management easy. The platform allows you to create and customize invoice templates and include line items. You can also use Melio to specify payment terms, which makes it an excellent solution for your business and customers.

Apart from the benefits mentioned above, Melio Payments can lead to significant cost-saving benefits and improvements in efficiency for your business. For instance, you can save on administrative overhead by automating repetitive tasks.

Processes that may use paper can also be eliminated since Melio promotes the digitization of your accounts payable and receivable procedures. That means you no longer have to deal with paper-based checks, receipts, and invoices, should you choose to do so.

Late payments are a no-no for businesses, especially those wanting to save money. You can preserve your working funds by avoiding late fees and penalties due to missed or delayed payments.

Every business needs good relationships with vendors and customers to thrive. When you have streamlined accounts payable and receivable processes, you can forge stronger working relationships. That’s mainly due to your professionalism, which involves prompt payments and efficient invoicing. These can help improve communication and trust with other parties. It is one of the keys to building long-term partnerships.

Finally, the updated platform allows users to pay using bill-by-ACH bank transfer or card. Vendors are also no longer required to sign up, meaning you can pay them however they want with Melio.

How Melio Payments Works

Just like with any other payment platform, you must first sign up for an account here: https://app.meliopayments.com/register. Signing up is easy and takes only a few minutes. It only asks for your email address and password. You can also use your Google or Intuit account (for QuickBooks users).