• Home
  • Free Funding Guide
  • What We Offer
    • Products
    • Services
    • Free Guide
  • About Us
  • Contact
  • Sign Up

  • Ask Joe Any Question!
  • Business Credit Cards
  • Business Line of Credit
  • Topics

The Ultimate Tillful Review (+New Secured Credit Offer for Businesses)

By Joe

Tillful review

Update: In July 2023, Nav acquired Tillful and launched the Nav Prime program (along with new a charge card offer) in September. According to Nav, the Tillful card is no longer available.

→ You can read the full review of Nav’s new card here: Is the Nav Prime Card Right for Your Business? Let’s Find out!

Recently, I came across a Facebook post in a private group, announcing a new secured credit card for businesses — it’s perfect timing for an offer like this since Wells Fargo and Brex no longer offer secured business credit cards. So, naturally, I had to explore the offer. And, what I found was so much more than just a credit card. 

This complete Tillful review is a breakdown of everything I learned, and how you might use this offer to build business credit. 

Here’s what’s covered: 

  • What is Tillful?
    • Tillful Business Credit Score Overview
    • Partner Offers Overview
    • Business Credit Education Overview
  • The Tillful Credit Card
  • The Tillful App
  • Tillful Company Overview
  • Frequently Asked Questions
  • Tillful Secured Credit Card Competitor Overview
  • The Verdict: Is Tillful the Real Deal?

Now, let’s get going! 

What is Tillful? 

Tillful is a fintech company that offers businesses a free credit score (which is different from a DUNS number and other traditional credit scores) that they use to match account holders with curated financial offers. To me, the business closely resembles a new Credit Karma for business. 

By connecting to users’ business bank accounts via Plaid, the platform is able to gain financial information about companies, which is delivered back to users to see how they stack up. 

Tillful also offers their own free, secured business credit card with 1.5% cash back, to help owners build business credit, an innovative and timely offer. 

Tillful Business Credit Score Overview

The folks at Tillful have created their own business health score, which ranges from 0-100 and is based partially — i.e. mostly — on a company’s cash reserves and industry, a measure of real-time financial performance. The Tillfull score is never shared with lenders and is meant to give users a fresh view of their company’s financial health. 
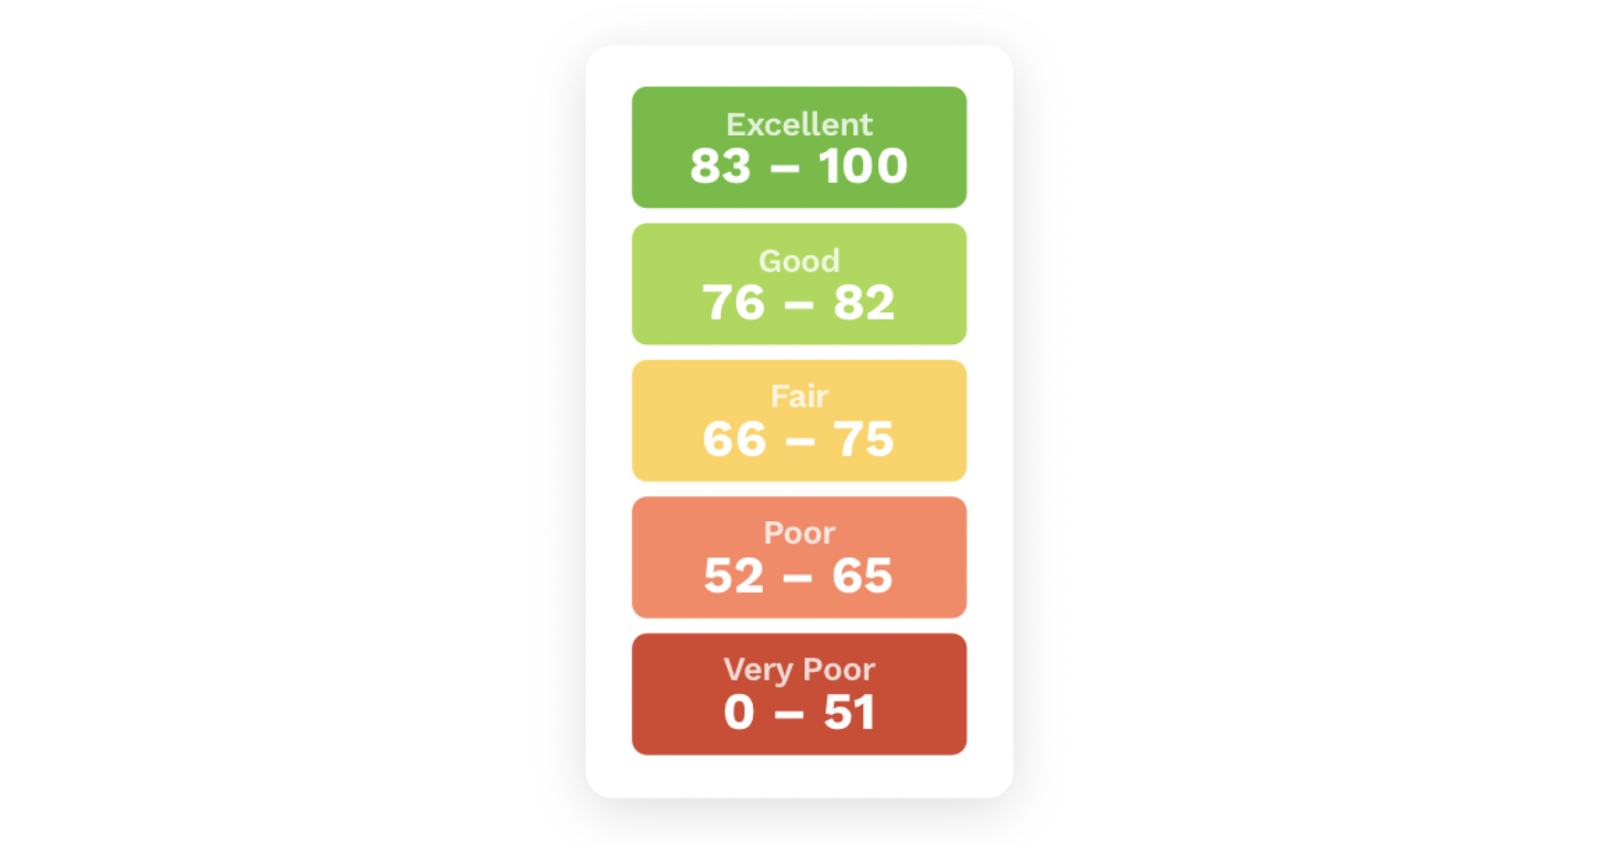
Tillful Business Health Score

I’m not confident that this scoring system will actually influence potential lenders outside Tillful’s platform, but it seems like a pretty clever and helpful tool. 

In addition, Tillful has partnered with Experian, who recently launched a machine-learned business credit score called Intelliscore Plus V3 (IPV3) — the new model is said to improve risk assessment for business lenders. Active Tillful account holders can request their free IPV3 business credit score at any time.

Experian IPV3 business credit score

However, Tillful users who want to see a full report will have to order it from Experian using a quick link in their Tillful account dashboard or by visiting Experian’s website directly. 

At least in part, the IPV3 score is based on a company’s tradeline payment history and ranges from 300-850. Rather than a 12-month model prediction, the IPV3 is based on the previous 24 months of credit history. 

Coming from Experian, I think this scoring system is going to stick and that continually more traditional lenders will use it to make funding decisions. 

Recommended: Nav Review: A Tool that Helps Build Up Your Business Credit Score 

Currently, Tillful has a 4-star rating on Trustpilot, which tells me they’re making users happy, for the most part. 
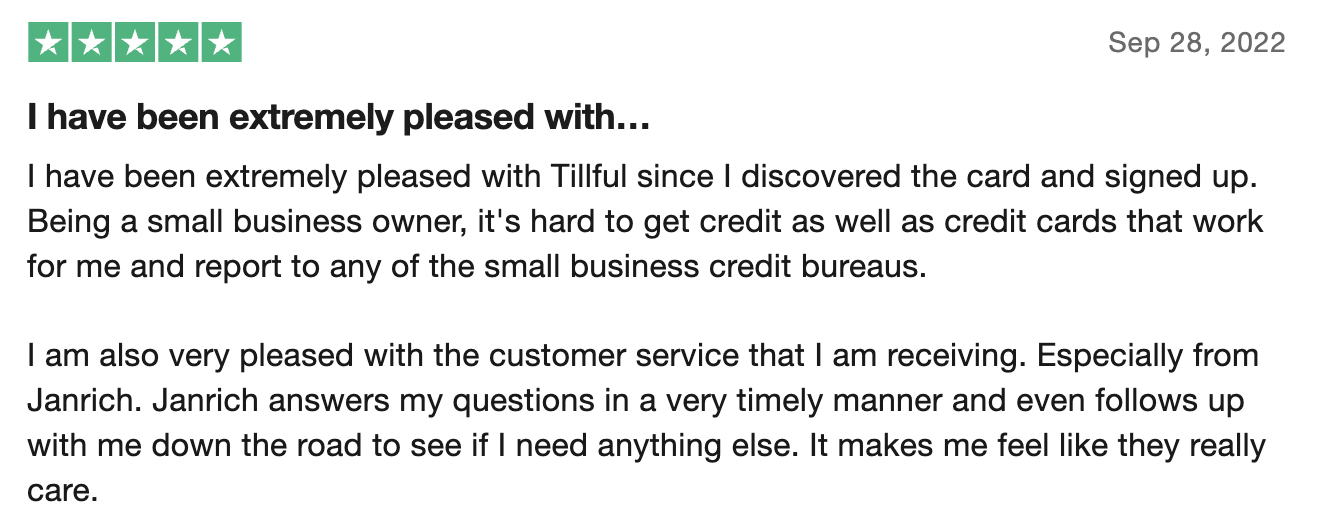
Tillful reviews

Most business owners typically don’t have all of the information they need to access business lines of credit — Tillful gives them a new way to establish business credit at no cost (other than a security deposit for the secured credit card). 

Recommended: This is How to Leverage Business Credit to Transform Your Life 

Partner Offers Overview

New businesses that show very low financial reserves won’t qualify for the Tillfull credit card, but will be directed to Biz2Credit for alternative funding. If you have multiple business bank accounts, consider connecting all of them to get more relevant offers. I caution against connecting bank accounts in poor standing. 
Tillful login

In addition to funding offers, Tillful might connect you with a new business banking or insurance offer. Especially since the company is fairly new, I assume they will continue to expand their partner offer — as of right now, it seems on par for a business just starting to build credit history (as long as you do your due diligence to make sure a better competitor offer doesn’t exist and pay your accounts responsibly). 

Business Credit Education Overview

Tillful is built to help companies improve their credit (and to earn from partner commissions), so the offer wouldn’t be complete without business credit education. Tillful’s blog is stacked with information about how to improve your credit score, streamline your cash flow, create an effective budget, and learn about COVID-19 financial relief. 
Tillful business credit resources

After browsing the blog, my official stance is that the information seems to be well-written, easy to digest, and helpful for businesses trying to build credit. 

The Tillful Credit Card

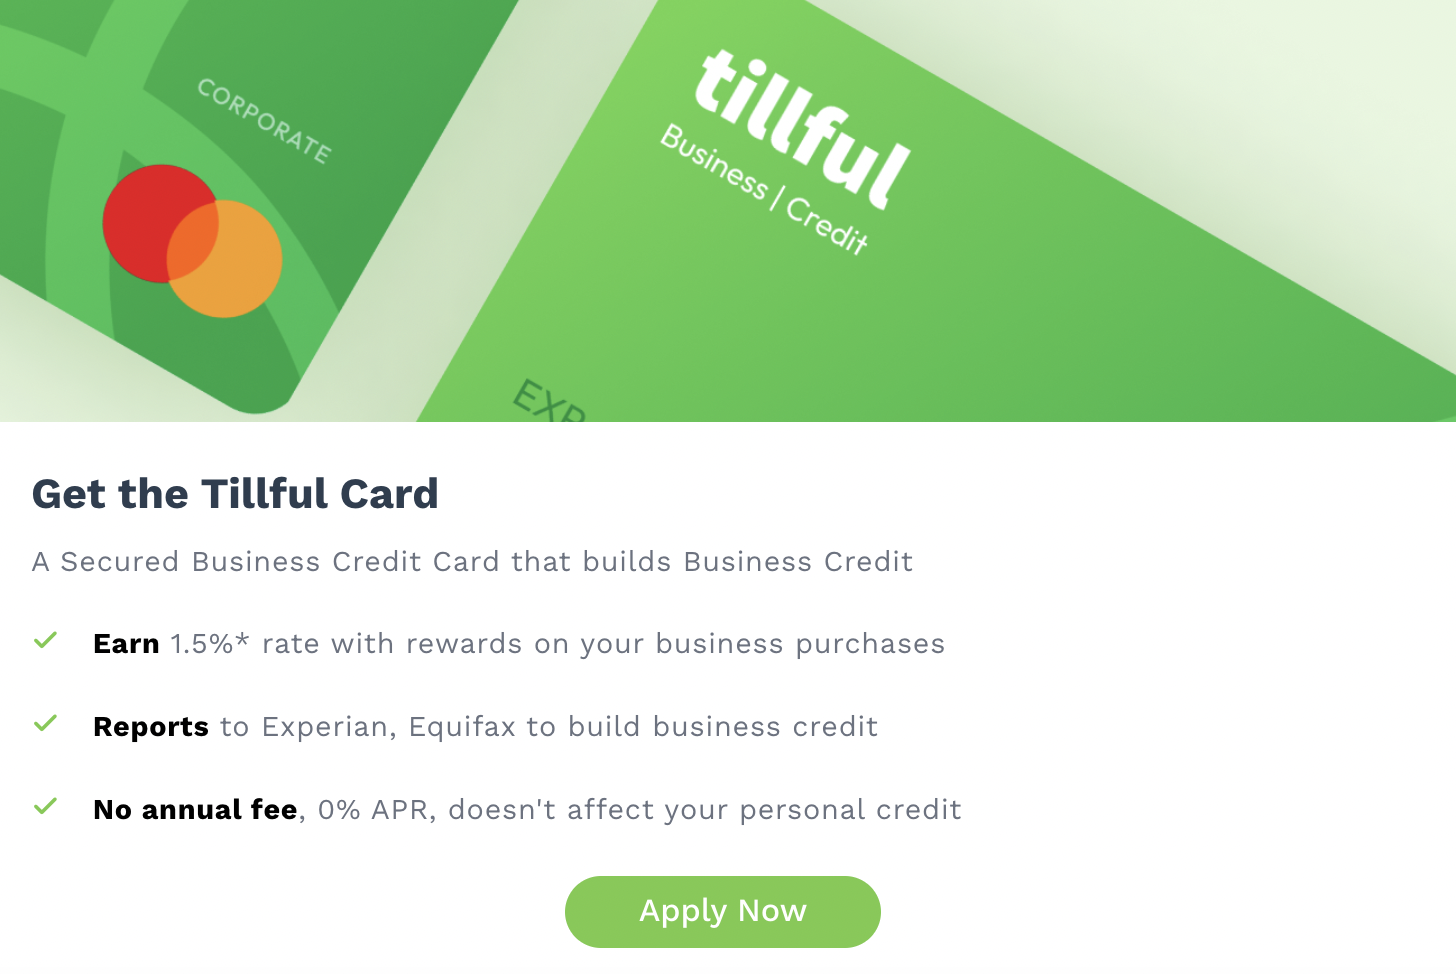
The Tillful business credit card is a secured card for legal entities. Like a charge card, the balance should be paid in full each month. Unlike other secured business credit cards, Tillful uses Plaid to connect to your business bank account, sizes up your cash flow and reserves, then makes an offer to apply if you are likely to qualify. 
Tillful card login

One highlight is that this card comes with 1.5% cash back rewards on all spending. If you read the fine print, this is a promotional rate, which means rewards could decrease over time. Next, there is no personal guarantee. Finally, there’s no hard pull to an applicant’s credit.  

Currently, the card reports payments to business credit bureaus to help build business credit scores. Tillful plans to report to Dun & Bradstreet in the near future.  

Since it is a secured card, you will be required to deposit funds into your account, and the minimum security deposit is $500.  

The Tillful App

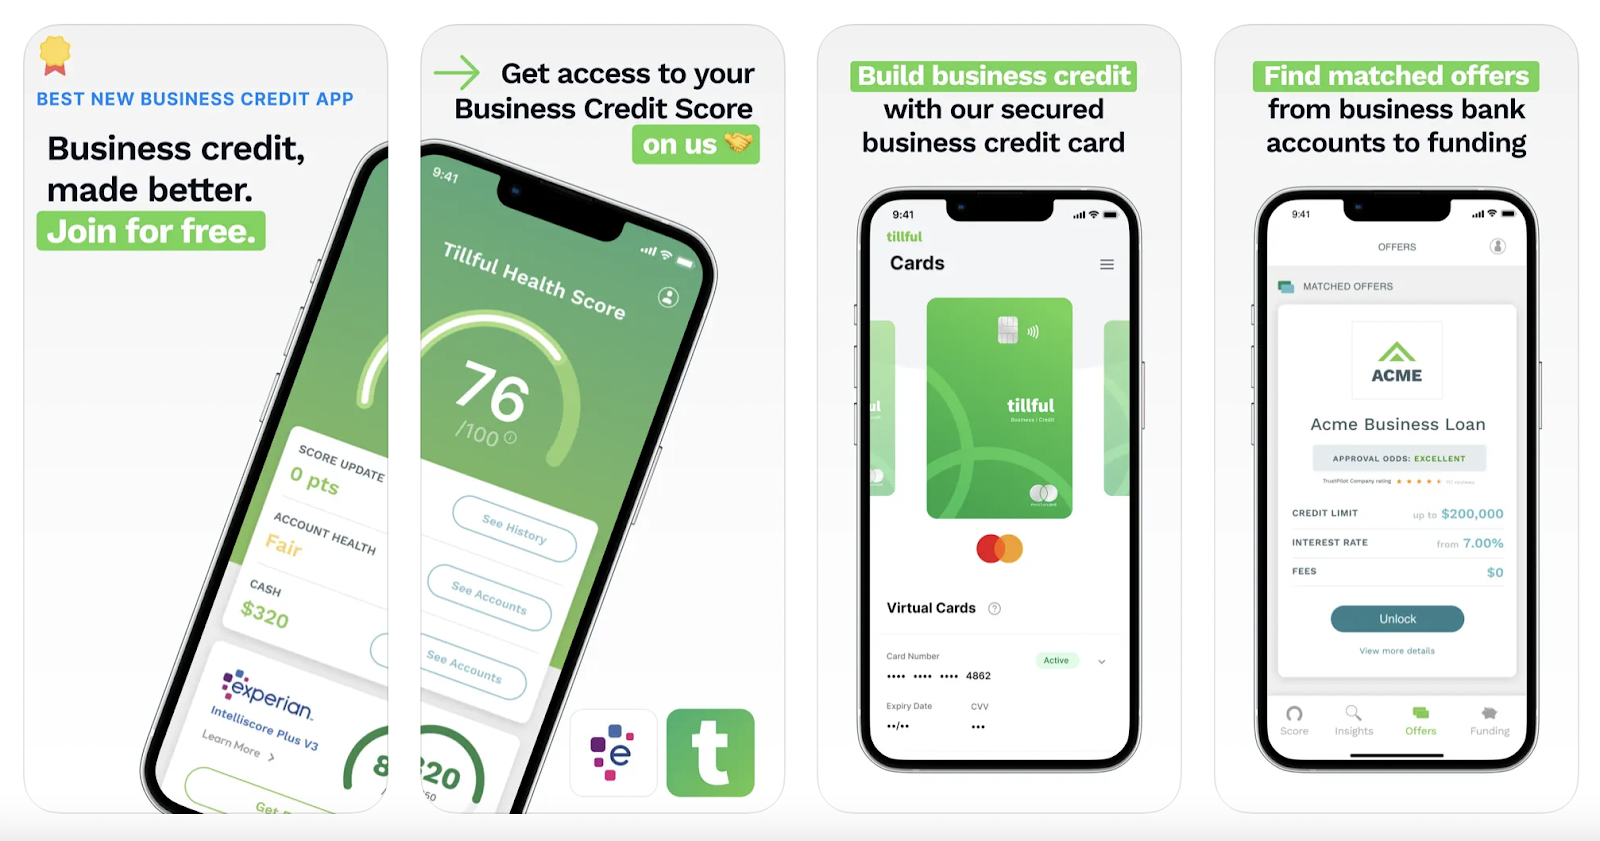
If you didn’t already guess, Tillful also has an app available on the iOS App Stores. It has a 4.4-star rating on the platforms. So, users can conveniently monitor business credit and apply for funding from an Apple device. Thus far, there is no Tillful app in the Google Play store (you might just as easily log in using your mobile browser).  
Tillful app

Using the app, you can get your free business credit score and see financial product recommendations, including funding options. It’s pretty straightforward. 

Tillful Company Overview

Located in the San Francisco Bay area, Tillful was founded by Ken So in June 2020. Tillful is a subsidiary of Flowcast, which is a company that uses AI to help financial institutions make credit decisions (hence the fast friends situation with Experian). 
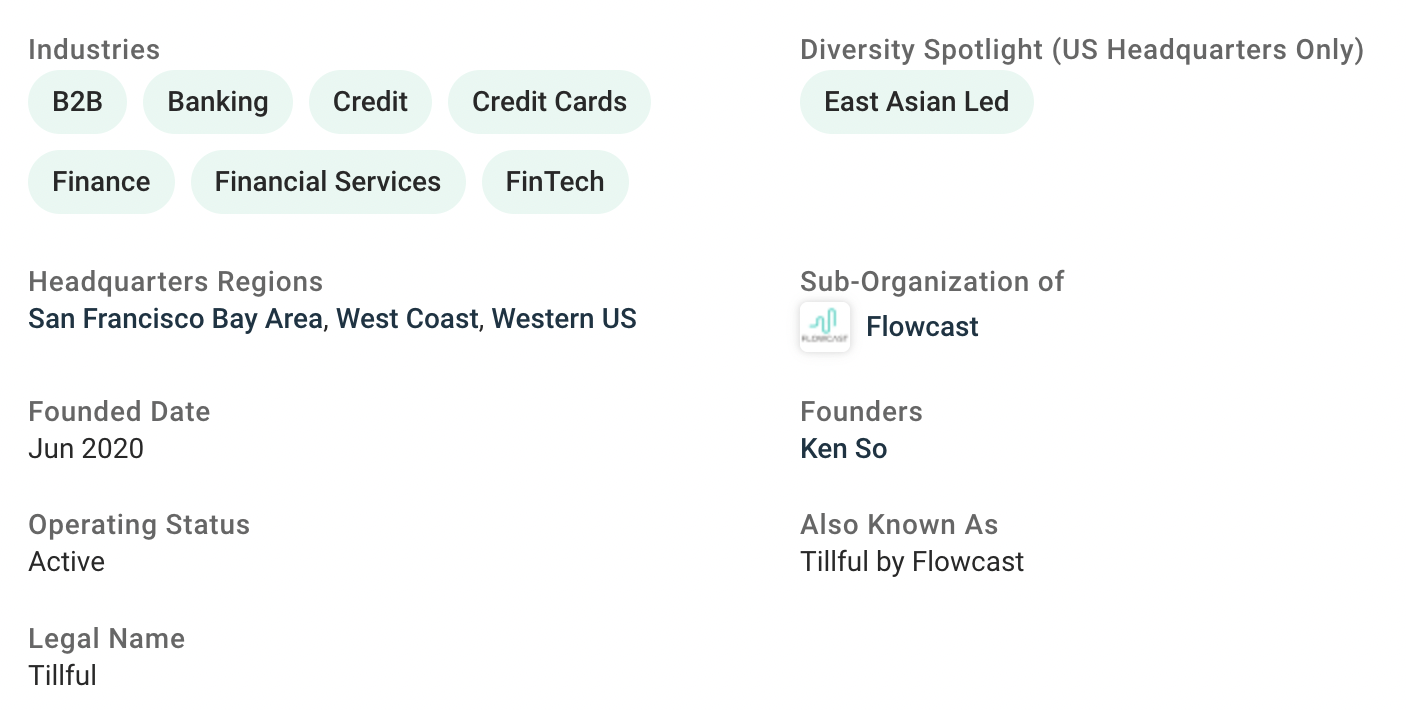
Tillful Crunchbase

Flowcast has been around since 2015, and has a five-star glassdoor rating. So, from what I can tell, they’re a great company to work for — in full disclosure, there are currently only two reviews, so this isn’t a particularly scientific sample to base opinions on. 

So, let’s talk about the founder, Ken So (also Flowcast’s CEO). Before all of this, So was the Director of Corporate Development at Ericsson and previously worked in the corporate dev department at Qualcomm – both very reputable companies. To me, this seems like a strong and trustworthy leader and makes me believe the offer is likely to be around for a while. 

According to Growjo.com, Tillful’s current annual revenue is estimated at $2.3 million. And, since they’re not reliant on external funding, they’re likely at an advantage over other newcomers in the business credit-building arena. 
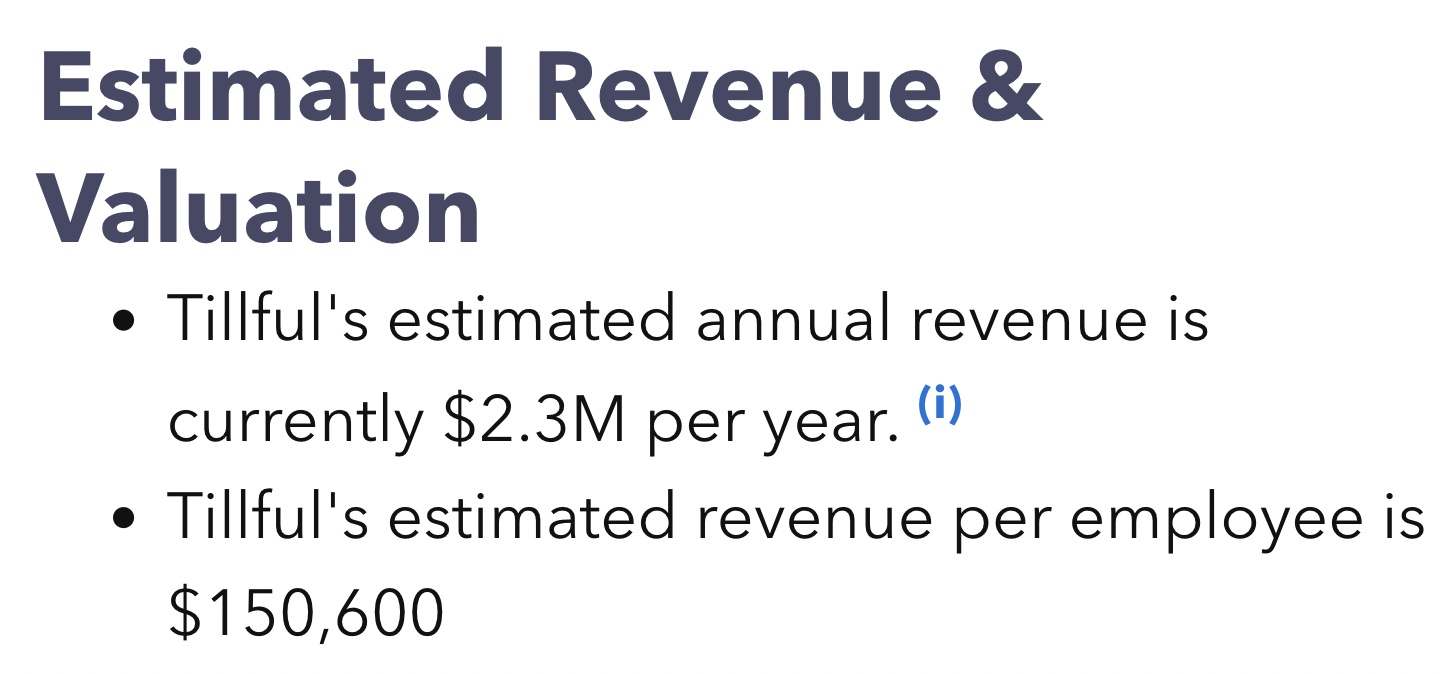
Tillful valuation

Frequently Asked Questions

Here are the answers to the questions people are asking about Tillful:

Is Tillful free?

Yes, Tillful’s offer is completely free – users can access their credit score and secured credit card. However, any partner offers that Tillful recommends may charge fees and interest.  

Does Tillful do a hard inquiry?

No, Tillful does not do a hard pull on business or credit reports. Instead, credit card approval is based on other factors. 

Does Tillful report to credit bureaus?

Yes, Tillful reports payment history to business credit bureaus, as the credit card offer is intended to help entities build credit. 

Which credit bureaus does Tillful report to?

Currently, Tillful reports payments to Experian and Equifax Business. 

Does Tillful report to Dun & Bradstreet?

Unfortunately, no. As of October 2022, Tillful does not report on-time payments to D&B or Equifax Business. However, they plan to in the near future. 

Tillful Secured Credit Card Competitor Overview

Tillful is not the only secured business credit card on the market — a couple of veterans still exist: Bank of America (BoA) and First National Bank of Omaha (FNBO). See how these three secured business credit cards stack up next to one another.

Tillful competitors, Tillful vs BoA vs FNBO

The key tradeoff with the Tillful secured card is that you should pay your account in full each month, while the other available cards have revolving terms — you can make a monthly minimum payment if you choose, so there’s a bit more freedom with the old-timers. 

However, monthly minimums come with the risk of high fees and interest; with the Tillful secured business credit card, if you make your payments as agreed, you’ll avoid this. Now, if you pay a BoA or FNBO card in full each month, you will avoid interest charges, so these offers almost balance each other out, not factoring FNBO’s $39 annual fee.

Tillful is available with a smaller minimum credit line. So, businesses with less cash in reserves are more likely to qualify. Plus. Tillful does no hard pull to your credit and there is no personal guarantee (the business owner is not liable for repayment of the funds — the business is), which is not the case with BoA or FNBO. 

If I were going to use a secured credit card to establish business credit, I would choose Tillful over BoA or FNBO. 

The Verdict: Is Tillful the Real Deal? 

Of course, the question I was most interested in answering when I started down the Tillful rabbit hole is whether or not this is a good offer for building business credit. After some digging, it appears that this is a legitimate offer with a ton of potential. The offer is free, the company will help businesses improve credit (with on-time payments, anyway), and the brand is transparent about what they provide. 

Right now, the biggest downside to Tillful’s offer is that they do not report on-time payments to D&B. To report to D&B, companies need at least 300 active accounts. So, I think it is likely that Tillful will do this in the future, in which case I would probably give the offer a 5-star rating (when appropriately utilized). 

With that said, Tillful does currently report payments to Experian Business, and they claim that they will be reporting to Dun & Bradstreet as well as Equifax Business soon. Whether they deliver on that offer is yet to be seen, but do keep your eyes peeled.  

Note that as far as business credit monitoring platforms, I’m still a bigger fan of Nav — mostly because I have more trust in established companies (Plus Nav has an Android app). But, I do encourage you to check out both offers and see which one you like best.

I teach a seven-step process to get up to $100K in business credit in as few as 30 days by leveraging the right combination of offers and setting up your business the correct way. If you’re interested in learning exactly how it works, join Business Credit Workshop today.
AtoB Business Gas Card Review: Is it Really a Superior Fleet Card?

By Joe

AtoB business gas card review

I have not used this card myself, but AtoB has been coming up in conversations about building business credit for over a year now. People in my network are giving the card and the company rave reviews. So, I had to find out what was up for myself. Now that I know, I definitely want to share this offer with readers.  

Here, learn everything you need to know about an AtoB business fuel card: overview, benefits, highlights, and application process (there’s even a bit of info about bonus offers from AtoB). 

Here’s the breakdown: 

  • What is the AtoB Gas Card?
    • Where is AtoB Located?
    • Who Owns AtoB Fuel Card?
  • AtoB Fuel Card Highlights (Beyond Savings & Ease)
    • 1. It’s Completely Free… Really
      • If it’s Free, How Does the AtoB Fuel Card Make Money?
      • Extra Offers From AtoB
    • 2. Get On-Time Payments Reported to Experian Business
    • 3. It’s Universal: Use Your Card Anywhere Visa is Accepted
    • 4. See the Best Nearby Stations to Buy Fuel
    • 5. Use Your Card to Pay Insurance, Maintenance, Tolls, & More
    • 6. Control Spending to Prevent Card Misuse
  • Here’s How to Apply for an AtoB Gas Card
    • The Secured Card Option From AtoB
  • Answers to Related Questions
  • Final Thoughts

Now, learn what this offer has in store.  

What is the AtoB Gas Card? 

AtoB offers a business “fleet card” for companies that would like to buy now and pay later for fuel and automotive services. In addition, the card offers bonuses like discounts up to 25 cents per gallon (determined by the underwriting team upon approval) on gas… and it’s free — zero fees.  

Fleet cards aren’t just for business owners, but for anyone who drives for your company. So, you can request multiple cards and provide one for each driver. 

The AtoB card is different from a typical credit card in that you don’t make minimum monthly payments. Instead, the terms are net 7 (you pay the card in full every week). 

I heard that AtoB offers net 7 terms (true) — this means cardholders are expected to pay their balance in full every 7 days — and that these terms could be expanded to net 14. While there might have been an offer to extend payment terms in the past, this is not the case. As of today, according to an AtoB sales rep, the only available terms are net 7.  

AtoB gas card reviews

Finally, their offer is geared toward but is not limited to serving the trucking and logistics industry, which is natural since trucking and logistics companies have the largest fleets. 

Where is AtoB Located? 

Celegans Labs, Inc., the name of AtoB’s parent company, is located in San Francisco, California, at Four Embarcadero Centre, Suite 1400. Their company actually does business from Carr Workplaces, a co-working space off Mission Street — a building about 8 blocks from Oracle Park (makes me wonder if they’re Giants fans). 

Who Owns AtoB Fuel Card? 

AtoB was founded in 2019 (not very long ago!) by Harshita Arora, Tushar Misra, and Vignan Velivela. Collectively, they seem to be a brilliant tech team. 

Harshita Arora, AtoB Co-Founder
Harshita Arora
Tushar Misra, Co-Founder of AtoB
Tushar Misra
Vignan Velivela, Co-Founder & CEO of AtoB
Vignan Velivela

Harshita Arora is a backend software engineer who previously founded Harshita apps, the company that built Crypto Price Tracker, which was acquired a few years back. 

Before AtoB, Tushar Misra attempted to build a decentralized charging station network for lighter-than-car vehicles as the CEO and Founder of Grido. In the course of fewer than 18 months, the company scaled to five cities in the US and Mexico before it looks like they closed the shop.

Vignan Velivela, AtoB’s current CEO, is a Carnegie Mellon graduate. And, before this venture, he worked full-time as a software engineer at Cruise (he created motion-planning software for self-driving cars).  

AtoB Fuel Card Highlights (Beyond Savings & Ease)

In addition to the savings (up to 25 cents per gallon) on fuel and the ease of making one fuel payment for multiple drivers, AtoB has some pretty impressive features and benefits. Take a look: 

1. It’s Completely Free… Really

The key benefit of an AtoB card is that it is free for qualified businesses. Most business gas cards charge monthly fees and interest. Not to mention, AtoB’s maximum savings are at least double that of any card I’ve ever heard of. 

If it’s Free, How Does the AtoB Fuel Card Make Money? 

Most fleet cards earn money with merchant rebates — essentially asking the merchant for a rebate each time a driver pays for fuel with their card. In AtoB’s case, where they offer up to 5% savings, rebates would have to be loftier than that. And, traditionally, merchant rebates range between 1-4%. 

According to a Buzzfile report on the company, AtoB generated just above a quarter million dollars in 2019 (this isn’t much for a company that now has at least 158 employees). 

AtoB Fuel Card Reviews

Someone told me that they believed AtoB had halted operations because of changing market conditions. As of today, September 2022, this rumor is false, and AtoB is still in operation — the business is very much alive and well. Any sluggish business in recent months could have had something to do with the funding round that just took place. 

After some digging, I found that AtoB has received a total of $257 million from 5 funding rounds since August 2020. Most recently, they announced another $75 million raised on August 16, 2022. And, with the founders’ tech background, I would wager that the majority of future profits will come from their software offer. 

Furthermore, AtoB has additional offers that generate revenue. 

Extra Offers From AtoB

Complementary to the zero-fee gas card offer, which certainly stands out, AtoB has other offers within its platform. 

  • AtoB Plus – Paid, subscription-based offers for added benefits. 
  • AtoB Wallet – Stripe-powered digital wallet. 
  • AtoB Payroll – In-app W2 and 1099 payroll platform.  
  • AtoB Factor – Invoice factoring for outstanding earnings (partner offer).

If any of these interest you, I encourage you to look into them — for non-cardholders, see AtoB’s terms & conditions to learn more.  

2. Get On-Time Payments Reported to Experian Business

Anyone building business credit will want to check out AtoB’s full offer when they find out that they report on-time payments to Experian Business every 30 days. 

Does A to B fuel card report to credit bureaus?

Several fuel cards do this — In fact, there are at least a dozen or so business gas cards that report on-time payments to credit bureaus (but, you don’t see me sharing full reviews about all of them, do you?).  

3. It’s Universal: Use Your Card Anywhere Visa is Accepted 

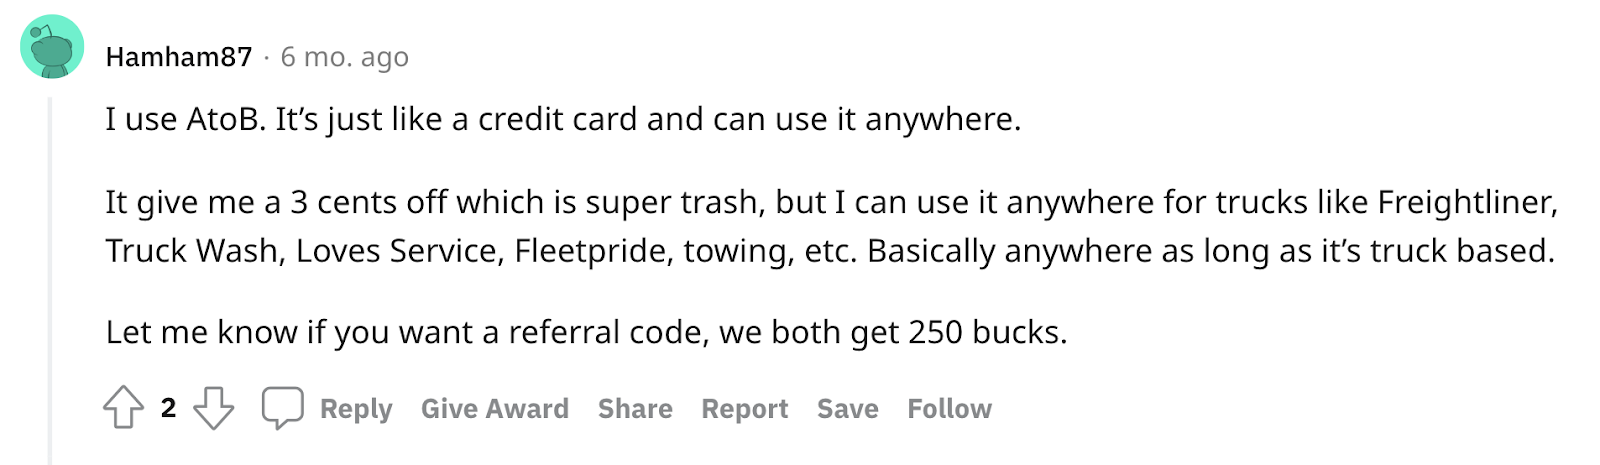
Many, if not most business gas cards are limited to specific, in-network gas stations. AtoB has eliminated that headache and can be used at any station that accepts Visa.  

AtoB fuel card reddit

Full disclosure: AtoB is not the only fuel card that does this. For instance, Comdata has a Mastercard, and Wex has some universal options — they have at least 30 small business gas card offers with various terms. 

4. See the Best Nearby Stations to Buy Fuel 

After 90 days of account and card activation, cardholders can access the AtoB app. You’ll have to reach out to support to activate this perk after you’ve been using your card(s) for a few months.

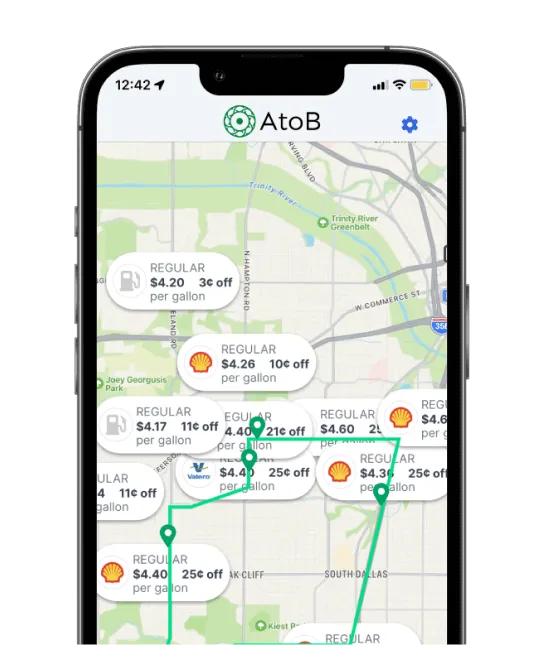
With the AtoB Driver mobile app, anyone can find the best in-network fuel savings in their area, even when they’re on the go — And, the in-app directory includes the fuel grade at each location, to make thoroughly-informed decisions. 

Where can I use atob gas card?

5. Use Your Card to Pay Insurance, Maintenance, Tolls, & More

Most fuel fleet cards offer variable savings on fuel for every gallon purchased. AtoB offers more savings. In addition, they offer business owners the option to opt-in to use your cards on other purchases

So, if you choose, you’ll be able to unlock the ability to use your card(s) to pay auto insurance, vehicle maintenance, bridge & interstate tolls, and other business costs. 

6. Control Spending to Prevent Card Misuse

According to a US fraud report from Shell, 86% of Fleet managers think that drivers’ card misuse results in 30 cents per gallon or 10% in added costs. And, AtoB has used this statistic to power their strategy, add security features to their offer, and to provide a savings prediction for businesses.   

A to B fuel card discounts

So, you’ll not only save via instant discounts but also prevent card misuse for up to 10% savings on gas costs. 

Here’s How to Apply for an AtoB Gas Card

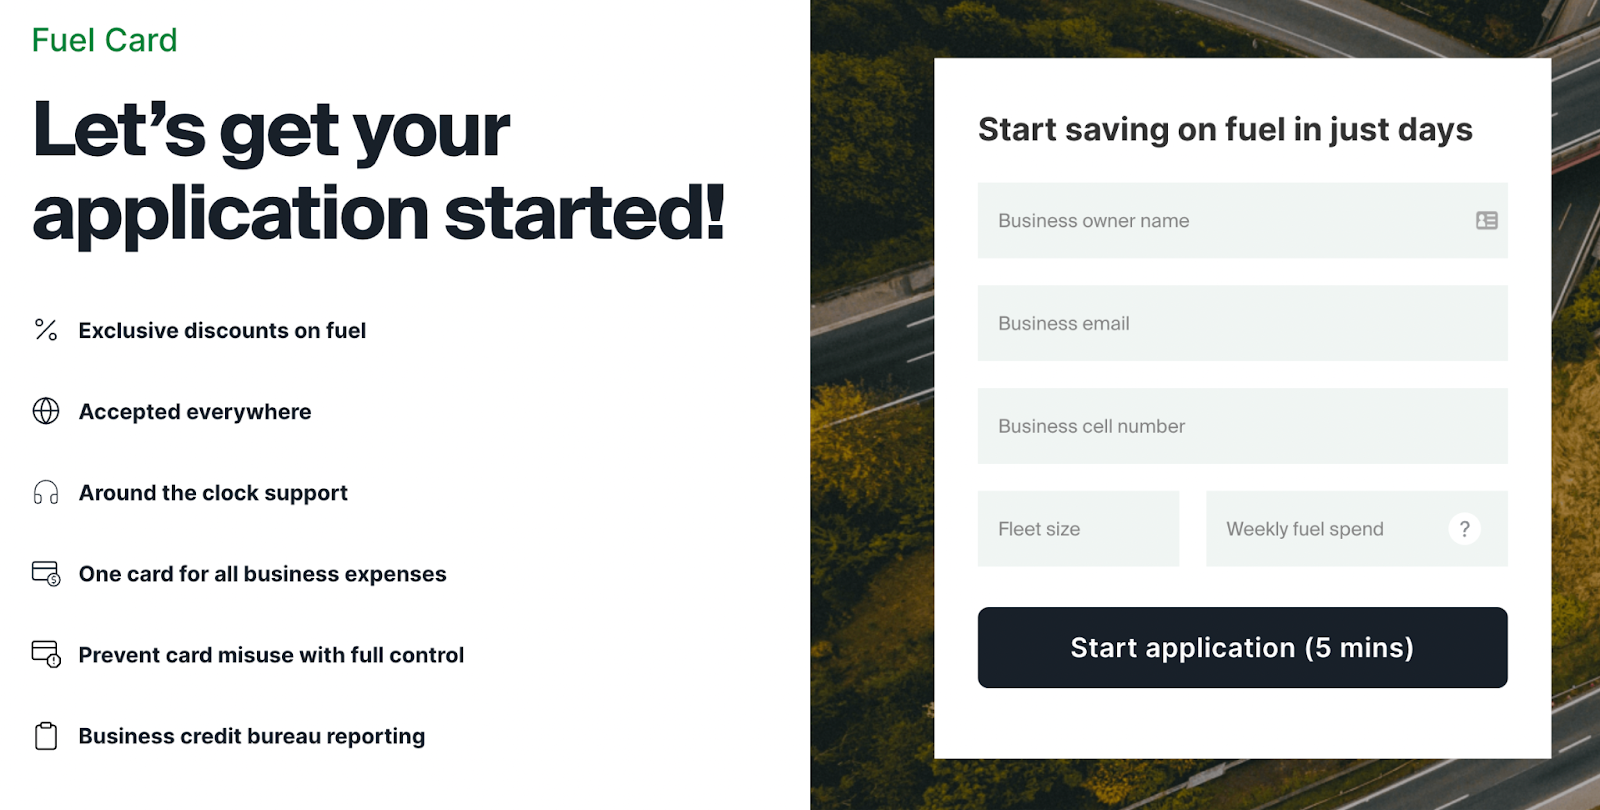
AtoB fuel card application

If you’re ready to apply, head over to AtoB.com, and click Get Started.

The application asks for basic contact info, company info, financial information, and your business location. You’ll have to be a legitimate business owner with an EIN to complete the online form. You’ll also need to share your weekly fuel spend and the number of vehicles you have, along with how many cards you need. And, you’ll need to upload a copy of your driver’s license.  

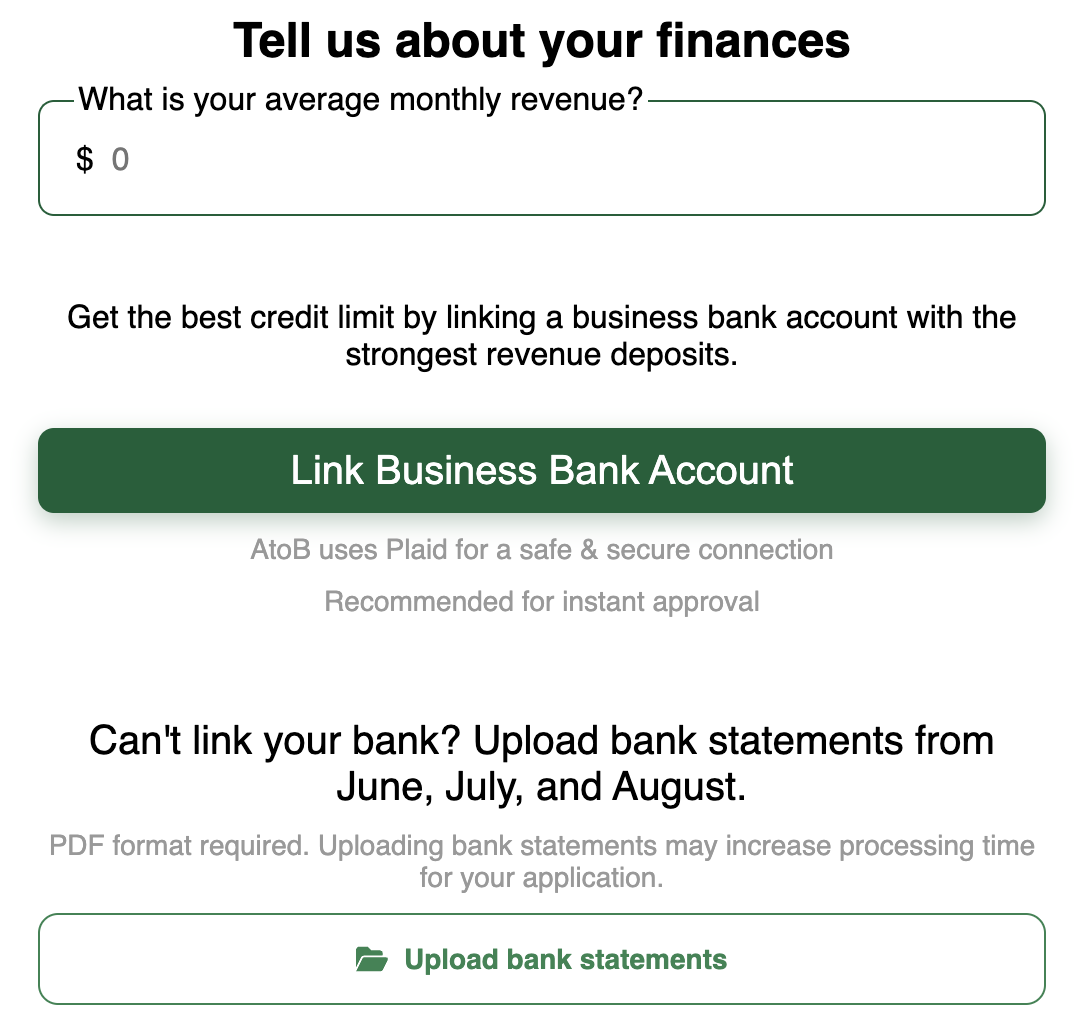
You can either link your business bank account or upload your three most recent business checking account statements. If you try to use a personal checking account, you won’t be able to proceed. 

A to B fuel card application financial information

Before you submit, you’ll have a chance to review the application info you entered. Once your email is confirmed, AtoB will review your information and get back to you within 5-7 business days (that is, according to the website — the sales rep I spoke with said it could take up to 14 days for a decision). 

AtoB fuel card requirements

While they state in their terms & conditions that they reserve the right to pull consumer credit, AtoB does not ask for a social security number during the application process. 

The Secured Card Option From AtoB

Business owners with lower, provable business income may qualify for a secured card (you put money into your account, and refill your fund balance as you go). While secured cards aren’t typically recommended — traditional secured card fees are just too high — this one is free and comes with most of the benefits AtoB offers. 

So, if you are unsure about your ability to qualify for a tradeline, this might still be an offer worth looking into. You be the judge.   

Answers to Related Questions

Will a gas card help build credit?

Many fuel cards report payment activity to credit bureaus, which can help build out the cardholder’s credit profile and, in turn, build credit. Fleet cards (business gas cards) often report on-time payments to D&B, Experian Business, and/or Equifax Business. So, yes, responsible payments made toward a balance on a gas card can help build credit.

Is there a “universal gas card?”

AtoB Fuel Card

Universal gas cards aren’t limited to in-network fuel purchases. There are universal cards. AtoB, for example, can be used anywhere Visa is accepted. And, companies like Comdata and Wex have universal options. 

Is fuel cheaper with a fuel card?

When used at discount locations, which vary from card to card, fuel cards enable the cardholder to save on the price per gallon of gas. AtoB offers savings of up to 25 cents per gallon at select locations and up to 5 cents per gallon universally.  Some fuel cards offer “cash price” or better at select stations.

What fuel card can be used anywhere?

Several fuel cards can be used anywhere. Any card with a Visa or Mastercard logo can be used wherever these types of payments are accepted. AtoB is a universal Visa card, Comdata offers a Mastercard, and Wex has a handful of universal card options. 

What business gas card is easiest to get?

Any secured business gas card is easy to get because you can fund the account with your own cash (and still take advantage of card benefits). Some secured cards come with high fees. AtoB, however, offers a free, secured business gas card to those who might not qualify for net 7 terms at the gate. Over time, most secured cards can be upgraded to more traditional credit terms.      

How do I apply for a gas card?

To apply for a gas card, 99% of the time, you can visit the website of the card you want and apply online. There may be some cases where you must file a paper application. Review a business credit application template to see what you might expect. 

Final Thoughts

In addition to the features and benefits already listed above, I love that AtoB, as a company, is so transparent — they’re not trying to hide anything (as far as I can tell), and their offer stands out from every competitor that I know of. 

If you’re in the market for a fleet card, I recommend you do more research on AtoB, and consider their offer. It seems to be a hit! Before you do, take a look at our list of gas cards that report to business credit bureaus.   

Would you like to learn how to obtain up to $100K in business credit in as few as 30 days? Join Business Credit Workshop today.

Lending Club Business Loans: Everything You Need to Know  

By Joe

Lending Club Business Loans

Key Takeaways

  • Lending Club offers personal and business loans for various needs.
  • The company was the first fintech to acquire a U.S. bank in 2020.
  • They have an A+ BBB rating and a 4.6 TrustScore™ on Trustpilot.
  • Their high-yield savings accounts provide up to 5.15% APY; business accounts earn 1.5% APY with 1% cash back.
  • Lending Clubs business loans are offered in partnership with Accion Opportunity Fund. 
  • The business loan application process is fast, with easy approval and direct deposits.

Since 2007, Lending Club has offered fair credit, unsecured, personal peer-to-peer (p2p) loans for debt consolidation and other major purchases. And they were the first fintech company to acquire a US regulated bank in 2020.  Recently, they acquired a credit card debt payoff app, which aligns with the mission they’re on to become a financial health company, not just a lender. 

Today, Lending Club offers personal and business borrowing, banking, investing, and financial resources. They’ve proven their ability to roll with the punches and their powerful offer is worth exploring. So, for every business owner wondering if you should work with the likes of Lending Club, here’s my honest opinion and complete overview. 

This is what’s in store: 

  • What is Lending Club?
    • What Bank Does Lending Club Use?
    • Company Overview
  • Lending Club Business Loans
    • 1. Loan Amounts from $5K to $250K
    • 2. Competitive Business Loan Rates
    • 3. Fixed Monthly Payments & No Prepayment Penalties
    • 4. Flexible Terms, Easy Application, & Quick Funding
  • How to Get a Small Business Loan with Lending Club
  • Frequently Asked Questions
  • Conclusion: Can Lending Club be Trusted?

Now, let’s go!

What is Lending Club? 

lending club business loans reviews

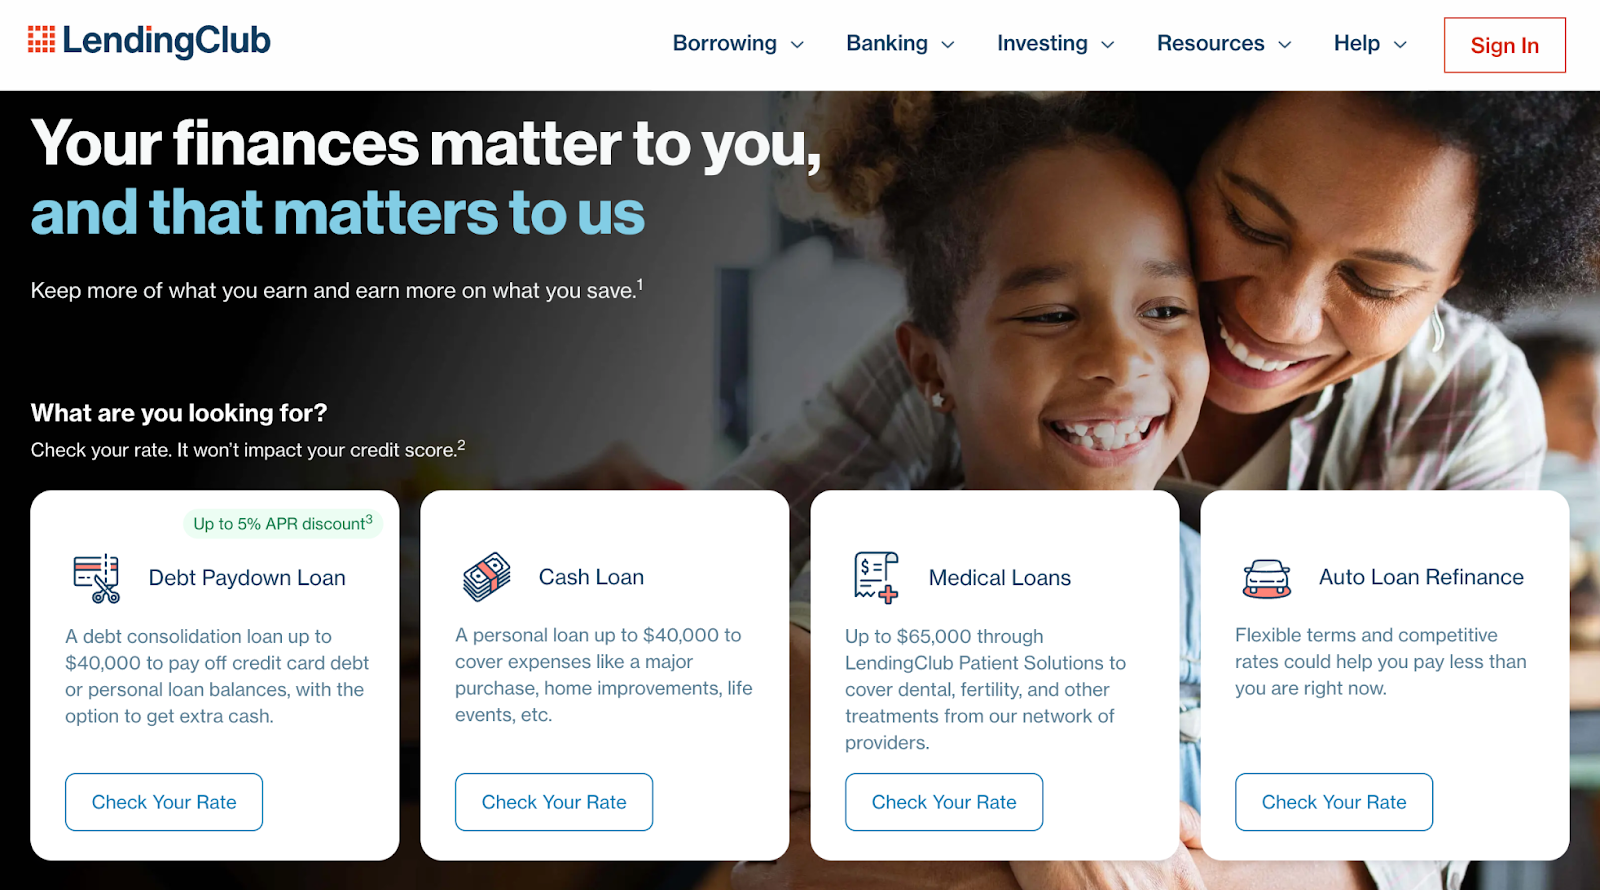
LendingClub is a digital bank that offers a mix of personal and business loans, auto refinancing, and banking products. Known as a “marketplace bank,” it connects borrowers with investors to provide lending services while keeping costs low by operating fully online. LendingClub has issued more than $90 billion in loans to over 4.8 million members since it started in 2007.

LendingClub’s loan products include:

  • Loans up to $40K to consolidate credit card debt or pay off personal loan balances.
  • Personal loans of up to $40K for major purchases, home improvements, or life events.
  • Loans up to $65K through the LendingClub Patient Solutions program for treatments like dental or fertility care.
  • Options to refinance car loans with flexible terms and competitive rates.
  • Small business loans up to $250K.

On top of loans, LendingClub offers banking products like Rewards Checking and High-Yield Savings Accounts with competitive interest rates and benefits like cash-back rewards. LendingClub’s high-yield CDs provide another savings option if you want to grow your savings steadily.

And, LendingClub positions itself as a bank that “only wins when customers succeed.”

You might also like: 11 Alternate Ways for Entrepreneurs to Raise Capital

What Bank Does Lending Club Use? 

In February 2020, the LendingClub Inc. acquired and merged with Radius Bank, then re-launched under a self-branded title. This merger cut out the middle man, which was meant to lead to lower rates promised to bring high yields on new savings accounts. 

At the time, I had doubts about how much difference this would actually make, since Radius Bank and Lending Club’s previous banking servicer (Webank) offered similar savings account yields at 0.25% APY. Happily, I was proven wrong. 

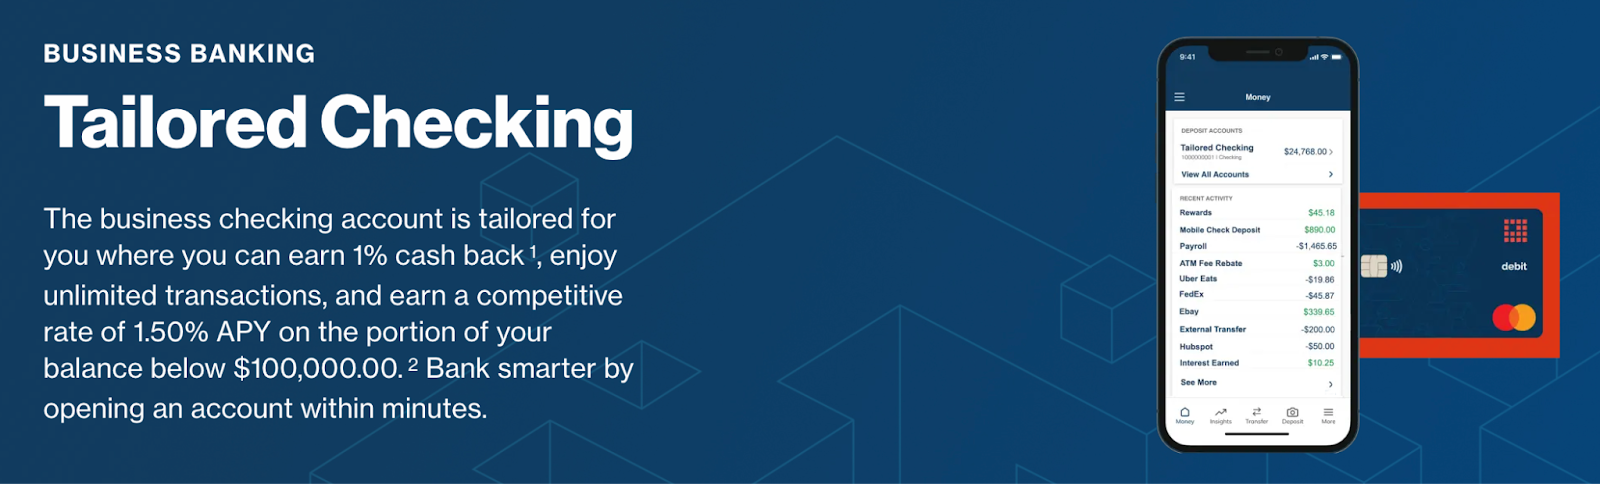
Lending Club now offers 4.8% APY to 5.15% APY on the full balance of LevelUp (personal) savings accounts. And, their Tailored Checking (business) accounts yield 1.5% APY up to $100K. 

lending club business loans review

Moreover, spending on Rewards Checking (personal) and Tailored Checking (business) accounts earn 1% unlimited cash back on spending. 

Recommended: 3 Best Credit Unions for Small Business Banking

Company Overview

Lending Club, aka Lending Club Corporation, is a San Francisco-based company that was founded in 2007 by Renaud Laplanch, who is also the CEO & founder of Upgrade. Prior to launching two successful financial corporations ten years apart, he was a product manager at Oracle. 

lending club scam

Oracle actually acquired one of Laplanche’s earlier products, MatchPoint, in 2005. So, he likely temporarily took over product management of that segment of Oracle’s business after the acquisition and merger. 

Before his entrepreneurial ventures, Laplanche served as an associate at New York’s Cleary Gottlieb, a leading international law firm.

In May 2016, Laplanche resigned following what was labeled “improper decision-making.” LendingClub’s board stated that the resignation took place after Laplanche went against investors’ wishes in a multi-million dollar deal—This was commonly referred to as “the Lending Club scandal,” and made it sound like some sort of pyramid scheme gone wrong, which wasn’t the case. 

At that time, the COO/CMO, Scott Sanborn, took over as Lending Club’s CEO. 

lending club business loans review

Sanborn has a strong business and marketing background, having held high-level executive roles at Home Shopping Network (HSN), RedEnvelope, and eHealthInsurance prior to 2010.

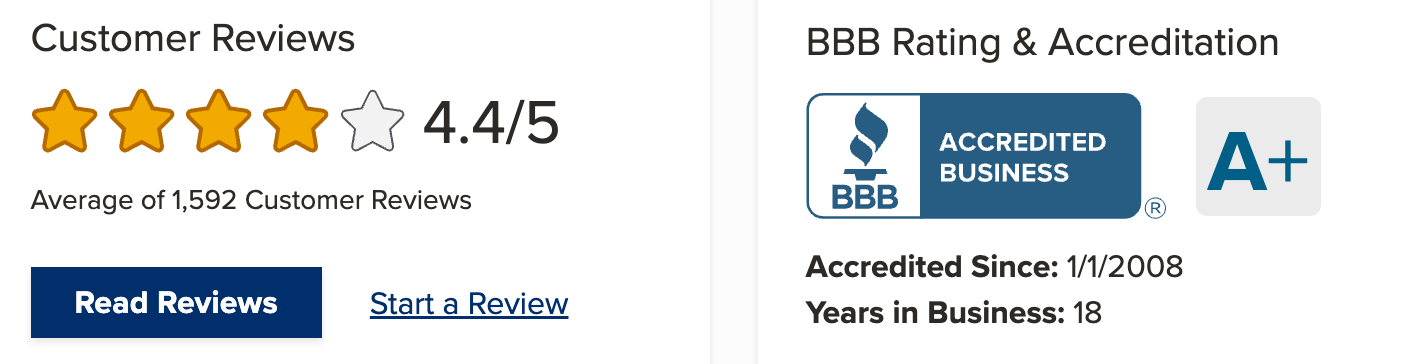
Today, Lending Club has an A+ Better Business Bureau (BBB) rating with 4.4 out of 5 average stars given and accreditation dating back to 2008. All of their 1,199 complaints in the last three years have been closed successfully. 

lending club small business loans reviews

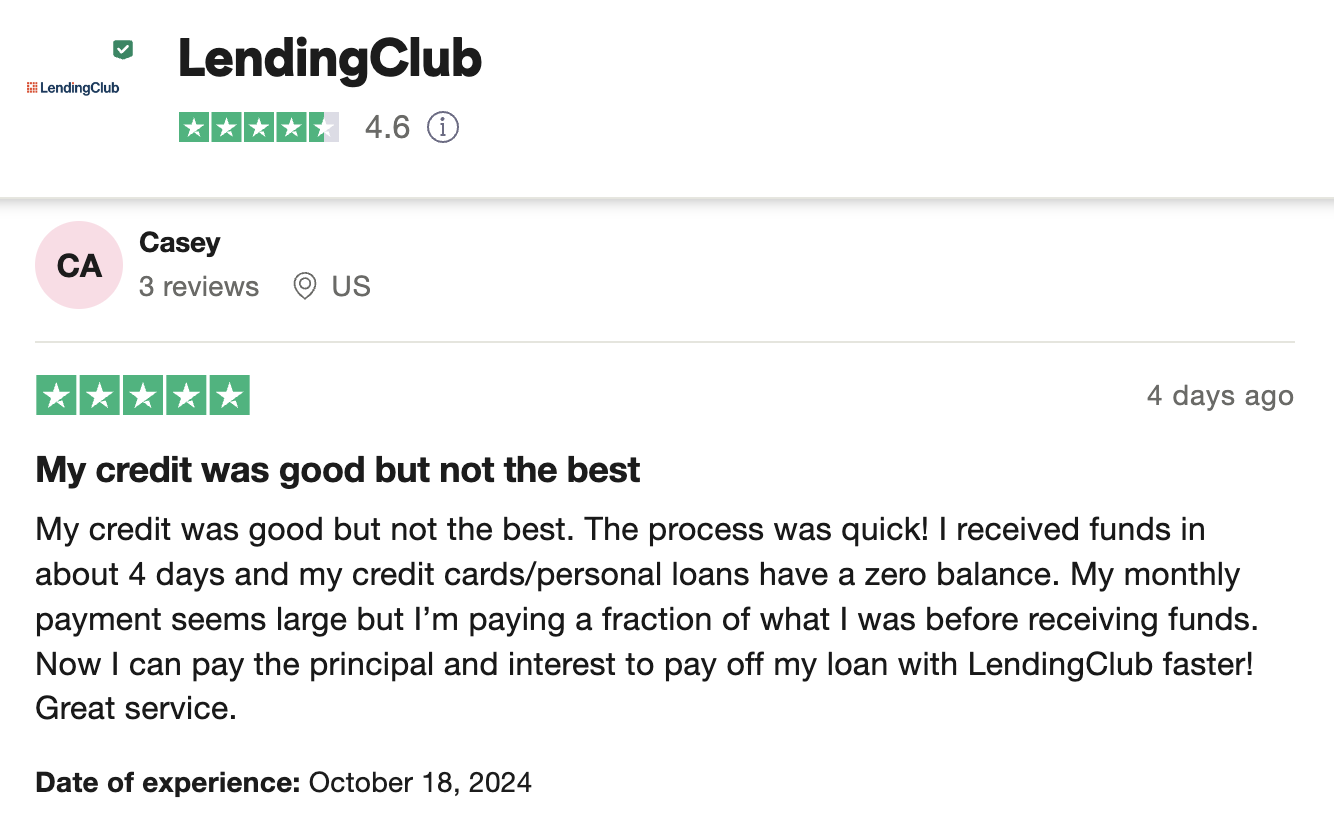
On Trustpilot, Lending Club’s TrustScore™ is 4.6 out of 5 (which is great for a financial offer). Customers praise its fast, easy loan process and “lower” interest rates. Positive reviews highlight efficient service and helpful customer support. Still, a small percentage report issues, mainly related to communication for investors and loan policies during the pandemic. 

lending club reviews

Overall, LendingClub is highly rated for quick funding and debt relief, though some users had isolated concerns.

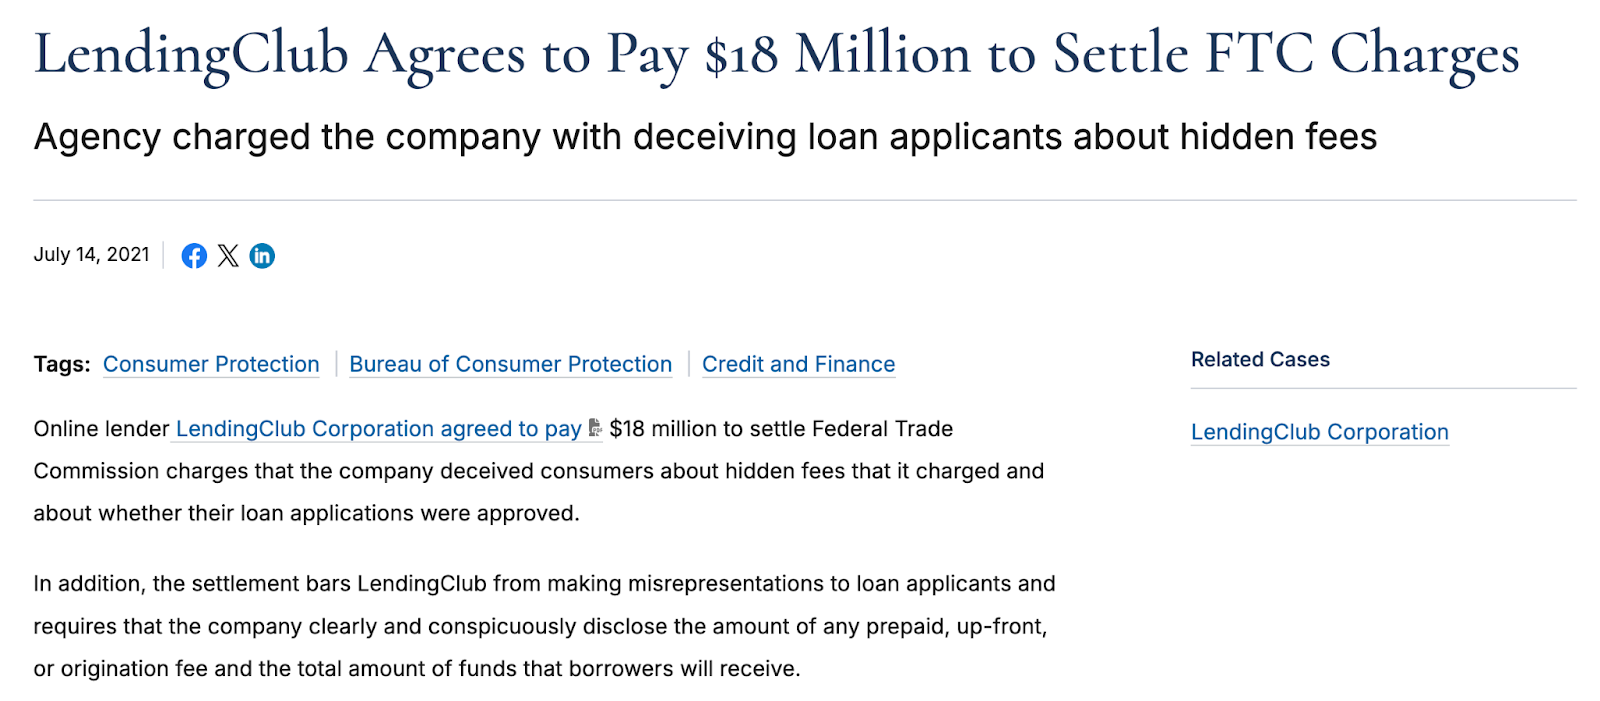
However, in 2018, Lending Club paid $18 million to settle FTC charges that alleged that the company included hidden fees in their loan processes. 

lending club scams

After this, Lending Club agreed to “clearly and conspicuously disclose the amount of any prepaid, up-front, or origination fee and the total amount of funds that borrowers will receive.” 

Since this incident, a lot of people still ask, ‘why is Lending Club shutting down?’ The answer is, it’s not. That was a rumor from the beginning.  

In all, it’s probably fair to say LendingClub has a generally positive standing but has faced serious issues with transparency in the past. But, they seem to have been addressed. 

You might also like: Is United Capital Source Legit? A Complete, Uncut Breakdown 

Lending Club Business Loans

does lending club offer small business loans

Lending Club small business loans and lending club SBA loans cater specifically to businesses. Their business financing offers higher amounts to qualified business owners than to consumers. So, let’s find out what you can expect and what you might qualify for. 

Note: Lending Club’s business loans are offered in partnership with Accion Opportunity Fund (a non-profit lender, that is also a driving force behind Skip’s small business grant offer). 

1. Loan Amounts from $5K to $250K

the lending club business loans

With Lending Club, your business can borrow between $5K and $250K, which can give you the flexibility to secure the right amount based on your business needs. This range covers a variety of financial goals, whether you’re expanding, covering expenses, or consolidating debt.

You might also like: Ramp Card Review: Is This the Corporate Card for You? 

2. Competitive Business Loan Rates

lending club business loans rates

Lending Club’s business loan rates, through Accion Opportunity fund, actually start on, at 8.49%. According to the most recent data from the Federal Reserve as of November 2024, the typical interest rate for small-business bank loans ranged between 6.42% and 12.41%.

Note: Lending Club’s SBA loan rates (not what we’re talking about here) are based on the current prime rate. 

You might also like: No-Doc Business Loans: Get Funds Without Proof of Income 

3. Fixed Monthly Payments & No Prepayment Penalties

small business loans lending club

Fixed monthly payments provide stability and make it easier to budget for loan repayments. This predictability can help keep your business cash flow on track without unexpected changes to payment amounts.

If you’re able to pay off your loan early, there are no penalties—This allows you to save on interest costs if your business finances improve sooner than expected, giving you more control over total loan expenses.

4. Flexible Terms, Easy Application, & Quick Funding

how long does lending club take to approve

With term options ranging from 1 to 5 years, you can choose the repayment period that best suits your business’s financial strategy. Shorter terms mean less interest overall, while longer terms can make monthly payments more manageable.

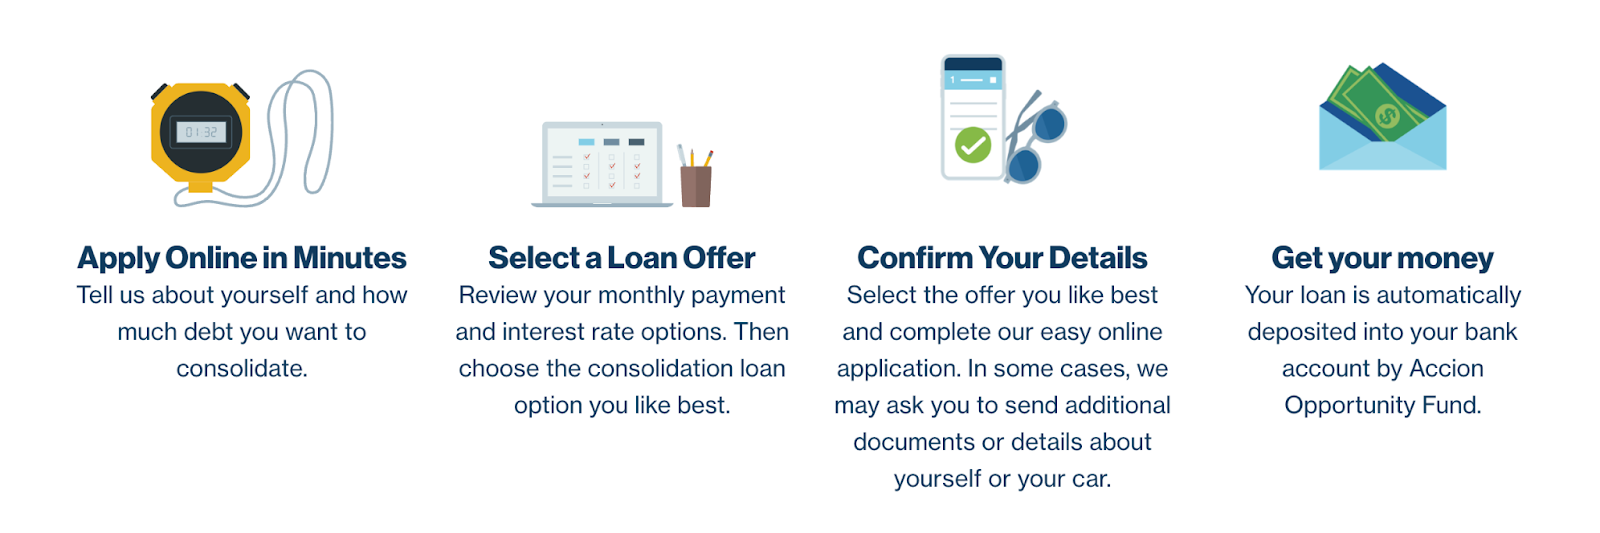
You can apply online in minutes, making the process quick and convenient. Once approved, Accion Opportunity Fund deposits the funds directly into your bank account, allowing you to access financing without delay.

How to Get a Small Business Loan with Lending Club

lending club business loans requirements

If you’re wondering how to get a business loan with Lending Club, the answer is uncomplicated.  

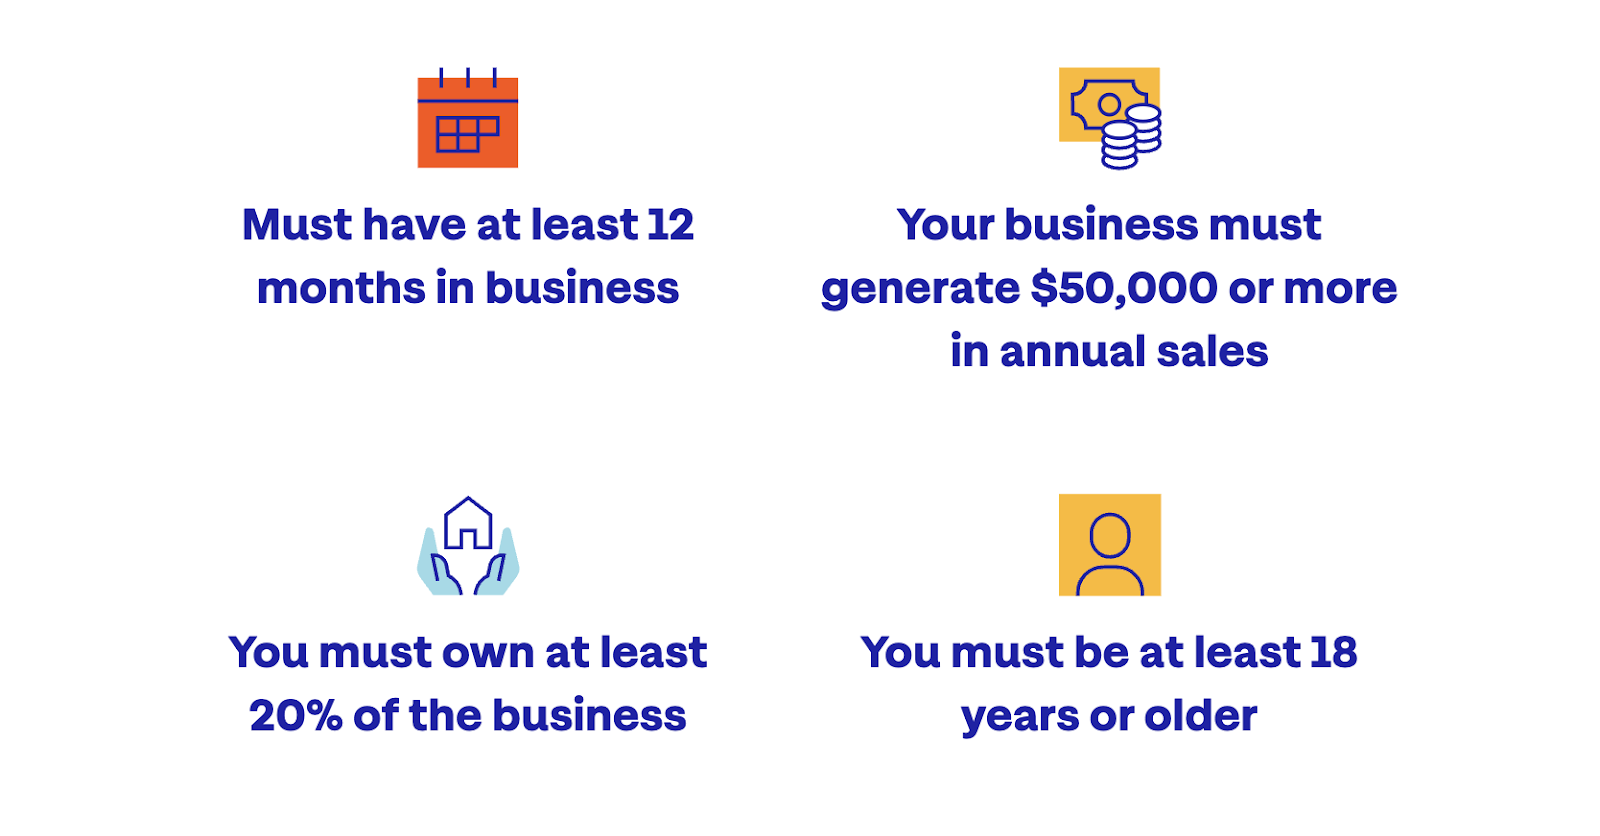
To qualify, your business needs to meet basic eligibility criteria:

  • 12+ months in business 
  • $50K+ in annual sales 
  • US-based company 
  • 20% or more ownership 
  • Consumer credit score of 600+

A lot of business loans that we review require at least 50% ownership for an owner-applicant to qualify. So, Lending Club stands out in this area. 

What credit score is needed for LendingClub?

While these loans appear to be issued based on the owner-applicant’s credit score, Accion Opportunity Fund is known to report business payment activity to Experian, Equifax, and Dun & Bradstreet—These are the leading business credit bureaus, so on-time payments can help you build your business credit score.  

You might also like: This is How to Leverage Business Credit to Transform Your Life 

Frequently Asked Questions

 Is it hard to get a loan through LendingClub?

LendingClub has flexible lending criteria, but you’ll generally need a good credit score, steady income, and a manageable debt-to-income ratio to qualify. Their process is straightforward, though approval requirements may vary.

Is LendingClub an actual loan company?

Yes, LendingClub is a legitimate online lending company that connects borrowers with investors for personal, business, and medical loans. They’ve been in operation since 2007.

Is LendingClub bank in trouble?

No, LendingClub is not currently facing any known legal or financial issues. The company has faced some challenges in the past, but it maintains high ratings on platforms like BBB and Trustpilot today.

Is LendingClub a safe place to put money?

Yes, LendingClub is generally considered safe for both borrowers and investors, with strong security protocols. However, as with any investment, there are risks, especially in loan investing.

Conclusion: Can Lending Club be Trusted?

As a borrower, LendingClub’s offer is legit, yes. The company is established and has grown to become a trustworthy funding source for personal loans, business loans, auto refinancing, and patient solutions. 

Through their partnership with Accion Opportunity Fund, you could qualify to get up to $250K in business credit if you and your business meet the qualifications. If you apply and don’t qualify for a business loan, Accion Opportunity will attempt to refer you to one of their partners to provide other resources. 

Are you ready to learn how to get up to $100K in business credit? Join Business Credit Workshop today! 

A Complete Torpago Business Credit Card Review