• Home
  • Free Funding Guide
  • What We Offer
    • Products
    • Services
    • Free Guide
  • About Us
  • Contact
  • Sign Up

  • Ask Joe Any Question!
  • Business Credit Cards
  • Business Line of Credit
  • Topics

How to Find Aged Shelf Companies for Sale +Why Buy Them? 

By Joe

aged shelf companies for sale

Looking to get into the world of aged shelf companies? You’re in the right place! Aged shelf companies, also known as blank check companies or ready-made businesses, are like the fine wine of the business world – they’ve been sitting on the shelf, waiting for the perfect moment to shine. 

In this guide, we’ll take you on a journey through the ins and outs of aged shelf companies, from what they are to where to find them.

Here’s what’s in store: 

  • What are Aged Shelf Companies?
    • What are the Characteristics of a Shelf Company?
    • How Much Does a Shelf Corporation Cost?
  • Why Buy an Aged Shelf Corporation?
    • What do People Do With Shelf Companies?
  • How to Find Aged Shelf Companies for Sale
    • 1. Online Business Brokers
    • 2. Legal & Financial Services
    • 3. Business Directories
    • 4. Networking
    • 5. Online Marketplaces
    • 6. Legal Notices
    • 7. Industry Conferences & Events
    • 8. Business Associations
    • 9. Online Forums and Classifieds
  • How to Protect Yourself From a “Bad” Shelf Company
  • FAQ
  • Final Thoughts

Now, let’s get to it! 

What are Aged Shelf Companies?
aged shelf company definition

Also known as blank check companies, ready-made companies, or simply “aged” companies, aged shelf companies are registered entities that have had no activity. Think of it as setting your business on a shelf to age like a bottle of wine. 

Check out our Shelf Corp - Special Deal!

See our discounted offer on an Aged Shelf Corp for sale (plus our best training included for free). Just click Add to Card below

Add to Cart
Lasso Brag

Like wine, when the right conditions are met, a business can improve when aged. Except, rather than enhance the flavor, a shelved company establishes corporate history and, when opened, can expedite business processes. 

Note: Shelf companies are not to be confused with “shell corporations,” which are typically empty entities used for concealing ownership, avoiding taxes, or engaging in illicit activities.

What are the Characteristics of a Shelf Company? 

In a nutshell, aged shelf companies have been around for several years or more, often decades, and remain inactive since their creation. They have a clean financial and operational history, with no debts or liabilities.

Now, let’s find out how much a shelf corporation costs and the considerations involved. 

How Much Does a Shelf Corporation Cost? 

So, how much does it cost to snag one of these shelf corporations? Well, it’s kind of like buying anything vintage – the price can vary, and it depends on several factors:

  1. Older shelf corporations tend to cost more because they’ve got that longer corporate history going for them.
  2. Where it’s registered matters. Some places have higher fees and maintenance costs.
  3. The person or entity selling the shelf corporation sets the price – It can be influenced by demand and what extras they throw in.
  4. Some sellers offer stuff like help with transferring ownership or handling compliance, which can affect the price tag.
  5. If the company’s got a snazzy name or a certain legal structure, that can drive up the cost. 
  6. Sometimes, you get additional documents like articles of incorporation or organization and credit reports, which can bump up the price. 
  7. The demand for shelf corporations in a particular area or industry can make the prices go up or down. 

See: Low-Risk NAICS Codes +Best SIC Codes for Business Credit

Prices can range from a couple hundred bucks up to ten grand, so do your homework – think about what you need and make sure to check for any hidden surprises before you dive in! 

Why Buy an Aged Shelf Corporation? 
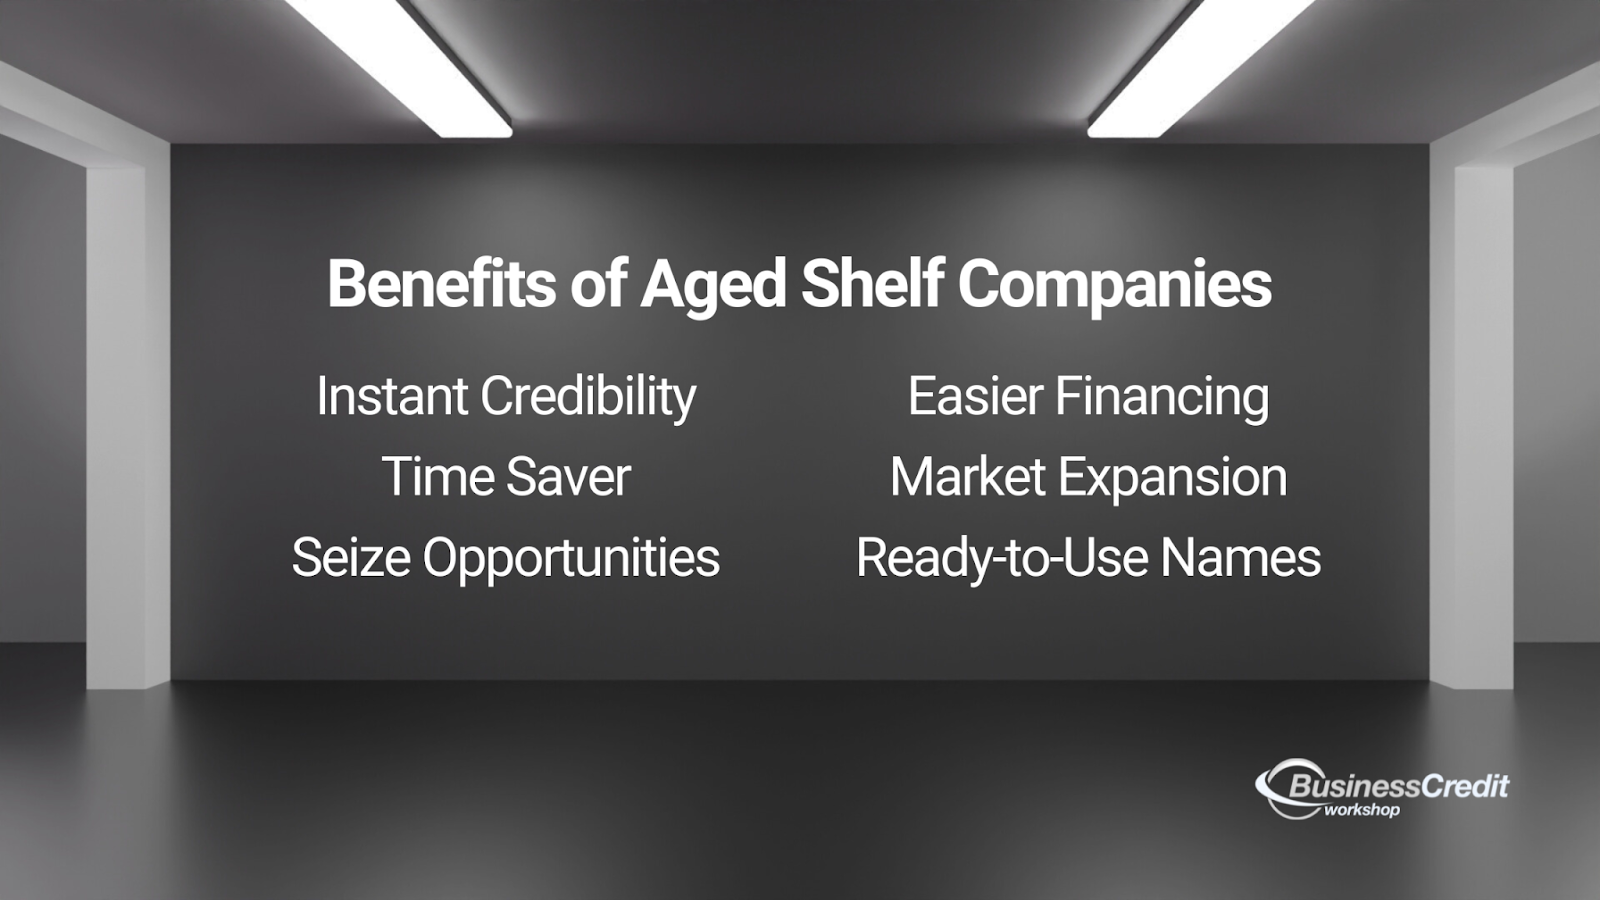
What is the meaning of a shelf company benefits

Now, let’s talk about why some folks choose to snag an aged shelf company—it’s kind of like thrift shopping for businesses.  

Here’s why you might want to buy one:

  • Instant street cred – These old-timers have been around the block for a while, so your business looks legit right from the start. Customers and partners might trust you more.
  • Skip the line – Instead of waiting in line to set up a brand-new business, you can waltz right in with a shelf company. Quick and easy, no fuss.
  • Grab opportunities – Sometimes, to get certain contracts or loans, you need a business with a bit of history. Shelf companies meet those requirements with style.
  • Borrowing made easy – If you need cash, lenders often prefer companies with a few years under their belt. With an established business, getting business credit can be smoother.
  • Blink and You’re In – Expanding your business into new markets? A shelf company can help you jump through those legal hoops faster.
  • Name Game – If the shelf company has a cool name, you can use it without the hassle of registering a new one.
  • Tailor-Made – When you choose a shelf company that fits your business strategy, it’s like a ready-made suit, but for your business.

Next, let’s look at what you can do with them. 

Recommended: This is How to Leverage Business Credit to Transform Your Life 

What do People Do With Shelf Companies?

So, what’s the deal with shelf companies? Well, folks use ’em for all sorts of reasons.

Imagine you’re in a hurry to kickstart a business or snag some sweet contracts. A shelf company’s like a shortcut because it’s been around for a while, making your new venture look trustworthy right from the get-go. Plus, if you need loans or want to expand into new markets, having a seasoned business can make things way smoother. You can also protect specific assets or use a snazzy business name without the usual hassles.

Maybe you’re already working a business, but you’re unincorporated. An aged shelf company offers a nice way to slide right into the 

But here’s the catch: before you take the plunge, do some digging. Not all shelf companies are the same, so be sure to check for any hidden surprises. 

How to Find Aged Shelf Companies for Sale
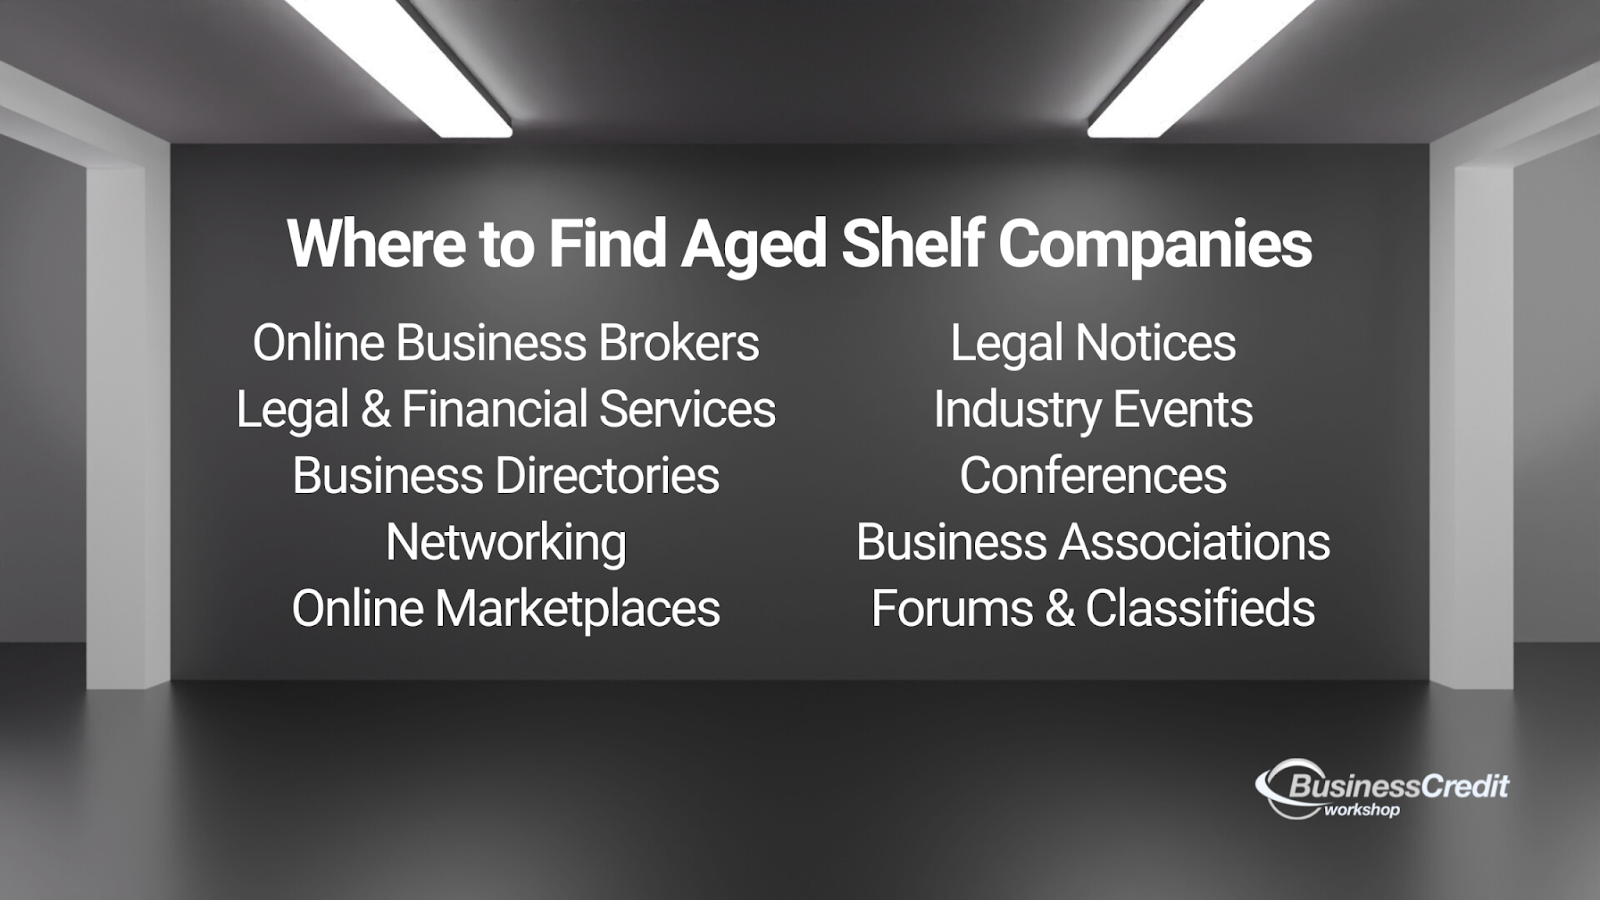
Where to find aged shelf companies

State Secretary of State (SOS) offices typically maintain records of registered business entities, including corporations and LLCs. 

However, while you can find information about existing businesses and their registration status through the SOS office, you typically won’t find aged shelf companies specifically listed for sale in these government databases.

Aged shelf companies are usually sold by individuals or businesses in the private sector, often through business brokers, legal and financial services, online marketplaces, or other commercial channels. 

If you’re interested in purchasing an aged shelf company, you would typically need to search for listings or consult with professionals and businesses that specialize in providing aged shelf companies for sale. These sellers acquire and maintain shelf companies and then offer them for purchase to individuals and businesses seeking to expedite the startup or expansion of a new venture.

Finding aged shelf companies for sale can be relatively straightforward with the right approach. Here’s how to go about it.

Certainly, let’s break down how to use each channel to secure an aged shelf company, along with the pros and cons of each approach:

1. Online Business Brokers

Numerous online business broker websites specialize in selling aged shelf companies. These platforms list various aged corporations available for purchase, complete with details about their age, location, and price. You can search and filter listings to find the one that suits your needs.

  1. Visit reputable online business broker websites like Corporations Today Inc. or BSC & Associates.
  2. Seek out aged shelf companies that match your criteria.
  3. Review listings, including details on age, location, and price.
  4. Contact the broker to express your interest and inquire about the purchase process.

Pros:

  • Wide selection of shelf companies.
  • Detailed listings with essential information.
  • Broker assistance with the purchase process.
  • Potential for competitive pricing.

Cons:

  • Broker fees may apply, increasing the overall cost.
  • Limited opportunity for direct negotiations with the seller.

2. Legal & Financial Services

Some law firms and financial services companies offer aged shelf companies as part of their services. They can provide guidance on the purchase process, ensure legal compliance, and help with the transfer of ownership.

  1. Consult law firms or financial service providers like Companies Incorporated or AmeriLawyer that offer aged shelf companies.
  2. Discuss your specific needs and budget with the service provider.
  3. Review available shelf companies in their inventory.
  4. Work with the service provider to complete the purchase and transfer of ownership.

Pros:

  • Expert guidance on legal compliance.
  • Streamlined purchase process.
  • Assistance with ownership transfer.
  • May include additional services such as registered agent services.

Cons:

  • Costs may be higher due to bundled services.
  • Limited selection compared to online listings.

3. Business Directories

You can check business directories or databases for companies that offer shelf corporations. Look for contact information and inquire about their available inventory.

  1. Explore business directories or databases.
  2. Identify companies offering shelf corporations for sale.
  3. Contact the companies directly to inquire about available aged shelf companies.

Pros:

  • Direct access to potential sellers.
  • May find local options easily.
  • Direct communication with the seller.

Cons:

  • Limited information available in directories.
  • May require extensive outreach and research.
  • Limited selection compared to specialized platforms.

4. Networking

Connect with entrepreneurs, business consultants, or professionals in your industry who may have knowledge of or access to shelf companies for sale. They might provide valuable recommendations or leads.

  1. Network with entrepreneurs, business consultants, or industry professionals.
  2. Share your interest in acquiring a shelf company.
  3. Seek recommendations or referrals from your network.

Pros:

  • Personalized recommendations.
  • Potential for insider information.
  • Trustworthy referrals from known contacts.

Cons:

  • Networking may take time.
  • Reliance on others to provide leads.
  • Limited control over the selection process.

5. Online Marketplaces

Explore online marketplaces like eBay or Flippa, where sellers occasionally list aged shelf companies for sale. Be sure to conduct due diligence and verify the legitimacy of the seller and the company being offered.

  1. Search online marketplaces like eBay for aged shelf companies.
  2. Review listings, including seller ratings and descriptions.
  3. Contact the seller to discuss the purchase.

Pros:

  • Accessibility to a wide audience.
  • Opportunity to negotiate directly with the seller.
  • Transparency through ratings and reviews.

Cons:

  • Limited availability of shelf companies.
  • May encounter less reputable listings.
  • Need for thorough due diligence on sellers.

6. Legal Notices

Check local or national legal publications or government websites for any notices about companies being offered for sale – This might lead you to aged shelf companies available in your jurisdiction.

  1. Check local or national legal publications or government websites for notices about companies for sale.
  2. Contact the parties offering shelf companies.
  3. Inquire about the available options.

Pros:

  • Potential to find local opportunities.
  • Information often publicly available.

Cons:

  • Limited listings.
  • May not be actively updated.
  • Limited details in legal notices.

7. Industry Conferences & Events

Attend industry-specific conferences, trade shows, or business events. You may come across vendors or experts who offer aged shelf companies as part of their services.

  1. Attend relevant industry conferences, trade shows, or events.
  2. Network with vendors or experts in the field.
  3. Inquire about any aged shelf companies they may offer.

Pros:

  • Direct access to industry-specific opportunities.
  • Face-to-face interactions for building trust.

Cons:

  • Limited availability during specific events.
  • May not align with your timeline.

8. Business Associations

Join business associations or chambers of commerce related to your industry. Members often share information and resources, including opportunities to purchase shelf companies.

  1. Join industry-related business associations or chambers of commerce.
  2. Engage with fellow members and express your interest.
  3. Seek information or leads from association members.

Pros:

  • Networking within your industry.
  • Trustworthy referrals from association members.

Cons:

  • Reliance on the association’s network.
  • May require time for connections to develop.

9. Online Forums and Classifieds

Participate in online forums, classified ad websites, or social media groups like Reddit r/business where businesses are discussed, bought, and sold. Some individuals or companies may advertise aged shelf companies there.

  1. Participate in relevant online forums, classified ad websites, or social media groups.
  2. Engage with members and express your interest in purchasing a shelf company.
  3. Inquire about any listings or opportunities available.

Pros:

  • Direct access to potential sellers.
  • Informal and open communication channels.
  • Potential for unique opportunities.

Cons:

  • Limited oversight, requiring thorough due diligence.
  • May encounter less reputable listings.
  • Time-consuming to filter through various sources.

When searching for aged shelf companies, always exercise caution and conduct thorough due diligence.

How to Protect Yourself From a “Bad” Shelf Company

So, before you buy an aged shelf company, you want to make sure you’re not getting a lemon, right? 
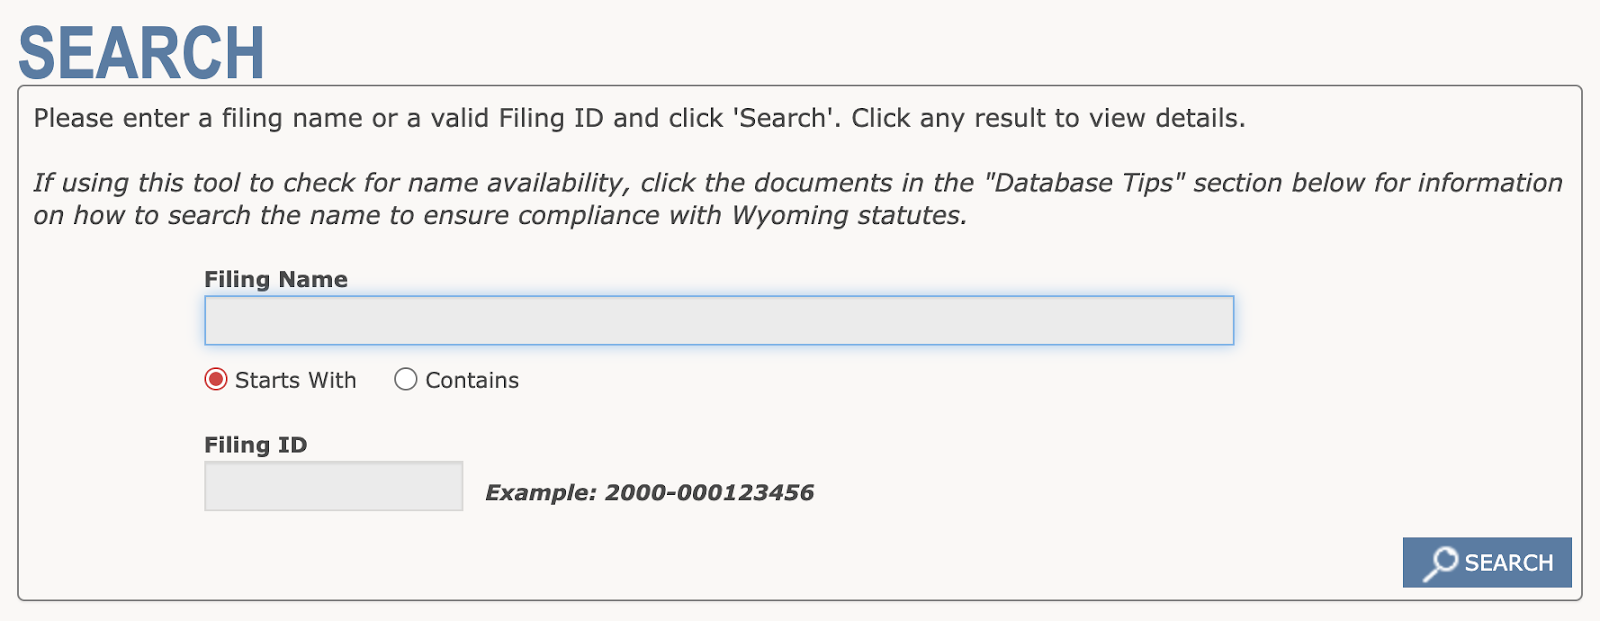
WY SOS Business Search

Here’s what you should do:

  • Check the articles – Look at the company’s articles of incorporation or organization. Make sure they match up with what you want to do with the business.
  • Review financial records – If you can, get your hands on financial statements. You’ll want to know if the company’s in good financial shape – It should have no debt. 
  • Verify ownership transfer – Ensure the ownership transfer process is legit and filed with the authorities. Get clear documentation of the transfer signed by both parties.
  • Legal documents – Check if there are any undisclosed legal issues or obligations lurking in the company’s records. And make sure the registered agent and address are up-to-date.
  • Credit package – If applicable, review any credit packages associated with the shelf company to understand any existing credit lines or financing agreements.

By going through these documents, you’ll have a better idea of what you’re getting into and can avoid any nasty surprises down the road. Be sure to verify the authenticity of the seller, review all of the company’s history and records, and consult legal and financial experts to ensure a smooth and secure transaction.

FAQ

Why do shelf companies exist?

Shelf companies are like prepped-up businesses waiting for action. They exist for folks who want to skip the startup hassle and dive into business with a history.

Do shelf companies pay taxes?

Yup, they’re not tax-free. Shelf companies, like any other business, need to pay taxes based on their income and location (if they have no income, their tax obligation would likely be $0).

Can you register a business in a state where you don’t live?

Absolutely! You can register a business in a state where you’re not living. It’s common for folks to do this to tap into specific business advantages or markets. But, if you are active in your home state, the business may need to be registered there as well. 

Should you buy a shelf corporation?

Well, it depends on your needs. If you want a head start and a business with history, it’s an option. But, always do your homework and make sure it’s the right fit for your goals.

Final Thoughts

So, there you have it – the lowdown on aged shelf companies, from what they are to why you might want to buy one and how to protect yourself from any surprises. Whether you’re looking to kickstart a business with instant history or expand your current venture, aged shelf companies offer a unique shortcut. 

But remember, it’s all about doing your homework, verifying the details, and making sure it’s the right move for your entrepreneurial journey. Cheers to your future business success!

Want to learn how to get up to $100K in business credit? Join Business Workshop today.

Check out our Shelf Corp - Special Deal!

See our discounted offer on an Aged Shelf Corp for sale (plus our best training included for free). Just click Add to Card below
Add to Cart
Lasso Brag

How to Raise Money for Real Estate Investment: A Beginner’s Guide

By Joe

How to raise money for real estate

Real estate is filled with lucrative opportunities. But, before you can reap the rewards, you need funds…Sometimes, you can do it all on your own. But, to make sizable investments, most people need to raise money.

The good news is, anyone with the right information can do it. My goal is to make fundraising easy to understand for everyone. Whether you’re a pro or just starting out, here, you’ll find the fundamentals you need to raise money for real estate investing.

Here’s what’s in store: 

  • Real Estate Ventures and Capital
    • Residential Real Estate
    • Commercial Real Estate
    • Real Estate Capital
  • Ways to Raise Real Estate Capital
    • 1. Business Credit
    • 2. Home Equity
    • 3. Peer-to-Peer Loan
    • 4. Private & Hard Money Lenders
    • 5. Self-Directed Accounts
    • 6. Wholesaling
    • 7. Crowdfunding & Syndication
    • 8. FHA & USDA Mortgages
  • Legal Obligations to Keep in Mind
  • Frequently Asked Questions
  • Conclusion

Now, let’s get it! 

Recommended: This is How to Leverage Business Credit to Transform Your Life 

Real Estate Ventures and Capital

Before we delve into the nitty-gritty of raising capital, it’s crucial to understand the fundamentals. 

You can invest in various types of properties, like single-family homes, towering skyscrapers, apartment buildings, senior living communities, medical facilities, shops, factories, and warehouses. 

The two main types of real estate are: 

  • Residential real estate
  • Commercial real estate

Real estate ventures, whether residential or commercial, require significant investment. This capital is essential for property acquisition, development, maintenance, and generating returns.

Residential Real Estate

How to raise money for real estate investment

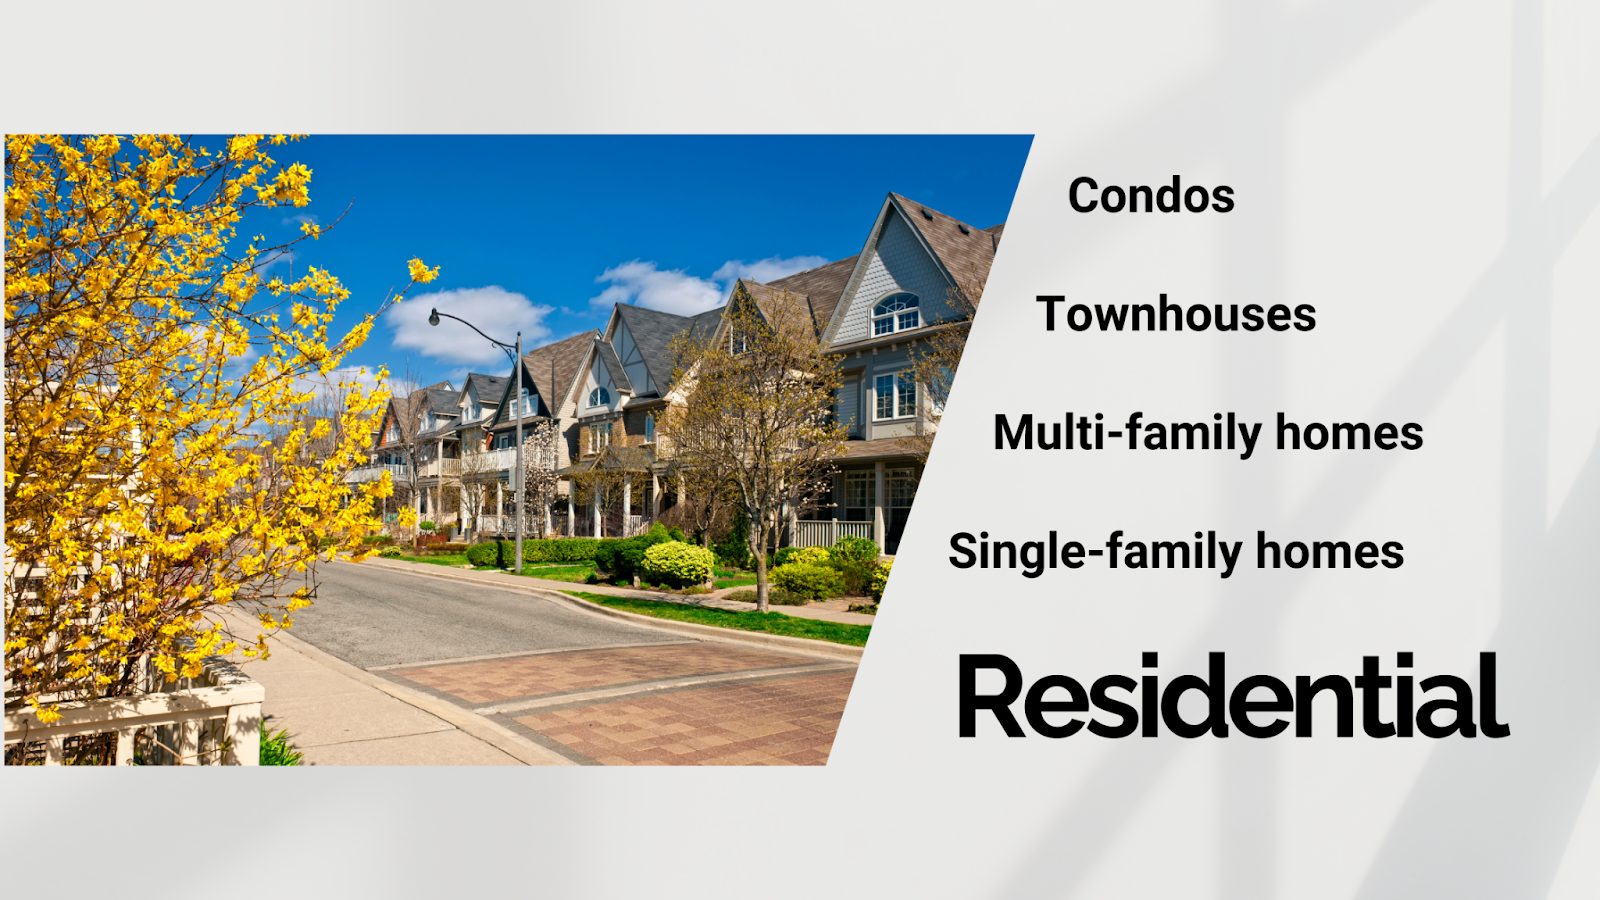
Residential real estate refers to properties that are designed and used for housing purposes. These properties are where people live, such as houses, apartments, condominiums, townhouses, and vacation homes. Residential real estate is typically divided into four main categories:

  • Single-family homes are stand-alone houses designed for a single family to live in. They come in various sizes and styles, from small cottages to large estates.
  • Multi-family homes include duplexes, triplexes, and apartment buildings. They provide housing for multiple families within a single structure.
  • Condominiums (condos) are individual units within a larger building or complex. Residents own their individual units and share common areas and amenities.
  • Townhouses are usually multi-story properties with shared walls between units. Each unit has its own entrance, and residents own both the interior and exterior of their unit.

Investors in residential real estate often focus on renting or selling these properties to individuals or families for residential purposes. The residential real estate market can be influenced by factors such as location, demand, economic conditions, and interest rates.

Commercial Real Estate

How to raise capital for commercial real estate

Commercial real estate is what we call the properties that are used for business and commercial purposes – It includes a wide range of property types, catering to various industries and needs. Some common types of commercial real estate include:

  • Office buildings are used for office spaces, ranging from small business offices to large corporate headquarters.
  • Retail spaces are designed for businesses to sell products or services to consumers. They can include shopping centers, malls, standalone stores, and restaurants.
  • Industrial properties include warehouses, manufacturing facilities, distribution centers, and industrial parks. These properties are essential for logistics and production.
  • Hospitality properties are hotels, motels, resorts, and other buildings that provide accommodations and services to travelers and tourists.
  • Special-use properties serve unique purposes – Think healthcare facilities, educational institutions, religious buildings, and entertainment venues.

Investing in commercial real estate often involves leasing properties to businesses or organizations. Commercial property values can be influenced by factors like location, accessibility, lease terms, and economic conditions.

Real Estate Capital

How to raise money for real estate investing

Real estate capital refers to the financial resources needed to invest in real estate properties. Capital is needed to purchase, develop, maintain, and operate real estate assets. 

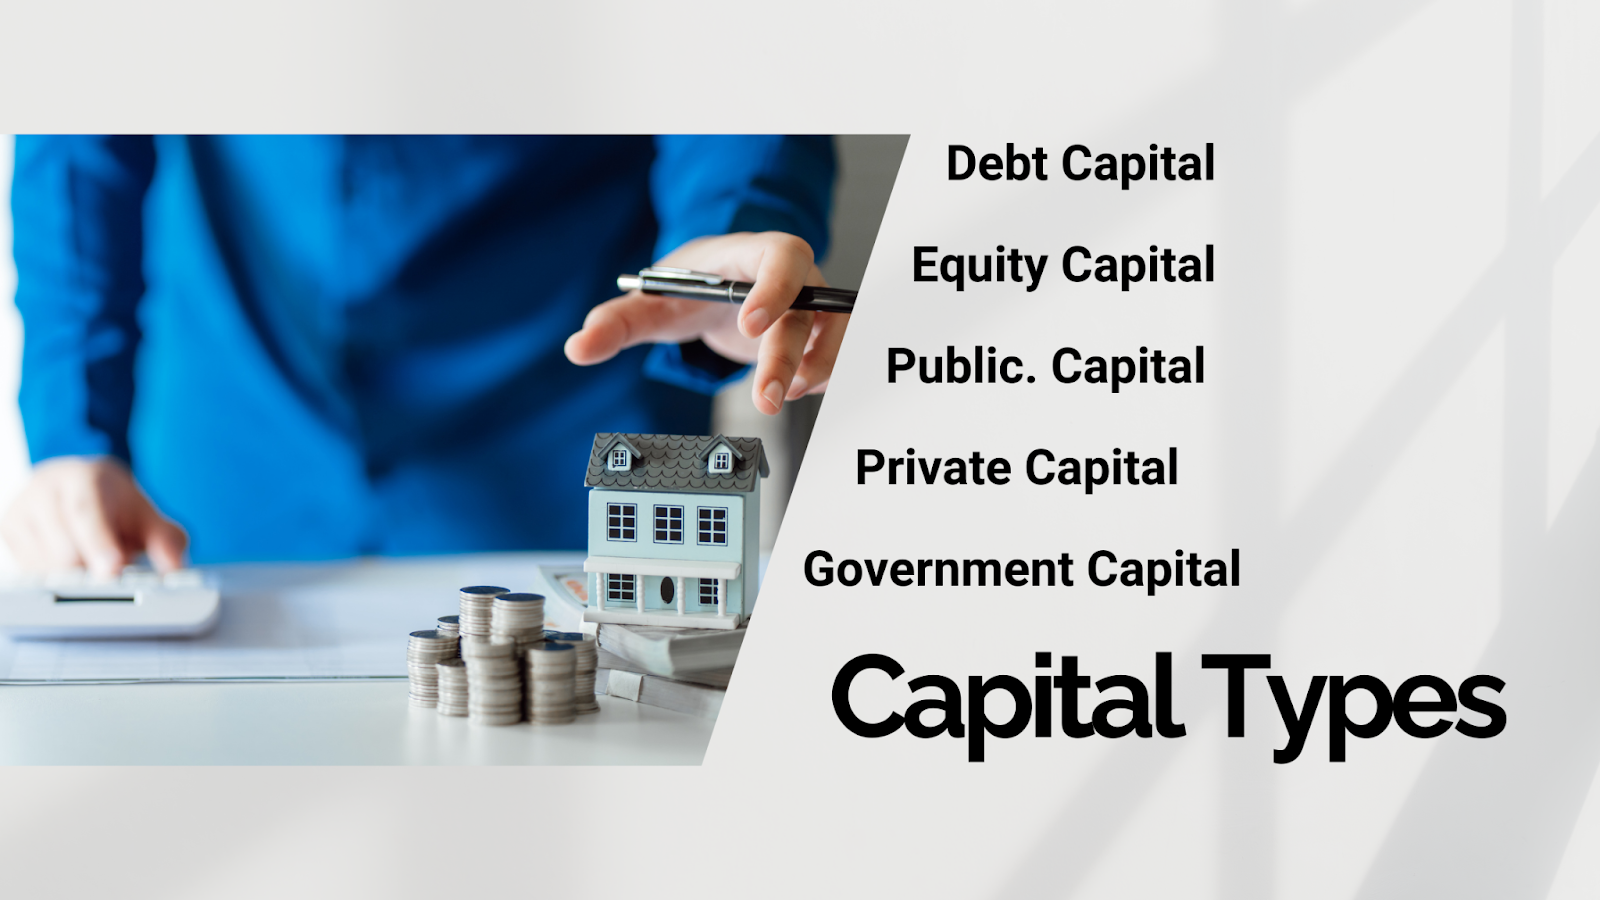
Various sources of real estate capital include:

  1. Equity capital comes from the property owner’s investment or ownership stake. It includes personal savings, investments, or contributions from partners or investors.
  2. Debt capital involves borrowing money to finance real estate investments. Common sources include mortgages, loans, and lines of credit from banks, financial institutions, or private lenders.
  3. Private capital can come from individual investors, family and friends, or private equity firms interested in real estate investments.
  4. Public capital can be raised by real estate companies through initial public offerings (IPOs) or by issuing real estate investment trusts (REITs) in the public market.
  5. Government capital comes from entities that may provide grants, subsidies, or incentives to support real estate development projects that align with public policy objectives.

Effective capital management is the cornerstone of real estate investing because it impacts the ability to acquire and maintain properties, generate rental income, and achieve desired returns on investment (ROI). 

Real estate capital strategies tend to vary depending on your objectives and the type of real estate you target. Let’s take a look at some strategies you can use. 

Recommended: The BRRRR Method: A Real Estate Portfolio-Building Blueprint 

Ways to Raise Real Estate Capital

Are you ready to dive into the world of real estate capital and explore various methods to kickstart your real estate journey? Let’s break down each strategy, providing a succinct definition, highlighting the benefits, outlining the risks, and guiding you on how to obtain each type of real estate capital.

1. Business Credit

How to raise money for real estate investments

Business credit involves using your company’s credit history and financial strength to secure loans or lines of credit for real estate investments using methods.

Benefits:

  • Separates personal and business finances.
  • Can provide significant capital for real estate endeavors.
  • May offer competitive interest rates and terms.

Risks:

  • Requires a strong business credit profile.
  • Defaulting on loans can harm your business credit.
  • Interest rates and terms may vary based on creditworthiness.

How to get business credit:

  1. Establish and build a solid business credit history.
  2. Maintain a good payment history with net 30 vendors and creditors.
  3. Apply for business credit cards and loans.

Recommended: 

  • Best Credit Cards for House Flippers
  • The Best Credit Cards for Landlords
  • How to Convert Credit Cards into Cash 

2. Home Equity

How to raise money for commercial real estate

Home equity represents the portion of your home’s value that you own outright, which can be leveraged as capital for real estate investments.

Benefits:

  • Access to a substantial source of capital.
  • Potential for competitive interest rates.
  • Can be used for various real estate projects.

Risks:

  • Tied to your home’s value, subject to market fluctuations.
  • Defaulting on home equity loans risks foreclosure.
  • Reduces your ownership stake in your primary residence.

How to Unlock Home Equity:

  1. Determine your home’s current value.
  2. Calculate your available equity.
  3. Apply for a home equity loan or line of credit.

Recommended: Should You Use a Real Estate Investor Line of Credit? 

3. Peer-to-Peer Loan

Raising private money for real estate investing

Peer-to-peer lending platforms connect real estate investors with individual or institutional lenders, allowing them to borrow funds for their projects.

Benefits:

  • Access to a wide network of potential lenders.
  • Competitive interest rates.
  • Streamlined application process.

Risks:

  • Varying lending criteria among platforms.
  • Potential higher interest rates for riskier borrowers.
  • Limited control over the selection of lenders.

How to access peer-to-peer loans:

  1. Research peer-to-peer lending platforms.
  2. Create a compelling loan request.
  3. Connect with potential lenders on the platform.

Recommended: Alternative Ways for Entrepreneurs to Raise Capital from Online Lenders

4. Private & Hard Money Lenders

How to raise capital to buy real estate with none of your own money

Private and hard money lenders are individuals or organizations that provide real estate loans, often with less stringent requirements than traditional banks.

Benefits:

  • Faster approval and funding compared to traditional lenders.
  • Flexible lending criteria, making them accessible to investors with lower credit scores.
  • May offer loans for various real estate projects.

Risks:

  • Higher interest rates and fees.
  • Shorter repayment terms.
  • Collateral may be required.

How to get private & hard money loans:

  1. Network with local real estate investment groups.
  2. Research and approach private lenders or hard money lending firms.
  3. Prepare a solid business plan and property details to present to lenders.

Recommended: A Review of Alpha Funding Partners – Are Their Solutions Right for You? 

5. Self-Directed Accounts

How to invest $100 000 dollars in real estate

Self-directed accounts, such as self-directed IRAs and 401(k)s, can enable you to invest your retirement savings into real estate assets. 

Benefits:

  • Potential for tax advantages within retirement accounts.
  • Diversification of retirement portfolio.
  • Control over real estate investment decisions.

Risks:

  • Strict IRS rules and regulations to follow.
  • Potential for penalties if not compliant with tax rules.
  • Limited access to funds until retirement age.

How to use self-directed accounts:

  1. Set up a self-directed IRA or 401(k) with a qualified custodian.
  2. Identify suitable real estate investment opportunities.
  3. Ensure compliance with IRS regulations and rules.

6. Wholesaling

How to make money in real estate with $5000

Wholesaling involves finding real estate deals at a discount and assigning the contract to another buyer for a fee, often requiring minimal upfront capital.

Benefits:

  • Low initial investment is required.
  • Quick turnaround for profits.
  • Opportunity to gain valuable experience in real estate.

Risks:

  • Highly competitive market.
  • Requires strong negotiation and deal-finding skills.
  • Success is not guaranteed for every deal.

How to start wholesaling:

  1. Build a network within the real estate industry and research auction options.
  2. Identify distressed properties or motivated sellers.
  3. Negotiate favorable purchase contracts and assign them to buyers.

7. Crowdfunding & Syndication

Raising money for real estate syndication

Crowdfunding platforms allow multiple investors to pool their capital into a real estate project, while syndication involves pooling funds under the leadership of an experienced sponsor.

Benefits:

  • Access to diverse real estate projects.
  • Lower investment thresholds.
  • Limited liability for individual investors.

Risks:

  • Project success depends on the sponsor’s expertise.
  • May require due diligence on crowdfunding platforms.
  • Returns may vary based on project performance.

How to Use Crowdfunding & Syndication:

  1. Research crowdfunding platforms or syndication opportunities.
  2. Evaluate project details, sponsor track record, and investment terms.
  3. Invest in projects that align with your goals.

8. FHA & USDA Mortgages

FHA & USDA Mortgages for real estate fundraising

FHA loans (3.5% down) and USDA loans (0% down) are government-backed mortgages for residential and agricultural (you don’t necessarily have to buy a farm as long as the location is rural) real estate investments. The kicker is that the down payments are low or non-existent and interest rates are lower than conventional loans. You might hear FHA mortgages referred to as “first-time homebuyer loans.” 

Benefits:

  • Low or no down payment requirements.
  • Accessible to first-time investors.
  • Competitive interest rates.

Risks:

  • Limited to owner-occupied properties (can be used for 1-4 unit properties if you occupy one unit).
  • Mortgage insurance is required.
  • Stricter property condition requirements.

How to qualify for FHA investment loans:

  1. Meet credit score and income requirements for local homebuying programs.
  2. Choose an eligible property type.
  3. Complete the FHA loan application process.

Recommended: Can You Pay a Mortgage with a Credit Card? The Answer is… Complicated 

Legal Obligations to Keep in Mind

How to legally raise private money

You need to comply with all local, state, and federal laws. Not all statutes are common knowledge. If this is where you’re headed, before we wrap up, I want to point out a couple of SEC regulations that might apply to you when you raise funds for real estate. 

Regulation D Rule 506(b) and Regulation D Rule 506(c) are two exemptions provided by the U.S. Securities and Exchange Commission (SEC) that allow private companies to raise capital from investors without having to register their securities offerings with the SEC. 

Both exemptions are commonly used in the world of real estate investing and apply to anyone who offers securities in exchange for investing in a venture – So, if you will offer investors some sort of return on investment, pay attention. 

Here’s a simplified breakdown of what you need to know about Regulation D Rule 506(b) and Regulation D Rule 506(c), so that you can choose the right one for your situation.

Regulation D Rule 506(b):

  • You can raise money from both wealthy and regular investors (up to 35 regular ones).
  • You can’t openly advertise your investment opportunity to the public. You can only share it with people you already know or have a relationship with.
  • You don’t have to do much to check if an investor is wealthy. They can just tell you, and you trust them.

Regulation D Rule 506(c):

  • You can only raise money from wealthy investors (no regular ones).
  • You can openly advertise your investment opportunity to anyone, even on the internet or social media.
  • You must carefully check if investors are truly wealthy by asking for proof like tax returns or statements from their bank or broker.

Under both rules, you need to fill out some paperwork (Form D) and send it to the government.

In simple terms, Rule 506(b) lets you raise money from a mix of rich and regular people but limits how you can advertise. Rule 506(c) is for raising money only from wealthy folks, but you can tell everyone about it. 

Choose the one that fits your needs and follow the rules to stay out of trouble with the government. Always consider seeking legal advice or consulting experts when navigating these regulations in your real estate investment journey.

(If you use your own business credit to invest in real estate, you don’t have to worry about SEC regulations because you’ll be the one to receive all of the profits.)

Recommended: Low-Risk NAICS Codes +Best SIC Codes for Business Credit in 2023 

Frequently Asked Questions

How do you structure raising money for real estate?

Consider partnerships, LLCs, REITs, syndications, private loans, and crowdfunding to structure real estate investments.

Sole Proprietorship VS LLC: How to Choose Your Entity Wisely 

How to raise money to buy real estate with none of your money?

Explore strategies like wholesaling, seller financing, partnerships, hard money loans, and lease options to minimize upfront capital.

What is the fastest way to build wealth in real estate?

Quick wealth in real estate can come from the BRRRR method, flipping, leveraging mortgages, commercial real estate, real estate development, and short-term rentals.

What part of real estate is most profitable?

Commercial real estate, multifamily properties, real estate development, short-term rentals, and real estate syndication tend to offer high profitability.

How does real estate make the most millionaires?

Real estate creates millionaires through property appreciation, rental income, leverage, tax benefits, and portfolio diversification.

Conclusion

Raising money for real estate investment may seem daunting, but armed with the knowledge and strategies from this guide, you’re well on your way to achieving your financial goals. 

These strategies offer various avenues to raise real estate capital, each catering to different investment preferences and financial situations. Choose the approach that aligns with your goals, and always conduct thorough research and due diligence before making any investments.

Remember, the path to real estate success begins with that first step. So, embrace the possibilities, start raising capital, and turn your real estate dreams into reality. Happy investing!

→ Want to learn how to obtain up to $100K in business credit in as few as 30 days? Join Business Credit Workshop today.

6 Best Fintech Credit Cards to Apply for (Consumer & Business)

By Joe

best fintech credit card

Are you an individual considering a slick, new way to use credit? Or, a business owner looking to supercharge your finances with the perfect fintech credit card? Look no further! 

Here, we’ll dive into the exciting world of fintech credit cards, introducing you to top contenders like Divvy, CredAI (the illustrious Unicorn Card), Bluevine, Stripe, Ramp, and Brex – essentially free credit cards for everyone. 

Fintech is making credit cards weirder, but also a lot more fun…Whether you’re a student or seasoned entrepreneur, you can navigate the fintech card landscape, making sure you’re armed with the right knowledge to make the best decision for your situation. 

Here’s what’s in store: 

  • What is a Fintech Credit Card?
  • Explore the 6 Best Fintech Credit Cards
    • 1. Brex – Your Stealthy Fintech Ally
    • 2. Divvy – The Power Credit Card
    • 3. Bluevine – Fintech Business Checking & Credit
    • 4. Stripe Corporate Card – Cashback and More
    • 5. Ramp – Redefining Fintech Credit Cards
    • 6. Meet the Unicorn Card – CredAI
  • Frequently Asked Questions
  • Conclusion

Now, let’s get crackin! 

What is a Fintech Credit Card?

In simple terms, a fintech credit card combines the innovation of financial technology (fintech) with the convenience and power of credit cards. Fintech credit cards often come with unique features, competitive rates, and advanced tools that empower business owners to manage their finances efficiently.

Explore the 6 Best Fintech Credit Cards

Let’s take a closer look at some of the leading fintech credit cards that are revolutionizing the way individuals and business owners manage their finances. 

1. Brex – Your Stealthy Fintech Ally

fintech credit card processing

For: Businesses seeking a free corporate card

The Brex Corporate Card is an enticing choice for businesses seeking a no-personal-guarantee credit card with rewards. The card, issued through Brex’s financial operating system, caters to tech, life sciences, and eCommerce companies. I

t’s characterized by its absence of annual fees, interest charges, and personal credit checks. Instead, creditworthiness is determined based on the company’s likelihood to repay funds. Brex offers various account options, including Cash, Card, and Cash & Card, tailored to different financial needs.

The card boasts rewards such as up to 30K bonus points, points per dollar spent, and partner perks, including discounts with industry giants like AWS, Slack, and Google Ads. With a focus on expense management, the card offers real-time tracking tools, virtual cards, and expense automation. Qualification requires a US-based business with an EIN and a business bank account.

Learn more: Brex Card Review: Is This Corporate Card Offer Too Good to be True? 

2. Divvy – The Power Credit Card

fintech credit builder

For: Business owners

Divvy is not just a business credit card; it’s a comprehensive financial solution tailored for businesses of all sizes. With Divvy’s innovative features, you gain access to budgeting tools, virtual cards, and enticing rewards. 

This high-tech card isn’t just a piece of plastic; it’s a gateway to efficient expense management, AP automation, and seamless spending control. Divvy’s user-friendly platform empowers businesses to allocate budgets, set spending limits, and automate payment approvals. 

The virtual card feature adds an extra layer of security for online and high-risk transactions. Additionally, Divvy offers a tiered rewards system, giving you the opportunity to earn points for your spending habits. These points can be redeemed for travel, gift cards, statement credits, or cash back. 

While Divvy’s customer service receives mixed reviews, the platform’s help center and communication tools aim to provide comprehensive assistance. If you’re a business owner seeking advanced financial tools that streamline your operations and enhance your financial management, the Divvy credit card might just be the power boost your business needs.

Learn more: In-Depth Divvy Credit Card Review: Read This Before You Apply 

3. Bluevine – Fintech Business Checking & Credit 

fintech credit union

For: Small business owners

Bluevine presents a game-changing solution for small business owners with its high-yield free business checking account. With the ability to earn 50X the national average interest on balances up to $100K, this offering stands out in the financial landscape. 

The account comes with no monthly fees or minimum deposits, making it particularly appealing for digitally-focused businesses, freelancers, and service providers. While Bluevine’s single-account holder policy and minimum requirements to collect interest might not suit all businesses, the benefits are noteworthy. 

The platform’s integration of sub-accounts, dedicated account numbers, and unlimited fee-free transactions adds to its appeal. Bluevine’s strategic partnership with MoneyPass ATM network provides widespread access to surcharge-free ATMs. However, cash deposits made at ATMs incur a fee. The option to grant access to your account without sharing login credentials is a unique feature, enhancing collaboration with bookkeepers and accountants.

Moreover, Bluevine’s line of revolving credit up to $250K, coupled with competitive rates, can offer additional financial support for qualifying businesses. Overall, Bluevine’s innovative offerings make it a compelling choice for businesses that prioritize digital transactions and aim to make the most of their account balances.

Learn more: Bluevine Review: Free, High Yield Small Business Checking! Are They Serious? 

4. Stripe Corporate Card – Cashback and More

Stripe credit card

For: Business owners using Stripe Payments

The Stripe Corporate Card offers a compelling credit card option for existing Stripe Payments users. This card comes with unique advantages, including no fees, 0% interest, and an appealing 2% cashback on spending in top two categories. 

Notably, with a spending of $5,000 on the Stripe Corporate Card, users gain access to $50,000 in free transactions on the platform. Furthermore, the card allows users to customize their logo, create branded cards, and even originate credit cards for their customers. 

The card is available as both virtual and physical options, with the latter delivered within days. Stripe’s innovative approach is fueled by its primary revenue source—transaction fees for processing payments, allowing them to offer these enticing features. However, the card is exclusively available to existing Stripe Payments users, requiring those interested to request an invitation. 

In comparison to similar offerings like Brex, the Stripe Corporate Card stands out with its cashback rewards. Stripe’s broader suite of financial services and its reputation as a payment processor further contribute to the appeal of the Corporate Card. This review aims to provide a comprehensive overview for business owners seeking a flexible and rewarding credit card solution.

Learn more: Have You Heard About the Free Stripe Corporate Card Cashback Benefits? 

5. Ramp – Redefining Fintech Credit Cards

fintech debit card

For: Businesses seeking a frde corporate card

The Ramp Corporate Card, provided by Ramp Financial, is a corporate credit card designed to help businesses save money. With an emphasis on cost reduction and rewards, the card offers a range of features that can benefit businesses of various sizes. This review delves into the offerings and highlights of the Ramp Corporate Card.

The card allows businesses to issue unlimited staff cards, each with customizable spending limits. Additionally, Ramp’s algorithm identifies potential savings opportunities by analyzing spending patterns.

The Ramp Corporate Card comes with no foreign transaction fees, late fees, interest fees, or annual fees. It offers a flat 1.5% cashback on all spending, allowing businesses to earn rewards across various expense categories – Ramp has partnered with various service providers, offering potential savings of up to $175K for cardholders who leverage these partnerships. These rewards encompass a range of services, from advertising credits to discounts on software subscriptions.

While specific requirements are not fully transparent, Ramp’s underwriting process se