• Home
  • Free Funding Guide
  • What We Offer
    • Products
    • Services
    • Free Guide
  • About Us
  • Contact
  • Sign Up

  • Ask Joe Any Question!
  • Business Credit Cards
  • Business Line of Credit
  • Topics

Torro Business Funding Review: Is This Zero Hassle Offer Legit?

By Joe

Torro Business Funding

If you’ve come across Torro Business Funding, you may have been referred by a franchise or an Instagram influencer. And, they may be offering you the funds you need to start or grow your business…But, for some reason, you’re still wondering if they’re legit. 

Here, you can find out what Torro Business funding is (how it’s different from a conventional lender), learn about the company, and explore what you can expect from their offer. You’ll even find answers to some common questions about this type of lending. 

This is what’s in store: 

  • What is Torro Business Funding?
    • Torro Funding Requirements
    • Company Overview
  • What Does Torro Business Funding Do?
    • 1. Quick, Online Application
    • 2. Funding Within a Week
    • 3. Syndicated Investor Financing
  • Frequently Asked Questions
  • Conclusion: Is Torro Funding Legit?

Now, let’s dive in! 

What is Torro Business Funding? 
torro business funding for startups

Torro is known as a source of “startup capital” and “business capital” – they offer hassle-free financing solutions geared toward small businesses. Torro is an alternative financial service provider that specializes in addressing cash flow and working capital needs. 

Unlike traditional banks and lenders, Torro offers a streamlined approach to access funds, and they emphasize the convenience and efficiency this offers business owners.

Whether you’re a post-revenue business seeking expansion or a pre-revenue startup in need of initial capital, Torro has tailored funding options to help you get cash to expand your business. 

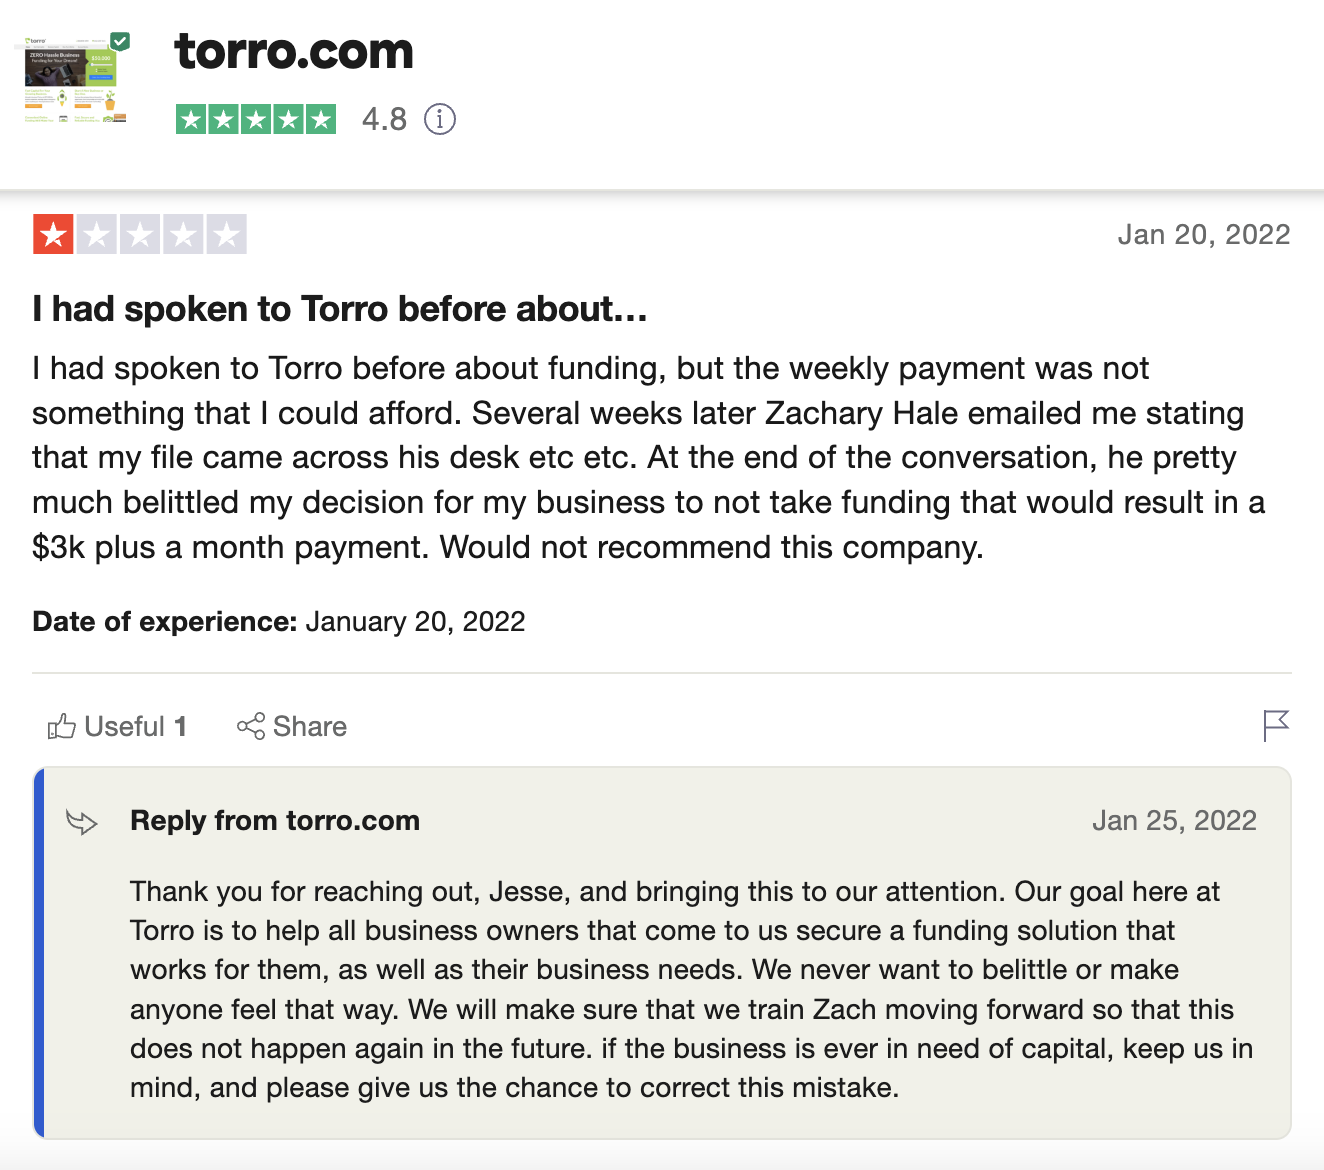
Interestingly, most of the small number of poor Trustpilot reviews seem to come from business owners who decided not to work with Torro after the initial consultation. Otherwise, they maintain a high rating on the platform (this is always impressive for a financial offer, as long as there reviews are real). 
torro business funding reviews

For pre-revenue businesses — which includes startups, franchises, or those looking to purchase a business — Torro offers a three-step process to obtain unsecured working capital (startup capital) between $5K to $125K to kickstart your business. 

For post-revenue businesses, Torro claims to simplify the process with a quick online application (business capital) to help you grow your operations with $5K to $725K. 

Within their wide funding range, they seem to have something for everyone. 

You might also like: How to Interpret Lendio Reviews: Is This Funding Company Legit? 

Torro Funding Requirements

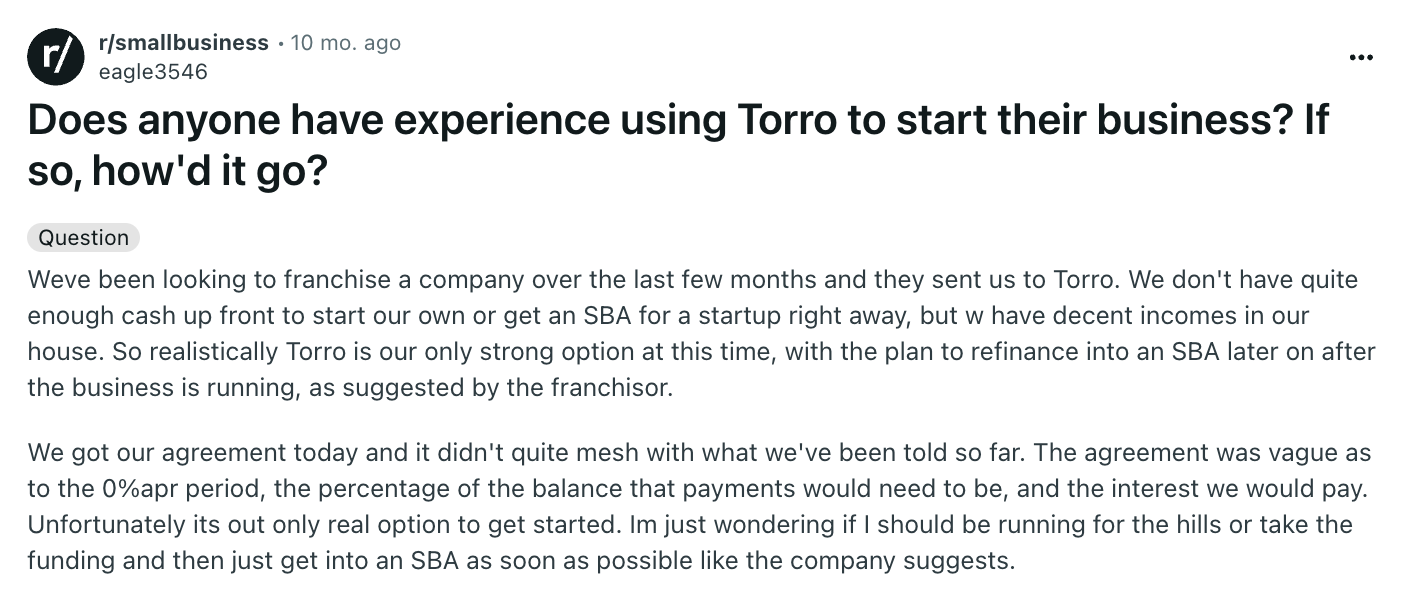
Torro’s funding is considered working capital. With this type of loan, repayment can happen as a percentage of your daily sales, and is most often “factored.” Factoring involves selling accounts receivable to a third party (“lender”) at a discount for immediate cash, while interest loans entail borrowing a sum of money that must be repaid with interest over time.

So, working capital loans are kinda like a payday loan for business. Because of this, their requirements are a bit more lax than a traditional business loan. 
Torro business funding Reddit

When you come across an offer that seems like it could be too good to be true, it’s only natural that your hair would stand up on end. I never recommend this type of loan, unless a business owner absolutely has no other option. The reason is that they tend to be the quickest and easiest funding you can get, but they are more expensive. 

Bear in mind, Torro is not the only alternative lender with relaxed requirements, and this isn’t a “scam,” it’s just a more expensive loan — i.e. not the most financially sound option you can take advantage of.  

Recommended: Could a Stripe Capital Loan Get Your Business Through a Rough Patch? 

Company Overview
Torro small business funding

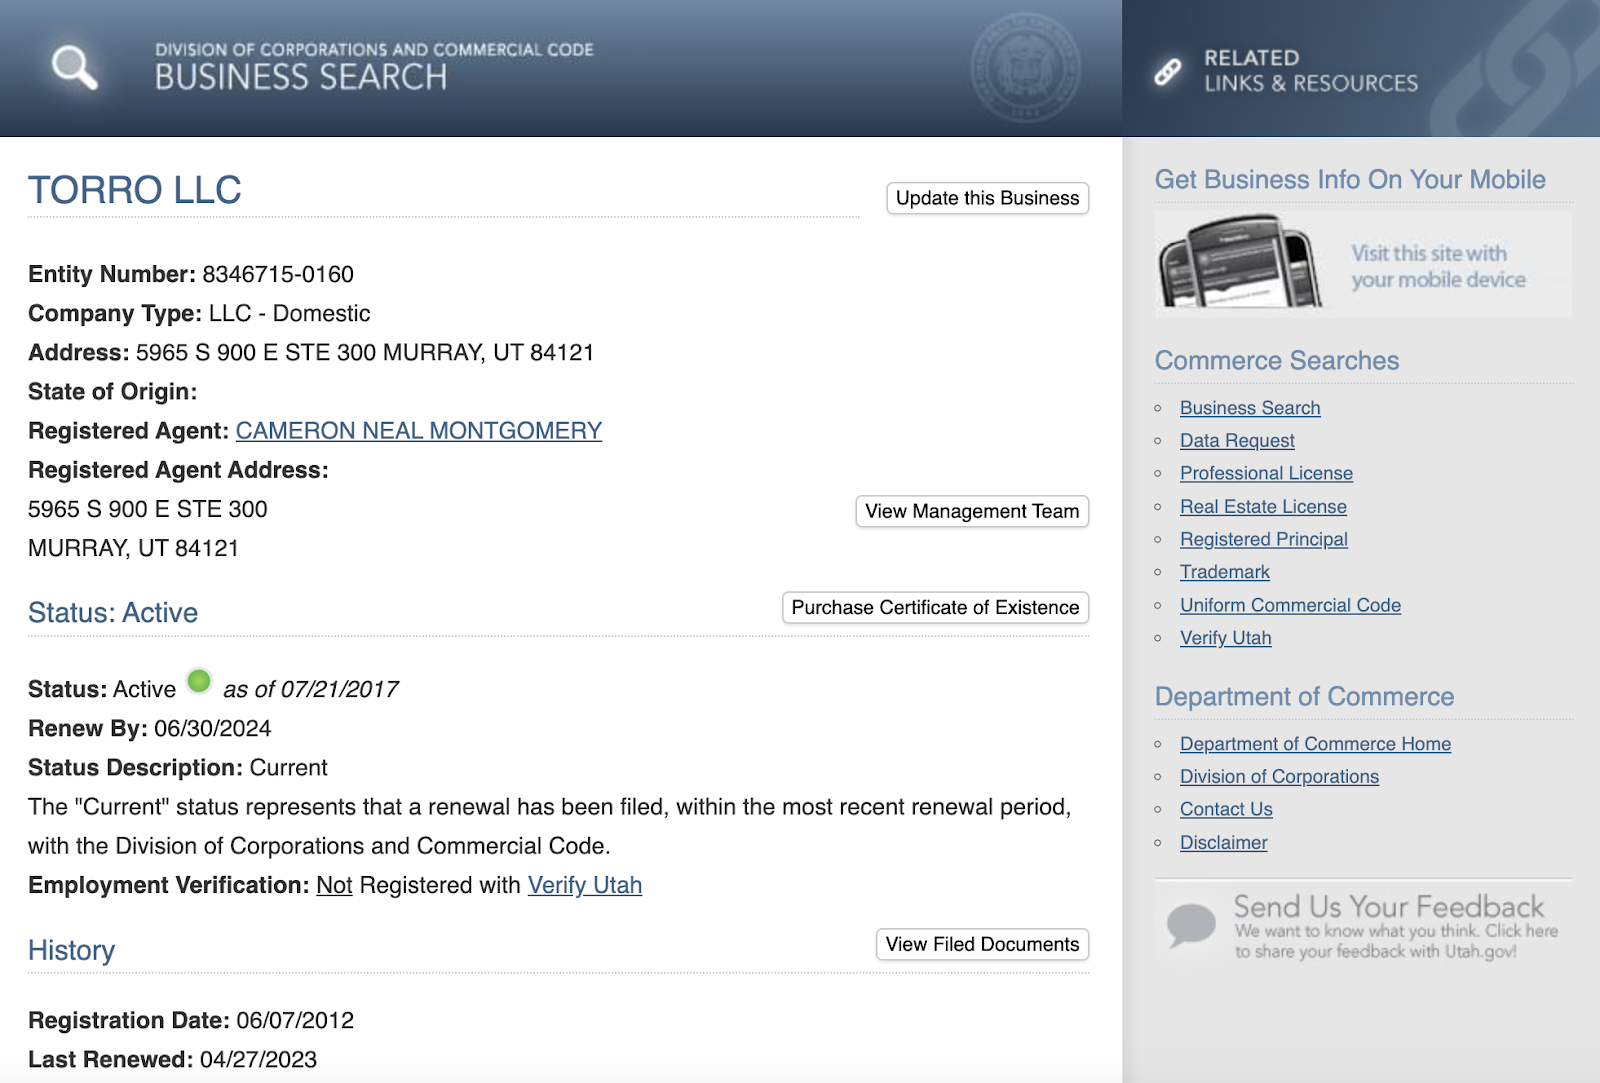
Established in 2015 and based in Salt Lake City, Utah, Torro LLC is an online funding platform, founded, owned, and managed by Cameron Montgomery. The company is in good standing with the Utah Division of Corporations and Commercial Code. 

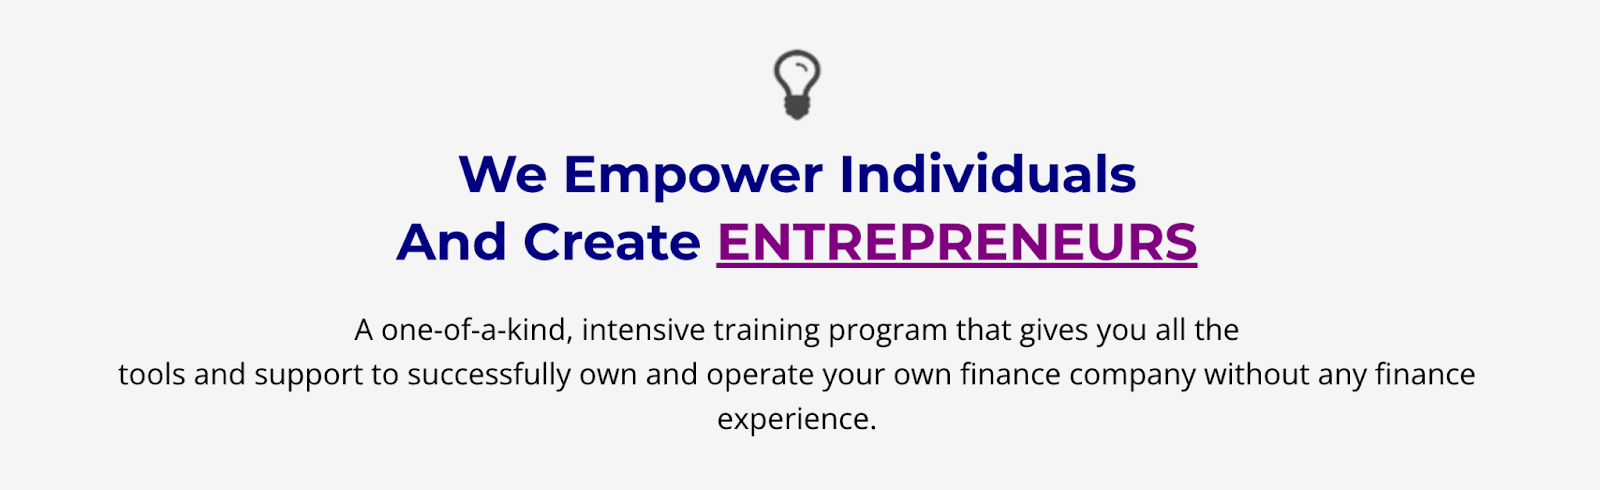
As the current CEO, Montgomery officially registered the company in 2012, and also does business as “The Broker Blueprint” – a training program that empowers individuals to become business loan brokers, connect borrowers with lenders, and secure financing for small businesses.
Is a loan shark a lender?

Prior to launching Torro, Montgomery didn’t share any work or education experience on LinkedIn. 

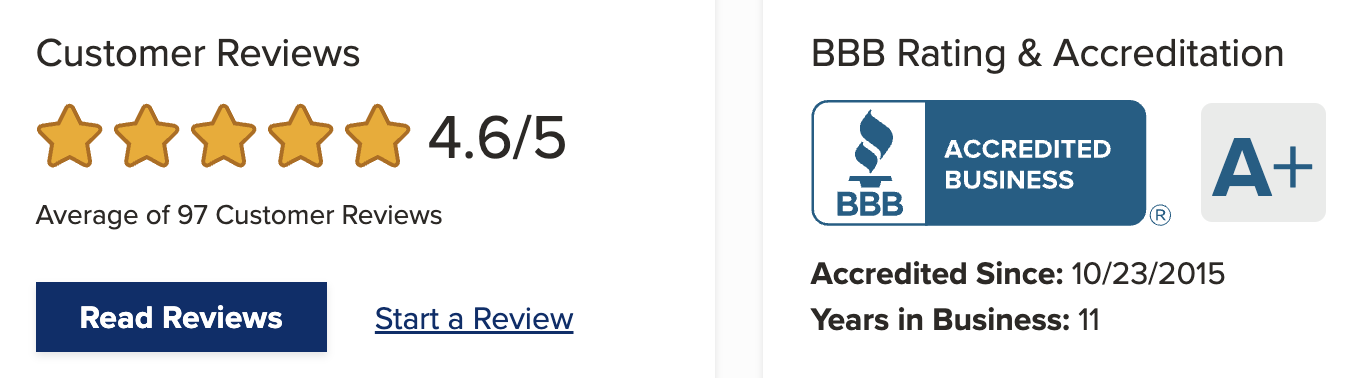
Torro is accredited with and maintains an A+, 4.6-star rating with the Better Business Bureau (BBB). I almost never see any positive reviews on the BBB website, let alone almost 90 of them. I’ll leave you to your own discretion on this one. 
Torro business funding bbb

What I can say is that there have only been 7 complaints with the BBB in the past 12 months – It’s not uncommon to see 50+ for a financial offer. 

I found one thing particularly odd – the company seems to have two websites that are exactly the same – one is at torro.com and the other at gotorro.com. It doesn’t seem like one of them is fake (Trustpilot cites torro.com and Crunchbase cites gotorro.com), so I have no idea why this would be. 

In all, Torro Funding has been in operation for nearly a decade, and they’re in good standing in the areas where it’s necessary. However, this isn’t the most transparent company I’ve ever seen — I would like to have seen more information about loan rates and terms on the company website and the founder’s previous experience on LinkedIn. 

 You might also like: Superior Tradelines Review: Is it a Scam or Legit Way to Build Credit? 

What Does Torro Business Funding Do? 

In a nutshell, Torro small business funding is a means to get the capital you need quickly. Let’s take a look at their application process, speed of funding, and what you can expect from this offer. 

Compared to other, comparable funding products, this one is pretty simple. 

1. Quick, Online Application 
Startup business loans with no revenue

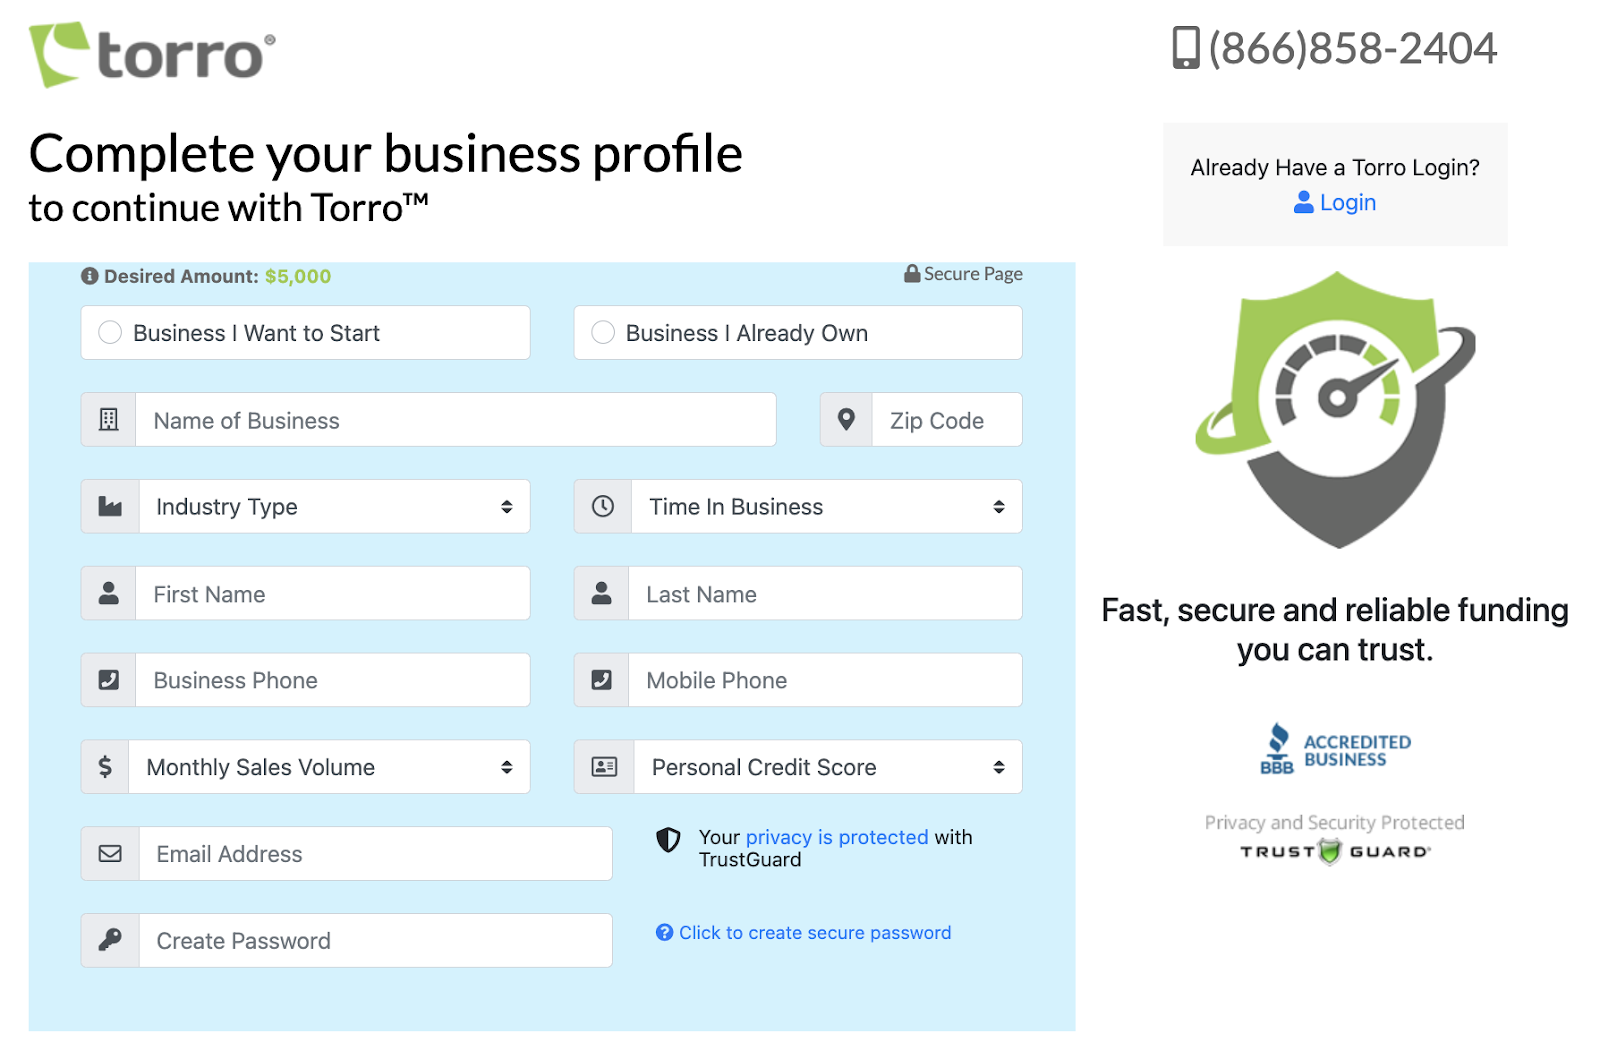
Torro’s online application asks only for the basic info about your business, like name, years in business, and your personal credit score. Of course, they want your income and contact info, but the pre-authorization doesn’t require that you enter your social security number. 

You can supposedly create an online account during the application process, but it has to be manually approved. This probably helps weed-out the people who are just here to spy, and aren’t actually interested in business capital. 

After you apply, you should get a call back within one business day. 

Recommended: Here’s How to [Actually] Get Business Credit With Just an EIN +More Options 

2. Funding Within a Week
Startup business loans with no revenue bad credit

With their proprietary QuickWrite® system, underwriting typically occurs within the same day, and approved businesses can access funding within 24 hours. To avoid unrealistic expectations, the video you’re taken to after you submit your application makes it clear that funding happens within a week. 

This is pretty quick, as far as business loans are concerned, though there are competitors who offer funds with the same urgency. 

Recommended: This is How to Build Business Credit Fast [Step-by-Step Guide] 

3. Syndicated Investor Financing 
Is equity funding good?

Torro has a network of investors who collectively provide the capital required by your business. Once the approval process is complete, these investors swiftly deposit funds into your bank account, often on the same day as approval, allowing you to utilize the funds immediately.

The loans are funded by a syndicated network of investors and financial resources associated with Torro – though, Torro doesn’t expressly state who these investors are. This is likely somehow related to Montgomery’s other program, The Broker Blueprint. 

You might also like: This is How to Leverage Business Credit to Transform Your Life 

Frequently Asked Questions

How can you get a business line of credit with no revenue? 

To obtain a business line of credit with no revenue, you typically need to explore alternative financing options such as secured credit lines, personal guarantees, or presenting a strong business plan and credit history.

How do you know if a loan company is scamming you? 

You can identify potential loan scams by researching the company thoroughly. Check for legitimate accreditation, verify contact information, read reviews, avoid upfront fees, and be wary of promises that seem too good to be true.

Are money loan apps safe? 

Money loan apps can be safe if they are reputable, regulated, and adhere to strict security measures for handling personal and financial information. It’s crucial to review the app’s privacy policy, user reviews, and security features before using it.

Are cash advance loans safe? 

Cash advance loans can be safe if obtained from reputable lenders and used responsibly. However, they often come with high interest rates and fees, you need to fully understand the terms and conditions before agreeing to a cash advance loan.

Are online loan requests legit? 

Online loan requests can be legitimate if they are from reputable lenders or financial institutions. It’s essential to verify the credibility of the website, review customer feedback, read the terms and conditions carefully, and ensure the website is secure before submitting any personal or financial information.

Conclusion: Is Torro Funding Legit? 

Again, Torro Funding is meeting the necessary requirements for a financial offer:

  • Registered, active, and in good standing with the state of Utah
  • Good ratings on Trustpilot and BBB
  • Transparent ownership documentation

Plus, I like that they’re a privately-owned business, which has some appeal over doing business with a big bank (there are pros and cons to each. 

Now, I would never step into a factored working capital offer unless it’s absolutely necessary — there are too many options that are much easier on your business budget. And, I wish there was more transparency into the loan rates and terms. 

Whether or not this is an offer you want to take advantage of, I’ll let you decide. 

Want to learn how to obtain up to $100K in business credit in as few as 30 days? Join Business Credit Workshop today!

Is BHG Financial Legit? Personal & Business Loans, VC, & More

By Joe

BHG Financial

While not a new company, BHG Financial started becoming wildly more popular than ever in 2022. Since then, they’ve been garnering attention with rumors that owners can get pre-revenue ($0 income) business loans with no personal guarantee. While applicant’s can expect a ton of phone calls from the moment they share their contact info with the company, this is true for most modern lenders. 

Most of all, people want to know if BHG Financial is legit. Keep reading to get the answer. 

Here’s what’s in store: 

  • What is BHG Financial?
    • Is BHG Financial Legit?
  • What Does BHG Financial Do?
    • 1. BHG Money Loans
    • 2. Fund-Ex Solutions Group
    • 3. BHG Bank Network
    • 4. NaluPay
    • 5. Risk Management Solutions Group
    • 6. BHG Connect
    • 7. BHG VC
  • Frequently Asked Questions
  • Conclusion: Is BHG a Legitimate Company?

Now, let’s get down to it! 

What is BHG Financial? 

BHG Financial is a financial company that offers various solutions for small and medium-sized businesses (SMBs) as well as consumers across the U.S.

Their approach involves using data analytics and technology to market and underwrite small business and unsecured consumer loans. They claim to be a disruptor in the industry, with a focus on providing innovative financial solutions. BHG operates with a proprietary online auction platform to sell loans to a large network of bank members.

Is BHG Financial Legit? 

According to the company website, BHG Financial started back in 2001 with a modest $25K and a small team. Fast forward to today, they’ve grown significantly. The numbers they highlight include over $15 billion in loan solutions, processing around 31,000 applicants each month, with 1,450 bank members and a team of 1,500 employees.

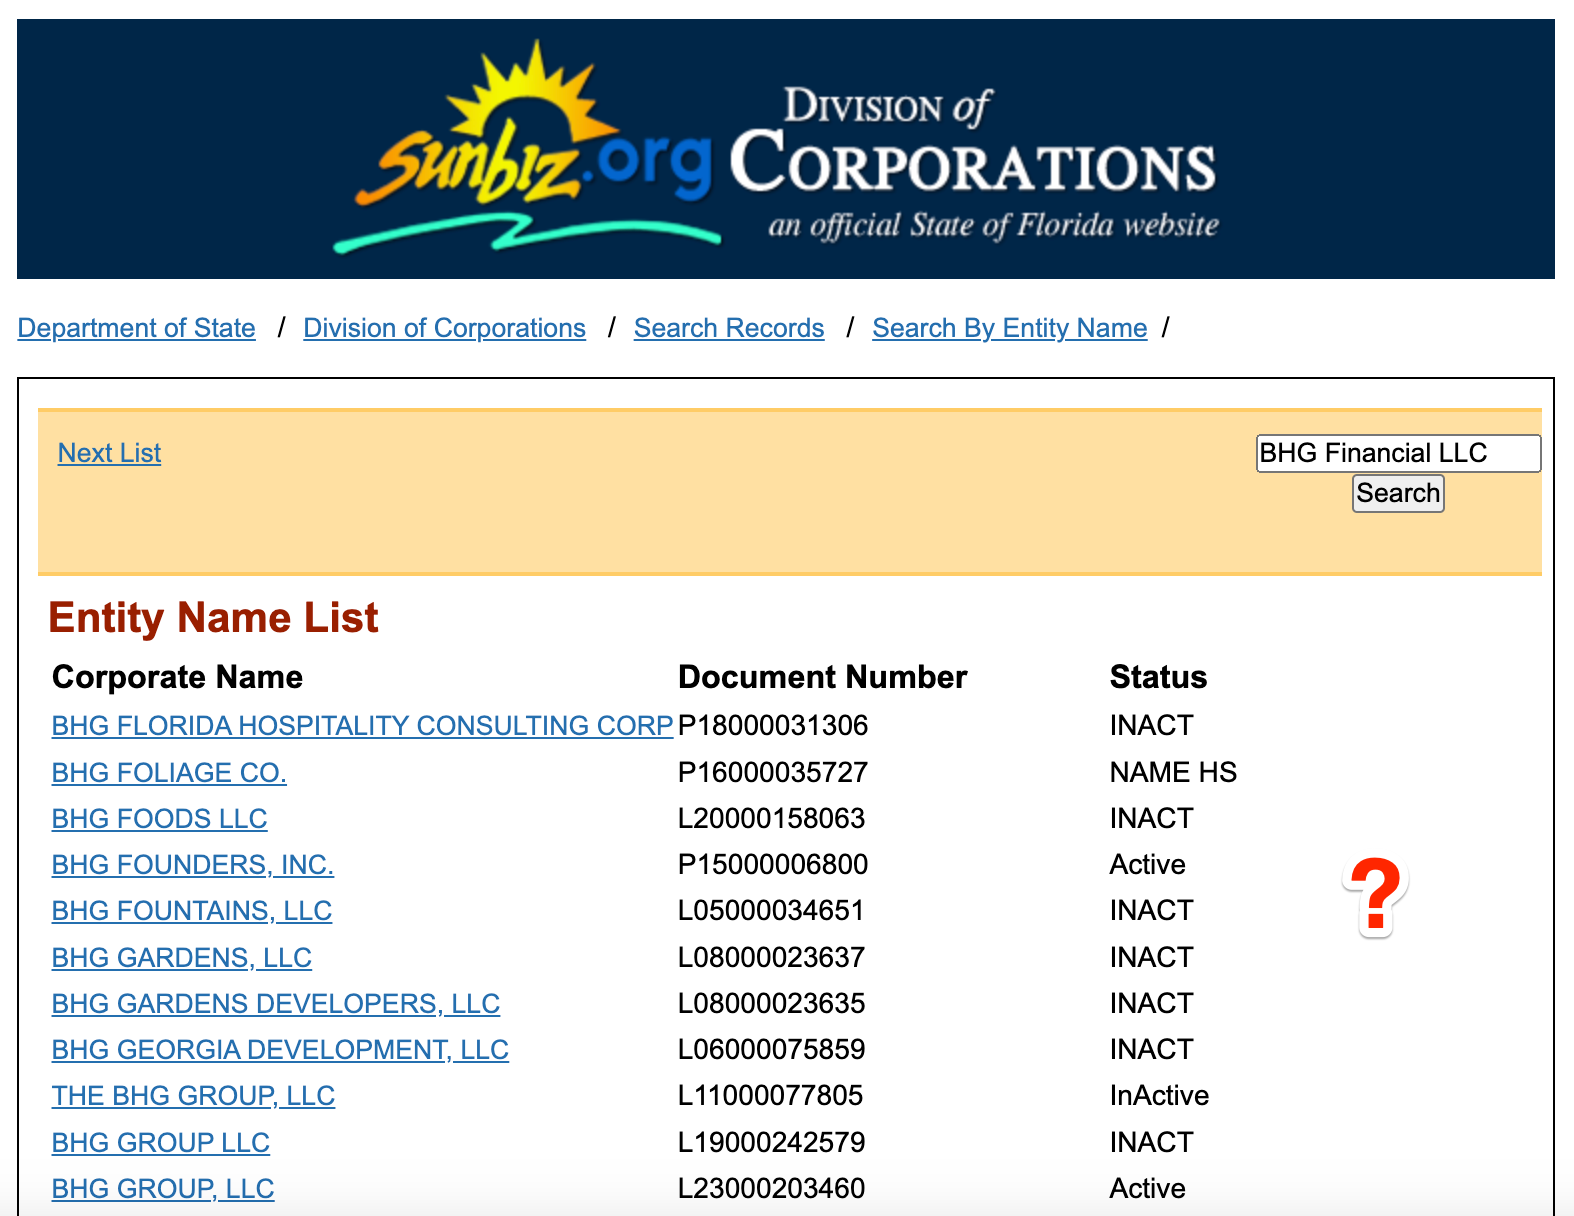
According to Crunchbase, BHG Financial (aka “BHG Financial LLC”) is a Ft. Lauderdale, Florida-based, for-profit company. 🚩However, according to Sunbiz.org (Florida’s Division of Corporations website), no such-named business is registered in the state. 

Who owns BHG Financial?

However, Banker’s Healthcare Group LLC. (per bngfinancial.com Terms & Conditions) is active and registered to Albert (Al) Crawford in Davie, Florida. Crawford is the current Co-Founder, Chairman, and CEO at BHG Financial where he’s been since the company’s humble beginnings. 

Bankers Healthcare Group is known to directly lend funds and offer financing, credit cards, and patient financing tailored for healthcare professionals for the past 20+ years.  

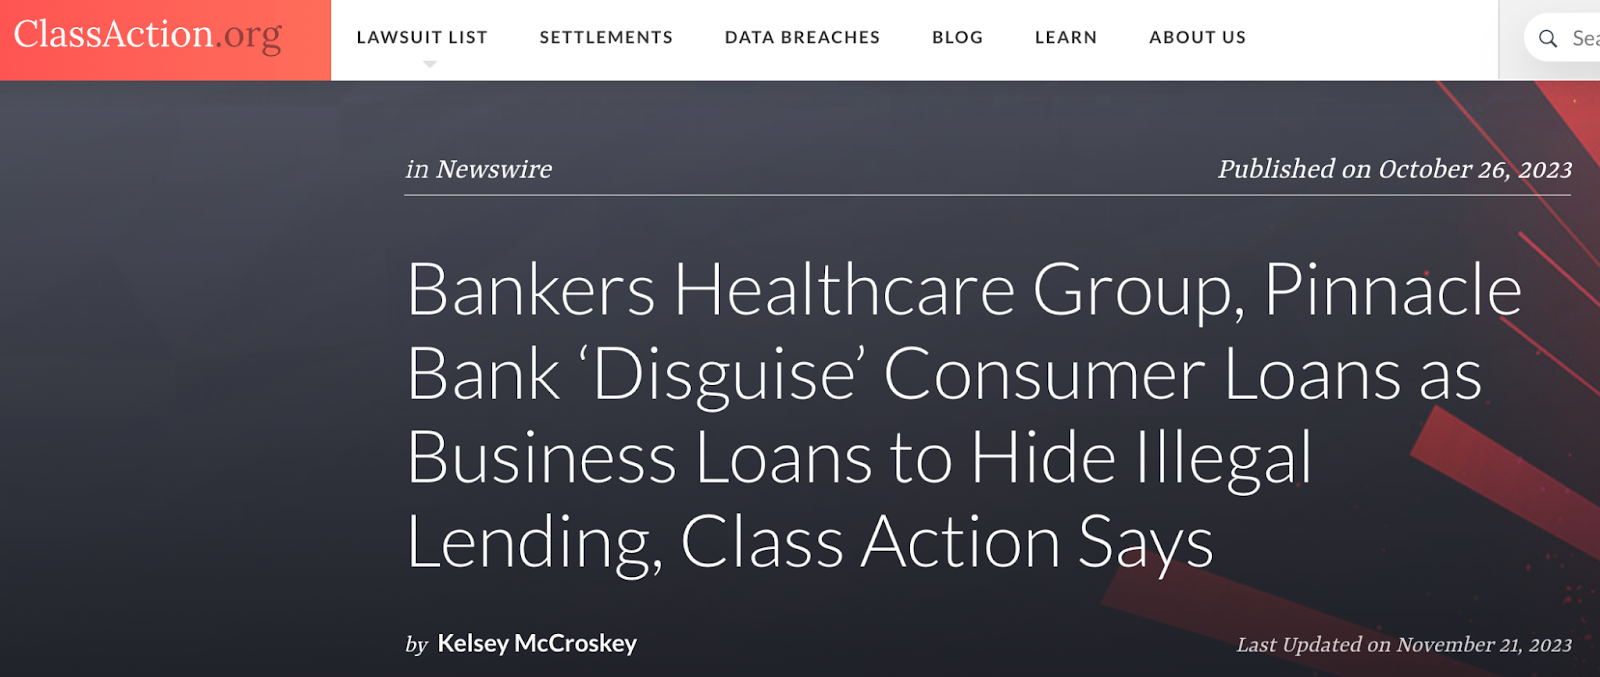
🚩 In digging deeper, I found that, as of November 2023, Bankers Healthcare Group is facing a proposed class action lawsuit that alleges they disguise consumer loans as business loans to cover up unlawful lending practices. If you follow along, you might be able to find out if this allegation has legs – it will be interesting to find out.

Who is BHG Financial?

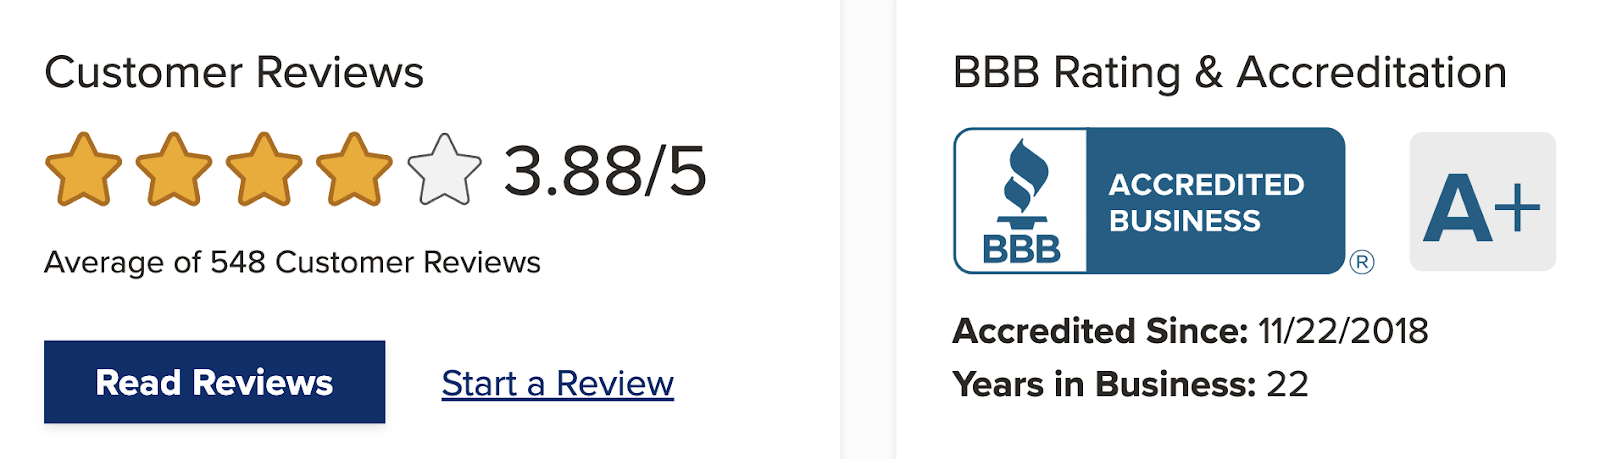
Despite 522 complaints in the past 3 years (175 closed in the past 12 months), BHG Financial maintains an A+ rating with the Better Business Bureau (BBB), where they’ve been accredited since 2018. 

BHG Financial Reviews BBB

Now, if the class action previously mentioned happens to stick, this rating might go down. 

As reported by at least Redditor, as a lender, BHG reps might try high-pressure tactics to get someone to take a loan offer, but they’re legit and their financial products are negotiable. 

BHG Financial Reddit

In all, the company has been around for over 20 years with its original leadership (they haven’t sold out), and they have no founded legal issues that indicate they’re going to take your money and run.  

You might also like: Torro Business Funding Review: Is This “Zero Hassle” Offer Legit?

What Does BHG Financial Do? 

BHG Financial is a parent company with several brands under their umbrella, including BHG Money and several other financial offerings. Let’s take a quick look at each of BHG’s brands and how they serve consumers and businesses. As they put it themselves, they “bring a diverse set of innovation solutions to the market. 

And, two of their brands offer financing for small business, so I’ll touch on them first. 

1. BHG Money Loans

BHG Money

BHG Money positions itself as a versatile financial solution, offering swift and hassle-free services for individuals and professionals. Whether you’re in need of business, personal, startup, or SBA 7(a) loans, or exploring credit card options, BHG Money caters to a diverse range of needs. 

BHG Money’s business loans include: 

  • Up to $500K with flexible terms up to 12 years
  • Debt consolidation loans
  • Existing business investment loans
  • New business opportunity loans
  • Medical practice loans (naturally)
  • Working capital loans

What’s cool is that these loans can be approved in as little as 24 hours, and they don’t require personal collateral, a business loan, or pro forma to qualify.   

This offering is particularly well-suited for individuals and professionals seeking efficient and convenient financing with a focus on prompt access to funds for various purposes.

Recommended: BHG Money Review: Did You Know They Offer Business Loans Too?

2. Fund-Ex Solutions Group Loans

BHG Financial Loan Requirements

As one of the 14 non-bank SBA 7(a) lenders, Fund-Ex Solutions Group provides rapid and flexible financing for small businesses. 

Fund-Ex Solutions Group caters to businesses with several loan options: 

  • Up to $5M with repayment terms up to 25 years
  • Commercial debt consolidation
  • Real estate
  • Start up or acquisition 
  • Equipment purchase
  • Renovation or expansion
  • New location 

Like BHG Money, Fund-Ex Solutions doesn’t require personal collateral, and these loans won’t impact your personal credit. You can use their loans for a variety of business purposes and there are no balloon payments at the end of the loan. 

This offering could be advantageous for small business owners aiming to access efficient and tailored financing solutions, supporting their growth and development endeavors.

3. BHG Bank Network

Who is BHG Financial

Tailored for financial institutions, BHG Bank Network provides a cutting-edge loan delivery platform. This platform not only allows banks to view but also to purchase top-performing assets. 

Ideal for banks looking to bolster their loan portfolio, BHG Bank Network leverages state-of-the-art technology to streamline the acquisition process of high-performing assets. This can enhance overall operational efficiency.

4. NaluPay

BHG Financial login

NaluPay distinguishes itself as a merchant-centric point-of-sale financing platform. Designed specifically for healthcare, home improvement, and retail businesses, NaluPay strives to make customer purchases more affordable. 

This offering is beneficial for businesses (in these sectors) that want to offer flexible financing solutions, to foster increased sales, and enhance customer satisfaction through accessible payment options.

5. Risk Management Solutions Group

BHG Financial Careers

The Risk Management Solutions Group concentrates on delivering regulatory, compliance, and risk management services. Targeted at financial institutions, this offering is designed to assist these entities in staying ahead of industry changes. 

It might be great for institutions navigating the complex landscape of regulations and effectively mitigating risks to ensure compliance and operational stability.

6. BHG Connect

BHG Financial Review

BHG Connect introduces a co-branded end-to-end lending program, simplifying the process for companies to seamlessly offer loans online. 

This program is an excellent fit for businesses looking to integrate lending options into their services effortlessly, providing customers with convenient online access to loans and enhancing the overall customer experience.

7. BHG VC

BHG Financial Interest Rate

Operating as a Corporate Venture Capital fund, BHG VC supports disruptive fintech founders and contributes strategic resources. BHG VC aims to facilitate rapid growth in the financial technology sector by providing comprehensive support to promising startups.

BHG VC might be suited for fintech entrepreneurs seeking both financial backing and strategic guidance for their innovative ventures. 

You might also like: Y Combinator: Fast Track to Success or Waste of Time? 

Frequently Asked Questions 

What credit score do you need for BHG? 

BHG typically requires a credit score in the good to excellent range, often around 680 or higher. However, specific credit score requirements may vary depending on the type of loan and individual circumstances.

What type of loan is BHG? 

BHG offers a range of loans, including business loans, personal loans, startup loans, and SBA 7(a) loans. The diversity of loan options caters to both professionals and businesses with varying financial needs.

Does BHG require collateral? 

For many of its loan products, BHG is known to provide unsecured loans, meaning they generally do not require collateral. This can be beneficial for borrowers who prefer not to pledge specific assets.

What is the BHG business loan rate? 

BHG’s business loan rates can vary based on factors such as the type of loan, the borrower’s creditworthiness, and prevailing market conditions. I’ve seen them range from 10% to 16%+. Contact BHG directly or visit one of their websites for the most accurate and up-to-date information on loan rates.

Do BHG loans affect credit? 

Yes, like any other loan, BHG loans can impact your credit. When you apply for a loan, BHG typically performs a hard inquiry on your credit report, which may have a temporary impact on your credit score. Timely repayments can positively influence your credit history, while late payments or defaults may have a negative effect. And, most of their business loans are likely to carry a personal guarantee (you’re responsible to pay it back if your business defaults).

Conclusion: Is BHG a Legitimate Company? 

Yep! BHG is a bona-fide financial technology company that offers not only consumer and business loans, but risk management, point of sale (POS) solutions, venture capital for startups, and more. 

There is an open class action proposal (as of January 2024), but the allegations haven’t been proven. And, according to the language, the claims against the company are likely to affect consumer loans, but not business loans. 

In all, if you’re looking at taking a loan with BHG, just be ready to negotiate ideal terms and ask for interest rates that you can comfortably work with. 

Do you want to learn how to get up to $100K in business credit in as few as 30 days? Join Business Credit Workshop today! 
3 Best Business Credit Cards for a New LLC +More Resources

By Joe

Business Credit Cards for New LLC

So, you’ve started a new LLC, and you’re interested in getting business credit cards. But, since your business is new, you haven’t established business credit yet. So, what are the most promising cards for you to apply for? 

Here, I’ll tell you what cards you might qualify for (along with their requirements), and explain exactly what I would do in your position. As a new business, you don’t automatically have business credit, so you may want to establish it now. 

Recommended: Download our Free Business Credit Checklist

Here’s what’s in store: 

  • What Are Business Credit Cards?
    • Can a Newly-Formed LLC Get a Credit Card?
  • Best Business Credit Cards for New LLCs
    • 1. Chase Ink Business Preferred
    • 2. Bank of America Executive Explorer
    • 3. Marriott Bonvoy Business
  • Corporate Cards to Consider
    • 1. Bill Spend & Expense (Formerly Divvy)
    • 2. PEX Expense
  • Best Loans for New Businesses
    • 1. Credibly
    • 2. LenCred
  • Frequently Asked Questions
  • Final Thoughts

Now, let’s roll!

What Are Business Credit Cards? 

Before we look at the cards you might qualify for, let’s make sure you’re clear on what you want. More often than not, business owners get other spending cards confused with business credit.  

Business credit cards are revolving lines of credit that can be used for business spending. Only a percentage of the total amount spent is required to be paid each billing cycle. Business credit cards accrue debt on any balance left unpaid. 

Meanwhile, corporate cards are either prepaid or must be paid in full at the end of each billing cycle. Corporate cards typically supplement robust business expense management software and tools. 

So, if you need funding, look at the credit cards below. And, If you need expense management, consider the recommended corporate cards. 

Recommended: Corporate vs Business Credit Card: What’s the Difference? 

Can a Newly-Formed LLC Get a Credit Card? 

So, how soon can you apply for a business credit card and do brand new LLCs get business credit? 

Getting a business credit card for a brand new LLC depends on factors like the business’s creditworthiness and the personal credit history of the owners. Typically, credit card issuers have a waiting period before a new business can apply, often a few months to a year (but this isn’t always the case). 

As a new LLC, it’s important to establish a clear separation between business and personal finances by: 

  • Obtaining an EIN
  • Opening a business bank account
  • Maintaining distinct records

The likelihood of approval is higher if the owners have a good personal credit score. As the business operates and builds a positive credit history, it becomes easier to qualify for business credit cards. Check with specific credit card issuers for their policies and requirements.

You might also like: Here’s How to [Actually] Get Business Credit With Just an EIN +More Options 

Best Business Credit Cards for New LLCs

Here, I’ll lay out my favorite business credit cards for new LLCs. You’ll see a summary of each offer (why I like it) and how long your business must be in operation before you apply. 

If you can’t get a business credit card yet, and you’re in need of immediate funding, scroll down to the loans section. Or, join Business Credit Workshop to learn how to get up to $100K in business credit in as few as 30 days. 

1. Chase Ink Business Preferred

credit cards for new businesses with no credit history

The Chase Ink Business Preferred card stands out as one of the top small business credit cards, thanks in part to its impressive sign-up bonus. Although it doesn’t offer a 0% APR and comes with an annual fee, there’s significant potential for savings and rewards. If you believe your business meets the qualifications, I recommend this one.

To qualify for the Chase Ink Business Preferred credit card, you don’t need a specific annual income or business history, but your revenue should cover the minimum monthly payment. 

Other requirements include: 

  • A FICO score of 670 or higher 
  • A minimum credit limit of $5,000

Chase evaluates your application using your personal credit score, with a recommended FICO score of 670 or higher. Keep in mind that while a good credit score is important, it doesn’t guarantee approval or denial. Whether you’re an incorporated business (LLC, corporation, partnership, non-profit, etc.) or a sole proprietor, you’re eligible to apply for the Chase Ink Business Preferred credit card.

Recommended: Chase Ink Business Preferred Credit Card: A Deep Dive Analysis 

2. Bank of America Executive Explorer

Startup business credit cards for new llc

Next, consider looking into the Bank of America Executive Explorer card. Despite its $375 annual fee, the card’s perks more than justify the cost. For instance, you receive a $600 Lounge Access credit annually and a $100 Airport Fast Track credit every four years. Moreover, you gain access to the Benefits on Us and Dinova Rewards programs. 

While a new LLC could be approved, it’s important to note that this isn’t a revolving credit line; rather, it functions as a “corporate credit card” that must be paid in full. To qualify, you must be an executive or owner of your company, and while there’s no minimum business history requirement, having an excellent credit score is crucial. 

Owners with FICO scores of 740 or higher stand the best chance of getting approved for Bank of America business credit cards.

Recommended: What is the Best Bank of America Business Credit Card for Your Needs? 

3. Marriott Bonvoy Business

Best business credit cards for new llc

I believe Marriott boasts one of the top hotel rewards card programs. The appealing part is that while you travel for work, the Marriott Bonvoy Business credit card helps you build business credit. If you meet the criteria, applying for and using this card is a smart move. 

Keep in mind that the Marriott Bonvoy Business Credit Card is exclusive to business owners and authorized representatives with a credit score of 700 or higher. 

Approval considerations also include factors like: 

  • Annual income 
  • Existing debts

Start earning travel rewards on your next hotel stay by applying now.

Recommended: Marriott Bonvoy Business Credit Card Review & Comparison 

Corporate Cards to Consider

If you’re looking for a spend card mainly to help with expense management, and you’ve got some revenue to back your account, a corporate card might be a better choice at this point – especially if your LLC is brand new, and your credit hasn’t been established. 

Now, my favorite thing about modern corporate cards is that many of them offer cash back on spending (some more than others). So, with these cards, you have a chance to earn on transactions that you or your employees make. Cool, right? 

Here are the two cards I would recommend…I’ll explain why.  

Recommended: 7 Best Cash Back Corporate Credit Cards to Explore in 2024 

1. Bill Spend & Expense (Formerly Divvy)

business credit cards for new llc without personal guarantee

Bill Spend & Expense, formerly known as Divvy, comes with its own set of advantages and disadvantages. If you’re considering whether to take advantage of this offer, reflect on the following questions:

  • Is your monthly business spending more than $5K?
  • Does your business have multiple staff members with spending privileges?
  • Can you pay your expenses in full each month?

If you answered “yes” to these questions, the Bill Spend & Expense card could be an excellent fit for you. Now, to meet eligibility requirements, a business owner must have a minimum personal credit score of 580, and having a score of 640 or higher increases the chances of approval. Additionally, a higher annual revenue enhances the likelihood of approval.

I personally highly recommend checking it out, specifically for the tiered cashback rewards. Sign up on the Bill.com website to find out the credit line you may qualify for.

Recommended: In-Depth Divvy (BILL) Credit Card Review: Read This Before You Apply 

2. PEX Expense

startup business credit cards ein only

PEX is another solid corporate card with some cool features, making it a good pick for businesses and nonprofits looking to manage expenses smoothly. It’s got prepaid and dynamic credit cards, throws in 1% cash back, and has a handy app that fits different industry needs.

The user experience is made even better with seamless integrations, virtual/physical cards, and customizable controls, backed by PEX’s positive company vibe.

While PEX is a great choice, if you’re running a startup or an e-commerce gig, you might want to check out alternatives like Brex, Bill Expense, or Shopify Credit that could be more spot-on for your needs. Always a good move to weigh your priorities and compare a few options when it comes to any financial stuff.

Oh, and PEX cards are designed for businesses and organizations, and the cool part is you can get them without worrying about minimum funding requirements—they can even be issued inactive. Nice, right?

Recommended: The PEX Card: Is it the Best Corporate Card for Your Business? 

Best Loans for New Businesses

Now, if you’re looking for the funding aspect of a credit card, but you haven’t established business credit, you still have options. While your repayment terms aren’t ideal on most of the options available to you right now, you can use one of these offers in a pinch. 

Note: I don’t typically recommend factoring-type financing or loan brokers. The problem is that the rates are typically very high. Still, I know that sometimes you gotta do what you gotta do to pay for emergencies to seize an opportunity to grow your business. I have thoroughly reviewed the following loans, and I’ll tell you the truth about them. 

Recommended: How to Get an SBA Business Loan 

1. Credibly

Business credit cards for new llc ein only

Credibly’s rates, covering everything from interest and factor rates to origination fees and admin fees for merchant cash advances, lean towards the higher side. If your business is on the newer side, your credit isn’t stellar, and you’re pulling in at least $15,000 per month, Credibly might be a viable option for securing the funding needed to keep your business going or expand. 

It’s a relatively young company, but it’s legit, with enough satisfied customers indicating it’s doing something right. However, I won’t strongly recommend their loans unless your business is in a tight spot, and if it is, be cautious about the personal guaranty—it can be risky. 

Before committing to Credibly or any other company, it’s a good idea to shop around for quotes. You might be able to find comparable loans with better rates, especially if your business is more established or you have a solid credit score.

Recommended: A Deep-Dive Credibly Review: Is Their Financing Right for You? 

2. LenCred

business credit cards for new llc with bad credit

If you’re in need of working capital or startup funds, and you’ve got solid credit but aren’t in a position for traditional funding options, LenCred could be the solution you’re looking for – It’s especially handy if you’re not keen on unconventional routes like crowdfunding and are okay with dealing with a 9% origination fee. 

LenCred’s financing services might just be the boost you need.

However, if you’re aiming to build up your business credit and prefer securing funding without hefty origination fees, LenCred might not be the best fit. Since they don’t use your business credit profile in the funding process, their lenders are unlikely to report to the business credit bureaus. So, it’s a trade-off to consider.

Recommended: This is the Truth About LenCred’s Small Business Financing 

Frequently Asked Questions

What is the fastest way to get business credit for an LLC? 

You first need to make sure the owner’s personal credit is in check and the business is properly established for “credit readiness.” Then, open a bank account and establish relationships at the bank. After that, make sure the business has a DUNS number, establish your first tradelines of credit, and pay your accounts at the right time. Finally, you just need to monitor your business credit before you apply for a new loan or line of credit. 

Download our free Business Credit Checklist to start building business credit. 

Can a single-member LLC build credit? 

Yes, a single-member LLC can build business credit with an EIN and a DUNS number. 

Can you get a business credit card with no revenue? 

The short answer is no. However, there are exceptions, for example, you may be able to get a business credit card with a personal guarantee if your income meets underwriting requirements. 

Do LLCs start out with good credit? 

When LLCs are initially registered, they have no business credit. In this case, credit decisions may be based on the owner’s personal credit. Businesses can build credit by establishing their business properly, setting up accounts with the right tradelines, and paying accounts on-time as agreed. 

What happens if an LLC defaults on a credit card? 

If an LLC defaults on a credit card, the creditor can go after business assets, send debts to collections, and sue to liquidate the company. If the credit card has a personal guarantee, the creditor may hold the business owner personally liable to repay the debt. 

Final Thoughts

Now that you’ve explored the best business credit cards for your new LLC, consider all options like the Chase Ink Business Preferred and PEX Expense to find what suits your business needs. Distinguish between business credit and corporate cards, with corporate options like Bill Spend & Expense offering a smooth ride for your expense management.

For loans, check out Credibly and LenCred, weighing perks and alternatives. 

Are you ready to learn how to get up to $100K in business credit in as few as 30 days? Join Business Credit Workshop today!
Amazon Business Prime Credit Card: Full Review +How to Get One

By Joe

Amazon Business Prime Credit Card

The Amazon Business Prime Credit Card has been around for awhile now, and it’s convenient for business spending with Amazon, AWS, and Whole Foods. But, that isn’t the only reason why you would want one. Here, I’ll lay out the card benefits in full and explain how to get a business credit offer from Amazon and Amex. 

For those who already have the card, I’ll explain how to get the most rewards with your spending and answer some common questions.

Here’s what’s in store: 

  • What is the Amazon Prime Business Credit Card?
    • Amazon Company Overview
  • Amazon Business Prime Credit Card Summary
    • How Does the Amazon Business Card Work?
    • Can Anyone Get an Amazon Business Prime Card?
    • How to Get an Amazon Prime Business Credit Card
  • Frequently Asked Questions
  • Wrapping Up

Let’s roll!

What is the Amazon Prime Business Credit Card? 

The Amazon Business Prime Card is like a VIP pass for your business expenses. With no annual fee, you can snag a $125 Amazon.com Gift Card just for getting approved—nice, right? 

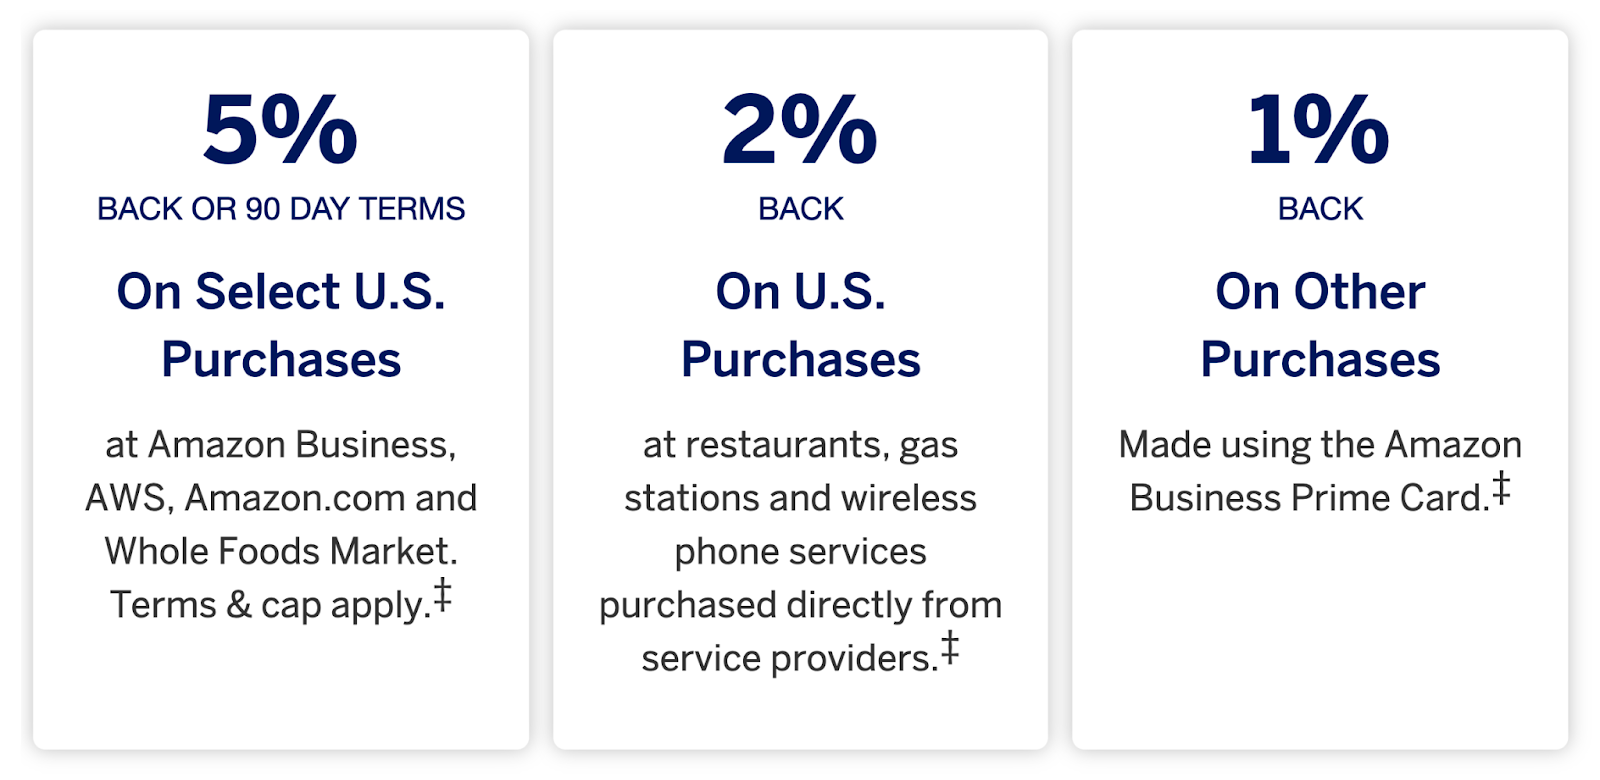
The more you spend at Amazon Business, AWS, Amazon.com, and Whole Foods Market, the more you earn back, like 5% back or 90-day terms on eligible purchases with a Prime membership – Dining out, filling up at gas stations, and handling phone bills also get you some sweet 2% back. Everything else? You still get a cool 1% back. 

Plus, the perks include: 

  • No foreign transaction fees
  • Expense management tools
  • Baggage insurance for your travels 

It’s like your business’s new best friend with benefits! 

You might also like: Amazon Corporate Credit Line – The Ultimate Guide 

Amazon Company Overview 

If you haven’t heard of Amazon, it would surprise me. Still, for the sake of staying true to my comprehensive nature, here’s a quick rundown. 

Amazon is the big dog of online everything…It started as a humble online bookstore in ’94, and look at it now—like the Godzilla of e-commerce. From A to Z, they’ve got it all, and I mean everything: Books, gadgets, groceries, cloud computing, streaming, you name it. 

Amazon Business Prime account

The founder, Jeff Bezos, turned a garage project into a tech empire over the course of the past 30 years. Fast shipping? Hello, Prime! They even got drones in the game. With fingers in so many pies, it’s hard to imagine a world without that iconic smiling arrow. 

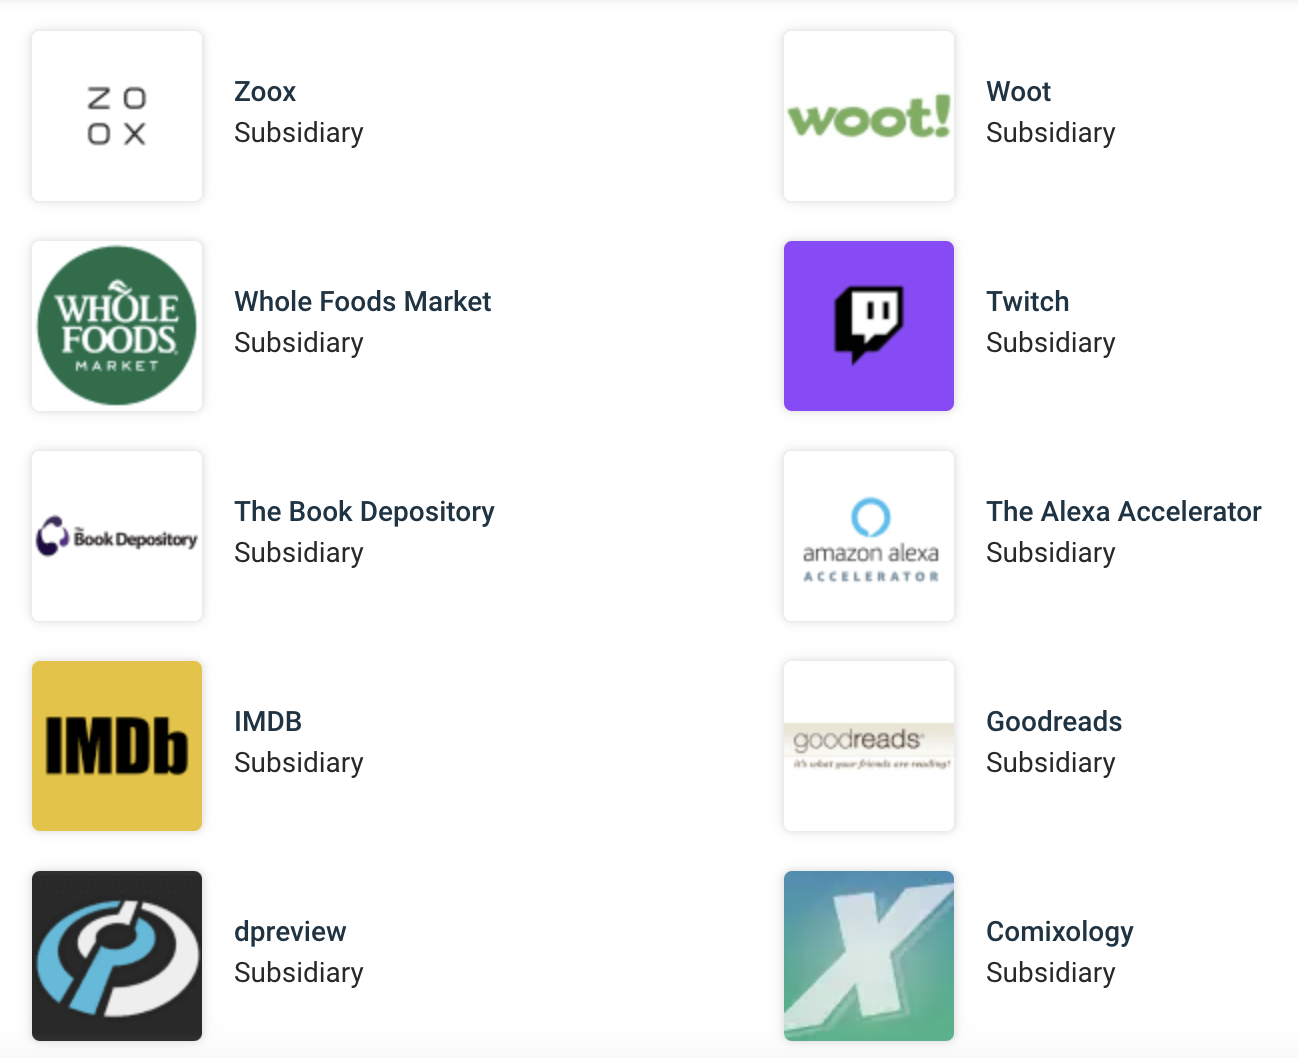
Amazon is a seattle-based company that now has a ton of subsidiaries including Xoox (future driverless, electric taxis), Whole Foods, Twitch, and IMDB. 

Amazon Subsidiaries

The current CEO, Andy Jassy, had been with the company since 1997, founded AWS in 2006, and took over Amazon Inc. when Bezos stepped down in 2021. 

At this point, there aren’t many industries Amazon doesn’t have their hand in. Still, their business credit card is serviced by Warren Buffet’s American Express (a Berkshire Hathaway company). The card doesn’t currently offer cashback on purchases with most subsidiaries, but they’re in an interesting position that would make this possible – I wonder if that’s something we could see in the future. 

Amazon Business Prime Credit Card Summary

Looking to level up your business game? Enter the Amazon Business Prime Credit Card—a great tool for savvy business spenders. From a $125 welcome gift card to cash back rewards on your favorite business expenses, this card is a VIP pass to Amazon-related savings. 

Let’s dive into the details!

How Does the Amazon Business Card Work?

So, how does this card work its magic? It’s all about the cashback game…Let’s review. 

Amazon Prime card for business

You earn 5% back or get extended 90-day terms on U.S. purchases (your choice) at: 

  • Amazon Business
  • AWS
  • Amazon.com
  • Whole Foods Market

The 5% cashback offer is good for up to $120K in spending per year. 

Dining out, fueling up, or sorting out your wireless bills? Enjoy 2% back—every other purchase scores you a solid 1% back. The more you spend, the more you earn. Simple as that.

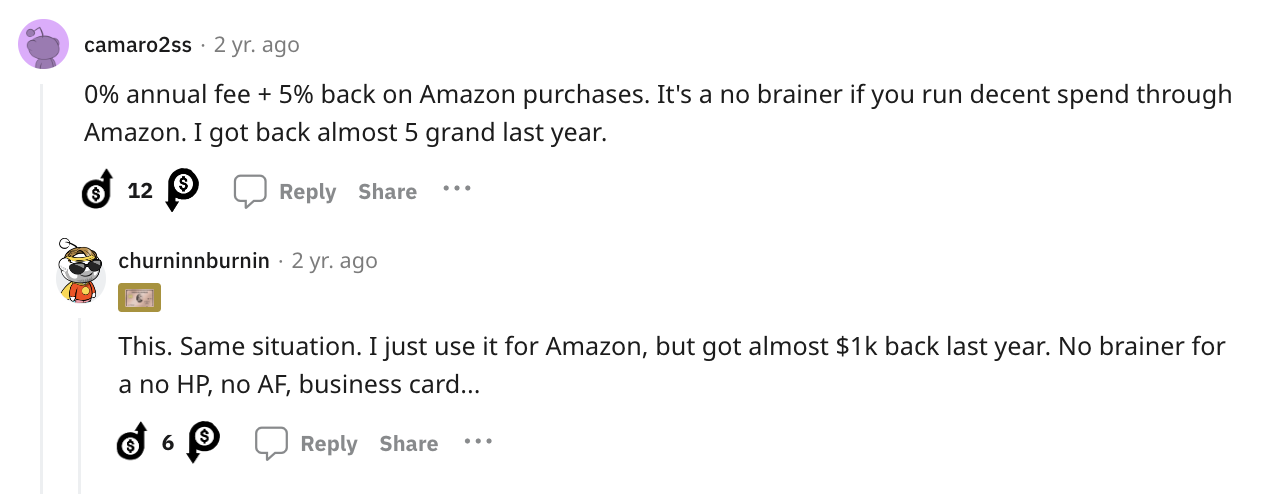
Amazon Business Prime Credit Card review Reddit

Then, as an Amex cardholder, you can take advantages of even more benefits: 

  • Gain deeper insights into your purchases for smarter decisions.
  • Simplify expense reconciliation with itemized, downloadable purchase details.
  • Earn rewards with no expiration, giving you flexibility in usage.
  • Redeem points on Amazon.com and Amazon Business (U.S.) or apply them to your balance.
  • Travel the world without worrying about foreign transaction fees.
  • Enjoy global card acceptance with American Express.

Plus, this card comes with no annual fee (they make up for this with your prime membership fee). If you play the game well, you can end up saving quite a bit. 

Moreover, you can leverage extra protection on purchases made with the card: 

  • Get an extended warranty on items you purchase with the card, up to one extra year.
  • Purchase protection guards your purchases for up to 90 days against theft or accidental damage.
  • Receive support with dispute resolution for any fraudulent or incorrect charges on your statement.

Hopefully, you won’t ever have to use them, but these perks will make life easier if you do. 

You might also like: Marriott Bonvoy Business Credit Card Review & Comparison 

Can Anyone Get an Amazon Business Prime Card?

The Amazon Business Prime Card is up for grabs for any business, but there are a couple things to note: 

  1. The basic requirements are that you are at least 18 years of age, own at least half of your business, and have a Prime or Business Prime account.
  2. While there’s no minimum credit score posted on the door, a solid creditworthiness vibe is key – people I’ve known to be approved for this card had a score of 700 or above. 
  3. You may need an EIN set up with the IRS, a business bank account, and a business address. 

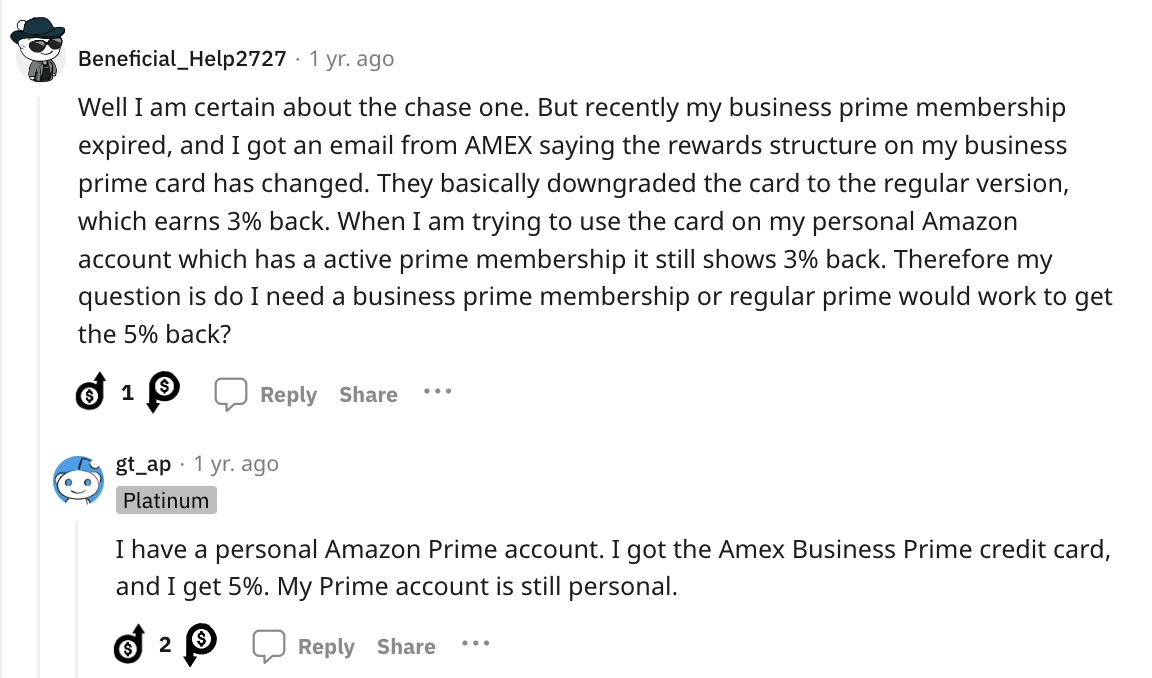
Note: If you downgrade your Amazon Prime account, Amex may downgrade your cashback rewards structure, but this doesn’t seem to happen to everyone. 

Amazon Business Prime Credit Card apply

People often wonder about the APR, and here’s the lowdown: Your annual percentage rate will dance in the 19.49% – 27.49% variable rate range. 

Recommended: Here’s How to [Actually] Get Business Credit With Just an EIN +More Options 

How to Get an Amazon Prime Business Credit Card

Pre-approval requirements for the Amazon Prime Business card are not crystal clear, but a decent credit score waltz will get you far. Keep those expenses in check, and you might just find this card in your wallet.