• Home
  • Free Funding Guide
  • What We Offer
    • Products
    • Services
    • Free Guide
  • About Us
  • Contact
  • Sign Up

  • Ask Joe Any Question!
  • Business Credit Cards
  • Business Line of Credit
  • Topics

A Complete Torpago Business Credit Card Review

By Joe

Torpago Business Credit Card

Torpago is a newer player in the corporate credit card game. And, they’re starting to pick up some traction in the business credit world. So, we’ve decided to examine their corporate credit card offer under a microscope and share our findings so that you can decide if this is the right option for you. 

Here’s what we’re going to cover: 

  • What is the Torpago Business Credit Card?
    • Who Owns Torpago?
    • Torpago Business Credit Card Benefits
    • Torpago Expense Management Features
    • Torpago Customer Service
    • How to Qualify for a Torpago Corporate Card
    • Does Torpago Report to Business Credit Bureaus?
  • Competitor Overview: Torpago vs Divvy
  • Final Thoughts

Now, let’s get to it! 

Torpago
Torpago

Torpago is gaining momentum as a new corporate credit card.

Apply Now
We may earn a commission if you make a purchase, at no additional cost to you.
Lasso Brag

What is the Torpago Business Credit Card?

For those who haven’t heard of it, the Torpago Business Credit Card is a corporate credit card and expense management platform. Corporate credit cards like this are designed for companies with multiple employees to enable staff to use a line of credit on authorized spending. 
Torpago LinkedIn

When I first landed on Torpago’s website, it put me in mind of Divvy — both have a corporate credit line, expense management, and virtual cards among other shared features. You’ll see a side-by-side comparison of the two offers before we wrap up. 

Who Owns Torpago? 

Torpago was founded by Brent Jackson in October 2018. Before launching this company, Jackson worked as the Operations Manager at Accrualify for a year and as a Senior Consultant at Deloitte for nearly half a decade. Jackson has a strong background in the business and finance industry. 

Torpago Business Credit Card Benefits

In addition to 1% cash back on all spending, Torpago partners with other brands to deliver savings to their cardholders. So, if you use Quickbooks, Carta, Plastiq, or Doordash, and pay for these services with a Torpago card, you can get added discounts from 2.25% up to 40%. 
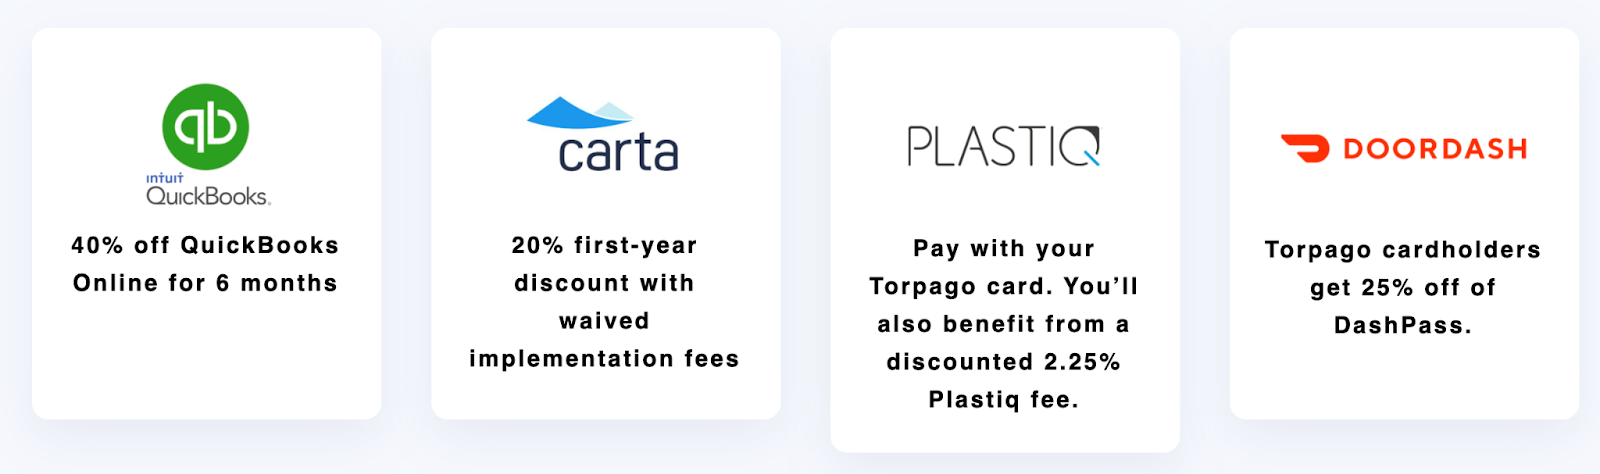
The company will likely continue to partner with more brands, so users will be able to access more markdowns on other future services (though, we’re not certain what those will be).  

As mentioned above, Torpago gives cardholders both physical and virtual cards. Physical cards are Visa credit cards that can be assigned to multiple staff members for each corporate account. Virtual cards are digital credit cards that can be assigned instantly without the need to wait for a physical card to arrive in the mail. And, both physical and virtual cards can be assigned to an unlimited number of staff members (as long as the credit limit is not exceeded). 

Automated expense tracking is another highlight that should get account holders excited. Each time a Torpago card is ran, data is sorted, synced, and accounted for. So, ideally, manual expense reports are eliminated.

Since the company is new, you can probably expect to see more future benefits. 

Torpago Expense Management Features 

One of the highlights of Torpago’s expense management platform is that it integrates with four other financial management platforms. 

  • Quickbooks Online
  • Oracle Netsuite
  • Financial Force 
  • Acumatica

So far and to my knowledge, no other corporate credit line and expense management platform has this many integrations (aside from maybe Stripe). 

Torpago Customer Service 

I did call the Torpago customer service number to ask if they have plans to add Quickbooks desktop to their integrations list. On that note, the Torpago phone number was a bit tricky to track down. If you are looking for it, they can be reached at 1 (650) 623-5429. 

I was disconnected the first time I tried calling in, but only spent a few seconds on the phone. The second time I called, I was told that I was the next caller in line. There was an option to leave a voicemail, which I didn’t take advantage of. 

After about 12 minutes of holding, I opted to reach out via the instant messaging option on the Torpago website. The reply time was advertised to be “under 6 hours.” I left my email address in the chat box (1:21 pm) and went back to what I was doing. 

I only ended up waiting 20-30 minutes for the first reply, but I still had more questions — I should have asked everything in one swoop. The user answering my questions was named Brent (I assume it was the founder himself, which leads me to believe the company is still very small). 

By the next morning around 10:30 am, all of my questions had been answered.

How to Qualify for a Torpago Corporate Card

If you are ready to try to obtain a Torpago corporate credit account, first look over the qualification terms. First of all, only US registered companies (sole proprietors, LLPs. LLCs, S-Corps, or C-Corps) can apply. So, if your company isn’t organized, you won’t be able to get a credit line. 

Next, you need an EIN and business checking account. Your account will be linked to the Torpago platform to verify businesss income. At this point, Torpago wants to see your monthly business income, but they do not publicly state the amount needed to qualify. My assumption is the higher the better… I wouldn’t apply without at least $10K in documented monthly revenue. 

Finally, you must not participate in prohibited activities. 

  • Sale of Schedule-I or Schedule II-V controlled substances without a pharmaceutical license
  • Production, sale, or distribution of marijuana, guns, ammunition, or other weapons
  • Gambling, betting, lottery, sweepstakes, or games of chance
  • MLM, cryptocurrency, counterfeit products, escort services
  • Professional services including law and consulting

See the full explanation in the above link if you aren’t sure or your business tends to fall into a gray area. Torpago seems to be designed for tech startups, but many other businesses can still qualify for an account. 

Does Torpago Report to Business Credit Bureaus? 

Most of my students and clients want to know if Torpago reports to business credit bureaus like Dun & Bradstreet. The reason this is important is because when on-time payments are reported to credit bureaus, it has a positive effect on a company’s business credit score.  

According to Torpago, on-time payments are reported to business credit bureaus. This is good news for anyone looking to build their business credit score. 

Recommended: This is How to Build Business Credit Fast [Step-by-Step Guide]

Competitor Overview: Torpago vs Divvy

Both Torpago and Divvy are free corporate lines of credit that require no personal guarantee, a rare offer. And, while they share these commonalities, they aren’t one in the same. Below are the key differences between the two offers. 

Torpago vs Divvy

If you’re interested in one of these credit lines because of the automated expense management, you might look at available integrations. For now, Torpago is the clear winner on this front if you use either Financial Force or Acumatica. However, Divvy currently offers the best rewards by a long shot. 

Learn about corporate card offers from Ramp, Amazon, Brex, Stripe, and Divvy. 

Final Thoughts

While Divvy has a similar offer with higher rewards, a more established partner base, and a more robust customer service team, Torpago is still a new player and has plenty of time to catch up. While I might not recommend applying for this credit line above other contemporary corporate offers, I wouldn’t rule them out as a legit and convenient option for business cash flow management.

If you want to learn how to obtain $100K in business credit in 30 days, join the Business Credit Workshop today. 
Capital on Tap Review: Is This Business Credit Card Any Good? 

By Joe

Capital on Tap

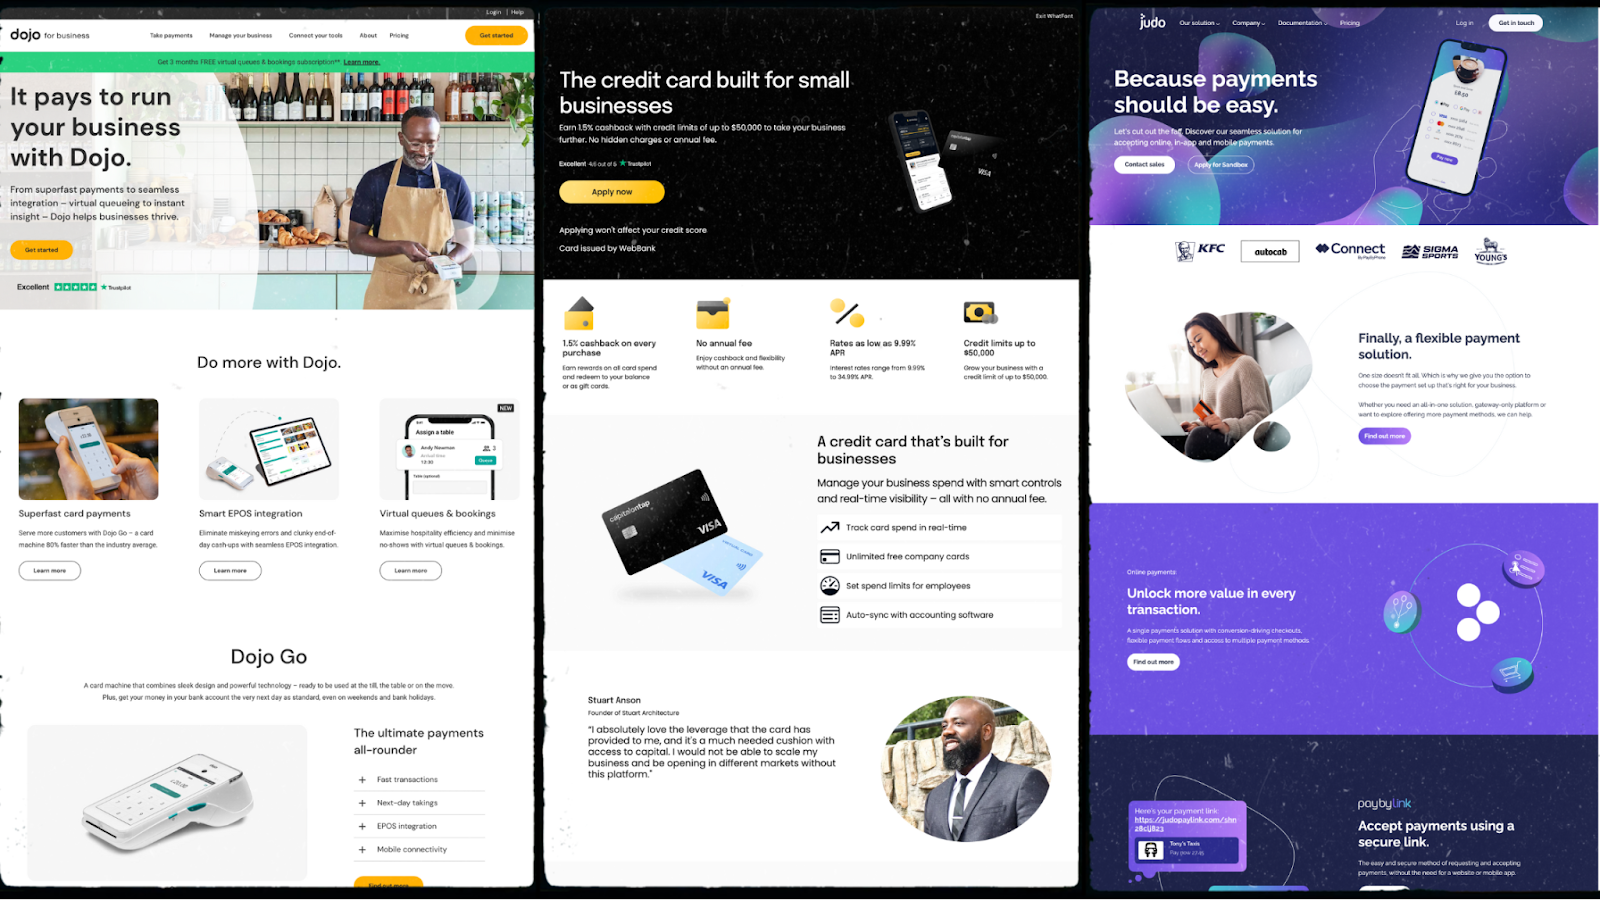
Since March 2021, when the U.K.-based company launched their U.S. business credit card, Capital on Tap has been a hot topic for business owners looking to obtain funding. They’re offering business credit lines up to $50K with cashback on all purchases. Sounds enticing, right? But, should you hop on this train or explore other options? 

Business Credit Card - $100 sign up bonus

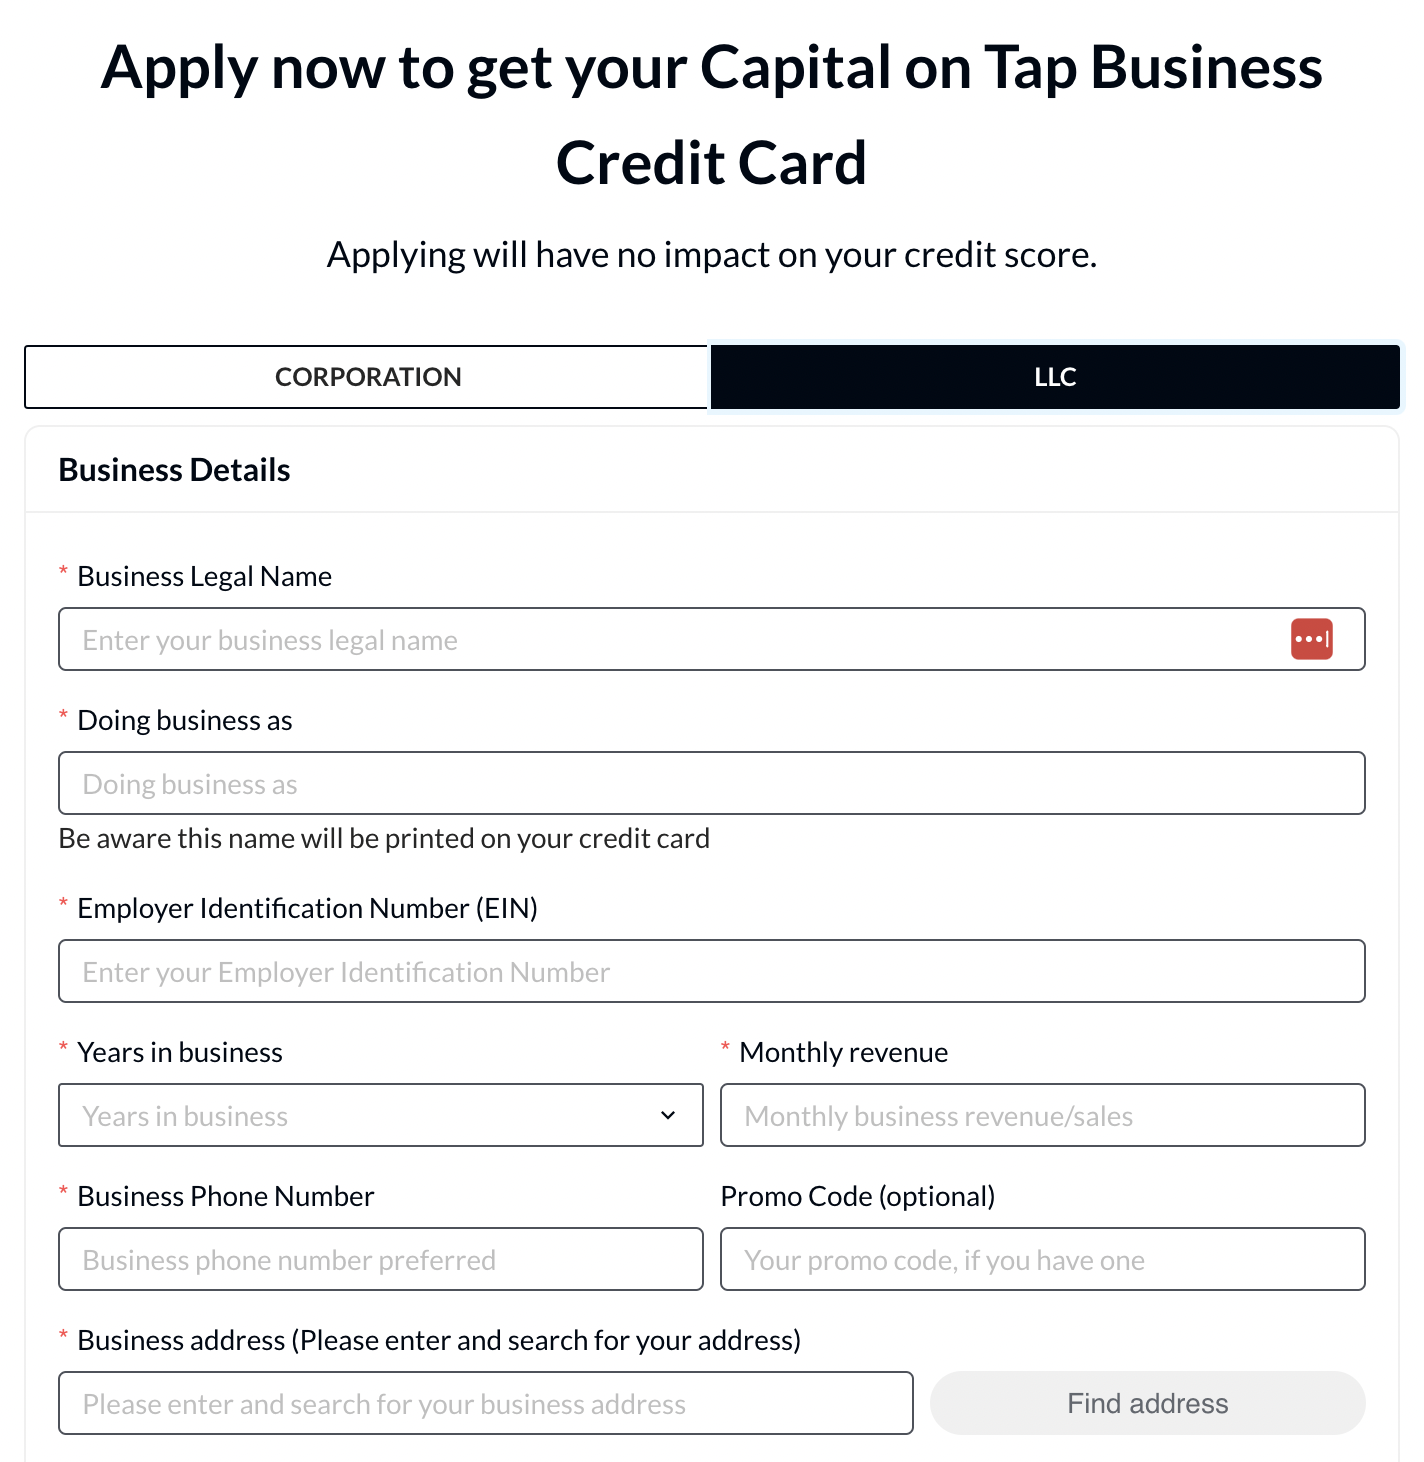
Apply now - takes 2 minutes and it will not impact your credit score. Your Capital on Tap business credit card will arrive within 4 days of approval!

Apply Now
Lasso Brag

We’ve done the research so that you don’t have to. 

Here’s what’s in store:

  • Company Overview
  • What is a Capital on Tap Credit Card?
    • Capital on Tap Requirements
    • Capital on Tap Credit Card Card Overview
    • Capital on Tap Complaints
  • Capital on Tap Competitor Overview
  • Frequently Asked Questions
  • Conclusion: Is Capital on Tap Legit?

Now, learn everything you need to decide if the offer is right for you. 

Company Overview

While the name sounds like an offer that could be akin to Capital One, the two companies are unrelated.

Capital on Tap is a subsidiary of New Wave Capital Limited, based in London (incorporated in Whales and the U.K.). The company was founded in 2012 by David Luck, George Karibian, and Jan Farrarons. Prior to starting Capital on Tap, Luck was part of the operations group at a venture capital company called KKR Capstone. 

Karibian and Farrarons also co-founded Dojo in 2009 and Judopay in 2012. Karibian is a serial entrepreneur who founded a couple of other companies prior to 2009. Both Dojo and Judopay are, to this day, successful payment processing companies. 

Who owns capital on tap?

Now, Capital on Tap credit cards for U.S. cardholders are issued by WebBank, headquartered in Salt Lake City, Utah. Originally founded in 1997, the company was acquired by Steel Partners Holding Corp. 

What is a Capital on Tap Credit Card? 

A Capital on Tap business credit card is a line of credit geared toward small businesses. In the US, They offer lines of credit up to $50K with 1.5% unlimited cashback on all spending. They boast that you can apply for a line of credit in as little as two minutes and get approved within 48 hours. 

Capital on Tap login

Despite some rumors, a Capital on Tap card does require a personal guarantee. So, if the business fails to pay the revolving debt as agreed, the individual/applicant will be responsible for the repayment. Business credit cards with no personal guarantee are actually very rare. 

Recommended: Here’s How to [Actually] Get Business Credit With Just an EIN +More Options 

Capital on Tap Requirements

If you’ve made it through the benefits overview, and this sounds like the card for you, let’s make sure you’re in a position to qualify for the offer.

Here’s what you need to have: 

  • Be the Director of or own at least 25% of your company
  • Business based in the U.S. 
  • Business annual revenue of at least $30K 
  • Good personal FICO credit score 

While Capital on Tap doesn’t broadcast its credit requirements, applicants with a score of 670 seem to be preferred. So, your odds of qualifying will increase with your FICO score.  And, these requirements are actually fairly lax. 

Capital on Tap Card Card Overview

Capital on Tap credit card

Before you think about applying, why would you want to? Capital on Tap has features and benefits that, when compared to other offers, will help you make a decision about whether or not this is the right card for you.

  • Unlimited Cashback – 1.5% cashback on all spending
  • Instant Rewards Redemption– Cashback redeemed instantly to help repay your card balance
  • Competitive Credit Limits – Credit lines as high as $50K
  • Fee-Free – No foreign transaction fees or ATM charges 
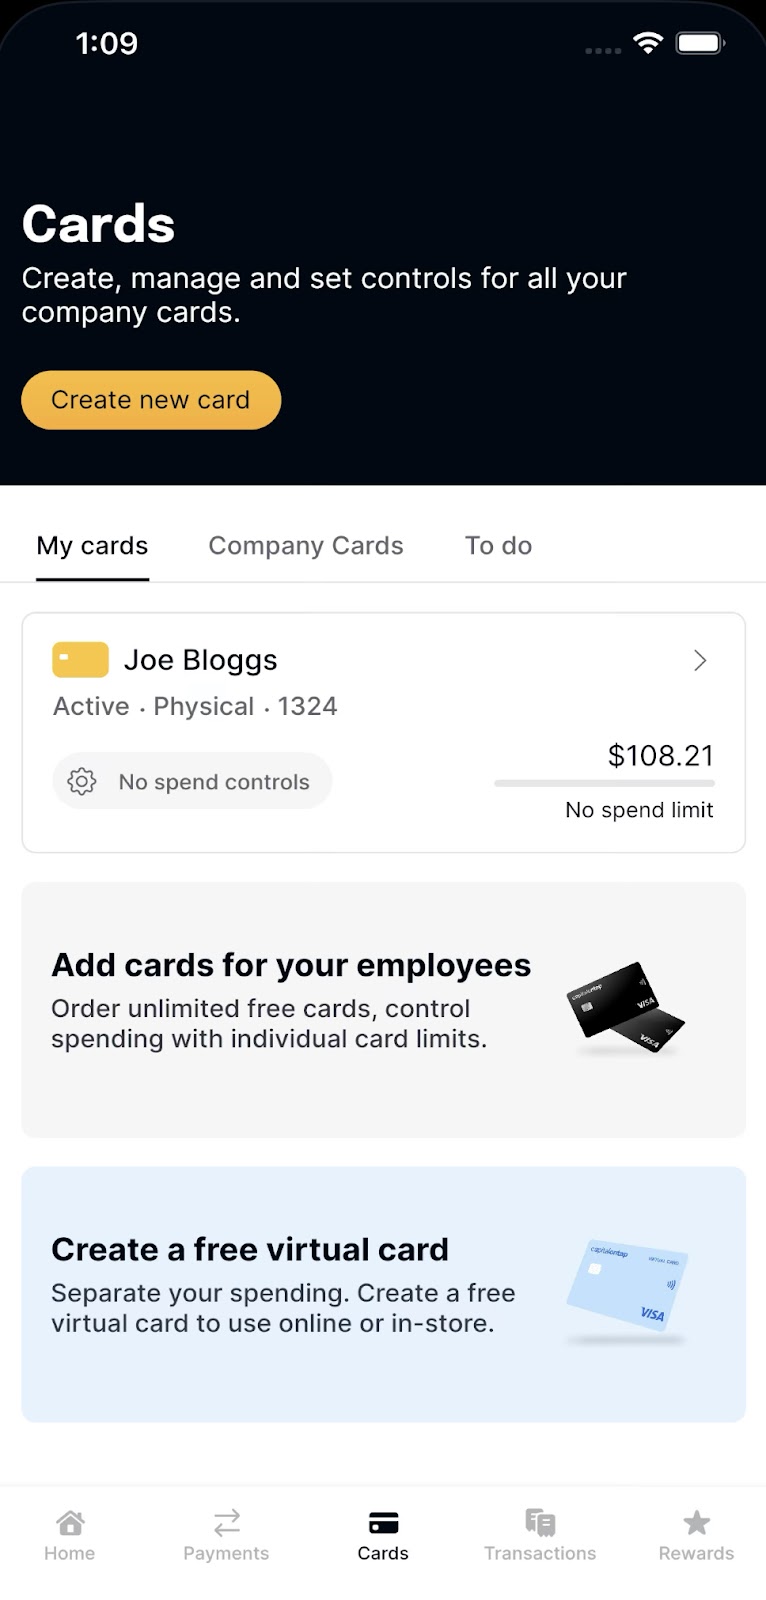
  • Free Employee Cards – Unlimited, free cards for employee spending
  • Spend Management – Budgeting tools to monitor employee spending 
  • No Annual Fee – Restrictions apply

While you can avoid interest “if you pay your balance in full each month,” actual interest for Capital on Tap cards ranges from 9.99% to 34.99% APR. 

Furthermore, while there is no initial fee for ATM use, your interest rate may increase when you pull cash from your balance at an ATM. 

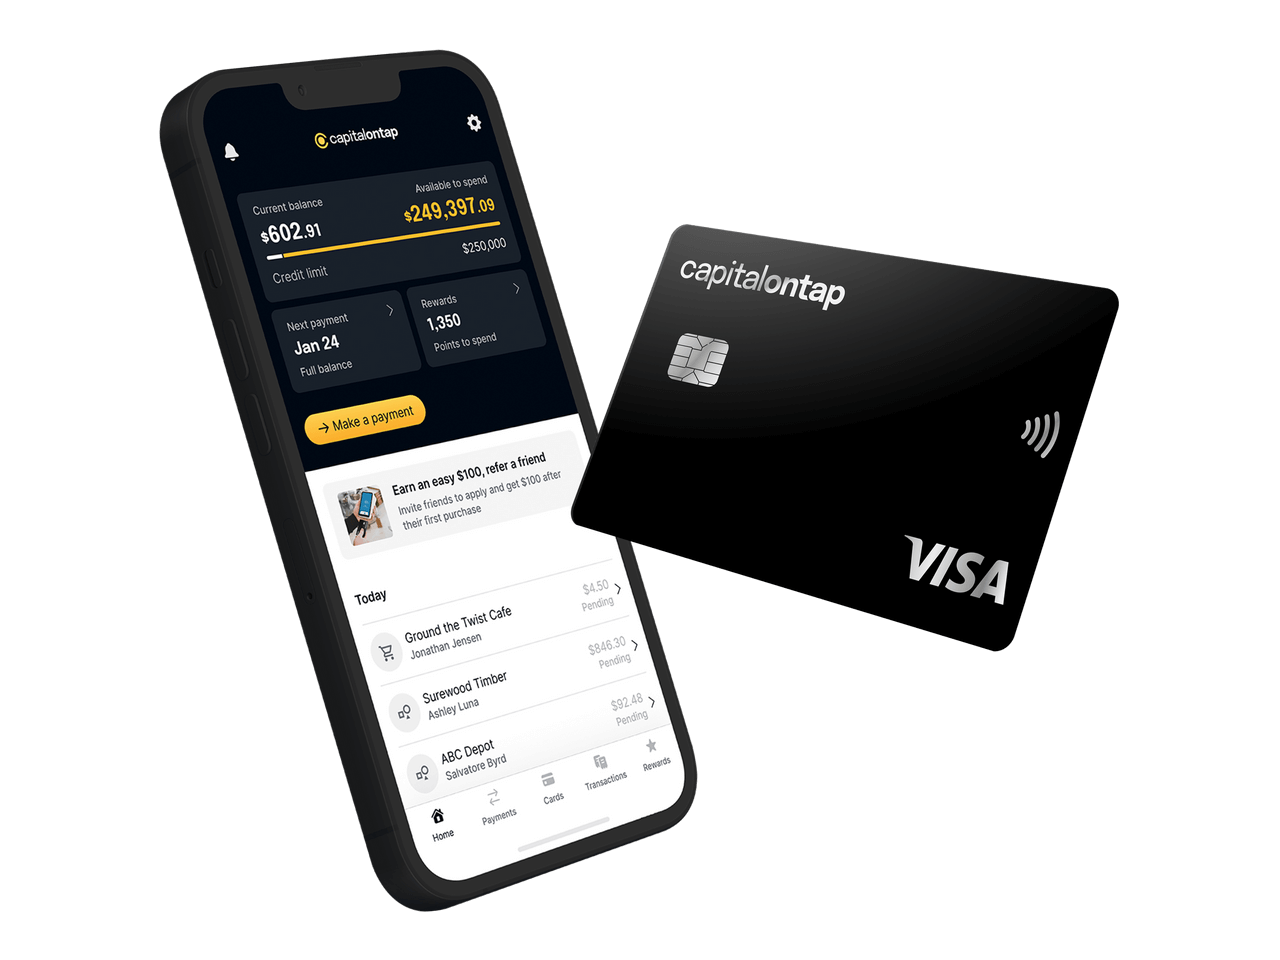
Now, the Capital on Tap mobile app does have a 4.9-star rating in the iOS marketplace, which is impressive, as it outshines some of the biggest banks. 

Capital on Tap app

If you use the app, you’ll be able to make card payments, manage your cards and rewards, create virtual cards, and view transactions. 

Capital on Tap Complaints

All business funding options come with their fair share of complaints. So, what do the people say is wrong with Capital on Tap’s offer? Only a small percentage of Trustpilot reviewers have had a bad experience. Here’s a summary of what unsatisfied cardholders and others don’t like. 

  • High interest rates
  • Poor customer service 
  • Excessive junk mail
Capital on Tap reviews Reddit

Note that most complaints mention the company’s advertising in one way or another — most do not mention the actual product. Keep in mind that financial “pre-approvals” are rarely a guarantee that you will qualify for a funding offer. 

Capital on Tap Competitor Overview

Capital on tap is popularly compared to Amex and Capital One’s business credit card offers. So, let’s take a look at how they stack up side-by-side. For this case, we’ll compare the Capital on Tap Founder Rewards Card with Amex Blue Business Cash and Capital One Spark Business Cash specifically. 

CashbackAnnual FeeIntro OfferAPRFX Fees
1.5%$0$200 w/$15K Spend in 3 Mos9.99% to 34.99%0%
2% for 1 Year
1% Ongoing
$0$250 to $500 w/$5K to $10K Spend 3 Mos13.24% to 19.24%2.7%
2%
$95
$500 w/$4.5K Spend in 3 Mos

Deferred Annual Fee
20.99% Variable0%

All of the cards come with their own set of pros and cons. For example, a Capital on Tap card comes with the lowest possible interest rates (9.99%) on regular spending, but can also be the highest (up to 34.99%). Spark Business Cash and Amex Blue Business offer the best introductory offers (Up to $500 with qualified spending). And, neither the Founder Rewards card nor the Amex Blue Business card will charge an annual fee. 

You’ll need to decide which features are most important to you. 

Frequently Asked Questions

What credit score do you need for capital on tap?

Capital on Tap has no set credit score requirement, but applicants with a score of at least 670 have a higher chance of qualifying. 

Is capital on tap a soft pull?

Yes. While a Capital on Tap card does require a personal guarantee, the credit pull is soft, so it will not impact your personal FICO score to apply. 

Does capital on tap require a personal guarantee?

Yes. If your business fails to make payments to Capital on Tap, you will be personally liable for the debt. 

Is capital on tap a charge card?

No. Capital Tap is a credit card, with a revolving line of credit. 

Which credit bureaus does Capital on Tap report to?

Capital on Tap reports payment history to Experian business.

Business Credit Card - $100 sign up bonus

Apply now - takes 2 minutes and it will not impact your credit score. Your Capital on Tap business credit card will arrive within 4 days of approval!

Apply Now
Lasso Brag

Conclusion: Is Capital on Tap Legit? 

From what I can tell, the Capital on Tap offer stacks up well against the competition and offers some decent benefits for a business in the right position. As you know, it’s not your only option. While it’s not my absolute favorite business credit card, it’s definitely one that I refer a lot of my coaching clients to check out. 

If you want to learn how you obtain $100K in business credit in as few as 30 days, join Business Credit Workshop today.

Ramp Credit Card Review: Is This the Corporate Card for Your Business?

By Joe

Ramp Card Review

If you’re on the hunt for the best funding and cash flow options for your business, traditional banks may not be your best bet right now. Lately, we’ve been writing about some of the most popular, alternative corporate card offers. When researching the top credit cards for startups, Ramp (a fairly new player in the game) ended up near the top of the list. While we weren’t surprised, that’s when we realized we should take a closer look and share our findings. 

This is what we’ll cover here: 

  • What is a Ramp Card?
  • How Can Ramp Help You Save?
    • Unlimited Staff Cards With Smart Spending Limits
    • Zero Fees & 1.5% Cash Back on Spending
    • $175K in Ramp Partner Rewards
  • Will You Qualify for a Ramp Corporate Credit Card?
  • How Does the Ramp Card Stack Up Next to Competitors?
  • Conclusion

Read on to learn more. 

What is a Ramp Card? 

A Ramp card is a corporate credit card designed to help businesses save money. By offering a free corporate card with rewards.

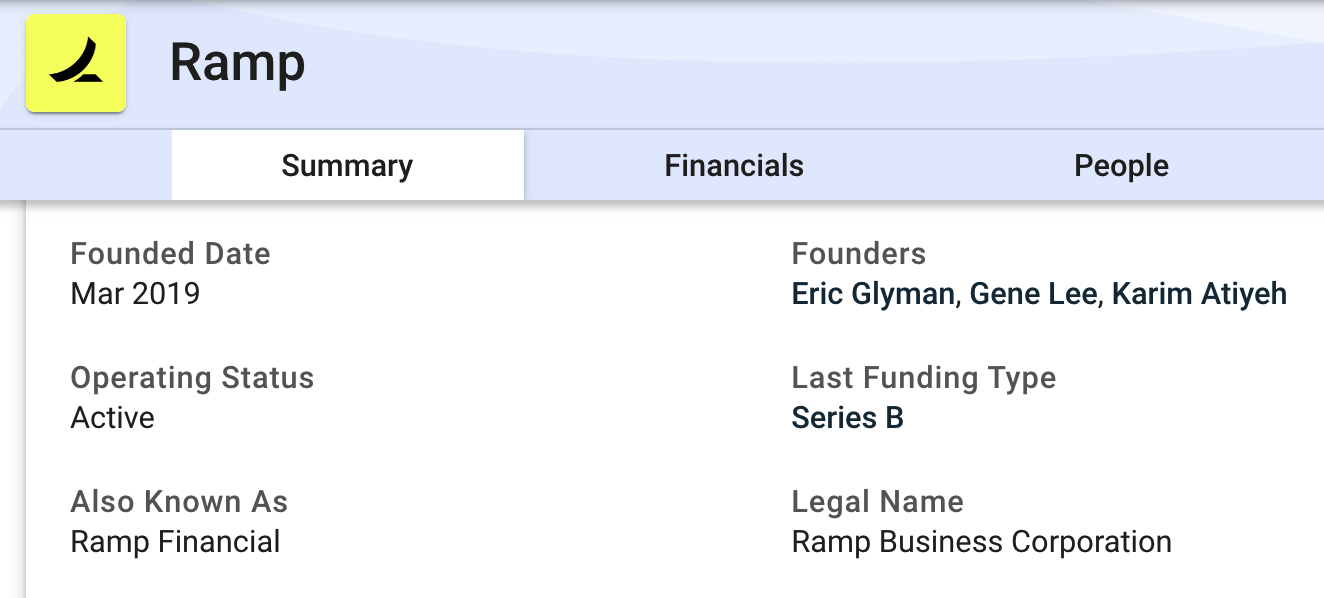
Ramp, aka Ramp Financials, aka Ramp Business Corporation, was co-founded in 2019 by Eric Glyman, Gene Lee, and Karim Atiyeh. All three co-founders main current C-level management positions at the company.  

Ramp credit card Crunchbase

While the company hasn’t been around as long as some of its competitors, the leadership team has notable experience in the financial industry. CEO, Eric Glyman, and CTO, Karim Atiyeh, also co-founded Paribus, where current CPO, Gene Lee, was a software engineer. Paribus was acquired by Capital One, where the trio stayed on staff until they launched Ramp. 

 Recommended: 7 Best Cash Back Corporate Cards to Explore

How Can Ramp Help You Save? 

In my opinion, Ramp rewards rank up there with the Brex card and other corporate credit cards. Here’s a summary of what you get if you go with Ramp for your business. 

Ramp Rewards

Unlimited Staff Cards With Smart Spending Limits

Do you want to enable multiple staff members to use your credit, but not sure how you can limit spending appropriately? If so, Ramp has you covered. If you qualify for the corporate credit card offer, you can take advantage of as many staff cards as you need. Plus, you can set spending limits on each card. 

Not only can you set limits, but the card’s algorithm identifies opportunities for savings. For example, you may be paying for duplicate subscriptions, missing cash back, or have a lower pricing plan available through one of your software vendors — Ramp will analyze spending and alert you to opportunities like this, which is a unique and invaluable perk. 

Zero Fees & 1.5% Cash Back on Spending

First, let’s look at the fees you don’t have to pay: 

  • Foreign transaction fees.
  • Late fees.
  • Interest fees.
  • Annual fees.
  • Costs per card. 

Take a look at your current credit cards and figure up how much you’re paying for the above fees and think about whether it’s time to make the switch. Other coporate credit cards like Brex and Divvy offer zero fees; they also offer cash back. So, it’s smart to weigh your options.

Now, in the case of Ramp, the cash back is 1.5% on everything. So, if you spend $500K per year, you’ll earn $7.5K in cash back alone. While this may not sound as impressive as 7X points on certain spending like the competition, Ramp’s offer opens your company to earn on any type of spending instead of specific costs like restaurants or software. 

$175K in Ramp Partner Rewards 

If you utilize offers from any of Ramp’s partners, you need to consider how much you can save by using their card to pay for services and subscriptions. Cardholders who leverage all offers can save up to $175K. While that’s not necessarily likely, you can save hundreds and even thousands with specific vendors. 

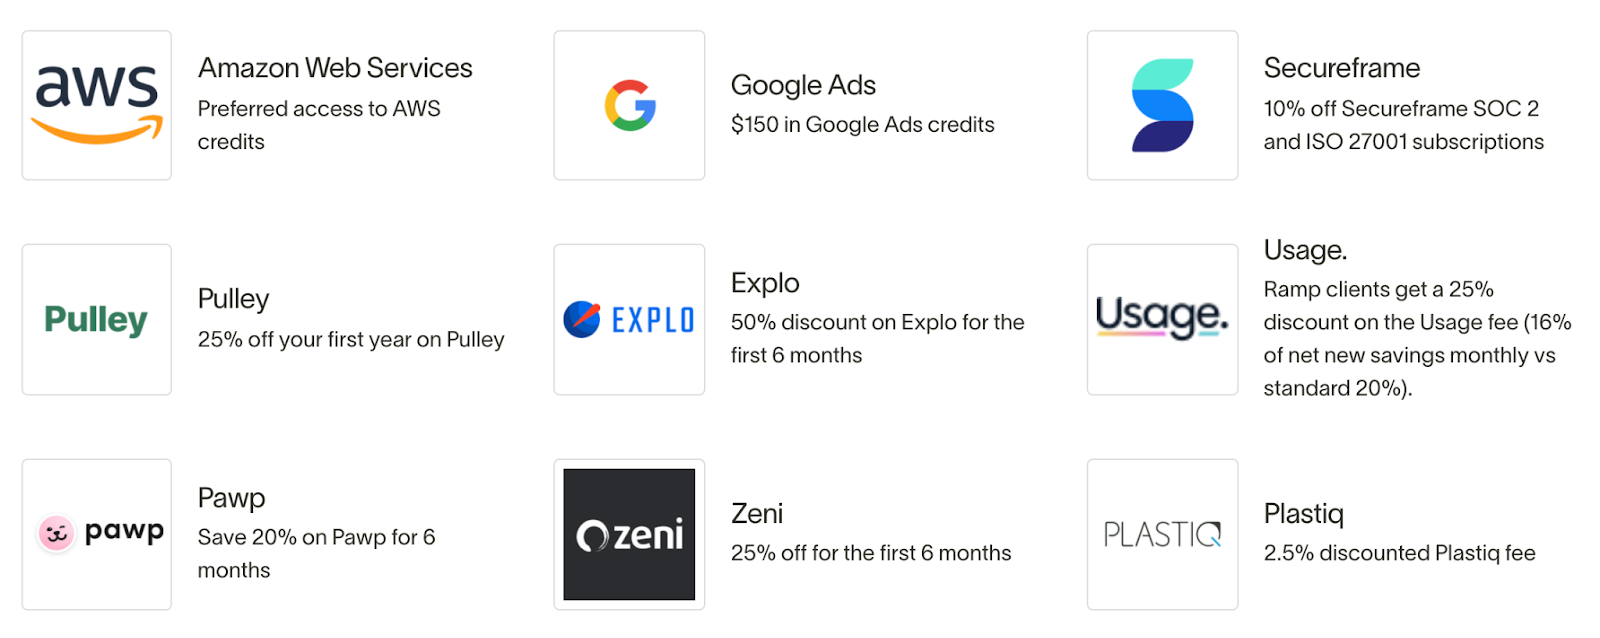
For example, if you use your Ramp card to pay for AWS, you can get preferred access to credits. You’ll also be able to take advantage of $150 in Google Ads, 25% off your first year of Pulley equity management, and a 2.5% discount on Plastiq bill pay. 

Ramp Partner Rewards

Some more impressive offers are $15K and $30K credits with Triplebyte software engineering and Datadog cloud monitoring respectively. If you’re using either of these services, that alone might make choosing a Ramp card more than worthwhile. 

Will You Qualify for a Ramp Corporate Credit Card? 

Ramp card requirements aren’t super transparent. But, we do know that there are no credit checks or founder guarantees. So, you don’t have much to lose by applying to find out.

From what I can tell, Ramp underwriting seems to be based on the following factors: 

  • How many employees your business has
  • Your company’s average monthly card spending 
  • Whether or not you have over $250K in your business account

I can almost guarantee that if you do not have at least $250K in your business account at this time, then you won’t qualify for the card. In this case, another card might be a better fit. 

Recommended Reading: 

  • What are the Best Business Credit Cards for Startups?
  • 3 Best Credit Unions for Small Business Banking 
  • The Best Business Credit Cards

How Does the Ramp Card Stack Up Next to Competitors?

Before you make a decision on whether or not to apply, it’s a good idea to take a peek at Ramp side-by-side with its top competitors. So, here’s what we know. 

Ramp vs Brex vs Divvy vs Stripe

The benefits you get with Ramp are competitive with other similar corporate cards from Stripe, Brex, and Divvy. 

Conclusion

If you can qualify for a Ramp card, the only reason you might not want to would be to go with a competing corporate card. Otherwise, this is a fantastic offer. Now, if you can’t yet qualify, but want to learn how to get up to $100K in business credit within as few as 30 days, you’re probably a good candidate for our credit courses and coaching. Join Business Credit Workshop today to start learning.

Brex Card Review: Is This Corporate Card Offer Too Good to be True?

By Joe

I mentioned Brex in my last post about the best business credit cards for startups (high on the list, I might add). That’s when it dawned on me that we haven’t covered the Brex corporate card offer yet. And, this is something you need to see. 

The two top highlights for the Brex card are that there is no personal guarantee (underwriters don’t look at your personal credit score) and it’s free. Not every business will qualify for one of these cards. But, if you are able to, it’s definitely worth looking into. 

This is what’s in store: 

  • Brex Card Overview
    • Who Owns Brex?
    • Brex Account Offers
    • How Does Brex Make Money?
  • Brex Card Rewards Summary
    • Up to 30K in Introductory Bonus Points
    • Earn 1-8X Points Per Dollar on Spending
    • $150K Worth of Partner Perks
    • Built-In, Real-Time Expense Tracking
    • Consultant, Accountant, & Travel Agent Connections
  • How to Qualify for a Brex Card
  • Brex vs Ramp vs Stripe vs Divvy
  • Final Thoughts

Keep reading to learn everything you need to know about the Brex corporate card and find out if this offer is too good to be true or right for your business.

Brex Card Overview

The Brex card, issued through the Brex financial operating system, is a corporate credit card, which means it’s designed for businesses with multiple employee spending (in this case, tech, life sciences, and eCommerce companies). However, corporate cards don’t have to be used by several staff members. In fact, some applicants qualify for a single corporate card with a $1K limit for individual business spending. 

Brex corporate credit card

Most corporate cards don’t require personal guarantees. Instead, applicants whose companies demonstrate a high probability to repay the funds are extended credit. The Brex card works the same way. So, if you own a company and you have a low FICO score, it shouldn’t affect your ability to obtain credit. 

Now, the most impressive feature of this card is that it’s free. Cardholders pay no annual fee, no interest, and no other costs. 

 Recommended: 7 Best Cash Back Corporate Cards to Explore

Who Owns Brex? 

Brex was co-founded by Henrique Dubugras and Pedro Franceschi in San Francisco, California. The pair previously co-founded the online payment system, Pagar.me before selling it in 2016 to Brazilian credit card processor, Stone. According to Forbes, the pair moved to the bay area to attend Stanford before dropping out after just a few months. Entrepreneurship seems to favor them. 

Brex Account Offers

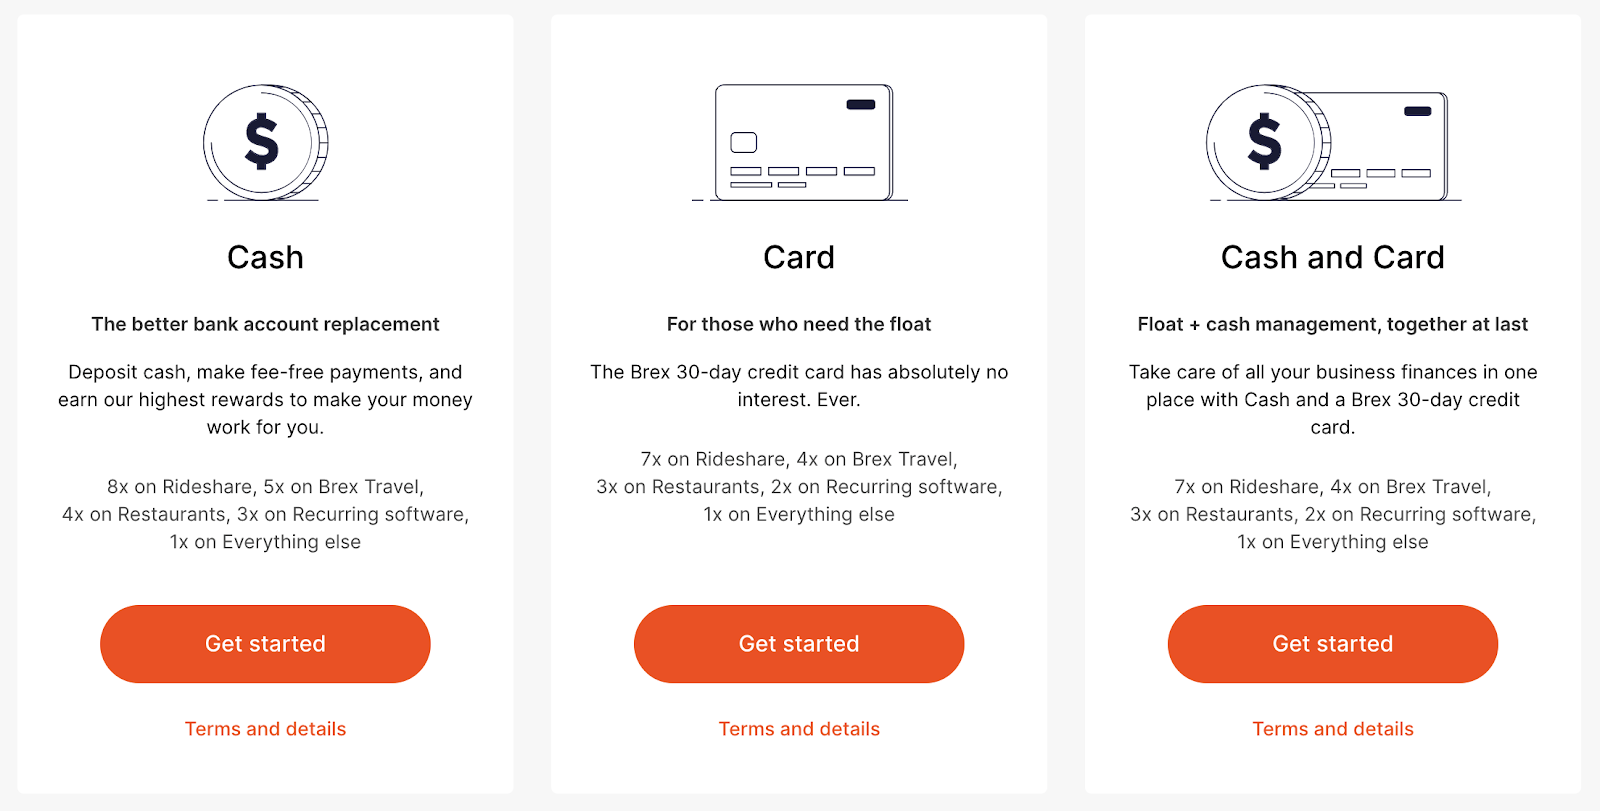
When you sign up for a Brex account, you will have the option to apply for three different offers: Cash, Card, or Cash & Card. 

Brex Cash vs Brex Card Accounts

A Cash account is similar to a checking account, though the website explicitly states that it is not a bank account. Still, you can use a Brex Cash account to deposit money, make payments without fees, and earn rewards. Using your “daily pay” account, you can earn rewards on all your spending.

Essentially, Brex offers a way to get funding with net 30 terms, which means your account must be paid in full at the end of each month. Traditionally, credit cards offer users the ability to make a “minimum payment” each month. Brex terms are a little different. So, if you’re looking for a way to fund a large purchase and pay it off slowly over time, this card isn’t for you. 

But, you can use a Brex Card to boost cash flow while you earn rewards. Furthermore, the company claims that tech companies specifically can get 10-20X higher limits than they will with other cards. 

Cash & Card is the best of both worlds. Boost your cash flow with the Brex Card while you handle business transactions through Brex Cash. 

How Does Brex Make Money? 

Rather than charge interest rates and annual fees, Brex earns a percentage from merchants for each transaction. Cardholders are offered attractive rewards on spending with partners and given incentives to pay daily rather than monthly like most other credit cards. Shorter payment terms for users frees-up cash flow for the brand, allowing them to offer attractive terms.  

Brex Card Rewards Summary

Above, I mentioned that Brex caters to tech, life sciences, and eCommerce businesses. While being in one of these industries isn’t a requirement to obtain credit, those that fall under this umbrella will benefit the most. In addition to being a free card with no fees or interest, here are the benefits of using Brex for your business spending.

Up to 30K in Introductory Bonus Points

Brex is the only corporate card with zero fees that currently offers an introductory bonus. Just for linking your new Brex credit card account to Brex Cash, you will earn 20K bonus points. In addition, when you spend $3K on your card in the first 3 months, you’ll earn 10K bonus points. 

Earn 1-8X Points Per Dollar on Spending

All Brex spending has the potential to earn you points. 

With a Brex Cash account, you can earn 8X points on rideshare apps, 5X points with Brex travel partners, 4X on dining at restaurants, 3X on recurring software subscription payments, and 1X on everything else.  

And, with a Brex Card, you can earn 7X points on rideshare apps, 4X points with Brex travel partners, 3X on dining at restaurants, 2X on recurring software subscription payments, and 1X on everything else. 

Points can be redeemed through Brex travel, via gift cards and cash back, or as statement credit (for cardholders who don’t use Brex Cash). 

$150K Worth of Partner Perks

Brex partners include big names like AWS, Slack, and Google Ads. If you were to utilize all of the savings offered as a Brex cardholder, you could redeem up to $150K in perks. 

  • AWS – $5,000 credit and up to $100,000 in AWS Activate, depending on eligibility
  • Slack – 25% off 12 months of eligible Slack paid plans
  • Carta – 20% discount on first year and waived implementation fees, plus 10,000 Brex Points
  • Zoom – 20% discount on annual Zoom subscription
  • Quickbooks – 40% off your first 12 months of QuickBooks
  • Google Ads – Up to $150 in Google Ads credit
  • Dropbox – Get 50% off on all Dropbox Business, Standard, or Advanced plans
  • Gusto – Get 50% off any plan for 12 months

Note that many of Brex’s competitors offer similar perks. 

Built-In, Real-Time Expense Tracking  

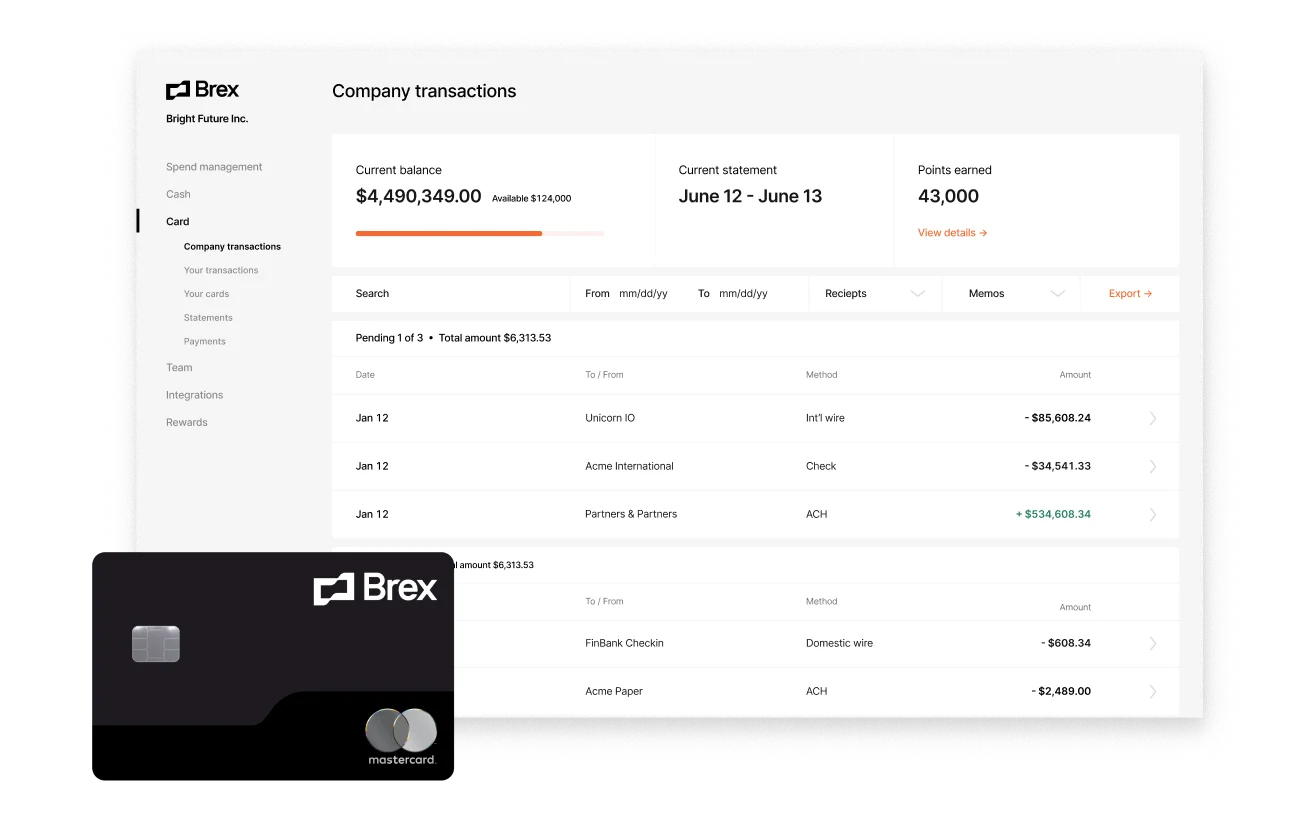
Essentially, Brex expense management tools enable you to put your expenses, including employee spending, on autopilot. Upload receipts and the software will match spending in your accounting platform. You may be able to cut reconciliation time by up to 50% and spend up to 75% less time chasing receipts. 

Brex Expense Tracking

You can also set up monthly spending limits for each card, which can give employees more flexibility and management more time freedom. 

Another key feature of Brex expense management are the virtual cards. Divvy has a similar offer, which means your employees don’t have to wait for a physical card to be issued. The technology seems to be a hit amongst users. 

Consultant, Accountant, and Travel Agent Connections 

When you book your trips via Brex Travel, you can access experienced corporate travel agencies for free. Travel agents are available 24/7 to help you redeem points and book with 30% to 60% discounts. 

Looking to hire an agency to help you with consulting services? Brex cardholders can access a directory of vetted agency and accounting partners that you can leverage to help you scale your business. Take advantage of the opportunity to work with service providers experienced with Brex expense tracking. As far as I know, other credit card companies don’t offer anything like this. 

How to Qualify for a Brex Card

Brex isn’t super transparent about their qualification terms, but here’s what we do know: 

  • You must have an EIN for a US-based business
  • You must have a business bank account
  • You will need to verify your identity with photos of your government-issued ID

Furthermore, here’s what we think, based on anecdotes from existing cardholders. 

  • You should have $50K to $100K in the bank at all times

If you bank with a smaller community bank or credit union, you will need to upload your two most recent bank statements. The process is quick and painless, but applications can take up to 15 days to review. 

Brex vs Ramp vs Stripe vs Divvy

Now, here’s how Brex stacks up side-by-side with its top competitors: Ramp, Stripe, and Divvy. 

Brex vs Divvy vs Ramp vs Stripe

Each of the corporate cards is free and comes with some alluring rewards. Some of the key value indicators when we compare are that Brex is the only card that seems to offer an intro bonus. Next, in order to qualify for Stripe’s corporate card, you must use their software and either wait or ask for an invitation. 

Final Thoughts

Brex has an impressive corporate card offer for tech, life sciences, and eCommerce companies. If you can qualify and you’ll take advantage of the rewards, I’m sure it’s worthwhile – you can’t really go wrong with free. But, if you aren’t able to qualify, you have plenty of other options. Want to learn how to obtain $100K in business credit in 30 days? Join Business Credit Workshop today! 

What are the Best Unsecured Business Credit Cards for Startups?

By Joe

business credit cards for startups

New business owners often fund their ventures with personal capital, which includes savings, loans, and credit cards. Without established business credit, companies sometimes have a hard time finding business credit cards they can qualify for. I’m often asked about the best business credit cards for startups, so I wanted to do a write-up to share with everyone. 

Here’s what’s covered: 

  • Startup Business Credit Basics
    • Secured vs Unsecured Credit Cards
    • Corporate vs Travel Rewards vs Cashback Card
    • What is the 5/24 Rule?
  • Best Corporate Credit Cards for Startups
  • Best Travel Rewards Credit Cards for Startups
  • Best Cashback Credit Cards for Startups
  • Final Thoughts

Keep reading to learn everything you need to know. 

Startup Business Credit Basics 

A business has its own credit scores, different from FICO scores. Before a business can qualify for a credit card, it must build business credit, which is separate from personal credit. A company must form their business in a way that sets them up to become “business credit ready,” network with banks, establish business credit profiles, then build small tradelines of credit. When they make the right moves, they can generate high credit scores and qualify for large lines of credit. 

Companies without business credit can get credit cards, but are often limited by personal credit. 

Secured vs Unsecured Credit Cards

There are several categories of credit cards available for businesses and individuals: secured and unsecured. Secured credit cards are designed for companies and people who want to build or repair credit by reporting responsible payment history. Unfortunately, secured credit cards require a deposit, essentially allowing you to spend your own money in exchange for reporting on-time payments to credit bureaus. 

On the other hand, unsecured credit cards extend deposit-free lines of credit to companies and individuals based on existing merit. Unsecured cards are typically available to those with moderate to excellent credit history. The higher the credit score, the more card benefits and higher limits a business or person can usually qualify for. Here, we’re going to talk only about unsecured credit cards for startups. 

Corporate vs Travel Rewards vs Cashback Card

Companies usually turn to credit cards to manage cash flow. Another top reason to use credit cards for business spending is to save and earn. Ideally, you want to pay off your card balance each month to avoid interest payments and cash in on the available discounts and rewards. 

  • Corporate cards help large companies manage employee spending and offer savings with high profile partners. 
  • Business travel cards are designed for companies that want to earn travel rewards like airline miles, free hotel stays, and more.
  • Business cashback cards provide rewards in the form of points that can be redeemed as cash to a bank account, applied toward a statement balance, or redeemed for other items. 

So, when you explore which card is right for you, first decide which you’re more interested in. Then, proceed through this list accordingly. 

What is the 5/24 Rule?

One last item to note before we move on to explore the cards listed here is Chase’s “5/24 rule.” All card issuers have provisions that, if not met, can immediately disqualify you from the ability to obtain a card. Chase has a black and white rule that if you have opened five or more personal credit cards within the past 24 months, you cannot open a new credit card account with them. 

So, if you want to apply for a Chase credit card, start with them before you move on to other banks. 

Best Corporate Credit Cards for Startups

Typically, corporate cards have lower risk to you as the business owner because they require no personal guarantee. But, they can be trickier to qualify for. Qualification terms are instead based on a company’s financial track record and proven ability to pay back funds. Right now, there are some impressive names in the corporate card game; here are the four top corporate cards for startups, none of which charge fees. 

1. Brex 

brex card

Read more about the Brex corporate card. 

2. Stripe 

stripe corporate card

Read more about the free Stripe Corporate Card’s cashback rewards. 

3. Divvy

divvy card

Read an in-depth Divvy credit card review before you apply.

4. Ramp

ramp card

Learn more about the Ramp card. 

Best Travel Rewards Credit Cards for Startups

Now, let’s take a look at the best startup business credit cards for the best travel rewards and sign on bonuses that I know of. 

1. Amex Marriott Bonvoy Businesses

marriott bonvoy business card

Read a Marriott Bonvoy Business credit card review and comparison.

2. Barclay American Airlines AAdvantage Aviator Business

Barclay AAdvantage Business Card

Learn more about Barclay’s AA Biz card. 

3. Bank of America Alaska Airlines Business

BoA Alaska Airlines Business card

Learn more about the BoA Alaska Biz card. 

4. CitiBusiness American Airlines AAdvantage Platinum