• Home
  • Free Funding Guide
  • What We Offer
    • Products
    • Services
    • Free Guide
  • About Us
  • Contact
  • Sign Up

  • Ask Joe Any Question!
  • Business Credit Cards
  • Business Line of Credit
  • Topics

Bluevine Review: Free, High Yield Small Business Checking! Are They Serious?

November 17, 2022 By Joe

Bluevine Business Checking Review

I’ve been really excited to review Bluevine since so many people have asked me about it. This is a free small business checking account offer that earns 50X the national average interest with no monthly fees or minimum deposits. Of course, they can’t possibly cater to every business owner… Can they?

That’s what we’ll explore here.   

  • Bluevine Business Checking Overview
    • Bluevine’s Line of Credit
    • Bluevine’s Bill Pay
  • Bluevine Company Overview
  • Frequently Asked Questions
  • The Verdict: Is Bluevine Legit?

Now, let’s fire away!

Bluevine Business Checking Overview

Bluevine offers free, single-user business checking accounts that can earn 2% interest on up to $100K with qualifying activity. There are no minimum deposits or NSF fees, which is incredible. 

One standout feature that Bluevine doesn’t seem to advertise much is the ability to give your bookkeeper access to your account without sharing your dedicated login information — this can come in handy!
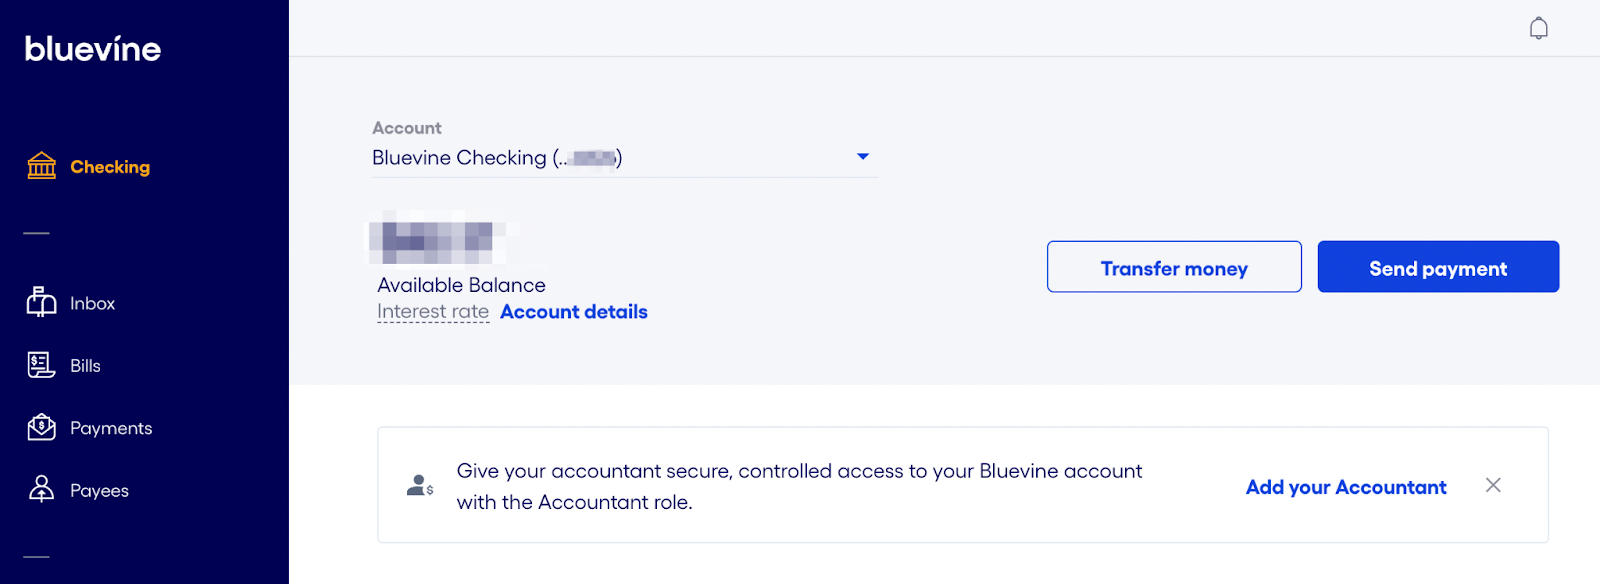
Bluevine login

To qualify for interest accrual, account holders must meet at least one of the following requirements: 

  • Spend $500 with your Bluevine debit card in a calendar month OR
  • Receive or deposit $2.5K via ACH, mobile deposit, wire transfer, or via a merchant payment processor (not ATM). 

Bluevine uses the MoneyPass ATM network, with 37K locations nationwide. So, if you’re super rural, you may not be able to access a surcharge-free ATM. In this case, you would pay $2.50 for every ATM transaction. 

While most services are free online and within the MoneyPass network, Bluevine charges $4.95 for all cash deposits made at an ATM. This might be steep for a business that makes multiple cash deposits, but online businesses wouldn’t be affected much. 

There are no limits to the number of transactions that can be made in a Bluevine account, but cash transfers are limited to $1.5K per transaction, $2K per day, and $7.5K per month.  

ProsCons
Free checking with no monthly feesNo joint accounts
2% interest on balances up to $100KMinimum requirements to collect interest
No minimum deposits$7.5K maximum monthly cash transfers
Sub-accounts with dedicated account numbers$2.50 fee for out-of-network ATMs
Unlimited, fee-free transactionsNo branch access (ATM-only)
No NSF fees$4.95 fee for cash deposits

So, a Bluevine checking account seems like a fantastic option for certain businesses. The offer seems to be catered to accountants, bookkeepers, freelancers, and other service businesses that primarily conduct digital transactions. 
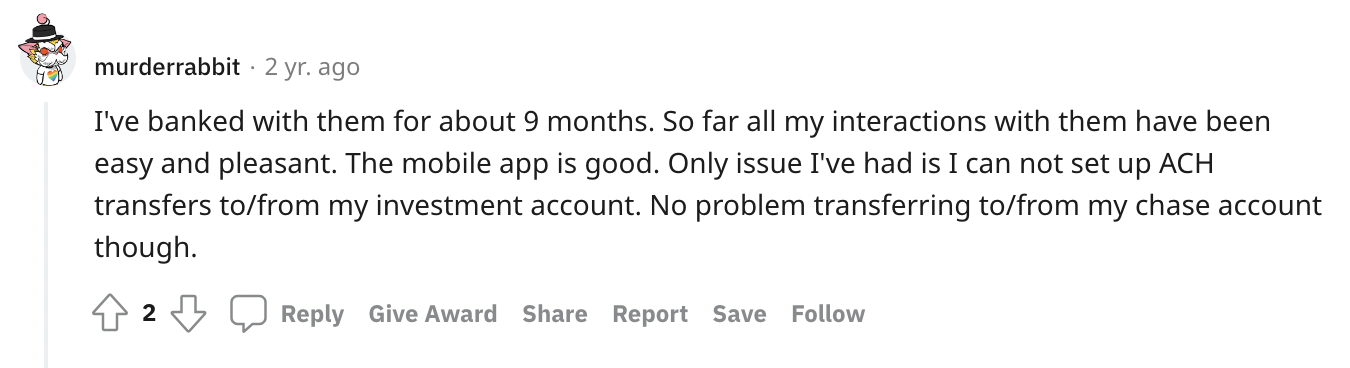
Bluevine review Reddit

Naturally, there are businesses that Bluevine isn’t going to work well for. 

For one, partnerships might not be a great fit, since only one account holder is permitted for each account. Next, super rural businesses without easy access to MoneyPass ATMs might end up paying quite a bit in surcharges (assuming you would need ATM access).  Finally, this offer is simply not well-suited for businesses that need to deposit more than $7.5K in cash monthly, as that’s where Bluevine maxes out. 

Fun Fact: Bluevine checking is powered by Coastal Community Bank, which is also the servicer for the X1 credit card. 

Bluevine’s Line of Credit

Bluevine offers lines of revolving credit up to $250K, with rates as low as 4.8%, serviced by Celtic Bank.  Once approved, you can get access to funds quickly. Note that the advertised interest rate is “simple interest,” which means compounding isn’t accounted for, and the low 4.8% is based on a 26-week repayment plan. 
Bluevine loan

You can apply for a line of credit online in minutes. Bluevine uses Plaid to connect to your bank account and analyze cash flow. To qualify, you must have been in business in the U.S. for at least 6 months, have at least $10K in monthly revenue, and have a personal FICO score of 625 or higher. 
Bluevine reviews

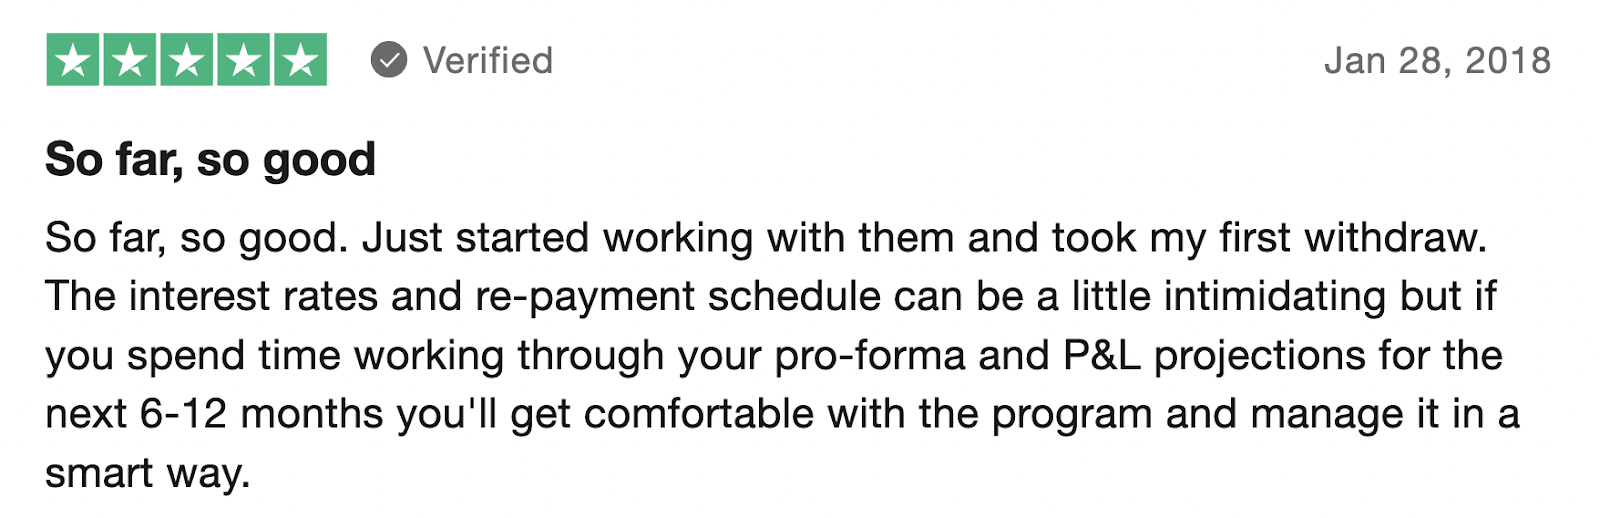
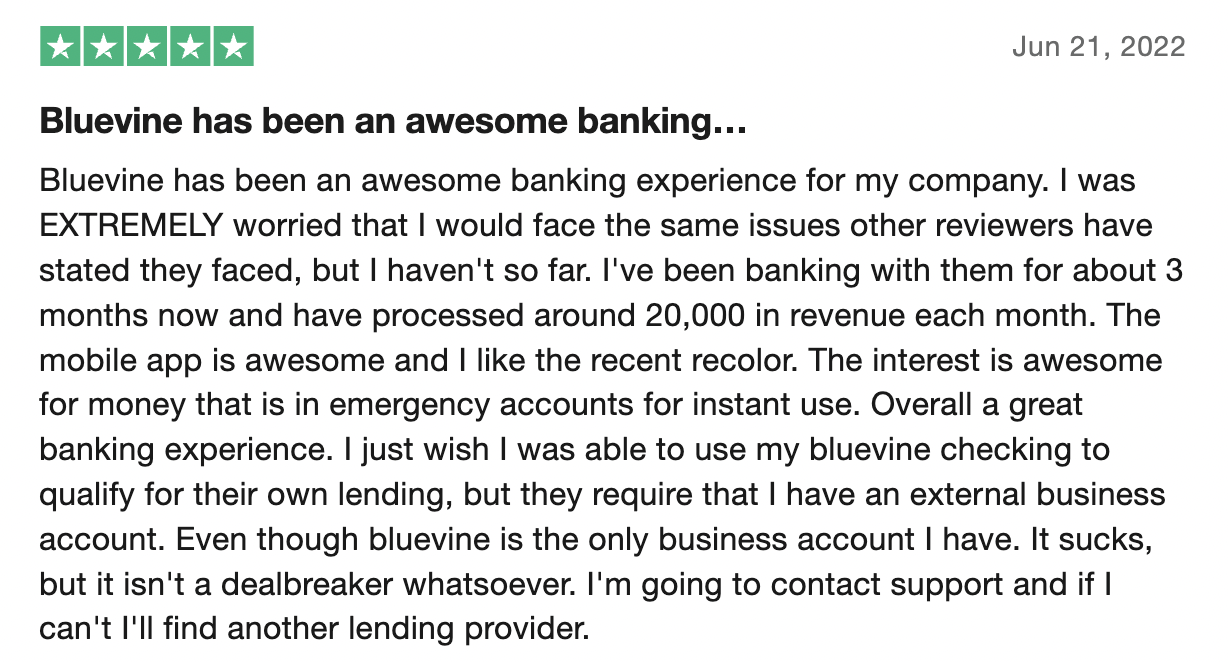
According to at least one satisfied lendee, you cannot apply for a Bluevine loan using your Bluevine checking account, which seems a little wonky. Hopefully, they will update their lending platform to work with their own bank at some point in the future. But, as of now, there doesn’t seem to be a workaround. 

If you apply and are approved for a Bluevine line of credit, you can choose to wire transfer funds for access within a few hours and a fee of $15. Alternatively, you can choose an ACH deposit, which can get your funds to you as soon as the next business day (however, in some cases this can take a few days). 

Recommended: Meet Celtic Bank: A Humble Brand With an Enormous Reach 

Bluevine’s Bill Pay

If you have the banking information for your payees, you can add them manually in your Bluevine account dashboard. I feel like online check services like Checkbook.io might be easier to use, since you only need an email address and name to deliver payments. But, bill pay is a nice feature for any bank account. 

Moreover, you can connect Bluevine to Quickbooks to view income and expenses from your checking account dashboard. 
Bluevine Bank

Bill pay funds are held by Silicon Valley Bank, a trusted FDIC-insured institution. All-in-all, I think Bluevine’s bill pay options are competitive. 

Bluevine Company Overview

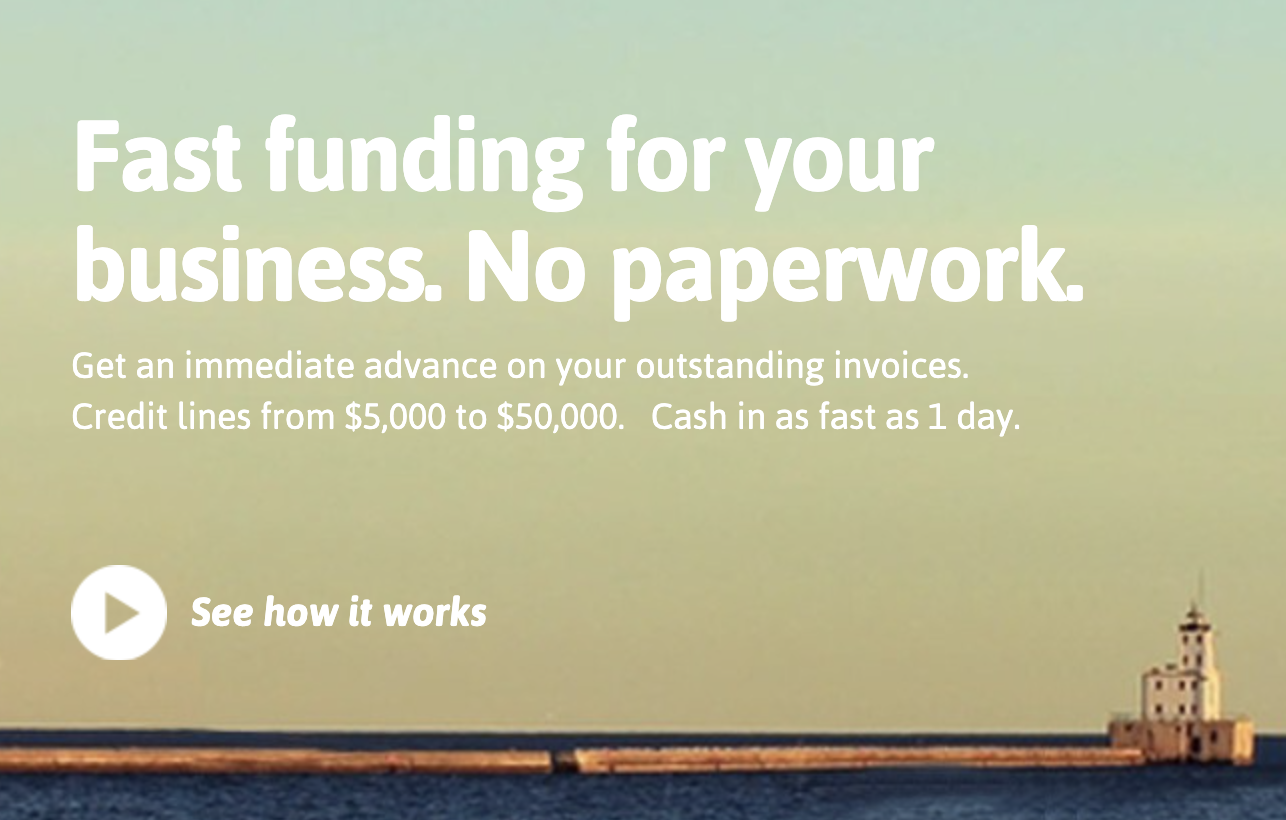
Bluevine Inc. was co-founded in July 2013 by Eyal Lifshitz, Moti Shatner, and Nir Klar in Redwood City, California. The company started as an invoice factoring company, offering capital loans from $5K to $50K with “cash in as fast as 1 day.” They exited the factoring game and announced their free checking account offer in early 2020.  

I found this gem from 2014 in the Wayback Machine: 
Bluevine capital

Frequently Asked Questions

What happened to Bluevine?

There are a few rumors floating around that Bluevine is not accepting new applications. This is not the case — Bluevine is accepting new applications for lines of credit and new bank accounts. The rumor that they were closed may have started when PPP funding ended, as Bluevine was an approved lender for the Paycheck Protection Program. 

Is Bluevine accepting new applications?

Yes! Despite the hearsay, Bluevine is currently accepting applicants for business checking accounts and lines of credit. 

Does Bluevine run a credit check?

Yes, Bluevine runs a credit check for applicants looking for a line of credit. For approval, applicants must have a FICO score of 625 or higher. 

Does Bluevine do a hard pull?

For businesses organized as an LLC, Bluevine does not do a hard pull, so applicants’ credit will not be negatively impacted. 

What bureau does Bluevine pull from?

Bluevine has a partnership with Experian, Equifax, and Dun and Bradstreet, and reports on-time payments to all three. 

Does Bluevine affect credit score?

Since they report payments to business credit bureaus, on-time payments to Bluevine will have a positive impact on your credit score.  

Does Bluevine charge a fee?

The only fees Bluevine charges for checking accounts are ATM fees for cash deposits. Most ATMs within the MoneyPass network are surcharge-free for Bluevine account holders. 

How much can I withdraw from Bluevine?

The maximum amount you can withdraw from Bluevine is $1,500 per transaction, $2,000 per day, and $7,500 per month

Is Bluevine a direct lender?

No. Bluevine’s lines of credit are serviced through Celtic Bank. 

Who owns Bluevine?

Bluevine was founded by Eyal Lifshitz, Moti Shatner, and Nir Klar, who still currently own and operate the company. 

What credit score does Bluevine use?

Bluevine uses applicants’ FICO scores to determine creditworthiness. 

Is Bluevine FDIC insured?

Bluevine checking accounts, loans, and bill pay funds are FDIC insured through the respective banks that service these offers (Coastal Community Bank, Celtic Bank, and Silicon Valley Bank).  

How many customers does Bluevine have?

As of February 2022, Bluevine had 450K customers. 

The Verdict: Is Bluevine Legit? 

Yep! This business checking offer is legit, and I would go as far as to say that I recommend it… for some business owners, namely accountants, freelancers, and other entities that conduct mostly digital banking. However, if you move a lot of cash through your company, or you have more than one owner, Bluevine probably isn’t your best option. 

As far as Bluevine’s line of credit, I do trust offers from Celtic Bank, but I’m not the biggest fan of these fast-cash-type offers that use the owner’s personal FICO score to determine creditworthiness. Instead, I like to teach business owners to obtain credit using their business credit. What I do like is that Bluevine reports payments to D&B. So, with responsible payments, a Bluevine loan can help you build business credit.  

If you’d like to learn how to obtain up to $100K in business credit in as few as 30 days, join Business Credit Workshop today.
A Full OnDeck Review: All You Need to Know About This Business Funding Offer 

November 10, 2022 By Joe

OnDeck Review

In the past, we’ve reviewed business funding offers from Fundbox, Lendio, and Kabbage. Until now, OnDeck (a company with a similar offer) has somehow slipped through the cracks. It’s vital for business owners who seek funding to know about all of their options. So, I want to provide a breakdown of OnDeck’s business lines of credit and term loans. 

Here, I’ll share everything you need to know about the offers from OnDeck so that you can decide if this is the right option for your business funding needs. 

Here’s what’s “in the hole:” 

  • What is OnDeck?
    • OnDeck Term Loans
    • OnDeck Lines of Credit
    • OnDeck Requirements
    • OnDeck Interest Rates
  • What to Expect When You Apply with OnDeck
    • OnDeck Partners
  • Frequently Asked Questions
  • The Verdict

Now, batter up! 

What is OnDeck? 

OnDeck is a small business lending company that promises to make the process fast and easy. The company has an A+ BBB rating, and has funded $14 billion to small business owners in the U.S., and they have a 4.8 TrustScore on TrustPilot. In a nutshell, they provide what seem like trusted term loans and lines of credit. 

So, are they legit? Let’s find out!

OnDeck Term Loans

OnDeck’s core offer is a term loan for small businesses. Term loans are set-amount, fixed-rate, loans with specific repayment schedules.

Here, you can get $5K to $250K loans with up to 24-month repayment terms. Automatic payments for an OnDeck term loan will be made daily or weekly. 

OnDeck Lines of Credit

The secondary offer from OnDeck is a line of credit. Lines of credit are a pre-set borrowing limit with revolving terms that can be used at any time. 

Here, you can get $6K to $100K lines of credit with 12-month repayment terms. Automatic payments for an OnDeck line of credit will be made weekly. 

OnDeck Requirements

As with most business funding options, you will need to meet minimum requirements to successfully obtain funding. With OnDeck, you must have at least one year in business, a consumer FICO score of at least 625, $100K annual business revenue, and a business bank account. 

Next, you must also operate outside of OnDeck’s list of restricted industries. Any business in the following industries are prohibited from obtaining funding through the platform:

  • Adult entertainment
  • Drug dispensaries
  • Firearms vendors
  • Government  
  • Non-profit and civic organizations 
  • Public administration
  • Horoscopes and fortune telling
  • Lotteries, casinos, and gambling
  • Gaming
  • Money service businesses
  • Rooming and boarding houses

Finally, funding through OnDeck is unavailable in Nevada, North Dakota, or South Dakota. 

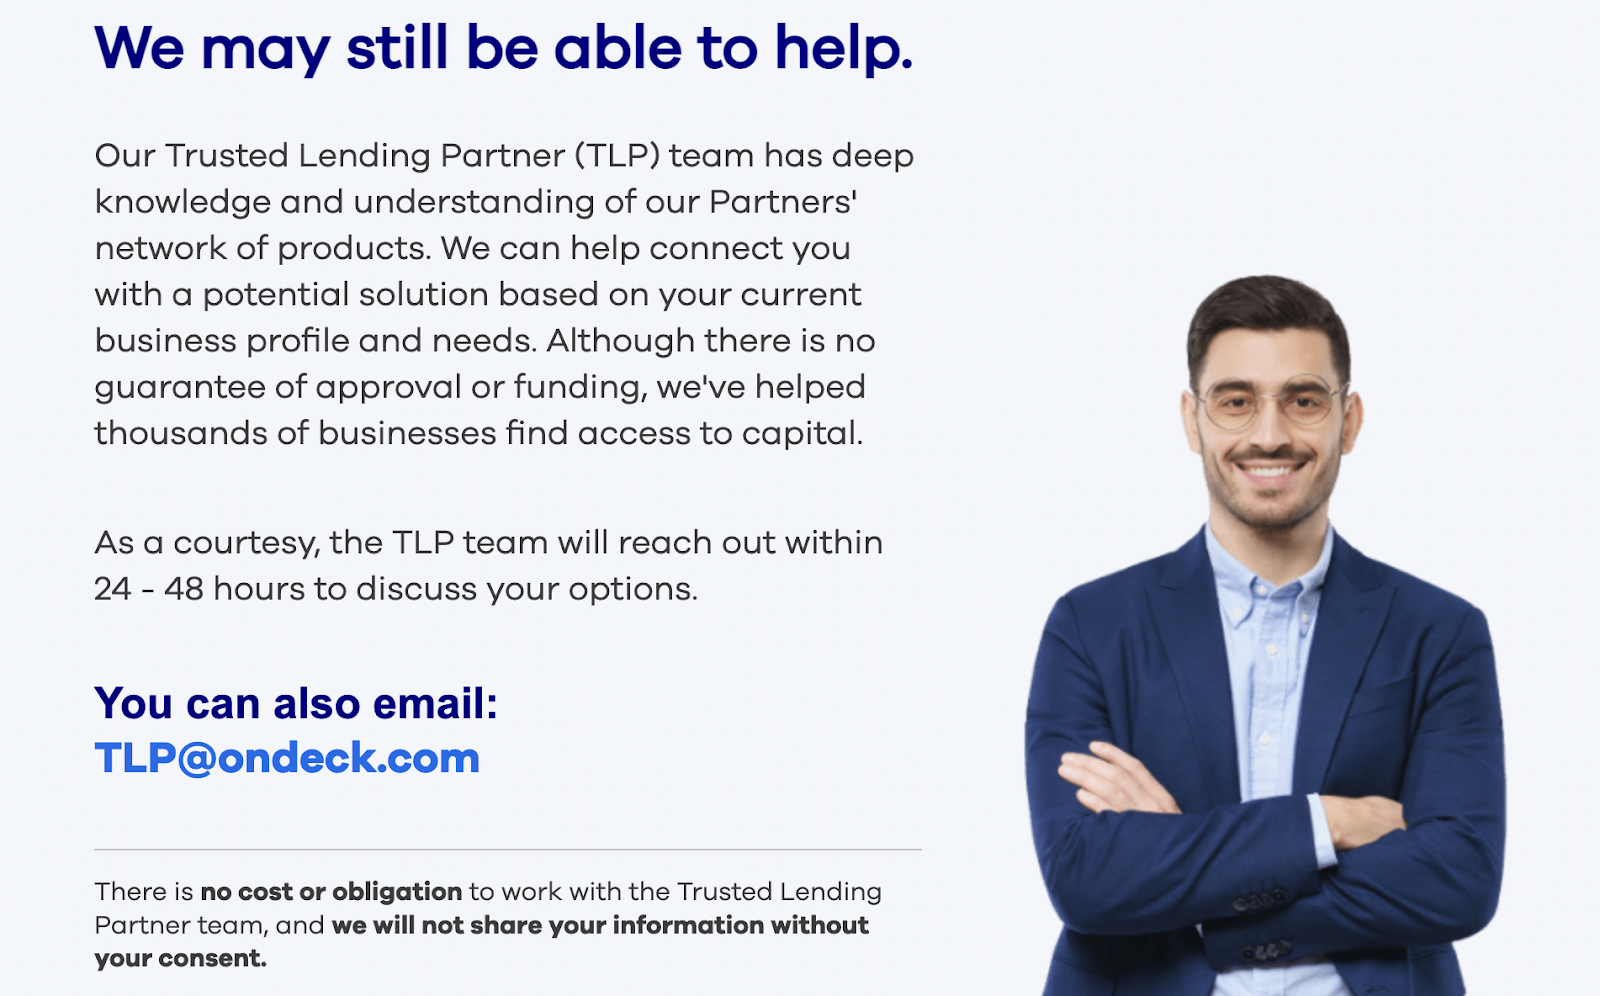
When the minimum requirements are not met, anyone who applies through the platform will be referred out to OnDeck’s Trusted Lending Partner team. 

OnDeck.com login

OnDeck Interest Rates & Fees

I have said this before, but I can’t say it enough. ALWAYS read the fine print. 

OnDeck Interest Rates

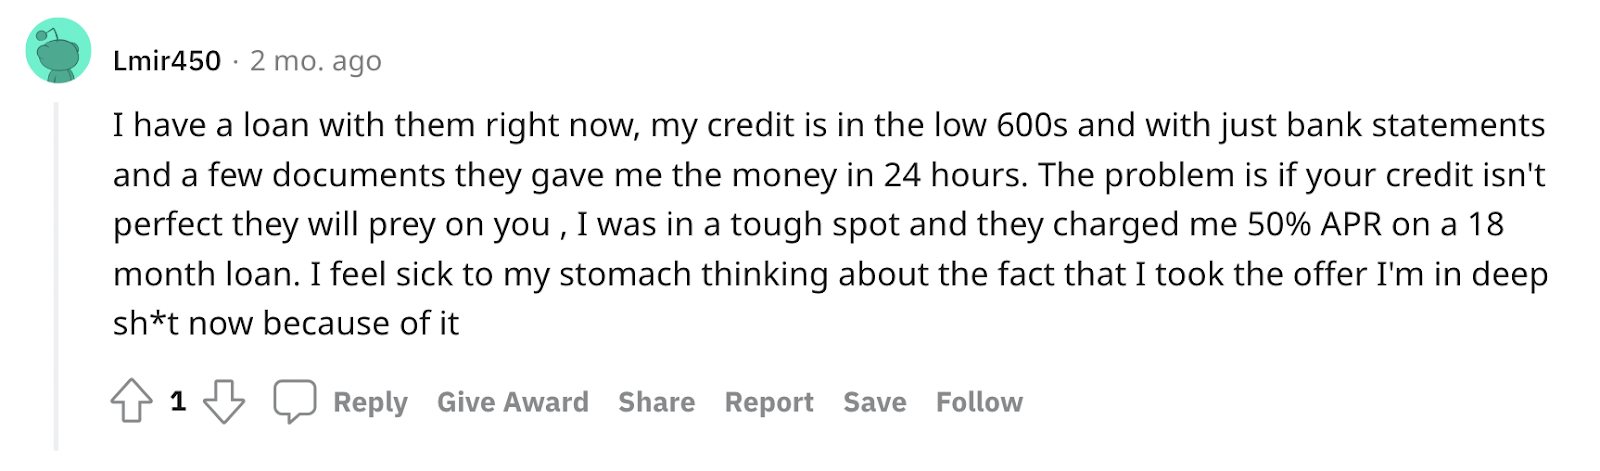
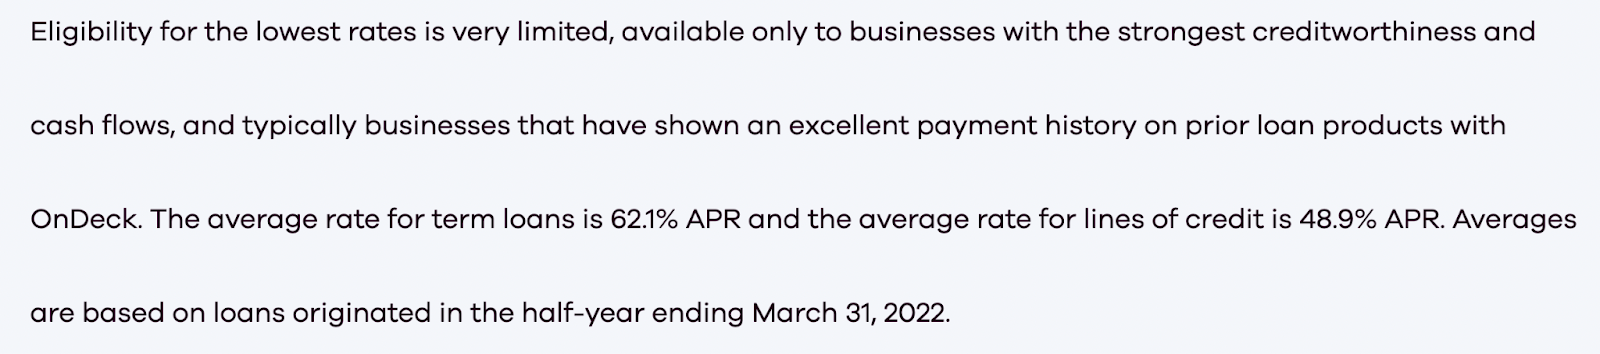
The average rate for OnDeck’s term loans is 62.1% APR and 48.9% APR for lines of credit (ouch!). This means that if you carry a balance, you’ll be paying a ton of interest, and could get yourself into trouble if you’re not careful. 

OnDeck reviews Reddit

Let me break this down assuming 50% interest on a $100K, 12-month OnDeck loan: Your monthly payment would be approximately $10,309.82 and your total interest would be $23,717.90 at the end of the year. 

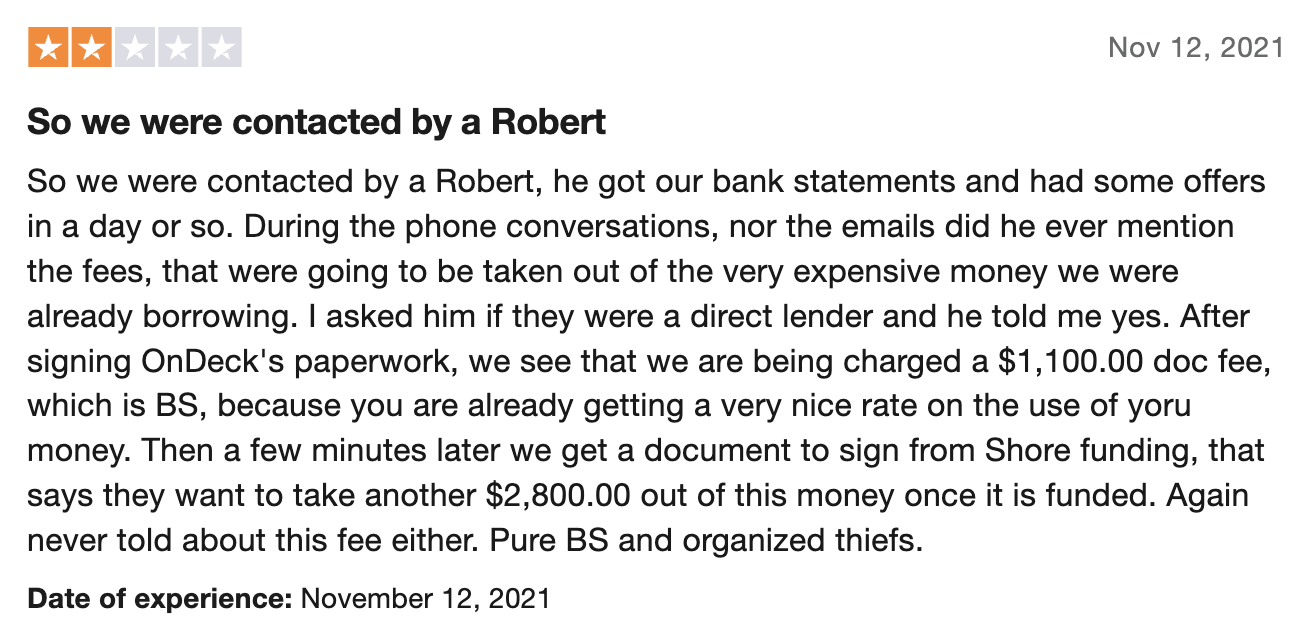
This is without considering fees, which, according to several sources, are not disclosed until closing, and can run in the thousands of dollars. 

OnDeck costs and loan fees

I think that if you have the revenue to qualify, you would be much better off looking into a free corporate credit card from Stripe, Torpago, Ramp, Divy, or Brex. And, if you aren’t there yet, you would do well to build your business credit. 

Recommended: 41 Companies That Help Build Business Credit

What to Expect When You Apply with OnDeck

If you choose to apply for funding with OnDeck, the first thing you’ll be asked is how much funding you think you need. If your needs fall within the $5K to $250K range, there might be an offer for you here. 

Next, they want to know how soon you need the funding. If you have 72 hours or you are looking for funding a month out, this will help determine how the company proceeds with your application. 

Then, they need to know what you need the money for. You’ll be provided with a space to describe how you will use any funds you obtain. 

From there, you’ll share your contact information with OnDeck and choose a password to create an account. You may be asked to enter a referral code (this will ensure that the person who referred you gets any bonus or incentive that they’re entitled to). So far in the process, the application process is simple. 

After that, you will need to share information about your business: legal entity name, address, phone number, EIN, gross annual revenue, and average bank balance. Finally, you will be asked to enter identifiable info about yourself, including your social security number (which lets me know they may do a hard pull to your personal credit. Update: We have been told by OnDeck that they do soft pulls, even after approval, but please verify this information). 

When you submit your application, OnDeck will immediately analyze the information you submitted, and attempt to make a pre-approval decision. 

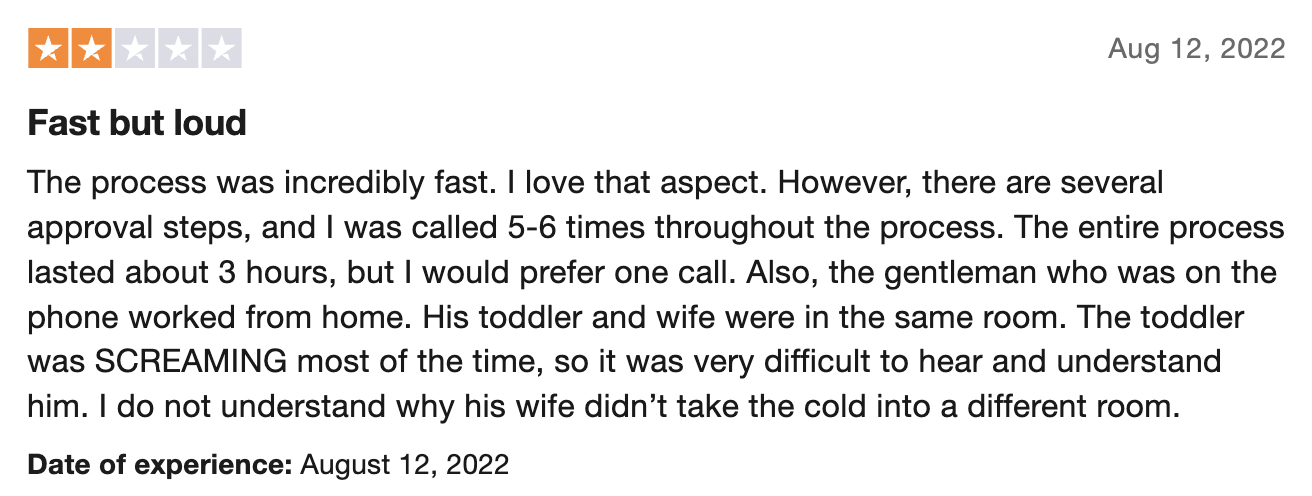
OnDeck reviews

Once pre-approved, be prepared to submit documentation to complete the loan process. Then, you can receive your funds or credit line within as few as 24 hours. Then, after 6 months or so of on-time payments, you may be able to refinance your loan for a lower rate. 

And, if you run into financial troubles, you will be required to pay your loan, possibly without much flexibility (this should be expected with most business financial offers, though some lenders will give you some grace). 

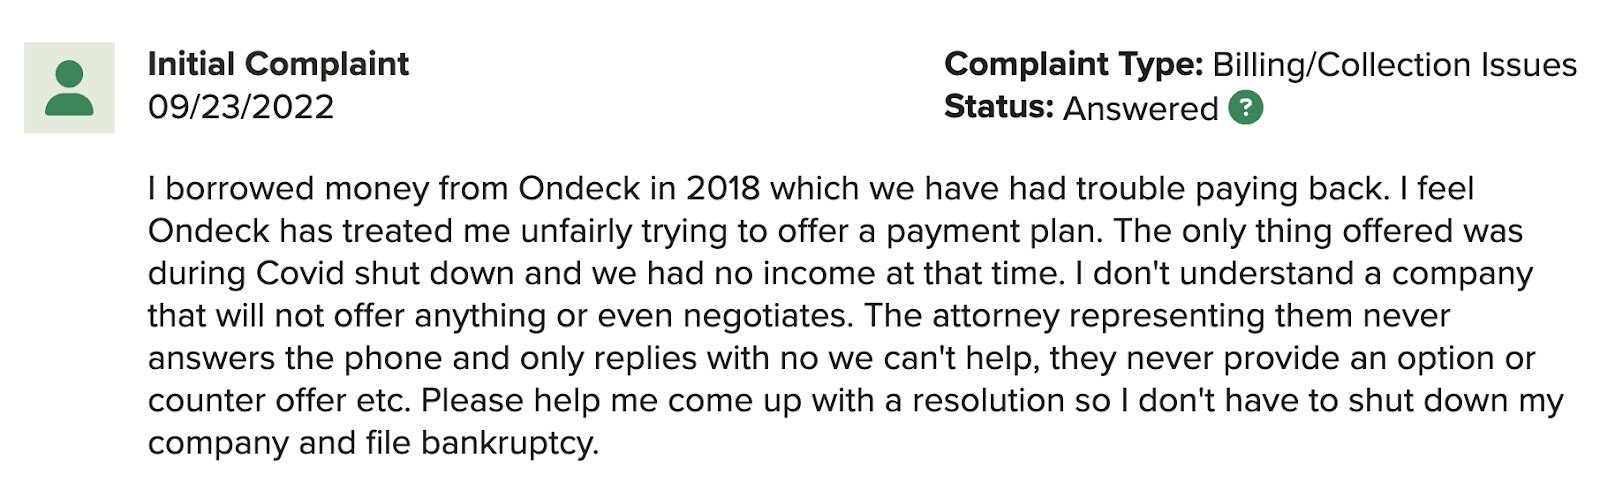
OnDeck reviews BBB

OnDeck Partners

The OnDeck Trusted Lending Partner team can be reached via email at tlp@ondeck.com at any time. But, an unsuccessful applicant will be contacted within 48 hours with offers from partners. OnDeck promises that they do not share your information with partners before asking for your consent. 

So, who is in the partner lineup? 

OnDeck has two types of partners: editorial and financial. 

Editorial partners are essentially affiliates. Anyone with a captive small business audience that might benefit from OnDeck’s offer may inquire. 

Financial partners are sales organizations or direct lenders who want to receive customer referrals from OnDeck. In exchange, OnDeck receives a referral fee. Lending partners must have been in business for at least two years, offer at least $1M in monthly business funding, have a functional, encrypted website, active business insurance, and be based in the United States.

Currently, OnDeck is referring applicants whose businesses are too young for internal financing to BitttyAdvance, who works with businesses as young as 6 months. They do require at least 3 months of business bank statements, a personal credit score of 450 or higher, and at least $5K in monthly business revenue.

OnDeck Partner Offer: BittyAdvance

BittyAdvance offers instant approval and next-day funding, and they have a good TrustPilot score. Before you apply, please do your due diligence — I haven’t had the chance to fully explore this offer yet, and can’t say whether or not I recommend it.

Note: OnDeck also has programs in Australia and Canada.   

OnDeck Company Overview

Originally located in the greater New York area, OnDeck Capital Inc. was founded in 2006 by Mitch Jacobs, the founder and current CEO of Plink. 

In July 2020, the OnDeck was acquired by Enova International, the company that purchased Pangea Monay Transfer in 2021. OnDeck’s home base is now in Chicago. The current CEO is Joe Coughlin. 

OnDeck is a publicly-traded company, and they’ve received a total of $1.2 billion in funding since launch. I would say they are here to stay. 

Frequently Asked Questions

Is OnDeck still in business?

Yes, OnDeck was acquired in 2020, and they are still very much in business. 

Who owns OnDeck?

OnDeck is now owned by Enova International and is publicly traded. 

Is there a minimum credit score for OnDeck?

Yes, OnDeck requires a minimum FICO score of 625.

What is the maximum amount you can borrow from OnDeck?

The most you can borrow from OnDeck at one time is $250K, in the form of a term loan. 

What type of loan is OnDeck?

OnDeck offers both term loans and lines of revolving credit. 

What are the terms for OnDeck?

OnDeck’s lines of credit should be paid in full within 12 months, while their term loans vary with repayment terms of up to 24 months. 

How does OnDeck make their money?

OnDeck makes money by charging loan fees and interest, with early rates in the 50% range. 

For a borrower, what are the benefits of choosing OnDeck?

OnDeck offers fast cash, with funds received within 24 hours. The catch is in the cost. 

Does OnDeck conduct credit checks?

Yes, OnDeck asks for a social security number in the loan application and requires a minimum personal FICO score (625) to approve funding. 

Does OnDeck require a personal guarantee?

Yes, OnDeck required a personal guarantee. Both the business and the owner are liable for any debts incurred. 

Does OnDeck use Plaid?

Yes, OnDeck uses Plaid for read-only access to business bank account information. 

The Verdict

Is OnDeck the home run you’re looking for? 

To be fair here, OnDeck is a legitimate company that seems to have a ton of happy borrowers — in fact, I know some of them personally. They are transparent with their offer, and they seem to be honest lenders (that in itself is a breath of fresh air). I am not one to turn people away from an offer like this… unless something better is available — in this case, better options might be available.  

However, if you won’t qualify for other, more feature-rich business funding options, OnDeck could be exactly what you need to get fast cash flow that helps you grow your business. Just make sure to explore competitors. And, no matter which platform you choose to obtain funding, be sure to do the math before you apply (i.e. How much will a loan actually cost, and can you afford it?).

If you’re interested in learning how you can obtain up to $100K in business credit in as few as 30 days, join Business Credit Workshop today.  
Is Biz2Credit Legit? A Complete Review

November 3, 2022 By Joe

Biz2Credit Review

As I’ve reviewed business credit builders and fintech offers on the rise, I keep seeing Biz2Credit pop up. I’ve seen a lot of advertising, and, most recently, I noticed that prior to linking a bank account to Tillful, their user dashboard links out to funding options from Biz2Credit — this tells me that the brands have partnered. And, since I like Tillful’s secured card offer, I thought I might find something good here as well. 

Now, before I give you the final verdict, it’s important for you to understand what makes me come to the conclusion I have. So, in the meantime, here’s everything you need to know: 

  • What Kind of Company is Biz2Credit?
  • Company Overview
  • How Does Biz2Credit Funding Work?
  • Biz2Credit Loan Requirements & Terms
    • 1. Working Capital
    • 2. Term Loans
    • 3. ERTC Loans
    • 4. Commercial Real Estate Loans
  • BizAnalyzer Overview
  • Biz2Credit’s Disaster Relief Hub
  • Biz2Credit’s Referral Program
  • Biz2Credit Partners
  • Frequently Asked Questions
  • Takeaway: Is This The Best Option for Small Business Funding?

Now, let’s get moving. 

What Kind of Company is Biz2Credit? 

Essentially, Biz2Credit is a business funding platform that helps small businesses get the cash they need (before they finish their cup of coffee). The goal is to provide owners with access to capital using technology to simplify the process. 

Biz2Credit offers a range of services, including working capital, business term loans, ERTC loans, and commercial mortgages. Biz2Credit provides a direct lending option through a subsidiary and partners with third-party lenders, which means they act primarily as an online broker to provide businesses with targeted partner offers. 

I know that one of the lending companies Biz2Credit worked with for PPP loans was Itria Ventures, which is a subsidiary of Biz2Credit. Beyond that, I didn’t find a lot of information about which partner lenders they work with regularly. 

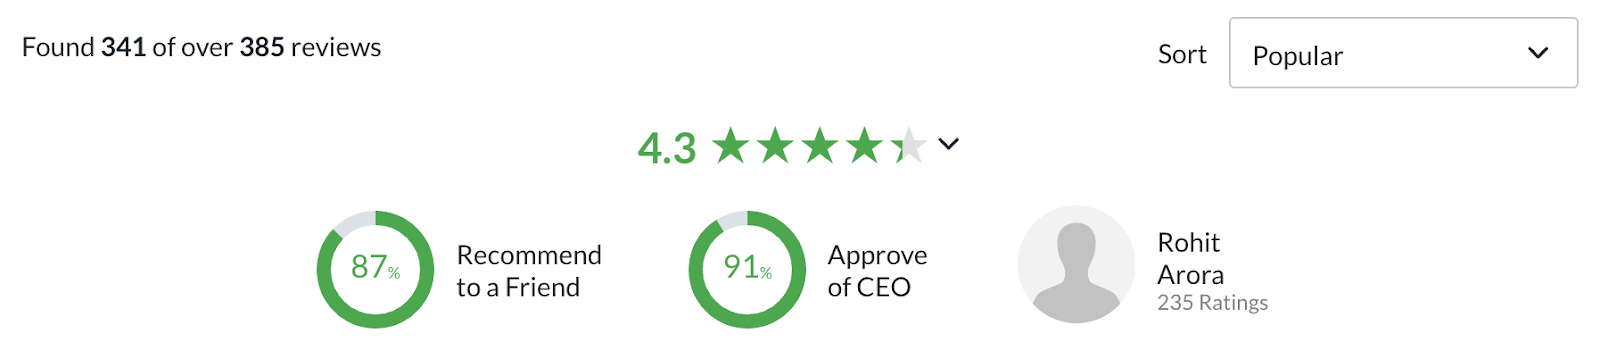
Next, it seems like most people who work for Biz2Credit would recommend a job at the company to a friend, and almost all employees approve of the CEO (according to Glassdoor). So, the company culture is likely great.  

Biz2Credit reviews Trustpilot
Note: Biz2Credit’s offer seems pretty similar to Lendio’s, except that Lendio also provides access to credit cards and acquisition funding.   

Company Overview

Biz2Credit Inc was founded in NYC, in 2007, by Ramit and Rohit Arora. So, the company has been around for over a decade — in that time, they’ve received $387 million in funding. Most recently, in 2019, they raised $52 million in a series B funding round led by Westbridge Capital. This tells me that Biz2Credit is likely here to stay. 

Ramit, the current company president, has ten-plus years of experience in risk management and has worked with notable companies like Citibank and Xerox. And, Rohit, the present CEO, has been a member of the Forbes finance council since 2017. They seem to me like a pair of trustworthy leaders. 

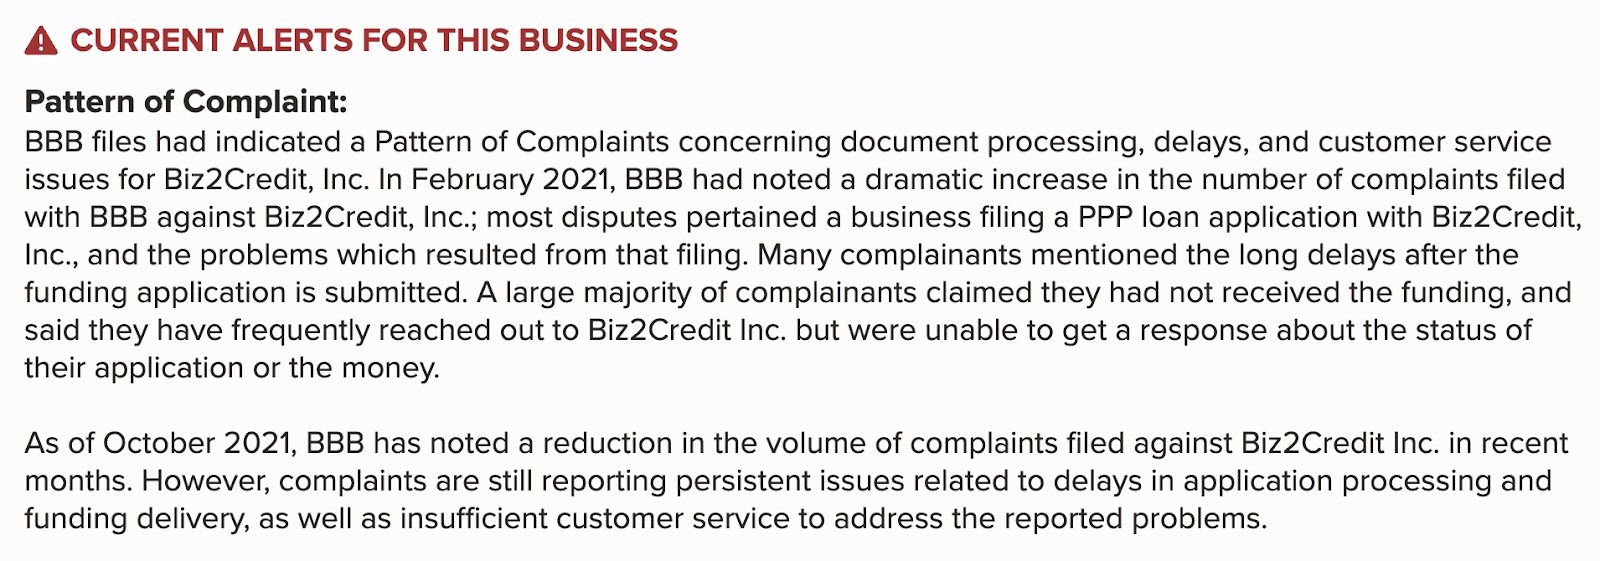
Biz2Credit did receive a lot of poor reviews following PPP loan services, and there was at least one class action lawsuit filed (also re: PPP). But, to be fair, everyone was navigating new territory at that time, and the class action was recently dismissed. 

Biz2Credit Reviews BBB

Not to mention that, despite the onslaught of PPP complaints, the company still has a 4.6 Trustpilot rating, which is pretty difficult for any financial service to maintain. 

You might also like: Torro Business Funding Review: Is This “Zero Hassle” Offer Legit?

How Does Biz2Credit Funding Work?

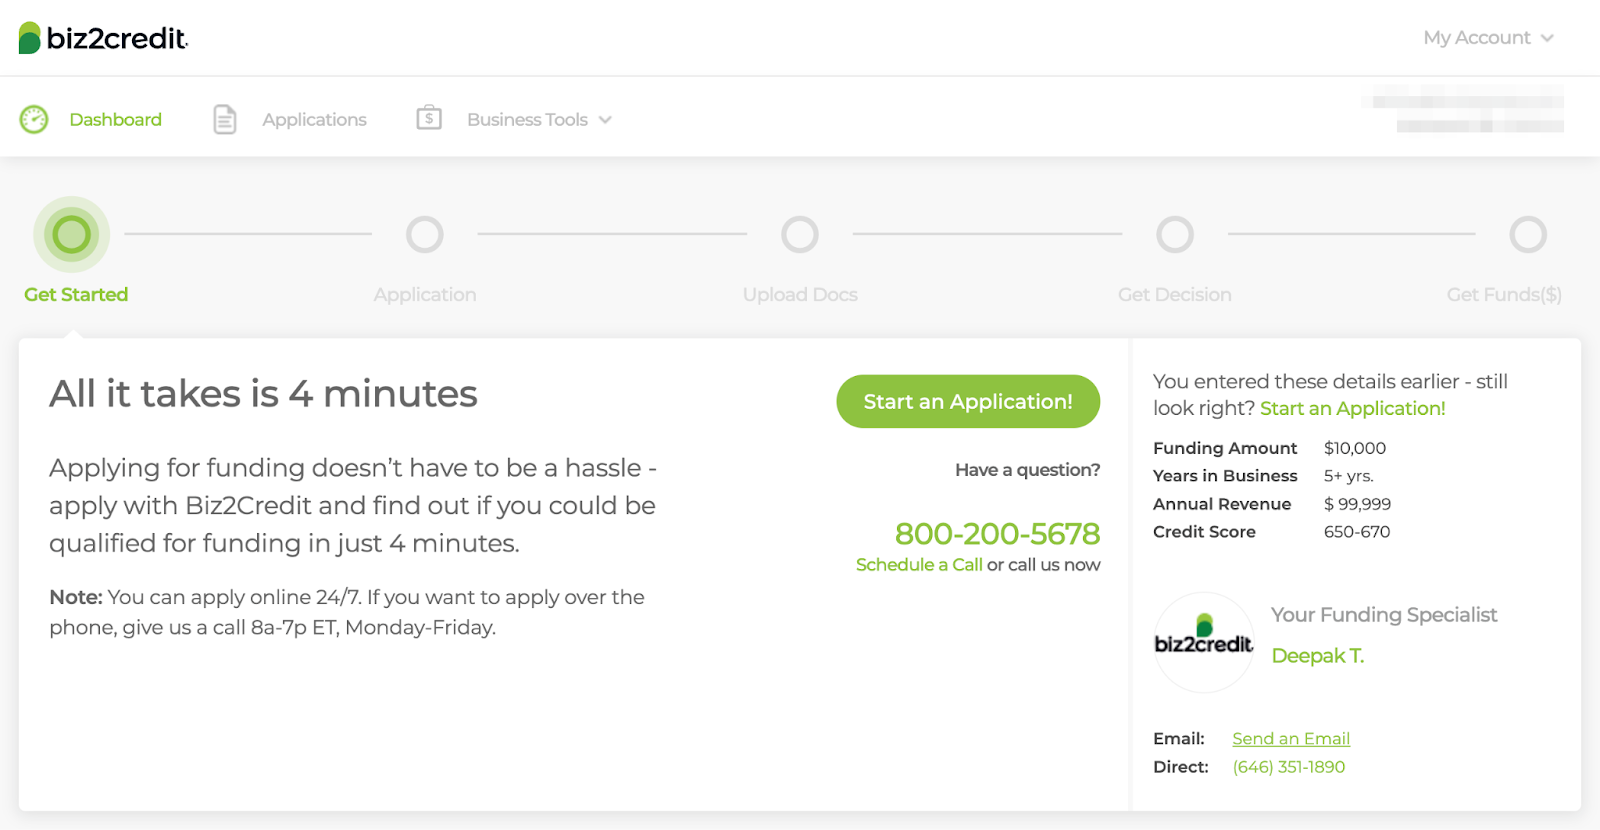
The first thing you can expect, if you decide to apply for funding through Biz2Credit is to “apply, which starts by you creating an account on the platform. You don’t have to move through the application process to create a user dashboard on the account. You do not have to share your social security number to create an account, but a hard inquiry is likely if you choose to follow through with a funding application. 

Biz2Credit Login

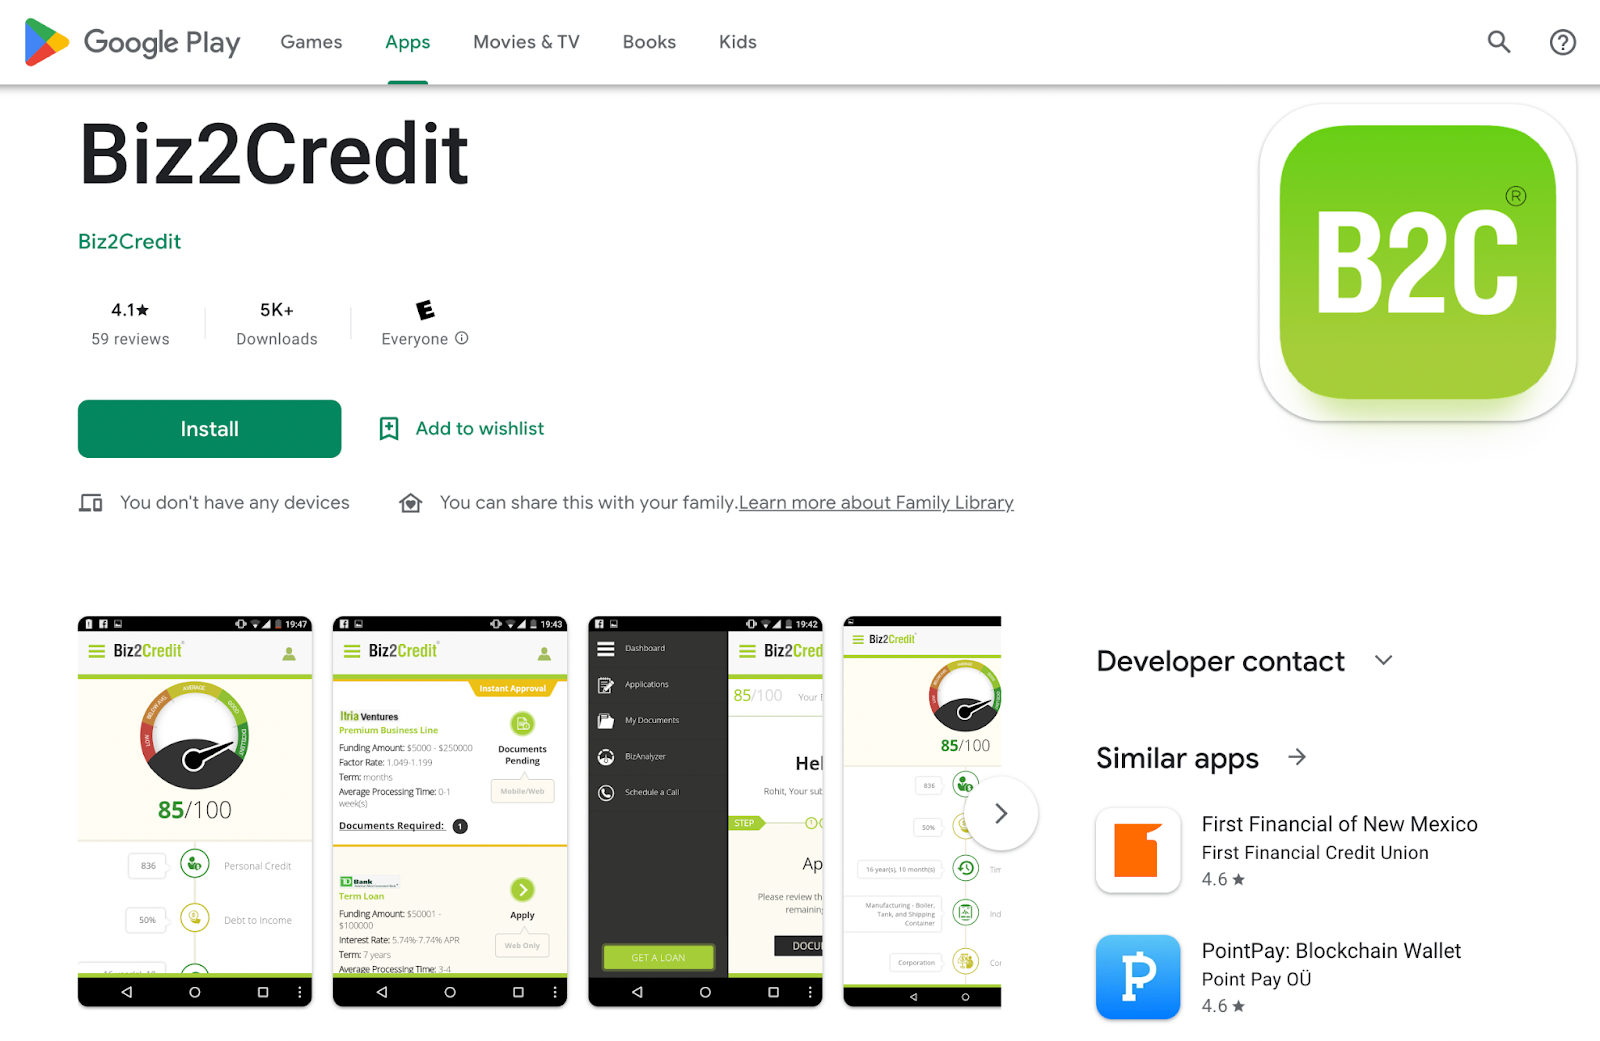
Biz2Credit also offers both iOS and Google Play apps, but neither have been updated in the past couple of years, so I would recommend keeping the application process online or via phone. 

Biz2Credit app

Biz2Credit enables applicants to submit information online or to apply over the phone by calling 800-200-5678. Once an application is submitted and approved, and your bank account is connected via Yodlee, your funds should be deposited directly within 72 hours (or less — many applicants say they got their funds in a day).

Funding requirements seem to be based on a blend of business revenue and your personal credit score, and any financing offer you receive will fall into one of four categories. 

Biz2Credit Loan Requirements & Terms

Requirements vary by funding type, but if your annual revenue is lower than $250K or your personal credit score is lower than 575 for working capital, or 660 for all other loans, you will not qualify. 

If you’re unqualified based on your personal credit score,  learn how to get business credit with just an EIN. But, if you think you may qualify, read on. Below is a quick overview of the terms and requirements for each type of Biz2Credit funding.  

1. Working Capital

Working capital loans (for financing day-to-day expenses) from Biz2Credit start at $25K and go up to $2M+. These loans can be paid back daily, weekly, or bi-weekly, as a percentage of your business receipts. 

Requirements: