• Home
  • Free Funding Guide
  • What We Offer
    • Products
    • Services
    • Free Guide
  • About Us
  • Contact
  • Sign Up

  • Ask Joe Any Question!
  • Business Credit Cards
  • Business Line of Credit
  • Topics

Marriott Bonvoy Business Credit Card Review & Comparison

January 18, 2020 By Joe Lawrence

Anyone interested in building business credit needs to understand all of their credit card options. As of today, Amex is offering 75K bonus points, and this has people talking. Plus, existing Chase cardholders are wondering if they should switch. So, here is a full and honest Marriot Bonvoy Business Amex credit card review led by a quick comparison with the Chase card.

First, What is a Marriott Bonvoy Business Credit Card? 

The Marriott Bonvoy Business credit card is a revolving line of credit offered from Amex or Chase on behalf of Marriott hotels. The card is famous for its travel rewards, which include complimentary stays at the hotels and more. Currently, Amex is the only bank accepting Marriott Bonvoy credit card applications from businesses.

Next, a Marriott Bonvoy Business Credit Card Comparison

marriott bonvoy business credit cards

First of all, the Marriot Bonvoy Business card from Chase is no longer open to new applicants. So, if you’re new to the credit cards and rewards offered by Marriott, you can no longer apply for the Chase card. Still, let’s take a quick look at how these cards stack up against one another.


0% Intro APRCashbackAnnual FeePointsBonus
Marriott Bonvoy Business™American Express® Card
NoPoints redeemable for cash$1256X per $1 spent at Marriott Bonvoy hotels
4X per $1 spent on dining
2X per $1 spent on all other purchases
+More
75K points for spending $3,000
Free night award after the first year anniversary
Free night for $60K annual spending
Marriott Bonvoy Business™ Visa®Credit Card

NoPoints redeemable for cash$953X per $1 spent at Marriott Bonvoy hotels
1X per $1 spent on all other purchases
Elite credit for every $3,000 spent
N/A

The annual fee on Chase’s Marriott credit card is significantly lower, which might make this card sound more appealing to many people. However, with the right amount of spending, your rewards for with the Amex credit card blow the Chase card out of the water. With Amex, you can earn double the rewards and more. 

In the case that you have a preference for working with Chase, while the Marriott Bonvoy Business Visa credit card from Chase is no longer available, you can still apply for the Marriott Bonvoy Boundless (personal) card. But, as a business owner looking to build your business credit, you need to understand that this card will not impact your Paydex score through D&B. 

⚠ Important Fine Print: You May Not Qualify for Amex’s Welcome Bonus 

Before you cut up or cancel your other rewards cards and apply for the Marriot Bonvoy Business credit card from Amex, you must read the fine print. While the benefits are indeed worthwhile for a traveler, there are instances when you won’t qualify for the welcome bonus.

Have held one of the following cards in the last 30 days: Marriott Bonvoy™ Premier Plus Business Credit Card from ChaseMarriott Rewards® Premier Plus Business Credit Card from ChaseMarriott Bonvoy Business™ Credit Card from ChaseMarriott Rewards® Business Credit Card from Chase

Have held one of the following cards in the last 90 days: Marriott Bonvoy Boundless™ Credit Card from ChaseMarriott Rewards® Premier Plus Credit Card from ChaseMarriott Bonvoy Bold™ Credit Card from ChaseMarriott Bonvoy™ Premier Credit Card from ChaseMarriott Rewards® Premier Credit Card from Chase

Have received a new cardmember bonus offer from one of the following cards in the last 24 months:Marriott Bonvoy Boundless™ Credit Card from ChaseMarriott Rewards® Premier Plus Credit Card from ChaseMarriott Bonvoy Bold™ Credit Card from ChaseMarriott Bonvoy™ Premier Plus Credit Card from ChaseMarriott Rewards® Premier Credit Card from Chase

If you still think you might qualify for the welcome bonus, read on — it’s a great program.  

Then, Learn About the Marriott Bonvoy Amex Business Credit Card Rewards

Now, let’s take a closer look at the Marriott Bonvoy credit card business cardholder travel rewards (in addition to building business credit) that you can leverage when you use this card.  

Hotel Rewards with the Marriott Bonvoy Business Credit Card
Marriott Hotel Rewards

What type of hotel rewards can you earn with the Marriott Bonvoy Business credit card? Here’s what you can earn. 

The Free Night Award + Statement & Property Credits

Each year, after your cardholder account opening anniversary (the date you’re approved for a Marriott Bonvoy Business credit card from Amex), you will receive a certificate for a free night stay at Marriott. And, for every $60K you spend in a year, you’ll receive an additional free night. 

This perk alone is easily worth the $125 annual fee. 

Complimentary Elite Status for 15 Nights

As a cardholder, you will enjoy Marriott Bonvoy Silver Elite Status for 15 nights. But, what does this mean? 

  • Enjoy 10% bonus points on your hotel stays. 
  • Leverage priority late checkout at your hotel stays.
  • Receive exclusive access to a dedicated reservation phone line. 
  • Use your phone to check in and out of your room (mobile key).
  • Bypass blackout dates when you reserve your stay. 
  • +More

And, if you spend $35K in a calendar year, you’ll be bumped up to Gold Elite Status. 

  • Enjoy 25% bonus points on your hotel stays. 
  • Leverage automatic enhanced room upgrade based on availability at check-in. 
  • Utilize a late checkout at 2:00 pm. 
  • Receive 250 or 500 bonus points when you arrive to spend on cocktails, meals, spa experiences, and more. 
  • +More

These perks will make your Marriott stay so much more enjoyable. 

WiFi Benefit

When you use a Marriott Bonvoy business credit card at checkout when booking your stay, you can enjoy an upgrade to complimentary, premium, in-room WiFi at all participating hotels. So, if you need high-speed internet to work, you won’t have to worry about sharing your connection with other guests. 

Airport Rewards with the Marriott Bonvoy Business Credit Card

Airport Rewards Marriott Credit Card

And, as a Marriott Bonvoy Business cardholder, what perks can you leverage at airports? Read about the air travel benefits below.  

Lounge Access + Priority Passes

As a cardholder, you can enroll in Priority Pass™ Select for priority boarding and access to 1,300 airport lounges around the world with up to two guests. Arrive early or spend your layovers in luxury. 

Priority Pass Select lounges include the following benefits. 

  • Comfortable seating and resting areas. 
  • Complimentary drinks, refreshments, and pre-flight snacks.
  • Charging stations for your phone and devices. 
  • Free WiFi.
  • Conference rooms for business meetings. 
  • Pre-flight spa treatments and massage.
  • Swimming pools. 
  • Family-friendly relaxation areas. 

Check on each airport you’ll be traveling with to find out which amenities are available.  

Global Access or TSA Precheck Credit Fee

As a Marriott Bonvoy Business Amex cardholder, if you apply for Global Access or TSA Precheck security clearance, you can receive a statement credit every four years. The credit covers the cost of each five-year program. 

Global Entry has the following benefits. 

  • No processing lines
  • No paperwork
  • Access to expedited entry benefits in other countries
  • Available at major U.S. airports
  • Reduced wait times
  • TSA Pre✓® Eligibility

Global Access statement credit: $100 after four years. 

And, here are the benefits of applying for TSA Precheck.

  • 5-minute or less wait-time at TSA. 

TSA Precheck statement credit: $85 after four years. 

Now, Here’s Everything Else You Should Know About Marriott Bonvoy Business Rewards

You’ve seen the benefits and rewards. Next, learn what else you need to know about the card before you apply. 

What Credit Score is Needed for a Marriott Rewards Card? 

According to users in the myFICO forum, it looks like the Marriott Rewards program requires a personal credit score of at least 650 for approval. This usually means you need a good or excellent Paydex score for approval of the business card. Although if someone has great personal credit, a business credit score may not be as heavy an approval factor. 

Need help with your score? Join the Business Credit Workshop today to boost your business credit score. 

How Do You Use Your Marriott Free Night? 

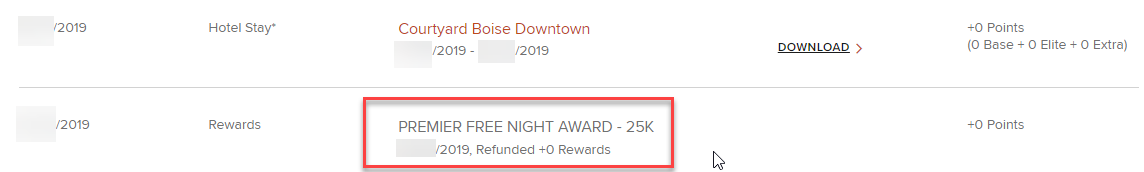
Have you earned a free night stay at Marriott? They should have sent you a certificate, accessible from your account dashboard. You can find it in the activity section. 

marriott free night

If you can find your Marriott Free Night Award certificate from your account dashboard, you should be able to use the “Use Points/ Certificates” option when checking out on Marriott.com. If not, contact support to redeem your award. 
use points for free travel
free hotel nights from marriott credit card

How Much is a Marriott Point Worth? 

The Point Calculator has a helpful Marriott Points Value Calculator that you can use to find out how much your earned points are worth. 

One Marriot Rewards point is worth an average of 0.7 to 1.5+ cents at Marriott hotels, ~0.4 cents toward airfare tickets and rental cars, and ~0.24 cents toward shopping and merchandise. 

And, 75K Marriott points are worth about $525 – $1,125+ at Marriott hotels, $300 toward airfare tickets and rental cars, and $180 toward shopping and merchandise.

According to Statista the most recent average night cost for a stay at Marriott in North America is $198.66. If you use your Amex Marriott Bonvoy Business credit card, this would earn you about 1,188 points. 

So, one night stay at Marriott is worth about  $14 – $30+ at Marriott hotels, $8 toward airfare and rental cars, and $5 toward shopping and merchandise. 

Can You Redeem Marriott Points for Cash? 

You can use your Marriott points to buy gift certificates, but you do not have the option to sell them and they have “no cash value,” according to Marriott Bonvoy’s terms and conditions. 

Do Marriott Rewards Points Expire? 

Yes. Marriot rewards points expire six years after the date they are deposited into a member’s account, no matter what their account activity status is. After this time, cardholders and Bonvoy members forfeit their right to use their points and rewards. 

Final Thoughts

In my opinion, Marriott probably has the best hotel rewards card program around. And, the most enticing aspect of leveraging the card is that it helps you establish business credit while you travel for work. So, the Marriott Bonvoy Business credit card is well worth applying for and utilizing if you can qualify. Apply now to start earning travel rewards with your next hotel stay. 

And, if you want to learn more about skyrocketing your business credit score and building out your credit profile, check out our free secrets of how to get $100K in business credit in 30 days. 
PNC Bank Business Credit Card Review & Comparison

January 11, 2020 By Joe Lawrence

When building business credit, it’s crucial to understand all of your options. Lately, many company owners, especially existing PNC business banking clients, are interested in learning more about PNC business credit cards. The bank offers five options, all with their own rewards systems and varying interest rates. 

So, what makes PNC Bank’s credit offerings stand out? How do the cards stack up against one another? And, what else do you need to know before you apply? Find out here. 

What is a PNC Business Credit Card? 

A PNC business credit card is a line of revolving credit extended to a business by PNC Bank. The company is a portfolio lender which means they lend their own money and they do not sell their loans or lines of credit to third parties. So, a PNC credit card is arguably a good one to get. 

PNC Business Credit Card Comparison

Find out which PNC business credit cards have a 0% introductory APR, cashback rewards, an annual fee, points, and other bonuses below. 


0% Intro APRCashbackAnnual FeePointsBonus
PNC Cash Rewards® Visa Signature® Business Credit CardX1.5%$0X$200 for spending $3,000 
PNC points® Visa® Business Credit CardXOptional$05 points per $1 spentLink personal PNC points card
PNC Travel Rewards Visa® Business Credit CardXX$01 mile per $1 spentDouble miles on first $2,500 spent
PNC Visa® Business Credit Card13 monthsX$0XX
PNC BusinessOptions® Visa Signature® Credit CardXOptionalUp to $500Optional$750 for spending $25,000 

Who is the PNC Cash Rewards Visa Signature Credit Card for? 

PNC Cash Rewards

The PNC Bank Cash Rewards card is one of the most popular options. No doubt, 1.5% cashback on spending is enticing for many business owners. Plus, if you spend $3,000 within the initial promotional period, you’ll receive an additional $200. So, if you’re in the market for a card that pays you to use it, this is the one. 

Do PNC Cash Rewards Expire? 

According to PNC’s cash rewards terms and conditions, your cash rewards will not expire as long as your account is open. However, as soon as you close your account, you forfeit any unused rewards. 

Who is the PNC Points Visa Business Credit Card for? 

PNC Points Visa Business Credit

The PNC Bank PNC Points card is similar to the cash rewards card, except you’ll earn five “points” on every dollar spent. Points are redeemable for cash, electronics, gift cards, merchandise, and travel. And, if you have a personal PNC points card, you can link the two for more rewards.  

How Much are PNC Points Worth? 

When weighing the points card as an option, you need to understand how points are redeemable. There are three sections in the PNC points rewards catalog: 

  • Travel
  • Gift Cards
  • Apple Store & Other Merchandise

You can directly book flights, hotels, cars, and other travel rewards, purchase gift cards and merchandise from the catalog. 

pnc points

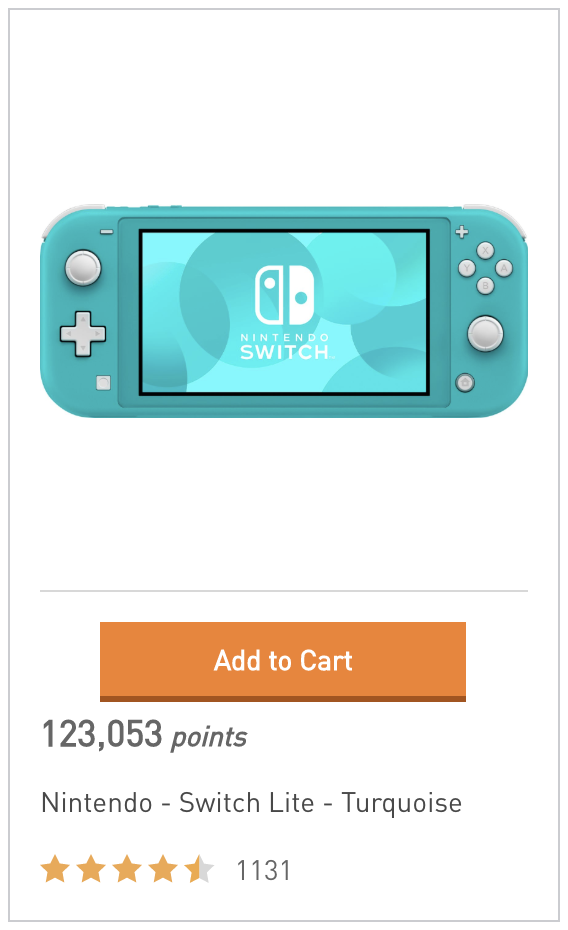
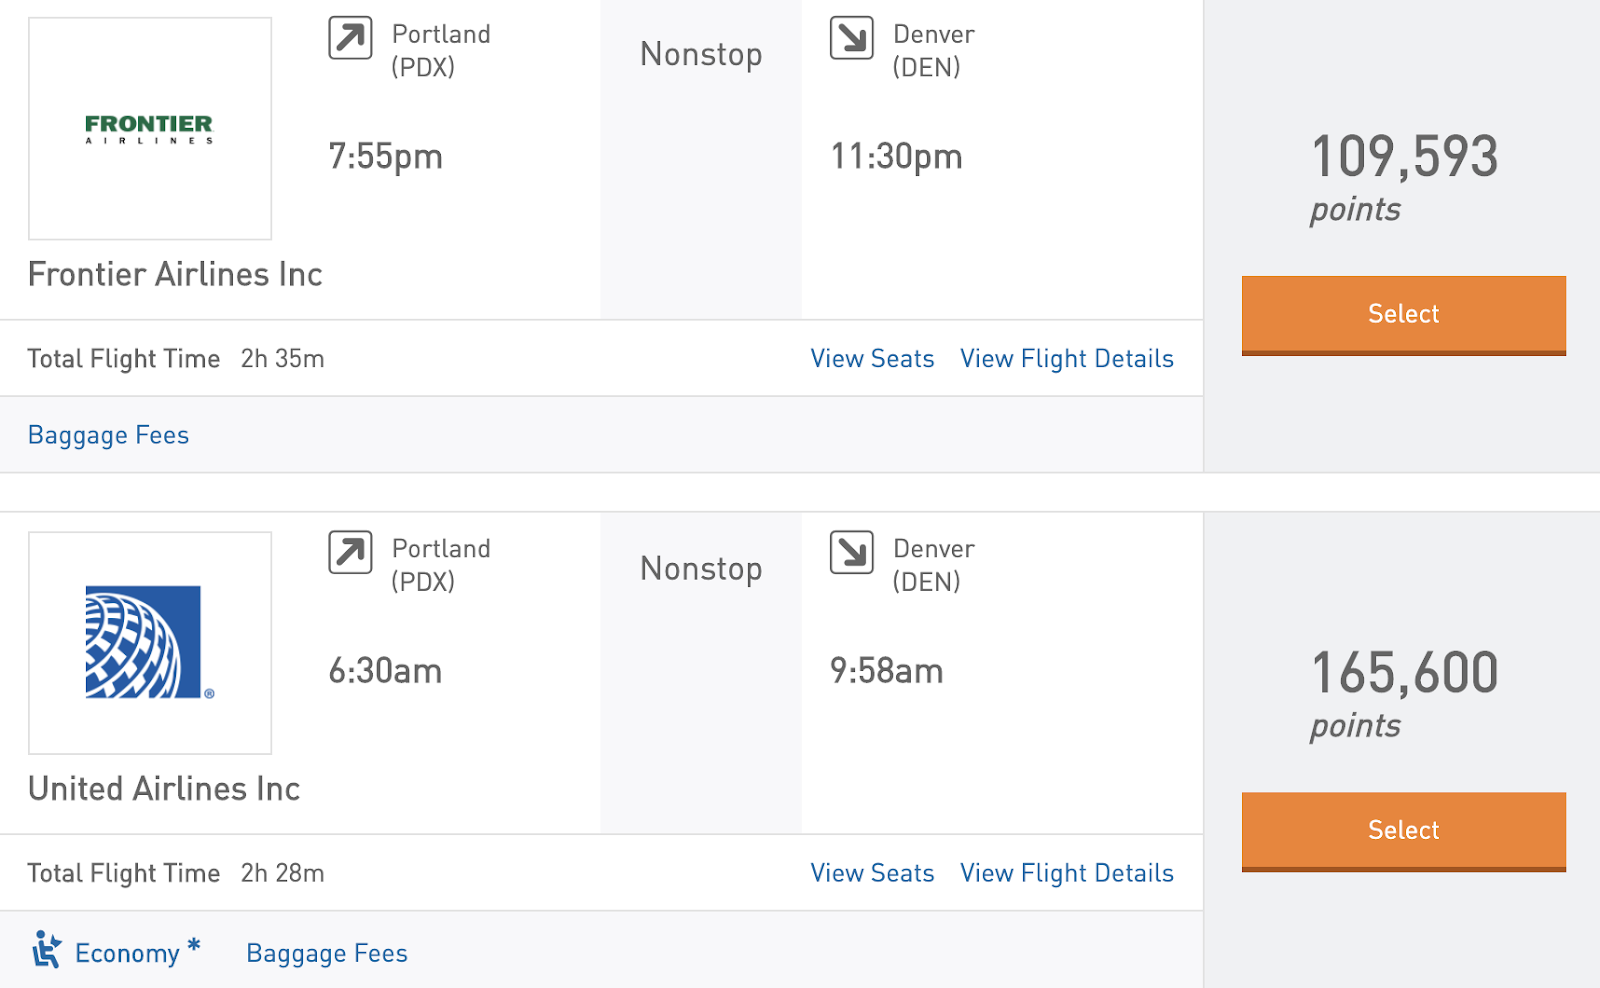
For an idea of what you can get for your points, a Nintendo Switch is redeemable for 123,053 points (or after $24,610.60 in spending). And, the same amount might get you a flight from Portland, Oregon to Denver Colorado.

pnc rewards points

Do PNC Points Expire? 

Unfortunately, yes, PNC points do expire. You have 48 months (about four years) from the time points are posted to your account to use them. So, you’ll need to monitor your points account to see how many are available at a given time.  

Who is the PNC Travel Rewards Visa Business Credit Card for? 

PNC Travel Rewards Visa Business Credit Card

The PNC Bank Travel Rewards card is perfect for travelers. You can earn one mile for every $1 spent and two miles on the first $2,500 in eligible purchases. Or, you can book your own travel and redeem your miles for a statement credit. If this sounds enticing, the travel rewards card might be right for you. 

Do PNC Travel Rewards Expire? 

According to PNC’s travel rewards terms and conditions, miles expire in December of the fourth calendar year after the miles were earned. So, like points, you have about four years to use miles. 

Who is the PNC Visa Business Credit Card for? 

PNC Visa Business

The PNC Bank Business Credit Card is a good starter card for small and medium-sized businesses looking to build credit. The 0% introductory rate for the first 13 billing cycles provides an incentive for companies who are looking to increase their short term and long term working capital or are ready to separate their business and personal spending. 

Related Reading: Fund&Grow Facts: An Honest Business Funding Services Review Overview of a paid financial service that helps companies establish multiple 0% APR lines of credit to grow their business.

Who is the PNC BusinessOptions Visa Signature Credit Card for? 

PNC BusinessOptions Visa Signature Credit Card

The PNC Bank BusinessOptions Visa Signature card is a better card for higher spending ($50,000 or more annually). While there is a maximum annual fee after the first year, you can avoid it by using your card for $100,000 or more in purchases each year. Plus, you can earn $750 statement credit by spending $25,000 on your card in the first three months. 

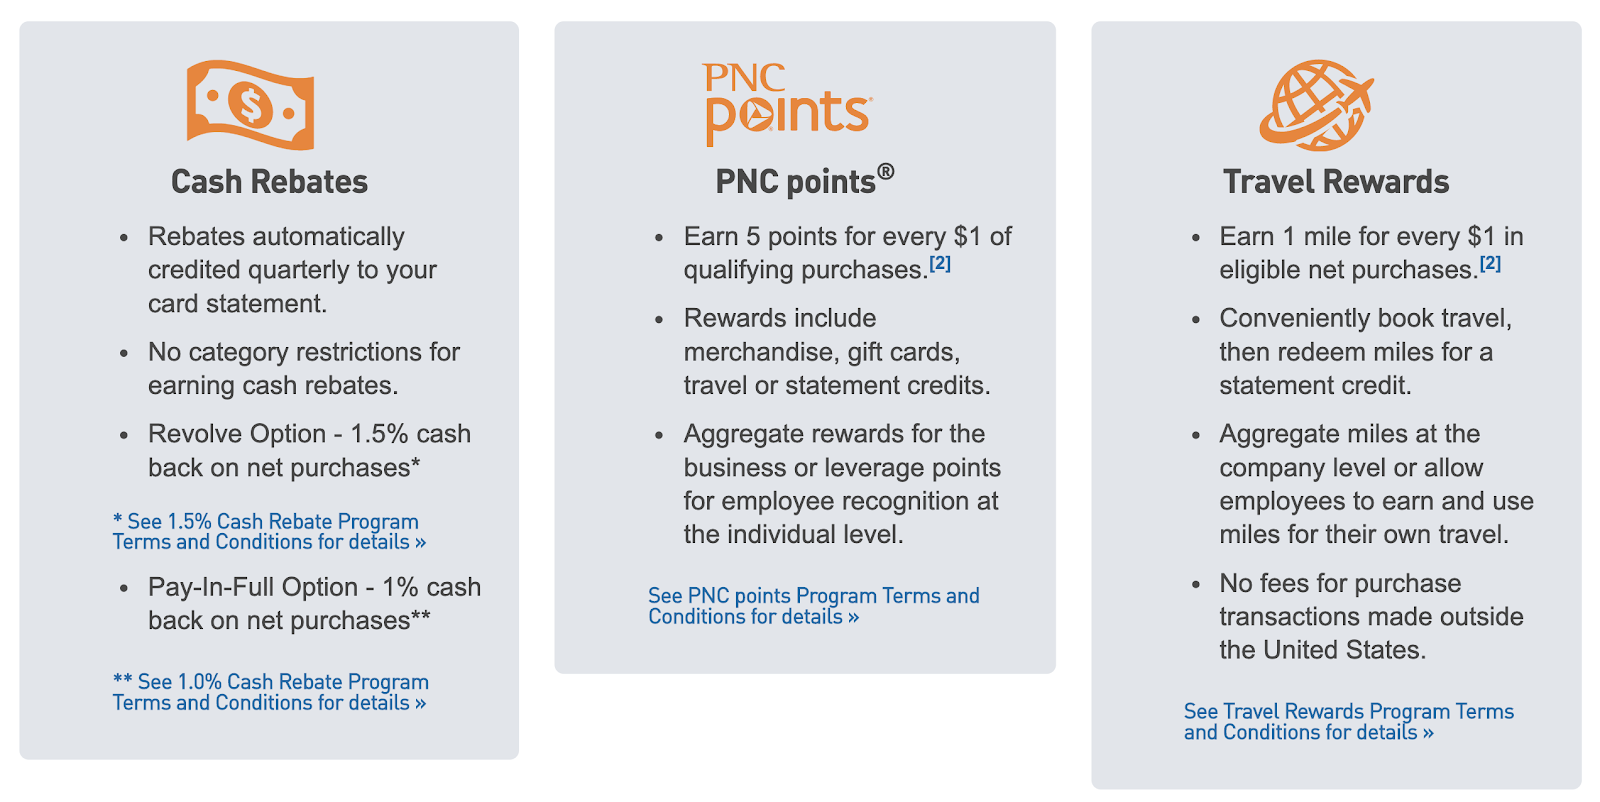
The best feature of the BusinessOptions card might be the fact that you can choose cash, points, or travel rewards. 

pnc cash rewards and points and travel

This card also has revolving and pay-in-full options for the most flexibility. 

Still not sure which card is right for you?: Find the right PNC credit card for your business. 

Commonalities With PNC Credit Cards

While PNC business credit cards vary and one or another might be better suited to your situations, there are some commonalities that they all share. 

What Credit Score is Needed for a PNC Credit Card? 

After reviewing the cards above, you may have an ideal card in mind. But, if your credit score is low, you may not be able to qualify yet. According to several cardholders in the MyFICO forum, those with lower credit scores (below 700) will have a difficult time getting a PNC credit card. 

So, if you don’t have established business credit, you might have better luck starting with net 30 vendors to boost your score before you graduate to revolving credit options like those offered through PNC. 

Are On-Time Payments on PNC Business Credit Cards Reported to Personal Credit Bureaus? 

While your personal credit score may impact your ability to qualify for a business credit card, your payments will be reported to Dun & Bradstreet.  Your Paydex score, as well as your Experian Business and Equifax Business credit scores, will be affected by on-time payments. 

How to Increase Your Credit Limit on a PNC Credit Card? 

As with all credit cards, the best way to increase your limit is to pay as agreed and keep your income updated in your account. You can learn more about this and some valuable hacks with a Business Credit Workshop membership. 

Your PNC business credit card limit is a reflection of your standing with PNC and your credit profile. For convenience, you can request a credit limit increase online from inside your account. 

Other Business Financial Services From PNC Bank

When selecting a credit card to use for business purchases, it’s helpful to know what else the issuer can offer your business. PNC Bank has a full suite of financial services for companies like yours. Most notable are the business checking, lines of credit, and term loans. 

  • PNC Small Business Checking – Choose from four tiers of business checking options based on your needs and leverage additional solutions as needed. 
  • PNC Business Lines of Credit – Based on your location, PNC Bank’s services can vary, but the portfolio lender offers business lines of credit other than credit cards. The amount you receive will be based on your credit profile.
  • PNC Business Term Loans – When you need a specific amount of funding to cover a business purchase like new equipment or real estate, PNC can help. 

Final Thoughts

If you’re in the market for a business credit card, you don’t need to ask if you should get a card from PNC Bank. Rather, the right questions to ask yourself are: 

  1. Will I qualify for a business credit card through PNC? 
  2. Which card is right for me? 

For cashback, choose the cash rewards Visa Signature card. To build points and redeem for gifts, select the points card. If you want to earn travel miles, apply for the travel rewards card. If you need a simple working capital boost, go for the PNC Visa business card.

And, if you need a full-featured card for high spend within your company, try to leverage the BusinessOptions Visa Signature card. And, if you’re interested in learning new ways to acquire more business credit and boost your business credit score,  learn how to obtain business credit in 30 days.

Testimonial from Sergey – Received $365,000 in Business Lines of Credit!

September 13, 2019 By Joe Lawrence

Sergey worked with us twice and both times got unsecured business lines of credit from local community banks. We called hundreds of banks and came up with a few “no-doc” lenders that did not require tax returns. The interest rates are super competitive and Sergey is now able to expand his business!

He followed the two step process:

1.) Build your business in such a way that banks want to lend to you

2.) Know where to apply for business line of credit and get an instant approval

Sign up for our training here

Everything You Need to Know About a DUNS Number – and Why You Should Care

July 12, 2019 By Joe Lawrence

Almost every business, at some time, will need a line of credit – and this is the main reason for needing a DUNS number.

If you own a small business, you may have paid a lawyer for articles of incorporation and to secure a federal tax id number so that you could start a company. However, now that you are in business, you may realize that the startup capital you have in the bank may not be enough, as your cash flow fluctuates.

In order to get a line of credit though, you are hearing from different people that you will also need a DUNS number. So, is a DUNS number the same as a federal tax id number?  If not, what is a DUNS number used for?

Let’s look at what a DUNS number is first. Then, why it is important to have one, how it works, and finally, how to apply for one.

understanding your DUNS number is crucial to getting credit
Understanding your DUNS Number is crucial to building business credit

What Is a DUNS Number?

A DUNS number is a unique nine-digit ID number that is also known as a D&B number and is short for Data Universal Numbering System. This number, which is like having a social security number for your business, is issued by Dun & Bradstreet to any business that completes their informational profile.

This profile is put into a database with 225 million other companies as part of a credit reporting service for businesses. This database works something like Equifax or TransUnion does for your individual credit report. It’s a free service, although you can pay a small fee to get your number faster.

What Is the Purpose of a DUNS Number?

The purpose of a DUNS number is to establish creditworthiness and credit history of your business. This system was established back in 1963 and standardizes business information so that banks and other creditors understand what they are looking at when your business applies for credit or a loan.

This is very similar to what a bank will look at when they go to TransUnion to see if they should issue you a credit card, mortgage, or insurance. 

Why Do I Need a Dun & Bradstreet number?

If you want to get a line of credit from a bank for your business, even if it is doing well, it is very hard to do it on your own. This is because a loan officer is not going to sort through your receivables, payables, or tax returns to see if your business is worthy of credit.

They will, however, give you a personal loan based on your credit score or a loan based on the equity in your house. However, it is never a good idea to take your personal money and use it to keep your business running. As well, the personal loan you qualify for is not usually enough to pay the bills a business will incur.

Plus, you and your family may wind up bankrupt if the business fails.

Applying for a personal credit card and using it for your business is also a bad idea – as you may run up bills that you cannot pay. Then your personal credit may be ruined.

Also a supplier may only work with you on a cash basis if your business is not creditworthy as proven by a recognized credit reporting agency like Dun & Bradstreet. So the best way to establish a positive credit history for your business that can be verified is to have and use a DUNS number.

What Is a DUNS Number Used For?

A Duns number is used to generate a credit report for any business that has completed the DUNS informational profile and then starts using the number to do business.

having a duns number can lead to the extension of credit
A D&B Number can lead to credit!

Doing business by using your DUNS number is the first step to start generating a credit history that can be verified by someone who wants to do business with you – including government agencies and other businesses who require it.

So registering with Dun & Bradstreet and getting a DUNS number assigned doesn’t really do anything for you until you start using it with other businesses that are also registered with a DUNS number and that can report payment history to Dun and Bradstreet.

In other words, if you purchase inventory from a vendor who has a DUNS number, they can report your credit limit, your payments, and years of doing business back to Dun & Bradstreet.

This is how you establish the credit history of your business and its creditworthiness. These positive reports will also allow your company to get credit cards and loans from banks without risking your personal credit.    

How Do I Find my DUNS Number Online?

To find out if your business already has a DUNS number or to see if a company with your same name already has a DUNS number go to https://www.dnb.com/duns-number/lookup.html.

If you don’t find any listing under your name, you can go apply for one yourself.

How Do I Get a DUNS Number?

To find out more about getting a D&B number, click here.  The process is as easy as going online to fill out the form and doesn’t take very long. Nevertheless, it is always good to enlist the professional help of someone who knows the process, as this will be information that will be used to build your business’s credit report.

You will also need all of the information required – like your business name as it appears on your articles of incorporation, the physical address of your business, type of business structure, etc. – before you begin filling out the form. 

How Long Does It Take to Get a DUNS Number?

You can get a DUNS number very quickly – usually in less a week – if you are will to pay a nominal fee to expedite the process.

If not, it only takes about ten or fifteen minutes to apply online, assuming you have all the information required. Then, it takes about 30 days to get your number.

But as we talked about earlier, the number is just the start. Now you will have to find other businesses who also have DUNS numbers and can report your payments and credit limits back to Dun & Bradstreet in order to generate a credit history you can use to keep expanding your business. You can see a list of net 30 vendors that do this here.

11 Alternate Ways for Entrepreneurs to Raise Capital with Online Lending Platforms

June 30, 2019 By Joe Lawrence

We’ve compiled the Complete list of Alternative Lending Platforms for Entrepreneurs. Here is what we found…

Starting your own business can be an incredibly satisfying endeavor. When you finally make that leap into the entrepreneurial world, it is often because you love what you do and are looking to make an impact in your particular industry.

However, starting a business does not come without its challenges.

One of the primary obstacles for entrepreneurs is how to fund their business – especially at the beginning. Anyone who has dabbled with starting a business knows that is can take a significant investment up front.

According to a study by LegalZoom and the Ewing Marion Kauffman Foundation, “80 percent of early-stage business owners are using personal funds to finance their companies.”

80% of early-stage business owners are using personal funds…

At such a high percentage of entrepreneurs self-funding their new business, it can be intimidating to even think about starting your own company because, the truth is, most people don’t have the kind of money it takes to start a business on their own.

So, how does one start a business and not completely deplete their entire life savings? There are actually quite a few ways to raise capital using online loans like Kabbage, OnDeck, Lending Club, Fundera, and lines of credit.

There is also always, of course, the option of taking a loan out from a bank; however, it generally takes more time, some collateral, and a great credit score in order to receive a loan from a traditional bank whereas an online loan often has an easy application process, higher approval, and you get the funds quicker.

First, let’s define what it means to “raise capital.” Capital is the amount of money or funds that it will take to get a small business off the ground in order to begin generating its own income and pay its employees and so forth.

We’re going to explore alternate ways to raise capital for entrepreneurs in order to help you to make an informed decision when it comes to raising capital for your small business. For each capital raising option, we’ll cover how long it takes to receive the money, how to qualify, and what other entrepreneurs have said.

how kabbage works
Here’s how Kabbage Works…

1. Kabbage

Kabbage is an online financial technology company. It’s based in Atlanta, Georgia and provides direct funding to entrepreneurs through an online lending platform. Kabbage is free to use and entrepreneurs don’t pay anything until they use their funds.

Small business owners can receive loans up to $250,000 and the company offers an easy to use app in order to track your funds and give you 24-hour access to the money. Kabbage can help bridge the gap between having a dream and making your dream a reality.

How To Qualify for Kabbage

Small businesses that have been in business for at least one year and have an annual revenue of at least $50,000 (or at least $4,200 per month for the last three months), along with a credit score of 560 or higher qualify for Kabbage.

Applying for Kabbage is very easy to do and requires minimal paperwork. All that’s needed is to create an online Kabbage account and provide basic information about your business (industry, years in business, and so forth).

Once your account is created, you’ll link your business bank accounts in order for Kabbage to revue the business’ revenue. After the application process is complete, Kabbage will let you know if you’ve been approved for a loan.

How To Use Kabbage

Kabbage offers three different ways to retrieve the funds when you need them. The Kabbage app is available for both iPhone and Android and allows you to withdraw funds and manage your account on the go at anytime.

The Kabbage online dashboard allows you to withdraw the funds that you need directly from your computer. The funds are instantly deposited into your account.

The Kabbage card allows you to “grow as fast you swipe” with access to your entire line of credit directly on your card.

Making Payments with Kabbage

Of course, taking money doesn’t come without the stipulation that you’ll pay it back after a certain amount of time. You can make payments with both the Kabbage app and the online dashboard.

Payments can be set up to bill a certain amount monthly or you can set up auto payment which will pay off the minimum payment for each month.

Kabbage Reviews from Fellow Entrepreneurs

There are many reviews on Kabbage’s loan services and they are all positive, for the most part. A review by Merchant Maverick states that:

“finding a lender more convenient than Kabbage would be difficult. In most cases, business owners can apply, get a decision on their rates and fees, and start drawing funds within a few minutes. That’s really fast, even for an industry that’s known for coming to quick lending decisions. The speed comes at a price, though. With fees that can reach up to 10% of your borrowing amount each month, this lender provides some of the more expensive loans you’re going to come across. And while they don’t have a prepayment penalty, some merchants don’t like that Kabbage’s loans are front-loaded, which means you might not be able to save very much money by repaying early.”

Wes Dunn, the founder of Dunn’s Attic in Florida used Kabbage to get his retail business off the ground and he said that what he likes most about Kabbage is how easy it is to apply and use the platform as well as how quickly he can retrieve funds when he needs them.

on-deck-capital

2. OnDeck

OnDeck is very similar to Kabbage and the two are often compared online. Primary differences between the two online lending platforms are the loan amount and minimum qualifications. We’ll explore those and more below.

How to Qualify for OnDeck

Similar to Kabbage, in order to qualify for OnDeck you need to have been in business for at least one year. However, OnDeck also requires that your business make at least $100,000 per year or more, and a personal credit score of 600 or higher.

Applying for a loan from OnDeck is quick and simple. Applying can be done online and only takes a few minutes. You’ll need to fill out basic personal and business information, as well as provide bank statements to show your business’ cash flow. You’ll be given an answer within minutes and, once approved, will receive your loan in two days.

How to Use and Make Payments with OnDeck

OnDeck offers a mobile app and also has an online dashboard where you can manage your account, retrieve money, etc… You can also make payments online or with the app.

OnDeck has a customer service team that is available for assistance over the phone 24/7. The loan specialists work with entrepreneurs and business owners on a daily basis and are highly qualified to answer any loan questions you might have.

OnDeck Reviews

Because OnDeck has a team of loan specialists that are always available to answer questions, the platform has a very personal feel to it.

An anonymous review on OnDeck’s review page says:

“Love our experience with OnDeck. Such a great company to work with and always follows through on expectations and promises. We have been approached by so many other companies for our funding needs but we have no interest in switching because the experience with them is so great. Katie our Account Manager is honestly amazing! So quick to get back to us and always helping to guide us in the right direction. Normally dealing with finance people is so hard but Katie is honestly a joy to work with. I would highly recommend OnDeck!”

If your business needs a larger loan and has been in business for at least a year with revenue of $100,000 or more, OnDeck is an excellent loan option.

lending club

3. Lending Club

Lending Club is different from more standard lending companies like OnDeck and Kabbage because it is a peer-to-peer lending company. Peer-to-peer lending is a way to offer lower rates for borrowing money while offering investors competitive returns.

LendingClub specifically was the first peer-to-peer lending company and uses technology to make the entire lending and borrowing process painless for all involved which has caused the company’s satisfaction rating to rank among the highest in the entire financial services industry.

How to Qualify for Lending Club

In order to qualify for a peer-to-peer loan through Lending Club, your business must have been around for at least one year, have at least $50,000 in annual sales, no bankruptcies, and you must own at least 20% of the business. Lending Club will also look to see if your personal credit score is at least fair or better.

Once you’ve confirmed that you qualify for Lending Club, you can begin the application process. You can apply online by answering a few questions about your business and Lending Club will give you an answer within minutes.

How does Lending Club Work?

Interested businesses can receive anywhere from $5,000 to $500,000 in loans and can have access to the money within as few as 7 days. Borrowers can use the app or the Lending Club website to access their money.

How to Make Payments

Borrowers can pay back their loan with confidence because Lending Club has low and fixed interest rates and you can easily make payments directly from your bank account. Another really nice thing about Lending Club is that there is no application, brokerage, or prepayment fees.

Lending Club Reviews

Lending Club has a slew of positive reviews with borrowers saying things like, “without LendingClub, we wouldn’t have been able to start our business two years ago.” Based on the reviews, it appears that borrowers have seen highly positive results from their experience with Lending Club. Supreme Accounting & Tax SVC said they were:

“surprised by how straight-forward the process was, and how quickly [their] loan was funded.” 

Other borrowers have been impressed with Lending Club’s ability to give large loans with good rates as well as the company’s superb customer service. If you’re interested in taking out a peer-to-peer loan, Lending Club should be at the top of your list.

4. LoanBuilder by PayPal

PayPal acquired Swift Financial, which is the financial institution behind LoanBuilder, in 2017. LoanBuilder’s mission is to “help businesses get the right funding quickly by letting them design loans that fit their unique needs to get approved based on how they manage their business.” We’ll walk through how to qualify and how it works to build your own loan below.

How to Qualify for LoanBuilder

In order to qualify for a LoanBuilder loan, your company must have been in business for at least nine months and make at least $42,000 in annual revenue. LoanBuilder works with businesses in over 500 different industries in the United States.

In order to apply and check your eligibility, there is an online questionnaire that should take anywhere from five to ten minutes to complete. Alternatively, you can call LoanBuilder at 1-800-347-5626 and speak with an expert live to apply. Upon completion of the questionnaire, borrowers can begin to build their loan based on estimated loan terms and their financial needs.

Once you’ve been approved for your loan, you’ll receive a contract electronically with instructions on how to receive your money and make payments.

How to Use LoanBuilder

If you are approved for a business loan through LoanBuilder, the funds will be directly deposited into your business’s bank account and can be received in as little as one business day.

Paying Back a Loan from LoanBuilder

To pay back your LoanBuilder loan, the company automatically makes withdrawals from your business’s bank account. You’ll be able to set the day of the week the funds are taken out and how much you pay; however, LoanBuilder does not allow negotiation on the frequency of the payments.

Loan durations through LoanBuilder typically have a payoff time of anywhere from 13 weeks to 52 weeks.

LoanBuilder Reviews

Doug Wiens, owner of Orange Coast Winery, says that before LoanBuilder his company lacked the collateral for a traditional loan. With the loan from LoanBuilder, Orange Coast Winery was able to re-do their wine tasting rooms, purchase more wine bottling materials, and upgrade their kitchen.

Steve Bilenky, Owner of Bilenky Cycle Works says that LoanBuilder was exactly what his company was looking for because of how easy LoanBuilder makes it to apply, receive, and pay back the loan.

LoanBuilder takes the fussiness out of applying for a loan and paying it back. Their customer service has also had many rave reviews.

5. Fundbox

Fundbox is a fintech company that uses cutting-edge technology and data science to help create financial options for small businesses. Fundbox claims that their use of common sense and technology help small businesses to gain more control over their finances in order to succeed and grow.

Currently, Fundbox has over 70,000 customers. According to Eyal Shinar, Fundbox’s CEO, “Small businesses are the core of our economy, yet the resources available to them are limited at best. We give small businesses new financial power and guidance so they succeed.” The company that got its start in 2013, is based in San Francisco and offers two products: an invoice financing offering and a line of credit.

For our purposes, we’re only going to talk about Fundbox’s line of credit.

How to Qualify

In order to qualify for Fundbox, you must have a business checking account, at least two months of using an accounting software (like Quickbooks or similar) or at least three months of transactions using the business bank account. Additionally, the business must have a minimum of $50,000 in annual revenue and must be located in the United States or surrounding U.S. territories (Guam, American Samoa, North Mariana Islands, Puerto Rico, or U.S. Virgin Islands).

Once you’ve met Fundbox’s qualifications and apply, you’ll typically get a decision from the company within three minutes.

How to use?

After Fundbox has approved you for a credit line, your funds will be available to you immediately and you can draw from them at any time. Generally, it does take one business day for the funds to deposit into your account. Additionally, you only have to pay when you draw funds and there is no continual fee.

How to pay?

Fundbox only charges you when you draw money from them. The example the website gives is that if you draw $1,000 for 12 weeks, the fees would start at $3.88 per week. Following that example, your weekly repayment would be $87.22, and the total (including fees) at the end of the 12 weeks would be $1,046.60.

You can also choose to pay over 24 weeks, which would be fees of $3.75 per week, weekly repayment at $45.41, and a total of $1,089.90 after 24 weeks.

Additionally, if you pay early Fundbox waives all of the remaining fees.

Reviews

One happy entrepreneur says that Fundbox is a:

“Good company to work with! Once your credit limit is established you can withdraw any amount up to your credit limit at any time. …I would definitely recommend these guys to any small business owners. 5/5 stars!”

Another reviewer mentioned that Fundbox’s payback tactic is a little “aggressive,” but they did still mention that the process was quite painless. According to another small business owner, Fundbox is perfect for the weeks when his business’s weekly revenue is slower than he would like. Because of Fundbox, his company never misses a beat.

6. LendingTree

LendingTree is the largest online lending marketplace in America. It connects borrowers with lenders that will fit their situation. LendingTree provides financial information and guides in order to help your business make the smartest financial decision possible.

The website breaks down all different types of loans including personal, home, auto, student, and business loans. Within each loan category, LendingTree also breaks down the different types of business loans. LendingTree believes that pursuing a loan should be part of a company’s strategic business plan and their in-depth research and review platform provides entrepreneurs with the resources needed in order to choose the best business loan.

How does LendingTree Work?

LendingTree prides itself on its ability to “get small business loans tailed to you.” The LendingTree website makes it easy to research and explore each of your loan options. First, the website asks which type of business you are – the options range anywhere from Sole Proprietor to a C-Corporation.

LendingTree then explains what a small business loan actually is and how it works followed by a step-by-step process for determining your need for a small business loan through the application and then finally the payment process.

The platform breaks down each type of business loan and touches on how long the loan term lasts, what the payment process is like, how high the interest rates are, and which business necessities each loan is geared towards. The website also offers a business loan calculator when you can plug in the loan amount, interest rate, and loan term in order to determine what your monthly payment would be.

In order to ensure that you are fully prepared when applying for your loan, LendingTree also features a borrowing calculator where you can plug in your annual revenue, monthly income, and credit score in order to determine how much you might be qualified to borrow.

If you use LendingTree’s questionnaire and checklists, you’ll go into the loan application process with the confidence to apply for the loan that is best for your company.

Reviews

Other entrepreneurs love using LendingTree for their financial questions and needs because the lending process is painless and hassle-free.

The customer service at LendingTree also is something to note – they are always available for your questions, no matter the time and no matter the issue. LendingTree prides itself on being simple, easy to use, and having no credit score impact. Based on their customer reviews, they stand by that through and through.

7. Fundera

Similar to LendingTree, Fundera gives clients knowledge and advice after diagnosing your financial situation. The company’s goal is to ensure that the financial decisions that your business is making are smart, practical, and efficient for reaching your financial and business goals.

Fundera allows you to look at a variety of options when it comes to small business loans in order for you to confidently make the best financial choice for your business’s specific needs.

How does Fundera Work?

Fundera provides small businesses with useful information and resources as it pertains to their businesses financial needs. When it comes to taking out a loan for your business, Fundera has a step-by-step online guide to help walk you through that process. The guide includes things like considering how much money you think your business needs, what the money will be used for, types of business loans, as well as your business’s capital and what you can realistically afford.

In addition to the loan help, Fundera also includes information on how to analyze your credit report and what your business needs with regards to qualifying for a small business loan.

When it comes to taking out a small business loan for your company, Fundera should be your first stop in order to understand all of the different loan nuances, terms, and payment policies in order to make the wisest choice for your small business.

Reviews

What other entrepreneurs are saying about how Fundera has helped their business is an excellent way to see how Funder could be beneficial to you. Some customers are seeing savings of $15,000 a month, while others have had an increase of 130% in sales.

Many entrepreneurs on the Fundera reviews page have mentioned that Fundera made it easier to reach their financial business goals with maximum ease and efficiency.

Runners Up Online Lending Platforms

These online lending platforms didn’t quite make the cut for this article to deep dive into all of their pros and cons; however, they are definitely worth mentioning. We’re going to briefly share a few helpful facts about each of our runners up online lending platforms.

8. StreetShares

StreetSharesis a business funding option whose claim to fame is that they “put the needs of business owners first.” It is a veteran-run company, which makes it unique and the company works by the following set of high moral values.

The company offers a variety of business loans, as well as lines of credit. All that’s needed to apply for a business loan through StreetShares is the ability to prove that your business can pay back the loan – you can do this by showing documents like bank statements and tax documents. Streetshares also will take your personal credit score into consideration as well.