• Home
  • Free Funding Guide
  • What We Offer
    • Products
    • Services
    • Free Guide
  • About Us
  • Contact
  • Sign Up

  • Ask Joe Any Question!
  • Business Credit Cards
  • Business Line of Credit
  • Topics

InDinero Unveiled: A Detailed Accounting & Tax Platform Review

April 27, 2024 By Joe

InDinero review

InDinero advertises itself as a business-saving solution to manage business accounting and taxes. And, may seem like a great, convenient option, especially when you want quick answers. 

But, is InDinero everything it’s cracked up to be? Here, I’ll share everything I know about the platform, the company, and insights to help you decide whether this is the right answer for your business needs. 

This is what’s in store. 

  • What is InDinero?
    • InDinero Pricing
    • Company Overview
  • What Does InDinero Do?
    • 1. Accounting + Bookkeeping
    • 2. CFO Advisory
    • 3. Business Tax Services
    • 4. Financial Planning & Analysis (FP&A)
  • Conclusion: Is InDinero Legit?

Now, let’s roll! 

What is InDinero? 

InDinero accounting

InDinero is a comprehensive financial services company designed to assist businesses with various aspects of their financial management. 

They offer services like: 

  • CFO (Chief Financial Officer) support
  • Tax planning and filing
  • Payroll
  • Accounting
  • Bookkeeping

Their CFO services provide strategic financial guidance, including budgeting, forecasting, and cash flow management to help you make informed decisions. For accounting and bookkeeping, InDinero aims to simplify financial processes, reduce errors, and enhance efficiency. They also specialize in tax planning to optimize strategies and minimize liabilities.

InDinero offers a blend of software and human support to handle complex financial tasks—It provides businesses with proactive advice and guidance to navigate the path towards growth and profitability.

You might also like: 1-800Accountant Reviews: Expectations vs Reality 

InDinero Pricing
How much does InDinero cost?

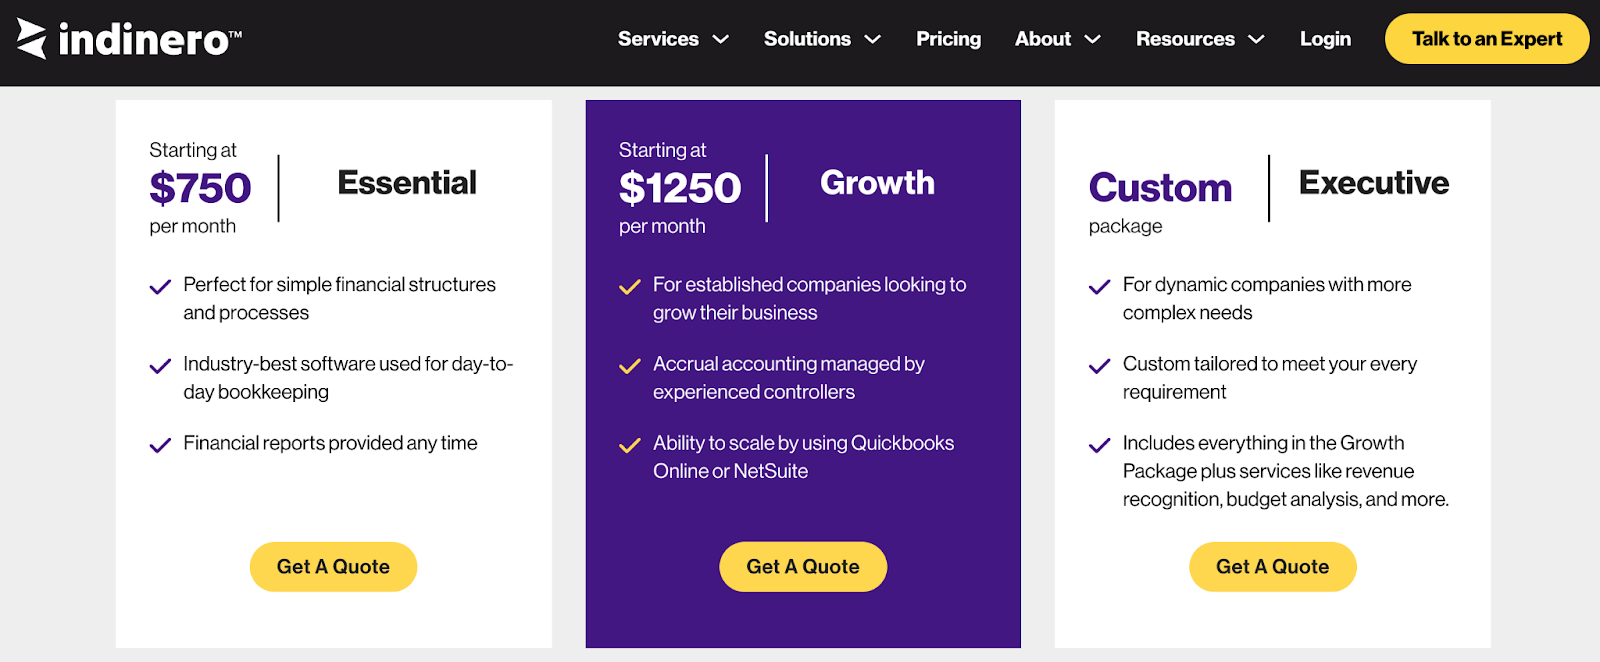
InDinero offers three pricing plans tailored to different business needs:

  • Essential package – Starting at $750 per month, this package is for  businesses with straightforward financial needs to leverage top-notch software for daily bookkeeping and on-demand financial reports.
  • Growth package – Starting at $1250 per month, this one’s ideal for established businesses looking to expand, managed by professionals who handle accrual accounting and facilitate scalability via platforms like Quickbooks Online or NetSuite.
  • Executive package – With custom pricing, the executive package is tailored for dynamic businesses with complex needs and offers advanced services like revenue recognition, detailed budget analysis, and personalized solutions.

To get accurate pricing and ensure you receive the right services for your business, reach out to InDinero for a customized quote.

You might also like: Melio Payments Review: Can It Make Business Payments & Getting Paid Easier?

Company Overview
InDinero location

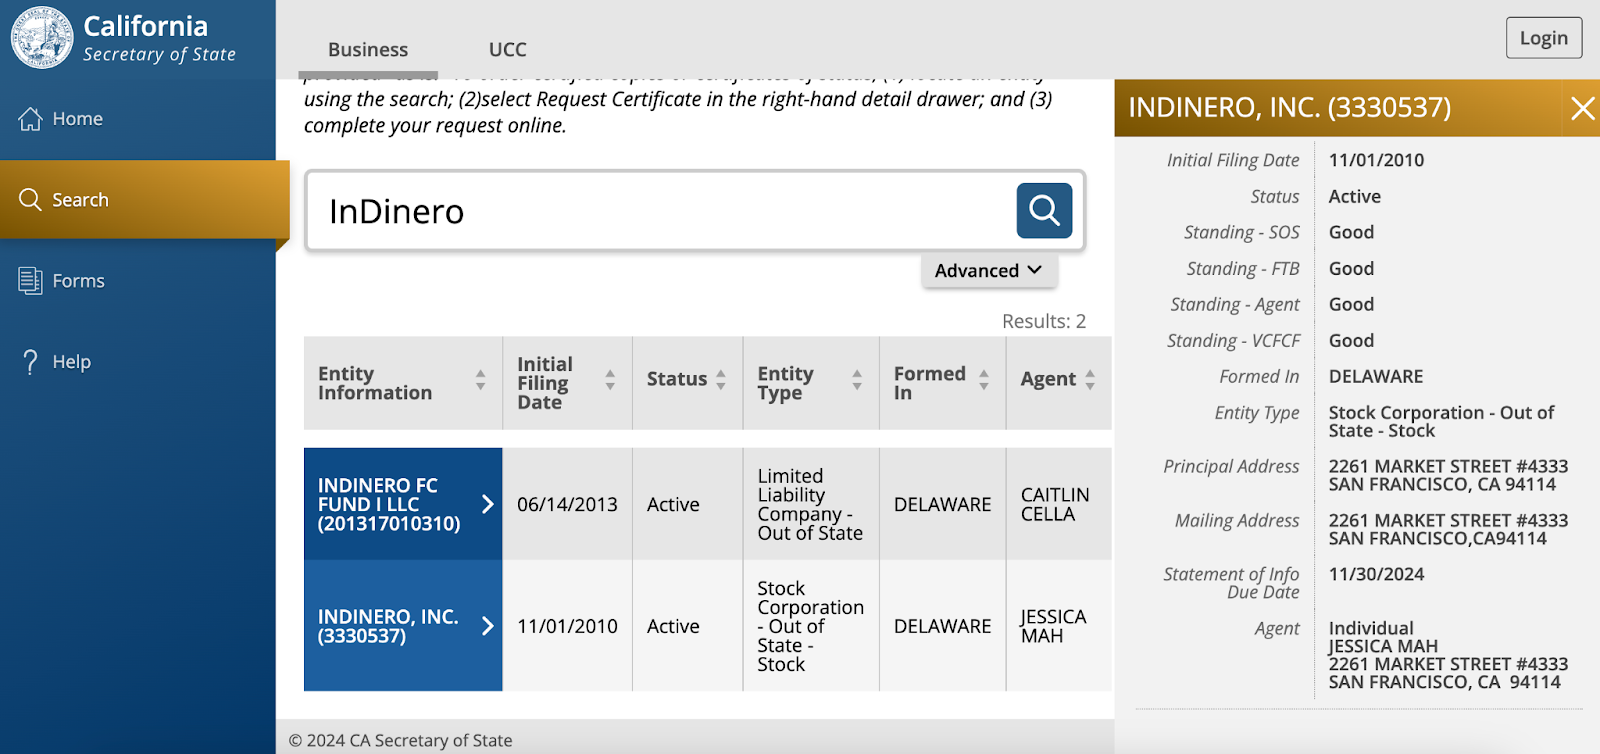
InDinero Inc. is a private, for profit, San Francisco-based company that was founded in 2009 by Jess Mah, Andy Su, and Andrea Barrica. The company is registered, active since 2010, and in good standing with California’s Secretary of State. 

Mah is also the “Head Honcho” at investment firm, Mahway, and a board member of biotechnology research institution, Astonishing Labs. 
InDinero founder Jess Mah

InDinero’s current CEO is John Frazier. Prior to starting at InDinero in January 2022, Frazier was a member of the advisory board at Technology Services Industry Associates (TSIA) and the COO of technology consulting company, Synoptek, before that. He also worked previously at Deloitte and JDA software.  
Who is the CEO of inDinero?

Leadership seems to have a strong technology background that most employees seem to support. According to Glassdoor, 61% of InDinero’s staff would recommend the company to a friend and 68% approve of the CEO. 
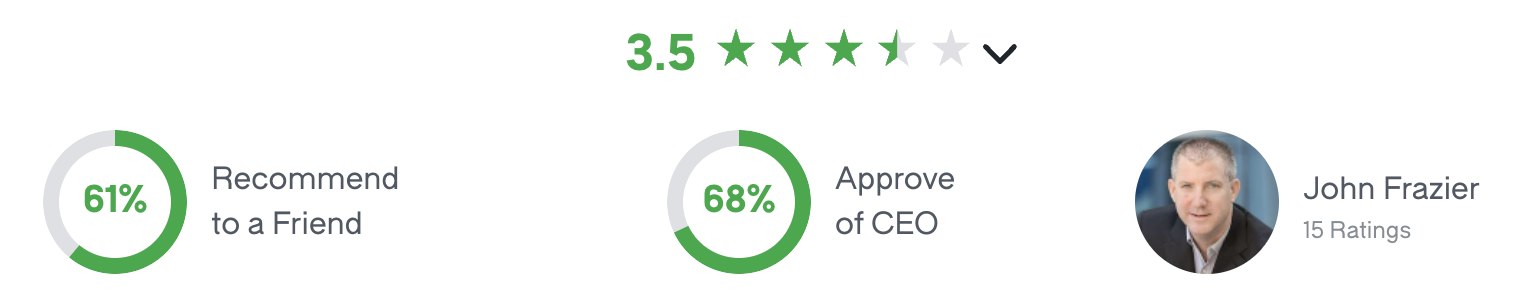
InDinero CEO

What staff has to say about a company says at least as much as what users think. InDinero’s G2 reviewers give the company an overall 4-star rating. For some reason. Despite being around for so many years, InDinero doesn’t have any ratings on Trustpilot. 
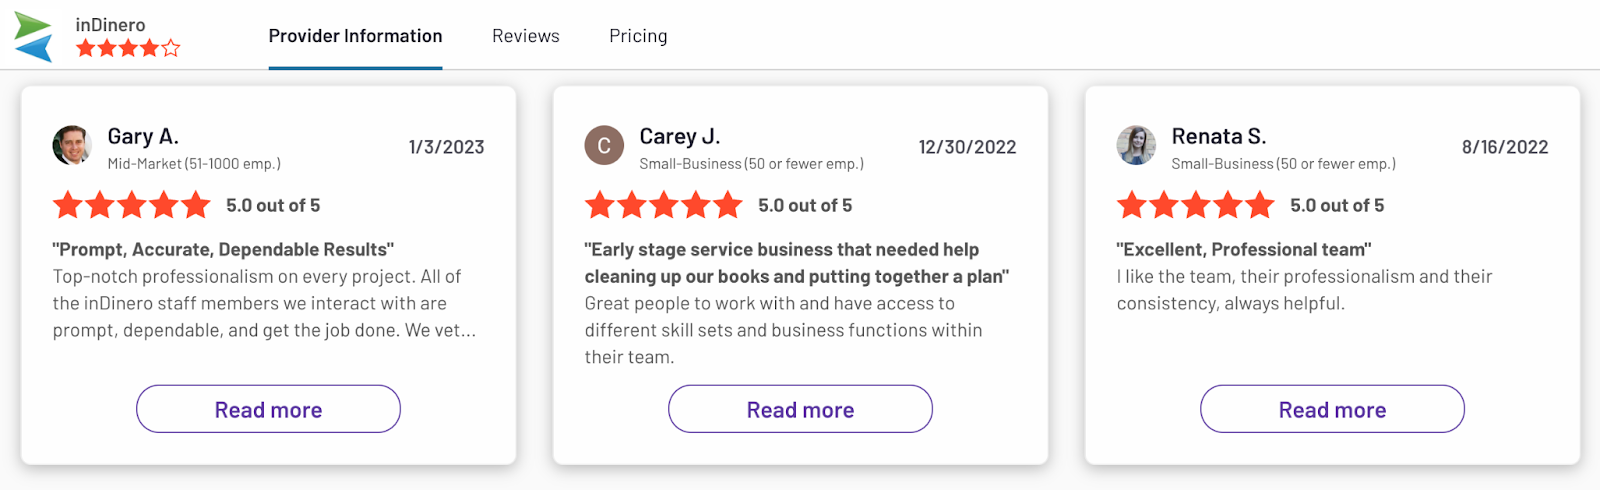
InDinero reviews

Likewise, one customer review (1-star) on the Better Business Bureau isn’t enough to gauge the way people think of the company. But, in InDinero’s favor, no complaints are listed on the platform, and they have an A+ rating.
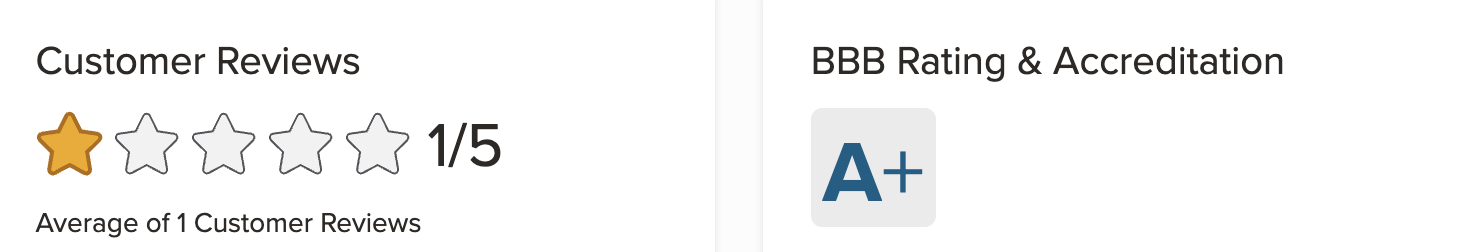
InDinero reviews BBB

I found a couple of pending lawsuits against InDinero – One claiming that InDinero misappropriated funds and another that an employee was wrongfully terminated. 
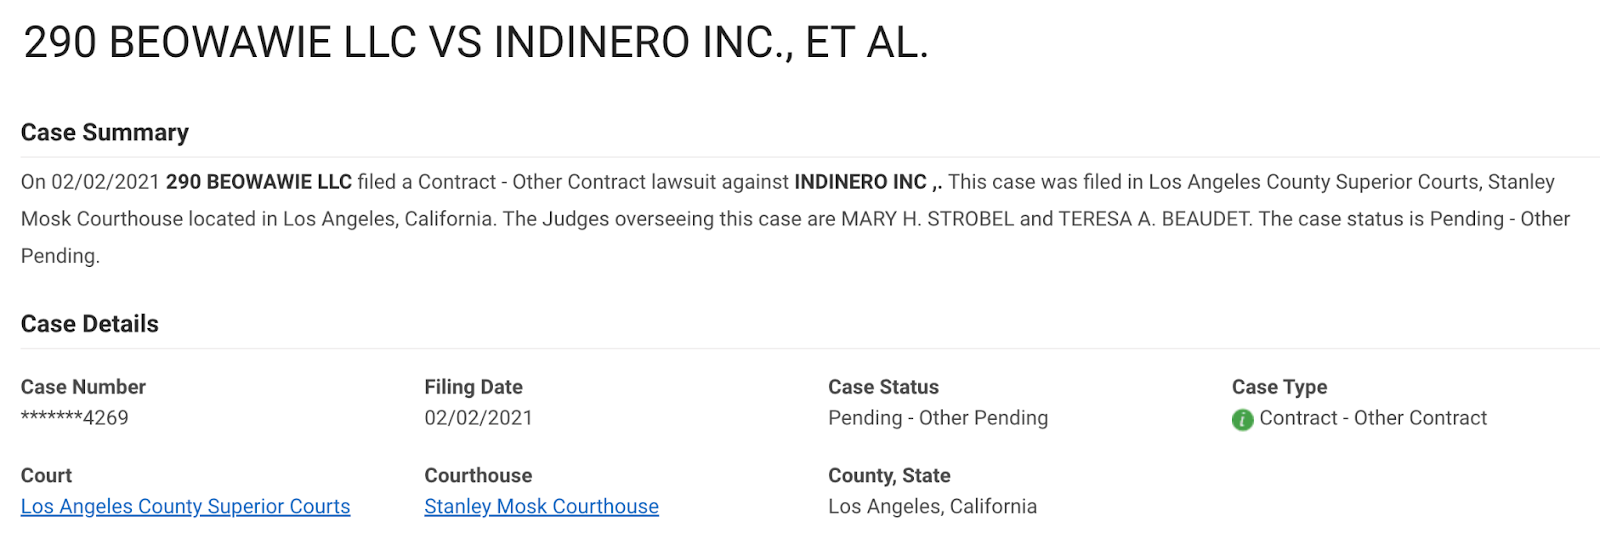
InDinero lawsuit

These allegations don’t have anything to do with how InDinero handles customer accounts, but it could speak to their overall business ethics. Keep in mind, the jury is still out on this.  

You might also like: Gusto Review: Let’s Really Evaluate This Famed Payroll Platform 

What Does InDinero Do? 

InDinero combines financial technology with outsourced accounting and bookkeeping services to give you financial data and help drive your business strategy. Whether you’re a startup or an established enterprise, InDinero might be a good place to get comprehensive guidance and support.

Read on to decide if this looks like an offer you might want to cash in on. 

You might also like: Comprehensive ZenBusiness Review: Is it Legit for LLCs? 

1. Accounting + Bookkeeping
Financial Accounting Services

InDinero’s accounting and bookkeeping services cover a wide range of essential financial tasks for businesses. This includes managing accounts receivables and payables, ensuring timely and accurate tracking of financial transactions. 

They handle expense tracking, invoicing, and generate detailed reports to provide insights into financial performance. Additionally, InDinero takes care of payroll processing and performs reconciliations to ensure that financial records are accurate and up-to-date.

2. CFO Advisory
inDinero revenue

InDinero provides strategic financial leadership through their CFO advisory services—This involves offering valuable insights and guidance to businesses in key financial decisions. Their team assists in due diligence processes, especially useful during mergers, acquisitions, or fundraising activities. 

InDinero also manages investor relations, helping you communicate effectively with stakeholders. The focus is on driving profitability through operational consulting, optimizing financial strategies to achieve business goals.

3. Business Tax Services
Accounting services company

InDinero’s business tax services cover comprehensive tax compliance for federal, state, and local regulations. They assist businesses in maximizing tax benefits, including R&D tax credits. 

InDinero identifies tax savings opportunities by leveraging tax credits, deductions, and strategic entity structuring. They provide proactive tax planning to optimize tax liabilities and ensure businesses are compliant with ever-changing tax laws.

4. Financial Planning & Analysis (FP&A)
InDinero technology solutions

InDinero’s FP&A services focus on helping businesses plan and forecast their financial future. They assist in budgeting processes, ensuring that financial resources are allocated efficiently. 

InDinero conducts scenario modeling to evaluate potential outcomes under different circumstances, enabling businesses to make informed decisions. They analyze key performance indicators (KPIs) to measure business performance and develop financial models that support strategic planning and growth initiatives.

Conclusion: Is InDinero Legit? 

InDinero is a reputable firm that merges state-of-the-art financial technology with skilled accounting and bookkeeping services to analyze financial data and provide practical guidance. Whether you’re a startup tackling growth hurdles or an established business aiming to enhance financial strategies, InDinero is dedicated to supporting businesses throughout their journey to financial success.

Is this something you need? Well, if it’s worth investing $750+ per month to find out, then it seems to me like a decent platform to try. However, I always advise that you shop around and make sure you know your options. 

And, if you’re the type of person who prefers in-person meetings and more personal support, then you may do better to find a local CPA or accountant to work with—This is important to consider, since InDinero works primarily remotely. 

Do you want to learn how to obtain up to $100K in business credit in as few as 30 days? Join Business Credit Workshop today!
Should You Accept a Square Business Loan Offer? 

April 22, 2024 By Joe

Square business loan

If you use a Square card reader, they may have offered you a business loan. If you’re trying to grow your business or you’ve got an immediate opportunity that you’d need financing to afford, you may be considering it. But, you want to know more about Square business Loans. 

How long does it take to get a Square business loan? Do Square loans affect your credit? What percentage do they take for repayment? I answer these questions and more here.  

This is what’s in store: 

  • What is a Square Business Loan?
    • Square Business Loan Cost
    • Company Overview
  • How Do Square Business Loans Work?
    • 1. Automated Offers
      • Square Business Loan Requirements
    • 2. No Personal Guarantee
    • 3. Quick Funding
    • 4. Automatic Repayment
    • 5. Transparent, Fixed Costs
    • 6. The Square App
  • Frequently Asked Questions
  • Conclusion: Are Square Business Loans Legit?

Now, let’s dig in! 

What is a Square Business Loan?

Square business loan reviews

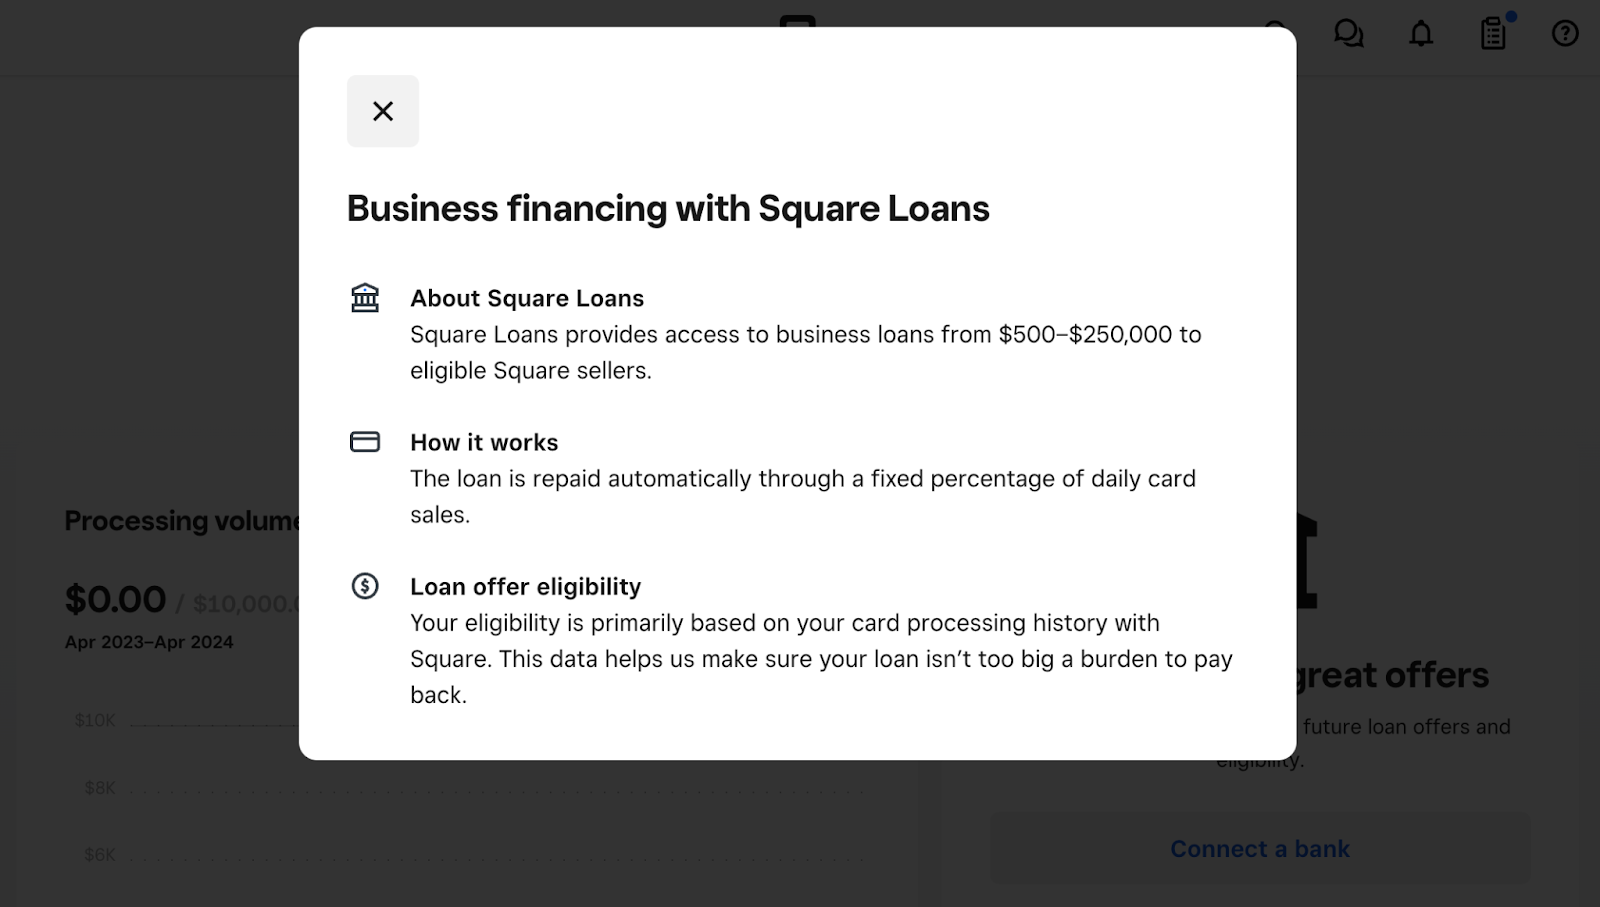
In a nutshell, a Square business loan is a cash advance financing offer for small businesses that use Square for payment processing.

It’s designed to provide quick access to capital for business needs like: 

  • Purchasing inventory
  • Covering operating expenses
  • Investing in growth opportunities

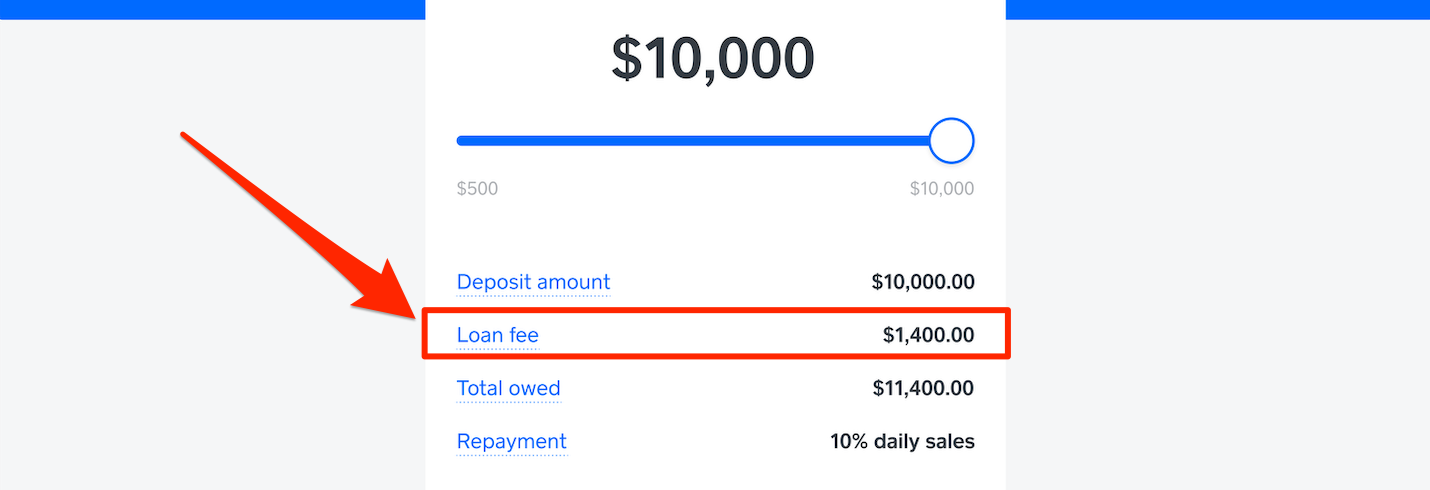
The loan amount can range from $300 to $250,000, and the repayment structure is straightforward: instead of traditional interest, there’s a flat fee, and you pay back a fixed percentage of your daily card sales through Square until the loan is fully repaid.

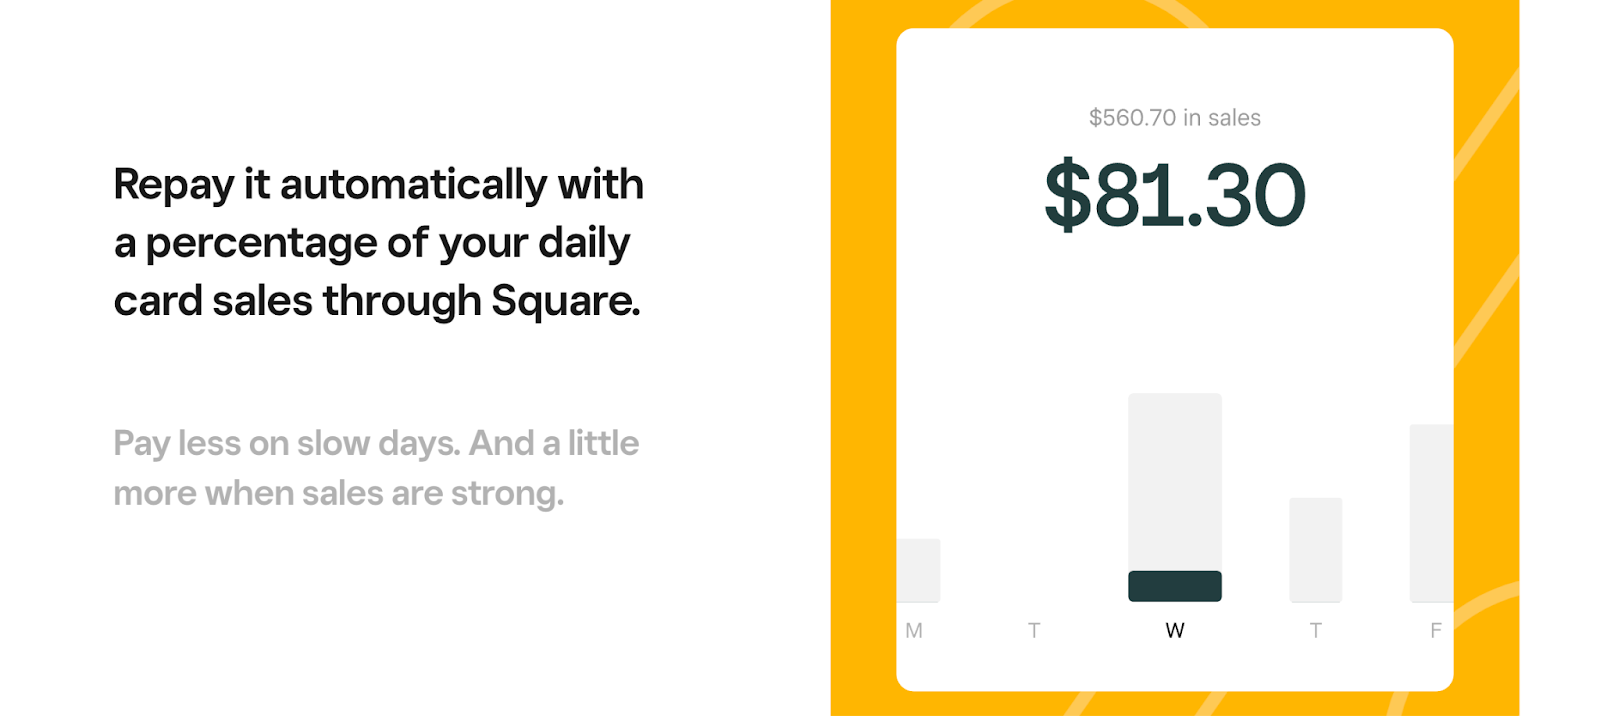
On days when your sales are high, you pay more towards the loan, and on slower days, you pay less. The loan offer is based on factors like your business’s payment processing volume, account history, and payment frequency.

You can make prepayments without any penalty. Square loans do not require a personal guarantee. And, there are no late fees or additional charges apart from the initial flat fee associated with the loan amount. 

You might also like: What’s the Best Payment Processor for a Small Business? Really 

Square Business Loan Cost

What percentage are Square loans? Reddit

Square loans don’t have a traditional interest rate. Instead, they charge a flat fee – “factor rate” – and then automatically deduct a percentage of your daily sales until the loan is paid off. For example, if you took an $8K loan with a $1K fee, Square might deduct around 15% of your daily sales to repay the loan, which is an example from a real borrower. 

Business owners have reported varying factor rates on Square loans: 

  • 1.13 (13.68% on a $95K loan)
  • 1.14 (14% on a $1K loan)
  • 1.135 (13.56% on a $31.7K loan)

Editorial reviewers have reported Square business loan factor rates between 1.10 and 1.16 (10-16%). Again, this is not the same as APR and does not represent an interest rate.  

You might also like: The Payoff Loan Review: Is This the Debt Consolidation Option for You? 

Company Overview

Square small business loan

Square Inc. is a San Francisco-based, private, for-profit company that was founded in 2009 by Jack Dorsey and Jim McKelvey. The mission was to make it easier for small businesses to accept credit card payments. 

Their key industry markets are, restaurants, retail, and beauty. Square’s first product was a credit card reader that could be plugged into an iPhone to process cards on the go. 

Now, they offer a large vast range of business products including: 

  • Commerce solutions like payment hardware and POS, invoicing, an online ordering platform, and shoppable websites.
  • Customer marketing products including email and SMS marketing, loyalty programs, customer management, gift cards, and photo studio. 
  • Staff management tools like scheduling and time tracking, team accounts, and human resources. 
  • Business banking that includes checking, savings, loans, and credit cards. 
  • Technology and development including dev specialists, access to APIs (for integration with business software), and a dedicated app marketplace.  

Jack Dorsey remains in the driver’s seat as the company’s current CEO (he stepped into this position in 2022), and is also the co-founder and chairperson of Block Inc.

Square Inc. CEO Jack Dorsey

Block® is the parent company of Square®, Cash App®, Spiral®, and Tidal®. 

What companies are owned by Block?

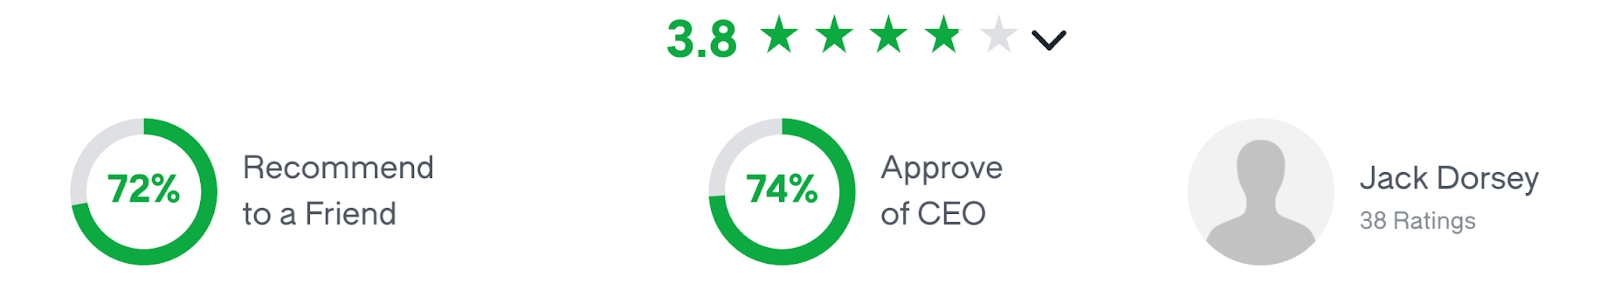
So, Square’s leadership is pretty corporate-minded, and employees seem to like that. According to Glassdoor®, most staff would recommend working at Square to a friend (72%) and approve of the CEO (74%). 

Square Inc. careers

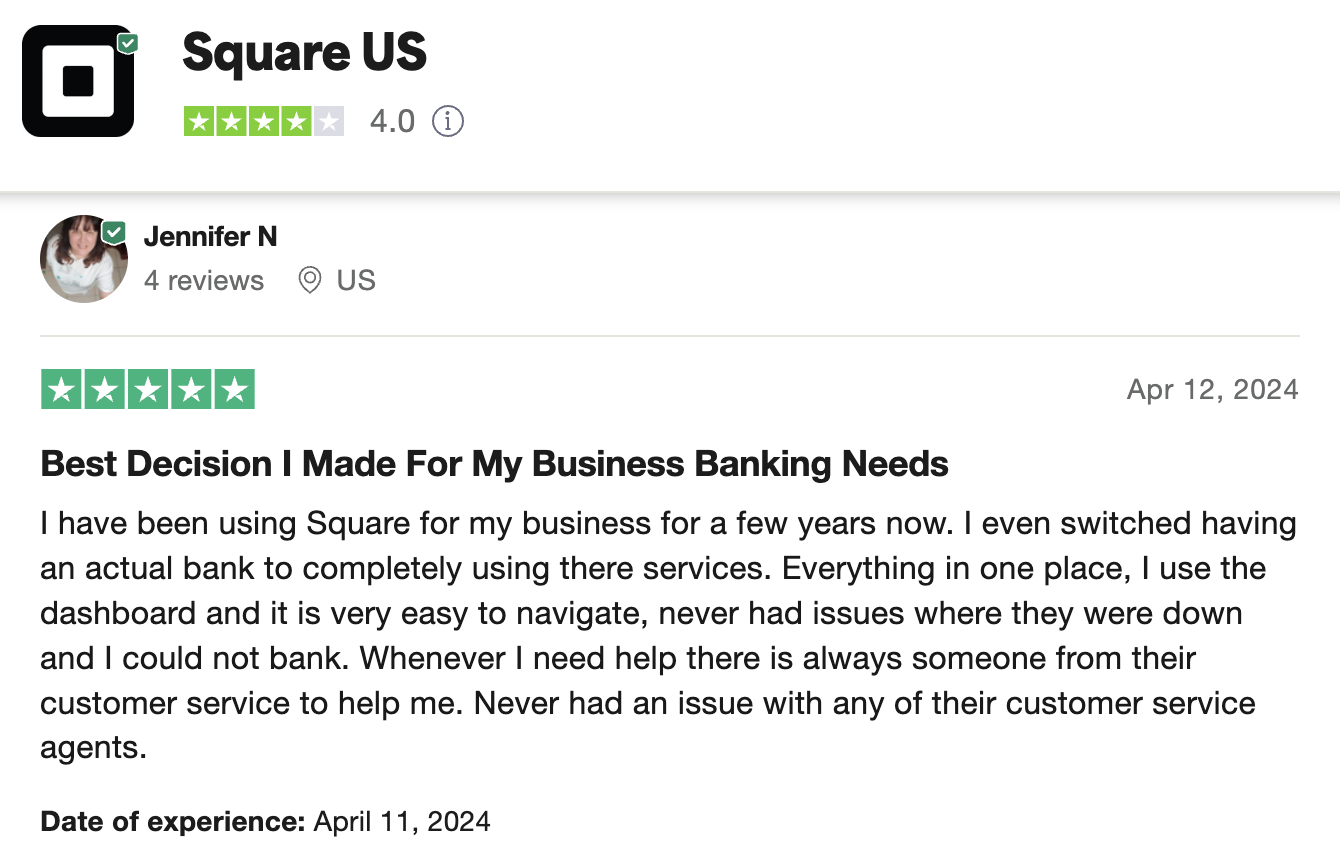
The majority of Square’s business customers seem to approve as well, with a 4-star trust rating on Trustpilot. Overall, Square receives positive feedback from users who appreciate its easy-to-use platform and helpful customer service. Customers value features like simplified navigation, quick deposits, and convenient payment options. 

Square reviews Trustpilot

Many have remained loyal to Square for years, citing its reliability and integrated functionalities for managing listings, reporting, and website credit card processing. However, some users have encountered issues with account deactivation and slow customer service response times, indicating areas for improvement in Square’s service experience.

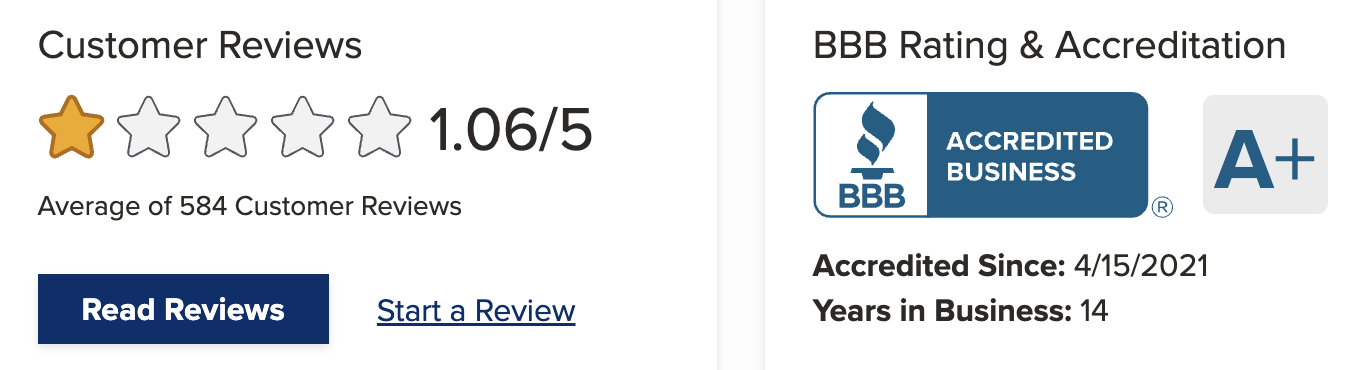
Meanwhile, Square Inc. has a 1.06-star customer rating and A+ rating with the Better Business Bureau (BBB).

It always surprises me to see how BBB grades are issued. Square Inc. has had 1,041 complaints closed on the platform in the past 12 months and 3,255 in the past 3 years—This seems high to me.  

As of January 26, 2024, Block is facing a class action over a provision in its terms of service barring users making any “objectionable” statements about the company in public. The parent company is actually party to several ongoing legal cases, both as a plaintiff and defendant across the country. But, I didn’t see anything to make me think that the company is conducting fraudulent business. 

Finally, Square business loans are issued by Square Financial Services, Inc., a Utah-Chartered Industrial Bank. Member FDIC. 

You might also like: Novo Bank Review: First-Rate Small Business Banking or Scam? 

How Do Square Business Loans Work? 

Now that we have all the fine details out of the way, let’s explore the features of a Square loan and what you can expect if you decide to accept an offer. In all, the process is pretty automated and convenient, but there are caveats you should be aware of. 

1. Automated Offers 

How much loan can I get from Square?

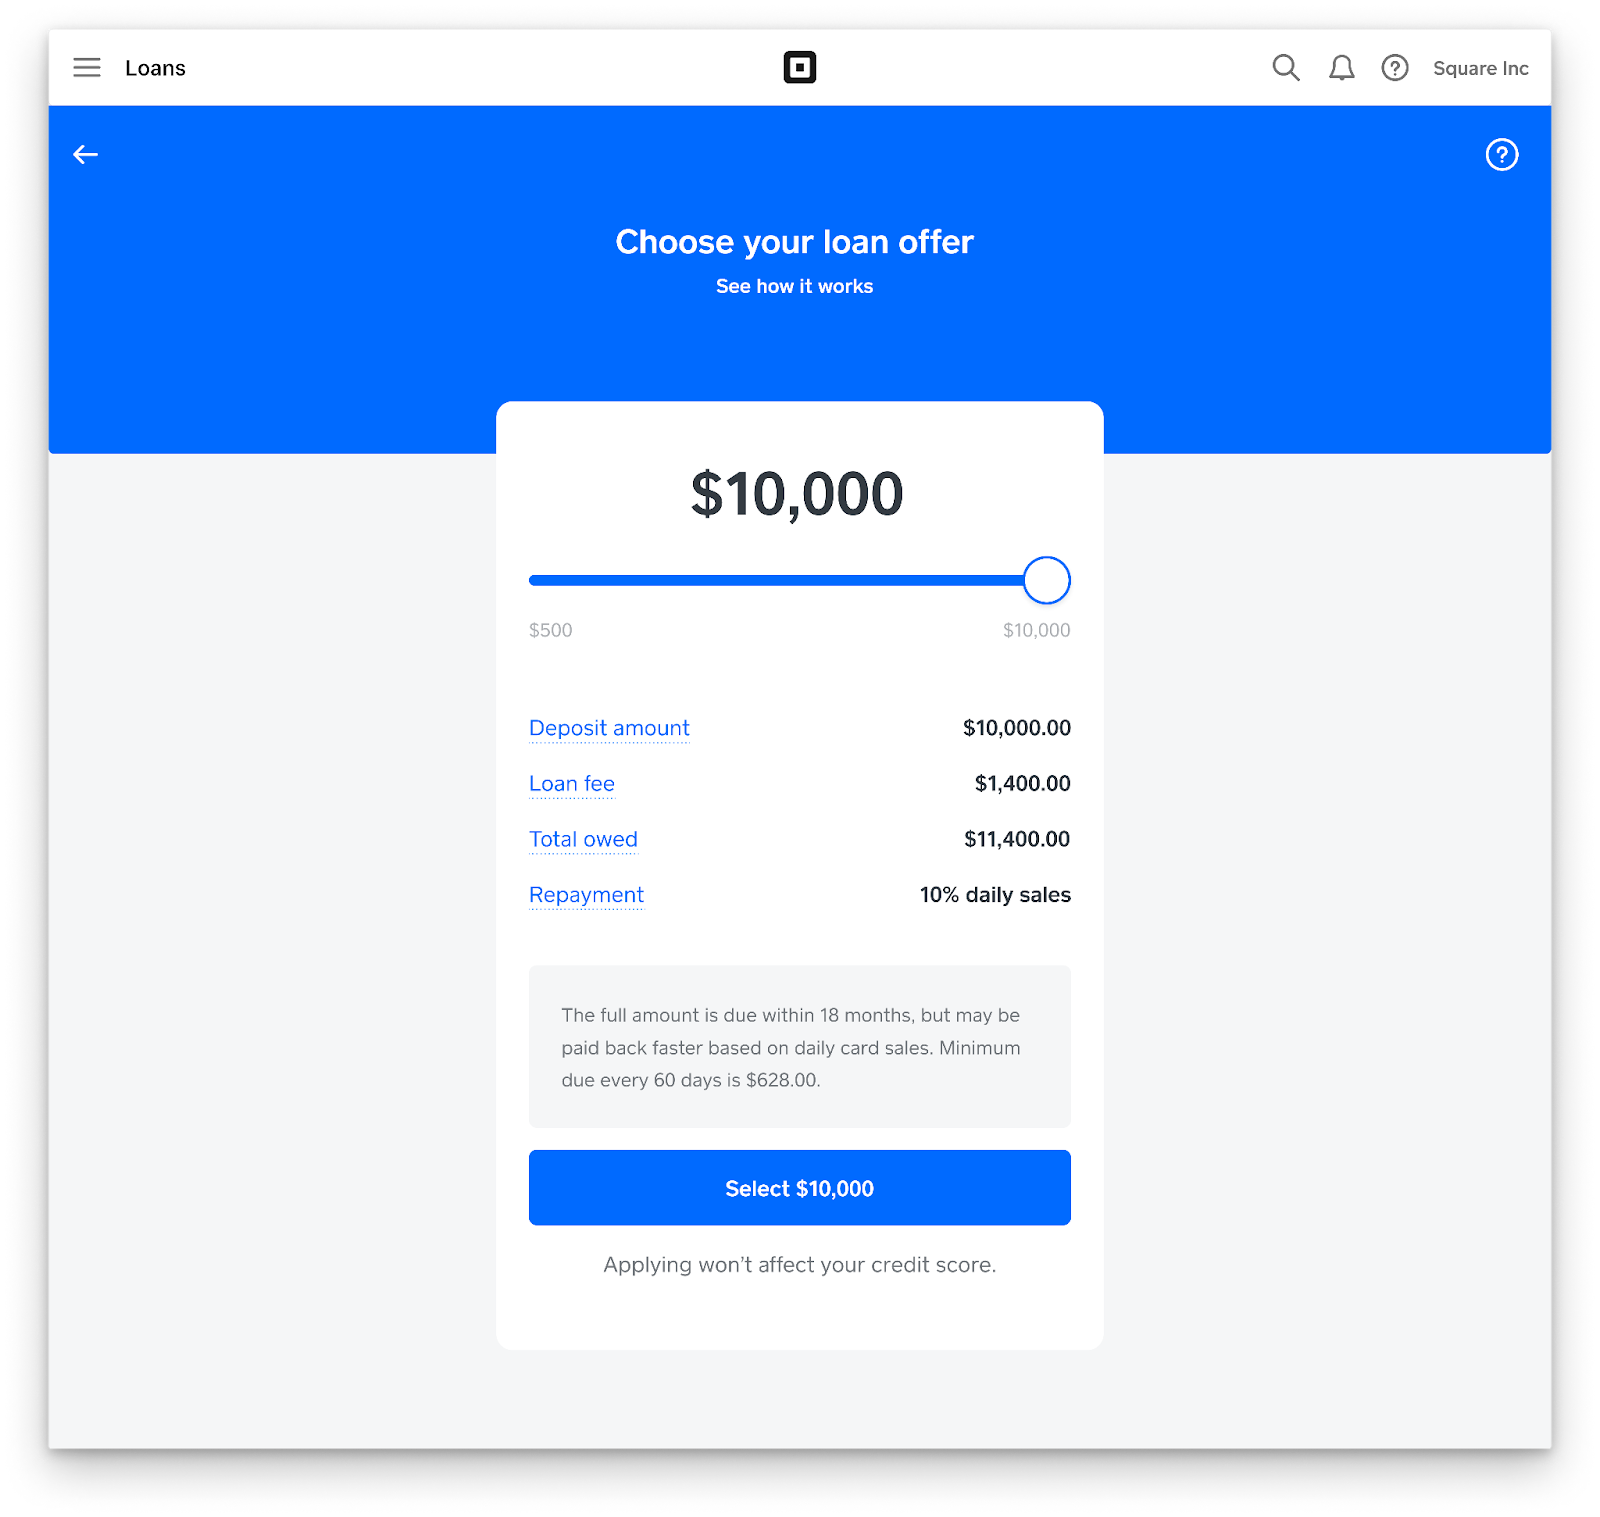
With Square business loans, you don’t apply for a loan—instead, you accept an offer through your dashboard. The platform looks at the eligibility factors, then lets you know if you can secure extra funds for your business. 

Qualified businesses will receive an offer through their dashboard and via email if their account looks like a good fit for funding. Then, all you need to do is accept it. 

Note that simply signing up for a Square account doesn’t make you automatically eligible.  

You might also like: Y Combinator: Fast Track to Success or Waste of Time? 

Square Business Loan Requirements

Why won't Square give me a loan?

To get an offer, you will need to meet certain requirements. First of all, you need to use the Square payment processing platform. 

Then, Square looks at several performance-based factors to determine loan eligibility:

  • You should process at least $10,000 in a year through Square to be eligible for a loan offer. 
  • Your Square account should show consistent payment processing to show that you can repay the loan through your account transactions.
  • A good mix of new and returning customers will strengthen your ability to qualify. 
  • Payment disputes and chargebacks can make you ineligible for a Square loan. 
  • Your bank account will be reviewed for insufficient funds, which will impact your eligibility. 
  • Payment limits or reserves on your Square account could disqualify you. 

If you have multiple Square accounts or locations with outstanding Square loans, they should all be in good standing, actively processing transactions, and loan repayment needs to be current.

Recommended: Here’s How to [Actually] Get Business Credit With Just an EIN +More Options 

2. No Personal Guarantee

Is Square still doing loans?

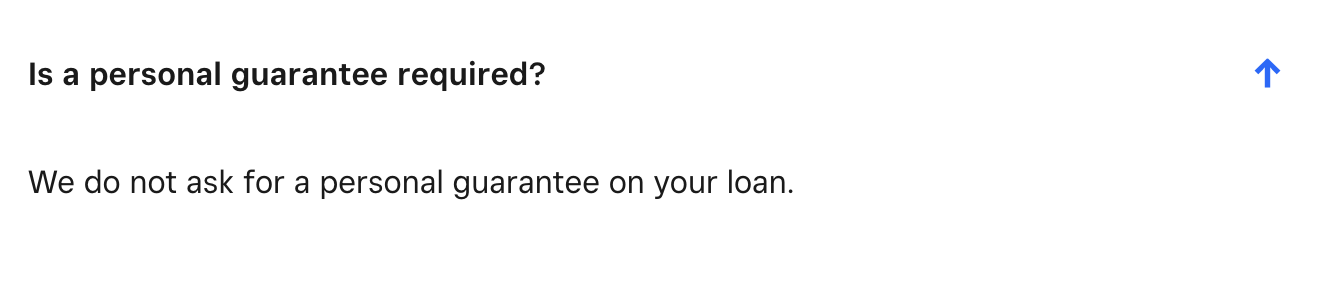
There is no personal guarantee (no PG) on a Square business loan—This means that Square won’t come after your personal assets if the loan defaults. And, no PG typically means no hard credit pull, and no impact to your credit score. 

For loan amounts up to $100,000, Square doesn’t need any collateral. 

However, for loans that exceed $100,000, they may secure your business assets and file a Uniform Commercial Code (UCC) statement with the Secretary of State (SoS) in your business’s jurisdiction.

Filing a UCC statement with the SoS creates an official record that establishes a Square’s interest in your business assets. This filing serves as a public notice to inform others, such as potential lenders or buyers, that the creditor has a security interest in your assets.

By filing a UCC statement, the lender is protecting their interest in case you default on the loan—It establishes a legal claim or lien on specific business assets like: 

  • Inventory
  • Equipment
  • Accounts receivable

This process is important for secured transactions and helps lenders secure their position in case of business insolvency or default…you won’t have to worry about this at all if your loan is less than $100K. 

You might also like: No-Doc Business Loans: Get Funds Without Proof of Income 

3. Quick Funding 

square loans

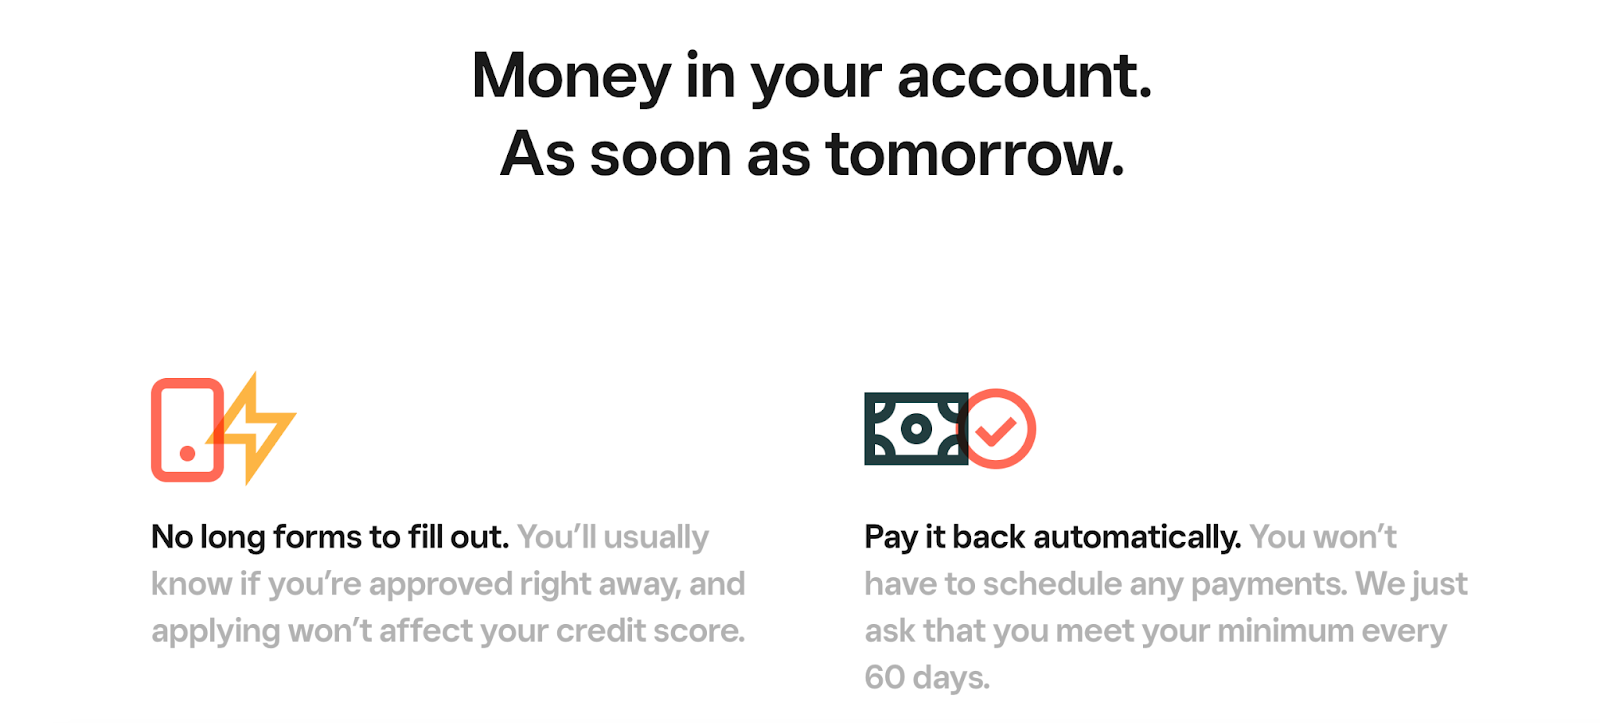
Square’s funding process is streamlined for speed and efficiency, aiming to deposit funds into your account as quickly as the next business day. 

When you apply for a loan, you’ll usually receive an immediate decision on approval, and this won’t have any impact on your credit score. 

Recommended: How Long Does It Take to Build Business Credit? Fast Guide 

4. Automatic Repayment

How are Square Loans Paid Back?

Square loans are repaid as a percentage of your daily sales. When business is good, payments are higher and on slow days, payments are lower—This is typical with a cash advance versus a fixed payment with a traditional business loan. 

The daily repayment method can result in an effective rate that’s higher than what you would probably find with a bank loan or credit card. While this type of loan can be convenient, it’s important to understand the total cost and impact on your cash flow, especially during slower months.

Square business loan calculator

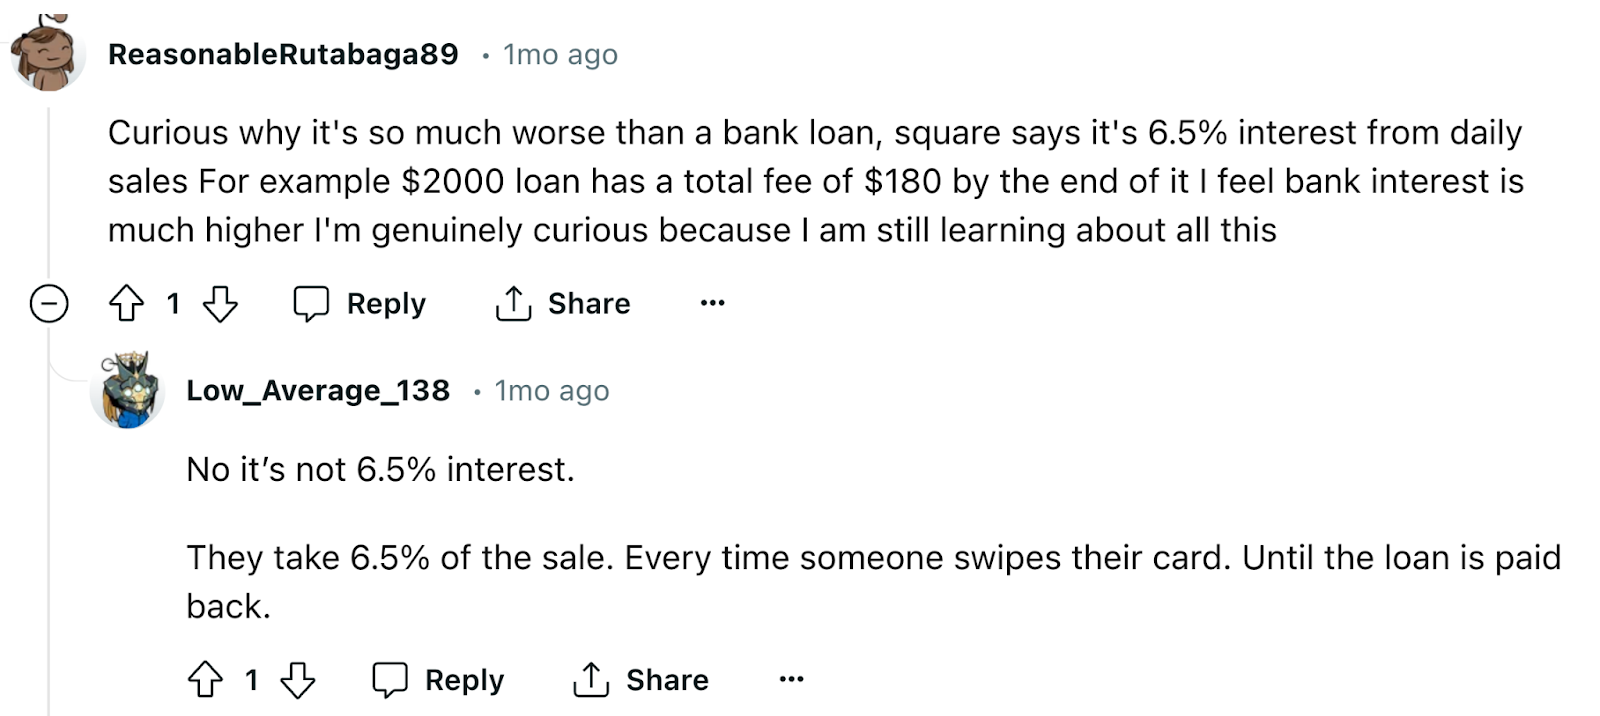
Anecdotally, I’ve seen borrowers mention repayment terms with percentage of daily sales as low as 6.5% and as high as 21%. If your repayment plan is charging too much, you may be able to negotiate lower daily repayment.  

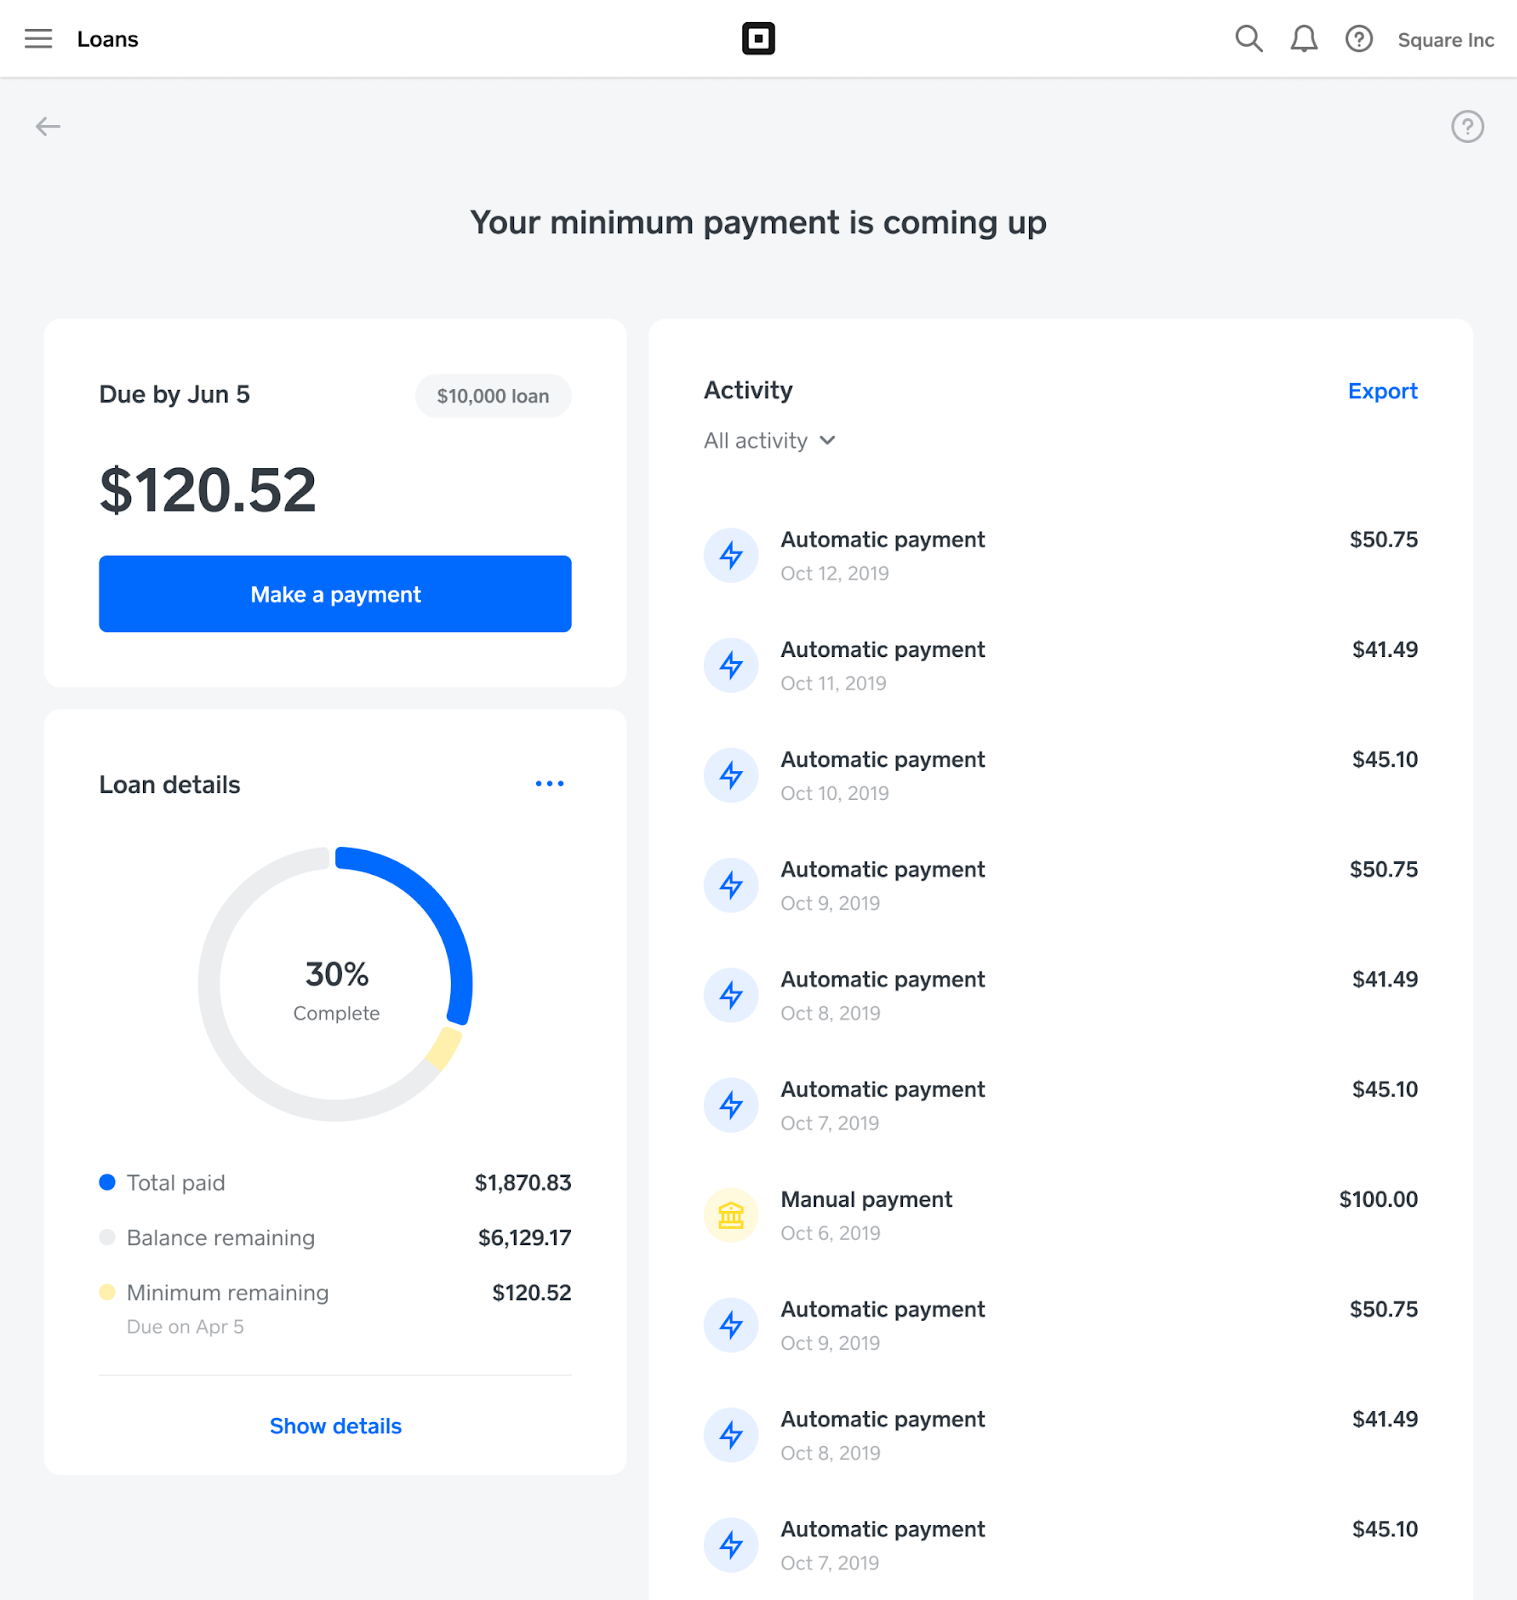
Moreover, Square loans require a minimum payment of 1/18th of the initial loan balance every 60 days, and the full loan amount must be repaid within 18 months. With this structure, for an $8K loan with a $1K fee, you would need to make a payment of at least approximately $444.44 every two months, and the total loan (including the fee) would need to be repaid within a year and a half at a rate of approximately $500 per month.

You might also like: Could a Stripe Capital Loan Get Your Business Through a Rough Patch? 

5. Transparent, Fixed Costs

Square loan login

Before you accept a loan, you will see the loan amount, fees, and repayment percentage upfront. It’s pretty straightforward. 

But, on top of the loan fee, you will pay processing fees on each transaction—all payment processors charge these fees in addition to any loans you might be repaying. 

Square’s processing fees differ based on the payment method:

  • For in-person transactions, 2.6% of the transaction amount plus 10 cents per transaction.
  • For online payments, 2.9% of the transaction amount plus 30 cents per transaction.
  • For invoice payments, 3.3% of the transaction amount plus 30 cents per card transaction, or 1% with a minimum of $1 per transaction for ACH bank transfers.
  • For manually entered transactions, 3.5% of the transaction amount plus 15 cents per transaction.

So, between the loan repayment and processing fees, you could pay upwards of 12.6% to 19.5% of each transaction until your loan is settled.  

You might also like: What You Need to Know About PayPal LoanBuilder for Business 

6. The Square App 

Square business loan login app

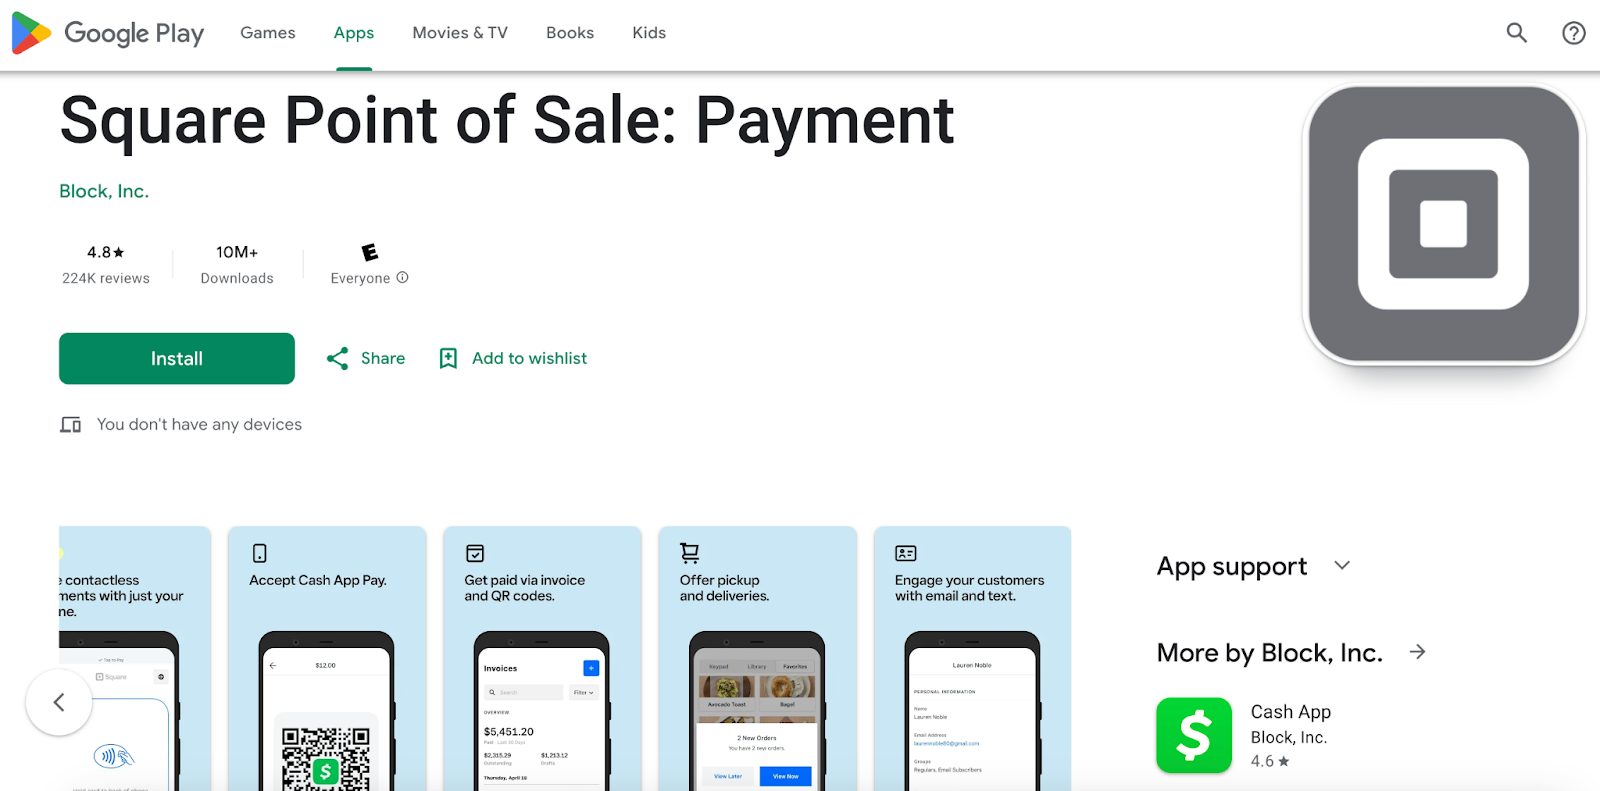
The Square Point of Sale (POS) app is available in the Google Play and Apple app marketplaces. It lets you accept payments easily using credit cards, contactless payments (like Google Pay and Apple Pay), gift cards, and invoicing right from your phone or computer. 

Within the app, you can: 

  • Manage your inventory
  • Track sales
  • View reports 

Plus, you’ll have funding options such as next-day transfers to your bank account for a fee or free transfers in one to two business days. 

Many users find it straightforward to use and appreciate its integration with other Square tools like eCommerce and team management. However, some people have experienced issues with customer support and account deactivation, so it’s important to keep that in mind.

You might also like: Expensify Card Review: A Detailed Expense Tracking Analysis 

Frequently Asked Questions

When does Square offer you a new loan?

Square offers loans through its Square Capital program based on your account activity and sales performance. Eligible sellers are notified of loan offers within their Square Dashboard or through email. Some borrowers have been offered new loans while still in repayment for a current loan. 

What is the limit on Square business?

The loan amount offered by Square Capital varies based on your business’s processing history, sales volume, and account activity. Square does not publicly disclose a fixed maximum limit, but you can check your eligibility and view loan offers in your Square Dashboard or contact Square Support for more details.

Conclusion: Are Square Business Loans Legit? 

In short, yeah, Square business loans are cash advances that are offered by a legitimate, trusted company. Cash advances have been known to get businesses through a rough patch or quickly fund short-term needs. 

However, they have always been the business equivalent of a personal payday loan. I never recommend that business owners take out a cash advance, or any other factored loan, unless there is absolutely no other alternative—This is because the costs are too high.

Instead, I suggest you research all of your options and take advantage of the offers that charge the lowest rates to optimize your business finances. 

Do you want to learn how to obtain up to $100K in as few as 30 days? Join Business Credit Workshop today!

Clover Capital Review: Read This Before You Accept an Offer

April 21, 2024 By Joe

Clover Capital

If you use Clover’s payment processor, you may have seen an offer come through via email or your Clover dashboard that asks you to see if you’re pre-qualified for Clover Capital. It may seem like a convenient, accessible way to secure the capital your business needs to grow and thrive. Now, you’re trying to find out if this offer is legit or just get more details. 

Here, I’ll walk you through everything I know about Clover Capital so that you can decide if it’s the right funding option for your business. We’ll look at what it is and peek behind the scenes at the company, how it works, and answer some common questions.  

This is what’s in store: 

  • What is Clover Capital?
    • What Percentage Does Clover Capital Take?
    • How Much Does Clover Capital Cost?
    • Company Overview
  • How Does Clover Capital Work?
    • 1. No Hard Credit Pull
    • 2. No Personal Guarantee
    • 3. Quick Funding
    • 4. Fixed Loan Costs
    • 5. Automatic Repayment
    • 6. The Clover Go® App
  • Frequently Asked Questions
  • Conclusion: Is Clover Financing Legit?

Now, let’s jump in! 

What is Clover Capital? 

Clover Capital review

Clover Capital is a financing option advertised to help businesses access funds quickly by leveraging their future credit and debit card sales. It’s not exactly a loan; rather, it’s an advance based on your projected sales. 

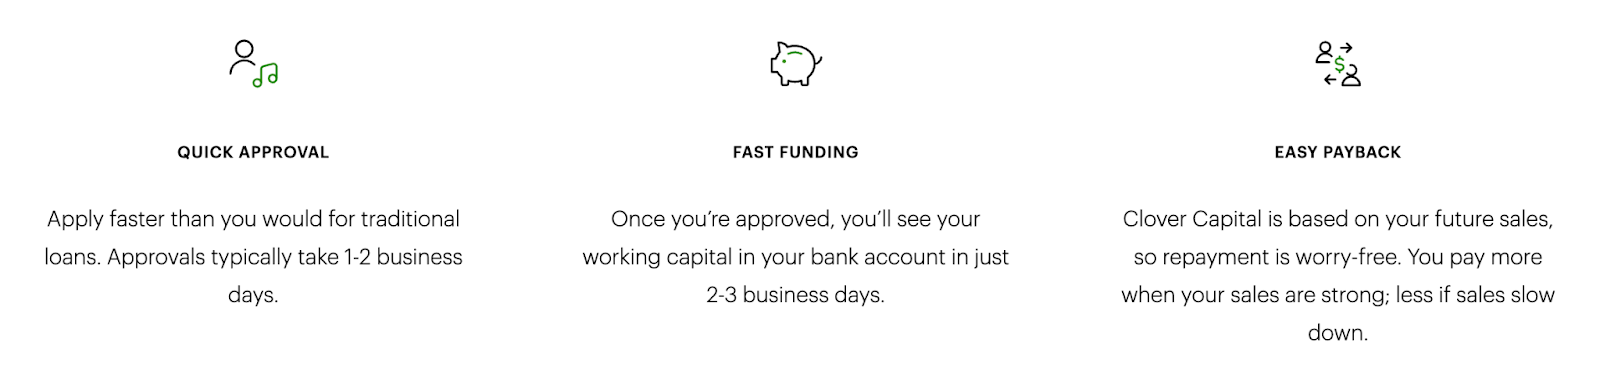
The process is straightforward: you apply, get approved within 1-2 business days, and receive the funds in 2-3 business days. The payments are then automatically deducted from your daily card sales, making it convenient and flexible—when sales are up, you pay more; when they’re down, you pay less.

To qualify, your business typically needs to be at least six months old with a minimum monthly processing volume of $1,000 over the past three months. 

Once approved, you can use the funds for various business needs like: 

  • Inventory
  • Equipment upgrades
  • Hiring staff
  • Marketing initiatives

A capital advance can pay for pretty much anything that can fuel business growth.

The process is quite streamlined: apply online, choose the best offer presented, get funded, and then enjoy the automated repayment process.

You might also like: How to Convert Credit Cards into Cash 

What Percentage Does Clover Capital Take? 

Clover Capital Advance

For Clover Capital repayments, the daily withholding percentage is determined by your credit card sales volume—it typically falls within a range of 8% to 15%. 

So, you’ll pay more during periods of strong sales and less during slower periods. 

How Much Does Clover Capital Cost? 

Clover Capital Factor Rate

Factor rates are used instead of traditional interest rates in merchant cash advances like Clover Capital. They are fixed amounts that do not compound over time, unlike interest rates. 

The specific factor rate assigned to a business is influenced by the: 

  • Business’s risk profile
  • Amount of the advance
  • Expected repayment period.

According to CardPointe (an integrated payment terminal solution that provides support for Clover Flex and Clover Mini terminals), the factor rate for Clover Capital generally falls around 1.29, varying within a range of 1.10 to 1.29. Essentially, if you receive funding of $10,000 with a factor rate of 1.29, the total amount to be repaid would be $12,900 (10,000 x 1.29).

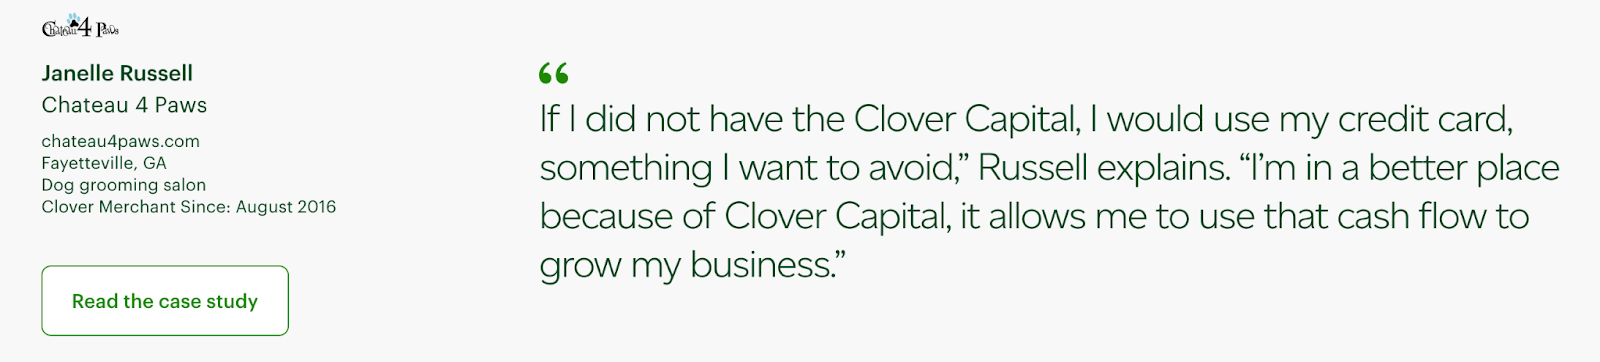
Something interesting I noticed is that the borrower review on the Clover Capital landing page notes that without Clover Capital they would use their credit card, which they wanted to evade.

The average interest rate on a credit card is 21.47%, according to the Federal Reserve, while community banks and credit unions offer lower rates (in my experience). Plus, you only have to worry about credit card interest if you carry a balance. 

Depending on the repayment strategy and payment amount, a credit card with a 21.47% interest rate and consistent, higher-than-minimum payments could potentially be cheaper than a factored loan with a 1.29 factor rate—It’s important to calculate and compare the total costs under different scenarios to determine the most cost-effective financing option based on your financial situation and repayment capabilities.

Recommended: 6 Best 0% APR Business Credit Cards to Check Out 

Company Overview

Clover Network Inc

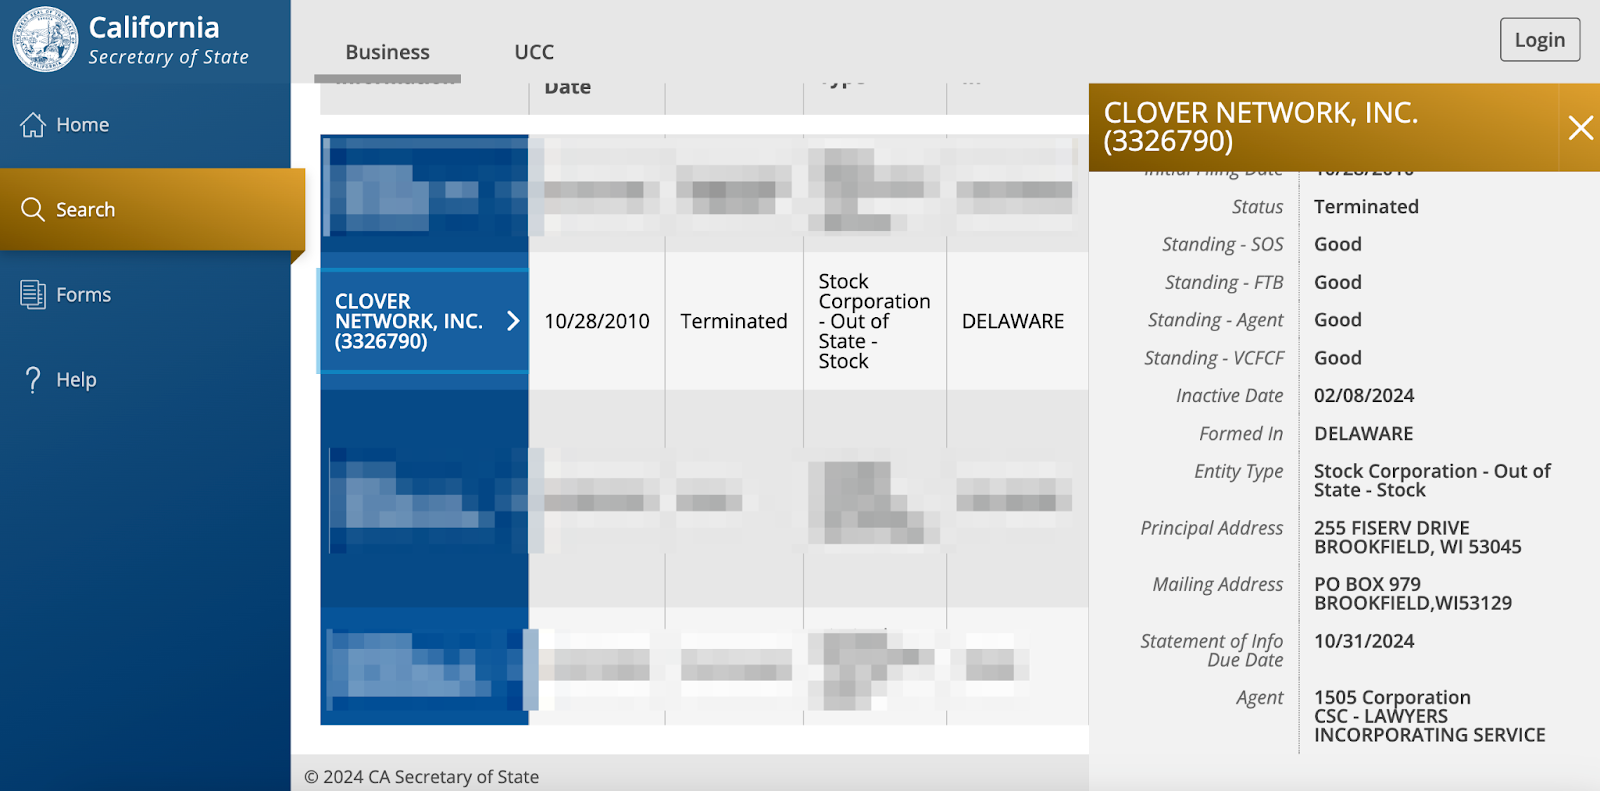
Clover, technically Clover Network Inc., is a private, for profit, California-based business that was founded in 2010 by John Beatty, Kelvin Zheng, Leonard Speiser, Mark Schulze. The company is incorporated in Delaware, which is known for being corporate-friendly.

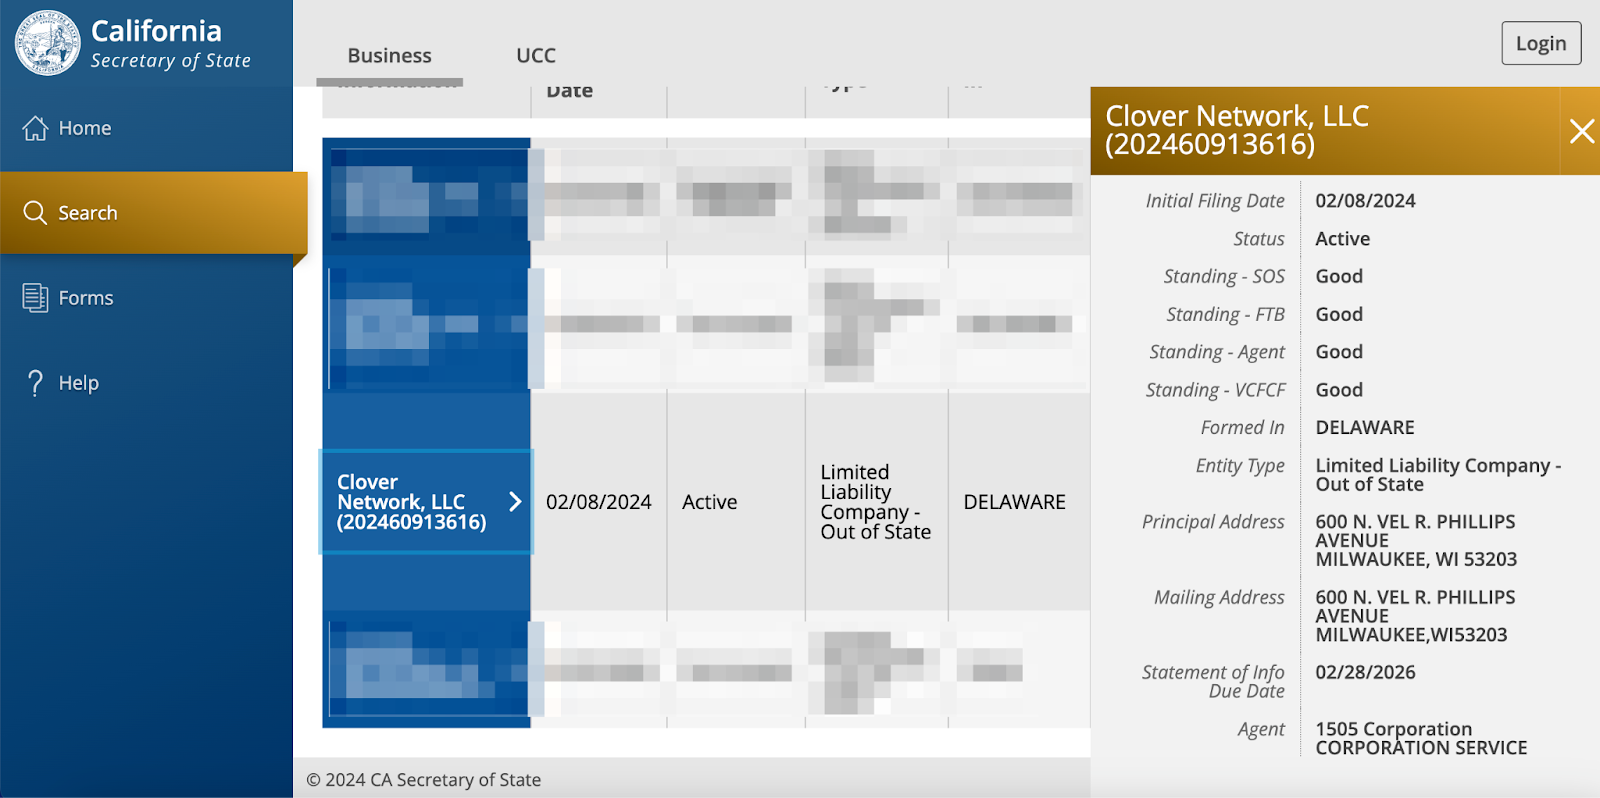
According to the California Secretary of State, the company was re-registered as Clover Network LLC in 2024—This raised a red flag, so I dug around to see if I could find out why this might have happened. 

Clover Network LLC

First, I found a class action lawsuit against Clover Network LLC, in which the company agreed to pay $15 million for soliciting services to phone numbers on the National Do Not Call Registry. Claim recipients would get about 60 bucks each. 

Then, I uncovered several other lawsuits in various stages—The legal claims against Clover Network Inc and Clover Network LLC involve patent infringement and other intellectual property claims. 

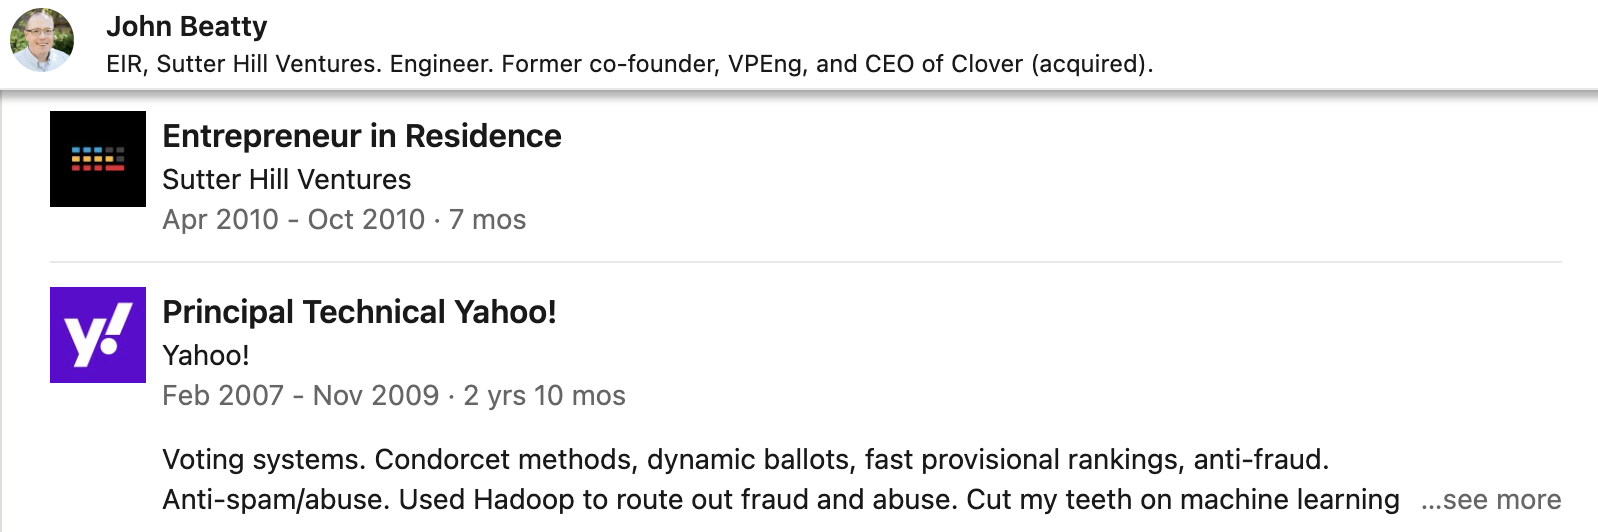
One of the original co-founders, John Beatty, is Clover’s current CEO. Prior to launching Clover, Beatty was part of a handful of engineering and entrepreneurial ventures. None of his prior history seem to relate to payment processing, but instead technology. 

Clover Network CEO

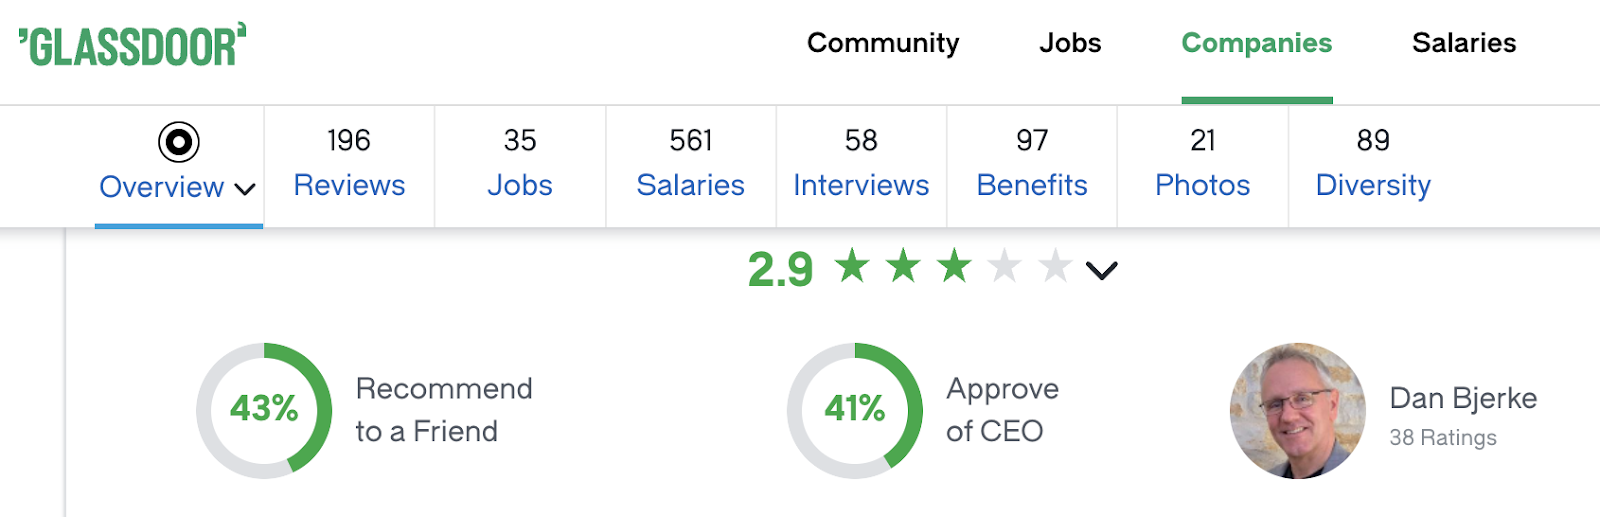
According to Glassdoor, Clover isn’t the best company to work for. Only a minority would recommend the company to a friend and even fewer approve of the company leadership. Staff opinions tell a lot about a company’s internal ethics and standards.  

Clover Network on Glassdoor

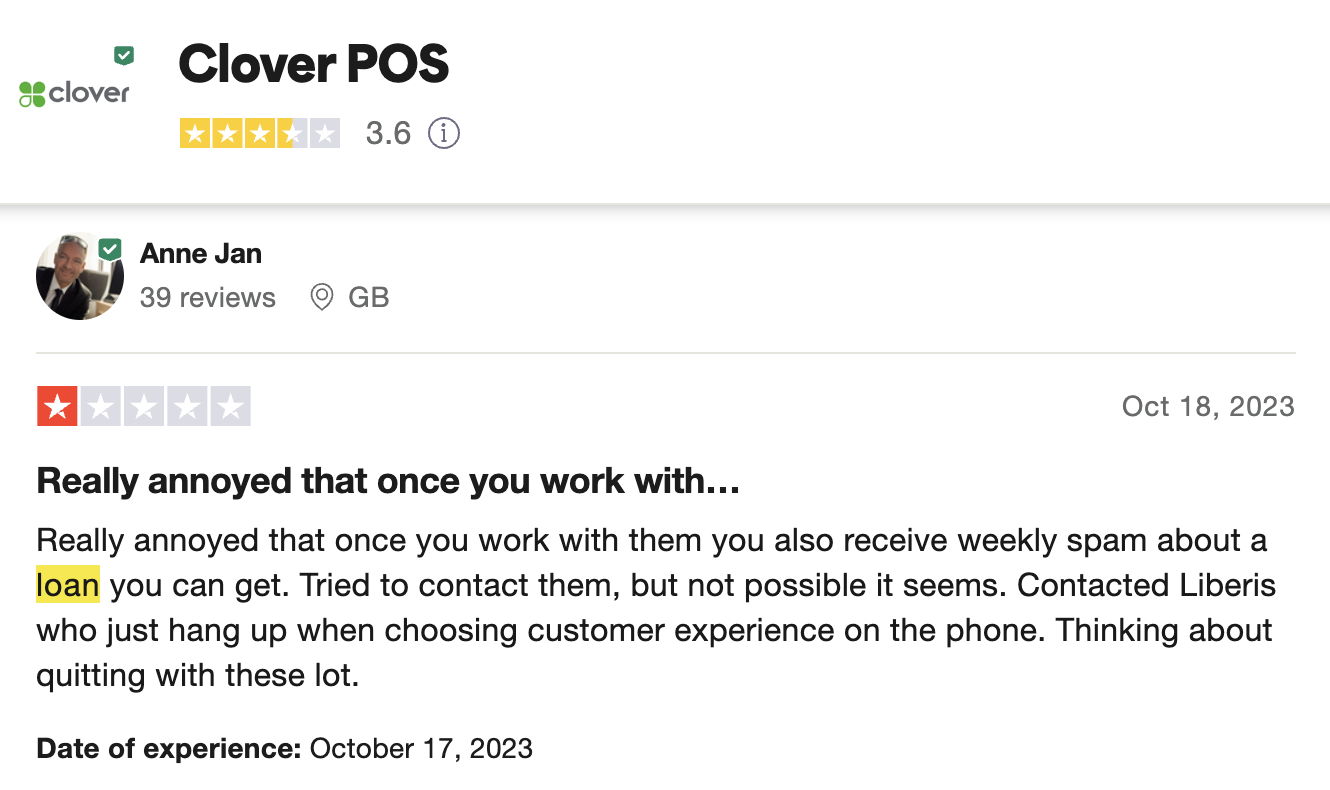
Even more importantly, customer views speak to the level of support and transparency that a company provides. Clover POS has a 3.6-star rating on the Trustpilot platform, which isn’t great. 

Clover Reviews Trustpilot

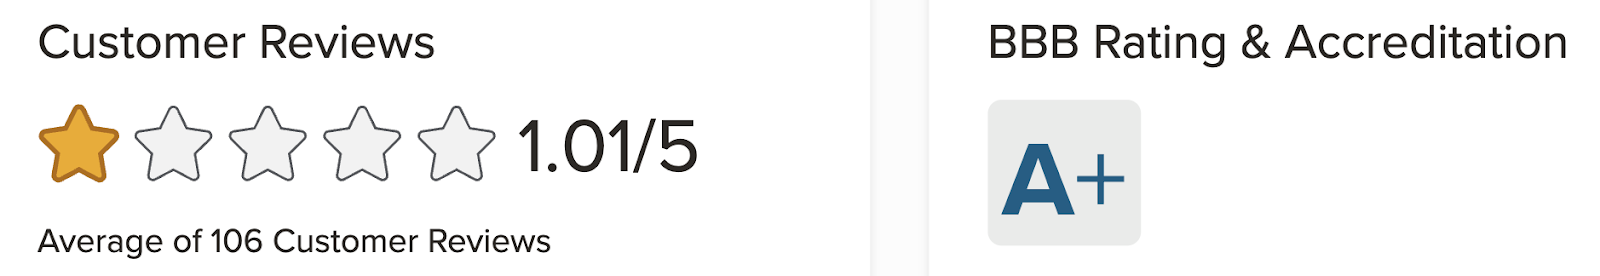
I couldn’t find an active Better Business Bureau profile for Clover, so I don’t know about recent complaints that may have been made on that platform. However, I did find that Clover’s parent company, Fiserv, has a 1-star rating, which is a bit of a red flag. 

Clover Reviews BBB

For the most part, Clover Network’s customers and staff are dissatisfied with the company. However, some people love the company, and experiences vary greatly. 

Recommended: What’s the Best Payment Processor for a Small Business? (Really) 

How Does Clover Capital Work? 

Clover Capital works by providing businesses with quick access to funds based on their future credit and debit card sales—It operates as a merchant cash advance rather than a traditional loan. 

Here’s how it generally works.

1. No Hard Credit Pull 

Clover Capital login

One of the perks of Clover Capital is that it won’t impact your credit score because there’s no hard credit pull to your personal or business credit. Clover doesn’t run your credit—This allows you to explore financing options without worrying about potential credit score decreases or leaving marks on your credit reports. 

Instead of focusing solely on credit history, Clover Capital considers factors like your business’s processing history and sales volume to determine funding eligibility. This approach provides you with accessible financing while protecting your credit scores from unnecessary inquiries.

Recommended: This is How to Leverage Business Credit to Transform Your Life 

2. No Personal Guarantee

Clover Capital loan

With Clover Capital, there is no personal guarantee required—This means you aren’t personally liable for the business debt. Typically, in business financing, a personal guarantee requires the business owner to be responsible for repayment if the business cannot fulfill its obligations.

With Clover Capital, the absence of a personal guarantee gives you an added layer of protection. In the event the business experiences difficulties and cannot repay the funding, the obligation remains with the business entity itself rather than extending to your personal assets or credit.

You might also like: Business Credit Cards without Personal Guarantee 

3. Quick Funding 

Does Clover have any hidden fees?

Once your application is submitted with the required documents, Clover Capital aims to provide approval swiftly, often within 1-2 business days. This quick approval process enables you to access the funds you need promptly to address immediate financial needs or capitalize on growth opportunities without unnecessary delays.

Overall, the combination of streamlined documentation requirements and expedited approval timelines makes Clover Capital a handy option for businesses seeking timely access to working capital.

You might also like: How Long Does It Take to Build Business Credit? Fast Guide 

4. Fixed Loan Costs

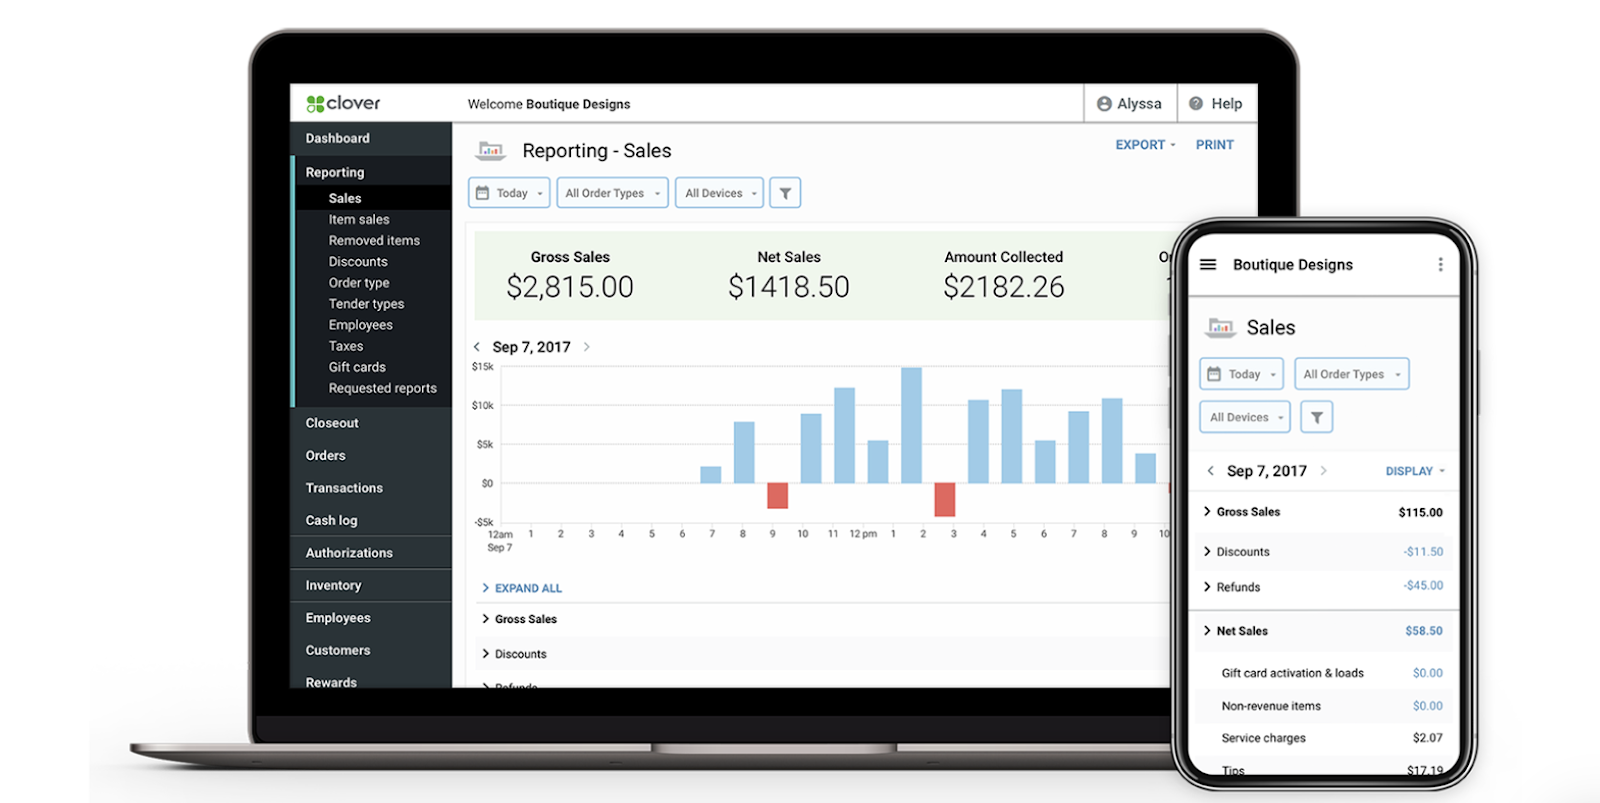
Clover dashboard

Clover’s fixed loan cost, represented by a factor rate, offers several benefits to businesses: 

  1. It provides predictable repayment terms, allowing for easier budgeting and financial planning without surprises from fluctuating interest rates. 
  2. The transparent terms of the fixed loan cost ensure clarity in pricing, making it easy for you to understand the total repayment amount and assess affordability. 
  3. Payments are flexible and adjust based on daily credit and debit card sales, making it easier to manage during slower sales periods. 

Overall, Clover’s fixed loan cost provides you with a transparent, predictable, and flexible financing solution tailored to your needs.

You might also like: Could a Stripe Capital Loan Get Your Business Through a Rough Patch? 

5. Automatic Repayment 

How do Clover payments work?

Automatic Repayment with Clover Capital streamlines the repayment process, making it convenient and hassle-free. Once approved, a percentage of your daily credit and debit card sales is automatically deducted to repay the loan. This ensures consistent payments aligned with your business’s cash flow.

However, this feature comes with a caveat: you need to use Clover POS (Point of Sale) to facilitate the loan repayment. Using Clover POS integrates the repayment process seamlessly into your daily business operations, but it requires businesses to utilize Clover’s POS system for payment processing to benefit from automatic repayment.

This comes with a caveat…you need to use Clover POS to repay the loan. This could be a deterrent, particularly if you’re not already using their payment platform. 

6. The Clover Go® App

Clover login

The Clover Go app is a mobile point-of-sale (POS) for small businesses. It enables you to accept credit cards, signature debit cards, and other payment forms directly on your mobile device(s). With Clover Go, you can process transactions securely and conveniently on the go.

Key features of the app include:

  • Credit card, signature debit card, and other payment method acceptance.
  • Real-time sales tracking to remotely monitor transactions and performance.
  • Business management functionality accessible from anywhere.

Users have rated Clover Go highly, with 4.6 stars on the Google Play store and 4.8 stars on the iOS marketplace. With Clover Go, you can accept payments, monitor sales, and manage operations from virtually anywhere. 

Frequently Asked Questions

What is the difference between Square Capital and Clover Capital? 

Square Capital offers business loans to eligible Square merchants, with repayment tied to daily Square sales. Clover Capital, on the other hand, provides merchant cash advances based on future credit and debit card sales for businesses using Clover POS systems.

How long does Clover Capital take to process? 

Clover Capital typically processes applications in 1-2 business days after receiving all required documentation. Funding is usually disbursed within 2-3 business days after approval.

Conclusion: Is Clover Financing Legit?  

Now, to answer the ultimate question: Is Clover worth it for small business?  

Clover Capital is a cash advance offer from a legitimate company that’s registered and actively operating. However, I never recommend that a small business seek cash advance funding unless there is absolutely no other option — the fees are just too high. And, after you sprinkle a few legal allegations on top, I couldn’t in good conscience make a recommendation for Clover Capital. 

Instead, I would recommend you shop around and explore all of your business funding options and choose the financing that aligns best with your needs and goals. 

Do you want to learn how to obtain up to $100K in business credit in as few as 30 days? Join Business Credit Workshop today!
What You Need to Know About PayPal LoanBuilder for Business

April 15, 2024 By Joe

PayPal Loan Builder

PayPal LoanBuilder is advertised as a quick, convenient way to get up to $100K in business funding. The company is more than reputable, and their marketing makes it sound like the easiest financing option in the world. But, what are the terms, how much does it cost, and is this really the best loan for your business? 

Let’s find out what LoanBuilder is, how it works, and explore exactly what you can expect if you apply. 

This is what’s in store: 

  • What is PayPal LoanBuilder?
    • How Much Does PayPal LoanBuilder Cost?
  • How Does PayPal LoanBuilder Loan Work?
    • 1. Apply With No Impact to Your Credit
    • 2. “Customizable” Funding
    • 3. Fixed-Fee Loan
    • 4. Fast Access to Funds
    • 5. Accessible Business Funding
    • 6. Weekly Repayment Terms Up to 12 Months
  • Frequently Asked Questions
  • Final Thoughts

Now, let’s get to it! 

What is PayPal LoanBuilder? 

Loan Builder PayPal

PayPal’s LoanBuilder is a service that offers fixed-term small business loans from $5,000 to $100,000 for first-time borrowers and up to $150,000 for repeat borrowers—the financing option is designed to be fast and flexible, with funds potentially available in your business bank account as soon as the next business day after approval.

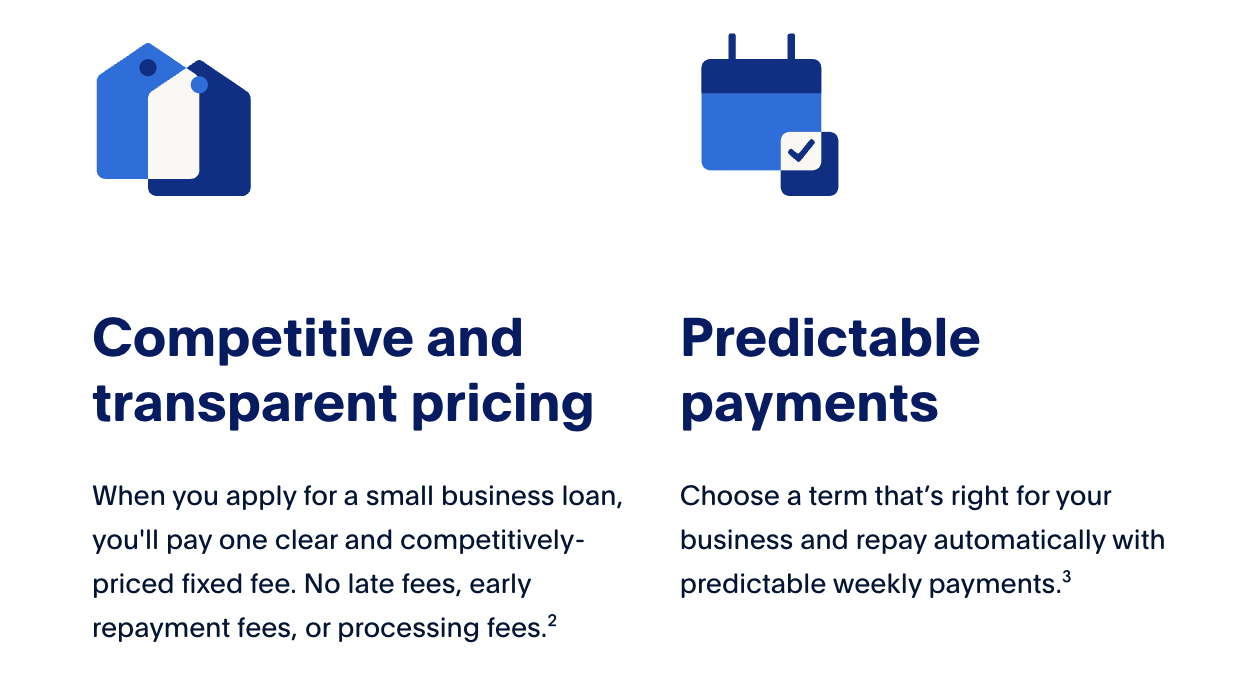
The loan comes with transparent pricing, where you pay a clear, fixed fee along with a $20 Returned Item Fee if a payment is returned. There are no late fees, early repayment fees, or processing fees. You can choose a repayment term that suits your business needs, and payments are automatically deducted weekly.

To check if your business is eligible for a LoanBuilder Loan, you can complete a quick online questionnaire. This process won’t impact your personal credit score. If eligible and approved, you can customize your loan amount and term, sign the contract electronically, and receive the funds quickly.

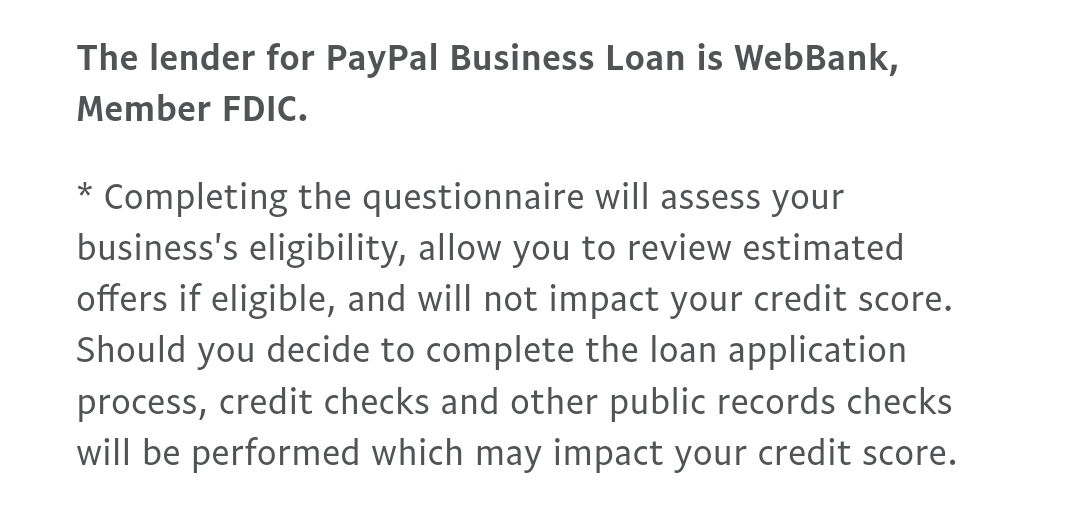
To qualify, your business needs to have been operational for at least nine months with an annual revenue of at least $33,300. Keep in mind that LoanBuilder is a service provided by PayPal in partnership with WebBank. The loan application and approval process is designed to be straightforward and streamlined, aimed at helping businesses manage cash flow, finance projects, or tackle other business challenges.

paypal loanbuilder requirements

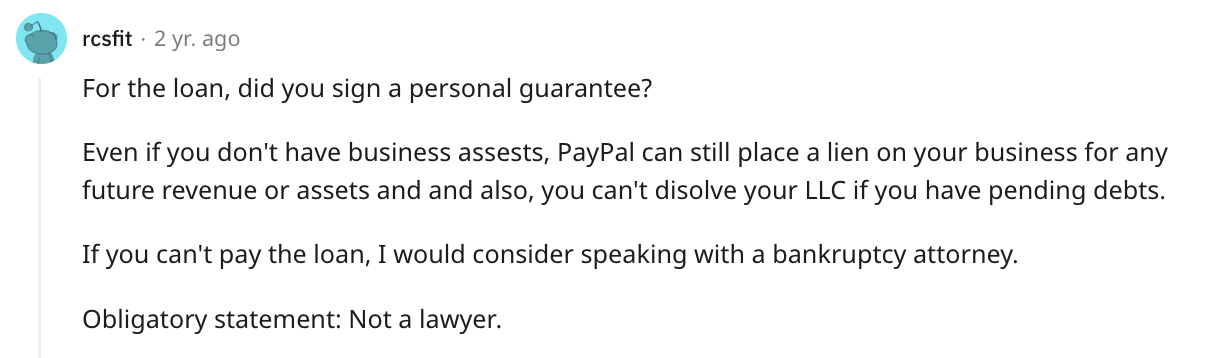
A LoanBuilder loan does require a personal guarantee. 

You might also like: Business Credit Cards without Personal Guarantee 

How Much Does PayPal LoanBuilder Cost? 

The cost of a LoanBuilder loan is determined by a single fixed fee known as the Total Loan Fee, which will be disclosed at the time of loan approval and remains consistent throughout the loan term. 

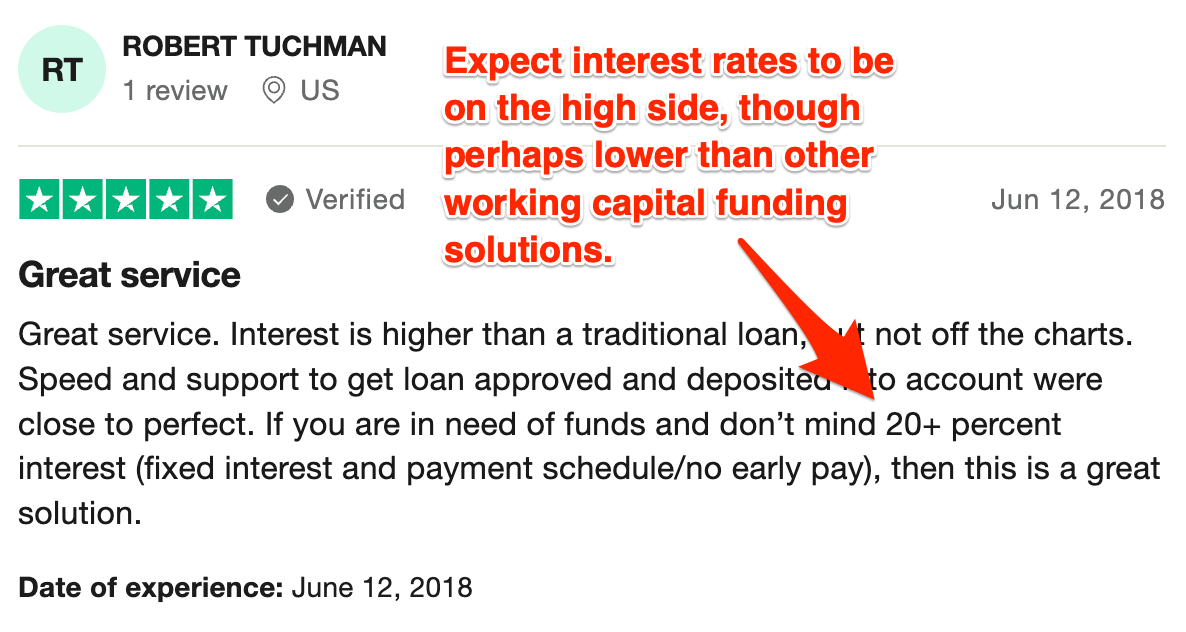
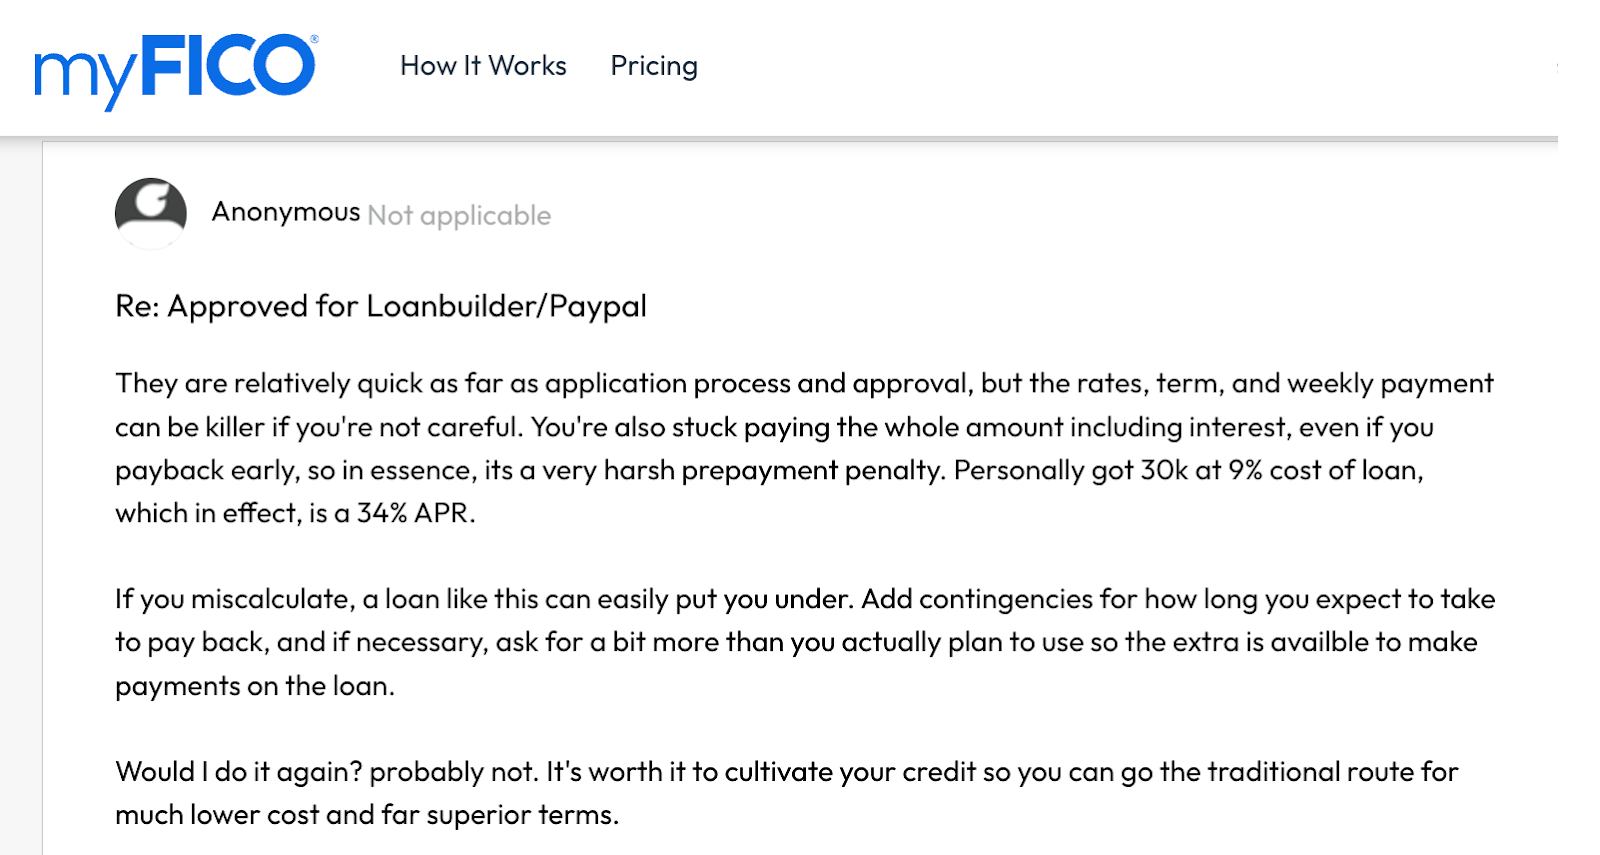
However, since this is a working capital-style loan, you should expect interest rates higher than you would get via, say, your business credit union. Still, they may be lower than other working capital solutions. 

PayPal Loan Builder interest rate

The specific amount of the Total Loan Fee varies based on: 

  1. The loan amount
  2. Repayment term
  3. Financial risk

LoanBuilder Loans do not have additional fees such as late fees, early repayment fees, or processing fees—The Total Loan Fee is the primary cost associated with borrowing and is included in your repayment schedule.

Paypal loanbuilder review

To see your LoanBuilder cost, you’ll need to complete the loan application process and review the personalized terms.

Recommended: 3 Best Credit Unions for Small Business Banking

How Does PayPal LoanBuilder Loan Work? 

LoanBuilder from PayPal offers a pretty simple approach to business financing, providing you with a customizable loan experience tailored to your business needs. 

With LoanBuilder, you have the freedom to: 

  • Access funds quickly
  • Repay with clarity
  • Benefit from straightforward terms 

Let’s delve into the key features that will help you decide if LoanBuilder is the best choice for your business funding.

You might also like: A Deep-Dive National Funding Review: Should You Accept an Offer? 

1. Apply With No Impact to Your Credit

PayPal Loan Builder application

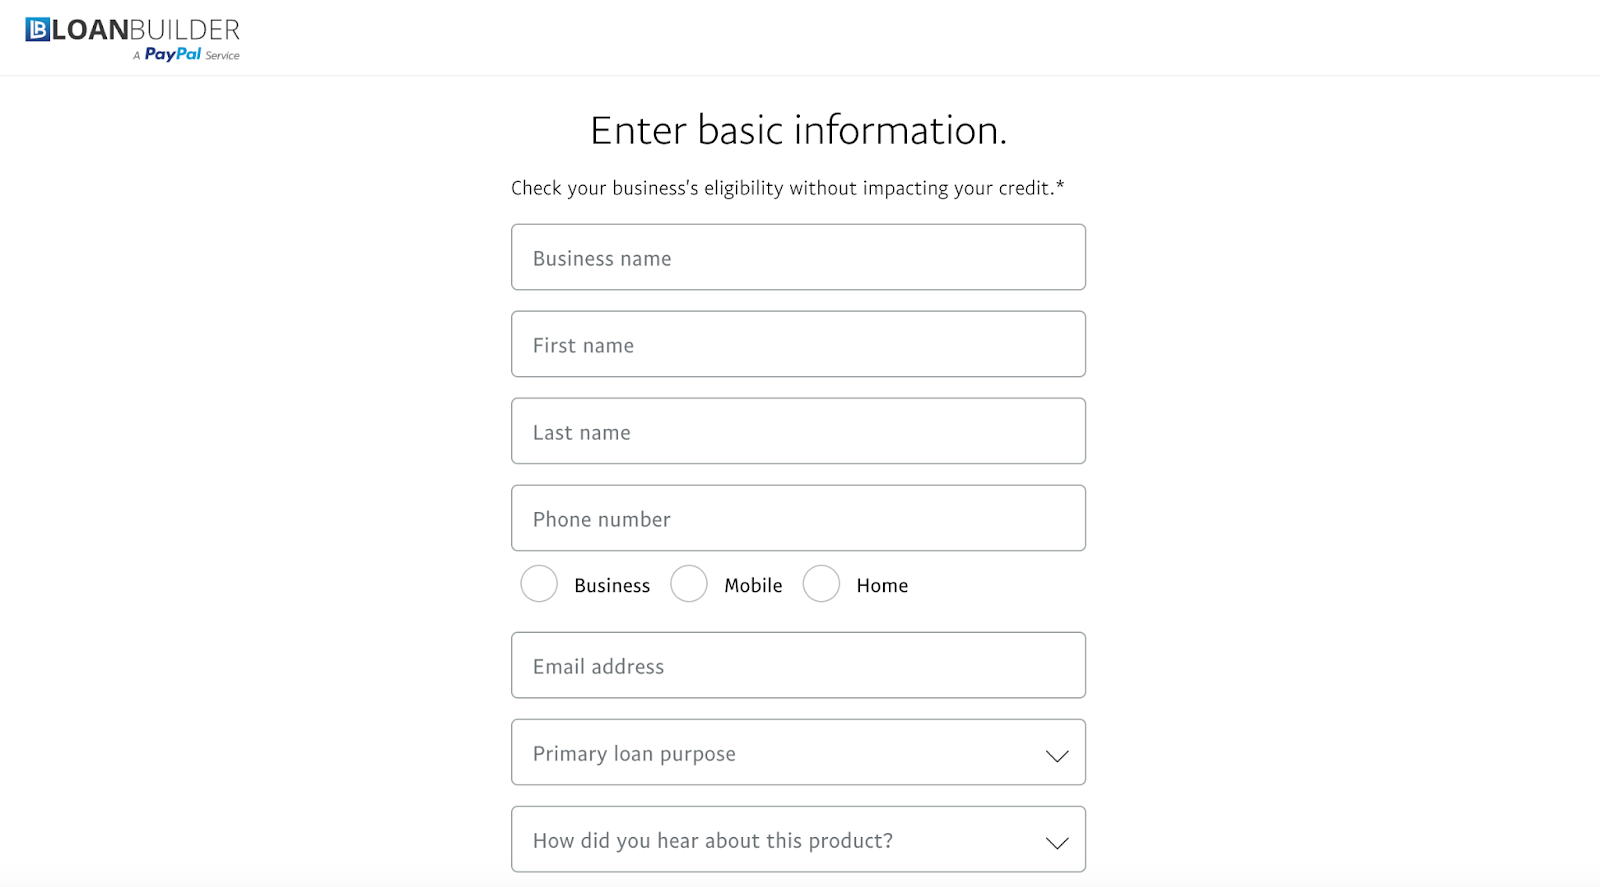
The PayPal LoanBuilder “application” is pretty straightforward. The questionnaire asks you for contact information, how you plan to use the funds, how you heard about the loan, business location, and business details. 

Details to have on-hand about your business include: 

  • Legal business name & DBA (if applicable)
  • Business address & website address
  • Entity type & state of incorporation
  • Annual revenue
  • Business start date
  • Number of employees
  • Industry & sub-industry
  • Percentage of ownership 

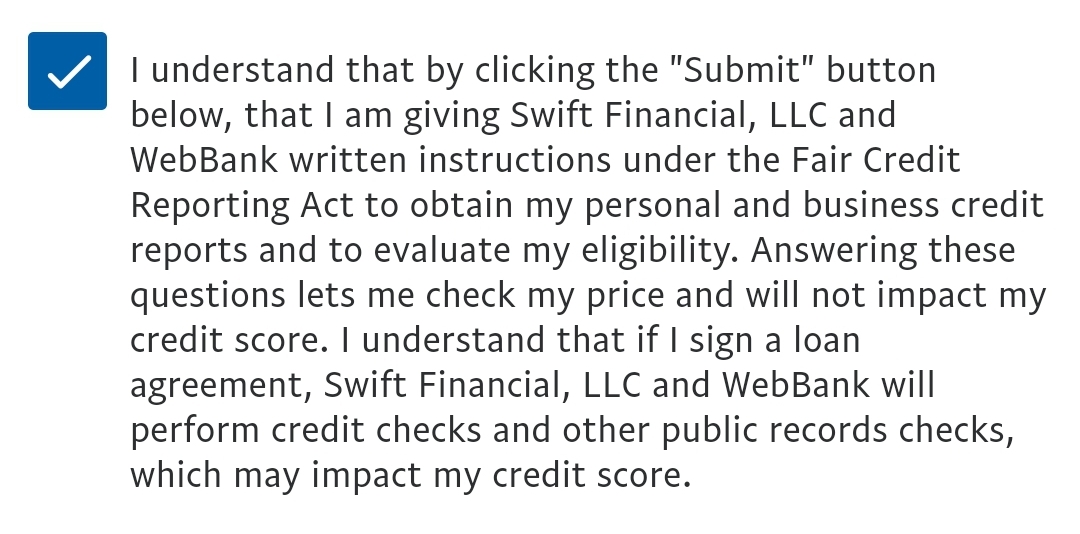
The application also asks for your Social Security Number and Employer Identification Number. Luckily, they do a soft inquiry into your personal credit for pre approval, which won’t negatively impact your credit score. 

PayPal Loan Builder soft inquiry

However, you will probably have to approve a hard pull for final approval. 

PayPal Loan Builder Hard Inquiry

Don’t move forward with that until you’re absolutely sure you want this loan.  

You might also like: Here’s How to [Actually] Get Business Credit With Just an EIN +More Options 

2. “Customizable” Funding

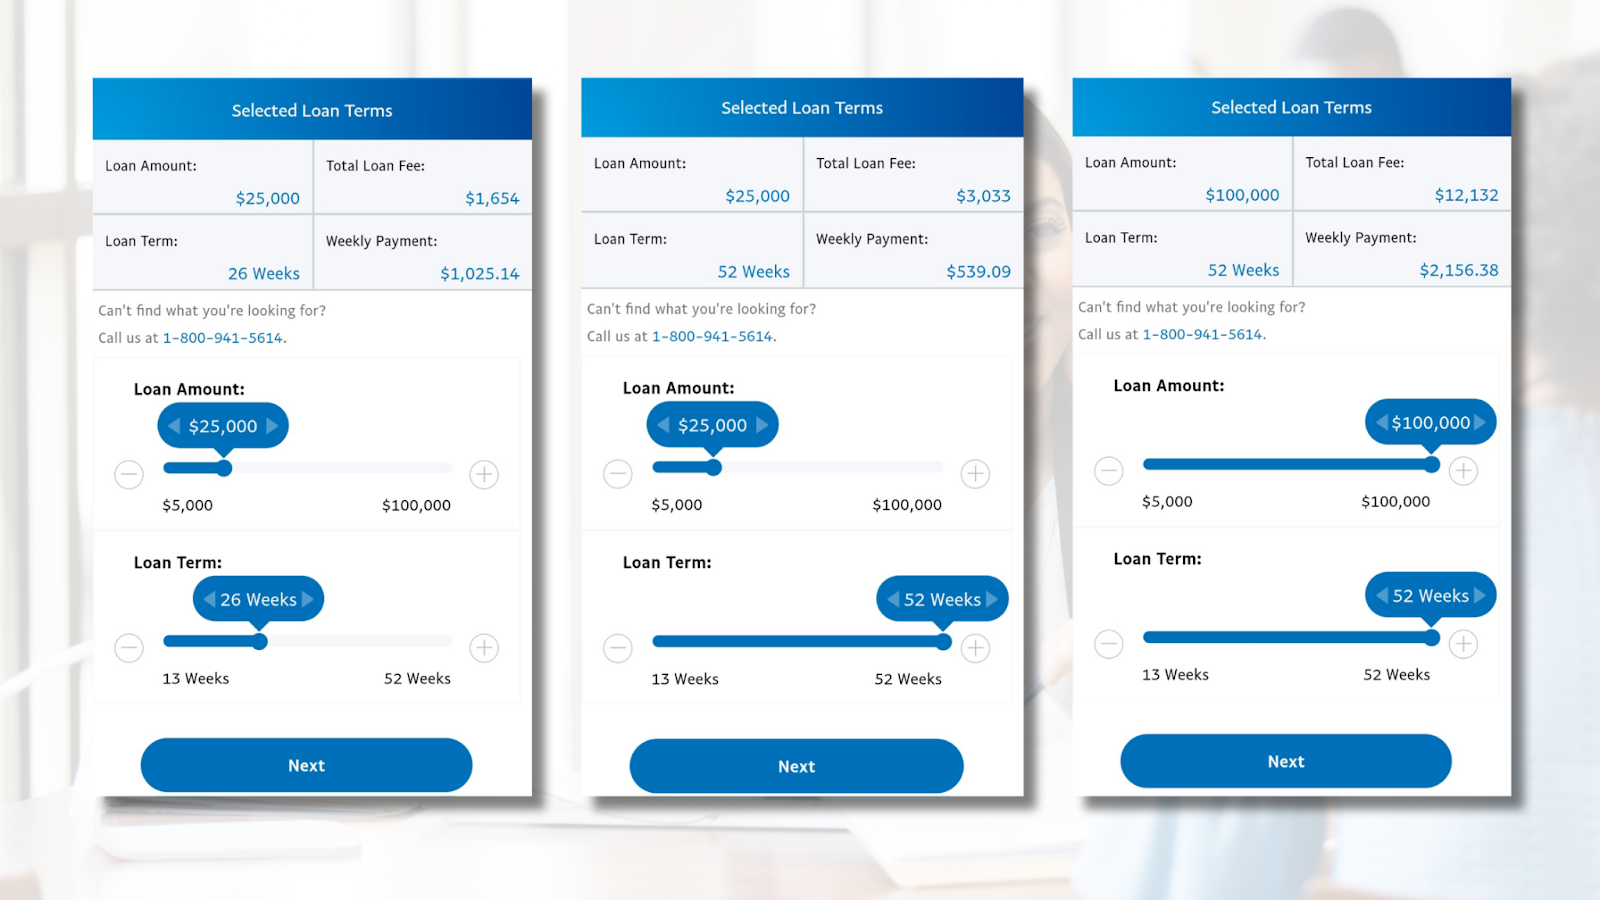
PayPal LoanBuilder Customized Loan

LoanBuilder advertises a “customizable” loan—This makes it sound as if you might get to choose your amount, terms, and rate, which would be pretty exciting. 

However, that’s not a realistic way to think about lending; lenders need to assess the financial risk before approving any type of financing. 

Still, after you’re pre-approved for a loan, you can choose your loan amount and repayment term. Your loan fee percentage will increase as your terms are extended. So, the longer you give yourself to pay off the loan, the higher your Total Loan Fee. 

If you do opt for this loan, consider giving yourself some extra time to pay it just in case something unexpected occurs, as you could be charged penalties for failing to pay on-time.  

3. Fixed-Fee Loan

PayPal Business Loan Builder

When you take out a LoanBuilder Loan, you won’t have any upfront fees deducted from the loan amount you receive. Instead, the cost of borrowing—the single fixed fee, known as the “Total Loan Fee”—is spread out and paid gradually over the entire duration (life) of the loan.

Here’s a breakdown of what this means:

  • When you receive the loan amount, the full sum is deposited into your business bank account without any immediate deductions for fees or charges. This ensures that you have access to the entire loan amount upfront to use for your business needs.
  • The cost associated with borrowing the money is represented by a single fixed fee—This fee is agreed upon and disclosed at the time of loan approval; it does not change over the course of the loan.
  • Rather than paying a fee upfront or separately, it is integrated into your loan repayment schedule. Each time you make a repayment towards your loan (typically on a weekly basis), a portion of that payment goes towards covering the Total Loan Fee. This fee is gradually paid down along with the principal amount of the loan.

By structuring the loan this way, you get clarity on the total cost of borrowing from the outset, and you can plan your repayments knowing how much will be allocated towards the loan principal and how much towards the fixed fee. 

4. Fast Access to Funds

PayPal Builder Loan

The LoanBuilder lending process is designed to be fast… 

First, when you check your eligibility, it’s done through a quick online questionnaire. This initial eligibility check does not involve a hard inquiry on your personal credit report, which means it won’t affect your consumer credit score—This is helpful because you can explore loan options without worrying about potential negative impacts on your credit rating.

If your LoanBuilder Loan application is approved, the funds are transferred directly to your business bank account, often by the next business day after approval—This rapid transfer ensures that you can access the funds quickly to address business needs or capitalize on opportunities right away.

5. Accessible Business Funding

PayPal Loan Builder login

The eligibility requirements for a LoanBuilder Loan can be considered relatively low compared to some traditional business loans:

  • At least nine months in business
  • $33.3K annual revenue 

Requiring a minimum of nine months in business is relatively short compared to other types of business loans that might need several years in operation. Newer businesses can access financing sooner in their development stages.

While this amount varies depending on the size and industry of your business, $33,300 annual revenue is a moderate threshold—It’s achievable for many small businesses, including startups and those in their early stages of growth.

These requirements are inclusive and accessible to a wide range of small businesses, including startups and those with modest revenue streams. 

You might also like: Y Combinator: Fast Track to Success or Waste of Time? 

6. Weekly Repayment Terms Up to 12 Months